

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Report: Insect Feed Market to Reach $425.8M by 2032 at 16.4% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Insect Feed Market: Navigating the 2026 Outlook with PW Consulting
Executive Summary: A Market at an Inflection Point
The global insect feed market stands at a critical juncture where sustainability mandates, regulatory liberalization, and scaling production capacity converge. Drawing on PW Consulting's latest market research, this analysis provides strategic decision-makers with a structured view of the market's trajectory from the base year of 2025 through the forecast period extending to 2032. The report is designed not as a static data repository but as a decision-making toolkit for executives navigating capital allocation, supply chain restructuring, and competitive positioning in an industry expanding at a compound annual growth rate of 16.4 percent. With historical revenues measured in USD Million across the 2020 to 2025 window and a clear projection horizon, the research bridges retrospective performance with forward-looking scenario planning. This article previews the strategic architecture of the full report, highlighting how the intelligence contained within supports precise, evidence-based choices for 2026 and beyond.
Market Trajectory and Macro Drivers: The Numbers Behind the Momentum
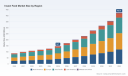
Historical performance reveals a market that has consistently outpaced conventional agricultural commodity growth. From a baseline valuation of approximately 88.5 in 2020, revenues climbed steadily through subsequent years, reaching 100.37 in 2021, 109.35 in 2022, 118.4 in 2023, and 126.68 in 2024. The base year 2025 closed at 147.0, setting the stage for a pronounced acceleration entering the forecast window. According to the full forecast, the market is projected to reach 172.94 in 2026, followed by 201.36 in 2027, 231.88 in 2028, 277.86 in 2029, 317.06 in 2030, 356.88 in 2031, and ultimately 425.8 by 2032. These figures reflect a double-digit CAGR of 16.4 percent that underscores both organic demand expansion and the compounding effect of capacity additions across key geographies.
Several macro forces are reinforcing this trajectory. Regulatory evolution is unlocking previously constrained feed categories. EU Regulation 767/2009 has long permitted insect proteins in aquaculture feed, and subsequent EU Official Journal approvals have extended commercial viability to pig and poultry applications, with inclusion limits reaching up to 20 percent in certain formulations. In parallel, the US FDA has completed GRAS determinations for insect proteins in select animal categories, and black soldier fly approvals for poultry and pet food have expanded during 2024 and 2025. These regulatory milestones remove friction from market entry and create a more predictable compliance environment for producers and feed formulators alike.
Cost dynamics further favor insect-based inputs. Production systems rely on upcycled organic waste substrates, including food processing byproducts, which can reduce material costs by up to 50 percent compared to conventional protein sources. This structural advantage, combined with life cycle assessments showing reductions in land and water use by 40 to 98 percent and lower CO2 emissions versus soy or fishmeal alternatives, strengthens the economic and sustainability case for adoption. As feed manufacturers and vertically integrated producers evaluate total cost of ownership, insect proteins are increasingly positioned as a resilient, low-impact feedstock rather than a niche supplement.
What the Report Delivers: Operational Intelligence for Corporate Strategy
The Insect Feed Market report from PW Consulting is structured to move beyond headline figures and equip stakeholders with actionable intelligence across multiple dimensions of the value chain. The analysis is built around a comprehensive segmentation framework that examines the market by region, by type, and by application, enabling users to isolate the segments most relevant to their operational footprint and growth ambitions. Rather than presenting generic aggregates, the report maps how each segment contributes to overall market momentum and where performance dispersion signals opportunity or risk.
At the operational level, the report details the technical and commercial parameters that shape competitiveness in this space. It examines how different insect species are positioned across feed categories, including aquaculture, poultry nutrition, swine nutrition, and pet food, and how production economics, substrate availability, and processing pathways influence margin structures. The research also tracks the interplay between historical performance and forecast assumptions, providing transparency into the drivers behind each projection interval. This allows strategy teams to stress-test their own forecasts, identify sensitivity points, and align internal planning with industry trajectory.
Beyond segmentation, the report incorporates a disciplined competitive analysis that maps the landscape of established and emerging players. It evaluates how firms are differentiating through biology, process engineering, geographic footprint, and commercial partnerships. Recent developments are contextualized within broader strategic patterns rather than treated as isolated events. The analysis is designed to help executives benchmark their position, anticipate competitive moves, and identify white spaces where first-mover advantage may still be attainable. All quantitative detail, including precise regional and application-level breaks and company-specific benchmarks, is reserved for the full report, ensuring that subscribers gain the granularity necessary for board-level and investment-grade decisions.
Competitive Landscape: Consolidating Players and Strategic Moves
The industry's competitive architecture reflects a mix of regional specialists, technology-driven biostartups, and firms pursuing scale through facility expansion and partnership strategies. The research profiles a core set of companies whose activities illustrate the strategic diversity shaping the market. EnviroFlight, headquartered in the United States, produces all-natural, locally sourced black soldier fly larvae feed ingredients for animal feed, pet food, and plants, with growing and processing operations based in the USA. Innovafeed, based in France, operates as a biotechnology company and leading insect producer for animal and plant nutrition, leveraging proprietary breakthrough technology for insect rearing. Protix, headquartered in the Netherlands, is recognized as a global leader in high-quality, low-impact insect solutions for feed and farming, with a focus on black soldier fly larvae across animal feed, pet food, aquaculture, and plant care. Entobel, a Singapore-based biotech company with operations in Vietnam since 2015, produces functional insect-based ingredients for animal feed and health.
Insect Feed Market
Additional profiles deepen the competitive picture. NextProtein, also based in France, produces insect-based protein for animal feed stocks by processing black soldier fly into dry protein powder, lipids, and fertilizer. Hexafly, from Ireland, combines nature and technology to bioconvert food waste into sustainably produced high-quality insect-based protein, oil, and fertilizer for animal feed. Beta Hatch, in the United States, industrializes insect agriculture within a regenerative food system, producing protein for plants and animals in a zero-waste system using mealworms. Nutrition Technologies, headquartered in Singapore, produces sustainable insect proteins, oils, and organic fertilizer for aquaculture, agriculture, and animal feed using black soldier fly. Together, these firms represent the spectrum of operational models currently driving market expansion.
Recent corporate actions reveal a market in which strategic positioning is being reinforced through tangible milestones. Innovafeed opened the North American Insect Innovation Center in Decatur, Illinois, as its first US facility for insect protein production, signaling a deliberate push into the North American market. Entobel became a Certified B Corp, aligning its operational model with formal sustainability credentials that increasingly matter to downstream customers and investors. Protix signed a multi-year supply agreement with Skretting for BSF meal in salmon feed formulations, illustrating how capacity and commercial partnerships are being structured to secure demand in high-value aquaculture channels. Nutrition Technologies rebranded as Sentara Group following expansion in insect protein production, reflecting a strategic recalibration as firms scale beyond single-product identities. For decision-makers, these developments are not merely news items; they are signals of where capital, technology, and customer relationships are concentrating.
Concentration, Regulation, and Cost Architecture: The Structural Underpinnings
A clear view of market structure is essential for assessing both opportunity and risk. Industry data indicate a moderately concentrated landscape, with the top three firms accounting for 32.5 percent of market share and the top five firms capturing 41.8 percent. This concentration profile suggests that while scale players have meaningful influence, there remains substantial room for regional specialists, niche innovators, and new entrants that can differentiate through biology, substrate economics, or vertical integration. For corporate strategy teams, this balance of concentration and fragmentation informs questions about partnership strategy, acquisition targets, and barrier-to-entry assessment in specific geographies or feed categories.
Regulatory and cost architectures are equally central to long-term planning. On the regulatory side, EU frameworks have progressively permitted insect proteins in aquaculture and, more recently, approved farmed insect proteins for pig and poultry feed with inclusion limits of up to 20 percent in certain formulations. In the United States, FDA GRAS determinations and expanding black soldier fly approvals for poultry and pet food during 2024 and 2025 have reduced uncertainty for market participants seeking to serve multiple animal nutrition channels. These developments collectively widen the addressable application base while creating a more uniform compliance foundation for production and reformulation.
On the cost side, the reliance on upcycled organic waste substrates provides a structural advantage that is difficult for conventional protein sources to replicate at comparable scale. By converting food processing byproducts and related organic streams into high-value feed ingredients, insect production can lower input costs while simultaneously addressing waste management and resource efficiency objectives. This dual benefit strengthens the value proposition for feed manufacturers, integrated agribusinesses, and sustainability-focused buyers. The report examines these dynamics in depth, connecting substrate economics, processing intensity, and end-market pricing to help executives identify where margin resilience is likely to be strongest across the forecast horizon.
Why This Report Matters for 2026 Decision-Making
For organizations making capital, procurement, and portfolio decisions in 2026, the market's pace of change leaves little room for lagging intelligence. The forecast period from 2026 through 2032 is characterized by sustained growth, regulatory opening, and increasing competition among producers with varying degrees of scale, geography, and technological differentiation. In this environment, strategic advantage depends on the ability to interpret macro trends through the lens of segment-specific dynamics, competitive moves, and operational feasibility. The PW Consulting Insect Feed Market report is designed to deliver exactly that interpretive layer.
Decision-makers will find value in the report's structured treatment of where growth is concentrating, which application categories are expanding most rapidly, and how regional markets compare in terms of demand intensity and competitive activity. The analysis also supports scenario thinking by linking historical performance to forecast assumptions, enabling teams to assess the implications of different growth paths, substrate availability scenarios, and regulatory developments. For investors and executives evaluating market entry, expansion, or partnership opportunities, the report provides the evidentiary foundation needed to prioritize initiatives and allocate resources with confidence.
Aqua Feed Market
Conclusion: From Insight to Action
The insect feed market is no longer an emerging curiosity; it is a scaling industry with clearly identifiable growth vectors, an evolving regulatory landscape, and a competitive field that rewards both biological innovation and operational discipline. PW Consulting's latest market research synthesizes the historical record, forecast trajectory, segmentation detail, and competitive intelligence into a single, decision-ready framework. The 16.4 percent CAGR and the progression from 147.0 in the base year 2025 toward 425.8 by 2032 are not just headline indicators; they are the starting point for a deeper conversation about where value will be created and how to position for it. The full report unpacks the segment-level breakdowns, regional comparisons, application-specific dynamics, and company-level analysis that leaders need to convert strategic intent into executed plans. For those responsible for shaping 2026 decisions and beyond, the complete intelligence is available through the source page, where the detailed dataset and proprietary analysis can be accessed in full.
For detailed analysis of this topic, please visit the official page: Insect Feed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Robotic Polishing Machine Market Hits $215M in 2025, Poised for 12.6% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Horizons: Navigating the Robotic Polishing Machine Market from 2026 Onward
Executive Overview
The industrial surface finishing landscape is undergoing a structural transformation, driven by the convergence of advanced robotics, precision control systems, and escalating demands for repeatable quality across complex geometries. For manufacturing executives, capital allocators, and procurement strategists, understanding the trajectory of the robotic polishing machine market is no longer a peripheral analytical exercise—it is a core component of operational planning, capacity investment, and competitive positioning. PW Consulting’s latest market research release delivers a comprehensive, forward-looking assessment engineered specifically to inform 2026 decision-making. This introduction outlines the strategic architecture of the study, the analytical frameworks it employs, and the decisive intelligence it surfaces. Readers are invited to engage with the full report for granular segmentation, modeling outputs, and actionable implementation roadmaps.
Robotic Polishing Cells Market
The analysis rests on a rigorously validated historical track record and a carefully constructed multi-year projection window. It traces market evolution across a defined historical span and extends the analytical horizon to the medium-term forecast period. By anchoring projections in observable supply-chain shifts, automation adoption curves, and sector-level capital expenditure patterns, the publication provides a defensible baseline for stress-testing investment hypotheses and aligning operational roadmaps with emerging market realities.
The 2026 Decision Landscape: Why Timing Matters
Entering 2026, enterprises across precision manufacturing, automotive assembly, electronics production, and industrial tooling face a shared strategic imperative: convert automation investments into measurable throughput gains, quality consistency, and labor flexibility. Market momentum suggests that the next several years will be characterized by accelerated deployment cycles, technology maturation, and evolving compliance expectations. In this environment, strategic planners require more than directional signals. They need validated sizing, scenario-tested growth pathways, and clear visibility into where capital will flow and how competitive dynamics will reshape vendor selection.
The research publication is structured to serve as a decision-support instrument rather than a static market snapshot. It maps the trajectory from the most recent baseline year through the forecast window, enabling leadership teams to calibrate their investment cadence, evaluate entry or expansion timing, and anticipate shifts in vendor pricing, integration complexity, and service requirements. By aligning forecast outputs with practical planning horizons, the study allows decision-makers to translate macro-level movement into actionable procurement and capacity strategies.
Historical Trajectory and Forward Momentum
Market expansion over the historical observation window provides a clear reference point for evaluating the scale and pace of ongoing adoption. Revenue progression across the reviewed historical years reflects sustained demand for automated finishing solutions, underpinned by quality standardization requirements, throughput optimization goals, and the broader shift toward flexible automation in discrete manufacturing. The data series captures the steady climb in system uptake as organizations transition from experimental automation to production-critical deployment.
Robotic Polishing Machine Market
Forward-looking projections extend this trajectory into the forecast period, illustrating a sustained growth pathway. The compound annual growth rate positions the market in a high-velocity band relative to adjacent industrial automation segments, signaling continued investment appetite and broadening application relevance. Revenue estimates for the near-term forecast years indicate a market that will continue to scale materially, with later projection points suggesting meaningful expansion as technology costs normalize, integration pathways mature, and end-user confidence in robotic finishing systems deepens. The overall market sizing framework offers executives a reliable macro baseline, while intentionally preserving detailed regional, application, and type-level breakdowns for the full report, where they can be examined alongside supporting methodology and scenario notes.
Structural Dimensions of the Market Opportunity
A market of this scale and pace cannot be understood through a single lens. The research decomposes the landscape into several interlocking structural layers, each designed to support a different class of strategic question.
- Technology and configuration pathways are evaluated to clarify how different machine architectures align with production objectives, surface complexity requirements, and integration footprints.
- Application relevance is mapped across major end-use environments, helping stakeholders determine where automated polishing delivers the strongest return on quality, cycle-time, and labor flexibility objectives.
- Geographic distribution is analyzed to identify demand concentration patterns, regional growth pacing, and localized adoption drivers that influence sourcing, service coverage, and partnership strategy.
This layered structure ensures that the study can be used both for executive-level market sizing and for operational planning tasks such as product-line alignment, regional rollout sequencing, and vendor shortlisting. By maintaining analytical discipline across these dimensions, the publication avoids overgeneralization and equips readers with a structured way to interrogate the opportunity space from multiple vantage points.
Competitive Architecture and Strategic Positioning
The competitive field in robotic polishing reflects a blend of established automation specialists, tooling and system integrators, and technology-forward entrants emphasizing intelligent control and adaptive finishing. The study profiles key participants to illuminate how strategic positioning, product focus, and geographic footprint shape market influence.
Several organizations feature prominently in the competitive landscape. Acme Manufacturing is highlighted for its emphasis on robotic polishing machines built around advanced belt polishing heads, targeting high-volume producers that require repeatable finishes on complex shapes. Mirka Ltd is examined for its broader systems approach, offering complete robotic polishing and sanding solutions that combine tooling and automation integration for industrial surface finishing. GrayMatter Robotics enters the analysis through its AI-powered systems, which scan and automate polishing workflows with a focus on expanding manufacturing capacity while reinforcing quality consistency. Dinosaw Machine is profiled for its 6-axis robotic arm and system portfolio designed for stone grinding and polishing, with an emphasis on force control and precision tooling. American Siepmann Corporation rounds out the competitive set through its supply of automated CNC polishing machines and robotic systems oriented toward high-precision industrial finishing.
These profiles are not presented as isolated corporate snapshots. Instead, they are contextualized within broader competitive dynamics, including technology differentiation, integration readiness, service and support expectations, and the strategic logic behind recent product and event-level developments. Recent activity underscores how rapidly the field is evolving. In late 2025, Dinosaw Machine presented an in-depth industry event analysis centered on stone polishing robot technology, detailing 6-axis force control and safety integration considerations. Around the same period, Mirka Ltd released an updated brochure for its robotic solutions, reinforcing its focus on automated polishing, sanding, and grinding systems. Such developments point to a market in which product refinement, application specificity, and compliance-aware engineering are becoming central to competitive differentiation.
Regulatory Guardrails and Operational Realities
As robotic finishing systems move deeper into production-critical roles, compliance and safety architecture increasingly shape procurement decisions. The market’s leading technology demonstrations increasingly reference governing industrial robot safety requirements, including structured risk assessments and protective measures that align with established ISO 10218 expectations. Rather than treating compliance as a separate administrative checklist, the research integrates it into the broader assessment of deployment readiness, integration risk, and total cost of ownership.
For planning teams, this means that technology selection is inseparable from operational governance. Machines that deliver superior finish consistency must also satisfy safeguarding, interoperability, and validation expectations within the user’s facility. The study examines how safety-centric engineering and compliance alignment influence vendor evaluation, installation timelines, and long-term reliability, ensuring that strategic recommendations account for both performance and operational accountability.
What the Full Report Delivers
The publication is designed as a modular intelligence framework that can be deployed across multiple internal use cases, from strategic planning and investment review to procurement alignment and competitive benchmarking. While this introduction establishes the strategic rationale and high-level market structure, the full report extends far deeper into the analytical detail required for concrete decision-making.
- Market sizing and growth modeling that connect historical performance with forward projections, enabling scenario planning across different adoption and pricing assumptions.
- Multi-dimensional segmentation analysis that isolates demand patterns across technology types, application environments, and regional footprints, with supporting commentary on what each split implies for sourcing and rollout strategy.
- Competitive profiling and positioning maps that clarify how leading participants differentiate themselves, where capability gaps may exist, and how procurement teams can structure vendor evaluations.
- Recent development tracking that ties product launches, technical presentations, and system updates to market implications, helping readers gauge momentum in specific sub-areas of the value chain.
- Operational and compliance considerations that connect technology choices to safety requirements, integration complexity, and facility-level implementation realities.
The report is built to support both near-term tactical questions and longer-horizon strategic planning. It provides the evidentiary scaffolding needed to evaluate market entry, capacity expansion, supplier diversification, and technology investment timing with greater confidence.
Strategic Takeaways for 2026 Planning
As enterprises move into the 2026 planning cycle, the robotic polishing machine market presents both a scaling opportunity and a complexity challenge. Demand momentum, technology maturation, and competitive differentiation are converging to reshape how organizations evaluate automation investments. The companies best positioned to capture value will be those that align system selection with production objectives, anticipate integration and compliance demands, and base procurement decisions on rigorous, scenario-tested intelligence rather than directional assumptions alone.
PW Consulting’s market research is intended to function as a strategic compass for that process. It synthesizes historical evidence, forward projections, competitive dynamics, and operational realities into a coherent decision-support structure. To fully exploit the analytical depth, segmentation breakdowns, and competitor intelligence embedded in the study, stakeholders should engage with the complete report. The full publication provides the detailed market architecture necessary to convert high-level trends into precise, execution-ready strategy.
For detailed analysis of this topic, please visit the official page: Robotic Polishing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chlorogenic Acid Market Hits $215M in 2025, Projects 5.69% CAGR to 2032
By pmarketresearch, 2026-09-15
Chlorogenic Acid Market 2026–2032: Strategic Intelligence for Formulation, Procurement, and Competitive Positioning
Why This Study Matters in the 2026 Decision Cycle
The chlorogenic acid market enters the 2026–2032 forecast window at a structural inflection point. After a decade of steady value accumulation, total market revenue reached an estimated USD 215.0 Million in 2025, extending a clear upward trajectory from USD 163.06 Million in 2020. The forward view projects a compound annual growth rate of 5.69 percent, translating the base-year position into an anticipated USD 226.87 Million in 2026 and a long-term valuation pathway that approaches USD 316.72 Million by 2032. These headline figures do more than chart volume; they signal a market that has graduated from niche botanical ingredient to a strategically contested category across nutraceuticals, functional beverages, cosmetics, and pharmaceuticals. For senior teams calibrating sourcing commitments, formulation roadmaps, or go-to-market timing, the 2026 environment demands a refined reading of supply-side leverage, regulatory direction, and competitive clustering—precisely the intelligence architecture built into this report.
A strategic reading of this growth curve must also account for concentration dynamics. The category is shaped by a moderately consolidated supplier base, where the top three players command an estimated 52.5 percent of revenue and the top five reach 60.0 percent. That concentration pattern matters because it compresses negotiation windows, amplifies the impact of capacity moves by leading firms, and determines which buyers can secure priority allocation during periods of raw-material stress. The full study unpacks how these concentration bands interact with regional sourcing patterns, type-level supply positioning, and application-level demand pull, but the core message for 2026 planners is straightforward: advantage in this market increasingly flows from the ability to map supplier leverage, not simply to track category growth.
Structural Forces Shaping the 2026–2032 Trajectory
Several converging dynamics are re-grading the risk-return profile of chlorogenic acid sourcing and product development. On the raw-material side, the category remains structurally tethered to global coffee and botanical supply chains. In 2024, global coffee production exceeded 11 million tons, with roughly 8 million tons traded internationally and Brazil and Vietnam accounting for nearly half of output. That concentration creates persistent exposure to weather variability, logistics friction, and regional policy shifts—variables that cascade directly into chlorogenic acid cost structures and availability. At the same time, the botanical component of the value chain extends beyond coffee beans into honeysuckle and eucommia-based pathways, which broadens the category’s raw-material mosaic but also introduces additional quality and traceability considerations.
Regulatory and trade signals add a second layer of strategic complexity. In specific food products such as coffee substitutes, the European Commission has implemented regulation setting chlorogenic acid limits below 100 mg/L, placing formulation ceilings on certain applications and nudging innovation toward compliant concentration strategies. In contrast, the FDA has recorded chlorogenic acid as a dietary substance with no specific quantity restrictions identified in its latest database, sustaining a comparatively permissive environment for dietary supplement and functional food development in the United States. Layered onto that divergence is a trade environment that continues to shift: in 2026, green coffee tariffs in the United States are being rolled back following reciprocal tariff adjustments, influencing import expenditures and altering the cost calculus for key producing regions. These are not peripheral details; they are the kinds of boundary conditions that determine whether a 2026 launch plan scales smoothly or encounters compliance and cost friction downstream.
Chlorogenic Acid Market
Where Demand Is Concentrating: Applications, Types, and Regional Pull
The demand architecture of the chlorogenic acid category is diversifying in ways that reward formulation teams willing to look beyond single-use assumptions. Nutraceutical applications continue to anchor a substantial share of value, reflecting sustained interest in metabolic health, antioxidant positioning, and functional wellness portfolios. Food and beverage applications represent a robust second engine, driven by the pursuit of clean-label functionality and the integration of bioactive ingredients into everyday consumption occasions. Cosmetics and personal care contribute a meaningful demand layer as well, leveraging chlorogenic acid’s relevance to skin-care efficacy narratives and premium botanical positioning. Pharmaceutical applications, while smaller in relative scale, carry outsized strategic importance because they demand higher purity standards, clinical-grade documentation, and API-grade consistency.
Ferulic Acid Market
On the supply composition side, green coffee beans remain the dominant type-level source for chlorogenic acid extraction, reinforcing the category’s continued dependence on coffee-sector dynamics. Honeysuckle and eucommia-based pathways further diversify the type landscape, enabling brand owners and ingredient suppliers to differentiate on botanical origin, extraction profile, and compliance story. Regionally, the market’s footprint is distributed across a broad set of demand centers rather than consolidated in a single geography, which means that procurement strategies must account for differing logistics costs, regulatory expectations, and supplier proximity advantages. The study provides a detailed map of how these type- and region-level structures interact with application-specific buying behavior, including where formulation needs are tilting toward standardized extracts, where cosmetic-grade consistency is becoming a gating requirement, and where pharmaceutical-adjacent documentation is reshaping supplier qualification.
Competitive Landscape: Concentration, Capability, and Recent Moves
The competitive field in chlorogenic acid is defined by a blend of global botanical extract specialists, science-backed API-oriented manufacturers, and high-volume producers with expanding international reach. Naturex, operating under Givaudan and headquartered in Avignon, France, continues to emphasize standardized green coffee bean extracts rich in chlorogenic acid for nutraceutical, functional beverage, and cosmetic applications, with a stated emphasis on traceability and quality compliance. Its recent operational moves illustrate how leading players are trying to harden supply resilience while simultaneously opening new formulation doors. In March 2024, Naturex expanded its Ecuador and Vietnam raw-material hubs to tighten supply security and traceability. In June 2023, it launched PureBrew Bioactives with high CGA concentration to accelerate beverage flavor solutions. For procurement and R&D teams, these moves are signals: they indicate where supply assurance is being invested and where beverage-oriented application development is being actively scored.
Applied Food Sciences, based in Austin, Texas, takes a more brand-and-formulation-centric stance, focusing on branded green coffee bean extracts with defined chlorogenic acid content for dietary supplements, weight-management, and metabolic health formulations. EUROMED SA, headquartered in Barcelona, Spain, positions around high-purity botanical extracts including chlorogenic acid-rich plant extracts for pharmaceutical APIs, dietary supplements, and clinical-grade nutraceutical formulations—an orientation that matters wherever purity and documentation form the basis of supplier selection. Sabinsa Corporation, in New Jersey, continues to advance science-backed herbal and botanical APIs including chlorogenic acid extracts with clinical validation for pharmaceutical, nutraceutical, and preventive healthcare products, reinforcing the category’s credibility thread in evidence-led markets.
On the high-volume production side, several China-based manufacturers have built substantial export-oriented footprints. Zhejiang Skyherb supplies green coffee bean and honeysuckle-based HPLC 98 percent chlorogenic acid extracts to over 45 countries. Nutragreen Biotechnology similarly focuses on green coffee bean and honeysuckle-based HPLC 98 percent extracts, with an estimated 13 percent global market share. Chenguang Biotech has developed a portfolio of 37 chlorogenic acid product variants, holds an estimated 11 percent global market share, and supplies markets across more than 45 countries. Changsha E.K. HERB focuses on natural ingredients including chlorogenic acid extracts for nutraceutical and functional food applications, while Nanjing Zelang extends into medical technology and botanical extracts including chlorogenic acid for pharmaceutical and supplement uses. Cymbio Pharma, based in India, rounds out the competitive picture with a focus on herbal and botanical APIs including chlorogenic acid extracts for pharmaceutical and nutraceutical markets.
Together, these profiles highlight a competitive environment in which differentiation is being built on extraction purity, botanical origin, traceability, clinical or regulatory substantiation, and geographic supply reach. The report examines how these company-level strategies map onto the broader concentration pattern and where their combined movements are likely to influence pricing power, supply security, and formulation availability across the forecast period.
What the Report Delivers: Operational Intelligence for 2026 Planning
This market research is designed as a decision tool rather than a purely descriptive overview. It integrates historical performance from 2020 through 2025 with a forecast window spanning 2026 to 2032, anchored in a base-year valuation of USD 215.0 Million and projected toward long-range market sizing in the vicinity of USD 316.72 Million by 2032. The study organizes that trajectory around the segmentation dimensions most relevant to formulation, procurement, and market-entry planning: regional demand distribution, type-level supply positioning across green coffee beans, honeysuckle, and eucommia, and application-level behavior across nutraceuticals, food and beverage, cosmetics and personal care, and pharmaceuticals.
Beyond the macro sizing, the report advances practical analysis in several areas that directly affect 2026 execution. It examines how concentration patterns shape bargaining dynamics and allocation risk, where supplier expansion and product launches are altering capability ceilings, and how regulatory divergence across key markets is reshaping formulation boundaries and documentation requirements. It also situates the category within wider raw-material and trade currents, including the structural dependence on coffee-sector output, the impact of evolving tariff and import-expenditure conditions, and the implications of regulatory limits in certain food applications. The objective is to help teams answer operational questions with greater precision: where demand is deepening versus broadening, which supply routes are becoming more resilient or more exposed, and which competitive capabilities are likely to set the pace for category standards over the next several years.
To keep the analysis usable for cross-functional teams, the study translates market structure into strategic implications. For procurement leaders, it clarifies where supplier concentration and capacity activity are most likely to affect availability and negotiation leverage. For R&D and brand teams, it connects application trends and regulatory signals to formulation choices and launch timing. For competitive-intelligence functions, it maps the major players’ orientations and recent moves against the concentration and segmentation landscape, enabling more informed benchmarking and scenario planning.
How to Use This Intelligence Before the 2026 Cycle Closes
The chlorogenic acid market is not simply expanding; it is reconfiguring around purity expectations, regulatory interpretation, botanical sourcing strategy, and supplier concentration. The headline growth path—moving from a 2025 base of USD 215.0 Million toward a multi-year trajectory above USD 300 Million—masks a more important story for operators: the same market that rewards scale and consistency also punishes undifferentiated sourcing in a landscape where traceability, compliance, and application-specific quality are increasingly decisive. The strategic winners in 2026 will be those who can pair demand insight with supply-side realism, using concentration data, type-level positioning, and competitive capability mapping to reduce uncertainty rather than simply track it.
This report provides the framework for that kind of decision-making, but the full segmentation detail, regional demand mapping, type-level value distribution, application-level breakdowns, and company-specific strategic positioning are presented in depth only in the complete study. For teams that need the underlying numbers, scenario-ready segmentation, and the analytical logic behind supplier and regulatory implications, the complete market intelligence is available through the PW Consulting research portal. Accessing the full report will allow your team to move from directional confidence to execution-ready precision before the 2026 planning cycle advances further.
For detailed analysis of this topic, please visit the official page: Chlorogenic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Steam Turbine Market to Grow at 2.8% CAGR to $31.79M by 2032, Asia Pacific Leads
By pmarketresearch, 2026-09-15
Powering the Future: Strategic Insights into the Global Steam Turbine Market 2026-2032
Executive Summary: Navigating a Transitional Decade
The global energy landscape is undergoing a profound transformation. As the world balances the urgent need for reliable baseload power with the accelerating demand for sustainable solutions, the steam turbine remains a critical asset in the infrastructure toolkit. Our latest comprehensive study, the Steam Turbine Market Analysis 2026-2032, offers a granular examination of this evolving sector. This report is not merely a numerical forecast; it is a strategic roadmap designed to guide stakeholders through a period of regulatory shifts, technological innovation, and geopolitical complexity.
Based on rigorous data modeling, the global steam turbine market is projected to reach a valuation of USD 27.39 Million in 2026, growing steadily to approximately USD 31.79 Million by 2032. This trajectory reflects a Compound Annual Growth Rate (CAGR) of 2.8% over the forecast period. While the growth rate may appear moderate, the underlying dynamics driving this expansion are complex, involving a mix of legacy fleet modernization, renewable integration, and emerging power demands. Understanding the nuances behind these figures is essential for capitalizing on market opportunities.
Market Trajectory and Macro Economic Context
The historical data from 2020 to 2025 establishes a baseline of resilience. The market demonstrated consistent recovery and growth, moving from USD 22.82 Million in 2020 to USD 26.2 Million in 2025. This five-year trend underscores the enduring demand for thermal power solutions, even as the grid decarbonizes. The forecast period from 2026 to 2032 anticipates a continuation of this upward trend, driven by specific macroeconomic and industrial forces.
However, interpreting these top-line numbers requires a deeper dive into the segmentation and regional drivers that constitute the whole. The aggregate figure masks significant variations across product types, applications, and geography. Our full report dissects these components, providing the specific revenue breakdowns and volume analysis necessary for precise market sizing and opportunity assessment. Without this detailed segmentation, investment decisions risk being based on incomplete intelligence.
Key Market Drivers: Technology and Demand Shifts
Several critical factors are converging to shape the market landscape in 2026 and beyond. The most prominent driver is the surging power demand from artificial intelligence and data centers. As digital infrastructure expands, the requirement for reliable, high-capacity power generation is accelerating combined-cycle projects that incorporate steam turbines. Industry data indicates that projects targeting online operation by 2028 are already in motion, creating a immediate pipeline for turbine manufacturers.
Additionally, regulatory frameworks are playing a pivotal role in dictating market flow. In the United States, the Environmental Protection Agency finalized New Source Performance Standards for stationary combustion turbines effective January 15, 2026. These standards impose efficiency subcategorization thresholds, requiring large low-utilization units to meet design efficiency levels of 38%. This regulation directly impacts turbine design specifications and compliance strategies. Simultaneously, the U.S. Department of Energy allocated USD 475 million in June 2025 to enhance steam turbine efficiency in clean energy infrastructure, signaling strong government support for technological upgrades.
Furthermore, the regulatory environment regarding existing coal-fired units remains stringent. EPA Section 111 standards require conversion to natural gas or Carbon Capture and Storage (CCS) retrofits by 2030-2039. This mandates a strategic pivot for utilities and investors, influencing the demand for specific turbine configurations capable of handling alternative fuels or adapted cycles. These regulatory pressures create both challenges and opportunities, necessitating a detailed understanding of compliance timelines and technical requirements.
Supply Chain and Material Considerations
The manufacturing landscape is not immune to external economic pressures. Recent industry data highlights that U.S.-China tariffs have driven up prices of nickel and chromium-based alloys essential for steam turbine components. These raw material cost fluctuations impact margins and project economics, requiring careful supply chain management and hedging strategies. Stakeholders must account for these cost variables when bidding on long-term contracts or projecting financial performance.
Our analysis delves into the supply chain vulnerabilities and cost structures associated with high-grade alloys, offering insights into how leading manufacturers are mitigating these risks. Understanding the interplay between geopolitical trade policies and material costs is crucial for accurate pricing strategies and contract negotiations.
Competitive Landscape: Leaders and Innovators
The market is characterized by a mix of established multinational corporations and agile regional players. Concentration remains significant, with the top three companies holding a CR3 of 48.0% and the top five holding a CR5 of 50.0%. This concentration suggests a market where scale, technological IP, and long-term service agreements are key differentiators.
Several key companies are defining the competitive frontier through strategic orders and technological advancements:
Gas Turbine Market
- Siemens Energy AG continues to lead with a broad portfolio spanning 90-1,900 MW for conventional, combined-cycle, and nuclear applications. Recent activity includes a significant contract with Oklo for the Aurora advanced reactor power plant and selection for Applied Digital's 1 GW AI data center power project. Their record backlog of €138 billion reflects strong market confidence.
- GE Vernova Inc. supplies over 30% of global installed steam capacity. Their STF-series, including the STF-A650 and STF-D600, are central to advanced combined-cycle reheat designs, maintaining their dominance in power plant solutions.
- Mitsubishi Heavy Industries, Ltd. focuses on high-efficiency turbines for gas turbine combined-cycle plants, with the M701F series offering hydrogen co-firing capabilities, aligning with decarbonization goals.
- Doosan Enerbility Co., Ltd. has secured recent North American orders, including a contract for two 370 MW-class steam turbines for a U.S. data center project, highlighting the shift towards digital infrastructure power needs.
- Dongfang Electric Corporation Ltd. and Shanghai Electric Group Co., Ltd. remain leading Chinese suppliers, driving volume in large-scale turbine production for utility and combined-cycle systems.
- Bharat Heavy Electricals Limited serves the Indian market with turbines and generators for power generation and cogeneration.
- Toshiba Energy Systems & Solutions Corporation and Ansaldo Energia S.p.A. provide specialized solutions for combined-cycle and cogeneration plants.
- Harbin Electric Corporation leverages strong domestic and export capabilities for power generation turbines.
The competitive dynamics are not static. Recent developments in 2025 and 2026 show a clear trend towards securing long-term backlogs and entering niche high-growth sectors like nuclear and AI data centers. Our report provides a detailed competitive profiling, analyzing market share, strategic positioning, and recent M&A or partnership activities that shape the industry hierarchy. Accessing the full report reveals the specific strategic moves that are defining market leadership in this cycle.
Segmentation Insights: Types and Applications
The market is bifurcated primarily by turbine type and application. The two main technological approaches are Impulse and Reaction steam turbines. Each type offers distinct advantages depending on the pressure stages and efficiency requirements of the plant. Similarly, applications range from traditional power generation to industrial oil and gas usage, and other specialized sectors.
Power generation remains the dominant application, but the proportion of revenue contributed by industrial sectors and the specific performance characteristics preferred in different regions vary significantly. The full study provides a deep dive into the performance metrics, efficiency ratings, and cost-benefit analysis of each segment. Knowing which segment is driving growth in specific timeframes allows for targeted product development and marketing strategies.
Regional Analysis and Growth Hotspots
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique set of drivers. For instance, Asia Pacific has historically shown substantial volume due to industrialization and energy access goals. North America and Europe are increasingly driven by efficiency upgrades and compliance with stringent environmental regulations.
However, the specific revenue contribution and growth rate for each region are subject to local policy changes, capacity additions, and retirement schedules of older plants. A superficial regional overview is insufficient for strategic planning. The detailed regional analysis in our full report breaks down country-specific regulatory environments, infrastructure projects, and demand forecasts, enabling clients to prioritize markets with the highest potential return on investment.
Steam Turbine Market
Strategic Value for 2026 Decision Makers
Why is this report essential for 2026? Because the margin for error is narrowing. With regulatory deadlines approaching for coal-fired units and rapid shifts in power demand profiles, decisions made today will determine operational viability and profitability over the next decade.
Our report is designed to answer critical strategic questions:
- How should capital be allocated between new builds and retrofits given the 2030-2039 compliance windows?
- Which turbine technologies are best positioned to meet the 38% efficiency thresholds for large units?
- How do raw material cost volatilities impact long-term contract pricing models?
- Which competitors are gaining ground in high-growth niches like nuclear micro-reactors and data center power?
The insights provided are not generic observations but data-backed revelations derived from extensive primary and secondary research. We isolate the signal from the noise, focusing on actionable intelligence that drives bottom-line results.
Conclusion: Accessing Complete Intelligence
The global steam turbine market is at an inflection point. While the top-line forecast indicates steady growth, the real value lies in understanding the mechanical levers driving that growth. From the impact of EPA standards on turbine design to the supply chain implications of alloy tariffs, and the competitive maneuvers of industry giants like Siemens and GE Vernova, the landscape is rich with complexity.
This article serves as a preview of the depth and breadth of our Steam Turbine Market Research. However, the strategic numbers, detailed segmentation splits, and comprehensive competitor matrices are reserved for our full publication. To secure a competitive advantage in 2026, you need more than general trends; you need precise data.
We invite you to access the full report to unlock the complete strategic intelligence required to navigate the 2026-2032 forecast period with confidence. The detailed breakdowns of region-specific values, application-specific revenue, and type-specific market shares are available exclusively through our comprehensive study. Make informed decisions with the full picture.
For detailed analysis of this topic, please visit the official page: Steam Turbine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Orally Disintegrating Tablets to Reach $344.8M by 2032, 8.5% CAGR
By pmarketresearch, 2026-09-15
Unlocking the Future of Patient-Centric Dosage: Strategic Insights into the Orally Disintegrating Tablet Market 2026–2032
The pharmaceutical industry is undergoing a quiet but profound transformation in how therapies are delivered. Patient adherence, ease of administration, and rapid onset of action are no longer secondary considerations; they are central pillars of modern drug development and commercial strategy. At the forefront of this shift is the orally disintegrating tablet (ODT) segment, a dosage form that bridges the gap between traditional solid oral dosage and advanced patient-centric delivery systems. As we step into 2026, decision-makers across pharmaceutical manufacturers, CDMOs, excipient suppliers, and life sciences investors require a clear, data-grounded view of where this market has been, where it is accelerating, and which structural forces will reshape competitive advantage over the next seven years.
This article introduces PW Consulting’s newly released Orally Disintegrating Tablet Market research, a comprehensive strategic briefing designed to equip executive teams with actionable intelligence for 2026 planning and beyond. Rather than offering surface-level aggregates, the study maps the interplay between historical trajectory, regulatory evolution, formulation innovation, and competitive positioning. Below, we preview the analytical framework, highlight the macro dynamics fueling growth, and outline the practical deliverables that make this research a critical asset for enterprise strategy.
Historical Trajectory and Forecast Horizon: A Resilient Growth Arc
Understanding the ODT market’s momentum begins with a disciplined look at its recent performance. Between 2020 and 2025, the global market expanded from approximately 163.15 million USD to 215.0 million USD, reflecting steady adoption across therapeutic categories and sustained investment in patient-friendly formulations. This historical progression is not merely a sequence of annual increments; it reveals a structural inflection in how manufacturers approach dose design, commercialization pathways, and end-user compliance.
Looking forward, the forecast window spans 2026 through 2032, a period expected to deliver continued expansion at a compound annual growth rate of 8.5 percent. By the close of the projection horizon, market revenue is anticipated to surpass 344.8 million USD. These figures provide a macro foundation for resource allocation, capacity planning, and partnership strategy. More importantly, they signal that ODT adoption is transitioning from a niche convenience to a mainstream formulation preference, particularly where rapid disintegration, swallowing difficulty mitigation, and taste-masked delivery create measurable clinical and commercial value.
For 2026 decision-making, this growth trajectory matters because it frames the window of opportunity for first-mover advantage in emerging indications, regional commercialization, and manufacturing scale-up. Companies that align their pipeline priorities, contract manufacturing relationships, and dosing platform investments with this forecasted cadence will be better positioned to capture share as the market matures.
Segment Architecture: Where Value Is Being Created
The ODT landscape is not a monolith. Value creation is distributed across therapeutic classes, disease indications, and regional ecosystems, each carrying distinct adoption drivers, formulation challenges, and reimbursement dynamics. A 500 mg weight ceiling and a 30-second disintegration expectation, as defined in longstanding FDA guidance, remain active commercial constraints that shape formulation strategy and directly influence manufacturing feasibility.
Within drug class segmentation, the market reflects a diversified portfolio spanning central nervous system therapies, anti-epileptic treatments, and a broad category of additional indications that collectively drive volume. The distribution of revenue across these classes underscores how ODT technology has moved beyond a single therapeutic niche to become a cross-indication platform. Similarly, disease indication mapping reveals that CNS disorders represent the largest demand pool, followed by gastrointestinal conditions, cardiovascular disorders, and allergy-related formulations. This spread matters because each indication carries its own clinical urgency, prescribing patterns, and patient demographics, which in turn shape lifecycle management strategies and commercialization sequencing.
Regional dynamics further complicate the picture. North America, Europe, and Asia Pacific each present distinct pathways shaped by regulatory calendars, reimbursement architectures, manufacturing localization trends, and evolving standard-of-care expectations. Europe, for example, benefits from favorable reimbursement policies supporting chronic disease treatments, while North America remains a hub for formulation innovation and branded ODT launches. Asia Pacific reflects expanding manufacturing capacity and growing access to advanced dosage forms. Latin America and the Middle East and Africa, though smaller in relative scale, represent emerging adoption corridors where access, affordability, and supply chain flexibility increasingly determine market entry success.
Because these segmentation layers interact with pricing, bioequivalence requirements, and sourcing logic, a superficial read of regional or therapeutic shares can be misleading. The full study provides the structured comparisons necessary to identify where differentiation is genuinely achievable and where competition is likely to compress margins.
Regulatory and Operational Dynamics Shaping 2026
No ODT strategy is complete without accounting for the regulatory and operational environment that governs formulation choices, approval pathways, and commercial viability. In late 2025, the FDA revised product-specific guidance for Primidone Oral Tablet ODT and recommended product-specific guidance for Escitalopram Oxalate ODT, reinforcing standardized bioequivalence study expectations with and without water. These updates matter because they directly influence generic approval pathways, development timelines, and the design of comparative studies. For manufacturers pursuing ANDA filings or evaluating lifecycle extensions, the guidance landscape can accelerate or constrain entry strategies depending on how formulation parameters align with bioequivalence expectations.
Operational realities are equally important. Generic ODT production depends on disciplined cost control around excipients, with multi-supplier sourcing strategies increasingly viewed as essential to maintaining competitive pricing and supply continuity. Meanwhile, the broader industry continues to grapple with formulation limits, disintegration performance targets, and the need to balance patient experience with manufacturing throughput. These operational forces create a natural filter: companies that treat ODT development as a pure formulation exercise often miss the broader commercial equation involving sourcing resilience, scale-up economics, and regulatory timing.
Recent developments also highlight the pace of innovation entering the market. In 2026, Emalex Biosciences received a US patent for an ODT formulation of ecopipam and initiated process development for cGMP manufacturing targeted for late 2026 or early 2027. Such milestones illustrate how formulation IP, process readiness, and manufacturing sequencing now converge to determine commercial readiness. For competitive analysts and pipeline strategists, tracking these events provides early signals about which therapeutic categories may see new ODT entrants, where differentiation can be established, and how manufacturing bottlenecks could affect launch timing.
Competitive Landscape: Platforms, Capabilities, and Positioning
The ODT competitive field is defined by a mix of technology providers, contract manufacturers, branded product owners, and excipient specialists. Each player contributes a distinct layer to the value chain, and understanding their capabilities is essential for mapping partnership opportunities, outsourcing strategies, and competitive threats.
Catalent Pharma Solutions, based in Swindon, United Kingdom, manufactures Zydis orally disintegrating tablets with cGMP production exceeding 1.5 billion doses annually at dedicated facilities. This scale positions the company as a significant capacity and technology reference point for ODT manufacturing. Adare Pharma Solutions, headquartered in Chicago, Illinois, offers AdvaTab ODT technology designed to deliver rapid-disintegrating tablets that are bioequivalent to conventional formulations, an attribute directly relevant to regulatory navigation and product equivalence strategies.
LGM Pharma, operating in the United States, functions as a CDMO offering contract manufacturing of high-dose ODTs, including recent ANDA filings for complex formulations. Its work highlights the growing intersection between formulation complexity and contract manufacturing demand. Vitaquest, based in New Jersey, specializes in nutraceutical ODT manufacturing with custom formulations for supplements, illustrating how ODT technology extends beyond prescription pharmaceuticals into consumer health and wellness categories.
In Europe, Dec Group, based in Switzerland, manufactures ODTs using Lyopan technology in collaboration with Rohrer for rapid-disintegrating solid doses, while Roquette, located in Lestrem, France, supplies excipients and two-component platforms that simplify ODT formulation and manufacturing. These technology and material enablers demonstrate that competitive advantage increasingly depends on integrated formulation platforms rather than isolated manufacturing claims.
Otsuka Pharmaceutical, headquartered in Tokyo, Japan, continues to develop and market branded ODT products such as Abilify Discmelt and Abilify Maintena ODT, reflecting the strategic role of brand owners in shaping prescribing familiarity and patient acceptance. At the market structure level, concentration metrics indicate a moderately consolidated field: CR3 reaches 36.0 percent and CR5 reaches 48.0 percent. This distribution suggests that while leading players hold meaningful share, there remains sufficient fragmentation to support new entrants, specialized CDMOs, and niche formulation providers that can compete on speed, customization, or therapeutic focus.
The strategic implication for 2026 is clear. Companies must assess where they sit within this value chain and how they intend to compete. For CDMOs, differentiation may come from high-dose capability, bioequivalence support, or regulatory acceleration. For branded manufacturers, the priority may be lifecycle extension, patient adherence programs, and indication expansion. For excipient and technology providers, the opportunity lies in platform simplicity, supply resilience, and manufacturing compatibility. The report’s competitive analysis is designed to help each player identify the right leverage points.
Inside the Report: What Decision-Makers Will Gain
PW Consulting’s Orally Disintegrating Tablet Market study is built to translate macro trends into operational decision support. The report goes beyond headline figures to provide a structured, cross-referenced view of market size, growth drivers, segmentation logic, regulatory touchpoints, and competitive positioning. It is designed for teams that need to align commercial planning, R&D prioritization, manufacturing strategy, and investment decisions with a consistent evidence base.
Key components of the research include a detailed market size and forecast framework spanning the base year through the 2032 projection period, with historical context that clarifies the pace and composition of growth. The segmentation analysis maps demand across drug classes and disease indications while preserving enough analytical discipline to avoid oversimplified conclusions. Regional perspectives are integrated to show how reimbursement, access, and manufacturing localization affect adoption paths without reducing the discussion to static share tables.
The report also provides a competitive profiling section that situates major players within the value chain, highlighting technology platforms, manufacturing scale, formulation strengths, and strategic orientation. Recent developments are incorporated to connect market structure with live industry events, including patent activity, guidance updates, and manufacturing timelines that can alter near-term competition. In addition, the study addresses operational considerations such as excipient sourcing, weight and disintegration constraints, and the practical implications of bioequivalence study expectations.
For executive teams, these elements combine into a practical toolkit. Commercial leaders can use the forecast framework to test demand scenarios and prioritize indication expansion. R&D and formulation teams can reference the regulatory and technical discussion to anticipate development constraints and align platform decisions with approval pathways. Procurement and supply chain stakeholders can evaluate sourcing logic and capacity considerations in the context of cost control and flexibility. Investors and strategy teams can use the competitive and concentration analysis to assess where consolidation pressure is likely to intensify and where specialized capabilities may command premium positioning.
Strategic Takeaways for 2026 Planning
As 2026 unfolds, the ODT market offers a clear example of how patient-centric formulation strategy can translate into durable commercial relevance. Several themes should anchor enterprise planning.
- Growth is structural, not cyclical. The combination of historical momentum and an 8.5 percent CAGR through 2032 suggests that ODT adoption will continue to expand across multiple therapeutic and patient-access contexts, making formulation flexibility a long-term asset rather than a short-term tactic.
- Regulatory clarity shapes speed. Recent FDA guidance revisions and product-specific recommendations influence bioequivalence design, generic pathways, and development sequencing. Teams that integrate regulatory trajectory into early formulation decisions can reduce downstream rework and accelerate commercialization readiness.
- Operational discipline determines margin resilience. With formulation weight limits, disintegration targets, and excipient sourcing requirements in play, competitive advantage increasingly depends on manufacturing efficiency, supplier flexibility, and cost-aware design.
- Platform capability outweighs one-off scale. The presence of multiple technology providers, CDMOs, and excipient specialists indicates that integrated formulation platforms and process readiness are becoming central to differentiation, especially for complex or high-dose products.
- Concentration leaves room for targeted positioning. With a moderately consolidated market structure, there is meaningful space for specialized players that can serve specific indications, formulation challenges, or regional access needs without attempting to compete solely on scale.
These themes point toward a practical conclusion: the organizations that will capture the most value in the ODT market are those that treat dosage form strategy as a multi-dimensional business decision, connecting clinical need, regulatory risk, manufacturing feasibility, and competitive positioning into a single coherent plan.
Conclusion: From Market Intelligence to Actionable Strategy
The Orally Disintegrating Tablet Market is entering a phase where informed strategic choices will separate scalable growth from marginal participation. Themacro trajectory, segmentation diversity, regulatory dynamics, and competitive structure described in this preview reflect a market that is both expanding and maturing. That combination creates opportunity, but only for teams equipped with detailed, current, and operationally relevant intelligence.
PW Consulting’s full market research is designed to provide that level of clarity. It translates broad growth signals into segment-level logic, regulatory context, competitive mapping, and development-ready insight, enabling decision-makers to move from awareness to action with confidence. For organizations planning 2026 pipeline prioritization, manufacturing partnerships, regional expansion, or competitive responses, the complete study offers the depth required to support decisive strategy.
To access the full forecast framework, segmentation analysis, competitive profiles, and operational insights, request the complete Orally Disintegrating Tablet Market report and integrate its findings directly into your 2026 strategic planning process.
Orally Disintegrating Tablet Market
Worldwide Oral Solid Dosage Medicine Market
For detailed analysis of this topic, please visit the official page: Orally Disintegrating Tablet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Booster Pump Market to Hit 226 Million in 2025, Projected 4.45% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Booster Pump Market: Navigating Growth from 2026 to 2032
The global infrastructure landscape is undergoing a fundamental recalibration, driven by urbanization, industrial expansion, and tightening regulatory frameworks. At the heart of water distribution and pressure management lies a critical mechanical component: the booster pump. As enterprises plan capital expenditures and supply chain strategies for the coming years, precise market intelligence is no longer a luxury but a necessity. PW Consulting presents a comprehensive analysis of the Booster Pump Market, designed to equip stakeholders with actionable data for decision-making in 2026 and beyond.
This market research serves as a strategic blueprint for navigating a sector characterized by steady consolidation and technological evolution. By examining historical trajectories and forecasting future demand, this report clarifies where value is being created and where risks are emerging. The following insights excerpt from our full study highlight the market's financial architecture, competitive intensity, and the regulatory currents shaping the industry.
Market Trajectory and Financial Framework
Understanding the scale and velocity of the booster pump market is essential for allocating resources effectively. Over the historical period from 2020 to 2025, the market demonstrated resilience and moderate expansion, reflecting steady global demand for water pressure solutions. The assessed market size reached 226.0 million USD in the 2025 base year, building upon a foundation established during the post-pandemic recovery phase. This growth underscores the essential nature of booster pump systems in maintaining infrastructure reliability across residential, commercial, and industrial sectors.
Looking forward, the forecast period spanning 2026 to 2032 projects a continued expansion trajectory. Market valuation is expected to ascend to approximately 228.88 million USD in 2026, reflecting the immediate year-over-year momentum. The compound annual growth rate during this forecast window is calculated at 4.45 percent. This steady CAGR suggests a mature yet growing market environment where incremental efficiency gains and replacement cycles drive volume, rather than explosive speculative demand. By 2032, the financial scope of the market is projected to reach 306.47 million USD. This long-term valuation provides a critical benchmark for stakeholders modeling ROI on manufacturing capacity or distribution network expansions.
Water Pumps Market
The financial data indicates a market that is not only growing but also stabilizing around predictable performance metrics. For investors and manufacturers, this reduces volatility risk. For procurement officers, it offers a clearer basis for budget forecasting. However, these top-level figures represent only the aggregate view. The distribution of this value across different technological types, application verticals, and geographic regions reveals distinct pockets of opportunity that are critical for targeted strategy.
Competitive Landscape and Strategic Positioning
The booster pump industry is defined by a mix of established global players and specialized manufacturers focusing on niche applications. Market concentration is moderate, with the top three players holding a combined share of 24.6 percent and the top five accounting for 31.8 percent of the market. This fragmentation implies that while dominance by major corporations exists, there is ample room for specialized competitors to thrive through customization and regional service excellence.
Key industry participants include Grundfos, headquartered in Denmark, which stands as a full-range manufacturer of energy-efficient booster pumps and packaged systems for residential, commercial, and industrial water pressure boosting. In the United States market, several firms hold significant positioning. US Pump Corp operates as a custom intelligent booster pump system manufacturer offering simplex to multi-pump configurations for commercial, industrial, irrigation, and domestic applications. Similarly, Nickerson Company serves as a supplier and installer of packaged booster pump systems with in-house repair services for municipal and commercial water pressure boosting.
Towle-Whitney contributes to the market as a manufacturer of simplex, duplex, and triplex water booster pump systems and digital mixing valves for residential to commercial and institutional use. Penn Pump & Equipment Company operates as a custom manufacturer and distributor of water pressure booster systems, variable-speed pumping packages, and related pumping equipment. Walrus of America supplies centrifugal booster pumps and plug-and-play replacement systems for residential, commercial, and OEM booster applications. Pentair provides high-pressure booster pumps and packaged booster systems under the Sta-Rite and Berkeley brands for residential and commercial use.
Further strengthening the competitive field, Gorman-Rupp Company manufactures centrifugal, submersible, and booster pump stations for municipal, industrial, and commercial water pressure boosting. Xylem offers domestic and commercial booster pump systems with digital connectivity options for high-rise and residential buildings. Wilo SE, based in Germany, manufactures compact domestic and commercial booster pumps with energy-efficient and smart control features. APEC Water Systems focuses on high-pressure reverse osmosis booster pumps for household and light commercial water pressure boosting. Finally, Franklin Electric supplies multi-stage water pressure booster pumps and VersaBoost Pro smart systems for residential and multi-unit applications.
Recent developments illustrate the dynamic nature of this competitive field. In March 2026, Duke Pumping Solutions launched a domestic vertical multistage booster pump series with DIN flange standards and steady flow performance. Following ASPE Tech Symposium discussions, Towle-Whitney introduced the TW2018W series variable-speed booster pump systems in April 2026. Pentair released an updated January 2025 list prices for high-pressure booster pumps and systems, signaling pricing adjustments relevant to procurement planning. Additionally, Gorman-Rupp completed the installation of a custom water booster pump station in Blaine, PA, in April 2026, while Islamorada Village issued RFP 26-05 for the upgrade of the North Plantation Key booster pump station, including demolition, new construction, and full commissioning. These events highlight the continuous cycle of product innovation and infrastructure investment driving the market.
Regulatory and Technical Dynamics
The market environment is heavily influenced by regulatory standards and technical specifications that dictate performance requirements and installation protocols. Compliance is not merely a legal obligation but a strategic differentiator for manufacturers offering certified solutions. In the United States, the New Jersey Administrative Code requires public community water systems to maintain a minimum pressure of 20 psi at street level. This regulation directly impacts the specification and sizing of booster pump systems in public infrastructure projects within the state.
Technical standards also play a pivotal role. The AWWA E102 standard updates for submersible vertical turbine pumps remain active for booster applications, guiding engineering choices for durability and efficiency. Furthermore, the Phius Water Pressure Booster Pump Estimator, released in July 2024, aids in residential energy use calculations for buildings over four stories, integrating energy performance into the design phase. These tools are becoming essential for engineers and architects aiming to meet sustainability goals.
Industry engagement continues to drive knowledge exchange. The AWWA Annual Conference & Expo is scheduled for June 21-24, 2026 in Washington, D.C., covering booster pump technologies. Such gatherings provide a forum for unveiling new standards and network-building. It is important to distinguish relevant regulatory shifts from noise in the broader consumer safety landscape. For instance, CPSC bicycle helmet recalls issued in June 2026 for non-compliant impact attenuation are unrelated to water booster pumps, yet they serve as a reminder of the broader compliance environment in which industrial manufacturers operate.
Operational Intelligence and Report Contents
To fully leverage the data outlined above, decision-makers require granular detail that goes beyond high-level trends. This report provides an in-depth examination of the segmentation structures that define revenue streams. It analyzes the breakdown of the market by product type, evaluating the dominance of centrifugal designs against reciprocating, rotary, and other specialized configurations. The study also dissects application verticals, providing visibility into how demand varies between water supply networks, industrial processes, agricultural operations, and other end-use scenarios.
Geographic analysis is another cornerstone of this research. The report delineates market performance across key regions, including North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region presents unique drivers, from infrastructure aging in developed economies to rapid urbanization in emerging markets. Understanding the relative weight and growth potential of these regions allows companies to prioritize market entry or expansion strategies.
Furthermore, the study incorporates a detailed competitive benchmarking analysis. It profiles the strategies, product portfolios, and financial health of key companies such as Grundfos, Pentair, and Xylem, among others. This section helps identify gaps in the market that competitors may be missing and highlights best practices in supply chain management and technology adoption. The report also includes a forecast model that extends through 2032, enabling sensitivity analysis for various economic scenarios.
Procurement decision-makers will find specific value in the sections dedicated to pricing trends and raw material cost dynamics. By correlating recent industry developments, such as the product launches by Duke Pumping Solutions and Towle-Whitney, with broader market pricing structures, the report offers a realistic view of cost pressures and margin opportunities. The inclusion of recent contract awards and RFPs, like the Islamorada Village project, provides real-world context for demand velocity in specific municipal segments.
Strategic Implications for 2026 Decision-Making
As we move deeper into 2026, the strategic imperative for booster pump market participants is to balance steady growth with technological agility. The market's projected growth to 306.47 million USD by 2032 suggests that scale will remain a viable path to profitability, but only for those who can navigate the moderate concentration of the top players. The 4.45 percent CAGR indicates that success will likely come from capturing share in specific high-growth segments rather than relying solely on overall market lift.
Energy efficiency and digital connectivity are emerging as key differentiators. With regulations like the Phius estimator influencing building design and standards like AWWA E102 guiding pump selection, manufacturers who integrate smart control features and energy-efficient designs into their commercial and residential offerings will be better positioned to capture premium segments. Companies like Grundfos and Wilo SE are already emphasizing these attributes, setting a benchmark for the rest of the industry.
Supply chain resilience and customization capabilities, showcased by firms like US Pump Corp and Penn Pump & Equipment Company, are also critical. As municipal and industrial clients seek tailored solutions for complex pressure boosting needs, the ability to deliver custom configurations without compromising lead times will be a significant competitive advantage. The recent installation activities by Gorman-Rupp and the RFP activities in regions like Florida suggest that infrastructure renewal projects are ongoing and present immediate revenue opportunities.
For investors, the moderate market concentration suggests a landscape where mergers and acquisitions could reshape the top tier, while organic growth remains strong in the mid-tier. For manufacturers, the focus must be on aligning product development with the regulatory and technical demands of the forecast period. For distributors, understanding the regional disparities in market size and growth potential is key to optimizing inventory and sales efforts.
Conclusion
The Booster Pump Market stands at a juncture where steady historical growth meets a future defined by regulatory precision and technological integration. The financial outlook supports confidence, but the details of segmentation, competition, and regional dynamics hold the keys to unlocking specific value. This report from PW Consulting provides the comprehensive intelligence required to navigate these complexities. It transforms raw data into strategic narratives, helping stakeholders identify where to invest, how to compete, and when to act.
Booster Pump Market
To access the complete dataset, including detailed segmentation percentages, regional revenue breakdowns, and full company profiles, we invite you to review the full market research report. The complete analysis offers the depth necessary for precision planning in 2026 and beyond. Ensure your strategy is built on the most robust intelligence available by accessing the full source material today.
For detailed analysis of this topic, please visit the official page: Booster Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Data Center Busway Market Reaches $215M in 2025, 9% CAGR Forecast to 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the AI Power Era: Inside the 2026 Data Center Busway Market Report
The global data center landscape is undergoing a structural transformation driven by the exponential power demands of artificial intelligence workloads. As hyperscale campuses expand and enterprise facilities retrofit for higher density, the infrastructure delivering power within the white space has become a critical bottleneck and a strategic differentiator. Our latest market research on the Data Center Busway Market provides the rigorous intelligence required to navigate this shift through 2032.
This document serves as a strategic preface to our comprehensive study. It outlines the macro trajectory, the competitive velocity, and the operational imperatives defining the sector. For executives responsible for capital allocation, infrastructure design, or supply chain resilience, the findings herein offer a decision-ready framework. However, the true depth of our analysis—down to granular segmentation drivers, regional procurement patterns, and proprietary risk matrices—is reserved for the full report, ensuring that organizational leaders possess the exclusive context needed to outperform the market curve.
The Macro Trajectory: Scaling from 215 Million to 344.8 Million
The market has demonstrated consistent upward momentum, evolving from a global revenue base of 163.15 million in 2020 to a projected 215.0 million in 2025. This growth reflects a sustained compound annual growth rate of 9.0 percent across the historical window, signaling that busway systems have transitioned from niche alternatives to mainstream power distribution standards.
Looking forward, our forecast model indicates that this momentum will sustain and accelerate. We project the market to reach 231.33 million in 2026, climbing to 253.41 million by 2027 and continuing toward 344.8 million by 2032. This trajectory is not merely a function of data center construction volume. It represents a fundamental shift in how power is routed within modern facilities. Traditional cabling architectures struggle to accommodate the spatial constraints and thermal profiles of high-density AI racks, making modular, plug-in busway systems the preferred engineering solution for scalable white-space optimization.
Busway-Bus Duct Market
For strategic planners, the implication is clear: the window for standardizing busway architectures at the design phase is narrowing. Organizations that delay infrastructure specification decisions risk higher retrofit costs and compatibility friction as facility density targets escalate. Our full report dissects the velocity of adoption across deployment stages, providing the sensitivity analysis required to model total cost of ownership under varying capacity expansion scenarios.
Operational Dynamics: Material Costs, Regulation, and AI Density
The market does not evolve in a vacuum. Three concurrent dynamics are reshaping procurement strategy and product selection criteria. Understanding their interplay is essential for accurate budgeting and risk mitigation.
-
Raw Material Volatility and Conductor Economics: Copper prices surged to 15-month highs in 2025, driven by supply chain disruptions and intensifying data center demand. This spike directly impacts the material cost structure of busway systems. In response, engineering teams are increasingly evaluating aluminum conductor options, which reduce weight and installation labor compared to copper in high-density deployments. The decision between copper and aluminum is no longer purely technical; it is a financial optimization problem tied to capacity planning cycles and local labor economics.
-
Regulatory Compliance and Infrastructure Upgrades: The EU Energy Efficiency Directive now requires data center operators to upgrade infrastructure, including busway replacement for compliance. This regulatory pressure transforms busway procurement from an operational upgrade into a compliance mandate in specific jurisdictions. Furthermore, UL listing requirements for specialized busway configurations ensure mission-critical reliability, adding a quality assurance layer that influences vendor selection and deployment timelines.
-
Hyperscale AI Construction and High-Ampacity Demands: The construction of hyperscale AI data centers is driving demand for high-ampacity busway systems exceeding 4000A. Traditional busway architectures rated for lower current thresholds are becoming obsolete in front-tier AI deployments. This shift pushes manufacturers to innovate in cross-sectional design, cooling integration, and tap-off modularity to support the power density profiles that AI training and inference clusters require.
These dynamics create a complex procurement environment. A decision that appears cost-effective on a per-meter basis may carry hidden integration risks or compliance gaps. Our report provides a structured evaluation matrix to assess these variables against your specific deployment profile, ensuring that procurement decisions align with both financial targets and operational resilience requirements.
Competitive Landscape: Innovation Velocity Among Market Leaders
The Data Center Busway Market operates with a measured concentration profile. The combined market share of the top three competitors stands at 24.6 percent, while the top five reach 26.2 percent. This relatively fragmented structure among leading players indicates that scale alone does not guarantee dominance. Instead, competitive advantage is increasingly derived from product-specific engineering, ecosystem integration, and speed of response to AI-driven specification changes.
Our analysis identifies a cohort of strategic players whose recent developments illustrate the direction of innovation:
-
Schneider Electric continues to advance the integration of power distribution with cooling and modular construction. The November 2025 launch of new EcoStruxure Pod Data Center solutions featuring high-power busway integrated with liquid cooling and prefabricated modules signals a shift toward turnkey AI cluster deployments. At Data Center World 2026, the company reinforced this trajectory with a booth showcasing NetShelter Power Shelf and busway integration for 48V AI systems, indicating an expansion into lower-voltage, high-efficiency architectures.
-
Vertiv has focused on scalable capacity within tight spatial footprints. The March 2026 announcement of a scalable high-capacity double-stack PowerBar Track busway system addresses growing AI data center demands while preserving white space. With PowerBar Track and double-stack busway systems supporting up to 2500A with copper and aluminum options and toolless tap-offs, Vertiv is positioning for rapid deployment cycles where installation efficiency matters as much as raw ampacity.
-
Eaton Corporation maintains a strong emphasis on modular flexibility. The Pow-R-Way III and PowerWave 2 track-style busway systems with modular tap-off enable scalable white-space and high-density power distribution. The company’s April 2026 presence at Data Center World 2026, showcasing modular data center solutions including busway power distribution, underscores a strategy aligned with facilities that require granular power zoning and future-proof expansion paths.
-
ABB Ltd offers the Lmax-T low-voltage busway systems with integrated protection, metering, and monitoring for data center server room distribution up to 86 kW per rack. This integrated approach appeals to operators seeking to reduce the number of discrete components in the power chain, streamlining maintenance and improving visibility at the rack level.
-
Siemens AG has pursued aluminum-based busway systems with smart monitoring for high-density AI data centers, complemented by strategic partnerships in power distribution. This playbook combines material efficiency with digital observability, enabling operators to monitor load profiles and thermal performance within the busway infrastructure itself.
-
LS Cable & System has introduced Data-way busway with modular plug-in taps and UL listing for high-capacity AI and energy-efficient data center power distribution. The UL listing provides a compliance anchor for mission-critical deployments, while the modular tap architecture supports rapid reconfiguration as rack densities evolve.
-
Legrand continues to provide data center busway solutions for modular power distribution in mission-critical facilities, emphasizing reliability and integration compatibility with broader facility management ecosystems.
-
nVent offers custom medium- and high-voltage bus systems for industrial and data center power applications, addressing operators whose power distribution needs extend beyond standard low-voltage architectures.
-
EAE Electric provides busway systems up to 6300A with data center-specific solutions for power distribution, targeting high-capacity deployments that demand robust current handling within a single busway run.
The competitive landscape is characterized by rapid product iteration and a clear focus on AI-specific requirements. Participation at events like Data Center World 2026 reflects a market where specification cycles are compressing and operators demand vendor responsiveness. Our report includes a comparative assessment of these players across product breadth, integration capabilities, and regional reach, enabling you to align vendor shortlists with your specific architectural and compliance requirements.
What Our Report Delivers: From Macro Trends to Actionable Intelligence
The full Data Center Busway Market research is structured to support decision-making at multiple organizational levels. Beyond the aggregate market sizing and growth projections, the study provides the operational granularity needed to translate market intelligence into procurement, design, and partnership strategies.
Key components of the analysis include:
-
Segmentation Architecture: A detailed breakdown of the market by system type, including three-phase five-wire configurations, three-phase four-wire variants, and other specialized formats. This segmentation reveals which architectures are gaining preference in specific deployment contexts and how design trade-offs influence adoption rates across different facility classes.
-
Application-Specific Demand Profiles: Analysis of demand patterns across hyperscale data centers, colocation facilities, and enterprise data centers. The study examines how power density targets, space constraints, and operational models differentiate the busway requirements of each segment, enabling you to benchmark your infrastructure plans against prevailing industry practices.
-
Regional Dynamics and Procurement Patterns: A geographic assessment that contextualizes demand drivers, regulatory environments, and supply chain maturity across major markets. This analysis supports multi-region expansion planning and helps identify regions where local content requirements or logistics considerations may influence vendor selection and lead-time expectations.
-
Competitive Benchmarking and Development Tracking: In addition to the profiles of the leading manufacturers, the report tracks recent product launches, trade show participations, and strategic moves that signal shifts in competitive positioning. This timeline of developments enables you to anticipate market evolution rather than react to it.
-
Risk and Cost Sensitivity Analysis: Structured evaluation of material price exposure, compliance timelines, and installation complexity factors. These insights help quantify the financial implications of different busway specification choices and support more accurate capital planning.
The report is designed to be actionable. Each section connects market data to operational implications, ensuring that technical leaders, procurement teams, and executive stakeholders can extract relevant insights without sifting through undifferentiated statistics.
Data Center Busway Market
Strategic Takeaways for 2026 Decision-Makers
As you evaluate your infrastructure roadmap for the remainder of 2026 and beyond, several priorities emerge from the market evidence:
-
Design for density, not just capacity. The shift toward AI workloads means that spatial efficiency and tap-off flexibility are as critical as raw ampacity. Busway architectures that support rapid reconfiguration and toolless connections will reduce deployment friction as rack layouts evolve.
-
Model material risk explicitly. Copper volatility and the availability of aluminum alternatives introduce cost variance into busway procurement. Incorporating conductor economics into your total cost of ownership models will improve budget accuracy and reveal scenarios where aluminum-based systems offer superior lifecycle value.
-
Align vendor evaluation with integration depth. The market leaders are increasingly competing on integrated monitoring, cooling compatibility, and modular shelf systems rather than busway conductors alone. Your vendor shortlist should reflect the degree to which you require ecosystem integration versus standalone power distribution.
-
Anticipate compliance-driven replacement cycles. In regions subject to energy efficiency mandates, busway replacement may transition from discretionary upgrade to regulatory requirement. Planning for compliance timelines now avoids rushed procurement and premium pricing later.
-
Access the full intelligence to de-risk capital decisions. While this overview establishes the market direction and competitive context, the complete report provides the segmented data, regional breakdowns, and scenario modeling necessary to finalize specifications, negotiate with vendors, and secure supply chain commitments.
The Data Center Busway Market is entering a phase where engineering precision, regulatory foresight, and vendor agility converge to define competitive advantage. Our report delivers the comprehensive intelligence required to navigate that convergence with confidence. To access the full analysis, including detailed segmentation insights, regional procurement patterns, and proprietary risk matrices, we invite you to explore the complete study on our platform.
For detailed analysis of this topic, please visit the official page: Data Center Busway Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Soy Sauce Market Hits $41.05B in 2025, Poised for 5.4% CAGR Through 2032
By pmarketresearch, 2026-09-15
Global Soy Sauce Market Strategic Outlook: Navigating Growth, Supply Chains, and Competitive Dynamics Through 2032
The global soy sauce market stands at a pivotal juncture. As consumer tastes diversify across culinary traditions, food manufacturers scale premiumization strategies, and raw material supply chains face renewed macroeconomic pressure, the category is evolving from a staple condiment into a structured, data-driven industry arena. For executives operating in food manufacturing, distribution, or ingredient procurement, understanding the trajectory of soy sauce demand is no longer a niche exercise. It is a strategic imperative.
Our latest market research initiative delivers a comprehensive, forward-looking analysis of this landscape. Designed for decision-makers who require actionable intelligence rather than superficial summaries, the study traces performance from historical baselines through a detailed forecast window, examining where value is created, how competitive advantages are shifting, and which structural forces will dictate profitability in the years ahead. This article offers a strategic preview of the report's analytical framework and explains why its findings are positioned to support high-stakes corporate planning throughout 2026.
Macro Trajectory and Strategic Implications
The market has demonstrated sustained expansion over the recent historical period, with revenue climbing steadily from approximately 29.95 billion USD in 2020 to 35.74 billion USD in 2023, before reaching an estimated 41.05 billion USD in 2025. This progression reflects more than nominal growth; it signals deepening penetration, rising unit values in premium categories, and sustained institutional demand across both household and commercial channels. The forecast horizon carries forward this momentum with a compound annual growth rate of 5.4 percent, positioning the market at 44.69 billion USD in 2026 and advancing toward the upper echelon of the high 50 billion USD range by the close of the projection window in 2032.
For corporate strategists, this trajectory carries several operational implications. A steady mid-single-digit growth profile suggests a maturing but still expandable category where incremental share gains require deliberate positioning rather than passive tailwinds. The sustained upward path also indicates that demand is not solely tethered to population growth in traditional markets; rather, it is being reinforced by product innovation, format diversification, and the continued globalization of Asian culinary influence. Officers tasked with capacity planning, brand portfolio management, or channel expansion should treat this overarching trend as a foundational input, while recognizing that underlying momentum varies meaningfully across segments and geographies. Our research isolates those variations so leadership can allocate resources where marginal returns are highest.
What the Report Delivers: Operational Intelligence for 2026 Decision-Making
This study was constructed to function as a working document for strategy, procurement, and commercial teams. Rather than stopping at headline numbers, the report breaks down the market architecture across multiple dimensions that matter directly to execution. Readers will find structured coverage of:
- Segment-Level Performance: Detailed assessments of product type categories, including light and dark soy sauce as well as other variants, with analysis of how each format's utility, flavor profile, and price positioning shape its respective demand curve. Household, food industry, and foodservice applications are examined separately, allowing executives to map consumption behavior to channel strategy and packaging decisions.
- Regional Dynamics: Geographic evaluation of how mature markets, high-growth regions, and emerging trade corridors contribute to total revenue. The analysis considers local culinary traditions, distribution maturity, import-export flows, and the interaction between regional purchasing power and product premiumization.
- Competitive Benchmarking: A focused examination of leading manufacturers and emerging innovators, covering operational scale, manufacturing footprints, export capabilities, and strategic moves that alter market positioning. This includes attention to facility expansion, brand architecture, and the competitive signaling evident in flagship product launches and trade presence.
- Cost and Input Environment: Assessment of the raw material backdrop, including soy commodity pricing trends and their implications for manufacturing cost structures, margin planning, and supplier negotiation timelines.
- Regulatory and Labeling Landscape: Comparative review of classification rules, GMO labeling obligations, and nutritional disclosure requirements across key jurisdictions, helping compliance and market-entry teams anticipate labeling burdens and consumer communication constraints.
- Strategic Scenarios and Forward Indicators: Synthesis of the data into decision-ready frameworks that translate market movement into potential strategic responses, including capacity timing, premiumization pacing, channel prioritization, and geographic expansion sequencing.
Each section is designed to connect directly to operational questions. Procurement leaders can reference the input-cost discussion to align hedging and sourcing windows. Commercial teams can use the segment and application breakdown to refine SKU strategy and packaging formats. Corporate development groups can leverage the competitive and regional analysis to identify where acquisition, partnership, or organic entry offers the most defensible positioning.
Competitive Landscape: Scale, Specialization, and Strategic Posture
The industry is shaped by a blend of large multinational producers, regionally dominant manufacturers, and specialized innovators pursuing differentiated flavor profiles. The concentration pattern reflects a market where scale advantages in brewing capacity, distribution reach, and brand recognition provide meaningful defensive moats, while differentiation in formulation, sourcing story, and premium positioning opens pockets of high-margin growth.
Among the most prominent players, Kikkoman Corporation continues to anchor its global footprint through a long-standing commitment to traditionally brewed production. With major facilities in the United States and a consistent export presence, the company's manufacturing expansion in its home region and overseas reflects a strategy of aligning supply capability with demand growth in key destination markets. Its planned first shipments from a new Wisconsin production facility in fall 2026 underscore the kind of capacity timing that can influence regional availability, cost competitiveness, and brand visibility well into the forecast period.
Foshan Haitian Flavouring and Food Co., Ltd. and Pearl River Bridge represent substantial production and distribution strength within China and broader Asian markets, with product portfolios extending across soy sauce and seasonings. Their scale in domestic channels and expanding international reach makes them central reference points for understanding how regional manufacturers compete on both volume and formulation variety. Lee Kum Kee Company Limited pursues a different strategic emphasis, concentrating on premium, naturally brewed varieties with worldwide distribution. This premium-oriented posture highlights the commercial opportunity that arises when brand narrative and product quality are aligned with global consumer curiosity about authentic condiment craftsmanship.
Yamasa Corporation and Shibanuma Soy Sauce Co., Ltd. further enrich the competitive picture by demonstrating the enduring relevance of specialized fermentation expertise. Their focus on naturally fermented products and established export channels illustrates how traditional production methods can be leveraged as differentiation assets in markets that reward authenticity and-consistency in flavor. At the opposite end of the scale spectrum, Bourbon Barrel Foods exemplifies a niche innovation pathway: microbrewed, barrel-aged soy sauce produced in repurposed bourbon barrels creates a distinct sensory profile that appeals to enthusiast buyers and specialty channels. While small relative to mass-market producers, such innovators signal an important structural truth about the category: differentiation in process and flavor story can command premium positioning even in a mature category.
These competitive postures do not exist in isolation. Recent activity illustrates how companies are using facility expansion, trade presence, and product visibility to reinforce market position. Kikkoman's U.S. facility milestone, with first shipments slated for fall 2026, represents a capacity event with implications for regional supply reliability and brand accessibility. Separately, broader trade activity in early 2026 highlighted the continued showcasing of leading Chinese soy sauce brands across light, dark, and standard varieties, reflecting the ongoing importance of trade platforms as both distribution touchpoints and competitive signaling arenas. Together, these movements suggest a landscape where incumbents defend share through scale and brand equity while challengers pursue differentiation through formulation, packaging, and channel specialization.
Soy Sauce Market
Market Dynamics and Structural Forces Shaping the Forecast Period
Several intersecting dynamics will influence how the projected growth materializes across segments and regions. Raw material economics sit at the center of cost planning. With USDA projections indicating a higher season-average farm price for soybeans ahead, manufacturers and private-label suppliers will need to monitor input-cost trajectories carefully as they set pricing, negotiate contracts, and evaluate margin protection strategies. The direction of soybean pricing can cascade into formulation cost planning, especially for producers operating on thinner margins or those dependent on domestic agricultural supply chains.
Regulatory variation across markets adds another layer of strategic complexity. Classification and labeling rules are not uniform, and the differences matter for product positioning, packaging design, and market-entry sequencing. In the United States, soy sauce is exempt from GM food labeling requirements, and nutritional labeling is not required for soy sauce products, creating a comparatively streamlined compliance environment for domestic production and imported goods sold into that market. By contrast, Taiwan classifies soy sauce as a deeply processed product and requires GMO food labeling, illustrating how the same category can face materially different disclosure obligations depending on jurisdiction. These contrasts matter for companies managing multi-market portfolios, because labeling burden, consumer communication norms, and supplier documentation expectations can differ even when the underlying product is identical.
Beyond input costs and regulation, demand-side shifts continue to reshape commercial strategy. The growing visibility of Asian cuisine in global foodservice and retail environments supports sustained interest in condiment authenticity, while premiumization trends encourage brand investment in brewing narratives, ingredient sourcing, and flavor complexity. At the same time, foodservice and industrial applications introduce volume-based demand that responds to menu innovation, institutional procurement cycles, and supply reliability. The interplay between household purchasing, food industry ingredient demand, and foodservice usage creates multiple pathways for growth, but those pathways are not equally attractive in every region. Our analysis separates these channels so that commercial leaders can match product formats, packaging sizes, and promotional strategies to the environment where they will perform best.
Soy Milk Market
Supply-side logistics also warrant attention. As production footprints expand and export flows intensify, distribution reliability, lead-time management, and regional inventory positioning become increasingly important determinants of market performance. The ability to align manufacturing capacity with demand concentration, while maintaining cost discipline amid variable input prices, will likely separate stronger operators from those that struggle to convert top-line growth into durable margin improvement.
Why This Research Matters for 2026 Strategy
Decision-makers entering 2026 need more than a retrospective snapshot. They need a structured view of where momentum is building, which competitive moves are reshaping positioning, and how external forces such as commodity pricing and regulatory variation will influence execution. This report is built to supply that view. It connects market-scale trajectory to the operational realities of segment differentiation, regional variation, input-cost exposure, and competitive behavior, enabling leadership teams to ground strategic choices in evidence rather than assumption.
For CEOs and division heads, the study offers a context for portfolio prioritization and geographic focus. For commercial and brand leaders, it provides a basis for SKU planning, premiumization pacing, and channel allocation. For procurement and supply chain executives, it frames input-cost planning and supplier strategy against a quantified demand backdrop. For corporate development teams, it highlights where scale, differentiation, and regional penetration create attractive points of entry or partnership.
The full report extends well beyond this overview. It contains the detailed segmentation data, regional assessments, competitive profiles, and scenario-level analysis that executives require to convert market intelligence into concrete action. Readers seeking the complete quantitative breakdown, granular segment evaluations, and the full set of strategic recommendations are encouraged to access the full publication through our official research portal, where the complete dataset and supporting analysis are available. In a market advancing steadily toward the high 50 billion USD range by 2032, the organizations that move earliest with informed, well-structured strategy will be best positioned to capture the value this growth creates.
For detailed analysis of this topic, please visit the official page: Soy Sauce Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com