

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Disposable Gloves Market to Hit $31.69B in 2025, Growing at 8.7% CAGR to 2032
By pmarketresearch, 2026-09-15
Toward a Resilient Supply Chain: Strategic Insights from the 2026 Disposable Gloves Market Research
The global disposable gloves market has transitioned from a crisis-driven demand surge to a mature, structurally complex growth environment. As enterprises recalibrate procurement strategies, capacity plans, and sustainability commitments for the 2026–2032 horizon, the need for granular, forward-looking intelligence has never been more acute. Our latest market research publication dissects the competitive, regulatory, and operational forces shaping this essential category of personal protective equipment and industrial consumables.
Built on a rigorous historical reconstruction spanning 2020 through 2025 and a forward-modeled forecast extending to 2032, this study translates high-level market trajectories into actionable decision frameworks. The research is designed for procurement leaders, supply chain architects, product strategists, and corporate development teams seeking to navigate an increasingly polarized landscape—one defined by persistent capacity overhang, divergent regional cost structures, accelerating sustainability mandates, and intensifying product differentiation.
The Macro Trajectory: Growth Punctuated by Structural Tension
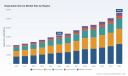
The surface narrative of the disposable gloves market is deceptively straightforward. From a 2020 baseline that reflected the early stages of pandemic-era procurement shocks, the market has expanded through a sustained upward arc, reaching a 2025 valuation of approximately 31.7 billion USD. The forecast period projects continued expansion, with the market expected to surpass 33.4 billion USD in 2026 and climb steadily toward 56.8 billion USD by 2032.
The implied compound annual growth rate of 8.7 percent positions disposable gloves above many adjacent industrial and healthcare consumables categories. Yet this headline figure belies the strategic complexity underneath. Growth is no longer a uniform tide lifting all manufacturers and end-users. Instead, it is being reshaped by a combination of oversupply dynamics, regional pricing asymmetries, material-specific substitution patterns, and compliance-driven procurement requirements that vary significantly across healthcare, industrial, and food service verticals.
Capacity Versus Demand: The Persistent Oversupply Equation
One of the most consequential structural themes for 2026 decision-making is the widening gap between global production capacity and realized demand. Industry analysis indicates that cumulative glove production capacity is on a trajectory to exceed 500 billion pieces annually within the next two years, while demand is estimated at roughly 400 billion pieces. This imbalance has direct implications for pricing strategies, inventory management, contract negotiations, and supplier diversification.
For procurement and sourcing teams, oversupply is not simply a short-term cost tailwind. It creates a bifurcated negotiation environment in which volume discounts, long-term supply agreements, and service-level commitments can be restructured—but only if organizations possess the operational readiness and supplier intelligence to act. For manufacturers, the same dynamic raises urgent questions about utilization rates, product mix optimization, and the economics of incremental capacity investment. The research unpacks how leading players are responding to this reality through material specialization, regionalized supply chains, and higher-value product architectures.
Regional and Cost Asymmetries in a Globalized Market
The disposable gloves market remains highly globalized, with production concentrated across a limited set of manufacturing hubs and demand distributed across diverse regulatory and clinical environments. This geographic tension is especially pronounced in the United States, where domestically produced, FDA-registered medical gloves carry distinct cost structures compared with imported alternatives. Labor cost differentials are substantial: foreign manufacturers in established production centers can offer disposable gloves at average prices as low as 0.02 USD per glove, while U.S.-based producers face significantly higher wage expectations.
Recent trade policy developments further complicate procurement planning. For example, U.S. Customs and Border Protection modified its Withhold Release Order in late 2024, lifting detention measures on certain disposable gloves produced in Malaysia provided that companies comply with other applicable trade laws. These regulatory adjustments, combined with the operational realities of validated production facilities, fair-wage employment commitments, and domestic manufacturing incentives, create a nuanced sourcing landscape. Organizations that rely on simplistic lowest-price heuristics risk exposure to compliance volatility, quality inconsistency, and supply continuity disruptions.
What the Research Delivers: A Practical Toolkit for Strategic Action
This study is engineered to move beyond macro-level commentary and provide decision-ready structure across the core dimensions that matter most to enterprise stakeholders.
Comprehensive Market Sizing and Forecast Architecture
The report maps historical performance across 2020–2025 and extends forward through 2032, using a disciplined methodology that captures the interplay between volume expansion, price normalization, material substitution, and end-user demand evolution. The forecast architecture is designed to support scenario planning, enabling teams to assess how shifts in regulatory requirements, procurement policy, or capacity utilization could alter growth paths in specific market environments.
Segmentation by Type, Application, and Region
The study examines the market through multiple lenses, including material types such as nitrile, natural rubber latex, polyvinyl chloride, and other variants, as well as application contexts spanning healthcare, industrial operations, food service, and adjacent use cases. Regional analysis provides a structured view of how demand and supply characteristics differ across major markets, helping organizations benchmark exposure, anticipate localization requirements, and identify growth pockets aligned with their strategic footprint.
Competitive Landscape and Company Profiles
A central contribution of the research is its detailed assessment of the competitive field. Rather than treating the market as a homogeneous set of producers and distributors, the study profiles leading organizations based on their strategic positioning, capacity orientation, product specialization, certifications, and recent operational developments. This enables readers to understand not just who competes in the market, but how competitive advantage is being constructed and defended.
Disposable Medical Gloves Market
Regulatory, Compliance, and Sustainability Dynamics
The research integrates regulatory and operational developments that directly affect sourcing, product selection, and supply continuity. This includes analysis of FDA-registered facility requirements, medical glove regulation, trade enforcement actions, reimbursement-linked procurement behaviors, and evolving sustainability expectations. The report also examines how traceability, material circularity, and chemical-exposure reduction are becoming increasingly relevant to procurement criteria in healthcare and industrial settings.
Recent Developments and Strategic Signal Extraction
To keep the analysis anchored in present-day momentum, the study incorporates recent corporate actions and industry events that signal where the market is heading. These include capacity expansions, product launches, sustainability recognitions, traceability platform expansions, and trade show participation that reflects regional market engagement. The emphasis is not on isolated news flow but on extracting durable strategic signals: where capacity is being committed, what product features are being prioritized, and how manufacturers are positioning for the next phase of differentiation.
Competitive Landscape: Strategic Positioning in a Concentrated Market
Market concentration remains a defining feature of the disposable gloves sector. The research notes a CR3 of approximately 40 percent and a CR5 of roughly 55 percent, indicating that a relatively small group of players exerts meaningful influence over pricing dynamics, capacity allocation, and category standards. At the same time, the presence of regionally anchored manufacturers, specialized material exporters, distributor-led healthcare providers, and sustainability-focused innovators ensures that competition plays out across multiple dimensions rather than through scale alone.
Disposable Gloves Market
Scale Leaders and Non-Latex Specialization
INTCO Medical has reinforced its position as a major global non-latex glove manufacturer, with annualized production capacity reaching 103 billion pieces by the end of 2025. Its recent 2025 annual report highlighted continued revenue growth and an expansion trajectory that underscores the strategic importance of nitrile and vinyl disposable gloves across healthcare, food safety, and industrial protection. For customers and competitors alike, INTCO exemplifies the scale-plus-material-specialization model, where volume capability is paired with a deliberate non-latex focus that aligns with broader industry substitution trends.
U.S. Manufacturing, Compliance Infrastructure, and Domestic Sourcing
Nephron Nitrile LLC operates a large U.S. production facility supplying powder-free nitrile and biodegradable polyurethane disposable gloves for medical, laboratory, industrial, food handling, and janitorial applications, with FDA registration and ISO-aligned practices. Its operating model illustrates a distinct competitive logic: domestic manufacturing capability, regulated medical glove compliance, and U.S.-based workforce deployment, all of which carry different cost and risk profiles compared with import-dependent sourcing. The study examines how this positioning intersects with procurement preferences for supply continuity, regulatory alignment, and domestic content considerations.
Established Global Players and Material Innovation
Ansell remains a leading provider of disposable nitrile and other material gloves, with advanced certifications and recent innovation activity in chemical-resistant and sustainable product options. In early 2026, Ansell launched the TouchNTuff 93-800 disposable glove, which offers up to 15 minutes of resistance to acetone and aggressive chemicals, and received the 2026 SEAL Business Sustainability Award for sustainable product innovation in the disposable gloves category. This dual focus—performance differentiation and sustainability recognition—reflects a broader competitive trend in which material performance and environmental positioning increasingly reinforce each other.
Malaysian Manufacturing Footprints and Compliance Emphases
Top Glove Corporation Bhd, Hartalega Holdings Berhad, and Kossan Rubber Industries Bhd each represent substantial manufacturing capacity and export-oriented participation in the global market. Their profiles highlight different strategic emphases within a shared regional base: strong compliance documentation and trade show engagement, emphasis on quality and global supply, and focus on non-sterile and medical disposable glove quality standards for export markets. The research situates these players within the wider context of Malaysian manufacturing’s role in global glove supply and the regulatory and pricing dynamics that shape their competitive environment.
Additional International Players and Channel-Focused Providers
The competitive set also includes Semperit AG Holding, which emphasizes innovation in nitrile and other disposable gloves for medical and industrial applications; B. Braun Melsungen AG, which focuses on healthcare-oriented disposable gloves as clinical and surgical consumables; and U.S.-based channel participants such as Medline Industries, Inc. and CARDINAL HEALTH, INC., which supply medical disposable gloves to healthcare institutions and hospitals and clinics. Together, these organizations demonstrate how the market is contested not only at the level of production capacity but also through distribution reach, clinical integration, and application-specific service models.
Industry Dynamics: Regulatory Shifts, Labor Economics, and Innovation Signals
The 2026 market environment is shaped by several overlapping forces that go beyond traditional supply-and-demand analysis. Regulatory developments continue to influence what can be imported, how medical gloves are validated, and which production facilities are eligible for certain procurement channels. At the same time, labor cost differentials and domestic manufacturing incentives introduce persistent tension into price formation and sourcing strategy.
Innovation activity provides another important read on market direction. Product launches are increasingly oriented toward chemical resistance, reduced chemical exposure, accelerator-free formulations, and sustainable material profiles. Traceability expansion is also gaining traction, with platforms extending to global latex and nitrile disposable gloves to advance circular materials and supply chain transparency. These developments matter because they signal how manufacturers are preparing for more demanding procurement specifications and more scrutinized supply chains.
A further dynamic is the growing relevance of sustainability as a procurement differentiator rather than a peripheral concern. Awards, certifications, and product-level innovation suggest that disposable gloves are increasingly being evaluated through a lens that combines occupational safety, chemical exposure management, and environmental performance. For enterprises, this raises practical questions about specification setting, supplier qualification, and the cost implications of shifting toward higher-differentiation gloves.
Strategic Implications for 2026 Decision-Makers
The disposable gloves market in 2026 is not simply larger than it was; it is more strategically layered. Growth remains robust at the aggregate level, but the value lies in understanding where growth is durable, where pricing power is eroding, and where competitive advantage is being rebuilt through compliance, material science, and supply chain transparency.
For procurement organizations, the most immediate implication is the need to move beyond single-threshold price comparisons. Oversupply can create attractive short-term pricing, but it also rewards buyers who have the internal capability to evaluate supplier reliability, regulatory status, material differentiation, and logistics resilience in an integrated way. For manufacturers and investors, the imperative is to clarify whether capacity additions are directed at commodity volume or at differentiated, higher-specification product segments with stronger margin defensibility.
For corporate strategy and market entry teams, the concentration structure of the market and the divergence between regional cost bases create both partnership opportunities and competitive risks. The presence of large-scale non-latex producers, U.S.-based regulated manufacturers, internationally certified exporters, and channel-oriented healthcare distributors means that market access strategies must be tailored to product category, end-user requirements, and regulatory context rather than treated as uniform global plays.
Why the Full Report Matters Now
This article offers a directional overview, but the full report is where the decision-grade detail lives. It provides the structured segmentation, company-level profiling, regulatory context, and forecast architecture needed to convert broad market awareness into concrete sourcing, investment, and product strategy decisions. The study is designed to support scenario-based planning across multiple what-if environments, from continued capacity overhang to shifting compliance requirements and accelerating sustainability-driven specification changes.
For organizations preparing for the 2026–2032 cycle, the strategic question is not whether disposable gloves remain essential—they clearly do—but how to position within a market where scale, compliance, material innovation, and transparency are increasingly inseparable from commercial performance.
To access the complete analysis, detailed segmentation discussion, competitive profiles, and forward-looking scenarios, visit the full Disposable Gloves Market research page from PW Consulting.
For detailed analysis of this topic, please visit the official page: Disposable Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Engine-Driven Welders Market Hits $1,380M in 2025, Forecast 4.91% CAGR to 2032
By pmarketresearch, 2026-09-15
The Engine-Driven Welders Market: Strategic Intelligence for the 2026 Decision-Maker
The industrial equipment landscape is undergoing a quiet but decisive transformation. As infrastructure projects multiply across emerging economies and legacy assets in developed markets demand intensive rehabilitation, the demand for reliable, mobile power and welding solutions has never been more critical. For executives in manufacturing, procurement, and strategic planning, navigating this space requires more than surface-level consumption forecasts. It demands a rigorous understanding of engine technology adoption, regional demand shifts, regulatory pressures, and the competitive maneuvers shaping the next seven years of market evolution.
PW Consulting's latest research initiative delivers a comprehensive, forward-looking analysis of the Global Engine-Driven Welders Market. Anchored in historical data spanning 2020 through 2025 and projecting through 2032, this report provides the analytical rigor necessary to allocate capital, refine product roadmaps, and anticipate competitive disruption. What follows is an executive preview of the market architecture, the forces driving its trajectory, and the proprietary analytical frameworks embedded within our full publication.
A Market Navigating Growth and Structural Realignment
Over the past half-decade, the engine-driven welders sector has demonstrated remarkable resilience, rebounding from supply chain bottlenecks and transitioning into a phase of measured, sustainable expansion. Current market valuations reflect a maturing industry that has successfully absorbed post-pandemic operational adjustments while capitalizing on the global construction and energy pipeline boom. The research models a clear upward trajectory, with total market revenue positioning itself for steady accumulation through the end of the forecast period.
At the core of this forecast lies a moderate yet consistent compounding growth rate, signaling an industry that is expanding beyond cyclical volatility and settling into a pattern driven by fundamental industrial demand, technological refinement, and strategic fleet modernization. Decision-makers will find that the growth narrative is not monolithic; rather, it is segmented by propulsion technology preferences, regional economic priorities, and application-specific operational requirements. Our analysis deconstructs these layers to reveal where value creation is most concentrated and where margin pressures may emerge.
Welding Equipment Market
Crucially, the report does not merely project headline numbers. It maps the underlying demand vectors, correlating equipment adoption rates with macroeconomic indicators, project financing cycles, and evolving on-site labor economics. By isolating these dynamics, we provide leadership teams with a diagnostic lens to stress-test their market assumptions and align their strategies with the components of growth that are most sustainable.
Technological Divergence and the Mobility Imperative
The modern engine-driven welder category is defined by a fundamental operational trade-off: portability and self-sufficiency versus fuel efficiency and emissions compliance. Within this tension, manufacturers are pursuing divergent engineering philosophies. Diesel-powered platforms continue to anchor heavy-duty and remote operations, capitalizing on torque reliability and extended runtime capabilities. Gasoline-driven units maintain strong footholds in lighter commercial and maintenance applications, where rapid deployment and lower upfront costs drive purchasing decisions. Meanwhile, LPG-fueled alternatives are carving out niche positioning, particularly in markets with stringent indoor or urban emissions regulations.
This technological segmentation is not merely a product classification exercise; it represents a strategic fork in the roadmap for equipment manufacturers and fleet operators alike. The research evaluates how engine architecture choices interact with total cost of ownership, service interval economics, and regional fuel availability. For procurement leaders, understanding the operational profile of each propulsion type is essential when aligning equipment specifications with project duration, site logistics, and local compliance frameworks.
Furthermore, the integration of auxiliary power generation into welding platforms has transformed these machines from single-purpose tools into multi-role assets. On active jobsites, this convergence directly reduces the logistical footprint of supporting equipment and mitigates the need for separate generator rentals. Our analysis quantifies the operational efficiency gains that arise from this consolidation, demonstrating how labor allocation and equipment utilization metrics shift when welding and power generation are unified into a single mobile unit.
Regulatory Pressure, Raw Material Volatility, and Operational Resilience
The engine-driven welders market operates at the intersection of mechanical engineering, emissions regulation, and commodity economics. Manufacturers and end-users alike must navigate an increasingly complex compliance environment, particularly in jurisdictions where engine emissions standards are tightening to align with broader environmental policy objectives. Recent product developments from leading OEMs highlight a clear industry response: new platform introductions are being engineered from the ground up to meet rigorous duty-cycle requirements while maintaining compact footprints suitable for service vehicles and confined job site logistics.
Simultaneously, raw material cost fluctuations remain a persistent variable in the manufacturing equation. Alternator components, control electronics, and engine subsystems are subject to supply chain pricing dynamics that ripple directly into production margins and, ultimately, end-user pricing strategies. The report incorporates scenario modeling that accounts for these input cost pressures, enabling readers to assess how different procurement and pricing architectures may hold up under periods of commodity volatility.
For competitive strategists, the regulatory and input-cost environment is not merely a constraint; it is a source of differentiation. Companies that can streamline compliance engineering, localize assembly where advantageous, and optimize bill-of-materials resilience are positioned to capture pricing power and market share. Our analysis highlights how the leading participants are structuring their operational responses to these external pressures, offering a template for evaluating internal capability gaps.
Competitive Architecture: Navigating an Oligopolistic Landscape
The competitive structure of this market is characterized by a high degree of concentration among established equipment manufacturers, with a handful of multinational players commanding a substantial share of industry revenue. This oligopolistic dynamic creates a market environment where brand recognition, service network density, and product lineage play decisive roles in procurement decisions. However, it also presents opportunities for focused differentiation, particularly among regional specialists and agile OEMs that can adapt quickly to localized application requirements and emerging market niches.
Our competitive profiling extends well beyond corporate biographies. The research evaluates each major participant through the lens of product architecture, engine partnerships, geographic assembly strategies, and end-market specialization. Large-cap manufacturers have historically leveraged established distribution channels and bundled service offerings to sustain market leadership, while mid-tier and regional producers have pursued competitive advantage through compact design optimization, fuel efficiency claims, and targeted deployment in agricultural, field-service, and export-oriented applications.
The report further examines the strategic significance of recent product launches that signal the industry's direction. New-generation platforms are increasingly emphasizing advanced arc performance, expanded generator capacity, and duty-cycle robustness tailored to harsh construction and industrial environments. These introductions reflect a broader market consensus: the next wave of competitive advantage will belong to manufacturers that can deliver high-utilization reliability without compromising mobility or compliance readiness. By mapping these product strategies against regional demand profiles, our analysis provides a tactical view of where competitive intensity is likely to escalate and where whitespace may still exist.
For strategic planners, understanding the concentration of market power is essential. The research provides a detailed assessment of how incumbent players are defending their positions through product portfolio breadth, technology licensing, and service ecosystem expansion, as well as where acquisition, partnership, or geographic entry strategies may reshape the competitive hierarchy over the forecast horizon.
Demand Vector: Where the Market Finds Its Pulse
The application landscape for engine-driven welders is diverse, stretching across heavy civil construction, pipeline installation and maintenance, mining operations, and broader infrastructure development. Each application segment carries distinct operational requirements, utilization patterns, and procurement cycles. In construction environments, for example, the ability to deploy self-contained power and welding capability directly to intermittent work zones translates into measurable efficiency gains. Pipeline and energy-sector projects demand equipment that can sustain prolonged duty cycles under remote or extreme conditions. Mining operations, meanwhile, prioritize fuel endurance, ruggedness, and compatibility with existing fleet logistics.
Our segmentation analysis isolates these application-specific drivers to reveal which end-use categories are generating the most consistent revenue streams and which are most sensitive to macroeconomic cycles or commodity price fluctuations. Rather than presenting static splits, the report contextualizes each application's growth potential within the broader framework of project financing, labor availability, and equipment utilization economics. Readers will gain a nuanced view of where fleet replacement demand, incremental capacity expansion, and new-project initiation are converging to drive volume.
Regional demand patterns are examined with equal rigor. The study evaluates how varying rates of infrastructure investment, energy sector activity, and industrial modernization shape geographic consumption profiles. By correlating regional project pipelines with equipment specification trends, the research identifies markets where localized assembly, distribution partnerships, or tailored product configurations may offer the highest strategic return. These insights are particularly valuable for organizations considering geographic expansion, export strategy refinement, or regional supply chain reconfiguration.
Report Architecture: Operational Intelligence for Strategic Execution
The full PW Consulting publication is engineered to be a working document, not merely a reference summary. Its architecture is designed to support cross-functional decision-making across product management, sales leadership, procurement, and corporate strategy. The report integrates quantitative market modeling with qualitative competitive assessment, delivering a unified view of market behavior and structural risk.
Core components of the analysis include a detailed historical reconstruction of market revenue dynamics from 2020 through 2025, a transparent demand-side forecast extending through 2032, and a segment-level diagnostic that maps propulsion technology preferences, application utilization profiles, and geographic consumption patterns. The research also incorporates a rigorous competitive benchmarking framework, profiling leading manufacturers and their strategic postures, recent product introductions, and regional assembly or distribution strategies.
In addition to market sizing and segmentation, the publication delivers forward-looking assessments of regulatory trajectory, input-cost exposure, and labor economics that directly influence equipment adoption. Scenario modeling is embedded throughout, enabling readers to evaluate how changes in compliance requirements, fuel pricing, or project financing conditions may alter demand momentum. The result is an analytical toolkit that can be applied to capital planning, product roadmap prioritization, pricing strategy, and market-entry evaluation.
Executive summaries, graphical data representations, and structured competitor matrices are integrated to ensure rapid assimilation of key insights, while the underlying methodology and source documentation provide the audit trail necessary for internal validation and board-level review.
Engine-Driven Welders Market
Strategic Takeaways for 2026 and Beyond
The engine-driven welders market is entering a phase where disciplined strategic positioning will separate long-term winners from reactive participants. Several high-level implications emerge clearly from our analysis. First, the market's growth trajectory is anchored in structural industrial demand rather than speculative cycles, creating a favorable environment for product innovation and service-led revenue expansion. Second, competitive differentiation will increasingly depend on the ability to balance compliance readiness, fuel efficiency, and field durability without sacrificing portability or total cost competitiveness.
Third, the concentration of market power among leading OEMs does not preclude opportunity; it reframes it. Regional specialists, export-focused manufacturers, and entrants with differentiated product configurations can capture value by serving application segments or geographic pockets where incumbent coverage is less dense or where localized assembly and service models confer a decisive advantage. Finally, the integration of labor-saving functionality, auxiliary power capability, and compliance-forward engineering is not a peripheral feature set; it is becoming a central purchasing criterion that will shape procurement specifications and fleet replacement cycles for years to come.
For decision-makers preparing their 2026 portfolios, the imperative is clear: base strategic commitments on granular, forward-validated market intelligence rather than on aggregate industry narratives.
Accessing the Full Research Intelligence
This article offers a strategic preview of the market architecture, competitive dynamics, and operational forces shaping the engine-driven welders sector. The underlying research contains a far more granular dissection of market sizing, segment-level demand modeling, competitive benchmarking, regulatory scenario mapping, and regional consumption diagnostics. Those detailed breakdowns are essential for calibrating investment thresholds, prioritizing product development, and validating market-entry assumptions.
To access the complete dataset, forecast tables, competitor profiles, and scenario frameworks, we invite you to consult the full PW Consulting Engine-Driven Welders Market research publication. The complete report provides the analytical depth required to translate market awareness into executable strategy.
For detailed analysis of this topic, please visit the official page: Engine-Driven Welders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Aqua Feed Market Hits $21.5B in 2025, Projects 6.98% CAGR to 2032
By pmarketresearch, 2026-09-15
Global Aqua Feed Market Outlook 2026: Navigating Growth Trajectories and Strategic Imperatives
The global aquaculture industry stands at a critical inflection point as it enters the 2026 fiscal year. Driven by escalating protein demand, finite wild capture stocks, and rapid technological maturation in feed formulation, the sector is reshaping how capital is allocated, how supply chains are structured, and how regulatory compliance is operationalized. Our newly commissioned Aqua Feed Market research initiative is designed to cut through the noise of high-level trade publications and deliver boardroom-ready intelligence. Rather than offering static snapshots, this study maps the structural forces that will dictate competitive positioning, margin sustainability, and geographic expansion priorities over the next seven years.
For executives, procurement leaders, and investment committees, the 2026 decision environment demands more than backward-looking sales data. It requires a forward-looking lens that connects macro revenue trajectories with segment-level behavior, competitive intensity, and policy-driven cost pressures. This article provides a strategic preview of the research framework, outlines the operational intelligence embedded in the full report, and explains why the market dynamics captured here translate directly into actionable corporate strategy.
Macro Trajectory and the Strategic Relevance of the 2026 Baseline
The market has demonstrated consistent, compounding growth across the historical review window. From a foundational revenue base of approximately 16.3 billion USD in 2020, the sector advanced through successive annual increments to reach an estimated 21.5 billion USD in 2025. The forecast horizon extends through 2032, with the top-line trajectory projecting a continued upward arc that pushes aggregate revenues toward the mid-34 billion USD range by the terminal forecast year. The compound annual growth rate anchored across the full forecast window sits at 6.98 percent, a figure that signals durable demand expansion rather than a short-lived cyclical surge.
What makes the 2026 baseline particularly valuable for enterprise planning is its positioning at the intersection of post-pandemic recovery normalization, structural capacity additions, and early-stage regulatory recalibration. The jump from the 2025 close to the 2026 opening estimate reflects both organic volume growth and the beginning of capacity projects that broke ground in the prior two years. More importantly, the 2026 starting point sits just before a series of policy mandates and formulation transitions that will alter cost curves and procurement strategies across multiple regional markets. Companies that calibrate their 2026 operating plans to the inflection dynamics captured in this study will be better positioned to protect gross margins, secure raw material access, and align product roadmaps with emerging certification requirements.
Segment Architecture and Portfolio Implications
Revenue distribution across production formats, species applications, and geographic corridors reveals where competitive advantages are being forged and where margin compression is most likely. The research dissects the market along three core axes: feed type, application species, and regional footprint. Each axis carries distinct operational implications for formulation R&D, mill utilization, distribution logistics, and customer acquisition.
Within feed types, the analysis contrasts the scale economics of traditional pellet operations against the value-added positioning of extruded formats, while also tracking niche and specialty categories that serve high-margin species or functional nutrition programs. For manufacturers, the choice of format mix is no longer purely a technical decision; it is a capital allocation signal that determines exposure to energy intensity, extrusion line utilization rates, and downstream pricing power.
Feed + Aquafeed Market
On the application side, the report maps revenue concentration across fish, crustacean, and other aquatic species categories. The commercial weighting of each application reflects both biological feed conversion dynamics and the maturity of regional aquaculture industries. Executives evaluating species diversification, vertical integration, or contract farming partnerships will find the application-level breakdowns essential for stress-testing revenue resilience against species-specific disease cycles, regulatory shifts, and input cost volatility.
Geographic distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa illustrates where production density, customer concentration, and growth velocity diverge. Rather than presenting static share figures, the full study connects regional totals to underlying drivers such as local milling capacity additions, species mix transitions, and trade flow adjustments. This framing allows strategists to identify where incremental investments will face headwinds from market saturation versus where earlier-stage demand curves still reward market entry or capacity expansion.
Competitive Intensity and the Restructuring of Market Power
The competitive landscape is defined by a moderately concentrated structure in which scale, formulation expertise, and regional milling footprints determine pricing leverage. The C3 concentration ratio of 24.6 percent and the C5 concentration ratio of 26.2 percent indicate that while top-tier players command meaningful share, substantial opportunity remains for mid-tier and regional specialists to compete through species-specific programs, localized supply chains, and differentiated nutrition platforms.
Global integrators such as Cargill Incorporated, Nutreco N.V., and BioMar A/S anchor the upper tier of the market. Cargill operates a broad international aqua nutrition footprint supported by a network of dedicated mills and species-focused brands, giving it the ability to serve salmon, shrimp, and other high-value segments at scale. Nutreco, through its Skretting platform, has consistently pursued capacity expansions and specialized formulations that target shrimp and other priority species, reinforcing its position as a technology-led supplier. BioMar has carved out a strong position in the high-value segment, ranking among the top global players and investing in capacity growth that aligns with premium salmon and shrimp demand.
The competitive field also includes specialized suppliers and regional powerhouses that shape local pricing dynamics and customer loyalty. Ridley Corporation Limited provides aqua feeds, additives, and premixes across global markets, while Alltech Inc. and Archer Daniels Midland Company contribute ingredient and nutrition-solution capabilities that influence formulation economics upstream. De Heus Animal Nutrition has accelerated its geographic expansion through new production facilities in Africa and Asia, directly challenging established incumbents in emerging corridors. Integrated operators such as Mowi plc illustrate a different competitive model, with dedicated in-house feed mills supplying the vast majority of their own farmed salmon requirements and thereby insulating part of their cost base from external market volatility.
In Asia and other high-growth regions, domestic manufacturers are rapidly scaling. Indian producers including Avanti Feeds Limited, Growel Feeds Private Limited, IFB Agro Industries Ltd, and Godrej Agrovet Limited are deepening their species coverage and formulation capabilities, while Thai Union Feedmill focuses on shrimp feed with recent profit growth reflecting strong sales momentum despite input cost pressures. In China, Haid Group operates at substantial scale with annual aquafeed volumes exceeding five million tonnes, underscoring the strategic weight of large domestic producers in shaping regional pricing and supply availability. European specialists such as Aller Aqua A/S and Dibaq Aquaculture complement the landscape with targeted fish and shrimp nutrition solutions that reinforce segment-level competition.
Operational Intelligence: What the Full Report Delivers
Beyond revenue corridors and competitor mapping, the study is built around actionable operational intelligence that connects strategy to execution. The report architecture is designed to support scenario planning, capital prioritization, procurement optimization, and regulatory readiness. Key deliverables include:
- Detailed revenue and volume trajectories across the 2026 to 2032 forecast window, structured to allow rolling adjustments as new operational data becomes available.
- Segment-level profiles that translate market size into realistic growth drivers, consumption patterns, and formulation demand shifts for each feed type and application category.
- Regional analyses that combine capacity additions, local species economics, trade dynamics, and policy influences to support market entry, capacity siting, and partnership decisions.
- Competitive benchmarking that evaluates scale, product breadth, regional presence, and recent strategic moves for the principal market participants.
- Regulatory and certification tracking, including the implications of updated sustainability and feed standards for mill compliance, ingredient sourcing, and customer qualification.
- Raw material cost and supply risk analysis, focusing on how protein sourcing dynamics, enzyme adoption, and alternative ingredient strategies affect formulation cost curves.
- Technology and innovation mapping that identifies where functional feeds, health-enhancing additives, and efficiency-driven formulations are creating premium pricing opportunities.
The methodology integrates historical reconstruction, forward-looking modeling, and qualitative validation to ensure that forecast outputs are tied to observable operational signals rather than abstract trend extrapolation. Each section is written to be usable by both commercial teams evaluating growth opportunities and supply chain teams managing cost and availability risk.
Policy, Raw Material, and Technology Pressures Reshaping Cost and Compliance
One of the most consequential dimensions of the 2026 outlook is the convergence of regulatory mandates, raw material volatility, and formulation innovation. These forces are not operating in isolation; they are interacting to redefine how mills manage phosphorus discharge limits, ingredient sourcing, and functional performance claims.
Regulatory dynamics are increasingly shaping formulation architecture. Recent updates to aquaculture sustainability and feed standards now require certified feed mills to align ingredient sourcing with defined environmental and traceability expectations. In parallel, national-level aquaculture acts are imposing nutrient discharge constraints that directly influence formulation chemistry. For example, phosphorus discharge limits in Norwegian production have pushed mills toward higher phytase enzyme usage and low-phosphorus formulations, a trend that illustrates how environmental policy translates into measurable changes in ingredient demand and additive consumption.
On the raw material side, protein sourcing remains a persistent cost driver. Supply disruptions in fishmeal markets have produced sharp price increases during short windows of scarcity, placing direct pressure on production economics and squeezing margins for mills that lack diversified ingredient strategies or long-term supplier arrangements. The resulting cost pressure is accelerating interest in alternative proteins, enzyme-enabled nutrient utilization, and formulation redesign that can preserve performance while reducing exposure to volatile marine ingredient markets.
Regional supply-side developments are also reshaping competitive geography. In Southeast Asia, estimated increases in national aquafeed production reflect recovery dynamics in local shrimp industries following contamination-related adjustments and remediation efforts. At the same time, new milling capacity in East Africa and expanded production in Indonesia is extending the physical footprint of suppliers and altering the balance between imported and locally produced nutrition solutions. These capacity shifts matter for procurement leaders because they change where volume can be sourced, how quickly mills can respond to regional demand spikes, and which competitors will control premium local relationships.
Why the 2026 Decision Window Requires Deep Market Intelligence
Entering 2026, the market rewards organizations that can connect top-line growth expectations with operational realities. A company may recognize that aggregate demand is expanding, but without a clear understanding of how revenue is distributed across formats, species, and regions, capital can be misallocated into overcapacity in mature corridors or underinvestment in higher-growth applications. Similarly, competitive strategy becomes reactive if the firm does not know where scale advantages are durable, where specialists are gaining ground, and where regulatory or raw material shifts will alter cost structures fastest.
The strategic value of this research lies in its ability to convert macro trajectory into execution-ready insight. For procurement and formulation teams, the report supports ingredient substitution planning, enzyme adoption analysis, and supplier diversification strategies. For commercial and business development teams, it helps prioritize species programs, regional expansion targets, and partnership structures. For executive leadership and investors, it provides a defensible base for capacity planning, margin defense, and competitive positioning across the forecast horizon.
Conclusion and Next Steps
The global aqua feed market is advancing along a credible growth path, but the returns on strategy will depend on how precisely organizations interpret the underlying drivers of that growth. The 2026 to 2032 period will reward players who understand where concentration is meaningful, where regional capacity is shifting, and how regulatory and raw material pressures are reshaping formulation economics. It will also reward those who move early on certification readiness, functional nutrition development, and supply chain diversification before structural advantages harden further.
Aqua Feed Market
This article has outlined the strategic framing and analytical depth embedded in our latest Aqua Feed Market study, but the full intelligence set includes the detailed segment breakdowns, company-specific benchmarking, regional capacity assessments, and forward-looking scenario analyses required to make precise planning decisions. To access the complete dataset, competitive profiles, and operative market forecasts that support 2026 strategy formulation, request the full report through our research portal and equip your leadership team with the intelligence needed to act ahead of market consolidation.
For detailed analysis of this topic, please visit the official page: Aqua Feed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultra Fine Copper Powder Market Hits $260.4M in 2025, Projects 7.42% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating the Ultra Fine Copper Powder Market: Strategic Intelligence for 2026 and Beyond
The ultra fine copper powder market stands at a critical inflection point. As industries converge around electrification, advanced connectivity, and miniaturized electronics, the demand for high-purity, precision-engineered copper particles has transitioned from a niche specialty to a strategic commodity. For executive teams, procurement leaders, and R&D directors, understanding the trajectory of this market is no longer optional—it is a prerequisite for resilient supply chain design, capability investment, and competitive positioning.
Our latest market research provides a granular, forward-looking assessment of the ultra fine copper powder landscape, calibrated to support enterprise decision-making through 2032. This overview outlines the macro trajectory, the structural forces reshaping supply and demand, the evolving competitive architecture, and the practical intelligence embedded in the full study. The goal is to equip you with the analytical framework needed to act decisively in 2026, while preserving the proprietary segmentation and scenario modeling for direct access to the complete intelligence package.
The Macro Trajectory: Sustained Expansion Anchored in Advanced Manufacturing
The historical record and forward projections paint a picture of consistent, compounding growth. From a baseline of 183.0 million USD in 2020, the market advanced through a series of steady increments, reaching 235.3 million USD by 2024. The momentum carried into 2025 with a valuation of 260.4 million USD, setting the stage for an estimated 279.07 million USD in 2026. Looking further ahead, the trajectory ascends toward 323.91 million USD by 2028, 383.03 million USD by 2030, and a projected 428.5 million USD by 2032.
This expansion is underpinned by a forecast period compound annual growth rate of 7.42 percent across the 2026 to 2032 horizon. Such a rate reflects more than cyclical recovery; it signals a structural uplift driven by the integration of ultra fine copper powder into high-value applications where particle size, purity, morphology, and surface engineering directly dictate performance outcomes. The growth curve is not uniform across all endpoints, nor is it evenly distributed geographically. The full study decomposes these variations into actionable demand vectors, capacity allocations, and regional supply-demand balances, allowing strategic planners to isolate where volume growth will concentrate and where margin dynamics will diverge.
For organizations evaluating capital deployment, inventory strategy, or technology roadmaps, the headline numbers serve as a directional anchor. The real strategic value lies in understanding the composition of that growth: which particle classifications are accelerating, which application verticals are pulling demand faster than capacity can respond, and how regional production ecosystems are reconfiguring to meet localized regulatory and performance requirements.
Structural Forces Reshaping Supply, Demand, and Margin Architecture
The ultra fine copper powder market is being reshaped by a cluster of interdependent dynamics that extend well beyond raw volume growth. At the production level, the dominant fabrication pathways rely on atomization and advanced wet processes that deliver controlled particle size distributions and tailored surface characteristics. These processes, however, carry inherent cost and compliance implications. Production via atomization is materially more energy-intensive than standard copper processing, contributing to elevated material pricing and creating a cost floor that differentiates ultra fine grades from bulk copper commodities. Energy pricing volatility, therefore, translates directly into margin sensitivity for producers and into procurement risk for downstream buyers.
Regulatory pressure adds another layer of complexity. European Chemicals Agency data indicates that approximately 52 percent of producers face regulatory delays stemming from REACH compliance concerning nanoparticle safety and environmental impact for ultra fine copper powder. This compliance burden is not merely a procedural hurdle; it influences time-to-market for new grades, shapes geographic sourcing preferences, and raises the barrier to entry for capacity expansions that lack robust environmental management systems. Simultaneously, stringent environmental regulations on waste and emissions from atomization processes require significant investment in pollution control technologies. Producers that have already integrated advanced abatement infrastructure hold a structural advantage, while late movers face both capital intensity and operational continuity risk.
Demand-side dynamics are equally transformative. EU policies actively promote copper-based solutions for green technologies, increasing demand for high-purity ultra fine copper powder while enforcing compliance. This policy tailwind aligns with broader industrial trends: the proliferation of multi-layer ceramic capacitors in 5G infrastructure and electric vehicle power electronics, the expansion of conductive inks and pastes for printed electronics, and the growing utilization of copper powders in powder metallurgy and advanced coatings. The intersection of performance-driven engineering and sustainability mandates is compressing product development cycles and elevating the importance of traceable, specification-grade supply.
The full report maps these dynamics into distinct segments, analyzing how energy costs, regulatory timelines, and application performance thresholds interact to shape pricing architecture, capacity utilization, and supplier qualification criteria. Rather than treating regulation as an external constraint, the study frames it as a competitive variable that rewards integrated compliance capability and disciplined process engineering.
Ultra Fine Copper Powder Market
Competitive Architecture: Specialization, Capacity, and Regional Strength
The competitive landscape is characterized by a concentrated yet highly specialized set of producers. The market exhibits a moderate concentration profile, with the top three players accounting for approximately 35.4 percent of revenue and the top five reaching roughly 48.2 percent. This structure reflects a market where technical differentiation, process know-how, and application-specific qualification matter as much as scale. Execution risk is high, and customer switching costs are often tied to validated performance in critical electronic, energy, and industrial applications.
Japan remains a central hub of advanced capability. Mitsui Mining & Smelting Co., Ltd. specializes in ultra-fine copper powder production for electronic components, MLCC electrodes, and battery applications, leveraging advanced atomization and wet processes to meet tight specification requirements. Sumitomo Metal Mining Co., Ltd. manufactures high-purity ultra-fine copper powder for powder metallurgy, electronics, and advanced materials using proprietary atomization technology, positioning itself across both industrial and high-specification end markets. DOWA Electronics Materials Co., Ltd. focuses on high-purity ultra-fine copper powders for MLCC electrode pastes and multi-layer ceramic capacitor applications, with a recent capacity expansion further extending its manufacturing footprint to target reduced electronic components in electric and 5G technology. Fukuda Metal Foil & Powder Co., Ltd. offers ultra-fine copper powders for conductive pastes, 5G applications, and high-aspect-ratio flake powders, while Gripm Advanced Materials Co., Ltd. manufactures electronics-grade ultra-fine copper powders below 1 µm D50 with capacity expansions designed for high-volume supply. New Saga Material Technology Co., Ltd. operates as a custom manufacturer of superfine pure copper powder across defined grade families for electronics, diamond tools, and advanced materials.
In Europe, GGP Metalpowder AG produces ultra-fine copper powder grades with surface treatments for electronics, conductive inks, and powder metallurgy, and recently introduced an ultra-fine copper range with single surface treatment against oxidation for electronics and conductive applications. Pometon S.p.A. supplies atomized ultra-fine copper and copper alloy powders for industrial applications including wear-resistant coatings and electronics, reinforcing the region’s strength in application-engineered materials.
North America and transregional channels add further diversity. American Elements provides high-purity ultra-fine copper powder for electronics, metallurgy, and advanced materials with custom purity levels, while Kymera International supplies engineered ultra-fine copper powder for powder metallurgy and specialty applications. UF Copper Supply operates as an exclusive sales channel for ultra-fine copper powder manufactured in US and EU facilities, targeting additive manufacturing and industrial uses and thereby connecting specialized production to emerging deposition and printing workflows.
The competitive implication for 2026 is clear: procurement strategies that treat ultra fine copper powder as a fungible input will encounter hidden performance and continuity risks. Supplier selection increasingly hinges on process control, surface engineering capability, regulatory readiness, and the ability to scale specific grade families without compromising purity or morphology. The full study provides a structured competitive mapping that ties company capabilities to application requirements, recent capacity actions, and product introductions, enabling procurement and strategy teams to prioritize qualification efforts and negotiation leverage.
What the Full Report Delivers: Operational Intelligence for Executive Decision-Making
This market research is designed as a working intelligence asset rather than a static overview. It integrates historical reconstruction, forward modeling, and segment-level analysis into a decision-ready format. The report content is structured to support multiple enterprise functions simultaneously:
- Market sizing and trajectory modeling that connects baseline valuations through the forecast horizon, enabling scenario planning for volume, price, and capacity under varying demand and regulatory conditions.
- Segmentation analysis by type, application, and region that isolates the drivers behind growth concentration, identifies where specification requirements are tightening, and clarifies which demand pockets are likely to outpace near-term supply flexibility.
- Competitive profiling and recent development tracking that captures capacity expansions, product launches, and technology moves, translating corporate actions into implications for sourcing strategy, supplier risk, and market entry timing.
- Regulatory and compliance context that frames REACH-related delays, environmental abatement requirements, and green-technology policy incentives as variables that affect cost structure, qualification cycles, and geographic sourcing logic.
- Production economics and raw material dynamics that address the energy-intensity of atomization, the pricing implications relative to standard copper, and the interaction between process cost and grade differentiation.
- Strategic recommendation frameworks tailored for capacity planning, supplier consolidation or diversification, R&D prioritization, and market-entry evaluation, with specific attention to the trade-offs between scale, purity, and application performance.
By consolidating these elements, the study allows leadership teams to move from broad market awareness to targeted action. Whether the objective is to secure reliable access to electronics-grade grades, evaluate partnership or investment opportunities, or calibrate inventory and pricing strategy against energy and compliance cost curves, the report provides the structural context needed to justify decisions with evidence rather than assumption.
Why This Research Matters for 2026 Decision-Making
The 2026 decision environment will be defined by three overlapping pressures: performance specification tightening, regulatory and environmental compliance acceleration, and supply chain reconfiguration around critical electronic and energy materials. Ultra fine copper powder sits at the intersection of all three. As 5G infrastructure, electric vehicle electronics, advanced capacitors, conductive materials, and additive manufacturing workflows continue to scale, the requirement for controlled particle characteristics and high purity will intensify. At the same time, compliance timelines and abatement investments will separate suppliers that can deliver consistently from those that face qualification delays or cost shocks.
Organizations that treat these forces as isolated issues will likely overpay for supply, underestimate qualification risk, or misallocate R&D and capital toward grades with limited demand pull. Organizations that integrate market sizing, segment dynamics, competitive capability, and regulatory economics into a single strategic view will be better positioned to sequence investments, negotiate with informed leverage, and build supply resilience without sacrificing performance.
The full study provides the depth required to operationalize that view. It preserves the segmentation splits, regional balances, application-level demand drivers, and company-specific developments that turn macro growth into executable strategy. For teams preparing budgets, sourcing plans, technology roadmaps, or market-entry assessments for 2026, the research offers a calibrated baseline and a structured path to scenario-based decision-making.
Next Steps: Accessing the Complete Intelligence Package
The overview presented here establishes the strategic framing and the market logic, but the decisive detail resides in the complete report. Segmentation-level demand patterns, regional supply-demand balances, type-specific growth behavior, and company-specific capacity and product moves are synthesized into actionable insights that cannot be fully reproduced in a summary format. Accessing the full study enables procurement, strategy, and engineering leaders to align on specification priorities, qualification sequencing, supplier risk allocation, and investment timing with a shared evidence base.
Ultra Fine Copper Market
For organizations preparing for the 2026 operating environment, the most valuable move is to convert market awareness into structured intelligence. The complete research delivers that conversion, mapping the 7.42 percent growth trajectory and the associated structural dynamics into a practical toolkit for decision-making across the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Ultra Fine Copper Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Air Ambulance Market to Hit $29.63B by 2032 at 8.5% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Air Ambulance Sector: Navigating the 2026-2032 Growth Trajectory
The air ambulance industry stands at a critical inflection point. As healthcare systems worldwide grapple with aging demographics, rising trauma incidence, and the persistent need for rapid critical care transport, the operational and financial landscape has never demanded sharper strategic vision. At PW Consulting, our latest comprehensive market study on the Air Ambulance sector is engineered not merely as a data repository, but as a decision-making architecture for executives, investors, and operational leaders preparing for the 2026 fiscal cycle and beyond. This introduction outlines the strategic scaffolding of the research, the macroeconomic forces reshaping operational models, and the precise analytical lenses we have applied to decode a market defined by both clinical urgency and commercial complexity.
Market Trajectory and the Strategic Imperative of 2026
Historical performance provides the baseline for forward planning. Between 2020 and 2025, the sector expanded from approximately 10.92 billion USD to 16.75 billion USD, reflecting a compound trajectory driven by increased emergency transport volumes, expanded service coverage into underserved geographic zones, and the gradual institutionalization of air medical logistics within regional healthcare networks. Looking ahead, our forecast window extends through 2032, with the market projected to reach 29.63 billion USD by the terminal year of our model. This expansion is underpinned by an 8.5 percent CAGR, a rate that signals sustained structural growth rather than cyclical fluctuation.
For enterprise decision-makers, the 2026 baseline carries specific operational weight. The transition from retrospective analysis to forward-looking allocation requires a clear understanding of how demand signals are shifting across transport models, aircraft configurations, and geographic delivery networks. Our research isolates these vectors without fragmenting them into isolated percentages, ensuring that leadership teams can map capital deployment, fleet modernization, and partnership strategies against a cohesive growth narrative. The key is recognizing that revenue scaling in this sector is rarely linear; it is mediated by regulatory compliance, reimbursement predictability, workforce availability, and regional infrastructure readiness. The study is designed to translate these interdependencies into actionable planning frameworks.
Operating Environment and Structural Dynamics
The commercial reality of air ambulance operations is shaped by intersecting forces that extend far beyond flight hours or base locations. Reimbursement architecture, for instance, has undergone meaningful recalibration. In 2025, the Centers for Medicare and Medicaid Services finalized updated reimbursement schedules for air ambulance transport, delivering greater cost certainty for both independent operators and hospital-affiliated programs. This stability is critical for long-cycle capital planning, particularly for organizations considering fleet refresh cycles or new base activations. Yet reimbursement clarity does not eliminate financial friction; it merely changes the shape of the planning exercise.
Regulatory frameworks add another layer of operational discipline. The No Surprises Act, enforced from 2022, prohibits balance billing by air ambulance operators and mandates the submission of detailed transport and medical cost data to the Department of Health and Human Services. Compliance is not a static checkbox; it is an ongoing data governance requirement that influences billing systems, clinical documentation workflows, and cross-jurisdictional transport protocols. Simultaneously, the Federal Aviation Administration continues to enforce safety standards, including CAMTS accreditation expectations and enhanced data collection obligations. These requirements compress operational margins in the short term while simultaneously elevating the barrier to entry for under-resourced competitors, a dynamic that quietly reshapes competitive positioning over multi-year horizons.
Emergency Ambulance Market
Cost structure remains a defining constraint. Air ambulance transport demands specialized medical personnel, including flight nurses and paramedics, maintained on continuous duty rotations to support 24/7 readiness. This staffing architecture, combined with aircraft maintenance, fuel volatility, and insurance exposure, contributes to median single-transport costs that consistently reside in the 36,000 to 40,000 USD range. Managing this cost stack while preserving mission readiness is one of the central operational tensions the market must navigate. Our analysis treats cost management not as a standalone efficiency exercise, but as a strategic variable that interacts with service model design, fleet mix optimization, and regional demand density.
Competitive Landscape and Strategic Positioning
The industry is characterized by a concentrated core alongside a diverse periphery of specialized operators, regional providers, and affiliated network models. Concentration metrics indicate that the top three firms command approximately 52.6 percent of market revenue, while the top five extend reach to roughly 65.2 percent. This concentration does not imply uniformity; rather, it reflects divergent strategic playbooks operating within the same clinical mandate.
Several organizations anchor the competitive landscape through distinct operational propositions. Air Methods, headquartered in Greenwood Village, Colorado, positions itself as a leading provider of emergency air medical services, deploying critical care clinicians for trauma, cardiac, pediatric, and burn transports across 48 states via helicopter and fixed-wing fleets. The company's recent activity illustrates the strategic tools available to scale leaders: a fleet expansion initiative announced in early 2026 to add nearly 50 aircraft, a network partnership with HCA Florida Healthcare to launch enhanced critical care access in North Central Florida, and a 10-year air ambulance services contract with the Government of Yukon and Alkan Air valued at approximately 157 million USD. These moves span capacity deployment, institutional partnership, and regional contracting, demonstrating how leading operators sequence growth across multiple vectors.
Air Ambulance Market
Global Medical Response, based in Lewisville, Texas, emphasizes an integrated ground and air medical transport model, encompassing emergency response and inter-facility patient relocation supported by clinical teams. This integration strategy reflects a broader industry logic: reducing handoff friction, expanding geographic coverage, and aligning transport modality with clinical acuity rather than defaulting to a single vehicle type. PHI Air Medical, operating from Tempe, Arizona, runs a national footprint with more than 100 helicopters across 80-plus bases, delivering 24/7 critical care transport alongside membership programs that provide out-of-pocket protection for patients. The membership layer is strategically significant because it introduces a recurring revenue and demand-smoothing mechanism that partially decouples financial exposure from episodic utilization.
REVA Air Ambulance, headquartered in Fort Lauderdale, Florida, occupies a specialized fixed-wing niche as the world's largest dedicated fixed-wing jet air ambulance operator, providing 24/7 bedside-to-bedside ICU-level medical transport across North and South America. Its positioning highlights the strategic value of long-range, high-acuity transport in an increasingly interconnected patient referral environment. Acadian Companies, based in Lafayette, Louisiana, operates its Air Med division to deliver helicopter and fixed-wing emergency and inter-facility transport across rural Louisiana and surrounding states, illustrating how regional density, familiarity with local healthcare ecosystems, and rapid response protocols can sustain competitive relevance outside national-scale playbooks. AirMedCare Network, located in West Plains, Missouri, functions as the largest air ambulance membership network, providing financial protection and access to affiliated providers, including Air Evac Lifeteam and REACH, for emergency and non-emergency rotor and fixed-wing transports. Its model demonstrates how network aggregation can create patient access at scale while distributing operational execution across affiliated entities.
Understanding how these players diverge in fleet composition, service model emphasis, geographic coverage, and membership integration is essential for any market participant evaluating partnership opportunities, competitive benchmarking, or market entry prerequisites. The research dissects these strategic postures without reducing them to static snapshots, instead mapping how each operator's choices interact with reimbursement predictability, regulatory compliance costs, and regional demand elasticity.
Research Architecture and Actionable Intelligence
Our study is structured to convert macro trends into operational decision support. The report begins with a comprehensive market sizing and trajectory analysis, anchoring leadership planning in a transparent 2020 to 2025 historical baseline and a 2026 to 2032 forecast window. From there, the analysis layers in service model dynamics, aircraft type deployment logic, and regional delivery patterns, with the intent of revealing how demand flows through different operational architectures rather than simply reporting where it lands.
The competitive section profiles the core operators shaping the industry's direction, examining strategic posture, fleet and base considerations, partnership patterns, and membership or network strategies where relevant. These profiles are paired with a recent developments tracking module that captures the cadence of real-world moves: network launches, contract expansions, fleet additions, and institutional partnerships. For decision-makers, this sequence matters because market positioning is often established through a series of coordinated actions rather than a single announcement. Tracking that sequence allows organizations to anticipate competitor capacity adjustments, partnership clustering, and geographic focus shifts before they become fully visible in headline metrics.
A dedicated dynamics section integrates the regulatory and reimbursement environment, including the operational implications of the No Surprises Act, CMS reimbursement updates, FAA safety and accreditation requirements, and the labor cost architecture that underpins per-transport economics. This section is written for practitioners who must reconcile compliance obligations with cost management, fleet utilization, and service availability targets. By linking regulatory and reimbursement developments to operational workflow and financial planning, the research helps organizations avoid the common pitfall of treating compliance as an isolated legal function rather than a strategic input to service design.
The report also addresses segmentation logic in a manner suited to strategic planning. Rather than fragmenting the narrative into narrow numerical slices, we analyze how hospital-based and community-based service models, rotary-wing and fixed-wing platforms, and regional delivery variations interact with demand patterns, reimbursement behavior, and operational readiness. This approach equips executives to evaluate portfolio mix, capacity allocation, and partnership structures with a clear understanding of which configurations are best suited to high-acuity emergency response, inter-facility relocation, long-range transport, or membership-supported demand stabilization.
Translating Intelligence into 2026 Decision-Making
As organizations move into 2026, the strategic questions facing air ambulance operators, healthcare systems, investors, and policy-adjacent stakeholders are converging. How should fleet modernization be sequenced against reimbursement certainty and maintenance cycle economics? Where should new bases or partnership hubs be placed to capture demand without overextending fixed-cost structures? How can service model design balance hospital-based integration with community-based reach? What membership or financial protection mechanisms can smooth utilization volatility while preserving clinical access? And how should organizations interpret competitor activity, regulatory shifts, and reimbursement updates as a combined signal rather than a set of disconnected events?
Answering these questions requires a research instrument that is both broad enough to capture systemic dynamics and precise enough to inform capital and operational choices. Our Air Ambulance market study is built for that purpose. It synthesizes historical performance, forward-looking trajectory, competitive positioning, and regulatory context into a single decision framework, enabling leadership teams to test scenarios, prioritize investments, and calibrate risk exposure with a shared analytical foundation.
The full study contains the detailed segmentation logic, competitor profiles, recent development timelines, and scenario-ready analytical tables that executives need to move from directional insight to implementation planning. If your organization is preparing capability expansions, evaluating partnership structures, assessing competitive exposure, or mapping reimbursement-aware operational strategy, the complete research package provides the granularity required to act with confidence. We invite you to access the full report to explore the complete market intelligence, detailed segmentation analysis, and strategic planning toolkit designed specifically for 2026 decision-making and the multi-year horizon that follows.
For detailed analysis of this topic, please visit the official page: Air Ambulance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Travel Insurance Hits $21.5 Billion in 2025, Poised for 5.7% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Imperatives in the Global Travel Insurance Market (2026–2032)
The global travel insurance market stands at a critical inflection point. As borders reopen fully, consumer expectations shift toward instant digital protection, and geopolitical volatility introduces new risk vectors, insurers, intermediaries, and travel technology platforms must recalibrate their growth playbooks. Our newly released Travel Insurance Market Outlook 2026–2032 is designed to cut through the noise and equip executive leadership with the structural intelligence required to allocate capital, shape product roadmaps, and defend market share in an increasingly granular and price-sensitive landscape.
The past half-decade has already demonstrated extraordinary momentum. Between 2020 and 2025, industry revenue expanded from 8.1 billion to 21.5 billion, reflecting not only a recovery from pandemic-era disruptions but a structural re-rating of travel protection as a baseline consumer expectation. Looking ahead, the market is projected to reach 23.18 billion in 2026 and continue climbing toward 32.0 billion by 2032, underpinned by a robust five-year compound annual growth rate of 5.7 percent. Yet headline figures alone are insufficient for strategic planning. The real value lies in understanding the mechanics of this expansion: which coverage dimensions are absorbing premium growth, how distribution architectures are being rewired, and where regulatory or operational friction is quietly compressing margins.
Why This Research Matters for 2026 Decision-Making
Corporate strategy in travel insurance cannot rely on retrospective summaries. The pace of product innovation, embedded distribution, and region-specific compliance regimes demands forward-looking, scenario-tested intelligence. This report is built as a decision-support instrument rather than a static market census. It is engineered to help strategy teams at carriers, investors, and travel ecosystem partners answer three foundational questions:
- Where is the next wave of profitable demand forming, and which customer segments are structurally underserved?
- How will distribution channels evolve as embedded insurance, white-label partnerships, and direct-to-consumer platforms redefine the point of purchase?
- Which operational cost pressures and regulatory shifts will determine whether scale translates into margin expansion or merely top-line growth?
The analysis is anchored in a rigorous historical baseline spanning 2020 through 2025, then extended across a detailed forecast window through 2032. Rather than presenting a single deterministic trajectory, the report layers in sensitivity considerations around macroeconomic travel demand, medical cost inflation, claims adjudication efficiency, and platform-based distribution adoption. For executives planning budget cycles, M&A screening, or product portfolio optimization in 2026, this framing provides the contextual discipline needed to separate durable structural shifts from transient post-pandemic rebounds.
Business Travel Insurance Market
Market Trajectory and Structural Growth Drivers
The trajectory from 2020 to 2032 tells a story of accelerating normalization followed by sustained, quality-led expansion. After moving from 9.17 billion in 2021 to 11.17 billion in 2022, the market stepped up to 13.83 billion in 2023 and 16.8 billion in 2024. The 21.5 billion valuation in 2025 marks a pivotal baseline, and the gradual climb to 24.64 billion by 2027, 28.59 billion by 2030, and 32.0 billion by 2032 suggests that travel insurance is transitioning from a discretionary add-on toward an integrated component of global mobility and risk management.
This expansion is not simply a function of higher passenger volumes. It reflects several compounding dynamics. First, medical cost escalation and an aging traveler demographic are increasing the perceived value of comprehensive protection, particularly for international itineraries where out-of-pocket exposure can be severe. Second, the digitization of booking journeys is making it easier to attach protection at the moment of travel planning, shortening acquisition cycles and expanding addressable demand among previously underinsured travelers. Third, business travel and hybrid work-related mobility are creating new insurance needs, blurring the line between traditional leisure coverage and corporate risk programs.
Importantly, the growth rate implies a maturing market with meaningful room for differentiation. A five-year CAGR of 5.7 percent signals that while the category is no longer in a hype phase, it remains rich with segmentation opportunities. The carriers that win will be those that interpret the aggregate trajectory correctly and then deploy underwriting, pricing, and service capabilities in the right risk pools and distribution contexts. Our report does not merely project the curve; it contextualizes where growth is likely to concentrate and where competitive intensity may erode premium adequacy.
Competitive Landscape and Strategic Positioning
The competitive architecture of the travel insurance market is defined by a blend of global multi-line carriers, specialized protection providers, and digital-native platforms that are rapidly reshaping consumer expectations. Market concentration remains a defining feature: the three largest players command approximately 58.2 percent of revenue, while the top five collectively account for around 62.5 percent. This level of concentration underscores the importance of scale in claims infrastructure, risk pooling, and brand trust, yet it also leaves substantial headroom for agile niche players and embedded-insurance innovators to capture differentiated demand segments.
Several incumbent and challenger organizations illustrate the strategic range now visible in the category. Allianz Travel, headquartered in Germany, continues to emphasize comprehensive travel insurance products spanning medical coverage, trip cancellation, and structured business travel plans, leveraging its broader corporate and consumer ecosystem to reinforce cross-selling and global assistance reach. AXA Assistance, based in France, positions itself around global assistance and insurance coverage for travel disruptions, medical emergencies, and repatriation, with an emphasis on speed and coordination across complex international incidents.
Travel Insurance Market
In the United States, Seven Corners focuses on specialty travel insurance plans for groups, families, and adventure activities with high medical limits, targeting risk segments where standard offerings may fall short. Travelex Insurance Services, headquartered in the United Kingdom, competes on on-demand and comprehensive travel insurance with family and multi-trip options, leaning into flexible consumer journeys. World Nomads, based in Australia, has built brand affinity around flexible multi-trip and adventure sports insurance tailored to digital nomads and backpackers, a segment that has grown in relevance as long-duration mobility becomes more common. IMG provides trip cancellation and medical coverage plans for international travelers, often serving customers who require structured protection for cross-border itineraries. Tin Leg, also U.S.-based, has carved out a position in cruise-specific and medical-focused travel insurance with high limits, demonstrating how verticalized product design can support premium positioning. Chubb, another U.S. player, has moved toward digital parametric travel insurance and emergency assistance services, reflecting a broader industry interest in automated triggers and faster claim resolution pathways. SafetyWing, likewise headquartered in the United States, pursues a nomad-friendly multi-trip and digital nomad travel insurance proposition, underscoring the segmentation power of lifestyle-driven risk profiles.
The strategic implication is clear: scale provides advantages in distribution and brand recognition, but differentiation increasingly comes from underwriting precision, claims experience, and distribution relationships. The report provides a structured framework for evaluating where incumbents can defend advantage through ecosystem integration, where mid-tier specialists can expand through product verticalization, and where digital platforms can capture share through seamless point-of-sale embedding.
Recent Industry Developments and Strategic Signaling
Recent corporate actions and product launches offer a live read on where competitive energy is being directed. In June 2026, Allianz Partners signed an agreement to acquire nib’s Australian and New Zealand travel insurance portfolio, including the Travel Insurance Direct brand, a 20-year white-labelled distribution agreement, and intermediary relationships. This move signals a deliberate push into regional distribution scale, brand consolidation, and intermediary network ownership, highlighting how established players are using acquisition to accelerate access to high-value distribution corridors rather than building them organically.
On the product front, Chubb launched Travel Pro in October 2025, a parametric digital travel insurance product integrated into booking processes for airlines, travel agencies, and financial institutions, offering instant refunds, weather guarantees, and emergency assistance. The launch illustrates a broader industry pivot toward embedded, trigger-based protection that reduces friction at the point of purchase and aligns payout mechanics with clearly defined disruption events. Such parametric approaches are not simply innovation theater; they represent a structural experiment in improving consumer trust, reducing adjudication complexity, and making insurance feel more like an integrated feature of the travel purchase rather than a separate administrative step.
Partnership strategies are equally revealing. In June 2025, Battleface embedded travel insurance with medical and baggage coverage directly into the TravelPerk business travel platform for European business travellers, demonstrating how B2B travel management platforms can become high-intent distribution channels for tailored protection. Around the same period, Squaremouth advanced its product architecture through multiple launches: a battleface Multi-Trip Annual plan in September 2025 offering flexible unlimited trips up to 60 days each year, and a Tin Leg Cruise plan in March 2025 with medical, cancellation, delay coverage, and cruise-specific benefits. These launches reflect a growing focus on flexibility, multi-trip convenience, and vertical-specific coverage design, all of which are becoming central to consumer acquisition and retention.
Together, these developments point to three strategic themes: consolidation of regional portfolios and distribution assets, acceleration of parametric and embedded product design, and sharper segmentation around trip frequency and travel mode. The report analyzes these moves not as isolated news items, but as signals that can inform competitor tracking, partnership strategy, and product roadmap decisions for 2026 and beyond.
Market Dynamics Shaping Margin, Compliance, and Customer Experience
Growth potential must be evaluated against the operational and regulatory constraints that shape profitability. Several recent developments highlight the pressure points that decision-makers cannot afford to ignore. The Insurance Council of Australia has reported that regulation is costing insurance customers up to 3.5 billion dollars a year through 30,000 obligations across 25 authorities. While this figure reflects a jurisdiction-specific context, it illustrates a broader challenge: compliance burden can expand quietly and become a material drag on efficiency, particularly for carriers operating across multiple regulatory environments.
Cost structure is another critical variable. Travel insurance companies can spend up to 80 percent of their budget on claims management, with 40 percent of that allocated to administrative costs. This distribution of spend underscores the strategic importance of claims modernization, automation, and first-time resolution capabilities. Carriers that continue to rely on heavy manual adjudication may find it increasingly difficult to sustain margin health as premium growth is competed away. In parallel, UK regulators are paying closer attention to governance over third-party data feeds, cloud ecosystems, and automated decisions in travel insurance. As underwriting and claims processes become more data-dependent and algorithmically mediated, governance expectations are rising, and compliance risk is increasingly tied to operational design rather than purely legal interpretation.
Consumer-facing friction also remains a persistent issue. Staysure research indicates that UK GPs lose more than 110,000 hours per year dealing with travel insurance paperwork, equivalent to 660,000 lost NHS appointments. While this is a provider-side pain point, it also reflects a broader inefficiency in documentation and claims interaction that can erode customer satisfaction and increase indirect ecosystem costs. On the pricing side, Squaremouth has noted that the average cost of international travel insurance is around 414 dollars, or roughly 25 dollars per day. This affordability framing matters because it suggests that consumer perception of value is closely tied to perceived trip risk and trip duration, not simply premium size. For strategy teams, this reinforces the need to align product design, communication, and distribution with the customer’s mental model of risk and convenience rather than treating price as an isolated competitive lever.
Our report translates these dynamics into strategic implications. It examines where compliance complexity is likely to intensify, where claims economics may reward automation and digital triage, and where consumer price sensitivity could either constrain premium growth or accelerate demand for streamlined, no-friction protection products. Rather than presenting these issues as discrete news items, the analysis integrates them into the broader market outlook so that executives can assess risk-adjusted growth options with greater clarity.
Scope, Methodology, and Practical Value of the Full Report
The full study is structured to be directly actionable for strategy, underwriting, distribution, and corporate development teams. It provides a comprehensive market mapping across multiple structural dimensions, including regional performance, type segmentation, coverage architecture, and distribution channel behavior. The report also examines competitive positioning, recent corporate moves, and the operational pressures that shape margin outcomes. Critically, it connects these elements to decision scenarios for 2026 planning, enabling readers to evaluate where to invest, where to partner, and where to defend existing positions.
Readers can expect detailed analysis of market evolution across the historical period and forecast horizon, along with structured interpretation of how different segments and channels interact to shape aggregate performance. The study does not merely list numbers; it explains the relationships that matter for strategy, including how distribution design influences acquisition cost, how coverage breadth affects claims exposure, and how product flexibility influences retention in multi-trip and long-duration travel segments. The analytical framework is designed to support portfolio prioritization, scenario planning, and competitive intelligence workflows.
To preserve the depth and decision-usefulness of the research, certain granular splits and detailed segment figures are reserved for the full publication. This intentional structure ensures that executives who engage with the complete report receive a rigorous, implementation-ready view of the market without distortion from oversimplified summaries. The preview above establishes the strategic context; the full report provides the precision required for internal modeling, investment screening, and product strategy.
Conclusion: Turning Market Intelligence into Strategic Advantage
The travel insurance market is expanding with scale, but scale alone will not determine winners in 2026. The carriers and platforms that outperform will be those that understand where premium growth is most defensible, where distribution relationships are being consolidated or disrupted, and where operational efficiency and regulatory readiness will separate margin-positive growth from nominal revenue expansion. Our Travel Insurance Market Outlook 2026–2032 has been built to support exactly that strategic work.
For leaders responsible for growth planning, product architecture, risk selection, or competitive positioning, the report offers a structured, evidence-based foundation for decision-making in a market that is becoming more digital, more segmented, and more operationally demanding. The macro trajectory is encouraging, the competitive signals are intensifying, and the operational constraints are real. The opportunity now is to convert that landscape into a clear strategic posture. We invite strategy and executive teams to access the full report for the complete dataset, segment-level interpretation, and competitive assessment needed to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Travel Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Unlocking Molecular Potential: A Strategic Roadmap for the Metal-organic Frameworks Market (2026–2032)
The industrial landscape of advanced materials is undergoing a transformative shift, driven by the urgent need for efficient gas separation, carbon capture, and sustainable catalytic processes. At the forefront of this revolution are Metal-organic Frameworks (MOFs), a class of compounds known for their ultra-high surface area and tunable porosity. For executives and investors navigating the chemical and materials sectors in 2026, understanding the trajectory of the MOF market is no longer optional—it is a strategic imperative.
PW Consulting is proud to introduce our latest comprehensive market research report, designed to equip decision-makers with the intelligence required to capitalize on this high-growth sector. This analysis delves into the commercial maturation of MOFs, moving beyond laboratory curiosity to industrial reality. As we stand at the inflection point where pilot projects evolve into multi-ton production scales, the data suggests a robust expansion cycle that demands careful strategic positioning.
Executive Summary: The Scale of Opportunity
Our research provides a detailed forecast grounded in historical performance and forward-looking modeling. The market valuation has demonstrated consistent upward momentum over the past five years, reflecting increasing adoption across energy and industrial sectors. In the base year of 2025, the global market revenue reached approximately 1.25 billion USD. Looking ahead to the forecast period ending in 2032, our models project significant growth, with the market poised to exceed 4.68 billion USD by the end of the projection window.
This trajectory represents a compound annual growth rate (CAGR) of 20.6 percent throughout the forecast period. Such a rate indicates more than just incremental improvement; it signifies a fundamental expansion in industrial applicability. For stakeholders evaluating capital allocation or technology integration, these figures suggest that the MOF sector is transitioning from a niche specialty to a cornerstone of next-generation industrial chemistry. The revenue unit tracked throughout this study is in billions of USD, providing a macro-level view of economic viability.
Market Dynamics and Historical Context
To understand the future, we must analyze the growth velocity observed from 2020 through 2025. The historical data reveals a steady climb from 0.65 billion USD in 2020 to the aforementioned 1.25 billion USD in 2025. This past performance establishes a reliable baseline for our projections. The acceleration observed in the 2024-to-2025 period, where valuation jumped from 1.08 billion USD to 1.25 billion USD, underscores a widening acceptance of MOF technologies in real-world applications.
This growth is not merely statistical; it is reflective of the underlying technology readiness levels (TRL) advancing. The market concentration indicates a moderately consolidated landscape, with the top three firms holding approximately 35 percent of the market share and the top five controlling around 50 percent. This structure suggests that while incumbents hold significant sway, there is ample room for agile competitors and specialized innovators to capture value, particularly in regions and applications where scale-up is just beginning.
Diverse Application Landscapes
The utility of MOFs spans several critical industrial functions. Our report segments the market by application to highlight where value is being generated and where future demand will emerge. Two primary categories drive the current revenue streams: gas storage and purification, and catalysis. Additionally, emerging fields such as carbon capture and drug delivery are gaining substantial traction, contributing nearly half of the segmentation mix when combined with other evolving uses.
The dominance of gas storage and purification applications highlights the material's inherent strength in selective adsorption. Industries requiring high-purity gas streams or efficient storage solutions are increasingly turning to MOFs over traditional adsorbents. Simultaneously, the catalytic segment remains vital, leveraging the customizable nature of MOF structures to enhance reaction efficiencies in chemical synthesis.
Furthermore, the convergence of carbon capture initiatives with pharmaceutical development creates a unique dual-drive scenario. In the context of global decarbonization goals, the demand for efficient carbon capture materials is intensifying. Our analysis indicates that this segment, alongside drug delivery systems, represents a high-growth vector within the broader application landscape. However, the specific revenue attribution for each region and application is detailed exclusively in the full report to ensure stakeholders engage with the most granular level of intelligence without dilution.
Technological Typologies and Regional Nuances
Understanding the material types available in the market is crucial for supply chain planning. The market is segmented by type, including Zeolitic Imidazolate Frameworks (ZIFs), Ultranmicroporous IOs (UiOs), and other varying types. ZIFs and UiOs currently represent significant portions of the technology mix, each offering distinct advantages regarding stability and cost-effectiveness. Our report dissects these typologies to explain which materials are best suited for specific industrial pressures and temperatures.
Zeolite Molecular Sieves Market
Geography also plays a pivotal role in market distribution. The global landscape is divided into key regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique regulatory environments, industrial demands, and adoption rates. While North America and Asia Pacific show strong indicators of industrial scalability, Europe remains a hub for advanced research and specialized manufacturing. The full breakdown of regional revenue splits and growth rates is reserved for the detailed findings within the complete market study, allowing our clients to benchmark their regional strategies against precise competitive intelligence.
Competitive Landscape and Key Players
The MOF market is contested by a mix of established chemical giants and specialized technology firms. Our report provides a comprehensive profiling of the key companies shaping this ecosystem. BASF SE, headquartered in Ludwigshafen, Germany, stands out as an exclusive commercial manufacturer of the Basolite MOF series, focusing on industrial-scale CO2 capture and sustainability applications. Their recentachievement marks a significant milestone in the industry, as they became the first company to successfully produce metal-organic frameworks on a multi-ton production scale for carbon capture in late 2025.
Metal-organic Frameworks (MOF) Market
Another notable player is Promethean Particles Ltd, based in Nottingham, United Kingdom. They are recognized as a leading industrial-scale producer of cost-effective MOFs via a patented continuous-flow process. Their focus extends to carbon capture, biogas upgrading, and atmospheric water harvesting. In November 2025, Promethean Particles fulfilled its largest-ever order of four tonnes of MOF for commercial applications, signaling strong market demand. To further support their manufacturing scale-up, they appointed their first Chief Financial Officer in October 2025 and demonstrated their carbon capture technology at a prestigious Institute of Physics showcase in February 2026.
In the United States, framerica, Inc. operates out of College Station, Texas, supplying AYRSORB F250 and other coordination polymer MOFs for oil and gas gas purification and selective adsorption. NovoMOF AG, located in Zofingen, Switzerland, develops and supplies cost-effective, high-performance MOFs optimized for industrial carbon capture. NuMat Technologies, Inc., based in Evanston, Illinois, provides custom MOF adsorbents and materials for gas separation, catalysis, and energy applications.
Other significant contributors include MOFapps in Oslo, Norway, specializing in MOF-based solutions for gas purification, separation, and storage. Strem Chemicals, Inc. in Newburyport, Massachusetts, supplies high-purity MOF powders and research-grade materials for academic and industrial catalysis. Advanced Chemical Synthesis and Manufacturing (ACSYNAM) in Canada manufactures custom MOFs for separation and specialty applications. Mosaic Materials Inc. and Decarbontek, Inc. are also pivotal; Decarbontek notably launched the commercial production and sale of their low-cost DCF-1 MOF in July 2025, available at kilogram scale for carbon capture.
Recent Industry Developments Driving Momentum
The period from late 2025 into early 2026 has been characterized by tangible commercial milestones rather than theoretical developments. The shift toward multi-ton production scales is the most critical trend. BASF's multi-ton production capability for carbon capture sets a new benchmark for what is commercially feasible. Similarly, Decarbontek's launch of DCF-1 MOF at kilogram scale demonstrates that cost-effective materials are becoming available for broader deployment.
Promethean Particles' fulfillment of a four-tonne order reinforces the supply chain's ability to meet large-scale industrial requirements. Furthermore, their demonstration to HRH The Duke of Edinburgh at the Institute of Physics highlights the growing visibility and political recognition of MOF technology as a solution for climate challenges. These events are not isolated; they are indicators of a maturing supply chain capable of supporting the forecasted growth.
Strategic Value for Decision-Makers
This report is constructed to serve as a decision-support tool for various stakeholders, including investors, R&D directors, and corporate strategists. By integrating historical data with a forward-looking forecast till 2032, we provide a timeline that aligns with typical capital investment cycles. The detailed segmentation allows firms to identify whitespace opportunities where competition is less intense but demand is growing.
For companies involved in gas separation or carbon capture, understanding the supply dynamics of key manufacturers like BASF and Promethean Particles is essential for supply chain security. For investors, the market concentration data and growth rates offer a metric for evaluating potential returns in this high-CAGR environment. The inclusion of company profiles, including headquarters and specific offerings, ensures that our clients can map the competitive terrain accurately.
Conclusion: Accessing the Full Intelligence
The Metal-organic Frameworks market is poised for a decade of significant expansion, driven by technological breakthroughs and urgent industrial needs. The gap between laboratory promise and industrial scale is closing, and the firms that understand the nuances of this transition will lead the market. Our analysis provides the foundational knowledge required to navigate this complexity.
However, the true depth of this analysis lies in the detailed data tables, regional breakdowns, and specific application revenue splits that define the operational landscape. To access the complete strategic intelligence, including the full segmentation splits, precise regional valuations, and in-depth competitive benchmarking, we invite you to explore the full report. Equip your organization with the foresight needed to thrive in the evolving materials economy.
For detailed analysis of this topic, please visit the official page: Metal-organic Frameworks (MOF) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Battery Separator Films Market Hits $215M in 2025, Sees 6.98% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Battery Separator Films Market: A 2026 Outlook
As the global energy transition accelerates, the battery separator film has emerged as a critical enabler of lithium-ion battery safety, performance, and longevity. For executives navigating the complex landscape of electric vehicle (EV) manufacturing, energy storage systems (ESS), and advanced electronics, understanding the trajectory of this specialized materials market is no longer optional—it is a strategic necessity. This comprehensive market research report, published by PW Consulting, offers a definitive analysis of the Battery Separator Films Market, providing the granular intelligence required to make informed capital allocation and supply chain decisions in 2026 and beyond.
The market has demonstrated resilient growth over the past half-decade, evolving from a niche component supplier landscape into a strategic battleground for material science innovation and regional manufacturing sovereignty. With the base year established at 2025 and a forecast period extending through 2032, this study captures the inflection points where historical performance meets future projections. The analysis reveals a market that has grown from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025, reflecting a compound annual growth rate (CAGR) of 6.98 percent throughout the forecast period from 2026 to 2032. This trajectory underscores the intensifying demand drivers linked to electrification trends while highlighting the volatility inherent in raw material supply chains and geopolitical trade dynamics.
For corporate strategists, investors, and procurement leaders, the value of this report lies in its ability to transform broad market trends into actionable intelligence. Rather than offering generic industry overviews, this research delves into the operational realities of production capacity, technological shifts between wet and dry process methods, and the competitive maneuvers of key players spanning Tokyo, Seoul, Shanghai, and North America. The following sections outline the core components of this analysis and explain why mastering these insights is vital for securing a competitive advantage in the upcoming cycle.
Market Trajectory and Growth Dynamics
The historical data from 2020 to 2025 illustrates a consistent upward trend, though not without periods of adjustment. The market valuation moved from 168.79 million USD in 2021 to 172.93 million USD in 2022, before accelerating to 187.04 million USD in 2023 and 201.4 million USD in 2024. This progression signals a market recovering from supply chain disruptions and ramping up to meet the surging requirements of the EV sector. Looking forward, the forecast projects the market size to reach 227.89 million USD in 2026, escalating to 250.5 million USD by 2027, and potentially attaining 344.8 million USD by 2032.
Such growth is not merely a function of volume but is deeply tied to technological enhancements and safety regulations. The demand for thinner, stronger, and more thermally stable separator films is driven by the need to increase energy density while preventing thermal runaway. Consequently, the market dynamics are influenced by a confluence of factors including raw material price volatility, specifically regarding polyethylene and polypropylene feedstocks which experienced fluctuations in 2025 due to oil price instability and supply chain constraints. Understanding how these cost pressures interact with pricing strategies across different regions and applications is a key deliverable of this report.
Furthermore, the regulatory environment plays a pivotal role in shaping market geometry. In North America, the U.S. Department of Energy provided a 1.2 billion USD direct loan to ENTEK for its Terre Haute, Indiana lithium-ion battery separator facility, signaling a strong governmental push to support domestic EV supply chains. This move aligns with broader Inflation Reduction Act content requirements aimed at reducing reliance on foreign suppliers. Similarly, in Asia, consolidation efforts such as Sumitomo Chemical restructuring its PERVIO lithium-ion secondary battery separator business by ceasing production at Ohe Works in Japan and consolidating functions at SSLM in South Korea highlight the industry's drive toward higher productivity and optimized manufacturing footprints. These regulatory and operational shifts create distinct opportunities and risks that our analysis unpacks in detail.
Regional and Segmented Insights
While global aggregates provide the macro view, the real strategic value lies in understanding the regional distribution of capacity and consumption. The report segments the market across key geographies including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique characteristics regarding manufacturing maturity, demand concentration, and policy support. For instance, North American manufacturing capacity expansions have accelerated significantly in 2025 and 2026, driven by the aforementioned DOE support and local content requirements. Meanwhile, Asia Pacific remains a dominant hub for both production and consumption, reflecting the concentration of battery cell manufacturing and EV assembly in the region.
The segmentation by type reveals a market dominated by polyolefin films, which include polyethylene and polypropylene variants, alongside polyester and other specialized types. The choice between wet-process and dry-process technologies often depends on the specific application requirements, cost structures, and desired pore structure properties. Polyethylene films are frequently associated with wet-process manufacturing for high-performance applications, while polypropylene is often utilized in dry-process methods for cost-effective solutions. The report details the market share dynamics between these types without exposing the sensitive proprietary data required for competitive benchmarking, ensuring clients understand the technological landscape while preserving the exclusivity of the full dataset.
Worldwide Polyolefin Battery Separator Films Market
Application-wise, the market serves diverse sectors ranging from semiconductor wafer manufacturing to integrated circuit (IC) packaging and broader energy storage uses. The semiconductor sector demands extremely high purity and precision, whereas EV and ESS applications prioritize safety, thermal resistance, and throughput. The growth in EV and energy storage system deployments has been a primary catalyst for lithium-ion battery separator demand, necessitating films that can withstand higher voltages and temperatures. Our analysis correlates these application drivers with capacity expansion announcements from major manufacturers to forecast where demand will outstrip supply or where oversupply risks may emerge.
Competitive Landscape and Strategic Movements
The battery separator films market is characterized by a moderately concentrated competitive structure, with the top three players holding a combined market share of approximately 24.6 percent and the top five accounting for 26.2 percent. This fragmentation suggests room for consolidation but also indicates a competitive environment where specialized technology and regional partnerships drive success. The report profiles key companies that are defining the industry standards, including Asahi Kasei Corporation, Toray Industries, Inc., SK Innovation Co., Ltd., SEM CORP Co., Ltd., W-SCOPE Corporation, ENTEK International, LLC, Microporous LLC, Freudenberg Performance Materials, UBE Corporation, and Ahlstrom Oyj.
Each of these entities is pursuing distinct strategic pathways. Asahi Kasei Corporation, headquartered in Tokyo, produces Hipore wet-process polyethylene and Celgard dry-process polypropylene battery separator films, positioning itself at the forefront of both major manufacturing technologies. Recently, in October 2025, Asahi Kasei formed a strategic agreement with Toyota Tsusho for North American supply of Hipore wet-process lithium-ion battery separators, a move that secures downstream demand and strengthens its presence in the US market. Similarly, Toray Industries manufactures Setela coated and uncoated polyethylene and polypropylene battery separator films tailored for EV and energy storage applications, leveraging its material science expertise to enhance product performance.
In South Korea, SK Innovation Co., Ltd. develops and supplies ceramic-coated and non-coated polyolefin battery separator films with enhanced safety features, addressing the critical thermal stability concerns in high-energy density cells. W-SCOPE Corporation, also based in South Korea, completed a major expansion at its Chungju plant in May 2025, doubling its lithium-ion battery separator output capacity. This capacity doubling reflects the aggressive scaling required to meet regional demand surges. UBE Corporation produces battery separator base films and related polyolefin materials, and looking ahead to May 2026, UBE MAXELL plans a 50 percent increase in lithium-ion battery separator base film production capacity at its Sakai Works in Japan to support EV and energy storage demand.
In North America, ENTEK International, LLC manufactures wet-process polyethylene and coated lithium-ion battery separator films for EV and energy storage. ENTEK completed the first major expansion of its lithium-ion separator production in the U.S. with full-scale operations at the Terre Haute, Indiana facility in October 2025, a milestone supported by significant federal financing. Microporous LLC, based in Virginia, unveiled its new ultra-thin coated wet-process polyethylene lithium-ion battery separator line at the Piney Flats, Tennessee facility in July 2025, showcasing innovation in coating technologies that improve safety and performance. Microporous also produces the ionForce coated wet-process polyethylene lithium-ion battery separator films, distinguishing its product portfolio through specialized coating solutions.
Chinese supplier SEM CORP Co., Ltd. acts as a global supplier of lithium-ion battery separator films including coated and uncoated polyolefin options, reflecting the strong manufacturing base in Asia. Freudenberg Performance Materials, headquartered in Germany, supplies innovative separator materials for lithium-ion batteries and energy storage systems, bringing European engineering precision to the market. Ahlstrom Oyj, based in Finland, develops battery separator materials including absorbent glass mat (AGM) and polyolefin films, diversifying its portfolio beyond traditional lithium-ion applications. These profiles are accompanied by an analysis of their recent developments, financial standing, and strategic focus areas, providing a holistic view of the competitive battlefield.
Operational Realities and Supply Chain Resilience
Beyond company profiles, the report examines the operational dynamics that influence market stability. The volatility in polyethylene and polypropylene feedstocks experienced in 2025 serves as a case study for the raw material risks inherent in this industry. Oil price fluctuations and supply chain factors can rapidly alter cost structures, impacting profit margins and pricing power. The research provides frameworks for assessing supplier reliability and hedging strategies against raw material volatility.
Regulatory compliance is another critical dimension. The U.S. DOE loan program supported domestic battery separator manufacturing to reduce reliance on foreign suppliers and meet Inflation Reduction Act content requirements. This regulatory tailwind is reshaping the geography of production, encouraging investment in North American facilities while prompting Asian manufacturers to establish local partnerships or production hubs to remain competitive in Western markets. The report analyzes how these regulatory shifts affect market entry barriers, compliance costs, and long-term capacity planning.
Battery Separator Films Market
Moreover, the trend toward production consolidation, exemplified by Sumitomo Chemical's restructuring of its PERVIO business to SSLM in South Korea for higher productivity, indicates an industry maturing toward efficiency and scale. Such moves often signal shifts in market leadership and supply availability. Understanding the timing and rationale behind these consolidations allows businesses to anticipate supply tightness or loosening and adjust their procurement strategies accordingly.
Actionable Intelligence for 2026 Decision Making
The ultimate goal of this market research is to empower decision-makers with the clarity needed to navigate uncertainty. Whether you are evaluating potential investment opportunities, optimizing your supply chain for cost and resilience, or formulating R&D roadmaps for next-generation separator technologies, this report provides the foundational data and strategic context necessary for success. The detailed segmentation data, competitive benchmarking, and forecast models contained within the full document are designed to be integrated directly into strategic planning processes.
Key takeaways for 2026 include the recognition that regionalization of supply chains is accelerating, driven by policy incentives and risk mitigation strategies. Companies that secure reliable access to separator films in key markets will gain a significant advantage in battery production consistency. Additionally, the technological divergence between wet and dry processes, and the increasing adoption of ceramic coatings and ultra-thin films, presents opportunities for differentiation. Stakeholders must assess whether their current supplier base is aligned with these technological trends or if diversification is required.
The report also highlights the importance of monitoring M&A activity and strategic partnerships. With a CR5 of 26.2 percent, the market is not dominated by a single entity, leaving space for consolidation or disruptive entry. Recent developments such as capacity expansions and production line launches indicate where capital is flowing. By tracking these investments, clients can identify emerging capacity centers and potential bottlenecks before they impact market pricing or availability.
In conclusion, the Battery Separator Films Market is at a pivotal juncture where growth, technology, and geopolitics intersect. The comprehensive analysis provided by PW Consulting offers a roadmap through this complexity. To access the full suite of data, including detailed regional revenue breakdowns, specific application market sizes, and proprietary competitive intelligence, stakeholders are invited to explore the complete report. This deep dive will equip your organization with the foresight needed to capitalize on the opportunities of the energy transition while mitigating the risks inherent in a rapidly evolving materials market.
For detailed analysis of this topic, please visit the official page: Battery Separator Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com