

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Battery Separator Films Market Hits $215M in 2025, Sees 6.98% CAGR Through 2032

Strategic Imperatives in the Battery Separator Films Market: A 2026 Outlook
As the global energy transition accelerates, the battery separator film has emerged as a critical enabler of lithium-ion battery safety, performance, and longevity. For executives navigating the complex landscape of electric vehicle (EV) manufacturing, energy storage systems (ESS), and advanced electronics, understanding the trajectory of this specialized materials market is no longer optional—it is a strategic necessity. This comprehensive market research report, published by PW Consulting, offers a definitive analysis of the Battery Separator Films Market, providing the granular intelligence required to make informed capital allocation and supply chain decisions in 2026 and beyond.
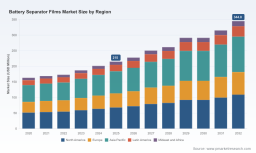
The market has demonstrated resilient growth over the past half-decade, evolving from a niche component supplier landscape into a strategic battleground for material science innovation and regional manufacturing sovereignty. With the base year established at 2025 and a forecast period extending through 2032, this study captures the inflection points where historical performance meets future projections. The analysis reveals a market that has grown from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025, reflecting a compound annual growth rate (CAGR) of 6.98 percent throughout the forecast period from 2026 to 2032. This trajectory underscores the intensifying demand drivers linked to electrification trends while highlighting the volatility inherent in raw material supply chains and geopolitical trade dynamics.
For corporate strategists, investors, and procurement leaders, the value of this report lies in its ability to transform broad market trends into actionable intelligence. Rather than offering generic industry overviews, this research delves into the operational realities of production capacity, technological shifts between wet and dry process methods, and the competitive maneuvers of key players spanning Tokyo, Seoul, Shanghai, and North America. The following sections outline the core components of this analysis and explain why mastering these insights is vital for securing a competitive advantage in the upcoming cycle.
Market Trajectory and Growth Dynamics
The historical data from 2020 to 2025 illustrates a consistent upward trend, though not without periods of adjustment. The market valuation moved from 168.79 million USD in 2021 to 172.93 million USD in 2022, before accelerating to 187.04 million USD in 2023 and 201.4 million USD in 2024. This progression signals a market recovering from supply chain disruptions and ramping up to meet the surging requirements of the EV sector. Looking forward, the forecast projects the market size to reach 227.89 million USD in 2026, escalating to 250.5 million USD by 2027, and potentially attaining 344.8 million USD by 2032.
Such growth is not merely a function of volume but is deeply tied to technological enhancements and safety regulations. The demand for thinner, stronger, and more thermally stable separator films is driven by the need to increase energy density while preventing thermal runaway. Consequently, the market dynamics are influenced by a confluence of factors including raw material price volatility, specifically regarding polyethylene and polypropylene feedstocks which experienced fluctuations in 2025 due to oil price instability and supply chain constraints. Understanding how these cost pressures interact with pricing strategies across different regions and applications is a key deliverable of this report.
Furthermore, the regulatory environment plays a pivotal role in shaping market geometry. In North America, the U.S. Department of Energy provided a 1.2 billion USD direct loan to ENTEK for its Terre Haute, Indiana lithium-ion battery separator facility, signaling a strong governmental push to support domestic EV supply chains. This move aligns with broader Inflation Reduction Act content requirements aimed at reducing reliance on foreign suppliers. Similarly, in Asia, consolidation efforts such as Sumitomo Chemical restructuring its PERVIO lithium-ion secondary battery separator business by ceasing production at Ohe Works in Japan and consolidating functions at SSLM in South Korea highlight the industry's drive toward higher productivity and optimized manufacturing footprints. These regulatory and operational shifts create distinct opportunities and risks that our analysis unpacks in detail.
Regional and Segmented Insights
While global aggregates provide the macro view, the real strategic value lies in understanding the regional distribution of capacity and consumption. The report segments the market across key geographies including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique characteristics regarding manufacturing maturity, demand concentration, and policy support. For instance, North American manufacturing capacity expansions have accelerated significantly in 2025 and 2026, driven by the aforementioned DOE support and local content requirements. Meanwhile, Asia Pacific remains a dominant hub for both production and consumption, reflecting the concentration of battery cell manufacturing and EV assembly in the region.
The segmentation by type reveals a market dominated by polyolefin films, which include polyethylene and polypropylene variants, alongside polyester and other specialized types. The choice between wet-process and dry-process technologies often depends on the specific application requirements, cost structures, and desired pore structure properties. Polyethylene films are frequently associated with wet-process manufacturing for high-performance applications, while polypropylene is often utilized in dry-process methods for cost-effective solutions. The report details the market share dynamics between these types without exposing the sensitive proprietary data required for competitive benchmarking, ensuring clients understand the technological landscape while preserving the exclusivity of the full dataset.
Worldwide Polyolefin Battery Separator Films Market
Application-wise, the market serves diverse sectors ranging from semiconductor wafer manufacturing to integrated circuit (IC) packaging and broader energy storage uses. The semiconductor sector demands extremely high purity and precision, whereas EV and ESS applications prioritize safety, thermal resistance, and throughput. The growth in EV and energy storage system deployments has been a primary catalyst for lithium-ion battery separator demand, necessitating films that can withstand higher voltages and temperatures. Our analysis correlates these application drivers with capacity expansion announcements from major manufacturers to forecast where demand will outstrip supply or where oversupply risks may emerge.
Competitive Landscape and Strategic Movements
The battery separator films market is characterized by a moderately concentrated competitive structure, with the top three players holding a combined market share of approximately 24.6 percent and the top five accounting for 26.2 percent. This fragmentation suggests room for consolidation but also indicates a competitive environment where specialized technology and regional partnerships drive success. The report profiles key companies that are defining the industry standards, including Asahi Kasei Corporation, Toray Industries, Inc., SK Innovation Co., Ltd., SEM CORP Co., Ltd., W-SCOPE Corporation, ENTEK International, LLC, Microporous LLC, Freudenberg Performance Materials, UBE Corporation, and Ahlstrom Oyj.
Each of these entities is pursuing distinct strategic pathways. Asahi Kasei Corporation, headquartered in Tokyo, produces Hipore wet-process polyethylene and Celgard dry-process polypropylene battery separator films, positioning itself at the forefront of both major manufacturing technologies. Recently, in October 2025, Asahi Kasei formed a strategic agreement with Toyota Tsusho for North American supply of Hipore wet-process lithium-ion battery separators, a move that secures downstream demand and strengthens its presence in the US market. Similarly, Toray Industries manufactures Setela coated and uncoated polyethylene and polypropylene battery separator films tailored for EV and energy storage applications, leveraging its material science expertise to enhance product performance.
In South Korea, SK Innovation Co., Ltd. develops and supplies ceramic-coated and non-coated polyolefin battery separator films with enhanced safety features, addressing the critical thermal stability concerns in high-energy density cells. W-SCOPE Corporation, also based in South Korea, completed a major expansion at its Chungju plant in May 2025, doubling its lithium-ion battery separator output capacity. This capacity doubling reflects the aggressive scaling required to meet regional demand surges. UBE Corporation produces battery separator base films and related polyolefin materials, and looking ahead to May 2026, UBE MAXELL plans a 50 percent increase in lithium-ion battery separator base film production capacity at its Sakai Works in Japan to support EV and energy storage demand.
In North America, ENTEK International, LLC manufactures wet-process polyethylene and coated lithium-ion battery separator films for EV and energy storage. ENTEK completed the first major expansion of its lithium-ion separator production in the U.S. with full-scale operations at the Terre Haute, Indiana facility in October 2025, a milestone supported by significant federal financing. Microporous LLC, based in Virginia, unveiled its new ultra-thin coated wet-process polyethylene lithium-ion battery separator line at the Piney Flats, Tennessee facility in July 2025, showcasing innovation in coating technologies that improve safety and performance. Microporous also produces the ionForce coated wet-process polyethylene lithium-ion battery separator films, distinguishing its product portfolio through specialized coating solutions.
Chinese supplier SEM CORP Co., Ltd. acts as a global supplier of lithium-ion battery separator films including coated and uncoated polyolefin options, reflecting the strong manufacturing base in Asia. Freudenberg Performance Materials, headquartered in Germany, supplies innovative separator materials for lithium-ion batteries and energy storage systems, bringing European engineering precision to the market. Ahlstrom Oyj, based in Finland, develops battery separator materials including absorbent glass mat (AGM) and polyolefin films, diversifying its portfolio beyond traditional lithium-ion applications. These profiles are accompanied by an analysis of their recent developments, financial standing, and strategic focus areas, providing a holistic view of the competitive battlefield.
Operational Realities and Supply Chain Resilience
Beyond company profiles, the report examines the operational dynamics that influence market stability. The volatility in polyethylene and polypropylene feedstocks experienced in 2025 serves as a case study for the raw material risks inherent in this industry. Oil price fluctuations and supply chain factors can rapidly alter cost structures, impacting profit margins and pricing power. The research provides frameworks for assessing supplier reliability and hedging strategies against raw material volatility.
Regulatory compliance is another critical dimension. The U.S. DOE loan program supported domestic battery separator manufacturing to reduce reliance on foreign suppliers and meet Inflation Reduction Act content requirements. This regulatory tailwind is reshaping the geography of production, encouraging investment in North American facilities while prompting Asian manufacturers to establish local partnerships or production hubs to remain competitive in Western markets. The report analyzes how these regulatory shifts affect market entry barriers, compliance costs, and long-term capacity planning.
Battery Separator Films Market
Moreover, the trend toward production consolidation, exemplified by Sumitomo Chemical's restructuring of its PERVIO business to SSLM in South Korea for higher productivity, indicates an industry maturing toward efficiency and scale. Such moves often signal shifts in market leadership and supply availability. Understanding the timing and rationale behind these consolidations allows businesses to anticipate supply tightness or loosening and adjust their procurement strategies accordingly.
Actionable Intelligence for 2026 Decision Making
The ultimate goal of this market research is to empower decision-makers with the clarity needed to navigate uncertainty. Whether you are evaluating potential investment opportunities, optimizing your supply chain for cost and resilience, or formulating R&D roadmaps for next-generation separator technologies, this report provides the foundational data and strategic context necessary for success. The detailed segmentation data, competitive benchmarking, and forecast models contained within the full document are designed to be integrated directly into strategic planning processes.
Key takeaways for 2026 include the recognition that regionalization of supply chains is accelerating, driven by policy incentives and risk mitigation strategies. Companies that secure reliable access to separator films in key markets will gain a significant advantage in battery production consistency. Additionally, the technological divergence between wet and dry processes, and the increasing adoption of ceramic coatings and ultra-thin films, presents opportunities for differentiation. Stakeholders must assess whether their current supplier base is aligned with these technological trends or if diversification is required.
The report also highlights the importance of monitoring M&A activity and strategic partnerships. With a CR5 of 26.2 percent, the market is not dominated by a single entity, leaving space for consolidation or disruptive entry. Recent developments such as capacity expansions and production line launches indicate where capital is flowing. By tracking these investments, clients can identify emerging capacity centers and potential bottlenecks before they impact market pricing or availability.
In conclusion, the Battery Separator Films Market is at a pivotal juncture where growth, technology, and geopolitics intersect. The comprehensive analysis provided by PW Consulting offers a roadmap through this complexity. To access the full suite of data, including detailed regional revenue breakdowns, specific application market sizes, and proprietary competitive intelligence, stakeholders are invited to explore the complete report. This deep dive will equip your organization with the foresight needed to capitalize on the opportunities of the energy transition while mitigating the risks inherent in a rapidly evolving materials market.
For detailed analysis of this topic, please visit the official page: Battery Separator Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com