

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ultra Fine Copper Powder Market Hits $260.4M in 2025, Projects 7.42% CAGR Through 2032

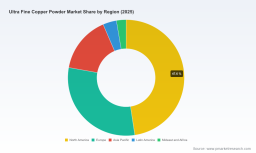
Navigating the Ultra Fine Copper Powder Market: Strategic Intelligence for 2026 and Beyond
The ultra fine copper powder market stands at a critical inflection point. As industries converge around electrification, advanced connectivity, and miniaturized electronics, the demand for high-purity, precision-engineered copper particles has transitioned from a niche specialty to a strategic commodity. For executive teams, procurement leaders, and R&D directors, understanding the trajectory of this market is no longer optional—it is a prerequisite for resilient supply chain design, capability investment, and competitive positioning.
Our latest market research provides a granular, forward-looking assessment of the ultra fine copper powder landscape, calibrated to support enterprise decision-making through 2032. This overview outlines the macro trajectory, the structural forces reshaping supply and demand, the evolving competitive architecture, and the practical intelligence embedded in the full study. The goal is to equip you with the analytical framework needed to act decisively in 2026, while preserving the proprietary segmentation and scenario modeling for direct access to the complete intelligence package.
The Macro Trajectory: Sustained Expansion Anchored in Advanced Manufacturing
The historical record and forward projections paint a picture of consistent, compounding growth. From a baseline of 183.0 million USD in 2020, the market advanced through a series of steady increments, reaching 235.3 million USD by 2024. The momentum carried into 2025 with a valuation of 260.4 million USD, setting the stage for an estimated 279.07 million USD in 2026. Looking further ahead, the trajectory ascends toward 323.91 million USD by 2028, 383.03 million USD by 2030, and a projected 428.5 million USD by 2032.
This expansion is underpinned by a forecast period compound annual growth rate of 7.42 percent across the 2026 to 2032 horizon. Such a rate reflects more than cyclical recovery; it signals a structural uplift driven by the integration of ultra fine copper powder into high-value applications where particle size, purity, morphology, and surface engineering directly dictate performance outcomes. The growth curve is not uniform across all endpoints, nor is it evenly distributed geographically. The full study decomposes these variations into actionable demand vectors, capacity allocations, and regional supply-demand balances, allowing strategic planners to isolate where volume growth will concentrate and where margin dynamics will diverge.
For organizations evaluating capital deployment, inventory strategy, or technology roadmaps, the headline numbers serve as a directional anchor. The real strategic value lies in understanding the composition of that growth: which particle classifications are accelerating, which application verticals are pulling demand faster than capacity can respond, and how regional production ecosystems are reconfiguring to meet localized regulatory and performance requirements.
Structural Forces Reshaping Supply, Demand, and Margin Architecture
The ultra fine copper powder market is being reshaped by a cluster of interdependent dynamics that extend well beyond raw volume growth. At the production level, the dominant fabrication pathways rely on atomization and advanced wet processes that deliver controlled particle size distributions and tailored surface characteristics. These processes, however, carry inherent cost and compliance implications. Production via atomization is materially more energy-intensive than standard copper processing, contributing to elevated material pricing and creating a cost floor that differentiates ultra fine grades from bulk copper commodities. Energy pricing volatility, therefore, translates directly into margin sensitivity for producers and into procurement risk for downstream buyers.
Regulatory pressure adds another layer of complexity. European Chemicals Agency data indicates that approximately 52 percent of producers face regulatory delays stemming from REACH compliance concerning nanoparticle safety and environmental impact for ultra fine copper powder. This compliance burden is not merely a procedural hurdle; it influences time-to-market for new grades, shapes geographic sourcing preferences, and raises the barrier to entry for capacity expansions that lack robust environmental management systems. Simultaneously, stringent environmental regulations on waste and emissions from atomization processes require significant investment in pollution control technologies. Producers that have already integrated advanced abatement infrastructure hold a structural advantage, while late movers face both capital intensity and operational continuity risk.
Demand-side dynamics are equally transformative. EU policies actively promote copper-based solutions for green technologies, increasing demand for high-purity ultra fine copper powder while enforcing compliance. This policy tailwind aligns with broader industrial trends: the proliferation of multi-layer ceramic capacitors in 5G infrastructure and electric vehicle power electronics, the expansion of conductive inks and pastes for printed electronics, and the growing utilization of copper powders in powder metallurgy and advanced coatings. The intersection of performance-driven engineering and sustainability mandates is compressing product development cycles and elevating the importance of traceable, specification-grade supply.
The full report maps these dynamics into distinct segments, analyzing how energy costs, regulatory timelines, and application performance thresholds interact to shape pricing architecture, capacity utilization, and supplier qualification criteria. Rather than treating regulation as an external constraint, the study frames it as a competitive variable that rewards integrated compliance capability and disciplined process engineering.
Ultra Fine Copper Powder Market
Competitive Architecture: Specialization, Capacity, and Regional Strength
The competitive landscape is characterized by a concentrated yet highly specialized set of producers. The market exhibits a moderate concentration profile, with the top three players accounting for approximately 35.4 percent of revenue and the top five reaching roughly 48.2 percent. This structure reflects a market where technical differentiation, process know-how, and application-specific qualification matter as much as scale. Execution risk is high, and customer switching costs are often tied to validated performance in critical electronic, energy, and industrial applications.
Japan remains a central hub of advanced capability. Mitsui Mining & Smelting Co., Ltd. specializes in ultra-fine copper powder production for electronic components, MLCC electrodes, and battery applications, leveraging advanced atomization and wet processes to meet tight specification requirements. Sumitomo Metal Mining Co., Ltd. manufactures high-purity ultra-fine copper powder for powder metallurgy, electronics, and advanced materials using proprietary atomization technology, positioning itself across both industrial and high-specification end markets. DOWA Electronics Materials Co., Ltd. focuses on high-purity ultra-fine copper powders for MLCC electrode pastes and multi-layer ceramic capacitor applications, with a recent capacity expansion further extending its manufacturing footprint to target reduced electronic components in electric and 5G technology. Fukuda Metal Foil & Powder Co., Ltd. offers ultra-fine copper powders for conductive pastes, 5G applications, and high-aspect-ratio flake powders, while Gripm Advanced Materials Co., Ltd. manufactures electronics-grade ultra-fine copper powders below 1 µm D50 with capacity expansions designed for high-volume supply. New Saga Material Technology Co., Ltd. operates as a custom manufacturer of superfine pure copper powder across defined grade families for electronics, diamond tools, and advanced materials.
In Europe, GGP Metalpowder AG produces ultra-fine copper powder grades with surface treatments for electronics, conductive inks, and powder metallurgy, and recently introduced an ultra-fine copper range with single surface treatment against oxidation for electronics and conductive applications. Pometon S.p.A. supplies atomized ultra-fine copper and copper alloy powders for industrial applications including wear-resistant coatings and electronics, reinforcing the region’s strength in application-engineered materials.
North America and transregional channels add further diversity. American Elements provides high-purity ultra-fine copper powder for electronics, metallurgy, and advanced materials with custom purity levels, while Kymera International supplies engineered ultra-fine copper powder for powder metallurgy and specialty applications. UF Copper Supply operates as an exclusive sales channel for ultra-fine copper powder manufactured in US and EU facilities, targeting additive manufacturing and industrial uses and thereby connecting specialized production to emerging deposition and printing workflows.
The competitive implication for 2026 is clear: procurement strategies that treat ultra fine copper powder as a fungible input will encounter hidden performance and continuity risks. Supplier selection increasingly hinges on process control, surface engineering capability, regulatory readiness, and the ability to scale specific grade families without compromising purity or morphology. The full study provides a structured competitive mapping that ties company capabilities to application requirements, recent capacity actions, and product introductions, enabling procurement and strategy teams to prioritize qualification efforts and negotiation leverage.
What the Full Report Delivers: Operational Intelligence for Executive Decision-Making
This market research is designed as a working intelligence asset rather than a static overview. It integrates historical reconstruction, forward modeling, and segment-level analysis into a decision-ready format. The report content is structured to support multiple enterprise functions simultaneously:
- Market sizing and trajectory modeling that connects baseline valuations through the forecast horizon, enabling scenario planning for volume, price, and capacity under varying demand and regulatory conditions.
- Segmentation analysis by type, application, and region that isolates the drivers behind growth concentration, identifies where specification requirements are tightening, and clarifies which demand pockets are likely to outpace near-term supply flexibility.
- Competitive profiling and recent development tracking that captures capacity expansions, product launches, and technology moves, translating corporate actions into implications for sourcing strategy, supplier risk, and market entry timing.
- Regulatory and compliance context that frames REACH-related delays, environmental abatement requirements, and green-technology policy incentives as variables that affect cost structure, qualification cycles, and geographic sourcing logic.
- Production economics and raw material dynamics that address the energy-intensity of atomization, the pricing implications relative to standard copper, and the interaction between process cost and grade differentiation.
- Strategic recommendation frameworks tailored for capacity planning, supplier consolidation or diversification, R&D prioritization, and market-entry evaluation, with specific attention to the trade-offs between scale, purity, and application performance.
By consolidating these elements, the study allows leadership teams to move from broad market awareness to targeted action. Whether the objective is to secure reliable access to electronics-grade grades, evaluate partnership or investment opportunities, or calibrate inventory and pricing strategy against energy and compliance cost curves, the report provides the structural context needed to justify decisions with evidence rather than assumption.
Why This Research Matters for 2026 Decision-Making
The 2026 decision environment will be defined by three overlapping pressures: performance specification tightening, regulatory and environmental compliance acceleration, and supply chain reconfiguration around critical electronic and energy materials. Ultra fine copper powder sits at the intersection of all three. As 5G infrastructure, electric vehicle electronics, advanced capacitors, conductive materials, and additive manufacturing workflows continue to scale, the requirement for controlled particle characteristics and high purity will intensify. At the same time, compliance timelines and abatement investments will separate suppliers that can deliver consistently from those that face qualification delays or cost shocks.
Organizations that treat these forces as isolated issues will likely overpay for supply, underestimate qualification risk, or misallocate R&D and capital toward grades with limited demand pull. Organizations that integrate market sizing, segment dynamics, competitive capability, and regulatory economics into a single strategic view will be better positioned to sequence investments, negotiate with informed leverage, and build supply resilience without sacrificing performance.
The full study provides the depth required to operationalize that view. It preserves the segmentation splits, regional balances, application-level demand drivers, and company-specific developments that turn macro growth into executable strategy. For teams preparing budgets, sourcing plans, technology roadmaps, or market-entry assessments for 2026, the research offers a calibrated baseline and a structured path to scenario-based decision-making.
Next Steps: Accessing the Complete Intelligence Package
The overview presented here establishes the strategic framing and the market logic, but the decisive detail resides in the complete report. Segmentation-level demand patterns, regional supply-demand balances, type-specific growth behavior, and company-specific capacity and product moves are synthesized into actionable insights that cannot be fully reproduced in a summary format. Accessing the full study enables procurement, strategy, and engineering leaders to align on specification priorities, qualification sequencing, supplier risk allocation, and investment timing with a shared evidence base.
Ultra Fine Copper Market
For organizations preparing for the 2026 operating environment, the most valuable move is to convert market awareness into structured intelligence. The complete research delivers that conversion, mapping the 7.42 percent growth trajectory and the associated structural dynamics into a practical toolkit for decision-making across the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Ultra Fine Copper Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com