

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Aqua Feed Market Hits $21.5B in 2025, Projects 6.98% CAGR to 2032

Global Aqua Feed Market Outlook 2026: Navigating Growth Trajectories and Strategic Imperatives
The global aquaculture industry stands at a critical inflection point as it enters the 2026 fiscal year. Driven by escalating protein demand, finite wild capture stocks, and rapid technological maturation in feed formulation, the sector is reshaping how capital is allocated, how supply chains are structured, and how regulatory compliance is operationalized. Our newly commissioned Aqua Feed Market research initiative is designed to cut through the noise of high-level trade publications and deliver boardroom-ready intelligence. Rather than offering static snapshots, this study maps the structural forces that will dictate competitive positioning, margin sustainability, and geographic expansion priorities over the next seven years.
For executives, procurement leaders, and investment committees, the 2026 decision environment demands more than backward-looking sales data. It requires a forward-looking lens that connects macro revenue trajectories with segment-level behavior, competitive intensity, and policy-driven cost pressures. This article provides a strategic preview of the research framework, outlines the operational intelligence embedded in the full report, and explains why the market dynamics captured here translate directly into actionable corporate strategy.
Macro Trajectory and the Strategic Relevance of the 2026 Baseline
The market has demonstrated consistent, compounding growth across the historical review window. From a foundational revenue base of approximately 16.3 billion USD in 2020, the sector advanced through successive annual increments to reach an estimated 21.5 billion USD in 2025. The forecast horizon extends through 2032, with the top-line trajectory projecting a continued upward arc that pushes aggregate revenues toward the mid-34 billion USD range by the terminal forecast year. The compound annual growth rate anchored across the full forecast window sits at 6.98 percent, a figure that signals durable demand expansion rather than a short-lived cyclical surge.
What makes the 2026 baseline particularly valuable for enterprise planning is its positioning at the intersection of post-pandemic recovery normalization, structural capacity additions, and early-stage regulatory recalibration. The jump from the 2025 close to the 2026 opening estimate reflects both organic volume growth and the beginning of capacity projects that broke ground in the prior two years. More importantly, the 2026 starting point sits just before a series of policy mandates and formulation transitions that will alter cost curves and procurement strategies across multiple regional markets. Companies that calibrate their 2026 operating plans to the inflection dynamics captured in this study will be better positioned to protect gross margins, secure raw material access, and align product roadmaps with emerging certification requirements.
Segment Architecture and Portfolio Implications
Revenue distribution across production formats, species applications, and geographic corridors reveals where competitive advantages are being forged and where margin compression is most likely. The research dissects the market along three core axes: feed type, application species, and regional footprint. Each axis carries distinct operational implications for formulation R&D, mill utilization, distribution logistics, and customer acquisition.
Within feed types, the analysis contrasts the scale economics of traditional pellet operations against the value-added positioning of extruded formats, while also tracking niche and specialty categories that serve high-margin species or functional nutrition programs. For manufacturers, the choice of format mix is no longer purely a technical decision; it is a capital allocation signal that determines exposure to energy intensity, extrusion line utilization rates, and downstream pricing power.
Feed + Aquafeed Market
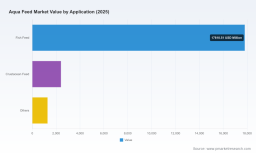
On the application side, the report maps revenue concentration across fish, crustacean, and other aquatic species categories. The commercial weighting of each application reflects both biological feed conversion dynamics and the maturity of regional aquaculture industries. Executives evaluating species diversification, vertical integration, or contract farming partnerships will find the application-level breakdowns essential for stress-testing revenue resilience against species-specific disease cycles, regulatory shifts, and input cost volatility.
Geographic distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa illustrates where production density, customer concentration, and growth velocity diverge. Rather than presenting static share figures, the full study connects regional totals to underlying drivers such as local milling capacity additions, species mix transitions, and trade flow adjustments. This framing allows strategists to identify where incremental investments will face headwinds from market saturation versus where earlier-stage demand curves still reward market entry or capacity expansion.
Competitive Intensity and the Restructuring of Market Power
The competitive landscape is defined by a moderately concentrated structure in which scale, formulation expertise, and regional milling footprints determine pricing leverage. The C3 concentration ratio of 24.6 percent and the C5 concentration ratio of 26.2 percent indicate that while top-tier players command meaningful share, substantial opportunity remains for mid-tier and regional specialists to compete through species-specific programs, localized supply chains, and differentiated nutrition platforms.
Global integrators such as Cargill Incorporated, Nutreco N.V., and BioMar A/S anchor the upper tier of the market. Cargill operates a broad international aqua nutrition footprint supported by a network of dedicated mills and species-focused brands, giving it the ability to serve salmon, shrimp, and other high-value segments at scale. Nutreco, through its Skretting platform, has consistently pursued capacity expansions and specialized formulations that target shrimp and other priority species, reinforcing its position as a technology-led supplier. BioMar has carved out a strong position in the high-value segment, ranking among the top global players and investing in capacity growth that aligns with premium salmon and shrimp demand.
The competitive field also includes specialized suppliers and regional powerhouses that shape local pricing dynamics and customer loyalty. Ridley Corporation Limited provides aqua feeds, additives, and premixes across global markets, while Alltech Inc. and Archer Daniels Midland Company contribute ingredient and nutrition-solution capabilities that influence formulation economics upstream. De Heus Animal Nutrition has accelerated its geographic expansion through new production facilities in Africa and Asia, directly challenging established incumbents in emerging corridors. Integrated operators such as Mowi plc illustrate a different competitive model, with dedicated in-house feed mills supplying the vast majority of their own farmed salmon requirements and thereby insulating part of their cost base from external market volatility.
In Asia and other high-growth regions, domestic manufacturers are rapidly scaling. Indian producers including Avanti Feeds Limited, Growel Feeds Private Limited, IFB Agro Industries Ltd, and Godrej Agrovet Limited are deepening their species coverage and formulation capabilities, while Thai Union Feedmill focuses on shrimp feed with recent profit growth reflecting strong sales momentum despite input cost pressures. In China, Haid Group operates at substantial scale with annual aquafeed volumes exceeding five million tonnes, underscoring the strategic weight of large domestic producers in shaping regional pricing and supply availability. European specialists such as Aller Aqua A/S and Dibaq Aquaculture complement the landscape with targeted fish and shrimp nutrition solutions that reinforce segment-level competition.
Operational Intelligence: What the Full Report Delivers
Beyond revenue corridors and competitor mapping, the study is built around actionable operational intelligence that connects strategy to execution. The report architecture is designed to support scenario planning, capital prioritization, procurement optimization, and regulatory readiness. Key deliverables include:
- Detailed revenue and volume trajectories across the 2026 to 2032 forecast window, structured to allow rolling adjustments as new operational data becomes available.
- Segment-level profiles that translate market size into realistic growth drivers, consumption patterns, and formulation demand shifts for each feed type and application category.
- Regional analyses that combine capacity additions, local species economics, trade dynamics, and policy influences to support market entry, capacity siting, and partnership decisions.
- Competitive benchmarking that evaluates scale, product breadth, regional presence, and recent strategic moves for the principal market participants.
- Regulatory and certification tracking, including the implications of updated sustainability and feed standards for mill compliance, ingredient sourcing, and customer qualification.
- Raw material cost and supply risk analysis, focusing on how protein sourcing dynamics, enzyme adoption, and alternative ingredient strategies affect formulation cost curves.
- Technology and innovation mapping that identifies where functional feeds, health-enhancing additives, and efficiency-driven formulations are creating premium pricing opportunities.
The methodology integrates historical reconstruction, forward-looking modeling, and qualitative validation to ensure that forecast outputs are tied to observable operational signals rather than abstract trend extrapolation. Each section is written to be usable by both commercial teams evaluating growth opportunities and supply chain teams managing cost and availability risk.
Policy, Raw Material, and Technology Pressures Reshaping Cost and Compliance
One of the most consequential dimensions of the 2026 outlook is the convergence of regulatory mandates, raw material volatility, and formulation innovation. These forces are not operating in isolation; they are interacting to redefine how mills manage phosphorus discharge limits, ingredient sourcing, and functional performance claims.
Regulatory dynamics are increasingly shaping formulation architecture. Recent updates to aquaculture sustainability and feed standards now require certified feed mills to align ingredient sourcing with defined environmental and traceability expectations. In parallel, national-level aquaculture acts are imposing nutrient discharge constraints that directly influence formulation chemistry. For example, phosphorus discharge limits in Norwegian production have pushed mills toward higher phytase enzyme usage and low-phosphorus formulations, a trend that illustrates how environmental policy translates into measurable changes in ingredient demand and additive consumption.
On the raw material side, protein sourcing remains a persistent cost driver. Supply disruptions in fishmeal markets have produced sharp price increases during short windows of scarcity, placing direct pressure on production economics and squeezing margins for mills that lack diversified ingredient strategies or long-term supplier arrangements. The resulting cost pressure is accelerating interest in alternative proteins, enzyme-enabled nutrient utilization, and formulation redesign that can preserve performance while reducing exposure to volatile marine ingredient markets.
Regional supply-side developments are also reshaping competitive geography. In Southeast Asia, estimated increases in national aquafeed production reflect recovery dynamics in local shrimp industries following contamination-related adjustments and remediation efforts. At the same time, new milling capacity in East Africa and expanded production in Indonesia is extending the physical footprint of suppliers and altering the balance between imported and locally produced nutrition solutions. These capacity shifts matter for procurement leaders because they change where volume can be sourced, how quickly mills can respond to regional demand spikes, and which competitors will control premium local relationships.
Why the 2026 Decision Window Requires Deep Market Intelligence
Entering 2026, the market rewards organizations that can connect top-line growth expectations with operational realities. A company may recognize that aggregate demand is expanding, but without a clear understanding of how revenue is distributed across formats, species, and regions, capital can be misallocated into overcapacity in mature corridors or underinvestment in higher-growth applications. Similarly, competitive strategy becomes reactive if the firm does not know where scale advantages are durable, where specialists are gaining ground, and where regulatory or raw material shifts will alter cost structures fastest.
The strategic value of this research lies in its ability to convert macro trajectory into execution-ready insight. For procurement and formulation teams, the report supports ingredient substitution planning, enzyme adoption analysis, and supplier diversification strategies. For commercial and business development teams, it helps prioritize species programs, regional expansion targets, and partnership structures. For executive leadership and investors, it provides a defensible base for capacity planning, margin defense, and competitive positioning across the forecast horizon.
Conclusion and Next Steps
The global aqua feed market is advancing along a credible growth path, but the returns on strategy will depend on how precisely organizations interpret the underlying drivers of that growth. The 2026 to 2032 period will reward players who understand where concentration is meaningful, where regional capacity is shifting, and how regulatory and raw material pressures are reshaping formulation economics. It will also reward those who move early on certification readiness, functional nutrition development, and supply chain diversification before structural advantages harden further.
Aqua Feed Market
This article has outlined the strategic framing and analytical depth embedded in our latest Aqua Feed Market study, but the full intelligence set includes the detailed segment breakdowns, company-specific benchmarking, regional capacity assessments, and forward-looking scenario analyses required to make precise planning decisions. To access the complete dataset, competitive profiles, and operative market forecasts that support 2026 strategy formulation, request the full report through our research portal and equip your leadership team with the intelligence needed to act ahead of market consolidation.
For detailed analysis of this topic, please visit the official page: Aqua Feed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com