

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: PTBBA Market to Reach $143.63M by 2032, Driven by 4.65% CAGR
By pmarketresearch, 2026-09-16
Navigating the Global 4-tert-Butylbenzoic Acid Market: Strategic Insights for 2026 and Beyond
Executive Summary: The Imperative for Data-Driven Decision Making
The global chemical landscape is undergoing a period of recalibration, driven by shifting supply chain dynamics, evolving regulatory frameworks, and persistent demand from core polymer and specialty applications. For decision-makers operating in the intermediates and additives space, 2026 represents a pivotal inflection point. In this environment, precision intelligence is no longer optional; it is the foundation of resilient capacity planning, procurement strategy, and competitive positioning. PW Consulting's latest Worldwide 4-tert-Butylbenzoic Acid (PTBBA) Market research report delivers exactly that— a comprehensive, forward-looking analytical framework designed to translate market complexity into actionable strategy.
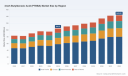
This report sits at the intersection of historical performance and forward trajectory. Drawing on a rigorous historical window spanning 2020 through 2025 and projecting outcomes across the 2026–2032 forecast horizon, the analysis captures both the structural consolidation of recent years and the emergent growth vectors that will define the next cycle. The overarching narrative is one of measured, sustained expansion: the market is projected to grow at a compound annual growth rate of 4.65 percent, supported by steady demand absorption across mature polymer applications and incremental pull from specialty grade requirements. Revenue is tracked in USD millions, providing a consistent valuation baseline for cross-markет benchmarking and investment modeling.
Worldwide 4-tert-Butylbenzoic Acid (PTBBA) Market
What distinguishes this study is its refusal to stop at headline growth. Instead, it dissects the operational and commercial architecture that underpins market performance—segment definitions, regional demand distribution, grade differentiation, feedstock economics, and the competitive maneuvers of incumbent and emerging players. The result is a strategic toolkit calibrated for procurement leaders, capacity planners, M&A analysts, and market entry strategists who need to navigate a market where margin preservation and supply security are increasingly intertwined.
Macro Market Architecture: Growth Trajectory and Structural Composition
The baseline market valuation establishes a clear upward slope over the analysis period. Revenue progressed from a measured base in the early 2020s, absorbed a notable acceleration during the 2022–2023 interval, and stabilized into a higher-order equilibrium by 2025. Looking ahead, the forecast arc signals consistent year-on-year expansion, with the market advancing through a series of stepwise increments that culminate in a substantially larger revenue pool by the close of the 2032 horizon.
This trajectory is not a mechanical extrapolation. It reflects the interplay of application reuse, downstream polymer demand retention, and the steady rationalization of grade specifications. The report frames this growth through three foundational segmentation lenses, each of which carries distinct commercial implications for buyers and producers alike.
Grade segmentation highlights the differentiated value pools within the market. High-purity refined grades command structural dominance in specification-sensitive applications, while industrial-grade material sustains a meaningful share tied to cost-optimized formulations and bulk processing. The split between these tiers matters because it shapes pricing architectures, contract structures, and qualification pathways—particularly for buyers who must balance performance requirements against total cost of ownership.
Application segmentation underscores the concentration of demand across a handful of core uses. A leading application category anchors a substantial portion of total consumption, supported by a secondary tier of high-volume functional additives and a broader tail of specialty and niche uses. This demand architecture has direct consequences for supply reliability, inventory strategy, and the pace at which new capacity can be absorbed without creating localized oversupply.
Regional segmentation reveals a market whose demand geography is heavily weighted toward one dominant zone, with a layered set of secondary regions contributing differentiated volumes. This distribution pattern has strategic ramifications for logistics optimization, localized inventory positioning, and the negotiation of long-term supply agreements. It also frames the relative exposure of different buyer bases to freight volatility, import dependency, and regional regulatory shifts.
Strategic Segment Intelligence: Understanding the Layers That Drive Value
For executives who require more than aggregated totals, the report delivers a granular but disciplined breakdown of the segments that constitute the total market. Rather than presenting segmented data as isolated percentages, the analysis contextualizes each layer within its commercial logic—explaining why certain grades persist in premium positioning, why specific applications exhibit resilient consumption, and how regional demand concentration influences sourcing risk.
The refined-grade segment, defined by purity thresholds exceeding 99 percent, occupies a central role in applications where impurity control, reproducibility, and downstream processing consistency are non-negotiable. Buyers in this tier typically operate under tighter qualification cycles and prioritize supplier reliability over marginal price differences. The industrial-grade segment, spanning the 98–99 percent range, serves a different commercial logic—one oriented toward volume efficiency, cost containment, and formulation flexibility. Understanding the balance between these two pools is essential for producers calibrating product mix and for buyers evaluating whether grade substitution is technically viable within their own processes.
On the application side, the analysis maps how demand concentrates around polymer stabilization, nucleating functionality, resin modification, and select personal care and specialty uses. Each application cluster carries its own demand elasticity, formulation sensitivity, and substitution risk. The leading application category continues to absorb the largest share of total consumption, but the report equally tracks the contribution of nucleating agents and alkyd resin modifiers as meaningful secondary pillars. A smaller but strategically important tail of personal care and cosmetic applications, alongside other niche uses, rounds out the demand base—offering incremental growth optionality without destabilizing the core volume profile.
Regionally, the report frames the global demand map as a hierarchy rather than a flat aggregate. A leading Asia-Pacific concentration anchors the market's volume center of gravity, while Europe, North America, and a combined rest-of-world grouping contribute differentiated demand layers. This distribution has consequences for everything from freight and inventory strategy to the relative attractiveness of localized production versus import dependency. The analysis intentionally avoids reducing regional dynamics to simple share percentages; instead, it situates them within the operational realities of sourcing, lead-time management, and regulatory exposure that actually drive procurement decisions.
Competitive Landscape and Recent Industry Developments
The PTBBA market is characterized by a mix of scale-oriented producers, specialty-grade specialists, and geographically distributed suppliers whose competitive positioning varies by region, product tier, and application focus. The report profiles a curated set of key companies whose activities collectively shape pricing behavior, supply availability, and the pace of capacity evolution.
Among the profiled participants, several Chinese manufacturers stand out for their scale orientation and vertically integrated operational models. Fareast Kingstar Chemical positions itself as a major PTBBA producer with substantial annual production capacity and a broader product footprint that includes related intermediates. Its integration of research, production, and sales, backed by ISO 9001 and ISO 14001 certification, reflects the operational discipline increasingly demanded by downstream buyers. Shanghai Ruifu Chemical similarly emphasizes high-purity material above 99.0 percent by HPLC, with capabilities spanning small to bulk quantities and custom synthesis support—an offering profile that appeals to buyers requiring specification assurance and flexible order structures.
Beyond China, the competitive field includes Japanese and Korean participants with distinct value propositions. FUSO CHEMICAL supplies PTBBA within its electronic materials portfolio, packaged for controlled handling and specification integrity across 20 kg paper bag and 500 kg big bag formats—a logistics and quality-control emphasis that differentiates it in specification-sensitive procurement contexts. Dsn Chem Co., Ltd. operates as an active export-oriented supplier, reinforcing the global reach of secondary-source options that buyers can leverage for supply diversification.
India's Vinati Organics contributes a distinct application angle, producing PTBBA used in alkyd resin stabilization and sunscreen-related formulations, with a track record of pursuing capacity expansions tied to PTBBA-related production. Additional Chinese producers, including Jiangxi Yongtong Technology, Hebei Aoge Chemical, Dalian Richfortune Chemicals, Haicheng Huacheng Chemical, and China Haohua Chemical Group, populate the broader supply base, each contributing to the market's overall availability and competitive tension across industrial and polymer-additive segments.
Recent developments further shape this competitive picture. A capacity expansion signal observed in April 2026 underscores a structural shift: reliance on imported intermediates for high-purity PTBBA is prompting investments in domestic capacity expansion, particularly across Asia. For procurement and supply-chain leaders, this signals a medium-term recalibration of import dependency, potential shifts in lead times, and the gradual emergence of new supply nodes that could alter regional negotiation dynamics.
Tetrabromobisphenol-A (TBBA) (CAS 79-94-7) Market
On the regulatory and trade front, a European Commission autonomous tariff suspension for 4-tert-butylbenzoic acid has maintained a zero-duty environment through the end of 2027. This policy posture reduces one layer of cost friction for import-dependent European buyers and reinforces the strategic relevance of import logistics and supplier qualification within the EU market context.
Feedstock Economics, Regulatory Context, and Demand Drivers
No analysis of PTBBA market dynamics is complete without addressing the upstream economics and regulatory architecture that condition supply behavior. The primary feedstock for 4-tert-Butylbenzoic Acid is p-tert-butyltoluene, produced via alkylation of toluene and subsequently oxidized to PTBBA. This linkage means that feedstock availability and pricing exert a direct influence on PTBBA production economics. Industry data points to a notable year-on-year price rise in related TBT markets, which has affected 2026 capacity utilization and reinforced the importance of feedstock hedging, supplier relationship management, and formulation flexibility.
Regulatory context adds another strategic dimension. PTBBA is registered under REACH with harmonized classification elements that include reproductive toxicity category considerations and specific hazard statements. For downstream users, this translates into documentation requirements, handling protocols, and supplier due diligence that must be factored into sourcing decisions. The regulatory landscape is also evolving in adjacent geographies: Taiwan's environmental authority included 4-tert-butylbenzoic acid in its prioritized existing chemicals batch for data collection and assessment, signaling a potential trajectory of heightened data requirements and compliance scrutiny in one more regional market.
On the EU side, historical context remains relevant for understanding current supply patterns. The absence of active EU production since around 2006 means that European demand relies on imports, with historical market volume estimates framing the scale of that import-dependent demand base. Combined with the tariff suspension environment, this creates a market structure where import reliability, supplier qualification, and logistics resilience are especially salient for European procurement teams.
These feedstock and regulatory dynamics do not merely add background color; they actively shape margin structures, supply risk profiles, and the relative attractiveness of different sourcing strategies. The report integrates these factors into its forward analysis so that buyers and producers can assess not just where demand is going, but what constraints and opportunities will condition the path to get there.
What the PW Consulting Report Delivers: Practical Tools for 2026 Strategy
Beyond market sizing and segmentation, the report is built around practical analytical deliverables that convert information into decision support. It provides a structured view of the competitive field, enabling users to map supplier capabilities, grade specializations, and regional footprints against their own procurement and expansion requirements. It frames demand by application and grade in a way that supports formulation planning, qualification prioritization, and substitution analysis. It contextualizes feedstock and regulatory factors so that supply-chain teams can incorporate them into risk assessments and sourcing models rather than treating them as peripheral considerations.
The report also addresses the operational implications of recent capacity and trade developments. By linking the observed capacity expansion signal to its underlying driver—imported intermediate reliance—and connecting the European tariff environment to its implication for import cost structures, the analysis helps users anticipate shifts rather than simply react to them. This forward orientation is particularly valuable for teams planning contract negotiations, inventory positioning, and qualification pipelines in a year when supply-side dynamics are actively evolving.
Concentration metrics further enrich the competitive picture. The market displays a meaningful degree of supplier concentration, with a defined share captured by a smaller group of leading participants. For buyers, this has implications for negotiation leverage, qualification redundancy, and the strategic value of qualifying secondary sources. For producers and investors, it highlights the commercial significance of scale, grade differentiation, and application-specific positioning as the market matures.
Why This Research Matters for 2026 Decision-Making
In a market defined by measured growth, concentrated demand, and shifting supply-side incentives, strategic advantage belongs to organizations that can align their sourcing, production, and expansion decisions with a clear-eyed view of where the market is heading. The PW Consulting Worldwide 4-tert-Butylbenzoic Acid Market report is designed to provide that view. It combines historical grounding, forward projection, segment-level intelligence, competitive profiling, and regulatory and feedstock context into a single analytical framework calibrated for executive use.
For procurement leaders, the report supports more resilient sourcing strategies by clarifying the demand layers, grade sensitivities, and supplier capabilities that actually drive supply security. For capacity planners and producers, it provides a demand trajectory and segmentation context that can inform investment timing, product-mix calibration, and regional focus. For market-entry and M&A teams, it offers the structural insight needed to evaluate where value is created, where competition is intensifying, and where white space or consolidation opportunities may emerge.
Full detail, including complete segmentation figures, regional and application-level data, and extended competitor profiles, is available in the complete study. The summary presented here is intended to demonstrate the analytical depth and strategic relevance of the research while preserving the full dataset and supporting detail for the in-depth review. Readers seeking the complete intelligence package are encouraged to access the full report to ensure that procurement, investment, and planning decisions are grounded in the complete market picture.
For detailed analysis of this topic, please visit the official page: Worldwide 4-tert-Butylbenzoic Acid (PTBBA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cooperage Equipment Market Hits $210.5M in 2025, Projects 6.85% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Cooperage Equipment Market: Navigating the 2026 Landscape
Executive Overview
The global cooperage equipment market is undergoing a structural transformation, driven by tightening quality standards in premium winemaking, evolving spirits aging protocols, and continuous automation across production facilities. Our latest market research provides decision-makers with a rigorous, forward-looking assessment of how equipment procurement, capacity planning, and competitive positioning will evolve through 2032. For executives operating in food and beverage manufacturing, industrial packaging, or specialized barrel production, this intelligence report delivers the analytical framework needed to align capital allocation with long-term operational resilience.
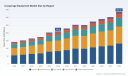
Drawing on historical performance data spanning 2020 through 2025 and projecting forward across the forecast period, the study maps a clear trajectory of sustained expansion. The overall market revenue reached approximately 210.5 million USD in 2025, reflecting a compound annual growth rate of 6.85 percent projected across the forecast horizon. By 2032, the sector is positioned to surpass 336 million USD in total revenue. These figures represent more than isolated growth metrics; they signal a maturing equipment ecosystem that is increasingly defined by precision engineering, workflow integration, and selective automation. For corporate strategists, understanding where value is concentrated and how purchasing priorities are shifting will determine competitive advantage in the coming cycle.
Market Trajectory and Strategic Implications
The historical arc from 2020 to 2025 reveals a consistent upward trend, with periodic accelerations tied to capacity expansions and technology adoption cycles. Revenue climbed from 142.35 million USD in 2020 to 151.89 million USD in 2021, then to 164.46 million USD in 2022, before reaching 173.91 million USD in 2023. The pace quickened notably as manufacturers invested in modernization, pushing figures to 202.97 million USD in 2024 and stabilizing at 210.5 million USD in 2025. This progression illustrates how post-pandemic operational restructuring and sustained demand for high-quality aging containers have reinforced investment confidence.
Looking ahead, the forecast period outlines a steady climb: 228.85 million USD in 2026, followed by 252.72 million USD in 2027. A brief normalization is expected in 2028 at 251.36 million USD, after which the market resumes its expansion toward 273.85 million USD in 2029, 290.19 million USD in 2030, 302.36 million USD in 2031, and 336.32 million USD in 2032. This pattern reflects a market that is not merely growing but recalibrating around efficiency, durability, and process control. Strategists should interpret these movements as indicators of where procurement budgets will be allocated, which equipment categories will face supply constraints, and how regional production networks will respond to shifting input costs.
Category Architecture and Operational Demand
The report dissects the market through multiple lenses, beginning with equipment type. Automatic equipment currently commands the larger revenue share, reflecting a broader industry preference for integrated handling, precision toasting, and repeatable finishing workflows. Manual equipment maintains a substantial presence, particularly among smaller production houses and specialty operations that prioritize flexibility and lower upfront capital exposure. The balance between these two categories continues to evolve as labor availability, throughput expectations, and quality assurance requirements reshape purchasing criteria.
Cooperage Equipment Market
Application segmentation further clarifies how demand is distributed across end-use environments. The food and beverage sector anchors the majority of equipment consumption, driven by beverage maturation, barrel maintenance, and hygiene-focused processing requirements. Industrial applications follow as a secondary but strategically important segment, while other specialized uses contribute additional demand where customized barrel construction or niche finishing processes are required. Understanding how these application streams interact with procurement cycles, maintenance schedules, and technology upgrade paths is essential for forecasting equipment utilization and capital replacement timing.
Wine Fermentation Equipment Market
Geographic Distribution and Supply Chain Considerations
Regional dynamics play a defining role in how equipment demand materializes. Europe represents the most significant market concentration, reflecting the depth of traditional barrel craftsmanship, established winery infrastructure, and sustained investment in aging-related processing. North America follows as a major demand center, shaped by large-scale beverage production, expanding distillery operations, and ongoing facility modernization. Asia Pacific, Latin America, and the Middle East and Africa collectively add further layers of growth, with each region exhibiting distinct procurement rhythms, import dependencies, and capacity-building timelines.
For strategic planners, regional variation is not simply a geographic breakdown but a signal of where service networks, parts availability, and technical support must be positioned. Companies evaluating expansion, distributor partnerships, or localized service capabilities will find the report’s regional analysis instrumental in mapping execution risk and identifying where equipment deployment is likely to face the strongest operational pull.
Competitive Landscape and Enterprise Positioning
The market’s competitive structure remains moderately concentrated, with the top three participants accounting for approximately 38.5 percent of revenue and the top five reaching about 52.7 percent. This concentration indicates a landscape where established suppliers hold meaningful influence over product standardization, service ecosystems, and technological direction, while still leaving room for specialized players to differentiate through application expertise, regional reach, and targeted product lines.
Within this environment, several companies illustrate the breadth of strategic approaches shaping the sector. Prospero Equipment Corporation, headquartered in Windsor, California, supplies cooperage equipment including barrel washers, hoop drivers, and stave planers designed for wine and spirits producers. Its recent expansion of an updated product catalog in October 2025, featuring enhanced barrel toasting and steaming equipment lines, underscores how suppliers are aligning product portfolios with production efficiency and quality consistency.
Winequip, based in Melbourne, Australia, provides cooperage machinery such as barrel repair tools, toasting equipment, and automated barrel handling systems. Its product breadth highlights the growing importance of post-production maintenance, repair capabilities, and workflow automation in sustaining long-term equipment utilization. Vintner Vault, operating from Paso Robles, California, distributes cooperage equipment including barrel racks, washing systems, and maintenance tools tailored for commercial wineries. Its distribution-oriented model demonstrates how channel strategies continue to influence equipment accessibility and implementation speed for operating facilities.
These enterprises represent different facets of the same competitive logic: product reliability, application-specific support, and the ability to meet evolving throughput expectations. The report evaluates how such players position themselves across product lines, geographic coverage, and service intensity, giving buyers and investors a structured view of where partnerships, procurement consolidation, or competitive displacement may emerge.
Operational Pressures and Input Market Reality
Equipment strategy cannot be separated from the material environment in which it operates. In 2025, French oak stave prices increased by 12 percent year-over-year due to supply constraints from European forests. This shift directly affects barrel production economics and, by extension, the demand profile for equipment that improves yield, reduces waste, and standardizes finishing outcomes. When raw material volatility intensifies, manufacturers and distributors increasingly look to equipment investments that enhance process control, improve throughput predictability, and support more consistent aging results.
For procurement leaders, this dynamic reinforces the importance of evaluating equipment not only on purchase price but on total operational value: durability, serviceability, integration with existing line configurations, and the capacity to adapt to material variability. The study incorporates these considerations into its analytical framework, helping decision-makers weigh capital deployment against the backdrop of input cost pressure and supply chain uncertainty.
What the Research Delivers for 2026 Decision-Making
This market research is structured to support practical strategic action rather than abstract observation. It combines historical trend analysis, forward-looking projections, category-level segmentation, and competitive profiling into a single decision-support framework. Readers will gain clarity on how equipment demand is evolving across major application streams, where automation is reshaping purchasing priorities, and how leading suppliers are adjusting their portfolios in response to production and material conditions.
The report also provides guidance on evaluating procurement timing, assessing service and maintenance requirements, and interpreting regional demand signals that influence deployment strategy. By integrating market size progression, concentration patterns, and company-level developments into a coherent narrative, the study enables executives to benchmark internal plans against broader market movement and to identify where strategic investment may yield the strongest operational return.
Conclusion
The cooperage equipment market is entering a phase where growth is increasingly tied to operational precision, automation maturity, and responsiveness to material cost dynamics. With revenue projected to advance from 228.85 million USD in 2026 toward 336.32 million USD by 2032, the sector presents both opportunity and execution risk for organizations navigating equipment procurement, production scaling, and competitive positioning. This research report is designed to give strategists, purchasing leaders, and industry executives the context needed to make informed decisions with confidence. To access the complete segmentation analysis, regional breakdowns, application-level demand patterns, and full competitive profiling, visit the source page for the complete intelligence package.
For detailed analysis of this topic, please visit the official page: Cooperage Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Antiperspirant Aluminum Chlorohydrate Market Hits $850M in 2025, Projected 5.2% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Worldwide Antiperspirant Aluminum Chlorohydrate Market: Strategic Intelligence for 2026
The global personal care industry stands at a critical juncture where formulation efficacy, regulatory compliance, and supply chain resilience intersect. For decision-makers operating within or adjacent to the antiperspirant sector, understanding the trajectory of aluminum chlorohydrate is no longer optional. As the primary active ingredient responsible for sweat reduction, aluminum chlorohydrate anchors a market that has demonstrated steady expansion through recent historical cycles and is projected to maintain disciplined growth over the coming forecast horizon. PW Consulting has compiled a comprehensive Worldwide Antiperspirant Aluminum Chlorohydrate Market study designed to translate macroeconomic signals, competitive movements, and regulatory shifts into actionable intelligence for 2026 and beyond.
This research is structured as a strategic companion rather than a static data repository. It maps historical performance across a six-year retrospective window and extends forward through a multi-year forecast period, enabling stakeholders to align procurement timelines, capacity planning, and market entry strategies with verified directional trends. The base year anchors the analysis at 2025, providing a calibrated reference point from which growth rates, concentration dynamics, and segment equilibria are measured. Readers seeking granular percentage allocations, discrete regional revenue figures, and application-specific breakdowns will find those detailed datasets within the full publication, where they are presented alongside methodological notes and scenario sensitivity models.
Market Trajectory and Macro Growth Architecture
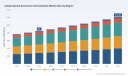
The worldwide antiperspirant aluminum chlorohydrate market has moved from a 2023 baseline of approximately 768 million USD to an estimated 808 million USD in 2024, reaching a projected 850 million USD in 2025. This progression reflects a compound annual growth rate of roughly 5.2 percent across the forecast horizon extending through the early 2030s. Such a cadence signals a mature yet expanding category, where volume gains are increasingly intertwined with value optimization, grade differentiation, and formulation innovation rather than relying solely on population-driven demand expansion.
Forward-looking valuations trace a consistent upward slope, with the market projected to approach 894 million USD in 2026, rising to 940 million USD in 2027 and crossing the 1 billion USD threshold shortly thereafter. The trajectory culminates in a projected 1.2 billion USD valuation by the end of the forecast window. This growth architecture is underpinned by continuous refresh cycles in personal care portfolios, the proliferation of body confidence and performance-oriented grooming products, and sustained demand for reliable sweat-control actives that function across diverse climatic and cultural usage patterns.
Importantly, these headline figures represent aggregate market dynamics. The distribution of value across forms, application formats, and geographies is far from uniform. Liquid formulations continue to command a substantial share of the total value pool, while powder-based routes maintain a distinct but smaller footprint. Within application channels, roll-on and stick formats have historically anchored consumer preferences, with sprays and creams-and-other segments contributing more specialized demand profiles. Regional performance similarly reflects divergent purchasing power, climatic drivers, and regulatory environments. The complete study isolates these dimensions with precise calibration, enabling readers to benchmark their own portfolio exposure against verified segment equilibria and to identify where competitive intensity is most concentrated.
Report Content and Operational Utility for Executives
PW Consulting’s analysis is engineered for immediate operational relevance. Beyond macro valuation frames, the report delivers a structured examination of market architecture, competitive positioning, and the external forces that shape cost structures, formulation choices, and compliance pathways. The content is organized to support cross-functional alignment among procurement, R&D, regulatory affairs, and commercial strategy teams, ensuring that insights can be translated into concrete action plans without requiring additional data reconstruction.
The document includes a detailed segmentation exploration that maps how different product forms and application formats compete for consumer attention and manufacturer investment. It describes the structural factors that drive volume allocation across these categories, including textural expectations, packaging compatibility, ease of formulation, and regional usage habits. By presenting these dynamics in a comparative framework, the report helps stakeholders identify where formulation innovation can unlock incremental share and where cost optimization may be achieved through grade selection or processing adjustments.
Supply-side intelligence forms another core pillar of the publication. The research examines the upstream ecosystem that feeds aluminum chlorohydrate production, including the role of alumina feedstocks, specialty chemical processing, and purity specifications required for cosmetic and personal care applications. It contextualizes how raw material pricing movements, refinery and specialty alumina capacity decisions, and logistics cost fluctuations influence the effective cost of goods for downstream formulators. These elements are treated not as isolated news items but as integrated variables within a cost-and-supply model that can be applied to budgeting, hedging considerations, and supplier evaluation processes.
The report also incorporates a regulatory and compliance review that addresses evolving chemical safety frameworks, concentration limits, labeling requirements, and regional substance restrictions. Regulatory trajectories are analyzed for their potential to reshape formulation choices, especially in high-sensitivity markets where consumer exposure concerns intersect with product efficacy expectations. By mapping these developments alongside ingredient functionality and grade differentiation, the study equips teams to anticipate reformulation needs, assess alternative grade suitability, and maintain alignment with both current mandates and emerging precaution-based standards.
Competitive Landscape and Key Company Positioning
The antiperspirant aluminum chlorohydrate market reflects a moderately concentrated competitive environment, with a limited group of large suppliers accounting for a significant portion of total value. This concentration creates both advantages and vulnerabilities for downstream customers. On one hand, established suppliers offer consistent quality, broad grade portfolios, and the ability to support global scale demands. On the other, reliance on a narrow supplier base can amplify exposure to capacity disruptions, regional logistics friction, and price volatility in upstream inputs. Understanding where competitive leverage resides is essential for procurement strategy and risk management.
Summit Reheis operates as a leading global supplier of aluminum chlorohydrate active ingredients for antiperspirant use, offering both standard and enhanced grades that support a wide range of deodorant and antiperspirant formulations. The company’s product range, including grades such as ACH 410 and Reheis AHA, illustrates the industry trend toward differentiated actives that balance efficacy with formulation compatibility. In late 2024, Summit Reheis introduced an ultra low-irritancy grade designed for sensitive skin antiperspirants, signaling how supplier innovation is increasingly oriented toward consumer tolerance and skin-friendly performance profiles.
Rio Tinto contributes to the supply landscape through its specialty alumina division, which produces high-purity aluminum chlorohydrate materials destined for personal care manufacturers worldwide. Its involvement highlights the importance of integrated upstream capability in maintaining consistent supply. In mid 2024, the company expanded specialty alumina production capacity by 15 percent to support growing antiperspirant active demand, demonstrating how capacity decisions at the specialty materials level can ripple through the broader market and influence availability in downstream channels.
Givaudan supplies aluminum chlorohydrate-based antiperspirant actives via its personal care division, with a focus on low-odor, high-efficacy grades that serve global deodorant brands. The company’s emphasis on sensory performance and brand-aligned characteristics reflects the broader shift in which antiperspirant actives are increasingly evaluated not only on biological efficacy but also on user experience, fragrance compatibility, and application feel. Recent updates to certification and sustainability reporting underscore the growing relevance of responsible sourcing and documented compliance in supplier selection.
Worldwide Aluminum Zirconium Tetrachlorohydrex Glycine (AZAG) Market
Nippon Light Metal Holdings manufactures high-purity aluminum chlorohydrate for antiperspirant applications, with particular emphasis on cosmetic-grade specifications and export-oriented supply reaching Asia-Pacific and global markets. Its positioning demonstrates how regional manufacturing expertise and purity control can support international demand while addressing market-specific quality expectations. In parallel, Advancion Corporation provides custom aluminum chlorohydrate solutions tailored to antiperspirant formulations, including polyaluminum chloride variants optimized for sweat reduction efficacy. This custom approach indicates a segment of the market where formulation engineers require more than off-the-shelf grades and instead seek partners who can tune material characteristics to specific performance targets.
Worldwide Antiperspirant Aluminum Chlorohydrate Market
Together, these players illustrate a competitive landscape shaped by grade differentiation, purity control, formulation support, and capacity responsiveness. The full report profiles these companies and others within a comparative framework, examining their strategic moves, product introductions, capacity actions, and certification developments. By mapping these activities against market share concentration and regional supply flows, the study clarifies where competitive barriers exist and where opportunities for differentiated supplier partnerships may emerge.
Industry Dynamics: Raw Materials, Regulation, Tariffs, and Logistics
Market behavior in aluminum chlorohydrate does not evolve in isolation. It is continuously reshaped by external conditions that influence cost, compliance, and competitive access. One of the most immediate pressures in recent quarters has come from raw material dynamics. Alumina feedstock prices have experienced notable upward movement, driven by bauxite supply constraints and broader mineral commodity tightness. This shift translates directly into elevated input costs for specialty chemical producers and, ultimately, into formulation economics for antiperspirant manufacturers. The report incorporates these material cost trends as part of a wider cost-structure analysis, helping readers distinguish between temporary shocks and structural cost recalibration.
Regulatory developments add another layer of complexity. In Europe, evolving chemical safety frameworks have introduced concentration restrictions relevant to aluminum chlorohydrate in cosmetic applications. These mandates affect formulation ceilings and can influence how brands position products across sensitive and general-use categories. Alongside concentration limits, broader environmental and health-related listings in certain jurisdictions have increased scrutiny for consumer-facing products containing aluminum compounds. Although such listings do not uniformly apply across markets, they shape labeling practice, consumer perception, and risk assessment in regions where precautionary communication is becoming more prominent.
Trade policy introduces further asymmetry across geographies. Tariff measures affecting imports of aluminum chlorohydrate from specific origins have altered the cost calculus for formulators that rely on cross-border sourcing. A 25 percent tariff structure linked to designated import classifications has placed additional pressure on supply plans that previously depended on lower-cost overseas material flows. For multinational brands and regional formulators alike, this reinforces the value of diversified sourcing, near-shoring considerations, and supplier relationships that can absorb policy-induced cost shifts without disrupting supply continuity.
Logistics costs also remain a salient factor. Global ocean freight rates for chemical shipments have seen meaningful increases, adding to the landed cost burden for internationally sourced actives and intermediates. These freight dynamics intersect with production scheduling, inventory positioning, and regional distribution strategies. In a market where grade consistency and delivery reliability matter, transportation cost volatility can influence regional pricing patterns and supplier selection even when base ingredient pricing appears stable.
Strategic Decision Framework for 2026
For executives planning 2026 operations, the strategic challenge is not merely to observe growth but to interpret it within the constraints and opportunities created by formulation trends, sourcing realities, and regulatory trajectories. The aluminum chlorohydrate market’s projected expansion at a disciplined compound rate suggests that demand will continue to provide a supportive backdrop, but that growth will increasingly reward organizations capable of managing complexity rather than simply riding volume momentum.
One priority is formulation strategy. As consumer expectations evolve around sensory feel, skin compatibility, and odor management, the selection of aluminum chlorohydrate grades becomes a tactical decision with both performance and market-access implications. Teams should evaluate how specific grades align with target user profiles, regional preference patterns, and packaging systems. The report’s segmentation insights help frame these choices by revealing how different application formats and product forms compete for share and where innovation may create differentiation without compromising cost efficiency.
A second priority is sourcing resilience. Given the concentration of supply among established active ingredient producers and the influence of upstream raw material pricing, procurement strategies should weigh supplier diversification, grade flexibility, and contractual structures that reduce exposure to freight and tariff volatility. Capacity expansion announcements from major suppliers indicate that supply-side responsiveness exists, but access to that capacity depends on relationship strength, specification alignment, and regional procurement planning. The full study provides the competitive and concentration context needed to assess where reliance is justified and where contingency planning is advisable.
A third priority is regulatory foresight. Concentration limits and precautionary listings are likely to continue shaping formulation decisions, especially for brands that operate across multiple jurisdictions. Anticipating reformulation requirements, reviewing alternative grade suitability, and monitoring certification and sustainability documentation can reduce the likelihood of disruptive compliance events. Interpretation of these developments should be integrated with R&D timelines so that product roadmaps remain aligned with both current mandates and plausible future constraints.
Finally, commercial strategy should reflect the interplay between geography, form, and application. While aggregate growth provides a positive market signal, regional and format-level dynamics differ materially. Organizations that understand where value is accumulating, which formats are driven by local usage patterns, and how trade and logistics conditions affect regional accessibility will be better positioned to allocate investment and adjust portfolio exposure. The complete report disaggregates these patterns in detail, allowing readers to map them against their own footprint and competitive context.
Why the Full Study Matters
Snapshot data and aggregated growth rates provide direction, but strategic decisions require deeper calibration. The full PW Consulting Worldwide Antiperspirant Aluminum Chlorohydrate Market report delivers the precision, segmentation detail, company-specific intelligence, and contextual analysis needed to convert market signals into executable strategy. It distinguishes between historical trend confirmation and forward-looking scenario interpretation, giving readers a structured basis for planning procurement, formulation, compliance, and market development activities throughout 2026 and beyond.
The publication is designed to serve as a shared reference point across functions, ensuring that commercial, technical, and supply teams are operating from a common evidence base. Its segmentation analysis isolates the dimensions that matter most to product planning, while its competitive and dynamics assessments provide context for risk management and supplier strategy. By consolidating macroeconomic data, regulatory developments, trade conditions, and company-level activity within a single analytical framework, the report reduces the time required to assemble actionable intelligence and increases the confidence with which decisions can be made.
For organizations seeking to navigate a market defined by steady expansion, concentrated supply, evolving regulation, and shifting formulation expectations, this research offers the depth required to move beyond generalizations and toward precise strategic positioning. The aggregated market figures, growth cadence, and competitive patterns outlined here are intended to establish the strategic frame. The detailed segmentation splits, discrete regional valuations, and application-level distributions that support them are presented in full within the complete study, where they can be examined alongside methodological notes and scenario-ready analysis.
In a category where ingredient performance, regulatory readiness, and supply continuity collectively determine market access, timely and well-structured intelligence is not an accessory. It is a prerequisite for confident action. PW Consulting’s Worldwide Antiperspirant Aluminum Chlorohydrate Market study provides that foundation, enabling leaders to align 2026 decisions with verified market direction, competitive reality, and operational feasibility.
For detailed analysis of this topic, please visit the official page: Worldwide Antiperspirant Aluminum Chlorohydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Boat Black Water Treatment Market to Hit $854.13M by 2032 at 6.89% CAGR
By pmarketresearch, 2026-09-16
Navigating the Currents: Strategic Intelligence for the Worldwide Black Water Treatment System for Boats Market (2026-2032)
Executive Overview: The Imperative for Precision Intelligence
As the maritime industry accelerates toward stricter environmental compliance and operational sustainability, the management of vessel-generated black water has evolved from a regulatory checkbox into a core component of marine engineering strategy. PW Consulting is pleased to introduce our comprehensive Worldwide Black Water Treatment System for Boats Market research, a strategic intelligence asset designed to equip decision-makers with the clarity required to navigate a sector defined by evolving regulatory frameworks, technological diversification, and shifting demand patterns across leisure, commercial, and defense segments.
This market study is built on a rigorous analytical foundation spanning historical performance from 2020 through the base year of 2025, with a forward-looking forecast period extending to 2032. Drawing from primary research, expert interviews, and verified secondary datasets, the report provides a 360-degree view of market structure, competitive positioning, and growth vectors. For executives evaluating capital allocation, product development roadmaps, or market entry strategies in the marine sanitation space, this intelligence serves as a critical reference point for minimizing risk and identifying high-value opportunities.
The maritime environment is no longer operating in a static regulatory landscape. Compliance with MARPOL Annex IV, IMO MEPC.227(64) effluent standards, and USCG classification requirements has fundamentally reshaped procurement cycles, technology selection, and vessel retrofit strategies. In this context, general industry narratives are insufficient. Stakeholders require granular, verified, and actionable intelligence that connects regulatory traction to commercial viability. Our report delivers precisely that: a consolidated, data-backed perspective that transforms market complexity into strategic clarity.
Market Trajectory and Growth Vector: A Data-Backed Lens
The worldwide market for black water treatment systems for boats has demonstrated consistent expansion over the past half-decade, reflecting a confluence of vessel modernization, environmental enforcement, and the growing commercialization of marine leisure and offshore operations. Based on verified revenue tracking, the market reached a valuation of approximately 535.4 million USD in the 2025 base year, following a measured growth curve from 382.45 million USD in 2020. This progression underscores a sector that has moved beyond early adoption dynamics into a phase of structured, demand-driven expansion.
Looking ahead, the forecast period through 2032 indicates sustained upward momentum, with a projected compound annual growth rate of 6.89 percent. By 2032, the market is anticipated to reach an estimated 854.13 million USD, signaling a meaningful expansion in total addressable demand. This trajectory is not merely a function of broader marine industry growth; it is increasingly tethered to regulatory-driven retrofitting, the replacement of legacy holding-tank-dependent configurations with advanced treatment technologies, and the integration of wastewater management into broader vessel system architectures.
Importantly, this growth is not uniform across all vessel classes or geographic deployments. The market's expansion is being shaped by differentiated adoption curves, varying compliance stringency, and distinct procurement behaviors between recreational, commercial, and defense end-users. Understanding where value is concentrating, which technology pathways are gaining traction, and how regional regulatory environments influence purchasing decisions is essential for any organization seeking to capture share in this evolving landscape. Our report unpacks these dynamics with precision, enabling clients to move beyond top-line growth narratives and develop segment-specific strategies grounded in verified market structure.
Segmentation Landscape: Technology, End-Use, and Regional Configuration
The architecture of the black water treatment system market is defined by three critical segmentation dimensions: system type, end-use application, and regional deployment. Each dimension carries distinct implications for product specification, certification pathways, pricing dynamics, and competitive positioning.
At the technology level, the market is structured around multiple marine sanitation device classifications and treatment methodologies, ranging from electrochemical and heat-based systems to biological and membrane-assisted platforms. These technology pathways are not interchangeable; they are governed by vessel size constraints, discharge zone regulations, operational profiles, and maintenance expectations. Type II and Type III marine sanitation devices have emerged as significant components of the market structure, reflecting their broader applicability across inspected vessels, larger recreational craft, and commercial platforms. Meanwhile, specialized Type I configurations continue to serve a focused but strategically important segment of smaller vessels operating under specific discharge allowances. The interplay between certification requirements, system complexity, and total cost of ownership creates a segmentation environment where technology selection is as much a compliance and operational decision as it is a product choice.
End-use segmentation further differentiates demand behavior. Leisure boats and yachts represent a substantial portion of market activity, driven by owner expectations for compact, odor-free, and low-maintenance solutions, as well as increasing environmental awareness within the recreational marine sector. Commercial vessels constitute another major demand pillar, where treatment system selection is shaped by operational uptime requirements, crew size, voyage duration, and compliance obligations across multiple jurisdictions. Military and defense applications, while smaller in relative scale, introduce distinct procurement dynamics tied to standardization, durability, and mission-specific performance criteria.
Regionally, the market reflects a concentration of activity in established maritime economies, while emerging marine markets present incremental but structurally important growth potential. Regulatory maturity, vessel fleet composition, after-sales service infrastructure, and local certification pathways all influence how regional demand translates into commercial opportunity. Rather than presenting isolated regional snapshots, the report integrates these geographic dynamics into a cohesive global map, helping clients identify where market presence is strongest, where compliance-driven demand is accelerating, and where tactical entry or expansion strategies may yield the highest return.
Regulatory and Operational Dynamics Shaping Market Behavior
The commercial trajectory of marine black water treatment systems is inextricably linked to the regulatory environment. International and national standards do not simply define compliance boundaries; they actively shape technology adoption, vessel design priorities, and procurement timelines. Under MARPOL Annex IV, vessels of 400 gross tonnage and above, or those certified to carry 15 or more persons, must be equipped with an approved sewage treatment plant, a sewage comminuting and disinfecting system with holding tank, or an appropriate holding tank configuration. Discharge of untreated sewage is restricted to distances beyond 12 nautical miles from the nearest land, at approved rates while underway at not less than 4 knots. These parameters create a baseline compliance framework that directly influences equipment specification across commercial and larger recreational vessels.
Ballast Water Treatment Equipment Market
Further refining the compliance landscape, IMO Resolution MEPC.227(64) establishes revised effluent standards and performance test criteria for sewage treatment plants, including nitrogen and phosphorus limits applicable to special areas such as the Baltic Sea. Treated effluent must produce no visible floating solids and must not cause discoloration of surrounding waters. These standards elevate the performance bar for treatment systems and reinforce the shift toward solutions capable of meeting stricter discharge criteria without reliance on passive holding alone.
In the United States, the USCG classification framework adds another layer of decision-making complexity. Type I systems, including electrochemical or heat-based configurations, are certified for vessels under 65 feet and may allow treated black water discharge in areas that are not designated as no-discharge zones. Type II systems apply to larger inspected vessels and require more stringent biological or chemical treatment processes under 33 CFR Part 159. For US-flagged vessels on international voyages, voluntary compliance with MARPOL Annex IV can be demonstrated through a USCG Statement of Voluntary Compliance based on NVIC 1-09 guidance, particularly where treatment plants meet MEPC.227(64) or equivalent standards. This regulatory ecosystem means that product certification, operational zone eligibility, and system sizing are not peripheral considerations; they are central to market access.
Operational considerations further influence purchasing behavior. Marine sewage treatment systems commonly incorporate corrosion-resistant construction materials, including marine-grade aluminum or steel coated with ceramic-filled epoxy, to withstand the demanding conditions of black water handling. System design must also account for maintenance frequency, footprint constraints, energy consumption, and ease of integration with existing vessel infrastructure. These practical realities create a purchasing environment where specifiers evaluate not only regulatory compliance, but also serviceability, reliability, and lifecycle cost. The result is a market in which differentiation is increasingly driven by engineering robustness, certification breadth, and application-specific optimization.
Competitive Arena: Leadership, Specialization, and Strategic Positioning
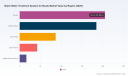
The competitive landscape for marine black water treatment systems is characterized by a mix of established marine equipment manufacturers, specialized sanitation providers, and global technology groups with integrated waste management capabilities. The market exhibits a moderately concentrated structure, with the top three competitors collectively holding approximately 32.4 percent of market share and the top five firms accounting for around 48.75 percent. This concentration suggests that while scale players exert meaningful influence, there remains substantial room for specialized firms to compete on technology differentiation, application focus, and regional service strength.
Several core companies illustrate the breadth of strategic positioning within the sector. GROCO offers a portfolio encompassing heat-based Type I systems such as Thermopure for vessels under 65 feet, electrochemical ElectroScan technology that generates disinfectant from salt water, and Type III holding system configurations designed for compact and reliable sanitation in recreational and small marine applications. Raritan Engineering Company is widely recognized for its ElectroScan Type I MSD, which uses electrodes to convert salt water into a bactericide, enabling black water treatment without reliance on holding tanks in permitted discharge areas for vessels up to 65 feet. Headhunter Inc. focuses on marine sewage treatment plants and MSDs, including the TidalWave HMX platform, which is IMO MEPC.227(64) and USCG Type II certified and employs chemical oxidation, hydro-maceration, and cross-flow separation for vessels over 65 feet with capacities ranging from 50 to 10,000 US gallons per day.
Worldwide Black Water Treatment System for Boats Market
On the international stage, De Nora contributes electrolytic marine wastewater treatment through its OMNIPURE platform, which uses DSA electrode technology for oxidation and disinfection without biological media or additives, and is certified to IMO MEPC.227(64) and USCG standards. RedFox Environmental Services manufactures USCG and IMO certified marine sewage treatment units for black water across marine, offshore, and land applications, meeting MEPC.227(64) and EPA compliance requirements, with production based in Louisiana and global service support. Ahead Sanitation Systems supplies USCG Certified Type II marine sanitation devices for a broad range of workboats, tugboats, towboats, barges, yachts, and pleasure craft, emphasizing lightweight, compact, odor-free, low-maintenance aerobic designs. HAMANN AG provides advanced wastewater treatment systems, including the HL-CONT Plus series, for combined black and grey water treatment on superyachts, cruise ships, ferries, and offshore or inland vessels, with compliance for MARPOL Annex IV special areas such as Alaska and the Baltic Sea, utilizing modular designs without filters or membranes.
Additional participants further diversify the competitive field. Scienco/FAST manufactures biological marineFAST sewage treatment systems for blackwater and combined waste streams, with nearly 5,000 installations worldwide and USCG/IMO certifications serving tugs, offshore supply vessels, and commercial ships. Evac delivers integrated marine water and waste management solutions as part of a broader total concept package for vacuum collection and black water processing across multiple vessel types. Wärtsilä offers complete marine waste and wastewater treatment packages, including sewage treatment plants and membrane bioreactor systems for black water management on all types of vessels. ACO Marine specializes in tailored wastewater treatment solutions, including biological Clarimar MF systems for black water, while RWO Water Technologies supplies marine sewage treatment plants as part of pollution prevention equipment with more than 45 years in marine water treatment. H2O Inc., through its Crapzapper line, provides biological marine sanitation devices dual-certified under USCG and IMO MEPC.227(64), with over 4,500 units installed worldwide for crews ranging from 2 to 500. Detegasa rounds out the competitive landscape with high-tech water and waste management solutions designed for navy, marine, and offshore industries.
These companies are not competing on a single axis. Differentiation is emerging through certification scope, vessel class specialization, treatment methodology, corrosion-resistant engineering, and the ability to provide integrated service and support across global fleets. Recent market activity reinforces this competitive intensity with a visible emphasis on trade presence and application-specific positioning. In February 2026, Raritan Engineering Company participated in the Miami International Boat Show, highlighting proven marine sanitation designs including ElectroScan systems. Ahead Sanitation Systems has an active exhibition calendar through the end of 2026, with scheduled showcases of USCG Certified Type II systems at the Inland Marine Expo, the Pacific Marine Expo, and the International WorkBoat Show, underscoring a deliberate push to strengthen visibility across workboat and commercial marine channels. In December 2025, industry coverage from Superyacht Times featured advanced wastewater treatment systems from ACO Marine and HAMANN, addressing black water volumes of up to 500 liters per person per day and the need for tailored sewage management spanning collection through discharge. These developments point to a competitive environment in which market access is being reinforced through demonstration, application focus, and compliance-aligned product narratives.
Report Scope: What Decision-Makers Will Gain
This market research report is designed to move beyond descriptive market overviews and deliver a structured, decision-ready intelligence framework. Clients will gain access to a detailed analysis of market sizing and forecast pathways, supported by historical context and forward-looking projections that clarify growth mechanics rather than simply reporting endpoints. The report examines segmentation dynamics across technology type, end-use application, and regional deployment, enabling users to assess where demand is concentrated and how purchasing behavior varies by segment.
The competitive analysis component provides a structured assessment of leading participants, their product positioning, certification portfolios, and strategic activity. Rather than presenting a static company list, the report contextualizes competitive behavior within the regulatory and operational realities that shape procurement decisions. This allows readers to evaluate not only who is active in the market, but how different players are aligning their offerings with compliance intensity, vessel class requirements, and regional service expectations.
The regulatory and operational sections integrate international and national compliance frameworks into a practical market context, helping users understand how effluent standards, discharge restrictions, and certification pathways influence technology selection, retrofit demand, and product design priorities. In addition, the report addresses material and engineering considerations that affect product durability, maintenance requirements, and lifecycle performance, providing context that is directly relevant to specification, procurement, and risk assessment.
To support strategic planning, the report also maps recent industry developments, including trade show activity, product showcases, and sector-specific coverage that signal how companies are positioning themselves across leisure, commercial, and superyacht applications. This combination of macro-level market structure and micro-level competitive intelligence creates a comprehensive reference point for strategic planning, investment evaluation, and market-entry analysis.
Strategic Application: How to Use This Intelligence in 2026
For organizations operating in or seeking to enter the marine black water treatment sector, the value of this research lies in its ability to connect market structure to action. Executives can use the forecast framework to align product roadmaps with anticipated demand growth, prioritize segment focus based on compliance-driven procurement cycles, and evaluate where technology differentiation offers the strongest competitive leverage. Suppliers can assess how certification breadth, system sizing, and corrosion-resistant engineering influence spec-in decisions across vessel classes, and identify where service and support capabilities may serve as differentiators in fragmented regional markets.
Procurement and specification teams can leverage the regulatory and operational analysis to better understand compliance eligibility, discharge zone constraints, and the practical implications of system type selection for different vessel profiles. Investors and strategic partners can use the market concentration and competitive positioning data to evaluate the intensity of rivalry, the degree of specialization in the supplier base, and the potential for consolidation or technology-led disruption. In all cases, the report is designed to reduce ambiguity and support decisions grounded in verified market structure rather than assumption.
Conclusion: Turning Market Complexity into Strategic Advantage
The worldwide black water treatment system for boats market is entering a phase in which regulatory precision, application specialization, and engineering reliability are increasingly decisive. With a 2025 base year valuation of approximately 535.4 million USD and a projected 2032 market size approaching 854.13 million USD at a 6.89 percent CAGR, the sector offers meaningful growth potential, but that growth is distributed across a nuanced competitive and regulatory landscape. Success in this environment requires more than awareness of overall market expansion; it demands a detailed understanding of technology pathways, certification dynamics, end-use behavior, regional variation, and competitive positioning.
PW Consulting's Worldwide Black Water Treatment System for Boats Market report is structured to deliver that understanding in a form that is immediately useful for strategic planning and commercial decision-making. To access the full dataset, segmentation breakdowns, competitive assessments, and detailed forecast architecture, we invite you to explore the complete report on our website. The full intelligence package provides the depth and granularity required to translate market awareness into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Black Water Treatment System for Boats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global HTML5 Games Market to Hit $73.67B Revenue by 2032 Amid 12.45% CAGR
By pmarketresearch, 2026-09-16
Navigating the HTML5 Games Market: Strategic Intelligence for 2026 and Beyond
The global gaming landscape is undergoing a quiet but profound restructuring. As device fragmentation intensifies, user acquisition costs climb, and platform gatekeepers tighten their control, HTML5 games have emerged as a decisive infrastructure layer for brands, publishers, and developers seeking frictionless, cross-device player engagement. Our latest research report, Worldwide HTML5 Games Market, maps this transformation with the precision required to turn market momentum into executable strategy. Built on a rigorous historical base spanning 2020 through 2025 and extended across a forecast window to 2032, the study is designed for executive teams that need more than headline growth figures—they need a clear operating manual for 2026 decision-making.
Worldwide HTML5 Games Market
Worldwide 2D Game Market
The market has already crossed a meaningful threshold. Total industry revenue reached approximately 32.4 billion USD in 2025, up from 15.2 billion USD in 2020, reflecting a compound annual growth rate of 12.45 percent over the historical period. Rather than treating this trajectory as a simple growth story, our analysis treats it as a structural signal: the browser-based gaming channel is maturing into a standalone commercial ecosystem with distinct monetization logic, distribution dynamics, and competitive rules. Looking ahead, the forecast window suggests continued expansion toward roughly 73.7 billion USD by 2032, with the most consequential strategic question no longer being whether HTML5 games will scale, but how organizations can position themselves to capture durable share within an increasingly crowded field.
That is precisely the question this report is built to answer.
Why This Report Matters for 2026 Strategy
Many market summaries stop at top-line projections. That approach is useful for broad awareness, but it is insufficient when 2026 planning requires allocation decisions across product roadmaps, partnership pipelines, regional priorities, and monetization design. This report is structured to support those choices. It provides a decision-grade view of how value is being created, moved, and captured across the HTML5 gaming value chain, with particular attention to the channels, revenue models, and competitive behaviors that are reshaping returns.
For publishers and brand teams, the study clarifies where discovery is happening and how player attention is being converted into recurring engagement. For developers and technology providers, it maps the practical realities of engine choice, distribution reach, and build-vs-partner trade-offs. For investors and corporate strategy groups, it frames market concentration, platform leverage, and the evolving economics of cloud-supported browser gaming. Throughout, the analysis is anchored in actionable segmentation rather than abstract narratives, enabling readers to interrogate the market from the perspective of their own operational constraints.
Equally important, the report integrates the operational pressure points shaping 2026. Web-based gaming does not exist in isolation. It depends on data infrastructure, connectivity economics, and a regulatory environment that is becoming more active by the quarter. By embedding these factors into the market narrative, the study helps leaders anticipate downstream effects on cost structures, deployment timing, and channel design before those pressures become embedded in quarterly results.
Market Architecture: Channels, Monetization, and Regional Logic
A defining feature of the HTML5 games market is that growth is not evenly distributed across channels or revenue models. It is concentrated where frictionless access and scalable monetization intersect. Our segmentation analysis traces how different distribution pathways and revenue architectures contribute to overall market formation, without treating any single pathway as a universal solution.
Distribution dynamics are especially important in 2026 because the channel mix determines both reach and commercial control. The report examines how social media mini-programs, mobile web browsers, desktop game portals, and messaging-platform integrations each shape acquisition velocity, session design, and retention potential. Instead of presenting any one channel as inherently superior, the analysis explains where each pathway creates advantage, what operational capabilities it demands, and how publishers should sequence channel investment based on audience type, product format, and monetization goals.
The same discipline applies to revenue design. In-game advertising, in-app purchases, and subscription and licensing models each carry distinct value-creation mechanics. The report analyzes how these models interact with user behavior, content genre, and platform economics, highlighting why many successful HTML5 portfolios are moving toward layered monetization rather than relying on a single stream. This matters for 2026 because margin stability increasingly depends on matching revenue architecture to audience intent, session length, and content cadence.
Regional dynamics are treated with equal care. The study considers how local device behavior, digital consumption patterns, platform ecosystems, and commercial norms shape adoption and monetization outcomes across major geographies. Rather than reducing regional performance to static share percentages, the report explains the structural drivers that determine where demand is forming, which audience segments are expanding fastest, and how organizations should calibrate market entry, localization, and partnership strategies accordingly. In practice, this gives leaders a more reliable basis for prioritizing expansion than top-line rankings alone.
Competitive Landscape: Platforms, Engines, and the New Center of Gravity
The HTML5 ecosystem is not defined by a single business model. It spans distribution platforms, publishing operations, engine and tooling providers, and development studios. That diversity is one reason the market remains both dynamic and strategically complex. Our competitive analysis maps these roles and shows how value is accumulating across the ecosystem, with special attention to organizations that are already shaping industry direction.
Distribution and publishing platforms are central to the market's current architecture. Companies such as GameDistribution and CoolGames illustrate how scale, cross-platform reach, and IP integration can create powerful discovery pipelines for browser-based casual games. Their influence goes beyond traffic volume: they structure how developers access audiences, how publishers assemble portfolios, and how licensed content is adapted for instant-play environments. GamePix similarly reflects the continued importance of unifying distribution across websites, applications, and carrier-linked channels, especially where regional access patterns differ from purely app-centric markets.
A notable signal in the current cycle is the strengthening of IP-led browser gaming strategies. CTW Cayman, operating through its G123.jp platform, has expanded rapidly as an anime IP-based HTML5 gaming operator, building a multi-title portfolio and extending its reach through a 2025 NASDAQ listing. Its 2025 capital raise underscores how market participants are funding platform growth, portfolio expansion, and geographic targeting across the United States, Europe, and Southeast Asia. This trajectory matters because it shows that browser-compatible gaming is increasingly being treated as a serious IP monetization channel rather than a peripheral marketing format.
On the technology side, the report examines the tooling landscape that enables HTML5 creation at scale. Engines and frameworks such as PlayCanvas, Phaser, and Construct highlight different development philosophies: high-end 3D browser experiences, widely adopted 2D JavaScript workflows, and accessible no-code or low-code creation paths. The strategic implication is that the market now supports a broad spectrum of production models, from rapid casual development to more ambitious interactive web applications. That flexibility is reshaping who can enter the market, how quickly products can be shipped, and what kinds of experiences are commercially viable in browser environments.
The competitive set also includes development studios with strong regional footprints and specialized capabilities. Firms based in India, Bangladesh, Italy, New Zealand, and other markets are increasingly active in HTML5 development, licensing, and cross-platform browser experiences. Their presence reflects a broader trend: HTML5's accessibility and deployment simplicity continue to enable distributed development models, which in turn affect pricing dynamics, time-to-market, and the strategic importance of production partnerships. The study places these players in context so readers can evaluate not only who competes, but where competitive advantage is actually being built.
Dynamics Shaping 2026: Momentum, Events, and Infrastructure Realities
Market growth does not occur in a vacuum. It is reinforced or constrained by product events, community activity, and the underlying economics of digital infrastructure. The report ties these forces together so leaders can distinguish durable trends from temporary noise.
Recent product activity shows how established titles and platform ecosystems are continuing to lean into HTML5 as an accessibility-first distribution strategy. Sustained rollout of browser-based editions of well-known game franchises illustrates the commercial appeal of instant access across devices, removing download friction while preserving broad audience reach. At the same time, platform-level performance milestones—such as high-volume play counts achieved through iterative seasonal updates and variant testing—demonstrate that HTML5 success increasingly depends on post-launch optimization, content cadence, and distribution refinement rather than launch-day visibility alone.
Community-driven development activity also remains a meaningful indicator of ecosystem vitality. Events focused on building and shipping HTML5 games create a visible feedback loop between experimentation, tooling improvement, and creative output. They also reflect the market's openness to rapid iteration, which is one reason the channel continues to attract both independent developers and commercial teams seeking efficient ways to test mechanics, audience response, and monetization concepts.
At the same time, the report addresses a less visible but strategically critical factor: the cost and regulatory environment surrounding the infrastructure that supports browser-based services. As cloud-supported web gaming scales, it intersects with a fast-evolving policy landscape around data center energy use, power procurement, and infrastructure cost recovery. In the United States, regulatory attention has intensified around the electricity demands associated with large-scale digital infrastructure, including proposals and state-level actions that differentiate large-load users through specialized rate structures. Policy discussions in 2026 have also promoted voluntary compacts under which major operators would cover a substantial share of new power generation and transmission upgrade costs.
For HTML5 gaming organizations, these dynamics are not abstract. They influence hosting economics, performance expectations, scaling assumptions, and the long-term cost base of always-on web services. By incorporating this context directly into the market analysis, the report helps readers factor infrastructure exposure into strategic planning rather than treating it as a downstream compliance issue.
What the Report Delivers: A Practical Intelligence Toolkit
The Worldwide HTML5 Games Market study is built to support concrete decisions. Its structure is designed to move from strategic context to operational insight, giving readers a comprehensive but usable reference for 2026 planning. Among its core components are:
- Historical market sizing and forecast modeling that traces revenue development from 2020 through 2032, with a clear view of growth momentum and projection logic.
- Segmentation analysis across distribution channels, revenue models, and regional dynamics, presented to support channel prioritization, monetization design, and market-focus decisions.
- Competitive profiling of leading platforms, publishers, engines, and development studios, including recent corporate developments, expansion moves, and product-level activity shaping the market.
- Industry dynamics coverage that connects gaming strategy with infrastructure cost pressures, regulatory direction, and ecosystem events affecting browser-based services.
- Strategic interpretation intended to help leaders translate market structure into portfolio decisions, partnership choices, and investment prioritization.
The report is intentionally designed to bridge market intelligence and execution. Rather than leaving readers with isolated figures, it frames the market as a set of interdependent choices: where to compete, how to monetize, which distribution relationships matter most, and how to prepare for the operational realities that will shape costs and scalability over the forecast period.
Using the Research for 2026 Decision-Making
The strongest value of this study lies in its use as a decision framework. For product and publishing leaders, it offers a basis for evaluating which channels and monetization models align with specific game formats and audience behaviors. For technology and engine selection teams, it clarifies the trade-offs between rapid development workflows and more advanced web-based interactive experiences. For partnership and M&A teams, it helps identify where platform leverage, distribution reach, and IP-driven browser strategies are creating durable advantages. For executive planning groups, it provides a structured way to integrate market growth expectations with infrastructure and regulatory risk.
In a market growing at a sustained double-digit pace, speed alone is not a strategy. The more durable advantage comes from understanding where value concentrates, how competitive positions are forming, and which assumptions about distribution, monetization, and infrastructure will hold up under scrutiny. This report is built to support precisely that kind of planning.
Access the Full Intelligence
The overview above highlights the strategic logic and scope of the worldwide HTML5 games market analysis, but the actionable detail—precise segmentations, competitive positioning, regional dynamics, and forward-looking market modeling—is developed fully within the complete report. For teams preparing 2026 investments, product roadmaps, and expansion strategies, the full document provides the evidence base needed to move from market awareness to confident decision-making.
To explore the complete findings, segmentation depth, and competitive analysis, request or download the full Worldwide HTML5 Games Market research. Doing so will give your team the structured intelligence necessary to navigate a rapidly maturing market with clarity, discipline, and strategic intent.
For detailed analysis of this topic, please visit the official page: Worldwide HTML5 Games Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Digital TV Modulator Market to Reach $855.55M by 2032, 4.81% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Connected Era: Inside the Worldwide Multi-Channel Digital TV Modulator Market 2026-2032
The global telecommunications and broadcast infrastructure landscape is undergoing a profound transformation. As bandwidth demands escalate and hybrid distribution models become the norm, the Worldwide Multi-Channel Digital TV Modulator market stands at a critical inflection point. Our latest market research, Worldwide Multi-Channel Digital TV Modulator Market, provides a comprehensive, data-driven examination of this vital sector, offering executives and strategic planners the clarity needed to navigate the complexities of 2026 and beyond. This report is not merely a collection of statistics; it is a strategic compass designed to illuminate market trajectories, competitive maneuvers, and the regulatory currents shaping the industry.
For decision-makers evaluating capital allocation, technology roadmaps, or market entry strategies, understanding the macro-environment is paramount. The market has demonstrated consistent growth over the past half-decade, reflecting the sustained demand for reliable, high-quality digital signal distribution across diverse sectors. The total revenue for the base year 2025 is established at 615.8 million USD, building upon a robust historical trajectory that saw the market expand from 492.3 million USD in 2020. This growth underscores the essential role that digital TV modulators play in modernizing infrastructure, whether for traditional broadcast headends, hospitality networks, or emerging hybrid IPTV environments. The forecast period from 2026 to 2032 anticipates continued expansion, with the market projected to reach 855.55 million USD by the end of the outlook window. This evolution is driven by a Compound Annual Growth Rate (CAGR) of 4.81 percent, signaling a steady, maturing market that rewards strategic positioning and technological agility.
Decoding the Market Architecture
A superficial glance at aggregate figures often masks the nuanced realities of supply and demand. Our analysis dissects the market through multiple critical dimensions, providing a granular view of where value is created and how different standards and applications influence overall performance. The technology landscape is segmented by modulation standards, reflecting the global diversity in broadcast protocols. The market encompasses DVB-T/DVB-T2, DVB-C/DVB-C2, ATSC/ATSC 3.0, and ISDB-T and DTMB standards. Each standard commands a distinct share of the revenue mix, influenced by regional adoption patterns, legacy infrastructure considerations, and the speed of next-generation transitions such as the rollout of ATSC 3.0 or the persistence of DVB-C in cable environments. Understanding the relative weight of these standards is essential for vendors tailoring product portfolios and for operators planning migration paths.
Geographically, the market exhibits a balanced but dynamic distribution. Revenue streams are dispersed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The Asia Pacific region currently reflects the largest revenue contribution, driven by rapid urbanization, expanding hospitality sectors, and extensive campus and community network deployments. North America and Europe follow, characterized by mature markets where incremental growth is fueled by high-density headend upgrades, 4K transport stream capabilities, and the integration of multi-channel modulation into hybrid broadcast-broadband workflows. Emerging regions in Latin America and the Middle East and Africa present distinct opportunities tied to infrastructure development and the modernization of cable and broadcasting networks. Our report provides a detailed regional analysis that goes beyond top-line numbers, exploring the specific drivers, challenges, and growth vectors within each territory.
Application segmentation further reveals the versatility of multi-channel digital TV modulators. The market serves a wide array of end-users, with Hospitality and Healthcare representing the largest application segment. This dominance is attributable to the need for reliable, customizable television distribution in hotels, medical facilities, and assisted living centers, where multi-channel modulators enable the delivery of localized content, information channels, and entertainment services over existing coaxial or RF infrastructure. Broadcasting and Cable TV Operators form another major pillar, leveraging high-density modulation solutions to manage signal distribution, headend efficiency, and the transition to advanced compression and transmission formats. Residential and Community Systems, as well as Commercial and Educational Facilities, round out the application landscape, each with unique requirements regarding scalability, ease of integration, and service flexibility. By quantifying the revenue contribution of each application, the report empowers stakeholders to align their product development and sales strategies with the most lucrative and rapidly evolving verticals.
Competitive Dynamics and Strategic Positioning
The competitive landscape of the multi-channel digital TV modulator market is characterized by a mix of specialized innovators, established broadcast equipment manufacturers, and regional players with strong local footprint. Our analysis profiles key companies that are shaping the industry, evaluating their product portfolios, technological capabilities, geographic reach, and strategic positioning. Thor Broadcast and Pro Video Instruments (VeCOAX) exemplify the focus on multi-channel HDMI to RF conversion solutions, offering systems that multiplex multiple HDMI or SDI sources into digital TV channels for CATV, hospitality, and broadcast distribution. Blonder Tongue Laboratories continues to serve professional video distribution and MATV/SMATV networks with tailored modulation hardware. In the Asian market, DIBSYS Technologies, Souka / Dingshengwei Electronics, Softel Optic, and Gospell Digital Technology provide a broad range of encoder modulators, multi-channel RF solutions, and headend systems that support DVB, ATSC, ISDB-T, and DTMB standards, often with added features like OSD and QR code insertion or simultaneous IPTV output. WISI Communications and Harmonic Inc. bring high-density encoding and modulation expertise to cable and broadcast headends, while Rohde & Schwarz contributes advanced test and broadcast equipment, including multi-channel DVB modulators designed for high-density deployments and 4K transport streams.
Market concentration metrics indicate a moderately fragmented environment, with the top three companies holding a combined share of 21.4 percent and the top five firms accounting for 34.85 percent. This structure suggests that while leading players exert influence, there is ample room for niche differentiation, regional specialization, and technology-driven disruption. Recent corporate activities highlight the dynamic nature of this landscape. In March 2025, Harmonic Inc. completed the acquisition of Nexstreaming, a move designed to strengthen its multi-channel digital TV modulation portfolio and accelerate integration with next-generation headend systems. This acquisition signals a strategic emphasis on consolidating capabilities to address the increasing complexity of hybrid broadcast and IPTV workflows. In May 2025, Imagine Communications announced a strategic partnership with Teleste to deliver integrated encoding, transcoding, and DVB modulator solutions, reflecting the industry's push toward seamless convergence of broadcast and IP-based distribution. Furthermore, in June 2025, Rohde & Schwarz introduced the R&S MMD series, a new line of multi-channel DVB modulators tailored for high-density headend deployments and 4K-capable transport streams. These developments underscore the importance of staying abreast of M&A activity, partnerships, and product launches, as they reshape competitive advantages and open new avenues for collaboration.
Navigating Regulatory Currents and Infrastructure Realities
Market growth does not occur in a vacuum; it is deeply influenced by regulatory frameworks, spectrum policy, and the economics of infrastructure deployment. Our report integrates critical industry context to help stakeholders anticipate external forces that may impact demand, compliance costs, and technology adoption. In the United States, regulatory decisions continue to shape the broadband and broadcast ecosystem. The U.S. Court of Appeals for the Sixth Circuit invalidated the FCC's 2024 Open Internet Order, ruling that broadband constitutes an information service under the Communications Act. This ruling has implications for how video distribution services interact with broadband networks and may influence the strategic planning of operators that rely on hybrid delivery models. Simultaneously, the FCC reauthorization of spectrum auction authority through the Big Beautiful Bill enables new proceedings for upper C-band spectrum auctions and the modernization of licensing for upper-microwave spectrum. These developments are highly relevant for broadcast and cable infrastructure, as spectrum availability and licensing conditions directly affect the deployment of digital TV modulation systems and the efficiency of signal distribution networks.
Infrastructure costs and technological trends also play a pivotal role. The datacom optical component market for fiber optics in data centers and telecom backhaul is projected to exceed 16 billion USD in 2025, driven by 400G and 800G shipments and AI-related interconnect demand. While this figure pertains to a broader optical market, it reflects the accelerating investment in high-capacity transmission networks that underpin modern digital TV signal distribution. As operators upgrade backhaul and edge infrastructure, the integration of multi-channel modulators with robust, high-throughput transport layers becomes increasingly important. Additionally, U.S. broadband policy emphasizes fiber deployment incentives under programs like BEAD, while addressing outdated copper line maintenance regulations that increase operational costs for hybrid video distribution systems. These policy dynamics highlight the need for cost-effective, future-proof modulation solutions that can adapt to evolving network architectures and regulatory requirements.
Operational Excellence: A Roadmap for 2026 Decision-Making
The Worldwide Multi-Channel Digital TV Modulator Market report is structured to deliver actionable intelligence. Beyond the macro analysis, the document provides a detailed examination of market drivers, restraints, and opportunities. It explores how factors such as the demand for high-density headend equipment, the transition to ATSC 3.0 and advanced DVB standards, the expansion of hospitality and healthcare networks, and the integration of IP-based workflows are shaping purchasing decisions and product specifications. The report also assesses challenges, including supply chain considerations, the cost of legacy system migration, and the competitive pressure from emerging regional manufacturers. By mapping these forces, the study enables readers to identify where to invest, which segments offer the highest growth potential, and how to mitigate risks associated with regulatory shifts or technology transitions.
TV Transmitter Market
A core strength of this research lies in its segmentation depth. Readers gain access to a comprehensive breakdown of the market by standard, region, and application, with revenue figures and growth projections that illuminate the relative performance of each segment. This granularity is essential for product managers seeking to prioritize R&D efforts, for sales teams targeting specific verticals, and for investors evaluating market attractiveness. The report also includes profiles of key companies, analyzing their strategies, recent developments, and positioning within the value chain. By synthesizing quantitative data with qualitative insights, the study provides a holistic view of the competitive environment and the strategic moves that are redefining industry leadership.
Why This Research Matters Now
As the market advances toward the 2032 horizon, the decisions made in 2026 will have lasting consequences. The CAGR of 4.81 percent indicates a market that is neither hyper-volatile nor stagnant, but rather one that rewards foresight, precision, and adaptability. Companies that understand the interplay between standards evolution, regional demand patterns, application-specific requirements, and regulatory developments will be best positioned to capture value. Our report equips stakeholders with the analytical foundation to make those decisions confidently. Whether you are evaluating a product launch, assessing a partnership, planning a regional expansion, or benchmarking your competitive standing, this research offers the evidence-based insights needed to move forward with clarity.
The media and broadcast technology sector is crowded with data, but not all data translates into strategic advantage. The Worldwide Multi-Channel Digital TV Modulator Market study is designed to bridge that gap. It transforms raw market figures into a coherent narrative of growth, competition, and opportunity. By focusing on the segments, standards, and dynamics that truly matter, the report helps organizations cut through noise and concentrate on the levers that drive performance. The inclusion of recent corporate developments, regulatory analysis, and infrastructure trends ensures that the intelligence is current and contextually rich, reflecting the realities of the 2026 operating environment.
Worldwide Multi-Channel Digital TV Modulator Market
For executives and analysts who require a deeper dive into specific regional trajectories, application-level revenue breakdowns, or detailed company benchmarking, the full report provides the comprehensive dataset and expert commentary necessary to support high-stakes decision-making. The insights presented here are a preview of the strategic value contained within the complete study. We invite you to access the full report to unlock the complete spectrum of market intelligence, from granular segmentation data to forward-looking scenario analysis, and to ensure that your organization is equipped with the knowledge needed to thrive in the evolving global multi-channel digital TV modulator market.
In an industry where technology cycles accelerate and regulatory landscapes shift, information is currency. This research is crafted to deliver that currency in a form that is precise, actionable, and aligned with the strategic priorities of modern enterprises. As you plan for the years ahead, let this study serve as your reference point for understanding where the market is headed, who is leading the way, and how to position your organization for sustained success.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Channel Digital TV Modulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Uniform Rental Market Hits $16.5B in 2025, Forecasts 4.25% CAGR to $22.07B by 2032
By pmarketresearch, 2026-09-16
Navigating the Uniform Rental Landscape: Strategic Intelligence for 2026 and Beyond
The uniform rental market stands at a pivotal juncture as organizations navigate shifting operational cost structures, evolving compliance requirements, and an increasingly consolidated competitive environment. As enterprises recalibrate their procurement strategies and workplace service expectations, the ability to anticipate demand shifts, evaluate supplier risk, and align rental agreements with long-term operational goals has never been more critical. Our latest Uniform Rental Market study delivers a comprehensive, forward-looking assessment designed specifically to equip executive decision-makers, procurement leaders, and industry strategists with the analytical rigor required to navigate the 2026 business landscape and the years ahead.
This research is structured not as a static snapshot, but as a dynamic decision-support framework. It maps the trajectory of a sector that has demonstrated remarkable resilience through recent macroeconomic volatility, while simultaneously confronting structural pressures ranging from supply chain reconfiguration to labor cost dynamics. By synthesizing historical performance patterns with rigorously modeled forward projections, the report provides a clear lens through which organizations can benchmark their positioning, identify whitespace opportunities, and mitigate exposure to emerging market disruptions.
Market Scale and Trajectory: A Foundation for Strategic Planning
Understanding the magnitude and momentum of the uniform rental sector is the first step toward embedding it effectively within corporate strategy. Over the historical window spanning 2020 through 2025, the market navigated a period of recovery, adaptation, and measured expansion. After moving past initial operational disruptions, the industry demonstrated a steady upward trajectory, with total market revenue climbing to approximately $16.5 billion by the 2025 base year. This progression reflects the enduring institutional demand for managed workwear solutions across sectors that prioritize standardization, compliance, hygiene, and operational efficiency.
Looking ahead to the 2026–2032 forecast period, the market is positioned for continued expansion at a compound annual growth rate of 4.25 percent. This growth path is not merely a linear extrapolation; it reflects the compounding effect of sustained enterprise adoption, incremental sectoral demand, and the gradual integration of advanced logistics and facility service models into traditional uniform rental frameworks. By the close of the forecast horizon in 2032, total market revenue is projected to approach $22 billion, signaling a sector that continues to embed itself more deeply into the operational fabric of modern enterprises.
For strategic planners, these macro-level indicators serve as a critical baseline. They underscore that uniform rental is not a commoditized, static service category, but a dynamic commercial ecosystem influenced by end-user procurement cycles, regulatory shifts, and competitive restructuring. Leaders who internalize this trajectory can better time contract renewals, evaluate capital allocation toward workplace service partnerships, and anticipate how broader economic conditions will shape pricing power and service expectations across the value chain.
Workwear and Uniforms Market
Core Segments and Demand Drivers: Where Growth Converges
The uniform rental ecosystem is shaped by multiple intersecting dimensions, each carrying distinct operational implications for providers and buyers alike. At the highest level, the market divides into several foundational categories that dictate product specifications, service logistics, and compliance requirements. Industrial uniforms remain the dominant segment, reflecting the persistent need for durable, safety-aligned workwear across manufacturing environments, warehousing operations, and heavy-duty service applications. Food and beverage uniforms represent another substantial pillar, driven by stringent hygiene standards, brand consistency requirements, and high-turnover operational models that favor rental over ownership. Healthcare and medical wear constitutes a third critical pillar, where regulatory compliance, infection control protocols, and specialized fabric performance create a highly differentiated service environment.
These categorical divisions are further amplified by application-specific demand patterns. Manufacturing and industrial environments remain the largest operational anchor for uniform rental programs, supported by the practical advantages of centralized laundering, inventory management, and replacement logistics. Healthcare facilities form a second major demand center, where uniform and clinical wear programs intersect with patient safety mandates and staff standardization initiatives. Hospitality and food services continue to represent a meaningful application segment, driven by brand image management, linen and uniform integration, and the operational complexity of multi-site service delivery. Commercial and retail services round out the broader application landscape, where appearance standards, employee branding, and seasonal staffing fluctuations influence rental program sizing and rotation models.
For enterprise decision-makers, the strategic value lies in recognizing how these segments interact with organizational priorities. A manufacturing firm evaluating vendor consolidation must weigh industrial-grade durability and safety compliance against total cost of ownership. A healthcare network designing a standardized clinical wear program must navigate fabric certifications, laundering validation, and staff comfort alongside contract flexibility. A hospitality operator managing multi-property uniforms and linens must reconcile brand consistency with rapid replacement cycles and regional service availability. Our report dissects these application-level dynamics in detail, providing the analytical scaffolding needed to match rental program design with operational reality.
Uniform Rental Market
Competitive Architecture and Consolidation Pressures
The competitive dynamics of the uniform rental market have entered a phase of pronounced restructuring. Market concentration metrics indicate a moderately consolidated landscape, with the top three providers collectively accounting for approximately 45.5 percent of total market revenue and the top five firms capturing roughly 58.2 percent. This concentration reflects the operational scale advantages inherent in uniform rental logistics, including route optimization, centralized laundering capacity, national delivery networks, and the ability to offer integrated facility service portfolios.
Several established players define the current competitive frontier. Cintas Corporation has built a comprehensive platform spanning uniform rental, facility services, and workplace supplies, serving diverse end markets with broad program flexibility. UniFirst Corporation delivers uniform rental and facility solutions to a substantial daily workforce footprint, emphasizing workwear, floor mats, and hygiene-related service offerings across multiple sectors. Vestis Corporation operates as a major North American provider with full-service uniform care, delivery, and maintenance infrastructure. Aramark integrates uniform rental within a broader facilities management umbrella, maintaining a particularly visible presence in healthcare, hospitality, and industrial environments. Alsco Uniforms brings more than a century of experience in work apparel, laundering, and linen supply, while Mission Linen Supply and Prudential Overall Supply demonstrate the continued importance of regionally anchored and specialized service models across Western markets and cleanroom or facility-specific applications.
The strategic landscape is now being reshaped by transformative consolidation moves. A landmark acquisition agreement announced in March 2026 will see Cintas acquire UniFirst in a transaction valued at $5.5 billion, a move explicitly designed to expand service capabilities and deepen workday solutions across combined client portfolios. With closing expected in the second half of 2026, this development will meaningfully reduce the number of major competitors in the North American uniform rental market and alter the competitive calculus for both suppliers and enterprise buyers. Organizations evaluating multi-year rental partnerships must now factor in potential service integration timelines, pricing strategy shifts, and the broader implications of a more concentrated supplier base on negotiation leverage and program customization.
Recent industry survey data reinforces the sense of measured momentum. The Q1 2026 Uniform and Linen Services Industry Survey, conducted in partnership with Robert W. Baird & Co., indicated steady growth with rental revenues performing above expectations for many respondents. At the same time, employment-driven wearer growth remained largely neutral in late 2025 surveys, pointing to a market where revenue expansion is increasingly driven by pricing discipline, service bundling, and retention rather than raw headcount expansion alone. These structural nuances are central to the competitive analysis presented in the full study.
Operational Dynamics and External Pressures
No strategic assessment of the uniform rental market is complete without confronting the external forces that shape cost structures, service design, and supplier resilience. The industry remains highly labor-dependent, relying extensively on route service representatives and laundry operations personnel to maintain service quality, delivery reliability, and garment lifecycle management. This labor intensity means that wage dynamics, workforce availability, and operational efficiency initiatives directly influence program economics and, by extension, contract pricing and service-level commitments.
Simultaneously, regulatory and trade environments have introduced new cost pressures. Revised U.S. tariffs on imported textiles and protective gear components implemented in 2025 have begun to pressure cost structures for uniform rental providers, prompting a broader reassessment of supplier diversification and sourcing strategies. For enterprises locked into long-duration rental agreements, these dynamics can affect garment replacement cycles, availability of specialized protective components, and the pace at which providers pass through cost adjustments. Understanding how suppliers are adapting their procurement footprints and inventory strategies is therefore essential for risk-aware contract design.
These operational and external pressures do not exist in isolation. They intersect with broader market dynamics, including the pace of consolidation, regional service density, and the growing expectation that rental providers function as integrated workplace service partners rather than simple garment lessors. Providers that successfully align logistics efficiency, compliance assurance, and flexible program design are best positioned to defend margins and retain enterprise accounts. Conversely, buyers that fail to evaluate supplier resilience, labor model sustainability, and sourcing diversification risk encountering service variability or unexpected cost shifts over the life of their contracts.
Inside the Report: Analytical Depth for Actionable Decisions
Our Uniform Rental Market study is engineered to translate complex market signals into clear, actionable intelligence. Rather than offering a superficial overview, the report delivers a multi-layered analytical architecture designed for executive review, procurement planning, and competitive benchmarking. The full study includes a detailed market sizing framework that traces historical revenue evolution and forward projections across the entire forecast horizon, providing a reliable baseline for capacity planning, investment prioritization, and demand forecasting.
The segmentation analysis goes beyond aggregate figures to examine how distinct uniform categories and application environments behave under varying operational and economic conditions. Readers gain access to structured assessments of demand drivers, replacement cycles, compliance dependencies, and service intensity across industrial, healthcare, food and beverage, hospitality, and commercial use cases. This segmented perspective enables decision-makers to isolate the most relevant growth vectors for their specific operating context and avoid the trap of treating the uniform rental market as a monolithic category.
The competitive intelligence section provides a systematic evaluation of leading providers, their service portfolios, geographic footprints, and strategic positioning. It examines how major operators differentiate through logistics scale, integrated facility services, specialized garment programs, and regional coverage models. The analysis also maps the implications of recent consolidation activity, offering a forward-looking assessment of how market concentration may influence pricing behavior, service innovation, and buyer negotiation dynamics over the coming years.
Complementing the structural analysis, the report incorporates an external dynamics review that addresses tariff impacts, labor cost sensitivities, industry survey signals, and the evolving expectation set around provider reliability and service integration. By linking these macro and operational factors directly to rental program performance, the study equips leaders with the context needed to stress-test supplier relationships, anticipate cost pressure transmission, and design contract frameworks that balance flexibility with long-term stability.
Why This Research Matters for 2026 Decision-Making
The strategic value of this study lies in its ability to convert market complexity into decision-ready clarity. In 2026, uniform rental procurement is no longer a routine administrative function; it is a strategic lever that touches workforce compliance, brand presentation, operational continuity, and total cost management. The convergence of a moderately concentrated supplier base, transformative consolidation, evolving trade and labor conditions, and steady demand growth creates an environment where informed procurement strategy can yield measurable competitive advantage.
Enterprises that engage with this research will be better positioned to evaluate vendor consolidation proposals, benchmark existing rental agreements against market trajectories, identify segments with the most favorable growth-to-risk profiles, and construct procurement roadmaps aligned with both operational needs and financial discipline. Suppliers and investors, meanwhile, will gain a clearer view of where service differentiation is most valued, how concentration is reshaping competitive incentives, and which application areas offer the strongest pathways for sustained expansion.
The complete Uniform Rental Market report expands significantly on the themes introduced here, delivering the detailed sizing architecture, segmented demand analysis, competitive evaluations, and dynamic risk assessments required for high-stakes decision-making. To access the full dataset, scenario frameworks, and provider-level strategic breakdowns, we invite you to explore the complete study on our website. In a market defined by consolidation, cost complexity, and steady structural growth, comprehensive intelligence is not simply an asset. It is the foundation of resilient strategy.
For detailed analysis of this topic, please visit the official page: Uniform Rental Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Sheep Milk Market Hits $6.28B in 2025, Projected to Reach $12.12B by 2032 at 9.85% CAGR
By pmarketresearch, 2026-09-16
Navigating the White Gold: Strategic Imperatives in the Global Sheep Milk and Infant Formula Market Through 2032
The global dairy landscape is witnessing a structural shift, driven by evolving nutritional science and a premiumization of consumer demand. At the forefront of this transformation is the sheep milk segment, particularly its application in infant formula. For corporate strategists, category managers, and investor relations teams, the period from 2026 through 2032 represents a decisive window of market consolidation and value creation. This insight serves as a strategic primer to our comprehensive Worldwide Sheep Milk and Infant Formula Market research, designed to equip decision-makers with the granular intelligence required to navigate a sector defined by high barriers to entry, complex regulatory environments, and robust compound growth trajectories.
The Macro Trajectory: A Decade of Accelerated Expansion
Our analysis establishes a clear, high-velocity growth curve for the sector. Valued at a baseline that has consistently expanded from 2020 through 2025, the global market has demonstrated remarkable resilience and accelerating momentum. The current year provides a pivotal inflection point, with total market revenue projections indicating a substantial step-up as manufacturing capacities scale and premium product adoption moves from early adopters to the mainstream.
Looking ahead, the forecast period through 2032 paints a picture of sustained, double-digit velocity. The compound annual growth rate is projected at 9.85 percent, a figure that significantly outpaces conventional dairy categories. This growth is not merely linear; it is being fueled by a convergence of nutritional advantages, demographic shifts, and strategic supply chain investments. By the close of the forecast horizon in 2032, the market is positioned to multiply substantially from its current footprint, reshaping the competitive hierarchy of the global infant nutrition sector. For stakeholders, understanding the precise drivers behind this trajectory and the timing of market inflection points is critical for capital allocation and product pipeline development.
Unpacking the Report: Operational Intelligence Beyond Headlines
While macro trends provide directional guidance, actionable strategy requires a forensic examination of the market mechanics. Our research deliverable is structured to provide immediate operational utility across multiple corporate functions. The report moves beyond aggregate figures to map the intricate ecosystem that defines value capture in this specialized segment.
Product Architecture and Formulation Dynamics
The report deconstructs the product landscape into its core commercial pillars, analyzing how different formulations command distinct price points, supply chain requirements, and consumer loyalty profiles. We examine the strategic positioning of ready-to-feed liquid sheep milk variants versus powdered formats, and critically, the dominant role that sheep milk-based infant formula plays in driving overall category valuation. The analysis dissects how manufacturers are leveraging the unique biochemical profile of sheep milk to differentiate products in a crowded marketplace, and how contract manufacturing arrangements are shaping the availability of private label and co-branded offerings in key consumer markets.
Channel Economics and Path-to-Market Strategies
Distribution is no longer a uniform function; it is a strategic battleground. Our research provides a detailed breakdown of channel performance, evaluating the economics of online retail ecosystems against traditional brick-and-mortar dominance. We analyze how specialty stores are cultivating premium brand equity, and how supermarkets and hypermarkets are adapting their shelf strategies to accommodate higher-margin sheep milk products. The report further investigates the emerging role of alternative channels and the logistical considerations that dictate channel profitability in a category where cold chain integrity and shelf-life management are paramount.
Regional Supply-Demand Asymmetries
Geographic dynamics in this market are defined by stark asymmetries between production hubs and consumption centers. The report provides a nuanced regional analysis that moves beyond simple volume tracking. It examines how production capabilities are concentrated in specific geographies with favorable agronomic conditions and established sheep farming heritage, while demand signals are emanating from diverse regional markets with varying regulatory frameworks and consumer readiness. Understanding these cross-border flows, tariff implications, and localized certification requirements is essential for any entity seeking to optimize its global footprint or enter new territories.
Competitive Landscape: The Architecture of Market Power
The sector is characterized by a competitive environment where scale, technical expertise, and supply chain control converge. Market concentration metrics indicate a moderately consolidated landscape, with the top three players commanding a significant share of total industry revenue, and the top five entities extending their influence further. This concentration reflects the high barriers to entry, including the capital intensity of milking infrastructure, the technical complexity of formulation and manufacturing, and the stringent regulatory compliance required for infant nutrition products.
Strategic Profiles of Key Market Participants
The report provides deep-dive competitive profiling of the organizations that are actively shaping the market trajectory. Our analysis highlights how leading producers are leveraging geographic advantages to secure premium raw material positioning. We examine how specialized sheep milking companies in New Zealand have established themselves as critical nodes in the global supply chain, producing both finished consumer products and bulk ingredients that feed into broader manufacturing networks. Their strategies revolve around grass-fed sourcing narratives, vertical integration from farm to formula, and the development of nutritional bases that enable other brands to formulate sheep milk products without owning upstream production assets.
Worldwide Sheep Milk and Infant Formula Market
We also analyze the strategic maneuvering of global nutrition giants that have entered the sheep milk space through targeted product launches and acquisitions. By adapting established brand architectures and leveraging distribution scale, these multinational players are testing the boundaries of sheep milk application, from toddler milk drinks to full infant formula ranges. The report evaluates their capacity to influence category standards and their approach to navigating regional formulation preferences. Additionally, the research maps the activity of regional dairy and nutrition companies operating across Europe, North America, and Asia, detailing how local market knowledge, specialized production capabilities, and targeted product portfolios are allowing them to carve out defensible positions in a globally competitive arena.
Contract Manufacturing and Ingredient Value Chains
A critical, often underappreciated layer of the competitive landscape is the role of contract manufacturing and ingredient supply. Our report dissects how several key entities are generating revenue and market influence not solely through branded consumer products, but through the provision of bulk sheep milk powders, nutritional bases, and contract production services. This B2B dimension of the market creates interdependencies and partnership opportunities that are central to understanding future M&A activity and strategic alliances. Companies that control high-quality, traceable ingredient supply are positioned to capture value across multiple branded end products, creating a multiplier effect on their strategic importance.
Regulatory and Supply Chain Fault Lines in 2026
The operational environment for sheep milk and infant formula is undergoing a period of regulatory recalibration. Recent policy developments have introduced new compliance obligations that directly impact manufacturing planning, sourcing strategies, and cross-border trade flows. Our report integrates these dynamics into a forward-looking risk assessment framework, ensuring that strategic plans are stress-tested against the evolving regulatory reality.
In late 2025, regulatory authorities in China implemented new production licensing rules that brought infant formula liquid milk under the same registration and production controls previously applied to powdered formulations. This regulatory harmonization effectively eliminated contract production pathways that were previously utilized by certain brand operators, forcing a structural shift in how liquid products are manufactured, registered, and brought to market in one of the world's most significant infant nutrition consumption regions. Simultaneously, at the beginning of 2026, European regulatory bodies reinforced import controls on specific functional ingredients used in infant formula manufacture, mandating enhanced border checks, laboratory analyses, and certification requirements. These measures introduce additional verification steps and supply chain transparency demands for manufacturers relying on imported functional oil components. The report quantifies the operational implications of these regulatory shifts and maps compliant pathway options for market entrants and established players alike.
The Premiumization Economics: Why Sheep Milk Commands Strategic Attention
The economic rationale for investing in sheep milk-based infant nutrition is rooted in a compelling nutritional narrative that translates directly into consumer preference and pricing power. Sheep milk possesses a whey-to-casein ratio that more closely aligns with human breast milk than conventional cow milk alternatives. This biochemical similarity supports digestion profiles that resonate with parents seeking gentler nutritional options for infants and toddlers, reducing tolerance issues and building brand trust. This physiological advantage is the foundational driver of product differentiation in a category where ingredient provenance and functional benefits are increasingly scrutinized by healthcare professionals and informed consumers.
However, this premium positioning is inextricably linked to supply economics. Sheep milk production incurs materially higher costs compared to conventional dairy species, driven by smaller herd sizes, lower total milk volumes per animal, and seasonal yield fluctuations. Raw sheep milk prices routinely trade at a significant premium over equivalent cow milk, creating a cost structure that demands precise inventory management, yield optimization, and premium pricing strategies to maintain margin integrity. The report provides a detailed analysis of these cost drivers, evaluating how different business models are managing the gap between input costs and realized selling prices, and identifying the operational levers that separate profitable operators from those that struggle to scale efficiently.
Strategic Recommendations for the 2026 Decision Cycle
As organizations formulate their strategic plans for the remainder of the decade, several actionable imperatives emerge from the data and competitive analysis. First, the concentration of production capabilities in a limited number of geographic regions necessitates a deliberate approach to supply chain resilience. Companies must evaluate long-term supply agreements, explore co-investment opportunities with upstream producers, and assess the risk exposure associated with reliance on single-source or concentrated ingredient flows.
Second, the regulatory environment demands proactive compliance architecture. With infant formula registration and production controls tightening in major markets, organizations must integrate regulatory strategy into product development timelines rather than treating compliance as a post-development checkpoint. The report outlines the specific registration pathways, documentation requirements, and testing protocols that will define market access in the coming years.
Third, channel strategy must be calibrated to the distinct economics of sheep milk products. Premium positioning requires distribution environments that support brand storytelling, consumer education, and controlled price maintenance. Our analysis provides a framework for evaluating channel partners, assessing shelf placement opportunities, and building omnichannel approaches that leverage online reach while preserving the premium experience in physical retail environments.
Accessing the Complete Intelligence Architecture
The analysis presented here provides a strategic overview of the market forces, competitive dynamics, and regulatory currents shaping the worldwide sheep milk and infant formula landscape. However, the full operational value of this research resides in the detailed segmentation data, regional market sizing, channel-specific revenue tracking, and granular company performance metrics that form the backbone of our comprehensive report. The precise market valuations for each product category, the channel-level revenue distributions, the regional demand allocations, and the forward-looking scenario models are essential tools for supply chain planning, pricing strategy, market entry assessments, and investor communications.
For corporate teams ready to translate this intelligence into executed strategy, the complete dataset provides the calibrated inputs required for financial modeling, capacity planning, and competitive response formulation. We invite strategic decision-makers, business development leaders, and market intelligence professionals to access the full Worldwide Sheep Milk and Infant Formula Market research to obtain the complete segmentation breakdowns, historical time-series data, five-year forecast trajectories, and detailed competitive profiling that will drive your 2026 and beyond planning cycles. The market is expanding with certainty; the organizations that succeed will be those that navigate its complexity with precision and data-driven clarity.
Goat Milk Infant Formula Market
For detailed analysis of this topic, please visit the official page: Worldwide Sheep Milk and Infant Formula Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com