

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Uniform Rental Market Hits $16.5B in 2025, Forecasts 4.25% CAGR to $22.07B by 2032

Navigating the Uniform Rental Landscape: Strategic Intelligence for 2026 and Beyond
The uniform rental market stands at a pivotal juncture as organizations navigate shifting operational cost structures, evolving compliance requirements, and an increasingly consolidated competitive environment. As enterprises recalibrate their procurement strategies and workplace service expectations, the ability to anticipate demand shifts, evaluate supplier risk, and align rental agreements with long-term operational goals has never been more critical. Our latest Uniform Rental Market study delivers a comprehensive, forward-looking assessment designed specifically to equip executive decision-makers, procurement leaders, and industry strategists with the analytical rigor required to navigate the 2026 business landscape and the years ahead.
This research is structured not as a static snapshot, but as a dynamic decision-support framework. It maps the trajectory of a sector that has demonstrated remarkable resilience through recent macroeconomic volatility, while simultaneously confronting structural pressures ranging from supply chain reconfiguration to labor cost dynamics. By synthesizing historical performance patterns with rigorously modeled forward projections, the report provides a clear lens through which organizations can benchmark their positioning, identify whitespace opportunities, and mitigate exposure to emerging market disruptions.
Market Scale and Trajectory: A Foundation for Strategic Planning
Understanding the magnitude and momentum of the uniform rental sector is the first step toward embedding it effectively within corporate strategy. Over the historical window spanning 2020 through 2025, the market navigated a period of recovery, adaptation, and measured expansion. After moving past initial operational disruptions, the industry demonstrated a steady upward trajectory, with total market revenue climbing to approximately $16.5 billion by the 2025 base year. This progression reflects the enduring institutional demand for managed workwear solutions across sectors that prioritize standardization, compliance, hygiene, and operational efficiency.
Looking ahead to the 2026–2032 forecast period, the market is positioned for continued expansion at a compound annual growth rate of 4.25 percent. This growth path is not merely a linear extrapolation; it reflects the compounding effect of sustained enterprise adoption, incremental sectoral demand, and the gradual integration of advanced logistics and facility service models into traditional uniform rental frameworks. By the close of the forecast horizon in 2032, total market revenue is projected to approach $22 billion, signaling a sector that continues to embed itself more deeply into the operational fabric of modern enterprises.
For strategic planners, these macro-level indicators serve as a critical baseline. They underscore that uniform rental is not a commoditized, static service category, but a dynamic commercial ecosystem influenced by end-user procurement cycles, regulatory shifts, and competitive restructuring. Leaders who internalize this trajectory can better time contract renewals, evaluate capital allocation toward workplace service partnerships, and anticipate how broader economic conditions will shape pricing power and service expectations across the value chain.
Workwear and Uniforms Market
Core Segments and Demand Drivers: Where Growth Converges
The uniform rental ecosystem is shaped by multiple intersecting dimensions, each carrying distinct operational implications for providers and buyers alike. At the highest level, the market divides into several foundational categories that dictate product specifications, service logistics, and compliance requirements. Industrial uniforms remain the dominant segment, reflecting the persistent need for durable, safety-aligned workwear across manufacturing environments, warehousing operations, and heavy-duty service applications. Food and beverage uniforms represent another substantial pillar, driven by stringent hygiene standards, brand consistency requirements, and high-turnover operational models that favor rental over ownership. Healthcare and medical wear constitutes a third critical pillar, where regulatory compliance, infection control protocols, and specialized fabric performance create a highly differentiated service environment.
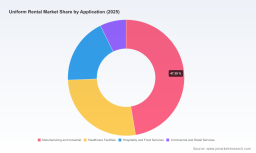
These categorical divisions are further amplified by application-specific demand patterns. Manufacturing and industrial environments remain the largest operational anchor for uniform rental programs, supported by the practical advantages of centralized laundering, inventory management, and replacement logistics. Healthcare facilities form a second major demand center, where uniform and clinical wear programs intersect with patient safety mandates and staff standardization initiatives. Hospitality and food services continue to represent a meaningful application segment, driven by brand image management, linen and uniform integration, and the operational complexity of multi-site service delivery. Commercial and retail services round out the broader application landscape, where appearance standards, employee branding, and seasonal staffing fluctuations influence rental program sizing and rotation models.
For enterprise decision-makers, the strategic value lies in recognizing how these segments interact with organizational priorities. A manufacturing firm evaluating vendor consolidation must weigh industrial-grade durability and safety compliance against total cost of ownership. A healthcare network designing a standardized clinical wear program must navigate fabric certifications, laundering validation, and staff comfort alongside contract flexibility. A hospitality operator managing multi-property uniforms and linens must reconcile brand consistency with rapid replacement cycles and regional service availability. Our report dissects these application-level dynamics in detail, providing the analytical scaffolding needed to match rental program design with operational reality.
Uniform Rental Market
Competitive Architecture and Consolidation Pressures
The competitive dynamics of the uniform rental market have entered a phase of pronounced restructuring. Market concentration metrics indicate a moderately consolidated landscape, with the top three providers collectively accounting for approximately 45.5 percent of total market revenue and the top five firms capturing roughly 58.2 percent. This concentration reflects the operational scale advantages inherent in uniform rental logistics, including route optimization, centralized laundering capacity, national delivery networks, and the ability to offer integrated facility service portfolios.
Several established players define the current competitive frontier. Cintas Corporation has built a comprehensive platform spanning uniform rental, facility services, and workplace supplies, serving diverse end markets with broad program flexibility. UniFirst Corporation delivers uniform rental and facility solutions to a substantial daily workforce footprint, emphasizing workwear, floor mats, and hygiene-related service offerings across multiple sectors. Vestis Corporation operates as a major North American provider with full-service uniform care, delivery, and maintenance infrastructure. Aramark integrates uniform rental within a broader facilities management umbrella, maintaining a particularly visible presence in healthcare, hospitality, and industrial environments. Alsco Uniforms brings more than a century of experience in work apparel, laundering, and linen supply, while Mission Linen Supply and Prudential Overall Supply demonstrate the continued importance of regionally anchored and specialized service models across Western markets and cleanroom or facility-specific applications.
The strategic landscape is now being reshaped by transformative consolidation moves. A landmark acquisition agreement announced in March 2026 will see Cintas acquire UniFirst in a transaction valued at $5.5 billion, a move explicitly designed to expand service capabilities and deepen workday solutions across combined client portfolios. With closing expected in the second half of 2026, this development will meaningfully reduce the number of major competitors in the North American uniform rental market and alter the competitive calculus for both suppliers and enterprise buyers. Organizations evaluating multi-year rental partnerships must now factor in potential service integration timelines, pricing strategy shifts, and the broader implications of a more concentrated supplier base on negotiation leverage and program customization.
Recent industry survey data reinforces the sense of measured momentum. The Q1 2026 Uniform and Linen Services Industry Survey, conducted in partnership with Robert W. Baird & Co., indicated steady growth with rental revenues performing above expectations for many respondents. At the same time, employment-driven wearer growth remained largely neutral in late 2025 surveys, pointing to a market where revenue expansion is increasingly driven by pricing discipline, service bundling, and retention rather than raw headcount expansion alone. These structural nuances are central to the competitive analysis presented in the full study.
Operational Dynamics and External Pressures
No strategic assessment of the uniform rental market is complete without confronting the external forces that shape cost structures, service design, and supplier resilience. The industry remains highly labor-dependent, relying extensively on route service representatives and laundry operations personnel to maintain service quality, delivery reliability, and garment lifecycle management. This labor intensity means that wage dynamics, workforce availability, and operational efficiency initiatives directly influence program economics and, by extension, contract pricing and service-level commitments.
Simultaneously, regulatory and trade environments have introduced new cost pressures. Revised U.S. tariffs on imported textiles and protective gear components implemented in 2025 have begun to pressure cost structures for uniform rental providers, prompting a broader reassessment of supplier diversification and sourcing strategies. For enterprises locked into long-duration rental agreements, these dynamics can affect garment replacement cycles, availability of specialized protective components, and the pace at which providers pass through cost adjustments. Understanding how suppliers are adapting their procurement footprints and inventory strategies is therefore essential for risk-aware contract design.
These operational and external pressures do not exist in isolation. They intersect with broader market dynamics, including the pace of consolidation, regional service density, and the growing expectation that rental providers function as integrated workplace service partners rather than simple garment lessors. Providers that successfully align logistics efficiency, compliance assurance, and flexible program design are best positioned to defend margins and retain enterprise accounts. Conversely, buyers that fail to evaluate supplier resilience, labor model sustainability, and sourcing diversification risk encountering service variability or unexpected cost shifts over the life of their contracts.
Inside the Report: Analytical Depth for Actionable Decisions
Our Uniform Rental Market study is engineered to translate complex market signals into clear, actionable intelligence. Rather than offering a superficial overview, the report delivers a multi-layered analytical architecture designed for executive review, procurement planning, and competitive benchmarking. The full study includes a detailed market sizing framework that traces historical revenue evolution and forward projections across the entire forecast horizon, providing a reliable baseline for capacity planning, investment prioritization, and demand forecasting.
The segmentation analysis goes beyond aggregate figures to examine how distinct uniform categories and application environments behave under varying operational and economic conditions. Readers gain access to structured assessments of demand drivers, replacement cycles, compliance dependencies, and service intensity across industrial, healthcare, food and beverage, hospitality, and commercial use cases. This segmented perspective enables decision-makers to isolate the most relevant growth vectors for their specific operating context and avoid the trap of treating the uniform rental market as a monolithic category.
The competitive intelligence section provides a systematic evaluation of leading providers, their service portfolios, geographic footprints, and strategic positioning. It examines how major operators differentiate through logistics scale, integrated facility services, specialized garment programs, and regional coverage models. The analysis also maps the implications of recent consolidation activity, offering a forward-looking assessment of how market concentration may influence pricing behavior, service innovation, and buyer negotiation dynamics over the coming years.
Complementing the structural analysis, the report incorporates an external dynamics review that addresses tariff impacts, labor cost sensitivities, industry survey signals, and the evolving expectation set around provider reliability and service integration. By linking these macro and operational factors directly to rental program performance, the study equips leaders with the context needed to stress-test supplier relationships, anticipate cost pressure transmission, and design contract frameworks that balance flexibility with long-term stability.
Why This Research Matters for 2026 Decision-Making
The strategic value of this study lies in its ability to convert market complexity into decision-ready clarity. In 2026, uniform rental procurement is no longer a routine administrative function; it is a strategic lever that touches workforce compliance, brand presentation, operational continuity, and total cost management. The convergence of a moderately concentrated supplier base, transformative consolidation, evolving trade and labor conditions, and steady demand growth creates an environment where informed procurement strategy can yield measurable competitive advantage.
Enterprises that engage with this research will be better positioned to evaluate vendor consolidation proposals, benchmark existing rental agreements against market trajectories, identify segments with the most favorable growth-to-risk profiles, and construct procurement roadmaps aligned with both operational needs and financial discipline. Suppliers and investors, meanwhile, will gain a clearer view of where service differentiation is most valued, how concentration is reshaping competitive incentives, and which application areas offer the strongest pathways for sustained expansion.
The complete Uniform Rental Market report expands significantly on the themes introduced here, delivering the detailed sizing architecture, segmented demand analysis, competitive evaluations, and dynamic risk assessments required for high-stakes decision-making. To access the full dataset, scenario frameworks, and provider-level strategic breakdowns, we invite you to explore the complete study on our website. In a market defined by consolidation, cost complexity, and steady structural growth, comprehensive intelligence is not simply an asset. It is the foundation of resilient strategy.
For detailed analysis of this topic, please visit the official page: Uniform Rental Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com