

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Antiperspirant Aluminum Chlorohydrate Market Hits $850M in 2025, Projected 5.2% CAGR to 2032

Navigating the Worldwide Antiperspirant Aluminum Chlorohydrate Market: Strategic Intelligence for 2026
The global personal care industry stands at a critical juncture where formulation efficacy, regulatory compliance, and supply chain resilience intersect. For decision-makers operating within or adjacent to the antiperspirant sector, understanding the trajectory of aluminum chlorohydrate is no longer optional. As the primary active ingredient responsible for sweat reduction, aluminum chlorohydrate anchors a market that has demonstrated steady expansion through recent historical cycles and is projected to maintain disciplined growth over the coming forecast horizon. PW Consulting has compiled a comprehensive Worldwide Antiperspirant Aluminum Chlorohydrate Market study designed to translate macroeconomic signals, competitive movements, and regulatory shifts into actionable intelligence for 2026 and beyond.
This research is structured as a strategic companion rather than a static data repository. It maps historical performance across a six-year retrospective window and extends forward through a multi-year forecast period, enabling stakeholders to align procurement timelines, capacity planning, and market entry strategies with verified directional trends. The base year anchors the analysis at 2025, providing a calibrated reference point from which growth rates, concentration dynamics, and segment equilibria are measured. Readers seeking granular percentage allocations, discrete regional revenue figures, and application-specific breakdowns will find those detailed datasets within the full publication, where they are presented alongside methodological notes and scenario sensitivity models.
Market Trajectory and Macro Growth Architecture
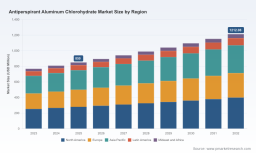
The worldwide antiperspirant aluminum chlorohydrate market has moved from a 2023 baseline of approximately 768 million USD to an estimated 808 million USD in 2024, reaching a projected 850 million USD in 2025. This progression reflects a compound annual growth rate of roughly 5.2 percent across the forecast horizon extending through the early 2030s. Such a cadence signals a mature yet expanding category, where volume gains are increasingly intertwined with value optimization, grade differentiation, and formulation innovation rather than relying solely on population-driven demand expansion.
Forward-looking valuations trace a consistent upward slope, with the market projected to approach 894 million USD in 2026, rising to 940 million USD in 2027 and crossing the 1 billion USD threshold shortly thereafter. The trajectory culminates in a projected 1.2 billion USD valuation by the end of the forecast window. This growth architecture is underpinned by continuous refresh cycles in personal care portfolios, the proliferation of body confidence and performance-oriented grooming products, and sustained demand for reliable sweat-control actives that function across diverse climatic and cultural usage patterns.
Importantly, these headline figures represent aggregate market dynamics. The distribution of value across forms, application formats, and geographies is far from uniform. Liquid formulations continue to command a substantial share of the total value pool, while powder-based routes maintain a distinct but smaller footprint. Within application channels, roll-on and stick formats have historically anchored consumer preferences, with sprays and creams-and-other segments contributing more specialized demand profiles. Regional performance similarly reflects divergent purchasing power, climatic drivers, and regulatory environments. The complete study isolates these dimensions with precise calibration, enabling readers to benchmark their own portfolio exposure against verified segment equilibria and to identify where competitive intensity is most concentrated.
Report Content and Operational Utility for Executives
PW Consulting’s analysis is engineered for immediate operational relevance. Beyond macro valuation frames, the report delivers a structured examination of market architecture, competitive positioning, and the external forces that shape cost structures, formulation choices, and compliance pathways. The content is organized to support cross-functional alignment among procurement, R&D, regulatory affairs, and commercial strategy teams, ensuring that insights can be translated into concrete action plans without requiring additional data reconstruction.
The document includes a detailed segmentation exploration that maps how different product forms and application formats compete for consumer attention and manufacturer investment. It describes the structural factors that drive volume allocation across these categories, including textural expectations, packaging compatibility, ease of formulation, and regional usage habits. By presenting these dynamics in a comparative framework, the report helps stakeholders identify where formulation innovation can unlock incremental share and where cost optimization may be achieved through grade selection or processing adjustments.
Supply-side intelligence forms another core pillar of the publication. The research examines the upstream ecosystem that feeds aluminum chlorohydrate production, including the role of alumina feedstocks, specialty chemical processing, and purity specifications required for cosmetic and personal care applications. It contextualizes how raw material pricing movements, refinery and specialty alumina capacity decisions, and logistics cost fluctuations influence the effective cost of goods for downstream formulators. These elements are treated not as isolated news items but as integrated variables within a cost-and-supply model that can be applied to budgeting, hedging considerations, and supplier evaluation processes.
The report also incorporates a regulatory and compliance review that addresses evolving chemical safety frameworks, concentration limits, labeling requirements, and regional substance restrictions. Regulatory trajectories are analyzed for their potential to reshape formulation choices, especially in high-sensitivity markets where consumer exposure concerns intersect with product efficacy expectations. By mapping these developments alongside ingredient functionality and grade differentiation, the study equips teams to anticipate reformulation needs, assess alternative grade suitability, and maintain alignment with both current mandates and emerging precaution-based standards.
Competitive Landscape and Key Company Positioning
The antiperspirant aluminum chlorohydrate market reflects a moderately concentrated competitive environment, with a limited group of large suppliers accounting for a significant portion of total value. This concentration creates both advantages and vulnerabilities for downstream customers. On one hand, established suppliers offer consistent quality, broad grade portfolios, and the ability to support global scale demands. On the other, reliance on a narrow supplier base can amplify exposure to capacity disruptions, regional logistics friction, and price volatility in upstream inputs. Understanding where competitive leverage resides is essential for procurement strategy and risk management.
Summit Reheis operates as a leading global supplier of aluminum chlorohydrate active ingredients for antiperspirant use, offering both standard and enhanced grades that support a wide range of deodorant and antiperspirant formulations. The company’s product range, including grades such as ACH 410 and Reheis AHA, illustrates the industry trend toward differentiated actives that balance efficacy with formulation compatibility. In late 2024, Summit Reheis introduced an ultra low-irritancy grade designed for sensitive skin antiperspirants, signaling how supplier innovation is increasingly oriented toward consumer tolerance and skin-friendly performance profiles.
Rio Tinto contributes to the supply landscape through its specialty alumina division, which produces high-purity aluminum chlorohydrate materials destined for personal care manufacturers worldwide. Its involvement highlights the importance of integrated upstream capability in maintaining consistent supply. In mid 2024, the company expanded specialty alumina production capacity by 15 percent to support growing antiperspirant active demand, demonstrating how capacity decisions at the specialty materials level can ripple through the broader market and influence availability in downstream channels.
Givaudan supplies aluminum chlorohydrate-based antiperspirant actives via its personal care division, with a focus on low-odor, high-efficacy grades that serve global deodorant brands. The company’s emphasis on sensory performance and brand-aligned characteristics reflects the broader shift in which antiperspirant actives are increasingly evaluated not only on biological efficacy but also on user experience, fragrance compatibility, and application feel. Recent updates to certification and sustainability reporting underscore the growing relevance of responsible sourcing and documented compliance in supplier selection.
Worldwide Aluminum Zirconium Tetrachlorohydrex Glycine (AZAG) Market
Nippon Light Metal Holdings manufactures high-purity aluminum chlorohydrate for antiperspirant applications, with particular emphasis on cosmetic-grade specifications and export-oriented supply reaching Asia-Pacific and global markets. Its positioning demonstrates how regional manufacturing expertise and purity control can support international demand while addressing market-specific quality expectations. In parallel, Advancion Corporation provides custom aluminum chlorohydrate solutions tailored to antiperspirant formulations, including polyaluminum chloride variants optimized for sweat reduction efficacy. This custom approach indicates a segment of the market where formulation engineers require more than off-the-shelf grades and instead seek partners who can tune material characteristics to specific performance targets.
Worldwide Antiperspirant Aluminum Chlorohydrate Market
Together, these players illustrate a competitive landscape shaped by grade differentiation, purity control, formulation support, and capacity responsiveness. The full report profiles these companies and others within a comparative framework, examining their strategic moves, product introductions, capacity actions, and certification developments. By mapping these activities against market share concentration and regional supply flows, the study clarifies where competitive barriers exist and where opportunities for differentiated supplier partnerships may emerge.
Industry Dynamics: Raw Materials, Regulation, Tariffs, and Logistics
Market behavior in aluminum chlorohydrate does not evolve in isolation. It is continuously reshaped by external conditions that influence cost, compliance, and competitive access. One of the most immediate pressures in recent quarters has come from raw material dynamics. Alumina feedstock prices have experienced notable upward movement, driven by bauxite supply constraints and broader mineral commodity tightness. This shift translates directly into elevated input costs for specialty chemical producers and, ultimately, into formulation economics for antiperspirant manufacturers. The report incorporates these material cost trends as part of a wider cost-structure analysis, helping readers distinguish between temporary shocks and structural cost recalibration.
Regulatory developments add another layer of complexity. In Europe, evolving chemical safety frameworks have introduced concentration restrictions relevant to aluminum chlorohydrate in cosmetic applications. These mandates affect formulation ceilings and can influence how brands position products across sensitive and general-use categories. Alongside concentration limits, broader environmental and health-related listings in certain jurisdictions have increased scrutiny for consumer-facing products containing aluminum compounds. Although such listings do not uniformly apply across markets, they shape labeling practice, consumer perception, and risk assessment in regions where precautionary communication is becoming more prominent.
Trade policy introduces further asymmetry across geographies. Tariff measures affecting imports of aluminum chlorohydrate from specific origins have altered the cost calculus for formulators that rely on cross-border sourcing. A 25 percent tariff structure linked to designated import classifications has placed additional pressure on supply plans that previously depended on lower-cost overseas material flows. For multinational brands and regional formulators alike, this reinforces the value of diversified sourcing, near-shoring considerations, and supplier relationships that can absorb policy-induced cost shifts without disrupting supply continuity.
Logistics costs also remain a salient factor. Global ocean freight rates for chemical shipments have seen meaningful increases, adding to the landed cost burden for internationally sourced actives and intermediates. These freight dynamics intersect with production scheduling, inventory positioning, and regional distribution strategies. In a market where grade consistency and delivery reliability matter, transportation cost volatility can influence regional pricing patterns and supplier selection even when base ingredient pricing appears stable.
Strategic Decision Framework for 2026
For executives planning 2026 operations, the strategic challenge is not merely to observe growth but to interpret it within the constraints and opportunities created by formulation trends, sourcing realities, and regulatory trajectories. The aluminum chlorohydrate market’s projected expansion at a disciplined compound rate suggests that demand will continue to provide a supportive backdrop, but that growth will increasingly reward organizations capable of managing complexity rather than simply riding volume momentum.
One priority is formulation strategy. As consumer expectations evolve around sensory feel, skin compatibility, and odor management, the selection of aluminum chlorohydrate grades becomes a tactical decision with both performance and market-access implications. Teams should evaluate how specific grades align with target user profiles, regional preference patterns, and packaging systems. The report’s segmentation insights help frame these choices by revealing how different application formats and product forms compete for share and where innovation may create differentiation without compromising cost efficiency.
A second priority is sourcing resilience. Given the concentration of supply among established active ingredient producers and the influence of upstream raw material pricing, procurement strategies should weigh supplier diversification, grade flexibility, and contractual structures that reduce exposure to freight and tariff volatility. Capacity expansion announcements from major suppliers indicate that supply-side responsiveness exists, but access to that capacity depends on relationship strength, specification alignment, and regional procurement planning. The full study provides the competitive and concentration context needed to assess where reliance is justified and where contingency planning is advisable.
A third priority is regulatory foresight. Concentration limits and precautionary listings are likely to continue shaping formulation decisions, especially for brands that operate across multiple jurisdictions. Anticipating reformulation requirements, reviewing alternative grade suitability, and monitoring certification and sustainability documentation can reduce the likelihood of disruptive compliance events. Interpretation of these developments should be integrated with R&D timelines so that product roadmaps remain aligned with both current mandates and plausible future constraints.
Finally, commercial strategy should reflect the interplay between geography, form, and application. While aggregate growth provides a positive market signal, regional and format-level dynamics differ materially. Organizations that understand where value is accumulating, which formats are driven by local usage patterns, and how trade and logistics conditions affect regional accessibility will be better positioned to allocate investment and adjust portfolio exposure. The complete report disaggregates these patterns in detail, allowing readers to map them against their own footprint and competitive context.
Why the Full Study Matters
Snapshot data and aggregated growth rates provide direction, but strategic decisions require deeper calibration. The full PW Consulting Worldwide Antiperspirant Aluminum Chlorohydrate Market report delivers the precision, segmentation detail, company-specific intelligence, and contextual analysis needed to convert market signals into executable strategy. It distinguishes between historical trend confirmation and forward-looking scenario interpretation, giving readers a structured basis for planning procurement, formulation, compliance, and market development activities throughout 2026 and beyond.
The publication is designed to serve as a shared reference point across functions, ensuring that commercial, technical, and supply teams are operating from a common evidence base. Its segmentation analysis isolates the dimensions that matter most to product planning, while its competitive and dynamics assessments provide context for risk management and supplier strategy. By consolidating macroeconomic data, regulatory developments, trade conditions, and company-level activity within a single analytical framework, the report reduces the time required to assemble actionable intelligence and increases the confidence with which decisions can be made.
For organizations seeking to navigate a market defined by steady expansion, concentrated supply, evolving regulation, and shifting formulation expectations, this research offers the depth required to move beyond generalizations and toward precise strategic positioning. The aggregated market figures, growth cadence, and competitive patterns outlined here are intended to establish the strategic frame. The detailed segmentation splits, discrete regional valuations, and application-level distributions that support them are presented in full within the complete study, where they can be examined alongside methodological notes and scenario-ready analysis.
In a category where ingredient performance, regulatory readiness, and supply continuity collectively determine market access, timely and well-structured intelligence is not an accessory. It is a prerequisite for confident action. PW Consulting’s Worldwide Antiperspirant Aluminum Chlorohydrate Market study provides that foundation, enabling leaders to align 2026 decisions with verified market direction, competitive reality, and operational feasibility.
For detailed analysis of this topic, please visit the official page: Worldwide Antiperspirant Aluminum Chlorohydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com