

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Boat Black Water Treatment Market to Hit $854.13M by 2032 at 6.89% CAGR

Navigating the Currents: Strategic Intelligence for the Worldwide Black Water Treatment System for Boats Market (2026-2032)
Executive Overview: The Imperative for Precision Intelligence
As the maritime industry accelerates toward stricter environmental compliance and operational sustainability, the management of vessel-generated black water has evolved from a regulatory checkbox into a core component of marine engineering strategy. PW Consulting is pleased to introduce our comprehensive Worldwide Black Water Treatment System for Boats Market research, a strategic intelligence asset designed to equip decision-makers with the clarity required to navigate a sector defined by evolving regulatory frameworks, technological diversification, and shifting demand patterns across leisure, commercial, and defense segments.
This market study is built on a rigorous analytical foundation spanning historical performance from 2020 through the base year of 2025, with a forward-looking forecast period extending to 2032. Drawing from primary research, expert interviews, and verified secondary datasets, the report provides a 360-degree view of market structure, competitive positioning, and growth vectors. For executives evaluating capital allocation, product development roadmaps, or market entry strategies in the marine sanitation space, this intelligence serves as a critical reference point for minimizing risk and identifying high-value opportunities.
The maritime environment is no longer operating in a static regulatory landscape. Compliance with MARPOL Annex IV, IMO MEPC.227(64) effluent standards, and USCG classification requirements has fundamentally reshaped procurement cycles, technology selection, and vessel retrofit strategies. In this context, general industry narratives are insufficient. Stakeholders require granular, verified, and actionable intelligence that connects regulatory traction to commercial viability. Our report delivers precisely that: a consolidated, data-backed perspective that transforms market complexity into strategic clarity.
Market Trajectory and Growth Vector: A Data-Backed Lens
The worldwide market for black water treatment systems for boats has demonstrated consistent expansion over the past half-decade, reflecting a confluence of vessel modernization, environmental enforcement, and the growing commercialization of marine leisure and offshore operations. Based on verified revenue tracking, the market reached a valuation of approximately 535.4 million USD in the 2025 base year, following a measured growth curve from 382.45 million USD in 2020. This progression underscores a sector that has moved beyond early adoption dynamics into a phase of structured, demand-driven expansion.
Looking ahead, the forecast period through 2032 indicates sustained upward momentum, with a projected compound annual growth rate of 6.89 percent. By 2032, the market is anticipated to reach an estimated 854.13 million USD, signaling a meaningful expansion in total addressable demand. This trajectory is not merely a function of broader marine industry growth; it is increasingly tethered to regulatory-driven retrofitting, the replacement of legacy holding-tank-dependent configurations with advanced treatment technologies, and the integration of wastewater management into broader vessel system architectures.
Importantly, this growth is not uniform across all vessel classes or geographic deployments. The market's expansion is being shaped by differentiated adoption curves, varying compliance stringency, and distinct procurement behaviors between recreational, commercial, and defense end-users. Understanding where value is concentrating, which technology pathways are gaining traction, and how regional regulatory environments influence purchasing decisions is essential for any organization seeking to capture share in this evolving landscape. Our report unpacks these dynamics with precision, enabling clients to move beyond top-line growth narratives and develop segment-specific strategies grounded in verified market structure.
Segmentation Landscape: Technology, End-Use, and Regional Configuration
The architecture of the black water treatment system market is defined by three critical segmentation dimensions: system type, end-use application, and regional deployment. Each dimension carries distinct implications for product specification, certification pathways, pricing dynamics, and competitive positioning.
At the technology level, the market is structured around multiple marine sanitation device classifications and treatment methodologies, ranging from electrochemical and heat-based systems to biological and membrane-assisted platforms. These technology pathways are not interchangeable; they are governed by vessel size constraints, discharge zone regulations, operational profiles, and maintenance expectations. Type II and Type III marine sanitation devices have emerged as significant components of the market structure, reflecting their broader applicability across inspected vessels, larger recreational craft, and commercial platforms. Meanwhile, specialized Type I configurations continue to serve a focused but strategically important segment of smaller vessels operating under specific discharge allowances. The interplay between certification requirements, system complexity, and total cost of ownership creates a segmentation environment where technology selection is as much a compliance and operational decision as it is a product choice.
End-use segmentation further differentiates demand behavior. Leisure boats and yachts represent a substantial portion of market activity, driven by owner expectations for compact, odor-free, and low-maintenance solutions, as well as increasing environmental awareness within the recreational marine sector. Commercial vessels constitute another major demand pillar, where treatment system selection is shaped by operational uptime requirements, crew size, voyage duration, and compliance obligations across multiple jurisdictions. Military and defense applications, while smaller in relative scale, introduce distinct procurement dynamics tied to standardization, durability, and mission-specific performance criteria.
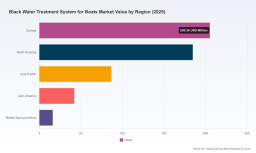
Regionally, the market reflects a concentration of activity in established maritime economies, while emerging marine markets present incremental but structurally important growth potential. Regulatory maturity, vessel fleet composition, after-sales service infrastructure, and local certification pathways all influence how regional demand translates into commercial opportunity. Rather than presenting isolated regional snapshots, the report integrates these geographic dynamics into a cohesive global map, helping clients identify where market presence is strongest, where compliance-driven demand is accelerating, and where tactical entry or expansion strategies may yield the highest return.
Regulatory and Operational Dynamics Shaping Market Behavior
The commercial trajectory of marine black water treatment systems is inextricably linked to the regulatory environment. International and national standards do not simply define compliance boundaries; they actively shape technology adoption, vessel design priorities, and procurement timelines. Under MARPOL Annex IV, vessels of 400 gross tonnage and above, or those certified to carry 15 or more persons, must be equipped with an approved sewage treatment plant, a sewage comminuting and disinfecting system with holding tank, or an appropriate holding tank configuration. Discharge of untreated sewage is restricted to distances beyond 12 nautical miles from the nearest land, at approved rates while underway at not less than 4 knots. These parameters create a baseline compliance framework that directly influences equipment specification across commercial and larger recreational vessels.
Ballast Water Treatment Equipment Market
Further refining the compliance landscape, IMO Resolution MEPC.227(64) establishes revised effluent standards and performance test criteria for sewage treatment plants, including nitrogen and phosphorus limits applicable to special areas such as the Baltic Sea. Treated effluent must produce no visible floating solids and must not cause discoloration of surrounding waters. These standards elevate the performance bar for treatment systems and reinforce the shift toward solutions capable of meeting stricter discharge criteria without reliance on passive holding alone.
In the United States, the USCG classification framework adds another layer of decision-making complexity. Type I systems, including electrochemical or heat-based configurations, are certified for vessels under 65 feet and may allow treated black water discharge in areas that are not designated as no-discharge zones. Type II systems apply to larger inspected vessels and require more stringent biological or chemical treatment processes under 33 CFR Part 159. For US-flagged vessels on international voyages, voluntary compliance with MARPOL Annex IV can be demonstrated through a USCG Statement of Voluntary Compliance based on NVIC 1-09 guidance, particularly where treatment plants meet MEPC.227(64) or equivalent standards. This regulatory ecosystem means that product certification, operational zone eligibility, and system sizing are not peripheral considerations; they are central to market access.
Operational considerations further influence purchasing behavior. Marine sewage treatment systems commonly incorporate corrosion-resistant construction materials, including marine-grade aluminum or steel coated with ceramic-filled epoxy, to withstand the demanding conditions of black water handling. System design must also account for maintenance frequency, footprint constraints, energy consumption, and ease of integration with existing vessel infrastructure. These practical realities create a purchasing environment where specifiers evaluate not only regulatory compliance, but also serviceability, reliability, and lifecycle cost. The result is a market in which differentiation is increasingly driven by engineering robustness, certification breadth, and application-specific optimization.
Competitive Arena: Leadership, Specialization, and Strategic Positioning
The competitive landscape for marine black water treatment systems is characterized by a mix of established marine equipment manufacturers, specialized sanitation providers, and global technology groups with integrated waste management capabilities. The market exhibits a moderately concentrated structure, with the top three competitors collectively holding approximately 32.4 percent of market share and the top five firms accounting for around 48.75 percent. This concentration suggests that while scale players exert meaningful influence, there remains substantial room for specialized firms to compete on technology differentiation, application focus, and regional service strength.
Several core companies illustrate the breadth of strategic positioning within the sector. GROCO offers a portfolio encompassing heat-based Type I systems such as Thermopure for vessels under 65 feet, electrochemical ElectroScan technology that generates disinfectant from salt water, and Type III holding system configurations designed for compact and reliable sanitation in recreational and small marine applications. Raritan Engineering Company is widely recognized for its ElectroScan Type I MSD, which uses electrodes to convert salt water into a bactericide, enabling black water treatment without reliance on holding tanks in permitted discharge areas for vessels up to 65 feet. Headhunter Inc. focuses on marine sewage treatment plants and MSDs, including the TidalWave HMX platform, which is IMO MEPC.227(64) and USCG Type II certified and employs chemical oxidation, hydro-maceration, and cross-flow separation for vessels over 65 feet with capacities ranging from 50 to 10,000 US gallons per day.
Worldwide Black Water Treatment System for Boats Market
On the international stage, De Nora contributes electrolytic marine wastewater treatment through its OMNIPURE platform, which uses DSA electrode technology for oxidation and disinfection without biological media or additives, and is certified to IMO MEPC.227(64) and USCG standards. RedFox Environmental Services manufactures USCG and IMO certified marine sewage treatment units for black water across marine, offshore, and land applications, meeting MEPC.227(64) and EPA compliance requirements, with production based in Louisiana and global service support. Ahead Sanitation Systems supplies USCG Certified Type II marine sanitation devices for a broad range of workboats, tugboats, towboats, barges, yachts, and pleasure craft, emphasizing lightweight, compact, odor-free, low-maintenance aerobic designs. HAMANN AG provides advanced wastewater treatment systems, including the HL-CONT Plus series, for combined black and grey water treatment on superyachts, cruise ships, ferries, and offshore or inland vessels, with compliance for MARPOL Annex IV special areas such as Alaska and the Baltic Sea, utilizing modular designs without filters or membranes.
Additional participants further diversify the competitive field. Scienco/FAST manufactures biological marineFAST sewage treatment systems for blackwater and combined waste streams, with nearly 5,000 installations worldwide and USCG/IMO certifications serving tugs, offshore supply vessels, and commercial ships. Evac delivers integrated marine water and waste management solutions as part of a broader total concept package for vacuum collection and black water processing across multiple vessel types. Wärtsilä offers complete marine waste and wastewater treatment packages, including sewage treatment plants and membrane bioreactor systems for black water management on all types of vessels. ACO Marine specializes in tailored wastewater treatment solutions, including biological Clarimar MF systems for black water, while RWO Water Technologies supplies marine sewage treatment plants as part of pollution prevention equipment with more than 45 years in marine water treatment. H2O Inc., through its Crapzapper line, provides biological marine sanitation devices dual-certified under USCG and IMO MEPC.227(64), with over 4,500 units installed worldwide for crews ranging from 2 to 500. Detegasa rounds out the competitive landscape with high-tech water and waste management solutions designed for navy, marine, and offshore industries.
These companies are not competing on a single axis. Differentiation is emerging through certification scope, vessel class specialization, treatment methodology, corrosion-resistant engineering, and the ability to provide integrated service and support across global fleets. Recent market activity reinforces this competitive intensity with a visible emphasis on trade presence and application-specific positioning. In February 2026, Raritan Engineering Company participated in the Miami International Boat Show, highlighting proven marine sanitation designs including ElectroScan systems. Ahead Sanitation Systems has an active exhibition calendar through the end of 2026, with scheduled showcases of USCG Certified Type II systems at the Inland Marine Expo, the Pacific Marine Expo, and the International WorkBoat Show, underscoring a deliberate push to strengthen visibility across workboat and commercial marine channels. In December 2025, industry coverage from Superyacht Times featured advanced wastewater treatment systems from ACO Marine and HAMANN, addressing black water volumes of up to 500 liters per person per day and the need for tailored sewage management spanning collection through discharge. These developments point to a competitive environment in which market access is being reinforced through demonstration, application focus, and compliance-aligned product narratives.
Report Scope: What Decision-Makers Will Gain
This market research report is designed to move beyond descriptive market overviews and deliver a structured, decision-ready intelligence framework. Clients will gain access to a detailed analysis of market sizing and forecast pathways, supported by historical context and forward-looking projections that clarify growth mechanics rather than simply reporting endpoints. The report examines segmentation dynamics across technology type, end-use application, and regional deployment, enabling users to assess where demand is concentrated and how purchasing behavior varies by segment.
The competitive analysis component provides a structured assessment of leading participants, their product positioning, certification portfolios, and strategic activity. Rather than presenting a static company list, the report contextualizes competitive behavior within the regulatory and operational realities that shape procurement decisions. This allows readers to evaluate not only who is active in the market, but how different players are aligning their offerings with compliance intensity, vessel class requirements, and regional service expectations.
The regulatory and operational sections integrate international and national compliance frameworks into a practical market context, helping users understand how effluent standards, discharge restrictions, and certification pathways influence technology selection, retrofit demand, and product design priorities. In addition, the report addresses material and engineering considerations that affect product durability, maintenance requirements, and lifecycle performance, providing context that is directly relevant to specification, procurement, and risk assessment.
To support strategic planning, the report also maps recent industry developments, including trade show activity, product showcases, and sector-specific coverage that signal how companies are positioning themselves across leisure, commercial, and superyacht applications. This combination of macro-level market structure and micro-level competitive intelligence creates a comprehensive reference point for strategic planning, investment evaluation, and market-entry analysis.
Strategic Application: How to Use This Intelligence in 2026
For organizations operating in or seeking to enter the marine black water treatment sector, the value of this research lies in its ability to connect market structure to action. Executives can use the forecast framework to align product roadmaps with anticipated demand growth, prioritize segment focus based on compliance-driven procurement cycles, and evaluate where technology differentiation offers the strongest competitive leverage. Suppliers can assess how certification breadth, system sizing, and corrosion-resistant engineering influence spec-in decisions across vessel classes, and identify where service and support capabilities may serve as differentiators in fragmented regional markets.
Procurement and specification teams can leverage the regulatory and operational analysis to better understand compliance eligibility, discharge zone constraints, and the practical implications of system type selection for different vessel profiles. Investors and strategic partners can use the market concentration and competitive positioning data to evaluate the intensity of rivalry, the degree of specialization in the supplier base, and the potential for consolidation or technology-led disruption. In all cases, the report is designed to reduce ambiguity and support decisions grounded in verified market structure rather than assumption.
Conclusion: Turning Market Complexity into Strategic Advantage
The worldwide black water treatment system for boats market is entering a phase in which regulatory precision, application specialization, and engineering reliability are increasingly decisive. With a 2025 base year valuation of approximately 535.4 million USD and a projected 2032 market size approaching 854.13 million USD at a 6.89 percent CAGR, the sector offers meaningful growth potential, but that growth is distributed across a nuanced competitive and regulatory landscape. Success in this environment requires more than awareness of overall market expansion; it demands a detailed understanding of technology pathways, certification dynamics, end-use behavior, regional variation, and competitive positioning.
PW Consulting's Worldwide Black Water Treatment System for Boats Market report is structured to deliver that understanding in a form that is immediately useful for strategic planning and commercial decision-making. To access the full dataset, segmentation breakdowns, competitive assessments, and detailed forecast architecture, we invite you to explore the complete report on our website. The full intelligence package provides the depth and granularity required to translate market awareness into actionable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Black Water Treatment System for Boats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com