

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PTBBA Market to Reach $143.63M by 2032, Driven by 4.65% CAGR

Navigating the Global 4-tert-Butylbenzoic Acid Market: Strategic Insights for 2026 and Beyond
Executive Summary: The Imperative for Data-Driven Decision Making
The global chemical landscape is undergoing a period of recalibration, driven by shifting supply chain dynamics, evolving regulatory frameworks, and persistent demand from core polymer and specialty applications. For decision-makers operating in the intermediates and additives space, 2026 represents a pivotal inflection point. In this environment, precision intelligence is no longer optional; it is the foundation of resilient capacity planning, procurement strategy, and competitive positioning. PW Consulting's latest Worldwide 4-tert-Butylbenzoic Acid (PTBBA) Market research report delivers exactly that— a comprehensive, forward-looking analytical framework designed to translate market complexity into actionable strategy.
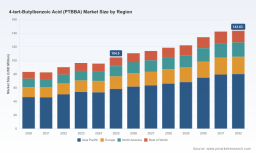
This report sits at the intersection of historical performance and forward trajectory. Drawing on a rigorous historical window spanning 2020 through 2025 and projecting outcomes across the 2026–2032 forecast horizon, the analysis captures both the structural consolidation of recent years and the emergent growth vectors that will define the next cycle. The overarching narrative is one of measured, sustained expansion: the market is projected to grow at a compound annual growth rate of 4.65 percent, supported by steady demand absorption across mature polymer applications and incremental pull from specialty grade requirements. Revenue is tracked in USD millions, providing a consistent valuation baseline for cross-markет benchmarking and investment modeling.
Worldwide 4-tert-Butylbenzoic Acid (PTBBA) Market
What distinguishes this study is its refusal to stop at headline growth. Instead, it dissects the operational and commercial architecture that underpins market performance—segment definitions, regional demand distribution, grade differentiation, feedstock economics, and the competitive maneuvers of incumbent and emerging players. The result is a strategic toolkit calibrated for procurement leaders, capacity planners, M&A analysts, and market entry strategists who need to navigate a market where margin preservation and supply security are increasingly intertwined.
Macro Market Architecture: Growth Trajectory and Structural Composition
The baseline market valuation establishes a clear upward slope over the analysis period. Revenue progressed from a measured base in the early 2020s, absorbed a notable acceleration during the 2022–2023 interval, and stabilized into a higher-order equilibrium by 2025. Looking ahead, the forecast arc signals consistent year-on-year expansion, with the market advancing through a series of stepwise increments that culminate in a substantially larger revenue pool by the close of the 2032 horizon.
This trajectory is not a mechanical extrapolation. It reflects the interplay of application reuse, downstream polymer demand retention, and the steady rationalization of grade specifications. The report frames this growth through three foundational segmentation lenses, each of which carries distinct commercial implications for buyers and producers alike.
Grade segmentation highlights the differentiated value pools within the market. High-purity refined grades command structural dominance in specification-sensitive applications, while industrial-grade material sustains a meaningful share tied to cost-optimized formulations and bulk processing. The split between these tiers matters because it shapes pricing architectures, contract structures, and qualification pathways—particularly for buyers who must balance performance requirements against total cost of ownership.
Application segmentation underscores the concentration of demand across a handful of core uses. A leading application category anchors a substantial portion of total consumption, supported by a secondary tier of high-volume functional additives and a broader tail of specialty and niche uses. This demand architecture has direct consequences for supply reliability, inventory strategy, and the pace at which new capacity can be absorbed without creating localized oversupply.
Regional segmentation reveals a market whose demand geography is heavily weighted toward one dominant zone, with a layered set of secondary regions contributing differentiated volumes. This distribution pattern has strategic ramifications for logistics optimization, localized inventory positioning, and the negotiation of long-term supply agreements. It also frames the relative exposure of different buyer bases to freight volatility, import dependency, and regional regulatory shifts.
Strategic Segment Intelligence: Understanding the Layers That Drive Value
For executives who require more than aggregated totals, the report delivers a granular but disciplined breakdown of the segments that constitute the total market. Rather than presenting segmented data as isolated percentages, the analysis contextualizes each layer within its commercial logic—explaining why certain grades persist in premium positioning, why specific applications exhibit resilient consumption, and how regional demand concentration influences sourcing risk.
The refined-grade segment, defined by purity thresholds exceeding 99 percent, occupies a central role in applications where impurity control, reproducibility, and downstream processing consistency are non-negotiable. Buyers in this tier typically operate under tighter qualification cycles and prioritize supplier reliability over marginal price differences. The industrial-grade segment, spanning the 98–99 percent range, serves a different commercial logic—one oriented toward volume efficiency, cost containment, and formulation flexibility. Understanding the balance between these two pools is essential for producers calibrating product mix and for buyers evaluating whether grade substitution is technically viable within their own processes.
On the application side, the analysis maps how demand concentrates around polymer stabilization, nucleating functionality, resin modification, and select personal care and specialty uses. Each application cluster carries its own demand elasticity, formulation sensitivity, and substitution risk. The leading application category continues to absorb the largest share of total consumption, but the report equally tracks the contribution of nucleating agents and alkyd resin modifiers as meaningful secondary pillars. A smaller but strategically important tail of personal care and cosmetic applications, alongside other niche uses, rounds out the demand base—offering incremental growth optionality without destabilizing the core volume profile.
Regionally, the report frames the global demand map as a hierarchy rather than a flat aggregate. A leading Asia-Pacific concentration anchors the market's volume center of gravity, while Europe, North America, and a combined rest-of-world grouping contribute differentiated demand layers. This distribution has consequences for everything from freight and inventory strategy to the relative attractiveness of localized production versus import dependency. The analysis intentionally avoids reducing regional dynamics to simple share percentages; instead, it situates them within the operational realities of sourcing, lead-time management, and regulatory exposure that actually drive procurement decisions.
Competitive Landscape and Recent Industry Developments
The PTBBA market is characterized by a mix of scale-oriented producers, specialty-grade specialists, and geographically distributed suppliers whose competitive positioning varies by region, product tier, and application focus. The report profiles a curated set of key companies whose activities collectively shape pricing behavior, supply availability, and the pace of capacity evolution.
Among the profiled participants, several Chinese manufacturers stand out for their scale orientation and vertically integrated operational models. Fareast Kingstar Chemical positions itself as a major PTBBA producer with substantial annual production capacity and a broader product footprint that includes related intermediates. Its integration of research, production, and sales, backed by ISO 9001 and ISO 14001 certification, reflects the operational discipline increasingly demanded by downstream buyers. Shanghai Ruifu Chemical similarly emphasizes high-purity material above 99.0 percent by HPLC, with capabilities spanning small to bulk quantities and custom synthesis support—an offering profile that appeals to buyers requiring specification assurance and flexible order structures.
Beyond China, the competitive field includes Japanese and Korean participants with distinct value propositions. FUSO CHEMICAL supplies PTBBA within its electronic materials portfolio, packaged for controlled handling and specification integrity across 20 kg paper bag and 500 kg big bag formats—a logistics and quality-control emphasis that differentiates it in specification-sensitive procurement contexts. Dsn Chem Co., Ltd. operates as an active export-oriented supplier, reinforcing the global reach of secondary-source options that buyers can leverage for supply diversification.
India's Vinati Organics contributes a distinct application angle, producing PTBBA used in alkyd resin stabilization and sunscreen-related formulations, with a track record of pursuing capacity expansions tied to PTBBA-related production. Additional Chinese producers, including Jiangxi Yongtong Technology, Hebei Aoge Chemical, Dalian Richfortune Chemicals, Haicheng Huacheng Chemical, and China Haohua Chemical Group, populate the broader supply base, each contributing to the market's overall availability and competitive tension across industrial and polymer-additive segments.
Recent developments further shape this competitive picture. A capacity expansion signal observed in April 2026 underscores a structural shift: reliance on imported intermediates for high-purity PTBBA is prompting investments in domestic capacity expansion, particularly across Asia. For procurement and supply-chain leaders, this signals a medium-term recalibration of import dependency, potential shifts in lead times, and the gradual emergence of new supply nodes that could alter regional negotiation dynamics.
Tetrabromobisphenol-A (TBBA) (CAS 79-94-7) Market
On the regulatory and trade front, a European Commission autonomous tariff suspension for 4-tert-butylbenzoic acid has maintained a zero-duty environment through the end of 2027. This policy posture reduces one layer of cost friction for import-dependent European buyers and reinforces the strategic relevance of import logistics and supplier qualification within the EU market context.
Feedstock Economics, Regulatory Context, and Demand Drivers
No analysis of PTBBA market dynamics is complete without addressing the upstream economics and regulatory architecture that condition supply behavior. The primary feedstock for 4-tert-Butylbenzoic Acid is p-tert-butyltoluene, produced via alkylation of toluene and subsequently oxidized to PTBBA. This linkage means that feedstock availability and pricing exert a direct influence on PTBBA production economics. Industry data points to a notable year-on-year price rise in related TBT markets, which has affected 2026 capacity utilization and reinforced the importance of feedstock hedging, supplier relationship management, and formulation flexibility.
Regulatory context adds another strategic dimension. PTBBA is registered under REACH with harmonized classification elements that include reproductive toxicity category considerations and specific hazard statements. For downstream users, this translates into documentation requirements, handling protocols, and supplier due diligence that must be factored into sourcing decisions. The regulatory landscape is also evolving in adjacent geographies: Taiwan's environmental authority included 4-tert-butylbenzoic acid in its prioritized existing chemicals batch for data collection and assessment, signaling a potential trajectory of heightened data requirements and compliance scrutiny in one more regional market.
On the EU side, historical context remains relevant for understanding current supply patterns. The absence of active EU production since around 2006 means that European demand relies on imports, with historical market volume estimates framing the scale of that import-dependent demand base. Combined with the tariff suspension environment, this creates a market structure where import reliability, supplier qualification, and logistics resilience are especially salient for European procurement teams.
These feedstock and regulatory dynamics do not merely add background color; they actively shape margin structures, supply risk profiles, and the relative attractiveness of different sourcing strategies. The report integrates these factors into its forward analysis so that buyers and producers can assess not just where demand is going, but what constraints and opportunities will condition the path to get there.
What the PW Consulting Report Delivers: Practical Tools for 2026 Strategy
Beyond market sizing and segmentation, the report is built around practical analytical deliverables that convert information into decision support. It provides a structured view of the competitive field, enabling users to map supplier capabilities, grade specializations, and regional footprints against their own procurement and expansion requirements. It frames demand by application and grade in a way that supports formulation planning, qualification prioritization, and substitution analysis. It contextualizes feedstock and regulatory factors so that supply-chain teams can incorporate them into risk assessments and sourcing models rather than treating them as peripheral considerations.
The report also addresses the operational implications of recent capacity and trade developments. By linking the observed capacity expansion signal to its underlying driver—imported intermediate reliance—and connecting the European tariff environment to its implication for import cost structures, the analysis helps users anticipate shifts rather than simply react to them. This forward orientation is particularly valuable for teams planning contract negotiations, inventory positioning, and qualification pipelines in a year when supply-side dynamics are actively evolving.
Concentration metrics further enrich the competitive picture. The market displays a meaningful degree of supplier concentration, with a defined share captured by a smaller group of leading participants. For buyers, this has implications for negotiation leverage, qualification redundancy, and the strategic value of qualifying secondary sources. For producers and investors, it highlights the commercial significance of scale, grade differentiation, and application-specific positioning as the market matures.
Why This Research Matters for 2026 Decision-Making
In a market defined by measured growth, concentrated demand, and shifting supply-side incentives, strategic advantage belongs to organizations that can align their sourcing, production, and expansion decisions with a clear-eyed view of where the market is heading. The PW Consulting Worldwide 4-tert-Butylbenzoic Acid Market report is designed to provide that view. It combines historical grounding, forward projection, segment-level intelligence, competitive profiling, and regulatory and feedstock context into a single analytical framework calibrated for executive use.
For procurement leaders, the report supports more resilient sourcing strategies by clarifying the demand layers, grade sensitivities, and supplier capabilities that actually drive supply security. For capacity planners and producers, it provides a demand trajectory and segmentation context that can inform investment timing, product-mix calibration, and regional focus. For market-entry and M&A teams, it offers the structural insight needed to evaluate where value is created, where competition is intensifying, and where white space or consolidation opportunities may emerge.
Full detail, including complete segmentation figures, regional and application-level data, and extended competitor profiles, is available in the complete study. The summary presented here is intended to demonstrate the analytical depth and strategic relevance of the research while preserving the full dataset and supporting detail for the in-depth review. Readers seeking the complete intelligence package are encouraged to access the full report to ensure that procurement, investment, and planning decisions are grounded in the complete market picture.
For detailed analysis of this topic, please visit the official page: Worldwide 4-tert-Butylbenzoic Acid (PTBBA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com