

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
Appliance Power Cord Market: How 6.8% CAGR and PVC-Dominant Supply Chains Are Reshaping Competition
By pmarketresearch, 2026-09-21
The Appliance Power Cord Market: Strategic Trends and Commercial Opportunities in a Growing Ecosystem
The appliance power cord market has evolved far beyond its origins as a basic utility component, transforming into a strategically significant segment where safety, material science, and global compatibility converge. Over the past five years, the industry has navigated supply chain recalibrations, tightening regulatory frameworks, and shifting appliance architectures that collectively redefine how manufacturers, distributors, and end-users value power connectivity. As households and commercial facilities increasingly prioritize reliability, energy efficiency, and interoperability, power cords are no longer viewed as interchangeable commodities. They function as critical interface components that influence product safety certifications, warranty exposure, and brand reputation. Understanding the structural dynamics of this market requires looking beyond unit volumes and examining the underlying forces shaping pricing, innovation, and competitive positioning.
Market Landscape and Core Challenges
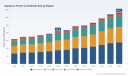
The global appliance power cord market has demonstrated steady expansion, with revenues growing from approximately $160.5 million in 2020 to an estimated $211.5 million in 2025, and is projected to reach roughly $333.4 million by 2032. This trajectory reflects a compound annual growth rate of approximately 6.8 percent, signaling sustained demand supported by replacement cycles, appliance modernization, and expanding manufacturing footprints. The market structure remains moderately fragmented, with the top three participants collectively holding roughly 27.5 percent of total revenue and the top five accounting for approximately 35.2 percent. This concentration level suggests that while scale players command meaningful share, specialized manufacturers retain viable positioning through customization, regional compliance expertise, and rapid fulfillment capabilities.
Beneath the headline growth, several structural challenges are reshaping how participants compete and allocate capital. First, safety certification and standardization complexity has intensified. Compliance with testing protocols such as UL 817 requires rigorous validation of durability, insulation integrity, and continuous load performance, raising the technical barrier for new entrants and increasing time-to-market for product lines. Second, material cost volatility and supply continuity remain persistent pressures. Copper conductor pricing and PVC insulation availability influence margin structures, and while supply trends have remained relatively stable through mid-2026, geopolitical trade flows, freight fluctuations, and regional manufacturing capacity still create pockets of disruption. Third, the market faces a tipping point in application diversity. As appliance categories expand and electrical architectures become more sophisticated, manufacturers must balance standardized inventory with highly customized configurations that meet local plug types, voltage requirements, and specialty use cases such as hospital-grade or heavy-duty environments.
Worldwide Domestic Appliances Market
These challenges are not merely operational friction points; they are strategic filters. Companies that can efficiently navigate certification pathways, maintain resilient material sourcing, and align product portfolios with evolving appliance lifecycles are better positioned to capture margin while defending against commoditization. Conversely, players relying on undifferentiated volume strategies risk exposure to price compression and interchangeability substitution.
Key Drivers Shaping Market Direction
Technological Innovation and Product Differentiation
Advancements in cord construction, terminal design, and insulation materials are steadily redefining performance expectations. Manufacturers are expanding high-voltage configurations, specialized ROJ-style connections, and hospital-grade variants that meet stringent durability and safety thresholds. These innovations respond directly to appliance architectures that demand higher continuous loads, improved heat resistance, and longer operational lifespans. The introduction of new heavy-duty and international configurations, alongside expanded high-voltage options compatible with major household appliances, illustrates how product roadmaps are being shaped by real-world usage requirements rather than baseline compliance alone. For commercial and residential appliance makers, access to differentiated cord sets translates into reduced warranty risk, simplified regional deployment, and stronger value proposition in premium product lines.
Regulatory and Standards Evolution
Regulatory frameworks continue to act as both a constraint and a catalyst. The UL 817 standard establishes rigorous testing expectations for safety and durability, effectively functioning as a market gatekeeper that rewards manufacturers with mature quality systems and transparent supply traceability. At the same time, electrical code updates are altering load management expectations. Recent NEC revisions addressing continuous load calculations for electric appliances, including dishwashers, ease certain engineering assumptions while reinforcing the importance of reliable cord performance under sustained operation. These regulatory shifts push manufacturers to design for durability rather than minimal compliance, and they increase the value of configurations that are pre-validated for specific appliance categories. In practical terms, certification readiness has become a strategic asset, not just a checkbox.
Demand-Side Shifts in Consumer and Commercial Behavior
End-user expectations are increasingly shaped by energy efficiency mandates and total cost of ownership considerations. Efficiency-driven appliance adoption places greater emphasis on components that can sustain performance over longer service lives, creating demand for durable, longer-lasting power cords in consumer households. Simultaneously, commercial facilities and rental housing operators prioritize configurations that minimize maintenance interruptions and simplify inventory management across multiple appliance types. The growing availability of hospital-grade and heavy-duty options reflects this broadening demand spectrum, where reliability specifications are tied directly to operational continuity. For manufacturers, this means product portfolios must accommodate both everyday replacement cycles and specialty applications without fragmenting production efficiency.
Supply Chain and Cost Structure Dynamics
Material stability has provided a favorable backdrop, with copper and PVC insulation remaining the primary inputs and supply trends holding relatively steady through mid-2026. Yet stability in raw materials does not eliminate structural cost pressures. Freight variability, regional labor dynamics, and the cost of maintaining multiple plug combinations and international variants can erode margins if production is poorly optimized. Companies that reduce minimum order friction, consolidate configurable SKUs, and align production with regional demand clusters achieve better cost discipline while preserving flexibility. In an environment where differentiation increasingly hinges on availability, lead time, and compliance assurance, supply chain agility has become a direct competitive advantage.
Competitive Landscape and Leading Strategies
The competitive field features a mix of focused domestic manufacturers and globally positioned suppliers, each leveraging distinct strategic angles. Quail Electronics has built a reputation around North American and international appliance power cords, including two- and three-prong options and high-voltage configurations tailored for refrigerators, washers, dryers, and ranges. Its approach emphasizes broad compatibility with major household appliances, which supports OEM and distributor relationships that value standardized yet robust solutions. Kord King positions itself as a large-scale U.S. manufacturer of custom appliance power cords, offering a wide range of plug combinations alongside hospital-grade and heavy-duty variants for both household and commercial applications. This customization-heavy model enables the company to serve customers with specialized requirements while maintaining a recognizable domestic manufacturing footprint. Interpower Corporation differentiates through country-specific international and North American cord sets, with a notable emphasis on accessibility through no-minimum-order policies. This flexibility lowers entry barriers for smaller appliance assemblers and export-focused operations that need localized compliance without large inventory commitments.
Additional players reinforce the market's diversity. Consolidated Electronic Wire & Cable and Electri-Cord Manufacturing both emphasize custom and standard power cords for household appliances, with offerings that span shielded, hospital-grade, and domestically or internationally compliant configurations. Volex Group brings a more global manufacturing perspective, supplying power cords and plugs across appliance and consumer electronics applications, which allows it to address multi-region demand with broader scale and cross-market synergies.
Strategic differentiation among these leaders clusters around three themes. First, certification and safety positioning functions as a trust signal that reduces buyer risk, particularly in applications where failure carries significant operational or liability consequences. Second, configuration breadth and customization capability determine how well a supplier can serve mixed appliance portfolios without forcing customers into overly narrow SKU sets. Third, fulfillment flexibility, including low minimum order thresholds and rapid international variant availability, enables smaller and mid-sized appliance manufacturers to source reliably without incurring excess inventory risk.
The competitive landscape is evolving through selective consolidation and persistent differentiation. While the market remains accessible to specialized suppliers, the premium increasingly flows to firms that can combine compliance assurance, regional variant depth, and efficient configuration management. New entrants face a meaningful hurdle in certification infrastructure and material continuity, but opportunities exist for players that identify underserved regional plug requirements or niche application segments such as specialty commercial appliances and higher-duty cycle environments. The result is a market that rewards operational precision and customer-specific value creation rather than pure volume competition.
Power Cords & Extension Cords Market
Forward Outlook: Three Trends Shaping the Next Three to Five Years
First, compliance-integrated product design will become a standard expectation rather than a differentiator. As safety and durability testing requirements remain entrenched and electrical code adjustments continue to influence load assumptions, cord suppliers that embed validation into their development cycles will reduce customer onboarding friction and shorten qualification timelines. The commercial opportunity lies in offering pre-certified configurations mapped to common appliance categories, which can lower procurement complexity and support faster time-to-market for appliance manufacturers. The primary risk is regulatory drift; if testing expectations tighten further or regional standards diverge, suppliers with less agile quality systems may face repeated redesign cycles.
Second, regional interoperability will drive demand for highly configurable yet efficiently managed cord portfolios. Global appliance trade and multi-market product launches require power solutions that accommodate local plug types, voltage standards, and specialty ratings without fragmenting into unmanageable SKU proliferation. Suppliers that invest in modular design, strategic inventory clustering, and clear international variant management will be better equipped to serve export-oriented and multi-region appliance programs. The upside is expanded addressable demand across cross-border appliance supply chains. The uncertainty lies in trade policy shifts and regional manufacturing localization pressures, which could alter sourcing patterns and favor domestic production in certain markets.
Third, durability and lifecycle value will command growing commercial attention. Energy efficiency mandates and total cost of ownership considerations are shifting buyer focus toward components that sustain performance through longer appliance lifespans. This dynamic favors reinforced insulation, higher-duty construction, and configurations validated for continuous use, particularly in households and commercial settings where replacement disruption is costly. The opportunity is to position durable cord sets as risk-reduction assets that support appliance reliability claims and reduce field failure exposure. The risk is that durability premiums must be justified through demonstrable performance and clear warranty or maintenance benefits; otherwise, price-sensitive buyers may continue favoring lower-cost alternatives in non-critical applications.
Strategic Considerations for Decision-Makers
For appliance manufacturers and original equipment suppliers, the priority is to treat power cord selection as a design-and-compliance decision with downstream operational implications. Selecting configurations that align with target market plug types, voltage ranges, and durability expectations can streamline certification, reduce field failure risk, and simplify warranty management. It is equally important to evaluate suppliers not only on unit price but on configuration breadth, certification readiness, and fulfillment flexibility, since these factors influence program launch speed and inventory efficiency. Where product roadmaps include international variants or specialty applications, partnering with suppliers that already maintain validated regional options can shorten development cycles and reduce qualification burden.
For investors evaluating exposure to this segment, the value proposition lies less in headline growth alone and more in the structural resilience of compliant, differentiated product lines. Companies with mature safety validation processes, manageable material exposure, and the ability to serve both standard and specialty applications are better positioned to defend margins across demand cycles. Investment theses should account for the impact of regulatory continuity, regional trade dynamics, and the extent to which a supplier can translate configuration complexity into commercial advantage rather than operational cost. Diversification across standard household applications and higher-specification commercial or hospital-grade segments can provide a more balanced exposure profile.
For procurement and supply chain leaders, the practical focus should be on minimizing qualification risk and inventory friction while preserving access to required configurations. Where demand spans multiple appliance types or regions, consolidating around suppliers with pre-validated variants and flexible order thresholds can reduce administrative overhead and improve responsiveness to design changes or late-stage program adjustments. Maintaining clear visibility into material continuity, certification status, and lead-time behavior for critical cord variants supports more resilient sourcing decisions, particularly when appliance launch schedules or regulatory updates introduce timing pressure.
PW Consulting
For organizations seeking deeper segmentation data, competitive benchmarking, and tailored recommendations aligned with specific product portfolios or regional strategies, the full research report provides expanded detail across market size trajectories, segmentation dynamics, and actionable planning frameworks. The complete version includes granular breakdowns and customized guidance designed to support precise sourcing, product roadmap, and investment decisions.
For detailed analysis of this topic, please visit the official page: Appliance Power Cord Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Medical Rubber Stoppers Market: Why Butyl Dominance and 5.5% CAGR Reshape Strategy
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Medical Rubber Stoppers Market
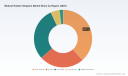
The medical rubber stoppers market stands at the intersection of pharmaceutical innovation and packaging reliability, serving as a critical component in the safe delivery of injectable drugs, biologics, and vaccines. Over the past five years, the market has progressed from a stable $900 million baseline in 2020 to an estimated $1.15 billion in 2025, reflecting consistent demand growth, expanded biopharmaceutical pipelines, and tightening quality expectations across global supply chains. Looking ahead through 2032, the market is projected to reach approximately $1.66 billion, extrapolating to a compound annual growth rate of 5.5 percent. This trajectory signals more than incremental expansion; it points to structural shifts in how elastomeric closures are specified, validated, manufactured, and integrated into drug packaging systems. For executives and investors navigating healthcare packaging, understanding what is driving this growth, where competitive advantages are being built, and how the regulatory and supply chain environment is evolving is essential for positioning portfolios and capital allocation effectively.
Market Snapshot and Structural Challenges
The medical rubber stoppers market today operates within a highly specialized segment of pharmaceutical packaging where performance, sterility, and compatibility are non-negotiable. Revenue growth over the historical period has been supported by rising volumes in injectable therapies, increased adoption of ready-to-use closure formats, and steady expansion in regions with growing centralized pharmacy operations and biotech manufacturing. The forecast period through 2032 suggests continued expansion, with growth rates that reflect both volume increases and higher value capture around premium, low-extractable, and pre-sterilized solutions. In a market of this kind, size alone does not explain competitive outcomes. The real story is in the concentration of capability, the pace of regulatory change, and the way demand-side requirements are reshaping product architectures.
Several structural challenges define the current inflection point for the industry. First, the cost environment for petroleum-derived feedstocks has introduced volatility into the production economics of butyl and bromobutyl rubber stoppers. During 2024, roughly 43 percent of manufacturers reported increased raw material costs driven by feedstock price swings, pressuring margins and complicating long-term pricing agreements. Second, regulatory expectations around extractables, leachables, compatibility, and sterilization are tightening at a pace that raises both technical and financial barriers. Updated guidance from the U.S. Food and Drug Administration in July 2024 on container closure systems underscored the need for manufacturers to document compatibility and perform container closure integrity testing, particularly for glass vials and stoppers. At the same time, the transition of USP Chapter 381 for elastomeric closures to new chapters 1381 and 1382, with a final implementation date of December 1, 2025, imposes updated testing requirements for functionality, extractables, and leachables. These shifts are not marginal; they change how products are validated, how documentation is maintained, and how quickly new formats can be qualified for clinical and commercial use.
Third, the market is experiencing an uncompromising demand for biological safety and sterility assurance. Biological evaluation of medical rubber stoppers must comply with ISO 10993 standards, and more than 58 percent of pharmaceutical packaging manufacturers cited increased validation and sterilization compliance expenses in 2024. Compliance costs are now a meaningful part of product economics and a differentiator in supplier selection. Taken together, these challenges reshape the playing field: suppliers that can deliver lower-extractable profiles, validated ready-to-use formats, and predictable cost structures gain disproportionate traction, while those relying on legacy designs and ad hoc compliance approaches face growing risk of displacement.
Key Drivers Propelling Market Change
The market’s trajectory is not simply a function of volume growth. It is being reshaped by overlapping forces that alter product requirements, customer expectations, and the economics of production. Three to four core drivers explain why the sector is evolving now and why the next several years will reward companies that align technology, regulatory readiness, and supply chain resilience.
Technology Innovation and Low-Extractable, Ready-to-Use Formats
Technological progress in elastomeric closure design is one of the most visible drivers. The shift toward low-extractable, ready-to-use stoppers addresses a long-standing requirement in injectable and biologic drug packaging: minimizing interaction between the closure and the drug product over extended shelf life. Recent product introductions illustrate this direction. Datwyler introduced Omniflex ready-to-use low-extractable stoppers targeted at long-shelf-life mRNA and monoclonal antibody applications. West Pharmaceutical Services expanded its NovaPure line with enhanced barrier properties for mRNA and biologic therapies. These developments are not incremental marketing moves; they respond to real formulation and stability needs in advanced therapies where closure integrity, extractables control, and sterilization readiness directly affect product viability. The commercial message is clear: premium, performance-led stopper designs are becoming the default choice for high-value biologics and mRNA platforms, and suppliers that can validate such formats at scale are moving up the value chain.
Policy, Regulatory Evolution, and Validation Intensity
Regulatory dynamics are accelerating the market’s shift toward standardized, well-documented, and rigorously tested closure solutions. The FDA’s July 2024 guidance on container closure system and component changes emphasizes compatibility documentation and container closure integrity testing for glass vials and stoppers. Simultaneously, the reorganization of USP elastomeric closure chapters, with final implementation by December 1, 2025, re-sets testing expectations for functionality, extractables, and leachables. For manufacturers and buyers alike, this environment increases the importance of pre-validated formats, traceable material specifications, and robust testing data. The burden is not only technical; it is operational. Suppliers must manage validation timelines, maintain documentation across product changes, and ensure that closures meet changing expectations without disrupting client onboarding. In practice, this favors suppliers with mature quality systems, broad test capabilities, and established relationships with pharmaceutical and biotech customers who value continuity and reduced qualification risk.
Butyl Rubber Market
Demand-Side Shifts in Biologics, Hospital Pharmacy, and Chronic Care
Demand is being shaped by the changing mix of drug therapies and the settings in which they are administered. The continued expansion of biologics, monoclonal antibodies, and mRNA-based products increases the need for closures that maintain stability and integrity over longer storage periods and in diverse climate conditions. At the same time, hospital pharmacy settings remain a significant demand center for sterile rubber stoppers used in injectable drugs and vaccines. Sterile stoppers used in these settings benefit from included reimbursement under existing DRG codes for parenteral therapies, with hospitals accounting for a substantial share of end-user demand. This reimbursement linkage matters because it stabilizes demand for sterile, high-compliance closures and creates a persistent pull for validated, hospital-ready products. The broader implication is that demand growth is not uniform across all closure types; it is concentrated where therapy complexity, sterility requirements, and reimbursement dynamics converge.
Supply Chain Cost Structures and Raw Material Dynamics
Beyond product and regulatory drivers, the supply chain environment is influencing competitiveness. Feedstock volatility for butyl and bromobutyl rubber has become a defining cost theme, affecting pricing stability and forcing manufacturers to manage input risk more actively. The impact is twofold. First, cost variability can compress margins unless suppliers have hedging strategies, flexible sourcing, or product mixes that balance higher-margin premium lines with volume-oriented formats. Second, cost pressures can accelerate regional sourcing decisions as buyers seek predictability, shorter lead times, and closer technical collaboration. Suppliers with scale, diversified feedstock strategies, and transparent cost management are better positioned to maintain commercial stability. In this respect, the market is rewarding operational discipline as much as product technology.
Competitive Landscape and Leading Strategies
The competitive field combines global elastomeric specialists, established pharmaceutical packaging groups, and high-capacity regional manufacturers. This mix creates a market where differentiation comes from product architecture, validation readiness, scale, and customer intimacy rather than commodity pricing alone. The market is also concentrated: the top three firms account for approximately 65 percent of revenue, and the top five reach around 72 percent. Such concentration indicates that scale, technology leadership, and long-term customer relationships are decisive in capturing premium segments.
Divergent Strategic Positions Among Leading Players
Leading companies are pursuing distinct strategic positions that reflect their capabilities and target segments. West Pharmaceutical Services focuses on premium elastomeric closures, including NovaPure and LyoTec ready-to-sterilize stoppers for injectable and lyophilized drug vials, and has expanded its NovaPure line with enhanced barrier properties for mRNA and biologic therapies. This positions West around reliability, advanced barrier performance, and compatibility with high-value drug programs. Datwyler Holding AG emphasizes high-quality butyl rubber stoppers and ready-to-use formats such as Omniflex for pharmaceutical and biotech packaging, recently introducing low-extractable stoppers for long-shelf-life mRNA and monoclonal antibody applications. Datwyler’s posture reflects a strategy centered on readiness, extractables control, and bioprocessing alignment.
In the capacity and scale segment, Hebei First Rubber Medical Technology manufactures medical-grade butyl and bromobutyl rubber stoppers with annual capacity of 10 billion units and supplies more than 40 countries with FDA and ISO certifications. Its participation in INTERPHEX USA in 2025 to promote bromobutyl rubber stoppers and related pharmaceutical packaging illustrates a strategy of combining scale, certification breadth, and active engagement with global buyers. Jiangsu Best New Medical Materials produces medical-grade grey rubber stoppers and plugs for pharmaceutical vials and infusion applications, adding further capacity and product variety in the regional supply base. On the diversified packaging side, AptarGroup offers elastomeric closures and related stoppers for drug delivery and pharmaceutical packaging, while Saint-Gobain Performance Plastics supplies medical and pharmaceutical elastomeric components including stoppers for healthcare applications. These firms extend the competitive field by leveraging broader packaging platforms and cross-segment capabilities. Japanese participants such as Sumitomo Rubber Industries and Nipro Corporation add a regional dimension: Sumitomo invested in a new R&D production line for advanced pharmaceutical rubber stoppers, signaling a commitment to technology and capacity for Asian and global biotech packaging needs, while Nipro offers rubber stoppers and related closures for injectable drug packaging and medical devices.
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive landscape is evolving along three axes. Consolidation remains a plausible path as larger players seek to strengthen scale, broaden product portfolios, and reduce customer switching risk through integrated offerings. Differentiation is intensifying around low-extractable, ready-to-use formats, faster qualification cycles, and compliance documentation, where the winners are those that can reduce time-to-market for drug manufacturers. New entrants and regional capacity expansions continue to challenge incumbents on cost and supply flexibility, particularly where certifications, volume capacity, and international distribution networks are in place. The likely outcome is a layered market: premium, technology-led suppliers capture high-margin biologic and mRNA programs; scale-oriented manufacturers win on volume, cost, and multi-country supply; and diversified packaging groups leverage platform breadth to serve multi-component packaging needs. Companies that can operate across more than one layer, or that can anchor a strong position in a specific high-value layer, will be best positioned to sustain growth.
Forward-Looking Scenarios and Commercial Opportunities
The next three to five years will likely be defined by three interrelated trends that translate directly into commercial opportunities for suppliers, buyers, and investors who can act on them early.
Acrylic Rubber Market
The first trend is the acceleration of low-extractable, ready-to-use closures as a standard expectation rather than a premium option. As mRNA platforms, monoclonal antibodies, and other biologics continue to expand, drug manufacturers will increasingly require closures that minimize interaction, support longer shelf life, and integrate seamlessly into sterile workflows. The opportunity lies in building validated formats that reduce qualification friction, shorten onboarding timelines, and provide documented compatibility and integrity data. Suppliers that can demonstrate repeatable performance across multiple therapy classes will be better positioned to secure long-term supply agreements.
The second trend is the deepening influence of regulatory and standards-driven compliance on sourcing decisions. With FDA guidance reinforcing container closure integrity documentation and USP chapters re-establishing testing expectations for elastomeric closures, buyers will place greater weight on suppliers’ validation records, test capabilities, and change control maturity. This creates a commercial opening for suppliers that can package compliance as a value proposition: faster qualification, comprehensive documentation, and lower risk of disruption during component changes. At the same time, the trend introduces risk for suppliers that rely on loosely documented processes or that underestimate the cost and time required to maintain alignment with evolving requirements.
The third trend is a more deliberate approach to cost and supply resilience, shaped by feedstock volatility and the need for predictable economics. Manufacturers and buyers will likely favor sourcing strategies that reduce exposure to raw material swings, balance multi-region supply where appropriate, and align product mix with margin realities. For suppliers, the opportunity is to combine cost discipline with technology value, offering transparent pricing mechanisms, flexible capacity, and a portfolio that spans both volume-oriented and premium formats. For investors, the signal is that competitive advantage will accrue to operators that can manage input volatility without sacrificing compliance or quality, especially in an environment where downstream demand remains robust.
These trends carry uncertainty. Regulatory timelines and interpretation can shift, particularly as chapters are implemented and guidance is applied in practice. Feedstock prices may move in ways that challenge margin assumptions. Demand for specific therapy platforms can change with clinical outcomes and reimbursement evolution. The commercial response should therefore be to build flexibility into product planning, maintain strong compliance capabilities, and avoid over-indexing on any single therapy or region. Opportunities will favor those who can adapt quickly while keeping quality and documentation intact.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product development with the direction of therapy and compliance evolution. Invest in low-extractable, ready-to-use formats that can be validated for biologics and mRNA applications, and ensure that documentation, testing, and change control systems are robust enough to meet FDA and USP expectations without protracted qualification cycles. Build feedstock risk management into commercial planning through diversification, hedging where feasible, and product mix strategies that protect margins. Where scale matters, use capacity and certification breadth to serve multi-country demand, but do so without compromising the performance profile that premium segments require. Balance volume and value by clearly segmenting the portfolio and assigning the right resources to each layer.
For investors, the market offers exposure to a sector with steady growth, clear differentiation potential, and rising barriers to entry around compliance and validation. The most promising targets are companies with demonstrated capability in low-extractable and ready-to-use formats, strong quality and documentation systems, and a credible strategy for managing raw material volatility. Evaluate customer concentration, certification breadth, and the ability to support faster qualification as part of any investment thesis. Watch for consolidation signals, regional capacity expansion with international certifications, and R&D investments that expand the performance envelope of closures. In this market, the durability of competitive advantage is closely tied to compliance readiness and the ability to reduce risk for drug manufacturers.
PW Consulting
For procurement and sourcing teams, the emphasis should be on qualification efficiency, supply resilience, and total cost of ownership rather than unit price alone. Prioritize suppliers that can provide validated, low-extractable, ready-to-use options with clear compatibility and integrity documentation, especially for injectable and biologic programs. Assess the supplier’s ability to manage feedstock-driven cost changes transparently and to sustain supply continuity across regions and demand cycles. Where hospital pharmacy demand and reimbursement linkages matter, ensure that the selected closures meet the sterility and compliance expectations that support parenteral therapy delivery. A balanced sourcing strategy that includes both premium-performance suppliers and capable scale providers can reduce risk while preserving flexibility.
The strategic picture is clear: the medical rubber stoppers market is moving toward higher performance expectations, more rigorous compliance, and greater emphasis on supply predictability. Navigating this environment requires detailed, segment-level data on product types, applications, regional demand patterns, pricing dynamics, and supplier capabilities. For decision makers seeking to translate these trends into sourcing choices, portfolio plans, or investment theses, a comprehensive report with granular segmentation and customized scenarios can sharpen the direction and reduce uncertainty. Access to that level of detail is the difference between reacting to change and shaping it.
For detailed analysis of this topic, please visit the official page: Medical Rubber Stoppers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Silicone-Based Fouling Release Coatings Market: Why 6.8% CAGR Reshapes Strategy
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Silicone-based Fouling Release Coatings Market
Market Landscape and Core Challenges
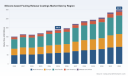
The global market for silicone-based fouling release coatings has entered a phase of steady expansion, driven by the maritime industry's evolving needs and regulatory pressures. From 2020 to 2025, the market demonstrated resilience despite fluctuations, growing from approximately 151.2 million USD to 190.5 million USD. This trajectory reflects a compound annual growth rate (CAGR) of 6.8% projected from 2026 through 2032, indicating sustained demand momentum. By 2032, the market is expected to surpass 297.5 million USD, signaling a maturing but still growing sector.
This growth is not uniform across all segments. The market exhibits moderate concentration, with the top three players holding 35.7% of the share and the top five capturing 48.2%. This structure suggests a competitive environment where established giants coexist with specialized players, creating room for strategic differentiation rather than pure price competition.
Despite the positive outlook, the industry faces critical challenges that could shape its future direction:
- Raw Material Volatility: The reliance on silicone raw materials makes the market susceptible to price swings driven by energy costs, logistics disruptions, and geopolitical tensions. Recent price revisions by major suppliers highlight the vulnerability of cost structures in this segment.
- Regulatory Compliance Complexity: Stricter environmental regulations, such as EU REACH and IMO conventions, mandate biocide-free formulations and organotin-free catalysts. While these regulations push innovation, they also increase formulation costs and require significant R&D investment to maintain performance standards without biocides.
- Performance vs. Cost Trade-offs: End-users, particularly ship operators, balance the long-term fuel savings from reduced fouling against the higher upfront costs of silicone-based coatings compared to traditional antifouling solutions. Demonstrating total cost of ownership benefits remains a key hurdle in broader adoption across all vessel types.
Key Drivers of Market Dynamics
Technological Innovation and Formulation Breakthroughs
Innovation in silicone chemistry is central to the market's evolution. Leading companies are developing advanced silicone elastomer systems that offer superior fouling release properties while adhering to biocide-free requirements. For instance, AkzoNobel's Intersleek series, including the 1100SR variant, exemplifies the focus on high-performance silicone systems that minimize drag and fuel consumption. Similarly, Hempel's Silic One and hydrogel-enhanced Hempasil systems represent efforts to combine silicone efficacy with enhanced surface properties for biocide-free hull protection.
These technological strides are not merely about replacing biocides; they are about improving durability and self-renewing capabilities. Jotun's SeaQuantum silicone elastomer coatings, designed for self-renewing hull performance, illustrate how formulators are tackling the challenge of coating longevity and consistent performance over multiple service intervals. Such innovations reduce the frequency of repainting, addressing a key concern for shipowners regarding maintenance downtime and lifecycle costs.
Regulatory Pressure as a Catalyst
Regulatory frameworks are acting as a powerful accelerator for silicone-based fouling release coatings. The International Convention on the Control of Harmful Antifouling Systems on Ships (IMO) mandates the use of biocide-free silicone fouling release coatings in sensitive ecological zones. With over 3,500 vessels restricted in 2024 under these provisions, the addressable market for compliant coatings is expanding. Furthermore, EU REACH regulations require organotin-free catalysts, pushing manufacturers to refine curing systems without compromising performance.
These regulations create a clear pull for silicone-based solutions, as traditional biocidal antifouling coatings face increasing restrictions. The shift is particularly pronounced in regions with stringent environmental enforcement, where compliance becomes a non-negotiable requirement for vessel operations. This regulatory tailwind is transforming silicone coatings from a niche premium option to a mainstream necessity in specific maritime segments.
Demand-Side Shifts Toward Sustainability and Efficiency
Ship operators and maritime companies are increasingly prioritizing fuel efficiency and carbon footprint reduction. Fouling release coatings directly contribute to these goals by reducing hydrodynamic drag, which lowers fuel consumption and emissions. As energy costs fluctuate and environmental, social, and governance (ESG) criteria gain weight in corporate decision-making, the economic and reputational benefits of silicone-based coatings become more compelling.
The demand is also being shaped by the expansion of sensitive ecological zones and port state control measures. Vessels operating in these areas must utilize compliant coatings, driving adoption among fleets that previously might have relied on conventional solutions. This demand-side pressure is reinforcing the market growth trajectory and encouraging investment in next-generation silicone formulations.
Supply Chain and Cost Structure Pressures
The cost structure of silicone-based fouling release coatings is undergoing significant stress due to upstream factors. Major silicone raw material producers have announced price increases, reflecting the impact of energy costs, logistics expenses, and raw material availability. Wacker Chemie AG, for example, implemented a price increase for all silicone-based products effective April 2026, citing disruptions in global supply chains related to energy, raw materials, and logistics. Similarly, Shin-Etsu Chemical Co., Ltd. revised selling prices for all silicone products by 10% or more starting May 2026, driven by sharply rising derived raw materials, energy, and logistics expenses.
These price revisions ripple through the value chain, affecting coating manufacturers' input costs and potentially impacting end-user pricing. The industry is navigating a period where cost escalation must be managed without eroding the value proposition of silicone coatings. This dynamic is prompting companies to optimize formulations, secure long-term supply agreements, and explore alternative sourcing strategies to mitigate volatility.
Competitive Landscape and Leading Strategies
The market is characterized by a mix of global coatings giants and specialized marine paint manufacturers, each pursuing distinct strategic positioning. AkzoNobel N.V., headquartered in Amsterdam, leverages its extensive marine coatings portfolio to offer Intersleek silicone elastomer foul release systems. Its strategy centers on integrating silicone technology into broader hull protection solutions, emphasizing performance data and fleet-wide efficiency gains. By tying silicone coatings to tie coats and complete systems, AkzoNobel aims to lock in customers through comprehensive service offerings.
PW Consulting
Hempel A/S, based in Copenhagen, differentiates through innovation in biocide-free systems. Its Silic One silicone-based foul release coating and Hempasil hydrogel-enhanced silicone systems target customers seeking advanced protection without biocides. Hempel's focus on hydrogel technology adds a layer of differentiation, potentially offering enhanced fouling release properties and durability, appealing to operators in ecologically sensitive regions.
PPG Industries, Inc., from Pittsburgh, provides SigmaWild and other silicone fouling release coatings as part of its biocide-free marine solutions. PPG's strength lies in its global reach and ability to scale innovation across diverse maritime markets. The company's strategy involves positioning silicone coatings within a wider suite of marine protection products, leveraging brand recognition and technical service networks to capture market share.
Jotun A/S, located in Asker, Norway, emphasizes self-renewing hull performance with its SeaQuantum silicone elastomer foul release coatings. Jotun's approach highlights the operational benefits of reduced maintenance frequency and consistent performance, resonating with shipowners focused on minimizing dry-docking intervals and maximizing vessel uptime.
Chugoku Marine Paints, Ltd., based in Osaka, markets the CMP BIOCLEAN series of advanced silicone foul release coatings for ocean-going vessels. As a regional player with strong ties to Asian maritime markets, Chugoku focuses on tailoring solutions to the specific operational profiles of vessels in the Pacific region, potentially offering competitive pricing and localized service support.
Sherwin-Williams Company, headquartered in Cleveland, supplies silicone-based foul release coatings under its marine and specialty coatings portfolio. Its strategy involves leveraging its vast distribution network and cross-selling opportunities across industrial and marine segments. Sherwin-Williams aims to integrate silicone coatings into broader coating solutions, appealing to customers seeking a single-source provider for multiple coating needs.
Pettit Marine Paint, located in Rockaway, New Jersey, provides silicone foul release coatings and systems for recreational and commercial marine applications. Pettit's niche focus allows it to cater to smaller vessel operators and recreational boaters, segments where ease of application and specialized customer service can be decisive factors.
The competitive landscape is evolving through consolidation and differentiation. While the top five players hold nearly half the market, the presence of specialized firms indicates opportunities for fragmentation in niche applications or regional markets. New entrants may find traction by focusing on specific vessel types, emerging regions, or novel formulation technologies that address unmet needs. However, the high barriers to entry posed by regulatory compliance, performance validation, and established supply chains favor incumbents with robust R&D and customer relationships.
Future Trends and Strategic Outlook
Accelerating Adoption Driven by Regulatory Expansion
Over the next three to five years, regulatory pressures are expected to intensify, further expanding the addressable market for biocide-free silicone fouling release coatings. As more regions implement stringent environmental protections and IMO regulations evolve, the number of vessels required to use compliant coatings will grow. This trend creates a clear opportunity for manufacturers to scale production and secure market share in advance of demand surges. However, companies must also anticipate potential regulatory fragmentation, where differing regional standards could complicate formulation strategies and market access.
Supply Chain Resilience and Cost Management as Competitive Differentiators
The recent wave of price increases from silicone raw material suppliers underscores the importance of supply chain resilience. Future market leaders will likely be those who can secure stable raw material supplies, optimize formulations to reduce silicone content without sacrificing performance, or develop partnerships that mitigate cost volatility. This trend may lead to strategic alliances between coating manufacturers and silicone producers, or inspire investment in alternative raw material sources. Businesses that fail to address cost structures risk margin erosion or loss of competitiveness in price-sensitive segments.
Silicone Resin Market
Performance Enhancements and Lifecycle Value Propositions
Innovation will continue to focus on enhancing the performance and lifecycle value of silicone coatings. Expect developments in multi-layer systems, improved adhesion promoters, and coatings that offer longer service life or easier application processes. The commercial opportunity lies in demonstrating total cost of ownership benefits that justify higher initial costs. Manufacturers that can provide robust data on fuel savings, reduced maintenance, and extended coating life will be better positioned to capture value. Conversely, a risk exists if performance claims are not consistently validated across diverse operating conditions, potentially leading to customer skepticism or reversion to traditional solutions where regulations permit.
Marine Anti-Fouling Coatings Market
Actionable Insights for Decision Makers
For Coating Manufacturers and Formulators
- Invest in Bio-based or Cost-Optimized Formulations: With raw material costs rising, exploring formulations that maintain performance while reducing dependency on high-cost silicone components can protect margins. R&D efforts should prioritize organotin-free curing systems and biocide-free architectures that comply with evolving regulations without compromising efficacy.
- Strengthen Supply Chain Partnerships: Engaging in long-term agreements with silicone suppliers or diversifying the supplier base can mitigate price volatility. Collaborative innovation with raw material producers may yield tailored solutions that address specific coating needs while stabilizing input costs.
- Expand Value-Added Services: Offering technical support, performance monitoring, and lifecycle cost analysis can differentiate offerings in a competitive market. Helping customers quantify fuel savings and maintenance reductions strengthens the value proposition and fosters loyalty.
For Investors and Financial Stakeholders
- Focus on Regulatory Tailwinds and Market Concentration: The market's moderate concentration and regulatory-driven growth present opportunities in companies with strong compliance capabilities and global reach. Evaluate players based on their R&D pipelines, regulatory responsiveness, and ability to scale silicone-based solutions across key maritime regions.
- Monitor Raw Material Dynamics Closely: Price revisions by major silicone producers can impact profitability across the value chain. Analyze how potential investments or portfolio companies manage input cost risks, as resilience in supply chain management will be a key determinant of long-term financial performance.
- Assess Niche and Regional Opportunities: While global giants dominate, specialized players serving recreational marine, specific vessel types, or emerging regions may offer high-growth potential. Look for companies with strong local relationships, tailored product lines, and the agility to adapt to regional regulatory changes.
For Shipowners and Procurement Teams
- Prioritize Total Cost of Ownership Assessments: When evaluating silicone-based fouling release coatings, look beyond initial price and consider fuel savings, reduced dry-docking frequency, and compliance benefits. Engage with manufacturers to obtain performance data relevant to your vessel types and operating profiles to make informed comparisons.
- Ensure Regulatory Compliance Proactively: Verify that selected coatings meet current and anticipated regulations in all operational zones, including sensitive ecological areas. Non-compliance can result in operational restrictions or penalties, making proactive selection of biocide-free and organotin-free solutions a strategic necessity.
- Leverage Supplier Expertise for Application Optimization: Proper application is critical to achieving the claimed performance of silicone coatings. Work closely with suppliers to ensure correct surface preparation, application conditions, and tie-coat usage. Investing in training or partnering with experienced applicators can maximize the return on coating investments.
The silicone-based fouling release coatings market is at a inflection point, shaped by regulatory mandates, technological advancements, and supply chain dynamics. Navigating this landscape requires a nuanced understanding of competitive strategies, cost structures, and emerging opportunities. Stakeholders seeking deeper granularity on segment-level data, regional breakdowns, and customized strategic scenarios are encouraged to explore comprehensive research resources that provide detailed market intelligence tailored to specific business needs.
For detailed analysis of this topic, please visit the official page: Silicone-based Fouling Release Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Acute Care Needleless Connector Market 1634M in 2026 Why Positive Displacement Shift Matters
By pmarketresearch, 2026-09-21
Acute Care Needleless Connector Market: Strategic Trends and Commercial Opportunities Through 2032
The acute care needleless connector market represents a critical intersection of patient safety, clinical efficiency, and supply chain economics. As vascular access practices continue to evolve alongside growing emphasis on healthcare-associated infection prevention, the connector segment has transitioned from a commoditized consumable to a strategically differentiated product category. Understanding where the market stands today, what forces are reshaping it, and how competitive players are positioning themselves provides essential context for executives navigating procurement, product development, or capital allocation decisions.
Acupuncture Needles Market
Market Landscape and Core Challenges
The global acute care needleless connector market has demonstrated steady expansion over the past half-decade, reaching an estimated 1.55 billion USD in 2025, with trajectory modeling pointing toward approximately 2.29 billion USD by 2032. The compound annual growth rate across the 2026 to 2032 horizon sits at 5.83 percent, reflecting a market that is growing at a pace consistent with broader medical device consumables while benefiting from compounding clinical and operational tailwinds. Growth is not merely volume-driven; it reflects a structural shift in how acute care facilities approach vascular access, infection prevention, and supply standardization.
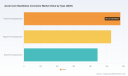
Geographically, the market remains heavily anchored in North America, followed by Europe and Asia Pacific, with Latin America and the Middle East and Africa representing smaller but steadily developing demand pools. Application-wise, hospital settings dominate consumption, reflecting the concentration of high-acuity patients, multilumen catheter use, and institutional pressure to standardize vascular access protocols. Clinics and ambulatory settings form a secondary demand base, while other care environments contribute incremental volume. Revenue distribution across product types shows a market increasingly aligned around fluid displacement performance, with positive and negative displacement configurations commanding the largest shares and neutral displacement gaining traction as clinical evidence around reflux control and microbial ingress prevention accumulates.
Key Challenges and Inflection Points
Despite the favorable growth backdrop, several structural challenges and decision points define the current market environment.
- Standardization versus clinical differentiation tension. Acute care procurement teams increasingly seek product standardization across departments to simplify training, reduce inventory complexity, and consolidate volume for contracting leverage. At the same time, clinical evidence is driving interest in differentiated connector performance around reflux characteristics, microbial ingress prevention, and occlusion management. Manufacturers must navigate the balance between offering clinically meaningful variation and meeting hospital demands for simplified formularies.
- Infection prevention accountability and total cost of care. Clinician awareness of catheter-related bloodstream infection risks has matured, but translating that awareness into purchasing behavior depends on how clearly connector performance associates with downstream outcomes and operating costs. Decision-makers are under pressure to justify product selection not just on unit price, but on risk reduction, flush frequency, thrombolytic use, and labor implications. This shifts the commercial battleground from specifications alone to demonstrated clinical and economic value.
- Pricing pressure amid supply chain normalization. After the volatility experienced in earlier years, supply chains have largely stabilized, and hospitals have regained bargaining leverage in group purchasing arrangements. This has intensified price scrutiny, particularly for commoditized connector SKUs. Suppliers that cannot articulate differentiated clinical value face margin compression, while those with evidence-backed positioning can defend premium pricing or secure longer contract cycles.
These challenges converge on a central question for the market: whether needleless connectors will continue to consolidate around a few clinically differentiated platforms, or whether buyers will privilege cost and standardization to the detriment of performance variation. The answer will shape competitive dynamics across the next several years.
Key Drivers Shaping Market Evolution
Clinical Evidence and Differentiation Around CLABSI Risk Management
One of the most consequential drivers in the market is the growing weight of clinical evidence connecting connector design to catheter-related bloodstream infection outcomes and treatment efficiency. Needleless connector performance is no longer evaluated only on ease of use or compatibility. Procurement and infection prevention teams are increasingly attentive to reflux behavior, microbial ingress prevention, occlusion risk, and downstream implications such as flush and thrombolytic consumption.
Recent regulatory labeling updates and peer-reviewed data have begun to crystallize these claims in ways that matter for purchasing decisions. For instance, clearances associated with neutral-displacement connector platforms have incorporated CMS study data indicating a measurable relative risk reduction in CLABSI within high-volume acute care hospitals, alongside claims related to pressure infusion performance and extended microbial ingress prevention windows. In parallel, independent systematic in vitro assessments of neutral displacement connectors have documented bidirectional fluid flow control with low reflux volumes, reinforcing the technical rationale behind neutral displacement as a clinically relevant parameter. These developments are not abstract; they directly inform formulary discussions where infection prevention metrics and nursing workflow matter.
Regulatory and Labeling Evolution as a Commercial Lever
The regulatory environment has evolved from a compliance floor into a commercial differentiator. FDA 510(k) labeling clearances are increasingly used to substantiate performance claims that support hospital adoption and value-based purchasing conversations. When labeling incorporates outcomes-linked evidence or functional claims such as pressure infusion capability and extended microbial ingress prevention, it offers clinicians and procurement teams a clearer basis for standardizing specific connector types across services.
This regulatory dynamic favors companies with established clinical data packages and regulatory execution capabilities. It also raises the bar for new entrants, since meaningful labeling claims require robust data generation and clear regulatory alignment. For incumbents, proactive labeling strategy can extend product lifecycle relevance and strengthen negotiating position in group purchasing discussions.
Demand-Side Shifts in Hospital Purchasing and Care Delivery
On the demand side, acute care facilities are optimizing vascular access programs to reduce variability, improve nurse efficiency, and manage total cost of care. HAIs remain a persistent concern, and connector selection is increasingly viewed as one component of a broader vascular access bundle rather than an isolated consumable decision. This mindset supports longer contract cycles for products that demonstrate consistent performance and compatibility within closed-system environments.
At the same time, labor constraints continue to influence consumable selection. Products that reduce flush frequency, minimize occlusion interventions, or simplify access routines can translate into meaningful workflow improvements. Evidence associating connector platforms with reduced thrombolytic use has gained commercial relevance because it ties device performance to drug cost savings and nursing time. These demand-side dynamics are nudging hospitals toward products with demonstrable operational benefits, especially in high-throughput acute care environments.
Supply Chain Maturation and Cost Structure Realignment
Supply chain stabilization has changed how both manufacturers and buyers think about cost. Earlier disruption-era urgency has given way to more disciplined contracting, inventory planning, and total cost evaluation. For manufacturers, this environment rewards scale, consistent quality, and strong GPO relationships. For buyers, it enables more deliberate evaluation of value over time rather than short-term price alone.
Worldwide Acute Care Electronic Health Recorder (EHR) Market
Cost structure considerations also affect OEM and precision-molded connector supply. Manufacturers that can combine design control, molding precision, and regulatory readiness are well positioned to serve global acute care suppliers seeking reliable sourcing. At the same time, any renewed cost pressure from raw materials, sterilization, or logistics could compress margins on undifferentiated products, reinforcing the trend toward value-based competition.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the largest players commanding a meaningful share of global revenue while operating across different strategic positions. The competitive field includes broad-line medical device manufacturers with established acute care franchises, specialized connector companies with focused product platforms, and OEM suppliers that serve the broader supply chain through precision molding and custom engineering.
Strategic Positioning of Leading Players
Several companies illustrate distinct approaches to capturing value in this segment.
- ICU Medical has leveraged a comprehensive needlefree connector portfolio around neutral-displacement technology, with a notable emphasis on infection-control positioning. Recent labeling activity has strengthened claims associated with CLABSI risk reduction and microbial ingress prevention, and the company has paired regulatory progress with group purchasing access through multi-year contracts. This combination of evidence, labeling support, and purchasing channel access illustrates a strategy centered on clinical differentiation and institutional adoption.
- Becton, Dickinson and Company maintains a strong acute care presence with needle-free connector offerings positioned around reduced CLABSI and occlusion risk. Clinical data associating certain connector platforms with lower thrombolytic use has added an economic dimension to product positioning, helping frame the discussion around total cost of care rather than device unit price. This approach aligns with BD's broader strength in hospital supply ecosystems.
- B. Braun Medical offers connector platforms optimized around neutral displacement and anti-reflux performance within hospital IV therapy workflows. Its positioning reflects integration into broader infusion and vascular access portfolios, which can be advantageous for customers seeking workflow compatibility and standardized consumables across multiple device categories.
- Vygon S.A. continues to serve acute care vascular access needs with neutral displacement connector options, emphasizing compatibility and clinical usability within hospital settings. The company's strategy reflects steady penetration through product reliability and regional distribution strength.
- Nexus Medical illustrates a more focused approach, with neutral displacement connectors engineered for minimal reflux volume and acute care applications. Independent testing documenting low reflux ranges supports its technical positioning and offers a basis for differentiation in clinically sensitive environments.
- RyMed Technologies has emphasized enhanced infection control through antimicrobial-impregnated connector designs, targeting institutions looking for additional layers of protection beyond mechanical displacement characteristics. This illustrates a complementary differentiation path that emphasizes material and surface-level interventions.
- Terumo Corporation and Smiths Medical both participate through needle-free connector offerings tied to broader infusion and catheter systems, reinforcing the value of portfolio integration and closed-system compatibility in hospital purchasing.
- Baxter International Inc. maintains connector offerings within acute care IV therapy, benefiting from established relationships and system-level compatibility. Its presence reflects the importance of broad acute care distribution and clinical familiarity.
- CHI FENG Co., Ltd. operates in a different part of the value chain, providing OEM/ODM precision-molded neutral needle-free connectors for global acute care suppliers. This role highlights the strategic importance of manufacturing precision, scalability, and design support in serving larger branded participants.
- PuraCath Medical has entered the conversation with new connector technology cleared for vascular access in critical care, using IT-based approaches to reduce CLABSIs in acute care settings. New entrants with distinct technical mechanisms can reshuffle attention within the segment if clinical data and adoption pathways align.
How the Landscape Is Evolving
The competitive environment is shifting along several axes. First, evidence-based differentiation is becoming more central, and labeling advances are turning clinical claims into commercial assets. Second, purchasing consolidation is increasing the importance of group purchasing access and multi-year contract readiness, especially for products that can demonstrate infection prevention and workflow value. Third, there is an ongoing tension between portfolio breadth and focused specialization. Broad-line players benefit from system compatibility and supply relationships, while focused players can compete on specific performance characteristics and clinical storytelling. Fourth, new entrants with novel mechanisms, such as IT-enabled connector designs, introduce potential disruption if they can generate compelling evidence and secure adoption in high-acuity settings.
Overall, the market is moving toward a split between clinically validated platforms competing on outcomes and operational value, and cost-optimized SKUs competing primarily on price and standardization. The former are likely to capture more durable share in acute care settings where infection prevention and workflow efficiency carry real financial and clinical weight.
PW Consulting
Future Outlook and Emerging Opportunities
Clinical Evidence Will Become a Licensing and Adoption Asset
Over the next three to five years, clinical evidence is expected to play an even greater role in connector selection. As hospitals refine vascular access protocols and infection prevention programs, products with robust data packages and regulatory-supported labeling claims will have an advantage in formulary discussions and GPO negotiations. This creates opportunity for companies that can sustain data generation, translate results into procurement-friendly narratives, and align clinical claims with total cost of care arguments. It also raises the importance of post-market evidence and real-world consistency, since hospital adoption increasingly depends on demonstrated performance over time.
Neutral Displacement and Reflux Control Will Remain Strategic Parameters
Neutral displacement design, reflux control, and microbial ingress prevention will continue to be central technical parameters in acute care applications. Independent testing, systematic reviews, and labeling developments are reinforcing the relevance of these characteristics. Companies that can clearly communicate reflux behavior, compatibility, and workflow implications will be better positioned to compete in high-acuity environments where occlusion management and infection risk matter. This also creates opportunities for product development investment aimed at reducing reflux volume, improving pressure infusion capability, and strengthening microbial barrier claims without sacrificing usability.
Consolidation in Procurement and the Rise of Value-Based Selection
Hospital procurement is likely to continue consolidating around fewer connector choices within individual institutions, driven by standardization, training efficiency, and purchasing leverage. Within that constraint, value-based selection will become more important, meaning products that can show reduced thrombolytic use, lower occlusion intervention frequency, and meaningful infection prevention association will have stronger staying power. For manufacturers, this implies that price competition alone will be insufficient in many acute care accounts; commercial success will depend on aligning device performance with hospital cost and quality priorities. For investors, it suggests that the most durable growth stories will emerge from platforms with both evidence and purchasing channel access.
Potential Risks and Uncertainties
Several uncertainties could alter the trajectory of the market. If clinical evidence remains fragmented or difficult to compare across products, buyers may default to price and standardization, compressing differentiation value. If reimbursement and cost pressures intensify, hospitals may prioritize short-term savings over performance-based selection, particularly in margin-constrained settings. Supply chain disruptions, raw material volatility, or regulatory changes affecting labeling claims could also affect product positioning and margin profiles. Finally, new technology entrants must prove not only technical merit but also adoption feasibility within hospital workflows and purchasing structures, which can slow the impact of otherwise promising innovations.
Strategic Implications for Decision-Makers
For Manufacturers
- Invest in evidence generation and labeling strategy as core commercial capabilities, not just regulatory exercises. Clinical claims that link connector performance to CLABSI risk, occlusion, and drug use can shape formulary discussions when supported by regulatory clearances and peer-reviewed data.
- Balance portfolio breadth with focused technical differentiation. If products are positioned around neutral displacement and reflux control, make those performance characteristics measurable, credible, and easy for clinical and procurement teams to understand.
- Strengthen group purchasing relationships and multi-year contract readiness. In a consolidating procurement environment, access to contracted volume can matter as much as product quality for sustained share growth.
For Investors
- Prioritize platforms with both clinical evidence and purchasing channel access. Revenue growth in this segment is increasingly tied to institutional adoption, and adoption depends on demonstrated value plus contract presence.
- Track labeling and clearance activity as leading indicators of competitive positioning. Regulatory-supported claims can shift purchasing attention and create differentiation that persists beyond feature comparisons.
- Monitor new entrants with distinct mechanisms, but assess adoption feasibility carefully. Technical novelty alone does not guarantee acute care uptake; workflow compatibility, evidence strength, and commercial execution determine whether innovation translates into share.
For Procurement and Hospital Leadership
- Evaluate connector selection as part of a broader vascular access and infection prevention strategy, not solely as a consumable price decision. Total cost implications, including thrombolytic use, flush frequency, and occlusion management, can materially affect operating economics.
- Seek standardized formularies where clinically appropriate, but preserve room for evidence-backed differentiation in high-acuity settings. Not all use cases demand the same connector performance profile, and segmentation can improve both safety and cost efficiency.
- Ask suppliers for clear, comparable performance data on reflux behavior, microbial ingress prevention, occlusion risk, and compatibility within existing systems. Consistency of evidence and post-market performance should weigh heavily in long-term contracting decisions.
The acute care needleless connector market is entering a phase in which clinical evidence, regulatory-supported labeling, and value-based procurement will increasingly determine competitive outcomes. Companies and buyers that treat connector selection as a strategic lever for infection prevention, workflow efficiency, and total cost management will be better positioned than those competing only on unit price or feature lists. For decision-makers seeking detailed segmentation data, regional dynamics, contract structures, and customized commercial implications, the full research report provides a deeper operational view of the market and the specific pathways most relevant to individual business contexts.
For detailed analysis of this topic, please visit the official page: Acute Care Needleless Connector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
UV LEDs Market at 11.9% CAGR: Why Asia Pacific and UV Curing Are Redefining Growth
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Opportunities in the UV LEDs Market
The ultraviolet LED sector has moved from a specialized component niche to a critical enabler of industrial, environmental, and healthcare infrastructure. Between 2020 and 2025, the global UV LEDs market expanded from $700.0 million to $1,230.0 million, reflecting a compound annual growth rate of 11.9% that extends through the forecast horizon to 2032. By the close of the projection period, revenue trajectories point toward $2,694.0 million, signaling a market that has crossed the threshold from incremental adoption to structural expansion. This growth trajectory is not merely a reflection of incremental efficiency gains; it captures a broader transition in how industries approach disinfection, curing, and environmental control as regulatory, technological, and supply chain conditions reshape competitive dynamics.
The market’s expansion has been uneven, shaped by material bottlenecks, geopolitical trade controls, and the uneven pace of certification and standardization across end-use sectors. While the headline numbers indicate robust demand absorption, the underlying mechanics reveal a landscape where competitive advantage increasingly depends on manufacturing scale, substrate availability, and the ability to align product development with regulatory timelines. Understanding these mechanics is essential for executives evaluating capital allocation, supply chain strategy, and product roadmap decisions.
Market Landscape and the Structural Challenges Shaping Growth
The UV LEDs market’s progression from $700.0 million in 2020 to $1,230.0 million in 2025 underscores a sustained demand pull, but the growth path has not been frictionless. The compounding rate of 11.9% masks underlying volatility in input costs, substrate constraints, and the uneven deployment of certified systems across regions and applications. The market remains moderately concentrated, with the top three firms holding a 24.6% share and the top five reaching 52.0%, a structure that reflects both the technical barriers to entry and the persistent fragmentation across wavelength-specific applications.
UV Lasers Market
Substrate Constraints and Per-Unit Economics
A persistent bottleneck lies in large-diameter aluminum nitride substrates, which remain limited to 3 inches or smaller. This constraint directly affects UV-C LED production economics by increasing per-unit costs and limiting wafer-scale yield improvements. For manufacturers, the implication is clear: scaling volume alone does not automatically translate into margin expansion when substrate supply restricts throughput and forces reliance on smaller-batch processing. Companies that can secure consistent substrate access or develop alternative packaging and yield-management strategies are better positioned to maintain cost competitiveness as demand intensifies.
Geopoliticized Material Supply Chains
Raw material access has become a strategic variable rather than a background procurement issue. China’s gallium and germanium export controls, implemented in August 2023 and tightened through 2025, restrict gallium nitride materials essential for UV LED substrates and chips. Licensing requirements and end-user restrictions targeting the United States have created parallel pressure on Asian producers reliant on Chinese materials, while U.S. export controls on gallium-related items have increased supply chain risk across the manufacturing ecosystem. In practical terms, this translates into longer qualification cycles, inventory hedging, and a growing premium on supply chain diversification and regional sourcing strategies.
Labor Intensity and Process Complexity
The market’s growth trajectory is also shaped by rising manufacturing complexity. UV LED manufacturing labor costs have risen by 10-12% annually in 2025 as a result of skilled semiconductor process requirements. This increase is not simply an inflationary headwind; it reflects the technical demands of wavelength precision, packaging reliability, and performance validation. Organizations that treat labor as a variable cost rather than a capability constraint risk underinvesting in process engineering, automation, and workforce development, which can erode competitiveness even as demand expands.
Core Drivers Accelerating Market Expansion
The market’s growth is being propelled by several reinforcing forces that extend beyond simple demand substitution. These drivers interact with one another, creating both acceleration and new constraints depending on how companies position their capabilities.
PW Consulting
Technology Innovation and Performance Breakthroughs
Performance gains are reshaping adoption economics, particularly in disinfection and curing applications where efficiency and output directly influence total cost of ownership. Recent developments illustrate the pace of progress: in August 2025, ams-OSRAM AG doubled UV-C LED efficiency to 10.2% through enhanced semiconductor technology, a milestone that strengthens the case for UV-C deployment in air, water, and surface applications where energy consumption and thermal management have historically constrained scalability. Separately, Nichia Corporation expanded its portfolio in October 2025 with new UV-A LED series at 365nm and 385nm wavelengths featuring improved flux output for industrial UV curing, alongside new UV-B 308nm and UV-A 330nm LEDs. These product moves reflect a broader industry push to broaden wavelength coverage and improve output consistency, enabling customers to tailor solutions to more demanding curing and disinfection requirements.
The technology trajectory is also visible in system-level innovations. Kyocera Corporation’s May 2025 launch of the Air-cooled UV LED light source G7A Series with revolutionary curing performance highlights how thermal management and integration can change performance expectations in industrial settings. As LED efficiency and light-source design improve, the conversation shifts from feasibility to deployment scale, particularly in applications that previously relied on mercury-based alternatives.
Policy and Regulatory Momentum
Regulatory frameworks are increasingly shaping adoption pathways by establishing performance benchmarks and compliance expectations. Mercury phase-down pressures and broader environmental regulations continue to favor mercury-free alternatives, reinforcing interest in UV LEDs across disinfection, curing, and purification use cases. At the same time, certification requirements add both credibility and cost. NSF/ANSI Standard 55 certification, for example, requires UV LED systems to meet specific testing for residential water treatment, adding compliance validation time and costs. For suppliers, this means that time-to-market is not only a function of product readiness but also of testing, documentation, and certification strategy. For buyers, certified products reduce deployment risk but require a longer evaluation cycle and more disciplined vendor qualification.
Demand-Side Shifts in Disinfection, Curing, and Environmental Control
Demand is being driven by a combination of hygiene expectations, industrial productivity requirements, and sustainability scrutiny. Disinfection and sterilization applications have gained institutional traction in settings where water, air, and surface treatment are prioritized, while UV curing continues to benefit from the broader industrial push toward faster processing and reduced chemical exposure. Medical and scientific uses add a more specialized but high-value demand layer, particularly where wavelength precision and reliability are essential. Security-related applications occupy a smaller share of the market but remain relevant where specialized detection and verification functions depend on UV illumination.
What distinguishes the current demand environment is the move from pilot deployment to broader integration. As performance improves and compliance pathways become clearer, more organizations are evaluating UV LEDs not as experimental alternatives but as core components of operational strategy. This shift increases volume potential while also raising expectations for consistency, durability, and integration support.
Synthetic Quartz Glass UV-LED Market
Supply Chain Restructuring and Cost Dynamics
Supply chain and cost structure changes are reshaping how value is captured across the value chain. The combination of substrate limitations, export-controlled materials, and rising skilled-labor costs is pushing companies to rethink sourcing, inventory management, and manufacturing geography. At the same time, efficiency improvements are altering the relative importance of component cost versus system-level performance. In many cases, a higher-performing LED can justify a higher unit cost if it reduces energy usage, simplifies thermal design, or accelerates throughput. This reframing favors suppliers that can demonstrate total system value rather than competing solely on component pricing.
Competitive Landscape and the Strategies Defining Leadership
The competitive field is defined by a blend of established LED manufacturers, specialty deep UV players, and vertically oriented solution providers. Market leadership is not simply a function of scale; it increasingly depends on wavelength-specific expertise, certification readiness, and the ability to align product portfolios with high-priority application segments.
Differentiation Through Application Focus and Wavelength Breadth
Seoul Viosys Co., Ltd. has concentrated on its Violeds UV-C LED series optimized for UVC disinfection in water, air, and surface applications, an approach that emphasizes targeted performance in high-demand sanitation use cases. Nichia Corporation has pursued a broader wavelength strategy, offering full-range UV-C, UV-B, and UV-A LEDs for disinfection and mercury-free applications, while also expanding its portfolio with recent UV-A and UV-B products aimed at curing and specialized uses. This breadth supports flexibility across customer requirements and positions the company to capture demand across multiple application layers.
Crystal IS and Sensor Electronic Technology, Inc. continue to emphasize high-performance UVC and deep UV LEDs spanning 240-365nm for sterilization, sensors, and biomedical uses, focusing on technical performance in settings where wavelength precision and reliability carry disproportionate weight. STANLEY ELECTRIC CO., LTD. differentiates with UV-C and UV-A LEDs featuring hermetic sealing for disinfection and curing, an engineering choice that highlights durability and integration reliability. ams-OSRAM AG has built a recognizable portfolio through its OSLON UV-C LED line for air, water, and surface disinfection, and its recent efficiency gains reinforce the strategic value of semiconductor-level performance improvement.
Luminus Devices supports healthcare disinfection, water purification, and industrial curing with UVC and UVA LEDs, aligning its portfolio with both public-health and industrial demand. Nikkiso Co., Ltd. focuses on deep UV-LEDs for mercury lamp replacement in water purification and air sterilization, a positioning that directly addresses the substitution dynamic across environmental applications. LG Innotek Co., Ltd. integrates UV LEDs into lighting and disinfection solutions, reflecting a different competitive angle that emphasizes system-level integration and broader product ecosystems rather than component-only positioning.
Market Evolution: Consolidation, Specialization, and New Entrants
The market’s moderate concentration suggests room for both consolidation and continued specialization. Top players are likely to deepen application-specific capabilities, especially where certification, substrate access, and efficiency gains provide durable differentiation. At the same time, the fragmentation across wavelengths and applications creates entry points for firms that can solve a specific performance, integration, or compliance problem more effectively than generalist competitors.
Consolidation pressure is expected to intensify where scale matters most, particularly in substrate-dependent manufacturing and in segments that require extensive qualification and customer support. Conversely, specialization is likely to remain attractive in deep UV, medical/scientific, and curing applications where performance requirements are tightly defined and the cost of underperformance is high. New entrants will need to navigate material constraints and skilled-labor costs, but they can still compete by targeting underserved wavelength gaps, developing novel packaging or thermal-management approaches, or building strong certification and compliance capabilities early.
Forward-Looking Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to define the market’s direction and the commercial opportunities attached to them.
Efficiency Gains as a Deployment Catalyst
Continued improvements in UV-C and UV-A efficiency are likely to accelerate adoption in applications where energy consumption, thermal load, and system size have previously limited scale. As efficiency rises, total cost of ownership comparisons become more favorable against legacy alternatives, especially in disinfection and curing settings where operating costs and space constraints matter. The commercial opportunity here is not limited to component sales; it extends to system design, integration services, and performance-based value propositions that tie product selection to operational outcomes.
Supply Chain Resilience Becomes a Competitive Differentiator
Material controls and substrate limitations are likely to keep supply chain resilience at the center of strategy. Companies that diversify sourcing, negotiate long-term substrate access, and build transparent compliance and traceability processes will be better positioned to manage cost volatility and customer qualification cycles. For buyers, supplier resilience is increasingly part of procurement risk assessment, which creates an advantage for vendors that can demonstrate stable access to critical inputs and predictable delivery performance.
Certification and Standardization as Adoption Accelerators and Gatekeepers
Regulatory and standards activity is expected to remain a dual force: enabling broader deployment by establishing trust and performance benchmarks, while also extending validation timelines and adding cost for suppliers. The companies that treat certification as a strategic capability rather than a late-stage compliance task will gain speed and credibility in sensitive applications such as residential water treatment and public-health-related disinfection. For the market as a whole, this trend raises the bar for entry but also rewards organizations that can align product development with regulatory expectations early.
Potential Risks and Uncertainties
Several uncertainties bear monitoring. Further tightening of material export controls could disrupt supplier planning and increase input volatility, particularly for producers with concentrated sourcing exposure. Substrate constraints may persist if large-diameter aluminum nitride supply does not expand at a pace matching demand, maintaining pressure on per-unit costs in UV-C production. Labor cost inflation could also compress margins if process automation and workforce development lag behind manufacturing complexity. Finally, regulatory divergence across regions may create uneven adoption speeds, making it harder to scale standardized solutions globally without localized compliance investment.
Actionable Guidance for Decision-Makers
The market’s trajectory offers distinct implications depending on an organization’s role in the value chain. The following considerations can help translate market dynamics into prioritized actions.
For Manufacturers and Technology Developers
Focus investment where performance differentiation is most defensible. That means prioritizing wavelength-specific improvements, packaging reliability, thermal management, and certification readiness in high-value applications rather than competing broadly on price alone. Strengthening supply chain resilience should be treated as a strategic capability, including substrate access, material sourcing diversification, and process automation to offset skilled-labor cost pressure. Companies should also evaluate whether they can capture more value through system-level integration or partnered solutions, particularly in disinfection and curing where end users increasingly evaluate total operating performance.
For Investors
Evaluate exposure not just by revenue potential but by supply chain positioning, wage and substrate risk, and the ability to navigate certification timelines. The most attractive opportunities are likely to be in companies that combine meaningful efficiency gains with application-specific traction and credible compliance pathways. Diversification across wavelength segments may reduce reliance on any single bottleneck, but specialization can also create durable advantages where performance requirements are strict and substitution options are limited. Track material control developments and substrate supply progress, as these factors are likely to influence both cost structures and the pace of scaling.
For Procurement and End-User Organizations
Treat UV LED selection as a total-cost and risk decision rather than a component purchase. Prioritize suppliers with demonstrated certification readiness, stable material access, and evidence of efficiency and reliability in the target application. Build evaluation cycles that account for compliance validation, integration requirements, and long-term supply continuity, especially in water treatment, healthcare disinfection, and industrial curing settings where downtime or failure carries operational penalties. Align specification decisions with actual duty cycles and environmental conditions rather than maximum output claims, since real-world performance is often determined by thermal design, packaging quality, and system integration as much as by LED output.
The UV LEDs market is moving from a phase of capability demonstration to one of scaled deployment, where efficiency, compliance, and supply chain resilience determine who captures value and how quickly adoption broadens. Detailed segment-level data, company benchmarking, and scenario-based forecasts can sharpen these decisions further and help organizations convert market momentum into a coherent strategy. For decision-makers seeking a deeper, application-specific view of the landscape, the full research report provides expanded segmentation detail, competitive profiling, and tailored recommendations designed to support capital, product, and procurement decisions with greater precision.
For detailed analysis of this topic, please visit the official page: UV LEDs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
LIS Market 2032: How 7.8% CAGR and 65% Concentration Shape Strategic Decisions
By pmarketresearch, 2026-09-21
Laboratory Information System (LIS) Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Navigating Growth Amid Structural Complexity
The Laboratory Information System market has matured from a niche operational tool into a core infrastructure layer for modern diagnostic and research laboratories. Over the historical period from 2020 to 2025, the market expanded from approximately $110.0 million to an estimated $157.5 million, reflecting a compound annual growth rate that underscores sustained institutional adoption. Forward projections through 2032 point toward continued expansion, with the market anticipated to reach roughly $264.6 million. This trajectory implies a steady annualized growth rate of approximately 7.8 percent, signaling that demand is no longer driven solely by baseline digitization but by deeper integration of data workflows, regulatory compliance, and analytical capabilities.
Several structural features characterize the current landscape. Market concentration remains notable, with the top three participants collectively accounting for roughly 65 percent of revenue and the top five capturing approximately 78 percent. This concentration suggests that scale, established compliance frameworks, and interoperability with legacy clinical systems continue to act as meaningful barriers to entry, while also creating room for specialized or cloud-native challengers in underserved segments. The composition of the installed base further highlights a shift in how organizations view laboratory software: integrated laboratory information systems now command a larger share of the total addressable spend compared with standalone deployments, reflecting a preference for platforms that unify test ordering, specimen tracking, result reporting, and billing within a single workflow.
At the application level, clinical diagnostics represents the dominant use case, absorbing the majority of system investments as hospitals, reference labs, and specialty testing facilities prioritize turnaround time, result accuracy, and seamless electronic health record connectivity. Laboratory management functions, while smaller in aggregate spend, are gaining strategic importance as operations scale, regulatory documentation requirements intensify, and managers seek centralized control over inventory, calibration, and audit trails. Regionally, North America continues to anchor the largest revenue pool, followed by Europe and the Asia Pacific region. Latin America and the Middle East and Africa represent smaller but structurally interesting markets, often characterized by evolving accreditation expectations and incremental modernization of public and private laboratory networks.
Key Challenges and Inflection Points
Despite the constructive demand environment, the market is encountering several pressure points that are reshaping purchasing decisions and implementation timelines.
- Regulatory acceleration is compressing adaptation windows. Upcoming changes to quality management expectations, including the transition toward ISO 13485 alignment referenced through updated quality system requirements, are forcing laboratories and vendors to reassess documentation logic, validation protocols, and audit readiness. For many organizations, compliance is no longer a one-time project but an ongoing operational discipline that must be embedded directly into LIS templates and reporting structures.
- Legacy integration and interoperability remain persistent friction. Laboratories frequently operate across heterogeneous instrument fleets, disconnected data repositories, and varying electronic health record environments. Deploying a new system therefore involves more than software installation; it requires reconciling data dictionaries, managing interface lifecycles, and ensuring that digitized workflows do not inadvertently increase manual reconciliation work.
- Total cost of ownership expectations are rising alongside functionality demands. As laboratories pursue faster turnaround, stronger traceability, and advanced analytics, decision-makers increasingly scrutinize not only license or subscription costs but also implementation effort, training overhead, interface maintenance, and long-term scalability. Organizations that underestimated these operational realities are reframing procurement around lifecycle value rather than initial price.
Core Drivers Reshaping the LIS Landscape
Technology Innovation and the Analytics Turn
Technology evolution is shifting the value proposition of laboratory information systems from transaction processing toward decision support. Cloud deployment models, modular architectures, and API-first designs are making it more practical to connect instruments, middleware, and enterprise applications without building heavily customized point-to-point interfaces. At the same time, the integration of data analytics capabilities is becoming a differentiator. Recent market activity illustrates this shift clearly: one major vendor acquired a data analytics firm to establish a dedicated innovations center, signaling that the next competitive frontier is not merely storing results but transforming them into actionable operational intelligence.
For laboratory operators, this trajectory means the most valuable systems are those that reduce manual handoffs, support real-time dashboards, and enable trend analysis across specimen volume, turnaround times, and quality metrics. The presence of artificial intelligence and machine learning features, when implemented responsibly, is increasingly associated with workload prioritization, anomaly flagging, and predictive staffing insights. Importantly, these capabilities are not uniformly mature across all vendors, which creates a meaningful evaluation gap for buyers comparing platforms on future extensibility rather than current feature lists.
Blood Bank Information Systems Market
Policy and Regulatory Dynamics as Both Constraint and Catalyst
Regulatory change is functioning as both a compliance burden and an adoption catalyst. The mandatory shift toward quality management system expectations aligned with ISO 13485, effective in early 2026, is prompting medical device and in-vitro diagnostic manufacturers to align documentation and process controls more tightly with international standards. For laboratory information systems, this translates into renewed emphasis on validated workflows, electronic record integrity, and traceable change control. Laboratories must also prepare for updated Centers for Medicare & Medicaid Services rules expected as early as late 2025, which may require adjustments to reporting templates and data handling practices.
Simultaneously, the accreditation landscape continues to reward digitization. Implementation cycles for ISO 17025 typically span 12 to 18 months from planning through accreditation, encouraging laboratories to select systems that can support standardized method validation, proficiency testing documentation, and audit-ready record retention from the outset. Administrative modernization is also reshaping operational routines; for example, regulatory survey fee payments have moved to online channels, reflecting a broader push toward digital process hygiene. Collectively, these developments raise the cost of lagging behind and strengthen the case for platforms that embed compliance logic into everyday workflows.
Demand-Side Shifts in Laboratory Operations
On the demand side, laboratories are under pressure to do more with constrained staffing while meeting rising expectations for speed and transparency. Clinical operators are increasingly prioritizing end-to-end visibility, from specimen accessioning through result verification and physician delivery, because delays or data gaps can cascade into downstream care delays and patient satisfaction erosion. In parallel, specialized testing and molecular workflows are expanding in complexity, requiring systems that can handle richer data structures, chain-of-custody tracking, and multi-step interpretive reporting.
Laboratory Water Purifier Market
Recent partnership activity in digital pathology illustrates how demand is pulling vendors toward seamless workflow integration. A notable collaboration brought together a laboratory information system provider and a digital pathology platform to streamline image and report integration, reducing the friction between slide review and result reporting. Such initiatives indicate that laboratories are no longer satisfied with isolated tools; they want connected ecosystems that support multidisciplinary review, remote consultation, and unified data access.
PW Consulting
Supply-Side and Cost Structure Evolution
The vendor side is adjusting to these expectations through targeted consolidation, capability expansion, and a growing emphasis on compliance-ready configurations. Acquisitions that add molecular capabilities or analytics depth are enabling established players to offer broader workflow coverage within a single relationship, which can simplify procurement and reduce integration risk for larger laboratories. At the same time, smaller and cloud-focused providers are competing on implementation speed, subscription economics, and niche conformance features, particularly for environmental, quality, and specialized testing labs that require ISO 17025-aligned documentation support.
Cost structures are therefore diverging. Large integrated platforms often command premium positioning but may lower the total number of vendor relationships and interface projects a laboratory must manage. Smaller or modular solutions can reduce initial procurement barriers and accelerate time to value, though they may require additional effort in connecting to enterprise systems or scaling across multiple sites. The practical implication is that cost comparisons are increasingly incomplete without an assessment of implementation burden, interface count, and ongoing support requirements.
Competitive Landscape: Positioning, Differentiation, and Consolidation Signals
The competitive field blends mature diagnostics and enterprise software companies with specialized informatics providers and emerging cloud-native entrants. The largest players benefit from broad installed bases, established device ecosystems, and the ability to position laboratory information systems within wider clinical or analytical portfolios. This positioning can be advantageous for organizations seeking a single vendor relationship across instruments, middleware, and reporting layers, but it may also introduce complexity if the broader portfolio is not equally optimized for laboratory workflow specifics.
Mid-tier and specialized vendors tend to compete on depth of laboratory-centered functionality, configuration flexibility, and domain-specific compliance support. Companies with strong roots in laboratory operations often emphasize intuitive accessioning, specimen tracking, result verification, and audit trail management, appealing to laboratories that prioritize usability and operational control. Cloud-oriented providers, meanwhile, differentiate through rapid deployment, subscription models, and simplified maintenance, which can be attractive to smaller labs or those with limited internal IT capacity. Some of these providers have also advanced compliance narratives, including demonstrations of AI-enabled environmental laboratory setups aligned with ISO 17025 expectations, reflecting a broader push to connect modern informatics with accreditation requirements.
Recent transactions and partnerships underscore a market in motion. The acquisition of a data analytics firm by a long-standing laboratory software vendor points to a strategy of embedding analytical horsepower directly into the platform. Another vendor completed a purchase to strengthen molecular capabilities, illustrating how companies are expanding into higher-complexity testing domains where data handling and interpretive workflows carry greater value. At the same time, partnerships focused on digital pathology integration show a willingness to build ecosystems rather than relying solely on proprietary end-to-end suites. These moves suggest a market that is consolidating around broader capability bundles while still encouraging targeted alliances where specialized functionality is critical.
Strategic Positioning Themes Among Leaders
- Ecosystem breadth versus workflow depth. Larger companies often compete on the strength of integrated device and enterprise connections, while smaller specialists compete on fine-grained laboratory workflow fit and faster configuration cycles.
- Compliance-by-design narratives. With regulatory expectations tightening, vendors that can demonstrate validated templates, robust change control, and accreditation-ready documentation gain a tangible advantage during evaluation cycles.
- Deployment and ownership models. Cloud subscriptions, hybrid architectures, and on-premises options continue to shape purchasing decisions, with laboratories weighing data control, IT capacity, and long-term scalability.
- Analytics and interoperability as future-proofing. Vendors investing in analytics centers or digital pathology partnerships are signaling that the next phase of competition will hinge on how well systems convert operational data into usable insight and connect across disciplinary boundaries.
How the Landscape Is Evolving
Three patterns are likely to shape the next phase of competition. First, consolidation will continue where scale, compliance portfolios, and analytics ambitions justify mergers or acquisitions, particularly among vendors seeking to add molecular, digital pathology, or data science capabilities. Second, differentiation will increasingly emerge in subsegments, as environmental labs, molecular diagnostics providers, and high-volume clinical operations each prioritize distinct compliance and workflow requirements. Third, new entrants and cloud-native challengers will persist in niches where implementation speed, transparent subscription economics, and modern user experience can outweigh the advantages of incumbent scale. The net effect is a market that is neither fully homogeneous nor fully fragmented, but rather stratified by the balance of integration needs, compliance demands, and operational complexity.
Forward Outlook: Three Trends to Watch Through 2032
Trend One: Compliance-EmbodiedPlatforms Become Table Stakes
As quality management expectations align more closely with international standards and CMS-related rules evolve, laboratory information systems will be judged not only on functionality but on how naturally they support documentation, validation, and audit readiness. Platforms that embed these requirements into daily workflows will reduce the lag between regulatory change and operational adaptation. For buyers, this increases the value of configurable templates, traceable record structures, and vendor support during accreditation cycles. For vendors, it raises the stakes around validation services, release discipline, and ongoing regulatory monitoring. A key uncertainty is the pace and granularity of rule implementation across jurisdictions, which may create uneven adoption timing and divergent regional requirements.
Trend Two: Analytics and Interoperability Move from Enhancement to Core Value
The next phase of growth will likely be driven by systems that transform laboratory data into operational insight. Dashboards for turnaround time, error rates, specimen flow, and resource utilization are becoming central to laboratory management, while smoother data exchange with electronic health records and external reporting systems is increasingly expected rather than optional. A notable acquisition establishing a data analytics innovations center suggests that leading vendors see analytical integration as a strategic growth lever rather than a peripheral feature. The commercial opportunity lies in helping laboratories make staffing, workflow, and quality decisions with greater precision. The risk is that overpromised analytics can create disappointment if data quality, integration scope, or change management are insufficient to support meaningful insight generation.
Trend Three: Modular, Cloud-Forward Deployments Expand in Select Segments
Cloud-native and modular deployment models are expected to continue gaining traction, particularly where laboratories seek faster implementation, lower upfront capital exposure, and simplified maintenance. Specialized and mid-sized laboratories may favor these models if they reduce the operational burden of hosting, patching, and interface upkeep. However, adoption will remain uneven in settings where data residency requirements, internal IT policy, or complex instrument ecosystems favor more controlled deployment approaches. The commercial implication is a bifurcated purchasing environment: cloud-forward solutions will likely grow fastest where agility and compliance configurability align, while integrated on-premises or hybrid solutions will retain strength in large, complex environments with substantial legacy investments.
Strategic Actions for Decision-Makers
For Laboratory Operators and Procurement Teams
- Evaluate platforms against the full operational lifecycle, including interface count, configuration effort, training burden, validation support, and long-term scalability, rather than focusing primarily on initial license or subscription cost.
- Prioritize systems that embed compliance logic and audit-ready documentation into daily workflows, especially where accreditation cycles and quality management transitions are imminent.
- Treat interoperability as a first-order requirement; map the current instrument and electronic health record landscape early to understand the integration scope a new system will need to absorb.
For Vendors and Manufacturers
- Invest in analytics, interoperability, and domain-specific compliance features that reduce the operational burden on laboratories, since these capabilities increasingly differentiate platforms in competitive evaluations.
- Use targeted partnerships and selective acquisitions to expand into molecular, digital pathology, or data science capabilities where organic development would be slower or riskier.
- Clarify deployment and ownership options with transparent total cost narratives, because buyers are increasingly comparing lifecycle economics across cloud, hybrid, and on-premises models.
For Investors and Strategic Planners
- Focus on vendors demonstrating measurable progress in analytics integration, compliance readiness, and workflow breadth, since these attributes are shaping the next round of procurement advantage.
- Watch for consolidation activity that signals shifts in capability boundaries, particularly where acquisitions add molecular depth, data science capacity, or specialized accreditation support.
- Assess regional variation carefully; market maturity, regulatory expectations, and laboratory modernization pace differ enough across geographies to influence both growth timing and competitive entry strategies.
Why Detailed Intelligence Matters Now
The laboratory information system market is entering a period in which regulatory timing, integration complexity, and analytics expectations will separate decision-makers who plan around lifecycle value from those who evaluate systems primarily on feature checklists. The trends outlined here point to a landscape where compliance-embodied design, connected workflows, and data-driven operations are increasingly central to commercial success. Yet the specifics that determine outcomes—such as regional rule timing, segment-specific accreditation demands, interface complexity, and vendor capability maturity—are difficult to assess from high-level trends alone.
For organizations making procurement, investment, or product strategy decisions, detailed segmentation data, vendor capability comparisons, and implementation-pattern analysis can materially improve the quality of the choice. A deeper examination of how spending is distributed across deployment models, laboratory types, and geographies, along with a closer look at recent transactions and compliance-driven purchasing shifts, provides the granularity needed to calibrate timing, scope, and risk. Readers seeking that level of detail can access the full PW Consulting research report for expanded segmentation data, company-level signals, and tailored scenario analysis suited to specific operational and investment contexts.
For detailed analysis of this topic, please visit the official page: Laboratory Information System (LIS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Carrageenan Market 2026: Why 5.6% CAGR and Kappa Demand Shift Everything
By pmarketresearch, 2026-09-21
Navigating the Carrageenan Market: Strategic Trends and Commercial Opportunities Through 2032
The global carrageenan market has transitioned from a mature commodity space into a strategically nuanced arena where functionality, sustainability, and regulatory compliance now define competitive advantage. In 2025, the market reached an estimated revenue of USD 1,000.0 million, building on a steady expansion trajectory from 2020 through 2025. Forward projections through 2032 indicate a compound annual growth rate of 5.6 percent, with revenue anticipated to surpass USD 1,433.0 million by the end of the forecast window. This growth is not merely incremental; it reflects structural shifts in how formulators, manufacturers, and end consumers value hydrocolloid functionality across food, beverage, pharmaceutical, and personal-care applications. The market’s evolution offers a clear lens into broader industry dynamics: ingredient portfolios are being re-engineered for clean-label expectations, supply chains are being re-evaluated for resilience, and regulatory frameworks are increasingly shaping technical feasibility.
For decision-makers across the value chain, the carrageenan landscape presents both familiar headwinds and unfamiliar inflection points. Understanding where growth concentrates, which pressures are structural rather than cyclical, and how leading players are positioning themselves provides a practical foundation for strategic planning. The following analysis examines the current market environment, the forces driving change, the competitive architecture, emerging trajectories, and actionable considerations for manufacturers, investors, and procurement leaders.
Market Landscape and Core Challenges
The carrageenan market’s size and growth profile reflect sustained demand across multiple application verticals, but the macro figures only tell part of the story. Revenue expansion from 2020 to 2025 was supported by consistent reformulation activity, rising adoption in plant-based and dairy-adjacent products, and expanding use in pharmaceutical and personal-care formulations. The forward projection through 2032 suggests continued upward momentum, yet the pace and composition of growth will be shaped by factors that extend well beyond baseline demand.
Several structural challenges are currently redefining how participants approach sourcing, formulation, and compliance. First, raw material availability remains a critical vulnerability. Red seaweed, the foundational input for carrageenan extraction, is exposed to biological and environmental pressures that can disrupt supply continuity. Disease outbreaks affecting seaweed cultivation have periodically constrained harvest volumes, and when coupled with broader energy cost volatility, the result is a supply environment where pricing power and inventory resilience vary significantly across suppliers and regions. This dynamic is not a temporary disruption; it reflects an ongoing tension between agricultural dependence and industrial scale.
Carbomer Market
Second, regulatory scrutiny is intensifying in ways that directly affect formulation feasibility and compliance economics. Emerging draft limits on carrageenan use in infant food within the European Commission have introduced new technical barriers and elevated compliance costs for processors. Parallel regulatory tightening in other markets, including stricter testing and certification requirements for food-additive suppliers, adds layers of administrative and operational complexity. These developments disproportionately affect companies without vertically integrated, GMP-certified facilities, effectively raising the barrier to entry for certain distribution channels and customer segments.
Third, the market’s structural concentration introduces both stability and strategic risk. With a significant share of revenue captured by a relatively small group of established players, competitive dynamics are shaped by scale advantages, formulation expertise, and long-term customer relationships. At the same time, this concentration can limit agility in responding to regional supply shocks or rapidly evolving application requirements. Participants must therefore balance the benefits of portfolio breadth and manufacturing scale with the need for localized sourcing flexibility and technical responsiveness.
The practical implication for executives is that carrageenan is no longer a straightforward input-purchase decision. It is increasingly a strategic variable tied to product performance, regulatory risk, and supply assurance. Businesses that treat it purely as a cost line item risk exposure to formulation constraints and supply interruptions, while those that integrate it into broader ingredient strategy, supplier qualification, and reformulation roadmaps are better positioned to capture value.
Key Drivers Shaping Market Dynamics
Several interconnected forces are propelling the carrageenan market forward, each influencing how value is created and where competitive gaps emerge.
Innovation in Application-Specific Formulations
Technical advancement remains one of the most visible drivers of market evolution. Rather than competing solely on bulk functionality, suppliers are developing specialized carrageenan-based solutions tailored to precise application needs. Recent product introductions highlight a clear directional shift: stabilizers and gelling systems are being engineered for clean-label positioning, alternative-protein textures, and demanding processing conditions. Notably, new carrageenan-based stabilizers designed for all-purpose cream applications and gelling solutions formulated specifically for plant-based abalone meat alternatives demonstrate how ingredient development is aligning with emerging consumer categories. These launches also indicate a broader industry pattern in which hydrocolloid providers are expanding their portfolios at trade events and through targeted commercialization, using direct customer engagement to validate functionality and accelerate adoption.
For formulators and product developers, this trend means carrageenan is increasingly viewed as a customizable functional ingredient rather than a standardized additive. The strategic opportunity lies in matching application-specific performance requirements with suppliers that can demonstrate reproducible results, technical support, and formulation compatibility across diverse processing environments.
Regulatory and Compliance Evolution
Regulatory dynamics are reshaping both market access and competitive positioning. Draft limits on carrageenan in infant food have heightened attention to safety standards, labeling expectations, and processing controls. In parallel, stricter certification requirements in major consumer markets have raised the operational bar for suppliers seeking to serve food-additive and personal-care segments. These developments are not uniformly negative; they create differentiation opportunities for companies that already operate under robust quality systems and can demonstrate traceability, consistent purity, and compliance readiness.
PW Consulting
For procurement and regulatory teams, the implication is clear: supplier qualification now extends beyond price and basic specification matching. It increasingly includes documentation of manufacturing standards, audit readiness, and the ability to navigate evolving regional requirements. Compliance capability is becoming a commercial asset, not just a cost center.
Demand-Side Shifts in Food and Personal-Care Formulations
Consumer and industrial demand continues to redirect carrageenan usage toward cleaner-label, plant-forward, and functionally optimized products. In food and beverages, reformulation efforts are driving interest in stabilizers and texturants that support mouthfeel, suspension, and gelation without relying on ingredient profiles that trigger consumer skepticism. Simultaneously, pharmaceutical and personal-care applications are expanding the utility of carrageenan in areas such as wound-care, sustained-release formulations, and premium cosmetic textures. These demand shifts are not isolated trends; they reflect a broader preference for ingredients that combine performance with transparency and naturalness.
From a commercial standpoint, this environment rewards suppliers and formulators who can articulate functional benefits in application-specific language and support customers through development cycles. The growth potential is strongest where carrageenan can solve a tangible formulation challenge while aligning with brand-level positioning.
Supply Chain Structure and Sourcing Geography
The geography of raw material supply remains a defining feature of market behavior. Southeast Asia accounts for the majority of global carrageenan raw-material supply, with Chile serving as a key alternative source. This concentration provides efficiency advantages but also exposes the market to trade, logistics, and biological risk. Any disruption in key cultivation regions can ripple through pricing, availability, and lead times, especially for buyers who rely on just-in-time sourcing or single-supplier arrangements.
Sustainability-oriented sourcing programs are beginning to influence supplier selection as well. Initiatives that align red seaweed procurement with recognized natural-ingredient standards are increasingly referenced as differentiators, particularly in customer segments where environmental claims and responsible sourcing carry commercial weight. The strategic takeaway is that supply resilience is now a function of diversification, certification, and relationship depth, not simply contract negotiation.
Competitive Landscape and Leading Strategies
The carrageenan market features a diverse set of participants spanning global hydrocolloid specialists, ingredient conglomerates, regional manufacturers, and application-focused suppliers. Their strategies reveal how companies are navigating scale, specialization, and compliance in a market that rewards both breadth and precision.
Global Scale and Portfolio Breadth
Several established manufacturers compete primarily through integrated capabilities, multi-type portfolios, and global sourcing infrastructure. Companies with production facilities across multiple regions and certification frameworks are well positioned to serve food, beverage, and personal-care customers with consistent supply and formulation support. Their advantage often lies in the ability to offer Kappa, Iota, and Lambda types within a single supplier relationship, reducing complexity for buyers while maintaining technical continuity across applications.
In this tier, differentiation is less about product novelty and more about reliability, scale, and the depth of technical service. Leadership in this space typically depends on maintaining ISO-aligned manufacturing environments, sustaining supplier and customer relationships across geographies, and reinforcing sustainability commitments that resonate with procurement criteria.
Gellan Gum Market
Specialization and Application Focus
Other participants pursue advantage through narrower focus and application-specific expertise. Specialty hydrocolloid manufacturers and regional producers often emphasize particular customer segments, such as clean-label food systems, pharmaceutical-grade materials, or industrial stabilizers. By concentrating on targeted use cases, these companies can develop deep formulation knowledge, respond quickly to niche requirements, and build strong references within specific industries.
Partnerships also play a meaningful role in this segment. Some suppliers collaborate with seaweed producers or extraction specialists to secure sourcing advantages and strengthen quality control, while others leverage commercial references and application data to reinforce credibility. This strategy can be particularly effective where customers value tailored solutions and closer technical engagement over broad portfolio breadth.
Regional Manufacturing and Sourcing Positionality
Manufacturers based in key seaweed-producing regions benefit from proximity to raw material supply and, in some cases, multi-plant production networks that support export-oriented volume and grade flexibility. For refined and semi-refined grades, this regional positioning can translate into competitive lead times and sourcing adaptability. At the same time, these players must manage the same supply-side risks affecting the broader market, including biological constraints on seaweed cultivation and logistical exposure to trade and freight dynamics.
The global landscape is therefore not a single hierarchy but a set of overlapping competitive models. Some players win on scale and integration, others on specialization and responsiveness, and still others on regional sourcing advantage. The market’s evolution is likely to continue rewarding companies that can combine at least two of these strengths while maintaining compliance and quality assurance as foundational capabilities.
Forward Trends and Commercial Implications
Looking ahead across the next three to five years, several trends are likely to shape how the carrageenan market develops and where commercial opportunities emerge.
Tighter Integration Between Sourcing, Compliance, and Formulation
One of the most durable trends will be the growing interdependence of raw material sourcing, regulatory compliance, and product formulation. As certification expectations rise and application requirements become more specific, suppliers and buyers alike will need to treat these elements as a connected system rather than separate workstreams. Companies with GMP-aligned facilities, traceable sourcing, and application-level technical support will be better equipped to navigate compliance barriers and serve demanding customer segments. For commercial teams, this creates opportunities to differentiate on reliability and service depth, particularly in markets where regulatory complexity is increasing.
Expansion of Application-Specific and Alternative-Protein Solutions
Demand for tailored stabilizer and texturant solutions is likely to remain a growth vector, especially in plant-based, dairy-adjacent, and premium personal-care applications. Product development activity centered on gelling systems, all-purpose stabilizers, and alternative-protein texture optimization points to a market that is moving toward functionality-defined selling. The commercial opportunity lies in pairing ingredient performance with development support, enabling customers to reduce time-to-market and improve formulation consistency. Suppliers that can demonstrate repeatable results across varied processing conditions will capture disproportionate value in this context.
Supply Resilience as a Strategic Differentiator
Given the market’s exposure to seaweed supply constraints and energy cost volatility, supply resilience will increasingly influence purchasing decisions. Buyers are likely to place greater weight on supplier diversification, inventory management, and long-term sourcing commitments. For producers, the ability to demonstrate stable availability, transparent sourcing practices, and responsive logistics can become a competitive advantage even when price remains an important consideration. This trend also raises the strategic importance of balancing regional sourcing dependence with alternative supply pathways and risk-mitigation planning.
At the same time, uncertainty remains. Regulatory directions may shift, raw material conditions may fluctuate, and customer preferences may accelerate or decelerate depending on broader economic and consumer trends. Businesses should therefore treat these forward trajectories as directional signals rather than fixed forecasts, and build flexibility into sourcing, formulation, and partnership strategies.
Actionable Considerations for Decision-Makers
Different roles within the value chain will derive different priorities from the current market environment, but several practical steps stand out across manufacturing, investment, and procurement perspectives.
For Manufacturers and Ingredient Suppliers
- Invest in application-specific technical capability and customer-facing formulation support, as differentiation increasingly depends on demonstrable performance in target use cases rather than generic product availability.
- Strengthen compliance readiness and quality-system visibility, especially where regulatory requirements are becoming more stringent, since certification and audit preparedness can function as commercial entry criteria.
- Diversify sourcing pathways and reinforce supply continuity planning to reduce exposure to regional raw material constraints and energy cost volatility.
For Investors and Strategic Buyers
- Evaluate participants not only on volume and revenue scale but also on compliance infrastructure, application expertise, and sourcing resilience, since these factors are increasingly tied to long-term competitiveness.
- Monitor where product innovation is converging with emerging demand categories, such as plant-based alternatives and premium personal-care formulations, to identify segments with stronger structural growth potential.
- Assess exposure to regulatory shifts and regional supply concentration, recognizing that market leadership may increasingly favor companies with integrated quality and sustainability capabilities.
For Procurement and Formulation Teams
- Expand supplier qualification criteria beyond price and basic specification matching to include manufacturing standards, traceability, and the ability to support application-specific development.
- Build sourcing flexibility through multi-supplier strategies or diversified regional exposure to reduce vulnerability to localized supply disruptions.
- Align ingredient selection with reformulation roadmaps early, so that functionality, labeling, and compliance considerations are addressed before scale-up rather than as afterthoughts.
The carrageenan market is evolving in ways that reward preparedness, technical depth, and strategic sourcing. For organizations that need granular segmentation data, regional demand detail, competitor benchmarking, and customized scenario planning, a more detailed research reference can provide the additional resolution required to translate these strategic signals into operational decisions. Exploring the fuller dataset and tailored analysis can help clarify where to prioritize investment, which supplier relationships deserve closer scrutiny, and how formulation roadmaps should adapt to the next phase of market development.
For detailed analysis of this topic, please visit the official page: Carrageenan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Audit Software Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The audit software market has entered a phase of accelerated expansion, driven by the convergence of digitization, heightened regulatory scrutiny, and the modernization of internal control frameworks. From 2020 through 2025, the market demonstrated resilient growth despite periodic macroeconomic headwinds and shifting enterprise investment priorities. The segment progressed from a mid-eight-figure revenue base to surpass the 1.1 billion threshold by 2025, reflecting a structural transition rather than a temporary uptick. Looking ahead to the 2026-2032 forecast horizon, the trajectory points toward a sustained compound annual growth rate near the low double digits, with projected revenues reaching into the mid-2.4 billion range by 2032. This expansion is not merely a function of more licenses being sold; it reflects a deepening embedding of audit management capabilities into core enterprise risk, compliance, and financial reporting operations.
The market's near-term momentum is underpinned by several structural characteristics. Cloud-based delivery models have achieved a majority share of revenue, signaling that the long-running debate between on-premise control and cloud agility has largely tilted toward scalability, remote accessibility, and integration readiness. Application demand is heavily anchored in financial services, insurance, and banking segments, where the cost of noncompliance and the complexity of audit evidence continue to escalate. Geographically, mature markets continue to dominate revenue concentration, but the growth narrative increasingly depends on emerging adoption in Asia Pacific and other regions where regulatory frameworks are formalizing and where organizations are leapfrogging legacy manual processes. Market concentration metrics indicate that no single vendor commands a dominant monopoly, suggesting ample room for differentiated strategies, vertical specialization, and category creation.
Despite this favorable backdrop, the industry faces several inflection points that will determine which players scale profitably and which encounter friction. First, the dimensionality of audit work itself is expanding faster than historical headcount models can absorb. Regulatory expectations around continuous monitoring, data lineage, external reporting transparency, and third-party risk are compressing audit cycles while raising evidentiary standards. Organizations that rely on fragmented spreadsheets, email-driven coordination, and disconnected control repositories are encountering diminishing returns as audit scopes widen. Second, the talent equation is shifting. Audit functions are contending with specialized labor constraints and rising cost structures, even as organizations demand faster turnaround, broader coverage, and more granular risk insight. Automation and analytics are becoming operational necessities rather than optional enhancements, but integrating these capabilities without disrupting workflows or compromising control integrity remains a complex transition. Third, data governance and platform trust have moved from technical footnotes to commercial imperatives. Audit software must support rigorous compliance postures, including SOC 2 Type II and ISO 27001 orientations, while enabling secure collaboration across internal teams, external auditors, and regulated business units. Platforms that cannot demonstrate these standards in product design, deployment, and operational practice face meaningful friction in enterprise sales cycles.
For decision-makers, the strategic implication is clear: audit software is no longer a point tool for documenting workpapers or scheduling fieldwork. It has become a connective tissue linking controls, evidence, risk assessment, and reporting. The organizations that win in this environment will be those that treat audit systems as an integral part of the control architecture, not an afterthought attached to the close process.
Audit Management Software Systems Market
Key Drivers Shaping the Market
Technology Innovation and the AI Turn in Audit Workflows
The most consequential driver reshaping the market is the infusion of artificial intelligence into audit planning, evidence analysis, and issue management. AI-powered platforms are beginning to reduce manual testing time for internal audit teams, with sector analysis indicating reductions of up to half in certain manual testing contexts. This shift is not simply about speed; it changes what audit functions can realistically cover. When routine evidence collection and repetitive testing steps are automated, teams can redirect attention to judgmental areas, anomaly investigation, and control design effectiveness. Automated audit analytics have also lowered specialized labor requirements for evidence collection and issue tracking, helping organizations maintain coverage without proportionally increasing headcount. These capabilities are particularly valuable in environments where financial reporting standards are evolving and where AI-assisted tools are increasingly used to meet new expectations in audit processes. In practice, this means audit software vendors are competing not only on workflow convenience but on how intelligently their platforms surface risk, prioritize testing, and accelerate reconciliation between control findings and remediation actions.
Another dimension of technological disruption is the convergence of audit, risk, and compliance into unified platforms. Historically, internal audit management, IT risk assessment, ethics and compliance case management, and operational audit tracking often lived in separate systems. The emergence of AI-powered GRC platforms optimized for audit, risk, and compliance workflows reflects a market preference for consolidation. Unified platforms reduce data silos, improve traceability across workstreams, and enable cross-functional analytics that would be cumbersome in fragmented environments. For vendors, this consolidation dynamic raises the stakes on integration depth, data model flexibility, and user experience. For buyers, it creates an opportunity to rationalize tool sprawl while improving the quality of assurance evidence.
PW Consulting
Regulatory and Policy Environment as a Persistent Demand Engine
Regulatory complexity continues to act as a durable catalyst for audit software investment. Financial services, insurance providers, and manufacturing organizations operate under an expanding set of expectations around controls testing, evidence retention, transparency, and continuity of oversight. Platforms must maintain rigorous compliance postures to support audit workflows in regulated industries, and market participants increasingly evaluate software through the lens of auditability, access control, and certification readiness. This is especially relevant for cloud deployments, where data residency, segregation, and third-party assurance are scrutinized more closely. At the same time, policy signals around financial reporting standards are prompting audit teams to adapt their methods and documentation. AI-assisted tooling is enabling teams to keep pace by standardizing analysis, improving repeatability, and streamlining review cycles. The implication is that regulatory pressure is no longer just a compliance cost; it is a catalyst for modernization that favors platforms capable of adapting to new standards without requiring wholesale process redesign.
Demand-Side Shifts in Enterprise Behavior
On the demand side, two behavioral shifts are particularly important. First, the internal audit function is increasingly expected to provide forward-looking assurance and cross-functional insight, not just historical verification. This shift pushes organizations toward platforms that support continuous monitoring, risk-based planning, and issue tracking that connects findings to remediation and governance oversight. Second, collaboration expectations are changing. Audit work increasingly spans internal teams, external auditors, and business process owners. Software that streamlines audit collaboration and improves efficiency gets traction because it reduces handoff friction, shortens review cycles, and improves version control across shared workpapers and assessments. These behaviors are especially pronounced in cloud adoption, where multi-user access, real-time updates, and integration with enterprise data sources become part of the value proposition. As organizations modernize audit operations, they are selecting tools that enable faster planning, more transparent fieldwork, and clearer reporting to audit committees and executive stakeholders.
Cost Structures, Automation, and the Reallocation of Audit Resources
The supply-side cost conversation is evolving as automation reshapes the economics of audit delivery. Manual testing time reductions and lower specialized labor requirements for evidence collection and issue tracking are altering how audit budgets are allocated. Rather than scaling linearly with audit scope, organizations can use automation to expand coverage and maintain quality while moderating the growth in labor intensity. This change benefits both buyers and vendors: buyers can pursue broader assurance programs without proportional cost escalation, and vendors can differentiate through analytics, workflow automation, and intelligent prioritization. However, the transition also raises the importance of change management. Tools that automate portions of the audit process must be introduced in ways that preserve control rigor, align with audit methodology, and support reviewer confidence. The vendors that succeed will be those that package automation within workflows that auditors trust, rather than offering point features disconnected from day-to-day practice.
Competitive Landscape and Leading Strategies
The competitive field in audit software is diverse, spanning established GRC franchises, internal audit specialists, quality and EHS-oriented platforms, and AI-forward analytics vendors. Several companies illustrate the dominant positioning strategies shaping the market.
- One notable trajectory is the move toward AI-powered GRC platforms optimized for audit, risk, and compliance workflows. A recent rebrand of AuditBoard to Optro reflects this direction, introducing a platform designed to centralize audit management, risk assessment, and compliance tools in a more integrated, intelligence-driven experience. The rebrand signals a strategic emphasis on cross-functional assurance, not siloed audit management alone.
- Traditional internal audit management providers continue to play an important role by focusing on the mechanics of planning, fieldwork, and reporting. Platforms such as TeamMate+ remain relevant for teams that value structured audit lifecycle support and mature methodology alignment. The enduring appeal of these solutions lies in their grounding in audit practice and their ability to support standardized workpaper and reporting habits.
- Cloud-native internal audit platforms emphasize controls testing, issue tracking, and a connected cloud experience. These solutions appeal to organizations seeking to modernize audit operations with real-time visibility and streamlined collaboration, particularly where distributed teams and frequent reporting cycles demand accessible, always-on environments.
- Resolver-style platforms bring automated workflows and risk intelligence to internal audit management, highlighting the value of guided workflows, structured issue management, and centralized risk context. This approach is attractive where audit organizations want greater consistency across engagements and stronger linkage between findings and remediation.
- Benchmark Gensuite illustrates the occupational and EHS audit segment, with capabilities for scheduling, staffing, and managing audits alongside repository tools. The emphasis on AI-native EHS audit management in recent positioning underscores how operational audit domains are being reimagined with intelligent workflows and specialized data models.
- Quality management-oriented providers such as Isolocity address audit planning, execution, and compliance certification within QMS and EQMS contexts. Here the audit software value proposition is tightly connected to certification readiness and process quality, not just financial or internal control assurance.
- Caseware showcases the convergence of audit and accounting workflows, with AI-powered platforms supporting engagement workflow and financial reporting. The appeal lies in connecting audit execution with the broader accounting and reporting lifecycle, especially for firms and organizations managing multiple engagements.
- GRC platforms with internal audit modules, such as Onspring, aim to combine automated workflows, analytics, and project management in a single environment. For organizations that want audit functionality embedded in a broader controls and governance framework, this modular approach offers flexibility.
- Oversight Systems represents the analytics-driven angle, using AI-powered financial analytics for risk detection, compliance, and automated audits. This positioning emphasizes anomaly detection and continuous insight, appealing to organizations that want proactive monitoring layered into their audit processes.
The strategic differentiation among these players falls into several recognizable patterns. Some vendors compete on depth of audit methodology and structured lifecycle support, which resonates with audit functions that prioritize rigor, repeatability, and explicit alignment to traditional audit practice. Others compete on platform breadth, embedding audit within GRC, quality, or accounting ecosystems to reduce fragmentation and provide a unified risk and control picture. A third group emphasizes intelligence and automation, seeking to compress manual effort, improve issue prioritization, and enable continuous monitoring through analytics. Each strategy has merit, and the most attractive positioning depends on the buyer's operating model, regulatory exposure, and appetite for workflow consolidation versus modular best-of-breed selection.
Market evolution is playing out through both consolidation and fragmentation dynamics. On one hand, buyers increasingly prefer platforms that reduce tool sprawl and connect audit workflows with risk, compliance, and reporting contexts. This encourages vendors to expand their scope and deepen integrations. On the other hand, specialized segments such as EHS audits, quality certification audits, and engagement-focused accounting workflows continue to support niche solutions with domain-specific functionality. New entrants and repositioning players are also reshaping categories, especially where AI and cloud architecture create opportunities to redefine usability, speed, and insight. Recent product launches and leadership updates in the sector illustrate this activity, including cloud audit releases with next-generation collaboration features and renewed executive emphasis on AI-native audit management in operational contexts. Taken together, the competitive landscape is becoming more application-specific, more intelligence-intensive, and more integrated across related assurance and governance functions.
Future Trends and Commercial Opportunities
From Periodic Audit to Continuous, Risk-Based Assurance
Over the next three to five years, audit software is likely to shift further from periodic, engagement-based execution toward continuous, risk-based assurance embedded in normal business operations. This trend is supported by the growing use of analytics, automation, and unified data models that make ongoing monitoring and testing more feasible. For commercial opportunity, this creates demand for platforms that can prioritize testing based on risk signals, maintain current evidence repositories, and connect control performance to governance dashboards. Organizations that can operationalize continuous insight will be better positioned to manage evolving reporting expectations and to respond faster when control weaknesses emerge. The opportunity lies not just in automation, but in making audit insights more timely, contextual, and actionable for decision-makers.
Platform Consolidation with Domain Depth
A second trend is the continued pressure toward platform consolidation, balanced by demand for domain depth in specific verticals and audit types. Buyers want fewer disconnected tools, but they also want audit workflows that fit financial services, manufacturing, quality management, EHS, or engagement-based accounting contexts. The winning commercial model is likely to combine broad connectivity with strong domain functionality, allowing organizations to standardize core audit processes while retaining the specialized features needed for particular assurance programs. Vendors that can deliver this balance may gain traction in mid-market and enterprise segments alike, especially where evidence integrity, collaboration, and certification readiness matter. Conversely, overly generic platforms risk losing ground to solutions that understand the nuances of specific audit domains and regulatory contexts.
AI as an Operating Assumption, Not a Differentiator
A third trend is the normalization of AI as an operating assumption rather than a standalone differentiator. As AI-assisted tools become more common in audit processes, expectations will rise around reliability, explainability, integration, and auditability of the tools themselves. The commercial opportunity will shift toward vendors that can show how intelligence is embedded in trusted workflows, how data is governed, and how outputs support reviewer judgment rather than replacing it. At the same time, this trend introduces uncertainty. AI adoption can create new questions about model governance, evidence quality, and process ownership, especially in regulated industries where audit integrity is paramount. Organizations will need to evaluate not only what a platform can automate, but how it maintains control over the audit process, supports evidence standards, and remains adaptable as expectations change.
Strategic Implications for Decision-Makers
For executives and strategy teams evaluating audit software, the near-term priority is to align tool selection with the desired operating model of the audit function. Organizations that want faster, more integrated assurance should favor platforms that connect planning, fieldwork, issue management, and reporting in a coherent workflow, with cloud accessibility and collaboration features that match how teams actually work. Those operating in regulated or specialized environments should weigh domain functionality more heavily, including support for relevant certification, controls testing, and evidence standards. In all cases, platform trust matters: buyers should assess how software supports SOC 2 Type II and ISO 27001 orientations and whether its design is compatible with the audit rigor required in their industry.
It Audit Services Market
For investors and market participants, the opportunity is to identify vendors that combine scalable platform economics with credible audit methodology and measurable workflow efficiency gains. The growth trajectory suggests expanding demand, but the more interesting question is which capabilities will become table stakes and which will sustain differentiation. Intelligence-led automation, strong integration, and domain relevance are likely to be durable value drivers, especially where vendors can demonstrate reduced manual effort, better coverage, and clearer issue remediation linkage. At the same time, the market's breadth means that category leadership will be uneven across segments, and the most attractive bets will depend on the specific vertical, deployment model, and regulatory exposure being served.
For procurement and audit leaders navigating vendor selection, the practical focus should be on total workflow fit rather than isolated feature checklists. Key evaluation questions include how well the platform supports risk-based planning, how efficiently it handles evidence collection and issue tracking, how smoothly it enables collaboration with external stakeholders, and how convincingly it supports compliance and security expectations. It is also prudent to consider the vendor's trajectory: recent rebrands, product launches, and leadership shifts can signal where companies are placing bets and how they intend to compete. In a market moving toward AI-enabled, cloud-based, and increasingly consolidated platforms, the most valuable intelligence is the kind that connects product direction with enterprise readiness and segment-specific needs.
For decision-makers seeking a fuller picture of segmentation dynamics, regional adoption patterns, competitive positioning details, and forward scenarios, a comprehensive research report can provide the granularity needed to translate these trends into procurement, investment, and operating decisions. Detailed segmentation splits, company-by-company profiles, and scenario-based sizing help translate market-level momentum into actionable strategy, especially when the choice set spans GRC platforms, internal audit specialists, quality and EHS solutions, and analytics-driven vendors.
For detailed analysis of this topic, please visit the official page: Audit Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Spectrometer Market 2026: Beyond the 7.97% CAGR—Key Drivers Reshaping Growth to $20.38B
By pmarketresearch, 2026-09-21
Spectrometer Market: Strategic Trends and Commercial Opportunities Beyond 2030
The global spectrometer market has entered a phase of sustained expansion driven by converging forces in analytical science, regulatory scrutiny, and technological maturation. From a base of approximately $8.05 billion in 2020, the market has grown to an estimated $11.95 billion in 2025, reflecting consistent demand across pharmaceutical research, clinical diagnostics, environmental monitoring, and industrial quality control. Looking ahead to 2032, the sector is projected to reach nearly $20.38 billion, underpinned by a compound annual growth rate of 7.97 percent. This trajectory signals more than incremental adoption; it points to structural shifts in how organizations deploy analytical instrumentation, integrate data workflows, and respond to tightening compliance requirements. For executives and investors, the question is no longer whether spectrometers will remain central to analytical operations, but how to position portfolios, supply chains, and R&D investments to capture the upside while navigating fragmentation and cost pressures.
Mapping the Current Landscape and Core Friction Points
The market expansion documented over the past half-decade masks underlying complexity. Growth has been fueled by higher instrument utilization in drug discovery and development, expanding proteomics and metabolomics programs, and broader adoption of clinical chemistry and toxicology workflows. At the same time, the industry is confronting several inflection points that will shape competitive outcomes over the next several years.
First, concentration dynamics remain moderate, with the top three players holding roughly 30 percent of total revenue and the top five collectively accounting for about 38 percent. This leaves substantial room for specialized vendors, regional specialists, and new entrants that can differentiate on application-specific performance, service models, or total cost of ownership. The presence of meaningful headroom suggests that scale alone will not guarantee dominance; rather, organizations that can align instrument capabilities with end-user workflows and regulatory traceability will capture disproportionate value.
Second, the cost structure of high-resolution systems continues to be shaped by component-level dependencies. Optical gratings and diffraction elements remain the primary raw material and core components for high-resolution spectrometer systems, with pricing influenced by specialized polymer and metal alloy supply chains. Volatility in these inputs can compress margins or delay product rollouts, especially for vendors relying on custom optics and precision-engineered assemblies. Companies that secure multi-source sourcing strategies, standardize modular optical architectures, or invest in alternative fabrication methods will be better positioned to stabilize pricing and maintain delivery reliability.
Nuclear Magnetic Resonance Spectrometer Market
Third, compliance and performance verification requirements are becoming more entrenched. ISO 17025 accreditation standards for spectrometer performance testing require recalibration every 12 to 24 months to maintain traceability in laboratory and industrial use. This creates recurring revenue opportunities through service contracts and calibration programs, but also raises the operational burden for end users who must manage downtime, documentation, and audit readiness. Vendors that embed automated calibration routines, remote diagnostics, and digital traceability into their platforms can reduce friction and strengthen customer retention.
What Is Driving the Next Wave of Growth
Several interlocking drivers explain why the spectrometer market is advancing at a pace that outpaces many adjacent analytical segments.
Technological innovation and platform convergence are central to the momentum. Recent product introductions illustrate how vendors are pushing into higher-throughput, hybrid, and benchtop formats. At analytica 2026, Bruker highlighted a Fourier 80 benchtop FT-NMR spectrometer and a timsMRMS platform aimed at higher-throughput chemistry laboratories, alongside a mobile FT-IR spectrometer that broadens on-site analytical capabilities. In the same period, Thermo Fisher Scientific unveiled the Orbitrap Excedion hybrid mass spectrometer and the Orbitrap Tribrid Apex mass spectrometer, reinforcing the direction toward hybrid architectures that combine resolution, speed, and multi-modal flexibility. SCIEX added to the momentum by unveiling the novus V55 triple quadrupole mass spectrometer at ASMS 2026, an indication of continued investment in triple quadrupole platforms for targeted quantitative workflows. These launches are not isolated events; they reflect a broader push to make advanced spectroscopy and mass spectrometry more accessible, faster, and easier to integrate into routine operations.
Regulatory and accreditation environments are shaping procurement behavior. Stricter expectations for data integrity, method validation, and instrument traceability are prompting laboratories and industrial users to standardize on platforms that support documented calibration cycles and auditable performance records. The requirement for periodic recalibration under ISO 17025 underscores the importance of service ecosystems and software-enabled compliance. Suppliers that can streamline accreditation preparation, reduce manual intervention, and provide clear performance benchmarks will benefit from extended sales cycles that convert into durable multi-year relationships.
Demand-side change is also reshaping the market. Pharmaceutical and biotech organizations are expanding analytical capacity to support drug discovery and development, while proteomics and metabolomics programs continue to drive adoption of high-sensitivity systems. Clinical chemistry and toxicology workflows are growing as point-of-care and centralized testing models mature. At the same time, industrial users in mining, environmental monitoring, and manufacturing are seeking portable or semi-portable formats that can deliver real-time insights without sacrificing reliability. The broadening of use cases is creating opportunities beyond traditional laboratory settings, particularly where portability, automation, and ease of use can reduce dependency on specialized operators.
Supply chain and cost dynamics are influencing both product design and pricing strategies. The reliance on specialized optical components, metal alloys, and polymer-based gratings ties instrument cost to niche supplier networks. In parallel, the integration of AI-enabled auto-calibration software in portable spectrometers is reducing operator dependency and supporting real-time on-site analysis in mining and environmental applications. This software-driven approach to calibration and performance management can partially offset hardware complexity by simplifying installation, routine upkeep, and field deployment. For vendors, the implication is clear: competitive advantage will increasingly come from bundling hardware with intelligent software, service assurance, and application-specific workflows rather than competing on specifications alone.
Competitive Positioning and the Evolution of the Landscape
The current competitive environment is defined by established players that are extending portfolios across complementary modalities while also targeting specific workflow pain points. Each major vendor is pursuing a distinct angle of differentiation.
Bruker Corporation, headquartered in Billerica, Massachusetts, has been emphasizing versatility across chemistry and bioanalysis. Its recent activity centers on benchtop FT-NMR and high-throughput platforms, positioning the company to serve laboratories that need compact footprints without sacrificing analytical depth. The combination of a benchtop FT-NMR system and a timsMRMS platform points to an intent to capture users who want both structural characterization and high-performance mass spectrometry in closely integrated workflows. The addition of mobile FT-IR capabilities further broadens the company's reach into field-deployable applications, aligning with demand for faster, on-site decision-making.
Thermo Fisher Scientific Inc., based in Waltham, Massachusetts, continues to lean into high-end hybrid and tribrid mass spectrometry architectures. The Orbitrap Excedion hybrid and Orbitrap Tribrid Apex systems highlight a strategy built around resolution, multi-dimensional analysis, and the ability to handle complex samples in demanding research and biopharma environments. By advancing hybrid configurations, the company is targeting users who require flexibility across qualitative and quantitative tasks, along with the throughput needed for large-scale programs. The emphasis on premium architectures positions the firm to serve as a cornerstone supplier for organizations that prioritize analytical performance and long-term platform investment.
Agilent Technologies, Inc., located in Santa Clara, California, maintains a strong focus on gas chromatography and mass spectrometry systems for laboratory analysis. Its strategy appears anchored in reliability, broad application coverage, and integration with laboratory information workflows. By strengthening GC and MS system portfolios, Agilent is reinforcing its role in routine and high-throughput analytical operations where consistency, support, and method robustness are paramount. This positioning appeals to customers who value proven performance across diverse sample matrices and want a familiar ecosystem for method development and operational scaling.
SCIEX, operating under Danaher Corporation in Framingham, Massachusetts, has been advancing targeted quantitative capabilities with a focus on triple quadrupole technology. The novus V55 triple quadrupole mass spectrometer launched at ASMS 2026 illustrates continued commitment to platforms that excel in quantification, regulatory-grade workflows, and routine testing environments. The emphasis on triple quadrupole architecture signals a strategic tilt toward customers who need reproducible quantitation and robust performance for compliance-driven applications.
Shimadzu Corporation, headquartered in Kyoto, Japan, continues to offer mass spectrometry and spectroscopy systems for analytical applications across a broad range of industries. Its approach reflects deep application knowledge and a global service footprint, which supports deployment in both research and industrial settings. By maintaining breadth across spectroscopy and mass spectrometry, Shimadzu is positioned to serve organizations that require multi-technique solutions and consistent regional support.
Waters Corporation, based in Milford, Massachusetts, extends its brand around Xevo series mass spectrometers and LC-MS systems. The focus on liquid chromatography-mass spectrometry integration underscores the importance of combining separation and detection in pharmaceutical, biological, and industrial workflows. Waters' positioning emphasizes performance in biological and small-molecule analysis, along with software and service layers that support data interpretation and operational efficiency.
Together, these players reflect a market that is both consolidated at the top and open to differentiation in the long tail. Consolidation pressures are likely to continue through partnerships, selective acquisitions, and ecosystem bundling, especially where vendors can combine instrumentation with software, service, and application expertise. At the same time, the moderate concentration levels suggest that new entrants and niche specialists can succeed by targeting underserved workflows, regional demand, or specific price-performance thresholds. The key differentiator will be the ability to translate instrument performance into measurable operational outcomes, whether through faster turnaround, lower total cost of ownership, simplified compliance, or more seamless integration with existing laboratory infrastructure.
What to Watch Over the Next Three to Five Years
The next phase of development will be shaped by the interplay of technology, regulation, and end-user expectations. Three trends are particularly significant.
Hybridization and modularity will become more central to product roadmaps. As laboratories seek to handle more complex analyses without expanding footprint or operator burden, platforms that combine high resolution with flexible acquisition modes will gain traction. Modular architectures that allow users to scale capabilities as needs evolve can reduce upfront capital risk and support incremental upgrades. The commercial opportunity here lies in offering platforms that can grow with the customer, supported by software and service layers that preserve performance consistency across configurations.
PW Consulting
Software-defined performance and intelligent calibration will become competitive necessities. AI-enabled auto-calibration software in portable spectrometers is already reducing operator dependency and enabling real-time on-site analysis in mining and environmental applications. Extending similar capabilities across broader instrument classes can shorten setup times, improve reproducibility, and reduce the frequency of manual intervention. For vendors, this creates an opening to differentiate through intelligent workflows, predictive maintenance, and remote performance monitoring. For buyers, it can translate into more consistent results and lower training overhead. The risk is that software features become table stakes quickly, so differentiation must be paired with genuine workflow value and reliable execution.
Regulatory traceability and service ecosystems will increasingly influence purchasing decisions. With ISO 17025 expectations anchoring recalibration cycles and performance verification, customers will favor platforms that make compliance manageable and auditable. This dynamic favors vendors with strong service networks, clear documentation, and digital traceability. The upside is recurring revenue and customer lock-in, but the challenge is executing consistently across geographies and instrument types. Companies that can standardize calibration and verification processes while preserving flexibility for local requirements will be better equipped to scale service operations profitably.
These trends create commercial opportunities for organizations that align product strategy with end-user economics. Laboratories and industrial users will reward solutions that reduce downtime, simplify accreditation, and integrate smoothly into existing data environments. Suppliers that can demonstrate measurable improvements in throughput, reproducibility, and total cost of ownership will be in a stronger position to win share, even in a competitive field. At the same time, potential risks include component cost volatility, uneven adoption of automation across regions, and the possibility that rapid software advancement raises expectations faster than hardware can deliver. Monitoring these dynamics closely will be essential for strategic planning.
Actionable Guidance for Decision-Makers
Manufacturers and technology providers should prioritize differentiation through workflow integration rather than specification competition alone. The current landscape shows that leading vendors are expanding into hybrid, benchtop, and portable formats while also emphasizing service, calibration, and software support. Companies that can align product roadmaps with real-world adoption barriers—such as calibration burden, operator dependency, and compliance documentation—will be better placed to capture demand across both premium and mid-tier segments. It is equally important to secure component supply strategies for optical gratings and diffraction elements, given the sensitivity of high-resolution systems to specialized polymer and metal alloy supply chains. Building sourcing resilience and standardizing modular optical designs can help stabilize margins and improve delivery predictability.
Investors should look beyond headline growth and assess where value is likely to accumulate. The market's moderate concentration suggests that both scaled incumbents and focused specialists can create value, but the basis of advantage differs. Premium hybrid and tribrid platforms can support long-term positioning in high-sensitivity research and biopharma applications, while portable and benchtop systems can open faster-growing field and routine analysis segments. Investors should also weigh exposure to recurring revenue from service, calibration, and software, particularly as accreditation requirements and traceability expectations increase. Finally, competitive risk should be evaluated in terms of ecosystem strength: vendors that can combine hardware, software, and service into a coherent value proposition are more likely to sustain pricing power and customer retention.
X-ray Fluorescence Spectrometer Market
Procurement leaders and end-user organizations should focus on total cost of ownership and operational resilience rather than initial purchase price. Instruments that simplify calibration, reduce downtime, and support documented performance verification can lower hidden costs and improve audit readiness. Procurement teams should evaluate vendor support networks, remote diagnostics, and software-enabled workflows as part of the purchasing decision, especially where ISO 17025-related recalibration cycles and traceability requirements are relevant. For organizations deploying instruments in diverse settings, portability, ease of use, and the ability to operate with reduced specialist involvement can be decisive factors. Aligning procurement criteria with long-term operational goals will help avoid underinvestment in service and support, which can erode the value of otherwise capable hardware.
Strategic decision-making in this market depends on access to granular segmentation data, competitor benchmarking, and regional demand patterns that reveal where adoption is accelerating and where pricing pressure is intensifying. Detailed sector breakdowns, application-level demand signals, and vendor-level positioning can sharpen capital allocation, R&D prioritization, and procurement strategy. For organizations seeking a more comprehensive view of the spectrometer market—including detailed segmentation, competitive analytics, and customized scenario planning—PW Consulting's full research report provides the deeper dataset and tailored insights needed to translate these trends into concrete next steps.
For detailed analysis of this topic, please visit the official page: Spectrometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Molybdenum Powder Market: Why 5.8% CAGR and 3D Printing Reshape Growth to 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Molybdenum Powder Market (2025–2032)
The global molybdenum powder market has entered a phase of structural expansion, driven by a convergence of industrial demand, technological adoption, and shifting supply chain dynamics. From a base valuation of approximately 163.15 million USD in 2020, the market has grown steadily to reach 215.0 million USD in 2025, reflecting a compound annual growth rate of 5.8 percent across the 2026 to 2032 forecast horizon. This trajectory signals more than a cyclical upturn; it points to a recalibration of how specialized metal powders are sourced, processed, and deployed across advanced manufacturing sectors. Understanding the underlying drivers, competitive positioning, and regulatory inflections is essential for executives and investors navigating this evolving landscape.
Market Overview and Contemporary Challenges
The market's expansion over the past five years has been characterized by steady revenue growth, with annual figures climbing from 168.81 million USD in 2021 to 207.98 million USD in 2024, before stabilizing at 215.0 million USD in 2025. Looking ahead, the forecast period projects consistent upward momentum, reaching 233.48 million USD in 2026 and scaling to 344.8 million USD by 2032. This growth is not uniform across all segments, nor is it insulated from macroeconomic and geopolitical friction. Several structural challenges and inflection points are reshaping how stakeholders approach procurement, production, and capacity planning.
- Regulatory volatility and supply chain realignment. Export controls and trade policy shifts have introduced pronounced uncertainty into cross-border flows of molybdenum powder. The imposition of restrictions in early 2025 prompted importers in North America and Europe to accelerate diversification strategies, while a temporary suspension of those controls extended through late 2026 created a window of adjustment rather than a permanent resolution. This regulatory back-and-forth has forced buyers to weigh short-term availability against long-term sourcing resilience.
- Raw material price transmission and margin pressure. Cost dynamics in the upstream concentrate market flow directly into powder pricing, with price increases of approximately 8 to 10 yuan per kilogram observed for every 100 yuan per ton-unit rise in molybdenum concentrate costs. This sensitivity compresses margins for producers who lack vertical integration or long-term feedstock agreements, while simultaneously testing the price tolerance of downstream manufacturers who rely on predictable input costs.
- Segment divergence and capability gaps. Demand is not growing evenly across product types or applications. Regular molybdenum powder continues to anchor the market, but spherical variants and other specialized grades are gaining traction in high-value use cases. Similarly, traditional powder metallurgy applications remain the dominant demand center, while additive manufacturing and other emerging applications are expanding at a faster pace from a smaller base. Companies that cannot bridge the gap between commodity-grade production and precision-grade specifications risk losing share to more technologically agile competitors.
Market concentration remains relatively moderate, with the top three players holding roughly 24.6 percent of total revenue and the top five capturing approximately 26.2 percent. This fragmentation suggests room for consolidation, but it also indicates that no single entity commands disproportionate pricing power. The competitive arena is therefore shaped less by market dominance and more by differentiation in purity, particle morphology, integration depth, and regional supply reliability.
Key Drivers Shaping Market Trajectory
Several interconnected forces are propelling the market forward, each reinforcing the others in ways that create both opportunities and structural shifts.
Technological Innovation and Material Performance Requirements
Advancements in powder production and application engineering are redefining what buyers expect from molybdenum powder. Spherical molybdenum powder, produced through controlled hydrogen reduction and precision milling, offers improved flowability, packing density, and consistency for additive manufacturing and high-performance coating processes. Grain size control in the 0.8 to 6.0 micrometer range, coupled with purity levels reaching 3N and beyond, enables manufacturers to meet tighter tolerances for aerospace components, semiconductor tooling, and high-temperature alloy applications. These technical capabilities are not merely incremental improvements; they open doors to applications where conventional irregular powders fall short, particularly in laser-based powder bed fusion and precision sintering workflows.
The broader trend toward miniaturization, weight reduction, and thermal management in advanced industrial equipment further amplifies the value of high-performance molybdenum powders. As engineers design components that must endure extreme temperatures, corrosive environments, or repeated thermal cycling, the material's intrinsic properties become a critical enabler rather than a substituteable input. This shift elevates the importance of supplier technical support, custom grading, and application-specific formulation capabilities.
Policy, Regulation, and Trade Dynamics
Policy interventions have become a defining factor in market behavior. Export controls introduced in early 2025 on molybdenum-related items, including powder, disrupted established trade routes and prompted procurement teams in the United States and other importing regions to identify alternative sources. The subsequent suspension of the one-year implementation window, effective through November 2026, provided temporary relief but did not eliminate the underlying strategic reorientation. Import volumes in the United States rose by 18 percent in 2025, reflecting both stronger apparent consumption and a deliberate effort to secure supply outside restricted channels.
This regulatory environment encourages a dual-track sourcing strategy: maintaining relationships with established suppliers while building redundancy through regional partnerships, inventory buffering, and qualification of alternative grades. For producers, the landscape rewards transparency, traceability, and the ability to demonstrate compliance with evolving export and import requirements. Companies that can navigate regulatory complexity without compromising delivery reliability are positioned to capture premium contracts and longer-term agreements.
Demand-Side Shifts in Manufacturing and Advanced Applications
End-user behavior is evolving as industries adopt more intensive material specifications and higher-value processing methods. Traditional powder metallurgy remains the largest application domain, supported by steady demand from components used in automotive, industrial machinery, and structural hardware. However, the growth narrative is increasingly shaped by additive manufacturing, where molybdenum powders are evaluated for their suitability in complex geometries, thermal stability, and post-processing performance. Research and commercial quantities of molybdenum powder are also being consumed by semiconductor manufacturing and high-temperature application sectors, where purity and consistency directly influence yield and reliability.
This demand-side evolution pushes suppliers to think beyond volume pricing and toward value-added services. Technical consultation, sample programs, grade customization, and joint development with end-users are becoming differentiators. Buyers are increasingly willing to pay for predictability and performance assurance, especially when production downtime or component failure carries significant cost.
Ferrochrome Powder Market
Supply Chain and Cost Structure Realignment
The link between upstream concentrate pricing and downstream powder costs creates a continuous pressure point that shapes procurement timing, inventory strategy, and contract structuring. When concentrate prices rise, powder prices follow with measurable lag and sensitivity, forcing producers to manage feedstock exposure carefully. Vertically integrated operations that control reduction capabilities and raw material inputs gain a structural advantage in margin stability, while non-integrated suppliers must rely on hedging, long-term agreements, or strategic stockpiling to mitigate volatility.
At the same time, global production volumes have expanded, with total molybdenum production reaching 672.6 million pounds in 2025, a 4 percent increase from the prior year, while usage rose 3 percent to 671.8 million pounds. This near-balance between production and consumption indicates a market that is tightening at the margin, where small disruptions or demand spikes can translate into price movement and allocation challenges. Supply chain resilience is therefore not just a regulatory response but a commercial necessity.
Competitive Landscape and Leading Strategies
The competitive environment features a mix of integrated producers, specialty suppliers, and research-oriented distributors, each pursuing distinct strategic positioning.
- Elmet Technologies operates through fully integrated powder reduction capabilities in the United States, serving alloys, stainless steel, and superalloy applications. This integration supports consistent feedstock control and tailored output for industrial alloy markets, positioning the company as a reliability-focused supplier for demanding metallurgical applications.
- Sumitomo Electric Industries manufactures 3N-purity molybdenum powder with grain sizes ranging from 0.8 to 6.0 micrometers via hydrogen reduction of high-quality raw material. The emphasis on controlled grain size and purity aligns with customers requiring repeatable performance for specialized processing, particularly where particle morphology influences flow and sintering behavior.
- American Elements supplies both commercial and research quantities of molybdenum powder and related metal powders, catering to a broad customer base that spans production-scale buyers and laboratory-scale developers. This dual-channel approach enables the company to capture early-stage demand signals and transition research-grade interest into commercial supply relationships.
- Goodfellow Corporation provides high-purity molybdenum powder up to 5N for semiconductor manufacturing, aerospace, and high-temperature applications. The focus on ultra-high purity and application-specific support targets segments where contamination control and material consistency are non-negotiable, allowing the company to compete on performance rather than volume.
- Stanford Advanced Materials supplies molybdenum metal powder for fabricated metal processing and industrial applications, emphasizing accessibility and broad industrial coverage. This positioning supports customers who need dependable supply for standard processing workflows and volume-oriented procurement.
- G K Min Met Alloys Co manufactures pure molybdenum powder as a core product for industrial use, anchoring its offering in purity and industrial applicability. The company's focus on pure-grade powder serves buyers seeking a straightforward, performance-reliable input for conventional powder metallurgy and related processes.
These players illustrate a market where differentiation is achieved through purity tiers, particle engineering, integration depth, and application specialization rather than sheer scale. The moderate concentration levels suggest that consolidation is possible, particularly as buyers seek fewer, more reliable supply partners amid regulatory and cost volatility. At the same time, new entrants with capabilities in spherical powder production, advanced hydrogen reduction, or niche high-purity segments can carve out positions by addressing unmet specifications. The trend is therefore one of selective convergence: larger, integrated players may absorb specialized capabilities, while focused suppliers compete on technical precision and customer proximity.
Future Trends and Commercial Implications (2026–2032)
Looking ahead, several trends are likely to shape the market's evolution and create distinct commercial opportunities.
Worldwide Ammonium Molybdate Market
- Additive manufacturing and high-purity specialization will accelerate premium segment growth. As 3D printing and advanced coating processes mature, demand for spherical and high-purity molybdenum powders is expected to outpace the broader market average. Suppliers that can guarantee tight grain size distributions, low contamination, and reproducible batch performance will capture higher-margin contracts. The commercial opportunity lies in building application-specific grade portfolios, offering technical co-development, and establishing qualification pathways that reduce customer adoption friction.
- Regional supply diversification will become a standard procurement posture. Regulatory controls, import volume increases, and concentrate cost sensitivity are pushing buyers to construct multi-region sourcing strategies. Over the next few years, this will favor suppliers with transparent compliance records, flexible logistics, and the ability to provide alternative grades without compromising performance. Companies that invest in regional inventory hubs, long-term offtake agreements, and clear traceability will be better positioned to secure supply in volatile conditions.
- Vertical integration and feedstock control will separate margin performers from price-takers. The direct transmission of concentrate price movements into powder pricing means that companies with integrated reduction capabilities or secured feedstock channels will enjoy greater margin stability. This dynamic encourages strategic partnerships, capacity expansion in integrated facilities, and long-term contracts that lock in raw material economics. For buyers, it means evaluating supplier resilience as part of total cost of ownership, not just unit price.
These trends carry inherent risks and uncertainties. Regulatory timelines may shift again, altering the pace of diversification and the cost of alternative sourcing. Concentrate price volatility can compress margins unexpectedly, especially for producers without hedging mechanisms. Technical adoption in additive manufacturing and high-purity applications may progress faster or slower than anticipated, depending on downstream equipment compatibility, certification requirements, and total cost comparisons with conventional alternatives. Stakeholders should therefore treat these trends as directional signals rather than fixed forecasts, and build flexibility into capacity, inventory, and supplier qualification strategies.
Strategic Recommendations for Decision-Makers
Different stakeholder groups can extract actionable value from the current market dynamics by aligning strategy with the underlying drivers.
For manufacturers and producers:
PW Consulting
- Evaluate vertical integration or long-term feedstock arrangements to reduce exposure to concentrate price swings and stabilize margin profiles.
- Invest in spherical and high-purity grade capabilities where application demand is growing faster than the commodity segment, and build technical support infrastructure to accelerate customer qualification.
- Develop multi-region supply options and transparent compliance documentation to meet buyer expectations for resilience and traceability amid regulatory uncertainty.
For investors and strategic planners:
- Focus due diligence on suppliers with differentiated technical capabilities, integration advantages, and demonstrated ability to navigate regulatory shifts without supply disruption.
- Monitor segment-level demand signals, particularly in additive manufacturing and high-purity applications, as leading indicators of margin expansion and premium pricing potential.
- Assess consolidation opportunities where fragmented supply bases and buyer demand for reliability create conditions for strategic acquisitions or partnerships.
For procurement and supply chain leaders:
- Adopt dual-track sourcing strategies that balance cost efficiency with resilience, including qualified alternative suppliers, strategic inventory buffers, and flexible grade substitutions where performance allows.
- Incorporate total cost of ownership metrics that account for regulatory risk, delivery reliability, and technical support, rather than relying solely on unit price comparisons.
- Engage suppliers early in qualification and joint development processes to secure capacity, lock in specifications, and reduce lead-time exposure during periods of demand acceleration.
The molybdenum powder market is moving through a period where technical differentiation, regulatory agility, and supply chain resilience determine competitive outcomes. Stakeholders who align their strategies with these forces can capture growth in premium segments, stabilize margins amid cost volatility, and build sourcing postures that withstand policy shifts. For executives and investors seeking deeper segmentation data, regional dynamics, and customized strategic scenarios, comprehensive research reports provide the granularity needed to translate these directional insights into precise, executable plans.
For detailed analysis of this topic, please visit the official page: Molybdenum Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com