

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
Pharmaceutical Equipment Market: Why 7.5% CAGR and Regional Shifts Change Everything
By pmarketresearch, 2026-09-21
Navigating the Pharmaceutical Equipment Market: Strategic Trends and Commercial Opportunities (2025–2032)
The global pharmaceutical equipment market is entering a phase of sustained, structurally driven expansion. Valued at approximately USD 169.3 million in 2025 , the sector is projected to reach USD 279.8 million by 2032 , translating to a compound annual growth rate of 7.5% across the 2026–2032 forecast window. This trajectory follows a consistent upward march from USD 120.45 million in 2020 , reflecting a market that has not merely recovered from supply chain disruptions but has fundamentally upgraded its operational baseline. Growth is no longer episodic; it is being embedded into capacity planning, compliance infrastructure, and technology adoption cycles. For executives and investors, the central question has shifted from whether demand will hold to which segments, geographies, and strategic positions will capture disproportionate value as the market matures.
Behind the headline figures lies a more complex reality. The sector is navigating a convergence of heightened regulatory stringency, rapid automation mandates, and divergent regional capacity builds. Companies that treat equipment procurement as a purely tactical capital expenditure are increasingly exposed to bottlenecks in validation, integration, and lifecycle support. Conversely, organizations that align equipment strategy with broader manufacturing resilience and compliance roadmaps are positioning themselves to scale output without proportional increases in risk or overhead. The following analysis unpacks the structural drivers, competitive dynamics, and forward-looking shifts that will define commercial decision-making over the next several years.
PW Consulting
Market Landscape: Growth Trajectory and Structural Headwinds
A Market Accelerating on Consistency, Not Spikes
The expansion pattern from 2020 through 2025 demonstrates a market that has moved past recovery-mode volatility and settled into a more predictable, demand-led cadence. Year-over-year progression has been steady, with each successive period adding meaningful increments to the base. This consistency matters strategically: it signals that procurement cycles are lengthening, validation timelines are being planned further in advance, and capital allocation is increasingly tied to multi-year capacity roadmaps rather than reactive 주문을. A 7.5% CAGR over the coming seven years implies that the market will roughly double in scale, a rate that outpaces many broader industrial equipment categories and reflects the specific weight of compliance-driven capital renewal and throughput upgrades.
The revenue composition also reveals where operational priorities are crystallizing. Oral solid dosage processing, blending and mixing operations, and separation technologies continue to anchor core production workflows, while sterilization and controlled-environment equipment underscore the non-negotiable nature of contamination control. These categories are not competing for the same budget pools; they are complementary layers of a modern manufacturing stack. As facilities seek to reduce changeover times, improve batch consistency, and meet increasingly granular audit expectations, the integration of these functional units into cohesive lines is becoming a competitive differentiator rather than a convenience.
The Three Critical Junctures Shaping the Next Cycle
First, regulatory qualification is no longer a post-purchase formality; it is a design constraint. Equipment that cannot be seamlessly documented through installation, operational, and performance qualification protocols introduces schedule risk and audit exposure. The industry context confirms that major regulatory frameworks continue to reinforce a documented qualification lifecycle with pre-defined acceptance criteria, making validation readiness a procurement prerequisite rather than an afterthought. This shifts bargaining power toward suppliers who can provide traceable documentation packages, modular calibration architectures, and lifecycle support that extends well beyond delivery.
Second, the tension between throughput ambitions and quality assurance is intensifying. High-output automation promises faster cycle times and lower per-unit costs, but it also compresses the margin for error. Facilities operating at higher speeds must demonstrate that process controls, in-line inspection, and environmental monitoring hold steady under continuous load. The commercial implication is clear: equipment that enables speed without compromising verifiable quality will command premium positioning, while solutions that trade one for the other will face increasing resistance during technology transfer and scale-up reviews.
Third, geographic capacity distribution is rebalancing. While established markets continue to upgrade existing lines and consolidate upstream processing, emerging manufacturing hubs are expanding foundational infrastructure at a pace that reshapes where procurement dollars flow. This divergence creates a bifurcated demand environment: mature regions prioritize modernization, compliance harmonization, and line integration, while newer capacity centers focus on core equipment deployment, operator training, and foundational qualification. Suppliers that can tailor deployment models, documentation depth, and after-sales support to these distinct profiles will capture broader share than those applying a uniform go-to-market approach.
Core Drivers Reshaping Demand and Investment Logic
Technology Innovation as a Throughput-and-Compliance Multiplier
Equipment design is increasingly converging around three technical imperatives: precision dosing and blending repeatability, closed or semi-closed processing to limit cross-contamination, and modular architectures that simplify changeovers and qualification. rotary tablet presses, fluid bed systems, and advanced encapsulation platforms are being engineered to sustain high output while reducing variability in critical quality attributes. At the same time, sterilizers, dry heat ovens, and autoclave systems are being refined to shorten cycle times without sacrificing thermal uniformity or documented process control. These innovations are not incremental; they directly affect batch release cadence, rework rates, and the cost of quality, making equipment selection a lever for both capacity and margin improvement.
The commercial ripple is significant. Manufacturers are increasingly evaluating total cost of ownership through the lens of validation effort, line integration complexity, and lifecycle service availability rather than sticker price alone. Equipment that arrives with pre-validated subsystems, clear user requirement specification alignment, and documented acceptance pathways reduces the hidden costs of commissioning. In practical terms, this means that suppliers offering engineered interoperability, standardized documentation packages, and predictable uptime profiles are gaining preference in competitive evaluations, even when upfront pricing is not the lowest.
Regulatory Tightening as a Catalyst for Capital Renewal
Policy and guidance continue to raise the floor for equipment qualification and process control. Across major jurisdictions, expectations around documented qualification lifecycles, calibration discipline, cleaning verification, and pre-defined acceptance criteria have become deeply embedded in good manufacturing practice frameworks. The direction is not toward more paperwork for its own sake; it is toward verifiable consistency that can withstand regulatory review and internal audit scrutiny. For equipment buyers, this environment favors platforms that are designed with qualification in mind from the outset, including accessible instrumentation, traceable configuration records, and service intervals that align with compliance calendars.
This regulatory rhythm also influences renewal timing. Facilities that originally commissioned equipment under less stringent expectations increasingly find that retrofitting or supplementing legacy lines is more disruptive than planned upgrades. As a result, capital cycles are being synchronized with compliance strategy: organizations are choosing to replace or augment equipment not only when output demands it, but when validation burden, audit findings, or process variability make continuation uneconomical. This dynamic supports the broader growth outlook while shifting the purchase trigger from pure volume expansion to a combined quality-and-capacity rationale.
Demand-Side Shifts in Manufacturing Footprints and Product Mix
On the demand side, product portfolios are diversifying in ways that stress equipment flexibility. The continued emphasis on oral solid dosage forms keeps tableting, blending, and encapsulation lines busy, but there is also growing interest in formats that require careful handling, controlled environments, or rapid line reconfiguration. At the same time, manufacturing footprints are being rethought in response to supply chain risk, regional incentive programs, and the desire to shorten time-to-market for key therapeutic categories. The result is a broader set of buyer priorities: not just throughput, but agility, documentation readiness, and the ability to run smaller, higher-value batches with minimal disruption.
Behaviorally, procurement teams are becoming more deliberate. Longer lead times for integrated lines, more complex qualification coordination, and greater internal expectations for lifecycle reliability are pushing buyers to involve engineering, quality, and operations earlier in the selection process. This multi-stakeholder buying cycle favors suppliers who can demonstrate process understanding, provide realistic deployment timelines, and offer post-installation support that addresses operational learning curves. Equipment that appears competitive in a spec sheet but underperforms in commissioning or operator onboarding is increasingly filtered out before final selection.
Cost Structure and Supply Chain Realignment
Cost dynamics are being reshaped by energy efficiency expectations, component availability, and the economics of integration. Energy-intensive thermal and sterilization equipment is under greater scrutiny, pushing suppliers and buyers alike to evaluate cycle optimization, insulation performance, and control precision as cost levers rather than mere technical specifications. At the same time, the cost of integration—engineering alignment, qualification documentation, and startup support—is becoming a larger share of total project spend. This has two strategic consequences: first, buyers are more willing to pay for reduced integration risk; second, suppliers that bundle deployment, training, and documentation into a coherent package can differentiate on total project predictability rather than discrete hardware pricing.
Supply chain stability also matters more than before. Components that affect calibration stability, sealing integrity, or control reliability can create cascading delays if unavailable at the right specification. The implication for the market is a gradual preference for equipment architectures that reduce single-point dependencies, simplify spare parts management, and allow phased commissioning when full-line delivery is constrained. In an environment where production schedules are tightly linked to commercial commitments, resiliency in equipment design and supplier support becomes a direct contributor to revenue assurance.
Competitive Dynamics: Positioning, Differentiation, and Market Evolution
How Leading Players Are Composing Their Advantage
The competitive landscape is anchored by firms that have built capabilities across processing, filling, and packaging, but their strategic emphasis differs in ways that matter for buyers and investors. German and Italian engineering-origin companies tend to lean into integrated line architecture, high-speed automation, and documentation rigor that aligns with demanding regulatory environments. Their value proposition often centers on end-to-end consistency: conveying, filling, sealing, and packaging units designed to operate as a coordinated system with shared control logic and streamlined qualification pathways. This integration advantage reduces interface risk and can shorten commissioning timelines when lines are scoped holistically rather than assembled from disparate vendors.
Worldwide Pharmaceutical Equipment Maintenance Services Market
At the same time, firms with strong positions in oral solid dosage equipment emphasize throughput precision, batch repeatability, and modular flexibility for tableting, blending, encapsulation, and coating workflows. Their differentiation frequently lies in maintaining tight control over critical processing parameters while enabling changeovers that do not destabilize quality attributes. Suppliers with specialized strength in liquid handling, vial filling, and bio-processing platforms add another layer of relevance by addressing products that require aseptic discipline, closed processing, and sensitive containment. In practice, this segmentation means that competitive advantage is increasingly defined by how well a company can match a specific product risk profile with the right combination of mechanical precision, environmental control, and documentation support.
Strategic positioning also extends to how companies engage with customers beyond the sale. Trade presence, technical forums, and application-focused demonstrations have become important channels for communicating capability in context rather than in isolation. Participation in industry events allows suppliers to showcase line integration concepts, sanitation-friendly designs, and high-output automation in front of buyers who are actively comparing configuration options. For the market overall, this shifts competition toward proven applicability: the ability to show how equipment behaves under realistic batch sizes, changeover patterns, and qualification expectations becomes a stronger deciding factor than brochure performance alone.
Market Structure: Consolidation Pressure and Segment Differentiation
Concentration in the sector suggests that a relatively small group of large players commands a substantial share of revenue, yet the market remains open enough for specialized entrants and regional specialists to compete on configuration, responsiveness, and application fit. This combination is creating two simultaneous pressures. First, larger players are incentivized to deepen integration across processing and packaging to capture the premium associated with reduced interface risk and more predictable qualification outcomes. Second, smaller or regionally focused firms are finding room by offering highly tailored solutions, faster local support, or cost-competitive configurations for specific dosage forms and facility types. The practical outcome is a market that is not simply consolidating into a single model, but differentiating into tiers of capability that serve distinct risk and budget profiles.
Evolution is also being shaped by how buyers allocate projects. Integrated, multi-unit lines tend to favor suppliers with broad portfolios and robust service networks, while point-solution purchases—such as a single tablet press, a blender upgrade, or a sterilization unit—can be won on application expertise, lead-time reliability, and documentation fit. This dual structure means that competitive success increasingly depends on both breadth and depth: the ability to propose a cohesive architecture when needed, and the credibility to deliver a focused solution when that is the smarter choice. Over time, this will likely encourage partnerships, selective acquisitions, and service expansions that widen each player’s effective footprint without requiring every vendor to own every capability end to end.
Forward Outlook: Three Trends That Will Shape 2027–2032
Trend 1: Qualification-by-Design Becomes a Default Expectation
Over the next several years, equipment that is designed with qualification documentation, calibration accessibility, and acceptance criteria traceability embedded into its architecture will move from preferred to expected. As audit scrutiny persists and internal quality systems mature, the cost of retrofitting documentation or reworking qualification packages will increasingly outweigh any upfront savings from less-prepared platforms. Commercial opportunity lies in solutions that reduce the friction of installation qualification, operational qualification, and performance qualification through standardized protocols, clear user requirement alignment, and service models that maintain compliance readiness across the lifecycle. Buyers who plan qualification timelines alongside equipment selection will compress project risk; suppliers who deliver that alignment will capture preference in contested evaluations.
Trend 2: High-Speed, High-Containment Lines Will Redefine Throughput Economics
The push for higher output will continue, but the definition of success is broadening to include containment integrity, inspection reliability, and minimal deviation under sustained load. Lines that combine fast cycle times with robust environmental control and in-line verification will offer a more defensible economics case than speed alone. This trend opens opportunities for vendors that can demonstrate how automation, vision inspection, and controlled processing work together to maintain quality at scale. It also raises risk for solutions that chase throughput without equivalent controls, since scale-up failures and batch variability can erase apparent efficiency gains.
Trend 3: Regional Diversification Will Create Tiered Procurement Patterns
As manufacturing capacity spreads across more regions, procurement behavior will increasingly reflect local priorities: foundational equipment deployment in newer hubs, and modernization, integration, and compliance harmonization in established markets. This will produce a tiered market in which the same functional category may be evaluated under different criteria depending on facility maturity, regulatory exposure, and operator experience. The strategic opportunity is to match deployment models—documentation depth, training intensity, spare parts logistics, and on-site support—to the specific context rather than assuming a one-size approach. The associated risk is misalignment: offering a highly integrated, documentation-heavy solution in a setting that prioritizes rapid deployment and affordability, or vice versa, can weaken commercial outcomes even when the equipment itself is sound.
Strategic Actions for Decision-Makers
For Manufacturers and Business Leaders
- Treat qualification readiness as a procurement gate. Evaluate equipment against documentation traceability, calibration access, and acceptance-criteria clarity early in the selection process to reduce commissioning risk and audit exposure.
- Prioritize integration over isolated spec optimization. Where feasible, scope processing, filling, and packaging as a coordinated system to minimize interface gaps, shorten validation coordination, and improve line predictability.
- Plan capacity expansion around product risk profiles. Align equipment type and automation level with the containment, inspection, and environmental requirements of the specific dosage forms and product mixes you intend to run.
For Investors and Strategic Allocators
- Focus on lifecycle value, not just unit pricing. Companies that combine engineering depth with deployment support, documentation packages, and service reliability are better positioned to defend margins and win contested projects.
- Watch for integration-led consolidation. Value is migrating toward suppliers that can reduce interface risk across processing and packaging; this creates advantages for broad-portfolio players and for regional specialists that can partner effectively into integrated projects.
- Map regional demand tiers. Recognize that growth will not be uniform: mature markets will reward modernization and compliance alignment, while emerging hubs will drive foundational equipment demand and operator-dependent deployment models.
For Procurement and Quality Leaders
- Engage engineering, quality, and operations earlier. Multi-stakeholder evaluation reduces the likelihood of selecting equipment that performs well on paper but creates friction during qualification, startup, or operator training.
- Standardize acceptance criteria before bidding. Clear user requirement specifications and pre-defined acceptance parameters improve vendor comparisons and lower the probability of post-delivery rework.
- Model total project cost with integration and validation in scope. Including commissioning, documentation, training, and spare-parts logistics in the evaluation framework produces a more realistic comparison of commercial offers.
The pharmaceutical equipment market is evolving from a transactional hardware environment into a strategically integrated, compliance-informed capital arena. Growth at a 7.5% CAGR through 2032 reflects more than incremental demand; it reflects a structural upgrade in how manufacturers think about throughput, quality assurance, documentation, and regional capacity. The winners in this environment will be those who align equipment decisions with broader operational and compliance roadmaps, and those who can demonstrate that alignment under realistic project conditions. For decision-makers seeking deeper segmentation detail, company-level positioning data, and customized deployment scenarios, the full PW Consulting research report provides the granular breakdown and tailored recommendations needed to translate these trends into actionable plans.
Semiconductor Equipment Market
For detailed analysis of this topic, please visit the official page: Pharmaceutical Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Motorcycle Apparel Market 2026: Why a 6.5% CAGR Hides Real Growth Drivers
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Motorcycle Apparel Market
The global motorcycle apparel sector is navigating a period of structural transformation, driven by evolving safety standards, material science breakthroughs, and shifting rider demographics. Market valuation reached approximately 263.0 million USD in 2025, expanding from a 2020 baseline of 207.45 million USD. Projections indicate the segment will scale to 404.7 million USD by 2032, reflecting a compound annual growth rate of 6.5 percent across the 2026-2032 forecast window. This trajectory underscores a market that is no longer defined solely by traditional riding gear cycles, but rather by sustained expansion fueled by functional innovation, regulatory realignment, and cross-regional demand generation.
Beyond headline growth figures, the sector is characterized by meaningful concentration dynamics. The top three players account for 48.2 percent of market revenue, while the top five collectively represent 65.3 percent. This concentration pattern suggests established incumbents hold considerable pricing leverage and distribution advantages, yet also leaves substantial runway for specialized manufacturers, regional challengers, and technology-integrated brands to capture differentiated positioning. The market is large enough to support multiple strategic plays, but competitive execution increasingly depends on how quickly organizations translate material, design, and compliance capabilities into rider-centric product architectures.
Current Market Structure and Key Inflection Points
The market is anchored by a product mix that prioritizes upper-body protection, with jackets representing the largest revenue contributor among apparel categories. Pants, gloves, footwear, base layers, and complementary accessories round out a diversified hardware ecosystem that serves both daily commuters and performance-oriented riders. Application-wise, on-road motorcycle apparel commands the largest share, reflecting the broader base of street riders, touring enthusiasts, and urban commuters who prioritize visibility, weather protection, and ergonomic fit. Off-road motorcycle apparel constitutes a meaningful secondary segment, sustained by adventure riding growth, enduro participation, and crossover demand from consumers who blend trail performance with road usability.
Regionally, Asia Pacific leads in absolute market scale, followed by Europe, Latin America, the Middle East and Africa, and North America. Each geography carries distinct demand drivers, ranging from motorcycle ownership penetration and commuting patterns to regulatory frameworks and weather-specific gear requirements. Rather than competing purely on price, successful players are differentiating through regional fit, climate-adaptive designs, and localized compliance alignment.
Three structural inflection points are reshaping how operators should think about the market:
- Safety as a baseline expectation rather than a premium feature. Riders increasingly assume impact protection, abrasion resistance, and ergonomic articulation as standard requirements. This shifts competitive differentiation away from basic protective function toward comfort, weight reduction, ventilation, and lifestyle integration.
- Regulation and classification pressure on supply chains. Standards such as Federal Motor Vehicle Safety Standard No. 218 and CE certification requirements are reinforcing the need for purpose-built protective clothing. At the same time, customs classifications that distinguish motorcycle-specific protective apparel from general-use garments affect sourcing strategies, tariff exposure, and product positioning.
- Material convergence between industrial, outdoor, and riding applications. Heavy denim and reinforced fabrics once associated primarily with workwear or outdoor use are being adapted for riding gear, blurring category boundaries and opening new design and sourcing pathways. This convergence creates opportunities for performance blends, enhanced durability, and cost-efficient material strategies, while also raising the bar for product validation and authenticity of use-case claims.
Core Growth Drivers Shaping the Market
Innovation in protective technology is one of the most consequential drivers in the sector. Impact protection is moving from add-on inserts to integrated system design, with advanced protective foams and engineered armor now appearing as standard elements across race, adventure, and road product lines. This transition matters because it changes the value proposition at the point of purchase: riders are increasingly evaluating fit, mobility, climate control, and protective coverage as a unified package rather than treating armor as an after-market consideration. In practice, brands that can standardize advanced protection across a large share of their range build both credibility and repeat-purchase momentum, especially in categories where safety perception directly influences buying decisions.
Regulatory and compliance dynamics reinforce this shift. Helmet and protective clothing standards are increasingly tied to fatality and injury reduction goals, and protective apparel is expected to meet defined certification frameworks. CE certification remains a critical benchmark for motorcycle protective clothing and gear, while national safety standards continue to shape what can be marketed as purpose-built riding equipment. These frameworks influence product development cycles, testing requirements, and market access. For manufacturers, compliance is no longer a back-office activity; it is a product strategy variable that affects design choices, material selection, and even packaging and labeling language.
Riding Gear Market
Demand-side behavior is also evolving. Riders are seeking apparel that performs across more use cases, including commuting, weekend touring, and light off-road exposure. This multi-use expectation favors versatile construction, modular layering, and seasonal adaptability. At the same time, fashion adjacency remains relevant, particularly in segments where riders treat motorcycle jackets and pants as part of broader wardrobe choices. The result is a dual demand structure: one strand prioritizes technical performance and certified protection, while another values styling, brand heritage, and everyday wearability. Companies that can balance both without compromising protective integrity are better positioned to expand their addressable audience.
Supply chain and cost structure changes add another layer of complexity. Raw material choices increasingly determine both performance outcomes and commercial resilience. Heavy denim fabrics, for example, are used by motorcycle apparel brands for protective riding gear, and heavy-duty denim garments for industrial and outdoor applications represent a substantial share of total heavy-duty denim usage, with motorcycle apparel brands incorporating similar materials. This overlap matters because it affects sourcing flexibility, cost negotiation, and the ability to scale reinforced textiles without sacrificing protective performance. Brands that diversify material sources, validate alternative textile constructions, and design for manufacturability can reduce exposure to single-source dependencies while preserving product integrity.
Motorcycle Gear Market
Competitive Landscape and Leading Strategic Positions
The competitive field blends legacy motorcycle heritage brands, technical apparel specialists, and protection-technology partners. Harley-Davidson, Inc. leverages its MotorClothes® and apparel line to connect riding gear directly with brand identity and a broad consumer base. Tourmaster operates with a broad accessory and apparel focus, extending from motorcycle apparel and heated apparel to gloves, motorcycle luggage, and covers, which creates cross-category relevance for riders seeking integrated gear solutions. Aerostich continues to emphasize equipment for motorcycle and scooter riders, reinforcing a design-led approach to riding-specific gear.
RST has built a clear technical differentiation path by integrating advanced impact protection as a standard feature across its range. In March 2026, RST launched a new apparel collection with 80 percent of the line featuring advanced D3O armor as standard across race, adventure, and road categories. This move signals a strategy centered on protection parity and rider confidence, rather than limiting premium protection to select premium SKUs. Acerbis took a different route in May 2026 by introducing a new denim line with four certified technical models designed for everyday commuting. That launch points to a growing commercial interest in bridging everyday fabric aesthetics with certified technical performance, especially for urban riders who want protective gear that does not read as purely specialized riding equipment.
Belstaff continues to position around men's motorcycle clothing, jackets, and gear tied to movement and lifestyle, reinforcing the appeal of heritage, fit, and stylistic credibility. D3O Lab's role in the ecosystem underscores the importance of protection technology as a shared infrastructure across apparel makers. By developing advanced impact protection technology integrated into motorcycle apparel, technology partners enable multiple brands to raise protective standards without each having to invent proprietary armor systems from scratch. This creates a layered competitive dynamic: apparel brands compete on fit, design, range breadth, and rider experience, while technology suppliers compete on performance characteristics, integration ease, and certification compatibility.
Several broader patterns are visible in how the landscape is evolving:
PW Consulting
- Integration of protection into standard assortments. Leading players are increasingly making advanced protective features part of the core range rather than confining them to high-margin or specialist products. This expands the practical reach of improved safety and normalizes higher protection expectations across price tiers.
- Category blending for everyday use. Releases such as certified denim models for commuting reflect a strategic push to reduce the psychological and aesthetic gap between protective gear and daily wear. This broadens the potential buyer pool and supports repeat usage in urban settings.
- Trade shows and product visibility as launch infrastructure. Events such as the Moto Austria 2026 exhibition, which featured a large selection of clothing and accessories, remain important for assortment signaling, retailer engagement, and trend confirmation. Visibility at these venues is increasingly tied to how clearly a brand communicates protection credentials, material innovation, and use-case versatility.
- Concentration with room for targeted disruption. While the market remains relatively concentrated, the presence of distinct strategic plays—heritage branding, heated and accessory ecosystems, armor integration, and certified commuter wear—indicates that differentiation is still achievable through product definition rather than scale alone.
Future Outlook: Three Strategic Trends for the Next 3-5 Years
Protection is likely to become more standardized across mainstream assortments. As more ranges adopt advanced armor and impact protection as default elements, the market will gradually shift from "optional upgrade" to "expected baseline." For commercial strategy, this means the value of protection alone may compress as a differentiator, while the value of integration quality—fit, weight distribution, ventilation, and washability—increases. Brands that make protection comfortable and unobtrusive will benefit from higher adoption and better rider compliance.
A second trend is the continued narrowing of the gap between protective gear and everyday apparel. Certified technical denim, versatile commuting jackets, and adaptable base layers suggest that motorcycle apparel will keep expanding into routine wear contexts. This opens opportunities for seasonal colorways, urban styling, and multi-environment performance, but it also raises the importance of maintaining authentic protective claims. Consumers and retailers will likely become more attentive to whether a product truly meets riding-specific performance expectations or merely borrows the appearance of motorcycle gear.
A third trend involves regulatory and classification scrutiny becoming more operationally relevant. Standards that define protective clothing and gear can influence product labeling, marketing language, and cross-border trade treatment. Customs classification decisions that distinguish motorcycle-specific protective apparel from general-use garments can affect sourcing choices and cost structures, especially when supply chains rely on materials or manufacturing bases in multiple regions. Companies that proactively align product definitions, testing documentation, and sourcing strategy with regulatory reality will face fewer friction points and greater commercial predictability.
These trends point to concrete commercial opportunities, but they also carry uncertainty. Material and protection innovation can create differentiation quickly, yet they can also raise cost structures and lengthen development cycles. Category expansion into everyday wear can increase demand, yet it can also invite scrutiny if protection claims are not clearly supported. Concentration among leading players can stabilize the market, yet it may also make it harder for smaller entrants to secure shelf space, distribution partnerships, or retailer attention without a sharply defined niche.
Implications and Action Steps for Decision Makers
For apparel manufacturers, the most useful priority is to treat protection, comfort, and styling as a single design equation rather than separate workstreams. Product lines that standardize advanced impact protection while maintaining fit for long rides, ventilation in warmer conditions, and aesthetic versatility for daily use are better aligned with where demand is heading. Equally important is material strategy. Manufacturers should evaluate reinforced textile options, validate alternative sourcing pathways, and ensure that product claims match the use cases they intend to serve. Clear documentation of certification status and intended application can reduce commercial risk and support retailer confidence.
For investors, the market presents a nuanced picture. Growth is steady and the addressable base is expanding, but value creation will likely favor companies with defensible differentiation rather than those competing primarily on volume or price. Attention should be given to brands that can demonstrate repeatable protection integration, credible compliance positioning, and product breadth across on-road and off-road applications. It is also worth monitoring how technology partners and apparel brands interact, since protection technology can be a multiplier for multiple competitors at once. The strategic question is not only which companies are growing, but which are building durable advantages in product definition, rider trust, and supply chain resilience.
For procurement and sourcing leaders, the priority is to align material selection with both performance and trade realities. Sourcing decisions should account for protective textile availability, certification compatibility, and classification implications that may affect import treatment and cost planning. Given the overlap between heavy denim used in motorcycle apparel and similar materials used in industrial and outdoor applications, procurement teams should assess whether dual-use sourcing can improve flexibility without undermining protective performance. Inventory planning should also reflect the increasing expectation that protection features are a standard part of the assortment rather than a limited premium subset.
Across all three roles, the practical takeaway is that the market is moving toward higher default safety expectations, broader everyday usability, and more intricate compliance and sourcing considerations. Decisions made now around product architecture, material strategy, and market positioning will shape how effectively a company can capture demand in the next growth cycle. Organizations that want to evaluate these dynamics at the level of segment splits, regional nuances, and company-specific benchmarks will find greater precision in the full research dataset and custom analysis, where detailed tables, scenario breakdowns, and targeted recommendations are available for deeper planning.
For detailed analysis of this topic, please visit the official page: Motorcycle Apparel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Inositol Market 2026: Why Plant Based Sources and 6.98% CAGR Reshape Strategy
By pmarketresearch, 2026-09-21
The Inositol Market: Strategic Trends and Commercial Opportunities Through 2032
The inositol market has transitioned from a niche biochemical ingredient to a strategically important segment within the broader nutritional and pharmaceutical supply chain. Valued at approximately $160.0 million in 2025, the market has expanded from $122.42 million in 2020, reflecting consistent demand growth across multiple downstream applications. Looking ahead, the trajectory points toward $255.82 million by 2032, with a compound annual growth rate of 6.98 percent. This expansion is not merely a function of population growth or generalized wellness trends. It reflects structural shifts in how manufacturers source active compounds, how regulators frame safety and labeling requirements, and how end users increasingly differentiate between synthetic and fermentation-derived alternatives.
For executives and strategic planners, the numbers tell only part of the story. The more critical question is what forces are reshaping competitive positioning, where margin pressure is emerging, and which capabilities will separate future leaders from followers. This analysis examines the market's core dynamics, the drivers accelerating change, the evolving competitive landscape, and the practical implications for manufacturers, investors, and procurement teams.
Market Context and Structural Challenges
The inositol market operates at the intersection of dietary supplements, pharmaceutical development, animal nutrition, and industrial applications. Demand is distributed across these segments, with dietary supplements and animal feed representing the largest application pools, followed by pharmaceutical use and other industrial or research-oriented applications. On the source side, plant-based production dominates supply, with animal-derived and synthetic routes occupying smaller but strategically important niches. Regional demand is balanced across North America, Europe, and Asia Pacific, with Latin America and the Middle East and Africa providing incremental growth corridors.
Despite this broad distribution, the market is not uniformly mature. Several structural challenges are shaping decision-making and forcing companies to reconsider sourcing strategies, product positioning, and compliance investments.
Raw Material Volatility and Sourcing Diversification
One of the most immediate pressures stems from input cost fluctuations. Rising corn prices through 2025 have prompted manufacturers to reconsider traditional feedstock dependencies and explore alternative raw material pathways. Rice bran and other plant-based inputs are increasingly being evaluated as viable alternatives for inositol extraction and fermentation processes. This diversification is not simply a cost-containment exercise. It reflects a broader recognition that feedstock concentration creates vulnerability, particularly when grain markets are influenced by weather patterns, trade policy shifts, or competing demand from biofuel and food sectors. Suppliers that can secure flexible sourcing agreements or invest in multi-feedstock fermentation capabilities are better positioned to stabilize margins and maintain consistent supply to downstream customers.
Regulatory Clarity and Compliance Burden
Regulatory developments are simultaneously creating opportunities and raising the bar for market participation. In the United States, the FDA's GRAS designation now permits inositol use in infant formula at defined dosage ranges of 4 to 40 milligrams per 100 kilocalories. This establishes a clearer pathway for manufacturers targeting the infant nutrition segment, but it also requires rigorous documentation, batch consistency, and labeling accuracy. In Europe, the European Food Safety Authority has confirmed inositol's safety profile with conservative dosing guidelines, which supports expanded applications while reinforcing the need for evidence-based positioning. At the same time, stricter compliance standards across dietary supplements and functional ingredients are encouraging manufacturers to invest more heavily in clinical research, transparency, and quality control. Companies that treat regulatory alignment as a strategic capability rather than a administrative hurdle are gaining trust with retailers, formulators, and end consumers.
Capacity, Purity, and Differentiation Pressure
The market's competitive structure remains moderately concentrated, with the top three players accounting for a combined share that reflects meaningful but not insurmountable barriers to entry. A CR3 of 35.6 percent and CR5 of 47.8 percent indicates that scale, technological capability, and application-specific expertise matter, but there is still room for specialized suppliers to compete on purity, sustainability, or niche performance characteristics. This dynamic creates pressure for mid-tier and emerging producers to articulate a clear value proposition. Suppliers offering generic bulk inositol face margin compression and customer switching risk, while those able to demonstrate fermentation-derived consistency, solvent-free processing, or application-tailored grades are better positioned to command premium positioning.
Core Drivers Reshaping the Market
The market's growth trajectory is being shaped by several interconnected forces. These drivers extend beyond basic demand expansion and reflect deeper changes in technology, regulation, consumer behavior, and supply chain economics.
1. Fermentation Technology and Sustainable Production Pathways
Technological progress in fermentation has emerged as a defining shift in how inositol is produced and positioned. Traditional extraction and chemical synthesis routes are increasingly being complemented, and in some cases displaced, by fermentation-based processes that offer higher purity, reduced solvent use, and more consistent batch profiles. The commercial launch of solvent-free fermented myo-inositol and the introduction of fermented D-chiro-inositol represent meaningful milestones. These products are being positioned as cleaner, sustainable alternatives for nutraceutical and health-focused formulations, aligning with broader industry expectations around ingredient transparency and environmental impact.
Strategic partnerships are reinforcing this trajectory. Collaborations between biotechnology developers and established chemical or industrial partners are accelerating process optimization and creating pathways for higher-volume production of fermentation-derived intermediates. For market participants, the implication is clear: fermentation capability is becoming a differentiator not just for environmental messaging, but for performance consistency, regulatory positioning, and appeal to formulators seeking cleaner ingredient profiles.
2. Regulatory Alignment and Application Expansion
Regulatory clarity is unlocking new application pathways while simultaneously raising quality expectations. The FDA's guidance on infant formula use and EFSA's supportive safety confirmation are examples of how regulatory frameworks can broaden addressable markets when manufacturers have the documentation and quality systems to meet requirements. These developments are particularly significant for companies targeting early-life nutrition, specialized dietary supplements, and pharmaceutical-adjacent applications where safety and traceability are non-negotiable.
At the same time, tighter compliance expectations are driving investment in clinical research and product transparency. Manufacturers are increasingly expected to substantiate functional claims, provide batch-level consistency, and maintain clear documentation across the supply chain. This environment favors companies that integrate quality, research, and regulatory affairs into their commercial strategy rather than treating them as back-office functions.
3. Demand-Side Shifts Toward Wellness, Metabolic Health, and Specialty Nutrition
End-user demand is evolving along several axes. In dietary supplements, growing consumer awareness of metabolic health, stress response, and hormonal balance has increased interest in inositol as a functional ingredient. In animal nutrition, the push toward improved gut health, feed efficiency, and alternatives to antibiotic growth promoters is expanding the relevance of inositol in feed formulations. Pharmaceutical and research applications continue to require high-purity grades for development and specialized use.
These demand-side shifts are not uniform, but they share a common thread: end users are increasingly selective about ingredient origin, purity, and supporting evidence. Brands and formulators are looking for suppliers that can provide not only consistent material, but also the technical support, regulatory documentation, and application expertise needed to integrate inositol effectively into finished products.
Inulin Market
4. Supply Chain Reconfiguration and Cost Structure Realignment
The inositol supply chain is being reshaped by feedstock dynamics, regional production capabilities, and the cost implications of different manufacturing routes. As corn-based inputs face price volatility, manufacturers are diversifying toward rice bran and other plant-based materials, while fermentation-based producers are investing in scale and process efficiency. These shifts are changing the relative economics of plant-based extraction, animal-derived sourcing, and synthetic production.
For procurement and supply chain teams, the practical implication is that supplier resilience now depends on feedstock flexibility, geographic diversification, and the ability to maintain quality across alternative inputs. Suppliers that can demonstrate robust sourcing strategies and consistent processing standards are better equipped to support long-term customer relationships in a volatile input environment.
Competitive Landscape and Strategic Positioning
The competitive field in the inositol market includes large-scale producers, specialized fermentation developers, established distributors, and research-grade suppliers. The diversity of players reflects the broad application base, but it also means that competitive advantage increasingly depends on how companies align their capabilities with specific customer needs and market segments.
Scale, Fermentation Expertise, and Global Supply
Several Chinese manufacturers have built significant capacity around plant-based myo-inositol and derivatives, including D-chiro-inositol and scyllo-inositol, produced via fermentation and supplied globally for supplements, pharmaceuticals, food, and animal nutrition. With annual capacity reaching thousands of tons in some cases, these suppliers compete on scale, cost efficiency, and the ability to serve multiple downstream markets. Their strategic positioning often emphasizes fermentation know-how, high-purity output, and broad application coverage. For customers seeking reliable volume supply across multiple formats, these players offer an attractive combination of capacity and versatility.
Other regional producers are similarly focused on fermentation-derived inositol and derivatives for dietary supplements, infant nutrition, and feed applications, with an emphasis on high-purity processes. Their value proposition centers on application-specific consistency and the ability to support specialized nutrition segments with controlled-quality material.
Sustainable Innovation and Product Differentiation in Advanced Markets
In the United States and Europe, a different competitive dynamic is emerging around sustainability, purity, and application-specific innovation. Manufacturers and distributors of bulk inositol powder and graded materials for nutritional, pharmaceutical, and industrial uses are active in supplying established markets with reliable volumes and clearly defined specifications. Some focus on whole-food nutritional supplements, offering plant-based inositol for wellness and dietary applications, while others serve industrial and research channels with ISO-certified chemical supply and laboratory-grade material.
D-Mannose Market
A particularly notable strategic move has come from biotechnology developers commercializing solvent-free fermented myo-inositol and industry-first fermented D-chiro-inositol as cleaner, sustainable alternatives for nutraceutical formulations. These launches are not just product additions; they represent a positioning strategy centered on sustainability, higher purity, and alignment with health-focused brands that value fermentation-derived ingredients. Partnerships with established industrial players further reinforce the credibility and scalability of these processes, signaling that fermentation-based differentiation is increasingly integrated into broader supply chain strategies rather than treated as a standalone innovation experiment.
PW Consulting
Research-Grade Suppliers and the High-Purity Segment
Several suppliers specializing in laboratory-grade and API inositol for research, pharma, and biotech applications occupy an important niche. These companies focus on high-purity biochemicals for development, analytical work, and specialized formulations. Their competitive advantage lies in quality documentation, consistency, and the ability to support technically demanding customers. For pharmaceutical developers, research institutions, and biotech teams, these suppliers provide the reliability and specification control required for advanced applications, even if their volumes are smaller relative to bulk nutrition and feed channels.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market's structure suggests multiple concurrent trends. On one hand, scale advantages in fermentation and bulk supply are encouraging consolidation among larger producers seeking to strengthen cost positions and global reach. On the other hand, the demand for specialized grades, sustainable sourcing, and application-specific support is sustaining a fragmented layer of niche suppliers and regional specialists. New entrants are likely to focus on fermentation innovation, solvent-free processes, or targeted application segments where purity and documentation create defensible positioning. The overall trajectory points toward a market where broad-scale suppliers and specialized innovators coexist, with competitive success determined by how well each aligns its capabilities with the expectations of its chosen customer base.
Forward Outlook: Trends and Commercial Implications
The next three to five years are likely to be defined by several interconnected trends that will shape both opportunity and risk for market participants.
1. Fermentation-Derived and Solvent-Free Products Will Gain Share in Premium Segments
As sustainability expectations rise and formulators seek cleaner ingredient profiles, fermentation-derived inositol and solvent-free processes are poised to capture greater attention in nutraceutical, wellness, and specialty nutrition applications. This trend will not eliminate extraction or synthetic routes across all segments, but it will increasingly differentiate premium offerings and influence procurement decisions among brands that prioritize transparency and environmental positioning. Companies that can demonstrate scalable fermentation capability, consistent purity, and credible sustainability claims will be best positioned to benefit from this shift.
2. Regulatory-Driven Application Expansion Will Open New Demand Pools
The combination of clearer regulatory guidance in the United States and Europe, along with growing interest in infant nutrition, metabolic health, and functional supplements, is likely to expand the addressable market beyond current baselines. Suppliers that invest in documentation, quality systems, and application support will be better equipped to enter these higher-value segments. The opportunity is not simply to sell material, but to provide the regulatory and technical scaffolding that allows customers to use inositol confidently in sensitive or regulated applications.
3. Feedstock Flexibility and Supply Chain Resilience Will Become Competitive Essentials
As input cost volatility persists and manufacturers diversify away from single-feedstock dependencies, the ability to maintain consistent quality across alternative raw materials will become a key differentiator. Supply chain resilience will increasingly be evaluated not just on price, but on sourcing flexibility, geographic diversification, and the ability to guarantee batch consistency under changing input conditions. Companies that build these capabilities into their operating model will be more reliable partners for customers operating in regulated or quality-sensitive environments.
Risks and Uncertainties
Several uncertainties could alter the trajectory described above. Feedstock price swings could compress margins or delay investment in alternative sourcing if volatility proves more persistent than expected. Regulatory environments may shift as authorities revisit dosing guidance, labeling expectations, or safety thresholds, particularly in sensitive applications such as infant nutrition. Competitive entry in fermentation-based production could intensify price competition in premium segments if new capacity outpaces demand growth. Finally, if clinical evidence or consumer perception does not keep pace with product launches, some innovation-driven positioning may face headwinds. Companies should monitor these variables closely and build flexibility into both sourcing and product strategy.
Actionable Guidance for Decision-Makers
The strategic implications differ depending on a company's role in the value chain, but several priorities are broadly relevant.
For Manufacturers and Producers
- Evaluate feedstock diversification as a strategic capability, not just a cost initiative. Multi-source strategies and flexible fermentation or extraction pathways can reduce exposure to commodity volatility and improve supply reliability.
- Invest in fermentation capability and solvent-free or high-purity processes where they align with target customer expectations. Differentiation in sustainability and purity is increasingly tied to commercial positioning in premium nutrition and pharmaceutical-adjacent markets.
- Strengthen quality documentation, regulatory support, and application expertise. Customers in regulated or quality-sensitive segments are looking for suppliers that can provide more than material; they want partners who can support formulation, compliance, and consistency.
For Investors
- Focus on companies with clear technological differentiation, scalable fermentation or production capabilities, and credible pathways into higher-value applications. Volume alone is less compelling than the ability to command premium positioning through purity, sustainability, or application support.
- Monitor regulatory developments as indicators of where demand is likely to expand. Clear guidance in infant nutrition, dietary supplements, and functional ingredients can signal near-term opportunity for suppliers with the right documentation and quality systems.
- Assess supply chain resilience and feedstock strategy as part of long-term risk evaluation. Companies that depend on a single input route or lack flexibility may face margin and continuity risk if commodity conditions shift.
For Procurement and Formulators
- Prioritize supplier resilience and quality consistency over short-term price advantages. In regulated or quality-sensitive applications, batch consistency, documentation, and sourcing transparency can reduce downstream risk and protect brand reputation.
- Engage suppliers early on application requirements, regulatory documentation, and technical support. The most valuable partnerships are built on alignment around purity, grade specifications, and the evidence or compliance support needed for the target market.
- Track fermentation-derived and solvent-free options as potential differentiation levers for product positioning. Where sustainability or cleaner ingredient narratives matter to end users, these alternatives may offer strategic value beyond basic material supply.
Closing Perspective
The inositol market is moving from a broadly functional ingredient space toward a more differentiated landscape shaped by fermentation innovation, regulatory clarity, feedstock dynamics, and evolving end-user expectations. The growth trajectory through 2032 reflects genuine expansion, but the commercial opportunity will be captured by companies that treat quality, sustainability, regulatory alignment, and supply resilience as strategic capabilities rather than operational details.
For organizations seeking deeper segmentation data, company-level benchmarking, region-specific demand patterns, and tailored strategic recommendations, the full PW Consulting research report provides a more granular view of the market and its participants.
For detailed analysis of this topic, please visit the official page: Inositol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ethylene Oxide Market: Why the 4.22% CAGR Trajectory Changes Everything
By pmarketresearch, 2026-09-21
Navigating the Ethylene Oxide Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Snapshot and Structural Dynamics
The global ethylene oxide (EO) market has demonstrated consistent expansion over the past half-decade, advancing from approximately $33.9 billion in 2020 to an estimated $41.7 billion in 2025. Projections indicate the market will reach roughly $55.7 billion by 2032, reflecting a compound annual growth rate of 4.22 percent across the forecast window. This trajectory underscores a resilient demand environment that continues to absorb incremental capacity, regulatory friction, and supply chain recalibrations without losing momentum. The underlying composition of value creation remains heavily weighted toward derivative chemistry, with a single downstream family accounting for the majority of volume conversion, while sterilization and specialty applications carve out a strategically critical but smaller share of total throughput.
Current market dynamics reveal two structural tension points that will define investment and operational decisions over the next several years. The first revolves around regulatory intensity targeting commercial sterilization operations, particularly in North America, where emission standards and permitting frameworks have tightened considerably. Facilities have responded by investing in containment engineering, permitting new sites, or adjusting operational footprints, but the pace and durability of compliance adjustments remain uneven across jurisdictions. The second tension lies in regional demand asymmetry. Asia Pacific has emerged as a high-growth conversion hub, driven by expanding polyester and antifreeze/coolant capacity, while mature regions are increasingly focused on high-margin medical and specialty applications rather than bulk commodity margins. This divergence is reshaping how producers allocate merchant-grade material and how sterilization service providers site their processing networks.
A third inflection point sits at the intersection of feedstock economics and end-use substitution pressure. Ethylene oxide pricing and availability are tightly coupled to upstream ethane and ethylene markets, which means cost structures can shift quickly when regional energy dynamics move. At the same time, certain downstream segments are experimenting with alternative sterilization modalities or material substitutions, especially where regulatory exposure and community emissions concerns create operational uncertainty. The result is a market that is still growing, but one in which growth is increasingly contingent on operational discipline, compliance readiness, and differentiated service capabilities rather than volume alone.
Key Drivers Reshaping the Ethylene Oxide Value Chain
Technology and Process Innovation
Innovation in EO handling, sterilization processing, and derivative conversion is moving from incremental improvement toward capability redefinition. On the sterilization side, service providers are increasingly combining EO cycles with complementary modalities such as gamma radiation and vaporized hydrogen peroxide to widen the range of sterilizable materials and reduce cycle times for mixed product portfolios. This hybrid approach matters because medical device manufacturers increasingly ship complex assemblies, polymer components, and temperature-sensitive instruments that cannot tolerate uniform treatment protocols. By layering sterilization technologies under one service framework, providers can offer design-for-sterilization guidance and post-processing validation that become value-added differentiators rather than commoditized throughput services.
In the derivative space, conversion efficiency and purity specifications are becoming more tightly linked to application performance. Ethylene glycols and glycol ethers continue to anchor large-scale industrial and consumer demand, but the highest-value niches are concentrating around ultra-pure grades for medical sterilization and specialty ethoxylates and ethanolamines used in formulation chemistry. Operators that can guarantee consistent purity, traceability, and lot-level documentation are gaining preferential access to regulated applications, which in turn raises the operational bar for newer entrants and rewards established facilities with mature quality systems and engineering depth.
Regulatory and Compliance Environment
Regulatory evolution remains the single most consequential variable for commercial sterilization operations. Recent EPA proposals to amend existing emission standards for commercial sterilization facilities reflect a deliberate balancing act: preserving the availability of life-saving devices that depend on EO sterilization while addressing community exposure concerns. The proposed adjustments, which include discussions around permanent total enclosure requirements and other operational conditions, signal that regulators are actively recalibrating compliance burdens in response to supply chain risk considerations. This matters commercially because sterilization capacity is not easily relocated or rapidly duplicated; permitting timelines, community engagement, and engineering retrofits can stretch project schedules and alter site economics.
Beyond federal action, state and local air quality programs continue to influence operating conditions, and enforcement outcomes can reshape community expectations and facility siting strategies. The trend is not a blanket regulatory contraction; rather, it is a selective tightening that creates compliance winners and losers. Operators with robust emissions control engineering, transparent monitoring practices, and documented safety governance are better positioned to sustain operating continuity. Conversely, facilities that rely on legacy configurations without proactive upgrade planning face greater uncertainty in permitting renewals, expansion approvals, and long-term site viability.
Demand-Side Shifts in Medical Devices and Industrial Applications
Demand behavior is bifurcating across application clusters. In medical and pharmaceutical channels, EO remains deeply embedded in sterilization workflows for in vitro diagnostics, catheters, syringes, disposable consumables, and other temperature-sensitive devices. The scale of this dependency reinforces the strategic importance of reliable sterilization capacity, particularly when device complexity increases and manufacturers require validated, repeatable processes with strong documentation support. As device portfolios diversify, sterilization is increasingly treated as an extension of product design and quality assurance, not simply a finishing step. This creates commercial opportunities for service providers that can align sterilization protocols with device development cycles and regulatory submissions.
Polyethylene Oxide (PEO) Market
On the industrial side, polyester fiber and PET resin production continue to anchor large-volume EO derivative demand, supported by apparel, packaging, and industrial polyester applications. Antifreeze and coolant formulations also remain substantial consumer of ethylene glycol derivatives, with demand tied to automotive, HVAC, and industrial machine cooling needs. While these bulk segments are more price-sensitive and cyclical than medical sterilization, they still provide the volume foundation that supports merchant EO economics. The strategic implication is that producers and converters must manage a dual rhythm: disciplined execution in cyclical commodity demand, and premium positioning in regulated, specification-driven applications that carry higher switching costs.
Ethanolamine Market
Supply Chain Reconfiguration and Cost Structure Dynamics
Cost and supply dynamics are increasingly influenced by geographic concentration in feedstock access and conversion capacity. Regional production clusters have shaped short-term availability and pricing behavior, with merchant EO distribution dependent on logistics, storage, and site-level handling standards. Because EO is both reactive and hazardous, the cost structure extends beyond raw material pricing to include safety systems, certification, transport controls, and insurance exposure. As a result, the economics of EO supply are highly sensitive to operational maturity and regional infrastructure quality, which gives established producers and integrated service networks a structural advantage in stable service delivery.
At the same time, sterilization demand for ultra-pure grades creates a specialized supply track that operates with higher quality and handling requirements than merchant commodity streams. This bifurcation means that the same molecule can command very different commercial treatment depending on application class, documentation needs, and compliance posture. Companies that can cleanly separate operational lanes, manage purity assurance, and maintain reliable throughput under tighter handling protocols are better positioned to capture margins in regulated segments, while commodity-focused players must compete more aggressively on availability, flexibility, and cost discipline.
Competitive Landscape and Strategic Positioning
How Leading Players Differentiate
The competitive field spans producers, sterilization service providers, and device manufacturers that intersect with EO across different segments of the value chain. Core enterprise profiles reveal three broad strategic orientations. Some organizations focus on high-purity medical-grade EO packaged for low-temperature sterilization of sensitive devices, emphasizing purity assurance, packaging integrity, and service support for regulated applications. Others position around contract sterilization services, offering validated processing in compliance with recognized sterilization standards and building multi-facility networks that can serve device manufacturers at scale. A third group includes large device manufacturers and diversified industrial players that use EO sterilization as part of their product delivery or supply operations, often embedding sterilization strategy into broader quality and regulatory planning.
Within this landscape, differentiation is increasingly driven by compliance capability, geographic reach, and service integration rather than by feedstock ownership alone. Sterilization providers that invest in validated protocols, engineering support, and emissions management can reduce the operational risk that device manufacturers are increasingly unwilling to absorb internally. Producers that supply merchant-grade EO benefit from volume stability in bulk derivative markets, but their strategic leverage grows when they can reliably serve regulated sterilization demand with consistent quality and logistics reliability. Device manufacturers that oversee their own sterilized product lines gain advantage by aligning material selection, packaging, and sterilization validation early in development, which can shorten qualification cycles and reduce downstream processing risk.
Recent operational moves illustrate these choices in practice. New sterilization facility construction in growth regions reflects the push to place capacity closer to expanding medical device and diagnostics manufacturing bases. Simultaneously, technology combinations that blend EO with other sterilization modalities are being introduced to accommodate broader material compatibility and sterility assurance requirements. Regulatory and legal resolutions around permitting and emissions have also become part of the strategic picture, reminding the market that operating license stability, community relations, and documented compliance practices are now central to long-term commercial viability.
PW Consulting
Market Structure Evolution
Market concentration remains relatively high, with a limited number of large players accounting for a substantial share of total value. That concentration is most visible in bulk derivative supply, where scale economics and feedstock access shape the competitive field. In sterilization services, the structure is more fragmented across geographies and facility networks, but consolidation trends are emerging where integrated service capabilities, multi-site footprints, and compliance infrastructure create defensible positions. The resulting landscape is neither purely consolidated nor purely dispersed; it is stratified, with commodity supply leaning toward scale concentration and specialized sterilization and device-related applications trending toward capability-driven consolidation.
The evolution trajectory suggests a continued pull toward operational maturity thresholds. New entrants will find it difficult to compete on pure price in regulated sterilization markets because qualification, documentation, emissions control, and long-term reliability create high switching costs for customers. At the same time, regional demand growth can still invite capacity additions in conversion and derivatives, especially where local polymer, packaging, and antifreeze demand expands. The practical outcome is a market where strategic advantage accrues to firms that combine scale, quality systems, compliance readiness, and proximity to end-use demand clusters, while generic capacity without differentiated execution faces margin compression and higher operational risk.
Forward Outlook: Three Trends Shaping 2027 to 2032
Trend One: Sterilization as a Stabilized Strategic Capability
Over the next several years, EO sterilization is likely to become more institutionalized as a specialized capability rather than a commoditized service. The combination of device complexity, regulatory scrutiny, and the continued scale of EO-dependent sterilization supports this direction. Providers that invest in standardized protocols, hybrid sterilization options, emissions engineering, and transparent compliance reporting will be better positioned to secure multi-year service relationships and reduce customer-side operational burden. The commercial opportunity lies not just in processing volume but in becoming a partner in device qualification, packaging design, and supply continuity, which can create stickier demand and more predictable revenue streams.
Trend Two: Regional Rebalancing of Conversion and Service Capacity
Demand growth will continue to be uneven geographically, and capacity expansion will follow end-use momentum rather than uniform global growth rates. Asia Pacific and other developing industrial regions will likely remain focal points for derivative expansion, particularly in polyester and coolant-related applications, while North America and Europe will keep attention on higher-value medical device sterilization and specialty derivatives. This rebalancing creates opportunities for companies that can site capacity intelligently, manage cross-border logistics for merchant EO, and align service networks with regional device manufacturing density. It also introduces risk for operators who assume demand migration will be linear; regional policy shifts, energy cost changes, and local permitting environments can alter the attractiveness of specific sites or expansion plans.
Trend Three: Compliance Discipline as a Margin Determinant
As emissions expectations and community oversight remain elevated in several jurisdictions, compliance performance is increasingly becoming a margin determinant rather than a back-office operational issue. Facilities that proactively manage containment, monitoring, permitting documentation, and community engagement will face lower interruption risk and stronger negotiating positions with regulators and customers. Conversely, facilities that treat compliance improvements as reactive or episodic will face greater exposure to enforcement actions, operational pauses, and reputational friction. The strategic implication is that capital allocation toward safety, engineering, and compliance infrastructure should be modeled as a growth enabler, not merely a cost center, especially for operations tied to regulated medical applications.
Strategic Actions for Decision Makers
For Manufacturers and Service Providers
Design EO-related operations around two parallel mandates: reliability in regulated applications and cost discipline in bulk derivative markets. For sterilization services, prioritize validated processing frameworks, hybrid modality flexibility, emissions engineering, and documentation quality that supports device manufacturers across qualification and production cycles. For derivative producers, sharpen purity assurance and lot-level traceability where premium grades command stronger positioning, while preserving operational efficiency in commodity conversion. Where expansion is contemplated, sequence site decisions around end-use density, permitting feasibility, and logistics reliability rather than treating capacity additions as purely volume-driven responses.
Strengthen supply resilience by clarifying which customer segments depend on merchant EO availability versus ultra-pure sterilization grades, then align inventory, handling, and distribution practices accordingly. Build contingency planning for feedstock price volatility and regional energy shifts, since those variables can quickly change margin profiles even when end-demand remains stable. Treat safety, compliance, and emissions management as core competencies that influence customer selection, permitting speed, insurance conditions, and long-term site viability.
For Investors
Screen opportunities through a lens of operational maturity and regulatory exposure, not just top-line growth potential. In sterilization-linked operations, assess emissions control capability, facility siting strategy, compliance documentation, and the degree to which the business is integrated with device qualification and service continuity. In producer and derivative conversion businesses, evaluate feedstock access, regional cost structure, purity capability for premium grades, and exposure to cyclical demand swings in polyester, antifreeze, and coolant markets. The highest-risk exposures often sit where compliance, permitting, or community relations are under-managed, even if revenue growth appears attractive in the near term.
Look for businesses that are converting regulatory pressure into durable competitive advantage by investing in engineering, monitoring, and multi-modality service options. In growth regions, distinguish between genuine demand-led expansion and speculative capacity additions; the former tends to be supported by local manufacturing density and downstream application growth, while the latter may face margin pressure if supply outpaces absorption. Finally, monitor where hybrid sterilization services and premium-grade handling create switching costs that protect revenue quality, since those are the segments most likely to sustain differentiated returns through cycles.
For Procurement and Supply Chain Leaders
Treat EO-dependent supply as a strategic continuity issue rather than a routine commodity purchase. Where medical devices, diagnostics, or temperature-sensitive materials depend on EO sterilization, validate supplier readiness across validation support, emissions posture, facility redundancy, and documentation quality. For industrial derivative procurement, focus on availability reliability, specification consistency, and logistics controls that account for hazardous-material handling and regional supply access. Diversifying processing routes or site options where feasible can reduce concentration risk, but only if alternative sources meet the same quality and compliance expectations required by your applications.
Incorporate compliance and operational resilience questions into supplier evaluation, including evidence of emissions management practices, permitting status, safety governance, and continuity planning. For categories where substitution or alternative sterilization modalities are technically feasible, run structured cost and risk comparisons rather than assuming price alone determines the best choice. In many cases, the lowest apparent unit cost can be offset by qualification delays, documentation gaps, or interruption risk in regulated supply chains.
From Market Intelligence to Execution
The ethylene oxide market is expanding, but the character of that expansion is changing. Growth is increasingly governed by compliance readiness, product complexity, regional end-use demand, and the ability to deliver reliable service across both regulated and commodity segments. Firms that understand these operating realities can align capacity, service models, and procurement strategies with where value is actually being created, rather than assuming that volume growth will automatically translate into favorable outcomes.
For teams that need a deeper, segment-level view of regional demand patterns, derivative conversion splits, application drivers, competitive footprints, and scenario-based sizing through 2032, the comprehensive PW Consulting research report provides detailed data and customized recommendations designed for implementation planning.
For detailed analysis of this topic, please visit the official page: Ethylene Oxide (EO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Peripheral Guidewire Market: 7.8% CAGR Trajectory Signals Shifting Value Pools
By pmarketresearch, 2026-09-21
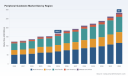
Strategic Shifts and Commercial Opportunities in the Peripheral Guidewire Market
The peripheral guidewire market has entered a phase of sustained expansion, underpinned by consistent revenue growth across the 2020–2025 period and a robust projected trajectory through 2032. Market size evolved from approximately $123.45 million in 2020 to $151.08 million in 2023, accelerating to $168.47 million in 2025. The forecast period from 2026 to 2032 projects a compound annual growth rate of 7.8 percent, with valuations scaling toward $283.0 million by the end of the horizon. This trajectory reflects not merely incremental expansion but a structural redefinition of how clinicians navigate peripheral vascular disease, diagnostic pathways, and minimally invasive interventions. For executives and investors, the market presents a maturing landscape where differentiation hinges on material science, regulatory agility, and partnership-driven distribution rather than volume alone.
Despite the positive momentum, the industry faces structural tensions that will shape competitive outcomes over the next five years. First, the balance between standardization and specialization remains unresolved. Guidewires must deliver reliable trackability and pushability across diverse anatomical targets, yet the proliferation of lesion complexity, smaller vessel diameters, and transradial access protocols demands tailored performance profiles. Second, regulatory harmonization is intensifying compliance costs while simultaneously raising barriers to entry for fragmented suppliers. The alignment of quality management systems with ISO 13485:2016 and the continued reliance on 510(k) pathways for device iterations create a dual dynamic: predictable clearance routes for incremental innovations, but elevated scrutiny for novel material combinations or performance claims. Third, reimbursement environments and hospital cost-containment programs are pressuring procurement teams to justify premium device selections, pushing manufacturers to demonstrate clinical outcomes, reduced procedure time, or lower complication rates to sustain pricing power.
Technology Innovation and Material Performance
Material science continues to anchor the market’s evolution. Nitinol-based constructions dominate performance-sensitive applications due to their superelastic properties and resistance to kinking, while stainless steel retains a strong foothold for routine procedural navigation where cost efficiency and torque control are prioritized. Composite architectures are gaining traction in scenarios requiring balanced flexibility and column strength, particularly where hydrophilic coatings and jacketed designs enhance lubricity without compromising tactile feedback. Innovation is increasingly moving toward micro-scale engineering: micro-cut nitinol sleeves, targeted coil geometries, and precision-layered jackets are enabling guidewires that maintain luminal support in smaller vessels while improving deliverability through tortuous anatomy. These advances are not cosmetic; they translate into longer device longevity, reduced procedural friction, and expanded use cases that blur the boundary between diagnostic traversal and interventional support.
Regulatory Environment and Quality System Alignment
The regulatory landscape is evolving from fragmented national expectations toward more converged quality frameworks. The finalization of quality management system rules aligning with ISO 13485:2016 has consolidated expectations around design control, risk management, and post-market surveillance, providing a clearer compliance pathway for manufacturers that invest early in standardized processes. Concurrently, 510(k) clearances for peripheral and neurovascular guidewires remain a practical route for incremental product iterations, but the emphasis on substantial equivalence and performance comparability means that innovation must be framed within demonstrable clinical or usability advantages. For companies operating across regions, the divergence in certification timelines—exemplified by CE MDR approvals and U.S. clearances—requires portfolio planning that anticipates geographic sequencing, not just device readiness.
Guide Wires Market
Demand-Side Shifts in Clinical Practice
Clinical adoption patterns are reshaping demand. Transradial access has expanded beyond coronary interventions, with growing interest in peripheral artery disease procedures that prioritize patient comfort, reduced bleeding complications, and faster recovery. At the same time, interventional volumes in lower extremity disease are rising as population risk factors persist and image-guided techniques improve procedural confidence. The convergence of these trends puts pressure on guidewire portfolios to support both diagnostic navigation and interventional maneuvering, often within a single procedural workflow. Hospital administrators and procurement committees increasingly evaluate device choices through the lens of procedure efficiency, compatibility with existing catheter systems, and the ability to reduce device swaps or redundant access attempts. Consequently, guidewire value propositions that emphasize reliability, trackability, and procedural versatility are gaining procurement attention.
Supply Chain and Cost Structure Pressures
Manufacturing complexity, raw material variability, and sterilization requirements continue to influence cost structures. The competitive intensity reflected in a moderately concentrated market—with the top three and top five players holding a modest combined share—indicates room for specialization but also rewards scale advantages in sourcing, testing, and quality assurance. Companies that can manage coating consistency, coil precision, and device finishing at scale are better positioned to absorb compliance overhead while maintaining margin integrity. At the same time, distribution strategies are becoming a more meaningful lever: exclusive partnerships and regional commercialization agreements allow established players to expand portfolios without proportionally increasing internal manufacturing footprint, while smaller innovators leverage targeted approvals to enter high-value markets with focused product lines.
Competitive Landscape and Leading Strategies
The competitive field combines multinational device platforms with specialized manufacturers and regional innovators, each pursuing distinct strategic positions. Abbott Laboratories provides a peripheral vascular intervention portfolio focused on support and navigation wires for lower extremity procedures, positioning itself around clinical familiarity and broad procedural coverage. Boston Scientific Corporation has emphasized challenging small vessel and peripheral artery disease interventions through dedicated lines, reinforcing a strategy centered on deliverability in complex anatomy. Terumo Corporation offers hydrophilic and specialty guidewires for interventional cardiology and peripheral procedures, leveraging coating technology and navigation feel as differentiators. Medtronic plc supplies peripheral guidewires for transradial access in peripheral artery disease treatment, aligning product design with the broader shift toward radial workflows. Asahi Intecc Co., Ltd. focuses on trackability and durability for PTA and PPI procedures, emphasizing precision engineering in repeat-use scenarios. Cook Medical LLC extends peripheral guidewire portfolios across urology, gastroenterology, and vascular access, reflecting a cross-specialty distribution logic rather than a single-vascular focus. B. Braun Melsungen AG designs guidewires for safe catheter placement in peripheral procedures, emphasizing controlled access and procedural safety. Merit Medical Systems, Inc. delivers high-precision guidewires across cardiovascular, peripheral, radiology, and urology interventions, supporting a diversified interventional footprint. Biotronik SE & Co. KG provides vascular access and intervention guidewires, adding to the regional and specialty coverage mix. CONMED Corporation manufactures guidewires and related peripheral intervention tools, while Cardinal Health, Inc. distributes guidewire products through its Cordis division for peripheral vascular procedures. Specialty and emerging players such as LA Vascular, Future Medical Design Co., Ltd., and BrosMed Medical illustrate a parallel layer of targeted innovation and regional commercialization.
Worldwide Wedge Pressure Catheter Market
Differentiation Through Product Architecture and Access Strategy
Leading strategies are bifurcating around two complementary models. The first is portfolio depth within a defined clinical pathway: companies invest in multiple diameters, tip designs, coating options, and support profiles to cover diagnostic traversal, lesion crossing, and post-dilation support. The second is targeted expansion through distribution and co-commercialization, where established platforms extend their reach by licensing or exclusively distributing specialized guidewires that complement existing procedural lines. Both approaches aim to reduce the need for clinicians to switch vendors mid-procedure, a practical driver of preference and order consistency. Differentiation is increasingly less about claiming generic superiority and more about demonstrating that a particular combination of tip stiffness, shaft flexibility, coating behavior, and compatibility with catheter systems solves a specific procedural bottleneck.
Market Evolution: Consolidation, Niche Focus, and New Entrants
The market structure suggests gradual consolidation in distribution and service delivery, but persistent fragmentation in product specialization. Incumbents benefit from clinician relationships, established training ecosystems, and the credibility of broad intervention portfolios, which strengthens repeat procurement. At the same time, niche players continue to enter with focused designs, CE MDR approvals, or 510(k) clearances that unlock regional opportunities. This dynamic creates a two-speed environment: large players compete on breadth, service, and procedural integration, while smaller entrants gain traction by addressing specific anatomical challenges, access routes, or coating preferences. Over time, the most resilient portfolios will likely combine internal engineering with selective partnership-driven expansion, balancing fixed cost exposure with the agility to enter new procedural niches.
Future Trends and Commercial Implications
Several trends are likely to shape the market over the next three to five years. First, the integration of guidewire performance with procedure efficiency will intensify. Devices that reduce navigation time, improve lesion access, or lower the likelihood of device exchange will be valued not only for clinical outcomes but also for throughput and resource utilization. Second, transradial and small-vessel access will continue to expand peripheral use cases, encouraging designs that preserve tactile feedback while supporting finer delivery systems. Third, the regulatory and quality environment will reward manufacturers that have already institutionalized ISO-aligned processes and can respond quickly to clearance requirements, potentially favoring organizations with disciplined design controls and documented performance comparability. These trends collectively point toward a market where technical performance, procedural fit, and commercial execution matter as much as raw device approval.
Commercial opportunities will accrue to companies that align product development with procurement realities. For manufacturers, the value proposition will increasingly include evidence of procedural reliability, compatibility with existing access systems, and a clear mapping to lesion complexity and vessel size. For investors, the market’s moderate concentration invites attention to firms that can convert specialized approvals into regional scale, and to platforms that use distribution agreements to extend portfolio breadth without proportionate manufacturing expansion. For procurement and clinical leaders, the opportunity lies in standardizing around guidewires that demonstrably reduce procedural friction, while maintaining flexibility for complex cases that require alternative support profiles. Potential risks include reimbursement variability that compresses device budgets, regulatory timeline shifts that delay regional launches, and material or coating consistency challenges that can affect device performance consistency at volume.
Strategic Actions for Decision-Makers
Guidance for Manufacturers
Product roadmaps should prioritize features that translate directly into procedural value: predictable trackability in tortuous anatomy, reliable torque transfer, and coating behavior that supports smooth advancement without compromising tactile control. Regulatory planning should treat geographic sequencing as a commercial decision, aligning approval timing with distribution readiness and clinician training capacity. Where internal scale is limited, selective distribution partnerships can accelerate market access while preserving engineering focus on performance differentiation. Quality systems should be designed with anticipated clearance expectations in mind, ensuring that design history, risk documentation, and performance comparability are ready when submission windows open.
PW Consulting
Guidance for Investors
Investment attention should focus on companies that demonstrate a credible path from product approval to commercial execution, particularly where regional clearance events can unlock share in targeted markets. The combination of moderate concentration and active specialty entrants suggests that value will emerge from execution discipline rather than broad market exposure alone. Distribution agreements and exclusive partnerships can be meaningful indicators of commercialization intent, but they should be evaluated alongside manufacturing readiness, service infrastructure, and the clarity of the underlying procedural need. Portfolio breadth is valuable, but breadth without procedural fit or reliable supply can dilute returns.
Guidance for Procurement and Clinical Strategy Leaders
Procurement strategies should weigh guidewire selection against total procedural impact, including navigation reliability, compatibility with existing catheter systems, and the likelihood of reducing device swaps in complex cases. Standardization where clinically appropriate can improve efficiency and inventory management, while maintaining access to specialty designs for challenging anatomy preserves procedural flexibility. Supplier evaluation should incorporate not only unit economics but also documentation quality, regulatory alignment, and the ability to support training and consistent supply. In an environment where procedure efficiency and access route preferences are evolving, device selection should be revisited periodically to ensure alignment with updated clinical workflows.
The peripheral guidewire market is expanding on the strength of procedural demand, material innovation, and evolving access preferences, but the most consequential decisions will be made by organizations that can connect device performance to real workflow outcomes. Detailed segment-level sizing, regional demand patterns, and company-specific benchmarking will sharpen strategic planning and reveal where commercial leverage is greatest. For decision-makers seeking granular data and tailored recommendations, the full PW Consulting market research report provides deeper breakdowns and scenario-based guidance to support investment, portfolio, and procurement decisions under evolving clinical and regulatory conditions.
For detailed analysis of this topic, please visit the official page: Peripheral Guidewire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
GET Market 2026: Why This 5.5% CAGR and $5.8B Outlook Changes Everything
By pmarketresearch, 2026-09-21
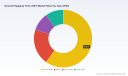
Strategic Shifts and Commercial Opportunities in the Global Ground Engaging Tools Market
The global market for ground engaging tools has entered a period of structural evolution. Valued at approximately USD 4,050 million in 2025, the market is projected to reach USD 5,800 million by 2032, representing a compound annual growth rate of 5.5% over the forecast period. Growth is not uniform across all geographies or equipment categories, but the overall trajectory reflects a maturing industry where performance optimization, total cost of ownership, and operational uptime increasingly drive purchasing decisions. The market remains moderately concentrated, with the top three players accounting for roughly 48.5% of revenue and the top five capturing about 65.2%. This concentration underscores scale advantages in engineering, distribution, and aftermarket service, while leaving meaningful room for specialized innovators and regional specialists to differentiate on fit, durability, and service responsiveness.
For executives and investors, the core question is not whether the market will grow, but how value will be created and captured as the industry transitions from replacement-driven demand to performance-driven procurement. The following analysis examines the defining challenges, demand and supply forces, competitive strategies, and forward-looking trends that will shape commercial outcomes through the end of the decade.
Market Landscape and Defining Pressures
The ground engaging tools market spans a broad portfolio of wear components—bucket teeth, adapters, blades, side cutters, lips, and complete bucket protection systems—deployed across excavators, loaders, dozers, and a range of other earthmoving and mining equipment. Bucket teeth represent the largest product category, reflecting their universal role across general construction and mining applications. Excavators anchor the application side of the market, followed by loaders and dozers, with the balance distributed across specialized attachments and mixed fleets. Regionally, North America and Europe together form the largest revenue base, while Asia Pacific and Latin America represent structurally faster-growing theaters tied to infrastructure development and mining expansion.
Several intersecting pressures are reshaping how manufacturers, fleet operators, and distributors approach the category:
- Material volatility and specification rigidity. Carbon steel wear plates, cutting edges, and high-abrasion steels remain foundational to ground engaging tools, yet they are subject to supply constraints and price fluctuations. At the same time, industry standards for hardox wear plate and high-abrasion steel continue to govern material selection, anchoring cost structures and requiring disciplined sourcing strategies.
- Skilled labor constraints are changing the value equation. Shortages of skilled technicians for heavy machinery maintenance are pushing operators toward long-life ground engaging tools and designs that reduce manual intervention. Components that resist premature wear, simplify replacement, and extend service intervals are gaining preference over lowest-unit-price alternatives.
- Safety standards are raising the bar on design. ISO and mining safety standards increasingly demand secure locking mechanisms in ground engaging tools, influencing product architecture and limiting the viability of indirect, non-conforming substitutes in regulated mining environments.
Together, these pressures are compressing price-based competition while elevating durability, interchangeability, and safety-compliant engineering as the primary arenas of differentiation. The strategic implication is clear: vendors that can stabilize input costs, design for serviceability, and align with recognized safety and material specifications will command stronger margin pools than those competing primarily on price.
What Is Driving Change: Technology, Regulation, Demand, and Supply
Technology and design innovation
Product innovation is shifting from incremental material improvements toward integrated systems that protect buckets, extend component life, and support faster replacement. Recent developments illustrate this direction. In April 2026, Bradken updated its ground engaging tools catalog with enhanced Zenith Plate Lip and Eclipse Cast Lip solutions, signaling continued emphasis on high-performance mining ground engaging tools for face shovels, front-end loaders, and backhoe excavators. In May 2026, Sandvik introduced the Mako™ GET as a next-generation bucket protection system tailored for underground loader operations, reinforcing the trend toward engineered protection packages that improve durability and productivity in demanding environments. Later in the same month, Haladjian Mining completed new ESCO® MaxDRP™ Ripper GET system installations for mining dozers, demonstrating how complete, specification-aligned systems are being deployed to optimize performance and equipment life in mining dozers and excavators.
Excavator Attachments Market
These releases share a common thread: they are not isolated wear parts but engineered systems designed to reduce operating costs and downtime. For manufacturers, the opportunity lies in bundling teeth, adapters, lips, and bucket protection into coherent configurations that simplify specification, improve fit, and reduce the risk of premature failure. For operators, this aligns with the broader industry shift toward monitored wear systems and digital monitoring technologies, which are accelerating adoption of data-informed maintenance decisions and creating a stronger link between component design and telemetry-compatible service models.
Policy and regulatory environment
Regulatory and standards-driven requirements are becoming a more decisive factor in product design and procurement. ISO and mining safety standards require secure locking mechanisms in ground engaging tools, which narrows the feasible design space and rewards manufacturers that can deliver compliant, field-proven solutions. Material specifications—particularly standards for hardox wear plate and high-abrasion steel—continue to shape what can be used in high-wear applications, reinforcing a preference for traceable, spec-aligned inputs in mining and regulated construction settings.
The commercial consequence is dual-edged. On one hand, compliance narrows the path for low-cost, non-conforming competitors and strengthens the moat for established engineering organizations. On the other hand, it imposes design and certification overhead that smaller entrants must manage carefully. Organizations that anticipate specification changes and invest in documented material traceability and locking-system integrity will find it easier to win and retain contracts in regulated segments.
Worldwide Ground Stabilization Geogrid Market
Demand-side behavior and fleet economics
Demand is being shaped less by headline equipment sales alone and more by how operators manage total cost of ownership. The decision to replace a tooth, adapter, or bucket protection system is increasingly evaluated against downtime, labor availability, and the durability of the installed configuration. In markets where skilled labor is scarce, long-life ground engaging tools and systems that reduce handling and installation time carry a premium. In mining, where machine utilization directly influences throughput, complete ground engaging systems that combine teeth, lips, adapters, and wear packages are gaining traction because they simplify specification and reduce variability in wear performance.
PW Consulting
In the aftermarket, the demand picture is broadening as fleets seek compatible wear parts that can be integrated across OEM and non-OEM equipment. A robust aftermarket ecosystem that offers teeth, adapters, cutting edges, blades, end-bits, and wear parts compatible with major manufacturer systems remains attractive to mixed-fleet operators who prioritize flexibility and uptime over single-brand lock-in. The practical insight for buyers is that compatibility, interchangeability, and documented performance across equipment types are becoming as important as the unit price of individual components.
Supply chain and cost structure dynamics
Cost structures are being pressured from both ends. On the input side, carbon steel wear plates and cutting edges are subject to supply constraints and price fluctuations, which can erode margins if not managed through specification discipline and supplier diversification. On the output side, competitive intensity among large, well-capitalized players and capable aftermarket specialists limits how much of those costs can be passed through in price-sensitive segments. The net effect is a strategic emphasis on design efficiency, material optimization, and service economies.
Manufacturers that can standardize high-performing configurations, reduce waste in fabrication, and align inventory with real wear patterns are better positioned to stabilize margins. At the same time, companies that can maintain regional service proximity and quick-turn availability for critical wear parts gain a measurable edge in markets where downtime is costly and logistics are complex.
Competitive Landscape and Strategic Positioning
The market’s moderate concentration reflects a layered competitive structure. Large, multi-brand manufacturers bring engineering scale, broad product lines, and integrated service networks. Specialized mining-focused producers compete on performance in demanding applications, often with differentiated lip, tooth, and wear-package designs. Aftermarket specialists provide broad compatibility and rapid local availability across major systems, enabling mixed-fleet operators to maintain uptime without full OEM dependence. The result is a market where scale, specialization, and service proximity each create distinct competitive advantages.
Several players illustrate how these advantages are being exercised:
- Caterpillar Inc. leverages a full line of ground engaging tools—including cutting edges, teeth, adapters, bucket protection, and Advansys systems—across excavators, wheel loaders, dozers, and mixed fleets. Its strategy emphasizes reducing operating costs and downtime, and recent moves such as extending Cat GET systems to support third-party buckets broaden the addressable market beyond proprietary equipment. This is a clear play to combine engineering credibility with fleet flexibility.
- ESCO Group LLC focuses on engineered lips, teeth, adapters, and full ground engaging systems for mining excavators, rope shovels, wheel loaders, and draglines. Its orientation toward optimizing performance and extending equipment life positions it strongly in mining applications where wear performance and system fit are closely scrutinized.
- Bradken Limited emphasizes high-performance mining ground engaging tools with differentiated solutions such as Zenith Plate Lip and Eclipse Cast Lip, along with bucket wear packages for face shovels, front-end loaders, and backhoe excavators. Its focus on demanding mining applications and periodic catalog refreshes illustrates a commitment to updating product architecture in line with field requirements.
- Sandvik AB provides the Shark™ GET range with Mako™ systems, Blue Pointer 2, profile bars, shrouds, and mechanical locking for underground mining buckets. The emphasis on durability, productivity, and mechanical locking aligns directly with safety and performance expectations in underground mining and demonstrates a systems-level approach to bucket protection.
- ITR America and ITR Africa operate extensive aftermarket lines of teeth, adapters, cutting edges, blades, end-bits, and wear parts compatible with major OEM systems for earthmoving equipment. Their value proposition centers on compatibility and availability across dozers, loaders, and excavators, which is especially relevant for mixed-fleet operators and regions with distributed service needs.
- Cutting Edge Supply offers a full range of aftermarket ground engaging tools—including cutting edges, teeth, adapters, buckets, and attachments—using alloy steels and hardox wear parts. This positions the company as a practical source for operators seeking spec-aligned materials and broad coverage in construction and earthmoving applications.
- Haladjian Mining provides the ESCO® MaxDRP™ Ripper GET systems, teeth, lips, and wear parts for mining dozers and excavators, supported by distributor-level installation activity. Its role highlights how regional execution and system-level offerings can deliver performance improvements in specific mining contexts.
Strategically, the market is evolving along three vectors. First, scale players are extending compatibility and service reach to capture value beyond proprietary equipment, as seen in moves to support third-party buckets with engineered ground engaging systems. Second, mining specialists are refining system designs and lip/teeth architectures to address high-wear conditions more effectively, often refreshing catalogs and product lines in response to field feedback. Third, aftermarket specialists continue to build regional density and compatibility breadth, making them indispensable to operators who manage diverse equipment pools. New entrants face the highest barriers where certification, material traceability, and locking-system integrity are required, but opportunities remain for focused innovators that can deliver differentiated wear performance, faster replacement, or telemetry-compatible service models.
Outlook Through 2032: Three Trends and What They Unlock
Looking ahead three to five years, the market direction is shaped by the convergence of material constraints, safety and specification requirements, and the growing importance of uptime economics. The following trends are likely to define commercial outcomes:
- From replacement parts to performance systems. Buyers will increasingly evaluate ground engaging tools as integrated protection and wear-management systems rather than collections of individual components. This favors manufacturers that can bundle teeth, adapters, lips, and bucket protection into coherent, documented configurations and provide guidance on specification and replacement intervals. Commercial opportunity lies in packaging, compatibility, and service-backed performance guarantees that reduce uncertainty for operators.
- Digital monitoring and data-informed wear management become mainstream. The accelerating adoption of monitored wear systems and digital monitoring technologies will link component design more tightly to usage data and maintenance planning. Over time, this creates opportunities for condition-based replacement, better inventory forecasting, and service offerings tied to actual wear rather than fixed schedules. The risk is that organizations without telemetry-compatible designs or data-driven service capabilities may lose share in fleets that prioritize predictive maintenance.
- Regional differentiation intensifies as cost and service pressures diverge. In price-sensitive segments, competition will remain tight, but in mining and regulated construction environments, durability, safety-compliant locking, and material traceability will command premiums. Regions with strong mining activity or infrastructure build-out will see faster demand growth for high-performance configurations, while mature markets will emphasize aftermarket breadth, component longevity, and mixed-fleet compatibility. Companies that localize service and inventory intelligently will capture more value than those relying on centralized, slow-turn models alone.
Potential risks and uncertainties should be monitored closely. Material price volatility and supply constraints can compress margins if input strategies are not diversified. Changes in safety and material standards can require redesigns and recertification, disproportionately affecting players with limited engineering bandwidth. Labor shortages can both increase demand for long-life tools and disrupt aftermarket execution if service capacity is insufficient. Finally, if monitored wear systems and digital tracking become widely adopted, data ownership and integration with fleet management platforms could emerge as new points of competitive differentiation, introducing vendor-lock-in considerations for operators.
Actionable Guidance for Decision-Makers
The commercial terrain is shifting from unit-price competition toward performance, compatibility, and service-driven value. Different roles in the value chain should respond accordingly.
For manufacturers and product leaders
- Design for system-level value. Prioritize configurations that combine teeth, adapters, lips, and bucket protection in documented packages that reduce specification complexity and downtime. Compatibility with major systems and support for third-party buckets can broaden addressable demand while preserving engineering credibility.
- Build resilience into the cost base. Diversify material sourcing for carbon steel wear plates and cutting edges, maintain spec-aligned documentation for hardox and high-abrasion steel usage, and standardize high-performing configurations to reduce fabrication waste and improve margin stability.
- Prepare for data-linked service. As monitored wear systems and digital monitoring technologies become more common, ensure component designs and service processes can integrate with usage data. This positions the product portfolio for condition-based maintenance offerings and more predictable aftermarket demand.
For investors and strategic planners
- Focus on durability economics. In a market where skilled labor is scarce and downtime is costly, long-life ground engaging tools and safety-compliant locking mechanisms have structural appeal. Evaluate exposure to regulated mining and infrastructure segments where performance and compliance can support stronger pricing power.
- Assess competitive moats by service proximity and compatibility breadth. Aftermarket specialists that combine spec-aligned materials with broad compatibility across OEM systems can sustain demand in mixed-fleet environments. Scale players with integrated service networks and expanding compatibility also warrant attention, especially where they can monetize uptime benefits beyond proprietary equipment.
- Watch for consolidation pressure in regional distribution. As product lines become more system-oriented and monitoring technologies mature, distribution models that can deliver fast-turn availability and technical support will gain importance. Gaps in regional service density may create both acquisition opportunities and execution risks.
For procurement, fleet managers, and contractors
- Specify for total cost of ownership, not just unit price. Evaluate ground engaging tools and systems against durability, replacement time, compatibility with existing equipment, and the reliability of locking mechanisms. In labor-constrained environments, designs that are durable and easy to service can reduce hidden costs that are often larger than the component price itself.
- Standardize where it pays. For mixed fleets, prioritize wear parts and systems with proven compatibility across major manufacturer configurations to simplify stocking, reduce errors, and keep equipment running. Documented performance and safety-compliant designs should be weighted alongside cost when making specification decisions.
- Plan inventory around real wear patterns. As monitored wear systems become more widespread, align stocking and replacement planning with actual usage data rather than fixed intervals. This reduces both stockouts and overstock, especially for high-wear applications in mining and heavy construction.
The most consequential decisions in this market will be made by organizations that can translate material constraints, safety requirements, and uptime economics into coherent product, sourcing, and service strategies. For readers seeking a more detailed segmentation view, regional demand pathways, and tailored recommendations for specific equipment categories and growth markets, the full PW Consulting study on the Ground Engaging Tools market provides deeper sub-segment data and customized guidance to support planning with precision.
For detailed analysis of this topic, please visit the official page: Ground Engaging Tools (GET) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Remittance Market 2026: Why 15.8% CAGR Growth Changes Everything
By pmarketresearch, 2026-09-21
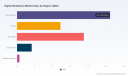
The Digital Remittance Market: Strategic Trends and Commercial Opportunities in a Rapidly Evolving Landscape
Market Overview and Core Challenges
The digital remittance market has transitioned from a niche convenience to a fundamental infrastructure layer for global money movement. Between 2020 and 2025, the sector expanded from approximately $8.7 billion to nearly $24.9 billion, reflecting a compound annual growth rate of 15.8% over the period. Looking ahead to 2032, trajectory modeling suggests the market will reach roughly $69.4 billion, sustained by the same structural forces that accelerated adoption over the past half-decade. Growth is not uniform across all segments, but the overall expansion signals a durable shift away from cash-dependent, branch-heavy transfer models toward digital, mobile-first, and increasingly automated channels.
Despite the headline momentum, the industry sits at a critical inflection point. Three interconnected challenges define the current environment. First, regulatory fragmentation continues to raise the cost of cross-border compliance, particularly for providers operating across multiple jurisdictions with divergent anti-money laundering and consumer protection standards. Second, the economics of last-mile delivery remain strained, especially in markets where telecommunications infrastructure costs, spectrum licensing, and agent network maintenance compress margins. Third, customer expectations have reset the competitive baseline: speed, transparency, and low friction are no longer differentiators; they are table stakes, which puts pressure on incumbent cost structures and forces continuous reinvestment in technology and partnerships.
These pressures are not purely defensive. They are reshaping who can compete, how value is captured, and where the next wave of margin improvement will originate. For decision-makers, the practical question is not whether digital remittance will keep growing, but which structural shifts will determine winners and laggards over the next several years.
Key Drivers of Market Change
Technological Innovation and Platform Integration
Technology is compressing the distance between origination and receipt while simultaneously lowering the marginal cost of each transfer. Mobile applications, messaging-based interfaces, and wallet integrations are extending reach into contexts where traditional banking penetration is limited but smartphone and data connectivity are expanding rapidly. Real-time payment rails, programmable settlement, and API-first infrastructure are enabling providers to embed remittance capabilities into broader financial and commercial workflows rather than treating them as standalone transactions.
The shift toward messaging and conversational interfaces illustrates how product design is expanding access. Recent product launches have shown providers using familiar communication platforms to reduce friction for both senders and recipients, including features that allow recipients to initiate requests directly and expansions of message-based sending into additional countries. In parallel, stablecoin-based settlement experiments are being used to test faster, more predictable cross-border movement of value, particularly where traditional correspondent banking routes are slow or expensive. These developments do not replace the need for strong compliance and liquidity management, but they do change the operating model by moving more of the transaction lifecycle into digital, traceable, and automatable workflows.
Policy and Regulatory Environment
Regulation remains one of the most powerful levers shaping market structure, cost, and speed. In the United States, new federal excise tax provisions on certain remittance transfers funded by cash, money orders, or cashier's checks have introduced a differentiated cost environment, with digitally funded transfers using bank or card sources exempt from the tax. Proposed regulatory clarifications around the scope of remittance transfer taxation further signal that policymakers are actively defining which channels and funding methods fall under new obligations. For operators, this creates both a pricing dynamic and a strategic incentive to steer customers toward digital funding paths that are more efficient from a tax and compliance standpoint.
At the same time, international regulatory bodies have been tightening expectations around risk-based oversight for digital channels. Guidance emphasizing AML/CFT compliance for digital remittance providers reflects a broader push to ensure that faster, more automated channels do not weaken oversight. Complementary analysis from multilateral forums has highlighted persistent licensing and regulatory barriers that can slow digitization, particularly for non-bank providers seeking to operate across borders. The net effect is a market where compliance capability is becoming a competitive asset rather than a back-office function. Providers that can align product design, onboarding, monitoring, and reporting with evolving requirements are better positioned to scale without running into structural bottlenecks.
Shifts in Consumer and Business Behavior
Demand-side behavior is changing on two tracks. For personal users, the expectation is increasingly about seamless, low-cost, and trackable transfers that fit into daily digital routines. Senders want clarity on fees and exchange rates, while recipients often prefer immediate availability through local wallets, bank accounts, or cash pickup where digital liquidity is not yet universal. This dual expectation pushes providers to offer multiple payout options and to optimize for local relevance rather than a single global template.
On the business side, cross-border payments are becoming more embedded in operational workflows. Companies that source, pay, or employ across jurisdictions need predictable settlement, multi-currency management, and automation that reduces manual intervention. This has increased interest in infrastructure-oriented solutions that connect enterprises to local payout networks and provide FX and payment capabilities in a more integrated form. As a result, the market is not only expanding in volume but also broadening in use cases, with business-driven flows becoming a meaningful component of overall digital remittance activity.
Cost Structure and Infrastructure Dynamics
The cost side of the market is being redefined by both technology and local infrastructure conditions. Digital channels can reduce some legacy handling costs, but they do not eliminate the expense of maintaining liquidity, managing FX exposure, meeting compliance requirements, and delivering reliable last-mile payouts. In some regions, telecommunications and spectrum-related costs add measurable pressure to the operating environment, affecting the economics of mobile-based delivery and agent-supported networks. Where infrastructure costs are elevated, providers must either absorb them, pass them through carefully, or redesign distribution to reduce dependence on high-cost pathways.
This creates an opportunity for differentiation based on distribution efficiency. Providers that can combine digital onboarding with optimized payout routing, selective partnerships, and stronger working capital management can improve unit economics even in challenging local conditions. Conversely, operators that rely on high-cost legacy touchpoints without sufficient automation may find margin expansion difficult, especially as customers compare experiences across increasingly transparent pricing environments.
Competitive Landscape and Leading Strategies
The competitive field blends established global transfer brands, technology-native platforms, and infrastructure-focused providers. Each group is pursuing a different angle of value creation, and the landscape is evolving through a mix of expansion, consolidation, and targeted partnership activity.
Several leading players have built their positioning around transparency, speed, and channel convenience. Some emphasize predictable exchange rates and low-cost bank-funded transfers, appealing to users who prioritize clarity and efficiency. Others leverage extensive agent and pickup networks alongside digital channels, preserving cash-oriented access while modernizing the front end. A third cohort focuses on platform and messaging integration, using familiar consumer touchpoints to expand reach and reduce onboarding friction. These divergent approaches reflect different assumptions about where the biggest growth and retention leverage lies: price transparency, physical reachability, or digital convenience.
A separate but increasingly important set of players operates more as enabling infrastructure than as consumer-facing brands. These providers supply cross-border payment and remittance capabilities to fintechs, banks, and enterprises, often emphasizing real-time settlement, multi-currency accounts, and localized payout capabilities. Their growth illustrates a broader trend: as more entities seek to embed international money movement into their own products or operations, the demand for robust backend rails and compliance-ready integrations is rising.
PW Consulting
Recent activity shows how companies are trying to extend their advantage. One global provider expanded a messaging-based sending feature into additional markets and introduced a recipient-initiated request capability, reinforcing a strategy centered on reducing friction and increasing engagement through familiar communication channels. Another major player introduced a stablecoin tied to its remittance network, signaling an interest in using digital asset infrastructure to support faster settlement and network expansion. A separate cross-border platform secured a partnership to enable transfers directly into a major regional wallet and linked bank accounts, highlighting the continued importance of local payment system access in high-volume markets.
Digital Insurance Market
Taken together, these moves point to a market that is both consolidating around strong digital brands and fragmenting through specialized infrastructure plays. Incumbents are modernizing distribution and experimenting with new settlement models, while newer and mid-sized players are carving out niches based on enterprise needs, regional payout strength, or integration depth. The likely trajectory over the next few years is not a single dominant model, but a layered ecosystem in which consumer-facing brands, B2B infrastructure providers, and local access partners compete and cooperate simultaneously.
Future Trends and Commercial Opportunities
Deeper Integration of Messaging, Wallets, and Embedded Flows
Over the next three to five years, digital remittance is likely to become less visible as a standalone product and more embedded into everyday digital interactions. Messaging-based requests, wallet-to-wallet movement, and integration with broader financial apps will continue to reduce the steps between intent and completion. For commercial players, this creates opportunities to design products that are not just about moving money, but about supporting the surrounding workflows: bill payment, family support, supplier settlement, and payroll-related cross-border needs. The winners will be those that can make the transfer experience feel local, immediate, and contextually relevant rather than generic and transactional.
Regulatory Capability as a Competitive Moat
As tax rules, licensing expectations, and compliance guidance continue to evolve, regulatory competence will increasingly separate scalable operators from those that face repeated friction. Providers that invest early in compliant digital onboarding, transaction monitoring, and transparent funding-path design will be better placed to manage cost exposure and expand into new corridors. There is also an opportunity for providers that can help customers navigate differentiated tax and funding environments by steering them toward more efficient digital channels, provided this is done with clear communication and strong compliance foundations. In practical terms, regulatory readiness will become part of the product value proposition, not just a legal requirement.
Stable Settlement Innovation and Corridor-Specific Optimization
Experiments with stablecoin-based settlement and other digital asset infrastructure are likely to mature in select corridors where speed, FX certainty, and liquidity management matter most. This does not imply uniform adoption across all markets; instead, it suggests a corridor-by-corridor optimization dynamic. Where traditional rails are slower or more expensive, digital settlement layers may offer meaningful improvements, especially when paired with strong local payout partners and robust risk controls. The commercial opportunity lies in identifying which corridors benefit most from alternative settlement, building reliable liquidity and compliance support around them, and integrating these capabilities without disrupting the customer experience.
These trends carry risks. Regulatory changes can shift cost structures quickly, especially where tax treatment or licensing rules differentiate between funding methods or provider types. Infrastructure costs in certain regions can constrain distribution economics, making it harder to scale without a tailored model. FX volatility, liquidity management, and fraud or misuse risks remain persistent challenges in any high-volume cross-border environment. Finally, customer adoption can be uneven: digital convenience expands reach, but not every recipient market is ready for fully digital payout, which means hybrid models will remain necessary for years.
Strategic Recommendations for Decision-Makers
For executives, investors, and operators evaluating the digital remittance space, the most useful lens is to treat the market as a set of shifting cost, compliance, and distribution dynamics rather than as a simple volume growth story. The following actions can help translate that perspective into better decisions.
Digital Banking Market
- Align product and funding-path design with the changing cost and tax environment. Where digital bank- or card-funded transfers carry different implications than cash-based funding, optimize the experience to make the more efficient path attractive and easy to use, while maintaining clear customer communication and compliance integrity.
- Invest in compliance and operational scalability as core product capabilities. Strong onboarding, monitoring, reporting, and licensing readiness should be treated as enablers of expansion, especially for providers planning to enter new corridors or serve business customers with higher documentation and control expectations.
- Build corridor-specific distribution strategies instead of relying on a single global template. Local payout preferences, wallet penetration, agent networks, and infrastructure costs vary widely. Tailoring routing, partnerships, and payout options to local conditions can improve unit economics and customer satisfaction more reliably than standardizing every market.
- Evaluate infrastructure and partnership plays for enterprise and embedded use cases. As more businesses and platforms seek integrated cross-border payment capabilities, there is room to capture value by providing reliable rails, multi-currency management, and localized settlement support, particularly when paired with strong FX and automation features.
- Monitor settlement innovation selectively and operationally. Where alternative settlement models can improve speed or cost in specific corridors, test them with disciplined risk controls and liquidity management. Avoid broad commitments until the corridor economics, regulatory stance, and customer readiness are well understood.
The strategic value of detailed intelligence in this market is high because the differences between corridors, funding paths, compliance regimes, and distribution models can decisively affect profitability and scalability. Broad market narratives are useful for orientation, but operational decisions depend on finer-grained insight into where growth is concentrated, which channels are most efficient, how regulatory changes alter cost structures, and which partnership or infrastructure models fit a given business profile. For leaders who need that level of clarity, a full research report can provide the segmented data, corridor-level context, and customized strategic guidance necessary to move from directional confidence to executable planning.
For detailed analysis of this topic, please visit the official page: Digital Remittance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydro Turbine Generator Market: The 5.0% CAGR Shift from Asia Pacific and Francis Turbines
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Hydro Turbine Generator Units Market
The global hydro turbine generator units market has entered a phase of measured but meaningful expansion, underpinned by a decade of steady capital deployment and a clear shift toward modernizing aging assets. The market, valued at approximately $2.6 billion in 2020, reached an estimated $3.5 billion in 2025, with projections indicating a trajectory toward $5.4 billion by 2032. This growth path corresponds to a compound annual growth rate of roughly 5.0 percent, reflecting a market that is expanding at a pace consistent with broader infrastructure and clean energy investment cycles while avoiding the volatility often seen in nascent technology segments.
The trajectory is not a simple function of new capacity additions. Instead, it reflects a layered dynamic: new large-scale projects continue to contribute, but the dominant near-term driver is the rehabilitation, uprating, and digital modernization of existing installations. This structural shift matters for commercial strategy because it changes the nature of demand from episodic greenfield events to a more continuous pipeline of service, component replacement, and efficiency upgrades. For decision-makers, the consequence is straightforward: the market's center of gravity is moving toward lifecycle value, performance reliability, and the ability to extract more output from existing water infrastructure.
Core Challenges and Inflection Points
Despite the positive outlook, the market faces a set of practical challenges that shape how value is created and captured. One of the most significant is the tension between long project lead times and the urgency of decarbonization and grid modernization. Hydropower development typically requires extended permitting, environmental review, and civil engineering preparation. This creates a mismatch between political or corporate ambition and execution speed, particularly in regions where regulatory processes are still evolving. The result is a market where strategic planning must account for multi-year horizons, and where companies that can compress timelines through modular design, standardized equipment, or strong local execution capability gain a durable advantage.
A second challenge lies in cost structure variability and supply chain sensitivity. Turbine and generator projects involve substantial steel-intensive manufacturing, specialized machining, and customized engineering tied to site-specific hydraulic conditions. Cost ranges can vary widely depending on unit size, turbine type, and installation complexity, which means margin discipline depends heavily on scope control, localization, and the ability to manage input cost fluctuations. At the same time, trade dynamics are shifting. In the United States, for example, imports of hydraulic turbines rebounded significantly in 2024, signaling that domestic demand is not always matched by local manufacturing capacity alone. This underscores the importance of understanding where procurement will be sourced, how logistics affect final delivery, and which suppliers can offer both technical credibility and regional responsiveness.
A third inflection point is the growing importance of the upgrade and rehabilitation segment. In the U.S. alone, capacity additions from turbine-generator upgrades amounted to hundreds of megawatts as of mid-2025, a clear sign that existing plants are becoming a major source of new productive output. This trend is not merely a short-term substitute for greenfield development; it reflects a deliberate strategy to increase generating efficiency, extend asset life, and improve grid reliability without the full cost and risk of new dam construction. For equipment suppliers and service providers, the implication is that aftermarket capability, retrofits, and performance optimization are becoming strategic rather than supporting activities.
Key Drivers Shaping Market Direction
Technology Innovation and Performance Enhancement
Technical advances are reshaping what hydro assets can deliver. One of the most commercially relevant shifts is the continued uprating of existing turbine-generator sets to increase output without proportionally expanding civil works. Recent large-scale rehabilitation projects demonstrate this pattern clearly: at Old Hickory Power Plant, Kaplan units were replaced and uprated from 25 MW to 45 MW each, expanding productive capacity enough to support roughly 125,000 homes. This kind of outcome is compelling for asset owners because it combines higher generation with retrofit execution rather than entirely new construction.
Beyond output gains, digitalization and automation are increasingly central to how hydropower equipment is specified and operated. Modernization contracts now frequently include controls, supervision, testing, and commissioning as integrated parts of the package, not optional add-ons. This reflects a broader market expectation that turbine generator units should be delivered with better integration between mechanical hardware and plant-level intelligence. As a result, companies that can provide both electro-mechanical equipment and the systems that optimize performance over time are positioned more strongly than those competing on hardware alone.
Policy and Regulatory Environment
Policy stability is a decisive factor in hydropower investment, and recent developments have reinforced the attractiveness of conventional hydro and pumped storage in several markets. In the United States, legislation signed in 2025 retained key investment and production tax credits for conventional hydropower and pumped storage through 2033. This continuity reduces uncertainty for long-cycle projects and strengthens the financial case for both new installations and major upgrades. For commercial strategy, the practical implication is that policy support is no longer just a background condition; it is a planning variable that affects project timing, financing structures, and the relative appeal of different technology choices.
At the same time, grid connection reform is becoming a critical enabler. Regulatory bodies in several regions have moved to reduce speculative project entries and accelerate the integration of pumped storage and hydropower into system planning. When grid access becomes more predictable, hydropower projects can progress with less risk of delays that erode returns. This is especially relevant for turbine generator suppliers, because faster and more reliable connection pathways improve the prospects for equipment orders and reduce the chance that projects stall before procurement decisions are finalized.
Demand-Side Shifts and Asset Owner Priorities
Demand is being shaped not only by new generation targets but also by how utilities, public authorities, and independent operators view hydropower within a broader energy mix. Hydropower is increasingly valued for dispatchability, storage potential, and its ability to complement variable renewables. That changes the purchasing lens: buyers are less focused solely on lowest initial equipment cost and more attentive to reliability, uptime, service responsiveness, and the ability to integrate with evolving grid requirements.
This shift is visible in the types of contracts being awarded. Large rehabilitation and modernization orders are being placed with suppliers capable of delivering turbines, generators, and associated auxiliaries as part of coordinated projects. The demand pattern suggests that asset owners prefer fewer, more integrated partnerships over fragmented procurement, particularly where projects involve complex installation supervision and commissioning. For suppliers, this means the commercial battleground is moving toward capability breadth, execution credibility, and lifecycle support rather than unit price alone.
Supply Chain and Cost Structure Dynamics
Cost structure remains one of the most practical drivers of competitiveness. Hydropower equipment manufacturing is capital intensive and strongly influenced by the cost of steel, machining capacity, and skilled labor. Because turbine and generator costs can vary substantially by size and type, project economics are sensitive to manufacturing efficiency, sourcing strategy, and the ability to standardize where possible without compromising site-specific performance.
The supply chain is also showing signs of regional rebalancing. Increased import activity in certain markets indicates that local manufacturing does not always meet demand in the near term, while international suppliers with strong project execution records continue to win major orders. At the same time, the rehabilitation pipeline is creating demand for specialized components, retrofits, and replacement units that require both technical precision and timely delivery. Suppliers that can manage this balance—offering proven designs, reliable manufacturing, and responsive project support—are likely to capture disproportionate share in a market where downtime and schedule risk are costly.
Competitive Landscape and Leading Strategies
Strategic Positioning of Major Players
The market is characterized by a meaningful degree of concentration, but it also contains a diverse set of participants with distinct positioning. Large, full-line suppliers have an advantage in major projects because they can deliver turbines, generators, automation, and associated auxiliaries within a coordinated framework. This breadth reduces integration risk for buyers and supports more complex rehabilitation or new-build programs. Companies with established footprints in both large and small hydro are particularly well placed to capture demand across a range of project sizes, which is valuable in a market where opportunities are dispersed across regions and asset classes.
Differentiation is increasingly tied to execution track record and service integration rather than product presence alone. Recent activity illustrates this pattern. ANDRITZ, for instance, has continued to secure substantial orders for both rehabilitation and new equipment, including modernization work in Thailand, a major rehabilitation order in Mozambique, and equipment orders for new Austrian projects. These assignments reinforce a positioning based on large-scale electro-mechanical supply, project supervision, and commissioning capability. GE Vernova has similarly engaged in refurbishment work, reflecting the strategic importance of established relationships in upgrading existing assets. Siemens Energy's emphasis on automation and controls aligns with the broader market shift toward integrated plant-level solutions.
In the smaller and medium-scale segment, the competitive logic is different. Here, specialization, design flexibility, and suitability for lower-head or constrained sites can matter more than full-line scale. Suppliers focused on micro and small hydro often compete on ease of deployment, material choices, and fit-for-purpose turbine designs. This creates room for niche players to build strong positions in specific geographies or application profiles, particularly where site conditions favor compact or specialized equipment.
Market Evolution: Consolidation, Differentiation, and Entry Dynamics
The competitive landscape appears to be evolving along several axes at once. On one side, large projects continue to reward suppliers with global reach, robust engineering capacity, and the ability to manage complex delivery. On the other, the rehabilitation trend is creating demand for companies that can respond quickly with retrofit expertise and reliable aftermarket support. This dual structure encourages both consolidation among players seeking broader capability bundles and differentiation among those serving specialized niches.
New entry is possible but not trivial. The market's technical demands, long project cycles, and need for proven reliability raise barriers for entrants lacking manufacturing scale or documented project experience. However, the spread of small and medium hydro opportunities, along with the continued relevance of modernization work, means that focused suppliers can still build defensible businesses by concentrating on specific turbine types, regional markets, or application segments. The most durable positioning tends to combine technical credibility with the ability to execute reliably in local conditions.
Future Trends and Commercial Implications
Trend One: Rehabilitation and Uprating as a Core Growth Engine
Over the next three to five years, rehabilitation and uprating are likely to remain central to market growth. Many existing plants operate with equipment that can be upgraded to improve output, efficiency, and reliability. As utilities and public operators face pressure to maximize the value of existing infrastructure, the commercial opportunity will increasingly lie in offering upgrade packages that include turbine and generator replacement, controls modernization, and commissioning support. This trend benefits suppliers with strong field service capabilities and the ability to design retrofits that minimize downtime and integration risk.
Worldwide Geothermal Turbines Market
For investors and manufacturers, the strategic implication is that lifecycle-oriented offerings should be treated as a primary growth path rather than a secondary revenue stream. The ability to bundle equipment with performance improvements and service continuity can strengthen margins and customer retention, especially in markets where new construction is constrained by permitting or capital availability.
Trend Two: Greater Integration of Digital and Automation Solutions
A second trend is the deepening integration of automation, control systems, and performance monitoring into hydro turbine generator packages. As grid requirements become more demanding and asset owners look for better operational visibility, equipment purchases are increasingly evaluated through the lens of plant-level outcomes rather than isolated component specification. Suppliers that can deliver coordinated hardware and control strategies will be better positioned to win complex bids and support long-term value creation.
This trend also creates opportunities in predictive maintenance, efficiency optimization, and remote performance support. Even where the core turbine generator hardware remains the cornerstone of the transaction, the value of complementary digital services is likely to rise. Companies that treat digital capability as integral to the product—not an afterthought—can differentiate in a market where many competitors offer similar mechanical solutions.
The related implication for procurement and planning is that buyers should evaluate suppliers based on total system performance and support capacity, not just initial equipment specifications. In practice, this means giving weight to installation supervision, testing, commissioning, and post-delivery service when comparing bids.
Trend Three: Regional Rebalancing and Supply Chain Adaptation
A third trend is likely to be continued regional variation in demand and sourcing. Some markets will lean more heavily on imports or international suppliers for specialized equipment, while others will seek greater localization to reduce logistics risk or support domestic industrial policy. This uneven landscape will reward suppliers with flexible manufacturing, strong logistics coordination, and the ability to adapt offerings to regional procurement expectations.
The commercial opportunity here lies in building regional relevance without abandoning global technical standards. Suppliers that can combine engineering consistency with local partnerships, service presence, or manufacturing proximity are well placed to navigate this environment. At the same time, project developers and procurers should monitor trade and import patterns closely, because shifts in sourcing can affect lead times, cost estimates, and the resilience of project schedules.
Risks and Uncertainties
These trends are promising, but they are not without uncertainty. Hydropower projects remain vulnerable to permitting delays, environmental scrutiny, and long approval cycles. Cost pressures in steel and skilled labor can affect both project viability and supplier margin structure. Policy support may be strong in some jurisdictions but less predictable in others, creating uneven conditions across regions. In addition, grid connection reforms and integration processes can accelerate or slow project development depending on local implementation. These variables mean that market opportunity should be assessed with an explicit focus on where execution risk is manageable and where supplier capabilities match the project environment.
PW Consulting
Strategic Actions for Decision-Makers
For Manufacturers and Equipment Suppliers
Position the portfolio around lifecycle value. Growth in rehabilitation and uprating means that successful suppliers will need to compete as much on retrofit capability, service integration, and uptime performance as on new-unit specifications. Investing in modernization packages, controls compatibility, and field execution strength can create a clearer competitive edge than competing on equipment breadth alone.
Build regional responsiveness without sacrificing technical consistency. Where import patterns and local procurement expectations are shifting, the ability to provide reliable delivery, localized support, and adaptable project execution can matter as much as the core product. For companies serving multiple geographies, this may mean strengthening partnerships, service footprints, or manufacturing flexibility in strategically important markets.
Emphasize integrated delivery where it matters most. Many large orders now include turbines, generators, auxiliaries, and commissioning in a single program. Suppliers that can reduce integration risk for buyers and coordinate complex delivery are more likely to win preference in competitive situations, especially where asset owners seek to streamline procurement and minimize coordination burden.
For Investors
Evaluate the rehabilitation and service opportunity as a structural part of the market, not a cyclical add-on. Upgrading existing plants offers a more predictable demand environment in some regions than entirely new hydro development, and it can provide recurring revenue potential through service and modernization activity. Projects or companies with strong aftermarket capability and established relationships with asset owners may be better positioned to capture this value.
Hydroelectric Generator Repair Market
Watch for policy and grid connection developments as leading indicators. Tax credit continuity, storage-related incentives, and grid integration reforms can materially affect project pacing and the attractiveness of hydropower investments. Understanding where these conditions are most supportive can help prioritize where to allocate attention and capital.
Assess supply chain resilience as part of the investment thesis. Because hydropower equipment is steel-intensive and project-specific, sensitivity to input costs, manufacturing capacity, and logistics is high. Companies with disciplined cost control, diversified sourcing, and proven execution are more likely to sustain margins through market variability.
For Procurement and Asset Owners
Prioritize total value over lowest initial price. In a market where rehabilitation, uprating, and integration are increasingly important, long-term performance, commissioning support, and service availability can have a greater effect on project outcomes than headline equipment cost. Procurement strategies should reflect this by weighting reliability, service responsiveness, and system integration in supplier evaluations.
Align procurement with the asset strategy. If the goal is to increase output from existing infrastructure, consider suppliers with demonstrated retrofit and uprating experience. If the goal is new capacity, focus on vendors with strong project delivery records and the ability to manage civil-mechanical-electrical integration. Matching supplier capabilities to the specific project type reduces execution risk and improves the chance of achieving performance targets.
Keep market intelligence current. Policy, trade patterns, and rehabilitation pipelines are shifting in ways that affect timing, sourcing, and cost. Because these variables can change faster than individual project cycles, access to detailed and updated market information is valuable for procurement planning, bid evaluation, and strategic capacity decisions.
Conclusion
The hydro turbine generator units market is expanding at a steady and strategically meaningful pace, driven by a combination of modernization demand, policy support, grid integration needs, and continued interest in hydropower's dispatchable value. The most important commercial shift is not simply that the market is growing, but that growth is increasingly tied to upgrading existing assets, integrating automation and controls, and competing on lifecycle performance as much as on equipment specification. For manufacturers, suppliers, investors, and asset owners alike, the opportunity lies in aligning capabilities with these realities: strong execution, reliable service, regional responsiveness, and the ability to deliver outcomes that matter over the full life of the asset. In a market where procurement decisions increasingly hinge on long-term performance and integration, detailed market intelligence becomes a practical tool for reducing risk and identifying where value can be captured most effectively.
For detailed analysis of this topic, please visit the official page: Hydro Turbine Generator Units Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Differential Pressure Sensors Market: Why 5.14% CAGR and Industrial Shifts Redefine Growth 2026–2032
By pmarketresearch, 2026-09-21
Differential Pressure Sensors Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global differential pressure sensors market has entered a phase of steady, technology-driven expansion. Valued at approximately 158.35 million USD in 2020, the market reached 200.05 million USD by 2025, with a projected compound annual growth rate of 5.14 percent through 2032. This trajectory reflects a mature yet evolving landscape where incremental performance gains, regulatory pressures, and shifting end-use demand converge to reshape competitive dynamics. For executives and investors, the market no longer operates as a commodity trade. It has become a battleground for precision, integration, and ecosystem alignment.
Behind the headline growth figures lies a more nuanced reality. The industry is navigating intense price compression, shifting trade policy exposure, and supply chain reconfiguration. These forces are not merely cost considerations; they are structural inflection points that will determine which players capture value in the next cycle and which remain trapped in margin erosion.
Market Snapshot and Structural Pressures
The revenue base has grown consistently over the past half-decade, but the composition of that growth reveals underlying tensions. Silicon-based sensing architectures dominate the product mix, leveraging economies of scale and compatibility with semiconductor manufacturing ecosystems. Metal and ceramic diaphragm variants maintain relevance in environments demanding corrosion resistance, mechanical robustness, or extreme operating conditions. Across applications, the market is anchored by industrial process control, HVAC systems, and automotive use cases, with medical devices and adjacent segments contributing steady, specialized demand.
Despite this breadth, three structural challenges are reshaping strategic decision-making:
- Sustained pricing pressure. Advances in semiconductor fabrication and broader competition are gradually pulling down average selling prices. Manufacturers that rely on volume without differentiated performance or integration capabilities face margin compression.
- Trade policy exposure. Tariff dynamics on pressure sensor imports have introduced pricing uncertainty and supply chain risk, particularly for manufacturers dependent on cross-border component flows. US-China trade tensions have further complicated import scenarios, forcing regional sourcing reevaluation and inventory strategy adjustments.
- Raw material and input volatility. Silicon wafers, specialty alloys, stainless steel, and engineering plastics form the backbone of sensor production. Procurement timing, supplier concentration, and distributor network quality directly influence cost structure and delivery reliability, especially for MEMS-based devices where material consistency is critical.
These pressures do not signal contraction. They signal a transition from unc differentiated supply to performance-anchored value creation. The companies that navigate this transition successfully will treat cost management, compliance readiness, and material strategy as competitive advantages rather than operational afterthoughts.
Key Demand and Supply Drivers Reshaping the Market
The market’s next phase of growth will be driven by factors that extend well beyond incremental unit volume increases. Four forces stand out as particularly consequential for strategic planning.
Technological Innovation and Sensor Integration
MEMS-based differential and gauge pressure sensors continue to expand their addressable range, with differential configurations reaching typical ranges up to 10 kPa in industrial, automotive, and consumer applications. Simultaneously, digital and board-mount formats are reducing the integration burden for original equipment manufacturers. Compact sensors with flexible interface options and multiple port configurations are becoming viable for embedded HVAC, medical instrumentation, and smart building controls. This trajectory lowers system-level engineering costs and opens opportunities for sensor fusion with airflow, temperature, and IAQ monitoring functions.
The commercial implication is clear. Differentiation is shifting from the sensor element alone to the surrounding value proposition: calibration stability, digital output readiness, integration ease, and application-specific tuning. Manufacturers that invest in interface flexibility, compact packaging, and robustness for embedded use cases are positioning themselves for volume growth in environments where space, reliability, and ease of deployment matter more than ever.
Regulatory and Standards Pressure in Building, Industrial, and Medical Sectors
Regulatory expectations around indoor air quality, energy efficiency, and process safety are tightening across multiple regions. In building automation, digital air differential pressure sensors are being deployed to enable smarter IAQ monitoring, fan energy reduction, and predictive maintenance workflows. In industrial process control, accuracy and repeatability requirements continue to push specification boundaries, particularly where differential readings influence control loops, leak detection, and filter monitoring. Medical applications add another layer of scrutiny, where sensor performance must align with clinical reliability expectations and device-level certification pathways.
For market participants, the regulatory environment is a double-edged sword. It raises compliance and validation costs, but it also creates stickier demand and longer product lifecycle relevance. Suppliers that can demonstrate consistent performance, documentation readiness, and application-specific validation are more likely to secure design-in positions in regulated end markets.
Pressure Sensors Market
Demand-Side Behavior and Application Diversification
End-use buyers are increasingly prioritizing system-level outcomes over isolated sensor specifications. In HVAC and building automation, the focus is on airflow management, energy optimization, and maintenance forecasting. In automotive and industrial settings, demand is shaped by electrification, tighter emissions expectations, and the need for robust measurement under variable operating conditions. Medical device manufacturers continue to seek low-differential and high-accuracy solutions for respiratory, filtration, and diagnostic applications.
This behavior change is reshaping procurement and design-in criteria. Buyers evaluate total cost of ownership, integration complexity, firmware or software compatibility, and supplier support for application engineering. The market is rewarding participants that can map sensor capabilities to end-use workflows rather than simply compete on discrete performance numbers.
Supply Chain Reconfiguration and Cost Structure Evolution
The input ecosystem for differential pressure sensors is adapting to new realities. Silicon and semiconductor material distributors are strengthening supply chain arrangements to support MEMS-based sensor production. At the same time, raw material procurement across silicon, stainless steel, specialty alloys, and plastics remains a sensitivity point that influences the value chain for pressure transducer production. Combined with tariff exposure and regional sourcing considerations, cost structures are becoming more variable and less predictable.
Strategically, this favors organizations that diversify supplier coverage, secure critical input capacity, and design for manufacturability with material availability in mind. It also favorsParticipants that can tolerate short-term cost fluctuations by offering higher reliability, accuracy, or integration value that reduces downstream rework and system failures.
Competitive Positioning and the Evolution of the Vendor Landscape
The competitive field is broad and heterogeneous, spanning semiconductor-oriented manufacturers, instrumentation specialists, industrial automation providers, and application-focused innovators. Market concentration remains moderate, indicating room for differentiation but also reflecting the fragmented nature of end-use requirements. Several companies illustrate distinct strategic postures within the market.
NXP Semiconductors focuses on MEMS-based differential and gauge pressure sensors with differential ranges up to 10 kPa, targeting industrial, automotive, and consumer applications. This positioning emphasizes semiconductor manufacturing leverage, integration potential, and broad application coverage. Honeywell International Inc. emphasizes differential pressure transducers and switches for building automation and HVAC, aligning with demand for reliable control and airflow monitoring in built environments. TE Connectivity offers piezoresistive and MEMS pressure sensors and transducers with wide pressure ranges, supporting applications that require flexibility across operating conditions and robust transducer architectures.
Robert Bosch GmbH and Denso Corporation both maintain strong footprints in automotive and industrial pressure sensing, including differential variants. Their relevance lies in the ability to align sensor performance with vehicle platforms, industrial equipment, and volume production requirements. ABB Ltd and IFM electronic GmbH concentrate on industrial process automation and control-oriented sensing, where reliability, transmitter integration, and process compatibility are paramount. Sensata Technologies spans automotive, industrial, and medical applications, positioning around breadth and application-specific pressure sensor portfolios.
In more specialized niches, Setra Systems uses capacitive sensing for industrial differential pressure transducers in HVAC and cleanroom environments, where stability and low-pressure accuracy matter. Omega Engineering addresses industrial and OEM applications with pressure sensors and transducers, while WIKA Alexander Wiegand SE & Co. KG and Keller AG für Druckmesstechnik focus on measurement technology for harsh environments and industrial differential use cases. Ashcroft Inc. complements this industrial emphasis with pressure gauges and transducers for demanding service conditions.
PW Consulting
The digital and embedded segments are gaining visible momentum. Sensirion AG offers digital differential pressure sensors for high-volume applications, supporting integration into automated and connected systems. Würth Elektronik introduced the WSEN-PDMS series, a compact, highly accurate differential pressure sensor for embedded HVAC and medical applications, with multiple port configurations and flexible interfaces. Belimo Automation AG launched a new Air Differential Pressure Sensor within its New Digital Generation line at the AHR Expo, enabling smart IAQ monitoring, fan energy reduction, and predictive maintenance through the Belimo Assistant 2 App. All Sensors Corporation targets ultra-low differential pressure sensors for medical and industrial use, while Superior Sensor Technology focuses on high-accuracy differential pressure sensors for semiconductor and industrial applications.
Industrial Differential Pressure Transducers Market
This landscape reveals several strategic patterns. First, competition is increasingly bifurcated between semiconductor-enabled integrators and application-focused instrumentation specialists. Second, digital connectivity, app-based monitoring, and predictive maintenance features are becoming differentiators in building and IAQ-related applications. Third, the market remains open enough for niche players to compete on ultra-low pressure ranges, harsh-environment robustness, board-mount compactness, or application-specific validation. Consolidation is possible where vertical integration, portfolio breadth, or regional reach creates scale advantages, but fragmentation persists where end-use specialization and customization remain decisive.
Forward-Looking Trends and Commercial Implications (2026–2032)
Looking ahead, three trends are likely to shape the market over the next three to five years.
Trend 1: Embedded Digital Sensing Becomes the Default for Smart Building and IAQ Applications
Digital differential pressure sensors with connectivity, software integration, and monitoring app compatibility are poised to gain share in HVAC and building automation, particularly where airflow optimization and predictive maintenance are priorities. This trend creates commercial opportunities for suppliers that can deliver not only sensing accuracy but also firmware readiness, communication compatibility, and support for integration into broader building management ecosystems. The risk, however, lies in execution complexity: software support, interoperability expectations, and cybersecurity considerations can become adoption barriers if not addressed early.
Trend 2: MEMS and Board-Mount Form Factors Expand in Medical and Embedded Industrial Use
Compact, accurate differential sensors are increasingly suitable for embedded medical instrumentation and industrial equipment where space, reliability, and interface flexibility matter. The emergence of multiple port configurations and flexible interface options is lowering integration friction and expanding design-in potential. This opens opportunities for volume growth in niches that previously required more customized or bulky solutions. The uncertainty is regulatory and application-specific: medical and certain industrial segments demand validation rigor, and certification pathways can slow adoption even when technical performance is attractive.
Trend 3: Cost, Sourcing, and Tariff Dynamics Will Continue to Influence Competitive Advantage
With average selling prices gradually declining and trade policy exposure persisting, the market will reward companies that manage input costs, diversify sourcing, and protect margin through value-added integration rather than pure volume competition. The commercial opportunity lies in designing for supply resilience, reducing dependency on single-region procurement, and aligning product architecture with material availability. The risk is that margin compression becomes structural for undifferentiated offerings, especially where tariff exposure and input volatility converge.
Strategic Implications for Decision-Makers
Different stakeholders face distinct priorities, but all should treat the market as a value-creation contest rather than a volume race.
For Manufacturers and Sensor Suppliers
- Prioritize integration-friendly architectures. Compact board-mount formats, flexible interfaces, and multiple port configurations reduce downstream engineering cost and expand addressable use cases in HVAC, medical, and embedded industrial applications.
- Invest in application-level validation and documentation. Regulated segments reward suppliers that can demonstrate consistent accuracy, robust calibration behavior, and readiness for certification pathways.
- Protect margin through differentiation, not discounting. Accuracy, stability, harsh-environment capability, digital integration, and application support are more sustainable defenses against price compression than volume-only strategies.
For Investors and Corporate Development Teams
- Assess portfolio fit across semiconductor-enabled and application-focused segments. The market rewards different capabilities in different niches, so acquisition or partnership strategy should align with end-use exposure rather than pursue blanket vertical integration.
- Monitor trade policy and input volatility as valuation-sensitive variables. Tariff exposure, sourcing concentration, and material availability can alter cost structures quickly, especially for MEMS-based product lines and cross-border import scenarios.
- Look for companies that combine sensing competence with software or ecosystem readiness. Digital monitoring, predictive maintenance, and app-based workflows are emerging as commercial differentiators in building automation and IAQ-adjacent segments.
For Procurement and End-Use Buyers
- Evaluate total cost of ownership beyond unit price. Integration complexity, calibration stability, lifecycle support, and compatibility with monitoring or control systems often matter more than the lowest initial sensor cost.
- Plan for supply resilience. Diversify supplier coverage where feasible and verify input and production continuity for critical applications, especially in medical, industrial process control, and building automation contexts.
- Align procurement criteria with long-term application goals. If predictive maintenance, IAQ optimization, or energy efficiency are strategic objectives, prioritize sensors and ecosystems that support those outcomes rather than treating sensing as a standalone component decision.
Conclusion and Research Access
The differential pressure sensors market is expanding with disciplined momentum, but its next chapter will be defined by integration, precision, and supply resilience rather than simple volume growth. Digital connectivity in building and IAQ applications, compact MEMS and board-mount formats in medical and embedded industrial use, and ongoing cost and sourcing pressures are reshaping where value accrues. Participants that align product strategy with end-use workflows, protect margin through differentiation, and prepare for trade and material volatility will be best positioned to capture durable share.
For decision-makers seeking deeper segmentation data, regional demand patterns, pricing trajectory detail, and company-level competitive benchmarking across the full forecast horizon, the complete PW Consulting research report offers extended analytics and customized guidance for strategic planning.
For detailed analysis of this topic, please visit the official page: Differential Pressure Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Brake Calipers Market 2026: Unpacking the Real Drivers Behind 5.4% CAGR Growth Through 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Brake Calipers Market
The brake calipers market is navigating a period of structural transformation, driven by evolving vehicle architectures, tightening safety standards, and the electrification of mobility. Market valuations have demonstrated steady expansion over the past half decade, with revenue climbing from approximately 1.22 billion USD in 2020 to an estimated 1.59 billion USD by 2025. Forward projections indicate continued momentum, with the market expected to reach roughly 2.30 billion USD by 2032, translating to a compound annual growth rate of 5.4 percent across the 2026 to 2032 forecast horizon. This trajectory reflects more than incremental volume growth; it signals a recalibration of how braking systems are designed, integrated, and monetized across passenger cars, commercial vehicles, and two-wheelers.
PW Consulting
Beneath the headline figures lies a market that is increasingly segmented by technology readiness, regional manufacturing footprints, and the pace of electronic integration. The revenue distribution shows clear geographic weight, with Asia Pacific generating the largest share, followed by Europe and North America, while Latin America and the Middle East and Africa contribute smaller but strategically important volumes. On the product side, floating calipers continue to command a larger revenue pool than fixed calipers, reflecting their prevalence in mainstream passenger and commercial platforms. Application-wise, passenger cars dominate the revenue mix, with commercial vehicles and two-wheelers forming meaningful secondary segments. Industry concentration remains moderately high, with the top three players accounting for approximately 45 percent of market revenue and the top five reaching around 65 percent, underscoring the influence of established OEMs suppliers and Tier 1 integrators.
This landscape is not static. The market stands at an inflection point where conventional hydraulic braking is being augmented, and in some segments displaced, by electronically controlled architectures. Recognizing where the market is headed requires looking past aggregate growth rates and examining the forces reshaping supplier positioning, cost structures, and demand patterns.
Brake Disc Market
Market Snapshot: Scale, Structure, and the Pressure Points
A Growing but Increasingly Complex Revenue Base
The market's expansion from 2020 through 2025 reflects a steady recovery and normalization in global automotive production, coupled with ongoing replacement demand in aftermarket channels. The projected climb to 2.30 billion USD by 2032 suggests that volume growth will be supported by platform refreshes, fleet modernization, and the gradual penetration of advanced braking features into mass-market segments. Yet growth is uneven. Regions with faster electrification adoption and stronger commercial vehicle activity are likely to outpace mature markets where replacement cycles are longer and price competition is more intense.
The concentration profile indicates that scale, engineering depth, and long-term OEM relationships still matter. Suppliers with broad portfolios spanning passenger and commercial segments, along with the ability to integrate electronic components, are well positioned to capture disproportionate value. At the same time, the presence of specialized high-performance and aftermarket-focused players highlights a market that rewards differentiated technical positioning as much as volume scale.
Key Challenges and Turning Points
Three pressure points are reshaping how participants approach the market.
- Technology transition and integration complexity. The shift toward electronically controlled braking and brake-by-wire architectures is changing the caliper from a purely mechanical actuator into a node within a broader safety-critical system. This raises engineering barriers, validates new testing and certification pathways, and forces suppliers to manage software and hardware development in tandem.
- Cost and sourcing pressures amid electrification. Vehicle platforms are evolving, and the brake caliper's role is being re-evaluated in the context of regenerative braking, weight targets, and packaging constraints. Suppliers must balance material choices, machining precision, and calibration costs while competing on price in segments where electrification does not immediately translate into higher unit economics.
- Regional volatility and supply chain realignment. Manufacturing footprints, logistics reliability, and regulatory divergence across markets are creating uneven operating conditions. Suppliers that depend on concentrated sourcing or single-region assembly face greater exposure to disruptions, while those with diversified production and localized engineering support are better equipped to maintain continuity.
These challenges are not merely operational headaches; they are strategic signals. They point to a market where the value equation is moving from component volume toward system capability, regional responsiveness, and the ability to meet functional safety requirements in electronically controlled environments.
Key Drivers Reshaping the Brake Calipers Market
Technology Innovation and the Rise of Electronically Controlled Braking
The most consequential driver is the accelerating integration of electronics into braking systems. Brake-by-wire and electro-hydraulic architectures are extending the role of the caliper beyond traditional actuation, enabling faster response, adaptive force distribution, and tighter integration with vehicle stability and regenerative braking strategies. Fourth-generation brake-by-wire systems have demonstrated full electronic actuation of calipers while meeting high automotive functional safety standards, marking a practical step toward software-defined braking. This evolution matters because it changes the caliper's development cycle: suppliers must account for sensor feedback loops, fail-safe behavior, and calibration across a wider range of driving conditions.
Worldwide Aircraft Brake Calipers Market
In parallel, high-performance and motorsport applications continue to push material and hydraulic design boundaries. New small-bore caliper configurations and carbon ceramic big brake kits illustrate how specialized segments are advancing thermal management, stiffness, and packaging efficiency. While these are niche volumes, they often serve as technology proving grounds and brand amplifiers that can influence premium OE programs and aftermarket credibility.
Policy and Regulatory Environment: Safety, Localization, and Functional Standards
Regulatory and safety requirements are increasingly shaping both product design and market access. Functional safety expectations for electronically controlled braking are rising, with ASIL-D class compliance becoming a relevant benchmark for systems that rely on electronic actuation. This raises the bar for validation, traceability, and supplier capability, favoring organizations with established safety engineering processes and mature testing infrastructure.
Localization trends are also influencing market dynamics. Partnerships and joint ventures aimed at adapting advanced braking technologies for regional markets illustrate how suppliers are responding to content requirements, cost structures, and speed-to-market considerations. For instance, collaborations focused on localizing brake-by-wire solutions in China and forming air brake joint ventures in India reflect a broader pattern: advanced brake systems are being adapted to regional manufacturing ecosystems rather than distributed solely through centralized global supply chains.
Demand-Side Shifts: Electrification, Fleet Mix, and Performance Expectations
Demand is being reshaped by three interrelated shifts. First, electrification is altering brake duty cycles. Regenerative braking reduces friction braking usage in certain driving conditions, which can affect wear patterns, caliper utilization, and the relative importance of precision actuation and thermal stability. Second, commercial vehicle demand remains a structural pillar, with fleet operators prioritizing downtime reduction, safety performance, and integrated braking solutions that can support higher vehicle weights and demanding duty cycles. Third, consumer and fleet expectations around safety, stopping performance, and system responsiveness are rising, encouraging adoption of advanced braking features that were once confined to premium or motorsport contexts.
These demand dynamics create a bifurcated opportunity set. In mainstream passenger vehicles, the focus is on reliability, cost efficiency, and incremental electronic integration. In premium, performance, and commercial segments, the opportunity lies in higher-specification calipers, tighter system integration, and solutions that support advanced safety and vehicle dynamics functions.
Supply Chain and Cost Structure Realignment
Cost structures are being reexamined as suppliers balance precision manufacturing with the added complexity of electronic integration. Material selection, machining tolerances, and assembly automation remain critical levers, but the growing presence of software-defined components means that value capture is increasingly tied to engineering capability and system-level optimization rather than component pricing alone. Supply chain resilience has also gained prominence, with participants enhancing multi-source sourcing, regional assembly options, and inventory strategies to reduce exposure to logistics bottlenecks and demand swings.
Recent product and funding activity reflects this environment. Investments in caliper production capabilities, launches of matched brake caliper, pad, and rotor packages, and continued motorsport-focused innovations all point to a market where suppliers are pursuing both scale efficiency and differentiated performance positioning simultaneously.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Leading Participants
The competitive field is shaped by companies with distinct technological emphases and customer bases. Several patterns stand out.
- High-performance and motorsport specialization. Some suppliers concentrate on high-performance calipers for luxury vehicles, supercars, and motorsport applications. This positioning emphasizes thermal performance, stiffness, weight optimization, and brand prestige. Specialized caliper designs, including small-bore configurations and carbon ceramic big brake kits, reinforce a premium performance narrative that can spill over into broader OE credibility and aftermarket demand.
- Electronic integration and OE breadth. Other leaders focus on brake calipers integrated with electronic control systems and ABS for global automotive OEMs, or on advanced calipers for intelligent safety systems and electric vehicle platforms. These players benefit from system-level engineering capabilities, broad OEM relationships, and the ability to align caliper design with vehicle-wide braking and safety architectures.
- Commercial vehicle and integrated braking solutions. Suppliers with strong commercial vehicle footprints are expanding integrated braking solutions and caliper offerings tailored to heavier-duty applications. This segment values durability, serviceability, and system reliability, and is increasingly receptive to electronically supported braking functions where they improve safety and operational efficiency.
- Regional OEM integration and component breadth. Additional participants emphasize brake calipers and related components for OEM integration across Asian and global vehicle markets, often combining calipers with complementary elements such as ceramic pads. This breadth can strengthen package value and improve positioning in cost-sensitive but volume-rich segments.
- Aftermarket and replacement focus. Some companies concentrate on replacement and OEM brake calipers for standard and heavy-duty vehicles, or on premium calipers matched with pads and rotors for enhanced safety and performance. This strategy targets continuity, fitment assurance, and the aftermarket's need for reliable, application-specific solutions.
Differentiation and Competitive Advantage
Differentiation in this market is increasingly multidimensional. Volume scale remains important, but it is no longer sufficient on its own. Suppliers that can combine precision mechanical design with electronic system integration, functional safety competence, and regional manufacturing flexibility are gaining relative advantage. High-performance specialists leverage technical heritage and brand association to command premium positioning, while broader OE-focused suppliers rely on integration depth, platform coverage, and system-level support. Meanwhile, aftermarket-oriented players compete on application coverage, quality consistency, and package completeness.
A notable competitive dynamic is the growing relevance of partnerships and joint ventures. Collaborations that localize advanced braking technologies or combine complementary capabilities are enabling faster market access, improved cost alignment, and stronger regional presence. This suggests that competitive advantage will increasingly depend on both internal engineering strength and the ability to structure alliances that reduce time-to-market and improve local responsiveness.
Market Structure Evolution: Consolidation, Differentiation, and New Entrants
The market is likely to continue evolving along three paths. Consolidation pressure will persist among suppliers seeking to strengthen OEM coverage, expand geographic reach, and build electronic integration capabilities through scale and acquisition. Differentiation will deepen as performance, commercial, and electronically controlled braking segments diverge in spec, validation requirements, and pricing dynamics. New entrants and niche players may find opportunities in specialized applications, regional localization, or targeted aftermarket packages, especially where they can offer clear technical or service advantages without needing to match the full breadth of global Tier 1 portfolios.
Recent launches and investment activity support this image of a market in motion. From motorsport small-bore calipers and premium matched brake packages to fourth-generation brake-by-wire systems and funded production advancements, participants are pursuing multiple routes to growth. The common thread is a push toward higher technical value and stronger application alignment rather than reliance on commodity volume alone.
Future Outlook: Trends and Commercial Opportunities
Trend 1: Software-Defined and Electronically Actuated Braking Will Move Deeper into Production
Electronically controlled braking is poised to expand beyond premium and specialized applications as vehicle architectures increasingly accommodate brake-by-wire and electro-hydraulic solutions. The commercial opportunity lies in calipers and associated system components that can meet strict functional safety requirements, support precise electronic actuation, and integrate cleanly with vehicle control strategies. Suppliers that can deliver validated, ASIL-compliant actuation performance and offer scalable integration pathways will be better positioned to participate in next-generation platform programs. The uncertainty here relates to adoption pace across mass-market segments, where cost sensitivity and validation timelines can slow deployment.
Trend 2: Regionalization and Localized Brake Technology Deployment Will Intensify
Market access strategies are increasingly shaped by localization. Partnerships and joint ventures that adapt advanced braking technologies for specific regions reflect the reality that cost, content expectations, and manufacturing ecosystems vary significantly by market. The commercial opportunity is twofold: suppliers can build stronger regional footholds by aligning production and engineering support with local demand, while customers can benefit from shorter lead times and improved cost structures. The risk is that localization efforts can fragment engineering resources and complicate harmonization across global platforms if not managed with clear architecture standards.
Trend 3: Performance, Commercial, and Aftermarket Segments Will Diverge Further in Spec and Value
The market is likely to see greater divergence between mainstream, performance, commercial, and aftermarket requirements. Mainstream passenger applications will continue to emphasize reliability, cost efficiency, and incremental electronic features. Performance and motorsport-related segments will keep pushing thermal, structural, and packaging boundaries, serving as both revenue niches and brand enablers. Commercial vehicle demand will favor integrated solutions that reduce downtime and support safety under demanding duty cycles. Aftermarket buyers will continue to value fitment confidence, application coverage, and package completeness.
The commercial opportunity is to align product portfolios and service models with these distinct value equations rather than treating the caliper market as a single homogeneous segment. Suppliers and investors that can identify which segment offers the best mix of margin, growth, and competitive defensibility will be better placed to allocate capital and engineering resources.
Strategic Actions for Decision-Makers
For Brake System Manufacturers and Tier 1 Suppliers
- Prioritize electronic integration and functional safety capability as core competencies, not optional add-ons. Investing in validation, calibration, and system-level engineering will increasingly determine eligibility for advanced braking programs.
- Align production footprints and sourcing strategies with regional demand patterns. Where localization trends are strengthening, consider partnerships or assembly options that improve responsiveness while preserving engineering consistency.
- Segment the portfolio deliberately. Mainstream, performance, commercial, and aftermarket applications require different design priorities, pricing strategies, and service models. Avoid diluting focus by treating all segments with the same value proposition.
For Investors and Strategic Planners
- Evaluate exposure to electronic braking adoption curves and regional localization trends when assessing growth potential. Revenue expansion will be uneven, and value capture will favor suppliers with the right combination of technology readiness and market access.
- Look beyond top-line growth to concentration and differentiation dynamics. In a market where leading players already hold substantial share, incremental opportunity often comes from specialization, regional positioning, or system-integration depth rather than undifferentiated volume gains.
- Monitor partnership activity and product launches as early indicators of strategic direction. Joint ventures, funded production expansions, and advanced system unveilings often signal where capabilities and market access are being built.
For Procurement and Fleet Decision-Makers
- Assess braking solutions based on total system fit, including electronic compatibility, functional safety readiness, and serviceability, rather than component price alone. As braking architectures become more integrated, the caliper's role within the broader system becomes more consequential.
- Plan for segment-specific requirements. Commercial fleets, passenger vehicle operations, and performance-oriented applications have distinct priorities, and purchasing strategies should reflect those differences in spec, validation, and support expectations.
- Build supplier evaluation frameworks that account for regional continuity, engineering support, and the ability to support evolving electronic braking functions over the vehicle lifecycle.
Closing Perspective
The brake calipers market is expanding, but the more important story is how its value base is shifting. Growth to roughly 2.30 billion USD by 2032, at a 5.4 percent CAGR across the forecast period, provides a useful macro frame, yet the real strategic challenge lies in navigating technology transition, regionalization, and segmentation divergence. Suppliers and investors that treat the market as a set of distinct value equations, and that invest accordingly in electronic integration, functional safety, and regional responsiveness, are more likely to capture durable advantage.
Detailed segment trajectories, regional breakdowns, competitor benchmarking, and application-level demand scenarios can sharpen these decisions further. For decision-makers seeking a deeper, customizable view of the market landscape and its commercial implications, the full PW Consulting research report offers expanded data and tailored analysis across the segments and dynamics discussed here.
For detailed analysis of this topic, please visit the official page: Brake Calipers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com