

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting Forecasts Worldwide Radiator Flushing Chemicals Market to Expand at a 5.48% CAGR Through 2032
By pmarketresearch, 2026-08-12
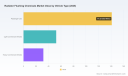
Worldwide Radiator Flushing Chemicals Market: Strategic Insights for 2026 Decision-Makers
PW Consulting today releases an executive briefing summarizing the strategic implications of our new Worldwide Radiator Flushing Chemicals Market report (base year: 2025; historical coverage: 2020–2025; forecast: 2026–2032). The global market demonstrates steady, mid-single-digit growth — a compound annual growth rate (CAGR) of 5.48% — with total industry revenues tracked and modelled in USD Million across 2020–2032. Our analysis translates that trajectory into concrete choices for suppliers, OEMs, aftermarket service providers, distributors and private equity investors preparing to act in 2026.
Worldwide Surface Protective Tapes Market
Snapshot: Macro trajectory and what it means for 2026
- Historical resilience: From 2020 through 2025 the radiator flushing chemicals market recovered from pandemic disruption into a sustained expansion phase, underpinned by rising vehicle parc maintenance cycles and renewed emphasis on cooling-system longevity in mixed fleets.
- Forecast discipline: Our model projects continued growth through 2032 at a 5.48% CAGR, reflecting a blend of mature-market replacement demand, higher maintenance intensity in aged fleets, and selective unit growth in emerging markets.
- Market structure: Concentration metrics point to a moderately consolidated market—our CR3 and CR5 indices indicate leading players hold meaningful share yet leave room for niche specialists, regional champions and innovative entrants to capture value.
This briefing outlines the strategic levers that will matter most in 2026, and explains how the full PW Consulting report equips leaders to act. (Note: to preserve the value of the complete intelligence package we intentionally withhold detailed sub‑segment percentages and proprietary scenario tables in this release.)
450kW EV Charger Market
Why 2026 is a pivotal planning year
- Input-cost inflection: Feedstock movements in 2025–26 — including volatility in ethylene glycol and oscillations in industrial phosphates — create both margin risk and tactical sourcing opportunities. Our sensitivity runs show small shifts in upstream pricing can materially affect OEM and private-label economics.
- Regulatory ripple effects: New regulatory instruments that took effect or were finalized for 2026 (notably tighter reclamation and refrigerant controls in the U.S., and building-code updates in California affecting EV charging and ventilation) are already altering maintenance patterns and service-channel economics. These changes increase demand for clearly compliant, traceable chemistry and for aftermarket providers who can certify proper environmental handling.
- Aftermarket premiumisation: Vehicle owners and independent workshops are showing a willingness to pay more for performance-restorative chemistries and time-saving treatment kits — provided durability claims are substantiated with verifiable testing and third‑party endorsements.
Practical contents of the PW Consulting report
The full report is designed as an operational playbook for 2026 decision cycles. Key, actionable chapters include:
Worldwide Taxi & Limousine Software Market
- Market sizing and validated forecasts (2020–2032) with scenario stress-testing under alternate raw-material and regulatory assumptions.
- Channel and route-to-market analysis (DIY retail, professional service networks, OEM/RPO programs), including margin ladders and recommended pricing tactics.
- Value-chain mapping and a raw-material cost-pass-through model that quantifies margin elasticity against ethylene glycol and specialty acid fluctuations.
- Buy-side guidance: supplier scorecards, contract levers and hedging frameworks for procurement teams.
- Product and portfolio playbooks: when to pursue acid vs. alkaline vs. solvent formulations; formulation lifecycle planning; claims substantiation and lab-validation protocols.
- Regulatory compliance checklist and a compliance-cost estimator tied to key jurisdictions, plus recommended labeling and stewardship practices.
- Competitive benchmarking and a transaction advisory annex: M&A screening criteria, integration risk maps and valuation multipliers for carve-outs and bolt-ons.
- 50+ company profiles, distributor intelligence and an executive contact map to accelerate commercial engagement.
The report is intentionally actionable: chapters are linked to one another so a procurement director can move from raw-material scenario to supplier contracting playbook, or a product manager can run from claim architecture to lab-test spec in a single workflow.
Competitive landscape: what the leading players reveal about strategic priorities
The industry combines multinational household brands with specialized chemistry firms and regionally strong formulators. A short synthesis of representative players highlights the strategic vectors we see in market behavior and what that implies for 2026 tactics.
- Prestone Products Corporation (Rosemont / Lake Forest, IL, USA) — A mass-market leader whose portfolio is built on broad OEM compatibility and strong retail presence. Strategy watchers should expect continued investment in consumer-facing assurance (clear compatibility claims) and supply agreements with national retail chains.
- Valvoline Inc. (Lexington, KY, USA) — Leverages service network and branded service centers to cross-sell flush services with proprietary chemistries. In 2026, co-branded service models and subscription maintenance packages will be a fast-follow for competitors.
- Liqui Moly GmbH (Ulm, Germany) — A specialty brand emphasizing performance restoration. European regulatory scrutiny and consumer willingness to pay for premium formulations suggest Liqui Moly will continue to push higher-margin chemistry innovations and expanded professional channels.
- CRC Industries, Inc. (Horsham, PA, USA) — Known for rapid-flush/acid-free formulations and industrial channel strength. CRC’s playbook indicates opportunities in light industrial and fleet-maintenance segments where downtime reduction is a sellable ROI.
- Bar’s Leaks (Holly, MI, USA) — Focused on niche fix-and-seal chemistry with strong DIY recognition; potential to extend into bundled maintenance kits sold through garage chains and e-commerce platforms.
- BG Products, Inc. (Wichita, KS, USA) — Professional-services oriented; BG's model underscores the premium for certified shop networks and multi-step system restoration protocols that justify higher labor/hour rates.
- Jelmar LLC (CLR PRO) (Skokie, IL, USA) — Rapid-action, biodegradable formulations highlight the demand for environmentallyfriendlier chemistries; expect continued marketing toward sustainability-conscious fleets and marine applications.
- Chemtex Speciality Limited & RX Marine International (India) — Regional formulators offering industrial-strength and marine-targeted products. Their competitive posture indicates export potential for cost-competitive, performance-grade chemistry into adjacent emerging markets.
- Callington (ROX®, Australia) — Concentrates and OEM-channel plays suggest value in specialized formulations for professional workshops and regional fleet operators.
Across these profiles the recurring themes are: channel control (service network vs. retail), formulation differentiation (efficacy, safety, biodegradability), and supply-chain resilience (feedstock sourcing and contract risk). Our report contains detailed comparative matrices and go-to-market scenario planning for each archetype.
Risk matrix and mitigation playbook
- Raw-material risk: We model ethylene glycol and phosphate-derived feedstock exposures and present hedging and dual-sourcing options that reduce cost volatility impact without eroding working capital efficiency.
- Regulatory/compliance risk: A 12–18 month checklist for product relabeling, disposal protocols, and reclaimed-material traceability to remain compliant with tightened rules effective in 2026.
- Channel disruption risk: A triage playbook for channel conflict — how to manage private-label growth while protecting core-brand retail agreements.
- Technology and substitution risk: Early-warning metrics for chemical substitution trends (bio-based cleaners, multifunctional additives) and an R&D investment guide to prioritize defensive or offensive projects.
Recommended moves for C-level teams in 2026
- Procurement: Lock in a two-tier procurement strategy — a medium-term contract for core feedstocks with price collars, combined with opportunistic spot sourcing when market dips occur.
- Commercial: Pilot subscription-style maintenance offerings in 2–3 pilot markets, pairing chemistries with certified workshop networks and a digital service record to monetize recurring revenue.
- Product: Fast-track one validated “eco-performance” formulation to capture buyer preference shifts while maintaining the existing line to serve legacy vehicle parc needs.
- M&A/Partnerships: Screen targets that bring either (a) channel access to high-margin professional networks, or (b) formulation IP that shortens R&D time to market for biodegradable and rapid-action chemistries.
- Regulatory: Assign cross-functional compliance owners to update labeling and disposal guidance across all high-priority jurisdictions before the second half of 2026.
How PW Consulting helps
PW Consulting’s full report delivers the underlying datasets, sensitivity models and playbooks summarized here, plus interactive planning tools to run customized scenarios for your specific cost structure and geographic footprint. For teams preparing budgets, product roadmaps or M&A pipelines in 2026, the report is structured to convert insight into executable plans within weeks.
To access the full report including regional and application-level breakdowns, granular competitive benchmarking, and our proprietary scenario and valuation models, visit the PW Consulting research portal or contact our market intelligence team for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Radiator Flushing Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cold Ramming Paste (CRP) Market Poised to Grow at a 4.0% CAGR Through 2032, Report Says
By pmarketresearch, 2026-08-12
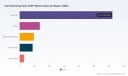
PW Consulting: Strategic Preview — Worldwide Cold Ramming Paste (CRP) Market Outlook for 2026 Decision-Makers
PW Consulting’s latest Worldwide Cold Ramming Paste (CRP) Market report presents a pragmatic, strategy-focused perspective for executives preparing capital, procurement, and R&D choices in 2026. Anchored on a 2025 base year assessment, our analysis quantifies the market at USD 487.04 Million and models a disciplined forecast through 2032, where a 4.0% compound annual growth rate (CAGR) points to a market that modestly expands into the mid-to-late decade. This briefing highlights how the report translates macro momentum into concrete, near-term actions while intentionally withholding detailed segment tables — to direct readers to the full report for the proprietary datasets and granular intelligence that underpin the recommendations below.
Neonate Ambulance Market
Why the 2026 Decision Window Matters
-
Mid-cycle positioning: The CRP market is at an inflection where steady growth and structural shifts (raw-material sourcing, environmental regulation, and product innovation) converge. Capital allocation and supplier strategy set in 2026 will determine cost curves and compliance readiness through the rest of the decade.
Worldwide Heim Joints Market -
Operational risk management: Raw-material exposure and binder regulatory risk create asymmetric supplier risks. Firms that pre-emptively diversify binders and secure high-quality feedstocks will materially reduce production interruptions and potential regulatory liabilities.
Worldwide GaN Wafers Market -
Product differentiation vs. commoditization: Demand-side dynamics favor suppliers who combine performance (thermal stability, electrical resistivity) with demonstrable environmental credentials. Buyers must weigh short-term price vs. long-term value creation when selecting partners.
Core, Data-Driven Takeaways (High-Level)
-
Market size and trajectory: After a temporary slowdown earlier in the decade, the CRP market returned to growth and is projected to expand at a ~4.0% CAGR through 2032. Our modelling anticipates steady, industrial-led demand driven primarily by aluminum smelting and metallurgical furnace maintenance cycles.
-
Concentration and competitive spacing: The industry exhibits measurable concentration — the top three players account for roughly mid-to-high forties percent of market value, while the top five collectively control well over sixty percent. This concentration underscores opportunities for scale-driven supply leadership but also leaves room for specialized regional and technology-focused competitors.
-
Cost and composition sensitivities: Typical CRP formulations continue to rely on anthracite or artificial graphite carriers combined with asphalt/pitch-type binders. Standard formulations frequently include a majority share of asphalt/coal tar pitch (historically 55–70% of binder systems) and achieve target electrical resistivity metrics in the industrial application range. These technical parameters directly affect life cycle cost and smelter performance.
Regulatory and Technology Dynamics Shaping 2026 Strategies
-
PAH and binder substitution: Regulatory scrutiny on polycyclic aromatic hydrocarbons (PAHs) from coal tar pitch binders is a persistent disruptor. Leading suppliers and certain smelters have adopted low- or zero-PAH alternatives (e.g., furan resins, lignin-derived binders, or treated pitches). The pace of regulatory tightening will be a primary determinant of near-term retrofit and replacement investment.
-
Eco-innovation as competitive currency: Vendors who can credibly certify low-PAH or PAH-free products gain preferential access to customers with aggressive ESG and occupational health mandates. Independent industrial trials and third-party certifications materially shorten procurement cycles for these buyers.
-
Feedstock concentration risk: Anthracite and certain graphite feedstocks remain regionally concentrated. Proximity to feedstock basins, integrated sourcing, or supply partnerships are strategic levers to control input-cost volatility and delivery reliability.
Competitive Landscape — Strategic Profiles and Implications
The report provides a tactical view of market participants from multinational incumbents to regional specialists. Key industry players examined in the full study include established multinationals with integrated supply chains, regionally strong manufacturers with local feedstock advantages, and specialized innovators delivering eco-friendly products. Representative strategic implications include:
-
Elkem ASA (Oslo): Leverages established cathode ramming brands and geographically diversified manufacturing — including facilities in South America — to support large-scale aluminum electrolysis customers. Strengths: established brand, integration into electrolysis supply chains, scale manufacturing. Strategic implication: large buyers can leverage Elkem for global standardization, while competitors can exploit niche performance differentials.
-
Maruti Electro Carbon (India): Focuses on thermal-stable formulations for high-temperature applications. Strengths: technical formulations for demanding environments; regional cost competitiveness. Strategic implication: attractive partner for cost-sensitive and large-volume regional smelters seeking improved thermal performance without premium global lead times.
-
Henan Rongxing, Ningxia manufacturers, Luoyang, Shandong, Wuhai, and Coalician (China-based cluster): Represent a robust supply base emphasizing product range breadth and competitive pricing. Many also offer eco-friendly variants and fast response on repair linings and retrofits. Strategic implication: vital for procurement diversification and competitive bidding, but buyers must validate product consistency and environmental claims.
-
Bawtry Carbon (UK) and Carbone Savoie (France): Specialty European players that emphasize product performance and eco-credentials (Carbone Savoie offers low/zero-PAH lines tested at pilot and industrial scales). Strategic implication: premium partners for customers prioritizing regulatory compliance and occupational health outcomes.
What the PW Consulting Report Delivers (Practical Content)
Our report is built for executives who need to move from insight to action. Key operational deliverables include:
-
Granular forecast models by type, application, and region (proprietary datasets and scenario toggles available in the full report).
-
Supplier benchmarking and capability matrices that evaluate product performance, environmental profile, cost position, and logistical resilience.
-
Raw-material sourcing heat maps, margin sensitivity dashboards, and hedging templates to quantify feedstock exposure under alternative price paths.
-
Regulatory-impact scenarios and compliance roadmaps that map binder substitution timelines to capital and operational expenditures.
-
Commercial playbooks for procurement (contract structures, certification clauses, audit checklists) and M&A screening filters for strategic acquisitions of regional specialists or technology innovators.
Recommended 2026 Playbook — Prioritized Actions
-
Conduct immediate supplier audits focused on binder composition and PAH reporting. Short-term procurement awards should include audit and remediation clauses tied to binder compliance.
-
Initiate mid-term co-development pacts with specialty resin and additive providers to accelerate validated low-PAH formulations tailored to your furnaces or cell technologies.
-
Formalize a feedstock diversification strategy: combine long-term purchase agreements with selective near-term spot coverage to manage price spikes without over-committing capital.
-
Prioritize retrofit budgets where regulatory risk and occupational exposure costs materially exceed the incremental price of eco-friendly CRP solutions.
-
Use supplier scorecards and total cost-of-ownership (TCO) analyses from the report to renegotiate multi-year contracts, emphasizing performance guarantees and environmental metrics.
-
Consider targeted acquisitions or joint ventures to secure regional manufacturing footholds in low-cost feedstock basins or to acquire proprietary low-PAH technologies.
How PW Consulting’s Intelligence Accelerates Your 2026 Decisions
Executives with exposure to CRP supply chains tell us they need three things: credible commercial forecasts, defensible supplier assessments, and executable transition roadmaps for regulatory change. Our Worldwide CRP Market report consolidates these elements into an actionable toolkit: scenario-modeled forecasts you can feed into capital planning, supplier scorecards you can operationalize immediately, and compliance-to-capex templates that convert environmental requirements into investment choices. Importantly, the report balances transparency and discretion — showing the methodological basis for our conclusions while reserving proprietary segment-level tables and supplier scores for report access.
For procurement, manufacturing, sustainability, and corporate development teams preparing decisions in 2026, the report reduces ambiguity and accelerates alignment between technical teams and the C-suite. Because the core segmentation tables and company-level benchmarking are gated, stakeholders seeking the underlying datasets, regional and application splits, and interactive models should consult the full report portal.
Next Steps
To access the full dataset, interactive scenarios, and supplier benchmarking modules that underpin this strategic preview, visit the PW Consulting report page for Worldwide Cold Ramming Paste (CRP) Market. The full report contains the detailed regional, type, and application breakdowns, plus downloadable models to support procurement negotiations, R&D prioritization, and investment cases for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Cold Ramming Paste (CRP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Polyetherimide (PEI) Films Market Eyes 7.12% CAGR Through 2032 After Reaching USD 521.5 Million in 2025
By pmarketresearch, 2026-08-12
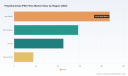
Worldwide Polyetherimide (PEI) Films Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
As materials technology converges with accelerating demand in electronics, aerospace, and electrified transport, polyetherimide (PEI) films have moved from a specialty niche to a strategic industrial material. PW Consulting’s latest Worldwide PEI Films Market study (base year 2025, forecast 2026–2032) puts this evolution in context: the global market is estimated at USD 521.5 million in 2025 and, under our base forecast, is set to expand at a compound annual growth rate (CAGR) of 7.12% through 2032, reaching roughly USD 843.7 million by the end of the projection period. For executives planning capital allocation, sourcing, product roadmap, or M&A activity in 2026, the report crystallizes where economic upside and risk intersect.
Holometer Market
Why PEI Films Matter for 2026 Strategic Decisions
PEI films occupy a unique value position. They combine high glass transition and continuous-use temperatures, excellent dimensional stability, and robust dielectric and flame-retardant characteristics. These attributes make PEI films indispensable in high-reliability domains: thin insulation in advanced electronics and semiconductors, lightweight thermal barriers and dielectric layers in aerospace, and class-leading components in medical devices and industrial equipment.
Wall Suction Unit Market
Two regulatory-technical datapoints frame near-term opportunity and constraint. First, certain PEI grades meet UL 94 V-0 flame ratings at thicknesses as low as 0.075 mm and can comply with aerospace flammability standards such as FAR 25.853 — a certification vector that shortens qualification cycles for aerospace OEMs when thin-gauge performance is validated. Second, select PEI formulations meet EU REACH limitations on BPA migration relevant to food contact and sensitive medical uses — an important commercial differentiator for suppliers targeting regulated end markets.
Worldwide Corporate Tax Software Market
Market Dynamics Shaping 2026
- Demand momentum is underpinned by continued investment in advanced electronics and electrification programs, which are shifting demand toward thin-gauge, high-performance films.
- Raw material volatility is a tangible near-term headwind: industry data show key monomer feedstocks experienced sizeable price increases in recent quarters, introducing cost uncertainty for film producers and downstream buyers.
- Supply-side concentration is meaningful. The market exhibits high aggregation among the top players, producing both barriers to entry and strategic windows for differentiated niche players.
What PW Consulting’s Report Delivers — Practical, Decision-Ready Intelligence
Our report is structured to support decisions across the investment, procurement, and product strategy lifecycles. Key practical deliverables include:
- A transparent market-sizing and forecast model that reconciles historical uptake (2020–2025) with our 2026–2032 scenarios. The model supports what-if analysis across price, volume, and substitution assumptions.
- Scenario playbooks: stress-tested demand cases (conservative, base, accelerated) tied to macroeconomic, regulatory, and feedstock shocks so buyers and producers can prioritize contingency plans.
- Supplier scorecards and capability maps that evaluate technical depth, capacity flexibility, regulatory compliance footprint, and go-to-market reach for leading producers.
- Cost-to-serve and margin sensitivity templates that quantify the impact of feedstock inflation, freight constraints, and regional manufacturing spreads on unit economics.
- Industry qualification timelines and recommended certification sequencing for aerospace, medical, and EV semiconductor applications to accelerate time-to-revenue.
- An M&A and partnership heatmap identifying where bolt-on investments, JV structures, or off-take agreements can de-risk capacity expansion or secure downstream access.
These components are presented with ready-to-use slide decks and spreadsheets so corporate teams can adapt insights to internal P&L models and procurement strategies. Crucially, the report provokes action rather than offering descriptive narration — it maps decisions to economic outcomes.
Competitive Landscape: Profiles and Strategic Implications
The PEI films market is shaped by differentiated player strategies: global petrochemical incumbents with integrated material portfolios, specialized polymer converters with technical depth, and custom compounders targeting niche electrical or acoustic properties. PW Consulting’s assessment of leading firms yields the following strategic takeaways:
- SABIC (Riyadh) leverages scale and brand-positioned ULTEM™ technology to serve aerospace, electronics, and medical OEMs with thin-gauge, high-temperature films. Its combination of global reach and established material datasheets accelerates qualification in regulated industries. Strategic implication: competitors must match certification readiness and technical support to compete on system-level adoption.
- Ensinger GmbH (Nufringen) positions itself around engineering-grade PEC/PEI films and customized thicknesses for automotive and technical applications. Its strength lies in application-driven customization. Strategic implication: collision between tailored solutions and volume economics creates niches for specialty converters.
- RTP Company (Winona) focuses on custom compounding and specialty films for electrical insulation and flexible circuitry. Its agility to formulate application-specific compounds is a go-to tactic to win early-stage design wins. Strategic implication: larger firms should consider partnerships or internal capability builds to capture early R&D-led demand.
Market concentration metrics reinforce the strategic environment: a small set of players command the lion’s share of available capacity and customer relationships, creating both a high barrier for large-scale disruption and a fertile landscape for targeted differentiation.
Supply Chain and Cost Risk — What to Hedge in 2026
Feedstock tightness and regional dynamics are visible stress points. Industry reporting notes that key monomers have experienced material price appreciation in recent periods, raising the ceiling on input costs for film producers. For procurement and strategy teams, key actions in 2026 should include:
- Locking multi-year supply agreements for critical monomers where feasible, with indexed pricing bands to share margin risk.
- Testing alternative chemistries and co-polymers where performance trade-offs are acceptable to reduce exposure to single-feedstock shocks.
- Evaluating near-sourcing or localized conversion capacity to reduce freight and lead-time risk in time-sensitive markets such as semiconductors and aerospace.
- Running scenario-based cost models provided in the PW report to quantify the P&L impact of ±15–25% raw material swings and to set minimum hedge thresholds.
Technology, Certification and Time-to-Market Constraints
PEI films often face long qualification lead times, particularly in aerospace and medical end markets where certification is non-negotiable and testing cycles extend procurement timelines. The report includes a certification road map that aligns material development milestones with certification windows (electrical, flammability and chemical migration), enabling companies to sequence R&D, qualification testing, and customer engagement to avoid costly time-to-market slippage.
A Practical Playbook for 2026 — Prioritized Actions
Below is PW Consulting’s recommended action ladder for companies active in or entering the PEI films value chain in 2026. Each recommendation is calibrated against market growth expectations and sector-specific risk profiles.
- Short-term (0–12 months): Secure critical monomer supply; prioritize certification-readiness for top-priority accounts; fast-track modular product offerings for electronics and EV thermal management.
- Medium-term (12–24 months): Invest in thin-gauge process optimization and cost reduction programs; pursue targeted partnerships for acoustic and high-temperature specialty grades; pilot near-shore conversion capacity where demand density justifies.
- Long-term (24+ months): Consider M&A to acquire niche compounding capabilities or capacity; scale sustainability and circularity initiatives (e.g., reclaim streams for industrial-grade reuse) and embed them into OEM procurement dialogues; institutionalize dynamic pricing linked to feedstock indices.
Why the Full Report Is Critical for 2026 Decision-Making
This preview highlights the structural drivers and recommended strategic plays, but the full PW Consulting report contains the granular inputs that decision-makers need: proprietary segment-level forecasts, supplier-level cost curves, an actionable M&A heatmap, and downloadable scenario models with configurable assumptions. If your 2026 plan involves CAPEX commitments, supplier consolidation, or accelerated product launches in aerospace, semiconductors, or EV applications, the incremental information provided in the full report materially changes go/no-go analyses and timing.
In a market growing at a mid-single-digit-plus CAGR with concentrated supply dynamics, small timing advantages or a single large qualification win can produce outsized returns. Conversely, underestimating raw material sensitivity or regulatory qualification time can lock in suboptimal investments. PW Consulting’s report translates these risk-reward trade-offs into executable steps aligned with corporate planning cycles.
For procurement directors, R&D leads, and corporate strategists preparing budgets and roadmaps for 2026, the question is no longer whether PEI films will matter — it is how to turn material performance into sustainable commercial advantage. Our report provides the analytics, scenario playbooks, and strategic frameworks required to answer that question with confidence. Access to the full dataset and supplier scorecards is available through PW Consulting’s report platform for teams seeking to convert insight into action.
For detailed analysis of this topic, please visit the official page: Worldwide Polyetherimide (PEI) Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Military Protective Gear Market to Reach USD 22,931.18 Million by 2032, Growing at a 4.5% CAGR
By pmarketresearch, 2026-08-12
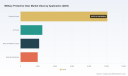
Worldwide Military Protective Gear Market — Strategic Executive Briefing (PW Consulting)
PW Consulting today releases an executive briefing drawn from our forthcoming Worldwide Military Protective Gear Market report (base year 2025, historical window 2020–2025, forecast horizon 2026–2032). This briefing distills the high‑impact insights defense leaders, suppliers, and investors must act on in 2026. It is crafted as a strategic “trailer”: it demonstrates the analytical depth of our work while intentionally withholding detailed subsegment and regional tables to encourage direct access to the full report for transaction‑critical data.
Braided Ground Jumpers Market
Market snapshot: what the numbers mean for strategy
The market for military protective gear continues to expand steadily. From an observed market value at the start of our historical window to a validated base‑year total in 2025, the sector is projected to grow at a compound annual growth rate (CAGR) of 4.5% through our forecast period 2026–2032. That trajectory takes the market from its 2025 valuation into materially larger absolute size by 2032, reflecting a confluence of persistent procurement programs, materials innovation, and geopolitical-driven demand.
Worldwide Non-Native Database Management Systems Market
Two quick implications for 2026 decision cycles:
Worldwide Medical Spray Market
- Program managers should reframe procurement timelines around multi‑year sustainment and upgrade windows rather than one‑off buys — predictable growth and replacement cycles offer opportunities for platform commonality and life‑cycle cost reduction initiatives.
- Investors and suppliers need to prioritize scalable manufacturing and strategic raw‑material access: as demand grows, margins will be determined by material cost management and the ability to deliver certified, performance‑guaranteed solutions at scale.
Why this market is structurally attractive — and where risks concentrate
Three structural features define the sector today:
- Technology layering: Protective systems are increasingly integrated — from advanced materials (aramids and UHMWPE) to sensor and communications integration in helmets and visors — creating value beyond base hardware.
- Procurement stickiness: Military procurement cycles, retrofit programs, and certification requirements produce multi‑year revenue streams with high barriers to entry once type approvals and logistics pipelines are established.
- Moderate market concentration: The top tier of suppliers holds meaningful but not overwhelming share, leaving room for niche specialists, regional champions, and innovative startups to scale through strategic partnerships and targeted contract wins.
Risks that will influence 2026 outcomes include raw‑material price volatility for premium ballistic fibers, the operational friction introduced by export controls such as ITAR, and accelerating regional procurement preferences that favor localized manufacturing partnerships.
Report coverage — practical and actionable
Our full report translates market intelligence into executable guidance. Core elements include:
- Validated market sizing and forward forecasts (2026–2032) with sensitivity scenarios tied to defense budget trajectories and material cost curves.
- Technology and product roadmaps across major categories — body armor systems, ballistic helmets and headborne systems, CBRN/respiratory protection, and protective eyewear/footwear — highlighting upgrade paths and integration opportunities.
- Supply‑chain and raw‑material analysis, with forward pricing scenarios for aramid fibers (e.g., Kevlar) and UHMWPE composites and a supplier risk heatmap for 2026 procurement planning.
- Regulatory and certification playbook covering international ballistic standards and export control constraints; practical compliance steps for cross‑border programs.
- A competitively framed M&A and partnership decision matrix identifying where scale, technology capability, or regional footprint unlock higher contract win rates.
- Differentiated go‑to‑market strategies for primes, component suppliers, and non‑tier‑one entrants — including margin models for sustainment and aftermarket service offerings.
Note: This briefing intentionally omits detailed regional and subsegment tables. The full report provides the complete numerical breakdowns necessary for bid modeling, supplier selection, and due diligence.
Competitive landscape — who matters and why
The market is served by a blend of large diversified primes, specialty material producers, and focused system integrators. PW Consulting’s competitive profiles assess each incumbent on technology roadmap, program references, manufacturing flexibility, and certification footprint. Highlights include:
- 3M Company — Leveraging lightweight composite design and integrated protective systems, 3M remains prominent where multi‑threat helmets and hearing/physiological protection converge with soldier systems.
- BAE Systems — A proven integrator of modular armor and plate systems, BAE plays strongly where end‑to‑end soldier protection suites and vehicle integration are prioritized by defense buyers.
- Gentex Corporation — A leader in helmet systems and communications‑integrated head protection; recent contract extensions underline its position on sustainment tractability for large defense logistics agencies.
- DuPont and Honeywell International — Materials suppliers that underpin the performance envelope of nearly every major product category; their technologies determine both capability and cost curves.
- Avon Protection and specialized suppliers (ArmorSource, Revision Military, MKU, Safariland, among others) — These firms occupy crucial niches from CBRN respiratory systems to modular dismounted soldier solutions, and are often the source of rapid innovation.
PW Consulting’s market concentration analysis shows a moderate level of aggregation at the top — sufficient to sustain competitive pricing pressure but not so concentrated as to block new entrants who can deliver validated performance and certified supply capability.
Recent developments shaping 2026 strategic choices
- Contract renewals and production awards are reinforcing incumbent supply chains — recent multi‑year contract extensions for helmet programs underscore the value of logistics readiness and compliance capabilities.
- Procurement of protective inserts and plates by major armed forces signals continued momentum for high‑performance armor solutions; suppliers able to combine manufacturing scale with certification capacity will win prioritized slots.
- Consolidation activity among mid‑tier specialists is creating acquisition pathways for primes seeking to vertically integrate or to acquire rapid access to new materials and manufacturing techniques.
Strategic playbook for 2026 — prioritized actions
To convert market trends into near‑term competitive advantage, PW Consulting recommends the following prioritized actions for decision‑makers:
- For defense primes and integrators: accelerate modular system strategies that enable incremental upgrades (sensors, communications, add‑on armor) without forcing full system requalification; this reduces program cost and shortens procurement cycles.
- For materials and component suppliers: secure long‑term offtake and hedging arrangements for aramid and UHMWPE feedstocks; invest selectively in certification capacity to shorten buyer validation timelines.
- For midsize manufacturers and niche innovators: pursue selective regional partnerships with defense OEMs to capitalize on localized procurement preferences and offset export control barriers.
- For investors and M&A teams: target bolt‑on acquisitions that close capability gaps in CBRN systems, helmet‑mounted sensors, or sustainment logistics rather than broad, unrelated diversification.
- For procurement offices: embed lifecycle‑cost modeling into RFPs and require modular upgrade roadmaps so that acquisition choices reward suppliers who can demonstrate endurance and upgradeability.
Regulatory and supply‑chain checklist
Three compliance and supply‑chain items should be on every 2026 checklist:
- ITAR and export licensing readiness for cross‑border deliveries of certain ballistic technologies — incorporate licensing cycle buffers into contracting timelines.
- Third‑party ballistic certification pathways — build these into product development roadmaps to avoid late‑stage rework and contract delays.
- Material sourcing diversification — develop alternative suppliers or stock strategies for premium fibers to mitigate single‑source disruptions and price spikes.
Why PW Consulting’s report is mission‑critical for 2026
Our report goes beyond market sizing. It couples quantitative forecasts with procurement playbooks, certification roadmaps, supplier due‑diligence templates, and investible deal flow scenarios. For organizations planning budgets, M&A, or R&D investments in 2026, the report provides:
- Actionable insights to prioritize spending where return and strategic value converge;
- A practical framework to accelerate fielding of integrated protection systems while managing compliance and supply‑chain risk;
- Competitive benchmarking and supplier scorecards that inform bid strategies and partnership selection.
Next steps — how to use this briefing
Use this briefing to align 2026 planning cycles around sustained market growth, rising materials intensity, and regulatory compliance. For transaction teams, procurement offices, and R&D leaders requiring the underlying numerical tables, subsegment splits, and scenario‑level sensitivities, the full Worldwide Military Protective Gear Market report provides the necessary depth and appendices — including validated vendor scorecards and model spreadsheets for bid and investment stress‑testing.
PW Consulting will continue to publish targeted updates as major program awards, material price shocks, or regulatory changes occur through 2026. For immediate advisory engagement or to secure the complete report with confidentiality‑graded datasets and supplier assessments, please contact our Commercial Intelligence team.
For detailed analysis of this topic, please visit the official page: Worldwide Military Protective Gear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Chain Door Guard Market to Grow at a 4.51% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Chain Door Guard Market: Strategic Imperatives for 2026 — PW Consulting Preview
As PW Consulting’s lead industry analyst, I present an executive preview of our newest market intelligence — the Worldwide Chain Door Guard Market study — designed to inform high-stakes decisions throughout 2026. The secure-access hardware sector is quietly evolving from a commodity-driven aftermarket into a standards-led, design-differentiated domain. Our report synthesizes five years of historical performance, a rigorous 2026–2032 forecast, competitive diagnostics, regulatory impact assessment, and actionable commercial playbooks. This preview highlights the strategic value of those findings while intentionally withholding core segmentation datapoints to encourage full report review and model access.
Worldwide Automated Storage and Retrieval Systems (ASRS) for Cold Storage Food Facility Market
Market trajectory: what the top-line shows
The chain door guard market is entering 2026 from a position of steady expansion. After a measured recovery phase in the early 2020s, the global market reached an appreciable annualized level by the 2025 base year and is forecast to continue expanding at a compound annual growth rate (CAGR) of approximately 4.51% over our 2026–2032 forecast horizon. Under our central scenario, the market climbs meaningfully in the near term before stabilizing into a mid-single-digit growth environment driven by a mix of replacement demand, new residential construction in select regions, retrofit activity in multifamily units, and specification-led volume from institutional procurement.
Worldwide Music School Software Market
Two implications for 2026 strategy follow immediately: first, growth is persistent but not runaway — strategic differentiation, operational efficiency, and targeted channel execution will determine winners. Second, the forecast profile supports investment in both product upgrade paths (certified/TS003-compliant designs, premium finishes) and distribution expansion (value-add partnerships with door manufacturers and distributors).
Ventriculo-atrial Hydrocephalus Shunts Market
Why this report matters to 2026 decision-makers
- Confidence for capital allocation: The top-line trajectory and scenario models enable CFOs and corporate development teams to size opportunity windows for capacity investment, M&A, and tooling spend with a clarity that reflects both demand drivers and downside stress cases.
- Product roadmaps aligned with regulation: With increasing regulatory scrutiny in mature markets (notably the UK’s TS003 regime and related certification programs), R&D and product management teams can prioritize TS003-compliant options and Secured By Design pathways to access specification-rich channels.
- Procurement and pricing optimization: Raw material volatility — particularly in stainless steel, zinc, and brass — means procurement teams must contend with cost swings. Our cost-sensitivity modules translate metal-price scenarios into unit-cost and margin impacts to inform hedging and supplier diversification decisions.
- Channel and route-to-market clarity: The market remains fragmented, and distribution strategies matter. The report’s channel analytics identify where trade, retail, professional installer, and OEM routes favor a premium-bundled approach versus a price-led commodity approach.
What’s in the PW Consulting report — practical, decision-ready outputs
We designed the study as an operational toolkit for 2026: not a descriptive pamphlet, but a playbook. Key contents include:
- Top-line market sizing and validated historical series (2020–2025) plus granular scenario forecasts for 2026–2032 under baseline, upside, and downside demand cases.
- Segment architecture (by region, material, and end-use) and elasticities — presented at an executive level in this preview, with complete tables and downloadable datasets in the full report.
- Competitive benchmarking and product mapping (feature, price band, certification status), with OEM/ODM archetypes and white-space analysis for product extensions.
- Regulation and standards matrix — practical compliance checklists per target market and cost-to-certify estimates for TS003 and other approvals.
- Raw material sensitivity models — scenario outputs tie metal price movements to BOM cost, margin pressure points, and suggested supplier strategies.
- Commercial playbooks — go-to-market templates for distributors, branded manufacturers, and private-label partners, including channel-specific pricing ladders and installation-service bundling options.
- M&A and partnership screening framework — shortlists and valuation heuristics for bolt-on manufacturing, regional distribution, and aftermarket service assets.
- Dashboard-ready data files — Excel models and slide-ready summary charts for investor presentations and boardrooms.
Competitive landscape — consolidated insight (without revealing sensitive splits)
The chain door guard universe remains materially fragmented: the three largest players capture less than one-fifth of total industry revenue, and the top five together command roughly a quarter of the market. That concentration profile shapes the strategic playbook: scale matters for procurement and channel reach, but niche specialization and certification-driven differentiation create defensible mid-market positions.
Key vendor archetypes we profile in-depth:
- D&D Hardware Industrial / D&D Builders Hardware — A manufacturing-oriented player with strong OEM/ODM capabilities, offering zinc and brass chain designs optimized for ease of install and customization. Their product list includes models targeted at both trade distributors and door manufacturers, making them a pivotal partner for private-label rollouts.
- ABUS — A standards- and performance-led incumbent with a global footprint. ABUS’s designs emphasize burglary protection and non-invasive installation variants, positioning them well in urban multifamily and higher-spec residential niches.
- Prime-Line Products — A broad-range supplier focused on assortment and finish variety for retail and retrofit channels. Their strength is SKU breadth and finish options, supporting large retailers and aftermarket fulfillment networks.
- UAP Limited — An innovation-oriented UK-based supplier that has recently launched the Bullet Door Chain — a slim, magnetic-hold product engineered to exceed TS003 benchmarks. This launch is a useful case study of how certification-led new products can quickly gain specification traction.
- Schlage (Allegion) and National Hardware (ASSA ABLOY) — Legacy hardware brands leveraging channel recognition, integrated access solutions, and distribution scale. Their portfolios are often specified in commercial and multifamily projects where established brand and warranty support drive procurement choices.
Across these archetypes, competitive advantages cluster around three axes: certification and standards compliance (a growing procurement filter), finish and materials diversity (a retail and builder demand lever), and OEM/ODM flexibility (a manufacturing cost and go-to-market enabler).
Market dynamics shaping 2026 strategy
- Regulatory tightening: In key western markets, TS003-style impact and opening-limitation standards are moving from voluntary to procurement de-facto requirements in certain housing and social-housing contracts. Secured By Design approvals further strengthen specification appeal for compliant products.
- Material-price volatility: Oscillations in stainless steel, zinc, brass, and aluminum costs affect BOMs and pricing power. Manufacturers with diversified supply bases or value-engineering capabilities will better absorb short-term shocks.
- Fragmented demand profile: A blend of retrofit, replacement, and new-build activity produces differing margin pools. Residential retrofit tends to be price-sensitive, while institutional and specified projects reward certified performance and resilience.
- Channel evolution: Big-box and online retail continue to favor SKU breadth and quick fulfillment, while trade distributors demand installation-ready kits, technical documentation, and warranty support.
Top-line recommendations for 2026
Our bottom-line counsel is pragmatic and prioritized for impact in the coming 12–18 months:
- Prioritize certification where it unlocks specification channels: For manufacturers targeting institutional or social-housing tenders, TS003 and Secured By Design credentials materially improve tender competitiveness.
- Hedge material exposure: Negotiate flexible pricing clauses with suppliers, explore alloy substitution opportunities where performance allows, and model three price-shock scenarios to protect margin targets.
- Segment go-to-market by channel economics: Deploy premium, certified SKUs into specification channels and allocate high-volume, value-engineered SKUs to retail and OEM partners where scale matters.
- Invest in OEM/ODM flexibility: Shorter lead-time customization and packaging options for door manufacturers or private-label customers are growing win factors; consider modular tooling investments rather than single-model bespoke lines.
- Pursue targeted M&A for distribution reach: Consolidating regional distributors or acquiring complementary product lines (e.g., limiters, viewers) can increase basket size per installer or retailer visit and create cross-sell efficiencies.
- Use product as a service lever: Explore installation and warranty bundles for higher-margin revenue and stickier channel relationships — particularly in markets where homeowners value turnkey security solutions.
How to use our models in your 2026 planning
Clients adopting our forecast models and scenario tools use them in three practical ways: (1) to size addressable revenue by channel and product family under different macro assumptions; (2) to stress-test procurement and pricing strategies against metal-price volatility; and (3) to prioritize capital allocation among plant upgrades, certification costs, and go-to-market investments. Our deliverables include raw model files so teams can run custom scenarios tied to corporate planning calendars.
Conclusion — the strategic edge for 2026
The chain door guard market offers a clear, mid-growth opportunity for well-prepared players in 2026: modest top-line expansion backed by pockets of specification-driven, higher-margin demand. Success will favor firms that operationalize standards compliance, manage material risk intelligently, and align channel strategies with product architecture. PW Consulting’s study provides the analytics, playbooks, and benchmarking to turn that opportunity into measurable commercial outcomes.
This preview presents the strategic framing and high-level findings. The full PW Consulting report contains the complete segmented datasets, competitor scorecards, scenario models, and step-by-step implementation playbooks that you will need to execute in 2026. To access the full study and downloadable models, please visit our report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Chain Door Guard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mini Program Short Drama Market Set to Reach USD 10,850 Million in 2025, Growing at a 13.9% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Mini Program Short Drama Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study, base year 2025, positions the global mini program short drama market as a maturation opportunity for platform owners, studios, IP holders, and advertisers. The market expanded strongly through the early 2020s and, according to our forecast model, is expected to grow from an estimated USD 10,850 million in 2025 to roughly USD 27,033 million by 2032 — a compound annual growth rate of 13.93% over the 2026–2032 forecast window. Market concentration remains meaningful but not prohibitive (CR3 ≈ 32.5%, CR5 ≈ 41.2%), signaling room for differentiated entrants while scale players continue to set platform and commercial norms.
Worldwide Internet Protocol Telephony Market
Why this matters for 2026 strategy
- Scale meets fragmentation: Rapid audience growth and platform innovation have created an ecosystem where meaningful reach is achievable, but monetization varies widely by distribution model, content vertical, and regional consumer habits.
- Regulatory and platform governance are now a core business variable: Filing, content review, and enforcement mechanisms introduced by major platforms have already reshaped supply-side economics and will determine feasible production models for 2026 and beyond.
- Globalization and localization are no longer optional: A substantial share of top-grossing short drama apps is driven by producers and product models originating in China; cross-border expansion (particularly into Southeast Asia and parts of East Asia) requires both tech-localization and culturally targeted creative strategies.
What the full report delivers (practical, decision-ready content)
- Market sizing and forward-looking revenue scenarios to support five investment profiles (platform owner, studio/co-producer, IP licensor, advertiser/brand partner, and localization services provider).
- Go-to-market playbooks that translate platform mechanics into executable launch plans: A/B testing templates, episode cadence optimization, and retention levers tied to measurable KPIs.
- Monetization optimization toolkit: comparative frameworks for pay-per-episode, in-app purchases, subscriptions, ad monetization mixes, and hybrid approaches — with sensitivity analyses based on user LTV and churn benchmarks.
- Regulatory compliance checklist and content governance flowcharts to minimize takedown risk and accelerate approvals across major platforms.
- Partner selection matrix and negotiation playbook: how to evaluate platform partners, distributor splits, production co-finance terms, and data-sharing clauses that matter for discovery algorithms and revenue share.
- Production economics models: episode budgeting templates, break-even calculators, and scenario planning for serialized vs. anthology formats under different compliance regimes.
- Localization and international rollout templates: cultural adaptation checklists, testing protocols for Southeast Asia and Japan, and monetization-localization coupling strategies.
- Primary research appendices: executive interviews, platform scraping methodologies, and the statistical assumptions underpinning our CAGR and scenario forecasts.
Strategic imperatives for 2026
- Prioritize platform alignment over pure reach. For content owners, securing “first-window” arrangements on high-traffic mini program ecosystems materially raises discoverability and conversion. For platforms, exclusive short-form IP remains an acquisition lever for stickiness.
- Design for compliance from concept stage. Because filing and content review are now enforced as an operational constraint, projects built around traceable cost structures and transparent metadata will see faster approvals and fewer removals.
- Optimize episodic cadence for retention and ad sequencing. Short dramas are a discovery-first product; episode length, cliff-hanger mechanics, and micro-monetization hooks should be iteratively tested with telemetry-driven hypotheses rather than set by legacy TV norms.
- Build modular IP pipelines. Favor IP that can be repackaged across formats (micro-episodes, interactive segments, short-form spin-offs) to maximize monetization avenues and reduce single-format risk.
- Invest in cross-border product-market fit early. International launches should start with product-market experiments in linguistically and behaviorally adjacent markets; incorporate local creators and moderated incentives to bootstrap engagement without heavy upfront spend.
Competitive landscape — what leading players are signaling
The competitive map blends global platform scale, production capabilities, and emergent specialized studios. Below are distilled strategic positions and near-term implications for partners and entrants.
Worldwide Automatic Tolling Systems Market
- Tencent / WeChat ecosystem (WeTV): Strengths lie in integrated social distribution, payment, and existing mini program throughput. Recent co-production deals with Western studios show a dual strategy: defend domestic market share while internationalizing premium short-form IP. For partners: prioritize social sharing mechanics and native payment integration in pitches.
- ByteDance (Douyin, Melolo, PikoShow): Aggressive cross-border platform launches and experimentations with free-model distributions indicate a play to scale reach first, monetize later through hybrid ad and in-app formats. Content partners should expect rapid A/B testing cycles and platform-driven creative constraints.
- Kuaishou: Recent strategic retrenchments demonstrate the risk of platform-level pivots; content partners must protect IP freedom and exit clauses if platform strategies change. Diversify distribution to reduce single-platform exposure.
- iQIYI, Youku (Alibaba), Bilibili, Mango TV: Traditional streaming incumbents are modularizing workflows for micro-episode production and introducing creator toolkits. The competitive advantage is production expertise and cross-promo across long-form catalogs.
- China Literature (Tencent): Intellectual property supply remains a critical moat. IP owners will increasingly act as co-producers rather than passive licensors, dictating narrative adaptations for vertical formats.
- International and specialist players (Mega Matrix / FlexTV, Snail / Interactive Films, ReelShort, DramaBox): These firms signal two important trends: (1) integration of AI for personalization and immersive storytelling, and (2) partnerships for global distribution. Western and Southeast Asian distribution channels are opening to mini program-style formats through joint development agreements.
Regulatory and content dynamics — business rules you cannot ignore
Platform-driven regulation has shifted from ad hoc enforcement to process-driven compliance. By mid-2024/2025, major platforms implemented filing and review systems; enforcement actions (including takedowns and platform exits) materially altered supply-side economics. In China alone, the short drama audience exceeded 660 million regular viewers by 2025, creating both a massive market and a concentrated attention economy where non-compliance yields both reputational and revenue loss.
Worldwide Cation Exchange Membranes Market
Implication: regulatory flowcharts and production traceability are now operational requirements, not just legal niceties. Our report provides templated compliance documents and a decision tree for production finance under differing filing regimes.
How to use this report in your 2026 planning cycle
- Board-level briefing: Extract the market sizing scenarios and sensitivity tables to re-evaluate content investment thresholds and ROI timelines.
- Business development: Use the partner-selection matrix to prioritize platform negotiations and co-production options that align with your risk appetite.
- Product and editorial teams: Implement the episode cadence and engagement playbooks in a three-month rapid experiment to validate retention hypotheses before scaling.
- Legal and compliance: Adopt the report’s checklist and metadata standards to reduce approval turnaround and avoid platform delisting risks.
Methodology and signal quality
The report synthesizes platform telemetry, app-store intelligence, primary executive interviews, and a curated dataset of production economics. Our forecast scenario uses 2025 as the calibration year and applies discrete growth drivers across distribution, monetization, and regional expansion vectors to arrive at the 2026–2032 projections. CR3 and CR5 concentration measures are included to contextualize competitive pressure. To preserve tactical advantage for clients and readers, we intentionally withhold certain micro-segmentation figures from this public brief — the full dataset and model assumptions are available in the complete report.
Next steps
For licensing, detailed segment breakdowns, and bespoke advisory packages (market entry, M&A diligence, or co-production strategy), PW Consulting offers tailored engagements that leverage the full 2026–2032 dataset and scenario models. The full report contains the granular splits and templates needed to operationalize the strategies summarized here — access details are available on our report landing page.
PW Consulting — helping leaders translate the unfolding mini program short drama opportunity into repeatable, compliant, and profitable operations for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Mini Program Short Drama Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Soundproof Ventilator Market at USD 698.24 Million in 2025; Europe Leads with USD 239.15M — Forecast to Reach USD 1,062.44 Million by 2032 at 6.18% CAGR
By pmarketresearch, 2026-08-12
Worldwide Soundproof Ventilator Market: Strategic Outlook for 2026
As organisations recalibrate building performance priorities—balancing energy efficiency, indoor air quality and acoustic comfort—the market for soundproof ventilators is moving from niche specification to mainstream procurement. PW Consulting’s newest market study provides a focused, decision-ready narrative for executives planning product strategy, capital allocation, and market entry across 2026. This briefing summarises the study’s strategic takeaways without disclosing the granular segment tables reserved for report subscribers.
Women Business Loan Services Market
Why 2026 is a strategic inflection for market participants
-
The market has shown sustained expansion through the last half-decade, advancing meaningfully from the early-2020 base to a robust 2025 volume. PW Consulting projects continued expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.18%—a rate that creates both scale opportunities and competitive pressure for product differentiation.
Building Automation Waste Sorting System Market -
Regulatory tightening in multiple jurisdictions is accelerating demand for ventilation solutions that explicitly meet acoustic performance targets alongside air exchange and energy metrics. Notable regulatory drivers include stricter noise guidance for sensitive rooms and updated building energy standards that elevate the role of ventilator design in permit approval workflows.
Worldwide Biogas Plants Engineering, Procurement and Construction Management (EPCM) Market -
Building owners and specifiers are treating acoustic ventilation as a value driver for occupant health, productivity and property value—reframing purchases away from lowest-first-cost toward lifecycle performance and compliance assurance.
Market trajectory at a glance (strategic macro indicators)
-
After steady historical growth from the 2020 baseline, the market reached a strong position in 2025 and is forecast to climb over the next six years, reaching a substantially larger market value by 2032 under the base scenario. This trajectory is consistent with an expanding retrofit opportunity set, elevated new-build acoustic standards, and greater public-sector procurement for healthcare and educational estates.
-
Competitive structure is neither fully consolidated nor atomised. The top three suppliers hold material share, and the top five increase that position further—creating a market where scale and specialised acoustic IP matter, but regional and product specialists can still capture premium niches.
Operational intelligence in the report — what executives will use in 2026
PW Consulting designed the study to be executable by strategy teams and business units. The report is not just descriptive; it contains actionable modules to support decisions that must be made in 2026:
-
Market sizing and demand-model frameworks that allow rapid recalibration to alternative macro and regulatory scenarios.
-
Competitive playbooks and supplier scorecards that distil acoustic performance, certifications, retrofit compatibility and channel reach into procurement-ready matrices.
-
Go-to-market roadmaps for manufacturers and distributors, including prioritized target segments, pricing levers, and specification strategies for winning hospital, educational and residential retrofit tenders.
-
Investment case templates and ROI calculators for R&D projects (e.g., hybrid active/passive systems, integrated heat-recovery), M&A screening and capex decisions.
-
Compliance checklists keyed to the most influential regulations and standards (noise limits, building energy codes), plus vendor audit guidance to reduce permitting risk.
Competitive landscape — positioning and implications
The player set spans specialist acoustic-ventilation brands, established HVAC component manufacturers and material innovators. Each archetype presents different partnership and competitive dynamics for 2026.
-
LUNOS Lüftungstechnik GmbH (Berlin): A clear leader in decentralized units that combine high acoustic insulation with options for heat recovery. Their engineering emphasis on high dB attenuation and passive decentralisation positions them well for residential new-builds and renovation markets where thermal performance must be preserved. Strategic implication: rivals must match acoustic claims with credible third-party test data or co-develop retrofit interfaces that simplify installer adoption.
-
SIEGENIA GROUP (Germany): Focused on whisper-quiet wall and window units with integrated sensors and filtration. Their productised CO₂ regulation and filter options make them attractive for noise-polluted urban projects. Strategic implication: product differentiation will increasingly hinge on systems-level integration (sensors + control logic) rather than acoustic attenuation alone.
-
Ventomaxx GmbH (Landshut): Specialist in passive and active systems engineered to meet German DIN 4109. Their compliance-driven approach is a blueprint for markets where certification and code compliance dominate procurement. Strategic implication: players targeting high-end retrofits must prioritise certified acoustic performance and installer-friendly documentation.
-
Titon Holdings plc & R.W. Simon Ltd (UK): Both are established in acoustic trickle ventilators and sound-attenuating slot vents; their product ranges—covering humidity control and high closed-sound reduction—are suited to conservational and retrofit contexts. Strategic implication: incumbents with strong OEM relationships (window and door system suppliers) will remain gatekeepers to retrofit channels.
-
FläktGroup, TROX GmbH and Greenheck Fan Corporation: These larger HVAC component players bring scale, distribution and integration capabilities for commercial and industrial applications—providing silencers, attenuators and louvers that integrate into centralised air handling systems. Strategic implication: expect continued competition on systems integration and bundled offers that pair acoustic silencers with filtration and fan efficiency guarantees.
-
Wuxi Sinceriend New Material Technology: As a materials-focused entrant, they highlight how advanced absorptive media and manufacturing efficiency can undercut or augment mechanical solutions, especially in cost-sensitive regions. Strategic implication: materials innovation is a lever for cost reduction and form-factor transformation—an area ripe for licensing or partnership.
Recent catalytic events that will shape 2026 decisions
-
Trade show product visibility remains a key adoption channel. A leading European specialist recently showcased new deployments and installation case studies at a major trade fair in early 2026, underlining the continued importance of demonstration projects for persuading specifiers.
-
New product launches that prioritise flame-resistant absorptive media and fan-noise mitigation for infrastructure applications were introduced in 2025—revealing cross-over demand from energy and data-center cooling into acoustic ventilation technologies.
-
Regulatory signals—such as stricter noise targets in the UK’s building guidance, the legacy requirements under DIN 4109 in Germany, and updated building energy standards in the U.S. state of California—are already reshaping specification language in tenders and permit submissions.
Technology, materials and procurement trends to monitor
-
Hybrid architectures that combine passive acoustic inlets with small-scale recuperative fans are emerging as a commercial sweet spot—balancing energy performance with acoustic requirements in both retrofits and new builds.
-
Materials such as galvanised steel, aluminium and advanced melamine-based absorbers are continuing to dominate due to their trade-offs in durability, fire performance and acoustic loss. Manufacturers who can validate fire and acoustic performance simultaneously will shorten permitting cycles.
-
Certifications and third-party acoustic testing are becoming procurement gatekeepers. Buyers are increasingly requiring Dn,e,w-style ratings or equivalent test evidence for high-sensitivity installations.
Practical recommendations for 2026 decision-makers
-
Product strategy: Prioritise acoustic performance claims that are verifiable by third-party testing and couple them with installation-friendly retrofit kits to accelerate specification in urban renovation projects.
-
Commercial strategy: Develop bundled offers that include compliance documentation, noise modelling support and installer training—these reduce procurement friction and command price premiums.
-
M&A and partnerships: Evaluate bolt-on acquisitions that provide certified acoustic IP, or distribution partnerships with window/door OEMs to lock in retrofit channels.
-
Supply chain: Secure access to key absorptive materials and pursue design-for-manufacture initiatives to protect margin against material cost volatility.
-
Public-sector bids: Build a compliance-first dossier for tender responses in healthcare and education as noise limits and indoor environmental quality requirements intensify.
Risk factors and mitigation
-
Regulatory uncertainty in some jurisdictions: Maintain flexible product families and modular documentation packs to adapt quickly to local codes.
-
Technology substitution from centralised systems: Focus on niches where decentralised acoustic performance is the only viable solution—historic buildings, single-room acoustic control, and projects prioritising minimal ductwork.
-
Margin pressure from low-cost entrants: Protect margin through certified performance, service offerings (warranty, site commissioning), and installer certification programs.
How PW Consulting’s report supports near-term execution
The full study arms commercial, product and M&A teams with the necessary analytics and playbooks to act in 2026. It includes scenario-tested demand curves, a supplier benchmarking library, acoustic test-benchmarks, and practical procurement/installation kits. PW Consulting’s proprietary models allow users to re-run forecasts under alternative regulatory and macro scenarios, producing tailored investment cases for strategic committees and boardrooms.
Next steps
For strategy teams preparing investment memos, product roadmaps, or channel strategies for 2026, PW Consulting’s report provides the market-level context and executable modules to accelerate decision-making. To access the full dataset, granular segment analyses, and the downloadable go-to-market playbooks, contact PW Consulting or visit our report page for subscription details and executive briefings.
For detailed analysis of this topic, please visit the official page: Worldwide Soundproof Ventilator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Headphones Without Mic Market Forecast to Grow from USD 4,800 Million in 2025 to USD 6,423.5 Million by 2032 at a 4.25% CAGR
By pmarketresearch, 2026-08-12
Worldwide Headphones Without Mic Market — Strategic Preview for 2026 Decisions
PW Consulting’s latest market research, "Worldwide Headphones Without Mic Market," is a decision-grade briefing built to inform product strategy, manufacturing choices, M&A diligence, and channel investments as companies plan for 2026 and beyond. The passenger on this journey is a mature, technically nuanced market that is nevertheless demonstrating steady expansion: our base-year sizing (2025) puts the market at approximately USD 4.8 billion, and our scenario-driven forecasts project a compound annual growth rate (CAGR) of 4.25% across the 2026–2032 horizon—delivering a materially larger market by the end of the forecast period.
Worldwide Human Machine Interface (HMI) Enclosures Market
Why this report matters for 2026 strategic planning
-
Actionable forecasting in an incremental-growth market: With several adjacent audio categories compressing and premium audio demand fragmenting between pro-audio, audiophile, and home entertainment use-cases, the forecast’s moderate CAGR hides structural shifts. Executives who plan only by headline growth risk being out-positioned by competitors that exploit niche premium segments and supply resilience.
Worldwide Merchant Marketing Software Market -
Risk-aware sourcing and cost engineering: Input-cost volatility, evolving regulation, and concentrated supplier capacity are changing sourcing economics—this report converts those risks into ranked mitigation options and contract-level levers.
MTHFR Gene Detection Kit Market -
Competitive differentiation beyond specs: As feature parity grows (build quality, driver technology, damping materials), distribution, brand heritage in pro and audiophile segments, and manufacturing flexibility become primary margin drivers. Our vendor benchmarking illuminates those differentiators.
Market snapshot (high-level)
Between 2020 and 2025 the market expanded from the high‑thousands into the mid‑single‑digit billions of USD, reflecting steady demand for both professional and high‑fidelity passive headphone designs. As noted above, our baseline 2025 market size is ~USD 4.8 billion. Under our central forecast—reflecting current macro assumptions, raw material trends, and regulatory shifts—the market expands at a 4.25% CAGR through 2032, reaching a significantly larger absolute size by the end of the period. Importantly, market concentration is meaningful but not prohibitive: the top three players account for a substantial share, while the top five collectively command just over half the market—conditions that favor both scale players and specialist independents with strong brand equity.
What’s inside the report (practical, transaction-ready content)
-
Robust methodology and scenario suite: Transparent market-sizing logic, sensitivity testing, and three-layer scenario outputs (conservative, base, aggressive) that map to alternative macro sets for 2026 board planning.
-
Go‑to‑market playbooks: Channel segmentations, pricing ladders, and promotion cadence templates for premium pro, studio, and audiophile sub-sectors—each with carry-through unit economics and margin waterfall models.
-
Vendor benchmarking: Comparative scorecards on product engineering, supply reliability, aftermarket service, and distribution strength—synthesising primary interviews and proprietary shipment data.
-
Supply‑chain risk maps: Critical‑path supplier lists, cost-sensitivity matrices (raw magnets, drivers, and wiring), lead-time scenario planning, and suggested contracting terms to hedge capacity bottlenecks.
-
Regulatory and compliance checklist: Practical compliance actions for regional regulatory updates, product labelling, and RoHS/REACH interactions — formatted as an internal audit-ready checklist.
-
M&A and partnership framework: Target-scoring templates for tuck‑ins, equity stakes, and JV partners, with deal structuring guidance tied to synergy capture and IP due diligence priorities.
-
CAPEX/OPEX buildouts: Modelled cost-to-scale paths for in-house driver assembly, contract manufacturing expansion, and selective verticalization for planar-magnetic supply chains.
Competitive landscape — who matters and why
The market is anchored by a mix of global incumbents and boutique specialists. Our competitive assessment focuses on product positioning, channel access, manufacturing exposure, and innovation pipelines. Companies covered in the report include Sony Corporation (Tokyo; https://www.sony.com), Sennheiser (Wedemark; https://www.sennheiser.com), Audio‑Technica (Machida; https://www.audio‑technica.com), Beyerdynamic (Helicon; https://www.beyerdynamic.com), Grado Labs (Brooklyn; https://gradolabs.com), AKG/Harman (Northridge; https://www.akg.com), Focal (Saint‑Étienne; https://www.focal.com), and Audeze (Costa Mesa; https://www.audeze.com).
-
Incumbent advantage: Large players like Sony and Sennheiser retain channel breadth and scale sourcing advantages. Their product lines span studio, broadcast, and consumer tiers, allowing cross-subsidization of narrower professional SKUs.
-
Specialist differentiation: Boutique brands (Grado, Audeze, Focal) compete on materials, driver tech (including planar and beryllium tweeter implementations), and brand storytelling—factors that preserve premium ASPs despite modest category growth.
-
Product cadence: The competitive set continues to release iterative pro and high‑end models (e.g., recent new-studio and pro updates in 2024–2025), reinforcing that R&D and OEM relationships remain key for sustaining premium segments.
-
Consolidation potential: Given the CR5 concentration profile, acquisitive strategies to buy scale and distribution, or to capture niche technology (planar driver IP, materials sourcing), are high‑utility plays for 2026 M&A pipelines.
Recent supplier and regulatory dynamics that change decision math
Executives need to bake several non-marketline factors into 2026 planning:
-
Raw-material cost pressure: Neodymium magnet pricing recorded an approximate year‑over‑year increase, reflecting supply constraints. This has a direct impact on mid- and high‑end driver bill‑of‑materials and compresses margin on fixed‑price contracts.
-
Labour-cost movement in Southeast Asia: Assembly markets have seen wage creep, which shifts the optimal factory footprint for low‑volume premium lines versus high-volume consumer SKUs.
-
Regulatory tightening: Recent updates to European hazardous‑substance directives impose new material ceilings for cable and component composition effective in early 2026—companies selling into those markets must validate BOMs and third‑party test certifications now.
-
Tariff environments remain consequential: Existing tariff constructs on imports from China continue to influence landed costs and channel pricing strategies in North America, reinforcing the need for tariff-mitigation playbooks.
-
Component lead-times: High‑end planar magnetic driver lead times have extended substantially due to concentrate processing bottlenecks—this is a driver‑specific constraint with outsized program risk for boutique audiophile launches.
Strategic implications and recommended 2026 playbooks
-
Sourcing diversification and hedging: Build dual‑sourcing for critical drivers and magnets, introduce conditional pricing clauses in multi‑year contracts, and consider inventory pre-buy strategies for high‑risk components when net present value (NPV) supports carry costs.
-
Product architecture for resilience: Modularize designs so that driver subsystems and cable assemblies can be swapped without platform requalification. This reduces time‑to‑market risk when alternative suppliers are activated.
-
Channel-first segmentation: Prioritize distribution investments in professional and audiophile channels where brand equity and service can support premium price points; use targeted DTC strategies for higher-margin limited runs.
-
M&A and JVs: Pursue tuck‑ins that fill driver‑technology gaps or that provide regional assembly capacity for tariff optimization. Our M&A framework ranks targets by capability, cultural fit, and achievable synergies.
-
Regulatory remediation as competitive moat: Early compliance and certification (RoHS/REACH) for new product families can become a point of differentiation for institutional buyers—treat certification timelines as product‑development gating criteria.
Decision support and how executives should use this briefing
For leadership teams preparing 2026 budgets, board materials, and product roadmaps, this report is constructed to be pragmatically useful: the scenario suite directly maps to five‑year P&L levers; supply‑chain modules provide contract language and cost‑takeout targets; and competitive scorecards enable side‑by‑side benching for potential acquisitions. We recommend three near‑term decision milestones:
-
Q1 2026: Finalize supplier hedges and pre‑purchase critical component allocations if your product roadmap depends on planar or rare‑earth‑based drivers.
-
Q2 2026: Execute channel pilot shifts into professional studios and audiophile retail, using shortened SKUs and limited editions to test higher ASP tolerance.
-
Mid‑2026: Revisit M&A and JV pipelines with a focus on regional assembly and driver technology: our scoring templates can accelerate screening and valuation workstreams.
Why PW Consulting’s perspective is unique
We combine supplier-level cost insight, product-portfolio analytics, and hands-on M&A frameworks tailored for audio-device ecosystems. This report integrates primary interviews with manufacturers, proprietary shipment and warranty datasets, and a supply‑chain stress model calibrated to the latest commodity, wage, and tariff inputs. The result is a compact but operationally actionable intelligence product—built for teams that must move from strategy to execution.
Accessing the full intelligence
This briefing is designed as a strategic “trailer”: it demonstrates the depth of the analysis, the rigor of our forecasting, and the practical utility of our playbooks while deliberately withholding full granular segmentation tables and model worksheets so that decision-makers can engage directly with our team for tailored deliverables. For the complete dataset, regional and application splits, downloadable financial models, and the full vendor scorecards (including negotiation playbooks and contract templates), visit our report portal or contact PW Consulting’s Head of Research to schedule a walkthrough and custom extract of the models for your business planning cycle.
Prepared by PW Consulting — Senior Strategy & Industry Analysis. For direct inquiries or to arrange a bespoke briefing aligned to your 2026 planning cadence, please contact our client team.
For detailed analysis of this topic, please visit the official page: Worldwide Headphones Without Mic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 6.15% CAGR for Worldwide Negative Ion Cyclotron Market in 2026–2032 Forecast
By pmarketresearch, 2026-08-12
Worldwide Negative Ion Cyclotron Market — Strategic Preview for 2026 Decision-Makers
Executive teaser
PW Consulting’s new market brief on the Worldwide Negative Ion Cyclotron Market positions executives to make higher-confidence decisions in 2026 and beyond. The sector has grown from an estimated USD 312 million in 2020 to roughly USD 425 million in 2025 and is forecast to expand at a steady compound annual growth rate (CAGR) of approximately 6.15% through 2032 — reaching the mid‑six‑hundred million USD range by the end of the forecast horizon. These aggregate trajectories reflect a combination of sustained clinical demand for PET radioisotopes, growing theranostics programmes, and ongoing investments in decentralized isotope production capacity. This release highlights the strategic implications of those macro trends while intentionally withholding the granular segmentation tables that are included in the full report.
Floating Solar Structure Market
Why this market matters for 2026 strategy
-
Operational resilience: The COVID-era disruptions and continuing supply-chain constraints for medical isotopes have driven hospital groups and national programmes to reconsider centralized supply models. On-site and regional cyclotron deployments are increasingly part of resilience and quality-of-care strategies.
Cybersecurity Vulnerability Assessment Service Market -
Theranostics and pipeline expansion: Momentum in theranostics is increasing demand for both diagnostic and therapeutic isotopes. That creates differentiated demand pressure across energy bands, facility types, and aftermarket service needs.
New Energy Box-type Substation Transformer Market -
Investor clarity: A transparent growth path with a mid-single-digit CAGR provides a predictable environment for capital deployment, acquisition planning, and greenfield facility buildouts — assuming buyers internalize regulatory and technical constraints.
Market dynamics and technical constraints
The sector’s near-term upside must be evaluated against several non-negotiable technical and regulatory realities. Commercial negative H- ion sources typically face space-charge and extraction limits that constrain beam currents in the 1–5 mA envelope; this is a persistent hardware bottleneck that caps per-unit throughput. Facilities deploying cyclotrons must also provision robust infrastructure — RF power systems on the order of hundreds of kilowatts and ultra‑high vacuum systems for stable negative ion acceleration — adding to upfront capex and ongoing technical risk.
On the regulatory side, operators and OEMs are navigating multiple overlapping frameworks. Medical cyclotron facilities and equipment are subject to international radiation protection and facility design standards (e.g., IAEA guidance) and, in key markets, medical device classification and quality-system requirements such as ISO 13485 under EU MDR regimes. High-energy systems (above certain energy thresholds) can trigger export licensing under dual‑use agreements, introducing transaction friction for cross-border sales and technology transfers.
Competitive landscape — what incumbents and challengers are focusing on
The global supply base is concentrated: top manufacturers capture a dominant share of commercial shipments and installed base, with the leading three firms representing roughly two-thirds of the market and the top five accounting for a substantially larger majority. That concentration reinforces the strategic importance of aftermarket services, spare-part logistics, and long-term service agreements as drivers of recurring revenue.
-
Ion Beam Applications (IBA) — A long-standing leader with a broad Cyclone family that covers low to high-energy needs. IBA’s positioning emphasizes high-energy capability for theranostic and therapeutic isotope production, global service coverage, and strategic wins in major health systems. Recent high-profile installations and orders underscore their role in scaling theranostic supply chains.
-
Advanced Cyclotron Systems Inc. (ACSI) — ACSI competes on modular, mid-energy systems optimized for multi‑isotope PET production and flexibility for clinical sites. Their regional deliveries and installations point to strength in adaptability and localized support models.
-
GE Healthcare — Leveraging a global imaging installed base, GE focuses on integrating cyclotron solutions with its end-to-end molecular imaging platforms and service networks. Their offerings are attractive for hospital groups seeking supplier consolidation and integrated service contracts.
-
Sumitomo Heavy Industries — A Japan-based OEM with reliable clinical-grade cyclotron technology, focusing on operational robustness and alignment with regional regulatory expectations in Asia-Pacific and other markets.
-
TeamBest Global — Competes on cost-competitive models and tailored solutions for smaller or emerging facilities, targeting price-sensitive deployments and markets seeking rapid capacity expansion.
Tactically, incumbents are differentiating through service agreements, turnkey installation capabilities, and collaborative partnerships with radiopharmacies and health systems. OEMs that convert installed-base trust into long-term service revenue will be best positioned to capture the more stable slice of total sector value over the next five years.
What the PW Consulting report contains (practical elements for action)
-
Market sizing, historical performance and scenario-driven forecasts at the total-market level (base year 2025, forecast 2026–2032).
-
Technology deep-dive: acceleration physics, common failure modes, beam current constraints, and RF/vacuum system requirements that matter at deployment stage.
-
Regulatory and compliance matrix: IAEA guidance, EU MDR classification considerations, ISO pathways, and export-control triggers.
-
Supplier benchmarking and capability maps covering product portfolios, service footprints, and commercialization strategies.
-
Investment and facilities playbook: capex/opex line items, commissioning timelines, staffing & competency requirements, and procurement checklists.
-
Strategic risk heatmap and mitigation playbooks for supply-chain disruptions, export licensing, and technology obsolescence.
-
M&A and partnership pipeline view to support strategic conversations with incumbent OEMs, radiopharmacies, and national programmes.
Actionable recommendations for 2026 decision-making
-
Prioritize service and spare parts as part of procurement: evaluate total life-cycle cost rather than initial capex alone. With a concentrated supplier base, long-term service contracts materially affect unit economics.
-
Build regulatory compliance into project timelines early: EU MDR, IAEA site requirements and export licensing can add months to commissioning if not anticipated.
-
De-risk high-energy ambitions: if pursuing >30 MeV capability, account for export-control complexity and partner with OEMs that demonstrate proven export‑licensing processes and international logistics experience.
-
Align capacity expansion with isotope roadmaps: match cyclotron energy and beam-current choices to the isotope portfolio your clinical or commercial roadmap requires — avoid one-size-fits-all procurements.
-
Invest in staff competencies and local service capability: technical staffing and on-site maintenance are the leading contributors to uptime and supply security.
-
Use modular deployment where speed-to-market matters: mid-energy, plug-and-play systems can lower initial barriers to entry for regional radiopharmacies and hospital networks.
-
Factor in hardware bottlenecks: current H- source and extraction physics place practical ceilings on single-unit throughput; consider distributed networks of cyclotrons rather than scaling a single high-current machine.
-
Evaluate M&A and strategic partnerships to gain access to aftermarket channels and accelerate market entry with lower execution risk.
Research methodology and what’s intentionally omitted here
The findings presented in this preview are drawn from our 2025 base-year synthesis, combining public company disclosures, recent press announcements, facility-level commissioning reports, interviews with technical and regulatory experts, and proprietary industry modelling covering 2020–2025 history with a forecast period through 2032. To comply with the “trailer” principle of this release, we have showcased aggregate market growth and strategic takeaways while omitting detailed region/application splits and granular segment matrices that form part of the full paid report. Those withheld tables and supplier-level revenue reconciliations are available in the comprehensive dataset and appendix of the full study.
Closing — how to use this preview
For hospital systems, radiopharma operators, OEMs, private equity investors, and government planners, this briefing should be treated as the strategic framework to prioritize investments and risk mitigations in 2026. The sector’s predictable aggregate growth (mid-single-digit CAGR) provides a favourable backdrop, but execution depends on mastering regulatory pathways, technical constraints, and service economics. PW Consulting’s full report converts the strategic contours summarized here into procurement-ready models, supplier scorecards, and scenario-based financials to support board-level and operational decisions.
To obtain the full dataset, facility-level models and supplier scorecards that underpin these conclusions, access the complete PW Consulting Worldwide Negative Ion Cyclotron Market report via our website or contact your PW Consulting account lead for a sample extract and executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Negative Ion Cyclotron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Livestock Diagnostics Kits Market valued at USD 1,845.5 Million in 2025 to surge to USD 3,162.9 Million by 2032 at an 8.0% CAGR
By pmarketresearch, 2026-08-12
Worldwide Livestock Diagnostics Kits Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s new market intelligence brief on the Worldwide Livestock Diagnostics Kits Market distils the high‑impact signals that will determine competitive advantage in 2026. Anchored on a 2025 base-year and a 2026–2032 forecast window, the study models the industry at a compound annual growth rate (CAGR) of 8.0% across the forecast period. Our proprietary sizing shows a market that expanded from approximately USD 1.28 billion (2020) to USD 1.85 billion (2025) and, under base-case assumptions, is projected to surpass USD 3.16 billion by 2032. This preview explains the report’s strategic value for executives, investors, and policy makers while intentionally withholding granular split data—designed to invite targeted engagement with the full report.
Worldwide Advanced Retail Space Management Applications Market
Why this report is essential for 2026 strategic choices
- High-stakes capital allocation: Diagnostics product roadmaps, manufacturing scale-up, and acquisition targets require confident revenue and margin trajectories—our forecast and scenario tools quantify those trade-offs.
- Fast-moving technology adoption: On‑farm point-of-care (POC) platforms and multiplex molecular assays are reshaping go-to-market economics; the report translates technical performance into commercial outcomes.
- Regulatory and trade alignment: Export controls and harmonized validation standards are increasingly determinative of addressable market access. The report maps the evolving compliance landscape and its commercial consequences.
- Risk management: Supply chain fragility for reagents and components, and disease outbreak volatility, require contingency playbooks—our scenarios operationalize trigger points and mitigation options.
Macro dynamics shaping 2026 decisions
- Structural growth and predictability: An 8.0% CAGR across the forecast period reflects robust, sustained demand driven by intensifying surveillance, value-driven herd health programs, and wider adoption of rapid, farm‑level tests.
- Regulatory convergence and market access: International authorities are moving toward more standardized validation and transparency. Notable frameworks include WOAH’s register and standardized validation procedures, and updated guidance from USDA APHIS that affect test validation and labeling—both create new commercial and compliance imperatives for kit providers.
- Product performance thresholds: Industry benchmarking shows multiplex PCR panels and lateral flow assays now achieving reported accuracy improvements (up to ~98%) and on‑farm result times under 15 minutes—this raises the bar for competitive differentiation and price justification.
- Concentration and competitive dynamics: Market concentration is meaningful but not prohibitive—incumbents capture a substantial portion of revenue, leaving profitable opportunity for specialist innovators and regional consolidators. The structure favors platform players with wide portfolios and scale‑efficient manufacturing.
Competitive landscape—what executives need to know
The market comprises global platform leaders, specialized test manufacturers, service laboratories, and agile point‑of‑care innovators. Key players we profile include:
Light Power Lithium Battery Market
- IDEXX Laboratories, Inc. (Westbrook, Maine, USA) — comprehensive livestock diagnostics spanning ELISA, PCR (RealPCR) and rapid tests, with a strong channel presence in both on‑farm and laboratory settings.
- Zoetis Inc. (Parsippany, New Jersey, USA) — broad immunodiagnostics, rapid tests and point‑of‑care platforms (recent Vetscan innovations) that leverage brand reach into production animal markets.
- Thermo Fisher Scientific Inc. (Waltham, Massachusetts, USA) — enterprise molecular and serological solutions with regulatory‑grade product lines suitable for surveillance and lab networks.
- Neogen, bioMérieux, Bio‑Rad, Indical/ Vimian Group, IDvet, Agrolabo and a cohort of regional specialists — each offering distinct strengths in rapid assays, ELISA, molecular kits, or laboratory services.
- Service and testing networks such as Eurofins and GD Animal Health provide complementary testing capacity and a channel for diagnostic kit uptake, particularly in export certification workflows.
Recent product activity—such as Zoetis’ roll‑out of AI‑enhanced point‑of‑care hematology platforms and IDEXX’s broader diagnostic panel launches—illustrates the dual trend of platform convergence (combining analytics, hardware and reagents) and value capture at the service layer.
Worldwide Database Marketing Market
What the full report delivers: operational, not just descriptive, intelligence
- Transparent methodology: A reproducible bottom‑up market sizing and an audit‑ready forecast model for 2026–2032, including sensitivity testing.
- Commercial segmentation: Breakdowns by region, technology, and animal type with dynamic dashboards (note: detailed split tables are available in the full report).
- Regulatory and validation matrix: Country‑by‑country validation requirements and time-to-market estimates calibrated to WOAH and USDA APHIS guidance.
- Competitive playbooks: Product benchmarking, route‑to‑market options (direct sales, distributor networks, service partnerships), pricing archetypes and margin models.
- Supply chain and manufacturing assessment: Critical raw material mapping, single‑source risk highlights, and recommended resilience levers.
- M&A and partnership intelligence: Candidate screening framework, valuation multiples observed in the last 24 months, and integration checklists for diagnostics acquisitions.
- Actionable scenario planning: Baseline (8.0% CAGR), upside and downside scenarios, with trigger events and response roadmaps.
How to use this intelligence in 2026 (practical pathways)
- Portfolio prioritization: Use the report’s product‑level profitability matrix to decide whether to accelerate POC lateral flow launches, expand multiplex PCR capacity, or license third‑party assays.
- Market entry sequencing: Leverage the regulatory matrix to prioritize launches in jurisdictions where harmonization and demand growth maximize ROI within 12–24 months.
- Partnership and channel strategy: Match test kits to channel models—distributors, lab networks, or integrated service offerings—to optimize price realization and adoption velocity.
- Manufacturing and supply resilience: Implement dual sourcing and strategic buffer inventories for reagents flagged as high‑risk in our supply assessment.
- M&A and JV playbook: Use our screening model to size tuck‑ins that fill technological gaps (e.g., AI-enabled POC analytics) or expand service footprints.
Executive strategic recommendations for 2026
- Invest selectively in rapid POC platforms and digital analytics. The combination of faster result times and embedded decision intelligence materially increases willingness-to-pay among producers and veterinarians.
- Prioritize regulatory alignment early. Build WOAH and USDA APHIS validation roadmaps into product development timelines to avoid market access delays and to support export-centric customers.
- Pursue hybrid commercial models: bundle consumables with subscription analytics and laboratory confirmatory testing to convert one‑time kit buyers into long‑lived customers.
- Strengthen reagent supply chains and localize critical manufacturing where feasible to reduce lead times and geopolitical risk exposure.
- Use M&A to acquire capabilities rather than revenue alone—target molecular assay specialists, platform analytics providers, or regional labs that provide immediate channel and regulatory footholds.
- Establish real‑time market monitoring KPIs (e.g., validation approvals, POC adoption rates, outbreak indicators) tied to governance forums so that strategy is adaptive rather than reactive.
Scenario planning and key risk indicators
Our scenario framework defines a baseline aligned with the modeled 8.0% CAGR, an upside case driven by accelerated tech adoption and regulatory harmonization, and a downside case tied to trade disruptions or raw material shortages. Critical indicators to watch include:
- Validation approvals and WOAH registry updates—significant accelerators of cross‑border adoption.
- Performance milestones on accuracy and time‑to‑result for multiplex assays and lateral flow devices—consumer and purchaser confidence hinges on these metrics.
- Supply chain lead times for critical reagents and consumables—early warning of potential margin compression or delivery failures.
- M&A activity among the leading platform players—signals consolidation and competitive exit/entry points.
Next steps and how to access full intelligence
This preview highlights the strategic contours that will matter most in 2026: a growing, technically maturing market with clear winners among platform integrators and opportunity for focused innovators. PW Consulting’s full Worldwide Livestock Diagnostics Kits Market report provides the guarded detail you need to operationalize these insights—complete segmentation tables, interactive forecast models, granular competitor financials, and customizable scenario dashboards. For board briefings, product roadmap validation, or acquisition diligence we offer bespoke workshops and hands‑on modeling sessions derived from the report’s primary research corpus.
Engage with PW Consulting to obtain the full dataset and executive briefing—our analysts will tailor the insights to your strategic horizon and decision cadence.
For detailed analysis of this topic, please visit the official page: Worldwide Livestock Diagnostics Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com