

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Military Protective Gear Market to Reach USD 22,931.18 Million by 2032, Growing at a 4.5% CAGR

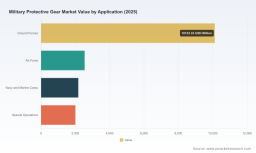
Worldwide Military Protective Gear Market — Strategic Executive Briefing (PW Consulting)
PW Consulting today releases an executive briefing drawn from our forthcoming Worldwide Military Protective Gear Market report (base year 2025, historical window 2020–2025, forecast horizon 2026–2032). This briefing distills the high‑impact insights defense leaders, suppliers, and investors must act on in 2026. It is crafted as a strategic “trailer”: it demonstrates the analytical depth of our work while intentionally withholding detailed subsegment and regional tables to encourage direct access to the full report for transaction‑critical data.
Braided Ground Jumpers Market
Market snapshot: what the numbers mean for strategy
The market for military protective gear continues to expand steadily. From an observed market value at the start of our historical window to a validated base‑year total in 2025, the sector is projected to grow at a compound annual growth rate (CAGR) of 4.5% through our forecast period 2026–2032. That trajectory takes the market from its 2025 valuation into materially larger absolute size by 2032, reflecting a confluence of persistent procurement programs, materials innovation, and geopolitical-driven demand.
Worldwide Non-Native Database Management Systems Market
Two quick implications for 2026 decision cycles:
Worldwide Medical Spray Market
- Program managers should reframe procurement timelines around multi‑year sustainment and upgrade windows rather than one‑off buys — predictable growth and replacement cycles offer opportunities for platform commonality and life‑cycle cost reduction initiatives.
- Investors and suppliers need to prioritize scalable manufacturing and strategic raw‑material access: as demand grows, margins will be determined by material cost management and the ability to deliver certified, performance‑guaranteed solutions at scale.
Why this market is structurally attractive — and where risks concentrate
Three structural features define the sector today:
- Technology layering: Protective systems are increasingly integrated — from advanced materials (aramids and UHMWPE) to sensor and communications integration in helmets and visors — creating value beyond base hardware.
- Procurement stickiness: Military procurement cycles, retrofit programs, and certification requirements produce multi‑year revenue streams with high barriers to entry once type approvals and logistics pipelines are established.
- Moderate market concentration: The top tier of suppliers holds meaningful but not overwhelming share, leaving room for niche specialists, regional champions, and innovative startups to scale through strategic partnerships and targeted contract wins.
Risks that will influence 2026 outcomes include raw‑material price volatility for premium ballistic fibers, the operational friction introduced by export controls such as ITAR, and accelerating regional procurement preferences that favor localized manufacturing partnerships.
Report coverage — practical and actionable
Our full report translates market intelligence into executable guidance. Core elements include:
- Validated market sizing and forward forecasts (2026–2032) with sensitivity scenarios tied to defense budget trajectories and material cost curves.
- Technology and product roadmaps across major categories — body armor systems, ballistic helmets and headborne systems, CBRN/respiratory protection, and protective eyewear/footwear — highlighting upgrade paths and integration opportunities.
- Supply‑chain and raw‑material analysis, with forward pricing scenarios for aramid fibers (e.g., Kevlar) and UHMWPE composites and a supplier risk heatmap for 2026 procurement planning.
- Regulatory and certification playbook covering international ballistic standards and export control constraints; practical compliance steps for cross‑border programs.
- A competitively framed M&A and partnership decision matrix identifying where scale, technology capability, or regional footprint unlock higher contract win rates.
- Differentiated go‑to‑market strategies for primes, component suppliers, and non‑tier‑one entrants — including margin models for sustainment and aftermarket service offerings.
Note: This briefing intentionally omits detailed regional and subsegment tables. The full report provides the complete numerical breakdowns necessary for bid modeling, supplier selection, and due diligence.
Competitive landscape — who matters and why
The market is served by a blend of large diversified primes, specialty material producers, and focused system integrators. PW Consulting’s competitive profiles assess each incumbent on technology roadmap, program references, manufacturing flexibility, and certification footprint. Highlights include:
- 3M Company — Leveraging lightweight composite design and integrated protective systems, 3M remains prominent where multi‑threat helmets and hearing/physiological protection converge with soldier systems.
- BAE Systems — A proven integrator of modular armor and plate systems, BAE plays strongly where end‑to‑end soldier protection suites and vehicle integration are prioritized by defense buyers.
- Gentex Corporation — A leader in helmet systems and communications‑integrated head protection; recent contract extensions underline its position on sustainment tractability for large defense logistics agencies.
- DuPont and Honeywell International — Materials suppliers that underpin the performance envelope of nearly every major product category; their technologies determine both capability and cost curves.
- Avon Protection and specialized suppliers (ArmorSource, Revision Military, MKU, Safariland, among others) — These firms occupy crucial niches from CBRN respiratory systems to modular dismounted soldier solutions, and are often the source of rapid innovation.
PW Consulting’s market concentration analysis shows a moderate level of aggregation at the top — sufficient to sustain competitive pricing pressure but not so concentrated as to block new entrants who can deliver validated performance and certified supply capability.
Recent developments shaping 2026 strategic choices
- Contract renewals and production awards are reinforcing incumbent supply chains — recent multi‑year contract extensions for helmet programs underscore the value of logistics readiness and compliance capabilities.
- Procurement of protective inserts and plates by major armed forces signals continued momentum for high‑performance armor solutions; suppliers able to combine manufacturing scale with certification capacity will win prioritized slots.
- Consolidation activity among mid‑tier specialists is creating acquisition pathways for primes seeking to vertically integrate or to acquire rapid access to new materials and manufacturing techniques.
Strategic playbook for 2026 — prioritized actions
To convert market trends into near‑term competitive advantage, PW Consulting recommends the following prioritized actions for decision‑makers:
- For defense primes and integrators: accelerate modular system strategies that enable incremental upgrades (sensors, communications, add‑on armor) without forcing full system requalification; this reduces program cost and shortens procurement cycles.
- For materials and component suppliers: secure long‑term offtake and hedging arrangements for aramid and UHMWPE feedstocks; invest selectively in certification capacity to shorten buyer validation timelines.
- For midsize manufacturers and niche innovators: pursue selective regional partnerships with defense OEMs to capitalize on localized procurement preferences and offset export control barriers.
- For investors and M&A teams: target bolt‑on acquisitions that close capability gaps in CBRN systems, helmet‑mounted sensors, or sustainment logistics rather than broad, unrelated diversification.
- For procurement offices: embed lifecycle‑cost modeling into RFPs and require modular upgrade roadmaps so that acquisition choices reward suppliers who can demonstrate endurance and upgradeability.
Regulatory and supply‑chain checklist
Three compliance and supply‑chain items should be on every 2026 checklist:
- ITAR and export licensing readiness for cross‑border deliveries of certain ballistic technologies — incorporate licensing cycle buffers into contracting timelines.
- Third‑party ballistic certification pathways — build these into product development roadmaps to avoid late‑stage rework and contract delays.
- Material sourcing diversification — develop alternative suppliers or stock strategies for premium fibers to mitigate single‑source disruptions and price spikes.
Why PW Consulting’s report is mission‑critical for 2026
Our report goes beyond market sizing. It couples quantitative forecasts with procurement playbooks, certification roadmaps, supplier due‑diligence templates, and investible deal flow scenarios. For organizations planning budgets, M&A, or R&D investments in 2026, the report provides:
- Actionable insights to prioritize spending where return and strategic value converge;
- A practical framework to accelerate fielding of integrated protection systems while managing compliance and supply‑chain risk;
- Competitive benchmarking and supplier scorecards that inform bid strategies and partnership selection.
Next steps — how to use this briefing
Use this briefing to align 2026 planning cycles around sustained market growth, rising materials intensity, and regulatory compliance. For transaction teams, procurement offices, and R&D leaders requiring the underlying numerical tables, subsegment splits, and scenario‑level sensitivities, the full Worldwide Military Protective Gear Market report provides the necessary depth and appendices — including validated vendor scorecards and model spreadsheets for bid and investment stress‑testing.
PW Consulting will continue to publish targeted updates as major program awards, material price shocks, or regulatory changes occur through 2026. For immediate advisory engagement or to secure the complete report with confidentiality‑graded datasets and supplier assessments, please contact our Commercial Intelligence team.
For detailed analysis of this topic, please visit the official page: Worldwide Military Protective Gear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com