

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Worldwide Reusable Food Wrap Market to Rise from USD 245.0 Million in 2025 to USD 397.3 Million by 2032 at a 7.15% CAGR
By pmarketresearch, 2026-08-12
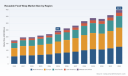
Worldwide Reusable Food Wrap Market: Strategic Imperatives for 2026 — A PW Consulting Outlook
Executive snapshot
As brands, manufacturers, and investors prepare their 2026 road maps, the reusable food wrap market presents a compelling mix of steady demand growth, regulatory tailwinds, and supply‑side complexity. Our latest PW Consulting report finds the global market expanding from roughly USD 173.5 million in 2020 to USD 245.0 million in 2025, with a forecast trajectory that anticipates continued expansion at a compound annual growth rate (CAGR) of 7.15% through the 2026–2032 window — reaching an estimated USD 397.3 million by 2032. These headline metrics frame a market that is maturing but still fragmented, where disciplined strategy can meaningfully move the needle on share and margin.
Solar Panel Recycling Management Market
Why this matters for 2026 decision‑makers
- Commercialization timing: A mid‑single digit CAGR masks pockets of accelerated adoption driven by policy shifts, retail assortment changes, and rising consumer interest in circular solutions. Companies that translate macro momentum into targeted GTM pilots in 2026 will be best positioned to scale in the second half of the decade.
- Regulatory acceleration: Emerging legislation in the United States — from statewide packaging mandates to single‑use restrictions — is already compressing runway for disposable alternatives and creating immediate demand avenues for reusable solutions. This dynamic reshapes procurement requirements for food service and retail buyers in the near term.
- Supply chain sensitivity: Raw material cost and availability are now first‑order considerations for product cost curves and margin planning. Volatility in beeswax pricing and diverse quality standards across sourcing geographies require active procurement strategies and scenario planning.
Data signals to watch — and act on
Several quantifiable indicators in our study have direct strategic implications for 2026 planning:
Worldwide Portable Flares Market
- Market scale and pace: The market’s progression from the mid‑hundreds of millions in 2020–2025 into the forecast period underscores sufficient consumer and commercial demand to justify investment in manufacturing scale, new SKUs, and channel expansion.
- Concentration and competitive structure: The sector remains relatively unconsolidated: the three‑firm and five‑firm concentration ratios indicate a market where incumbents coexist with numerous regional and niche players. That fragmentation creates M&A and partnership opportunities for companies aiming to build integrated platforms or secure distribution footholds.
- Raw material dynamics: Market intelligence shows transactional spikes and broad variance in beeswax pricing — for example, visible trades recorded at approximately USD 18.29/kg in late‑2025 contrasted with other reported average export price series. These differences reflect supply chain segmentation (spot trades vs. contract volumes) and imply that procurement sophistication — hedging, alternative raw materials, certification premiums — will directly influence cost competitiveness.
Regulatory context shaping demand in 2026
Policy measures are moving from aspirational goals toward enforceable standards. State‑level actions in the U.S. requiring recyclability/compostability of single‑use packaging and targeted bans on single‑use foodware are already influencing RFPs, buyer specifications, and retailer listings. For companies targeting commercial channels (food service, institutional procurement), compliance pathways and certification capabilities must be front‑and‑center in product development and sales messaging for 2026.
Worldwide Cherry Oil Market
Competitive landscape — practical insights
The market features a mixture of pioneering boutique brands, purpose‑led startups, and specialized manufacturers. Notable participants include established pioneers that have built brand equity around organic and certified supply chains, alongside large manufacturers offering OEM/ODM services with global compliance capabilities.
- Brands with strong storytelling and certification pedigree have an advantage in premium retail and direct‑to‑consumer channels. Their differentiation is rooted in material provenance, design, and lifestyle positioning.
- Manufacturer‑suppliers with scale and compliance credentials are winning institutional contracts and private‑label business, especially where price, minimums, and regulatory documentation matter.
- Across the value chain there is room for consolidation. Strategic buyers seeking rapid scale should evaluate bolt‑on acquisitions that bring manufacturing capacity, quality certifications, or distribution reach in key markets.
Profiles in our analysis include market pioneers known for organic, GOTS‑certified offerings; innovative zero‑waste brands building lifestyle portfolios; and major Asian manufacturers with LFGB/REACH/FDA capability that supply both branded and private‑label channels. The competitive map is a mosaic of brand equity, manufacturing competence, and channel intimacy.
What our full report delivers (practical, actionable content)
This research is designed as an operational toolkit for teams making 2026 commitments. Highlights include:
- Granular market sizing and a transparent forecasting model with scenario analysis and sensitivity testing to model material cost shocks and policy acceleration.
- Supply chain deep dives covering raw material markets, contract vs. spot dynamics, quality differentials, and a procurement playbook that outlines hedging, blended sourcing, and back‑to‑back contracts.
- Regulatory impact matrices mapping key jurisdictions to compliance actions and buyer requirements, enabling commercial teams to prioritize target accounts and tailor qualification documents.
- Channel profitability models by sales route (retail, DTC, food service, private label) with illustrative unit economics and SKU rationalization guidance.
- Competitive benchmarking of leading brands and manufacturers — capability heatmaps that compare certification, design IP, manufacturing scale, and channel penetration.
- M&A and partnership playbooks, including valuation frameworks, integration risk checklists, and a short list of acquisition archetypes that unlock rapid scale or capability.
- Primary research findings: buyer personas, procurement RFP excerpts, and 10 case studies showing how incumbents and challengers implemented rollouts with timeline and cost outcomes.
Strategic recommendations for 2026
- Prioritize procurement resilience: Establish multi‑tier supplier relationships for beeswax and alternative coatings, introduce minimum supply contracts, and budget for short‑term price stress in 2026 financial plans.
- Certify and document: Secure relevant material and process certifications (GOTS, FDA, LFGB, REACH where applicable) to unlock retail listings and institutional RFPs that will increasingly require documentary proof.
- Segment go‑to‑market by buyer need: Deploy distinct propositions for lifestyle retail (design, organic credentials), food service (durability, cost-per-use), and private label (price, lead times). Use pilots in high‑value accounts to refine pack formats and reuse messaging.
- Use policy as a growth lever: Map regulatory timelines to account prioritization — e.g., jurisdictions with imminent single‑use mandates should be targeted first for commercial partnerships and distribution investments.
- Evaluate strategic scale options: For mid‑sized players, assess M&A or joint ventures that add manufacturing capacity, compliance documentation, or access to institutional channels. For investors, target assets that combine brand premium with manufacturing control.
- Measure total cost of ownership for buyers: Create buyer tools that quantify cost‑per‑use and environmental benefits to dismantle price resistance in procurement processes.
Conclusion — the 2026 inflection point
The reusable food wrap market is entering a transitionary phase: robust headline growth, clear regulatory momentum, and supply‑side nuances that reward preparation and specialization. For companies willing to act in 2026 — by shoring up supply, certifying products, and aligning commercial models to buyer procurement cycles — the opportunity is to convert category growth into defensible, higher‑margin businesses.
Next steps — where to get the full intelligence
This article is a strategic preview designed to surface the most consequential decisions for 2026. Our complete Worldwide Reusable Food Wrap Market report provides the underlying datasets, regional and application splits, company revenue estimates, and downloadable financial models that support execution. To access the full report, detailed segment tables, and the proprietary scenario model, visit the PW Consulting report page or contact our market intelligence team.
For detailed analysis of this topic, please visit the official page: Worldwide Reusable Food Wrap Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting report: Worldwide Mosquito Repellent Water for Pregnant Women Market to expand at 7.5% CAGR through 2032
By pmarketresearch, 2026-08-12
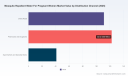
Worldwide Mosquito Repellent Water For Pregnant Women Market: Strategic Preview for 2026 Decisions
PW Consulting today releases an executive preview of our newest market research: the Worldwide Mosquito Repellent Water For Pregnant Women Market. This briefing distills the report’s strategic implications for executive teams making portfolio, R&D, channel, and M&A decisions in 2026. It highlights the macro trajectory, key competitive dynamics, regulatory contours, and the practical playbook included in the full report—while intentionally withholding the granular segmentation matrices and country-level opportunity maps that are part of the paid deliverable.
Worldwide Cloud Management Platform (CMP) Market
Macro trajectory: a resilient, mid‑single‑digit market with clear upside
The segment has demonstrated steady expansion through the first half of the decade, rising from a modest base in 2020 to a materially larger global market by 2025. Our base-year model (2025) values the market at approximately USD 275 million, with projections pointing to sustained growth into the forecast window. Under our central scenario, the market grows at a compound annual growth rate (CAGR) of roughly 7.5% through 2032, arriving at a markedly larger market by the end of the period.
Worldwide Anti Mould Paints Market
For strategy teams, these high‑level dynamics matter: the category is not a hyper‑scale mass market yet, but it is large enough and growing quickly enough to justify dedicated product lines, targeted regulatory investments, and channel experiments—particularly for firms that can credibly address safety and efficacy for pregnant consumers.
Worldwide Jowar Flour Market
Drivers and structural dynamics shaping 2026 strategy
- Health‑first consumer framing. Pregnant consumers and their care networks are increasingly informed and risk‑averse, favoring products that are supported by authoritative guidance. Public health agencies and professional organizations continue to emphasize EPA‑registered repellents as the primary option for disease prevention in pregnancy when applied as directed.
- Regulatory clarity reduces ambiguity. Continued guidance from major health authorities reinforces the safety profile of a defined set of active ingredients when used according to label directions (for example, DEET up to 30% and alternatives such as picaridin and IR3535). That regulatory clarity lowers the bar for market entry while increasing the importance of proper labeling and regulatory compliance.
- Product differentiation through formulation science. Leading products combine proven actives with skin‑compatibility additives—e.g., humectants and dermatologically friendly bases—to address concerns around sensitivity, hydration, and odor for pregnant women. This creates a defensible R&D pathway beyond simply changing active ingredients.
- Channel evolution and trust signals. Pharmacies, prenatal care channels, and regulated online specialty retailers are becoming primary discovery and purchase points due to their ability to convey health‑safety credentials. Digital education (content and live support) is an increasingly important adjunct to product labels.
- Supply chain and raw material considerations. Demand for certain actives and compatibility agents is heightening sourcing risks and supplier bargaining dynamics, making early supplier diversification and strategic inventory decisions more critical for 2026.
Competitive landscape: incumbents, challengers, and how they are positioning
The market’s concentration is moderate: our competitive analysis indicates that the top three firms account for roughly one‑third of global industry revenue, with a top five presence approaching half of the total—an environment that favors both scale and agility. Below we summarize the competitive archetypes and strategic behaviors that corporate leaders must weigh when crafting plans for 2026.
- Global CPG incumbents (scale + regulatory muscle). Firms such as SC Johnson (OFF! brand) leverage robust regulatory teams, wide manufacturing footprints, and established trade partnerships. Their strength is in rapid label‑compliant product rollouts and shelf presence within conventional retail—useful where risk‑averse consumers seek familiar brands with authoritative backing.
- Specialist outdoor/repellent brands (technical credibility). Companies like Sawyer and Repel (Spectrum Brands) focus on efficacy messaging, often emphasizing specific active ingredients with well‑documented performance. Their channels blend outdoor specialty retail with pharmacy placements to reach both expectant mothers and broader protective users.
- Niche, pregnancy‑focused innovators. Players such as PARA'KITO and certain regional manufacturers have carved a niche by marrying family‑oriented safety messaging with product formats and marketing targeted at pregnant buyers; they often push formulation innovations and softer ingredient portfolios while relying on regional or online distribution to scale.
- Regionally focused OEMs and formulators. Some manufacturers are optimizing products for local consumer preferences (hydration, scent, application method) and regulatory thresholds—this gives them agility but creates challenges in scaling globally without additional compliance investments.
For decision‑makers, the takeaways are straightforward: incumbents compete on trust and reach; specialists compete on technical claims and channel targeting; and challengers compete on niche safety or formulation narratives. Winning in 2026 will require a hybrid approach that combines authoritative evidence, accessible channels, and product comfort.
Product and formulation trends to prioritize in 2026
- Evidence‑backed actives with user‑centric adjuncts. Products pairing proven repellents (e.g., regulated options supported by safety reviews) with skin‑care additives such as hyaluronic acid or other humectants are gaining traction. This is a tangible product playbook for brands seeking both clinical credibility and consumer comfort.
- Labeling, claims, and advisory tools. Transparent, clinically framed labeling that references regulatory guidance—backed by accessible educational assets for prenatal providers—drives uptake. Brands that invest in clear advisory tools for pregnant users accelerate adoption.
- Format experimentation. Spray and roll‑on formats optimized for even coverage, low inhalation exposure, and ease of application for pregnant users are favored. Packaging innovations that communicate dosing and precautions simply are powerful trust builders.
- Digital health integration. Integration of helplines, chat, and digital dosing reminders embedded in e‑commerce experiences supports conversion and repeat purchase among pregnant cohorts.
Strategic imperatives for 2026 corporate decision‑makers
As companies set budgets and allocate resources for 2026, the following strategic imperatives should be considered. Each recommendation is linked to practical implications and near‑term actions that PW Consulting’s full report unpacks in operational detail.
- Prioritize regulatory and labeling investments. Secure EPA/region‑equivalent registration where feasible; invest in labeling that explicitly addresses pregnancy safety per authoritative guidance. Immediate action: allocate budget and project timelines for registrations and third‑party safety reviews.
- Develop differentiated formulation roadmaps. Create product roadmaps that pair validated actives with skin‑care adjuncts to address pregnant consumers’ sensitivity concerns. Immediate action: establish cross‑functional R&D sprints to test combinations that do not compromise repellent efficacy.
- Channel‑led go‑to‑market strategies. Prioritize pharmacy and prenatal‑care channels alongside high‑quality e‑commerce to capture both point‑of‑care purchase and pre‑purchase digital research behavior. Immediate action: pilot co‑promotions with prenatal clinics and targeted digital education campaigns.
- Hedge supply and build sourcing resilience. Identify single‑source dependencies for key actives and negotiate multi‑tier supplier agreements. Immediate action: conduct a supplier concentration risk assessment and model inventory buffers for 2026‑2027.
- Use acquisition and partnership selectively. Given moderate market concentration, acquisitions of niche formulators or partnerships with prenatal health platforms can accelerate market entry with manageable capital outlay. Immediate action: develop an M&A criteria matrix focused on regulatory dossiers, formulation IP, and channel access.
What PW Consulting’s full report delivers (practical, transaction‑grade tools)
The complete report is designed as a tactical playbook for B2C and B2B leaders. Key deliverables include:
- Proprietary market model and scenario forecasts (2026–2032) with sensitivity testing for disease‑outbreak shocks, regulatory changes, and channel shifts.
- Competitive benchmarking dashboards covering product portfolios, claims, pricing bands, and route‑to‑market strategies—presented for major competitors and regional leaders.
- Go‑to‑market playbooks for launching pregnancy‑targeted formulations across channel archetypes, including step‑by‑step marketing and regulatory timelines.
- R&D prioritization matrices and cost‑benefit analyses for formulation options (including clinical evidence investment recommendations and timelines for claim substantiation).
- Supply chain risk maps and mitigation strategies, including supplier scorecards and inventory posture scenarios aligned to 2026 purchasing cycles.
- M&A screening models tailored to this segment—quickly flagging targets that provide regulatory dossiers, differentiated formulations, or superior channel access.
We have intentionally withheld the detailed segmentation tables, country‑level opportunity maps, and full competitor revenue splits in this preview. Those granular insights, which form the core of decision‑grade intelligence for 2026 planning, are accessible in the full paid report and interactive data package.
Final assessment: why 2026 is a pivotal execution year
The convergence of clearer regulatory guidance, shifting prenatal consumer expectations, and favorable market growth dynamics makes 2026 a pivotal year for companies that want to convert strategic intent into tangible share gains. The market’s mid‑single‑digit CAGR and moderate concentration profile create a unique window where both established players and well‑capitalized challengers can achieve outsized returns from targeted investments in safety, formulation, and channel credibility.
For executive teams, the core decision is not whether to participate; it is how to allocate finite resources—between regulatory certification, formulation development, channel partnerships, and M&A—to build a credible, trust‑based franchise for pregnant consumers. Our full report supplies the playbooks, models, and competitor intelligence to convert those strategic choices into 2026 operational plans.
How to access the full intelligence
PW Consulting offers customized briefings and packaged intelligence subscriptions for executives and investment teams preparing 2026 budgets. To obtain the full Worldwide Mosquito Repellent Water For Pregnant Women Market report, including interactive datasets and competitor scorecards, please visit our research portal or contact our client services team for a tailored walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Mosquito Repellent Water For Pregnant Women Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ox Bezoars (Cow Bezoars) Market Reaches USD 1,288.6 Million in 2025, Set to Expand at a 9.0% CAGR Through 2032
By pmarketresearch, 2026-08-12
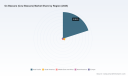
Worldwide Ox Bezoars (Cow Bezoars) Market: Strategic Imperatives for 2026 — PW Consulting Exclusive Preview
PW Consulting today releases an executive preview of our forthcoming Worldwide Ox Bezoars (Cow Bezoars) Market report. As the industry transitions from traditional supply chains toward biotechnological sourcing and tighter regulatory oversight, this preview outlines the strategic value the full report will deliver to boardrooms and investor committees preparing decisions in 2026.
Worldwide Mirrorless Cameras Market
Why this market matters in 2026
Ox bezoars occupy a unique intersection between centuries-old Traditional Chinese Medicine (TCM) practice and modern pharmaceutical interest. Over the last half-decade the global market has expanded materially. Using 2025 as our analytical base year, PW Consulting’s modeling shows sustained growth driven by demand diversification, product innovation, and supply-side evolution. Our base-to-forecast work projects a compound annual growth rate (CAGR) of approximately 9.0% across the 2026–2032 forecast window, with the industry more than doubling in total revenue over the longer term under our central case.
Worldwide 3D Design Software Market
For decision-makers in 2026, this dynamic presents a set of clear choices: pursue scale via upstream supply integration, invest in in-vitro and synthetic alternatives to address sustainability and traceability concerns, or target premiumization and clinical research partnerships that can unlock higher margin channels. Each option carries distinct operational, regulatory and capital implications — and our full report translates those implications into executable plans.
Worldwide Solid End Mills Market
Snapshot of market structure and concentration
The ox bezoar ecosystem is neither purely fragmented nor tightly monopolized. Market concentration metrics indicate a moderate level of aggregation at the top: the three largest participants account for a substantial portion of revenues, while the top five increase that share meaningfully. For strategists, this profile signals an industry where scale matters, but nimble entrants and differentiated producers still have room to shape niches.
Implication: incumbents can protect margins through scale and established routes-to-market, while challengers can win by addressing structural weaknesses — quality assurance, traceability, or scalable cultivated supply.
Regulatory and sustainability dynamics shaping 2026 strategy
- Regulatory recognition within TCM frameworks: Ox bezoars are classified as traditional Chinese medicine materials under national pharmacopeias, bringing a baseline requirement for authentication and quality-control protocols for pharmaceutical or medical use. Buyers and manufacturers must build compliance programs that meet these specific pharmacopoeial requirements.
- Western regulatory stance: Major regulatory agencies such as the FDA and EMA currently do not recognize ox bezoars as approved pharmaceuticals. In many markets they remain herbal or supplement ingredients without a standardized Western drug status. This restricts certain commercialization pathways but also creates an opportunity for firms investing in clinical substantiation to achieve first-mover regulatory advantage.
- Export and conservation constraints: Exports of cattle-derived materials face international conservation-related regulation, including coverage under multilateral agreements that aim to prevent overexploitation. Exporters, traders, and downstream processors must weave compliance into supply-chain design to avoid trade interruptions.
Collectively, these dynamics mean that 2026 strategic plans must integrate regulatory monitoring, traceability systems, and scenario-based compliance playbooks as operational fundamentals — not afterthoughts.
Key market drivers and risk vectors
- Demand-side diversification: Traditional medicinal use continues to underpin demand, but modern pharmaceuticals and laboratory research are emerging as higher-margin and higher-growth end markets. Strategic investors should map adjacent pharmaceutical opportunities that require clinical data and tighter quality controls.
- Supply-side innovation: In-vitro cultivation and biofabrication technologies are moving from pilot to commercial scale. These approaches promise to mitigate scarcity, reduce ecological pressure, and offer consistent quality — however, scale-up economics and regulatory acceptance remain gating factors.
- Traceability and authentication: Quality assurance technologies — from DNA barcoding to spectroscopy-driven fingerprinting — are rapidly becoming de facto requirements for premium buyers and exporters. Firms that deploy robust QA+traceability systems can command price premia and reduce transaction friction.
- Price and supply volatility: Traditional supply is subject to livestock cycles, regional export controls, and seasonal availability. Buyers should embed hedging strategies and diversified sourcing to protect margins.
- Reputational and conservation risk: Overharvesting concerns attract scrutiny from regulators, NGOs and consumers. Brands must proactively demonstrate sustainable sourcing or transition plans to avoid reputational damage.
What PW Consulting’s full report delivers (practical, decision-grade content)
Our full Worldwide Ox Bezoars Market report is designed for executives making capital allocation, M&A, product development, or market-entry decisions in 2026. It goes beyond forecast tables to deliver an operational playbook. Highlights include:
- Scenario-based revenue and margin models calibrated to 2026 planning horizons (base, upside, downside), with sensitivity drivers and stochastic risk overlays.
- Supply-chain risk matrix mapping geographic sourcing nodes, export control implications, and mitigation levers (vertical integration, diversification, inventory strategy).
- Go-to-market playbooks for three archetype entrants: incumbent producer, biotech cultivator, and specialty pharmaceutical partner — each with recommended timelines, required CAPEX, and go/no-go triggers.
- Regulatory roadmap and compliance checklist for major export/import jurisdictions, including authentication and quality standard templates aligned with pharmacopeial requirements.
- Commercial benchmarks for pricing tiers, contract structures, and premiumization levers — framed to help procurement teams negotiate durable supplier agreements.
- Technology assessment of cultivated and synthetic pathways, including TRL (technology readiness level), scale-up challenges, and partner ecosystems for manufacturing and IP licensing.
- M&A playbook and valuation heuristics tailored to this market’s concentration profile — how to size synergies, identify bolt-ons, and evaluate roll-up strategies in a moderately concentrated market.
- Executive dashboards and KPI sets — designed for monthly and quarterly board reporting to track progress against 2026 strategic initiatives.
Competitive implications and recommended 2026 moves
While we withhold specific segment-level disclosures in this preview, the structural insights point to a small set of high-impact actions that will separate winners from laggards in 2026:
- Invest in traceable, certified supply: Firms securing authenticated supply chains (including cultivated sources where feasible) will reduce regulatory friction and create defensible price positioning.
- Pursue selective clinical validation: For participants aiming at modern pharmaceutical channels, targeted clinical programs — even small, rigorous studies — can convert TCM demand into regulated pharmaceutical opportunity.
- Partner for scale: New entrants should consider strategic partnerships with established distributors or contract manufacturers to accelerate market access while deferring heavy CAPEX.
- Hedge resource risk: Procurement strategies that include inventory optimization, multi-source contracts, and alternative-material R&D will protect margins in the face of export controls or supply shocks.
- Prepare for premiumization: Product differentiation through certified sourcing, GMP-compliant processing, and clinical backing can create higher-margin product tiers that insulate against commodity price compression.
Strategic value to 2026 corporate planning
For corporate planners, the report’s most immediate value is actionable clarity. The market’s projected growth trajectory and concentration characteristics enable realistic capacity and capex planning; the regulatory overlays determine compliance-driven timelines; and the technology outlook clarifies R&D roadmaps. Combined, these elements let boards answer three priority 2026 questions with evidence-based confidence:
- Should we vertically integrate supply or source from certified partners?
- Where do we allocate R&D dollars between cultivated/synthetic pathways and clinical validation for higher-margin channels?
- Which M&A targets or strategic alliances offer the most accretive path to secure supply and distribution?
What this preview does — and does not — disclose
This preview is deliberately calibrated as a strategic teaser: we provide market-scale context, growth dynamics, and prescriptive frameworks to demonstrate the report’s value for 2026 decision-making. To preserve the integrity of our client-grade intelligence and to encourage direct engagement, we do not disclose detailed subsegment or region/application-level breakdowns in this release. Those granulated data, company profiles, and price curves are available in the full report.
Next steps — where to get the complete intelligence
PW Consulting’s full Worldwide Ox Bezoars (Cow Bezoars) Market report contains the granular segmentation, supplier and product-level benchmarks, and downloadable decision-support tools referenced above. For procurement teams, corporate strategists, private equity investors and regulatory managers preparing 2026 plans, the full report converts industry signals into executable programs.
Reach out to PW Consulting to request the detailed report package, including our scenario models and an executive briefing tailored to your organization’s strategic posture.
About PW Consulting
PW Consulting is a global strategy firm advising CEOs and boards across specialty natural products, pharmaceutical adjacent markets, and biofabrication sectors. Our advisory combines market forecasting, regulatory intelligence and transaction support to help clients convert emerging-market growth into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Ox Bezoars (Cow Bezoars) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smart Solar Urban Equipment Market to Expand at a 15.02% CAGR, Powering Global Urban Sustainability
By pmarketresearch, 2026-08-12
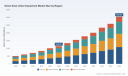
Worldwide Smart Solar Urban Equipment Market — Strategic Imperatives for 2026
PW Consulting’s new market study on Worldwide Smart Solar Urban Equipment distills seven years of historical observation (2020–2025) and a forward-looking forecast (2026–2032) into an actionable intelligence pack for executives, investors, city planners, and systems integrators preparing strategy in 2026. The market has matured from an early commercial phase into a scale-up opportunity: our base-year assessment shows industry revenue at USD 1,142.8 Million in 2025 and a near-term projection of USD 1,342.9 Million in 2026, with a 2026–2032 compound annual growth rate (CAGR) of 15.02% that takes the market to roughly USD 3,043.7 Million by 2032. That macro trajectory changes how boards frame capital allocation, partnership choices, and pilot-to-scale timelines in 2026 — and our report is designed to convert those high-level signals into executable decisions.
Worldwide Moving Software Market
Why the timing matters: macro signals shaping 2026 choices
-
Demand inflection. Historic growth through 2025 demonstrates clear momentum for smart solar furnishings, off-grid street lighting, kiosks and integrated waste/charging networks. The transition from one-off pilots to portfolio procurement is underway, meaning 2026 is the window when pilots must demonstrate repeatable unit economics if vendors expect pipeline acceleration.
Smart Network Managed Switches Market -
Unit-cost and supply drivers. Utility-scale PV installed cost benchmarks and module spot pricing continue to ripple into product cost models. Recent utility-scale averages (reported by LBNL) and module spot price differentials between global and U.S. markets highlight persistent cost arbitrage and local-content implications that buyers and manufacturers must model into 2026 procurement strategies.
Worldwide Source Code Management Software Market -
Policy and trade dynamics. Tariff episodes and rapid global PV additions — with concentration in a handful of manufacturing geographies — create procurement and risk-management priorities for manufacturers and municipal buyers. Targeted incentive programs at state and local levels provide near-term co-funding windows that can materially improve project IRRs for 2026 deployments.
-
Market structure. Measured concentration in this market remains low-to-moderate: the top three and top five supplier groups account for a modest share of total market revenue, leaving room for regional champions and niche platform players to scale rapidly through services, integration, and performance contracts in 2026.
What the report delivers — practical modules for operational strategy
-
Proprietary market-sizing and demand model: a transparent methodology with scenario outputs (conservative, base, upside) for 2026–2032 to help finance teams stress-test capex and OPEX assumptions.
-
Buyer and procurement playbooks: step-by-step RFQ templates, performance-based contract clauses, warranty and service-level schedules, and procurement evaluation rubrics tailored to municipal and commercial buyers.
-
Technology and product taxonomy: a practical decision matrix that maps solar urban equipment types to service bundles (lighting, charging, connectivity, waste management) and anticipated maintenance profiles.
-
TCO and pricing sensitivity tool: inputs reflect real-world component cost trends and regional pricing levers so CFOs can model CAPEX vs. OpEx trade-offs for 2026 buying cycles.
-
Vendor due-diligence pack: scorecards, reference-check templates, and integration risk checklists for shortlisting and piloting suppliers.
-
Commercialization playbooks: channel strategies, subscription/lighting-as-a-service (LaaS) models, and municipal partnership frameworks to accelerate revenue conversion.
-
Regulatory & incentive compendium: an up-to-date library of tariffs, grants, and local funding instruments that create immediate arbitrage opportunities for projects commencing in 2026.
-
Case studies and pilot blueprints: deconstructed deployments with measured KPIs on uptime, energy yield, and citizen engagement to reduce time-to-scale risk.
Competitive landscape — who to watch and how to position
The report profiles leading technology suppliers and integrators active in smart solar urban equipment. Key archetypes include platform-lean providers that combine IoT, connectivity and service contracts; high-efficacy off-grid lighting specialists; modular urban-furniture manufacturers; and smart waste and compaction system providers. Representative companies discussed in the report illustrate these archetypes and their go-to-market approaches — from firms emphasizing full-stack city deployments and subscription-based lighting to suppliers focused on high-performance, rapid-deploy systems for events and infrastructure.
-
Platform-and-services players are differentiating through integrated IoT, remote asset management and multi-service revenue streams (connectivity, environmental sensing, security). These suppliers are positioned to win long-term service contracts in municipalities seeking single-vendor responsibility.
-
Product-specialist vendors are competing on efficiency, reliability and ease of deployment: high-lumen LEDs, robust energy storage and designs supporting extended autonomy reduce O&M friction and appeal to departments of transportation and parks authorities where trenching and mains connections are cost-prohibitive.
-
Niche system suppliers — for example in solar-powered waste compactors — are gaining traction by addressing specific urban pain points and integrating telemetry that optimizes collection routes, creating defensible value-propositions for cities with constrained waste budgets.
Recent vendor activity underlines these dynamics: product catalog updates emphasizing deployability and event-grade performance; high-visibility installations approaching completion; and thought leadership publications shaping municipal procurement priorities. These developments provide clues about which competitors are moving towards platformization versus product specialization — a critical distinction when designing partnerships or M&A screens in 2026.
Key risk vectors for 2026 and recommended mitigations
-
Supply-cost volatility: module and component price differentials across markets can erode margins. Mitigation: adopt multi-sourcing, commit to forward purchase agreements, and explore localized assembly to capture incentive regimes and reduce tariff exposure.
-
Trade and regulatory shifts: tariffs and compliance regimes can change supplier economics rapidly. Mitigation: include contractual pass-through clauses and maintain inventory buffers for critical components.
-
Procurement inertia and integration risk: municipalities often require extended evaluation cycles and proof-of-concept outcomes. Mitigation: design 90–180 day pilots with predefined KPIs, performance-based payments, and standardized interface specifications for rapid replication.
-
Aftermarket and O&M surprises: field reliability will determine long-term TCO. Mitigation: instrument systems with remote monitoring from day one and price service-level agreements to align incentives on uptime.
How Boards and strategic teams should use this report in 2026
-
Investor diligence and portfolio allocation: use scenario outputs and vendor scorecards to size addressable markets and set realistic pace for Series A/B capex deployment.
-
OEM and integrator growth planning: adopt the go-to-market playbooks to pick initial verticals where payback is fastest, then scale via channel partnerships supported by our procurement templates.
-
City and municipal strategy: leverage the procurement and pilot blueprints to unlock local incentive co-funding windows and structure performance-based contracts that limit political and budget risk.
-
M&A and partnership screening: apply our consolidation scenarios and concentration metrics to identify attractive targets that fill capability or geographic gaps while keeping integration risk quantifiable.
Why PW Consulting’s study is different
This report couples a transparent, reproducible market model (historical 2020–2025 calibration and 2026–2032 scenario outputs) with hands-on procurement and commercialization tools. We combine vendor-level diligence, a curated incentive and regulatory tracker, and a practical TCO engine that embeds recent component-cost intelligence and trade exposures. Importantly, our approach is deliberately practitioner-focused: instead of publishing raw, uncontextualized split tables in this announcement, we present synthesized guidance and diagnostic tools in the full report that convert market-level trends into immediate operational steps for 2026.
Next steps and how to access the intelligence you need
Executives and procurement leads preparing 2026 strategies should treat this report as the playbook for converting market growth into repeatable revenue or reliable public services. To preserve competitive value for clients and purchasers, we have intentionally withheld the detailed segmentation tables from this press release — the full vendor scorecards, regional and application split matrices, and financial-model workbooks are included in the complete report and online portal.
Contact PW Consulting or visit our report landing page to request the executive summary, schedule a briefing, or license the dataset and scenario tools. For teams with immediate pilot or procurement decisions in 2026, our analysts are available for rapid workshops to map the report’s tools to your specific operating environment and to design a 90–180 day evidence plan that de-risks scale-up.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Solar Urban Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Child‑Resistant Blister Lidding Film Market Poised for Growth at a 6.94% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Child-Resistant Blister Lidding Film Market — Strategic Preview for 2026 Decisions
PW Consulting’s latest market study on the Worldwide Child-Resistant Blister Lidding Film Market provides a forward-looking, operationally focused briefing designed to inform boardroom decisions in 2026. Anchored on a base year of 2025, the study synthesizes five years of historical performance (2020–2025) with a detailed forecast through 2032. The market grew from a subdued base in 2020 to an estimated USD 975.0 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.94% through the forecast horizon, reaching roughly USD 1,559.1 million by 2032. This briefing distils the report’s most consequential insights — enough to act on now — while reserving the full segmentation tables and supplier scorecards for the full report.
Vessel Diesel Particulate Filters Market
Why this report matters for 2026 strategic planning
-
Timing-sensitive capital allocation: With mid-single-digit CAGR and accelerating demand pockets, decisions on capacity expansion, conversion investments, and acquisition targets in 2026 will determine market share capture through the next cycle.
Cell Identification and Characterization Testing Services Market -
Regulatory risk and compliance as business risk: Child-resistant lidding is governed by high-stakes protocols whose compliance timelines and testing regimes directly affect product time-to-market and commercialization costs.
Medical Soft Skin Adhesive Market -
Commercial differentiation: Innovations in recyclability, senior-friendly ergonomics, and barrier performance are converging with customer and regulator expectations. Firms that translate these features into validated value propositions will command price premia.
-
Procurement and sourcing resilience: Feedstock volatility and logistics tightness will be pivotal to margin preservation in 2026. The report quantifies exposure by feedstock and proposes hedging and supplier-diversification playbooks.
Key data-driven takeaways
-
Structured growth with pockets of acceleration: The market’s projected growth to about USD 1.56 billion by 2032 (CAGR ~6.94%) is neither uniform nor random — it reflects structural drivers such as an aging population mix, steady pharmaceutical demand (Rx and OTC), and rising regulatory enforcement globally.
-
Regulation is a material growth lever and constraint: Child-resistant packaging must meet protocol thresholds such as the U.S. CPSC Protocol 1700.20 (designed to limit a child’s ability to access contents) and established adult-use durability standards like EN 14375, which specifies rigorous adult usability criteria. These standards raise the technical bar for product design, testing, and validation cycles.
-
Raw material dynamics matter more than ever: Primary substrates remain aluminum foil laminated with PET or PVC at typical foil thicknesses of roughly 9–20 microns. Recent commodity data point to aluminum trading near levels that materially alter unit economics (reference: aluminum price data as reported in early-2026 commodity summaries). Procurement strategy, contract tenor, and opportunistic hedging will be decisive in 2026.
-
Policy and taxation introduce asymmetric cost pressure: Macro policies such as the UK Plastic Packaging Tax (noted at c. £217.85 per tonne for packaging with limited recycled content) and EU mandates for recycled content in plastics through 2030 are already changing supplier product roadmaps and capital plans.
-
Margin bifurcation driven by sustainability and function: Products that successfully combine high-barrier performance with mono-material recyclability or meaningful recycled content are beginning to capture higher commercial traction. Conversely, legacy multi-layer laminates without clear end-of-life pathways are increasingly exposed to regulatory and commercial discounting.
Competitive landscape — what incumbents and challengers are doing
The competitive field comprises global converters, specialty film houses, and regional specialists. While the market is not a pure commodity, it exhibits moderate concentration with a handful of established suppliers exerting outsized influence on standards, certification pathways, and distribution channels.
-
Amcor plc (Melbourne, Australia) — A large integrated supplier leveraging global scale to commercialize recyclable child-resistant lidding films. Recent product launches indicate a strategic focus on sustainable formulations that meet pharmaceutical barrier requirements while reducing lifecycle impact.
-
Constantia Flexibles (Vienna, Austria) — Known for high-barrier aluminum lidding foils and multi-layer films, actively showcasing innovations at key trade events and maintaining deep relationships with pharma packagers seeking tested, high-integrity solutions.
-
Tekni-Plex (Wayne, PA, USA) — Focuses on thermoformable lidding and senior-friendly peel mechanics; certification updates underscore attention to regulatory compliance and user-centric design tradeoffs.
-
Winpak Ltd. (Winnipeg, Canada) — Emphasizes high puncture resistance and medical-grade performance, which appeals to markets with heavy sterility and handling demands.
-
Alpine Packaging, ProAmpac, Hood Packaging, Sonoco Products Company — These and other regional players specialize in customization, speed-to-market, and niche features such as peel-reseal mechanisms, recyclable laminates, and tailored barrier properties.
Collectively, leading suppliers are differentiating along three vectors: (1) regulatory-certified child-resistance and adult-usability balance, (2) sustainability credentials and recyclability, and (3) service and supply-chain reliability. The most successful players in 2026 will be those that can simultaneously demonstrate certified performance and an economically viable path to lower environmental impact.
Report content — practical, actionable modules
The full PW Consulting report is structured for execution. Key, plug-and-play deliverables included are:
-
Market forecast engine with scenario overlays (base, regulatory-accelerated, and substitution-accelerated scenarios) to stress-test investments and commercial plans.
-
Regulatory compliance matrix that maps global standards (including CPSC and EN frameworks), test pass/fail implications, certification timelines, and recommended pre-submission test plans to accelerate approvals.
-
Supplier scorecards and plant-capacity mapping derived from primary interviews — enabling rapid shortlisting for procurement, trial runs, and dual-sourcing strategies.
-
Raw-material exposure dashboard that models aluminum price sensitivity, feedstock substitution pathways (e.g., PET monomaterials), and tax/policy impacts such as plastic taxes and recycled-content mandates.
-
Commercial playbooks for segmentation, pricing sensitivity analyses, and channel strategies for pharma OEMs, contract packagers, and OTC brands.
-
M&A and JV playbook with target typologies, valuation yardsticks, and integration checklists focused on capability, regulatory foothold, and geographic access.
-
Operational KPIs and pilot templates to de-risk time-to-market for new lid formulations, including sample test protocols aligned with major regulatory methods.
2026 roadmap — operational priorities for executives
-
Prioritize validated sustainable formats: Begin 2026 with a portfolio triage that isolates SKUs vulnerable to near-term policy headwinds (e.g., single-use multi-layer laminates without clear recycling pathways) and accelerate pilots for recyclable or recycled-content alternatives.
-
Lock in raw-material strategy: Negotiate multi-year arrangements or financial hedges for aluminum and critical film substrates; consider alternate substrate trials where barrier and test compliance permit.
-
Invest in testing and certification front-loading: Secure lab capacity and pre-certification runs to compress approval lead times. Passing recognized protocols (CPSC, EN) on first submission yields meaningful commercial advantage.
-
Design for the end-user: Balance child-resistance with senior usability — products that fail adult-usability criteria risk commercial rejection even if technically child-resistant.
-
Operationalize supplier risk management: Establish dual-sourcing for critical SKUs, map logistics pinch-points, and maintain buffer strategies calibrated to product-criticality.
-
Scan for inorganic moves: 2026 is likely to see opportunistic M&A and strategic partnerships focused on proprietary chemistries, recyclable laminate technologies, and regional capacity expansion — prepare acquisition filters and integration plans now.
How PW Consulting supports execution
PW Consulting delivers not just a market snapshot but a practitioner’s toolkit: bespoke scenario modeling, due-diligence support for transactions, sourcing optimization, and tailored regulatory roadmaps. Our engagement teams combine packaging engineers, regulatory specialists, and commercial strategists who translate the report’s insights into executable plans aligned with 2026 budgets and KPIs.
Next steps
This briefing offers a strategic overlay designed to accelerate 2026 decision-making. For access to the full dataset, including granular segmentation, supplier scorecards, plant-level capacity maps, and the scenario-ready forecast engine, consult the full Worldwide Child-Resistant Blister Lidding Film Market report. PW Consulting can provide an executive briefing and an implementation workshop to convert insights into a one-year operational plan that aligns with your capital and market priorities.
Contact PW Consulting to schedule a briefing and gain full access to the models and templates that will make 2026 a year of measurable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Child Resistant Blister Lidding Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Sauna Steam Generator Market Tops USD 707.06 Million in 2025, Poised for 6.61% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Sauna Steam Generator Market — 2026 Strategic Preview
Executive summary
PW Consulting’s latest market study on the Worldwide Sauna Steam Generator market positions 2026 as an inflection year for manufacturers, integrators, and strategic investors. The market has expanded steadily from the early 2020s and—driven by renewed consumer interest in wellness, tightening energy rules in major markets, and rising commercial installations—our base-case forecast sees continued growth at a compound annual growth rate (CAGR) of 6.61% through 2032. Measured in USD million, the global market crossed the mid‑hundreds mark in the middle of the decade and continues to scale into the latter half of the forecast period.
MRI Radiofrequency Coils Market
Why this report matters for 2026 decisions
- Timing: 2026 is both a compliance and investment hinge point—regulatory efficiency thresholds, certification windows, and new product cycles converge, creating concentrated windows for re-tooling and market positioning.
- Policy-driven demand: Energy efficiency mandates in major trading blocs accelerate replacement cycles in commercial installations and alter product specifications for new builds.
- Commercial tailwinds: Growth in wellness tourism and hospitality refurbishment programs drives larger, higher‑specification projects that change procurement dynamics and aftermarket service opportunities.
- Strategic value: The report converts top-line growth into actionable choices—product roadmaps, go-to-market timing, supply chain mitigation, and M&A prioritization—targeted to 2026 execution calendars.
Market snapshot (what the headline numbers tell you)
From a macro standpoint, the sauna steam generator sector shows resilient, mid-single-digit growth underpinned by both residential upgrades and commercial demand. Our historical series demonstrates a consistent upward trajectory through 2025, and our scenario framework projects sustained expansion underpinned by a 6.61% CAGR for the 2026–2032 forecast window. This growth profile supports a strategic posture that balances near‑term efficiency upgrades with medium‑term capacity planning and service expansion.
Industrial Flash Memory Chip Market
Key market dynamics shaping 2026 strategy
- Regulatory pressure and product spec redefinition. The recent Energy Efficiency Directive in major markets requires commercial steam generators to meet elevated efficiency thresholds by 2026. For suppliers, this alters design priorities and provides a first‑mover advantage to manufacturers who can demonstrate compliant, field‑tested units.
- Raw material and cost inflation. Stainless steel costs—central to boiler construction—have risen materially, with industry indices reporting an 8% year‑over‑year increase and price points that materially pressure BOM (bill of materials) assumptions. Manufacturers without hedging strategies or process redesigns face margin compression.
- Service and labor scarcity. Certified installation technicians are commanding premium rates in advanced markets, and average installation labor costs have increased meaningfully. This raises the value of installer networks, service contracts, and product designs that lower on‑site labor time.
- Commercial demand uplift. Wellness tourism and spa development accelerated through 2025, creating larger, more sophisticated projects that demand higher‑capacity systems and integrated control ecosystems.
- Certification and safety. Regulatory and buyer expectations for safety certification—such as standards attesting to overheating protections—are table stakes for commercial procurement. Manufacturers must demonstrate compliance early in the sales cycle to avoid exclusion from RFPs.
Competitive landscape — strategic takeaways
The market is moderately concentrated, with the top tier of established brands accounting for a significant portion of industry revenues. Market concentration metrics indicate that the three largest suppliers control a meaningful share of the market, while the top five consolidate a clear majority—an important signal for potential acquirers and channel partners about competitive density and pricing power.
Worldwide Product Compliance Software Market
Leading firms continue to differentiate along several vectors: product integration with broader sauna systems, digital controls and connectivity, energy efficiency, and commercial service capabilities. Below we summarize the strategic profiles of notable incumbents covered in the report:
- Steamist (Long Island City, NY) — Known for a broad capacity range that spans residential to high‑capacity commercial units. Strengths include an established distribution network and a product portfolio that supports scale projects.
- Mr. Steam (Hauppauge, NY) — Positions itself on the premium end with app‑enabled control ecosystems and finished interior solutions, leveraging design and software as differentiation.
- Amerec (Woodinville, WA) — Competes on reliability and a balanced product ladder; recent investments emphasize dependable performance for mid‑sized commercial installations.
- TyloHelo (Hillerstorp, Sweden) — A strong European systems integrator that focuses on end‑to‑end sauna and steam solutions, often favored by institutional buyers for turnkey projects.
- Harvia (Muurame, Finland) — Deep ties to commercial installers and export markets; recent catalog updates emphasize energy‑efficient models optimized for global deployment.
- KLAFS GmbH (Schwäbisch Gmünd, Germany) — Specialist in wellness‑area systems for hotels and spas with an emphasis on European compliance standards and bespoke installations.
- Saunacore (Richmond Hill, ON) — Niche player in stainless‑steel commercial boilers, winning projects that demand durable, modular build approaches.
Recent competitive moves you need on your radar
- Mr. Steam launched an enhanced Bluetooth‑enabled product line at a major technology show in early 2025—an indicator that digital features continue to be a purchase differentiator for premium buyers.
- TyloHelo’s product showcases at industry exhibitions in late 2024 suggest accelerating technology demo cycles and increased buyer willingness to evaluate next‑generation equipment in person.
- Harvia’s catalog refresh emphasized energy‑efficient variants tailored to export markets—an explicit response to regulatory tightening and a likely driver of exportable product design standards.
What the PW Consulting report contains — practical, operational intelligence
This study combines quantitative forecasts, qualitative intelligence, and actionable playbooks designed to be used directly by product, supply chain, and corporate strategy teams. Key deliverables include:
- Comprehensive market sizing and a multi‑scenario forecast through 2032, including sensitivity tests for regulatory and raw‑material shocks.
- Competitive scorecards that benchmark product portfolios, distribution reach, and after‑sales capabilities for the leading vendors.
- Unit‑level cost modelling templates and BOM sensitivity analyses that isolate the impact of steel price swings, currency movements, and labor cost inflation.
- Regulatory tracker and compliance impact matrix that maps new efficiency rules and certification requirements to product design levers and time‑to‑market implications.
- Commercial playbooks for OEMs and channel partners covering pricing tactics, warranty design, installation‑economy product features, and service subscription models.
- M&A heatmaps and integration checklists aimed at identifying targets by capability (e.g., control software, modular boilers, regional installers) and estimating synergies.
Actionable strategic guidance for 2026 (where to prioritize resources)
- Product engineering — Prioritize energy‑efficiency retrofits and modular designs that reduce on‑site labor. Certification‑forward design shortens bid cycles for commercial projects.
- Supply chain & procurement — Hedge critical raw materials and diversify steel suppliers; invest in design substitutions that lower stainless steel intensity without compromising longevity.
- Commercial go‑to‑market — Build integrated offerings for wellness tourism operators and hotel groups that combine equipment, controls, and preventative maintenance into a single contract.
- Service & labor strategy — Scale certified installer networks and remote diagnostics to reduce dependency on scarce high‑cost technicians, and monetize preventive maintenance.
- M&A & partnerships — Target bolt‑on acquisitions that fill gaps in controls software, testing/certification capabilities, or regional service footprints to capture near‑term project pipelines.
Risk factors and mitigations
- Commodity shocks: Steel price volatility will stress margins—mitigate via supplier contracts and design SOR (structures of reduction) to lower steel usage.
- Regulatory misalignment: Non‑compliant products risk exclusion from tenders—maintain a regulatory roadmap and accelerate compliance testing for key markets.
- Channel disruption: New entrants offering integrated wellness experiences could disintermediate traditional OEMs—respond with bundled service models and dealer incentives.
FAQ — quick answers to questions clients ask us
- What certifications matter most? Safety and overheating protection standards are mandatory in several markets; aligning product development timelines with those certification windows is essential for 2026 commercial eligibility.
- How material is labor cost to project economics? In high‑cost regions, certified installer shortages are already adding a premium to total installed cost; products designed for rapid, low‑skill installation materially improve competitiveness.
- Is consolidation likely? Given moderate concentration metrics, we expect continued horizontal consolidation—particularly acquisitions that offer control software or service networks to broaden recurring revenue.
Next steps — how to use this insight
PW Consulting’s report is designed as an operational tool for 2026 planning cycles: engineering roadmaps, procurement negotiations, budget allocations, and M&A diligence. This executive preview highlights the signals you need to interpret; the full report contains the granular segmentation, supplier financials, and project‑level case studies required to convert insight into executable plans.
To access the detailed segmentation, vendor benchmarking tables, and the downloadable cost modelling templates that underpin our recommendations, please visit the report landing page and secure your copy. PW Consulting clients may also schedule a strategy session to translate these findings into a 90‑day implementation plan tailored to their organization.
For detailed analysis of this topic, please visit the official page: Worldwide Sauna Steam Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Concrete Densification Polishing Material Market Poised for 6.15% CAGR (2026–2032)
By pmarketresearch, 2026-08-12
Worldwide Concrete Densification Polishing Material Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study on Worldwide Concrete Densification Polishing Materials is designed as a decision-grade playbook for CFOs, procurement leads, product managers, and corporate development teams preparing strategies for 2026 and beyond. Our analysis shows the market moving from an estimated USD 985.4 Million in 2025 to roughly USD 1,099.2 Million in 2026, and projecting to USD 1,496.4 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.15% across the 2026–2032 forecast window. These headline numbers mask important structural dynamics—supply-chain pressure, product-technology divergence, and sustainability-driven commercialisation—that will determine winners and losers in the coming 18–36 months.
Worldwide Ligand Binding Assay Market
What the report delivers — practical, transaction-ready intelligence
-
Actionable market model: transparent bottom-up sizing and top-down sanity checks for 2020–2025 (historical) and a seven-year forecast through 2032, with scenario runs for low-, base-, and high-growth pathways.
Worldwide ServiceNow Store Apps Market -
Commercial segmentation framework: a decision-oriented taxonomy by product technology, end-use application, and region—structured to inform product roadmap, pricing, and channel decisions. (Note: detailed segment tables and numeric splits are available exclusively in the full report.)
Worldwide Silicon Friction Resistant Bronze Alloys Market -
Supply-chain and raw-material playbook: a granular view of feedstock dependencies, cost drivers, and supplier concentration; includes a procurement risk matrix and hedging options tailored for densifier chemistries.
-
Sustainability & regulatory mapping: audit of certification pathways (EPDs, LEED v5, embodied carbon metrics), plus a blueprint for converting product environmental data into sales advantage on commercial and institutional projects.
-
Competitive intelligence dossier: curated profiles of incumbent manufacturers, specialty formulators, and equipment-integrators, with capability maps, recent strategic moves, and M&A / partnership candidate shortlists.
-
Go-to-market playbooks: segmented GTM templates for contractors, distributors, and specifiers; margin and pricing sensitivity models; and a field-service staffing model for roll-out of premium densifier systems.
Why this matters to 2026 corporate strategy
Three dynamics converge to make 2026 a pivotal year for the densification / polishing materials industry:
-
Commercial expansion: steady market growth implies attractive top-line opportunities for specialised formulators and distributors, but growth is uneven across applications and geographies—making targeted market entry and prioritisation essential.
-
Raw-material volatility: production costs for silicate-based systems are tightly coupled to soda ash, silica feedstocks, and energy inputs. Historical commodity and energy shocks have already translated into meaningful cost inflation for densifier precursors; operators without a procurement hedging strategy are exposed to margin compression.
-
Sustainability as a specification gatekeeper: project owners and architects increasingly require Environmental Product Declarations (EPDs) and lifecycle metrics to qualify materials for low-carbon flooring credits. Early movers with validated EPDs and transparent GWP footprints are already gaining specification precedence on major commercial and institutional projects.
Competitive landscape — concentrated yet open to disruption
The densifier market is characterised by a mix of established chemical companies, specialised formulators and regional suppliers. Measured concentration is modest: top-three and top-five market concentration ratios underscore a market where incumbency matters, but meaningful share gains remain feasible through technology or distribution advantages.
-
Curecrete Distribution, Inc. (United States) — longstanding originator with legacy brands and system-level solutions for high-performance polishing.
-
W. R. Meadows, Inc. (United States) — integrated commercial systems combining lithium-silicate densifiers with floor-finishing platforms aimed at industrial and institutional customers.
-
Sika AG (Switzerland) — global reach and multi-chemistry product lines that support both architectural and industrial flooring segments.
-
The Euclid Chemical Company, LATICRETE, PROSOCO, Ecolab and several specialist suppliers (United States and Europe) — each offering distinct formulation advantages, distribution footprints, or specification support for polished concrete systems.
-
Innovators and alternative-technology entrants — Adhesives Technology (Convergent) with silica-free spray-on densifiers and new colloidal silica formulations—are changing the innovation frontier and creating new points of differentiation for project teams.
For corporate development teams, the implication is clear: the market is neither monopolised nor commoditised. Success in 2026 will come from combining product credibility (including EPDs and field performance data) with distribution scale or targeted partnerships in priority end markets.
Raw materials, margin mechanics and scenario planning
Silicate feeds and colloidal silica remain the dominant chemistry families for densification technologies. Production economics are exposed to a small set of upstream drivers—soda ash, silica sand, sulfuric acid, and energy. Historical periods of supply constraint and higher energy pricing materially lifted producer costs, and our modelling shows that a recurrence of such dynamics could compress EBITDA margins by mid-single digits for manufacturers without cost recovery mechanisms.
Key planning recommendations embedded in the report include:
-
Procurement strategies that blend spot purchases with contracted supply and regional sourcing diversification.
-
Product substitution pathways—how and when to pivot from traditional sodium silicate chemistries toward colloidal silica or hybrid formulations to manage exposure to single-commodity swings.
-
Pricing playbooks that convert raw-material pass-throughs into customer-facing value propositions, including delivery reliability and specification-risk mitigation.
Sustainability & regulatory developments — a commercial imperative
Environmental Product Declarations and lifecycle metrics have moved from marketing differentiator to procurement prerequisite in major commercial and institutional builds. Notably, recent supplier actions to publish validated EPDs for densifiers signal a turning point: manufacturers who present independently verified environmental metrics will find enhanced access to large-scale, sustainability-focused projects. Our report maps the certification pathways, quantifies likely specification uplift for certified products, and provides a template to fast-track EPD generation within six to nine months.
PROSOCO’s publication of EPDs for multiple densifiers in early 2026 is a concrete example of this trend—firms that follow quickly will be better positioned when owners and designers codify low-GWP flooring in specifications.
Deal and partnership playbook — where to look in 2026
Strategic options that the report evaluates and ranks by expected ROI include:
-
Bolt-on acquisitions to acquire formulation IP (colloidal silica, silica-free chemistries) and EPD-ready product lines.
-
Distribution partnerships or minority investments to secure channel access in high-growth geographies and end-use verticals.
-
Co-development agreements with equipment manufacturers (polishing systems) to create vertically integrated solution offerings that capture higher lifetime value from contractors and specifiers.
-
Licensing and OEM arrangements to accelerate product roll-out without the fixed-cost burden of greenfield manufacturing.
90 / 180 / 365-day roadmap for executives
-
0–90 days: Conduct a procurement vulnerability assessment; prioritize product SKUs for EPD development; initiate targeted conversations with top distributors and specifier networks.
-
90–180 days: Execute pilot EPDs for flagship products; lock in medium-term supply contracts for critical feedstocks; run margin-sensitivity scenarios and adjust pricing strategies.
-
180–365 days: Launch certified-product marketing to sustainability-minded specifiers; evaluate two acquisition or partnership targets aligned to formulation or distribution gaps; roll out contractor training and warranty programs for premium systems.
How PW Consulting’s analysis de-risks your 2026 plan
The report combines transparent, auditable market modeling with proprietary supplier interviews and competitive due diligence to create a playbook that is both strategic and tactical. It isolates four value-creation levers for 2026: product-certification leadership, feedstock-cost management, targeted distribution scale, and differentiated system offerings (chemistry + equipment + service). Each lever is supported by measurable KPIs and implementation checklists to accelerate time-to-impact.
Next steps — access the full intelligence
This briefing intentionally emphasizes the strategic implications while withholding the granular segment tables, region/application splits, and deal-level financials that corporate teams rely on for transactions. PW Consulting’s full report contains the detailed segment numbers, comprehensive supplier scorecards, scenario-based valuation models, and executable M&A shortlists that underpin the recommendations summarized above. For teams preparing budgets, procurement programs, product roadmaps, or M&A activity in 2026, the full dataset and annexes are essential.
Contact PW Consulting to obtain the complete Worldwide Concrete Densification Polishing Material Market report and the accompanying Excel model to run custom scenarios that reflect your organisation’s cost structure, distribution footprint, and strategic ambitions.
For detailed analysis of this topic, please visit the official page: Worldwide Concrete Densification Polishing Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Consumer Electronic Biometrics Market to Surge at 15.7% CAGR, Transforming Smartphones and Wearables
By pmarketresearch, 2026-08-12
Worldwide Consumer Electronic Biometrics Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting's Senior Strategic Consultant and Chief Industry Analyst, I am pleased to present an executive preview of our latest market intelligence: the Worldwide Consumer Electronic Biometrics Market report (base year 2025, forecast 2026–2032). This briefing is written as a strategic “trailer” — it surfaces the report’s most actionable insights and the macro drivers that will determine winners and losers in 2026, while intentionally withholding granular segment datapoints to direct executives and deal teams to the full report for competitive and commercial execution details.
Surface Drilling Rigs Market
Executive snapshot: Why 2026 is a pivotal year
Biometric authentication in consumer electronics is moving from convenience to a core security and UX differentiator. Our top-line projection shows the market expanding from USD 27,452.12 Million in 2025 to USD 76,218.45 Million by 2032, with a compound annual growth rate (CAGR) of 15.7% across the 2026–2032 forecast horizon. Market concentration is meaningful but not prohibitive: the leading three vendors account for roughly 42% of industry revenue, while the five largest capture about 58% — a structure that sustains competition and creates M&A and partnership arbitrage opportunities for fast-moving challengers.
Single Port Surgical Microscope Beam Splitter Market
What this report delivers — practical, boardroom-ready intelligence
- Scenario-grade market sizing and forecasts validated against supply-side unit economics and demand proxies, built to inform budgeting and investment cycles for 2026–2028.
- Actionable go-to-market playbooks for hardware vendors, chipset integrators, OEMs and platform providers — including partnership archetypes and priority customer segments.
- Strategic supplier scorecards and an IP/technology risk map that correlate sensor modalities, integration complexity, and long-term upgrade pathways for consumer devices.
- Regulatory and geopolitical heatmaps that quantify operational risk vectors tied to export controls, foundry concentration and biometric data governance.
- Commercial due diligence packs for M&A and JV activity: valuation implications, synergies, and five‑year integration planning templates.
- Product and roadmap recommendations (short, medium, long) with engineering trade-off matrices — enabling product owners to decide which biometric modalities to prioritize under constrained BOM and silicon availability.
Core market dynamics shaping 2026 strategy
- Demand acceleration driven by multi-device ecosystems: Biometric modules are no longer isolated features in smartphones — they are becoming consistent authentication layers across laptops, wearables, payment instruments and smart-home endpoints.
- Technology convergence: Optical, ultrasonic, and contactless 3D modalities are advancing in parallel. Software and sensor fusion are emerging as the primary battleground for user experience and spoof-resilience claims.
- Supply-side concentration and geopolitical risk: Fingerprint sensor IC and module production is tied to wafer foundry capacity concentrated in East Asia. Recent export-control regimes for advanced computing components have direct compliance implications for biometric processing chains and vendor sourcing strategies.
- Regulatory momentum around biometric data and use-cases: Industry-led standardization (for example, initiatives to standardize biometric performance in payment cards) is intersecting with national export-control frameworks and privacy law developments, creating both barriers and enablers for product roll-outs.
- Large installed base effect: Hardware adoption momentum remains robust — over 1.5 billion smartphones shipped in 2024 incorporated fingerprint sensors — which sustains component demand even as higher-end modalities scale.
Competitive landscape — strategic takeaways
The industry map includes vertically integrated platform leaders, semiconductor-focused suppliers, pure-play sensor specialists, and system integrators. Below are strategic observations on the most influential players and what their positions mean for competitors, suppliers, and enterprise customers in 2026.
Thin Wafer Processing and Dicing Equipment Market
- Apple Inc. — As an integrator that controls hardware, OS, and secure enclave architecture, Apple sets the premium benchmark for UX and privacy-focused messaging. Their model underscores the value of owning both silicon and secure software stacks; for challengers this raises the bar for differentiation through superior cross-device integration or open ecosystem advantages.
- Samsung Electronics — Samsung demonstrates how device OEMs can combine in-display ultrasonic/optical sensors with platform-level biometric workflows. The company’s scale and supply-chain control highlight the strategic advantage of aligning sensor sourcing with device roadmaps to capture margin and time-to-market.
- Qualcomm Technologies — Qualcomm’s role as a chipset-level integrator of biometric subsystems illustrates the platform play: by embedding biometric primitives into SoCs, chipset vendors can accelerate adoption among Android OEMs. For buyers, this centralization simplifies integration but shifts leverage toward the chipset vendor.
- Goodix, Synaptics, Fingerprints, Egis, Fingerprint Cards (Fingerprints) — These specialist sensor suppliers continue to push sensor innovation, power efficiency and cost optimization. Their success will hinge on strategic partnerships with foundries and on diversifying into new device categories beyond smartphones.
- IDEX Biometrics — By focusing on thin‑film and card-grade implementations, IDEX positions itself at the intersection of payment certification initiatives and wearables, an attractive niche as biometric-on-card standards evolve.
- IDEMIA, NEC, Suprema — These system-level biometric solution providers bring algorithmic strength and enterprise productization experience. Their capabilities are particularly relevant to OEMs that need turn‑key authentication stacks or compliance-ready solutions for regulated markets.
Recent market-moving events and what they imply for 2026
- NEC’s recognition as a leader in biometric innovation signals continued premium demand for high-accuracy algorithms and enterprise-grade verification that can be adapted into consumer product lines.
- The announced acquisition moves in the sector — exemplified by a recent large-scale M&A involving a biometric portfolio — indicate consolidation dynamics that can accelerate standardization, scale cost synergies, and reshape supplier bargaining power.
- Innovations such as metalens-based contactless fingerprint modules and localized indigenously developed sensors in important regional markets are reminders that hardware innovation and regional capability-building will both be critical competitive levers.
Risk matrix — near-term (12–24 months) vs medium-term (24–48 months)
- Near-term: Supply-chain disruptions tied to wafer foundry concentration and export-control compliance represent the most tangible operational risk for 2026 product launches.
- Medium-term: Regulatory and standards evolution (including biometric-on-card performance criteria) and consumer privacy frameworks will reshape product validation requirements and certification timelines, impacting time-to-revenue for new form factors.
- Persistent: Competitive pressure to reduce BOM costs while improving spoof resilience will sustain merger and partnership activity among sensor specialists, chipset providers and system integrators.
Strategic imperatives for different players in 2026
- Device OEMs: Prioritize modular architectures that enable multiple biometric modalities to be field-upgraded in software; secure supply agreements with multiple qualified sensor sources; invest selectively in proprietary AI-driven anti-spoofing.
- Sensor and IC suppliers: Focus on cost-down roadmaps, differentiate through software stacks and developer ecosystems, and pursue strategic alliances with regional foundries to mitigate geopolitical supply risk.
- Chipset and platform vendors: Embed biometric primitives and privacy-preserving compute capabilities into SoC roadmaps; offer robust developer APIs and certification tooling to accelerate OEM integration.
- Payment and card providers: Engage early with standardization bodies and prioritize certification readiness as biometric-on-card initiatives gain regulatory traction.
- Investors and M&A teams: Target assets that deliver vertical synergies (algorithm + sensor) or that provide access to defended regional markets where domestic sourcing is strategic.
How PW Consulting’s report supports 2026 decision cycles
This report was designed to be directly actionable for 2026 planning calendars. It includes investment-grade market size and growth trajectories by modality and device class, supplier benchmarking, scenario stress tests against export-control vectors, and an M&A playbook with valuation sensitivities. We combine quantitative forecasting with qualitative, board-level strategic recommendations so CTOs, CFOs and corporate development teams can make coordinated decisions under uncertainty.
Conclusion — a call to pragmatic opportunity
2026 will be a defining year for stakeholders in consumer electronic biometrics. The addressable market trajectory is strong — underpinned by continued smartphone penetration, expanding cross-device authentication needs and rapid modality-level innovation — and the industry structure favors both scale and specialist plays. However, the interplay of supply-chain concentration, regulatory shifts, and evolving standards means that firms must balance short-term sourcing and integration choices with longer-term investments in software and standards alignment.
For boardrooms, product leaders and investors preparing 2026 budgets and go-to-market plans, our report provides the quantitative backbone and decision-ready strategic guidance needed to convert market momentum into sustainable advantage. To access the full dataset, detailed segmentation tables, vendor scorecards and actionable M&A playbooks, please refer to the complete PW Consulting Worldwide Consumer Electronic Biometrics Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Consumer Electronic Biometrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Consumer and Enterprise Hearables Market Set to Surge at a 12.35% CAGR
By pmarketresearch, 2026-08-12
Worldwide Consumer and Enterprise Hearables Market – Strategic Outlook for 2026
PW Consulting’s new Worldwide Consumer and Enterprise Hearables Market report (base year 2025; forecast period 2026–2032) provides a practical, decision-ready synthesis for executives shaping product, procurement, and M&A strategies in 2026. The hearables sector is no longer a narrow audio hardware market: it sits at the intersection of consumer entertainment, workplace collaboration, and regulated health services. With a projected compound annual growth rate (CAGR) of 12.35% across the 2026–2032 forecast window, the market is set to scale from an estimated USD 68.6 billion in 2025 to well over USD 155 billion by 2032 — creating an expanding set of strategic choices for manufacturers, enterprise IT leaders, healthcare providers, and investors.
Worldwide Stress Ball Market
Why the 2026 Decision Window Matters
-
Acceleration of multi-domain use cases: Hearables are evolving from a single-purpose audio accessory to multifunctional endpoints supporting communications, health monitoring, and immersive media. This convergence means procurement and product roadmaps initiated in 2026 will determine which platforms capture enterprise integration and clinical validation over the next half-decade.
Square Fuse Market -
Supply-chain and input risks are maturing into strategic constraints: Component volatility (microphones, MEMS sensors, and select raw materials) and geopolitically driven tariff dynamics are already shaping manufacturing footprint decisions. Near-term localization and supplier diversification choices will materially affect cost-to-serve and time-to-market in 2026–2027.
Absorbable Biofilm Market -
Competitive consolidation and concentration: The hearables market demonstrates a mid-to-high level of concentration among leading vendors (three- and five-firm concentration metrics indicate sizable but contestable leadership). This structure favors strategic alliances, white-label partnerships, and targeted acquisitions as pragmatic routes to scale.
What the Report Delivers — Practical Outputs for 2026 Strategy
-
Proprietary market model and scenario suite: A transparent forecasting engine calibrated to 2020–2025 historical trends and five alternative 2026–2032 scenarios (base, upside, downside, disruption, and rapid enterprise adoption). Each scenario maps revenue, unit volumes, and ASP sensitivities so executives can stress-test capital allocation and product timing.
-
Actionable GTM playbooks: Channel segmentation, enterprise procurement templates, and partner enablement frameworks tailored for four buyer archetypes — corporate IT buyers, healthcare providers, consumer OEM partners, and telco/streaming platforms.
-
Vendor scorecards and decision matrices: Comparative evaluations across product, software ecosystems, enterprise features (security, device management, UC integration), and clinical/regulated features for hearing health. These scorecards are structured to drive supplier rationalization and RFP design without needing full bespoke audits.
-
Supply-chain risk register and mitigation roadmap: Mapping of component concentration hotspots, lead-time sensitivities, and mitigations such as dual-sourcing, regional assembly hubs, and inventory hedging. The register includes trigger thresholds to prompt sourcing shifts and contingency manufacturing plans.
-
M&A and partnership playbook: Identification of target archetypes (technology enablers, clinical validation partners, ODMs) and valuation guidance under different synergy assumptions, plus integration checklists to capture cross-sell potential between consumer and enterprise channels.
-
Regulatory and compliance primer: Practical guidance for navigating cross-border regulatory landscapes relevant to medical-grade hearables, worker safety standards, and data privacy obligations tied to biometric and health telemetry.
Competitive Landscape — What Leaders and Challengers Mean for 2026 Choices
Leading consumer electronics firms retain strong leverage through ecosystems, brand equity, and distribution reach. Niche incumbents excel in clinical-grade capabilities, enterprise communication features, or high-fidelity audio. Our qualitative assessment of core vendors emphasizes strategic positioning rather than undisclosed share-level data, to help readers map partners and competitors to their own strategic objectives.
-
Apple Inc. – Deep ecosystem integration and a clear path to blend audio, health, and OS-level features. Apple’s platform advantage drives user preference and simplifies enterprise provisioning for organizations standardized on Apple devices. For enterprises, Apple is a primary candidate when user experience and vendor-managed security are priorities.
-
Samsung Electronics – Strong Android-aligned ecosystem and cross-device functionality. Samsung’s strength lies in broad Android reach and device interoperability, especially valuable for mobility-first enterprises and telco partnerships.
-
Sony Group and Bose – Premium audio differentiation through ANC and sound engineering. These firms are natural partners for use cases where sound quality and noise mitigation in hybrid workplaces are mission-critical.
-
GN Audio (Jabra) and Plantronics/Poly – Enterprise-first product lines optimized for unified communications and contact centers. Their device management and collaboration-focused features reduce total cost of ownership in large deployments.
-
Demant, Starkey, WS Audiology – Hearing-health and clinical-grade capabilities bridge consumer adoption and regulated medical services. Organizations entering occupational-health monitoring or tele-audiology should prioritize partnerships with vendors experienced in clinical workflows and reimbursement pathways.
-
Sennheiser, Shure – Professional audio firms that offer high-performance devices for commercial venues and pro-audio integration, relevant to enterprises requiring stage-quality audio or specialized AV integration.
-
Xiaomi, LG – Value-tier and portfolio players that expand reach into cost-sensitive segments and provide OEM/ODM partnership opportunities for scale-oriented strategies.
Industry Dynamics Shaping Tactical Decisions in 2026
-
Component and raw material volatility: MEMS microphones, certain semiconductor inputs, and specific raw materials have experienced supply pressure. Procurement teams should expect fluctuating lead times and price volatility and set contractual mechanisms (e.g., indexation, minimum order commitments, or dual-sourcing clauses) to stabilize supply.
-
Tariffs and regional manufacturing: Trade policy shifts are encouraging regional assembly and local sourcing to mitigate tariff exposure. Companies evaluating 2026 capex should include near-shoring and regional hub scenarios in their TCO models.
-
Form-factor and feature differentiation: High-fidelity audio, immersive spatial formats, and health-monitoring telemetry (AI-driven) are becoming table stakes in premium tiers. Commodity play remains crowded; differentiation increasingly requires software services and ecosystem partnerships.
-
Regulatory and privacy considerations: Integration of biometric and health data creates new compliance obligations. Enterprises must reconcile device telemetry with privacy policies, security baselines, and, if applicable, medical device regulation pathways.
Concrete Recommendations for 2026 Planning
-
Adopt a tiered supplier strategy: Segment suppliers into strategic, transactional, and contingency tiers. Lock in strategic relationships for platform and clinical integration; maintain transactional pools for commodity components to preserve pricing flexibility.
-
Prioritize software-enabled differentiation: Shift R&D and partner investment toward software services — device management, firmware-level AI features, and cloud analytics — where margins and lock-in potential are higher.
-
Embed regulatory checkpoints in product roadmaps: For hearables addressing health or worker-safety use cases, integrate regulatory assessment gates early to avoid late-stage redesigns and market access delays.
-
Design procurement KPIs around end-to-end outcomes: Move beyond unit cost metrics to measures such as TCO per active device, mean time to replacement, firmware security posture, and integration time with enterprise UC systems.
-
Readiness for consolidation: Monitor M&A signals among niche technology enablers and clinical suppliers; small tuck-ins can accelerate time-to-market for enterprise-grade features and unlock cross-selling into adjacent channels.
Signals to Watch Through 2026
-
Announced regional manufacturing expansions or new supplier contracts for critical components.
-
Product firmware releases that move hearables into regulated-health functionality or introduce device-level AI telemetry.
-
Enterprise IT procurement pilots that standardize on a single vendor ecosystem for device provisioning and collaboration.
-
M&A activity among clinical/hearing-health players or acquisitions of AI/signal-processing startups by consumer OEMs.
Final Note — Strategic Value of the Report
PW Consulting’s report synthesizes macro trajectories, vendor positioning, and operational playbooks into a single advisory asset designed to accelerate quality decision-making in 2026. By combining a robust forecasting backbone (covering 2026–2032 with scenario analysis), vendor scorecards, and a supply-chain risk register, the report equips leadership teams to prioritize investments that capture growth while hedging material and regulatory risks.
For executives who need the underlying segment-level detail, vendor-level scorecards, and downloadable model files to execute procurement, product, or M&A playbooks, the full report and bespoke advisory engagements are available via PW Consulting’s research portal. Our approach intentionally highlights strategic direction and operational levers while preserving the granular segmentation and model outputs for secure report access and consulting engagements.
For detailed analysis of this topic, please visit the official page: Worldwide Consumer and Enterprise Hearables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Face & Voice Biometric Market to Accelerate at 14% CAGR, Reaching USD 18.72 Billion by 2032
By pmarketresearch, 2026-08-12
Worldwide Face Voice Biometric Market — A Strategic Preview for 2026 Decision-Makers
As organizations finalize budgets and roadmaps for 2026, biometric modalities that combine face and voice are moving from experimental pilots to mission-critical layers of identity architecture. PW Consulting’s latest market study — the Worldwide Face Voice Biometric Market — provides a forward-looking foundation for executives, security architects, product leaders, and investors who must balance opportunity, compliance and operational risk. This preview highlights the report’s strategic value without revealing proprietary segment-level figures; it is designed to help you decide which questions to prioritize this year and where to go for the full intelligence set.
Worldwide Aroma Diffusion Machines Market
Why this market matters for 2026
Face-and-voice multi-modal biometrics is one of the fastest-growing subsegments of identity and access management. After sustained expansion during 2020–2025, the total market has crossed several inflection points: enterprise deployments are scaling beyond point solutions, regulatory regimes are becoming more prescriptive, and edge compute improvements are enabling sub-100ms real-time matching in practical deployments. Our study quantifies this momentum: global market size has more than doubled over the past five years and is forecast to expand at a compound annual growth rate of 14.0% through 2032, reaching a materially higher scale by the end of the forecast window.
Worldwide Aseptic Bottle Closure Systems Market
For 2026 planning cycles, that growth trajectory translates into three concrete implications for enterprise decision-makers:
Worldwide Sales & Ops Planning Software Market
- Budget: Vendors will expect larger, multi-year commitments as projects move from PoC to production.
- Integration: Multi-modal deployments require orchestration across device hardware, edge/ cloud models, and identity workflows.
- Governance: Heightened regulatory and standards scrutiny will influence vendor selection, data processing models, and consent architectures.
What the report delivers (practical, actionable content)
The report is built to be operationally useful to 2026 buyers and strategists. Highlights include:
- Market sizing and momentum: historical and forecast curves that show where adoption is accelerating and where relative maturity has been reached, with explicit scenario planning for conservative, base, and upside cases.
- Go-to-market playbooks: tailored strategies for vendors selling into finance, government, contact-centers, consumer devices and healthcare — with channel, pricing and contract templates you can adapt.
- Vendor scorecards and procurement checklist: a standardized evaluation framework covering accuracy, liveness, latency, privacy-by-design, interoperability and support models, enabling side-by-side comparison without bespoke RFP construction.
- Deployment blueprints: reference architectures for cloud-native, edge-accelerated and hybrid implementations that include compute sizing, network patterns, latency budgets and fallback flows for degraded channels.
- Risk matrices and compliance pathways: adaptive compliance maps tied to jurisdictional regimes, conformity assessment checkpoints and recommended evidence for audit trails.
- M&A and partnership opportunity maps: strategic criteria for acquiring capability versus partnering, with a prioritized list of target profiles and integration risk assessments.
We intentionally present these items as decision-ready modules; the full report contains templates, scoring models and vendor evaluations that accelerate procurement and reduce technical debt when migrating to multi-modal architectures.
Market structure and concentration — what it means for buyers
The sector is neither a pure winner-takes-all market nor a fragmented long-tail of obscure players. Measured concentration indicates room for both scale vendors and specialist innovators: a small set of large vendors exerts meaningful influence, but nearly half of market value still resides outside the top global leaders. For enterprise buyers, this structure creates a dual imperative:
- Partner with established vendors for scale, support and compliance maturity in regulated deployments (e.g., border control, banking, healthcare).
- Maintain procurement flexibility to incorporate emerging specialists that deliver niche capabilities such as advanced liveness detection, voice anti-spoofing, or low-power edge inference.
Competitive landscape — who to watch
Our report profiles established players and high-impact specialists shaping multi-modal face-voice solutions. Selected profiles include:
- NEC Corporation (Tokyo, Japan): Known for NeoFace and integrated voice modules, NEC is advancing real-time multi-modal surveillance and enterprise authentication suites.
- Aware Inc. (Bedford, MA, USA): Provider of Knomi SDKs optimized for mobile and desktop, with recent platform integrations enhancing ease-of-deployment.
- ID R&D (Neurotechnology, Cambridge, MA, USA): Focused on liveness detection across voice and face, securing contact-center and access-control use cases.
- Daon Inc. (Reston, VA, USA): Offers an identity platform combining face, voice and behavioral signals for KYC and identity proofing at scale.
- Voice Biometrics Group (Redmond, WA, USA): Specialist in voice-first solutions with companion facial matching for fraud prevention.
- Thales Group (Paris, France): Systems integrator for border and digital identity programs, delivering multi-modal biometric suites tied to national programs.
- HID Global (Austin, TX, USA): Focuses on mobile authenticators and enterprise access use cases blending face and voice.
- Verint Systems (Melville, NY, USA): Integrates voice biometrics with facial recognition for customer authentication and workforce management.
Recent developments underline active productization and market movement: NEC released an enhanced NeoFace Watch with integrated voice biometrics (Oct 2025); Aware announced deeper Android authentication integrations (Jun 2025); ID R&D achieved an independent PAD certification for its products (Mar 2025); Daon piloted IdentityX in a European bank’s mobile KYC flows (Nov 2024). Each event signals growing commercial readiness and regulatory-grade engineering efforts by vendors.
Regulatory and standards dynamics — the non-negotiables
Regulatory attention is shaping vendor roadmaps and enterprise procurement decisions. Notable dynamics to incorporate into 2026 strategy:
- The EU AI Act classifies biometric recognition systems as high-risk when used for identification, imposing conformity assessment requirements that affect cross-border deployments.
- GDPR and related data protection guidance treat biometric data as sensitive; enterprises must define lawful bases and consent models before large-scale rollouts.
- Standards such as ISO/IEC 30107-3 (presentation attack detection) and ongoing NIST evaluations for face recognition algorithms (including voice integration test vectors) are increasingly used by procurement and compliance teams as technical acceptance criteria.
- Hardware constraints — edge NPUs and mobile SoCs — are a practical gating factor for latency-sensitive use cases. Real-world deployments often require modern edge AI accelerators to meet sub-100ms matching SLAs.
Put simply: meeting compliance and standards is now a go/no-go check in enterprise sourcing, not an afterthought.
Strategic recommendations for 2026
Based on the study’s scenarios, practitioner playbooks and vendor scoring, PW Consulting recommends five immediate actions for enterprise leaders:
- Define use-case tiers and SLAs: categorize initiatives into low-, medium- and high-risk lanes (e.g., convenience vs. regulated identity proofing) and assign matching security and privacy controls.
- Adopt a modular architecture: separate liveness and matching modules from orchestration, enabling component swaps as standards and vendors evolve.
- Prioritize certified building blocks: require ISO/PAD and independent lab validations (e.g., iBeta/NIST) in RFPs to shorten integration timelines and reduce rework.
- Plan for edge-first designs where latency and availability matter: evaluate device-level inference capabilities and hybrid cloud fallback strategies to minimize user friction and system downtime.
- Establish legal and consent frameworks now: integrate consent capture, retention and portability features into product design to avoid retrofitting under stricter rules.
How to use the full report in procurement and governance
The full PW Consulting report is structured to accelerate procurement cycles and governance readiness. It contains:
- Vendor shortlists aligned to use-case and compliance profiles;
- Pre-built RFP language and evaluation checklists;
- Operational runbooks for phased rollouts and SRE handoffs; and
- Audit evidence templates aligned with regulatory conformity assessments.
For security and identity teams, these artifacts reduce the time from decision to production while lowering integration risk. For strategic planners and investors, the report’s scenario models and M&A opportunity maps convert market growth assumptions into quantified deal and product priorities.
Conclusion — what to act on this quarter
As 2026 budget windows close, face-and-voice biometrics will increasingly be treated as core infrastructure rather than optional enhancement. PW Consulting’s market forecast — reflecting robust historical growth and a 14.0% CAGR over the forecast period — shows both scale and opportunity. But success will hinge on disciplined architecture, standards-aligned procurement, and proactive legal governance.
Use this preview as a checklist: prioritize SLAs and compliance, insist on certified components, architect for edge performance, and keep procurement flexible to onboard specialist capabilities. For the full dataset, vendor scorecards, playbooks and procurement templates that power execution — and to access the underlying segmentation, scoring and scenario details withheld here — please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Face Voice Biometric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com