

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Consumer Electronic Biometrics Market to Surge at 15.7% CAGR, Transforming Smartphones and Wearables

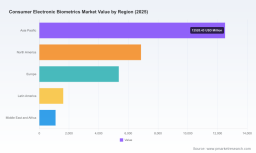
Worldwide Consumer Electronic Biometrics Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting's Senior Strategic Consultant and Chief Industry Analyst, I am pleased to present an executive preview of our latest market intelligence: the Worldwide Consumer Electronic Biometrics Market report (base year 2025, forecast 2026–2032). This briefing is written as a strategic “trailer” — it surfaces the report’s most actionable insights and the macro drivers that will determine winners and losers in 2026, while intentionally withholding granular segment datapoints to direct executives and deal teams to the full report for competitive and commercial execution details.
Surface Drilling Rigs Market
Executive snapshot: Why 2026 is a pivotal year
Biometric authentication in consumer electronics is moving from convenience to a core security and UX differentiator. Our top-line projection shows the market expanding from USD 27,452.12 Million in 2025 to USD 76,218.45 Million by 2032, with a compound annual growth rate (CAGR) of 15.7% across the 2026–2032 forecast horizon. Market concentration is meaningful but not prohibitive: the leading three vendors account for roughly 42% of industry revenue, while the five largest capture about 58% — a structure that sustains competition and creates M&A and partnership arbitrage opportunities for fast-moving challengers.
Single Port Surgical Microscope Beam Splitter Market
What this report delivers — practical, boardroom-ready intelligence
- Scenario-grade market sizing and forecasts validated against supply-side unit economics and demand proxies, built to inform budgeting and investment cycles for 2026–2028.
- Actionable go-to-market playbooks for hardware vendors, chipset integrators, OEMs and platform providers — including partnership archetypes and priority customer segments.
- Strategic supplier scorecards and an IP/technology risk map that correlate sensor modalities, integration complexity, and long-term upgrade pathways for consumer devices.
- Regulatory and geopolitical heatmaps that quantify operational risk vectors tied to export controls, foundry concentration and biometric data governance.
- Commercial due diligence packs for M&A and JV activity: valuation implications, synergies, and five‑year integration planning templates.
- Product and roadmap recommendations (short, medium, long) with engineering trade-off matrices — enabling product owners to decide which biometric modalities to prioritize under constrained BOM and silicon availability.
Core market dynamics shaping 2026 strategy
- Demand acceleration driven by multi-device ecosystems: Biometric modules are no longer isolated features in smartphones — they are becoming consistent authentication layers across laptops, wearables, payment instruments and smart-home endpoints.
- Technology convergence: Optical, ultrasonic, and contactless 3D modalities are advancing in parallel. Software and sensor fusion are emerging as the primary battleground for user experience and spoof-resilience claims.
- Supply-side concentration and geopolitical risk: Fingerprint sensor IC and module production is tied to wafer foundry capacity concentrated in East Asia. Recent export-control regimes for advanced computing components have direct compliance implications for biometric processing chains and vendor sourcing strategies.
- Regulatory momentum around biometric data and use-cases: Industry-led standardization (for example, initiatives to standardize biometric performance in payment cards) is intersecting with national export-control frameworks and privacy law developments, creating both barriers and enablers for product roll-outs.
- Large installed base effect: Hardware adoption momentum remains robust — over 1.5 billion smartphones shipped in 2024 incorporated fingerprint sensors — which sustains component demand even as higher-end modalities scale.
Competitive landscape — strategic takeaways
The industry map includes vertically integrated platform leaders, semiconductor-focused suppliers, pure-play sensor specialists, and system integrators. Below are strategic observations on the most influential players and what their positions mean for competitors, suppliers, and enterprise customers in 2026.
Thin Wafer Processing and Dicing Equipment Market
- Apple Inc. — As an integrator that controls hardware, OS, and secure enclave architecture, Apple sets the premium benchmark for UX and privacy-focused messaging. Their model underscores the value of owning both silicon and secure software stacks; for challengers this raises the bar for differentiation through superior cross-device integration or open ecosystem advantages.
- Samsung Electronics — Samsung demonstrates how device OEMs can combine in-display ultrasonic/optical sensors with platform-level biometric workflows. The company’s scale and supply-chain control highlight the strategic advantage of aligning sensor sourcing with device roadmaps to capture margin and time-to-market.
- Qualcomm Technologies — Qualcomm’s role as a chipset-level integrator of biometric subsystems illustrates the platform play: by embedding biometric primitives into SoCs, chipset vendors can accelerate adoption among Android OEMs. For buyers, this centralization simplifies integration but shifts leverage toward the chipset vendor.
- Goodix, Synaptics, Fingerprints, Egis, Fingerprint Cards (Fingerprints) — These specialist sensor suppliers continue to push sensor innovation, power efficiency and cost optimization. Their success will hinge on strategic partnerships with foundries and on diversifying into new device categories beyond smartphones.
- IDEX Biometrics — By focusing on thin‑film and card-grade implementations, IDEX positions itself at the intersection of payment certification initiatives and wearables, an attractive niche as biometric-on-card standards evolve.
- IDEMIA, NEC, Suprema — These system-level biometric solution providers bring algorithmic strength and enterprise productization experience. Their capabilities are particularly relevant to OEMs that need turn‑key authentication stacks or compliance-ready solutions for regulated markets.
Recent market-moving events and what they imply for 2026
- NEC’s recognition as a leader in biometric innovation signals continued premium demand for high-accuracy algorithms and enterprise-grade verification that can be adapted into consumer product lines.
- The announced acquisition moves in the sector — exemplified by a recent large-scale M&A involving a biometric portfolio — indicate consolidation dynamics that can accelerate standardization, scale cost synergies, and reshape supplier bargaining power.
- Innovations such as metalens-based contactless fingerprint modules and localized indigenously developed sensors in important regional markets are reminders that hardware innovation and regional capability-building will both be critical competitive levers.
Risk matrix — near-term (12–24 months) vs medium-term (24–48 months)
- Near-term: Supply-chain disruptions tied to wafer foundry concentration and export-control compliance represent the most tangible operational risk for 2026 product launches.
- Medium-term: Regulatory and standards evolution (including biometric-on-card performance criteria) and consumer privacy frameworks will reshape product validation requirements and certification timelines, impacting time-to-revenue for new form factors.
- Persistent: Competitive pressure to reduce BOM costs while improving spoof resilience will sustain merger and partnership activity among sensor specialists, chipset providers and system integrators.
Strategic imperatives for different players in 2026
- Device OEMs: Prioritize modular architectures that enable multiple biometric modalities to be field-upgraded in software; secure supply agreements with multiple qualified sensor sources; invest selectively in proprietary AI-driven anti-spoofing.
- Sensor and IC suppliers: Focus on cost-down roadmaps, differentiate through software stacks and developer ecosystems, and pursue strategic alliances with regional foundries to mitigate geopolitical supply risk.
- Chipset and platform vendors: Embed biometric primitives and privacy-preserving compute capabilities into SoC roadmaps; offer robust developer APIs and certification tooling to accelerate OEM integration.
- Payment and card providers: Engage early with standardization bodies and prioritize certification readiness as biometric-on-card initiatives gain regulatory traction.
- Investors and M&A teams: Target assets that deliver vertical synergies (algorithm + sensor) or that provide access to defended regional markets where domestic sourcing is strategic.
How PW Consulting’s report supports 2026 decision cycles
This report was designed to be directly actionable for 2026 planning calendars. It includes investment-grade market size and growth trajectories by modality and device class, supplier benchmarking, scenario stress tests against export-control vectors, and an M&A playbook with valuation sensitivities. We combine quantitative forecasting with qualitative, board-level strategic recommendations so CTOs, CFOs and corporate development teams can make coordinated decisions under uncertainty.
Conclusion — a call to pragmatic opportunity
2026 will be a defining year for stakeholders in consumer electronic biometrics. The addressable market trajectory is strong — underpinned by continued smartphone penetration, expanding cross-device authentication needs and rapid modality-level innovation — and the industry structure favors both scale and specialist plays. However, the interplay of supply-chain concentration, regulatory shifts, and evolving standards means that firms must balance short-term sourcing and integration choices with longer-term investments in software and standards alignment.
For boardrooms, product leaders and investors preparing 2026 budgets and go-to-market plans, our report provides the quantitative backbone and decision-ready strategic guidance needed to convert market momentum into sustainable advantage. To access the full dataset, detailed segmentation tables, vendor scorecards and actionable M&A playbooks, please refer to the complete PW Consulting Worldwide Consumer Electronic Biometrics Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Consumer Electronic Biometrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com