

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 6.15% CAGR for Worldwide Negative Ion Cyclotron Market in 2026–2032 Forecast

Worldwide Negative Ion Cyclotron Market — Strategic Preview for 2026 Decision-Makers
Executive teaser
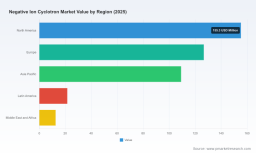
PW Consulting’s new market brief on the Worldwide Negative Ion Cyclotron Market positions executives to make higher-confidence decisions in 2026 and beyond. The sector has grown from an estimated USD 312 million in 2020 to roughly USD 425 million in 2025 and is forecast to expand at a steady compound annual growth rate (CAGR) of approximately 6.15% through 2032 — reaching the mid‑six‑hundred million USD range by the end of the forecast horizon. These aggregate trajectories reflect a combination of sustained clinical demand for PET radioisotopes, growing theranostics programmes, and ongoing investments in decentralized isotope production capacity. This release highlights the strategic implications of those macro trends while intentionally withholding the granular segmentation tables that are included in the full report.
Floating Solar Structure Market
Why this market matters for 2026 strategy
-
Operational resilience: The COVID-era disruptions and continuing supply-chain constraints for medical isotopes have driven hospital groups and national programmes to reconsider centralized supply models. On-site and regional cyclotron deployments are increasingly part of resilience and quality-of-care strategies.
Cybersecurity Vulnerability Assessment Service Market -
Theranostics and pipeline expansion: Momentum in theranostics is increasing demand for both diagnostic and therapeutic isotopes. That creates differentiated demand pressure across energy bands, facility types, and aftermarket service needs.
New Energy Box-type Substation Transformer Market -
Investor clarity: A transparent growth path with a mid-single-digit CAGR provides a predictable environment for capital deployment, acquisition planning, and greenfield facility buildouts — assuming buyers internalize regulatory and technical constraints.
Market dynamics and technical constraints
The sector’s near-term upside must be evaluated against several non-negotiable technical and regulatory realities. Commercial negative H- ion sources typically face space-charge and extraction limits that constrain beam currents in the 1–5 mA envelope; this is a persistent hardware bottleneck that caps per-unit throughput. Facilities deploying cyclotrons must also provision robust infrastructure — RF power systems on the order of hundreds of kilowatts and ultra‑high vacuum systems for stable negative ion acceleration — adding to upfront capex and ongoing technical risk.
On the regulatory side, operators and OEMs are navigating multiple overlapping frameworks. Medical cyclotron facilities and equipment are subject to international radiation protection and facility design standards (e.g., IAEA guidance) and, in key markets, medical device classification and quality-system requirements such as ISO 13485 under EU MDR regimes. High-energy systems (above certain energy thresholds) can trigger export licensing under dual‑use agreements, introducing transaction friction for cross-border sales and technology transfers.
Competitive landscape — what incumbents and challengers are focusing on
The global supply base is concentrated: top manufacturers capture a dominant share of commercial shipments and installed base, with the leading three firms representing roughly two-thirds of the market and the top five accounting for a substantially larger majority. That concentration reinforces the strategic importance of aftermarket services, spare-part logistics, and long-term service agreements as drivers of recurring revenue.
-
Ion Beam Applications (IBA) — A long-standing leader with a broad Cyclone family that covers low to high-energy needs. IBA’s positioning emphasizes high-energy capability for theranostic and therapeutic isotope production, global service coverage, and strategic wins in major health systems. Recent high-profile installations and orders underscore their role in scaling theranostic supply chains.
-
Advanced Cyclotron Systems Inc. (ACSI) — ACSI competes on modular, mid-energy systems optimized for multi‑isotope PET production and flexibility for clinical sites. Their regional deliveries and installations point to strength in adaptability and localized support models.
-
GE Healthcare — Leveraging a global imaging installed base, GE focuses on integrating cyclotron solutions with its end-to-end molecular imaging platforms and service networks. Their offerings are attractive for hospital groups seeking supplier consolidation and integrated service contracts.
-
Sumitomo Heavy Industries — A Japan-based OEM with reliable clinical-grade cyclotron technology, focusing on operational robustness and alignment with regional regulatory expectations in Asia-Pacific and other markets.
-
TeamBest Global — Competes on cost-competitive models and tailored solutions for smaller or emerging facilities, targeting price-sensitive deployments and markets seeking rapid capacity expansion.
Tactically, incumbents are differentiating through service agreements, turnkey installation capabilities, and collaborative partnerships with radiopharmacies and health systems. OEMs that convert installed-base trust into long-term service revenue will be best positioned to capture the more stable slice of total sector value over the next five years.
What the PW Consulting report contains (practical elements for action)
-
Market sizing, historical performance and scenario-driven forecasts at the total-market level (base year 2025, forecast 2026–2032).
-
Technology deep-dive: acceleration physics, common failure modes, beam current constraints, and RF/vacuum system requirements that matter at deployment stage.
-
Regulatory and compliance matrix: IAEA guidance, EU MDR classification considerations, ISO pathways, and export-control triggers.
-
Supplier benchmarking and capability maps covering product portfolios, service footprints, and commercialization strategies.
-
Investment and facilities playbook: capex/opex line items, commissioning timelines, staffing & competency requirements, and procurement checklists.
-
Strategic risk heatmap and mitigation playbooks for supply-chain disruptions, export licensing, and technology obsolescence.
-
M&A and partnership pipeline view to support strategic conversations with incumbent OEMs, radiopharmacies, and national programmes.
Actionable recommendations for 2026 decision-making
-
Prioritize service and spare parts as part of procurement: evaluate total life-cycle cost rather than initial capex alone. With a concentrated supplier base, long-term service contracts materially affect unit economics.
-
Build regulatory compliance into project timelines early: EU MDR, IAEA site requirements and export licensing can add months to commissioning if not anticipated.
-
De-risk high-energy ambitions: if pursuing >30 MeV capability, account for export-control complexity and partner with OEMs that demonstrate proven export‑licensing processes and international logistics experience.
-
Align capacity expansion with isotope roadmaps: match cyclotron energy and beam-current choices to the isotope portfolio your clinical or commercial roadmap requires — avoid one-size-fits-all procurements.
-
Invest in staff competencies and local service capability: technical staffing and on-site maintenance are the leading contributors to uptime and supply security.
-
Use modular deployment where speed-to-market matters: mid-energy, plug-and-play systems can lower initial barriers to entry for regional radiopharmacies and hospital networks.
-
Factor in hardware bottlenecks: current H- source and extraction physics place practical ceilings on single-unit throughput; consider distributed networks of cyclotrons rather than scaling a single high-current machine.
-
Evaluate M&A and strategic partnerships to gain access to aftermarket channels and accelerate market entry with lower execution risk.
Research methodology and what’s intentionally omitted here
The findings presented in this preview are drawn from our 2025 base-year synthesis, combining public company disclosures, recent press announcements, facility-level commissioning reports, interviews with technical and regulatory experts, and proprietary industry modelling covering 2020–2025 history with a forecast period through 2032. To comply with the “trailer” principle of this release, we have showcased aggregate market growth and strategic takeaways while omitting detailed region/application splits and granular segment matrices that form part of the full paid report. Those withheld tables and supplier-level revenue reconciliations are available in the comprehensive dataset and appendix of the full study.
Closing — how to use this preview
For hospital systems, radiopharma operators, OEMs, private equity investors, and government planners, this briefing should be treated as the strategic framework to prioritize investments and risk mitigations in 2026. The sector’s predictable aggregate growth (mid-single-digit CAGR) provides a favourable backdrop, but execution depends on mastering regulatory pathways, technical constraints, and service economics. PW Consulting’s full report converts the strategic contours summarized here into procurement-ready models, supplier scorecards, and scenario-based financials to support board-level and operational decisions.
To obtain the full dataset, facility-level models and supplier scorecards that underpin these conclusions, access the complete PW Consulting Worldwide Negative Ion Cyclotron Market report via our website or contact your PW Consulting account lead for a sample extract and executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Negative Ion Cyclotron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com