

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Polyetherimide (PEI) Films Market Eyes 7.12% CAGR Through 2032 After Reaching USD 521.5 Million in 2025

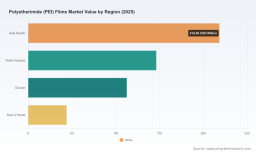
Worldwide Polyetherimide (PEI) Films Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
As materials technology converges with accelerating demand in electronics, aerospace, and electrified transport, polyetherimide (PEI) films have moved from a specialty niche to a strategic industrial material. PW Consulting’s latest Worldwide PEI Films Market study (base year 2025, forecast 2026–2032) puts this evolution in context: the global market is estimated at USD 521.5 million in 2025 and, under our base forecast, is set to expand at a compound annual growth rate (CAGR) of 7.12% through 2032, reaching roughly USD 843.7 million by the end of the projection period. For executives planning capital allocation, sourcing, product roadmap, or M&A activity in 2026, the report crystallizes where economic upside and risk intersect.
Holometer Market
Why PEI Films Matter for 2026 Strategic Decisions
PEI films occupy a unique value position. They combine high glass transition and continuous-use temperatures, excellent dimensional stability, and robust dielectric and flame-retardant characteristics. These attributes make PEI films indispensable in high-reliability domains: thin insulation in advanced electronics and semiconductors, lightweight thermal barriers and dielectric layers in aerospace, and class-leading components in medical devices and industrial equipment.
Wall Suction Unit Market
Two regulatory-technical datapoints frame near-term opportunity and constraint. First, certain PEI grades meet UL 94 V-0 flame ratings at thicknesses as low as 0.075 mm and can comply with aerospace flammability standards such as FAR 25.853 — a certification vector that shortens qualification cycles for aerospace OEMs when thin-gauge performance is validated. Second, select PEI formulations meet EU REACH limitations on BPA migration relevant to food contact and sensitive medical uses — an important commercial differentiator for suppliers targeting regulated end markets.
Worldwide Corporate Tax Software Market
Market Dynamics Shaping 2026
- Demand momentum is underpinned by continued investment in advanced electronics and electrification programs, which are shifting demand toward thin-gauge, high-performance films.
- Raw material volatility is a tangible near-term headwind: industry data show key monomer feedstocks experienced sizeable price increases in recent quarters, introducing cost uncertainty for film producers and downstream buyers.
- Supply-side concentration is meaningful. The market exhibits high aggregation among the top players, producing both barriers to entry and strategic windows for differentiated niche players.
What PW Consulting’s Report Delivers — Practical, Decision-Ready Intelligence
Our report is structured to support decisions across the investment, procurement, and product strategy lifecycles. Key practical deliverables include:
- A transparent market-sizing and forecast model that reconciles historical uptake (2020–2025) with our 2026–2032 scenarios. The model supports what-if analysis across price, volume, and substitution assumptions.
- Scenario playbooks: stress-tested demand cases (conservative, base, accelerated) tied to macroeconomic, regulatory, and feedstock shocks so buyers and producers can prioritize contingency plans.
- Supplier scorecards and capability maps that evaluate technical depth, capacity flexibility, regulatory compliance footprint, and go-to-market reach for leading producers.
- Cost-to-serve and margin sensitivity templates that quantify the impact of feedstock inflation, freight constraints, and regional manufacturing spreads on unit economics.
- Industry qualification timelines and recommended certification sequencing for aerospace, medical, and EV semiconductor applications to accelerate time-to-revenue.
- An M&A and partnership heatmap identifying where bolt-on investments, JV structures, or off-take agreements can de-risk capacity expansion or secure downstream access.
These components are presented with ready-to-use slide decks and spreadsheets so corporate teams can adapt insights to internal P&L models and procurement strategies. Crucially, the report provokes action rather than offering descriptive narration — it maps decisions to economic outcomes.
Competitive Landscape: Profiles and Strategic Implications
The PEI films market is shaped by differentiated player strategies: global petrochemical incumbents with integrated material portfolios, specialized polymer converters with technical depth, and custom compounders targeting niche electrical or acoustic properties. PW Consulting’s assessment of leading firms yields the following strategic takeaways:
- SABIC (Riyadh) leverages scale and brand-positioned ULTEM™ technology to serve aerospace, electronics, and medical OEMs with thin-gauge, high-temperature films. Its combination of global reach and established material datasheets accelerates qualification in regulated industries. Strategic implication: competitors must match certification readiness and technical support to compete on system-level adoption.
- Ensinger GmbH (Nufringen) positions itself around engineering-grade PEC/PEI films and customized thicknesses for automotive and technical applications. Its strength lies in application-driven customization. Strategic implication: collision between tailored solutions and volume economics creates niches for specialty converters.
- RTP Company (Winona) focuses on custom compounding and specialty films for electrical insulation and flexible circuitry. Its agility to formulate application-specific compounds is a go-to tactic to win early-stage design wins. Strategic implication: larger firms should consider partnerships or internal capability builds to capture early R&D-led demand.
Market concentration metrics reinforce the strategic environment: a small set of players command the lion’s share of available capacity and customer relationships, creating both a high barrier for large-scale disruption and a fertile landscape for targeted differentiation.
Supply Chain and Cost Risk — What to Hedge in 2026
Feedstock tightness and regional dynamics are visible stress points. Industry reporting notes that key monomers have experienced material price appreciation in recent periods, raising the ceiling on input costs for film producers. For procurement and strategy teams, key actions in 2026 should include:
- Locking multi-year supply agreements for critical monomers where feasible, with indexed pricing bands to share margin risk.
- Testing alternative chemistries and co-polymers where performance trade-offs are acceptable to reduce exposure to single-feedstock shocks.
- Evaluating near-sourcing or localized conversion capacity to reduce freight and lead-time risk in time-sensitive markets such as semiconductors and aerospace.
- Running scenario-based cost models provided in the PW report to quantify the P&L impact of ±15–25% raw material swings and to set minimum hedge thresholds.
Technology, Certification and Time-to-Market Constraints
PEI films often face long qualification lead times, particularly in aerospace and medical end markets where certification is non-negotiable and testing cycles extend procurement timelines. The report includes a certification road map that aligns material development milestones with certification windows (electrical, flammability and chemical migration), enabling companies to sequence R&D, qualification testing, and customer engagement to avoid costly time-to-market slippage.
A Practical Playbook for 2026 — Prioritized Actions
Below is PW Consulting’s recommended action ladder for companies active in or entering the PEI films value chain in 2026. Each recommendation is calibrated against market growth expectations and sector-specific risk profiles.
- Short-term (0–12 months): Secure critical monomer supply; prioritize certification-readiness for top-priority accounts; fast-track modular product offerings for electronics and EV thermal management.
- Medium-term (12–24 months): Invest in thin-gauge process optimization and cost reduction programs; pursue targeted partnerships for acoustic and high-temperature specialty grades; pilot near-shore conversion capacity where demand density justifies.
- Long-term (24+ months): Consider M&A to acquire niche compounding capabilities or capacity; scale sustainability and circularity initiatives (e.g., reclaim streams for industrial-grade reuse) and embed them into OEM procurement dialogues; institutionalize dynamic pricing linked to feedstock indices.
Why the Full Report Is Critical for 2026 Decision-Making
This preview highlights the structural drivers and recommended strategic plays, but the full PW Consulting report contains the granular inputs that decision-makers need: proprietary segment-level forecasts, supplier-level cost curves, an actionable M&A heatmap, and downloadable scenario models with configurable assumptions. If your 2026 plan involves CAPEX commitments, supplier consolidation, or accelerated product launches in aerospace, semiconductors, or EV applications, the incremental information provided in the full report materially changes go/no-go analyses and timing.
In a market growing at a mid-single-digit-plus CAGR with concentrated supply dynamics, small timing advantages or a single large qualification win can produce outsized returns. Conversely, underestimating raw material sensitivity or regulatory qualification time can lock in suboptimal investments. PW Consulting’s report translates these risk-reward trade-offs into executable steps aligned with corporate planning cycles.
For procurement directors, R&D leads, and corporate strategists preparing budgets and roadmaps for 2026, the question is no longer whether PEI films will matter — it is how to turn material performance into sustainable commercial advantage. Our report provides the analytics, scenario playbooks, and strategic frameworks required to answer that question with confidence. Access to the full dataset and supplier scorecards is available through PW Consulting’s report platform for teams seeking to convert insight into action.
For detailed analysis of this topic, please visit the official page: Worldwide Polyetherimide (PEI) Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com