

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
PW Consulting: Rotator Cuff Injury Therapy Market to Hit USD 2,951.21 Million by 2032, Growing at a 6.1% CAGR
By pmarketresearch, 2026-07-02
Rotator Cuff Injury Therapy Market 2026 Outlook: Strategic Imperatives from PW Consulting's New Market Report
Executive overview
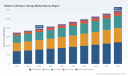
PW Consulting today releases its definitive market intelligence brief on the Rotator Cuff Injury Therapy market, framed to support executive decision‑making across product, commercial, regulatory and M&A agendas in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the report models the market as a multi‑billion dollar device and therapy sector (USD, revenue in Million) that is set to expand at a compound annual growth rate (CAGR) of 6.1% through 2032. Our base‑case arithmetic pegs the market at approximately USD 1,949.82 Million in 2025 with a near‑term step to ~USD 2,068.76 Million in 2026 and a long‑term projection to about USD 2,951.21 Million by 2032.
Rotator Cuff Injury Therapy Market
Why this report matters for 2026 corporate strategy
For medtech and biologics executives, hospital procurement leads, private equity teams and regional market entrants, 2026 is the year to convert clinical momentum into commercial traction. The combination of guideline endorsements for bioinductive approaches, recent device clearances and persistent reimbursement complexity is reshaping where value is created across the care pathway.
Rotator Cuff Injury Therapy Market
-
Product roadmaps: The market’s steady growth at 6.1% CAGR creates a predictable window to amortize new platform investments — but only for technologies that demonstrably reduce re‑tear rates or shorten total care episodes. Firms must prioritize clinical end points and economic evidence alongside engineering advances.
Rotator Cuff Injury Therapy Market -
Regulatory & launch sequencing: Multiple FDA 510(k) clearances for augmentation matrices and new repair systems in 2024–2025 have lowered technical entry barriers. Still, first‑mover advantage now depends on post‑market evidence generation and favorable guideline positioning.
-
Reimbursement and pricing strategy: Procedural reimbursement for arthroscopic repair remains nuanced. For example, complexity‑based modifiers are successfully applied in a limited minority of cases, which directly affects premium pricing for augmented repairs. Negotiating favorable hospital contracting terms will be decisive.
-
M&A and partnership timing: The sector’s innovation cadence — from suture anchor refinements to bioinductive implants and novel space‑occupying devices for irreparable tears — makes 2026 a pivotal year for tuck‑ins that add biologic or augmentation capabilities to established instrumentation platforms.
What the report contains — practical, transaction‑ready intelligence
PW Consulting’s analysis is structured to convert insight into action. The report includes:
-
Verified market sizing and a seven‑year forecast (2026–2032) with scenario lanes for conservative, base and aggressive uptake curves;
-
Driver and barrier analysis mapping clinical guidelines, device approvals, payor behaviors and provider economics to expected product adoption timelines;
-
Technology deep dives covering suture anchors, knotless systems, augmentation matrices, biologics and implants designed for massive/irreparable tears;
-
Reimbursement playbook: coding risk analysis, modifier usage benchmarks and commercial levers for securing hospital and ASC reimbursement premiums;
-
Competitive landscaping with strategic profiles, pipeline intelligence and capability matrices for the sector’s leading suppliers;
-
Go‑to‑market frameworks and a 12‑ to 36‑month tactical plan tailored for incumbents, challengers and private equity‑backed platforms; and
-
Client‑ready model files and sensitivity tools that let users re‑run forecasts under custom assumptions.
Note: the report intentionally omits publicly distributed granular segment line items from this press summary to preserve the value of the full dataset. Authorized purchasers receive exhaustive regional, treatment‑type and end‑user splits along with downloadable tables and charts.
Competitive landscape — how leading firms are positioning in 2026
The competitive environment is evolving from hardware‑led battles toward mixed portfolios that combine anchors and instrumentation with biologics, augmentation matrices and supportive implants. Key strategic postures observed among incumbents and challengers include:
-
Product breadth and ecosystem plays: Established orthopedics platforms continue to leverage their existing surgical instrument footprints to bundle anchors, suture systems and kits that shorten OR time and reduce variability.
-
Biologics and augmentation differentiation: Several companies have prioritized bioinductive or bioresorbable matrices to address re‑tear economics. Guideline endorsements for bioinductive approaches have created a greenfield for commercialization of such adjuncts.
-
Minimally invasive and salvage solutions: Innovations targeted at massive or irreparable tears — including balloon implants and scaffold technologies — are attracting clinical interest and changing referral patterns.
-
Regulatory and evidence acceleration: Firms that combine rapid 510(k) clearances with robust post‑market registries and health economics analyses are winning quicker uptake in hospital systems.
Representative companies examined in our competitive profiles include global medtech leaders and focused orthopedics innovators active in clinical adoption and product development. Each profile contains capability maps, recent launches and clinical evidence assessments to aid partnership, licensing and acquisition decisions.
Recent developments shaping near‑term strategy
-
Clinical guidelines: The American Academy of Orthopaedic Surgeons’ updated guideline emphasizes bioinductive implants to reduce re‑tear rates, strengthening the clinical case for augmentation devices.
-
Regulatory activity: Several augmentation matrices and repair systems received FDA clearances in 2024–2025, expanding the menu of commercially available adjuncts and creating competition for clinical share.
-
Commercial milestones: Industry conferences in early 2026 showcased next‑generation repair systems and biologic implants, accelerating awareness among key opinion leaders.
-
Economic signals: Independent analyses indicate a meaningful lifetime societal cost‑saving for patients undergoing repair versus nonoperative treatment — a powerful argument for payors and hospital CFOs when evaluating adoption of higher‑cost adjuncts.
Actionable 2026 playbook — five high‑impact moves
-
Prioritize evidence‑grade launches: Align product introductions with registries and randomized studies that target re‑tear reduction and cost per quality‑adjusted life year (QALY) improvements.
-
Design reimbursement experiments: Pilot enhanced payment bundles and modifier usage protocols with lead hospitals and ASCs to capture incremental procedure economics.
-
Bundle hardware + biologic offers: Create commercial bundles that simplify purchasing decisions for hospital procurement teams and demonstrate OR efficiency gains.
-
Identify bolt‑on M&A targets: Use our heatmaps to shortlist assets that add augmentation biology, novel scaffolds or ASC distribution channels to your portfolio.
-
Build RWE fast: Deploy pragmatic registries at top centers to collect function, re‑tear and resource‑use outcomes — enabling premium contracting and faster guideline uptake.
How PW Consulting’s methodology supports board‑level decisions
The report combines primary interviews with surgeons, hospital procurement leads and payor advisors, alongside procedure‑level pricing analytics and device adoption curves. We triangulate manufacturer disclosures, regulatory databases and clinical literature to produce transparent, auditable forecasts. The deliverable suite includes scenario models and a bespoke slide deck to accelerate C‑suite briefings and investor diligence.
Call to action — where to get the full intelligence
This press release intentionally provides a high‑value executive synopsis while preserving the report’s detailed segment tables and company financial estimates for authorized users. The full PW Consulting Rotator Cuff Injury Therapy Market report contains the granular regional, treatment‑type and end‑user breakdowns, company revenue estimates, market share matrices, and downloadable model files necessary for transaction execution and operational planning.
To access the complete dataset, scenario models and client advisory options for 2026 strategy, please visit the PW Consulting market reports page or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Rotator Cuff Injury Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Etifoxine Hydrochloride Market to Grow at a 5.2% CAGR Through 2032
By pmarketresearch, 2026-07-02
Etifoxine Hydrochloride Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting today publishes an executive briefing that condenses the strategic implications from our full Etifoxine Hydrochloride Market report (base year 2025; historical review 2020–2025; forecast 2026–2032). Built for corporate strategy teams, product leaders, BD&L groups and private equity investors, this piece outlines why Etifoxine deserves attention in 2026 and how our report converts market intelligence into executable choices — while preserving the detailed segment and revenue tables for subscribers of the full study.
Etifoxine Hydrochloride Market
Why this report matters for planning in 2026
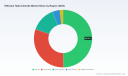
Etifoxine’s market trajectory is clear: the global market has expanded steadily over the historical window and our modeled baseline projects continued growth through the 2026–2032 forecast period at a compound annual growth rate (CAGR) of 5.2%. Using 2025 as the base year and USD (Million) as the reporting currency and unit, our scenarios show the market moving from its mid‑2020s level to materially higher absolute demand by the end of the decade. For companies weighing portfolio prioritization, capacity investments or regional launches, the combined force of moderate organic growth, regulatory frictions, and a shifting competitive set creates a narrow window in 2026 to secure supply, evidence-generation pathways and distribution footholds.
Etifoxine Hydrochloride Market
Report deliverables — practical tools, not just charts
- Integrated financial model (editable Excel) with base case, conservative and upside scenarios for 2026–2032 planning, including sensitivity levers for price pressure, generic entry timing and market access.
- Commercial launch playbook templates: go‑to‑market sequencing, payor engagement checklists, KOL/RWE study designs and sample local launch budgets.
- Regulatory and safety risk matrix mapping EMA precedent and major national regulators, with triggers for label changes, contraindication management and post‑marketing surveillance obligations.
- Supply‑chain heat maps and supplier scorecards for API sourcing, including risk indices and mitigation options for single‑sourced components.
- M&A and JV screening framework tailored to Etifoxine: valuation multipliers, due‑diligence red flags and integration checklists emphasizing compliance and pharmacovigilance readiness.
- Commercial diagnostics and payer-impact assessment tools to quantify expected reimbursement levers and price elasticity under different competitive entry timelines.
These deliverables are oriented toward teams that must convert market intelligence into project plans in the coming 12–18 months. The full report contains the underlying data tables and market-split models that feed these tools.
Etifoxine Hydrochloride Market
Market dynamics and near-term catalysts
- Regulatory posture is a key determinant. The EMA’s past evaluation has affirmed a continued role for Etifoxine in anxiety disorders while emphasizing contraindications related to severe cutaneous reactions and severe hepatic impairment. That regulatory framing creates differential labeling and risk management obligations across jurisdictions — a core consideration for 2026 market-entry timing.
- Geographic access remains uneven. Etifoxine is not authorized in every major market, and the absence of a US approval creates both a constraint and a potential long-term opportunity for companies that can generate bridging evidence.
- Clinical pipeline developments are strategic inflection points. A notable ongoing trial scheduled to start in early 2026 will evaluate Etifoxine as a preventive therapy for Chemotherapy‑Induced Peripheral Neuropathy (CIPN). Positive signals from that program would materially broaden therapeutic positioning and payer conversations.
- Generics and local manufacturing are accelerating. Recent generic launches and regulatory approvals in key markets are compressing price points and shifting the value chain toward cost-efficient API sourcing and local packaging strategies.
In short, the interplay of regulatory nuance, clinical repositioning potential, and manufacturing economics makes 2026 a pivotal year to convert strategy into defensible execution.
Competitive landscape — who matters and why
Our competitive analysis focuses on the firms currently shaping supply, marketing and commercialization:
- Biocodex (France) — the marketer historically associated with Stresam. Biocodex’s legacy brand presence creates a reference standard for clinical positioning and physician familiarity.
- Sun Pharmaceutical Industries Ltd. (India) — has secured national approvals and advanced post‑marketing surveillance activity in its home market, signaling an aggressive commercialization posture and capacity to scale branded or generics supply rapidly.
- Metrochem API Private Limited and Global Calcium Pvt Ltd (India) — API manufacturers whose presence reduces entry barriers for companies seeking cost‑effective active pharmaceutical ingredient sources.
- Nizhpharm (Russia) — launched the country’s first domestic generic in mid‑2025, illustrating how local players can capture share quickly where regulatory pathways favor generics.
From a concentration standpoint, the market exhibits moderate degree of aggregation: our CR3 and CR5 metrics highlight that the top three and top five firms hold meaningful shares of supply and commercialization strength, but the structure still allows for targeted new entrants and niche incumbents to win with the right combination of price, distribution and evidence. The full report quantifies these concentration measures and models their impact on pricing and margin trajectories under alternative entry scenarios.
Strategic imperatives for 2026
- Prioritize regulatory and safety investments. With constrained labeling in certain geographies and an elevated post‑marketing surveillance expectation, companies should budget for active safety monitoring and plan label risk mitigations before full commercial roll‑out.
- Secure API diversity now. Our supply‑chain analysis shows that early dual‑sourcing and inventory hedging materially reduce the probability of costly supply interruptions and enable competitive tender responses.
- Design an evidence‑first commercial approach. Where clinical repositioning (e.g., CIPN prevention) is plausible, pre‑emptive investment in small‑scale, payer‑focused RWE studies yields asymmetric returns during initial reimbursement negotiations.
- Define a launch cadence that blends legacy brand recognition with price competitiveness. For companies entering markets where incumbent brands exist, hybrid strategies that offer differentiated access programs or local manufacturing partnerships outperform pure cost plays.
- Use M&A judiciously. Targets that immediately add regulatory dossiers, local distribution or validated API capacity compress time‑to‑market. Our M&A screening tool identifies traits that de‑risk integration and accelerate commercial scale.
What this means for different stakeholder groups
- Pharma executives: Reprioritize small, high‑confidence investments in regulatory and pharmacovigilance frameworks to ensure rapid, compliant rollouts in growth markets.
- Manufacturers/API suppliers: Invest in contract capacity and quality assurance that meet both EU and fast‑growing emerging market standards — a differentiator in RFPs and tenders.
- Investors/PE: Favor assets with regulatory dossiers, existing distribution contracts and the ability to execute local manufacturing; avoid exposure to targets with single‑source API risk unless price is materially discounted.
- Clinical teams: Evaluate near‑term RWE commitments that could convert Etifoxine from a single‑indication therapy to a multi‑use neuroprotective adjunct, contingent on CIPN and related evidence generation.
Methodology and confidence in our outputs
Our analysis uses 2025 as the base year, applies a transparent forecasting framework across 2026–2032 and reports values in USD (Million). Inputs include primary interviews with manufacturers, regulators and payers; proprietary shipment and pricing datasets; and triangulation with public regulatory records and clinical registries. We stress‑test assumptions across price erosion scenarios, generic entry timing and regional access permutations to produce both deterministic and probabilistic forecasts. Where regulatory uncertainty or trial outcomes create material variance, our report provides alternate scenario outputs and playbooks for each case.
Getting the full intelligence
This announcement highlights the report’s strategic value while reserving the full set of segmented tables, regional and application splits, price curves and downloadable models for subscribers. If your 2026 plan depends on precise segment-level forecasts, supplier assessments or the playbooks referenced above, the full Etifoxine Hydrochloride Market report contains the granular data and executable templates needed to move from strategy to implementation.
PW Consulting’s advisory teams are available to walk leadership through bespoke interpretations of the report, run integrated financial stress tests, and co‑design launch or M&A playbooks tailored to your portfolio objectives. For organizations that require a short, high‑impact workshop to translate findings into a 90‑day action plan, our consultants can deliver an outcomes‑focused session grounded in the report’s evidence base.
In an evolving competitive and regulatory landscape, the 2026 planning horizon rewards teams that pair disciplined data with operational preparedness. Our Etifoxine Hydrochloride Market report is built to be the analytics backbone of that preparedness — supplying the models, regulatory intelligence and commercial playbooks that convert market opportunity into defensible outcomes.
For detailed analysis of this topic, please visit the official page: Etifoxine Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Inorganic Feed Mycotoxin Binders & Modifiers Market to Reach USD 1,308.21 Million by 2032, Expanding at a 5.15% CAGR
By pmarketresearch, 2026-07-01
Inorganic Feed Mycotoxins Binders and Modifiers Market: Strategic Imperatives for 2026 — PW Consulting Insight Brief
As supply chains, regulatory regimes, and feed production economics converge under intensified global scrutiny, inorganic mycotoxin binders and modifiers have moved from niche risk-mitigation products to strategic levers in animal nutrition portfolios. PW Consulting’s latest market study — based on a 2020–2025 historical review with a 2026–2032 forecast horizon — quantifies that transition and frames specific decisions executives must make in 2026 to capture durable value.
Inorganic Feed Mycotoxins Binders And Modifiers Market
Market trajectory at a glance
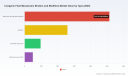
Key macro context from our report: the global Inorganic Feed Mycotoxins Binders and Modifiers market base year is 2025 (USD, Million), and the category has expanded from an estimated USD 716.1M in 2020 to USD 920.5M in 2025. Our forecast projects continued growth through 2032, reaching an estimated USD 1,308.2M, underpinned by a compound annual growth rate (CAGR) of approximately 5.15% over the 2026–2032 period.
Inorganic Feed Mycotoxins Binders And Modifiers Market
These headline metrics reflect more than raw demand — they signal structural forces reshaping market economics: sustained feed-industry exposure to mycotoxin risk; broadening acceptance of mineral-based interventions across species; and an innovation premium for products that demonstrably balance efficacy with nutrient safety. PW Consulting’s report unpacks these drivers and translates them into investment and portfolio decisions for 2026.
Inorganic Feed Mycotoxins Binders And Modifiers Market
Why 2026 is a pivotal year for corporate strategy
-
Operationalizing scale: With mid-single-digit market growth entrenched, 2026 will differentiate companies that convert R&D credibility into commercial scale. Firms that can move from lab and controlled-trial efficacy to predictable supply and validated on-farm ROI will command pricing power and channel preference.
-
Regulatory alignment wins market access: Regulatory clarity — for example, authorizations that recognize certain bentonites for aflatoxin mitigation — favors players who align product dossiers to jurisdictional frameworks while proactively generating data on nutrient bioavailability and animal safety as required by agencies such as EFSA.
-
Raw-material security as a competitive moat: Because key products are mined aluminosilicates and related minerals (bentonite, montmorillonite, HSCAS, sepiolite, zeolites), companies that secure upstream access, diversify sourcing, or vertically integrate processing will alleviate margin volatility and guarantee product consistency.
Competitive landscape — concentration, positioning, and recent moves
The market remains moderately concentrated. Our analysis indicates that the top three players account for approximately 28.5% of market revenues (CR3), while the top five reach about 39.2% (CR5). That means meaningful share remains accessible to fast-moving challengers and specialty players who can combine technical differentiation with channel execution.
Headline competitor profiles in the report include:
-
Amlan International (Oil-Dri Corporation of America) — Focused on proprietary mineral-based binders such as Calibrin-A and Calibrin-Z, with product positioning that emphasizes rapid aflatoxin binding and broad-spectrum biotoxin capture. Amlan has been active in product commercialization and partnerships — notably launching clay-based formulations in strategic markets and showcasing innovations at major trade events in 2025.
-
Kemin Industries — Offers the TOXFIN range leveraging activated adsorbents and argillaceous minerals for broad-spectrum binding and aflatoxin B1 reduction. Kemin’s strength is integrated technical services and established sales reach in feed additive channels.
-
Tolsa — European clay-specialist with blended products combining bentonite, sepiolite, and activated carbon for mycotoxin sequestration; their asset base is oriented to mineral processing and feed applications.
-
Bentoli Inc. — A focused supplier of clay-based mycotoxin binders and feed additives, oriented to livestock and poultry markets with pragmatic formulations addressing toxin control.
Recent developments documented in the industry underscore commercial momentum: product launches and strategic showcases by leading players in 2025–2026 demonstrate both market validation and competitive escalation. PW Consulting’s report analyzes these moves and the implied playbooks, including regional go-to-market sequencing, channel partnerships, and co-development models.
Regulatory and raw-material dynamics that will shape strategy
-
Regulatory expectations: Authorities increasingly require evidence not only of mycotoxin sequestration but also of neutral impact on nutrient bioavailability and animal safety. The report maps the testing frameworks and dossier requirements across key jurisdictions and offers a prioritized certification pathway for market entry and claims substantiation.
-
Raw material reality: Inorganic binders are predominantly mined minerals with variable properties. Particle size distribution, thermal processing, and activation treatments materially affect binding spectrum and capacity. Our technical annex evaluates supply concentration, beneficiation costs, and potential pinch points that could affect 2026 sourcing strategies.
-
Standards and lab validation: Standardized in vitro and in vivo assay protocols matter for buyer confidence. The report recommends a test matrix that balances regulatory acceptability, commercial relevance, and cost-efficiency for product qualification programs.
What the PW Consulting report delivers — practical, transaction-ready intelligence
PW Consulting’s market study is deliberately action-oriented. Beyond market sizing and forecast scenarios, the deliverables include:
-
Commercial playbooks for product launch and channel expansion, including pricing strategies, distributor scorecards, and on-farm trial sequencing.
-
M&A and partnership screening frameworks to identify targets that deliver mineral supply, processing capability, or route-to-market reach. Our due-diligence checklist covers technical validation, regulatory dossiers, and integration risk markers.
-
Operational templates for supply-security: sourcing maps, contingency plans for material variability, and processing tolerances that preserve product efficacy.
-
Decision-support models that translate technical performance (binding spectrum, adsorption capacity) into commercial outcomes (feed conversion, mortality reduction, return on investment) under multiple farm-level scenarios.
-
Competitive battlecards summarizing rival product claims, technological differentiators, and likely responses — enabling rapid strategy alignment for marketing and sales teams.
Strategic recommendations for executives planning 2026 moves
-
Prioritize validation that regulators and buyers accept: Invest in a dual-track evidence program — regulatory-grade dossiers for market access and pragmatic field trials that speak to feed mills and integrators. Demonstrated safety with no nutrient impairment is a gating factor for mainstream adoption.
-
Secure and optimize the supply chain: Lock in multi-source access to critical clays, evaluate beneficiation partnerships to standardize product quality, and consider toll-processing agreements to scale quickly without heavy capex.
-
Differentiate beyond basic adsorption: The winners will be those who articulate product stories around spectrum breadth (polar and nonpolar mycotoxins), kinetics (speed of binding), and formulation compatibility (premix, pelleting resilience). Strategic investments in surface modification and hybrid adsorbent blends will pay off.
-
Leverage partnerships for faster market penetration: Distribution alliances with feed additive companies, co-marketing with veterinary pharmaceutical partners, and region-specific launch partners can compress commercialization cycles and share trial costs.
-
Prepare M&A playbooks now: Given moderate concentration and available specialty assets, build a shortlist of targets that provide either upstream mineral control or complementary technologies (e.g., activated carbons, sepiolite-based formulations). The report’s M&A framework makes this plug-and-play for corporate development teams.
How to use PW Consulting’s insight for board-level decision making
Boards and executive teams should treat inorganic mycotoxin binders as both a defensive necessity and an offensive growth vector. The decision lens we recommend for 2026 revolves around three questions:
-
Can we ensure supply and technical consistency at target scale?
-
Do our product claims meet the evidentiary bar demanded by regulators and large feed buyers?
-
Where on the spectrum of build, partner, or buy do we maximize shareholder value within an acceptable timeline?
PW Consulting’s report provides tailored scenario analyses and financial templates that attach probabilities and expected value to each path, enabling boards to set funded initiatives for 2026 with clarity and accountability.
Closing — why this report matters now
The market’s historical climb from a mid-2020s base to the forecasted 2032 figure reflects persistent demand for risk mitigation in feed systems and an openness to mineral-based solutions. However, the market will reward only those players who can translate laboratory efficacy into validated supply-grade products, navigate evolving regulatory expectations, and secure resilient raw material sources.
Our research balances technical depth with commercial pragmatism: it reveals where structural value exists, where competitive pressures will intensify, and what operational and regulatory investments are non-negotiable in 2026. For executives charting next-year budgets and strategic priorities, the report is a decision-ready guide that connects science to P&L outcomes without leaving risk unquantified.
Next steps
PW Consulting invites industry leaders to a concise executive briefing to explore tailored implications for their portfolios, including scenario-based ROI modeling and a prioritized action plan for 2026. The full report contains detailed segmentation, territorial and application breakdowns, and granular competitor profiles for executives and deal teams — access it through our official release channels to unlock the supporting datasets and proprietary templates referenced above.
For detailed analysis of this topic, please visit the official page: Inorganic Feed Mycotoxins Binders And Modifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sleep Apnea Masks Market Poised to Expand at 8.15% CAGR from 2026–2032
By pmarketresearch, 2026-07-01
Sleep Apnea Masks Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
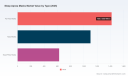
PW Consulting’s latest market research on the Sleep Apnea Masks market provides an evidence-driven playbook for executive teams preparing critical 2026 decisions. The global market has moved from roughly USD 2.06 billion in 2020 to an estimated USD 3.15 billion in 2025, and is projected to reach approximately USD 5.45 billion by 2032 at a compound annual growth rate (CAGR) of about 8.15% over the forecast horizon. These macro dynamics, combined with a high degree of industry concentration (CR3 ~78.4%; CR5 ~89.6%), materially change the geometry of competitive opportunity—favoring scale, differentiated clinical value, and payor-aware commercialization.
Sleep Apnea Masks Market
Why this report matters for 2026 strategic decisions
2026 is a watershed year for sleep-therapy stakeholders: regulatory clarity is crystallizing, new entrants and incumbents are introducing differentiated interfaces and AI-enabled features, and reimbursement pathways continue to evolve in core markets. Our study translates these external forces into an actionable decision framework for product managers, business development leads, procurement directors, and private equity firms. The research combines a rigorous top-down market sizing with bottom-up validation across clinical, regulatory, and channel inputs to produce a practicable roadmap—not an academic exercise.
Sleep Apnea Masks Market
Core market dynamics — concise, actionable signals
-
Steady market expansion: The market’s trajectory from 2020 through 2025 demonstrates durable demand as diagnosis rates, treatment adherence programs, and device compatibility improve. The forecast to 2032 at an 8.15% CAGR signals sustained commercial upside for firms that can convert clinical efficacy into patient-preferred interfaces and payor-aligned value propositions.
Sleep Apnea Masks Market -
High concentration: The top three and five players together control a substantial share of market value, which elevates the importance of partnership, niche specialization, and selective M&A to attain competitive scale.
-
Regulatory and reimbursement contours: CPAP masks remain regulated as Class II devices under 510(k) pathways in the U.S., and public payors like Medicare maintain established HCPCS coverage and replacement schedules for mask interfaces—both elements that shape product rollout timing and commercial models.
-
Materials and manufacturing: Medical-grade silicone continues to be the dominant cushion material due to biocompatibility and cleaning durability—an operational constraint that influences supplier selection and cost curves.
Competitive landscape: what incumbents and newcomers reveal
Our qualitative and transactional analysis profiles leading OEMs and relevant new entrants, mapping technology vectors, channel footprints, and regulatory milestones that materially affect go-to-market choices:
-
ResMed (San Diego): Continues to invest in integrated therapy ecosystems—AI-enabled comfort and personalization are now cleared and increasingly embedded as a differentiator for mask-device pairing. For partners, the lesson is clear: compatibility with device-side intelligence is a near-term commercial must.
-
Fisher & Paykel Healthcare (Auckland): Advances in cushion and headgear design—aimed at fit and seal consistency—underscore the continued yield from engineering-led differentiation in core mask types.
-
Philips Respironics (Amsterdam/Pittsburgh operations): Remains a scale competitor with broad interface portfolios; integration of user experience innovations into established channels is their primary lever for retention.
-
Inogen (Goleta): The Aurora entry demonstrates that adjacent respiratory players can rapidly introduce credible CPAP masks when supported by clinical-use studies—new entrants should plan for rapid evidence generation to accelerate channel acceptance.
-
REMSleep (Blackshear): Recent expanded FDA 510(k) clearance for a nasal pillow system exemplifies how regulatory wins can unlock institutional channels and broaden patient applicability—especially relevant for companies targeting hospitals and sleep labs.
-
Other OEMs (Drive DeVilbiss, React Health, Bleep, BMC Medical): These companies highlight alternative routes to market—from value-focused OEM supply to design-led niche products—illustrating multiple commercialization archetypes beyond incumbent strategies.
Recent product and regulatory developments: strategic takeaways
Key events through early 2026 underscore the bifurcation of competitive advantage into (a) clinical/regulatory credibility and (b) user-centered design integrated with device ecosystems. Examples include AI-enabled comfort features now cleared for market, new cushion/headgear launches, and regulatory clearances that extend product usage into institutional settings. For strategic planners, the implications are straightforward: prioritize regulatory roadmaps and clinical evidence generation concurrent with design investments to compress time-to-revenue.
What’s inside the PW Consulting report (practical deliverables)
Our report is structured as an executive-grade decision toolkit rather than a purely descriptive market brief. Key deliverables include:
-
Macro and micro market sizing with a validated forecast model and scenario analyses to stress-test 2026–2032 revenue paths.
-
Competitive matrix and capability heatmaps describing product portfolios, regulatory status, and channel strength—designed to support rapid partner/target screening.
-
Commercial playbooks for four go-to-market archetypes: incumbent OEM scale, challenger specialist, value/OEM supply, and platform-integrated device partnerships.
-
Regulatory and reimbursement maps with timing assumptions and risk buffers to accelerate launch approvals and payer contracting.
-
Supplier and cost structure benchmarks focused on cushion materials, headgear sourcing, and high-volume manufacturing levers.
-
M&A and partnership target shortlists with acquisition valuation frameworks and integration checklists tailored for 2026 deal pacing.
-
Clinical adoption levers and patient adherence frameworks—translating mask design and comfort features into measurable adherence uplift and downstream device utilization.
Recommended actions for leadership teams in 2026
The following strategic actions distill our analysis into immediate next steps for companies looking to capture disproportionate share of the forecast growth:
-
Prioritize regulatory sequencing: align 510(k) or equivalent filings with parallel clinical-use studies to shorten commercialization cycles, particularly if targeting institutional channels.
-
Invest in compatibility partnerships: ensure mask designs are interoperable with AI-enabled therapy features from major device OEMs to avoid exclusion from integrated ecosystems.
-
Optimize supplier base for silicone cushions: secure biocompatible material supply and dual-sourcing plans to mitigate cost and availability risks.
-
Map reimbursement timing and documentation: build HCPCS-aligned product lifecycles and replacement plans into commercial contracts to protect unit economics.
-
Segment route-to-market: deploy differentiated routes (direct for premium platforms, distributors for mid-market, OEM supply for scale) rather than a one-size-fits-all distribution model.
-
Consider bolt-on M&A for rapid feature acquisition (e.g., headgear technology, AI comfort algorithms) instead of multi-year internal development for near-term market access.
-
Document adherence economics: quantify how small improvements in seal and comfort translate into measurable increases in therapy compliance and downstream device revenue.
Why PW Consulting’s approach reduces strategic execution risk
Our methodology blends time-series market modeling with primary interviews across clinicians, procurement officers, and payor representatives, producing high-confidence forecasts and executable commercial plans. Importantly, while we present overall market size and concentration metrics to guide portfolio sizing and capital allocation, the report intentionally withholds granular public disclosure of proprietary subsegment splits in this release—those detailed segmentation tables, regional builds, and customer-level insights are included in the full report to support transaction-level diligence.
Next steps and how to use this study
For boards, this report serves as an input to 2026 capital allocation decisions: whether to greenlight product investments, pursue M&A, or shift distribution strategies. For commercial teams, the implementation playbooks provide immediate templates for payer engagement and channel rollout. For R&D leaders, the product-pricing-supplier nexus in the report helps prioritize features that materially improve adherence while protecting margins.
PW Consulting invites decision-makers to access the full report for the detailed segmentation tables, regional and application breakdowns, and our proprietary scenario models that underpin the revenue forecasts. The complete dataset and executable annexes are designed to be directly reusable in strategic planning, investment memos, and transaction diligence.
Conclusion
The Sleep Apnea Masks market offers predictable growth and concentrated competitive structures that reward focused strategic moves in 2026. Companies that synchronize regulatory strategy, evidence generation, supply resilience, and channel design will capture the bulk of the opportunity. PW Consulting’s study is structured to turn these insights into executable plans—download the full report to see the proprietary subsegment data, calibrated scenarios, and operative templates that will make your 2026 choices decisive.
For detailed analysis of this topic, please visit the official page: Sleep Apnea Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luciferase Assay Market to Expand from USD 620.0M (2025 base) to ~USD 992.3M by 2032 at 6.95% CAGR — North America, Reporter Gene Assays and Drug Discovery Drive Growth as Top 3 Hold 42.5%
By pmarketresearch, 2026-07-01
Luciferase Assays 2026: Strategic Imperatives from PW Consulting’s Market Brief
Why this report matters for executive decisions in 2026
As life-science stakeholders recalibrate R&D portfolios and commercialization roadmaps for the post-pandemic era, an evidence-based understanding of assay markets has become a strategic necessity. PW Consulting’s Luciferase Assay Market brief — based on a 2025 base year, a 2020–2025 historical window, and a 2026–2032 forecast horizon — provides precisely that. The global market is projected to continue growing at a compound annual growth rate (CAGR) of 6.95%, with an estimated overall market size in 2025 of USD 620.0 Million and a credible pathway to nearly USD 1.0 Billion by the end of the forecast period. For R&D leaders, product managers, corporate development teams, and investors, these topline dynamics translate into very concrete choices about where to allocate capital, when to accelerate product launches, and how to structure partnerships to capture high-value, high-growth niches.
Luciferase Assay Market
Executive summary — strategic takeaways
- Market momentum is solid but selective: steady mid-single-digit CAGR signals predictable growth but also intensifying competition among established kit and reagent suppliers.
- Innovation is bifurcating value chains: advanced luciferase chemistries and two-color bioluminescence modalities are redefining sensitivity, multiplexing and imaging use cases — creating differentiation opportunities for first movers.
- Commercial strategy must be granular: go-to-market decisions (direct sales vs distribution, reagent commoditization vs premium platforms, and RUO positioning) will determine margin profiles and longer-term stickiness.
- Regulatory footprint remains limited: luciferase assays are predominantly research-use-only (RUO), shaping adoption patterns in clinical workflows and licensing conversations.
What the PW Consulting brief delivers — practical, actionable intelligence
Designed as a decision-support tool rather than an academic exercise, the report combines quantitative forecasts with hands-on frameworks that operational teams can apply immediately. Key deliverables include:
Luciferase Assay Market
- Topline market model and scenario analyses reflecting base, upside and downside demand conditions through 2032 (with sensitivity to pricing, reagent cycle times and HTS adoption rates).
- Competitive mapping and capability benchmarking for the major vendors active in luciferase assays and adjacent luminescence solutions.
- An assay-technology adoption matrix that links assay performance attributes (sensitivity, dynamic range, multiplex capability, and instrument dependency) to buyer personas in academia, biotech and pharma.
- A procurement and validation playbook for end-users — supplier selection criteria, assay validation checklists, and operational KPIs for lab managers scaling HTS operations.
- Commercial and M&A playbooks — acquisition target profiles, partnership archetypes, and valuation heuristics relevant to corporates and PE investors seeking exposure to this subsector.
Competitive landscape — who matters and why
The luciferase assay space is a mix of global life-science platform players, specialized assay innovators and agile reagent houses. Market concentration indicates leading vendors hold a meaningful combined share of the market, yet the landscape remains contestable due to technology-led disruption. PW Consulting’s assessment emphasizes differentiated competitive moats rather than raw market share alone.
Luciferase Assay Market
- Promega Corporation (Madison, WI, USA) : A recognized leader in reporter systems with deep product breadth spanning NanoLuc and dual-reporter platforms. Recent product signaling — notably the April 2026 presentation of a red‑shifted luciferase (“NanoPrism”) and two‑color bioluminescence workflows — underscores Promega’s strategy to expand applications in multiplexed readouts and imaging-centric use cases.
- Thermo Fisher Scientific Inc. (Waltham, MA, USA) : A platform incumbent offering a broad luciferase kit portfolio that benefits from scale, instrument integration, and global reach — an attractive partner for organizations seeking bundled solutions and standardized protocols.
- Revvity Inc. (formerly PerkinElmer; Waltham, MA, USA) : Focused on high-throughput formats and automation-friendly reagents; a strong contender for customers prioritizing throughput and robotics compatibility.
- Biotium Inc. (Fremont, CA, USA) : A value-and-performance player targeting cost-sensitive researcher segments with optimized single-tube and dual assays.
- Abcam plc (Cambridge, UK) and Merck KGaA / MilliporeSigma (Darmstadt, Germany) : Both supply luciferase substrates and complementary tools within larger reagent portfolios; their strength is in channel breadth and cross-selling into established reagent relationships.
For decision makers, the central question is less “who is on top?” and more “which vendor profile aligns with my strategic aim?” — whether that is to capture premium, differentiated assay performance, to secure high-volume, low-cost reagents, or to embed luciferase assays within broader instrument–consumable ecosystems.
Technology and innovation dynamics to watch in 2026
- Red-shifted and dual-emission systems. New chemistries and engineered luciferases that expand spectral separation and increase tissue-penetrating signal are unlocking imaging and in vivo applications previously limited by blue-shifted light outputs.
- Two-color bioluminescence and multiplexing. The ability to run orthogonal reporter measurements in single wells accelerates screening efficiency and reduces reagent and sample use — a clear value driver for HTS-focused customers.
- Integration with digital readouts and AI-based signal processing. Enhanced software packages that deconvolute overlapping signals and correct for instrument drift are becoming as important as reagents in delivering reliable results.
Regulatory and market-access context
It is important to emphasize: luciferase assay kits remain primarily designated as research-use-only (RUO). This classification constrains direct entry into diagnostic pathways and means that clinical lab adoption will continue to require translational validation programs or companion diagnostic strategies. For commercial teams, RUO status influences labeling, marketing, reimbursement expectations and the pace at which assays can be embedded into regulated clinical workflows.
Strategic plays for 2026 — recommended moves by PW Consulting
Based on the report’s modeling and company-by-company analysis, we recommend that organizations consider the following prioritized actions in 2026:
- Product strategy: Prioritize investment in platform features that reduce total cost-of-experiment for customers (multiplexing, miniaturization, and reagent stability). Products that demonstrably shorten time-to-answer command pricing power.
- Go-to-market segmentation: Differentiate messaging and distribution by buyer persona — academic core labs, discovery groups in mid‑sized biotech, and enterprise pharma HTS teams — rather than using a one-size-fits-all approach.
- Partnerships and integrations: For firms without instrument footprints, pursue co-development agreements with plate-reader and imaging OEMs to embed assay chemistries as preferred workflows; conversely, instrument vendors should secure exclusive reagent partnerships to lock in consumable revenue streams.
- M&A and corporate development: Buyers should hunt for targets that bring either novel luciferase chemistries (e.g., red-shifted reporters) or data‑centric software that improves signal fidelity — both of which materially impact customer switching costs.
- Operational resilience: Strengthen supply chain flexibility for critical substrates and enzymes and design redundancy into raw material sourcing to avoid costly stockouts which damage customer trust.
How the report supports implementation
The brief is constructed to move readers from insight to action. Each strategic recommendation is paired with a tactical implementation appendix that contains:
- Vendor selection scorecards and procurement timelines;
- Validation SOP templates and acceptance criteria for assay performance;
- Commercial KPIs to monitor adoption, churn and channel effectiveness;
- Deal checklists for M&A diligence focused on IP robustness, manufacturability and regulatory positioning.
Market concentration and competitive intensity
Our concentration analysis shows that leading firms capture a meaningful portion of the market revenue pool, reflecting consolidation around platform capabilities and distribution strength. However, pockets of opportunity persist for focused innovators — particularly those that offer demonstrably superior assay sensitivity, multiplexing or imaging compatibility. The market is therefore amenable to both scale plays and targeted technology-led entrants.
Final perspective — the strategic clock is ticking
As the market grows at a mid-single-digit CAGR, the absolute opportunity is significant but will be claimed by organizations that move early on technological differentiation, tighten commercial segmentation and align operational models to the realities of RUO designation. PW Consulting’s Luciferase Assay Market brief offers the analytical underpinnings and actionable playbooks to support those decisions — while intentionally withholding granular subsegment tables and certain proprietary splits to protect the report’s full strategic value.
Next step
For executives and investors seeking the complete dataset, detailed segmentation tables, vendor scorecards and the full implementation playbook, consult the full Luciferase Assay Market report on PW Consulting’s website. Our team is also available to run custom scenario modeling or to lead a half‑day strategy workshop tailored to your portfolio and commercial objectives.
For detailed analysis of this topic, please visit the official page: Luciferase Assay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Suppository Base Market to Climb from USD 650.0 Million in 2025 to USD 945.54 Million by 2032, Backed by a 5.5% CAGR
By pmarketresearch, 2026-07-01
Suppository Base Market: Strategic Imperatives for 2026 — PW Consulting Insights
As global pharmaceutical manufacturers, compounding pharmacies, and specialty excipient suppliers plan budgets and M&A strategies for 2026, a clear, actionable view of the suppository base market becomes a critical enabler of competitive advantage. PW Consulting’s newest market research — anchored on a 2025 base year, informed by 2020–2025 historical dynamics, and forecasting through 2032 — synthesizes commercial, regulatory, and technical intelligence into a decision-grade resource. Our top-line macro model identifies steady expansion with a compound annual growth rate of 5.5% across the forecast window, positioning the market for meaningful strategic moves in the coming 12–18 months.
Suppository Base Market
Market Snapshot: Macro Trajectory and What It Means
The suppository base market has shown resilient growth through the early 2020s, driven by forces including sustained demand from therapeutic categories suited to rectal and vaginal delivery, steady activity among compounding pharmacies, and ongoing product innovation from established excipient manufacturers. By our 2025 base year the global market reached the mid-hundreds (USD, million). The model projects continued growth into 2026 and beyond, consistent with a 5.5% CAGR for the forecast period, with intermittent acceleration tied to regulatory clarifications, supply-chain normalization, and targeted product launches.
Suppository Base Market
- Growth drivers: aging populations in established markets, expanded chronic-disease management programs that favor alternate routes of administration, and stable compounding demand for individualized therapies.
- Constraining factors: raw-material sourcing volatility for hard fat bases, regulatory scrutiny around excipient provenance, and margin pressure among distributors and compounding intermediaries.
- Market rhythm: periods of inventory restocking and catalog refreshes by major suppliers create windows for commercial negotiation and tactical sourcing shifts.
Why 2026 Is a Strategic Inflection Point
Several converging dynamics make 2026 a year when senior leaders should convert strategic options into executable plans:
Suppository Base Market
- Regulatory cadence: Documented compliance pathways (for example, European Pharmacopoeia recognition of certain hard fats and USP references for common bases) reduce technical uncertainty but raise the bar on documentation, supplier audits, and change control.
- Supplier consolidation and differentiation: Suppliers continue to sharpen portfolios around hard fats, PEG blends, and specialty bases for mucosal tolerance and drug dispersion. Visible catalog updates and marketing pushes from incumbent vendors emphasize quality and GMP pedigree — attributes buyers will increasingly pay for.
- Supply-chain risk: Raw material sourcing (notably vegetable-derived saturated fatty acids) remains exposed to agricultural inputs and regional logistics; strategic inventory, dual-sourcing, and supplier assurance programs will materially reduce interruption risk.
- Commercial optimization: With overall market growth modest but steady, winning companies will prioritize product-service bundles, formulation support, and certification-backed premium positioning rather than competing on commodity pricing alone.
What the PW Consulting Report Delivers — Practical, Executable Insight
Our report is built as a toolset for decision-makers, not an academic exercise. Key deliverables include:
- Top-line market model: A transparent macro-level sizing and a model you can flex under alternative scenarios (price shocks, regulatory events, raw-material shortages).
- Segment-level thesis without gratuitous giveaway: We map the market by route, base type, and region in a way that highlights where growth and margin expansion opportunities lie while reserving full granular figures for the full report to preserve strategic value.
- Supplier due-diligence framework: A checklist and scoring model to evaluate GMP compliance, inspection history, product-grade registration, and commercial reliability.
- Formulation selection matrix: Practical guidance for selecting base families (hard fats, PEG systems, synthetic blends) against product attributes such as melting behavior, active compatibility, mucosal tolerance, and cold-chain needs.
- Regulatory playbook: Mapping to pharmacopoeial requirements and jurisdictional nuances, with a prioritized list of compliance tasks for market access and quality audits.
- Commercial playbook: Pricing levers, contract structures, inventory strategies, and partnership archetypes tailored to manufacturers, distributors, and compounding pharmacies.
- M&A and partnership radar: High-level criteria and a shortlist of capability gaps that create acquisition interest; detailed target profiles and financial multiples are included in the full report.
Competitive Landscape — Strategic Profiles of Core Players
The market displays a mix of global excipient specialists, compounding-focused suppliers, and regional formulators. Our competitive mapping highlights capability clusters rather than just brand names, enabling buyers to align supplier selection with strategic priorities.
- IOI Oleo GmbH (Hamburg): A long-established producer of hard fat bases with recognized grades such as WITEPSOL®. IOI emphasizes GMP-certified production, a broad registered-grade catalog, and compliance with major pharmacopoeias. Recent catalog refresh activity reinforces a strategy to anchor premium hard-fat supply through documentation and multiple registered grades tailored to suppository and ovule applications.
- Medisca (Montreal/US operations): A distribution and compounding-focused supplier promoting both classic and “natural” suppository bases. Medisca’s pathway centers on availability for compounding pharmacies and clear product positioning for pharmacy-grade supply chains; recent promotional efforts underscore channel-focused commercialization.
- PCCA (Houston): Deeply embedded in the compounding community, PCCA offers proprietary bases and support services. Their competitive advantage is a blend of brand loyalty among independent compounding pharmacies and technical service that reduces formulation risk for users.
- SpecializedRx (USA): Positions itself on accessibility for compounding and a selection of proprietary blends. The supplier model focuses on product breadth and channel convenience.
- Gattefossé (France) and Croda Pharma (UK): Both bring formulation science and excipient expertise, with product development geared to drug dispersion, mucosal compatibility, and stability. These players are natural partners for pharmaceutical companies seeking co-development and validated excipient solutions.
Strategic takeaway: incumbent excipient manufacturers maintain technical leadership through registered grades and GMP messaging, while compounding-focused suppliers differentiate through channel reach and formulation support. Buyers should not evaluate suppliers on price alone — certification, batch-release robustness, and co-development capabilities are decisive procurement criteria.
Strategic Playbook: What Winning Looks Like in 2026
Across manufacturers, suppliers, and investors, a coherent set of actions will separate winners from followers:
- Manufacturers of finished dosage forms: Prioritize excipient qualification pathways now. Invest in early formulation compatibility studies and secure second-source agreements for critical base families to mitigate supply interruptions.
- Excipient suppliers: Differentiate through documented GMP pedigree, grade diversity, and formulation support. Consider modular service offers (e.g., small-batch custom blending, compounding kits) to capture higher-margin adjacent revenue.
- Compounding pharmacies and distributors: Leverage supplier partnerships to reduce inventory burdens while securing priority access to high-demand grades; demand traceability and certificate-of-analysis (CoA) standards that align with downstream regulatory scrutiny.
- Private equity and strategic investors: Look for targets that combine technical IP (novel base blends or dispersion technologies) with channel access to compounding markets. Pay special attention to companies with validated GMP operations and documented inspection histories.
- Risk management: Implement a raw-material watchlist tied to supplier audit schedules, and build scenario-based inventory models into procurement planning for 2026.
Methodology, Data Integrity, and Where to Find the Granular Intelligence
Our analysis synthesizes primary supplier documentation (including recent catalog and product updates), public regulatory standards (e.g., European Pharmacopoeia and USP references), company disclosures, and interviews with formulation scientists and procurement leads across the value chain. Recent public developments — such as IOI Oleo’s product brochure update and Medisca’s market availability announcements — were validated and contextualized within our commercial model.
PW Consulting’s forecast and scenario outputs are presented with transparent assumptions, sensitivity testing, and a reproducible financial model. To adhere to best-practice competitive disclosure and to preserve the commercial value of the full dataset, we present macro-level sizing and trend analysis in this release while withholding full segment-by-region and detailed application-by-type breakdowns. Those granular splits, including the full regional and application matrices and supplier-share tables, are available in the complete report package on our website.
How to Use This Intelligence in Q1–Q2 2026
- Immediate actions (0–3 months): Run supplier qualification audits against our due-diligence checklist; secure short-term dual-source agreements for hard-fat grades; request CoAs and GMP evidence from key vendors.
- Near term (3–9 months): Execute formulation compatibility studies using prioritized base candidates; model price / margin sensitivity under alternate raw-material scenarios; negotiate commercial terms that include service-level guarantees for critical grades.
- Medium term (9–18 months): Lock in strategic partnerships or bolt-on acquisitions that close capability gaps (e.g., co-development of improved dispersion bases) and integrate excipient supply into product development roadmaps for new dosage forms.
Concluding Perspective
The suppository base market is neither a large-scale growth story nor a static commodity market — it is a steady, technically nuanced sector where regulatory provenance, supplier reliability, and formulation expertise determine commercial outcomes. For decision-makers charting strategy in 2026, the choice is clear: act now to secure certified supply, invest selectively in formulation capability, and use M&A or partnership plays to obtain technical differentiation. PW Consulting’s full report provides the granular charts, regional and application splits, supplier share estimates, and a downloadable financial model needed to operationalize these strategic moves.
For access to the full dataset, segment breakdowns, and our interactive scenario model, please visit the PW Consulting report page and request the Suppository Base Market full report. The detailed intelligence within that package is designed to support board-level decisions and tactical procurement plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Suppository Base Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Home Pet Deworming Market to Reach USD 4,975.99 Million by 2032 on a 6.75% CAGR
By pmarketresearch, 2026-07-01
Home Pet Deworming Medicine Market: Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market intelligence on the Home Pet Deworming Medicine market maps a commercially significant, resilient category that is entering its next phase of growth and structural reconfiguration. Our analysis shows the market expanding from a historical base of approximately USD 2.27 billion in 2020 to roughly USD 3.15 billion in 2025, with a projected compound annual growth rate (CAGR) of 6.75% over the 2026–2032 forecast window. Under that baseline trajectory the market is on course to approach USD 5.0 billion by 2032, implying sustained demand for both prescription-adjacent and over‑the‑counter pet deworming solutions.
Home Pet Deworming Medicine Market
This briefing is a strategic “trailer”: it surfaces the near-term commercial implications and executive actions that matter for 2026, demonstrates the analytical depth of the full report, and deliberately withholds granular segment-level tables and precise sub‑regional shares to encourage acquisition of the source report for detailed decision-making inputs.
Home Pet Deworming Medicine Market
Why this matters for 2026 — the executive takeaways
- Structural growth with tactical inflection points. The macro expansion underpins continued investment appetite: larger incumbents and challenger brands have room to grow through product line extensions, channel penetration, and formulation innovation. However, growth is uneven across modalities and geographies, and 2026 will be a year when selective investment decisions — not blanket scale-ups — generate value.
- Margin pressure from generic entrants and API sourcing. The advent of additional generic fenbendazole options and concentrated API production in Asia is resetting cost and pricing dynamics. Firms that secure resilient supply chains and flexible pricing strategies will protect margins and commercial momentum.
- Regulatory and labeling momentum affects go-to-market timing. FDA activity in recent quarters has influenced product availability and OTC labeling expectations; regulatory rhythm will determine timing for launches, relaunches, and promotional campaigns.
- Channel and care model evolution. The continuum from veterinary clinics to retail and e-commerce is becoming more fluid. Brands that align product formats, packaging, and messaging to channel-specific purchase triggers will capture higher lifetime value per pet.
Market dynamics shaping 2026 strategies
Several convergent forces are reshaping the competitive playing field:
Home Pet Deworming Medicine Market
- Persistent pet health demand: Companion animal ownership and preventive care penetration remain core demand engines. Pet owners increasingly view deworming as a routine component of wellness, creating recurring purchase behavior that favors multi-dose and palatable formats.
- Product format differentiation: While multiple delivery formats coexist, formulation convenience (palatability, single-dose effectiveness), safety labeling, and perceived value influence both channel acceptance and repeat purchase. R&D and packaging investments that improve user experience can deliver disproportionate returns.
- Supply-side economics: API concentration in parts of Asia—particularly for fenbendazole—has created a cost-advantaged supply base but also heightens geopolitical and quality-control risk. Manufacturers and private-label partners should reassess supplier diversification and qualification strategies in 2026.
- Regulatory catalysts: Recent approvals and emergency authorizations show regulators are actively engaged in the companion animal parasiticide space. These actions affect timing, labeling, and the competitive landscape for both prescription and OTC products.
Regulatory and industry events — implications for 2026
- New generic approvals accelerate price competition. The January 2026 FDA approval of a generic fenbendazole oral suspension highlights a trend: established chemical classes are becoming accessible to lower-cost manufacturers. Expect margin compression in categories where generics can replicate efficacy and labeling.
- Targeted emergency authorizations influence tactical response. Recent emergency use activity in late 2025 underscores how episodic regulatory actions (e.g., for emergent parasitic threats) can create short‑term procurement needs and reputational opportunities for market participants with pre‑cleared products.
- Labeling and OTC compliance remain non-negotiable. Home-use dewormers must adhere to approved labeling and clear usage instructions. Companies that preemptively optimize label clarity and consumer education reduce adverse events, OTC recalls, and reputational risk.
Competitive landscape — who to watch and why
The market remains led by established animal-health multinationals and a cohort of specialized veterinary pharmaceutical firms. Market concentration metrics show a moderate level of aggregation: the top three firms hold a meaningful portion of market value, and the top five consolidate an even larger share—creating both barriers and partnership opportunities for mid‑sized players.
- Zoetis (Parsippany, NJ) — A global leader with an extensive companion animal portfolio. Zoetis’s product set includes well‑established liquid formulations for puppies and dogs; its strengths are brand recognition, veterinary channel penetration, and scale manufacturing.
- Merck Animal Health (Rahway, NJ) — Known for broad-spectrum chemistries, Merck competes on proven efficacy and channel trust. Its established canine dewormer positions it well for clinical recommendations and bundled preventive care offerings.
- Elanco (Greenfield, IN) — Combines an aggressive commercial footprint with recent regulatory engagement. Its chewable and specialty offerings make Elanco a versatile competitor across retail and clinic channels.
- Virbac (Fort Worth, TX) — Focused on palatable chewables and targeted formulations; Virbac emphasizes product differentiation through flavoring and ease-of-administration for pet owners.
- PetIQ (Eagle, ID) — A retail-focused challenger with strong over‑the‑counter positioning and private-label agility; PetIQ competes on value and mass channel reach.
- Boehringer Ingelheim, Ceva, Dechra — These regional and global players augment the market through veterinary networks and niche product portfolios, often serving as innovation partners or acquisition targets.
- Central Garden & Pet (Farnam) and Durvet — Players with established OTC and farm-to-pet channels that can leverage distribution to scale companion animal formulations rapidly.
Collectively, incumbents combine brand trust, clinical trial data, and channel partnerships. Newer or niche entrants must therefore compete on either price (leveraging lower-cost APIs), user experience (palatability, dosing simplicity), or channel innovation (direct-to-consumer subscription models, vet telehealth integration).
What the PW Consulting report delivers — practical, transaction-ready outputs
Our full report is designed for commercial and corporate teams planning 12–36 month initiatives. Key practical deliverables include:
- Proprietary market-sizing models with historical validation (2020–2025) and scenario-based forecasts to 2032, including sensitivity analysis around API cost shocks and regulatory disruptions.
- Channel economics and go‑to‑market playbooks tailored to veterinary clinics, retail chains, e-commerce, and hybrid subscription models; recommended promotional mixes by channel archetype.
- Product positioning matrices that map efficacy, convenience, and price-to-value for chewables, spot-on treatments, and oral suspensions — coupled with SKU rationalization guidance for portfolio managers.
- Supply-chain risk heatmaps and a supplier‑segmentation framework reflecting API concentration, lead time risk, and quality-control checkpoints; actionable supplier diversification options.
- M&A and partnership screening tools: a short list of capability gaps where bolt‑on acquisitions or co‑development agreements can accelerate time‑to‑market, with payback scenarios.
- Regulatory playbook summarizing labeling requirements, filing timelines, and contingency plans for emergency authorizations or rapid approvals.
Strategic recommendations for 2026
- Prioritize supply resilience over lowest-cost sourcing. Given API concentration and recent generic entries, build dual sourcing, buffer inventory strategies, and supplier audit schedules into 2026 procurement plans.
- Segment products by customer journey, not just formulation. Design packaging, dosing guidance, and digital instruction flows that reduce perceived complexity for first-time pet owners and increase adherence in recurring purchasers.
- Be prepared for accelerated generic competition. Where chemical classes are off‑patent, protect margins through branded value propositions (convenience, palatability, vet endorsement) rather than head‑to‑head price confrontation.
- Leverage regulatory milestones as commercial catalysts. Monitor approval pipelines and emergency-use authorizations closely; align marketing and distribution ramp plans to regulatory timing to capture capture-to-market windows.
- Invest selectively in channels with data feedback loops. Digital and subscription channels that generate owner adherence and repeat purchase data create durable competitive advantage; prioritize pilots that can be scaled quickly.
- Use M&A selectively to fill capability gaps. Consider acquiring regional manufacturing or formulation capabilities that shorten lead times and reduce supply risk, or select brands that bring differentiated consumer trust in key markets.
Methodology note and data provenance
The report synthesizes company filings, regulatory databases, proprietary surveys of veterinarians and pet owners, trade-channel scans, and primary supplier interviews. Our forecasting applies scenario-based modeling to historical sales (2020–2025) and applies a 6.75% CAGR baseline for 2026–2032, with downside and upside variants reflecting API cost shocks and accelerated generic penetration. For confidentiality and strategic clarity, this public preview omits the granular tables, regional splits, and SKU-level forecasts that are included in the full dataset.
Next steps — how to use this intelligence in 2026
For executive teams preparing 2026 plans, the full PW Consulting Home Pet Deworming Medicine Market report provides the actionable inputs needed to:
- Build 12–36 month product and channel roadmaps supported by detailed financial models;
- Structure supplier contracts and inventory buffers to mitigate API concentration risk;
- Design launch sequences aligned to regulatory windows; and
- Screen M&A targets and JV partners with quantifiable payback thresholds.
If your team seeks a compact strategic workshop or a tailored version of the dataset (e.g., custom country-level demand curves, SKU P&L templates, or due-diligence checklists), PW Consulting can deliver modular deliverables aligned to board and investor decision calendars.
Call to action
This preview exposes the strategic inflection points that will define winners and laggards in 2026. To access the full segmentation tables, country and channel breakdowns, company scorecards, and the downloadable Excel model that underpins our forecasts, please consult the full Home Pet Deworming Medicine Market report on the PW Consulting website or contact our industry practice. The complete dataset contains the granular inputs required to translate the insights above into executable plans and financial commitments.
For detailed analysis of this topic, please visit the official page: Home Pet Deworming Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.5% CAGR for Jewelry Beads Market (2026–2032)
By pmarketresearch, 2026-07-01
Jewelry Beads Market 2026 Strategic Outlook — Why PW Consulting’s New Report Is a Decision-Maker’s Playbook
As buyers, manufacturers, and investors prepare budgets and strategic roadmaps for 2026, the jewelry beads market presents a blend of steady growth, structural change, and margin pressure that requires deliberate, data-backed responses. PW Consulting’s latest Jewelry Beads Market report (base year 2025) synthesizes a seven-year historical lens (2020–2025) with a seven-year forecast horizon (2026–2032), quantifying market dynamics and translating them into actionable decisions. The global market stood at USD 2,150 Million in 2025 and — under our base-case assumptions — resumes growth at a compound annual growth rate (CAGR) of 5.5% through 2032, reaching roughly USD 3,128 Million in 2032. This release is purpose-built to guide 2026 investment, sourcing, and product strategies.
Jewelry Beads Market
Why this matters for 2026 planning
- Predictable overall growth, uneven pockets of opportunity. After the pandemic-related shock and a period of volatility in the early 2020s, the market has stabilized into a mid-single-digit growth corridor. That macro consistency creates a reliable top-line backdrop for capital allocation — but the value will accrue disproportionately to firms that capture margin improvements and supply-chain optionality.
- Fragmented competitive structure that favors focused scale. The market concentration is low: the three largest firms account for under one-fifth of global value, and the top five capture less than a quarter. That fragmentation preserves opportunities for niche leaders, private-label play, and vertically integrated players to expand via targeted investments.
- Cost pressure vectors are identifiable and actionable. Energy cost increases for glass production, tariff uncertainty on certain origins, and tightening hazardous-material limits for jewelry components are the primary cost and compliance levers through 2026.
Data-driven takeaways for executives
- Prioritize SKU rationalization and value segmentation. With overall growth modest but consistent, the quickest uplift to margin comes from rebalancing assortments toward premium and differentiated beads (precision-cut crystals, premium seed beads, specialty gemstones) while pruning low-margin commodity SKUs.
- Hedge sourcing with multi-origin strategies. Given current tariff dynamics and sourcing risks tied to specific origins, adopt a dual- or tri-source model for critical inputs to reduce single-origin exposure and maintain negotiating leverage.
- Invest selectively in upstream integration. The fragmented market rewards firms that internalize key value-chain steps (e.g., precision finishing, specialty coatings, proprietary color ranges) that command price premiums and improve quality control.
- Operationalize regulatory compliance as a commercial differentiator. Compliance with cadmium and lead limits (including region-specific restrictions) is a baseline expectation for B2B and consumer channels — firms that can demonstrate robust testing, certifications, and transparent supply chains capture procurement preference.
- Leverage digital channels and community marketing. DIY and maker communities continue to drive demand in jewelry-making and fashion accessories; allocating marketing and fulfillment resources to these channels yields higher lifetime value and brand loyalty.
What the PW Consulting report delivers (practical, executable items)
- Comprehensive market model: A downloadable financial model with historical series (2020–2025) and baseline, upside, and downside scenarios for 2026–2032. The model is parametrized for price, volume, and input-cost shocks so users can run bespoke sensitivity tests.
- Go-to-market playbooks: Channel-specific playbooks for wholesale distribution, direct-to-consumer, kits and tutorials, and OEM partnerships — each with KPI frameworks, sample P&L impacts, and rollout roadmaps.
- Cost and margin diagnostic: Line-item cost builds for glass, crystal, metal, plastic/acrylic and gemstone beads, incorporating recent energy-cost trends and tariff exposures to inform pricing, promo cadence, and supplier contracts.
- Regulatory & compliance pack: Practical checklists and supplier audit templates addressing cadmium, lead, and surface-coating limits that are now standard expectations in major markets; includes recommended lab-testing frequency and sample QA language for contracts.
- M&A and partnership shortlist: A curated list of acquisition targets and strategic partners segmented by capability (manufacturing scale, specialty finishes, distribution reach), accompanied by valuation heuristics and integration risks.
- Risk matrix and contingency playbooks: Playbooks for tariffs, energy-price shocks, and logistic disruptions, with decision triggers that counsel when to renegotiate suppliers, raise prices, or accelerate product transitions.
Competitive landscape: what incumbents and challengers are doing
The competitive set is diverse, ranging from premium crystal specialists to high-volume wholesalers and vertically integrated manufacturers. Key companies profiled in the report include:
Jewelry Beads Market
- Fire Mountain Gems and Beads (Grants Pass, Oregon, USA; https://www.firemountaingems.com) — A large U.S.-based distributor with deep e-commerce and catalog capabilities. Strengths include assortment breadth and fulfillment scale; their challenge is protecting margins in commoditized categories while building exclusives.
- Preciosa Ornela (Zásada, Czech Republic; https://www.preciosa-ornela.com) — A lead player in Czech glass seed beads with strong heritage and color-trend leadership; their seasonal trend releases and manufacturing backlog can set design cycles for downstream customers.
- MIYUKI Co., Ltd. (Japan; https://www.miyuki-beads.co.jp/english/) — Synonymous with precision seed beads, Miyuki’s value is quality and consistency, enabling premium artisans and designers to command higher prices.
- Swarovski AG (Austria; https://www.swarovski.com) — The premium crystal lens for jewelry applications. Swarovski’s brand strength and technical finishing create durable pricing power for precision-cut crystal beads.
- PandaHall (China; https://www.pandahall.com) — High-volume wholesale and one-stop supplier model, important for cost-sensitive channels and fast-turn assortments.
- BeadKraft, Shipwreck Beads, PotomacBeads — U.S.-based specialists that have successfully blended curated assortments with community engagement and tutorial-driven commerce.
Recent industry activity in 2026 underscores market dynamics: trade shows and seasonal trend releases continue to shape demand (notably new color collections and designer collaborations), while procurement sensitivity to tariffs and energy-cost-driven supplier price actions has increased negotiation intensity. Our report synthesizes how these moves affect product cycles and channel economics.
Jewelry Beads Market
Regulatory and trade considerations that affect 2026 choices
- Materials compliance is non-negotiable. Jurisdictional limits on heavy metals in jewelry components now shape sourcing and product design. Buyers need to codify testing and supplier attestations into contracts to avoid recalls and reputational damage.
- Tariffs and origin risk influence sourcing decisions. Import duties on certain bead categories and periodic tariff actions on goods from particular origins create short-term cost variability; incorporate tariff-scenario funds into procurement planning.
- Energy and production-cost volatility. Facilities relying on energy-intensive glass production faced notable cost increases recently — an operational risk that can compress margins unless passed through or mitigated by efficiency upgrades.
Prioritized 90–180 day playbook for 2026
- 90 days: Run the PW Consulting model using your own SKU and supplier data; identify 10 SKUs to delist and 10 SKUs to premiumize. Demand a compliance certificate pack (test results + supplier attestation) from your top 10 suppliers.
- 180 days: Negotiate dual-sourcing contracts for high-risk inputs; pilot a premium-bead capsule with controlled marketing spend; implement a quarterly tariff-impact review tied to procurement approvals.
- 6–18 months: Evaluate small-scale vertical integration (e.g., finishing/coating capacity) or targeted M&A to secure differentiated product capabilities and shorten lead times.
Methodology, confidence, and what we intentionally withhold
PW Consulting’s estimates combine bottom-up supplier and channel surveys, customs and trade flows, price-tracking of commodities and finished beads, and validation interviews with manufacturers, distributors, and design houses. The report includes a transparent, scenario-based forecast framework and stress-tested sensitivity models. To honor the “trailer” principle and channel readers to the full report, we have deliberately not published granular segmentation tables and region/application-level share dashboards in this press release. The full report contains detailed splits by region, material type, and application; supplier-level concentration maps; and downloadable model files for client customization.
Next steps
If your organization is planning supply-chain moves, product-line pivots, or M&A activity in 2026, PW Consulting’s Jewelry Beads Market report offers the quant tools, competitive intelligence, and compliance playbooks you need to act with conviction. For an executive briefing, live model walkthrough, or to license the full dataset and segment-level projections, contact PW Consulting to schedule a tailored advisory session.
For detailed analysis of this topic, please visit the official page: Jewelry Beads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Diabetes Telemedicine Technology Market to Grow at a 13.5% CAGR Through 2032
By pmarketresearch, 2026-07-01
Diabetes Telemedicine Technology Market: Strategic Imperatives for 2026
PW Consulting’s latest market insight – Diabetes Telemedicine Technology Market – frames 2026 as the year when digital diabetes care transitions from programmatic experimentation to scalable clinical and commercial execution. The market has moved from niche pilots to mainstream deployment: our base-year calibration places the global market at roughly USD 5.65 billion in 2025, with a near-term uplift to about USD 6.82 billion in 2026 and a compound annual growth rate of 13.5% across the 2026–2032 forecast horizon, culminating in a market north of USD 13.7 billion by 2032. This growth trajectory is being driven by reimbursement shifts, device-platform convergence, and a maturing evidence base — factors that will shape board-level choices in 2026.
Diabetes Telemedicine Technology Market
Why 2026 is an Inflection Point
-
Reimbursement realignment: The extension of Medicare telehealth flexibilities and the introduction of new remote patient monitoring (RPM) codes create clearer revenue pathways for continuous remote diabetes management. These policy moves materially reduce commercial uncertainty for technology vendors and clinical providers planning scale‑up in 2026.
Diabetes Telemedicine Technology Market -
Product and integration momentum: Device vendors and platform players are shipping integrated solutions that blur the lines between hardware and software. Recent regulatory and product milestones illustrate this: manufacturers are securing clearances for integrated sensor–pump solutions and launching multi‑parameter remote monitoring devices focused on complication prevention.
Diabetes Telemedicine Technology Market -
Consolidation pressure and concentration: As adoption scales, commercial markets are consolidating; our market concentration analysis shows a high degree of revenue capture by leading vendors, creating winner-take-most dynamics for certain value propositions.
-
Outcome evidence is catching up: Clinical and economic studies supporting telemedicine-enabled glucose management and complication avoidance are increasingly robust, enabling payers and large health systems to evaluate ROI with greater confidence.
What PW Consulting’s Report Delivers
This report is designed as a decision-ready toolset for executives, investors, and clinical leaders preparing for 2026. We follow a "signal-to-decision" approach: highlight the strategic routes that matter, provide operational playbooks to act, and preserve the underlying data packages for authorized download. Key deliverables include:
-
Market sizing and forecasts (TAM/SAM/SOM) using multiple scenario lenses — baseline, conservative, and accelerated adoption pathways — with transparent assumptions and sensitivity models.
-
Reimbursement and policy playbook that maps current RPM and telehealth codes, anticipated regulatory permutations, and payer adoption timelines — prioritized by commercial impact for 2026 planning.
-
Vendor and technology benchmarking — qualitative and quantitative assessments across platform capability, clinical evidence, go‑to‑market reach, and partner ecosystems. We profile major market participants and their strategic positioning.
-
Clinical and economic evidence library with standardized templates for ROI modeling, including outcomes measures required by payers (e.g., Hba1c trajectories, acute event avoidance, and utilization offsets).
-
Integration and deployment blueprints that outline technical requirements (APIs, EHR integration, cybersecurity), operational staffing models for virtual diabetes clinics, and patient engagement sequences optimized for retention.
-
M&A and partnership playbook: valuation levers, diligence checklists (regulatory, reimbursement, clinical data), and recommended integration priorities post-acquisition.
To respect strategic confidentiality and the “trailer” principle, this release highlights the analytic depth but intentionally omits the full segmentation tables and line-item forecasts. The complete dataset, including granular technology, end‑user and regional splits, and downloadable financial models, is available to subscribers and clients who access the full report.
Competitive Landscape — Snapshot for 2026 Decisions
The competitive map in diabetes telemedicine is defined by complementary strengths: device OEMs anchoring clinical trust, digital platform vendors orchestrating data flows, and specialized care programs delivering outcomes. Our qualitative assessment of core participants highlights where 2026 advantage is likely to accrue.
-
Glooko Inc.: A platform-centric player offering device-agnostic data aggregation, EHR integration, and clinical dashboards. Well-suited for health systems seeking vendor-neutral interoperability and rapid RPM enablement.
-
Teladoc Health (Livongo): Combines scalable telehealth infrastructure with longitudinal diabetes coaching and supply logistics. The integration of programmatic care with telemedicine makes it a go-to partner for payers and large employers.
-
Podimetrics: Focused on complication prevention with remote temperature and pressure monitoring; recent product expansion broadens its clinical value beyond foot ulcers into inpatient‑at‑home workflows.
-
Virta Health: Offers a clinically oriented chronic‑care model aimed at type 2 diabetes reversal. Its strength lies in outcome-driven contracts and demonstrated biomarker impact — a template for value-based arrangements.
-
Dexcom and Abbott: Leading CGM innovators. Their device-level data and shareable ecosystems are the backbone for many remote monitoring programs, enabling near real-time clinical triage and automated coaching interventions.
-
Medtronic: Integrates insulin delivery with sensor inputs and is advancing automated insulin delivery systems that are telehealth‑friendly. Regulatory clearances for cross‑platform integration accelerate the adoption of closed-loop care in remote settings.
Collectively, the market is already concentrated: the top three players capture a majority of market revenues, and the top five capture a substantially larger share — a dynamic that influences strategic choices for new entrants and incumbents alike.
Strategic Recommendations for 2026
-
Providers and Health Systems: Prioritize integrated pilots that bundle CGM-enabled pathways with RPM staffing and payer contracting pilots. Focus on measurable outcomes (Hba1c reduction, reduction in ER visits) and design contracts with shared savings triggers.
-
Payers and Employers: Move from limited coverage pilots to outcomes‑based coverage with defined escalation criteria. Invest in digital prevention programs that capture at‑risk cohorts early and align incentives to long‑term disease modification.
-
Device and Platform Vendors: Standardize interoperability (FHIR, SMART on FHIR) and ship evidence packages that speak to payer requirements. Emphasize modular commercial models — device plus SaaS plus services — to expand revenue per patient and improve retention.
-
Investors and M&A Teams: Target companies with defensible recurring revenue, demonstrated clinical outcomes, and clear pathways to reimbursement. Consolidation opportunities exist where clinical evidence or EHR penetration can accelerate commercialization.
Decision Framework: How to Use This Report in Q1–Q3 2026
Executives should use a phased decision framework when translating insight into action: (1) Assess reimbursement risk using our coded scenarios; (2) Define a 100–500 patient pilot that validates workflows and economics; (3) Build an integration backbone to capture device and EHR data; (4) Negotiate commercial terms with payers using real-world outcomes from pilots; (5) Scale with a repeatable operations playbook and supplier rationalization to manage total cost of care.
Recent Developments That Matter
-
Product innovation: New multi-parameter remote monitoring devices extend clinical utility beyond glycemic control into complication prevention and mobility assessment — enabling broader telemedicine value propositions.
-
Regulatory progress: Integration clearances between major CGM sensors and insulin delivery platforms reduce clinical friction for closed-loop remote care models.
-
Policy tailwinds: Updated Medicare policies in early 2026 provide concrete reimbursement pathways for shorter RPM monitoring cycles and expanded telehealth services for diabetes self‑management.
Next Steps
For executives deciding where to allocate capital, launch pilots, or negotiate payer contracts in 2026, this report offers both the macro roadmap and the operational toolkits needed to act. PW Consulting’s full Diabetes Telemedicine Technology Market report contains the granular segmentations, downloadable financial models, and vendor scorecards required to operationalize a strategy. Contact our research team to obtain the complete dataset, model access, and a tailored briefing for your organization.
For detailed analysis of this topic, please visit the official page: Diabetes Telemedicine Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digoxin Market Poised for Steady Expansion with 3.15% CAGR Through 2032
By pmarketresearch, 2026-06-30
Digoxin Market 2026: Strategic Signals for Executives — PW Consulting Insight Brief
As life sciences leaders prepare their 2026 playbooks, the digoxin market offers a case study in mature-drug stability, supply-chain sensitivity, and steady, specialty-driven demand. PW Consulting’s latest Digoxin Market report — anchored on a 2025 base year and a seven-year forecast horizon to 2032 — synthesizes historical behavior, near-term inflection points, and actionable decision frameworks for manufacturers, generic sponsors, API suppliers, and investors. This brief outlines the strategic value of the report for 2026 decision cycles while intentionally withholding detailed segment tables and raw datasets to encourage stakeholders to consult the full publication for proprietary modelling and downloadable assets.
Digoxin Market
Why digoxin matters in 2026
-
Stable therapeutic role: Despite being an established cardiac glycoside, digoxin remains clinically relevant in specific indications and care pathways, underpinning predictable demand among formularies and hospital systems.
Digoxin Market -
Supply-chain concentration: Production of active pharmaceutical ingredient (API) and finished-dosage formulations is concentrated among a limited set of specialized manufacturers, which creates both geopolitical and operational exposure — a critical factor for procurement and continuity planning.
Digoxin Market -
Regulatory predictability with specialist friction: Digoxin’s legacy status reduces the likelihood of rapid therapeutic disruption, but regulatory requirements for compendial reference standards and Orange Book listings keep compliance and product lifecycle management top of mind.
Market trajectory — headline numbers and what they imply for planning
Our model shows a mature but positive trajectory. The global digoxin market expanded from a modest baseline in 2020 to an estimated USD 187.0 Million in 2025, and we forecast growth to approximately USD 233.2 Million by 2032, reflecting a compound annual growth rate (CAGR) of about 3.15% across the 2026–2032 forecast window. This pace signals a low-volatility environment where incremental gains arise from demographic trends, steady prescribing in core indications, and selective geographic growth rather than disruptive innovation.
For 2026 planning, that profile yields three practical implications:
-
Capacity planning should prioritize reliability over scale: modest market growth reduces the urgency for greenfield expansion but heightens the value of resilient contracts and dual-sourcing strategies.
-
Margin preservation and cost-to-serve optimization become competitive levers: when volume growth is constrained, manufacturers that can extract operational efficiencies and optimize route-to-market will outpace peers on profitability.
-
Targeted portfolio strategies win: bundles of finished dosage, generics, and adjacent cardiovascular offerings create cross-sell synergies that matter more than competing on single-product volume.
Supply dynamics and regulatory context
Two structural features of the digoxin supply environment matter for immediate executive attention. First, there is a narrow set of qualified suppliers for critical inputs: compendial reference standards are provided through institutional bodies and European authorities, establishing a compliance floor that ties analytical and quality programs back to a small number of reference providers. Second, API manufacturing capacity is concentrated in a handful of specialized producers that combine botanical sourcing know-how with pharmaceutical-grade synthesis capabilities.
For procurement and quality teams, the consequence is clear: supplier audits, long-term quality agreements, and contingency inventories should be standard components of any 2026 sourcing strategy. Regulatory teams should also prioritize pharmacopoeial compliance pathways and maintain up-to-date Orange Book mappings for finished-dosage suppliers to ensure seamless market access.
Competitive landscape — who matters and why
The digoxin ecosystem features actors across the vertical chain: primary API manufacturers, finished-dosage producers, and organizations that specialize in analytical reference standards. The market concentration metrics further underline that while the market is not monopolistic, the leading players provide meaningful pricing and supply influence — our concentration analysis shows the top three firms account for a significant portion of market supply, and the top five extend that influence further.
-
C2 Pharma (UK) — A primary producer of digoxin API, C2 Pharma supplies compendial-grade material to major formulators. Their positioning on API quality and global distribution makes them a go-to partner for companies seeking pharmacopeial-compliant feedstock.
-
Alkaloids Corporation (India) — Leveraging botanical manufacturing capabilities, Alkaloids Corporation is a major API supplier with scale-oriented production assets that appeal to generics manufacturers and contract formulators.
-
Vital Labs and Alchem — Active API suppliers integrated into global supply networks; their agility in contract manufacturing and tolling arrangements provides flexible capacity options for customers.
-
Hikma, Sandoz, Stevens J, Sun Pharma, Aurobindo Pharma — Established suppliers of finished-dosage digoxin tablets and generics, these firms maintain market access through regulatory listings and broad commercial reach.
-
Sigma-Aldrich (USA) and EDQM (Europe) — Providers of reference standards and compendial materials critical for analytical testing and regulatory compliance; their role anchors pharmacopoeial conformity.
PW Consulting’s full report maps supplier capabilities, manufacturing footprints, and regulatory listings to operational risk matrices, enabling procurement teams to prioritize vendor remediation and M&A teams to identify consolidation targets. We highlight, but in this public brief do not disclose, the specific capacity concentrations and counterparty exposure metrics that underpin our risk scores.
What’s inside the report — practical deliverables for 2026
The report is designed as a hands-on toolkit for corporate strategy, commercial planning, and investment diligence. Key deliverables include:
-
Market model with scenario outputs — base, upside, and downside cases — and an interactive model (license) that allows users to stress-test assumptions across volume, price, and substitution dynamics.
-
Supply-chain heatmaps and supplier scorecards — covering qualification status, capacity resilience, geographic exposure, and audit histories to prioritize contingency actions.
-
Regulatory and reimbursement compendium — synthesis of pharmacopeial reference standards, Orange Book listings, and national-level access considerations for the largest markets.
-
Commercial playbooks — segmented GTM approaches, pricing benchmarks, tender-readiness checklists, and formulary engagement strategies tailored to generic and specialty players.
-
M&A and partnership pipeline — prioritized targets and integration risk assessments for firms seeking to consolidate API supply or strengthen finished-dose capabilities.
-
Operational checklists — recommended production redundancy plans, quality KPIs, and CAPA templates keyed to digoxin’s specific control points.
Each deliverable ties back to proprietary data and expert judgment; the full report contains the underlying tables, regional and application segmentation, and downloadable datasets that power the summary models. This brief intentionally omits those granular tables to preserve the value proposition of the full research package.
Strategic imperatives for 2026
-
For API producers: Prioritize quality differentiation and long-term supply agreements. Given the modest CAGR, securing premium pricing requires demonstrating consistent pharmacopeial compliance and rapid turn-up capability for crisis orders.
-
For finished-dose manufacturers and generics: Focus on cost-to-serve reduction and tender competitiveness. Strategic investments in capacity optimization and regulatory file readiness will be more value-creating than large-scale capacity expansion.
-
For procurement and supply-chain leaders: Implement multi-tiered sourcing strategies and contract clauses that address force majeure and quality drift. Establishing secondary qualified suppliers and onshore buffer inventories should be high-priority actions for 2026.
-
For investors and M&A teams: Look for targets that add technical depth (botanical/chemical synthesis know-how), compendial expertise, or finished-dose capabilities in hospital and institutional channels. Valuation should account for integration costs and the low-growth base case.
-
For regulatory and quality functions: Maintain alignment with compendial updates and Orange Book changes. Investing in robust reference-standard programs and analytical capacity reduces time-to-market risk for lifecycle filings.
Risks and leading indicators to monitor in 2026
While the market is mature, a handful of variables could materially affect short-term dynamics:
-
API concentration shocks — plant outages or regulatory actions at key API sites could tighten supply rapidly due to concentrated production footprints.
-
Policy shifts in institutional procurement — changes in tender frameworks or hospital formularies could alter price dynamics faster than underlying demand.
-
Compendial or analytical updates — revisions to reference standards or testing requirements can introduce friction and lead times for product release.
Our forecast model maps these risks to probability-weighted scenarios and prescribes mitigations for each stakeholder group; the full report contains the scenario matrices and trigger points recommended for inclusion in corporate risk registers.
Conclusion — how PW Consulting’s report supports 2026 decision-making
For executives building strategies in 2026, digoxin is a low-growth, high-certainty asset class where differentiation emerges from supply reliability, regulatory readiness, and operational efficiency rather than rapid market expansion. PW Consulting’s Digoxin Market report equips decision-makers with the market sizing, concentration metrics, supplier assessments, and tactical playbooks needed to translate that insight into concrete actions — whether the objective is to secure supply, optimize margins, pursue M&A, or defend market share.
To access the full dataset, interactive model, and supplier-specific risk matrices referenced in this brief — including detailed segmentation by region, type, and application — visit our report landing page for licensing and download options. The granular tables and proprietary scores are available only in the comprehensive report package and are the necessary next step for teams that need to operationalize these insights in 2026.
For detailed analysis of this topic, please visit the official page: Digoxin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com