

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
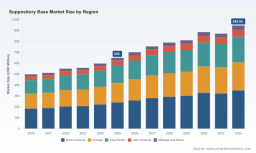
PW Consulting: Suppository Base Market to Climb from USD 650.0 Million in 2025 to USD 945.54 Million by 2032, Backed by a 5.5% CAGR

Suppository Base Market: Strategic Imperatives for 2026 — PW Consulting Insights
As global pharmaceutical manufacturers, compounding pharmacies, and specialty excipient suppliers plan budgets and M&A strategies for 2026, a clear, actionable view of the suppository base market becomes a critical enabler of competitive advantage. PW Consulting’s newest market research — anchored on a 2025 base year, informed by 2020–2025 historical dynamics, and forecasting through 2032 — synthesizes commercial, regulatory, and technical intelligence into a decision-grade resource. Our top-line macro model identifies steady expansion with a compound annual growth rate of 5.5% across the forecast window, positioning the market for meaningful strategic moves in the coming 12–18 months.
Suppository Base Market
Market Snapshot: Macro Trajectory and What It Means
The suppository base market has shown resilient growth through the early 2020s, driven by forces including sustained demand from therapeutic categories suited to rectal and vaginal delivery, steady activity among compounding pharmacies, and ongoing product innovation from established excipient manufacturers. By our 2025 base year the global market reached the mid-hundreds (USD, million). The model projects continued growth into 2026 and beyond, consistent with a 5.5% CAGR for the forecast period, with intermittent acceleration tied to regulatory clarifications, supply-chain normalization, and targeted product launches.
Suppository Base Market
- Growth drivers: aging populations in established markets, expanded chronic-disease management programs that favor alternate routes of administration, and stable compounding demand for individualized therapies.
- Constraining factors: raw-material sourcing volatility for hard fat bases, regulatory scrutiny around excipient provenance, and margin pressure among distributors and compounding intermediaries.
- Market rhythm: periods of inventory restocking and catalog refreshes by major suppliers create windows for commercial negotiation and tactical sourcing shifts.
Why 2026 Is a Strategic Inflection Point
Several converging dynamics make 2026 a year when senior leaders should convert strategic options into executable plans:
Suppository Base Market
- Regulatory cadence: Documented compliance pathways (for example, European Pharmacopoeia recognition of certain hard fats and USP references for common bases) reduce technical uncertainty but raise the bar on documentation, supplier audits, and change control.
- Supplier consolidation and differentiation: Suppliers continue to sharpen portfolios around hard fats, PEG blends, and specialty bases for mucosal tolerance and drug dispersion. Visible catalog updates and marketing pushes from incumbent vendors emphasize quality and GMP pedigree — attributes buyers will increasingly pay for.
- Supply-chain risk: Raw material sourcing (notably vegetable-derived saturated fatty acids) remains exposed to agricultural inputs and regional logistics; strategic inventory, dual-sourcing, and supplier assurance programs will materially reduce interruption risk.
- Commercial optimization: With overall market growth modest but steady, winning companies will prioritize product-service bundles, formulation support, and certification-backed premium positioning rather than competing on commodity pricing alone.
What the PW Consulting Report Delivers — Practical, Executable Insight
Our report is built as a toolset for decision-makers, not an academic exercise. Key deliverables include:
- Top-line market model: A transparent macro-level sizing and a model you can flex under alternative scenarios (price shocks, regulatory events, raw-material shortages).
- Segment-level thesis without gratuitous giveaway: We map the market by route, base type, and region in a way that highlights where growth and margin expansion opportunities lie while reserving full granular figures for the full report to preserve strategic value.
- Supplier due-diligence framework: A checklist and scoring model to evaluate GMP compliance, inspection history, product-grade registration, and commercial reliability.
- Formulation selection matrix: Practical guidance for selecting base families (hard fats, PEG systems, synthetic blends) against product attributes such as melting behavior, active compatibility, mucosal tolerance, and cold-chain needs.
- Regulatory playbook: Mapping to pharmacopoeial requirements and jurisdictional nuances, with a prioritized list of compliance tasks for market access and quality audits.
- Commercial playbook: Pricing levers, contract structures, inventory strategies, and partnership archetypes tailored to manufacturers, distributors, and compounding pharmacies.
- M&A and partnership radar: High-level criteria and a shortlist of capability gaps that create acquisition interest; detailed target profiles and financial multiples are included in the full report.
Competitive Landscape — Strategic Profiles of Core Players
The market displays a mix of global excipient specialists, compounding-focused suppliers, and regional formulators. Our competitive mapping highlights capability clusters rather than just brand names, enabling buyers to align supplier selection with strategic priorities.
- IOI Oleo GmbH (Hamburg): A long-established producer of hard fat bases with recognized grades such as WITEPSOL®. IOI emphasizes GMP-certified production, a broad registered-grade catalog, and compliance with major pharmacopoeias. Recent catalog refresh activity reinforces a strategy to anchor premium hard-fat supply through documentation and multiple registered grades tailored to suppository and ovule applications.
- Medisca (Montreal/US operations): A distribution and compounding-focused supplier promoting both classic and “natural” suppository bases. Medisca’s pathway centers on availability for compounding pharmacies and clear product positioning for pharmacy-grade supply chains; recent promotional efforts underscore channel-focused commercialization.
- PCCA (Houston): Deeply embedded in the compounding community, PCCA offers proprietary bases and support services. Their competitive advantage is a blend of brand loyalty among independent compounding pharmacies and technical service that reduces formulation risk for users.
- SpecializedRx (USA): Positions itself on accessibility for compounding and a selection of proprietary blends. The supplier model focuses on product breadth and channel convenience.
- Gattefossé (France) and Croda Pharma (UK): Both bring formulation science and excipient expertise, with product development geared to drug dispersion, mucosal compatibility, and stability. These players are natural partners for pharmaceutical companies seeking co-development and validated excipient solutions.
Strategic takeaway: incumbent excipient manufacturers maintain technical leadership through registered grades and GMP messaging, while compounding-focused suppliers differentiate through channel reach and formulation support. Buyers should not evaluate suppliers on price alone — certification, batch-release robustness, and co-development capabilities are decisive procurement criteria.
Strategic Playbook: What Winning Looks Like in 2026
Across manufacturers, suppliers, and investors, a coherent set of actions will separate winners from followers:
- Manufacturers of finished dosage forms: Prioritize excipient qualification pathways now. Invest in early formulation compatibility studies and secure second-source agreements for critical base families to mitigate supply interruptions.
- Excipient suppliers: Differentiate through documented GMP pedigree, grade diversity, and formulation support. Consider modular service offers (e.g., small-batch custom blending, compounding kits) to capture higher-margin adjacent revenue.
- Compounding pharmacies and distributors: Leverage supplier partnerships to reduce inventory burdens while securing priority access to high-demand grades; demand traceability and certificate-of-analysis (CoA) standards that align with downstream regulatory scrutiny.
- Private equity and strategic investors: Look for targets that combine technical IP (novel base blends or dispersion technologies) with channel access to compounding markets. Pay special attention to companies with validated GMP operations and documented inspection histories.
- Risk management: Implement a raw-material watchlist tied to supplier audit schedules, and build scenario-based inventory models into procurement planning for 2026.
Methodology, Data Integrity, and Where to Find the Granular Intelligence
Our analysis synthesizes primary supplier documentation (including recent catalog and product updates), public regulatory standards (e.g., European Pharmacopoeia and USP references), company disclosures, and interviews with formulation scientists and procurement leads across the value chain. Recent public developments — such as IOI Oleo’s product brochure update and Medisca’s market availability announcements — were validated and contextualized within our commercial model.
PW Consulting’s forecast and scenario outputs are presented with transparent assumptions, sensitivity testing, and a reproducible financial model. To adhere to best-practice competitive disclosure and to preserve the commercial value of the full dataset, we present macro-level sizing and trend analysis in this release while withholding full segment-by-region and detailed application-by-type breakdowns. Those granular splits, including the full regional and application matrices and supplier-share tables, are available in the complete report package on our website.
How to Use This Intelligence in Q1–Q2 2026
- Immediate actions (0–3 months): Run supplier qualification audits against our due-diligence checklist; secure short-term dual-source agreements for hard-fat grades; request CoAs and GMP evidence from key vendors.
- Near term (3–9 months): Execute formulation compatibility studies using prioritized base candidates; model price / margin sensitivity under alternate raw-material scenarios; negotiate commercial terms that include service-level guarantees for critical grades.
- Medium term (9–18 months): Lock in strategic partnerships or bolt-on acquisitions that close capability gaps (e.g., co-development of improved dispersion bases) and integrate excipient supply into product development roadmaps for new dosage forms.
Concluding Perspective
The suppository base market is neither a large-scale growth story nor a static commodity market — it is a steady, technically nuanced sector where regulatory provenance, supplier reliability, and formulation expertise determine commercial outcomes. For decision-makers charting strategy in 2026, the choice is clear: act now to secure certified supply, invest selectively in formulation capability, and use M&A or partnership plays to obtain technical differentiation. PW Consulting’s full report provides the granular charts, regional and application splits, supplier share estimates, and a downloadable financial model needed to operationalize these strategic moves.
For access to the full dataset, segment breakdowns, and our interactive scenario model, please visit the PW Consulting report page and request the Suppository Base Market full report. The detailed intelligence within that package is designed to support board-level decisions and tactical procurement plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Suppository Base Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com