

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rotator Cuff Injury Therapy Market to Hit USD 2,951.21 Million by 2032, Growing at a 6.1% CAGR

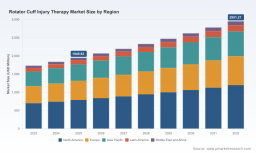
Rotator Cuff Injury Therapy Market 2026 Outlook: Strategic Imperatives from PW Consulting's New Market Report
Executive overview
PW Consulting today releases its definitive market intelligence brief on the Rotator Cuff Injury Therapy market, framed to support executive decision‑making across product, commercial, regulatory and M&A agendas in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the report models the market as a multi‑billion dollar device and therapy sector (USD, revenue in Million) that is set to expand at a compound annual growth rate (CAGR) of 6.1% through 2032. Our base‑case arithmetic pegs the market at approximately USD 1,949.82 Million in 2025 with a near‑term step to ~USD 2,068.76 Million in 2026 and a long‑term projection to about USD 2,951.21 Million by 2032.
Rotator Cuff Injury Therapy Market
Why this report matters for 2026 corporate strategy
For medtech and biologics executives, hospital procurement leads, private equity teams and regional market entrants, 2026 is the year to convert clinical momentum into commercial traction. The combination of guideline endorsements for bioinductive approaches, recent device clearances and persistent reimbursement complexity is reshaping where value is created across the care pathway.
Rotator Cuff Injury Therapy Market
-
Product roadmaps: The market’s steady growth at 6.1% CAGR creates a predictable window to amortize new platform investments — but only for technologies that demonstrably reduce re‑tear rates or shorten total care episodes. Firms must prioritize clinical end points and economic evidence alongside engineering advances.
Rotator Cuff Injury Therapy Market -
Regulatory & launch sequencing: Multiple FDA 510(k) clearances for augmentation matrices and new repair systems in 2024–2025 have lowered technical entry barriers. Still, first‑mover advantage now depends on post‑market evidence generation and favorable guideline positioning.
-
Reimbursement and pricing strategy: Procedural reimbursement for arthroscopic repair remains nuanced. For example, complexity‑based modifiers are successfully applied in a limited minority of cases, which directly affects premium pricing for augmented repairs. Negotiating favorable hospital contracting terms will be decisive.
-
M&A and partnership timing: The sector’s innovation cadence — from suture anchor refinements to bioinductive implants and novel space‑occupying devices for irreparable tears — makes 2026 a pivotal year for tuck‑ins that add biologic or augmentation capabilities to established instrumentation platforms.
What the report contains — practical, transaction‑ready intelligence
PW Consulting’s analysis is structured to convert insight into action. The report includes:
-
Verified market sizing and a seven‑year forecast (2026–2032) with scenario lanes for conservative, base and aggressive uptake curves;
-
Driver and barrier analysis mapping clinical guidelines, device approvals, payor behaviors and provider economics to expected product adoption timelines;
-
Technology deep dives covering suture anchors, knotless systems, augmentation matrices, biologics and implants designed for massive/irreparable tears;
-
Reimbursement playbook: coding risk analysis, modifier usage benchmarks and commercial levers for securing hospital and ASC reimbursement premiums;
-
Competitive landscaping with strategic profiles, pipeline intelligence and capability matrices for the sector’s leading suppliers;
-
Go‑to‑market frameworks and a 12‑ to 36‑month tactical plan tailored for incumbents, challengers and private equity‑backed platforms; and
-
Client‑ready model files and sensitivity tools that let users re‑run forecasts under custom assumptions.
Note: the report intentionally omits publicly distributed granular segment line items from this press summary to preserve the value of the full dataset. Authorized purchasers receive exhaustive regional, treatment‑type and end‑user splits along with downloadable tables and charts.
Competitive landscape — how leading firms are positioning in 2026
The competitive environment is evolving from hardware‑led battles toward mixed portfolios that combine anchors and instrumentation with biologics, augmentation matrices and supportive implants. Key strategic postures observed among incumbents and challengers include:
-
Product breadth and ecosystem plays: Established orthopedics platforms continue to leverage their existing surgical instrument footprints to bundle anchors, suture systems and kits that shorten OR time and reduce variability.
-
Biologics and augmentation differentiation: Several companies have prioritized bioinductive or bioresorbable matrices to address re‑tear economics. Guideline endorsements for bioinductive approaches have created a greenfield for commercialization of such adjuncts.
-
Minimally invasive and salvage solutions: Innovations targeted at massive or irreparable tears — including balloon implants and scaffold technologies — are attracting clinical interest and changing referral patterns.
-
Regulatory and evidence acceleration: Firms that combine rapid 510(k) clearances with robust post‑market registries and health economics analyses are winning quicker uptake in hospital systems.
Representative companies examined in our competitive profiles include global medtech leaders and focused orthopedics innovators active in clinical adoption and product development. Each profile contains capability maps, recent launches and clinical evidence assessments to aid partnership, licensing and acquisition decisions.
Recent developments shaping near‑term strategy
-
Clinical guidelines: The American Academy of Orthopaedic Surgeons’ updated guideline emphasizes bioinductive implants to reduce re‑tear rates, strengthening the clinical case for augmentation devices.
-
Regulatory activity: Several augmentation matrices and repair systems received FDA clearances in 2024–2025, expanding the menu of commercially available adjuncts and creating competition for clinical share.
-
Commercial milestones: Industry conferences in early 2026 showcased next‑generation repair systems and biologic implants, accelerating awareness among key opinion leaders.
-
Economic signals: Independent analyses indicate a meaningful lifetime societal cost‑saving for patients undergoing repair versus nonoperative treatment — a powerful argument for payors and hospital CFOs when evaluating adoption of higher‑cost adjuncts.
Actionable 2026 playbook — five high‑impact moves
-
Prioritize evidence‑grade launches: Align product introductions with registries and randomized studies that target re‑tear reduction and cost per quality‑adjusted life year (QALY) improvements.
-
Design reimbursement experiments: Pilot enhanced payment bundles and modifier usage protocols with lead hospitals and ASCs to capture incremental procedure economics.
-
Bundle hardware + biologic offers: Create commercial bundles that simplify purchasing decisions for hospital procurement teams and demonstrate OR efficiency gains.
-
Identify bolt‑on M&A targets: Use our heatmaps to shortlist assets that add augmentation biology, novel scaffolds or ASC distribution channels to your portfolio.
-
Build RWE fast: Deploy pragmatic registries at top centers to collect function, re‑tear and resource‑use outcomes — enabling premium contracting and faster guideline uptake.
How PW Consulting’s methodology supports board‑level decisions
The report combines primary interviews with surgeons, hospital procurement leads and payor advisors, alongside procedure‑level pricing analytics and device adoption curves. We triangulate manufacturer disclosures, regulatory databases and clinical literature to produce transparent, auditable forecasts. The deliverable suite includes scenario models and a bespoke slide deck to accelerate C‑suite briefings and investor diligence.
Call to action — where to get the full intelligence
This press release intentionally provides a high‑value executive synopsis while preserving the report’s detailed segment tables and company financial estimates for authorized users. The full PW Consulting Rotator Cuff Injury Therapy Market report contains the granular regional, treatment‑type and end‑user breakdowns, company revenue estimates, market share matrices, and downloadable model files necessary for transaction execution and operational planning.
To access the complete dataset, scenario models and client advisory options for 2026 strategy, please visit the PW Consulting market reports page or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Rotator Cuff Injury Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com