

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Digoxin Market Poised for Steady Expansion with 3.15% CAGR Through 2032

Digoxin Market 2026: Strategic Signals for Executives — PW Consulting Insight Brief
As life sciences leaders prepare their 2026 playbooks, the digoxin market offers a case study in mature-drug stability, supply-chain sensitivity, and steady, specialty-driven demand. PW Consulting’s latest Digoxin Market report — anchored on a 2025 base year and a seven-year forecast horizon to 2032 — synthesizes historical behavior, near-term inflection points, and actionable decision frameworks for manufacturers, generic sponsors, API suppliers, and investors. This brief outlines the strategic value of the report for 2026 decision cycles while intentionally withholding detailed segment tables and raw datasets to encourage stakeholders to consult the full publication for proprietary modelling and downloadable assets.
Digoxin Market
Why digoxin matters in 2026
-
Stable therapeutic role: Despite being an established cardiac glycoside, digoxin remains clinically relevant in specific indications and care pathways, underpinning predictable demand among formularies and hospital systems.
Digoxin Market -
Supply-chain concentration: Production of active pharmaceutical ingredient (API) and finished-dosage formulations is concentrated among a limited set of specialized manufacturers, which creates both geopolitical and operational exposure — a critical factor for procurement and continuity planning.
Digoxin Market -
Regulatory predictability with specialist friction: Digoxin’s legacy status reduces the likelihood of rapid therapeutic disruption, but regulatory requirements for compendial reference standards and Orange Book listings keep compliance and product lifecycle management top of mind.
Market trajectory — headline numbers and what they imply for planning
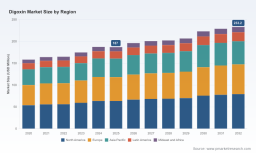
Our model shows a mature but positive trajectory. The global digoxin market expanded from a modest baseline in 2020 to an estimated USD 187.0 Million in 2025, and we forecast growth to approximately USD 233.2 Million by 2032, reflecting a compound annual growth rate (CAGR) of about 3.15% across the 2026–2032 forecast window. This pace signals a low-volatility environment where incremental gains arise from demographic trends, steady prescribing in core indications, and selective geographic growth rather than disruptive innovation.
For 2026 planning, that profile yields three practical implications:
-
Capacity planning should prioritize reliability over scale: modest market growth reduces the urgency for greenfield expansion but heightens the value of resilient contracts and dual-sourcing strategies.
-
Margin preservation and cost-to-serve optimization become competitive levers: when volume growth is constrained, manufacturers that can extract operational efficiencies and optimize route-to-market will outpace peers on profitability.
-
Targeted portfolio strategies win: bundles of finished dosage, generics, and adjacent cardiovascular offerings create cross-sell synergies that matter more than competing on single-product volume.
Supply dynamics and regulatory context
Two structural features of the digoxin supply environment matter for immediate executive attention. First, there is a narrow set of qualified suppliers for critical inputs: compendial reference standards are provided through institutional bodies and European authorities, establishing a compliance floor that ties analytical and quality programs back to a small number of reference providers. Second, API manufacturing capacity is concentrated in a handful of specialized producers that combine botanical sourcing know-how with pharmaceutical-grade synthesis capabilities.
For procurement and quality teams, the consequence is clear: supplier audits, long-term quality agreements, and contingency inventories should be standard components of any 2026 sourcing strategy. Regulatory teams should also prioritize pharmacopoeial compliance pathways and maintain up-to-date Orange Book mappings for finished-dosage suppliers to ensure seamless market access.
Competitive landscape — who matters and why
The digoxin ecosystem features actors across the vertical chain: primary API manufacturers, finished-dosage producers, and organizations that specialize in analytical reference standards. The market concentration metrics further underline that while the market is not monopolistic, the leading players provide meaningful pricing and supply influence — our concentration analysis shows the top three firms account for a significant portion of market supply, and the top five extend that influence further.
-
C2 Pharma (UK) — A primary producer of digoxin API, C2 Pharma supplies compendial-grade material to major formulators. Their positioning on API quality and global distribution makes them a go-to partner for companies seeking pharmacopeial-compliant feedstock.
-
Alkaloids Corporation (India) — Leveraging botanical manufacturing capabilities, Alkaloids Corporation is a major API supplier with scale-oriented production assets that appeal to generics manufacturers and contract formulators.
-
Vital Labs and Alchem — Active API suppliers integrated into global supply networks; their agility in contract manufacturing and tolling arrangements provides flexible capacity options for customers.
-
Hikma, Sandoz, Stevens J, Sun Pharma, Aurobindo Pharma — Established suppliers of finished-dosage digoxin tablets and generics, these firms maintain market access through regulatory listings and broad commercial reach.
-
Sigma-Aldrich (USA) and EDQM (Europe) — Providers of reference standards and compendial materials critical for analytical testing and regulatory compliance; their role anchors pharmacopoeial conformity.
PW Consulting’s full report maps supplier capabilities, manufacturing footprints, and regulatory listings to operational risk matrices, enabling procurement teams to prioritize vendor remediation and M&A teams to identify consolidation targets. We highlight, but in this public brief do not disclose, the specific capacity concentrations and counterparty exposure metrics that underpin our risk scores.
What’s inside the report — practical deliverables for 2026
The report is designed as a hands-on toolkit for corporate strategy, commercial planning, and investment diligence. Key deliverables include:
-
Market model with scenario outputs — base, upside, and downside cases — and an interactive model (license) that allows users to stress-test assumptions across volume, price, and substitution dynamics.
-
Supply-chain heatmaps and supplier scorecards — covering qualification status, capacity resilience, geographic exposure, and audit histories to prioritize contingency actions.
-
Regulatory and reimbursement compendium — synthesis of pharmacopeial reference standards, Orange Book listings, and national-level access considerations for the largest markets.
-
Commercial playbooks — segmented GTM approaches, pricing benchmarks, tender-readiness checklists, and formulary engagement strategies tailored to generic and specialty players.
-
M&A and partnership pipeline — prioritized targets and integration risk assessments for firms seeking to consolidate API supply or strengthen finished-dose capabilities.
-
Operational checklists — recommended production redundancy plans, quality KPIs, and CAPA templates keyed to digoxin’s specific control points.
Each deliverable ties back to proprietary data and expert judgment; the full report contains the underlying tables, regional and application segmentation, and downloadable datasets that power the summary models. This brief intentionally omits those granular tables to preserve the value proposition of the full research package.
Strategic imperatives for 2026
-
For API producers: Prioritize quality differentiation and long-term supply agreements. Given the modest CAGR, securing premium pricing requires demonstrating consistent pharmacopeial compliance and rapid turn-up capability for crisis orders.
-
For finished-dose manufacturers and generics: Focus on cost-to-serve reduction and tender competitiveness. Strategic investments in capacity optimization and regulatory file readiness will be more value-creating than large-scale capacity expansion.
-
For procurement and supply-chain leaders: Implement multi-tiered sourcing strategies and contract clauses that address force majeure and quality drift. Establishing secondary qualified suppliers and onshore buffer inventories should be high-priority actions for 2026.
-
For investors and M&A teams: Look for targets that add technical depth (botanical/chemical synthesis know-how), compendial expertise, or finished-dose capabilities in hospital and institutional channels. Valuation should account for integration costs and the low-growth base case.
-
For regulatory and quality functions: Maintain alignment with compendial updates and Orange Book changes. Investing in robust reference-standard programs and analytical capacity reduces time-to-market risk for lifecycle filings.
Risks and leading indicators to monitor in 2026
While the market is mature, a handful of variables could materially affect short-term dynamics:
-
API concentration shocks — plant outages or regulatory actions at key API sites could tighten supply rapidly due to concentrated production footprints.
-
Policy shifts in institutional procurement — changes in tender frameworks or hospital formularies could alter price dynamics faster than underlying demand.
-
Compendial or analytical updates — revisions to reference standards or testing requirements can introduce friction and lead times for product release.
Our forecast model maps these risks to probability-weighted scenarios and prescribes mitigations for each stakeholder group; the full report contains the scenario matrices and trigger points recommended for inclusion in corporate risk registers.
Conclusion — how PW Consulting’s report supports 2026 decision-making
For executives building strategies in 2026, digoxin is a low-growth, high-certainty asset class where differentiation emerges from supply reliability, regulatory readiness, and operational efficiency rather than rapid market expansion. PW Consulting’s Digoxin Market report equips decision-makers with the market sizing, concentration metrics, supplier assessments, and tactical playbooks needed to translate that insight into concrete actions — whether the objective is to secure supply, optimize margins, pursue M&A, or defend market share.
To access the full dataset, interactive model, and supplier-specific risk matrices referenced in this brief — including detailed segmentation by region, type, and application — visit our report landing page for licensing and download options. The granular tables and proprietary scores are available only in the comprehensive report package and are the necessary next step for teams that need to operationalize these insights in 2026.
For detailed analysis of this topic, please visit the official page: Digoxin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com