

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
PW Consulting: Convenient Camping Cooler Market to Grow at 5.8% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
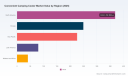
Convenient Camping Cooler Market — Strategic Preview for 2026 Decision-Making
Executive snapshot
As the outdoor recreation economy normalizes into a new post‑pandemic cadence, the Convenient Camping Cooler market is entering a phase of steady expansion and pronounced product innovation. Our latest PW Consulting market model shows the global market expanding from roughly USD 965 million in 2025 to an estimated USD 1.43 billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.8% across the 2026–2032 forecast window. That trajectory, paired with a moderate market concentration (CR3 ≈ 42.5%; CR5 ≈ 48.2%), creates a landscape in which nimble challengers and incumbent premium brands can both capture meaningful share — provided they align product, channel and sourcing strategies to emerging commercial and regulatory realities.
Convenient Camping Cooler Market
Why this briefing matters for 2026 strategy
-
Time‑sensitive compliance and product design: New environmental standards and material regulations (notably EU requirements taking effect in 2027) change product specs and allowable materials; businesses must build compliance into 2026 product roadmaps to avoid costly redesigns or market entry delays in 2027.
Convenient Camping Cooler Market -
Input cost volatility is no longer a background risk: Fluctuations in petroleum‑derived polyurethane foams and polymers materially affect component costs and margin stability — manufacturers need procurement playbooks and hedging scenarios now, not later.
Convenient Camping Cooler Market -
Feature differentiation drives premium pricing: Mobility (wheels), foldability and lightweight construction have moved from “nice-to-have” to purchase drivers. Firms that can translate those attributes into reliable, measurable performance (ice retention, durability, leak resistance) will command premium positioning in key retail and direct channels.
-
Channel mix decisions pivot around convenience: Consumers increasingly value compact storage and single‑person portability, reshaping adjacent merchandising and logistics choices across omni‑channel retailers and D2C platforms.
Key market dynamics at a glance
-
Growth profile: After accelerating through the early 2020s, growth moderates into a steady mid‑single digit phase; the market reached approximately USD 964.5 million in 2025 and is projected to surpass USD 1.4 billion by 2032 on a 5.8% CAGR for 2026–2032. That steady expansion supports investment in incremental innovation and selective capacity build‑outs rather than broad, capital‑intensive network expansions.
-
Concentration and competitive intensity: With the top three and top five firms controlling under half the market, there remains ample scope for regional and niche players to scale through product specialization, channel partnerships and value engineering.
-
Raw material & cost pressure: Volatility in polymer and foam inputs induces margin variability for manufacturers heavily exposed to petroleum feedstocks. Suppliers and OEMs are experimenting with alternative formulations and recycled content, but substitution timelines vary by cost and performance trade‑offs.
-
Regulatory overlay: Stricter rules on non‑biodegradable plastics, plus region‑specific energy and environmental standards (EU rules effective in 2027), require manufacturers to validate sourcing, production and end‑of‑life pathways for products destined for regulated jurisdictions.
-
Consumer preference shifts: Practical convenience features — lighter weight, wheels, collapsibility, and organizational accessories — are driving purchase decisions across both casual campers and more experienced outdoor consumers. These preferences also influence lifetime value via higher attachment/upsell rates for accessory ecosystems (dry bins, straps, drinkware).
-
Safety and reliability: Industry surveillance shows no major recalls in 2025–2026; the sector is focused on leak resistance, insulation performance and robustness as differentiators that reduce warranty costs and protect brand equity.
Competitive landscape — what leading players are doing
Market leadership continues to be defined by a mix of premium engineering, scale manufacturing and brand equity. PW Consulting’s qualitative review of core competitors highlights the following strategic moves and positioning:
-
YETI (Austin, TX) maintains a premium, performance‑led posture with rotomolded hard coolers designed for multi‑day retention and durability; recent updates in 2026 (lightweight Roadie 8 and enhancements to the Roadie 24) signal continued investment in solo‑use and portability segments.
-
Igloo (Cedar Park, TX) competes on accessibility and sustainability experiments, expanding recycled and compostable offerings while maintaining broad price‑point coverage across injection and rotomolded platforms.
-
Coleman (Oklahoma City, OK) leverages heritage outdoor distribution and has introduced a category‑disrupting Snap ’N Go collapsible hard cooler in 2026 — an example of structural innovation that addresses storage constraints faced by mass‑market consumers.
-
RTIC and Canyon Outdoor continue to emphasize value engineering for durable rotomolded units, while Engel focuses on ultra‑light injection‑molded designs that balance portability with thermal performance.
-
RovR’s award recognition and expanded product lines (redesigned RollR wheeled coolers and TravelR soft coolers) underscore how mobility and modular organization can be leveraged to create new sub‑segments within the convenience category.
Strategic playbook for 2026 (practical, executable moves)
-
Embed compliance into product roadmaps: Assume that products sold into regulated regions will require materials, labeling and recyclability validation by 2027. Begin design freeze windows with compliant material specifications in 2026 to avoid costly retrofits.
-
Hedge raw material exposure: Contractually diversify resin and foam supply, test bio‑based or recycled blends now, and model three cost scenarios (baseline, +15%, +35% feedstock inflation) to quantify margin levers and pricing cadence for 2026–2027.
-
Prioritize feature stacks that map to willingness‑to‑pay: Run rapid conjoint studies focused on mobility (wheels vs. detachable trolley), storage (collapsible vs. fixed), and performance (ice retention vs. weight). Use results to define two‑tier SKUs: a premium retention‑focused line and a convenience‑focused mass line.
-
Channel economics and assortment rationalization: Rebalance assortment between big‑box, specialty outdoor, and D2C. Test exclusive SKUs and accessory bundles through pilot programs to measure acquisition cost, attach rates and post‑purchase NPS.
-
Operationalizing innovation: Shorten prototype cycles by adopting modular tooling for lids and drain assemblies, enabling faster A/B testing of features like integrated straps, quick‑drain plugs, and organizational inserts.
-
M&A and partnership targets: Look for bolt‑on acquisitions that provide manufacturing flexibility (injection‑molding capacity or specialty assembly for wheeled platforms), or license technologies for foldable hard‑shell mechanics. Partnerships with recycling and take‑back service providers can also accelerate compliance credentials.
-
Pricing and margin management: Implement dynamic pricing pilots tied to channel and seasonality. Build margin waterfalls to identify where value can be reclaimed (packaging redesign, freight optimization, warranty self‑service).
-
Marketing and product storytelling: Translate technical performance (e.g., verified ice retention test protocols) into consumer assurances and retailer selling tools, while using convenience narratives to reach urban, apartment‑dwelling campers who prioritize storage and portability.
What PW Consulting’s full report delivers (highly practical content)
Our full market study extends this preview with the operational detail required to execute in 2026: forecasting models through 2032, scenario analyses for raw material and regulatory shocks, SKU‑level product economics, priced channel strategies, supplier scorecards, commercial playbooks for premium vs. mass segments, and a due diligence dossier for M&A and strategic partnerships. To preserve competitive value in this preview, we have deliberately withheld full regional and application breakdown tables, detailed company revenue shares, and downloadable financial model files — these are included in the complete report package.
Concluding recommendation
For executive teams making allocations in 2026, the decision levers are clear: accelerate compliant product variants now, lock in diversified supply options to mitigate feedstock volatility, and adopt a dual‑track commercialization approach that monetizes both premium performance and convenience‑driven mass offerings. The market’s steady growth profile and fragmented competitive structure reward focused product differentiation coupled with disciplined operational execution. PW Consulting’s full Convenient Camping Cooler Market report contains the granular, actionable intelligence to convert these strategic priorities into a 12‑ to 36‑month implementation roadmap.
Next steps
Contact our PW Consulting research desk or visit the report page to access the full dataset, downloadable models, and a tailored briefing session. In a category where small feature changes determine both price elasticity and brand perception, the right data today prevents costly missteps tomorrow.
For detailed analysis of this topic, please visit the official page: Convenient Camping Cooler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Face Mask Anti-Pollution Market to Reach USD 5.0 Billion by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-13
Face Mask for Anti-pollution Market: Strategic Outlook and Action Framework for 2026
Executive teaser — why this study matters to your 2026 playbook
As regulatory attention tightens and urban air quality concerns move from episodic debate to persistent boardroom risk, the anti-pollution face‑mask market has shifted from a defensive, episodic category to a strategic product line for consumer, industrial, and institutional players. Our PW Consulting study captures this inflection: the global market, which we track on a 2025 base year, has shown steady historical expansion and is projected to grow at an approximate compound annual growth rate of 6.98% over the next several years. That growth trajectory implies meaningful scale expansion by the end of our forecast window, bringing product and channel choices into sharper focus for companies planning investments, partnerships, or repositionings in 2026.
Face Mask for Anti-pollution Market
High‑level market picture (what we modelled)
- Base year and horizon: analysis anchored to 2025 with historical context from 2020–2025 and a forward-looking forecast through 2032.
- Growth dynamic: sustained mid-single‑digit CAGR underpins a market that is expanding in size and complexity rather than consolidating into a single dominant model.
- Concentration: the competitive landscape is fragmented enough that nimble entrants and differentiated incumbents both have room to scale — the market is not tightly monopolized.
Why the growth is strategic — five converging forces
- Regulatory tightening and public procurement: Governments and agencies across major economies are increasing air‑quality standards and procurement preparedness. These moves are accelerating demand for certified high‑filtration solutions and are raising the bar for compliance documentation and testing pathways.
- Material and product innovation: Advances in nanofiber filters, improved electrostatic media, and miniaturized ventilation assist technologies are enabling masks that combine higher particle capture with better wearer comfort. Rechargeable micro‑ventilators and modular filter cartridges are transitioning from niche to mainstream product attributes.
- Sustainability and lifecycle scrutiny: A renewed focus on environmental impact is altering the disposable-versus-reusable economics and influencing policy, procurement, and retail assortment decisions. Manufacturers and brands face pressure to demonstrate lifecycle improvements and circularity pathways.
- Smart product integration: IoT‑enabled features (air quality sensors, usage logging, filter life indicators) are moving from industrial proofs‑of‑concept into commercial models, creating new service and subscription revenue opportunities.
- Supply‑chain reshoring and capacity moves: Capacity additions and regional manufacturing initiatives in 2024–2025 have created opportunities to shorten lead times and to satisfy domestic content preferences in critical markets.
Regulatory and external events shaping 2026 decisions
- Policymakers are signaling more active oversight of air‑filtering respirators, with draft guidance and policy statements circulating that could affect premarket pathways and labeling for high‑filtration consumer and industrial masks. Companies must plan for potential adjustments to testing, claims substantiation, and documentation timelines.
- Public and private investment in local manufacturing capacity has accelerated — including the commissioning of new face‑mask production facilities — which alters sourcing calculus for firms that previously relied on long international supply chains.
- Environmental campaigns and public education initiatives — exemplified by large consumer‑facing campaigns launched in 2025 — are shifting consumer preferences toward reusable and certified solutions. Brands without credible sustainability narratives risk losing premium share.
Competitive landscape — what to watch among incumbent and challenger players
The field includes a mix of multinational industrial suppliers and specialized niche brands. Each archetype brings different advantages and strategic implications:
Face Mask for Anti-pollution Market
- Large industrial multinationals (e.g., 3M Company, Honeywell): These players leverage scale, regulatory relationships, and established distribution in medical and industrial channels. Their portfolios often include certified NIOSH/FFP products and they are increasingly integrating smart features and enterprise services. For competitors, this means competing on service, customization, or channel specialization rather than price alone.
- Specialist reusable brands (e.g., Cambridge Mask Co., Respro, Totobobo, RZ Mask): These companies emphasize advanced filtration media, reusable architectures, and fit engineering. Their strengths are product differentiation, brand authenticity on health/sustainability, and direct‑to‑consumer channels. They set the benchmark on higher‑price, longevity‑oriented propositions.
- Regional and emerging players: Local manufacturers and startups are nimble on cost and speed to market, often filling white spaces created by distribution gaps or specialized local regulations.
Recent industry moves — for example, consumer education campaigns that emphasize environmental impacts and the commercial rollouts of IoT‑enabled industrial respirators — are illustrative of strategic plays in positioning, not just product innovation. Our analysis drills into these tactics and maps which models are likely to scale.
Face Mask for Anti-pollution Market
What's in the PW Consulting report — practical components for 2026 planners
- Market sizing and scenario models that show upside and downside trajectories under alternate regulatory and technology adoption pathways.
- Go‑to‑market playbooks segmented by channel (retail, healthcare, industrial procurement, B2B subscription services) describing pricing, margin profiles, and inventory strategies.
- Regulatory impact assessment with recommended product development pathways and compliance milestones for planned launches in 2026–2027.
- Technology adoption roadmaps that prioritize filter media, fit engineering, and smart add‑ons according to willingness‑to‑pay and competitive density.
- Five M&A and partnership archetypes with example scorecards for target screening, valuation sensitivities, and integration risk mitigation.
- Commercial risk matrices covering supply‑chain interruption, raw‑material cost inflation, and reputation exposure tied to environmental claims.
To respect competitive sensitivities and the trailer principle, the public synopsis deliberately omits granular regional and application splits — these are provided in the full dataset and model pack available through our subscription portal.
Recommended strategic moves for executive teams in 2026
- Prioritize compliance‑ready roadmaps: Assume a progressively more stringent regulatory environment for consumer and industrial respirators. Allocate product development resources to meet likely premarket documentation and third‑party verification requirements, and sequence launches to leverage early certifications as differentiation.
- Design for reuse and serviceability: Where economics permit, pivot toward reusable architectures with replaceable filter elements and transparent lifecycle metrics. This reduces exposure to single‑use backlash and creates subscription or replacement parts revenue streams.
- Embed value through sensors and service: For industrial and premium consumer segments, integrate sensor capabilities to enable predictive maintenance, regulatory reporting, and data subscriptions — unlock higher lifetime value and stickiness.
- Localize supply strategically: Use selective reshoring or regional partnerships to shorten lead times for high‑certification SKUs while preserving low‑cost offshore production for commoditized lines.
- Segment channel strategies: Differentiate product portfolios by channel — healthcare and industrial channels require certification and service, while mass retail benefits from clear messaging, sustainability claims, and affordability.
- Pursue targeted M&A: Look for bolt‑on acquisitions that add filtration IP, certification capabilities, or established DTC brands with strong sustainability narratives. Avoid broad rollups without clear integration cases for regulatory and quality systems.
How this report helps you de‑risk decisions in 2026
Our analysis translates broad market growth into operational and investment implications: manufacturers can size the incremental capacity needed for certified products; R&D leaders can prioritize filter and fit innovations; procurement heads can redesign sourcing with risk buffers; and commercial teams can sequence launches by channel profitability. Importantly, the study’s scenario models let teams stress‑test strategies under alternate regulatory and technology adoption timelines — enabling resource phasing that preserves optionality.
Closing note — what you won’t find here (and why you should read the full report)
In keeping with our trailer approach, this introduction emphasizes strategic direction and actionable themes while withholding the granular regional, product‑type, and application breakdowns that drive specific business cases. If your 2026 objectives require fine‑grained targets — such as optimized SKU counts by channel, region‑level incidence maps, or precise margin simulations — those data and our interactive model are included in the full PW Consulting deliverable. Access to that dataset will allow you to generate scenario‑specific P&L impacts, quantify capex needs, and validate acquisition valuation sensitivities.
Next steps
- Schedule a briefing with our industry team to walk through the interactive model and the prioritized implementation roadmap for 2026.
- Request a customized annex that maps our findings to your product portfolio, regulatory exposures, and supply chain topology.
PW Consulting’s Face Mask for Anti‑pollution Market study transforms a growing, complex market into a set of prioritized strategic actions. For leaders facing 2026 decisions, the critical choice is not whether the market matters — it does — but how to sequence investments to capture durable value as regulation, sustainability, and technology reshape the competitive frontier.
For detailed analysis of this topic, please visit the official page: Face Mask for Anti-pollution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microscope Glass Slide Market to Reach USD 253.6M by 2032 (CAGR 5.2%)
By pmarketresearch, 2026-07-13
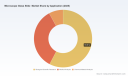
Microscope Glass Slide Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic preview of our new Microscope Glass Slide Market study. This briefing highlights why the study is a must-read for procurement officers, operations leaders, product managers, investor teams, and regulatory affairs groups planning action in 2026. It demonstrates the analytical depth underpinning the full report while deliberately withholding core segment-level granularities to drive targeted follow-up and licensing of the complete study.
Microscope Glass Slide Market
Executive snapshot
-
The global microscope glass slide market is in steady, predictable expansion. Using 2025 as the report base year (USD, revenue unit: Million), the market grew from the low hundreds in 2020 to approximately 178.4 million in 2025 and is projected to reach roughly 253.6 million by 2032. The compounded annual growth rate (CAGR) for the forecast window is 5.2%.
Microscope Glass Slide Market -
Growth is driven by the confluence of sustained clinical pathology volumes, expanding life-science research activity, and increasing adoption of digital and automated microscopy workflows that impose higher quality and specification demands on consumables.
Microscope Glass Slide Market -
Market structure shows moderate concentration: the leading three manufacturers control a meaningful portion of the market, with the top five commanding a clear majority—dynamics that materially influence pricing power, distribution relationships, and standards-setting.
Why this study matters for 2026 strategic choices
-
Timing: 2026 will be a pivotal year for procurement and manufacturing decisions. Buyers face tighter cost visibility from raw-material and energy volatility, while suppliers must resolve capacity, certification, and product-differentiation choices to capture premium pathology and research demand.
-
Precision matters: The transition to digital pathology scanners and automated slide-handling increases technical specifications (flatness, low fluorescence, edge geometry). Organizations that align purchasing specifications with scanner compatibility and laboratory automation will reduce rework, downtime, and slide rejection—real operational levers that the full report quantifies.
-
Regulatory and reimbursement context: Quality management and in vitro diagnostic (IVD) compliance are non-negotiable. The report maps certification pathways and the practical requirements of ISO 13485 and relevant regulatory statutes in major markets, and it shows how reimbursement frameworks affect hospital tender behavior and unit economics in clinical settings.
Market trajectory and practical interpretation
-
Market scale and growth: From a public-data-derived baseline in 2020 through 2025, the market has expanded consistently to an estimated 178.4 million USD in 2025, and the forecast envisions a continued climb to approximately 253.6 million USD by 2032 at a 5.2% CAGR. For executives, this translates into a market that is large enough to support multiple specialized players yet compact enough that operational excellence and certification matter for market share movements.
-
Operational translation: Buyers and OEMs should interpret the forecast not as an invitation to commoditize procurement but as an indicator that premium specifications—sterility, low autofluorescence, certified packaging, and automation compatibility—offer margin and risk-mitigation benefits. The full study itemizes which technical improvements produce the most tangible reductions in pathology workflow waste and scanner integration failures.
Key dynamics shaping supplier and buyer strategy
-
Raw materials and cost pressure: Energy-driven increases in float-glass input costs and localized supply chain disruptions in 2025 created margin pressure for manufacturers in several regions. The study models the pass-through scenarios and identifies the supplier strategies—vertical integration, longer-term energy hedges, and alternate sourcing—that materially mitigate margin erosion.
-
Regulatory and quality regimes: Compliance with ISO 13485 and applicable regulatory provisions for IVD-related consumables is now table stakes. Our analysis shows how those requirements translate into capital and process investments, how they affect time-to-market for specialty slides, and how compliant producers secure preferential positioning with large hospital systems and OEM scanner partners.
-
Tendering and price signals: Clinical supply tenders and hospital purchasing practices remain sensitive to per-slide economics and assured supply. The report contextualizes publicly available reimbursement and tender-unit pricing data to show where cost competition threatens quality, and where premium slides can command firm placement due to performance advantages in high-throughput pathology labs.
-
Technology and product evolution: Demand for low-fluorescence glass, chemically reinforced substrates, and specialty coatings is rising in step with digital pathology and high-resolution imaging. Manufacturers who combine material science with ISO-grade production and clean-room packaging are positioned to capture premium segments; our case studies show the quantifiable uplift those attributes provide.
Competitive landscape — who matters and why
-
Market leaders and distinct capabilities: The industry comprises established global names with differentiated value propositions—some emphasize scale and global distribution, others focus on specialty engineered glass, and several family-owned or niche European and Asian manufacturers provide clean-room packaging and adhesive technologies. The report provides a point-by-point strategic assessment of each major participant’s capacity, certification posture, production footprint, and go-to-market strategy.
-
Recent moves that change the competitive map: Notable 2024–2026 developments include acquisition-driven product launches, refreshed product catalogs aimed at clinical and research customers, and renewed certification activity. These moves signal consolidation in premium product lines and an emphasis on vertically integrated supply to secure product quality and geography-specific supply assurances.
-
Barrier-to-entry and differentiation: While commodity plain slides remain accessible, differentiated offerings—adhesive surfaces, low-fluorescence substrates, specialized coatings, and matched coverglass systems—require investment in process control and certification, creating structural advantages for incumbents and potential niches for highly focused entrants.
What the full PW Consulting report delivers (practical, actionable content)
-
Validated market model: Historical (2020–2025) and forecast (2026–2032) revenue modeling with scenario analysis under alternate cost, demand, and regulatory pathways.
-
Segment-level playbooks: Deliverable-level strategies for procurement, product management, and M&A teams showing how to prioritize investments across product types, margin pools, and geography-weighted demand drivers (note: our public-facing preview omits the granular segment shares and price schedules preserved for licensed report users).
-
Supplier risk matrix: Quantified assessment of supplier concentration, single-source exposures, and contingency options that can be executed within 90–180 days to secure clinical supply continuity.
-
Specification-to-cost mapping: A practical tool that links slide technical specifications (e.g., flatness tolerances, fluorescence thresholds, sterilization options) to unit-cost outcomes and downstream pathology workflow impacts; this enables procurement to set evidence-based technical requirements rather than pure lowest-price selection.
-
Competitive profiles and procurement negotiation templates: Company capability maps, recent product and certification events, and templated RFP language to accelerate commercial engagement and reduce vendor-selection cycles.
How executive teams should use this preview to prepare for 2026
-
Procurement leaders: Use the report’s specification-to-cost mapping to redesign RFPs that favor performance-adjusted bids. Short-term actions include revising technical annexes to address compatibility with digital scanners and requiring ISO 13485 certification in vendor pre-qualification.
-
Manufacturers: Calibrate investment in process control and packaging automation. The market favors producers that can assure low scrap rates and consistent performance at scale—investments that pay back through premium positioning in clinical tenders.
-
Investors and M&A teams: Look for targets that combine specialty material competence with clean-room production and a path to certification. Smaller players with unique adhesive or low-fluorescence technologies are attractive consolidation candidates.
-
Regulatory and quality heads: Prioritize certification refreshes and documentation to ensure compatibility with major-market IVD pathways. Delays in compliance create meaningful commercial friction in hospital procurement processes.
Next steps — how to access the full intelligence
-
The preview you are reading showcases our analytical framework, market trajectory, and the decision-useful outputs embedded in the full Microscope Glass Slide Market study. The complete report contains the granular regional and application segmentation, price curves, supplier scorecards, and downloadable procurement templates that will enable rapid execution in 2026.
-
Engage PW Consulting for a briefing workshop: purchasers and manufacturers will benefit from a tailored 90-minute executive session where we map the study’s findings to your supply base and action plan, including a 90–180 day vendor risk remediation checklist.
In sum, the microscope glass slide market is not a simple commodity arena—quality, certification, and downstream compatibility drive real economic value. PW Consulting’s full study arms decision-makers with the revenue-backed forecast, supplier intelligence, and operational playbooks required to act decisively in 2026. For access to the proprietary segment tables, detailed regional and application breakdowns, and the procurement-ready tools referenced above, please contact PW Consulting to license the complete report.
For detailed analysis of this topic, please visit the official page: Microscope Glass Slide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tonic Water Market to Reach USD 367.72 Million by 2032, Growing at 8% CAGR
By pmarketresearch, 2026-07-13
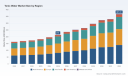
Tonic Water Market 2026: Strategic Imperatives from PW Consulting’s Industry Brief
As the tonic water category moves from a traditional mixer into a dynamic, flavor-driven beverage segment, boards and executive teams must translate rising consumer interest into defensible revenue streams. PW Consulting’s latest market research—anchored on a 2025 base year and spanning historical performance from 2020–2025 with forecasts through 2032—provides the decision-grade intelligence that leaders will use to set 2026 priorities. This preview summarizes the high-level market trajectory, competitive dynamics, and the kinds of operational playbooks included in the full study, while preserving the detailed sub-segment data for subscribers and clients.
Tonic Water Market
Why 2026 Is a Pivotal Year
Between 2020 and 2025 the global tonic water market demonstrated steady expansion, reflecting both on-trade recovery and the acceleration of premiumization and home mixology. In 2025 the category reached a clear inflection point (base year), creating a launchpad for growth under multiple scenarios. Our forecast models—built on the 2025 baseline—project an aggregate compound annual growth rate (CAGR) of 8.0% during the 2026–2032 period, driven by premium and differentiated offerings, health-oriented formulations, and channel diversification. Under the central case, market value increases materially over the forecast horizon, signaling room for incumbent consolidation, challenger disruption, and strategic portfolio reshaping.
Tonic Water Market
Macroeconomic and Category Trajectory (Headline Figures)
- Base year: 2025 (report anchor).
- Forecast window: 2026–2032, with modeled outcomes across conservative, base, and aggressive scenarios.
- CAGR (2026–2032): 8.0% (USD, revenue unit: Million).
- Market expansion is meaningful—our models show sustained acceleration beyond the short-term post-pandemic rebound, supporting investment in capability and new SKUs.
Key Demand Drivers and Structural Shifts
- Premiumization and mixology culture: Consumers and trade operators are trading up to bespoke tonics and botanical variants that enhance cocktail narratives. Premium brands have translated provenance and ingredient stories into price premiums and boutique on-trade placement.
- Health and low-calorie alternatives: Reduced-sugar and naturally sweetened formulations continue to win distribution, particularly where brands can credibly combine taste and clean-label claims.
- Home consumption: Elevated home mixology—accelerated during recent years—remains sticky. Consumers purchasing nature-forward mixers expect variety and bar-quality performance at home.
- Channel evolution: E-commerce and direct-to-consumer models complement grocery and on-trade channels; omnichannel go-to-market strategies are required to capture full value.
- Supply chain and ingredient sourcing: Access to quinine, botanicals, and specialty flavorings creates both opportunity and vulnerability—sourcing strategies materially impact cost and margin profiles.
Competitive Landscape: Concentration and Strategic Positions
The category exhibits moderate concentration—our concentration metrics indicate that the top three players account for a majority share and the top five increase that share materially. This structure creates a dual environment: established global players retain shelf and on-trade advantages, while agile premium challengers exploit white space in flavor innovation and channel-first tactics.
Tonic Water Market
Representative company positions analyzed in the report include:
- Schweppes (London, UK): Heritage advantage with a multi-variant portfolio. Strengths: broad commercial reach, classic and low-sugar offerings, scale manufacturing. Strategic question: how to refresh legacy branding to capture premium wrists and younger demographics without eroding core equity.
- Fever-Tree (UK): Premium specialist known for provenance-led storytelling and selective distribution agreements. Strengths: brand equity in premium bars and retail; consistent innovation. Considerations: margin management as premium competition increases.
- Double Dutch (UK): Niche premium and botanical focus; recent portfolio moves indicate acceleration (including a Mediterranean-inspired launch in late 2025 and a strategic rebranding in early 2026). These actions show deliberate effort to broaden appeal while protecting craft credentials.
- Boylan Bottling Co. (US): Domestic producer emphasizing locally sourced ingredients and nostalgic positioning. Strengths: US supply chain control and retail placement; opportunity to scale via selective national partnerships.
- Britvic (UK): Large mixer portfolio with multiple tonic SKUs. Strengths: route-to-market and private label capability. Strategic trade-off: balancing scale with the need to protect premium brand margins.
- Smaller entrants (e.g., Dappled, Match Tonic, Owen’s Mixers, Arctic Blue): These brands are important sources of innovation—specialist flavor work, low-calorie formulations, and regional distribution plays. Their agility pressures incumbents on product life-cycle speed and authenticity.
Recent Strategic Moves That Matter
- Double Dutch (2025–2026): A Mediterranean-inspired tonic launch in late 2025 followed by a brand repositioning in early 2026 illustrates a playbook we expect to be replicated: introduce provenance-led SKUs, then broaden naming and marketing to maximize cross-market appeal. This two-step approach reduces initial risk while enabling scale.
- Channel partnerships and distribution pacts: Observed distribution alliances—particularly between premium specialists and regional distributors—are enabling rapid penetration into on-trade accounts and specialty retail, while protecting brand positioning.
What the Full Report Contains (Practical, Actionable Elements)
PW Consulting’s full study is designed as a decision-support toolkit for commercial, innovation, and M&A teams. Highlights include:
- Proprietary demand models (historical 2020–2025 and forecasts 2026–2032) with scenario toggles to test price, penetration, and channel assumptions.
- Interactive revenue and margin simulators (USD, Million) calibrated to distinct SKU archetypes and operating cost baselines.
- Go-to-market playbooks tailored to brands at different scale stages—covering assortment strategy, retailer negotiation frameworks, on-trade activation plans, and e-commerce conversion tactics.
- Innovation and product roadmaps: flavor prioritization matrices, cost-to-launch templates, and sensory validation protocols for botanical and low-sugar variants.
- Supplier and sourcing risk register with mitigation strategies for key raw materials, including contract structure options and regional sourcing trade-offs.
- M&A and partnership screening: criteria-based shortlists, valuation heuristics, and integration playbooks for acquiring scale or capability (e.g., flavor labs, regional bottlers).
- Regulatory and labeling guidance relevant to claims (e.g., “natural,” “zero sugar”) across major jurisdictions.
Strategic Recommendations for 2026 Decision-Makers
- Prioritize a two-tier portfolio: Maintain core mainstream SKUs to protect mass distribution while developing a distinct premium line with clear provenance and botanical storytelling. Use phased rollouts to test pricing elasticity before national scale-up.
- Invest in formulation for taste parity: Low- and no-sugar tonics must deliver on taste. Allocate R&D to mouthfeel enhancers and natural flavor extraction; consider contract R&D partnerships to accelerate time-to-market.
- Channel-specific assortment: Tailor SKUs for on-trade, grocery, and direct-to-consumer channels rather than a single blanket approach. Trade buyers and bartenders prioritize different attributes than home consumers; align packaging and price points accordingly.
- Secure upstream supply: Lock-in favorable long-term agreements for key botanicals and quinine to protect margin volatility. Consider dual-sourcing strategies for critical ingredients.
- Lean into experiential marketing: Use bartender partnerships, tasting tours, and cross-brand cocktail programs to drive premium perception and justify higher ASPs (average selling prices).
- Evaluate M&A for capability gaps: For companies seeking rapid capability expansion—whether in flavor craft, regional bottling capacity, or e-commerce infrastructure—targeted acquisitions can compress the path to scale. Use our M&A playbook for diligence and integration sequencing.
Implications by Stakeholder
- Brands: Invest in SKU differentiation, storytelling, and taste-first R&D. Defend core distribution while piloting premium variants in strategic markets.
- Retailers: Curate a balanced tonic set that captures both mainstream demand and higher-margin craft options; design in-aisle education for new flavor variants.
- Suppliers: Prepare for rising demand volatility and offer collaborative supply agreements; premium brands will pay for certified sourcing and traceability.
- Investors: Look for companies with clear routes to margin expansion via premiumization and channel diversification; prioritize those with controllable supply chains and defensible brand equity.
How to Use This Intelligence in 90 Days
- Run our scenario tool to stress-test pricing and volume assumptions for your top three SKUs.
- Pilot one premium botanical tonic in a controlled on-trade cluster while tracking sales velocity and margin contribution.
- Initiate supplier conversations to create hedging options for primary botanicals and quinine equivalents.
- Assess M&A targets against the report’s acquisition criteria and shortlist two for preliminary diligence.
PW Consulting’s full Tonic Water Market report contains the segmented tables, regional and application breakdowns, and company-level scorecards necessary to operationalize the recommendations above. This preview is intentionally selective—designed to demonstrate the report’s strategic depth while guiding you to the detailed models and segment-level insights available in the full deliverable.
Next Steps
Executives seeking to convert 2026 market momentum into sustainable advantage should review the full study and accompanying model suite. The complete package includes download-ready financial models, SKU-level P&L templates, and a prioritized implementation roadmap tailored to the tonic water value chain. Contact PW Consulting or visit the report landing page to access the full intelligence set and to arrange a strategy workshop that adapts the findings to your business context.
For detailed analysis of this topic, please visit the official page: Tonic Water Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Animal Feed Enzymes Market to Reach USD 1,820 Million by 2025 (6.0% CAGR)
By pmarketresearch, 2026-07-13
Animal Feed Enzymes Market — Strategic Briefing for 2026
Market snapshot (what the numbers tell us)
By the 2025 base year this market had evolved from a niche additives category into a strategic lever for feed efficiency and sustainability. Our topline metrics anchor the analysis: global revenues rose steadily through the early 2020s, with the addressable market reaching approximately USD 1,820 Million in 2025. Under the baseline forecast (our 2026–2032 projection set), the market expands at a mid-single-digit pace — a 6.0% compound annual growth rate — reaching a materially larger market by 2032. The near-term step‑change between 2025 and 2026 is visible in our forecasting model and reflects both product upgrades and sharp adoption in higher-value feed formulations.
Animal Feed Enzymes Market
These headline figures hide important internal dynamics — consolidation among incumbents, premiumisation of next‑generation enzyme grades, and higher volatility in inclusion rates linked to fluctuating feed-ingredient prices. The report quantifies these interactions and translates them into actionable scenarios for corporate planning in 2026.
Animal Feed Enzymes Market
Why this research matters for 2026 decision-makers
- Investment allocation: Decide whether to prioritise R&D for next-gen phytases, expand manufacturing capacity, or pursue M&A to close portfolio gaps.
- Commercial strategy: Set pricing architecture that captures value from premium enzyme grades while protecting share in price-sensitive segments.
- Procurement optimisation: Re-design supplier contracts and hedging strategies to limit exposure to raw-material swings that materially affect enzyme use.
- Regulatory & market access: Sequence product launches in regions with lengthier clearance processes to maximise first-mover returns on novel enzyme technologies.
What the full report delivers — operationally usable intelligence
This is not a high-level narrative. The report is designed for immediate operational adoption across strategy, commercial, and technical functions. Key deliverables include:
Animal Feed Enzymes Market
- Addressable-market maps: granular demand models by feed formulation archetype and livestock nutrition strategy (note: public summary hides the line-item splits; full dataset available in the source report).
- Price-elasticity and inclusion-rate models: dynamic sensitivity analyses showing how enzyme uptake shifts under different corn/soybean price scenarios.
- Regulatory pathway playbooks: EFSA/other-region decision timelines, dossier requirements, and go‑to‑market sequencing to reduce approval risk for next‑gen enzyme grades.
- Supplier scorecards and procurement templates: capability matrices, manufacturing footprints, service-level KPIs and contract clauses to mitigate supply disruptions.
- Product and technology benchmarking: head-to-head profiles of commercial enzyme lines, stability under pelleting temperatures, and differential value capture potential.
- M&A & partnership playbooks: valuation frameworks, integration checklists, and a shortlist of target archetypes by strategic objective (capacity, portfolio, channel).
- Scenario planning tools: three central market scenarios (base, accelerated premium adoption, and raw-material shock) with P&L and working-capital implications.
- Implementation roadmaps: 30/90/180-day action plans tailored to manufacturers, feed formulators and distributors.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three firms account for a meaningful share of market revenue, and the top five extend that dominance. This structure creates both barriers and opportunities — incumbents can leverage scale, but pockets of openness remain for differentiated technology or commercial models.
- Novonesis: Following a material acquisition completed in 2025, Novonesis enlarged its enzyme platform and distribution reach. The transaction reshaped route-to-market dynamics and raises the stakes in consolidation-driven strategy.
- BASF SE: While a major technology and distribution player, BASF’s strategic review of its feed-enzyme business signals potential portfolio realignment that could create windows for competitors or new entrants.
- Adisseo: With regulatory approvals for next-generation phytase technology and demonstrated pellet stability, Adisseo is capturing premium positions in feed formulators aiming for higher nutrient release and sustainability claims.
- Kemin, Cargill, Novus, AB Enzymes, IFF, Alltech and DuPont: These firms form a competitive cohort with differentiated strengths — multi‑enzyme blends, strong distribution channels, or proprietary enzyme platforms — and remain active in product launches and regional expansions.
Collectively these players set market norms on pricing, distribution models and technical support packages. The CR3 and CR5 metrics in our report quantify how concentrated influence is at the top and the practical implications for pricing power and innovation diffusion.
Market dynamics and headwinds to factor into 2026 strategy
- Premiumisation of enzyme grades: Next‑generation phytases and stabilised formulations that survive industrial pelleting are commanding higher price points. Capturing these premiums requires validated feed‑level performance data and a targeted commercial approach.
- Raw-material volatility: Corn and soybean meal price swings change the economics of enzyme inclusion. Procurement teams must align contract design and elasticities to avoid margin erosion when feed prices spike.
- Regulatory complexity: Regional clearance processes differ; earlier approvals create competitive moats. Firms with regulatory-ready dossiers gain first-mover advantages for premium products.
- Consolidation and strategic re-positioning: Recent transactions and strategic reviews create transient pockets of opportunity for bolt-on deals, distribution realignment, or partnership formation.
- Sustainability and nutrient management: The role of enzymes in reducing phosphorus excretion and lowering feed carbon intensity elevates their strategic value to integrators and corporate sustainability teams.
Recommended strategic plays for 2026
- For manufacturers: Prioritise product lines with defensible technical differentiation (stability to pelleting, multi‑enzyme synergy). Use our ROI models to justify targeted CAPEX on pilot facilities versus licensing deals.
- For feed formulators and integrators: Run designed pilots with next‑gen phytases across representative operations, using the report’s inclusion-rate templates to quantify feed-cost savings and margin impact before roll‑out.
- For distributors and channel partners: Rebalance commercial incentives toward bundled solutions (enzyme + technical services) that capture recurring revenue and reduce churn.
- For investors and M&A teams: Use the market-concentration and scenario outputs to identify attractive entry points — either through buying differentiated niche innovators or acquiring scale in consolidating segments.
How to convert the insight into 90‑day action
- Day 0–30: Use the supplier scorecards to shortlist vendors and initiate NDA-enabled data exchanges. Stress-test your current enzyme contracts against our price-elasticity scenarios.
- Day 30–60: Deploy a 4–6 week pilot for a next‑gen enzyme in a high‑value feed stream; use the report’s metrics to fast-track ROI validation and internal approvals.
- Day 60–90: Finalise commercial terms with preferred suppliers, update procurement templates, and brief the executive committee with the scenario P&L impacts provided in the report.
The trailer — what this summary omits and why
In keeping with the “trailer” principle, this briefing intentionally showcases insights and commercial implications while withholding line‑by‑line segment tables, regional share breakdowns, and per-application revenue figures. Those granular datasets, model files and the full competitive scorecards are included in the source report and are essential for detailed go/no‑go decisions, contract negotiations and M&A valuation work.
Concluding note — why act in 2026
Enzyme technologies have moved from commoditised additives to strategic enablers of feed efficiency and sustainability. With a structurally growing market, measurable premium opportunities for differentiated products, and a consolidation backdrop that will reshape distribution and pricing, 2026 is a pivotal planning year. Firms that couple technical validation with commercial agility — leveraging regulatory sequencing and procurement‑led risk mitigation — will capture disproportionate value over the forecast horizon.
To access the complete dataset, supplier scorecards, and the full suite of implementation tools referenced here, please consult the PW Consulting Animal Feed Enzymes Market report. The full report contains the granular segmentation and model outputs necessary to translate these strategic recommendations into executable plans.
For detailed analysis of this topic, please visit the official page: Animal Feed Enzymes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Kinesio Tape Market — Strategic Preview for 2026: Why This Report Matters
Executive snapshot
As PW Consulting’s Senior Strategy Advisor, I present a concise, high-fidelity preview of our Kinesio Tape Market research — an actionable intelligence package built to inform executive decision-making throughout 2026. The market is on a clear expansion path: using 2025 as the base year, our topline model places global revenue in the mid-hundreds of USD Million and projects continued acceleration through the 2026–2032 forecast window at an 8.2% compound annual growth rate. Historical performance from 2020–2025 shows resilient demand despite episodic supply and reimbursement noise, positioning the industry at a strategic inflection point as product innovation, sustainability, and clinical adoption converge.
Kinesio Tape Market
Why 2026 is a strategic inflection year
-
Consolidation and professionalization: Recent M&A and brand-level investments have shifted the competitive environment from fragmented commodity selling toward integrated, clinically informed product lines and omnichannel distribution. This is the year many leaders will convert brand equity into scalable clinical and institutional contracts.
Kinesio Tape Market -
Evidence and certification tipping points: Requirements for skin-contact biocompatibility (ISO 10993) and the ongoing enforcement of device classifications (e.g., Class I medical device subject to FDA 510(k) pathways in the U.S.) are raising the bar for product development and procurement. Firms that embed these standards early narrow commercial risk and accelerate access to institutional buyers.
Kinesio Tape Market -
Material and application innovation: Advances such as graphene-infused adhesives, eco-friendly substrates, and water-resistant constructions are creating product differentiation opportunities beyond price. Early adopters who can translate materials science into clinically validated outcomes will capture the premium segment.
Market trajectory — what the headline numbers mean for strategy
Readers should view the topline model as a directional framework for capital allocation. From 2020 through the 2025 base year the market demonstrated steady expansion, and our forecast extends that momentum through 2032, driven by product innovation, broader clinical adoption, and rising sports and rehabilitation demand globally. An 8.2% CAGR over the forecast window implies that mid-market and premium segments will expand faster than lower-margin commoditized supply — a critical insight for product, manufacturing and sales strategies.
For decision-makers, the implications are straightforward: growth exists, but margins will favor companies that combine differentiated product features (material science, ISO-certified biocompatibility) with institutional access (clinical partnerships, athletic program endorsements) and operational control (supply chain resilience, cost-to-serve optimization).
Competitive landscape: who matters and why
The market sits in a moderately concentrated competitive structure. A small set of established and legacy brands still command a meaningful share of value, but recent activity indicates an opening for both incumbents and well-funded challengers to extend reach and capture higher-margin use cases.
-
Kinesio Holding Corporation — the originator of the category — remains strategically important as both a brand and technology steward. Recent product launches emphasize eco-friendly formulations, aligning with institutional procurement trends and major event selection committees.
-
KT Tape (now under Bridges Consumer Healthcare LLC) — acquisition activity has accelerated omnichannel and R&D investment, and the brand’s evolution toward technologically enhanced adhesives (including graphene-infused prototypes) is a credible route to premiumization.
-
RockTape — notable for clinician-oriented product development and new self-application lines, RockTape’s partnerships with sports-rehab providers signal a play for institutional adoption.
-
TheraBand, Mueller, SpiderTech and other established suppliers — these players bridge clinical and consumer channels, leveraging broader product portfolios and distribution networks to defend market positions.
-
Regional and specialized manufacturers (Japan, Korea, Europe) — these firms continue to supply high-performance and certified tapes, increasingly competing on product attributes and sustainability credentials.
Recent market events — acquisitions, certifications for major teams, and launches of graphene- and biodegradable-based products — materially change competitive posture. The full report contains a strategic benchmarking matrix that evaluates product roadmaps, channel reach, certification status and innovation pipelines to identify takeover targets and partnership candidates.
Regulatory and reimbursement dynamics — constraints and opportunities
-
Regulatory frame: In the U.S., kinesio tapes are classified as Class I medical devices; firms must manage FDA 510(k) clearance pathways where applicable and demonstrate compliance with skin-contact biocompatibility standards such as ISO 10993. These certifications are increasingly a commercial gate rather than a technical nicety.
-
Reimbursement realities: Kinesio taping itself is often not a reimbursable procedure under dominant public payors, and supplies are typically coded under applicable tape HCPCS codes. This means commercial strategies should not assume growth via reimbursement-driven volume — instead, the primary levers are institutional contracts (clinics, sports federations), employer wellness programs, and consumer retail.
-
Clinical evidence and procurement: As clinical buyers demand documented outcomes, vendors who invest in randomized studies, registries, or institutional pilots will unlock procurement pathways that are less price-sensitive and more quality-driven.
Supply chain and product architecture considerations
Raw material architecture remains central: modern kinesio tapes typically rely on a latex-free acrylic adhesive paired with a porous textile backing engineered for stretch and breathability. Manufacturers should prioritize supply continuity for specialty adhesive chemistries and sustainable substrate options. Near-term risks include adhesive raw material volatility, certification lead times for new substrates, and potential tariff or logistics shocks in trans-regional sourcing.
What our full report delivers — operationally actionable content
The full PW Consulting Kinesio Tape Market report moves beyond high-level narrative. It equips leaders with executable playbooks and decision support tools, including:
-
A detailed go-to-market playbook segmented by buyer persona (clinician, athletic program manager, retail purchaser) with recommended channel mixes and KPIs to measure traction.
-
Product development scorecards linking material choices (e.g., textile construction, adhesive formulations) to clinical performance metrics and procurement preferences.
-
Regulatory roadmap templates for FDA registration and ISO 10993 certification timelines, resource estimates and risk checkpoints.
-
Commercial scenarios and pricing models calibrated to the 2026 revenue base and 8.2% CAGR forecast — supporting unit economics, margin expansion levers, and cash-flow timelines for new product introductions.
-
Competitive benchmarking and M&A target shortlists derived from strategic fit, technology gaps and aftermarket synergies — including integration playbooks to preserve customer relationships and accelerate cross-sell.
-
Operational tools: supplier scorecards, packaging optimization checklists for sustainability compliance, and SKU rationalization frameworks that prioritize high-margin SKUs and reduce complexity.
Importantly, the report intentionally withholds granular regional and application-level revenue splits in this preview to preserve the full, data-rich models available in the paid analysis. Executives seeking the explicit segmentation matrices, price-by-region benchmarks, and addressable-market micro-models should consult the complete dataset.
Recommended strategic moves for 2026
-
Prioritize certification and clinical validation: Start ISO 10993 testing and plan for FDA engagements now; the timeline to certification can be a competitive differentiator.
-
Invest in material differentiation: Allocate R&D resources toward high-value adhesives and sustainable substrates that align with institutional procurement and major event specifications.
-
Build institutional channels: Secure pilot partnerships with leading sports-rehabilitation clinics and national training programs — these partnerships accelerate evidence generation and brand authority.
-
Optimize go-to-market mix: Balance direct institutional sales with omnichannel consumer presence; use digital buyer journeys to convert professional endorsements into retail demand.
-
Hunt for smart acquisitions and alliances: Target adjacent suppliers that fill capability gaps (e.g., adhesive chemistry, diagnostic adjuncts) and accelerate access to new procurement channels.
Next steps — how to use this intelligence
If your 2026 planning cycle includes product launches, capital allocation, or M&A, treat this preview as the strategic frame. The full PW Consulting report contains the underlying models, sensitivity analyses and detailed competitor dossiers needed to convert these strategic recommendations into executable plans. For teams focused on immediate deployment, our consulting practice offers tailored workshops that map the report’s insights to your commercial and R&D roadmaps.
For access to the complete dataset, segmentation matrices, and the proprietary scenario-planning model, please refer to the report landing page or contact PW Consulting directly. The rich mix of regulatory, clinical, and commercial intelligence in the full analysis is designed to remove ambiguity and enable confident 2026 decisions.
For detailed analysis of this topic, please visit the official page: Kinesio Tape Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Perlite & Vermiculite Market to Reach USD 6.30B by 2032, 5.75% CAGR
By pmarketresearch, 2026-07-13
Perlite and Vermiculite Market: Strategic Imperatives for 2026 — PW Consulting Preview
As companies set budgets and capital priorities for 2026, the expanded perlite and exfoliated vermiculite complex presents a mix of steady demand, material-specific technical challenges, and opportunity windows for firms that move with speed and clarity. PW Consulting’s new market study — anchored to a 2025 base year and projecting through 2032 — synthesizes historical behavior (2020–2025) with forward-looking scenarios (2026–2032). The market is forecast to expand at a compound annual growth rate (CAGR) of 5.75% over the forecast window. To frame the scale: the global market grew from a multibillion-dollar level in 2020 to an elevated 2025 base, and is anticipated to continue its upward trajectory into the early 2030s. This preview explains why our analysis is strategically material for decisions you must take in 2026, what proprietary insight the full report contains, and how leading players are already positioning themselves.
Perlite and Vermiculite Market
Why 2026 Is a Decision Point
-
Demand stability meets structural change. Longstanding end uses — construction insulation and lightweight aggregates, horticultural substrates, and industrial filtration — continue to underpin baseline demand. Simultaneously, higher-performance applications (precision filtration, engineered lightweight composites) and regulatory pressures (workplace dust control and product stewardship) are driving material differentiation and premiumization.
Perlite and Vermiculite Market -
Supply-side dynamics are granular and site-specific. Perlite and vermiculite are mined, expanded, and processed in localized clusters. Ore quality and processing technology materially affect product performance: for example, crude vermiculite ore typically includes 3–4 percentage points of moisture that affect expansion characteristics during exfoliation — a technical detail that alters yields and product mix at plant level.
Perlite and Vermiculite Market -
Regulatory and trade considerations are non-trivial. Perlite is widely regulated as a “nuisance dust,” requiring consistent compliance investments across jurisdictions. Moreover, expanded perlite and vermiculite are classified under a specific HS code (6806.20), an operational detail that influences customs treatment, duties, and cross-border sourcing strategies.
-
Market structure favors both scale and nimbleness. The industry is fragmented — the three- and five-firm concentration ratios remain low relative to many mineral value chains — which both limits pricing power among global majors and creates acquisition opportunities for firms seeking route-to-market expansion or downstream integration.
What PW Consulting’s Report Delivers (Practical, Executable)
-
Robust market sizing and scenario modeling: historical series (2020–2025), base-year calibrated estimates (2025), and three scenario-led projections through 2032 that stress-test demand against macro shocks, energy price regimes, and policy shifts.
-
Demand-driver analytics: differentiated by application archetypes and value-chain position, with quantified growth levers and elasticity assumptions to help forecast product-specific volumes under alternative adoption curves.
-
Supply-constraint mapping: deposit quality, beneficiation and expansion capacity, and logistic chokepoints mapped to a supplier risk scorecard for near-term (12–18 month) and medium-term (18–36 month) horizons.
-
Price benchmarking and input-cost models: indexed to energy and freight vectors, with sensitivity matrices for ore-grade variation, expansion yield, and milling loss.
-
Commercial playbooks: go-to-market options for producers, tolling and contract-manufacture models for downstream users, and M&A scorecards for acquirers targeting consolidation or capability acquisition.
-
Regulatory and ESG checklists: compliance pathways for nuisance-dust controls, product labeling implications of HS-classification, and practical steps for reducing lifecycle emissions in expansion processing.
-
Operational deep-dive annexes: exfoliation process variables, particle-size control for filtration media, closed-cell expanded product characteristics, and guidance for pilot-scale trials.
Data-Driven Snapshot (Preview)
PW Consulting’s calibrated market series shows consistent expansion from the early 2020s into the mid-decade, with the base-year (2025) reflecting both cyclical recovery in construction and steady growth in horticulture and industrial segments. The forecast path we present to 2032 is driven by a 5.75% CAGR, which implies meaningful growth potential for firms that can align capacity and product quality with evolving end-use requirements. Because this preview intentionally omits granular regional and application splits, the full report contains the detailed breakdowns that underwriting teams and corporate strategists will require to model investment returns or to size M&A targets.
Competitive Landscape — How to Read the Field
-
Global majors vs. regional specialists: Firms such as Imerys (France) exemplify a platform play, investing in product innovation and engineered filter aids. A concentration of capabilities among a handful of global groups coexists with a long tail of specialist processors and miners, particularly in North America, Europe, and parts of Asia and the Mediterranean basin.
-
Service and product differentiation is winning share: Companies that pair basic expanded perlite with application-specific processing (milling to filter-grade size, closed-cell formulations, or horticultural blends) are capturing premium margins. Recent product innovations demonstrate the commercial payoff for precision particle control and brand positioning.
-
Recent movements to note: capacity and capability investments in 2025 indicate where firms expect near-term demand to be strongest — examples include precision filter-aid product launches and new or expanded processing facilities. These moves materially alter regional supply balances and should inform sourcing decisions in 2026.
-
Fragmentation creates acquisition windows: low overall market concentration (three- and five-firm CRs in the mid-20% range) means numerous attractive bolt-on targets exist for companies seeking scale or route-to-market in priority countries. However, successful roll-ups require fast post-acquisition integration of quality control and logistics to avoid margin erosion.
Strategic Playbook for 2026 Executives
-
Prioritize supply-security contracts with tiering by ore quality. Because ore characteristics materially affect expansion yields and product consistency, securing multiple source options reduces operational risk.
-
Invest selectively in downstream differentiation. Opportunities in precision filtration, engineered lightweight systems, and horticultural substrates reward modest R&D and pilot-plant investment.
-
Time capacity investments to demand signals, not sentiment. With a multi-year CAGR in the mid-single digits, capital projects should be phased and include contingency for energy and freight volatility.
-
Leverage regulatory compliance as a commercial asset. Demonstrable controls on dust emissions and product stewardship can shorten procurement cycles with larger industrial buyers and unlock premium contracts.
-
Use M&A to buy capabilities, not just volume. Assets that add proprietary processing (milling to precise particle distributions, closed-cell expansion capability) or established distribution in high-value end markets will outperform low-synergy volume acquisitions.
-
Operationalize traceability and quality analytics. Data-rich production monitoring—tracking ore moisture, expansion yield, and particle-size distributions—reduces returns and supports premium product claims.
Risks and Contingencies to Monitor in 2026
-
Input-cost shocks: energy and freight spikes rapidly erode margins in expansion-intensive processes; hedging and flexible tolling contracts are cost-effective mitigants.
-
Regulatory tightening: tighter dust-control requirements or shifts in classification could necessitate plant retrofits, particularly in jurisdictions raising occupational health standards.
-
Ore variability: site-level differences in moisture and mineralogy impact yields — realistic worst-case yield scenarios should be built into project appraisals.
-
Geopolitical and trade friction: HS-code aligned duty treatments and localized protective measures can change net landed costs faster than capex cycles permit adjustment.
Illustrative Industry Signals (Selective)
-
Product innovation continues to accelerate: premium filter-aid grades and milled perlite products released in 2025 signal buyer willingness to pay for performance enhancements rather than commodity pricing alone.
-
Capacity moves are geographically targeted: new or enlarged processing facilities opened in 2025 show where suppliers are betting on demand concentration; such investments shift regional logistics economics and competitive dynamics.
-
Public production disclosures underscore materiality: disclosed production volumes and values from established regional players provide hard checkpoints against which private company claims should be validated.
Concluding Guidance — How to Use This Preview
This article is intentionally a strategic “preview” — it highlights the analytical lens and executive actions that PW Consulting recommends for 2026 without exposing the granular regional, application, and pricing tables that underpin investment-grade decisions. If your firm is evaluating capacity projects, acquisition targets, or supply contracts in perlite and vermiculite, the full PW Consulting report provides the detailed split-views, price curves, and risk-scored supplier matrices you need to underwrite decisions with confidence.
For companies planning to allocate capital or revise procurement strategies in 2026, time is the critical variable: early movers that align technical capability with proven demand pockets — while effectively managing dust regulation, ore variability, and logistical friction — will convert the underlying mid-single-digit growth trajectory into outsized returns. PW Consulting’s full study delivers the operational detail and scenario-tested recommendations required to make those calls.
For detailed analysis of this topic, please visit the official page: Perlite and Vermiculite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Arsenic Removal Market to Expand at 6.5% CAGR Through 2032
By pmarketresearch, 2026-07-13
Arsenic Removal Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s senior industry analysts, we present a high-level strategic primer on the Arsenic Removal Market ahead of our full 2026 study release. This introduction lays out the market’s trajectory, the competitive contours, and the practical decision levers that executives should be weighing now. Numbers cited below are macro-level only; detailed regional, application and vendor-level splits are intentionally reserved for the full report to preserve the “trailer” character of this brief and to guide decision-makers to the complete intelligence package.
Arsenic Removal Market
Market arc and headline metrics
The market for arsenic removal technologies has shown steady expansion through the early 2020s and enters 2026 from a position of durable growth. Using 2025 as the base year, our topline model indicates a market measured in the low-hundreds (USD, million) that expands at a compound annual growth rate (CAGR) of approximately 6.5% over the forecast window to 2032. That growth reflects the intersection of regulatory persistence, incremental infrastructure investment, and technology-driven replacement cycles.
Arsenic Removal Market
For executives this means two important takeaways: first, the market is large and expanding fast enough to justify dedicated commercial focus, but second, it is not a rapid one-off boom — it rewards optimized product lifecycles, service models and financing pathways that capture recurring revenue over many years.
Arsenic Removal Market
Drivers and headwinds that will shape 2026 choices
-
Regulatory constancy and compliance demand — The U.S. EPA’s maintenance of the arsenic MCL (10 µg/L) continues to anchor municipal and community-level investment in treatment upgrades. Many public systems are identified in regulatory reviews as requiring system refreshes or technology changes to sustain compliance rather than one-time remediation.
-
Small-system affordability and financing dynamics — Financing programs targeted at small community systems remain an essential enabler of demand. Access to low-cost capital and grant/loan programs materially affects procurement cycles and the selection of technologies with predictable lifecycle costs.
-
Operational cost pressure and lifecycle externalities — The lifecycle cost of arsenic removal solutions is amplified by hazardous-waste classification of spent media and sludges, and by regional shortages of trained operators. These factors increase both O&M burdens and the total cost of ownership (TCO) over asset life.
-
Sectoral demand pockets — Beyond municipal drinking water, targeted industrial users (for example, food & beverage and specialty agriculture) are emerging as meaningful pockets of demand where high-value, performance-guaranteed systems are prioritized over lowest upfront cost.
-
Technology substitution and hybridization — Established approaches (adsorption, ion exchange, membranes, oxidation/coagulation) are being recombined and optimized to address local water chemistry, waste-handling constraints and footprint limits. Effective differentiation increasingly depends on service packaging and waste-minimization credentials, not technology novelty alone.
Structural implications for supplier economics
The combination of regulatory-driven base demand and pronounced operational externalities creates a supplier market where margin capture stems less from raw-media sales and more from bundled services: validation studies, guaranteed-performance contracts, media regeneration/logistics, and remote monitoring. Suppliers that can materially lower disposal costs or extend media life while assuring compliance will see disproportionate commercial returns.
In procurement conversations during 2026, buyer teams will privilege TCO models that explicitly quantify disposal and labor risk. At the same time, suppliers that can offer financing partnerships or align with public funding mechanisms will improve sales velocity into smaller systems where capital constraints otherwise delay upgrades.
Competitive landscape — who matters and why
The market landscape today is a mix of specialty media manufacturers, packaged-system integrators, engineering firms and consumer-focused vendors. Each cohort plays a different role in the commercialization chain:
-
Specialist media firms (e.g., companies deploying high-selectivity titanium-oxide or other proprietary adsorbents) focus on product performance and regeneration characteristics. Their commercial edge is in materials science, often supported by targeted field validation.
-
Process integrators and EPCs bring packaged, site-ready systems that reduce installation complexity for municipalities and industry customers. Their value proposition is speed-to-compliance and single-point accountability for performance guarantees.
-
Residential and commercial POU/POE brands compete on certification, ease-of-use and channel reach. Certifications and recognized media brands remain central to adoption in household and small-business contexts.
-
Bioprocess and precipitation specialists are relevant where wastewater and groundwater projects demand robust heavy-metal co-removal strategies and where sludge management can be integrated into existing treatment trains.
Key vendors profiled in our study (representing these competing archetypes) include technology-focused media manufacturers, packaged-system suppliers and consumer brands. Each has a distinct go-to-market logic: media innovators demonstrate technical differentiation and case studies; engineering firms translate that into municipal scale; consumer brands convert certification into retail and installer demand. Recent field activity—such as a series of high-profile installations in specialty agricultural regions and exhibition activity at major trade shows—underscores active pipeline development and field validation as a commercial accelerant.
Strategic playbook for 2026
For C-suite and business-unit leaders, the following strategic moves should be considered as part of 2026 planning cycles:
-
Buyers (municipal & industrial): Insist on total cost of ownership proposals that quantify waste disposal, operator training and lifecycle replacement. Structure procurement to include performance-based milestones tied to regulatory outcomes; retain contractual rights for independent verification.
-
Suppliers: Shift commercial emphasis from unit sales to lifecycle services. Develop media-regeneration or take-back programs to address hazardous-waste liabilities; bundle remote monitoring to mitigate labor shortages and provide predictive maintenance revenue.
-
Investors and M&A strategists: Look for tuck-in targets that add local service footprints or unique waste-management capabilities. The market rewards scale in servicing distributed, small-system clients and technology differentiation in minimizing secondary waste.
-
R&D and product leaders: Prioritize selectivity, regeneration potential and lower-sludge processes. Pilot hybrid solutions that combine oxidation pretreatment with high-selectivity adsorption to optimize media life and reduce downstream handling costs.
-
Procurement and finance teams: Coordinate with public financing programs and structure phased financing to align capital expenditures with observed compliance deadlines. Consider outcome-linked pay structures where allowable under procurement rules.
What the PW Consulting report delivers
The full PW Consulting Arsenic Removal Market study is designed as an operational playbook for 2026. Highlights include:
-
Topline market sizing (USD, million) with historical baseline (2020–2025), a clearly documented base year (2025), and a scenario-modeled forecast covering 2026–2032 using a 6.5% central CAGR—useful for medium-term capacity and investment planning.
-
Vendor scorecards and comparative technology matrices that evaluate performance, waste profile, install footprint, and service readiness across major solution categories.
-
Actionable procurement templates and TCO calculators that integrate disposal liabilities, labor availability risk and public financing levers so procurement teams can quickly compare proposals on an apples-to-apples basis.
-
Case studies and field validation dossiers, including recent real-world installations that illustrate technology selection under non-ideal chemistries and constrained budgets.
-
Regulatory mapping and compliance timelines that translate policy persistence into procurement urgency and capital planning timelines.
-
Risk matrices and mitigation playbooks—covering supply chain stress, raw-material variability, and hazardous waste handling—that finance and operations teams can use to stress-test initiatives prior to commitment.
Note: the public executive summary intentionally omits detailed regional and application-level splits, vendor revenue shares and certain granular cost tables. These are available in the full, licensed dataset and accompanying interactive dashboards.
Closing — what to act on in the next 90 days
For leaders preparing 2026 budgets and strategy cycles, the next quarter is the window to: finalize portfolio priorities (capex vs O&M-led offerings); initiate or accelerate pilots that validate low-waste, low-labor options in environments with constrained operator availability; and engage early with financing partners to align procurement timelines with compliance deadlines. The macro trajectory supports continued investment, but the highest ROI will accrue to organizations that internalize lifecycle externalities—especially waste management and operator dependency—into product design and commercial models.
PW Consulting’s full report delivers the datasets, scoring frameworks and procurement-ready tools to operationalize these recommendations. For access to the complete market breakdowns, vendor benchmarks and interactive TCO models, please visit our report page or contact our industry practice to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Arsenic Removal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Allergy Immunotherapies Market Eyes 8.5% CAGR Through 2032
By pmarketresearch, 2026-07-13
Allergy Immunotherapies Market — 2026 Strategic Outlook and Executive Briefing
PW Consulting presents a focused strategic primer to orient executive decisions in 2026 for the Allergy Immunotherapies market. This briefing previews the analysis, scenarios, and decision frameworks contained in our full market research study — demonstrating the rigor of our approach while intentionally withholding detailed segment-level tables and run-rate figures to encourage access to the complete intelligence package.
Allergy Immunotherapies Market
Market snapshot — sizing and trajectory
Using 2025 as the base year, the global allergy immunotherapies market sits at approximately USD 2.1 billion and is on a steady growth path. Our forecast model projects an 8.5% compound annual growth rate through the 2026–2032 horizon, reflecting continued adoption of both established subcutaneous approaches and expanding immunomodulatory formats across respiratory and food allergy indications. By the end of the forecast window the market reaches mid‑single‑digit billions (USD ~3.7 billion in 2032 per our model), driven by regulatory approvals, product line extensions into pediatric populations, and payor modernization in select markets.
Allergy Immunotherapies Market
Historically (2020–2025) the market recovered from pandemic-related disruptions and entered a phase of renewed investment and clinical momentum — dynamics that underpin our bullish but disciplined forecast. Market concentration is moderate to high: the top three players control a majority share, and the top five exert strong influence on pricing, supply capacity, and clinical narrative (CR3 ≈ 55%; CR5 ≈ 68%).
Allergy Immunotherapies Market
Why this research matters for 2026 decisions
- Timing matters for product launches and label expansions. Recent and imminent regulatory events — including pediatric label expansions and country-specific licensing transitions — materially alter launch economics and go-to-market sequencing. Our report aligns timing assumptions with regulatory calendars and payer readiness across major markets to optimize launch windows.
- Reimbursement and clinic economics are shifting. U.S. Medicare coding and payment updates, updated specialty society guidelines that reduce administrative friction, and national-level transitions from unregistered to licensed products in key European markets create differentiated reimbursement landscapes. These shifts change revenue certainty and should inform contracting strategies now.
- Supply chain and capacity decisions are strategic. With a handful of manufacturers controlling formulation and extract capacity, decisions to expand production, invest in fill/finish, or secure contract manufacturing partnerships carry multi‑quarter lead times and significant bargaining power implications.
- M&A and partnership windows are opening. Given the market’s concentration and the technological diversity (tablets, patches, injectables, recombinant extracts), 2026 is a pivotal year for bolt-on acquisitions, licensing deals, and co-development agreements that can materially accelerate pipeline positioning.
Competitive landscape — strategic positioning of core players
Our competitive analysis synthesizes commercial portfolios, pipeline assets, manufacturing capabilities, and corporate strategies for the leading companies. High-level positioning follows; the full report delivers detailed SWOTs, launch-readiness matrices, and scenario-driven revenue models for each company.
- ALK‑Abelló A/S (Hørsholm, Denmark) — A leader in sublingual tablet innovations with a strong R&D pipeline and recent regulatory momentum. ALK’s strengths include tablet platform depth and market access expertise; continued pediatric label expansions bolster long‑term adoption potential.
- Stallergenes Greer (Paris, France) — Focused on both SCIT and SLIT with investments in production capacity. Positioned to capitalize on standardized extracts and venom therapy, Stallergenes benefits from robust manufacturing scale but must navigate differentiated reimbursement across countries.
- Allergy Therapeutics plc (London, UK) — Notable for novel adjuvant technologies and recent regulatory wins under new frameworks. Its product approvals and advancing paediatric trials make it an attractive partner or acquisition target in markets where licensed alternatives are newly required.
- HAL Allergy Group, LETI Pharma, Allergopharma, Jubilant HollisterStier — These regional and global suppliers drive customized extract capability and niche product differentiation. Their value lies in flexibility for personalized SCIT and regional regulatory know‑how.
- Biomay AG, DBV Technologies, Aimmune (Nestlé Health Science) — Technology innovators in recombinant allergens and epicutaneous/oral immunotherapies. Their platforms represent both upside risk to incumbent extract-based players and partnering opportunities for route-of-administration diversification.
- Merck KGaA — A major pharmaceutical incumbent with established SLIT assets and the commercial muscle to scale launches; their positioning signals ongoing competitive pressure on pricing and promotional intensity.
Across the competitive set we identify two strategic archetypes: (1) scale-focused incumbents optimizing extract breadth and manufacturing, and (2) platform innovators pushing new delivery modalities and pediatric expansion. Successful mid‑market strategies will combine selective platform partnerships with manufacturing certainty and targeted payer engagement.
Dynamics shaping 2026 market outcomes
Five dynamics will disproportionately influence performance in 2026:
- Regulatory transitions: Country-level policy shifts that convert unregistered therapies to licensed products are compressing the runway for incumbents and creating first‑mover advantages for licensed alternatives. Compliance timelines will force portfolio rationalization.
- Reimbursement evolution: Ongoing Medicare and national payer updates (including finalized RVU policies and local coverage directives) are altering unit economics for clinic-delivered immunotherapy versus self-administered options.
- Clinical adoption and persistence: Recent position papers and real-world persistence studies are reshaping clinician recommendations between subcutaneous and sublingual formats — an increasingly important factor for formulary decisions.
- Patient access and pediatric expansion: Pediatric approvals and label expansions unlock large addressable populations but require tailored compliance and adherence programs to realize uptake.
- Manufacturing and supply resilience: Capacity constraints and lead times for standardized extracts and novel delivery systems mean that early capacity commitments will be necessary to avoid launch delays or missed market share.
Notable, timely events to factor into 2026 planning include pediatric label expansions for house dust mite sublingual tablets and recent marketing authorisations under specialized regulatory frameworks in Europe — both of which will materially shift addressable populations and competitive dynamics for specific product classes.
What our full report delivers — pragmatic, decision-ready content
The published study is structured to support immediate strategic action and due diligence. Key deliverables include:
- Market-sizing models with base-year calibration (2025) and scenario runs across 2026–2032; interactive dashboards permit sensitivity testing on pricing, uptake, and regulatory outcomes.
- Commercial launch playbooks and channel economics for clinic-administered versus at-home therapies, including payer contracting templates and clinic revenue impact calculators.
- Regulatory and reimbursement timelines mapped by major market with strategic mitigation options for transitional risk.
- Detailed company profiles, competitive reaction matrices, and M&A valuation compendia — plus integration risk checklists for manufacturing and R&D assets.
- Operational levers and procurement strategies to secure extract supply and fill/finish capacity, with a supplier heatmap and risk scoring.
- Patient adherence and delivery-format analyses incorporating recent persistence evidence to model long-term revenue durability.
Importantly, while this brief highlights the report’s analytical depth, the full dataset — including granular regional and application splits, price/per-unit assumptions, and modelled revenue by subsegment — is available exclusively within the complete study to support licensing, partnerships, and transaction diligence.
Actionable recommendations for executives in 2026
- Prioritize payer‑first launches in markets with clear reimbursement updates. Sequence resources to markets where LCDs, national frameworks, or specialty society guidance have reduced commercial friction.
- Secure manufacturing commitments early. Lock capacity or partner with CMOs for critical extract and delivery platforms to avoid multi‑quarter delays; consider contingent payment structures to share risk.
- Evaluate targeted M&A and licensing for platform expansion. For incumbents, acquiring or licensing delivery innovations can protect share against disruptors; for innovators, partnerships with scale manufacturers accelerate commercialization.
- Invest in adherence and patient support programs tied to pediatric expansions. Pediatric uptake depends on caregiver confidence and real-world persistence; commercial models should incorporate nurse support, digital adherence tools, and outcomes tracking.
- Build regulatory playbooks and scenario hedges. Map approval timelines and prepare adaptive pricing and contracting strategies for both optimistic and conservative regulatory outcomes.
Concluding perspective — using this intelligence
The Allergy Immunotherapies market in 2026 is dynamic: rising demand, concentrated supplier power, and evolving regulatory/reimbursement frameworks create both risk and opportunity. PW Consulting’s full report equips executives with the granular models, market-entry playbooks, and competitive maps needed to convert insight into defensible strategy. This briefing demonstrates our analytical approach and the decision levers that matter; the complete study contains the underlying segmentation strike‑zone data, downloadable models, and proprietary valuation work that boards, corporate development, and commercial teams require to act with confidence.
For teams preparing product launches, evaluating acquisitions, or reconfiguring commercial operations, the time to align strategy with the 2026 regulatory and reimbursement calendar is now. Access to the full report will provide the segmented revenue models, price decks, and market share scenarios that translate this briefing into executable plans.
For detailed analysis of this topic, please visit the official page: Allergy Immunotherapies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stainless Steel Vacuum Bottle Market to hit USD 6,698M by 2032 at 3.53% CAGR
By pmarketresearch, 2026-07-13
Stainless Steel Vacuum Bottle Market — Strategic Outlook for 2026 (PW Consulting Preview)
Executive snapshot
The stainless steel vacuum bottle market has matured into a resilient consumer and industrial segment. On a macro scale, PW Consulting’s baseline sizing places the market at approximately USD 5,279 Million in 2025 (base year) and projects a compound annual growth rate (CAGR) of 3.53% through our forecast horizon, reaching roughly USD 6,698 Million by 2032. The trajectory from 2020 to 2025 shows steady expansion with episodic volatility tied to raw material price swings, trade policy shifts, and episodic product-platform refreshes by market leaders.
Stainless Steel Vacuum Bottle Market
This preview is designed as a strategic “trailer”: it synthesizes the high‑level implications contained in our full study to equip boards, corporate strategy teams, and PE/VC investors for 2026 planning cycles. To preserve the discoverability and commercial value of the report, detailed segment-level tables, regional splits, channel-specific demand curves, and unit-level pricing matrices have been intentionally withheld from this summary.
Stainless Steel Vacuum Bottle Market
Why this research matters in 2026
- Actionable market sizing — A defensible market baseline and top‑down forecast (2026–2032) support investment sizing, portfolio review, and organic growth targets.
- Margin & cost-to-serve clarity — Our model isolates the impact of stainless steel input prices, tariff scenarios, and logistics costs on gross margins across common product archetypes.
- Go-to-market alignment — Channel, pricing and SKU strategies in the full report map to retailer shelf economics and direct-to-consumer unit economics.
- M&A & partner screening — The study’s valuation and capability matrices identify inorganic opportunities for capacity, distribution, and IP play.
- Risk management — Scenario analyses quantify downside risk from tariff renewals, raw material shocks, and demand compression, enabling pre-emptive hedging and procurement plays.
What the PW report delivers (practical contents)
- Methodology and assumptions — transparent modelling logic, base-year reconciliation (2025), and sensitivity levers for raw materials, freight and pricing.
- Market sizing & forecast — historical analysis (2020–2025) and a segmented forecast to 2032 with baseline CAGR of 3.53%.
- Segment diagnostics — product-type archetypes, channel economics, and use-case demand drivers (outdoor vs indoor consumer behaviors, gifting, corporate procurement).
- Competitive benchmarking — commercial profiles, margin proxies, capacity footprints and innovation roadmaps for leading suppliers.
- Supply chain & cost-to-serve mapping — supplier concentration, nearshoring options, contract manufacturing profiles and logistics stress points.
- Regulatory & trade intelligence — tariff and trade-policy scenarios, compliance checklists, and mitigation playbooks for import-dependent operators.
- Commercial playbooks — SKU rationalization, pricing architecture, DTC conversion levers, retailer negotiation points and promotional elasticity models.
- M&A and investment screening tools — target scorecards, valuation sensitivity to demand and raw material assumptions, and integration risk checklists.
- Proprietary data annex — unit pricing bands by archetype, wholesale/retail margins, and downloadable forecast model (Excel).
Competitive landscape — who to watch and why
The market is characterized by a mix of heritage brands with deep distribution and newer premium entrants that have driven category re‑engineering through design, material quality and direct-to-consumer experiences. Our coverage focuses on established leaders that shape product standards and trade dynamics:
Stainless Steel Vacuum Bottle Market
- Thermos LLC (Schaumburg, Illinois) — a classic brand anchored in broad retail distribution and a large installed base. Its strength lies in widespread shelf presence and proven double-wall vacuum technology across price tiers.
- YETI Holdings, Inc. (Austin, Texas) — the premiumization playbook: brand elevation, deliberate SKU expansions and a focus on outdoor performance. Recent product expansions (Rambler variants, Travel Bottle and Silo collections) illustrate how new SKUs can re‑energize share and ASPs while imposing incremental supply chain complexity.
- Hydro Flask (Bend, Oregon) — lifestyle and wellness positioning, strong DTC and community marketing; excels in premium finishes and leakproof closures that command brand premiums.
- Stanley 1913 (Seattle, Washington) — heritage and authenticity leveraged into a broad portfolio; appeals to both legacy workwear/trade segments and contemporary outdoor consumers.
- Zojirushi Corporation (Osaka, Japan) — engineering and thermal retention expertise with high consumer trust in performance-critical products (e.g., travel mugs and insulated food containers).
These firms collectively demonstrate three structural moves that matter: (1) premiumization and brand-led pricing power; (2) SKU proliferation to capture adjacent use-cases; and (3) diversification of channel mix (retail + DTC) to improve margin capture. Market concentration is moderate — a handful of global brands hold meaningful influence, yet there is room for nimble regional players and private-label manufacturers to compete on cost or speed.
Regulatory, raw-material and trade dynamics — the near-term wildcards
Recent events have re-emphasized the importance of trade policy and raw-material volatility in strategic planning. In 2025, incremental U.S. import tariffs increased landed costs for many importers of stainless steel insulated flasks, pressuring gross margins. While a February 20, 2026 U.S. Supreme Court decision invalidated certain tariffs under one authority, alternative tariff measures remain and legal/regulatory uncertainty persists. Concurrently, manufacturers continue to manage fluctuations in stainless steel pricing, transportation, labor availability and equipment lead times.
For manufacturers and retailers, the implication is unambiguous: procurement strategy, flexible manufacturing contracts, and hedging become core competencies. For brands, transparent cost pass-through mechanisms and consumer communications around sustainability and quality can preserve margins in inflationary windows.
Strategic imperatives for 2026 planning
- Fortify supply chain optionality: Nearshoring, multi-sourcing of stainless feedstock, and strategic inventory buffers for key SKUs reduce disruption risk and shorten time-to-market for trend-driven launches.
- Rationalize SKU portfolios: Use price-elasticity and contribution-margin analysis to eliminate low-turn, low-margin SKUs and redeploy capital to high-margin premium lines or variant innovations.
- Monetize premiumization: Invest in product features that consumers recognize—thermal performance, lid innovation, personalization and sustainable material claims—while protecting price architecture through targeted trade promotions.
- Hedge regulatory exposure: Scenario-based cost models should be embedded in commercial planning. Negotiate clauses with suppliers to share tariff exposures and explore tariff engineering (product classification optimization) where legally permissible.
- Pursue adjacent M&A thoughtfully: Targets that add manufacturing capacity, establish DTC capabilities, or secure intellectual property around lid/insulation tech deliver outsized optionality.
- Embed sustainability as a margin lever: Recycled stainless content, take-back programs and repair services can reduce volatility in feedstock sourcing while resonating with premium customers.
Stress scenarios we model in the full study
- Tariff reinstatement or escalation: quantifies margin impact and retail price elasticity under multiple pass‑through assumptions.
- Raw-material price shock: isolated stainless steel cost increases and their cascading effect on gross margins by archetype.
- Demand slowdown vs. premium pull-through: tests how consumers trade down or consolidate SKUs under macro softness.
- Supply chain disruption: simulates regional factory outages, shipping bottlenecks and labor disruptions on fulfilment and backlog management.
How to use this preview
If your 2026 planning requires defensible topline targets, a risk-adjusted investment thesis, or a playbook for SKU and channel optimization, this preview should inform board-level conversations and short-listing of scenarios. The full PW Consulting report provides the granular tables, regional/channel breakouts, and downloadable forecast model needed to translate strategic intent into executable plans.
Next steps
For access to the complete dataset, segment-level demand analytics, pricing matrices, and the model that powers our USD 5,279 Million baseline and 3.53% CAGR projection to 2032, please visit the PW Consulting report page or contact our research desk. The full study includes the proprietary scenario workbench that corporate strategy teams can license for internal planning and investor diligence.
For detailed analysis of this topic, please visit the official page: Stainless Steel Vacuum Bottle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com