

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Allergy Immunotherapies Market Eyes 8.5% CAGR Through 2032

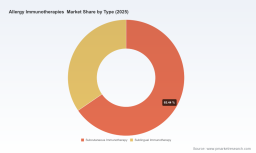
Allergy Immunotherapies Market — 2026 Strategic Outlook and Executive Briefing
PW Consulting presents a focused strategic primer to orient executive decisions in 2026 for the Allergy Immunotherapies market. This briefing previews the analysis, scenarios, and decision frameworks contained in our full market research study — demonstrating the rigor of our approach while intentionally withholding detailed segment-level tables and run-rate figures to encourage access to the complete intelligence package.
Allergy Immunotherapies Market
Market snapshot — sizing and trajectory
Using 2025 as the base year, the global allergy immunotherapies market sits at approximately USD 2.1 billion and is on a steady growth path. Our forecast model projects an 8.5% compound annual growth rate through the 2026–2032 horizon, reflecting continued adoption of both established subcutaneous approaches and expanding immunomodulatory formats across respiratory and food allergy indications. By the end of the forecast window the market reaches mid‑single‑digit billions (USD ~3.7 billion in 2032 per our model), driven by regulatory approvals, product line extensions into pediatric populations, and payor modernization in select markets.
Allergy Immunotherapies Market
Historically (2020–2025) the market recovered from pandemic-related disruptions and entered a phase of renewed investment and clinical momentum — dynamics that underpin our bullish but disciplined forecast. Market concentration is moderate to high: the top three players control a majority share, and the top five exert strong influence on pricing, supply capacity, and clinical narrative (CR3 ≈ 55%; CR5 ≈ 68%).
Allergy Immunotherapies Market
Why this research matters for 2026 decisions
- Timing matters for product launches and label expansions. Recent and imminent regulatory events — including pediatric label expansions and country-specific licensing transitions — materially alter launch economics and go-to-market sequencing. Our report aligns timing assumptions with regulatory calendars and payer readiness across major markets to optimize launch windows.
- Reimbursement and clinic economics are shifting. U.S. Medicare coding and payment updates, updated specialty society guidelines that reduce administrative friction, and national-level transitions from unregistered to licensed products in key European markets create differentiated reimbursement landscapes. These shifts change revenue certainty and should inform contracting strategies now.
- Supply chain and capacity decisions are strategic. With a handful of manufacturers controlling formulation and extract capacity, decisions to expand production, invest in fill/finish, or secure contract manufacturing partnerships carry multi‑quarter lead times and significant bargaining power implications.
- M&A and partnership windows are opening. Given the market’s concentration and the technological diversity (tablets, patches, injectables, recombinant extracts), 2026 is a pivotal year for bolt-on acquisitions, licensing deals, and co-development agreements that can materially accelerate pipeline positioning.
Competitive landscape — strategic positioning of core players
Our competitive analysis synthesizes commercial portfolios, pipeline assets, manufacturing capabilities, and corporate strategies for the leading companies. High-level positioning follows; the full report delivers detailed SWOTs, launch-readiness matrices, and scenario-driven revenue models for each company.
- ALK‑Abelló A/S (Hørsholm, Denmark) — A leader in sublingual tablet innovations with a strong R&D pipeline and recent regulatory momentum. ALK’s strengths include tablet platform depth and market access expertise; continued pediatric label expansions bolster long‑term adoption potential.
- Stallergenes Greer (Paris, France) — Focused on both SCIT and SLIT with investments in production capacity. Positioned to capitalize on standardized extracts and venom therapy, Stallergenes benefits from robust manufacturing scale but must navigate differentiated reimbursement across countries.
- Allergy Therapeutics plc (London, UK) — Notable for novel adjuvant technologies and recent regulatory wins under new frameworks. Its product approvals and advancing paediatric trials make it an attractive partner or acquisition target in markets where licensed alternatives are newly required.
- HAL Allergy Group, LETI Pharma, Allergopharma, Jubilant HollisterStier — These regional and global suppliers drive customized extract capability and niche product differentiation. Their value lies in flexibility for personalized SCIT and regional regulatory know‑how.
- Biomay AG, DBV Technologies, Aimmune (Nestlé Health Science) — Technology innovators in recombinant allergens and epicutaneous/oral immunotherapies. Their platforms represent both upside risk to incumbent extract-based players and partnering opportunities for route-of-administration diversification.
- Merck KGaA — A major pharmaceutical incumbent with established SLIT assets and the commercial muscle to scale launches; their positioning signals ongoing competitive pressure on pricing and promotional intensity.
Across the competitive set we identify two strategic archetypes: (1) scale-focused incumbents optimizing extract breadth and manufacturing, and (2) platform innovators pushing new delivery modalities and pediatric expansion. Successful mid‑market strategies will combine selective platform partnerships with manufacturing certainty and targeted payer engagement.
Dynamics shaping 2026 market outcomes
Five dynamics will disproportionately influence performance in 2026:
- Regulatory transitions: Country-level policy shifts that convert unregistered therapies to licensed products are compressing the runway for incumbents and creating first‑mover advantages for licensed alternatives. Compliance timelines will force portfolio rationalization.
- Reimbursement evolution: Ongoing Medicare and national payer updates (including finalized RVU policies and local coverage directives) are altering unit economics for clinic-delivered immunotherapy versus self-administered options.
- Clinical adoption and persistence: Recent position papers and real-world persistence studies are reshaping clinician recommendations between subcutaneous and sublingual formats — an increasingly important factor for formulary decisions.
- Patient access and pediatric expansion: Pediatric approvals and label expansions unlock large addressable populations but require tailored compliance and adherence programs to realize uptake.
- Manufacturing and supply resilience: Capacity constraints and lead times for standardized extracts and novel delivery systems mean that early capacity commitments will be necessary to avoid launch delays or missed market share.
Notable, timely events to factor into 2026 planning include pediatric label expansions for house dust mite sublingual tablets and recent marketing authorisations under specialized regulatory frameworks in Europe — both of which will materially shift addressable populations and competitive dynamics for specific product classes.
What our full report delivers — pragmatic, decision-ready content
The published study is structured to support immediate strategic action and due diligence. Key deliverables include:
- Market-sizing models with base-year calibration (2025) and scenario runs across 2026–2032; interactive dashboards permit sensitivity testing on pricing, uptake, and regulatory outcomes.
- Commercial launch playbooks and channel economics for clinic-administered versus at-home therapies, including payer contracting templates and clinic revenue impact calculators.
- Regulatory and reimbursement timelines mapped by major market with strategic mitigation options for transitional risk.
- Detailed company profiles, competitive reaction matrices, and M&A valuation compendia — plus integration risk checklists for manufacturing and R&D assets.
- Operational levers and procurement strategies to secure extract supply and fill/finish capacity, with a supplier heatmap and risk scoring.
- Patient adherence and delivery-format analyses incorporating recent persistence evidence to model long-term revenue durability.
Importantly, while this brief highlights the report’s analytical depth, the full dataset — including granular regional and application splits, price/per-unit assumptions, and modelled revenue by subsegment — is available exclusively within the complete study to support licensing, partnerships, and transaction diligence.
Actionable recommendations for executives in 2026
- Prioritize payer‑first launches in markets with clear reimbursement updates. Sequence resources to markets where LCDs, national frameworks, or specialty society guidance have reduced commercial friction.
- Secure manufacturing commitments early. Lock capacity or partner with CMOs for critical extract and delivery platforms to avoid multi‑quarter delays; consider contingent payment structures to share risk.
- Evaluate targeted M&A and licensing for platform expansion. For incumbents, acquiring or licensing delivery innovations can protect share against disruptors; for innovators, partnerships with scale manufacturers accelerate commercialization.
- Invest in adherence and patient support programs tied to pediatric expansions. Pediatric uptake depends on caregiver confidence and real-world persistence; commercial models should incorporate nurse support, digital adherence tools, and outcomes tracking.
- Build regulatory playbooks and scenario hedges. Map approval timelines and prepare adaptive pricing and contracting strategies for both optimistic and conservative regulatory outcomes.
Concluding perspective — using this intelligence
The Allergy Immunotherapies market in 2026 is dynamic: rising demand, concentrated supplier power, and evolving regulatory/reimbursement frameworks create both risk and opportunity. PW Consulting’s full report equips executives with the granular models, market-entry playbooks, and competitive maps needed to convert insight into defensible strategy. This briefing demonstrates our analytical approach and the decision levers that matter; the complete study contains the underlying segmentation strike‑zone data, downloadable models, and proprietary valuation work that boards, corporate development, and commercial teams require to act with confidence.
For teams preparing product launches, evaluating acquisitions, or reconfiguring commercial operations, the time to align strategy with the 2026 regulatory and reimbursement calendar is now. Access to the full report will provide the segmented revenue models, price decks, and market share scenarios that translate this briefing into executable plans.
For detailed analysis of this topic, please visit the official page: Allergy Immunotherapies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com