

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Convenient Camping Cooler Market to Grow at 5.8% CAGR (2026–2032)

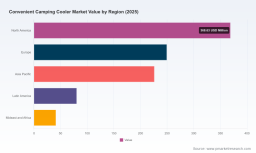
Convenient Camping Cooler Market — Strategic Preview for 2026 Decision-Making
Executive snapshot
As the outdoor recreation economy normalizes into a new post‑pandemic cadence, the Convenient Camping Cooler market is entering a phase of steady expansion and pronounced product innovation. Our latest PW Consulting market model shows the global market expanding from roughly USD 965 million in 2025 to an estimated USD 1.43 billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.8% across the 2026–2032 forecast window. That trajectory, paired with a moderate market concentration (CR3 ≈ 42.5%; CR5 ≈ 48.2%), creates a landscape in which nimble challengers and incumbent premium brands can both capture meaningful share — provided they align product, channel and sourcing strategies to emerging commercial and regulatory realities.
Convenient Camping Cooler Market
Why this briefing matters for 2026 strategy
-
Time‑sensitive compliance and product design: New environmental standards and material regulations (notably EU requirements taking effect in 2027) change product specs and allowable materials; businesses must build compliance into 2026 product roadmaps to avoid costly redesigns or market entry delays in 2027.
Convenient Camping Cooler Market -
Input cost volatility is no longer a background risk: Fluctuations in petroleum‑derived polyurethane foams and polymers materially affect component costs and margin stability — manufacturers need procurement playbooks and hedging scenarios now, not later.
Convenient Camping Cooler Market -
Feature differentiation drives premium pricing: Mobility (wheels), foldability and lightweight construction have moved from “nice-to-have” to purchase drivers. Firms that can translate those attributes into reliable, measurable performance (ice retention, durability, leak resistance) will command premium positioning in key retail and direct channels.
-
Channel mix decisions pivot around convenience: Consumers increasingly value compact storage and single‑person portability, reshaping adjacent merchandising and logistics choices across omni‑channel retailers and D2C platforms.
Key market dynamics at a glance
-
Growth profile: After accelerating through the early 2020s, growth moderates into a steady mid‑single digit phase; the market reached approximately USD 964.5 million in 2025 and is projected to surpass USD 1.4 billion by 2032 on a 5.8% CAGR for 2026–2032. That steady expansion supports investment in incremental innovation and selective capacity build‑outs rather than broad, capital‑intensive network expansions.
-
Concentration and competitive intensity: With the top three and top five firms controlling under half the market, there remains ample scope for regional and niche players to scale through product specialization, channel partnerships and value engineering.
-
Raw material & cost pressure: Volatility in polymer and foam inputs induces margin variability for manufacturers heavily exposed to petroleum feedstocks. Suppliers and OEMs are experimenting with alternative formulations and recycled content, but substitution timelines vary by cost and performance trade‑offs.
-
Regulatory overlay: Stricter rules on non‑biodegradable plastics, plus region‑specific energy and environmental standards (EU rules effective in 2027), require manufacturers to validate sourcing, production and end‑of‑life pathways for products destined for regulated jurisdictions.
-
Consumer preference shifts: Practical convenience features — lighter weight, wheels, collapsibility, and organizational accessories — are driving purchase decisions across both casual campers and more experienced outdoor consumers. These preferences also influence lifetime value via higher attachment/upsell rates for accessory ecosystems (dry bins, straps, drinkware).
-
Safety and reliability: Industry surveillance shows no major recalls in 2025–2026; the sector is focused on leak resistance, insulation performance and robustness as differentiators that reduce warranty costs and protect brand equity.
Competitive landscape — what leading players are doing
Market leadership continues to be defined by a mix of premium engineering, scale manufacturing and brand equity. PW Consulting’s qualitative review of core competitors highlights the following strategic moves and positioning:
-
YETI (Austin, TX) maintains a premium, performance‑led posture with rotomolded hard coolers designed for multi‑day retention and durability; recent updates in 2026 (lightweight Roadie 8 and enhancements to the Roadie 24) signal continued investment in solo‑use and portability segments.
-
Igloo (Cedar Park, TX) competes on accessibility and sustainability experiments, expanding recycled and compostable offerings while maintaining broad price‑point coverage across injection and rotomolded platforms.
-
Coleman (Oklahoma City, OK) leverages heritage outdoor distribution and has introduced a category‑disrupting Snap ’N Go collapsible hard cooler in 2026 — an example of structural innovation that addresses storage constraints faced by mass‑market consumers.
-
RTIC and Canyon Outdoor continue to emphasize value engineering for durable rotomolded units, while Engel focuses on ultra‑light injection‑molded designs that balance portability with thermal performance.
-
RovR’s award recognition and expanded product lines (redesigned RollR wheeled coolers and TravelR soft coolers) underscore how mobility and modular organization can be leveraged to create new sub‑segments within the convenience category.
Strategic playbook for 2026 (practical, executable moves)
-
Embed compliance into product roadmaps: Assume that products sold into regulated regions will require materials, labeling and recyclability validation by 2027. Begin design freeze windows with compliant material specifications in 2026 to avoid costly retrofits.
-
Hedge raw material exposure: Contractually diversify resin and foam supply, test bio‑based or recycled blends now, and model three cost scenarios (baseline, +15%, +35% feedstock inflation) to quantify margin levers and pricing cadence for 2026–2027.
-
Prioritize feature stacks that map to willingness‑to‑pay: Run rapid conjoint studies focused on mobility (wheels vs. detachable trolley), storage (collapsible vs. fixed), and performance (ice retention vs. weight). Use results to define two‑tier SKUs: a premium retention‑focused line and a convenience‑focused mass line.
-
Channel economics and assortment rationalization: Rebalance assortment between big‑box, specialty outdoor, and D2C. Test exclusive SKUs and accessory bundles through pilot programs to measure acquisition cost, attach rates and post‑purchase NPS.
-
Operationalizing innovation: Shorten prototype cycles by adopting modular tooling for lids and drain assemblies, enabling faster A/B testing of features like integrated straps, quick‑drain plugs, and organizational inserts.
-
M&A and partnership targets: Look for bolt‑on acquisitions that provide manufacturing flexibility (injection‑molding capacity or specialty assembly for wheeled platforms), or license technologies for foldable hard‑shell mechanics. Partnerships with recycling and take‑back service providers can also accelerate compliance credentials.
-
Pricing and margin management: Implement dynamic pricing pilots tied to channel and seasonality. Build margin waterfalls to identify where value can be reclaimed (packaging redesign, freight optimization, warranty self‑service).
-
Marketing and product storytelling: Translate technical performance (e.g., verified ice retention test protocols) into consumer assurances and retailer selling tools, while using convenience narratives to reach urban, apartment‑dwelling campers who prioritize storage and portability.
What PW Consulting’s full report delivers (highly practical content)
Our full market study extends this preview with the operational detail required to execute in 2026: forecasting models through 2032, scenario analyses for raw material and regulatory shocks, SKU‑level product economics, priced channel strategies, supplier scorecards, commercial playbooks for premium vs. mass segments, and a due diligence dossier for M&A and strategic partnerships. To preserve competitive value in this preview, we have deliberately withheld full regional and application breakdown tables, detailed company revenue shares, and downloadable financial model files — these are included in the complete report package.
Concluding recommendation
For executive teams making allocations in 2026, the decision levers are clear: accelerate compliant product variants now, lock in diversified supply options to mitigate feedstock volatility, and adopt a dual‑track commercialization approach that monetizes both premium performance and convenience‑driven mass offerings. The market’s steady growth profile and fragmented competitive structure reward focused product differentiation coupled with disciplined operational execution. PW Consulting’s full Convenient Camping Cooler Market report contains the granular, actionable intelligence to convert these strategic priorities into a 12‑ to 36‑month implementation roadmap.
Next steps
Contact our PW Consulting research desk or visit the report page to access the full dataset, downloadable models, and a tailored briefing session. In a category where small feature changes determine both price elasticity and brand perception, the right data today prevents costly missteps tomorrow.
For detailed analysis of this topic, please visit the official page: Convenient Camping Cooler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com