

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Stainless Steel Vacuum Bottle Market to hit USD 6,698M by 2032 at 3.53% CAGR

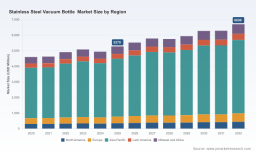
Stainless Steel Vacuum Bottle Market — Strategic Outlook for 2026 (PW Consulting Preview)
Executive snapshot
The stainless steel vacuum bottle market has matured into a resilient consumer and industrial segment. On a macro scale, PW Consulting’s baseline sizing places the market at approximately USD 5,279 Million in 2025 (base year) and projects a compound annual growth rate (CAGR) of 3.53% through our forecast horizon, reaching roughly USD 6,698 Million by 2032. The trajectory from 2020 to 2025 shows steady expansion with episodic volatility tied to raw material price swings, trade policy shifts, and episodic product-platform refreshes by market leaders.
Stainless Steel Vacuum Bottle Market
This preview is designed as a strategic “trailer”: it synthesizes the high‑level implications contained in our full study to equip boards, corporate strategy teams, and PE/VC investors for 2026 planning cycles. To preserve the discoverability and commercial value of the report, detailed segment-level tables, regional splits, channel-specific demand curves, and unit-level pricing matrices have been intentionally withheld from this summary.
Stainless Steel Vacuum Bottle Market
Why this research matters in 2026
- Actionable market sizing — A defensible market baseline and top‑down forecast (2026–2032) support investment sizing, portfolio review, and organic growth targets.
- Margin & cost-to-serve clarity — Our model isolates the impact of stainless steel input prices, tariff scenarios, and logistics costs on gross margins across common product archetypes.
- Go-to-market alignment — Channel, pricing and SKU strategies in the full report map to retailer shelf economics and direct-to-consumer unit economics.
- M&A & partner screening — The study’s valuation and capability matrices identify inorganic opportunities for capacity, distribution, and IP play.
- Risk management — Scenario analyses quantify downside risk from tariff renewals, raw material shocks, and demand compression, enabling pre-emptive hedging and procurement plays.
What the PW report delivers (practical contents)
- Methodology and assumptions — transparent modelling logic, base-year reconciliation (2025), and sensitivity levers for raw materials, freight and pricing.
- Market sizing & forecast — historical analysis (2020–2025) and a segmented forecast to 2032 with baseline CAGR of 3.53%.
- Segment diagnostics — product-type archetypes, channel economics, and use-case demand drivers (outdoor vs indoor consumer behaviors, gifting, corporate procurement).
- Competitive benchmarking — commercial profiles, margin proxies, capacity footprints and innovation roadmaps for leading suppliers.
- Supply chain & cost-to-serve mapping — supplier concentration, nearshoring options, contract manufacturing profiles and logistics stress points.
- Regulatory & trade intelligence — tariff and trade-policy scenarios, compliance checklists, and mitigation playbooks for import-dependent operators.
- Commercial playbooks — SKU rationalization, pricing architecture, DTC conversion levers, retailer negotiation points and promotional elasticity models.
- M&A and investment screening tools — target scorecards, valuation sensitivity to demand and raw material assumptions, and integration risk checklists.
- Proprietary data annex — unit pricing bands by archetype, wholesale/retail margins, and downloadable forecast model (Excel).
Competitive landscape — who to watch and why
The market is characterized by a mix of heritage brands with deep distribution and newer premium entrants that have driven category re‑engineering through design, material quality and direct-to-consumer experiences. Our coverage focuses on established leaders that shape product standards and trade dynamics:
Stainless Steel Vacuum Bottle Market
- Thermos LLC (Schaumburg, Illinois) — a classic brand anchored in broad retail distribution and a large installed base. Its strength lies in widespread shelf presence and proven double-wall vacuum technology across price tiers.
- YETI Holdings, Inc. (Austin, Texas) — the premiumization playbook: brand elevation, deliberate SKU expansions and a focus on outdoor performance. Recent product expansions (Rambler variants, Travel Bottle and Silo collections) illustrate how new SKUs can re‑energize share and ASPs while imposing incremental supply chain complexity.
- Hydro Flask (Bend, Oregon) — lifestyle and wellness positioning, strong DTC and community marketing; excels in premium finishes and leakproof closures that command brand premiums.
- Stanley 1913 (Seattle, Washington) — heritage and authenticity leveraged into a broad portfolio; appeals to both legacy workwear/trade segments and contemporary outdoor consumers.
- Zojirushi Corporation (Osaka, Japan) — engineering and thermal retention expertise with high consumer trust in performance-critical products (e.g., travel mugs and insulated food containers).
These firms collectively demonstrate three structural moves that matter: (1) premiumization and brand-led pricing power; (2) SKU proliferation to capture adjacent use-cases; and (3) diversification of channel mix (retail + DTC) to improve margin capture. Market concentration is moderate — a handful of global brands hold meaningful influence, yet there is room for nimble regional players and private-label manufacturers to compete on cost or speed.
Regulatory, raw-material and trade dynamics — the near-term wildcards
Recent events have re-emphasized the importance of trade policy and raw-material volatility in strategic planning. In 2025, incremental U.S. import tariffs increased landed costs for many importers of stainless steel insulated flasks, pressuring gross margins. While a February 20, 2026 U.S. Supreme Court decision invalidated certain tariffs under one authority, alternative tariff measures remain and legal/regulatory uncertainty persists. Concurrently, manufacturers continue to manage fluctuations in stainless steel pricing, transportation, labor availability and equipment lead times.
For manufacturers and retailers, the implication is unambiguous: procurement strategy, flexible manufacturing contracts, and hedging become core competencies. For brands, transparent cost pass-through mechanisms and consumer communications around sustainability and quality can preserve margins in inflationary windows.
Strategic imperatives for 2026 planning
- Fortify supply chain optionality: Nearshoring, multi-sourcing of stainless feedstock, and strategic inventory buffers for key SKUs reduce disruption risk and shorten time-to-market for trend-driven launches.
- Rationalize SKU portfolios: Use price-elasticity and contribution-margin analysis to eliminate low-turn, low-margin SKUs and redeploy capital to high-margin premium lines or variant innovations.
- Monetize premiumization: Invest in product features that consumers recognize—thermal performance, lid innovation, personalization and sustainable material claims—while protecting price architecture through targeted trade promotions.
- Hedge regulatory exposure: Scenario-based cost models should be embedded in commercial planning. Negotiate clauses with suppliers to share tariff exposures and explore tariff engineering (product classification optimization) where legally permissible.
- Pursue adjacent M&A thoughtfully: Targets that add manufacturing capacity, establish DTC capabilities, or secure intellectual property around lid/insulation tech deliver outsized optionality.
- Embed sustainability as a margin lever: Recycled stainless content, take-back programs and repair services can reduce volatility in feedstock sourcing while resonating with premium customers.
Stress scenarios we model in the full study
- Tariff reinstatement or escalation: quantifies margin impact and retail price elasticity under multiple pass‑through assumptions.
- Raw-material price shock: isolated stainless steel cost increases and their cascading effect on gross margins by archetype.
- Demand slowdown vs. premium pull-through: tests how consumers trade down or consolidate SKUs under macro softness.
- Supply chain disruption: simulates regional factory outages, shipping bottlenecks and labor disruptions on fulfilment and backlog management.
How to use this preview
If your 2026 planning requires defensible topline targets, a risk-adjusted investment thesis, or a playbook for SKU and channel optimization, this preview should inform board-level conversations and short-listing of scenarios. The full PW Consulting report provides the granular tables, regional/channel breakouts, and downloadable forecast model needed to translate strategic intent into executable plans.
Next steps
For access to the complete dataset, segment-level demand analytics, pricing matrices, and the model that powers our USD 5,279 Million baseline and 3.53% CAGR projection to 2032, please visit the PW Consulting report page or contact our research desk. The full study includes the proprietary scenario workbench that corporate strategy teams can license for internal planning and investor diligence.
For detailed analysis of this topic, please visit the official page: Stainless Steel Vacuum Bottle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com