
Blogs
PW Consulting: Worldwide 4‑Vinyl Guaiacol Market Poised for 5.15% CAGR over 2026–2032 Forecast
By pmarketresearch, 2026-08-18
Worldwide 4‑Vinyl Guaiacol Market — Strategic Preview for 2026 Decision‑Making
PW Consulting’s latest market study on Worldwide 4‑Vinyl Guaiacol delivers forward‑looking intelligence designed to accelerate executive decision‑making in 2026. The compound’s dual role as a high‑impact aroma chemical and an intermediate in specialty syntheses has produced a market that is stable yet responsive to shifting raw‑material economics, sustainability preferences and regulatory norms. This preview summarizes the report’s strategic value, key market dynamics and recommended actions for manufacturers, ingredient buyers, and investors — while intentionally withholding granular segment toplines to encourage readers to consult the full report for the underlying datasets and model output.
Worldwide Full Grain Leather Market
Market snapshot: size, trajectory and concentration
Measured in USD Million, the global 4‑Vinyl Guaiacol market expanded steadily from 2020 through 2025, reflecting consistent demand reinforcement from flavor and fragrance formulators and specialty chemical users. After reaching a mid‑single‑digit billion‑dollar equivalent threshold in 2025, our forecast model — built on a detailed bottom‑up supply and demand mapping — projects continued growth through 2032 at a compound annual growth rate (CAGR) of approximately 5.15% for the 2026–2032 forecast window.
Worldwide Dioctyl Fumarate Market
Notably, the model captures a short, technical plateau around 2026 consistent with feedstock cost normalization and inventory corrections, followed by a resumption of volume and value growth driven by premiumization in food & beverage applications, expanding cosmetic formulations that utilize smoky/spicy notes, and incremental use as pharmaceutical intermediates.
Worldwide Fire Protection Contractor Market
Market concentration measures indicate a moderately consolidated competitive landscape: the top three suppliers account for a meaningful share of market revenues, and the five leading players represent an even larger portion. This structure creates both advantages and vulnerabilities — price leadership and capacity control on one hand, and supply disruption concentration risk on the other.
What the PW Consulting report delivers (practical, actionable content)
- Market sizing & forecasting model (2020–2032) with scenario variants and sensitivity to ferulic‑acid pricing, production route adoption (natural vs synthetic), and regulatory shifts.
- Pricing and margin analytics linking feedstock spot dynamics to finished‑good pricing, with hedging and contract design playbooks.
- Supply‑chain heatmap and supplier scorecards covering quality certification, capacity, geographic risk, and sustainability credentials.
- Technology assessment comparing decarboxylation and extraction routes, including process economics and scale‑up timelines.
- Commercial playbooks for flavor houses and fragrance houses (go‑to‑market, specification management, and value‑based pricing strategies).
- Regulatory checklist (including food‑use recognition and documentation pathways) and risk register for cross‑jurisdictional commercialization.
- M&A and partnership filters for buyers seeking bolt‑on capacity or vertical integration into ferulic‑acid feedstocks.
- Three practical case studies illustrating supplier negotiation tactics, a product reformulation project leveraging a natural extract, and an investor diligence package.
Competitive landscape: who matters and why
Our competitive analysis assesses established specialty chemical distributors, dedicated aroma chemical manufacturers, and emerging bio‑extractors. Select profiles illustrate strategic positioning relevant to 2026 planning:
- Foreverest Resources Ltd. (China) — Specialized in naturally extracted 4‑Vinyl Guaiacol derived from corn ethanol fermentation volatiles. Their bio‑based positioning is attractive to clean‑label formulators and brands seeking fermentation‑derived credentials.
- Penta International (USA) — Offers multiple grades and dilutions including natural and synthetic options. The breadth of product forms supports customers that require tailored specifications and private‑label formulations.
- Simson Pharma Limited (India) — Focused on custom synthesis and exportable, certified batches, aligning with customers who require consistent certificates of analysis and scale‑to‑order supply.
- Parchem Fine & Specialty Chemicals (USA) — Acts as a global distributor for specialty applications, providing market reach and logistics infrastructure that smaller manufacturers may lack.
- United Aromatics, Gogia Chemical, Aroma Aromatics & Flavours (India) — A cluster of regional manufacturers supplying food‑grade, certified materials at competitive cost points; important contenders in cost‑sensitive supply chains.
- R C Treatt & Co Ltd (UK) — Known for supplying high‑impact aroma chemicals to fragrance houses in Europe, with longstanding buyer relationships and formulation expertise.
- Sigma‑Aldrich (MilliporeSigma, USA) — Supplies research and analytical grades with rigorous documentation — an important supplier for R&D, bench validation and early stage formulation work.
Across these players, we observe a strategic split between suppliers emphasizing bio‑based, traceable extraction routes and those competing on synthetic cost and scale. For buyers, the choice is increasingly less binary and more dependent on brand positioning, regulatory requirements, and total cost of ownership.
Supply‑side dynamics and raw‑material risk
4‑Vinyl Guaiacol is predominantly produced via decarboxylation of ferulic acid, itself sourced from agricultural byproducts such as rice bran, wheat bran and maize bran. Spot pricing and availability of ferulic acid have been materially volatile; our sector analysis recorded quarter‑on‑quarter volatility in China in the 12–18% range during 2024–2025. This volatility stems from agricultural production cycles, competing industrial demand and episodic logistical constraints.
Alternative sourcing routes — notably extraction from corn ethanol fermentation volatiles — are commercially available and offer an attractive bio‑based narrative; however, these routes have different unit economics, yield profiles and certification pathways. Our report models the cost breakevens and time‑to‑scale for each route and proposes risk‑mitigation tactics including long‑term forward contracts, strategic inventory buffers and selective vertical integration into ferulic‑acid supply chains.
Regulation, applications and commercial pull
4‑Vinyl Guaiacol is recognized within flavor industry standards (FEMA number 2675) for use in food flavoring, contributing clove‑like, smoky and spicy notes. Acceptance in this context reduces regulatory friction for reformulation and product launches; nonetheless, labeling, origin claims (natural vs synthetic), and halal/kosher certifications remain important commercial differentiators.
Demand drivers are diverse: premiumization in food & beverage products (artisan bakery, craft beverages), expanded use in perfumery where smoky/spicy accords are sought, and a steady role as an intermediate in specialty pharmaceutical syntheses. These demand pockets interact with supply constraints to create differentiated pricing bands and margin opportunities.
2026 strategic priorities — what to do next
- Procurement (0–6 months): Implement a dual‑track sourcing program that blends spot purchases with staggered forward contracts tied to ferulic‑acid indices; qualify at least two alternative suppliers from different regions for critical SKUs.
- R&D & Formulation (0–12 months): Run comparative bench trials of natural vs synthetic grades to quantify sensory delta and margin impact; secure research‑grade supply from certified distributors for controlled trials.
- Commercial (6–12 months): Segment customers by willingness to pay for bio‑based claims and reprice premium specifications accordingly; refresh specification sheets and QC acceptance to reduce batch rejection rates.
- Operational Resilience (6–18 months): Build inventory triggers and logistics contingencies for feedstock shocks; evaluate targeted vertical integration into ferulic‑acid supply or tolling partnerships with bio‑extractors.
- M&A & Partnerships (12–24 months): Use our M&A filters to shortlist bolt‑on assets that add traceable bio‑extraction capacity or expand geographic reach into underserved regions.
- Sustainability & Certification (ongoing): Prioritize certifications (organic, kosher/halal, chain‑of‑custody) aligned with core customer segments to command differentiation and price premiums.
Why PW Consulting’s report matters for 2026
Executives face a choice in 2026: act proactively to hedge raw‑material volatility and capitalize on premium demand, or risk being outmaneuvered by more agile competitors that have secured feedstock and validated bio‑based claims. PW Consulting’s report equips decision‑makers with the quantitative models, supplier intelligence, and playbooks needed to make those choices with confidence — while flagging the specific tactical moves that unlock near‑term margin improvement and long‑term strategic resilience.
For commercial teams, product managers and corporate development professionals, the deliverables are practical: a modular forecasting engine, supplier due‑diligence templates, regulatory checklists and prioritized investment options. For investors, the study reveals where returns concentrate under alternative scenarios and which asset types (extraction capacity vs synthetic scale) are most sensitive to feedstock swings.
Next steps
This preview highlights the strategic implications of the 4‑Vinyl Guaiacol market for 2026 planning. Our full report contains the detailed datasets, scenario outputs, supplier scorecards and executable templates that underpin the recommendations summarized here. To obtain the complete analysis, model files and the full set of tactical playbooks, please visit PW Consulting’s market reports page or contact our industry team directly.
For detailed analysis of this topic, please visit the official page: Worldwide 4-Vinyl Guaiacol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide 3‑Phase Distribution Boards Market to Reach USD 11,047.43 Million by 2032, Growing at a 5.85% CAGR (Forecast Period 2026–2032)
By pmarketresearch, 2026-08-18
Worldwide 3-Phase Distribution Boards Market — Strategic Insights for 2026 Decision-Makers
PW Consulting today publishes an executive briefing drawn from our forthcoming Worldwide 3-Phase Distribution Boards Market report (base year 2025, historical coverage 2020–2025, forecast 2026–2032). As capital programmes reset and electrification priorities accelerate, this research note distills the actionable intelligence that senior executives — from product management to procurement, M&A and regional expansion teams — need to shape investment choices in 2026. The analysis demonstrates why the market’s steady expansion, evolving competitive dynamics and regulatory momentum demand a recalibrated strategy across the value chain.
Sliding Bearing Market
Market snapshot: a clear growth runway
Our topline market model shows the global 3-phase distribution boards market expanding from an estimated USD 5,580.4 million in 2020 to USD 7,420.0 million in the base year 2025, and continuing to grow into the forecast horizon. PW Consulting’s baseline projection anticipates the market reaching roughly USD 8,019.3 million in 2026 and climbing to approximately USD 11,047.4 million by 2032, underpinned by a compound annual growth rate (CAGR) of 5.85% across the forecast period. These totals reflect the aggregate of product, retrofit and services demand across industrial, commercial and residential applications and incorporate the latest observable trends in capex, construction activity and retrofitting cycles.
Worldwide Industrial Li-ion Batteries Market
Market concentration metrics indicate room for both scale and strategic carve-outs: the top three vendors account for just over 32% of market revenues (CR3), while the top five capture roughly 47% (CR5). This structure presents opportunities for consolidation plays as well as profitable regional and application-focused niches.
Worldwide Oil Production Software Market
Why 2026 is an inflection year
- Regulatory tightening and standards alignment. The industry is operating in an increasingly prescriptive environment. Compliance requirements such as IEC 61439-1:2020 and regional code updates (including the US NEC 2023 Edition’s changes for switchboards/panelboards and the EU’s Ecodesign requirements where applicable) are elevating technical and documentation thresholds for manufacturers and system integrators.
- Cost and supply-chain pressure. Raw material volatility is an operational reality: for example, copper prices for busbars and hot-rolled coil steel costs for enclosure fabrication materially influence BOM economics and lead times. Procurement strategies in 2026 must actively hedge price and lead-time exposure to protect margins.
- Technology-led differentiation. Digital integration (digital twins, remote monitoring), enhanced arc flash protection, modular/prefabricated configurations and plug-and-play solutions are shifting buyer preferences. Leading suppliers are already embedding these attributes in new product releases and system architectures.
- Demand composition shift. Growth is driven by a mix of new-build projects (commercial and industrial), data center expansion, distributed generation and a sizeable retrofit market as owners modernize aging switchgear to meet safety and energy-efficiency targets.
Competitive landscape — what leading suppliers are doing now
The market includes global electrical OEMs and regional specialists. Major manufacturers such as Schneider Electric (Rueil‑Malmaison, France), ABB (Zurich, Switzerland), Siemens (Munich, Germany), Eaton (Dublin, Ireland) and Legrand (Limoges, France) continue to defend broad portfolios spanning low-voltage cubicles to integrated distribution systems, emphasizing IEC compliance, modularity and digital services. At the same time, regional champions — including Larsen & Toubro, Havells and CHINT Global — are leveraging local footprint, price competitiveness and tailored IP ratings to win large infrastructure and industrial projects.
Recent vendor activity is instructive for strategic planning: Eaton’s March 2024 launch of an arc-resistant low‑voltage air-insulated range underscores safety-driven product investment; Siemens’ digital twin showcase at Hannover Messe (February 2024) signals accelerated digitalization of switchgear asset management; ABB’s roll‑outs for data-center optimized switchboards and Schneider Electric’s UL certification for new modular platforms demonstrate parallel plays in compliance and product modularity. PW Consulting’s report offers vendor scorecards and case studies that synthesize these developments into implications for purchasing, product roadmaps and partnership strategies.
Practical implications for procurement, product and M&A teams in 2026
- Prioritize modular platforms that reduce installation risk and shorten time-to-commission. Modular designs and prefabricated assemblies lower on-site labour exposure and can be decisive in large commercial or data-center bids.
- Embed regulatory and safety compliance upfront. Engineering teams must treat standards (IEC updates, NEC labeling, Ecodesign) as non-negotiable product requirements; failure to do so raises rework costs and time-to-market risks.
- Hedge raw material exposure and diversify supplier bases. Given observed copper and steel price dynamics and concentrated component supply, procurement plans should include multi-sourcing, strategic inventory buffers and forward contracts where feasible.
- Explore bolt-on acquisitions and JV models in under‑penetrated regional markets. With a mid-level market concentration profile, there is scope for roll-up strategies that target installation capability, local certification expertise and aftermarket services.
- Monetize services: retrofit, predictive maintenance and lifecycle contracts. As installed bases age, service revenue becomes a durable margin stream; digital monitoring and remote diagnostics are central to these offers.
What PW Consulting’s report contains — operational, not academic
- Replicable market-sizing model (USD Million) spanning 2020–2032, with scenario testing and sensitivity to raw-material and construction-cycle shocks.
- Demand by mounting method, end-user category and region (detailed segment tables and growth curves are included in the full report for subscribers).
- Vendor benchmarking: product portfolios, technical differentiators, manufacturing footprint analysis, certification gaps and go-to-market capabilities.
- Cost-build templates and BOM drivers that quantify the impact of copper and steel price swings on board economics.
- Regulatory mapping and compliance checklists (IEC 61439, NEC 2023 implications, EU Ecodesign intersections) framed for product managers and compliance officers.
- M&A playbook and screening matrix that aligns targets to strategic objectives: capability acquisition, channel expansion and technology lift.
- Actionable 12–24 month implementation roadmaps for procurement, product and services teams, with KPIs and risk mitigations.
In keeping with the report’s role as a decision‑ready tool, PW Consulting provides granular segment-level modelling and company-level revenue splits only through the full report package and client engagements. This briefing is intended to preview the analytical depth and strategic guidance available in the complete deliverable.
Recommended 90‑day priorities for 2026 planning cycles
- Conduct an immediate BOM sensitivity review to quantify margin impact from current copper and steel price scenarios; lock critical long-lead items where warranted.
- Initiate a product compliance audit against IEC 61439-1:2020, NEC 2023 and regional Ecodesign rules to identify remedial certification needs and avoid market access delays.
- Prioritize pilots for modular, prefabricated assemblies with two strategic customers to validate installation time and cost benefits.
- Screen acquisition candidates in regions where local certification and installation capacity are constraints to growth.
- Define a service proposition (retrofit + monitoring) that leverages digital twin capabilities and remote diagnostics to generate recurring revenues.
How PW Consulting can help
Our full report equips executives with the quantitative and qualitative evidence needed to justify investment cases, prioritize R&D and execute commercial expansion. PW Consulting also offers tailored advisory services — from vendor diligence to pilot design, sourcing optimization and M&A execution — anchored in the data and playbooks contained in the report.
For executives preparing 2026 budgets and strategic plans, this briefing demonstrates why a combination of compliance-led product upgrades, supply-chain resilience and service monetization will define competitive winners. To access the complete dataset, vendor scorecards and downloadable models, please consult the PW Consulting report landing page — the full report contains the detailed segment tables and granular regional and application splits needed to operationalize the strategies summarized here.
For detailed analysis of this topic, please visit the official page: Worldwide 3-Phase Distribution Boards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Geocomposite Market to Grow at a 7.5% CAGR Through 2032
By pmarketresearch, 2026-08-18
PW Consulting Releases Strategic Brief: Worldwide Geocomposite Market — Positioning for Decisive Investment and Procurement in 2026
Executive summary
PW Consulting’s latest Worldwide Geocomposite Market report synthesizes five years of historical performance and a seven‑year forecast to provide executives with the actionable intelligence required to make high‑stakes decisions in 2026. The market has expanded steadily from approximately USD 432 million in 2020 to roughly USD 620 million in 2025, and PW projects a continuation of that momentum into 2026 and beyond — with the market expected to exceed USD 689 million in 2026 and to grow at a compound annual growth rate of 7.5% through the 2026–2032 forecast window, culminating in a market north of USD 1.0 billion by 2032.
Worldwide 2-Amino-5-Methylthiazole Market
Why 2026 is a pivotal year for geocomposite strategies
Several converging forces make 2026 a decision inflection point for producers, large buyers (infrastructure contractors, waste management operators, and mining companies), and investors:
Hydro-Pumped Storage Plants Market
- Macro infrastructure activity and climate‑resilient retrofit programs are increasing demand for engineered drainage, reinforcement, and containment solutions.
- Regulatory signals — from federal-level proposals to state orders — are shifting technical specifications toward composite liner and drainage systems, elevating the role of geocomposites in compliance strategies and tender outcomes.
- Raw material volatility and feedstock mix choices are creating meaningful margin and sourcing risk: polymer feedstock cycles and differences between virgin and recycled inputs are changing cost structures, driving product design tradeoffs and commercial negotiation dynamics.
- Market concentration and supply-side moves (capacity expansions, M&A, and technology integrations) are reshaping bargaining power between buyers and suppliers, particularly for higher‑value or higher‑performance product tiers.
Report scope and practical utility for decision‑makers
The PW Consulting report was constructed with a practitioner’s perspective: not a purely academic forecast, but a playbook designed to be used during boardroom capital allocation debates, procurement renegotiations, product roadmap sessions, and M&A diligence. Key practical deliverables include:
Worldwide Risk Advisory Service Market
- Robust market sizing and trend analysis spanning 2020–2025 with a firm 2026 baseline and detailed scenario forecasts through 2032 to stress‑test investment cases.
- Three forward scenarios (baseline growth, accelerated infrastructure, and raw‑material shock) that quantify impacts on demand, pricing power, and capacity utilization.
- Supplier heatmaps and capability dossiers that benchmark manufacturing technologies, product portfolios, certification footprints, and export reach — enabling targeted shortlists for strategic partnerships or supplier consolidation.
- Cost‑sensitivity models and procurement toolkits that translate feedstock price shifts into unit cost and margin outcomes, and provide negotiating levers and contractual clauses to mitigate pass‑through risk.
- Regulatory-impact matrices that map emerging rules and guidance (federal and state) to specification changes, compliance costs, and opportunity windows for compliant geocomposite solutions.
- Case studies and an implementation playbook covering specification optimization, field validation protocols, and lifecycle costing to support technical commercial conversations with owners and engineers.
- M&A and capex evaluation frameworks that prioritize targets and brownfield/greenfield investments using demand‑backed thresholds and scenario‑driven payback analysis.
Competitive landscape: what executives must know
The industry exhibits a moderate degree of concentration — with the top three players controlling a material share of market revenues and the top five accounting for a clear majority of organized sales channels. This structure drives differentiated strategies across incumbents and challengers:
- Established global specialists that combine advanced manufacturing and specification influence (examples include companies with deep roots in geotextiles, geogrids, or geomembranes) are leveraging product breadth and engineering services to secure infrastructure and environmental contracts.
- Technology‑oriented firms focus on high‑strength and performance‑certified solutions for soil reinforcement and slope stabilization, where technical differentiation supports premium pricing and long‑term project relationships.
- Volume producers with export orientation serve large civil and landfill markets by competing on cost, scale, and lead‑time efficiency; they are important strategic partners for global contractors but are sensitive to feedstock cycles and freight disruptions.
- Integration plays — where geomembrane, geotextile, and extrusion capabilities converge via acquisition or capacity expansion — are increasing competitive pressure in drainage and composite liner segments, changing procurement dynamics for specifiers and owners.
Our report contains company‑level analysis on the sector’s leading names, profiling strategic positioning, technology advantages, manufacturing footprint considerations, and go‑to‑market strengths and vulnerabilities. That analysis synthesizes public filings, company publications, product datasheets, and on‑the‑ground channel feedback to create an actionable supplier shortlist and a shortlist of plausible acquisition targets for scale and technology buyers.
Recent industry developments that will shape 2026 outcomes
- Manufacturers and trade groups have just issued updated manufacturer guides and product datasheets that refine transmissivity, tensile and filtration metrics — documentation that buyers and engineers will reference in upcoming tenders.
- Notable portfolio integrations have added production capacity into certain geosynthetic lines, altering regional supply dynamics and shortening lead times for composite liner and drainage products.
- Market signals point to wider deployment of geocomposites on major highways and slope stabilization projects emphasizing lifecycle performance and sustainability, raising the bar for product certification and quality control.
- Regulatory movements at both federal and state levels are tightening technical requirements for containment and leachate management systems; compliance‑driven demand is expected to accelerate adoption of composite solutions in specified jurisdictions.
Strategic playbook for market participants in 2026
Executives should translate market intelligence into a tight set of actions. PW recommends the following prioritized moves:
- Recalibrate procurement: negotiate multi‑year feedstock linkage clauses, establish dual‑sourcing in critical product lines, and adopt indexed pricing mechanisms to reduce P&L volatility from polymer swings.
- Product portfolio prioritization: rationalize SKUs to focus R&D and production on higher‑margin, specification‑driven products (drainage composites, high‑strength reinforcement systems) while automating low‑value commodity lines.
- Regulatory engagement: proactively submit performance data during spec revision processes in key jurisdictions and design compliance‑forward product variants to capture tender advantages.
- Selective capacity investment: defer greenfield capacity unless tied to long‑term offtake; prioritize brownfield upgrades and production flexibility (modular lines, extrusion versatility) to respond quickly to specification shifts.
- M&A and partnership criteria: target targets that fill technology gaps (transmissivity, composite board performance), add validated certification schemes, or provide strategic geographic distribution hubs with lower freight exposure.
- Commercial go‑to‑market adjustments: align sales incentives with lifecycle value metrics, develop owner‑facing calculators to demonstrate total cost of ownership improvements, and bundle engineering support with product bids.
How to use the full PW Consulting report
This article is a strategic preview designed to highlight the report’s decision‑critical insights without disclosing the granular segmentation tables, region/application allocations, or unit‑level pricing matrices that underpin our recommendations. The full report includes:
- Detailed regional and application split tables, including historical series and growth drivers by market segment;
- Comprehensive supplier scorecards and capacity maps with technology and certification overlays;
- Unit‑level cost models, sensitivity runs and pass‑through scenarios tied to multiple feedstock price paths;
- Operational checklists for procurement, R&D gating criteria, and M&A due diligence templates.
Decision‑makers preparing 2026 budgets, capital plans, procurement RFPs, or M&A screens will find the full set of quantitative models and supplier dossiers indispensable for accelerating certainty and reducing execution risk.
Conclusion — why this report matters for 2026
As the geocomposite market scales past the mid‑2020s, the combination of regulatory tightening, infrastructure demand, and feedstock cyclicality will create both opportunity and operational risk. PW Consulting’s Worldwide Geocomposite Market report converts those macro‑trends into pragmatic actions: it quantifies demand and margin levers, highlights supplier strengths and vulnerabilities, and provides the tactical toolset procurement teams and corporate strategists need to lock in advantage. For executives preparing to allocate capital, renegotiate supply agreements, or pursue strategic acquisitions in 2026, the full report is designed to shorten decision cycles and increase confidence in outcomes.
To access the complete analysis, detailed segment tables, supplier scorecards, and executable playbooks, visit PW Consulting’s report page for the Worldwide Geocomposite Market.
For detailed analysis of this topic, please visit the official page: Worldwide Geocomposite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flexible Surgical Robot Market Hits USD 620 Million in 2025, Poised for Rapid Expansion
By pmarketresearch, 2026-08-18
Flexible Surgical Robot Market 2026: Strategic Imperatives for Executives
PW Consulting’s new market study on Flexible Surgical Robots positions 2026 as the inflection year for strategic decisions across medtech OEMs, hospital systems, investors, and policy makers. Our analysis shows the flexible surgical-robotics sector moving from a promising niche into a commercially meaningful market: the industry is forecast to grow from a 2025 base of USD 620.0 million to roughly USD 1.6 billion by 2032, reflecting a compound annual growth rate (CAGR) of 14.5% over the 2026–2032 forecast period. That trajectory is underpinned by accelerating clinical validation, focused capital deployment, and emerging reimbursement and regulatory frameworks that collectively lower adoption barriers.
Worldwide Open Peripheral Pump Market
Why 2026 Matters: Convergence of Clinical, Capital, and Policy Catalysts
Several concurrent dynamics elevate 2026 from a planning year to a decisive year for resource allocation and strategic repositioning. Clinically, flexible platforms are moving from feasibility and early efficacy demonstrations to multicenter trials and more complex procedures. Industry capital flows are following: venture and strategic funding rounds have expanded R&D runway for differentiated platforms. Regulators and payers are, in parallel, crystallizing the environment for commercialization—clarifying pathways and early reimbursement signals that materially affect hospital purchasing decisions.
Atosiban Acetate API Market
- Clinical validation acceleration: First-in-class clinical milestones and Institutional Review Board–backed trials are enabling stronger surgeon acceptance and establishing comparative-effectiveness hypotheses for follow-on studies.
- Targeted capital deployment: Follow-on rounds and strategic investments are concentrating on platforms that can convert clinical wins into repeatable, cost-effective workflows.
- Regulatory & reimbursement tailwinds: Recent regulatory activity emphasizes modular, indication-specific flexible designs, while new CPT codes and payer dialogues are creating early pathways to monetize advanced procedures.
Market Structure and Competitive Dynamics
The flexible surgical-robotics market is already displaying a clear structure: innovation is concentrated among a handful of technology-driven entrants and a few established strategic players that leverage distribution scale. Our concentration analysis highlights this consolidation: the top three firms account for roughly 58% of the market, and the top five approach 77%, signaling both a high barrier to scale and concentrated competitive power among incumbents and well-funded challengers.
Smart Power Line Inspection System Market
Key company archetypes identified in the report illustrate strategic variety:
- First-mover, indication-focused innovators: Companies developing platform technologies that enable specific endoluminal or single-incision procedures. These firms emphasize clinical trials, modular instrument suites, and direct surgeon engagement to establish clinical utility.
- Miniaturization and component specialists: Entrants that focus on sub-millimeter to millimeter-scale actuation and flexible instrumentation—positioned as upstream suppliers or niche-system OEMs with easier integration into existing endoscopes.
- Platform-and-channel incumbents: Larger medtech companies that incorporate flexible capabilities into broader portfolios and leverage global sales channels to accelerate adoption for high-volume indications.
Representative companies and recent developments are discussed in our competitive dossier. Highlights to note include early pivotal procedures and significant funding rounds that materially de-risk product advancement and commercial scale-up, as well as regulatory milestones that validate clinical trial pathways for flexible platforms.
What the Report Contains: Operationally Actionable Intelligence
PW Consulting’s report is built as a decision-support toolkit for 2026 initiatives. It blends quantitative market sizing with qualitative frameworks so that each class of stakeholder can convert insight into action without wading through raw datasets alone. The report’s operational elements include:
- Top-line market sizing and seven-year forecasts (2026–2032), including scenario-tested downside and upside cases tied to clinical and reimbursement milestones.
- Technology deep-dives that map platform architectures, instrument modalities, and integration vectors—highlighting where performance trade-offs exist (e.g., dexterity versus miniaturization) and which approaches are clinic-ready.
- Clinical evidence inventory and trial-mapping, pinpointing the lead indications, trial phases, and time-to-evidence thresholds that matter for hospital adoption.
- Regulatory and reimbursement playbooks that translate FDA pathways and CPT developments into commercialization timelines and pricing levers.
- Buyer economics and hospital procurement modeling that incorporate capital cost, maintenance, and per-procedure disposables—enabling ROI gates tied to volume thresholds and reimbursement realization.
- Competitive landscaping and capability matrices for leading firms, with strategic scenarios including M&A targets, partnership archetypes, and white-space opportunities.
- Go-to-market blueprints for OEMs and service providers, including a channel assessment, surgeon training pathways, and institutional adoption roadmaps.
To preserve competitive integrity and invite deeper engagement, the report intentionally provides rich, actionable frameworks while the full granular segmentation tables and line-item forecast sheets (region-by-region, mechanism-by-mechanism, and application-level dollars) are available through our primary subscription channel.
Strategic Implications by Stakeholder
PW Consulting synthesizes the market implications into clear strategic moves for the primary stakeholders who need to act in 2026.
- OEMs and new entrants: Prioritize platforms that can demonstrate both procedure-level clinical advantage and manageable unit economics. Invest in second-order capabilities—data connectivity, modular disposables, and service models—that convert single-procedure wins into recurring revenue.
- Hospital systems and health networks: Develop cross-disciplinary adoption committees that assess flexible-robotic propositions against full cost-of-care metrics. Negotiate bundled agreements that align device procurement with shared-savings on reduced length-of-stay and complication avoidance.
- Investors and strategic acquirers: Focus on firms that combine technical differentiation with a credible clinical pathway—evidence of multicenter trials, regulatory momentum, and early reimbursement discussions materially de-risks exit timing.
- Payers and policy-makers: Engage earlier with evidence-generation strategies to define coverage positions and payment levels that incentivize high-value uses without promoting inappropriate utilization.
- Component suppliers: Lock in dual-sourcing and scalable manufacturing capacity now; lead times for miniaturized, flexible components will create bottlenecks as adopters move from pilot to scale.
Priority Moves for 2026 — A Tactical Checklist
- Close clinical-evidence gaps for highest-potential indications. Target randomized or multicenter comparative studies that speak directly to payer value propositions.
- Build reimbursement playbooks around evolving CPT and CMS signals—translate codes into price-to-procedure models that hospitals can operationalize.
- Design flexible commercial models (lease, subscription, outcome-sharing) to lower upfront capital barriers and align incentives with utilization.
- Secure integrated surgeon training programs and proctorship pathways to shorten time-to-first-case and mitigate early-adopter friction.
- Validate supply-chain robustness by qualifying alternate suppliers for critical flexible-actuation components and disposables.
Risks, Uncertainties, and What to Watch in 2026
Key uncertainties remain: the pace of surgeon training and comfort, the final shape of reimbursement codes and coverage policies, and the economics of disposables versus reusable instrument strategies. Our sensitivity analyses identify three high-impact triggers that could alter the growth path materially: large-scale comparative trials showing unequivocal clinical or economic benefit; adverse reimbursement determinations; and supply-chain constraints that raise per-procedure costs beyond hospital thresholds.
Conclusion — The Strategic Value of the Report for 2026
Decision-makers need market intelligence that is both rigorous and operationally directive. PW Consulting’s Flexible Surgical Robot Market report offers precisely that: a clear forecast rooted in up-to-date clinical and regulatory signals, competitive mapping that reveals where market power is consolidating, and a tactical playbook for converting technological promise into commercial adoption. For executives preparing 2026 budgets, R&D roadmaps, or M&A strategies, the report provides the evidence-based frameworks and scenario models needed to make confident, time-sensitive choices.
For organizations ready to move from inquiry to implementation, PW Consulting’s full dataset and consultative briefings will map out the granular segmentation, unit-economics worksheets, and tailored go-to-market models necessary to operationalize a 2026 strategy. Contact PW Consulting to arrange a briefing and access the complete forecast model and proprietary scenario tools.
For detailed analysis of this topic, please visit the official page: Flexible Surgical Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Most Mistfall Hunter runs are decided before the first serious fight begins. You can have strong gear, a full supply of healing items, and still lose everything because the squad wandered too far apart or pushed at the wrong time. A better approach is to treat each expedition as a series of choices. Where are we going? What do we need? Which fights help us, and which ones only create noise? Keeping an eye on Mistfall Hunter Gyldenblod and other valuable resources makes those choices feel more important, because a careless death can set back several future runs. Stay close enough to help one another, use simple callouts, and don't chase a wounded enemy around a corner without knowing what's waiting there.
Make Teamwork Practical, Not Complicated
Good communication doesn't mean talking nonstop. Short, useful information is better: one enemy behind the wall, two players near the Bell, healing now, or fall back. Everyone should know who starts a fight, who watches the flank, and who can rescue a teammate if things go bad. A frontline player can draw attention, but that player shouldn't sprint so far ahead that support cannot keep up. Damage dealers need to agree on a target instead of spreading attacks across the whole enemy team. Support players should watch more than health bars; they also need to notice incoming pressure and save defensive tools for the moment they matter. After a win, reload, heal, and regroup. Plenty of squads throw away an easy victory by chasing one escaping player into a second team.
Pick Your Fights Around the Bell
The Bell changes the way nearby teams move, so getting there first doesn't automatically mean you've won. Before starting the objective, check the entrances, nearby cover, and likely routes from other squads. One player can begin the interaction while the others hold angles and listen for footsteps. If another team appears, ask what the fight actually achieves. Is the area safe enough to contest? Do you have enough healing? Has a third squad already heard the noise? Sometimes holding a strong position is smarter than charging out into the open. If a battle starts, focus on a quick finish. A damaged enemy who escapes may heal, revive a teammate, and return when your resources are low. Once the Bell and worthwhile loot are secured, extraction should become the priority rather than an excuse to keep hunting.
Spend Cooldowns and Healing With a Plan
New players often heal only after their health is nearly gone. By then, the enemy has already decided the pace of the fight. Move behind cover as soon as you take serious damage, and don't be afraid to give up a few metres of ground to create space. Save movement skills for more than an opening attack. They can break line of sight, interrupt a chase, or get a downed teammate out of danger. The same goes for major defensive abilities. Using one just to deal a little extra damage can leave the squad helpless when the enemy really commits. Watch what opponents have spent. If their escape tool is gone, pressure them. If your own key ability is unavailable, play quietly until it returns. Small pauses often win fights that constant aggression would lose.
Survive the PvE Pressure as Well
Rival hunters aren't the only threat in Mistfall Hunter. Elite creatures can pin a player in place, draw attention from another squad, or force everyone into a bad position. Learn which attacks have obvious warning signs and which enemies punish close-range greed. Ranged players should keep enough distance to react, while melee fighters need a clear exit before committing. Don't burn every powerful attack on a protected target if a better opening is seconds away. When a dungeon fight gets messy, move together instead of scattering in panic. A quick retreat can reset the encounter and keep a rival team from finding you weakened. Before entering high-risk content, check your consumables, equipment, and resource budget. Progress feels much better when one failed run doesn't wipe out everything you need for the next few attempts.
Know When the Run Has Paid Off
Extraction games reward restraint, even when the scoreboard makes aggression feel tempting. You don't need every elimination, every chest, or one more risky detour. Once the squad has a useful haul and the route out looks manageable, leave while you still control the situation. That habit builds a stronger resource reserve and gives you more chances to practise difficult content. If your supply is running low, choosing to buy Mistfall Hunter Gyldenblod can support your next run, but it won't replace sound positioning or communication. Keep the team together, listen before pushing, and treat every fight as optional until it clearly improves your position. The players who extract consistently aren't always the ones with the best aim; they're the ones who recognise danger early and refuse to turn a good run into a needless loss.
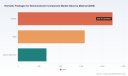
PW Consulting: Hermetic Packages Market to Expand from USD 4,500 Million in 2025 to USD 7,017 Million by 2032 at a 6.55% CAGR — Ceramic Segment Leads with USD 2,240 Million
By pmarketresearch, 2026-08-18
Hermetic Packages for Semiconductor Component Market — Strategic Imperatives for 2026
PW Consulting today publishes an executive briefing tied to our full market study, "Hermetic Packages for Semiconductor Component Market" (base year 2025, forecast 2026–2032). The briefing synthesizes the report’s most consequential findings for corporate leaders preparing budget cycles, product roadmaps and supply‑chain reconfiguration in 2026. Our analysis is grounded in a consistent historical dataset (2020–2025) and a forward projection that assumes a compound annual growth rate (CAGR) of 6.55% across the forecast window. In simple scale terms, the market expanded from USD 3,250 Million in 2020 to USD 4,500 Million in 2025 and, under our baseline model, approaches USD 7,017 Million by 2032.
Ship-specific Display Market
Why 2026 is a Strategic Inflection Point
Several converging forces make 2026 the year when strategy becomes execution for hermetic packaging suppliers, semiconductor OEMs and systems integrators:
Vitamin K2 Market
- Technology-driven demand: Continued miniaturization, the thermal and reliability demands of high‑power AI accelerators, and expansion of mmWave RF devices are increasing the technical bar for hermetic solutions.
- Regulatory and qualification pressure: High‑reliability sectors — aerospace, defense and medical — continue to require MIL‑STD and Class H/K level qualifications, elongating time‑to‑market and raising the cost of design changes.
- Supply‑chain resilience and geopolitics: Onshoring initiatives and industrial policy measures aimed at securing critical semiconductor supply chains are reshaping investment incentives for domestic hermetic package capacity.
- Materials and thermal engineering: Adoption of advanced materials (for example AlSiC for thermal management and multilayer ceramic cores to reduce warpage) is shifting supplier specializations and BOM economics.
For 2026 planning, these dynamics translate into specific boardroom priorities: accelerate qualification programs for next‑generation packages, protect roadmap timelines from supplier concentration risk, and prioritize design for hermeticity early in the silicon/package co‑development cycle.
Fresh Onions and Shallots Market
Market Trajectory: What the Numbers Mean for Decision Makers
Our base‑case projection (CAGR 6.55%) embodies a market that is expanding steadily rather than exploding. That growth profile creates a different set of strategic choices than a rapidly hyper‑growing market: suppliers and OEMs must synchronize capacity investments with medium‑term demand certainty, avoid overbuild in narrow subsegments, and carve out higher‑margin niches through specialty materials, qualification services and design‑for‑reliability offerings.
- Capacity planning: Given the moderate but persistent growth trajectory, incremental capacity additions that emphasize flexibility (modular lines, multi‑material process capability) are preferable to single‑purpose greenfield plants.
- R&D and IP: Investing in material science (ceramics, glass‑to‑metal seals, AlSiC composites) and process IP that reduce qualification cycles will yield outsized returns in high‑reliability markets.
- Commercial models: Value‑added services — qualification partner programs, accelerated testing, and custom build‑to‑print options — create differentiation in a market where commoditization pressure exists in standard form factors.
Full segmented demand curves by region, material and application are included in the full report; intentionally, this briefing omits those granular splits to drive direct engagement with the source material for procurement and strategy teams building business cases.
What the Full Report Delivers — Practical, Actionable Tools
We designed the report for use in 2026 planning cycles. Key deliverables include:
- Quantitative demand model (2020–2032) with scenarios (baseline, upside, downside) and sensitivity levers to test price, qualification time, and adoption rates for new materials.
- Supplier scorecards and capability maps assessing process breadth (ceramic HTCC, glass‑to‑metal, AlSiC brazing, molded ceramic), qualification throughput, and geopolitical supply‑chain exposure.
- Go‑to‑market playbooks for suppliers targeting aerospace/defense, medical and AI/high‑power markets — including sales motion, certification roadmaps and sample‑to‑production timelines.
- CapEx prioritization and ROI templates calibrated for the industry’s unit economics and lead‑time realities.
- Regulatory compliance matrix and accelerated qualification checklists for MIL‑STD and Class H/K pathways.
- Design‑for‑hermeticity best practices and yield optimization guidance for packaging engineers collaborating with fab partners.
These deliverables are explicitly practical — designed to be imported into procurement RFPs, product development Gantt charts and board‑level capital allocation models.
Competitive Landscape: Strategic Profiles and Implications
The market comprises a mix of material specialists, vertically integrated fabricators and niche engineered‑product companies. Our competitive analysis covers a representative set of leaders and innovators; the full report contains extended company profiles and comparative scorecards. Selected strategic observations follow:
- SCHOTT AG (Mainz, Germany) — Strength: deep expertise in hermetic microelectronic packages and hybrid solutions. Strategic implication: well‑positioned to lead cross‑border programs where integrated optical/glass solutions are required; prospective partners should evaluate SCHOTT for co‑development where glass hermeticity is a differentiator.
- AMETEK Inc. (Aegis / Hermetic Seal) (USA) — Strength: glass‑to‑metal seals and flatpack heritage for defense/aerospace. Strategic implication: a natural supplier for programs requiring long lifecycle support and high‑reliability traceability; consider long‑term supply agreements to secure capacity for defense contracts.
- Kyocera Corporation (Japan) — Strength: multilayer ceramic hermetic packages and recent commercialization of multilayer ceramic core substrates to mitigate warpage. Strategic implication: semiconductor OEMs pushing advanced packaging (AI and high‑power) should evaluate Kyocera as a materials partner to solve warpage and co‑packaging thermal challenges.
- Electronic Products Inc. (EPI) (USA) — Strength: vertical integration across HTCC ceramic and glass‑to‑metal hermetic processes. Strategic implication: attractive partner for OEMs seeking single‑source qualification and shorter supply chains; useful in onshoring strategies.
- Complete Hermetics (USA) — Strength: bespoke hermetic packages and a recent product refresh emphasizing RF, MEMS and power applications. Strategic implication: ideal for prototyping and low‑volume high‑mix programs where customization and rapid iteration matter.
- CPS Technologies Corporation (USA) — Strength: AlSiC hermetic solutions with thermal management focus. Strategic implication: suppliers and OEMs targeting high‑power modules should assess CPS for thermal subsystem integration.
- StratEdge Corporation (USA) — Strength: fully hermetic molded ceramic packages optimized for microwave/mmWave up to ~18 GHz. Strategic implication: positioned to capture share from 5G/6G infrastructure and automotive radar programs.
- Materion Corporation (USA) — Strength: materials and lid covers, braze alloys essential to hermetic supply chains. Strategic implication: an upstream lever for manufacturers seeking material differentiation or supply security.
- Teledyne Technologies (incl. Micross) (USA) — Strength: system‑level assembly and hermetic packaging for space and medical. Strategic implication: a partner of choice where turn‑key assemblies and traceability are mandatory.
Across this competitive set, our analysis highlights two strategic playbooks that consistently outperform: (1) specialization in a narrowly defined reliability or frequency niche combined with accelerated qualification services, and (2) horizontal integration across materials and assembly to reduce vendor count for high‑assurance programs.
Risks, Scenarios and Strategic Responses
Key risks that should influence 2026 capital and partnership decisions include:
- Raw material volatility and single‑source dependencies (e.g., specialty alloys and composites used for thermal management).
- Qualification timeline overruns driven by stricter MIL‑STD/Class H/K testing and lengthening aerospace/space certification cycles.
- Geopolitical shifts that incentivize onshoring, altering comparative cost structures and creating short‑term capacity squeezes.
We model three scenarios in the full report: a baseline (CAGR 6.55%), an upside where defense/AI acceleration pushes near‑term adoption, and a downside where substitution and longer qualification drag growth. For corporate planning, we recommend stress‑testing financial models against the downside for procurement lead times and the upside for capacity constraints to avoid being caught undercapacity or overleveraged.
How to Use This Intelligence in 2026 Planning
Leaders assembling 2026 budgets should treat hermetic packaging not as a commodity line item but as a strategic node that affects product reliability, time‑to‑field and program margins. Practical steps we recommend this planning season:
- Start qualification conversations now: move early into qualification lanes with at least two suppliers to shorten contingency lead times.
- Adopt modular capacity investments: prefer flexible investments that can be redeployed across materials and form factors.
- Negotiate outcome‑based contracts: link pricing to yield and qualification milestones to align supplier incentives.
- Invest in co‑engineering: internal packaging and reliability engineers should be embedded with supplier teams during prototype stages.
Next Steps — Accessing the Full Intelligence
This briefing is intentionally concentrated on strategic implications and programmatic actions; the full PW Consulting report contains the granular market tables, regional and application splits, comprehensive company scorecards and the downloadable demand model used to generate our forecasts. If your 2026 planning requires vendor shortlists, supplier risk heat maps, or the scenario model exported to your financial templates, the full report and data packs are available through PW Consulting’s market research portal.
For boards, procurement committees and R&D leaders entering the 2026 planning season: hermetic packaging will not be a back‑office detail. It is a determinative factor in program timing, reliability and total cost of ownership. Our analysis provides the calibrated market view and tactical toolset to convert growth into profitable, defendable market share — but the specific segmentation tables and supplier benchmarking you need to operationalize these recommendations are held in the full report.
Contact PW Consulting to arrange a briefing of the full dataset, request customized seg‑by‑application scenarios, or commission a tailored supplier due‑diligence engagement calibrated to your program timelines.
For detailed analysis of this topic, please visit the official page: Hermetic Packages for Semiconductor Component Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Tuberculosis Therapeutics Market Poised for 5.82% CAGR Through 2026–2032
By pmarketresearch, 2026-08-18
Worldwide Tuberculosis Therapeutics Market: Strategic Intelligence to Shape 2026 Decisions
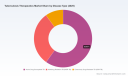
PW Consulting’s new market intelligence brief for the Worldwide Tuberculosis (TB) Therapeutics Market synthesizes clinical, commercial, and policy dynamics into an operational playbook for 2026. Anchored on a 2025 base year assessment and our 2026–2032 forecast, the study projects steady expansion underpinned by incremental uptake of shorter, all-oral regimens, generic entry following patent expirations, and sustained donor and government demand for scalable treatment pathways. The market is forecast to grow at a compound annual growth rate (CAGR) of 5.82% over the projection window—gestures toward material opportunity across originators, generics manufacturers, public health procurers, and investors while also flagging acute access and funding risks that will shape winners and losers in the next 18 months.
Worldwide On-Demand Delivery Software Market
Why this report matters for 2026 strategic choices
-
Actionability: The report translates epidemiology and clinical pipeline trends into commercially actionable scenarios—pricing and reimbursement sensitivity models, product prioritization matrices, and regulatory-readiness checklists targeted at the 2026 decision calendar.
Worldwide On-Line Analytical Processing (OLAP) Business Intelligence Consulting Services Market -
Timing: Several catalytic events converge in and around 2025–2026 (regulatory approvals, patent expiries, late-stage trial readouts). Our analysis maps these inflection points to concrete business actions—e.g., accelerated generic launches, supply-chain hedges, or licencing negotiations—with quarter-by-quarter decision triggers for 2026.
Construcion Machinery Slip Rings Market -
Risk-weighted returns: We provide risk-adjusted revenue scenarios and portfolio impact assessments to help executives calibrate R&D spend, manufacturing scale-up, and M&A activity in an environment where clinical efficacy, access policy, and donor funding can pivot value rapidly.
-
Competitive clarity without spoiling the playbook: The brief demonstrates deep competitor and pipeline insight to inform negotiations and partnership targets, while preserving full granular segment tables and price-sensitivity models to drive readers to the source for transaction-level intelligence.
Macro picture: growth, concentration and what they mean
Built on a 2025 base and extrapolated through 2032, the market outlook indicates consistent expansion at roughly a mid-single-digit CAGR. This trajectory reflects a balance between growing demand for treatment of drug-resistant forms of TB, the adoption of WHO-recommended shorter all-oral regimens, and countervailing pressures from donor funding gaps and price erosion as generics enter key markets. Market concentration metrics point to a moderately consolidated landscape (top-three and top-five firm concentration indices are material), implying that strategic moves by a small set of global and regional players will materially influence pricing, supply, and therapeutic mix across 2026.
Clinical and regulatory inflection points to watch in 2026
-
Late-stage pipeline catalysts: Clinical advancement of novel agents and regimen trials can accelerate transitions from long multi-drug treatments to shorter, all-oral courses. The market brief provides a calibrated view of which investigational assets are most likely to change standard-of-care by 2026–2028 and what that will mean for incumbent portfolios.
-
Patent expiries and generic entry: Key originator patents are reaching expiry windows that permit rapid generic entry in multiple jurisdictions. Our analysis estimates the likely timing and pricing impacts of such entries and models survival curves for branded volumes under different access scenarios.
-
Regulatory approvals and guideline uptake: WHO regimen recommendations and national guideline updates will be the proximate drivers of procurement cycles. The report links clinical readouts and approvals to expected adoption timetables in donor-funded and self-financed markets—information essential for planning 2026 manufacturing and tender participation.
Competitive landscape—who does what and where strategy matters
The market is characterized by a mix of international originators, specialized non-profits, and a robust generics manufacturing base concentrated in certain emerging-market hubs. Our strategic profiles synthesize each player’s commercial positioning, pipeline exposure, manufacturing footprint, and access strategies to identify realistic partnership and competitive threats for 2026:
-
Large originators with proprietary assets: Players that commercialize newer therapies for drug-resistant TB are positioned to capture premium pricing in the near term, but face erosion risk as patents lapse and generics scale. Their strategic options include licensing, voluntary technology transfers, and targeted price differentiation to preserve value while supporting access commitments.
-
Non-profit developers and regimen innovators: Organizations developing shorter, all-oral regimens occupy outsized influence over standard-of-care shifts. Their trial readouts and policy advocacy will directly affect demand for both branded and generic products.
-
Generics manufacturers and API suppliers: A dense set of manufacturers that supply first- and second-line medicines—and crucial APIs—form the backbone of global supply. Their ability to scale, maintain quality standards, and secure API supply will determine who can rapidly capture market share post-patent expiry.
For decision-makers, the competition analysis in the brief flags where collaboration (e.g., product donation, pooled procurement, co-manufacturing) is strategically superior to head-to-head competition in 2026—especially when tender size, regulatory complexity, and procurement timelines are factored in.
Policy, funding and access constraints that will shape 2026 outcomes
Policy and funding considerations are central to any commercial plan for TB therapeutics. The global funding gap for TB prevention, diagnosis and treatment remains significant versus stated targets; constraint in available resources will moderate price tolerance and increase the importance of cost-per-cure economics. The report connects macro funding shortfalls and treatment success rate trends to procurement behavior and donor strategy, helping firms anticipate demand shocks and design adaptive pricing and access plans.
Practical deliverables included in the report
-
Scenario-based revenue models: Multiple demand scenarios with sensitivity to regimen adoption, pricing, and procurement pathways—ready to be adjusted with company-specific inputs.
-
Regulatory and guideline assimilation: A timeline that maps clinical trial milestones to expected WHO and national guideline updates, with suggested regulatory engagement playbooks.
-
Manufacturing and API risk matrix: Supplier concentration analysis, quality-certification heatmaps, and contingency strategies for API disruptions—structured for contract manufacturing decisions in 2026.
-
Commercial go-to-market blueprints: Tender-entry strategies, differentiated pricing frameworks for donor-funded vs. private-pay segments, and partnership archetypes optimized for scale and access.
-
M&A and partnership screeners: Targets and transaction rationales, with quick-read investment cases and downside scenarios to support board-level deliberations.
-
Stakeholder engagement playbooks: Communications and advocacy templates for working with national programs, donors, and civil society to accelerate uptake while managing reputational risk.
Recommended 2026 decision roadmap
We recommend that leadership teams align a set of prioritized actions across three horizons to capitalize on the 2026 inflection landscape:
-
Near-term (Q1–Q4 2026): Lock in supply and regulatory pathways for high-priority products; commence price and access negotiations in markets where guideline updates are imminent; formalize technology-transfer or licensing agreements to prepare for generic competition.
-
Medium-term (2026–2028): Scale manufacturing capacity tied to demand scenarios, execute M&A or strategic partnerships to shore up API supply, and invest selectively in registrational studies supporting regimen indications that map to WHO-recommended treatment algorithms.
-
Longer-term (through 2032): Maintain optionality in R&D pipelines for next-generation molecules while building enduring relationships with procurers and health systems to capture value from regimen shifts and programmatic scale-ups.
How leading organizations will use this intelligence
-
Originators: To decide between defensive price strategies versus open-licensing models and to prioritize geographic registration plans aligned with guideline updates.
-
Generics manufacturers: To time capacity investments and pursue WHO prequalification and procurement partnerships; our models help determine how quickly price competition will compress branded margins post-patent expiry.
-
Donors and purchasers: To model cost-per-cure trade-offs across regimens and to design pooled-procurement vehicles that maximize purchasing power while ensuring supplier diversity.
-
Investors and M&A teams: To screen targets with strategic API positions, regulatory filings, or access partnerships that de-risk near-term revenues despite market transitions.
Where the “trailer” leaves you and why you should consult the full report
This article outlines the strategic implications and action agenda that PW Consulting’s full report provides in operational detail. To preserve proprietary transaction-ready analytics we have intentionally withheld granular segment tables and price-point matrices from this preview. The full report contains the complete dataset, detailed regional and disease-type segmentation, supplier concentration by molecule and API, and downloadable scenario models that can be run with client-specific inputs—tools essential for any organization making binding commercial or capital-allocation decisions in 2026.
Next steps
-
If you are preparing procurement calendars, manufacturing investments, or M&A activity for 2026, begin with a scenario workshop: use our models to stress-test your portfolio under the three demand and funding trajectories we outline.
-
Engage early with policy stakeholders to anticipate guideline adoption timelines; regulatory and procurement timing will be the decisive variables for revenue realization in 2026–2027.
-
Contact PW Consulting for a tailored briefing and access to the full dataset and interactive financial models that underpin these conclusions.
PW Consulting’s Worldwide Tuberculosis Therapeutics Market report is designed to convert epidemiology and pipeline momentum into crisp strategic decisions. For organizations that must act in 2026, the difference between opportunistic positioning and reactive shortfall will be determined by the quality of scenario planning and the speed of execution—both are front and center in our full deliverable.
For detailed analysis of this topic, please visit the official page: Worldwide Tuberculosis Therapeutics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide C5 Resin Market to Rise from USD 2,860 Million in 2025 to USD 3,794 Million by 2032 at a 4.12% CAGR
By pmarketresearch, 2026-08-18
Worldwide C5 Resin Market: Strategic Imperatives for 2026 — PW Consulting Preview
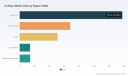
As companies prepare capital allocation, procurement realignment, and product strategy for 2026, PW Consulting publishes an executive preview of our forthcoming Worldwide C5 Resin Market report. Our analysis shows the global C5 resin market—measured on a USD million revenue basis—moving from an estimated USD 2,860 million in the 2025 base year toward roughly USD 3,794 million by 2032, representing a compound annual growth rate (CAGR) of approximately 4.12% across the 2026–2032 forecast window. This trajectory reflects steady, commercially relevant growth driven by adhesive tackifier demand, evolving rubber compounding needs, and paint & coating formulations shifting toward engineered hydrocarbon solutions.
Agriculture Accounting Software Market
Why this report matters to 2026 decision-makers
-
Actionable clarity in a period of structural change: Many procurement and strategy teams enter 2026 confronting regional supply imbalances and regulatory uncertainty. Our report synthesizes supply-side moves, feedstock trends, and trade policy impacts into decision-ready insights for sourcing, inventory policy, and regional footprint planning.
Bone Resorption Inhibitors Market -
Investment screening and M&A prioritization: With a moderately concentrated supplier base at the top and a fragmented second tier, the landscape is ripe for strategic bolt-on acquisitions, joint ventures, or capacity redeployment. We show which asset types and geographies will deliver the most defensive value under three downside scenarios.
Worldwide Supply Chain Cost-To-Serve Analytics Software Market -
Commercial optimization for formulators and converters: For OEMs and adhesives/rubber formulators, the report provides an applied toolkit—tackifier substitution roadmaps, cost-to-performance matrices, and risk-weighted supplier scorecards—that reduce adoption friction and accelerate qualification cycles.
Market dynamics shaping the 2026 agenda
-
Supply rebalancing and regional flow shifts: Recent industry events have accelerated regional imbalances. North American hydrogenated resin line rationalization has pushed the region toward increased dependence on imports, while Asia continues to add new resin-making capacity. These flows are being reshaped by both commercial choices and policy instruments.
-
Trade and tariff noise: Targeted trade measures remain a material influence on global trade patterns. Ongoing Section 301 tariffs and the partial unwinding of broader controls in 2026 have altered flows and created near-term arbitrage opportunities—important for procurement teams evaluating supplier diversification versus localized stocking.
-
Feedstock and cost stability: C5 feedstock availability, derived from naphtha and cracker streams, exhibited relative price stability in late 2025. That calm provides a window for forward procurement contracts and structured hedges, but volatility can re-emerge if cracker utilization or heavy petrochemical maintenance cycles change.
-
Domestic capacity growth in Asia: New lines and brownfield expansions in Asia are recalibrating the global cost curve and delivery lead times. For buyers, the strategic question is whether to lock in long-term supply from incumbent integrated suppliers or shift to emerging producers that are scaling quickly.
-
Product mix and formulation trends: Demand for higher-performance and hydrogenated variants continues within specialty adhesives, pressure-sensitive formulations, and advanced rubber compounds. That trend raises the bar for quality- and specification-driven supply chains and supports premiumization of certain resin grades.
Competitive landscape: players, strategic moves, and implications
-
Eastman Chemical Company (USA) — A well-capitalized supplier with a broad portfolio of aliphatic and hydrogenated C5 resins. Eastman’s integrated position and technical service capability make it a preferred strategic partner for adhesive formulators seeking rapid scale-up and global technical support.
-
Kolon Industries, Inc. (South Korea) — A leading regional producer with deep capabilities in high-purity C5 resins and hydrogenated grades. Kolon’s investments in higher-purity product lines signal an intent to capture specialty pockets where performance and consistency command premium pricing.
-
ExxonMobil Corporation (USA) — A major traditional supplier whose selective shutdowns and portfolio adjustments have immediate market ripple effects. Recent capacity rationalization in hydrogenated lines has contributed to upstream sourcing challenges for North American buyers, underscoring the need for contingency planning.
-
Zeon Corporation & Arakawa Chemical (Japan) — Technology-focused producers that serve high-performance adhesive and elastomer markets; their product breadth supports formulators requiring tight grade control and tailored tackifier performance.
-
Neville Chemical, Cray Valley (TotalEnergies), and a cluster of Chinese producers — These firms complete a competitive tapestry of global incumbents and agile regional suppliers. China-based manufacturers have visible momentum in expanding scale and global reach; this has implications for pricing dynamics and lead-time optimization.
-
Market concentration signals — The market exhibits moderate top-tier concentration, with the three largest producers capturing a meaningful share but leaving substantial room for mid-sized and regional suppliers to compete. This structure increases the value of differentiated service models and localized supply guarantees.
Recent developments that will matter in 2026
-
Regulatory and corporate restructuring in Asia has prompted portfolio reviews among downstream chemical players; consolidation and strategic repositioning in Korea and Japan are affecting regional feedstock allocations and partnering strategies.
-
Targeted capacity expansions and brownfield upgrades by established players are creating differentiated capability clusters—some focused on high-purity specialty resins, others on broad commercial grades—changing the competitive match-up across applications.
-
Significant plant line closures for hydrogenated grades in North America have altered net trade balances, emphasizing the importance of import strategies, tolling arrangements, and safety-stock policies for 2026.
What the PW Consulting report delivers — practical modules
-
Market sizing and validated forecast model (2020–2032) with scenario toggles: our financial model is built in a way that allows executives to stress-test demand elasticity and price pass-through under alternative macro cases.
-
Segment diagnostics and opportunity mapping: deep dive playbooks for resin types (aliphatic, copolymer, hydrogenated) and end-use clusters that identify margin pools, qualification timelines, and go-to-market mechanics.
-
Supplier heatmaps and risk-adjusted sourcing templates: a procurement-ready framework combining lead-time volatility, quality fit, regulatory exposure, and commercial flexibility.
-
Trade-flow and tariff impact analysis: dynamic routing scenarios that quantify shifts in logistics cost and landed price under prevailing trade measures and alternative tariff outcomes.
-
Technical substitution and product migration guides: stepwise plans to migrate formulations between resin grades with minimal requalification cycles and cost disruption.
-
M&A, JV and capex playbooks: acquisition targets, integration checklists, and capex prioritization matrices tailored to buyers and strategic investors active in the hydrocarbon resin ecosystem.
Recommended 2026 strategic actions — five high-impact moves
-
Formalize dual-sourcing for critical grades: prioritize at least one regional and one global supplier to mitigate delivery shocks from unexpected plant outages or policy shifts.
-
Implement a short-duration forward purchasing program tied to cracker utilization indices: take advantage of the current feedstock calm to secure favorable terms without overexposing balance sheets.
-
Prioritize qualification of hydrogenated and high-purity variants for premium end-markets: these grades offer better margin defensibility where performance matters.
-
Reassess inventory strategy in light of trade frictions: shift from pure cost-minimization to resilience-weighted inventory targets for facilities serving multiple plants or markets.
-
Use M&A/JV selectively to obtain quick access to local capacity or downstream channel control—but only against rigorous IRR and integration metrics provided in our acquisition playbook.
How to use the full report
This release is intended as a strategic preview: it articulates the high-level market trajectory, the levers that matter in 2026, and the playbook executives should adopt to protect and grow margin. The full PW Consulting Worldwide C5 Resin Market report contains the granular segment-level data, regional and application splits, supplier scorecards, and downloadable financial models that boards, strategy teams, and procurement leaders will find indispensable when making binding 2026 decisions. We deliberately withhold the detailed subsegment datapoints in this preview to ensure that organizations seeking immediate operational guidance consult the complete dataset and model hosted on our site.
Conclusion
The C5 resin market in 2026 is neither a classic boom narrative nor a stagnant commodity story—it is a slowly expanding, structurally shifting market where the winners will be those that pair technical differentiation with supply-chain resilience. PW Consulting’s report equips executives with the foresight and the operational tools required to convert the coming changes into competitive advantage. For the authoritative dataset, scenario models, and supplier-level playbooks, access the complete Worldwide C5 Resin Market report on PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Worldwide C5 Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Recycled Containerboard Market Valued at USD 146.5 Billion in 2025, Set to Expand at a 4.69% CAGR Through 2032
By pmarketresearch, 2026-08-18
Recycled Containerboard Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Report
PW Consulting today releases a comprehensive market research briefing on the global Recycled Containerboard market, purpose-built to inform the strategic decisions of corporate leadership and investors for 2026. The report synthesizes a multi-year view of supply, demand, policy and feedstock dynamics and translates those into operational playbooks, capital-allocation guidance and near-term scenario options. This press briefing presents the report’s strategic value proposition, high‑level market trajectory and the decision levers that business leaders should prioritize this year. For full segmentation, granular regional and application breakdowns, and proprietary model outputs, please consult the full report.
General Metal Finishing Solutions Market
Market Snapshot: Growth Measured, Transition Underway
Our analysis shows the recycled containerboard market as a large, steadily expanding sector. By our base year (2025) the market reached approximately USD 146.5 Billion and the forecast envelope points to continued expansion at a compound annual growth rate of roughly 4.69% through 2032, taking the market to about USD 201.9 Billion by the end of the forecast period. That trajectory underlines a structural growth theme driven by packaging substitution toward recycled fibre, rising e‑commerce-related packaging volumes, and regulatory pushes toward higher recycled content.
Car Sharing App Market
However, aggregate growth masks two critical realities that will shape 2026 strategy. First, feedstock and manufacturing ecosystems remain cyclical and regionally differentiated: recovered paper availability and pricing volatility can compress margins quickly, and second, regulation and buyer-specification shifts are increasingly decisive for market access and premium positioning. The report marries the macro growth narrative with these operational frictions so decision makers can translate top‑line opportunity into executable near‑term plans.
Precious Metal Evaporation Materials Market
Why the 2026 Planning Cycle Is Different — and What to Do About It
- From volume to value: As recycled containerboard becomes a default choice for many corrugated applications, margin capture increasingly depends on product-performance differentiation (weight, printability, flatness) and supply-security assurances rather than pure tonnage growth. Executive teams should realign commercial incentives and investments to monetize differentiated recycled grades.
- Regulatory inflection points are immediate: Extended Producer Responsibility (EPR) frameworks are moving from proposal to implementation in multiple jurisdictions, with some laws now specifying significant minimum post‑consumer recycled content. This changes procurement math for brand owners and creates new demand signals for manufacturers who can guarantee compliant content and chain-of-custody documentation.
- Feedstock risk is corporate risk: Recovered paper markets showed signs of rebound in early 2026 after a soft patch in late 2025; even modest swings in OCC availability or price transmission materially impact thin‑margin recycled grades. Procurement, hedging and asset flexibility must be hardwired into 2026 plans.
- Operational tightness coexists with selective capacity expansion: Despite near‑term production variability in some regions, many producers are selectively investing in recycled grades and machine rebuilds. Companies must weigh the long lead times and payback profiles of converted or new recycled machines against the competitive benefit of first‑mover capacity in underserved corridors.
What PW Consulting’s Report Delivers — Hands‑On, Actionable Intelligence
Our research is designed to be operational: not an academic forecast but a decision‑support tool. Key deliverables inside the report include:
- Proprietary market sizing and a scenario matrix that links macro demand trajectories to feedstock availability and pricing sensitivities.
- Commercial playbooks for sellers and buyers — pricing architecture, specification migration paths, and supply‑contract templates tailored for recycled fibre supply chains.
- Capital allocation frameworks for mill owners and converters: break‑even mappings, retrofit prioritization, and greenfield vs conversion decision trees with IRR and payback sensitivities under multiple feedstock and price paths.
- An M&A and JV playbook identifying strategic pockets (tech-enabled deinking, local closed‑loop models, high‑brightness recycled liner) and the financial profile of value creation levers that acquirers should target.
- Operational benchmarking and a plant‑level diagnostic toolkit covering yield, fibre loss, water and energy intensity, and quality‑control levers that materially affect paper performance for customers.
- Regulatory readiness tools: a compliance checklist for EPR regimes, product labeling implications, and supplier traceability templates to support procurement teams and sustainability reporting.
Each section is supported by primary interviews with mill operators, converters and major buyers, plant‑level audits and a bottom‑up demand model calibrated to 2020–2025 historicals and 2026–2032 forecast scenarios.
Competitive Landscape: Who’s Competing on What
The recycled containerboard market remains moderately fragmented: global leadership is distributed among vertically integrated pulp and paper majors, regional specialists, and independent recycled-only operators. Competitive advantage today is built on three capabilities — consistent recycled feedstock procurement, product performance engineering (weight, strength, printability), and integrated closed‑loop solutions for large buyers.
- International Paper — A major global participant with established recycled liner and fluting grades in its EMEA footprint; IP’s play emphasizes high‑performance lightweight grades that enable lower board weights without sacrificing performance.
- ND Paper — Focused on reliable strength and print quality for demanding packaging uses; ND’s asset base targets consistency as its primary commercial differentiator.
- Stora Enso — Highlights 100% recycled fibre testliner offerings with a product strategy around structural performance, flatness and low grammage for e‑commerce and industrial packaging customers.
- Cascades — Emphasizes a full recycled lineup across white and brown grades, pursuing both sustainability claims and surface quality improvement to capture premium applications.
- DS Smith — Positions high‑brightness 100% recycled white liners for FMCG and food applications where printability and visual appeal command price premiums.
- Kruger, New Indy, Pratt and others — Each occupies regional niches or scale positions: Kruger and New Indy have early mover recycled histories in North America; Pratt emphasizes closed‑loop systems; independent suppliers often lead on cost and customized services for localized demand.
- Mondi — Recently brought new recycled‑focused capacity online in Italy; the company’s approach illustrates how targeted capital projects can quickly alter regional supply balances for high‑quality recycled testliner and fluting.
Our competitive analysis goes beyond company positioning to evaluate capital intensity, technology adoption (deinking, refining, optimization), customer mix, and contractual exposure to feedstock and finished‑goods volatility. That analysis provides an M&A and partnership heat map for 2026 priorities.
Recent Industry Signals to Watch in 2026
- Several producers have brought recycled-dedicated machines and upgrades into production in the past 18 months, signaling continued industrial commitment to 100% recovered fibre offerings in priority regions.
- Procurement teams are reacting to recovered paper market dynamics: early 2026 saw a modest rebound in recovered paper availability and regional price stabilization after late‑2025 softness. Procurement strategies should incorporate shorter contract cycles and optionality clauses for feedstock supply.
- Regulatory change is accelerating buyer requirements. New EPR schemes and state‑level mandates are driving brand owners to demand verifiable recycled content and chain‑of‑custody documentation from suppliers; some jurisdictions have set explicit post‑consumer recycled content thresholds that will alter procurement specifications.
- Production metrics in some markets reflect a 2025 year‑on‑year reduction in output even as operating rates stayed high; this underlines the role of maintenance cycles and feedstock shortages in near‑term availability.
Practical Strategic Choices for 2026
Executives should treat 2026 as a year for tactical repositioning and capability building rather than only capacity race expansion. Key actions we recommend:
- Implement a three‑tier procurement strategy: secure core feedstock through anchor contracts, maintain a flexible spot overlay to capture opportunistic supply, and invest in or partner on local collection and sorting where economics permit.
- Prioritize product R&D on surface quality and weight efficiency to expand addressable applications and defend margins against commodity downward pressure.
- Stress‑test capital projects against three feedstock and price scenarios and incorporate regulatory compliance timelines into capex phasing to avoid stranded asset risk.
- Use the report’s M&A heat map to identify bolt‑on acquisitions that deliver either geographic feedstock security or product diversification (e.g., white‑top recycled liners or high‑brightness solutions for food packaging).
- Operationalize EPR readiness: upgrade labelling, chain‑of‑custody systems and customer reporting to convert regulatory compliance into a commercial differentiator.
Conclusion — The Strategic Edge in 2026
The recycled containerboard market is no longer a back‑office sustainability narrative; it is a core commercial battleground with clear profit pools for firms that can integrate feedstock security, product performance and regulatory compliance. PW Consulting’s report equips executive teams with the scenario analysis, operational templates and competitive intelligence required to make defensible 2026 decisions — from procurement and plant investments to M&A and customer contracts.
This briefing is a preview designed to show the depth of analysis and practical outputs the full report contains. To access detailed regional and application segmentation, proprietary pricing and margin models, and the complete suite of implementation tools referenced here, please visit PW Consulting’s report page and download the full Recycled Containerboard Market study.
For detailed analysis of this topic, please visit the official page: Recycled Containerboard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Industrial Press Machine Market to Expand at a 5.18% CAGR Through 2032
By pmarketresearch, 2026-08-18
PW Consulting: Strategic Brief — Worldwide Industrial Press Machine Market (2026 Outlook)
PW Consulting today publishes a strategic briefing drawn from our new Worldwide Industrial Press Machine Market report — a practitioner-focused intelligence asset designed to shape capital allocation, product strategy, and M&A decisions through 2026 and beyond. Using 2025 as the analytical base year, our global market system is tracked in USD (Million) with a projected compound annual growth rate (CAGR) of 5.18% across the forecast horizon. The market expanded meaningfully through 2020–2025 and, under our central scenario, progresses toward a materially larger installed base and serviceable market by 2032.
Corporate Travel Booking Platforms Market
Why this matters for 2026 corporate strategy
-
Timing capital: With moderate, steady growth and pockets of accelerated investment, 2026 is a year where the sequencing of capital projects — greenfield presses versus retrofit and automation programs — will determine total cost of ownership and payback periods.
Electric Train Battery Market -
Input-cost sensitivity: Steel-market dynamics and trade policy introduced higher near-term uncertainty in 2025. Organizations that proactively hedge raw-material exposure and redesign supply chains to reduce steel-intensive content will protect margins.
Worldwide Electro-optical Converters Market -
Technology pivot points: The migration to servo-driven systems and integrated automation is no longer niche; it is reshaping buyer selection criteria around precision, energy efficiency, and digital integration.
-
Aftermarket economics: Service, spare parts, and retrofit revenues are becoming essential to sustaining margins as equipment lifecycles lengthen and customers seek guaranteed uptime under tighter production schedules.
What PW Consulting’s report delivers
-
Robust market sizing and forward-looking scenario analysis, calibrated to market events through the 2025 base year and projecting to 2032 with multiple demand scenarios and sensitivity cases tied to raw-material and trade-policy assumptions.
-
Practical go-to-market playbooks for OEMs and component suppliers — from product positioning and pricing levers to channel design, local-assembly thresholds, and retrofit service bundling.
-
Procurement and supply-chain stress tests, including break-even analyses for vertical integration versus global sourcing, and supplier concentration mapping to identify single points of failure.
-
Competitive benchmarking with vendor scorecards across engineering capability, automation integration, aftermarket footprint, and balance-sheet resilience.
-
A curated M&A pipeline and diligence checklist highlighting acquisition targets likely to accelerate access to key end-markets, digital capability, or regional manufacturing scale.
-
Operational playbooks for manufacturers and end-users — CAPEX prioritization grids, retrofit vs. replace matrices, and pilot-to-scale templates for automation deployment.
Competitive landscape: who matters and why
The market remains moderately fragmented, with concentration metrics indicating space for scale plays: the top three firms capture a meaningful but not overwhelming share, and the top five firms broaden that concentration band further. This structure creates both opportunity for consolidation and room for specialized players to defend niches.
-
Schuler Group (Göppingen, Germany) — A broad-spectrum supplier of mechanical, hydraulic, and servo presses. Schuler’s global service footprint and deep OEM relationships in high-volume stamping make it a reference player for full-line systems and turnkey lines.
-
AIDA Engineering (Japan) — High-precision mechanical and servo presses oriented to high-speed stamping. AIDA’s engineering reputation positions it well where cycle time and die-life economics dominate procurement choices.
-
Amada (Japan) — Known for sheet-metal forming equipment and automation, Amada’s product breadth in punching and bending complements press makers who need to offer integrated cell solutions to contract manufacturers.
-
Komatsu Press (Japan) — Strong in heavy industrial stamping and automation-enabled solutions; Komatsu’s integration of presses with higher-tier material handling continues to win large-scale industrial projects.
-
Beckwood Press Company (St. Louis, USA) — Specialist in custom-engineered hydraulic and servo-electric presses. Beckwood is attractive for OEMs needing bespoke capabilities for composites, molding, or specialty forming.
-
Pacific Press Technologies (USA) — Focused on North American metal forming needs with a reputation for reliable hydraulic and straight-side presses and a strong OEM-aftermarket channel.
-
Macrodyne Press (North America) — Heavy-duty hydraulic presses for deep draw and hydroforming; the firm is strategically positioned for large-scale vehicle and industrial applications where scale and force are differentiators.
-
French Oil Mill Machinery Co. (USA) — Longstanding heritage in custom hydraulic presses, particularly in compression molding and rubber applications; an example of how specialized product competence sustains market niches.
-
Ermaksan (Turkey) — Offers CNC hydraulic and servo turret punch presses; presents an alternative for cost-conscious regional buyers seeking modern control systems.
-
Fagor Arrasate (Spain) — Supplies mechanical and hydraulic presses and full stamping lines; notable for turnkey solutions in automotive and appliance segments.
-
Sutherland Presses & Stamtec (USA) — Both bring manufacturing locality and trusted U.S.-made quality, appealing to buyers prioritizing short lead times and domestic support.
Supply-chain and input-cost dynamics shaping decisions in 2026
Two critical, observable forces are shaping supplier economics and pricing strategies heading into 2026. First, raw-material dynamics: steel prices stabilized in the low–mid ranges in mid-2025 and remain a key driver of frame and component costs. Second, trade policy changes — most notably elevated U.S. steel tariffs implemented in 2025 — have created a bifurcated sourcing environment where domestic producers gain pricing support but import-dependent players face higher input costs. Coupled with structural overcapacity in global steel markets, these dynamics argue for differentiated procurement playbooks: tactical hedges for near-term volatility and strategic reconfiguration of BOMs and subassembly sourcing for medium-term resilience.
Technology & product trends that will re-write competitive scorecards
-
Servo and hybrid presses: Adoption is being driven by buyers demanding tighter tolerances, lower energy intensity, and better integration with digital controls. These systems are increasingly the default for precision stamping and higher mix–lower volume production profiles.
-
Automation and Industry 4.0 integration: Press lines are being sold as node-enabled assets — remote diagnostics, predictive maintenance, and line-level optimization are table stakes for premium OEMs and leasing offerings.
-
Modularity and retrofitability: Product families that allow incremental capability upgrades (controls, drives, safety) dramatically improve customer ROI and create recurring aftermarket monetization opportunities.
Actionable takeaways for executives planning 2026
-
Recalibrate CAPEX: Prioritize mixed investments — small pilot projects in servo and automation plus targeted replacement of legacy assets that create bottlenecks.
-
Design supplier risk playbooks: Implement dual-sourcing strategies for critical steel components and evaluate nearshoring of final assembly where tariffs and lead time exposures are material.
-
Monetize installed base: Build service tiers (SLA-backed uptime, condition-based maintenance) to convert fixed-cost installed assets into recurring-revenue streams.
-
Segment go-to-market by capability: Use differentiated sales motions for high-volume automotive stamping versus precision electronics forming; standardize offerings where possible and modularize where necessary.
-
Accelerate partnerships with automation integrators and controls suppliers to shorten time-to-value for buyers and create bundled greenfield and retrofit propositions.
-
Evaluate M&A for capability gaps: Target acquisitions that immediately add digital controls, regional service networks, or material-handling expertise to close visible gaps in competitive scorecards.
Recent market activity and signals
Industry events and product showings continue to validate the market momentum and technology transition. For example, machine builders participated in major manufacturing exhibitions in early 2026 to showcase new forming and press-line integrations — a reminder that OEMs are actively pursuing visibility and order pipelines as end-users refresh assets.
Why PW Consulting’s report is the decision tool for 2026
Our report combines transparent, auditable methodology with practitioner tools: demand-model Excel workbooks, vendor scorecards, stress-test scenarios, and a prioritized action checklist. We balance high-level foresight (macro demand and trade impacts) with hands-on levers (procurement negotiation scripts, retrofit ROI calculators, and go-to-market templates) so that executives do more than understand the market — they act on it.
This briefing intentionally highlights strategic themes and decision-relevant insight while reserving the granular segment tables, regional breakdowns, and line-item supplier economics for the full report and accompanying datasets. Industry leaders and buyers who require the detailed segmentation, downloadable models, and vendor-level financials will find those deliverables in the full PW Consulting publication and Excel annex.
For executives preparing 2026 plans, the choice is straightforward: rely on high-level intuition, or use a field-tested, data-driven playbook that aligns capital, capability, and go-to-market efforts against the real levers that move margin and market share. PW Consulting’s Worldwide Industrial Press Machine Market report delivers the latter.
Contact and access
PW Consulting’s market research and advisory teams are available to present bespoke briefings, workshop CAPEX scenarios, or support vendor diligence. Access to the full report, annex data files, and proprietary models is available through PW Consulting’s publication channels.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Press Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com