
Blogs
PW Consulting: Worldwide Rodder Machine Market to Expand at a 5.01% CAGR During 2026–2032 Forecast
By pmarketresearch, 2026-08-18
Worldwide Rodder Machine Market 2026: Strategic Preview for Decision‑Makers
Executive snapshot — from PW Consulting
PW Consulting’s latest market research, the Worldwide Rodder Machine Market Report (base year 2025, forecast 2026–2032), is designed as a strategic playbook for executives, procurement officers, product leaders, and investors who must make confident, near‑term decisions under accelerating infrastructure and regulatory pressures. The market has shown steady expansion from USD 345.5 million in 2020 to USD 432.5 million in 2025 and is projected to continue climbing — reaching approximately USD 448.2 million in 2026 and approaching USD 608.5 million by 2032. Our forecast period CAGR is 5.01% (2026–2032), a tempo that rewards disciplined positioning and targeted investments.
Bispecific Antibody Development Platform Market
Why this report matters for 2026 decisions
-
Procurement optimization — Municipalities and utilities facing tighter budgets must reconcile regulatory inspection cycles with total cost of ownership (TCO) and lifecycle maintenance. Our research translates market growth and procurement trends into buying triggers and timing recommendations that reduce cycle time and financial risk.
Worldwide Heavy Duty Truck Seat Market -
Product strategy — Manufacturers and OEMs evaluating electrification, modular designs, or hybrid rodding platforms need to match R&D priorities with adoption curves and procurement specifications. The report maps those inflection points to practical product roadmaps.
Worldwide Speed Gate Market -
M&A and partnership screening — With a moderately concentrated vendor landscape, granular competitive intelligence and scenario modeling in the report help acquirers and strategic partners prioritize targets and integration pathways.
-
Supply‑chain and raw material risk management — Steel and aluminum price volatility are not abstract threats; they materially affect margins and quoting consistency. We provide hedging and sourcing playbooks tuned to different business models (OEM, contract manufacturer, rental fleet).
Market dynamics: actionable insights
-
Infrastructure and regulatory demand anchors growth. Mandated inspection and cleaning cycles — notably in North America and the EU — continue to underwrite recurring procurement for municipal and utility fleets. These regulatory drivers create a predictable replacement and fleet‑expansion cadence that can be monetized through consumables, maintenance contracts, and retrofit programs.
-
Electrification and non‑invasive solutions are moving from novelty to procurement line items. The commercial introduction and promotion of battery‑electric continuous rodders have opened a second wave of substitution away from diesel‑powered units in applications where noise, emissions, and operational footprint matter.
-
Raw material cost exposure is a lever and a constraint. Frame and cable metallurgy represents a material portion of BOM cost; volatility in steel and aluminum markets translates into price sensitivity at the OEM and contractor levels. Effective 2026 sourcing strategies will combine forward contracts, alternate materials analysis, and local supplier diversification.
-
Service‑led revenue models are emerging as a margin stabilizer. Rental fleets, maintenance contracts, and outcome‑based service agreements (e.g., guaranteed throughput or downtime SLAs) can offset cyclical equipment sales and capture aftermarket economics.
-
Market concentration is meaningful but not prohibitive. A small number of established vendors account for a significant share of supplier revenue, creating a competitive environment where regional specialists and niche innovators can still carve defensible positions.
Competitive landscape — who matters and why
The competitive field blends long‑established North American OEMs, specialist manufacturers, and international volume producers. PW Consulting’s vendor analysis focuses on capability vectors that matter for 2026: product breadth (continuous vs sectional rodders), power architecture (diesel, electric, battery), service network, and aftermarket ecosystem.
-
RIDGID (Emerson) — Elyria, Ohio ( https://www.ridgid.com): RIDGID’s legacy in mainline solutions and robust sectional systems positions it as a go‑to for municipal and heavy institutional customers. Strengths: product robustness, tool kit breadth, and established service channels. Strategic implication: incumbency advantage for large‑scale bids, but incremental opportunity exists for RIDGID to accelerate digital services and battery options.
-
TSE International (OK Champion) — USA ( https://tse-international.com): TSE’s continued investment in the S660E battery‑electric continuous rodder marks a pivotal technology shift that buyers are beginning to consider as a direct alternative to larger vacuum fleets in sensitive urban operations. Strengths: battery drive systems, high production capacity, and a strong value proposition for emission‑constrained environments. Strategic implication: suppliers and fleet managers should model TCO and operational impact of battery units within 12–36 month procurement cycles.
-
General Pipe Cleaners (General Wire Spring Company) — McKees Rocks, Pennsylvania ( https://drainbrain.com): With sectional Rodrunner machines and proven two‑way operation for professional and municipal use, General Pipe Cleaners remains a performance leader for tough clogs and long runs. Strengths: product focus on performance and durability. Strategic implication: attractive target for rental fleet specialists seeking reliable, high‑utilization platforms.
-
Electric Eel Manufacturing Company — Springfield, Ohio ( https://www.electriceel.com): A longstanding drum and continuous machine manufacturer, Electric Eel’s emphasis on product range and rental/professional markets makes it a cornerstone supplier for service companies. Strengths: deep OEM heritage, broad product line. Strategic implication: an ideal partner for businesses layering telematics and predictive maintenance on existing fleets.
-
Sewer Equipment Co. of America — USA ( https://sewerequipment.com): Focused on water‑conserving mechanical rodding solutions, Sewer Equipment addresses utilities where water use and environmental impact are procurement constraints. Strategic implication: niche differentiation through sustainability‑focused features can win municipal RFPs.
-
Spartan Tool LLC — USA: Spartan remains a practical option for contractors and municipalities seeking reliable rodding and drain cleaning equipment. Strategic implication: strong distribution partnerships and rental house relationships are key competitive levers.
-
Hebei Sinta FRP Co., Ltd — China ( https://www.sintaductrodder.com): Specializing in fiberglass duct rodders and cable pullers, Hebei Sinta brings lower‑cost alternatives and accessory integration to global cable‑laying and pipeline cleaning deployments. Strategic implication: international buyers should balance initial capex savings with logistics, certification, and aftermarket readiness.
Recent market signals to watch in 2026
-
Public procurement continues to shape fleet composition — a recent municipal bid for a truck‑mounted jet rodder underscores ongoing investment in capacity for storm and sanitary infrastructure (public bid, March 2026).
-
Electrified rodding platforms are moving from announcement to field availability — OEMs are actively promoting battery‑electric models as quiet, emission‑free alternatives (product launch and promotion activities in 2025–2026).
-
Raw material attention remains high across design and procurement planning cycles; teams should model material price scenarios in their 2026 budgets.
What the PW Consulting report delivers (practical content)
We built this report as a toolkit for executives who must act in 2026. Key deliverables include:
-
Macro market sizing and seven‑year forecast (2026–2032) with scenario overlays and sensitivity to raw material and regulatory shocks.
-
Buyer persona segmentation and procurement playbooks for municipalities, utilities, rental houses, and telecom integrators.
-
Product benchmarking and capability matrices that compare continuous vs sectional platforms, propulsion options, and maintenance footprints.
-
Supply‑chain stress tests and sourcing playbooks that quantify exposure to steel and aluminum pricing and propose mitigation levers.
-
Vendor scorecards and M&A screening templates focused on integration risk, aftermarket potential, and cross‑sell opportunities.
-
Operational tools — TCO calculators, maintenance scheduling templates, and procurement specification language ready for RFP inclusion.
-
Case studies and procurement timelines designed to compress evaluation cycles and reduce fleet disruption during unit rollouts.
Strategic recommendations for 2026 (high‑impact, low‑latency)
-
For OEMs: Prioritize modular electrification. Develop hybrid architectures that retrofit existing frames to accept battery packs and telematics modules to capture early adopters while protecting legacy revenue.
-
For fleet operators: Pilot battery‑electric continuous rodders in high‑sensitivity districts with defined emissions or noise constraints. Use short‑term rental or lease pilots to validate TCO before large capital purchases.
-
For procurement teams: Embed lifecycle cost and service availability clauses into RFPs; require performance data under local operating conditions rather than relying solely on vendor claims.
-
For private equity and strategics: Use the report’s M&A screen to identify targets that complement incumbent service networks or provide technology adjacency (telematics, battery integration, specialized tooling).
-
For supply‑chain leaders: Lock in strategic allotments of critical metals, qualify secondary suppliers for key subassemblies, and evaluate near‑shoring options for high‑value components.
How to use this preview — next steps
This article is a deliberately calibrated preview: it highlights structural growth, vendor dynamics, and strategic playbooks while withholding detailed segment allocations and granular regional splits to preserve the full operational intelligence available in the full report. If your 2026 capital planning, R&D roadmap, or M&A pipeline depends on a precise, executable view of the rodder machine market, PW Consulting’s full report provides the complete dataset, vendor scorecards, and ready‑to‑deploy templates.
Contact PW Consulting to access the full Worldwide Rodder Machine Market Report and schedule a tailored briefing with our senior industry analysts. We will walk your team through customized scenarios, procurement contract language, and an implementation checklist to convert insight into measurable outcomes within 90 days.
About the author
Prepared by PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst — our practice combines field‑tested infrastructure procurement experience with rigorous market analytics to help clients convert market momentum into defensible growth and sustainable operations.
For detailed analysis of this topic, please visit the official page: Worldwide Rodder Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide NTP & PTP Time Servers Market Poised for 8.12% CAGR Through 2026–2032
By pmarketresearch, 2026-08-18
PW Consulting: Strategic Brief — Worldwide NTP & PTP Time Servers Market Outlook (2026 Strategic Preview)
Executive summary
As enterprises prepare their 2026 technology roadmaps, precise timekeeping is moving from a niche infrastructure concern to an operational imperative. PW Consulting’s new Worldwide NTP & PTP Time Servers Market report synthesizes five years of historical tracking (2020–2025) with a rigorous forecast through 2032, delivering decision-grade insight for CIOs, CTOs, network architects, and procurement leads. The market has expanded from roughly USD 425 million in 2020 to an estimated USD 642.5 million in 2025, and our modeling projects continued acceleration — reaching approximately USD 1,109.7 million by 2032 driven by an 8.12% CAGR across the forecast horizon. This growth is underpinned by regulatory tightening, the migration of real-time workloads to edge and cloud fabrics, and advances in PTP (IEEE 1588) implementations and GNSS-anchored timing resilience.
Worldwide Data and Analytics Service Market
Why this matters for 2026 planning
- Strategic timing is now a differentiator: Accurate and auditable timestamps are mandatory for regulatory compliance in financial markets, essential for 5G and telco service-level guarantees, and increasingly critical for distributed cloud-native applications and real-time industrial control.
- Procurement must balance accuracy, resilience and cybersecurity: Buyers need to evaluate products not only on sub-microsecond accuracy but also on GNSS holdover performance, oscillator technology, hardware timestamping, and integration with Zero Trust security models.
- Operational visibility trumps vendor feature lists: Operators need playbooks for deployment, monitoring and incident handling when GNSS is disrupted — the report includes practical checklists and failure-mode mitigation patterns that materially reduce operational risk.
Market trajectory and what the numbers reveal
The market’s compound annual growth trajectory (8.12% CAGR through 2026–2032) reflects sustained demand across multiple verticals. Our longitudinal series shows a steady climb from the mid-400s (USD million) in the early 2020s to the mid-600s by 2025, with an inflection as PTP adoption and telco modernization programmes accelerate. For 2026 specifically, the market is poised to break through new thresholds as hyperscale data center operators, telecom providers rolling out profile-compliant PTP, and regulated financial institutions refresh on-premises timing infrastructure.
Worldwide Oil & Gas Processing Seals Market
Core dynamics shaping vendor strategy
- PTP adoption and the NTP transition: A major structural shift is underway: applications that once tolerated millisecond-class NTP are migrating to sub-microsecond and nanosecond-class PTP solutions. This transition creates demand not only for PTP grandmasters and hardware timestamping but also for hybrid NTP/PTP architectures that enable phased migration.
- GNSS dependency and holdover engineering: GNSS remains the predominant primary reference, but engineering emphasis has shifted to oscillator-based holdover (OCXO, Rubidium, Cesium) and multi-constellation resilience strategies to maintain service integrity during signal outages.
- Security and zero trust: Time servers are now part of the attack surface. Vendors embedding cryptographic protections, hardware security modules, and compliance with enterprise Zero Trust standards will outcompete legacy offerings in procurement cycles.
- Service alternatives and platformization: Precision Time as a Service offerings from major colocation and cloud players are reshaping buy vs. build decisions. Buyers must weigh the operational simplicity of managed PTP/NTP services against sovereignty, latency determinism and auditability of on-premise appliances.
Report deliverables — what’s inside (practical, decision-ready)
PW Consulting’s report is structured around actionable modules that translate market data into procurement and deployment actions. Highlights include:
Worldwide Tampography Inks Market
- Transparent market-sizing methodology and reconciled historical series (2020–2025) with scenario-based forecasting through 2032.
- Technology deep-dives: comparative analysis of PTP profiles, hardware timestamping implementations, GNSS integrations, and oscillator holdover engineering.
- Regulatory and standards mapping: how financial regulations, telecom specifications, and critical-infrastructure requirements affect timing tolerances and procurement criteria.
- Vendor benchmarking and feature-mapping: an objective scorecard focused on accuracy, resilience, security, manageability and total cost of ownership.
- Deployment playbooks: risk registers, monitoring KPIs, incident runbooks for GNSS loss, and sample procurement RFIs tailored to enterprise and service-provider needs.
- Investment and ROI models: multi-year total-cost scenarios for appliance purchases vs. managed services, including sensitivity to oscillator type and failure rates.
Competitive landscape: who matters and why
The time-servers market is moderately consolidated, with our concentration metrics indicating that the top vendors hold a substantial portion of industry revenue — an important signal for buyers seeking longevity and support stability. The competitive field brings a mix of specialist manufacturers, semiconductor-enabled platform vendors, and systems integrators. Key positioning observations:
- Meinberg (Bad Pyrmont, Germany): A long-standing specialist whose LANTIME and microSync lines emphasize hardware timestamping and oscillator options across industrial, broadcast and data center use cases. Recent product introductions signal a focus on energy efficiency and trading-grade timestamp fidelity.
- Microchip Technology (Chandler, AZ): Combines semiconductor-level timing expertise with enterprise-class appliances that align to Zero Trust architectures — attractive for large networks demanding integrated security and scale.
- Safran — Navigation & Timing (formerly Orolia/Spectracom): Targets the high-end of the market with sub-nanosecond-capable devices and resilience features suitable for telecom, finance and defense applications.
- Oscilloquartz (ADVA): Focused on telco and mobile infrastructure operators with compact grandmasters and profile-compliant PTP implementations that ease integration into existing timing fabrics.
- EndRun Technologies, Brandywine Communications, Masterclock and specialist OEMs: Provide focused offerings for enterprise, broadcast, transportation and government sectors — their product breadth supports bespoke solutions where domain-specific certifications and integrations matter.
- Regional and emerging players: A number of localized vendors and integrators cater to government and critical-infrastructure procurements; these players can be attractive for missions requiring local support, certification and price-competitive alternatives.
Recent industry moves you should factor into 2026 decisions
- Product innovation continues: established vendors introduced next-gen PTP grandmasters and compact GNSS‑synchronized appliances with improved power efficiency and dual-port PTP capability, tightening the performance gap between high-end and mid-market devices.
- Regulatory pressure remains material: timestamp accuracy requirements from financial regulators and auditing frameworks are driving adoption of PTP or enhanced NTP in trading and compliance-sensitive environments.
- Colocation and cloud providers are offering precision time services that change the calculus for distributed enterprises, especially those balancing latency-sensitive physics against operational overhead.
Practical recommendations for technology and procurement leaders
- Adopt a phased migration strategy to PTP where mission-critical workloads require sub-microsecond fidelity; retain hybrid NTP/PTP architectures to preserve legacy integrations.
- Specify holdover performance in procurement documentation; OCXO vs. Rubidium choices materially affect incident recovery and TCO under GNSS outage scenarios.
- Embed security requirements into RFPs: mandate signed time sources, authenticated NTP/PTP, and integration with enterprise identity and key management systems.
- Model managed services as an overlay, not a replacement, for core sovereign functions — use colocation PTP as a scalability lever while retaining auditable on-premise references for compliance.
Conclusion — the strategic imperative
Accurate, resilient and secure time distribution has moved from a technical utility to a strategic enabler. With the market on a steady growth path and the 2026 planning cycle underway, organizations that treat timing as a first-class architectural decision — combining resilient hardware, rigorous procurement criteria and operational runbooks — will reduce compliance risk, improve performance for latency-sensitive workloads and gain an operational advantage in distributed systems.
Next steps
PW Consulting’s full report contains the complete dataset, vendor scorecards, deployment templates, and the proprietary scenario models that underpin our forecast. For procurement teams, network architects, and executive sponsors preparing 2026 budgets, the report provides the evidence-based guidance needed to prioritize investments and select suppliers. Visit the PW Consulting website to access the full report and supporting materials.
For detailed analysis of this topic, please visit the official page: Worldwide NTP & PTP Time Servers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Metal Fiber Filter Cartridge Market Poised to Climb from USD 426.08 Million in 2025 to USD 677.16 Million by 2032 at a 6.84% CAGR — Asia Pacific Leads with USD 180.79 Million
By pmarketresearch, 2026-08-18
Worldwide Metal Fiber Filter Cartridge Market — Strategic Briefing for 2026 Decisions
PW Consulting’s new market study on the Worldwide Metal Fiber Filter Cartridge Market offers a focused, decision-ready intelligence package for executive teams planning capital allocation, product development, supply-chain hedging, and go-to-market moves in 2026. Built on a 2020–2025 historical base and forward-looking modeling through 2032, the study quantifies the market’s trajectory (USD 426.08 Million in 2025, rising from USD 312.45 Million in 2020) and projects expansion to approximately USD 677.16 Million by 2032 at a compound annual growth rate (CAGR) of 6.84%. For strategy teams facing constrained budgets and competitive disruption, this briefing extracts the implications that matter most for actionable planning while reserving granular segmentation tables for subscribers to the full report.
Worldwide HPV DNA Test Market
Why metal fiber cartridges now sit at the center of industrial filtration strategy
-
Material and process advantage: Sintered metal fiber cartridges deliver a unique combination of high permeability, high dirt-holding capacity, and thermal/corrosion robustness that makes them the preferred choice where ceramic, polymeric, or mesh filters reach performance limits—particularly in high-temperature and chemically aggressive services.
Worldwide Ceftiofur Sodium Market -
Regulatory and quality drivers: Increasingly strict process purity and particulate control requirements—especially in chemical processing, high-purity polymer filtration, and critical energy assets—raise the technical bar for filtration media. Market-leading porous metal fiber media can meet precise absolute micron ratings and high dirt-holding thresholds required by these applications.
Adaptable Accelerator Cards Market -
Circular-economy tailwind: Sintered metal fiber solutions support full recyclability and enable in-situ cleaning (backflush/backpulse), extending service life and lowering life-cycle emissions—an operational and ESG advantage that procurement and plant managers are beginning to prioritize in vendor selection and capex approval processes.
What the PW Consulting report delivers to a 2026 decision-maker
-
Proprietary market model: A capacitated forecast from 2026–2032 with scenario variants covering base, accelerated-adoption, and downside raw-material-pressure cases. The model is available in editable format to stress-test internal investment cases.
-
Commercial playbooks: Go-to-market templates for OEMs, filter houses, and aftermarket specialists that map route-to-revenue across direct OEM supply, spec-based approvals, and service-driven aftermarket models.
-
Technology & product roadmap: Comparative analysis of media types (stainless steel fiber, nickel and specialty alloys, sintered mesh variants), performance trade-offs, and near-term development priorities—scored by filtration efficiency, durability, cleanability, and manufacturing complexity.
-
Supply-chain and cost sensitivity analysis: Raw-material scenario sweeps, supplier concentration mapping, and procurement hedging playbooks that convert metal-price volatility into actionable sourcing decisions.
-
Vendor scorecards and M&A heatmap: Confidential benchmarking of incumbent suppliers, capability gaps, and acquisition targets aligned to three strategic themes—technology differentiation, geographic coverage, and aftermarket presence.
-
Case studies and ROI tools: Real-world examples across petrochemical, power, pharmaceutical, and aerospace use cases plus embedded ROI calculators for CAPEX vs. operating-cost trade-offs, cleaning interval optimization, and total cost of ownership (TCO) comparisons.
Market dynamics and near-term headwinds to factor into 2026 plans
-
Price volatility in feedstock: Stainless steel—the primary raw material for the bulk of metal fiber cartridges—experienced notable volatility in 2025 (a measurable decline over the year with a pronounced intra-year swing). Meanwhile, high-performance alloys (nickel, titanium, Hastelloy) have retained firmer pricing due to constrained upstream dynamics. Implication: margin compression risk for standard stainless-steel felt products and a cost-rationalization opportunity for suppliers of alloyed media.
-
Service-life economics: The ability to clean and reuse sintered fiber cartridges changes procurement dynamics from “buy-and-replace” to “buy-and-service.” Firms that can operationalize cleaning regimes and aftermarket service contracts capture outsized lifetime value.
-
Regulatory and specification tightening: High-purity and absolute micron requirements increasingly favor certified porous metal fiber solutions. Compliance readiness (certifications, test data, validated cleaning procedures) is becoming a procurement precondition for major industrial buyers.
-
Concentration and competitive intensity: The supplier landscape shows a set of established global players alongside agile regional manufacturers. This structure supports competitive differentiation through quality, certification, service, and aftersales rather than purely on price.
Competitive landscape — strategic positions of principal players
-
Bekaert (Belgium) — A pioneer in metal fiber media with well-developed sintered stainless-steel fiber nonwoven products. Strengths: institutional reputation, high-permeability media (Bekipor®), and deep process-application expertise. Strategic implication: Bekaert is positioned to capitalize on large industrial projects and to lead in sustainability messaging around recyclability and in-situ cleaning.
-
Mott Corporation (United States) — Known for cleanable sintered fiber and porous metal cartridge filters for high-temperature, corrosive applications. Strengths include material science depth and cleanable cartridge platforms. Strategic implication: Mott is a natural partner for buyers prioritizing long-life assets and operational uptime.
-
Pall Corporation (United States) — Offers porous metal fiber media and pleated sintered metal elements for high-purity and polymer filtration. Strengths: strong brand in high-spec filtration and certified micron performance. Strategic implication: Pall will continue to defend premium segments where certification and traceability matter most.
-
Porvair Filtration Group (United Kingdom) — Focused on sintered metal fibre media and cleanable cartridges with low pressure drop and high dirt-holding capacity. Strengths: niche engineering focus and aftermarket services. Strategic implication: Porvair can win through service-led differentiation and retrofit solutions.
-
GKN Powder Metallurgy (Germany) — Innovator in metallic membrane cartridge filters (recent product launch in mid-2025). Strengths: R&D-led product introductions and supply-chain scale in powder metallurgy. Strategic implication: GKN’s metallic membrane launch accelerates fine-filtration competitiveness and pressures incumbents to upgrade product portfolios.
-
China-based manufacturers (Filson, Brother Filtration, Saifilter, Hebei Sinft) — Offer competitive cost structures and growing technical capability in sintered fiber felts and cartridges. Strategic implication: expect continued pressure on commodity stainless-steel cartridge pricing; premium differentiation will hinge on certification, reliability data, and service guarantees.
Recent signals that should influence near-term playbooks
-
Product innovation: GKN’s mid-2025 introduction of metallic membrane cartridge filters underlines an industry push toward finer filtration at competitive pressure points—an important signal for R&D prioritization and partnership scouting.
-
Raw-material trends: The interplay between stainless-steel price swings and stable high-alloy pricing prescribes a segmented supply strategy—lock-in for commodity stainless, selective spot-buy or long-term contracts for alloyed inputs.
-
Operationalization of circularity: Suppliers that can demonstrate validated cleaning protocols and a closed-loop supply approach will increasingly outrank competitors on total-cost and ESG criteria.
Actionable strategic moves for 2026
-
Prioritize aftermarket economics: Build or acquire cleaning and remanufacturing capacity. A service-led model improves margins and creates stickiness with large industrial accounts seeking predictable uptime.
-
Implement a dual-source procurement strategy: Hedge commodity stainless exposure with a combination of long-term contracts and tactical spot allocation; for specialty alloys, pursue strategic partnerships to secure supply and predictable pricing.
-
Invest selectively in fine-filtration R&D: Allocate R&D to metallic membrane and sintered composite structures that reduce pressure drop while improving filtration efficiency—areas where premium pricing is defendable.
-
Align sales to specification gates: Embed certification and test-data deliverables into commercial proposals targeting regulated industries (pharma, specialty chemicals, high-purity polymers).
-
Scan for bolt-on acquisitions: Look for regional filter houses with strong aftermarket footprints or niche alloy-processing capabilities to accelerate capability expansion without long lead-time organic builds.
-
Quantify TCO in procurement decisions: Replace headline unit-price comparisons with life-cycle cost models that capture cleaning cycles, downtime risk, and disposal/recycling value.
Conclusion — where the value is for 2026
Metal fiber filter cartridges are moving from a niche, performance-first category into a mainstream element of industrial filtration strategies—driven by lifecycle economics, regulatory rigor, and product innovation. With the market expanding from roughly USD 312 Million in 2020 to USD 426 Million in 2025 and an expected climb to about USD 677 Million by 2032 at a 6.84% CAGR, 2026 is a pivot year for executives who must decide where to invest in R&D, supply security, and aftermarket services.
PW Consulting’s full report equips leadership teams with the models, vendor scorecards, and executable playbooks needed to convert market growth into above-market returns. Detailed regional and application splits, confidential vendor benchmarking, and the editable forecast workbook are available on the report landing page—these granular elements are deliberately reserved for subscribers to preserve decision advantage and enable custom scenario work specific to your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Fiber Filter Cartridge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 8‑bit Automotive MCU Market at US$850 Million in 2025 — Asia Pacific Leads with US$425M; Poised to Reach US$1,010.38 Million by 2032 at 2.5% CAGR (Top 3 Hold 68.5%)
By pmarketresearch, 2026-08-18
PW Consulting: Strategic Brief — 8‑bit Automotive MCU Market Outlook to 2032
As automotive architectures continue to bifurcate between cost‑sensitive, highly integrated vehicle subsystems and compute‑intensive domain controllers, 8‑bit microcontrollers (MCUs) remain an indispensable element of the automotive electronics stack. PW Consulting’s new market research report — base year 2025, historical coverage 2020–2025, and forward projections through 2026–2032 — delivers the strategic intelligence executives will need to make high‑stakes product, sourcing, and M&A decisions in 2026. Built on an evidence base of supplier filings, tier‑1 OEM interviews, design‑win tracking, and production validation, the analysis highlights a measured but durable market expansion at a 2.5% CAGR.
Methylmalonic Acidemia Treatment Market
Why 2026 Is a Pivotal Year for Automotive MCU Strategy
-
Regulatory and safety expectations are converging toward a stricter certification posture: AEC‑Q100 Grade 0 qualification and ISO 26262 functional safety requirements (commonly up to ASIL B for many 8‑bit use cases) are now baseline expectations for new designs. This increases the qualification burden — and therefore the switching costs — for OEMs and Tier‑1s.
High Precision Inductors Market -
Supply‑chain normalization post‑2021 volatility has stabilized lead times for automotive‑grade devices, but geopolitical dynamics are accelerating regionalization pressures that favor onshore or nearshore sourcing in Asia for many OEM supply chains.
Meat Certification Market -
Technological choreography between 8‑bit MCUs and higher‑order controllers (16/32‑bit) is increasingly critical. Cost optimization, software continuity, and lifecycle support now shape not only component selection but also architecture roadmaps and procurement strategies.
Market Trajectory at a Glance
PW Consulting’s topline modelling shows a steady, resilient expansion of the 8‑bit automotive MCU market. In USD (Million), the market progressed from approximately 810 in 2023 to 830 in 2024 and 850 in 2025 (base year). Our forecast projects growth to about 871.25 in 2026 and continues to expand to roughly 1,010.38 by 2032, reflecting a compound annual growth rate of 2.5% for the forecast period.
What this trajectory signals for corporate decision‑makers is a mature market with incremental unit growth and sustained aftermarket relevance. Investment decisions should therefore be guided by margin preservation, long‑tail service economics, and the ability to sustain multi‑year qualification and production commitments rather than by chasing rapid volume gains.
What the Report Delivers — Operational, Decision‑Ready Insights
-
Actionable scenarios for procurement and dual‑sourcing to reduce supplier concentration risks while protecting cost targets.
-
Qualification and certification roadmaps that align engineering timelines with OEM launch calendars for AEC‑Q100 Grade 0 and ISO 26262 compliance.
-
Supply‑chain stress tests and contingency playbooks that quantify inventory exposure and outline tactical mitigation measures for localized disruptions.
-
Technology migration models that evaluate the commercial tradeoffs between retaining 8‑bit platforms and migrating to 16/32‑bit solutions across functional domains.
-
A vendor scorecard framework and an M&A playbook to prioritize targets and partnership structures that strengthen product portfolios or regional manufacturing footprints.
-
Lifecycle and obsolescence management protocols to preserve aftermarket revenues and minimize redesign costs over multi‑year programs.
In keeping with the “prequel” purpose of this release, the report contains detailed regional, application and type‑level splits and revenue overlays, which are intentionally not reproduced here so decision‑makers will consult the full deliverable for granular allocations and model assumptions.
Competitive Landscape — Key Players and Strategic Postures
The 8‑bit automotive MCU market is concentrated, with leading vendors commanding substantial installed bases and ecosystem depth. PW Consulting estimates that the top three vendors control a significant majority of market share, and top five concentration rises further — a structure that favors established suppliers that combine automotive qualification, long product lifecycles, and broad software/ecosystem support.
-
Microchip Technology (Chandler, AZ) — Microchip remains a dominant force in automotive‑grade 8‑bit MCUs, offering AEC‑Q100 Grade 0 qualified PIC and AVR families with CAN/CAN FD support and functional safety credentials up to ISO 26262 ASIL B. Their portfolio targets body, HMI, and sensor applications where thermal resilience and robust communication interfaces are critical.
-
STMicroelectronics (Geneva) — ST continues to actively support its STM8AF/STM8AL series, expanding packaging and ecosystem tools to sustain design wins in body and powertrain contexts. Recent portfolio updates through early 2026 underscore ST’s commitment to the automotive 8‑bit segment as part of a broader multi‑architecture automotive strategy.
-
NXP Semiconductors (Eindhoven) — NXP’s legacy S08 and HC‑series remain relevant in cost‑sensitive applications. Their advantage lies in long‑term automotive qualifications and depth across CAN‑based networked subsystems that remain common in production fleets.
-
Silicon Laboratories (Austin) — Silicon Labs brings high‑integration 8‑bit devices with features like integrated 12‑bit ADCs in compact packages, appealing to sensor and compact control applications that demand analog performance in constrained BOMs.
-
Renesas Electronics (Tokyo) — Renesas’ RL78 family (8/16‑bit hybrids) addresses low‑power, automotive‑qualified needs for body control and lighting domains, benefitting from Renesas’ deep relationships with OEMs and Tier‑1s.
-
Infineon Technologies (Neubiberg) — Infineon maintains legacy XC800 alternatives for demanding applications, with a focus on industrialization and high‑reliability deployments.
Recent product availability and portfolio refreshes from several of these vendors in early 2026 confirm that incumbents are prioritizing ecosystem continuity, extended temperature ranges (up to 150°C), CAN FD capabilities, and functional safety flows rather than radical architectural displacement.
Strategic Implications for OEMs, Tier‑1 Suppliers and Semiconductor Vendors
-
For OEMs: Lock in long‑lead qualification windows early. Because certification and production stability drive switching costs, early alignment on supplier roadmaps, common‑software strategies, and obsolescence clauses is essential to protect program economics.
-
For Tier‑1s: Prioritize supplier consolidation with contingency agreements. The market’s concentration creates both dependency and bargaining leverage. Use that leverage to negotiate stronger lifecycle support and cost pass‑through protections.
-
For Semiconductor Vendors: Differentiate through systems‑level support — expand dev‑tool chains, certify reference designs, and package safety and quality services to commoditize switching pain for OEMs. Consider regional capacity and service nodes to address geopolitical localization pressures in Asia.
-
Across the ecosystem: Adopt hybrid migration strategies. Preserve 8‑bit platforms where they make economic sense (lighting, simple body functions, sensors) while accelerating software portability and abstraction layers for functions that will ultimately migrate to 16/32‑bit domains.
Methodology, Validation and What We Withhold in This Brief
Our quantitative projections rely on historical shipment and revenue reconciliations from 2020–2025, validated against supplier disclosures, design‑win trackers, and OEM program roadmaps. Forecast scenarios blend bottom‑up module demand (per vehicle BOM modeling) with macroeconomic and vehicle production forecasts, and include sensitivity analysis for lead‑time disruptions and policy shifts.
To preserve the strategic utility of this brief while protecting proprietary analytics, we have intentionally withheld the granular regional, application, and product‑type revenue splits that appear in the full report. These withheld elements include modelled allocations that directly inform supplier selection and competitive pricing strategies; they are available only in the complete report package to ensure decision‑makers can act on fully attributable, auditable figures.
How to Use the Report for 2026 Decision‑Making — A Tactical Roadmap
-
Integrate the report’s qualification roadmap into your 2026 program cadence: map AEC‑Q100 and ISO 26262 gates to engineering milestones and procurement contracts.
-
Run the included supplier stress test against your inventory and production plan to quantify risk exposure and identify where buffer stocks or alternate sourcing are cost‑effective.
-
Apply the vendor scorecard to upcoming RFQs: weigh long‑term support and software ecosystem advantages more heavily than short‑term BOM savings for components with multi‑year production lives.
-
Pursue targeted partnerships or bolt‑on acquisitions if your strategy requires immediate expansion of automotive‑grade 8‑bit product lines or regional manufacturing presence.
Conclusion & Access
For organizations that must balance cost, reliability, and long‑term program stability, PW Consulting’s 8‑bit Automotive MCU Market report provides the disciplined, operational intelligence necessary to prioritize investments in 2026 and beyond. The market is growing steadily but not explosively — success will accrue to those who manage qualification timelines, supplier concentration, and technology migration with rigor.
To obtain the full report, including the detailed regional and application splits, vendor profiles with revenue estimates, and the complete suite of tactical templates and scenario models, please visit PW Consulting’s research portal or contact our client services team for enterprise licensing and bespoke advisory engagements.
For detailed analysis of this topic, please visit the official page: 8-bit Automotive Microcontrollers (MCU) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Fast Electric Rolling Door Market Poised for a 7.85% CAGR Through 2032
By pmarketresearch, 2026-08-18
Fast Electric Rolling Door Market: Strategic Imperatives for 2026 Decision‑Makers
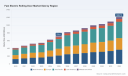
As organizations recalibrate facility operations for energy efficiency, throughput, and resilience, fast electric rolling doors have moved from a niche operational purchase to a strategic asset. PW Consulting’s new Fast Electric Rolling Door Market report (base year 2025) synthesizes five years of historical tracking (2020–2025) with scenario‑based forecasts through 2032. The headline: the addressable market is entering a sustained growth phase in 2026, with a compound annual growth rate (CAGR) of approximately 7.85% over the forecast window. This briefing highlights the report’s strategic value for 2026 planning while intentionally preserving the granular segmentation intelligence that is available only in the full report.
High Purity SiC Parts Market
Why 2026 is a Pivotal Year
-
Policy and procurement cycles are aligning. Energy efficiency mandates (notably provisions under 10 CFR 433 in the U.S.) and incentive structures have accelerated procurement timelines for solutions that reduce air exchange and thermal loss—attributes inherent to high‑speed rolling door systems.
EV Harness Market -
Input‑cost volatility, particularly in steel and aluminum markets, has created both risk and opportunity. Manufacturers and procurement teams that act in 2026 with hedging, design substitution, or pass‑through pricing strategies will materially outperform peers on margin stability.
Marine Wire Rope Market -
Technology differentiation (controls, impact resilience, modular designs) is reshaping total cost of ownership. Buyers are increasingly valuing lifecycle performance and uptime rather than lowest first‑cost, changing vendor selection criteria.
Market Trajectory: The Numbers You Need to Know
PW Consulting’s top‑level model shows a clear recovery and re‑acceleration in 2026 following steady growth in the prior half‑decade. The report’s base‑year analysis (2025) and forward projections through 2032 reflect a market expanding at roughly 7.85% CAGR—supporting strategic investment cases for manufacturers, integrators, and large end‑users contemplating fleet refreshes, retrofit programs, or new facility specifications.
Importantly, while headline growth is robust, the market is not uniform: material selection, door architecture (fabric vs. rigid constructions), and application context (logistics, cold chain, manufacturing) deliver distinct risk/reward profiles. PW Consulting’s full dataset provides the granular segmentation that procurement and product teams depend on; here we outline the implications without disclosing the proprietary splits.
Operational and Commercial Implications for 2026
-
Procurement strategy: Adopt a hybrid sourcing approach. Locking long‑lead material contracts where feasible mitigates exposure to steel price swings—historical analysis in the report shows price fluctuations can be large enough to erode margin or require price reset clauses in supplier contracts. Tactical use of multi‑year agreements with indexed adjustments is recommended for high‑volume programs.
-
Product planning: Prioritize modular control systems and retrofit‑friendly architectures. These features drive faster payback via reduced installation time and lower downtime costs—an increasingly critical purchase justification in logistics and cold‑storage environments.
-
Energy & sustainability: Align product roadmaps with energy efficiency standards and incentive windows. ENERGY STAR and other local programs have created near‑term financial incentives that change the ROI calculus for upgraded door systems; capital budgeting in 2026 should explicitly model these credits and the operational savings from reduced air exchange.
-
Pricing & margin management: Factor in input tariff risk. Recent tariff actions on steel and aluminum materially increased OEM cost bases; scenario planning with discrete tariff and price‑pass‑through assumptions should be mandatory in 2026 pricing reviews.
Competitive Landscape: Who Matters and Why
The fast electric rolling door market combines global engineering leaders, specialized regional fabricators, and an active aftermarket ecosystem. Competitive intensity varies by application: high‑throughput logistics and cold‑chain segments favor high‑performance, certified systems from established global suppliers, while localized security and hurricane‑zone applications remain the domain of regionally focused manufacturers.
-
Rytec Doors (Jackson, WI): Reputation for high‑performance commercial and industrial doors with deep installed base strength. Their recent product updates emphasize energy efficiency and impact resistance—key differentiators for warehouse operators prioritizing uptime and thermal control.
-
Albany Doors (Kenosha, WI): A leader in fabric and high‑speed roll‑up solutions. Albany’s product breadth and focus on logistics applications make them a go‑to for integrators specifying high‑duty‑cycle systems.
-
Hörmann (Steinhagen, Germany): A European heavyweight with advanced control platforms and a recent expansion into Southeast Asia, broadening local production and shortening supply chains for regional customers.
-
EFAFLEX (Bruckberg, Germany): Technology leader known for ultra‑fast spiral and vertical doors. Their recent Next‑Generation product family adds calibrated variants for premium, eco, and basic tiers—an explicit move to segment the value curve more finely.
-
Rite‑Hite (Milwaukee, WI): Known for robust fabric high‑speed doors and proprietary auto re‑feed mechanisms, appealing to high‑traffic dock operations seeking minimal downtime.
-
Cornell Iron Works , Cookson Door Products , Janus International , and Rolling Door Manufacturing : These firms illustrate the market’s regional depth—offering security‑grade, code‑compliant products (including hurricane‑zone solutions) and local installation/service networks that matter for many end users.
Market concentration is meaningful but not prohibitive: a combination of global champions and numerous niche players creates opportunities for both scale‑driven incumbents and agile specialists. M&A prospects often center on acquiring manufacturing scale in lower‑cost regions, adding controls/IP, or expanding service footprints—strategies reflected in recent transactions and product launches.
Recent Industry Moves and What They Signal
-
EFAFLEX’s November 2025 Next‑Gen rollout stratifies offerings into premium/eco/basic variants—indicating a shift toward configurable product platforms to win across different buyer personas.
-
Rytec’s 2025 line updates focusing on energy and impact resistance underscore the market premium for durability and lifecycle efficiency in warehouse environments.
-
Hörmann’s Southeast Asia acquisition (2025) demonstrates the growing importance of local production and shorter logistics for lead‑time‑sensitive projects.
-
New entrants and product launches in 2026 (e.g., ASTA America’s high‑speed rolling steel series) suggest continued innovation in speed and durability metrics—pressuring legacy platforms to modernize.
Risk Factors to Watch in 2026
-
Raw material volatility: Historical data points to material cost spikes that can distort annual P&L. The report includes sensitivity tables and procurement playbooks to stress‑test supplier exposure.
-
Regulatory shifts: Evolving energy codes and local standards (including tax credit expirations or renewals) can materially change adoption economics. Decision‑makers should align replacement cycles with policy windows.
-
Installation and aftermarket service: Field service networks are a competitive moat. Companies that underinvest in installation training and local service risk losing whole‑of‑life revenue streams.
What the PW Consulting Report Delivers (Practical Components)
-
Proprietary market sizing and 2026–2032 forecasting model (top‑level numbers highlighted here), with configurable scenario engines for material pricing and policy outcomes.
-
Supplier and technology matrix mapping product archetypes to application economics—designed to support fast vendor shortlists and RFP templates.
-
Procurement playbook including contract language samples, indexation strategies, and total cost of ownership calculators tailored to door architecture and duty cycle.
-
Go‑to‑market and channel strategies for manufacturers seeking to expand into new regions or verticals, plus M&A diligence checklists for strategic acquirers.
-
Service and aftermarket optimization guidance—how to structure SLA tiers, spare‑parts stocking policies, and digital monitoring to uplift recurring revenue.
Recommendations for 2026 Corporate Planning
-
For OEMs: Invest in modular control platforms and flexible manufacturing footprints now; the ability to deliver localized variants and rapid service will be a key differentiator.
-
For facility owners/operators: Prioritize lifecycle cost and energy impact in procurement decisions; model incentive capture (where available) and align rollouts with energy‑code timelines.
-
For investors and acquirers: Target bolt‑on plays that add service density, controls IP, or low‑cost regional manufacturing—these levers accelerate payback in a market growing at ~7.85% CAGR.
Next Steps
This briefing has highlighted the strategic contours for 2026 without revealing the segmented market intelligence that drives tactical decisions. PW Consulting’s full Fast Electric Rolling Door Market report contains the detailed regional/application splits, supplier share tables, and customizable financial models that procurement, product, and M&A teams require to act decisively this year. For organizations that need to convert the 2026 growth window into measurable advantage, the full report and accompanying Excel model are essential operational tools.
Contact PW Consulting to access the complete report package, tailored briefings, and scenario workshops that translate market projections into executable plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Fast Electric Rolling Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Polylaurolactam Market to Expand at 5.6% CAGR — From USD 1,485.5 Million in 2025 to USD 2,175.32 Million by 2032
By pmarketresearch, 2026-08-18
Worldwide Polylaurolactam (PA12) Market — Strategic Briefing for 2026 Decision-Makers
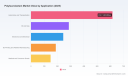
PW Consulting’s latest Worldwide Polylaurolactam Market study (base year 2025, forecast 2026–2032) consolidates proprietary data, primary interviews, and supply-chain modeling to deliver an executive-grade roadmap for commercial, procurement, and R&D leadership. Our analysis shows the PA12 market entering its next phase of steady expansion, with the global revenue base near the mid‑point of the last decade and a compound annual growth rate (CAGR) of 5.6% built into our 2026–2032 projections. For organizations that rely on PA12 for high‑performance plastics—automotive, industrial and electronics OEMs, material suppliers, and compounders—this report is a practical instrument for calibrating 2026 budgets, capacity plans, and strategic partnerships.
Driver Training Management Software Market
Why PA12 Matters in 2026
Polylaurolactam (commercially known as PA12 or Nylon 12) occupies a premium position in polymer portfolios: it combines low water absorption, chemical resistance and dimensional stability with process flexibility across extrusion, injection molding, and powder/filament systems used in additive manufacturing. These material characteristics are driving sustained demand in segments where performance and regulatory compliance outweigh raw material cost pressures. Our market model traces the sector’s recovery from early‑decade volatility into a structurally healthier landscape as electrification, lightweighting and additive manufacturing adoption continue to unlock new mid‑cycle demand.
Vehicle-Mounted Ni-Mh Battery Market
Headline Market Dynamics
- Measured growth path: The global PA12 market is modeled to grow at a steady mid‑single digit CAGR through 2032 under our base case. That trajectory reflects a mix of incremental substitution in automotive systems, capacity additions in Asia, and scaling of specialty grades for 3D printing and medical applications.
- High supplier concentration: Market concentration is pronounced: the top three suppliers control a large majority of global shipments, while the top five extend that dominance substantially. This concentration shapes pricing power, contract terms, and the pace at which new grades reach commercial scale.
- Raw material volatility and supply risk: Laurolactam—the monomer feedstock for PA12—remains sensitive to upstream petrochemical dynamics. Our analysis shows recent softening in laurolactam prices in late 2025, and direct dependencies on butadiene-derived intermediates create ongoing exposure to feedstock cycles.
- Sustainability as a procurement vector: OEM targets for sustainable polymer content are elevating the strategic importance of bio‑based PA12. Automakers and industrial buyers increasingly require supply‑chain transparency and a credible roadmap to 20–30% sustainable polymer incorporation by 2030, creating both risk and opportunity for incumbent and emerging suppliers.
Competitive Landscape — What Matters to Buyers and Investors
The competitive map is defined by a handful of vertically integrated producers and specialty polymer houses. These players combine scale production, global logistics footprints, and grade portfolios spanning extrusion, injection molding, and powder systems for additive manufacturing. In practice, this yields three commercial realities for market participants in 2026:
Worldwide Outdoor LED Street Lighting Market
- Negotiation leverage is asymmetric: large, multi‑grade suppliers control continuity and premium grade availability, which matters when qualifying parts for safety‑critical applications.
- Regional capacity expansions—particularly in Asia—translate into pricing pressure for commodity grades while premium, performance‑differentiated formulations retain margin resiliency.
- Sustainability and traceability initiatives are becoming core competitive differentiators; companies that can certify bio‑content and demonstrate low‑carbon supply chains command premium buyer attention.
Among the companies we profile in detail, several represent archetypes buyers will want to benchmark: a global specialty polymer leader with world‑scale production; a chemical group that couples PA12 with bio‑based product lines; a European engineering polymer house focused on high‑performance compounds; a Japanese producer oriented to precision molding grades; and a large integrated Chinese producer rapidly scaling domestic capabilities. Recent market movements exemplify these dynamics—price adjustments by an Asian integrated player in early 2026 and public sustainability positioning by a leading European producer during 2025 have already shifted negotiation postures across the supply base.
Strategic Implications for 2026 Planning
- Procurement and contract strategy: Locking tiers of security and price protection for core PA12 grades should be prioritized for programs with long qualification cycles. Consider blended sourcing across a global leader and regionally advantaged producers to manage supply continuity versus cost.
- Sourcing for sustainability: Establish supplier scorecards that weight verified bio‑content, carbon footprint disclosures, and third‑party certification. Early partnerships with bio‑PA12 pilots can secure pathway advantage as OEM mandates crystallize.
- Product and process R&D: Invest selectively in compound development and additive manufacturing feedstock qualification. Materials that shorten cycle time, reduce scrap, or enable lightweighted assemblies will capture disproportionate value.
- M&A and JV playbook: For mid‑sized polymer converters and specialty chemical investors, bolt‑on acquisitions of capacity or technical compounding assets offer rapid access to growth. Our report includes scenario analysis for acquisitive strategies under varying price and demand assumptions.
- Risk management: Hedging laurolactam exposure and maintaining visibility on butadiene markets should be part of treasury and procurement roadmaps. We model stress scenarios that quantify margin impact from feedstock shocks across product lines.
What the Full Report Contains — Practical Tools Inside
PW Consulting’s study is designed as an operational playbook rather than a high‑level snapshot. Clients receive:
- Proprietary demand and supply models with editable assumptions for scenario planning (price, adoption, capacity additions).
- Supplier scorecards and a negotiation checklist tailored to PA12 grade families and supply risks.
- Technology deep dives comparing extrusion, injection and powder system economics for manufacturers and AM users.
- Regulatory and sustainability roadmaps mapping OEM targets to material pathways, plus recommended actions for procurement and product development teams.
- An M&A and investment appendix containing valuation sensitivities and integration risk factors for target archetypes across regions.
To preserve commercial value and follow the pre-release principle, the public briefing intentionally omits the detailed regional, grade and application split tables; those granular datasets and the interactive model are available to subscribers and licensed purchasers on the report portal.
Near‑Term Signals and Monitoring Dashboard
For 2026 execution, we recommend establishing a simple monitoring dashboard of five leading indicators that correlate closely with PA12 market condition and price direction:
- Spot and contract laurolactam price trends, particularly feedstock differentials tied to butadiene cycles.
- Capacity announcements and debottlenecking projects in major regional hubs.
- Orderbook and design wins in target end‑markets—especially high‑volume automotive programs and AM series production ramps.
- Supplier actions on sustainability: publication of bio‑PA12 supply commitments, trade‑off analysis between biobased content and lifecycle impacts.
- Major procurement actions and public price notices from vertically integrated producers as they adjust to feedstock shifts.
We continue to watch two high‑impact developments closely. First, upstream raw material behavior: the recent softening in laurolactam pricing observed in Q3–Q4 2025 reduced near‑term cost pressure, but the dependency on petrochemical intermediates leaves the market exposed to renewed volatility. Second, capacity and policy: China’s ongoing expansion of laurolactam and Nylon 12 production capacity is reshaping regional competitiveness and will influence feedstock flows and export dynamics over the next 24–36 months.
Final Recommendation for Decision‑Makers
As PA12 demand broadens across established and emerging applications, the strategic challenge for 2026 is balancing security of supply with margin preservation and sustainability compliance. Our core recommendation: adopt a dual approach—lock operational continuity for core grades through multi‑tiered agreements with leading global suppliers, while investing in targeted development of higher‑margin, sustainability‑aligned formulations and additive manufacturing feedstocks.
PW Consulting’s Worldwide Polylaurolactam Market report equips executives with the market intelligence, supplier benchmarking and executable playbooks needed to operationalize that approach. For access to the full dataset, regional and application splits, and the interactive forecast model, please visit the report portal where licensing options and tailored consulting engagements are available.
For detailed analysis of this topic, please visit the official page: Worldwide Polylaurolactam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide FR4 Plates Market Forecast to Grow at 6.15% CAGR, Reaching USD 18,982.35 Million by 2032
By pmarketresearch, 2026-08-18
Worldwide FR4 Plates Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
PW Consulting’s newly released market research brief on the Worldwide FR4 Plates Market provides a focused, decision-ready roadmap for executives preparing budgets, supply-chain strategies, and product roadmaps in 2026. Built on a multi-year historical series and a seven-year forecast horizon, the study synthesizes macroeconomic trends, raw-material dynamics, regulatory drivers, and a practical competitive playbook—while reserving the granular segmentation tables for subscribers who require the full dataset and modeling assumptions.
Polyurethane Intravenous Indwelling Needle Market
Market at a Glance: Growth Trajectory and What It Means for 2026 Decisions
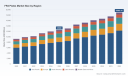
The FR4 plates market has demonstrated steady expansion over the past half-decade, with market value rising from the lower single-digit billions in 2020 to USD 12.5 billion in our base year of 2025. Our forecast work indicates robust, sustained growth through the projection window, with an embedded compound annual growth rate (CAGR) of 6.15% across the 2026–2032 period and a market size approaching USD 19.0 billion by 2032. For leadership teams, these aggregate metrics translate into three immediate imperatives for 2026 planning: (1) align capacity and product mix investments to a multi-year growth profile rather than one-off demand shocks; (2) incorporate volatile input-cost scenarios into capital allocation and pricing frameworks; and (3) prioritize regulatory compliance and product reformulation where required to preserve market access and margins.
Worldwide Microtube Storage Racks Market
Why This Report Matters to 2026 Strategy
- Actionable scenario modeling: The brief includes near-term and base-case scenarios that quantify revenue and margin sensitivities under alternative raw-material price paths and demand-shock scenarios—enabling CFOs and supply-chain leaders to stress-test 2026 P&L projections without building bespoke models.
- Supplier playbook and scorecards: We evaluate leading producers across technical capability, geographic footprint, capacity flexibility, and compliance preparedness—equipping procurement teams with negotiation levers and short-listed alternative suppliers for rapid sourcing decisions.
- Regulatory compliance matrix: A practical mapping of RoHS/REACH implications, plus reformulation pathways for halogen-free and lead-free variants, helps R&D and product teams prioritize reformulation investments to unlock or retain key market segments.
- Go-to-market and pricing tactics: Commercial teams receive tested approaches for passing through feedstock-driven cost increases while protecting share—ranging from indexed pricing agreements to value-based bundling for differentiated laminates.
Key Market Dynamics Shaping 2026 Outcomes
The 2026 competitive landscape for FR4 plates is being shaped by three converging vectors:
Feeding Nutrition Bag Market
- Feedstock price volatility: Input-cost pressures are material. For example, regional epoxy resin pricing shows divergent levels—industry data from March 2026 records roughly USD 2.13/kg in Northeast Asia versus approximately USD 4.63/kg in Europe—creating significant cross-regional cost differentials. Copper price swings and announced increases in fiberglass feedstock have already triggered price adjustments among laminate producers in 2025, and further volatility is baked into our scenarios for 2026.
- Regulatory-driven reformulation: RoHS and REACH remain binding constraints for global electronics applications. The combined effect of these regulations has accelerated demand for halogen-free and lead-free resin systems; companies that can demonstrate robust compliance and validated supply chains will secure a pricing premium and preferential access to OEM programs.
- Demand composition evolution: While traditional consumer-electronics demand remains a large end-market driver, the fastest-growing applications are tied to higher-specification use cases—those that require higher Tg materials, improved dielectric stability, or tighter reliability testing for automotive and industrial electronics. This favors suppliers that can offer differentiated formulations and proven reliability records.
Competitive Landscape: Profiles and Strategic Postures
The market exhibits a measured level of concentration, with leading groups holding a meaningful share of global capacity while a sizeable tail of regional and specialized producers competes on price, niche capability, or service. Our report’s competitive chapter builds operator profiles, recent strategic moves, and likely near-term playbooks. Highlights include:
- Isola Group (Chandler, AZ, USA): Global specialist in high-performance FR-4 epoxy laminates and prepregs. Recent product-documentation updates and reinforced RoHS declarations signal a push to shorten qualification cycles with OEMs and to support lead-free assembly programs—an advantage when bidding for multilayer PCB opportunities requiring validated materials.
- Ventec International Group (Taoyuan County, Taiwan): A broad product portfolio spanning standard and higher-spec laminates, with capabilities for halogen-free variants. Their geographic proximity to major EMS and PCB clusters supports rapid supply and qualification timelines—critical for customers seeking reduced lead times.
- Kingboard Laminates/Kingboard Chemical (Hong Kong/China): A vertically integrated producer that has demonstrated pricing agility; December 2025 pricing adjustments in response to copper and fiberglass feedstock costs underscore how upstream integration and feedstock sourcing strategies influence commercial position.
- Nan Ya Plastics Corporation (Taipei, Taiwan): Strong emphasis on environmental compliance and a broad Tg range suitable for consumer and automotive electronics, positioning them well as OEMs demand higher reliability and regulatory transparency.
- Regional and specialty players (U.S. and China-based manufacturers and distributors): Companies such as Current Inc., Hebei JingHong, Jiujiang Leadcomp, and distributors like Professional Plastics supply electrical-grade sheets, cut-to-size parts, and localized support. These players often win on lead times, custom cutting, and industrial/insulation applications outside mainstream PCB demand.
Our assessment shows a moderate top-tier concentration: combined shares for the three and five largest producers reflect an industry where scale confers advantages in feedstock access and qualification bandwidth, but where mid-tier and regional specialists retain meaningful niches—creating a dynamic M&A and partnership corridor for 2026.
Operational and Commercial Playbook for 2026
Executives should translate the report’s insights into three specific action streams for 2026:
- Supply resilience and input-cost hedging: Put in place raw-material procurement strategies that combine multi-sourcing, regional hedges, and indexed purchase agreements for epoxy and copper. Our scenario tables show that even modest variations in resin and glass prices materially shift gross margins—procurement should therefore be central in commercial planning.
- Product-mix and capex prioritization: Allocate R&D and capacity investments toward higher-Tg, halogen-free, and automotive-qualified FR4 variants. These subsegments are expected to outgrow the market-average rate, and early investment shortens time-to-qualification with OEMs—translating into premium pricing potential.
- Commercial and regulatory readiness: Adopt standardized, audit-ready RoHS/REACH declaration packages and establish faster sample-qualification processes. The report includes template contractual language and a supplier scorecard that helps procurement and legal teams accelerate supplier onboarding without sacrificing compliance.
What the Full Report Contains (and Why You’ll Want It)
PW Consulting’s full Worldwide FR4 Plates Market report delivers detailed modules designed for executive action:
- Comprehensive historical dataset (2020–2025) and forecast model (2026–2032) with sensitivity scenarios and margin impact analysis;
- Segmentation by product type, application, and region with demand drivers and demand-qualification pathways (note: granular segment figures are reserved for the complete report to preserve competitive confidentiality and to support client-specific modeling);
- Supplier scorecards, recent-developments timeline, and a shortlist of near-term M&A and JV candidates based on capacity, technology, and geographic fit;
- Practical annexes: contract templates for indexed pricing, a regulatory compliance checklist, and a unit-cost decomposition model linking resin, glass, and copper prices to laminate production economics;
- Primary research: interviews with procurement heads, plant managers, and OEM buyers, along with proprietary shipment-inventory reconciliations to validate end-market demand.
Closing: How to Use This Intelligence in 2026
For boards and executive teams, the path through 2026 is about converting structural market growth into durable margin improvement while managing volatility. PW Consulting’s brief equips leaders with the scenario language, supplier intelligence, and actionable checklists needed to make defensible choices on capital allocation, pricing architecture, and compliance-driven product strategy. The top-line growth trajectory—from roughly USD 12.5 billion in 2025 to nearly USD 19.0 billion by 2032 at a 6.15% CAGR—creates opportunities for both scale players and nimble specialists. The differentiator for winning companies will be their ability to pair technical product differentiation with disciplined feedstock management and accelerated regulatory qualification.
To access the full dataset, segmentation tables, supplier scorecards, and negotiation playbooks that operationalize these conclusions, visit the PW Consulting report landing page or contact our industry advisory desk for a tailored briefing. Our analysts stand ready to translate the market forecast into a prioritized 90-day action plan for procurement, product, and commercial teams.
For detailed analysis of this topic, please visit the official page: Worldwide FR4 Plates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Phlegm Suction Tube Market to Rise from USD 650 Million in 2025 to USD 926.9 Million by 2032 at a 5.2% CAGR
By pmarketresearch, 2026-08-18
Worldwide Phlegm Suction Tube Market — Strategic Preview for 2026: PW Consulting’s New Market Intelligence
Executive Summary
PW Consulting today releases a forward-looking executive preview of our full market research report on the Worldwide Phlegm Suction Tube market. Built on an audited historical baseline (2020–2025) and a seven-year forecast (2026–2032), the study synthesizes clinical, commercial, regulatory, and operational intelligence that will directly inform buy-side, sell-side and policy-making decisions in 2026.
Offshore Wind Foundation Market
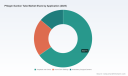
Key headline metrics: the global market expanded from approximately USD 510.5 million in 2020 to USD 650.0 million in 2025. Under the scenarios modeled in this research, the market reaches roughly USD 926.9 million by 2032, representing a 2026–2032 compound annual growth rate (CAGR) of about 5.2%. Market concentration is moderate: the top three players account for roughly 42.6% of market value and the top five for about 58.4% — a structure that supports both consolidation and continued opportunity for specialist innovators.
Worldwide Disc Grinder Market
Why this study matters for 2026 decision-makers
- Timing: 2026 is a strategic inflection point — suppliers that lock in supply-chain resilience, regulatory clarity, and differentiated clinical value now will secure preferred-provider status as procurement cycles accelerate.
- Margin preservation: Rising demand for disposable systems and biocompatible materials increases procurement complexity and cost pressure. Buyers and manufacturers need forward-looking price benchmarking and material-sourcing playbooks to protect margins.
- Regulatory and reimbursement alignment: Recent shifts in standards and coding make early alignment a competitive advantage. The report clarifies what compliance investments produce outsized commercial return in 2026 and beyond.
What PW Consulting’s full report delivers (practical, operational content)
This release is a strategic preview. The full report is designed as a hands-on toolkit for commercial leaders, procurement officers, R&D heads and M&A teams. Key deliverables include:
Power Plant Lightning Protection Market
- Market sizing and scenario-based forecasts (base year 2025; historical period 2020–2025; forecast 2026–2032) with sensitivity analyses and breakouts by product architecture, clinical setting, and geography (note: granular segment datapoints are available in the full report).
- Supply chain and cost stack mapping that identifies single-source risks, material cost drivers (PVC, silicone, specialty polymers), and tiered supplier scorecards for near-term sourcing decisions.
- Regulatory and reimbursement navigator: a practical matrix mapping ISO and FDA requirements, key HCPCS codes and payer triggers, plus a compliance-impact calculator to prioritize investments that unlock access to critical markets.
- Buyer’s playbook for procurement teams: contract language templates, inventory buffers calibrated to lead times, and a supplier qualification checklist focused on sterility assurance and radiation/irradiation process controls.
- Clinical adoption roadmaps for closed vs. open suction systems, with use-case analytics across hospital ICU, emergency, ambulatory, and home-care pathways — highlighting cost-per-procedure, infection-control trade-offs, and clinician adoption barriers.
- Commercial intelligence dossier on 12+ manufacturers including product portfolios, differentiators, manufacturing footprint, and go-to-market strategies — complemented by a near-term M&A heatmap and partnership scenarios.
- Price and margin benchmarks, product-level gross margin estimates, and suggested strategic pricing levers tailored to hospitals, GPOs, and home-care distributors.
Competitive Landscape — strategic reads on core players
The market combines global medical-disposables incumbents with nimble regional manufacturers. Our qualitative and quantitative benchmarking indicates four recurring strategic postures: scale players focusing on portfolio breadth and distribution; cost-leaders emphasizing high-volume disposable supply; specialized innovators introducing value-added design (e.g., closed-system features, directional valves); and contract manufacturers serving OEMs.
- Cardinal Health — leverages broad distribution and clinical relationships to position Argyle™ and Medi-Vac™ lines as procurement-safe, hospital-ready options. Strength: channel reach and integrated supply agreements. Watch: margin pressure in commoditized SKU lines.
- BD (Becton Dickinson) and Medline Industries — compete on clinical trust and product hygiene design; their emphasis on kit solutions and procedural convenience resonates with busy OR/ICU buyers. Strength: trust and product standardization. Risk: exposure to commoditization absent continuous product differentiation.
- Teleflex and Smiths Medical — position higher on critical-care specificity and sterile, performance-tested assemblies. Strategic strength in high-acuity settings where clinicians accept premium for reliability.
- Regional manufacturers (Angiplast, Suzhou Sunmed, Shanghai Teamstand, Dispowell, Luck Medical, Amsino, Sunset Healthcare Solutions) — deliver cost-competitive, high-volume products and increasingly pursue regulatory approval to enter western markets. Strategic play: targeted regulatory investments can unlock rapid share gains in export markets.
Recent credible events underscore dynamic competitive risks and opportunities. For example, a 510(k) clearance secured in mid-2025 illustrates how targeted regulatory wins accelerate access to procedure-grade applications in developed markets; conversely, a high-profile recall in early 2025 highlighted sterility-process risk for closed systems and the reputational damage such events can impose across a supplier’s portfolio. These developments shift procurement criteria: buyers prioritize demonstrable sterility assurance and supplier transparency as much as unit price.
Market dynamics: regulation, reimbursement, and material drivers
- Standards and device classification: Suction catheters are governed by ISO standards that set dimensions, flow performance and sleeve design; many tracheobronchial kits are Class II under FDA regulations with nuanced 510(k) requirements. Manufacturers that embed ISO and FDA expectations into early-stage design significantly reduce time-to-market risk.
- Reimbursement environment: Updated payer guidance (including recent Medicare coding clarifications) modifies the economics of device selection in post-acute and home-care channels. The report’s reimbursement model converts coding changes into facility-level P&L implications.
- Raw materials and manufacturing: Demand for biocompatible PVC and silicone, and the broader U.S. medical tubing market dynamics, are primary upstream cost drivers. The report quantifies elasticity points where polymer substitution, process automation, or strategic VMI (vendor-managed inventory) can improve margins.
Strategic implications and recommended 2026 actions
PW Consulting’s practical guidance for leadership teams entering 2026 centers on five priorities:
- Secure sterility assurance: Audit irradiation contracts and sterile-process validation now; the cost of remediation after a sterility event materially exceeds pre-emptive validation spend.
- Segment the go-to-market approach: Differentiate offerings between acute-care closed systems and high-volume open suction devices for ambulatory/home settings. Tailored contracting and clinical evidence packages increase win rates.
- Cost-to-serve optimization: Rebalance SKU portfolios to reduce low-turn SKUs, negotiate polymer supply contracts indexed to transparent indices, and pilot regionalized production to shorten lead times for major buying clusters.
- Regulatory arbitrage and market entry: Prioritize 510(k) and other market clearances for differentiated devices where premium pricing is viable — and use export-focused OEM partnerships to scale commodity SKUs.
- M&A and partnerships: Pursue tuck-ins for capability gaps (sterility analytics, polymer processing, closed-system valves) or strategic supplier agreements to secure critical polymer throughput.
How PW Consulting’s report supports execution
The full deliverable provides executable artifacts — supplier RFP templates, a regulatory-cost impact calculator, and a procurement negotiation playbook — enabling commercial teams to translate market intelligence into immediate operational moves. Financial-model annexes convert top-line forecasts into SKU-level revenue targets and margin scenarios under alternate raw-material and pricing assumptions.
Next steps & how to access the full intelligence
This preview intentionally surfaces the analysis framework and strategic conclusions while withholding granular segmentation datapoints that are included in the full report. Clients and decision-makers who require the underlying split-by-region, type, and application matrices, the detailed company scorecards and the downloadable tools should contact PW Consulting for access to the full Worldwide Phlegm Suction Tube Market report and supporting datasets.
In 2026, the players who win will not only understand the market’s steady mid-single-digit growth trajectory, but also operationalize sterility, supply-chain control, and targeted regulatory investments to capture disproportionate share. PW Consulting’s study is designed to be the operational blueprint for those choices.
For detailed analysis of this topic, please visit the official page: Worldwide Phlegm Suction Tube Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Phenolic Curing Agent Market Set for 5.12% CAGR — Key Growth Drivers and Regional Leaders Unveiled
By pmarketresearch, 2026-08-18
Worldwide Phenolic Curing Agent Market — Strategic Outlook for 2026: Why This Report Will Be a Boardroom Imperative
PW Consulting’s latest market study on the Worldwide Phenolic Curing Agent Market is published with a clear mandate: equip senior executives, commercial leaders and M&A teams with an executable intelligence set to make confident decisions in 2026. The market reached an estimated USD 861.3 Million in our 2025 base year and, under our central forecast, expands at a compound annual growth rate (CAGR) of 5.12% over 2026–2032 toward just over USD 1.22 Billion by 2032. Those headline numbers capture growth momentum — but the report’s strategic value lies in the operationally-focused tools and scenario framings that translate that momentum into concrete choices for procurement, product strategy, and inorganic growth.
Worldwide Traval Retail Cosmetic Market
Why boards and strategy teams will rely on this study
-
Actionable, not academic: beyond topline sizing, the report delivers supplier scorecards, margin-impact models and a commercial playbook that to-the-dollar estimates how raw-material moves and customer mix shifts will flow to your P&L.
Worldwide Tubing Connections Market -
Risk-to-return mapping: we quantify and stress-test the market under multiple raw-material and regulatory shock scenarios — enabling procurement and R&D leaders to prioritize hedging, reformulation, or vertical options.
Head Mirror Market -
Competitive clarity: a focused benchmarking of leading participants and capability gaps helps identify targets for bolt-on acquisitions, strategic partnerships, or joint development agreements.
Key themes shaping 2026 strategic choices
-
Price and margin pressure from raw-material volatility — Phenol and formaldehyde price swings are no longer episodic. Our monitoring through April 2026 registered substantial increases in key Asian and European phenol hubs and a material step-up in U.S. formaldehyde prices in late 2024. These cost moves are compressing gross margins for producers that cannot pass through rapidly or reformulate toward lower-cost chemistries.
-
Regulatory complexity is increasing — Recent regulatory activity (for example, reporting obligations introduced for certain phenolic derivatives under TSCA’s SNURs) imposes new compliance burdens and potential time-to-market friction for product introductions and reformulations in North America. This alters the calculus for product launches and for acquiring technology or plants that serve regulated uses.
-
Demand pockets remain durable but selectively evolving — End-use engines such as electronics encapsulation, industrial coatings systems, adhesives and advanced composites continue to anchor demand. Within these pockets, formulators are asking for higher-functionality resins, lower-VOC solutions and improved thermal/electrical performance — providing premium niches for suppliers that can invest in application-specific R&D.
-
Moderate market concentration creates maneuvering room — Market concentration metrics indicate a market where the top three vendors account for a meaningful share, and the top five for just over half of industry volume. That structure enables regional champions and specialty players to carve defensible positions while also leaving opportunities for M&A consolidation that meaningfully alters competitive dynamics.
Competitive landscape — what the leading suppliers signal for 2026 strategy
Our report profiles manufacturers and specialty suppliers across the value chain, from global resin platforms to toll processors and niche phenolic houses. Public and private participants — including established resin majors, integrated chemical producers, and specialty tollers — show differentiated plays:
-
Global resin majors bring scale and integrated upstream capabilities, enabling them to navigate raw-material cycles and support large industrial accounts with global supply footprints.
-
Specialty phenolic houses and toll manufacturers offer agility, formulation depth and the ability to service strict application requirements such as electronics and high-performance composites.
-
Some players emphasize coating-grade novolac and resole crosslinkers, while others focus on epoxy-curing compatibility for molding compounds — these strategic choices define customer segments, margin profiles and capital intensity.
To be concrete about names (and why they matter): major global suppliers, integrated chemical producers and specialized phenolic manufacturers are all active in the market. Their positioning ranges from broad aftermarket and OEM supply networks to focused toll-manufacturing and application-driven R&D. This mix means that commercial strategies in 2026 must be calibrated by supplier type — negotiating differently with a captive-volume global player versus a specialty toller capable of rapid reformulation support.
Operational playbook embedded in the report
For executives who need to move from insight to implementation, the study contains a practical set of tools and templates, including:
-
Supplier risk matrix: ranks counterparties by concentration exposure, price-transmission elasticity, and regulatory footprint to prioritize secure, cost-efficient sourcing.
-
Raw-material sensitivity models: quantify EBITDA impact across multiple phenol and formaldehyde price scenarios, enabling finance teams to model forward curves and set appropriate hedge ratios.
-
Reformulation decision tree: a roadmap that links performance targets to reformulation levers, R&D cost estimates, and expected time-to-market under current regulatory timelines.
-
M&A playbook: a prioritized target-screening framework emphasizing capability gaps, regional footprint, and near-term integration risks — and a valuation approach that captures price-cycle volatility inherent to chemical intermediates.
-
Commercial acceleration kit: win/loss frameworks and sample contract clauses (price adjustment language, force majeure drafting aligned with raw-material volatility) that legal and commercial teams can deploy immediately.
Scenario planning — three plausible market pathways for 2026–2028
-
Baseline (central) — Continuation of steady demand and partial pass-through of raw-material cost increases: the market grows in line with our 5.12% medium-term CAGR as formulators accommodate higher input costs through a mix of price adjustments and modest reformulation.
-
Up-cycle (price shock mitigated) — If phenol/formaldehyde supply tightness eases or feedstock prices retreat, producers with underutilized capacity could regain margin through volume recovery and reinvestment in higher-spec products, accelerating premium segment adoption.
-
Regulatory-constrained (cost of compliance rises) — Heightened regulatory actions or new reporting/registration requirements elevate compliance costs and time-to-market barriers, favoring larger integrated firms and creating acquisition windows for smaller players seeking liquidity.
What leadership teams should do in the next 12 months
-
Embed raw-material scenarios into quarterly planning: update price-pass-through triggers for customer contracts and revise capex prioritization to favor flexible, lower-capital intensity projects.
-
Fast-track supplier diversification and strategic inventory: secure multi-sourcing for critical phenolic intermediates and evaluate toll-manufacturing partnerships where capital deployment is undesirable.
-
Accelerate application-focused innovation: invest selectively in higher-margin niches — e.g., electronic-grade curing systems and specialty coating crosslinkers — that demonstrate insensitivity to small-volume cost shocks.
-
Use M&A opportunistically: target regional specialists and tollers whose integration can reduce sourcing risk, add formulation capability, and provide footholds in priority geographies.
Report contents — what you will find inside (high level)
-
Independent market sizing and method notes (historical 2020–2025; base year 2025) and scenario-based forecasts through 2032.
-
Cost and pricing analytics: forward-looking phenol and formaldehyde curves, plus margin impact models.
-
Segment and application demand narratives that identify durable demand pockets and emerging premium opportunities (note: detailed, proprietary subsegment tables and regional splits are available in full report access only).
-
Supplier profiles and competitive benchmarking against capability, capacity and regulatory coverage metrics.
-
Actionable annexes: sourcing playbooks, sample contract clauses, and an M&A target filter.
Closing strategic takeaway
For leadership teams preparing 2026 budgets and strategic roadmaps, the phenolic curing agent market presents both pressure and optionality. The near-term environment is defined by raw-material volatility and tighter regulatory scrutiny; yet, demand durability — backed by applications in electronics, coatings, adhesives and composites — supports disciplined investment in differentiation. PW Consulting’s report provides the analytical foundation and the executable toolset to convert market trajectories into defensible commercial and capital-allocation moves. We present the evidence you need to prioritize: whom to partner with, what to build, and where to acquire — while reserving the granular subsegment datasets that are central to deal and procurement execution for licensed access.
To access the full dataset, proprietary segment tables, and the interactive scenario toolset that management teams will use in 2026 planning cycles, visit the official report page or contact PW Consulting’s industry desk for a briefing and tailored advisory engagement.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Curing Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Robust 12.5% CAGR for Worldwide Next‑Generation Data Storage Market Through 2032
By pmarketresearch, 2026-08-18
Worldwide Next-Generation Data Storage Market — Executive Strategic Briefing (PW Consulting)
Introduction
As enterprises finalize technology budgets and strategic roadmaps for 2026, PW Consulting’s new Worldwide Next-Generation Data Storage Market report delivers the market context and decision-grade tools needed to make high-stakes infrastructure choices with confidence. Built on a rigorous historical baseline (2020–2025) and a detailed forecast window (2026–2032), the study models the transition dynamics across traditional and emerging storage paradigms and quantifies the commercial runway for next-generation solutions. The market is sizable and accelerating: our base-year snapshot (2025) places the global market at USD 86,700 Million, rising to an estimated USD 102,547 Million in 2026 and projected to approach USD 197,736 Million by 2032—reflecting an aggregate forecast CAGR of 12.5% (USD, revenue unit: Million).
Disposable Morcellator Blade Market
Why this report matters for 2026 decision-makers
-
Timing and capacity planning — The combination of strong near-term growth and sustained mid-term expansion creates a narrow window for locking in the right balance of capacity, performance, and cost-efficiency. Procurement cycles started in H2 2025 will collide with vendor roadmaps and supply-chain rhythms in 2026; our report identifies optimal staging points for capacity refresh, expansion, and diversification.
Worldwide Utilities¡¯ Customer Information System (CIS) Software Market -
Technology bet sizing — Organizations must weigh incremental upgrades to flash and software-defined platforms against strategic pilots of MRAM, DNA storage, and other emerging persistent-memory technologies. The report’s readiness assessments and scenario modelling help quantify where pilot investment is justified versus where mainstream deployments will deliver ROI in the 2026–2028 window.
Standalone Photovoltaic Water Pump System Market -
Risk and resilience — With concentration metrics indicating meaningful market power among leading vendors (CR3: 38.5%; CR5: 56.4%), the report highlights supplier lock-in risks and contingency strategies for supply disruption, pricing pressure, and interoperability constraints—critical inputs for enterprise risk committees and CIOs.
-
Energy, sustainability and compliance — New KPIs and standards (ISO/IEC 30134 series, evolving IEEE work on AI environmental measurement, and tighter ISO 27001 expectations) are re-shaping procurement and operational requirements. The study offers actionable guidance on aligning storage choices with PUE/WUE/carbon benchmarks and information-security audit readiness.
What the report contains — practical, operational intelligence
-
Consolidated market sizing and growth modelling: a transparent methodology covering historical 2020–2025 data and detailed projections for 2026–2032 with sensitivity bands and scenario alternatives to support board-level investment decisions.
-
Technology readiness and adoption roadmaps: maturity matrices for core and emerging storage classes, including operational triggers for migrating to all-flash, hybrid architectures, software-defined storage, MRAM, and DNA-based archival systems.
-
Procurement playbook and TCO models: configurable CapEx/Opex templates, lifecycle cost illustrations, and vendor negotiation checklists that translate market-level trends into procurement-level actions for 2026 RFPs.
-
Vendor scorecards and partnership archetypes: synthesis of strategic positioning, product strengths, ecosystem fit, and go-to-market motions for leading vendors—designed to accelerate vendor shortlisting while flagging partnership and co-innovation opportunities.
-
Regulatory and infrastructure impact analysis: applied implications of ISO and IEEE standards, data-center utility constraints (including grid connection wait-time dynamics), and compliance controls that materially affect deployment timelines and TCO.
-
Executive decision frameworks: one-page decision matrices, prioritization rubrics, and a short list of “must-ask” vendor questions for 2026 procurement reviews.
Competitive landscape — strategic takeaways
The market is shaped by an interplay of legacy incumbents, flash and silicon specialists, and emergent platform innovators. Below are high-level strategic positions derived from company-level analysis; the report contains expanded vendor dossiers and a detailed assessment of partnership opportunities.
-
IBM Corporation — Positioned around enterprise-class systems and research-driven innovation, IBM couples advanced tape and archival capabilities with AI-optimized data-management platforms. IBM’s R&D footprint and enterprise services strength make it a default partner for large-scale, regulated archival initiatives.
-
Hewlett Packard Enterprise (HPE) — HPE’s emphasis on hybrid cloud, all-flash arrays, and software-defined architectures targets scalability for AI workloads. Expect HPE to compete on integrated solutions that blend on-prem performance with cloud-native management.
-
Dell Technologies — Dell’s portfolio, anchored by PowerStore and PowerMax families, is focused on high-performance, AI-driven, hybrid-cloud deployments. Dell remains a go-to for enterprises that need tightly integrated stack performance and broad channel coverage.
-
NetApp — Specializes in unified storage and hybrid cloud data services with a strong story for data mobility and tiering; strategically relevant for organizations prioritizing data lifecycle management across private and public clouds.
-
Pure Storage — A pure-play all-flash vendor with a sustainability and Evergreen subscription ethos; attractive for rapid performance refreshes and operational simplicity.
-
Micron, Samsung, Western Digital, Seagate — These suppliers drive the component-level roadmap (NAND, DRAM, HDD, HAMR, SSD). Their product roadmaps and capacity commitments are the critical upstream levers that influence vendor time-to-market and pricing dynamics.
-
Everspin Technologies — MRAM specialist with practical validation for high-reliability applications; relevant to edge and high-end transactional use cases where endurance and persistence matter.
-
Twist Bioscience, Atlas Data Storage — Pioneers in DNA-based archival storage: their roadmaps and commercialisation advances (including Atlas Eon 100) mark the beginning of a new long-term archival option. These players are best suited for early-adopter pilots focused on ultra-dense, ultra-long-retention use cases.
-
Hitachi Vantara, Huawei — Enterprise-focused platforms with strong data-management capabilities and regionally differentiated market approaches; important to consider in multi-cloud, multinational deployments from a geopolitical and compliance lens.
Recent market developments and practical implications
-
Atlas Data Storage’s partnerships and commercial platform launches (late 2025 into 2026) reduce a portion of the execution risk for DNA archival pilots—making 2026 a viable year for controlled production experiments with clear archival use-cases.
-
Patent activity and product innovations (e.g., TEAMGROUP’s patents, PROMISE Technology’s AI-optimized RAID systems, Everspin’s MRAM validation) indicate an acceleration of both performance and security features; these developments should shorten vendor evaluation cycles for proof-of-concept projects.
-
On the standards and compliance front, ISO/IEC 30134 and updates to ISO 27001—together with IEEE efforts to measure AI’s environmental footprint—are creating new procurement specs. Enterprises that bake these into RFPs today will avoid rework and compliance risk in 2026–2027 deployments.
-
Infrastructure constraints—specifically extended grid connection lead times in key data-center markets—are materially shaping deployment architecture decisions: more buyers are factoring behind-the-meter generation and colocated battery solutions into storage rollouts. The report models the cost and timeline impact of these alternatives.
Actionable 60–90 day playbook for CIOs and procurement leads
-
Reassess capacity forecasts against updated market growth curves and vendor roadmap timelines; prioritize modular purchases that preserve optionality for 2027–2028.
-
Launch targeted pilots for one emerging technology where the business case is clear (e.g., MRAM for endurance-critical workloads or DNA for long-term archival), coupled with measurable KPIs tied to cost-per-TB-equivalent and durability.
-
Embed sustainability and security KPIs (aligned to ISO/IEC 30134 and ISO 27001 expectations) into RFP evaluation matrices to avoid retrofitting solutions post-deployment.
-
Stress-test vendor supply commitments against upstream component constraints and include clear contractual remedies for delayed delivery or quality variances.
-
Update disaster recovery and data-mobility strategies to reflect multi-tier storage economics—ensure that archival tiers are decoupled operationally from hot AI/transactional tiers.
Next steps and how to access the full intelligence
This briefing highlights the strategic contours of the next-generation storage landscape and the near-term choices that will determine competitive advantage in 2026 and beyond. For procurement-ready figures, regional and application splits, detailed vendor scorecards, customizable TCO models, and RFP templates, access the full PW Consulting Worldwide Next-Generation Data Storage Market report. The report is designed to be operational: download the complete dataset and playbooks to accelerate 2026 execution, or contact our advisory team to commission a tailored vendor shortlisting and procurement strategy workshop.
For detailed analysis of this topic, please visit the official page: Worldwide Next-Generation Data Storage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com