
Blogs
PW Consulting: Worldwide Landscape Rock Market Tops USD 5,650 Million in 2025, New Report Finds
By pmarketresearch, 2026-08-18
Worldwide Landscape Rock Market: Strategic Insights for 2026 — PW Consulting Release
Executive Overview
PW Consulting's latest market study, Worldwide Landscape Rock Market (base year 2025), delivers an actionable intelligence package designed to inform capital allocation, procurement, and go-to-market strategies in 2026 and beyond. The landscape rock market has demonstrated resilient expansion through the post-pandemic recovery period and, under our central scenario, continues to compound at a 5.45% CAGR over the 2026–2032 forecast window. The global market value reached approximately USD 5,650 million in 2025 and is projected to follow a multi-year upward trajectory, reflecting both sustained end-market demand and evolving supply-side dynamics.
Short Drama Promotion Authorization Platform Market
Why This Report Matters for 2026 Decision‑Makers
-
Timely strategic clarity: Developers, aggregate producers, distributors, and institutional investors face competing impulses — expand capacity, vertically integrate supply, or pivot to value-added imported stone lines. This report frames those choices with scenario-based outcomes tied to macro demand drivers and margin sensitivity analysis.
Worldwide Big Data Integration Platform Market -
Operational focus: With quarry expansions and new product introductions accelerating in late 2025 and early 2026, operational leaders need short-cycle modeling that ties throughput, haul distances, and product grading to working capital and freight cost stress tests. Our modelling isolates the variables that drive first‑order P&L impact.
Chopsticks Packaging Machine Market -
Regulatory and sustainability read-across: Environmental regulation and community scrutiny are reshaping permitting timetables and reclamation obligations. The study translates regulatory shifts into cost-and‑schedule deltas for greenfield and brownfield projects — a practical input for 2026 capital budgeting.
Market Trajectory and Key Macros
From 2020 through 2025 the market expanded steadily, reflecting continued residential landscaping activity, commercial hardscaping projects, and municipal park investments. PW Consulting’s forecast captures the compounding influence of urbanization trends, renovation cycles in mature markets, and rising adoption of ornamental and sustainable hardscape solutions in growth markets. Under our central projection, the market grows at a 5.45% CAGR through 2032, with demand drivers varying by end-use intensity, regulatory environment, and raw material availability.
What the Report Contains — Practical, Tactical, and Transactional
The study is organized into a toolkit for executives who must convert insight into action without delay. Key deliverables include:
-
Market size and forecast model (2020–2032) with scenario toggles — base, downside, and accelerated growth pathways.
-
Supply chain maps and unit cost curves — quarry-to-yard cost decomposition, freight sensitivity tables, and break-even haul distances by product class.
-
Regulatory risk matrix — permitting timelines, environmental compliance cost multipliers, and recommended mitigation levers for common jurisdictional constraints.
-
Competitive benchmarking — strategic profiles, capability maps, and playbooks for the leading producers, distributors, and specialty quarries.
-
M&A and partnership playbook — valuation heuristics, integration checklists, and a prioritized list of target attributes for bolt-on acquisitions or supply agreements.
-
Commercial templates — tender language, sample pricing schedules tied to yardage and tonnage coverage metrics, and guidance for structuring long-term supply contracts under fluctuating transportation costs.
-
Sustainability and ESG scorecard — performance indicators tied to water use, reclamation plans, and low‑carbon transport pathways that matter to municipal and institutional buyers.
Competitive Landscape: From Global Aggregates to Specialty Stone
The market is structurally fragmented — with the top three and top five players accounting for a relatively small share of global sales — a dynamic that preserves opportunity for regional consolidation and specialist entrants. Our analysis profiles incumbent global aggregates leaders alongside nimble specialty suppliers:
-
Global aggregates majors (e.g., Holcim, CRH plc, Heidelberg Materials, Boral Limited) bring scale advantages in crushed stone supply, logistics networks, and integrated contracting relationships with construction clients. Their scale enables competitive pricing on basic landscape grades and positions them to offer bundled solutions for large commercial projects.
-
Large U.S. producers (e.g., Vulcan Materials Company, Martin Marietta) combine robust domestic quarry footprints with distribution channels that service both construction aggregates and landscaping markets. Their ability to optimize grading and to leverage backhaul logistics is a margin lever worth monitoring.
-
Specialty and decorative stone suppliers (e.g., Aggregates International, Polycor Inc., Kafka Granite, Euro Quarries, Yardco Rock & Stone) differentiate through curated product assortments, imported premium lines, and enhanced aesthetic specifications favored in high‑end residential and resort segments. Recent premium product launches from major landscape suppliers illustrate how value-added imports can shift customer expectations.
-
Regional wholesalers and hardscape manufacturers (e.g., Techo‑Bloc, Basalite Concrete Products, RCP Block & Brick) integrate complementary hardscaping products with landscape rock offerings to capture higher-ticket projects and recurring spec work.
For strategic buyers and investors, the fragmentation implies multiple routes to scale: horizontal consolidation of regional quarries, vertical integration with distribution networks, or a focus on premium imported lines that command superior margins. The full report provides a prioritized M&A targets list and accretion/dilution modelling templates for 2026 deal screening.
Supply, Cost, and Regulatory Dynamics
Raw material sourcing remains dominated by natural stone quarries producing crushed limestone, granite, and sandstone. Practical operational metrics — for example, coverage rates such as one cubic yard of rock ground cover approximating 160 sq ft at a 2‑inch depth, or pallet and tonnage coverage metrics for cobble and beach pebbles — translate directly into logistics planning, inventory turns, and order sizing. These unit measures are embedded in our procurement calculators so buyers can convert landscaping specifications into yardage and freight cost projections quickly.
Environmental and permitting frameworks are increasingly influencing time-to-market. Sustainable quarrying practices, water management controls, and reclamation plans are becoming procurement prerequisites for major commercial and municipal contracts. Our regulatory section maps common jurisdictional requirements and the implied capital and operating cost impacts, offering practical mitigation paths such as staged reclamation bonds, community engagement playbooks, and water-use reduction technologies.
Recent Market Signals and What They Foreshadow
-
Product innovation: SiteOne Landscape Supply’s premium imported natural stone line (Solstice) highlights an accelerating trend toward higher-margin, design-driven product introductions by large distributors — a strategic response to customer preferences for differentiated aesthetics.
-
Operational expansion: Approvals for significant quarry expansions indicate that some producers are positioning to capture mid‑cycle demand increases; these projects change supply balances locally and can compress regional price spreads if realized at scale.
-
Performance resilience: Industry reports of steady performance among stone operations point to durable underlying demand in both residential and commercial landscaping, supporting continued investment appetite into 2026.
Actionable Guidance for 2026
For executives preparing strategic plans for 2026, the study provides prioritized actions by function:
-
Procurement: Move from spot buys to hybrid contracts that combine indexed pricing with volume collars to protect margins during freight volatility.
-
Operations: Use our unit cost curves to benchmark quarry throughput and to determine whether investments in washing/grading lines or secondary crushing deliver acceptable payback under your demand profile.
-
Commercial: For distributors and hardscapers, introduce curated premium lines alongside a value-tier portfolio — our pricing elasticity analysis identifies optimal SKU mixes for different customer segments.
-
Investment: Prioritize targets with contiguous quarry footprints or productive reclamation plans that reduce closure risk; our integration checklist pinpoints the top five operational KPIs that drive post‑deal value capture.
-
ESG: Implement the sustainability checklist included in the report to accelerate permitting and to access procurement lists that increasingly favor low‑impact suppliers.
Risk Scenarios and Contingency Playbooks
The report lays out three plausible scenarios — conservative, central, and accelerated — each paired with tailored contingency playbooks. Risks analyzed include commodity‑grade substitution, local permitting clampdowns, freight cost spikes, and demand softening in high‑end residential renovations. For each risk, we quantify exposure in terms of EBITDA sensitivity and provide operational levers (e.g., routing optimization, temporary SKU refocus, contract renegotiation templates).
How to Access the Full Intelligence
This release is a strategic preview: the granular, segment-level forecasts, proprietary pricing matrices, and downloadable scenario models are housed in the full report package and on our client portal. PW Consulting’s full dataset enables drill-down to product-class economics, region-by-region supply maps, and supplier scorecards — information we intentionally withhold from public summaries to preserve commercial sensitivity and to ensure clients receive curated, decision-ready intelligence.
Concluding Perspective
Landscape rock is more than an inputs commodity: it sits at the intersection of urban design trends, environmental stewardship, and logistics economics. For 2026, leaders who translate this market intelligence into tactical actions — optimizing supply chains, selectively investing in capacity, and differentiating through premium product assortments — will capture disproportionate value. PW Consulting’s Worldwide Landscape Rock Market report equips those leaders with the models, benchmarks, and playbooks they need to act confidently in a market characterized by fragmentation, emerging premium demand, and tightening regulatory expectations.
For immediate access to the full report, data worksheets, and an onboarding briefing for your executive team, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Landscape Rock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide N‑Hexadecane Market to Reach USD 303.32 Million by 2032, Growing at a 4.8% CAGR
By pmarketresearch, 2026-08-18
Worldwide N‑Hexadecane Market — Strategic Briefing for 2026 Corporate Decision‑Makers
Executive summary
PW Consulting’s newly released Worldwide N‑Hexadecane Market report synthesizes five years of historical performance and a seven‑year forecast to deliver actionable intelligence for procurement chiefs, product strategists, and M&A teams. The n‑hexadecane market demonstrated steady expansion through the 2020–2025 period, reaching an estimated USD 218.45 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 4.8% across our 2026–2032 forecast horizon. By 2032 our base scenario projects the market to approach the low‑three‑hundred‑million USD range — a trajectory that signals both sustainable demand and room for strategic repositioning.
Nylon Quick-Disconnect Terminal Market
Why this matters for 2026 planning
- Budgeting and procurement: The market’s mid‑single‑digit CAGR supports multi‑year supply agreements but also necessitates agility to manage price volatility tied to feedstock cycles and refining throughput.
- Product positioning: N‑hexadecane’s role as an analytical standard, industrial solvent/intermediate, and functional component in phase‑change materials creates cross‑industry exposure — a strength for vertically integrated players and a complexity for pure distributors.
- M&A and partnership timing: Concentration metrics show a market where the top three and top five suppliers hold meaningful, but not dominant, shares. This creates pockets of consolidation opportunity while still leaving space for nimble challengers focused on service, logistics, or specialty grades.
Market snapshot (what the headline numbers tell you)
- Historical context: The market expanded steadily from the start of the decade through 2025, reflecting steady end‑market demand and incremental product diversification.
- Current scale: PW Consulting estimates the market at USD 218.45 Million in 2025 (base year), with a forecasted value of USD 229.85 Million in 2026 under our central scenario.
- Outlook: With a projected CAGR of 4.8% for 2026–2032, the market reaches approximately USD 303.32 Million by 2032 in our central projection, implying predictable growth but with meaningful variance by scenario.
- Structure and concentration: Our concentration analysis indicates a moderately consolidated market — the top three firms together account for a significant portion of supply, and the top five are estimated to control a clear majority — a landscape that favors scale advantages but still rewards differentiation.
Key market dynamics shaping 2026 choices
- Feedstock and refining linkages: N‑hexadecane is a petroleum‑derived saturated hydrocarbon commonly produced as a distillate fraction or as a modeled output in conversion processes. Consequently, feedstock availability and refinery/renewable diesel processing decisions flow directly through to upstream supply tightness and grade availability.
- Price and margin volatility: Market pricing displays periodic oscillation influenced by regional feedstock supply, logistics constraints, and downstream demand cycles. For procurement and trading desks, hedging strategies and tiered contracting with volume flex clauses are now practical necessities.
- Regulatory framings: N‑hexadecane is codified in regulatory references for analytical testing and specific technical uses. Recent clarifications in food‑contact and reference material designation in major jurisdictions underscore the importance of documented purity and traceability for suppliers and users alike.
- Application diversification: While established uses (analytical standards, solvent/intermediate roles) remain core, thermal energy storage (phase‑change materials) and laboratory standardization are driving incremental, higher‑value demand pockets that reward specialized grade control and technical services.
Competitive landscape — what we observed
The competitive map for n‑hexadecane combines branded specialty chemical producers, regional commodity manufacturers, and global importers/distributors. Key strategic archetypes are visible across the sample set we evaluated:
Wireless HART Handheld Devices Market
- Specialty/high‑purity manufacturers (example: manufacturers offering GMP/SGS‑assured, ultra‑high purity grades). These companies compete on product specification, certification, and regulatory documentation — attributes prized by analytical labs, pharmaceutical testing, and certification bodies.
- Commodity producers with scale and integrated refining links. Such players leverage feedstock access and bulk logistics to supply broader industrial markets where price and volume matter more than boutique grades.
- Global distributors and logistics integrators who add value through multi‑country warehousing, just‑in‑time fulfillment, and regulatory import expertise. For many downstream users, distribution partners reduce working capital and mitigate regional supply shocks.
Representative firms we tracked illustrate these archetypes:
Cybersecurity Vulnerability Assessment Service Market
- TNJ Chemical — a supplier positioned on high‑purity credentials and compliance pathways, supplying both analytical and industrial channels with documented quality standards.
- Wego Chemical Group — a global importer/distributor model focused on supply chain reach and inventory deployment across markets to solve logistical complexity for customers.
- Sartort and other regional manufacturers — emphasizing reliable bulk supply and product specifications suited to industrial customers seeking cost efficiency.
- Specialty lab suppliers and U.S./Japan‑based vendors — serving the research and analytical segments with catalog availability, product stewardship, and application support.
Strategic implication: incumbents with combined strengths in documented quality, regulatory traceability, and logistical reach will capture premium segments. New entrants should therefore prioritize one of these axes rather than attempt broad, undifferentiated competition.
What PW Consulting’s report delivers to practitioners
The report is designed as an operational playbook for 2026 decision cycles, not merely a descriptive market narrative. Highlights include:
- Proprietary demand models that reconcile historical shipment data (2020–2025) with bottom‑up application drivers across industrial and analytical use cases.
- Scenario frameworks (central, upside, downside) that stress‑test outcomes under alternate feedstock and regulatory paths for 2026–2032.
- Supplier benchmarking across quality, certification, geographic reach, and logistics capability — enabling buyers to segment potential partners by value proposition rather than price alone.
- Playbooks for procurement and R&D leaders: contract design templates, sample specifications for high‑purity needs, and supplier evaluation checklists to accelerate sourcing cycles.
- Regulatory and compliance trackers tied to practical supplier documentation requirements — critical where analytical traceability or food‑contact reference uses are invoked by testing standards.
Risk map and mitigation strategies
- Supply disruption risk — mitigation: diversify through a portfolio of licensed distributors and regional manufacturers, implement safety‑stock policies aligned to lead‑time analytics.
- Price swings — mitigation: flexible contracting, indexed pricing collars, and selective vertical hedging in regions where feedstock exposure is material.
- Regulatory or specification drift — mitigation: require traceability and third‑party certification in contracts; maintain engagement with notified bodies and standard‑setting groups.
- Competitive margin compression — mitigation: capture value through bundled services (logistics, analytics), invest selectively in value‑adding grades, or pursue bolt‑on M&A in adjacent specialty segments.
Actionable recommendations for 2026
- Procurement: renegotiate renewals to include volume flexibility and quality audits; pilot a dual‑sourcing strategy for critical grades in the first half of 2026.
- R&D and product teams: prioritize qualification of higher‑value grades for phase‑change and analytical applications, where willingness to pay for traceability is highest.
- Corporate development: screen targets among mid‑tier manufacturers and logistics integrators that can be folded into a differentiated service offering; concentration metrics suggest opportunities for regional consolidation.
- Regulatory/compliance teams: update standard purchase specifications to reflect current regulatory references and require supplier attestation where n‑hexadecane is used as a prescribed reference material.
Next steps and how to access the full intelligence
This briefing outlines strategic implications and headline market metrics. PW Consulting’s full Worldwide N‑Hexadecane Market report contains the granular splits, supplier scorecards, scenario model worksheets, and procurement templates that decision‑makers will need to operationalize a 2026 plan. We intentionally preserve segment‑level tables and proprietary pricing paths within the full report to ensure clients receive immediate, competitive advantage from the detailed data.
For enterprise licensing, bespoke briefings, or to commission a tailored supplier due diligence for your 2026 procurement cycle, contact PW Consulting’s Chemical Markets team. Our analysts are available to walk through the model, stress‑test your vendor strategy, and deliver a short‑form implementation roadmap aligned to your fiscal calendar.
For detailed analysis of this topic, please visit the official page: Worldwide N-Hexadecane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Signage Design Services Market Poised to Expand at a 7.5% CAGR
By pmarketresearch, 2026-08-18
Strategic Outlook 2026: Digital Signage Design Services Market — PW Consulting Intelligence Brief
As organizations recalibrate customer experiences and internal communications for a post-pandemic, hyper-digital world, the market for Digital Signage Design Services has moved from niche investment to strategic infrastructure. PW Consulting’s latest market research (base year 2025) shows the market at USD 2.25 billion and tracking a steady compound annual growth rate (CAGR) of 7.5% through our forecast horizon. Our modeling anticipates continued expansion to the end of the 2032 forecast period, reinforcing that design and content services will be central to the ROI of any digital signage deployment.
Waterline Test Kits Market
Why this report matters for 2026 enterprise decisions
For boardrooms and operational leaders tasked with capital allocation in 2026, the decision to invest in digital signage is no longer only about hardware. It’s a multi-dimensional judgment involving creative capability, software and CMS integration, regulatory compliance, and ongoing content operations. PW Consulting’s report translates market trajectories into decision-useful guidance. It bridges the gap between high-level growth projections and the concrete choices that determine whether a digital signage program becomes a durable enterprise capability or a short-lived experiment.
Solenoid Valve Plug-in Connector Market
Key takeaways for decision-makers:
Multi-Cloud Security Operations Platform Market
- Market momentum: The services market has grown materially since 2020 and is projected to continue at a mid-single-digit to high-single-digit CAGR, reflecting steady demand for professionally designed content and integrated service models.
- Value shift: Total cost of ownership is increasingly driven by content lifecycle, CMS flexibility, and service ease-of-use rather than hardware alone.
- Risk vectors: Compliance (privacy, emissions, accessibility) and labor availability are immediate operational constraints that need mitigation planning in 2026.
What the PW Consulting report delivers — practical, deployment-focused content
We structured the research to be directly actionable for procurement, marketing, facilities, and IT leaders. The report does not merely plot trends — it provides operational tools you can use when planning your 2026 programs:
- Buyers’ Playbook: RFP templates, vendor evaluation scorecards, negotiation levers, and service-level agreement (SLA) clauses that align with content production, CMS uptime, and accessibility requirements.
- Design & Content Frameworks: Reusable templates, motion-graphics standards, and interaction patterns that accelerate time-to-first-campaign while preserving brand quality.
- Implementation Checklists: Site survey protocols, installation coordination guides, and commissioning tests that reduce rollout friction across multi-site deployments.
- TCO and Lifecycle Models: Cost modeling tools that fold in content production, management, software subscriptions, and refresh cycles to reveal true ongoing spend versus one-time capital outlays.
- Compliance & Privacy Playbook: Practical steps for GDPR-ready interactive experiences, RF/wireless compliance awareness, and ADA/OSHA alignment for workplace and public-facing signage.
- Case Studies & Benchmarks: Operational examples from enterprise rollouts, vendor partnerships, and modular pilots that illustrate trade-offs and outcomes without exposing proprietary client KPIs.
Competitive landscape: reading vendor strengths in 2026
The supplier ecosystem for design services remains fragmented and specialized. A small number of firms provide end-to-end, vertically integrated offerings, while many niche providers deliver specialized creative, integration, or manufacturing capabilities. Our fieldwork and vendor assessment highlight distinct value propositions among market leaders:
- Mood Media (Austin, TX) — Strength: End-to-end solutions combining in-house creative services with managed content and installation capabilities, optimized for retail and hospitality environments.
- Visix (Norcross, GA) — Strength: Robust software and enterprise-oriented creative teams, with a strong emphasis on templates, interactive wayfinding, and internal communications.
- SpeedPro (Centennial, CO) — Strength: National production network that supports localized, fast-turn branded content and large-format production and installation.
- FASTSIGNS (Carrollton, TX) — Strength: Broad footprint for consulting, fabrication, and multi-site rollout support, frequently chosen by multi-location enterprises seeking standardized implementations.
- S3 Technologies (Ohio) — Strength: Integration and turnkey support for interactive touch and large LED solutions, with strong service and support models.
- Tyko Sign Group (USA) — Strength: Architectural-grade integration, engineering and site-specific immersive experiences for landmark environments.
- Indovance Inc. (USA) — Strength: Outsourced design and technical drawing services, useful where enterprises need scalable, compliance-aware design documentation.
Collectively, the market’s structure favors partnerships: enterprises increasingly stitch together creative agencies, CMS vendors, and local installers to deliver outcomes, rather than relying on single-source providers. That creates procurement complexity — but also competitive entry points for firms that can guarantee interoperability and predictable SLAs.
Regulatory and operational dynamics shaping 2026 strategies
Design and deployment choices are constrained by a set of regulatory and labor realities that are often underappreciated in early project stages:
- Regulatory compliance: Wireless components and IoT-enabled signs must meet radio-frequency emission rules; interactive systems that collect personal data must be designed for GDPR-style consent, data minimization, and, where relevant, Data Protection Officer oversight.
- Accessibility & safety: Content and hardware choices must account for ADA accessibility and workplace visibility standards, as well as OSHA requirements for safety messaging in industrial contexts.
- Labor market pressures: An aging design workforce in certain markets and regional shortages of skilled installers are driving up service lead times and costs; firms should plan for contingent supplier networks and workforce development partnerships.
Effective 2026 programs will bake these constraints into procurement criteria and project timelines rather than treating them as downstream compliance checks.
Strategic playbook — prioritized actions for 2026
Based on scenario analysis and client engagements, we recommend the following six priorities for organizations committing budget in 2026:
- Start with a content-first pilot: Validate creative workflows, CMS interoperability, and measurement before large-scale hardware rollout. A 90–120 day pilot reduces downstream change orders and content rework.
- Procure for modularity: Specify APIs, open standards, and clear handoffs between creative, CMS, and display hardware so you can swap suppliers without a full replatform.
- Embed compliance and privacy by design: Require vendor attestations for RF compliance, GDPR readiness, and ADA alignment in early-stage contracts, and include audit rights.
- Model full-life costs: Use lifecycle TCO models to compare vendor bids; prioritize predictable recurring fees and transparent production pricing over low initial hardware price points.
- Plan for human capital: Create a blended delivery model that mixes internal content governance with external creative partners; invest in a small in-house design ops function to maintain brand consistency.
- Measure with business KPIs: Tie signage performance to revenue, footfall conversion, safety outcomes, or employee engagement metrics rather than vanity engagement metrics alone.
Key performance indicators and governance
Adopt a concise KPI set to govern programs at scale. Recommended measures include campaign conversion lift, content freshness cadence, CMS uptime and incident response, SLA compliance for install and service, accessibility audits passed, and TCO variance against budget. Align these KPIs to procurement SLAs and executive dashboards so performance is visible and actionable.
How PW Consulting’s full report supports your 2026 roadmap
The published report combines quantitative market modeling (historical 2020–2025 trends and a 2026–2032 forecast), vendor assessments, and over a dozen case studies. It includes downloadable tools — RFP templates, TCO calculators, and a vendor selection scorecard — designed for immediate use in 2026 procurement cycles. Our methodology is transparent: we detail data sources, interview protocols, and scenario assumptions so stakeholders can adapt insights to their specific risk tolerances and timelines.
We intentionally hold back certain granular segmentation outputs from this brief to preserve the integrity of our proprietary models and to encourage engagement with the full dataset. The comprehensive report contains the detailed splits, regional dynamics, and service-type trajectories that procurement teams and strategy groups use to build capital plans and operational budgets.
Final recommendations for 2026 decision-makers
Digital signage has entered a phase where design services and content operations determine the long-term value of deployments. In 2026, prioritize modular procurement, embed compliance into vendor contracts, and run rapid pilots that stress-test CMS and content workflows. Focus capital allocation on the parts of the program that drive repeatable outcomes — content engines, governance, and measurement — rather than one-off hardware price advantages.
For organizations preparing investment cases or vendor selection processes this year, PW Consulting’s report provides the market context, playbooks, and practical tools you need to move from intent to scalable execution. To access the full analysis, modeling annex, and decision tools, request the Digital Signage Design Services Market report from PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Digital Signage Design Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Slim Drapery Motors Market to Expand at 11.32% CAGR, Reaching USD 731.93 Million by 2032
By pmarketresearch, 2026-08-18
Worldwide Slim Drapery Motors Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Market Snapshot
The market for slim drapery motors has transitioned from a niche luxury fixture into a mainstream building and retrofit technology. PW Consulting’s analysis shows the sector scaling rapidly: global revenues rose steadily through the early 2020s and reached an estimated USD 345.5 Million in 2025 (base year). Under the scenario set out in our latest research, the market is projected to sustain a compound annual growth rate (CAGR) of 11.32% over the 2026–2032 forecast period, with total market size moving to the high hundreds of millions by the end of the projection window. For strategic leaders building 2026 plans, these dynamics convert a technology trend into a commercially material growth opportunity.
Worldwide Fiber Optic Extensometers Market
Why This Matters to 2026 Decision-Makers
- Accelerating adoption windows: The convergence of cordless battery technology improvements, quieter brushless motors, and smart-home interoperability is shortening adoption cycles. Organizations that establish product-market fit and channel access in 2026 will capture outsized lifetime value as the category mainstreams.
- Regulatory and specification drivers: Tighter child-safety rules and energy performance requirements in building codes are increasing demand for cordless, motorized window treatments. This shifts product specs and procurement criteria in new-build and retrofit projects alike.
- Cost-to-serve inflection: Wire-free, Li-ion and low-voltage designs materially reduce installation labor and coordination costs—an important lever in retrofit-heavy markets where electrician involvement increases project friction and expense.
Industry Dynamics: What’s Shaping the Next 18–36 Months
Our sector diagnostics identify three compounding forces that will define winners and losers over the next two to three years:
Worldwide Business Centre Market
- Battery and electronics innovation: Advances in compact Li-ion packs and energy-efficient brushless motors extend charge cycles and enable behind-panel installation without bulk. Recent product updates in the market demonstrate up to several hundred reliable cycles per charge—sufficient for most residential and hospitality use cases—and signal a step-change in perceived convenience.
- Smart-home standards convergence: Interoperability protocols (Zigbee, Matter, and proprietary ecosystems) are accelerating demand for plug-and-play integrations. Products that ship with validated integrations to major control platforms reduce friction for specifiers and installers and shorten sales cycles to end users.
- Channel economics and specification shifts: The category is increasingly driven by two commercial vectors: premium residential/hospitality specifications and value-driven retrofit channels. Each demands a different proposition: one focuses on high-load capacities, near-silent operation and aesthetic discretion; the other prioritizes easy retrofit installation, battery life, and cost-to-install.
Competitive Landscape — Strategic Positions and Moves
The slim drapery motor market exhibits a moderate level of concentration: the top three vendors collectively control a substantial share, and the top five players consolidate a clear majority of market presence. This creates both competitive pressure and partnership opportunities for challengers and component suppliers.
Oxidation Stability Reactor Market
Key market actors illustrate distinct strategic plays:
- Somfy (France): A clear leader in high-end integrations, Somfy’s recent launch of the Glydea ULTRA 50 WireFree Zigbee motor (showcased in 2026) underscores a premium, protocol-first approach—high load capacity, discreet installation and ready-made compatibility with leading smart-home systems. Their distribution partnerships and legacy relationships in commercial and hospitality channels preserve strong specification pull.
- Rowley Company (R-TEC Automation, USA): Focused on practical behind-panel installations and track-integrated solutions, Rowley’s offerings emphasize ease of integration in traverse systems and a balance of battery/AC options—positioning them well in both retrofit and new-build segments where discreet aesthetics matter.
- Hunter Douglas (Netherlands) & Silent Gliss (Switzerland): These established systems and track manufacturers leverage channel depth and product breadth—combining hardware, motorization and services to address hospitality and premium residential clients seeking turnkey solutions and building management integration.
- BTX Intelligent Fashion / Skyco and Chinese OEMs (Dooya, Misdar): These players are advancing battery-powered motor performance, electronic-limit features, auto-calibration and competitive price points. BTX’s 2025 updates to its Li-ion Tumo motors illustrate how mid-market players can upgrade feature sets while maintaining channel agility.
Recent Market Signals Executives Should Note
- Somfy’s 2026 public demonstrations and Helser Brothers’ distribution announcements validate demand for Zigbee-enabled, high-load wire-free motors in luxury applications—this is both a technology and go-to-market blueprint for premium positioning.
- BTX’s 2025 product refresh shows the pace at which mid-tier suppliers are closing performance gaps on battery life and load capability, compressing differentiation windows for incumbents who rely on hardware capabilities alone.
- Material and labor economics—lighter aluminum/polymer tracks and cordless designs—are reducing installation friction and enabling faster scaling through retrofit channels, particularly where electrician costs previously constrained adoption.
What PW Consulting’s Report Delivers — Practical, Board-Level Utility
The full report is designed as an executive tool to support strategic planning, product roadmap prioritization and commercial execution in 2026. Highlights include:
- Scenario-based revenue forecasts and sensitivity analysis tied to adoption drivers (smart-home protocol uptake, code changes, battery price declines).
- Go-to-market playbooks segmented by channel type (premium specifiers, retrofit installers, hospitality procurement) including partner archetypes and commercial terms that shorten procurement cycles.
- Supply-chain and component risk matrices prioritizing Li-ion cell sourcing, brushless motor suppliers and track-material strategies to protect gross margins under rising commodity volatility.
- Regulatory impact assessment with compliance roadmaps for new child-safety and energy codes—actionable items for product design and certification timelines.
- Competitive benchmarking and M&A scouting frameworks to identify acquisition targets for rapid capability build (battery management systems, app/cloud integrations, retrofit mounting systems).
Actionable Playbook: Three Priority Moves for 2026
- Product and systems integration: Prioritize shipping motors with validated Zigbee/Matter integrations and certified compatibility with at least one leading smart-home platform. Technical validation removes a common specifier blockade and materially reduces time-to-install.
- Channel architecture: Build dual GTM streams—(a) a spec-driven premium track that partners with architects, hospitality integrators and builders; (b) a volume retrofit channel that leverages installers, retail resellers and e-commerce for faster conversion. Tailor SKUs, warranty policies and training resources to each stream.
- Supply-side defensibility: Secure primary and secondary sources for key battery and brushless motor components, and invest in design-for-manufacturability to reduce disruption risk. Evaluate strategic partnerships or minority investments in component specialists to protect lead times.
KPIs & Monitoring Framework for 2026
We recommend a focused dashboard to translate strategy into measurable results:
- Revenue growth by channel, average selling price migration, and margin per install.
- Installation cycle time and electrician-hours saved (as a proxy for retrofit attractiveness).
- Interoperability certifications achieved (Zigbee/Matter/other) and percent of SKUs with validated integrations.
- Warranty return rates and field reliability (cycles-per-charge performance and failure modes).
- Supplier lead-time variability and inventory days of critical components.
A Word on Competitive Risk and M&A
The market’s moderate concentration suggests room for consolidation and rapid capability acquisition. Incumbents with channel scale can neutralize niche competitors by bundling motorization with hardware and service contracts; conversely, well-capitalized challengers can leapfrog via software/cloud-enabled ecosystems or targeted M&A for IP in battery management and retrofit mounting. For acquirers, target selection should prioritize interoperability, proven battery performance, and established installer networks.
Accessing the Full Analysis
This release is a strategic preview crafted to inform 2026 decision-making. The full PW Consulting Worldwide Slim Drapery Motors Market report contains granular scenarios, regional and application segmentation, supplier scorecards, and play-by-play implementation guides that are intentionally excluded from this summary to preserve commercial value. For procurement teams, product leaders and corporate strategy groups preparing budgets and roadmaps in 2026, the complete report provides the detailed datasets and executable line-items required to operationalize the priorities outlined above.
Contact PW Consulting for the full market brief and to schedule a tailored workshop that converts these findings into a customized 90- and 180-day action plan aligned to your organization’s capabilities and risk appetite.
For detailed analysis of this topic, please visit the official page: Worldwide Slim Drapery Motors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.42% CAGR for Worldwide Ultra‑Low Temperature Freezers for Medical Market
By pmarketresearch, 2026-08-18
Worldwide Ultra Low Temperature Freezers for Medical Market — Strategic Preview
PW Consulting today releases a strategic preview accompanying our forthcoming market research report on the Worldwide Ultra Low Temperature (ULT) Freezers for Medical Market. Purpose-built for executives planning capital investments, procurement heads, product leaders and investors in 2026, this briefing distills the high-impact takeaways from a comprehensive study that spans historical performance (2020–2025), uses 2025 as the base year, and delivers a granular forecast through 2032.
Worldwide Amino Acetic Acid Market
Why this matters for 2026 decision cycles
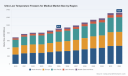
The ULT freezer market for medical use is no longer a niche equipment category — it is a business-critical intersection of clinical compliance, lifecycle cost management and sustainability targets. Our analysis shows the global market grew steadily through the 2020–2025 period and reached an inflection point in 2025. The market is positioned to expand at a compound annual growth rate (CAGR) of approximately 5.42% over the 2026–2032 forecast window, reaching materially larger scale by 2032.
Worldwide Mechanical Estimating Software Market
That trajectory creates two imperative realities for decision-makers in 2026:
Worldwide L-Glutamic Acid Market
- Capital allocation choices made this year — whether to retrofit legacy -86°C assets, replace with new energy-efficient units, or outsource storage to third-party biobanks — will determine five- to seven-year operating budgets and compliance risk profiles.
- Regulatory and certification changes are tightening validation requirements for storage equipment, raising the bar for product design, documentation and aftermarket service — decisions on suppliers, certification investments and service contracts must reflect that new baseline.
What the market dynamics mean in practice
Our report integrates macro drivers that are changing procurement and product strategies across hospitals, biobanks, pharmaceutical companies and research institutes. Key dynamics include:
- Regulatory tightening: The FDA’s Quality Management System Regulation (QMSR), effective February 2, 2026, introduces more prescriptive validation and documentation expectations for equipment used to store high-value medical products. In parallel, ULT freezers intended for storage of vaccines, human cells and tissues remain regulated under EU MDR as medical devices — a continuing design and compliance requirement for suppliers targeting clinical markets.
- Energy and total cost pressure: Legacy -86°C platforms impose high ongoing power costs and create sustainability headwinds for healthcare providers aiming to reduce carbon intensity. Technology advances — including improved insulation, dual-cooling architectures and non-hermetic compressor systems — are enabling substantial daily energy reductions, shifting procurement evaluation from purchase price toward lifecycle cost and environmental impact metrics.
- Consolidation and competitive structure: The market exhibits moderate concentration. Our concentration analysis indicates that the top three suppliers account for over forty percent of the global medical ULT freezer revenue base, while the top five approach the mid‑fifty percent range — a structure that shapes bargaining leverage, aftermarket service models and component supply strategies.
Competitive landscape — what leading suppliers are emphasizing
Manufacturers active in the medical ULT space are differentiating across three axes: compliance and documentation for regulated users; energy and lifecycle economics; and integrated service models (remote monitoring, validation support, and rapid-response maintenance). Our review of incumbent and emerging suppliers highlights distinct positioning:
- Thermo Fisher Scientific Inc. — portfolio depth and global services play. Emphasizes energy efficiency, temperature homogeneity and compliance support for clinical and biobanking customers.
- PHC Corporation (PHCbi) — dual-cooling and eco-efficiency. Continues to invest in dual-cooling architectures and recently expanded its ECO-focused product lines to target energy-conscious institutional buyers.
- Eppendorf AG — laboratory performance and precise control. Focuses on control systems and sample protection for research-intensive users.
- Haier Biomedical — cost and scale advantage. Competes with energy-efficient product variants and models certified for clinical use, leveraging manufacturing scale for price-sensitive markets.
- Helmer Scientific, B Medical Systems, Arctiko, Stirling Ultracold, NuAire, So-Low, Labcold, BINDER, LAUDA, Corepoint Scientific, Accucold — a mix of medical-grade specialists, energy-centric innovators, and regional manufacturers. These firms collectively broaden customer choice across features, certifications and service footprints.
Notably, early-2026 product activity — including new energy-optimized models introduced by major suppliers — underscores a market pivot: vendors are responding to buyer demand for validated, lower-energy ULT solutions that integrate with hospital quality systems.
Regulatory and operational implications for procurement and engineering teams
For organizations evaluating ULT assets in 2026, the convergence of regulation and energy mandates leads to concrete procurement criteria:
- Compliance-first specifications: Require suppliers to demonstrate alignment with FDA QMSR validation pathways and to provide MDR/ISO-compliant design documentation where applicable.
- Lifecycle costing and energy ROI: Shift procurement scoring to include energy consumption metrics, mean time between failures, and predictive maintenance capabilities — not just upfront cost.
- Service and validation packages: Favor vendor offerings that bundle validation kits, IQ/OQ protocols and extended service level agreements to reduce internal validation burden and speed time-to-use.
- Data and remote monitoring: Prioritize controllers and telemetry capable of secure data logging, audit trails and remote alarms to meet clinical chain-of-custody requirements.
Strategic playbook for suppliers, buyers and investors
Our report translates market signals into actionable strategies for three audiences:
- Suppliers and OEMs — Product and commercial strategies: Invest in medical-grade documentation, modular designs that reduce validation cycles, and energy technologies that demonstrably lower TCO. Pursue certification investments (e.g., ISO 13485) and develop bundled service offerings for clinical customers who prize end-to-end compliance.
- Healthcare and laboratory buyers — Procurement and asset-management strategies: Reframe decisions around validated TCO analyses, prioritize vendors with demonstrable compliance workflows, and assess retrofit versus replacement using scenario modelling that accounts for energy savings, downtime risk, and regulatory timelines.
- Investors and financiers — Investment themes: Target companies with differentiated energy platforms, recurring-service revenue models, or superior regulatory-support capabilities. Monitor consolidation dynamics; a mid-market with defined concentration metrics often creates acquisition and roll-up opportunities for scale and service uniformity.
What’s inside the PW Consulting report (practical, non-proprietary overview)
Our full report is constructed to be a working toolkit for 2026 strategy. It combines market sizing and a forward-looking forecast with a suite of operational deliverables that buyers and suppliers can act on immediately, including:
- Scenario-based demand models and TCO calculators that let you test retrofit vs. replacement outcomes under different energy-price and capital-allocation assumptions.
- Supplier benchmarking frameworks covering compliance posture, service coverage, energy performance, and aftermarket economics (presented without disclosing client-sensitive share details).
- Procurement templates and validation playbooks that align with FDA QMSR and EU MDR expectations — IQ/OQ checklists, documentation templates, and audit-ready evidence packages.
- Priority investment roadmaps for R&D and product managers outlining features that materially influence purchase decisions (e.g., dual-cooling redundancy, telemetry integration, and modular refrigeration systems).
- Regulatory impact assessments and risk matrices that connect device-level design choices to organizational validation workloads and compliance timelines.
Executive recommendation — immediate next steps for 2026
Leaders preparing 2026 budgets and capital plans should treat ULT freezer strategy as a cross-functional decision. We recommend four immediate actions:
- Run a short-form TCO and risk assessment across your ULT estate using energy and validation inputs — prioritize candidates for replacement where energy payback and compliance risk align.
- Insist on QMSR- and MDR-aligned evidence from suppliers during RFP stages; require validation support as part of the procurement package to reduce internal workload.
- Negotiate service pilots with telemetry-enabled units to validate real-world energy and uptime performance before committing to large fleet purchases.
- For suppliers, accelerate certification programs and shift commercial offers toward bundle models that lock in recurring revenue while lowering buyer adoption friction.
Where to access the full intelligence
This preview is a strategic extract from PW Consulting’s full report on the Worldwide Ultra Low Temperature Freezers for Medical Market. The complete study includes the full historical dataset, detailed regional and application forecasts, vendor scorecards, and downloadable tools referenced above. The full dataset and templates provide the operational depth required to execute 2026 investment and procurement plans with confidence.
To obtain the full report and associated decision-support tools, visit the PW Consulting publications page. Our team is available to arrange bespoke briefings and to run client-specific scenario workshops that map the report’s insights directly onto your capital and compliance timelines.
PW Consulting — transforming market intelligence into executable strategy for the medical cold chain.
For detailed analysis of this topic, please visit the official page: Worldwide Ultra Low Temperature Freezers for Medical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Emergency Weatherproof Batten Market to Reach USD 603.7 Million by 2032 at 5.5% CAGR; Asia Pacific Leads with USD 135 Million
By pmarketresearch, 2026-08-18
Emergency Weatherproof Batten Market: Strategic Preview for 2026 Decision‑Making
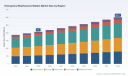
PW Consulting’s latest industry briefing offers a focused, strategic preview of the Emergency Weatherproof Batten market as companies prepare decisions for 2026. Built on a proprietary market model with a 2025 base year, the analysis synthesizes historical performance (2020–2025), near‑term dynamics, and a seven‑year forecast horizon (2026–2032). At the macro level, the market is expanding steadily — from an estimated USD 415 million in 2025 and growing at a compound annual growth rate (CAGR) of approximately 5.5% to reach roughly USD 604 million by 2032 — driven by energy‑efficiency transitions, tightening compliance requirements, and increased specification activity in harsh‑environment projects.
Flip Chip Packages Market
Why this preview matters to 2026 strategy
- The emergency weatherproof batten category sits at the intersection of safety regulation, energy transition, and resilient infrastructure spending. Procurement cycles for industrial, public infrastructure, and commercial projects commonly run on multi‑year timelines; the decisions made in 2026 will shape installation and retrofit volumes for the remainder of the decade.
- Regulatory alignment is becoming a commercial edge. Mandatory and best‑practice standards (for example, national emergency‑lighting codes and international fixture safety standards) are raising the bar on battery chemistry, ingress protection, and testing protocols — turning compliance from a checkbox into a supplier selection criterion.
- Operational cost reductions from LED migration and remote monitoring are now quantifiable and widely used in business cases for retrofits. Stakeholders who can demonstrate lower total cost of ownership (TCO) can capture specification wins in a market with measured supplier concentration (CR3 ≈ 22.5%, CR5 ≈ 31.8%).
What the market dynamics mean in practice
- Energy and operational efficiency are primary demand drivers. LED‑based emergency battens offer material energy savings and extended service lives versus legacy technologies, translating to lower lifecycle costs for asset owners and stronger ROI for retrofits.
- Battery technology and product robustness are differentiators. Adoption of LiFePO4 chemistry, longer warranty terms, and higher ingress/impact ratings (IP65/IP66, IK08) are de‑risking installations in outdoor and industrial settings and are increasingly required by specifiers.
- Compliance and testability influence procurement. Local and international standards (including national emergency‑lighting codes and IEC fixture safety requirements) directly affect product design, labelling, and post‑installation maintenance regimes; suppliers that provide straightforward compliance documentation and remote testing capabilities are favored.
- Supply‑chain and material trends are non‑trivial. For example, upstream price movements for engineering plastics used in housings and diffusers are creating episodic cost pressure; observed pricing data from China in early 2026 show downward price signals for polycarbonate driven by softer demand in adjacent sectors — a factor that affects margin planning and sourcing strategies.
Competitive landscape — positioning and tactical moves
Our competitive scan combines product profiling, recent product and compliance developments, and a supplier capability lens. The field features a mix of regional specialists and international OEMs, with clear segmentation between premium, compliance‑led players and cost‑focused manufacturers that serve OEM/ODM channels.
CCD Image Sensors Market
- Regional specialists with compliance‑led portfolios: Several established Australian manufacturers have built reputations on products engineered for harsh environments and code compliance. Their offerings increasingly include LiFePO4 batteries, selectable colour/output options, and “maintained” emergency operation modes to suit car parks, warehouses, and other critical facilities.
- Feature‑rich LED innovators: Vendors are differentiating through features such as white‑tuning, dimmability, wireguard/diffuser options, and integrated wireless monitoring platforms for remote diagnostics — all of which reduce onsite maintenance costs and support portfolio premiumization.
- China‑based OEM/ODM scale players: Industrial producers in Shenzhen and elsewhere continue to supply robust IP65/IP66 fixtures at competitive price points for large‑volume infrastructure projects (tunnels, workshops, outdoor sites), often offering native emergency systems and private‑label partnerships.
- Recent signals to watch: updates published in early 2026 by compliance‑active vendors and product launches announced in 2025–2026 indicate accelerating focus on enhanced emergency classifications, wireless monitoring, and temporary outdoor safety lighting — each reflecting different go‑to‑market plays.
Strategic implications and recommended actions for 2026
Based on our synthesis of market growth, regulatory drivers, supplier capabilities, and supply‑chain noise, PW Consulting recommends the following practical moves for firms participating in the emergency weatherproof batten value chain.
Reptile Heating and Lighting Supplies Market
- Manufacturers — prioritize certifiable robustness and TCO messaging. Product roadmaps should emphasize LiFePO4 battery integration, higher IP/IK ratings, and extended warranties. Equip product sheets with compliance evidence and lifetime cost calculators to convert specifiers focused on evacuation safety and lifecycle economics.
- Distributors & wholesalers — evolve from logistics to solutions provision. Expand capabilities to offer specification packages, on‑site testing services, and firmware/remote monitoring bundles. These value adds protect margins as price competition intensifies and enable recurring service revenue.
- Project owners & facility managers — build retrofit prioritization frameworks. Use energy‑and‑safety KPIs to rank retrofit candidates; target facilities where LED upgrades plus smart monitoring yield the fastest payback. Incorporate compliance audit clauses into procurement to ensure installed fixtures meet code and insurer expectations.
- Specifiers & consultants — demand testability and documentation. Insist on suppliers that provide clear evidence of compliance with national standards and international safety norms, as well as remote diagnostic capability for scheduled verification without full site interventions.
- Procurement & sourcing teams — mitigate material and logistics risk. Establish dual sourcing for critical plastics and battery components and negotiate flexible pricing clauses tied to a transparent input‑cost index. Consider regional manufacturing partnerships to shorten lead times for emergency projects.
What PW Consulting’s full report delivers (practical contents)
The full Emergency Weatherproof Batten Market report is structured to be actionable for commercial strategy and procurement decisions. Key deliverables include:
- Proprietary market model (historical 2020–2025, base year 2025) and scenario‑based forecasts through 2032, with sensitivity analysis covering demand shocks and regulatory tightening.
- Market segmentation across regions, product types, and applications with demand drivers and adoption curves (note: headline segmentation summaries are discussed in this preview; detailed segment figures are available in the full report).
- Supplier scorecards and comparative feature matrix covering design robustness, battery chemistry, monitoring capability, compliance documentation, warranty terms, and go‑to‑market strength.
- Commercial playbook including specification templates, procurement contract clauses, retrofit prioritization tool, and sample ROI models for LED + monitoring upgrades.
- Supply‑chain risk register and raw‑material sensitivity assessment with recommended sourcing mitigations and inventory strategies.
- Innovation radar and roadmap — from battery evolution to wireless remote testing — highlighting technology inflection points and expected timelines for wider adoption.
- Regulatory impact analysis covering national emergency lighting codes and IEC fixture safety requirements, plus a compliance checklist for specifiers and installers.
Near‑term watchlist (Q1–Q4 2026)
- Regulatory clarifications and enforcement activity in major markets — any updates to national emergency‑lighting codes will alter procurement requirements and retrofit schedules.
- Advances in remote monitoring platforms and standardized remote test protocols — early adopters will capture maintenance savings and long‑term contract wins.
- Raw material pricing trajectories for engineering plastics and battery cell supply dynamics — these will affect supplier margins and may trigger contract renegotiations or localized sourcing moves.
- Competitive product rollouts that bundle compliance documentation, longer warranties, and remote testability — expect suppliers that combine these features to expand spec share in safety‑sensitive verticals.
Concluding perspective
The Emergency Weatherproof Batten market is maturing into a solutions‑oriented sector where safety compliance, durability, and lifecycle economics govern commercial outcomes as much as unit price. With steady growth projected through 2032 at an approximate 5.5% CAGR, the commercial opportunity is meaningful for firms that can align product design, regulatory readiness, and service‑led go‑to‑market approaches. PW Consulting’s full report provides the granular segmentation, supplier benchmarking, and procurement tools needed to operationalize these insights. This press release intentionally omits detailed segment‑level data to protect the tactical intelligence contained in the full study; decision‑makers seeking the complete dataset, segmented forecasts, and supplier matrices are invited to access the full report on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Emergency Weatherproof Batten Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Processed Seafood Market Set to Reach USD 86,105.63 Million by 2032 at a 5.12% CAGR
By pmarketresearch, 2026-08-18
Worldwide Processed Seafood Market 2026: Strategic Imperatives from PW Consulting
As senior industry analysts at PW Consulting, we are releasing an executive preface to our new Worldwide Processed Seafood Market report — a focused, actionable briefing designed to sharpen corporate decisions throughout 2026. The processed seafood sector is entering a phase where steady volume growth, material-price volatility, evolving traceability obligations, and concentrated pockets of strategic scale are creating both clear opportunities and asymmetric risks. This pre-release summarizes the macro trajectory, competitive dynamics, regulatory inflection points, and the pragmatic toolset our full report delivers to executives preparing 2026 plans.
Worldwide Advertising Management Platform Market
Market trajectory at a glance
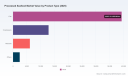
The processed seafood marketplace has expanded meaningfully over the last half-decade. PW Consulting’s baseline sizing shows a market that grew from roughly USD 48.5 billion in 2020 to approximately USD 60.8 billion by the 2025 base year. Under our forecasted scenarios for the 2026–2032 horizon, the market continues to expand at a compound annual growth rate of 5.12%, with an estimated market value of about USD 63.7 billion in 2026 and sustained growth thereafter.
Snowblower Market
That steady, mid-single-digit CAGR reflects three simultaneous dynamics: (1) persistent consumer demand for protein convenience and value-added seafood formats; (2) upward pressure on raw-material and logistics costs; and (3) regulatory and traceability investments that are shifting cost and capability requirements for processors and brand owners. For executives planning capital allocation, portfolio prioritization, or M&A activity in 2026, these macro facts are non-negotiable inputs.
Outdoor Fixed Screen Market
Why this report matters for 2026 decisions
- Practical forecasting tailored to decision windows: We translate market growth and price volatility into planning scenarios that align with typical 12–36 month corporate decision cycles, enabling CFOs and business unit heads to stress-test budgets and contract strategies.
- Regulatory-readiness mapping: The report maps current and imminent traceability, trace testing, and food-safety obligations to operational checklists and CAPEX timelines — critical for avoiding supply disruptions and costly recalls.
- Actionable competitor playbook: Beyond headline rankings, we profile leading processors by capability (cold chain, value-added manufacturing, brand reach) and suggest concrete counter-moves for market entrants and incumbents alike.
- Scenario-based sourcing strategies: We provide decision trees for diversifying raw-material channels, managing freight and tariff exposure, and optimizing buffer inventories under multiple price and supply-shock scenarios.
What the full report contains (practical modules)
- Dynamic market model — interactive dashboards with year-by-year baseline and scenario projections for 2020–2032, ready for export into financial models.
- Segmentation frameworks — region, processing type, and product type segmentation with historic series and forecast splits (note: this preface omits granular subsegment figures; full data tables are available with the report).
- Competitive matrix and capability maps — supplier footprints, vertical-integration scores, and value-chain strengths and weaknesses for major players.
- Regulatory & compliance playbook — FSMA traceability alignment, GDST modular standards implications, and food-safety testing programs translated into facility-level actions and investment timetables.
- Risk & resilience toolkit — recall-response templates, supplier audit prioritization, and insurance/indemnity negotiation guides tailored to processed seafood.
- Go-to-market & innovation levers — product-format prioritization (e.g., frozen value-add vs. commodity canned lines), private-label strategies, brand partnerships, and commercial pricing elasticity analysis.
Competitive landscape — what to watch in 2026
The processed seafood industry is structurally fragmented: the top three and top five firms account for single-digit to low-twenties percentage shares of global market value, leaving substantial room for regional champions and nimble innovators. This fragmentation creates fertile ground for strategic consolidation, targeted bolt-on acquisitions, and capability-driven differentiation.
- Thai Union Group PCL (Samut Sakhon, Thailand) — A global leader across canned tuna, frozen seafood, and value-added brands with an extensive worldwide supply chain. Recent strategic moves and partner investments position it to accelerate branded and private-label initiatives.
- Maruha Nichiro Corporation (Tokyo, Japan) — One of the largest integrated seafood concerns with broad processed seafood operations and deep procurement channels in Asia and beyond.
- Mowi ASA (Bergen, Norway) — The world’s largest salmon farming and processing company, focused on retail and foodservice fillets, portions, and value-added products.
- Nippon Suisan Kaisha (Nissui) (Tokyo, Japan) — A major integrated player with strong frozen and highly-processed product capabilities and global distribution reach.
- High Liner Foods (Nova Scotia, Canada) — A leading North American frozen value-added specialist; its 2025 acquisition activity expanded its branded portfolio and U.S. market depth.
- Trident Seafoods, Lerøy Seafood Group, Royal Greenland, Austevoll Seafood, Cooke Inc., Pacific Seafood Group, Bolton Group, Kyokuyo — Each brings differentiated strengths in wild-caught niches, aquaculture integration, regional distribution networks, or European market presence.
Collectively, these players illustrate two viable strategic archetypes for 2026: (1) scale-driven integration focused on raw-material security and cost efficiency; and (2) capability-driven specialization emphasizing branded value-adds, traceability differentiation, and retail/foodservice partnerships.
Regulatory and supply signals shaping near-term strategy
- Traceability standardization: The Global Dialogue on Seafood Traceability (GDST) public consultation (2026) signals a shift toward a commodity-agnostic, modular standard that will make traceability investments more interoperable but also raise minimum compliance thresholds for processed products.
- FSMA traceability expansion: New FSMA traceability obligations for items on the Food Traceability List introduce recordkeeping needs for farms and processors — companies will need to retrofit or upgrade batch-level traceability and supplier onboarding processes to maintain U.S. market access without friction.
- Food-safety testing and recalls: Recent recall events in frozen products underscore the operational impact of supplier eligibility and testing regimes. We map preventive controls and rapid response protocols that materially reduce recall cost and brand damage.
- Raw-material price pressure: International price indices and USDA outlooks point to above-average upward pressure on seafood pricing into 2026. Companies must plan both hedging and commercial tactics to preserve margin while retaining market share.
Practical recommendations for 2026 planning
- Prioritize traceability investments with ROI gating: Treat traceability as both compliance and commercial enablement. Phase investments by priority markets and SKU value rather than blanket upgrades.
- Revisit sourcing diversification: Move beyond single-origin reliance for high-risk species. Use dual-sourcing contracts and conditional inventory pooling to smooth supply shocks without significant working-capital increases.
- Accelerate value-added frozen capability where margin pools exist: Our market modelling shows compelling risk-adjusted returns for certain frozen value-added formats versus commodity canned lines — but the exact mix is company- and market-dependent; the full report provides the decision matrices and payback scenarios.
- Design targeted M&A playbooks: Given the fragmented market, bolt-on acquisitions can rapidly add processing footprint, retail relationships, or product formats. We provide a prioritized target-screen checklist and integration playbooks to de-risk 100-day plans.
- Embed recall readiness in commercial contracts: Standardize supplier obligations on testing, indemnities, and logistics, and align insurance strategies to preserve cash flow during events.
Case signals and near-term catalysts
A few recent developments signal where executives should allocate attention this quarter:
- High Liner Foods’ 2025 acquisition of leading U.S. frozen brands increased its value-added portfolio and illustrates the attractiveness of branded frozen lines in North America.
- Strategic investment in Thai Union by a major trading house highlights alliance-based approaches to securing scale and market access.
- GDST’s 2026 traceability consultation and FSMA updates elevate traceability from compliance ‘nice-to-have’ to strategic differentiator—companies that lead on verified traceability can command price premiums and preferred placement with large retailers.
- Recent recalls tied to supplier eligibility and contamination incidents are a reminder that operational controls and supplier vetting have direct balance-sheet consequences.
How PW Consulting helps — report deliverables and advisory options
The full report is designed as both an intelligence product and a practical implementation kit. Deliverables include:
- Downloadable time-series market model (2020–2032) with scenario toggles and exportable data tables.
- Segmentation dashboards by region, processing type, and product category (granular splits are available in the paid release).
- Competitive scorecards and M&A target prioritization framework tailored to client strategic intent.
- Operational playbooks for traceability upgrades, supplier risk management, and recall response.
For companies preparing budgets, negotiating supplier agreements, or evaluating acquisition targets in 2026, the intelligence and executable frameworks in our report compress months of research into decision-ready guidance. Because this release follows a “trailer” principle, we have intentionally withheld the granular segment tables and proprietary assumptions that underpin our models; these are included with the full report and our advisory engagements.
Next steps
Executives and investors who require the full dataset, scenario models, and tailored advisory — including workshops to align finance, procurement, and operations teams for 2026 risk scenarios — should contact PW Consulting for access to the complete Worldwide Processed Seafood Market report and accompanying consulting packages. The full report contains the granular segmentation data, forecast assumptions, and playbooks necessary to convert insight into immediate action.
PW Consulting remains committed to providing decision-grade intelligence that turns complex market dynamics into clear, executable strategies. In the face of rising input costs, evolving regulatory frameworks, and fragmented competitive dynamics, the companies that pair disciplined operational rigor with strategic investments in traceability and value-added formats will set the pace in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Processed Seafood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Breath Out Filters Market to Reach USD 1,444.78 Million by 2032 with 5.78% CAGR — Hospitals Segment Alone at USD 616.49 Million
By pmarketresearch, 2026-08-18
Worldwide Breath Out Filters Market — PW Consulting Report: Strategic Imperatives for 2026
PW Consulting today releases a comprehensive industry study, Worldwide Breath Out Filters Market (base year 2025, forecast 2026–2032), designed to equip senior executives, product leaders, purchasing heads and M&A teams with the intelligence required to make high-confidence decisions in 2026. The report combines rigorous market-sizing, regulatory mapping, supply-chain stress-testing and competitive benchmarking to translate technical filter performance into commercial advantage.
Polymeric Positive Temperature Coefficient Device Market
Market snapshot: scale, trajectory and concentration
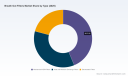
After a period of volatility between 2020 and 2025, the worldwide breath out (exhalation/breathing circuit) filters market stabilized at approximately USD 975 million in 2025 and is projected to expand to about USD 1.04 billion in 2026. PW Consulting’s modeled baseline shows a compound annual growth rate (CAGR) of 5.78% across the 2026–2032 forecast period, culminating in a materially larger market by 2032. Competitive concentration is meaningful: the top three suppliers account for a substantial portion of global revenue, and the top five consolidate more than half the market—an environment that supports both scale-focused incumbents and targeted challengers with differentiated value propositions.
Worldwide Mortgage CRM Software Market
Why 2026 is a pivotal decision year
- Normalization and capital planning: Healthcare providers that deferred capital refreshes and procurement process changes during recent years are entering a planning cycle in 2026. This creates an opportunity window for vendors that can couple clinical evidence with predictable supply and service terms.
- Regulatory tightening and product-design implications: Breathing system filters are regulated medical devices under established quality frameworks (including ISO and regional device clearance processes). Manufacturers that build regulatory-first development, manufacture and post-market surveillance into their roadmaps minimize commercialization risk.
- Procurement emphasis on infection control and economics: Hospital protocols around single-patient use and circuit management—balanced against episodic pressure to extend product dwell times in crisis scenarios—require nuanced value propositions that blend infection-control evidence, lifecycle cost and logistical simplicity.
- Supply and raw-material risk: The market relies on specialized hydrophobic and pleated membrane media and manufacturing practices that must be validated to medical-device standards. Raw material availability and validated vendor relationships will determine which manufacturers can scale without compromising quality.
What the report delivers — practical, operational intelligence
PW Consulting structured this study to be a doer's playbook rather than an academic survey. Key deliverables include:
Worldwide Antiinflammatory Drugs Market
- Market sizing and demand scenarios calibrated to hospital-capacity, anesthesia throughput and mechanical-ventilation usage profiles (base/accelerated/adverse cases).
- Regulatory and standards matrix mapping global pathways (including premarket submission expectations, ISO conformance, and country-specific nuances) and an action checklist for product submissions and conformity assessment.
- Supplier and product scorecards across clinical performance, manufacturing quality (ISO 13485 alignment), supply-chain resilience and cost-to-serve—designed to feed procurement RFPs.
- Raw-material dependency and supply-risk heatmaps that highlight single-source exposures and alternative-sourcing pathways for hydrophobic and electrostatic media.
- Go-to-market archetypes and pricing strategies for device OEMs, contract manufacturers and distributors—covering single-patient disposables, HME hybrids and machine-side filtration.
- M&A and partnership playbooks: target criteria, valuation sensitivities and integration checklists for bolt-on filtration assets and complementary respiratory-device portfolios.
- Operational playbooks for clinicians and hospital procurement teams to harmonize infection-control protocols with inventory policy (fresh patient-side filters, circuit duration rules, and emergency substitution workflows).
Competitive landscape: leaders, differentiators and strategic moves
The report’s competitive analysis profiles established filtration manufacturers and healthcare OEMs that shape market dynamics. Industry leaders are characterized by proven clinical-filter performance, validated manufacturing quality and breadth of channel access; mid-tier and niche players compete on specialization—such as humidification-compatible HMEs, ultra-low-resistance HEPA devices, and compact filters for portable oxygen/respiratory devices.
- Pentair (engineered filtration division) and Pall (Cytiva) stand out for validated high-efficiency appliances suitable for both patient- and machine-side applications and for their deep experience in medical manufacturing controls and regulatory compliance.
- European system suppliers and specialist filtration manufacturers provide broad portfolios spanning electrostatic, hydrophobic pleated media and HME combinations, enabling bundled sales into anesthesia and critical-care accounts.
- Large healthcare OEMs and anesthesia-platform vendors leverage compatibility and integrated consumable strategies to lock value into installed fleets; independent device suppliers focus on differentiated performance or cost leadership for specific use cases.
Recent regulatory clearances in 2025—illustrative of ongoing product refresh activity—show the pace of incremental innovation and market entry. The practical implication for 2026 decision-makers is clear: vendor selection must weigh not only nominal performance claims but also registration status and change-management capabilities.
Regulation, clinical practice and procurement—operational dynamics
Filters for anesthesia and respiratory care are subject to clear design and connector standards and typically follow Class II device pathways in several major jurisdictions. The single-patient-use requirement, coupled with guidance on device handling (no reprocessing, no steam or gas sterilization), shapes hospital inventory policies and total cost calculations. Clinically, service protocols that allow extended circuit duration with patient-side filter exchange create procurement patterns that favor predictable, single-use consumables and simplify traceability.
For manufacturers and purchasers alike, the message is that compliance and tested performance are table stakes; speed-to-market derives from disciplined submission strategies and post-market surveillance capabilities that align with modern hospital procurement expectations.
Six strategic imperatives for 2026
- Design for regulatory-first commercialization: Integrate ISO 13485-aligned processes from concept through production validation so that new SKUs hit market quickly with minimized regulatory friction.
- Pursue modular product platforms: Build families of filter modules (e.g., HME-compatible, high-flow HEPA, hydrophobic machine-side options) that share core components to reduce qualification time and cost.
- Secure raw-material partnerships: Lock multi-year agreements with media suppliers and validate second-source capability to avoid single-point failures during demand surges.
- Differentiate on service and logistics: Offer outcome-oriented contracts—bundling clinical training, inventory-as-a-service and just-in-time replenishment—to accelerate adoption among hospital systems.
- Targeted M&A and alliances: Use acquisition to buy capability (e.g., specialized hydrophobic media, manufacturing footprints in growth markets) rather than volumes alone; prioritize integration of regulatory and QA teams.
- Embed evidence in commercial messaging: Couple filtration performance metrics with peer-reviewed infection-control outcomes and lifecycle-cost models to win formulary inclusion.
How PW Consulting’s report helps you act in 2026
Executives will find this report most useful when planning near-term capital allocations, negotiating multi-year supply contracts, scoping product roadmaps, or screening M&A targets. The study’s scenario-based demand model lets procurement leaders stress-test inventory policies under hospital-capacity and clinical protocol shifts. Product and regulatory teams receive a prioritized checklist for global filings and clinical validation, while corporate development teams get an M&A heatmap and valuation sensitivity analysis tailored to filtration assets.
To preserve commercial value and to encourage hands-on engagement, the report employs a “teaser” release approach: this press summary highlights the analytical depth and the strategic insights available while reserving the detailed segmentation tables, supplier scorecards and proprietary scenario outputs for the full report portal.
Next steps
For executives planning budgets, vendor strategies, product launches or M&A activity in 2026, PW Consulting’s Worldwide Breath Out Filters Market study provides an actionable intelligence pack and a set of executable playbooks. Visit our website to access an executive summary, request a custom briefing or license the full dataset and interactive dashboards.
Contact PW Consulting to schedule a tailored workshop that maps the report’s insights to your organization’s 2026 priorities—whether you are an OEM, distributor, hospital system or investor seeking to convert market visibility into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Breath Out Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Casting Tip & Nozzle Market to Reach USD 480.88 Million by 2032, Growing at a 5.24% CAGR
By pmarketresearch, 2026-08-18
Worldwide Casting Tip And Nozzle Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market study on the Worldwide Casting Tip And Nozzle Market delivers an evidence-based, actionable outlook tailored for executives making high-stakes decisions in 2026 and beyond. The market has shown steady recovery and growth through the early 2020s, expanding from a multi-hundred million USD base in 2020 to an estimated USD 336.11 Million in our 2025 base year. Under our central forecast the market continues to expand through the 2026–2032 horizon at a compound annual growth rate (CAGR) of approximately 5.24%, reaching roughly USD 481 Million by 2032. These macro trajectories reflect the combined effect of production intensity in primary metals, demand for higher surface quality, and investment in process efficiencies across continuous casting and die-casting operations.
Worldwide Mocap Camera Market
Why this report matters for 2026 choices
2026 is the inflection point for many strategic decisions in the casting tips and nozzles ecosystem. Companies face simultaneous pressures to raise productivity, reduce water and energy footprints, mitigate raw-material risk, and capture aftermarket revenue. Our work translates market momentum into decision-ready intelligence: where to allocate CAPEX, how to structure supplier contracts, which product innovations warrant accelerated R&D, and what M&A targets meet strategic criteria.
HBM Controller IP Market
-
Timing CAPEX and capacity: the forecast window identifies the optimal window for incremental capacity versus brownfield modernization.
Telemedicine Integrated Consultation Vehicle Market -
Supplier and materials strategy: granular materials risk scenarios inform whether to secure long-term supplies or pursue vertical integration for critical inserts and refractories.
-
Product strategy and aftermarket: the report prioritizes features and service offerings that convert one-time sales into recurring revenue streams.
What’s inside: operational, practitioner-oriented content
PW Consulting designed this study as a practical toolkit for commercial, technical and M&A teams. Content highlights include:
-
Market sizing and forecasting methodology (transparent assumptions and scenario variants) with an interactive model to stress-test pricing, production, and demand shocks.
-
Buyer and OEM segmentation frameworks and procurement personas to support targeted commercial outreach (note: detailed segmentation tables and proprietary split data are available in the full report package).
-
End-to-end supply chain maps and bottleneck analyses identifying critical upstream materials and single-source exposures.
-
Price and margin benchmarking across product families and distribution channels, with recommended margin-improvement levers.
-
Technical appendix on materials and manufacturing: performance trade-offs for ceramic fibers, aluminum silicate systems, zirconia inserts, and composite solutions.
-
Regulatory and quality-control playbooks for secondary cooling systems and continuous-casting spray patterns, intended for process engineers and compliance teams.
-
Transaction support: criteria checklists for bolt-on acquisitions and cross-border roll-ups, plus a short list of prioritized target profiles.
Competitive landscape — reading the field in 2026
The market exhibits moderate concentration: leading firms hold meaningful scale but room remains for niche specialists and technology-focused entrants. This structure favors both platform plays (to aggregate aftermarket services) and focused technology providers (to win technical specifications at OEMs).
-
Pyrotek Inc. — known for modular casting tip assemblies that reduce on-site assembly time and service complexity. Their emphasis on ready-to-insert systems presents a clear value proposition for casthouses focused on uptime and lean operations.
-
AdTech Metallurgical Materials — strong in high-temperature calcined products engineered for twin-roll continuous casting. Recent product catalog updates underscore a push to codify performance claims (e.g., non-stick finishes and dimensional stability at elevated temperatures) into standardized offerings for strip and foil mills.
-
Lechler / Spraying Systems Co. — both firms compete at the intersection of hydraulic and air-mist secondary cooling nozzles. Their differentiators are precision spray engineering, fluid-usage optimization, and strong integration capability with automation and cooling control systems.
-
Dyson Technical Ceramics, Zircoa, and other zirconia-focused suppliers — these specialists address erosion-resistant metering nozzles for steel continuous casting. Their strength is material science and long-run reliability, a premium buyers are willing to pay when extended casting times and quality imperatives dominate.
-
LMM Group and similar refractory suppliers — positioned on the ladle-to-tundish flow-control axis; they compete on delivery security, custom-form components and compatibility with foundry operational practices.
-
hotset GmbH — niche provider of sprue nozzle heaters delivering process control in hot-chamber die casting; a must-watch where die-casting productivity is a priority.
Recent vendor activity reinforces these trends: product catalog refreshes for high-temperature aluminum silicate nozzle families and ongoing engineering emphasis on non-stick, zero-shrinkage components point to incremental competition on materials and repeatability rather than simple price plays.
Materials, technology and process dynamics
Five technical themes shape supplier selection and product roadmaps for 2026:
-
Material performance: zirconia inserts, calcined aluminum silicate systems and ceramic-fiber composites remain the core material toolkit. Their selection is a trade-off among erosion resistance, thermal shock tolerance, and unit cost.
-
Spray and flow precision: uniform spray patterns and flow metering are non-negotiable for preventing surface defects and maximizing yield—driving demand for engineered nozzle geometries and retrofittable control modules.
-
Resource efficiency: water and air consumption reduction are now commercial attributes, not just regulatory responses—products that materially reduce utility intensity command premium placement.
-
Service and modularity: plug-and-play tip assemblies, exchangeable metering systems and aftermarket diagnostics increase uptime and shorten replacement cycles.
-
Digital integration: sensor-enabled nozzles and cloud analytics begin to shift value capture from hardware alone to closed-loop performance services.
High-impact strategic plays for 2026
Based on our scenario analysis, PW Consulting recommends the following priority moves for market participants and their investors:
-
Secure upstream raw-material exposure selectively — hedge zirconia and specialist ceramic supplies where possible, or qualify multiple qualified suppliers to lower single-source risk.
-
Shift to service-led monetization — couple nozzle hardware sales with performance guarantees, spare-part agreements, and remote diagnostics to increase lifetime value.
-
Target high-value niches with clear technical entry barriers (e.g., long-run tundish metering systems, twin-roll nozzles for thin-gauge aluminum) and use joint-development agreements to accelerate adoption.
-
Invest in retrofit-friendly products and field-installable upgrades that reduce OEM procurement cycles and open aftermarket channels.
-
Use M&A to consolidate fragmented aftermarket networks or to acquire sensor and analytics capabilities that accelerate a service transition.
-
Embed water- and energy-efficiency metrics into product specs to win tenders where sustainability is part of procurement scoring.
Top risks and mitigants
Key risks for 2026 decisions include raw-material price volatility, regulatory tightening around water use and emissions, and faster-than-expected substitution through novel materials or additive manufacturing. Each risk has practical mitigants documented in the report — from supplier diversification playbooks to staged CAPEX options and technical validation protocols for new materials.
How to use this report in your 2026 planning cycle
Procurement directors, plant managers, R&D leads and corporate development teams can use the report immediately to:
-
Build scenario-based procurement contracts that align supply commitments with expected production ramps.
-
Prioritize pilot projects that de-risk sensor-enabled nozzle deployments before full rollouts.
-
Screen acquisition targets using our proprietary target-fit scorecard to accelerate diligence.
-
Quantify savings opportunities from switching to higher-efficiency secondary cooling systems and from extending nozzle service life through design changes.
Proprietary data and next steps
To preserve the tactical advantage for report users, we present high-level market trajectories and strategic implications here while retaining the granular segment-level tables, regional splits, and full company benchmarking in the paid report package. That detailed dataset includes downloadable spreadsheets, an interactive forecasting model, full supplier scorecards and technical appendices that underpin the recommendations summarized above.
For teams preparing 2026 budgets, sourcing roadmaps or acquisition pipelines, PW Consulting’s Worldwide Casting Tip And Nozzle Market report is engineered to convert insight into executable plans. Visit our official report page to access the complete dataset, methodological notes, and bespoke advisory options.
For detailed analysis of this topic, please visit the official page: Worldwide Casting Tip And Nozzle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Rocket Propulsion Systems Market Forecast to Grow at 7.5% CAGR, Rising from USD 6,480.5 Million in 2025 to USD 10,751.47 Million by 2032
By pmarketresearch, 2026-08-18
Worldwide Rocket Propulsion System Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As governments and commercial actors accelerate plans for satellite constellations, reusable launchers, and deep-space exploration, the rocket propulsion systems market is entering a decisive phase. PW Consulting’s new market study — with a 2025 base year, a 2020–2025 historical analysis and a 2026–2032 forecast horizon — provides executives with the operational intelligence needed to shape boardroom decisions in 2026. The global market is on a multi-year ascent, underpinned by a steady compound annual growth rate (CAGR) of 7.5% and robust expansion heading into the forecast period. This release highlights the report’s strategic value without disclosing the granular subsegment datapoints reserved for subscribers.
Glass Axial NTC Thermistors Market
Market trajectory and what it means for near-term strategy
Between the historical window and the forecast horizon, the propulsion market demonstrates clear momentum driven by a mix of commercial launch demand, defence modernization, and renewed governmental investment in space exploration. The market’s pace of expansion — captured in a mid-single-digit to high-single-digit CAGR — signals that 2026 will be a make-or-break year for firms that must choose between scaling manufacturing capacity, pivoting to new propellant and engine architectures, or doubling down on service and integration offerings.
Gyratory Crusher Market
- Capital allocation: The growth profile supports disciplined capacity investments, particularly in modular production lines and additive manufacturing, but timing is critical to avoid capital misalignment.
- Product strategy: Diversification across propulsion technologies (chemical, electric, hybrid) should be evaluated against lifecycle economics and reuse strategies that are becoming standard expectations for new entrants.
- Risk-adjusted returns: With steady aggregate growth, companies that combine technology differentiation with resilient supply-chains and regulatory compliance will capture disproportionate upside.
What the report delivers — practical components for executive action
PW Consulting’s study is intentionally built for decision-makers who require actionable insights rather than descriptive overviews. The report contains:
Worldwide LED Desk Lamp Market
- End-to-end market sizing and a transparent forecasting model (2026–2032) that clients can adapt to their scenarios.
- Technology roadmaps and maturity assessments for liquid, solid, hybrid, and electric propulsion, including a short-list of disruptive enablers (e.g., additive manufacturing, methane and LOX architectures, electric pump-fed cycles).
- Supply-chain heatmaps that identify concentration risks at raw-material, propulsion component, and test-facility nodes, together with mitigation playbooks.
- Commercial and defence go-to-market templates—pricing frameworks, launch-service bundling options, and long-term service contracts that preserve margin as competition intensifies.
- M&A and partnership blueprints: target-screening criteria, synergies assessment, and valuation sensitivities calibrated to propulsion-specific earnings drivers.
- Regulatory and export-control compliance checklists mapped to major jurisdictions, and certification pathways for commercial orbital providers.
- Scenario-driven stress tests for production scale-up, supply-chain disruption, and regulatory tightening, along with prioritized contingency actions.
Competitive landscape — who matters and why
The market remains concentrated enough that incumbent vendors and rapid innovators each influence technology trajectories and commercial norms. Aggregate concentration metrics indicate that the top-tier companies control a meaningful share of industry revenues, reflecting a mix of long-cycle programmes and rapidly scaling private ventures. PW Consulting’s analysis synthesizes public disclosures, test milestones, and programme commitments to profile strategic postures across a representative set of players:
- Aerojet Rocketdyne (Canoga Park, CA) — A legacy propulsion house with deep heritage in cryogenic and modular liquid engines; a strategic asset for governmental heavy-lift programmes and a potential partner for organisations seeking to onshore critical liquid-engine production.
- SpaceX (Hawthorne, CA) — A market-shaper whose iterative engine development and integrated launch-stack economics have reset expectation curves for cost-per-kg and reusability margins.
- Blue Origin (Kent, WA) — Focused on methane/LOX architectures for medium-to-heavy lift, Blue Origin’s propulsion programmes are important for competitive benchmarking in methane-fueled staged architectures.
- Rocket Lab (Long Beach, CA) — Represents the small-to-medium launch segment’s move toward electric-pump-fed and Rutherford-style innovations; an example of how component-level innovation can cascade into new vehicle classes.
- Northrop Grumman (Falls Church, VA) and Avio (Colleferro, Italy) — Both firms illustrate enduring demand for large solid-rocket motor technologies in defence and institutional markets, where reliability and heritage matter more than unit-cost disruption.
- Newer entrants (Ursa Major, Relativity Space, Firefly, Stoke Space) — These companies demonstrate the commercial cycle of rapid prototyping, additive manufacturing, and vertical integration. They are important from a competitive-threat and partnership-opportunity perspective.
- Major OEMs in Asia (IHI Corporation, Mitsubishi Heavy Industries) — Reflect regional industrial strategies to sustain national launch capability and support commercial market entrants.
Recent industry events — test milestones, first flights, and contract awards — are reshaping partner and supplier strategies. Examples include full-duration static fires of next-generation engines, first flights of vehicles using new boosters, and government contract wins that restart legacy-production lines. These developments accelerate decisions around test-facility capacity, production scaling, and rightsized supplier portfolios.
Regulation, export controls and supply-cost dynamics — immediate operational priorities
- Export controls and ITAR: Propulsion technologies remain closely controlled in key jurisdictions. Organisations must incorporate export-license lead times and compliance costs into revenue models and partnership timetables.
- EU dual-use controls: Recent regulatory frameworks limit cross-border component flows; firms targeting non-domestic growth should structure supply chains to reduce strategic choke points.
- Certification regimes: Commercial operators must factor in regulatory qualification under aviation and spaceflight safety statutes as part of time-to-market and product roadmap planning.
- Raw-material pricing: Industrial inputs (for example, LOX pricing band observations) have implications for OPEX sensitivities and should inform long-term purchase agreements and on-site production investments.
- Geopolitical sourcing: Sanctions and export restrictions on specific foreign propulsion systems have driven substituted domestic supply programmes and new industrial partnerships—opportunities for companies that can offer certified alternatives.
Risks and mitigation — what to prioritize in 2026
Our risk matrix synthesises the primary threats to 2026 execution along with mitigants that can be operationalised immediately:
- Supply-chain concentration: Mitigate by dual-sourcing critical components, qualifying secondary suppliers, and investing in inventory hedging that balances working capital with mission assurance.
- Certification bottlenecks: Pre-position engineering resources on compliance pathways and engage regulators early through pilot qualification programmes.
- Capex misalignment: Defer non-essential greenfield capacity until validated demand signals; prefer modular upgrades and contract manufacturing to reduce fixed-cost exposure.
- Competitive commoditisation: Protect margins through system integration services, long-term maintenance contracts, and IP on manufacturing processes (e.g., printing geometries, unique turbopump designs).
- Regulatory shock: Scenario-plan for tightened export controls or sanctions; pursue localization and certified replacements where feasible.
Practical recommendations for boardrooms and corporate development teams
For 2026 decision cycles, PW Consulting recommends a three-track approach:
- De-risk and scale: Prioritise investments that shorten test-to-qualification timelines and enable scalable production without large upfront fixed costs. Where capital is required, stage investments against validated commercial commitments or firm government contracts.
- Partner and hedge: Combine strategic partnerships with nimble supplier qualification programs. Pursue JV structures in markets with restrictive export regimes to secure access while preserving compliance.
- Differentiate through services and systems: Move up the value chain by offering propulsion-as-a-service, integrated launch packages, or long-term sustainment contracts that smooth revenue volatility.
Why PW Consulting’s full report is decision-critical
This preview outlines the strategic contours that will influence outcomes in 2026, but boards and strategy teams require the full dataset and scenario models to act with precision. The complete report includes editable forecast models, supplier scorecards, technology readiness timelines, and a curated list of potential M&A and partnership targets with valuation and synergy assumptions. It also provides a regulatory playbook customised for major export-control regimes and certification pathways—tools that materially shorten analysis-to-decision cycles.
To access the full intelligence package — including source-modeled forecasts, proprietary risk scoring, and our recommended implementation roadmaps — PW Consulting invites corporate subscribers and institutional clients to download the comprehensive report or schedule a strategic briefing with our aerospace and defence practice leaders.
Closing note
The worldwide rocket propulsion system market delivers measurable growth and strategic opportunity, but success in 2026 will hinge on disciplined capital allocation, rigorous compliance, and an operational approach that converts technology advantage into resilient revenue streams. PW Consulting’s study is designed to equip leaders with the foresight and the playbooks to win — the full, granular intelligence is available in our complete report.
For detailed analysis of this topic, please visit the official page: Worldwide Rocket Propulsion System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com