
Blogs
PW Consulting: Linear Motors Market Hits $102.5M in 2025, Projected 7.25% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Linear Motors Market: A 2026 Decision-Maker's Guide
The linear motors market stands at a critical inflection point as industrial automation, precision engineering, and functional safety requirements reshape how motion control systems are specified, deployed, and scaled. For executives, procurement leaders, and R&D directors operating in 2026, navigating this landscape demands more than surface-level trend watching. It requires a rigorous, data-grounded understanding of where capital is flowing, which technological paths are gaining commercial traction, and how competitive forces are consolidating around performance, compliance, and supply chain resilience.
PW Consulting’s latest linear motors market research study is designed to serve as a strategic compass for exactly these decisions. Drawing on a six-year historical baseline and a forward-looking forecast window extending through 2032, the report translates macro market trajectories into actionable intelligence. This article previews the analytical framework, structural insights, and competitive intelligence embedded in the full study, while illustrating why access to the complete dataset can materially improve investment, sourcing, and product-roadmap decisions in the current operating environment.
Market Trajectory and the Strategic Weight of Compound Growth
Over the 2020–2025 historical window, the linear motors market expanded from approximately 72.5 million USD to 102.5 million USD, reflecting sustained demand from automation upgrades, high-throughput material handling, and precision positioning applications. The trajectory does not flatten after 2025. Instead, the forecast period through 2032 points to continued expansion, with the market projected to reach 170.5 million USD by the end of the forecast horizon.
The central planning parameter for leadership teams is the compound annual growth rate of 7.25 percent across the 2026–2032 forecast period. In practical terms, this growth rate signals a maturing but still accelerating market, where incremental volume gains are increasingly tied to application-specific optimization rather than broad-based adoption alone. For 2026 decision-making, this has several implications:
- Capital allocation models must account for multi-year value capture rather than short-cycle procurement savings, especially where linear motion is integrated into higher-throughput or higher-precision production lines.
- Forecasting accuracy depends on distinguishing between baseline replacement demand and incremental expansion driven by automation intensity, throughput targets, and safety-related system redesigns.
- Pricing and margin strategies need to reflect shifting demand patterns across motor types, integration complexity, and the growing premium on certified, application-ready motion solutions.
The full study unpacks how these top-line movements interact with regional demand centers, application mix, and technology adoption curves. Rather than presenting static figures, the report maps the interplay between historical momentum and forward demand signals so that strategy teams can test scenarios against a consistent quantitative base.
Structural Shifts Across Types, Applications, and Deployment Models
Linear motors are no longer a niche alternative to rotary-plus-transmission architectures. They are increasingly specified as primary actuators in environments where direct-drive responsiveness, positioning accuracy, and integrated control matter. The market reflects this shift through a clear structural hierarchy in technology and use-case adoption.
On the technology side, linear induction motors continue to represent the largest share of market value, supported by their robustness, scalability, and suitability for high-duty industrial environments. Linear permanent magnet motors occupy a significant and strategically important segment, particularly where efficiency, force density, and precision are paramount. The remaining share covers other motor variants that serve specialized or application-tailored requirements. This composition matters for 2026 planning because each technology path carries distinct implications for sourcing, thermal management, control integration, and total cost of ownership.
On the application side, industrial automation remains the dominant demand engine, reflecting the broader push toward higher-speed, higher-accuracy production and process machinery. Conveyor systems form the second major application pillar, where linear motors contribute to direct-drive conveyance, synchronized motion, and reduced mechanical complexity. A further set of application requirements rounds out the market, spanning precision positioning, specialized material handling, and other targeted deployments.
These structural patterns are not merely descriptive. They shape where suppliers compete, how integrators design systems, and where end users are most willing to absorb higher upfront costs in exchange for performance, reliability, or safety benefits. The report’s segmentation analysis provides the context needed to evaluate which demand pockets are expanding fastest, which are stabilizing, and where substitution risk or technology crossover may alter future share dynamics.
Competitive Landscape: Consolidation, Differentiation, and Continuous Innovation
The linear motors market remains moderately concentrated, with the top three competitors accounting for roughly 28.5 percent of market revenue and the top five reaching about 35.0 percent. This concentration level suggests a landscape where scale, product breadth, application expertise, and integration capability create meaningful advantages, while still leaving room for specialized players to compete on precision, customization, and niche performance credentials.
Linear Motors Market
Several established and emerging players illustrate the diverse competitive playbook now shaping the market:
- LinMot, headquartered in Spreitenbach, Switzerland, emphasizes direct-drive industrial linear servo motors, linear rotary motors, linear modules, and complete systems for industrial automation. Its single-source approach positions it as a partner for customers seeking integrated linear motion solutions rather than component-level purchasing.
- H2W Technologies, based in the United States, manufactures a broad portfolio spanning brushless, brush, voice coil, linear stepper, linear induction, and polynoid linear motors, along with related components and stages for industrial motion control. This breadth supports flexible engineering responses across varied application requirements.
- HIWIN Corporation, headquartered in Taiwan, focuses on permanent magnet linear synchronous motors and high-performance single-axis and multi-axis linear motion systems and stages, aligning closely with precision positioning and automation demands.
- Kollmorgen, also based in the United States, offers direct-drive linear motors and linear axes integrated with servo drives and safety systems, with particular relevance to industrial automation and semiconductor applications where motion integrity and functional safety are critical.
- ITG Motor, located in Suzhou, China, specializes in custom high-precision ironcore and ironless linear motors for automation, robotics, and precision motion control, reflecting the growing importance of application-tailored design in cost-sensitive and performance-sensitive segments alike.
- Maccon GmbH, in Germany, produces ironless and ironcore linear motors in kit form for precision motion applications, an approach that appeals to integrators and OEMs seeking modularity and design flexibility.
- Prodrive Technologies, based in the United Kingdom, develops and manufactures high-performance linear motors and actuators for motion control systems, emphasizing performance-tuned solutions for demanding control environments.
- Beckhoff Automation, headquartered in Germany, provides linear servomotors and integrated automation solutions supporting high-speed linear motion, reinforcing the trend toward tightly coupled control hardware and motion hardware.
- Aerotech, based in the United States, designs and manufactures custom linear and curvilinear motors for precision motion in industrial and research applications, illustrating the ongoing role of custom engineering in high-value deployments.
Recent corporate activity underscores that competition is not only about product breadth but also about regulatory readiness, firmware-enabled safety, and system-level integration. In early 2026, LinMot released new products for the year, including advancements in linear systems and modules, signaling continued investment in application-ready offerings. Around the same time, Kollmorgen launched the SafeMotion Monitor SMM 3.0 firmware upgrade, enabling SIL 3 compliance and EnDat 2.2 safe feedback support for linear motor applications. These moves matter because they show how competitive advantage is increasingly tied to certified safety performance and integrated control reliability, especially in high-risk or high-value use cases.
Operational Dynamics Shaping 2026 Strategy
Market growth does not occur in a vacuum. Several operational and environmental factors are actively influencing adoption speed, sourcing decisions, and product design priorities. Understanding these dynamics is essential for building realistic 2026 plans.
Material Supply and Cost Exposure
Permanent-magnet linear motors depend on neodymium-iron-boron alloys, and the supply chain for refined rare-earth materials remains heavily concentrated. China supplies over 90 percent of refined neodymium-praseodymium material, and prices for these inputs climbed 243 percent between 2020 and 2025. For motor manufacturers, integrators, and end users, this creates a direct cost and availability consideration that can influence design tradeoffs, inventory strategy, and supplier selection. The full report evaluates how material exposure interacts with technology mix and regional sourcing patterns so that teams can assess vulnerability and mitigation options with greater precision.
Functional Safety as a Market Accelerator
Safety certification is no longer a compliance checkbox; in many applications, it is a prerequisite for deployment. Kollmorgen’s SMM 3.0 firmware upgrade illustrates how linear motor motion systems can be configured to achieve SIL 3 certification for functional safety in high-risk applications such as semiconductor manufacturing and material handling. This type of development expands the addressable market in environments where risk tolerance is low and downtime or safety incidents carry significant financial and operational consequences. It also raises the strategic importance of selecting suppliers whose platforms can support certified safety architectures without compromising performance.
Cost, Skills, and Adoption Friction
Despite strong long-term demand, broad adoption of linear motor systems in cost-sensitive facilities remains constrained by high upfront acquisition costs and shortages of skilled technicians capable of specifying, commissioning, and maintaining advanced motion systems. These friction points do not negate the market’s growth trajectory, but they do influence the pace and pattern of adoption. In practice, they favor applications where the return on precision, throughput, or reduced mechanical complexity is easiest to justify, and they make integration support, training, and lifecycle service increasingly important purchase criteria.
Regulatory Framing and System Integration
Regulatory and standards-driven expectations continue to shape product design and system integration. For example, LinMot’s products include a Declaration of Incorporation under the EU Machinery Directive for partly completed machinery incorporated into industrial systems. Such frameworks influence how components are specified, documented, and integrated into larger assemblies, reinforcing the value of suppliers and partners that can provide compliant, traceable, and system-ready solutions.
What the Full Study Delivers for 2026 Decision-Making
The complete PW Consulting linear motors market research report is built for practitioners who need more than high-level narrative. It translates market structure and momentum into an operational reference that can be used across strategy, procurement, engineering, and competitive intelligence functions. Among its core contributions:
Linear Motion Systems Market
- A consistent market size and forecast framework covering 2020 through 2032, giving leadership teams a shared quantitative baseline for planning, budgeting, and scenario analysis.
- Segment-level context across region, type, and application, structured to help identify where demand is strongest, how technology mix is evolving, and which use cases are driving adoption momentum.
- Competitive profiling of key participants, including headquarters location, product orientation, and market positioning, enabling benchmarking of capabilities, differentiation strategies, and likely areas of future competition.
- Integration of recent industry developments, including product launches, firmware and safety-related upgrades, and material and cost dynamics, so that strategic assumptions reflect current operating conditions rather than stale benchmarks.
- Analytical support for practical decisions such as supplier selection, vertical exposure, geographic prioritization, total cost of ownership evaluation, and technology roadmap alignment.
Importantly, the full study goes beyond describing what is happening. It is organized to help decision-makers answer questions that directly affect 2026 execution: which demand drivers are most durable, where performance and compliance requirements are reshaping purchasing criteria, how material and skilled-labor constraints may affect adoption timing, and which competitive approaches are most likely to influence pricing, availability, and system integration complexity over the forecast period.
Why the Complete Dataset Matters Now
The linear motors market is large enough to matter strategically and complex enough to reward disciplined analysis. A 7.25 percent forecast CAGR, a market size trajectory moving from 102.5 million USD in 2025 toward 170.5 million USD by 2032, and a competitive landscape that blends broad-portfolio incumbents with specialized precision suppliers all point to a market where informed choices can create meaningful advantage. Yet the strategic value of these numbers depends on context. The same headline growth rate can imply very different actions depending on technology exposure, application focus, regional demand intensity, and the regulatory or supply-chain pressures affecting a specific business.
That is why the full report is structured to protect analytical rigor while giving executives the granularity they need to act. Rather than leaving teams to infer implications from aggregate figures, the study connects market size, segmentation context, competitive behavior, and operational dynamics in one coherent framework. For organizations evaluating product investments, automation upgrades, sourcing strategies, or competitive positioning in 2026, this integrated view reduces guesswork and improves the quality of strategic judgment.
The complete linear motors market research study is available through PW Consulting’s official report page, where decision-makers can access the full forecast tables, segmentation analysis, competitive profiles, and operational dynamics assessment that underpin the insights summarized here. For teams preparing 2026 plans, the difference between a general market overview and a detailed, decision-ready intelligence package can be the difference between reactive positioning and deliberate strategic advantage.
For detailed analysis of this topic, please visit the official page: Linear Motors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Nanocrystalline Soft Magnetic Material Market to Hit $3.34B by 2032 at 9.2% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Nanocrystalline Soft Magnetic Material Market: A 2026 Executive Briefing
The global transition toward high-efficiency power electronics, next-generation grid infrastructure, and advanced electromagnetic sensing has placed nanocrystalline soft magnetic materials at the center of a critical technological inflection point. As industries accelerate their adoption of high-frequency transformers, compact electric motors, and precision inductive components, material selection has become a decisive competitive variable. Our latest market research, Nanocrystalline Soft Magnetic Material Market, is designed to equip strategic decision-makers with the analytical rigor required to navigate this rapidly evolving landscape through 2026 and beyond.
Drawing on a comprehensive six-year historical baseline and an extended seven-year forecast horizon, the report translates macroeconomic momentum into actionable intelligence. The market has demonstrated consistent expansion, with recorded revenue scaling from approximately 1.15 billion USD in 2020 to 1.8 billion USD by 2025. This trajectory reflects sustained investment in power conversion efficiency, electrification mandates, and the ongoing miniaturization of electromagnetic assemblies. Looking ahead, the forecast period extending to 2032 projects continued upward momentum, anchored by a compound annual growth rate of 9.2 percent. The compounding effect of this growth pathway will reshape supply chain priorities, manufacturing capacity allocation, and technology licensing strategies across multiple industrial verticals.
Worldwide Nano Crystalline Soft Magnetic Materials Market
Market Structure and Strategic Trajectory
Understanding the nanocrystalline soft magnetic materials sector requires more than tracking headline figures. The market operates at the intersection of metallurgy, electromagnetic engineering, and global manufacturing logistics. Nanocrystalline alloys have emerged as preferred solutions in applications demanding low core loss, high permeability, and exceptional saturation characteristics under dynamic operating conditions. Their deployment spans power infrastructure, industrial automation, consumer electronics, and specialized sensing systems. As operational frequencies continue to rise and efficiency standards tighten, legacy magnetic architectures are increasingly being evaluated against nanocrystalline alternatives that deliver superior performance-per-weight ratios and reduced thermal stress under continuous duty cycles.
Nanocrystalline Soft Magnetic Material Market
The structural composition of the market reveals a diversified material ecosystem. Iron-based nanocrystalline alloys currently dominate volume deployment, driven by their established reliability in transformer cores, distribution networks, and high-power conversion modules. Cobalt-based and nickel-based variants occupy more specialized segments where tailored magnetic properties, corrosion resistance, or extreme environmental tolerance are required. This multi-material architecture creates both competitive differentiation and supply chain complexity. Manufacturers must balance metallurgical consistency, scrap recovery rates, annealing cycle optimization, and ribbon thickness tolerances to maintain performance thresholds demanded by end-users. The report dissects these technical and operational variables, mapping how material composition choices influence total cost of ownership, qualification timelines, and long-term reliability in mission-critical deployments.
Competitive Landscape and Enterprise Positioning
The nanocrystalline soft magnetic materials market is characterized by a concentrated yet dynamically evolving competitive field. Our concentration analysis indicates that the top three players command approximately 47.5 percent of documented market revenue, while the top five collectively represent roughly 68.2 percent. This concentration reflects the barriers inherent in primary alloy production, precision ribbon manufacturing, and high-volume core fabrication. Nevertheless, the ecosystem extends well beyond the dominant incumbents, encompassing regional manufacturers, custom fabricators, and specialized assemblers that expand the market’s geographic and application reach.
Proterial, Ltd. remains a foundational reference point in the sector, with its FINEMETnanocrystalline technology and associated core solutions setting long-standing performance benchmarks for high-frequency transformers and power electronic modules. VACUUMSCHMELZE GmbH & Co. KG continues to strengthen its positioning through VITROPERM iron-based nanocrystalline ribbons and tape-wound core designs optimized for low-loss operation and high permeability. Metglas, Inc. maintains a commercially significant footprint by supplying FINEMET-based and FINEMET-compatible ribbons and foils for transformer and power applications, effectively bridging primary material innovation with downstream fabrication requirements.
The competitive periphery is increasingly active. China Amorphous Technology Co., Ltd. has expanded its portfolio across amorphous and nanocrystalline soft magnetic materials, cores, and ribbons for electronic components and transformer applications. Dongguan JH Amorphous Co., Ltd. has carved out a specialized role in custom and OEM nanocrystalline and amorphous soft magnetic cores, rings, and assemblies tailored for power electronics. MK Magnetics, Inc. operates as a focused producer and fabricator of tape-wound nanocrystalline soft magnetic cores, leveraging materials sourced from primary suppliers. Bomatec AG contributes as a supplier and processor of nanocrystalline soft magnetic ribbons, products, and components across diverse magnetic applications. Londerful New Material Technology Corp. has positioned itself as an export-oriented provider, targeting markets including Japan, Korea, and Europe with nanocrystalline soft magnetic materials and components.
These enterprises are not merely competing on volume; they are actively reshaping supply resilience, customization capabilities, and regional manufacturing footprints. The report examines how each player navigates the tension between standardized high-volume production and highly specified OEM requirements, and how their strategic choices influence procurement negotiations, qualification lead times, and end-market responsiveness.
Operational Intelligence and Analytical Scope
Strategic decision-making in this sector requires granular visibility into operational variables that external market summaries typically overlook. Our research is structured to provide a multi-dimensional view of the market, with explicit attention to the mechanics that drive revenue, capacity utilization, and competitive advantage.
- Historical and forecast modeling across the full 2026 to 2032 horizon, with clearly defined assumptions regarding capacity additions, technology adoption curves, and demand elasticity across end-use sectors.
- Material-type segmentation analysis that evaluates performance trade-offs, processing requirements, and application compatibility among iron-based, cobalt-based, nickel-based, and other alloy configurations.
- Application-level evaluation covering transformers, electric motors, inductors, chokes, and magnetic sensors, with emphasis on how performance specifications and procurement cycles differ across each vertical.
- Competitive profiling that extends beyond headline capabilities to include manufacturing positioning, supply chain dependencies, customization readiness, and regional service infrastructure.
- Regulatory and input-cost analysis that traces the impact of raw material economics on production planning, margin structures, and supplier alliance strategies.
- Qualitative scenario framing that connects near-term operational developments with longer-term strategic shifts, enabling leadership teams to stress-test growth assumptions.
A defining feature of this report is its emphasis on practical deployment intelligence. Rather than stopping at aggregate market sizing, the analysis connects technical characteristics to procurement behavior, qualification pathways, and capacity planning. Decision-makers can use the framework to assess whether their current material portfolios align with emerging performance requirements, whether supplier diversification strategies are sufficient to mitigate input volatility, and whether regional expansion or OEM partnership models are likely to yield faster market access in the coming planning cycles.
Industry Dynamics and Near-Term Disruptors
The operational environment for nanocrystalline soft magnetic materials is being shaped by persistent cost pressures and strategic supply chain realignment. Elevated raw material costs for soft magnetic alloys continue to restrain market growth at multiple nodes of the value chain, influencing everything from ribbon pricing to core fabrication economics. In response, leading manufacturers are pursuing structured supplier relationships and forward-looking procurement arrangements to secure critical inputs and stabilize production economics.
Recent developments illustrate this dynamic in practice. VACUUMSCHMELZE GmbH & Co. KG moved to reinforce input security by signing a memorandum of understanding for a strategic alliance designed to secure high-purity rare earth oxides essential for nanocrystalline alloy processing. This action underscores a broader industry pattern: access to high-quality precursor materials is becoming a strategic differentiator, not merely a procurement task. In parallel, Dongguan JH Amorphous Co., Ltd. advanced its capacity and customization capabilities through the mass production launch of a custom nanocrystalline magnetic ring assembly following two years of testing for a leading Italian electronics manufacturer. The company subsequently completed a physical facility expansion to increase output capacity for nanocrystalline and amorphous soft magnetic cores. These moves reflect a wider trend in which regional manufacturers are building credibility through documented qualification cycles, OEM co-development, and incremental capacity deployment.
For enterprise leaders, these dynamics carry clear strategic implications. Companies reliant on single-source material supply face elevated exposure to price volatility and qualification bottlenecks. At the same time, manufacturers that can demonstrate consistent ribbon quality, controlled annealing performance, and repeatable core assembly tolerances are gaining leverage in procurement negotiations. The report contextualizes these pressures within a broader market framework, helping stakeholders distinguish between transient cost fluctuations and structural shifts in supply chain architecture.
Strategic Implications for 2026 Decision-Making
The 2026 planning cycle represents a pivotal moment for organizations operating in or adjacent to the nanocrystalline soft magnetic materials market. Demand expansion is no longer speculative; it is being reinforced by efficiency mandates, frequency-drive adoption, and the ongoing electrification of industrial and commercial systems. At the same time, the competitive field is fragmenting in strategically meaningful ways. Incumbents are reinforcing their primary material advantages while expanding supplier alliances. Regional manufacturers are converting customization capability into OEM credibility. Fabricators and assemblers are positioning themselves as intermediaries between primary ribbon producers and application-specific end users.
Within this environment, strategic questions become sharply defined. How should procurement teams structure material sourcing to balance performance consistency with input-cost volatility? Which application segments offer the fastest qualification pathways for nanocrystalline substitution, and where do legacy designs still maintain cost-performance advantages? How should companies interpret recent capacity expansions and supplier alliances when evaluating long-term supply resilience? And, perhaps most critically, where should organizations allocate internal engineering resources to capture value from high-permeability, low-loss material architectures without overcommitting to premature standardization?
Our report is built to support these decisions by combining market-level trajectory analysis with operational depth. Leadership teams can use the findings to refine capacity planning assumptions, benchmark supplier options against documented capabilities, and align research-and-development priorities with the application segments most likely to drive near-term adoption. The analysis also supports more disciplined evaluation of partnership and co-development opportunities, particularly where OEM qualification cycles and regional service requirements create meaningful barriers to rapid market entry.
Access the Full Strategic Intelligence
The nanocrystalline soft magnetic materials market is expanding along a clear and measurable growth pathway, but the strategic value of this expansion depends on the quality of the intelligence used to navigate it. Aggregate figures provide direction; operational, competitive, and application-level analysis provide execution advantage. Our full study delivers the depth required to convert market momentum into concrete planning decisions, whether the objective is supplier diversification, capacity evaluation, application targeting, or competitive positioning.
To access the complete dataset, segmentation analysis, competitive profiles, and forward-looking scenario frameworks, please refer to the full report page. The detailed intelligence within the study is structured for immediate use by strategy, procurement, engineering, and market-development teams preparing for the 2026 to 2032 planning horizon.
For detailed analysis of this topic, please visit the official page: Nanocrystalline Soft Magnetic Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: IEMS Market Hits $35.2B in 2025, Projected 8.27% CAGR to Reach $61.85B by 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for Industrial Energy Management: Navigating the $61.85 Billion Horizon by 2032
The global industrial landscape is undergoing a fundamental transformation where energy efficiency and operational resilience are no longer peripheral concerns but central pillars of competitive strategy. As we move through the mid-2020s, Industrial Energy Management System (IEMS) solutions have evolved from optional optimization tools into critical infrastructure for manufacturing, heavy industry, and process sectors. PW Consulting has released a comprehensive market research report that provides enterprise decision makers with the analytical rigor required to align capital allocation, technology procurement, and sustainability roadmaps with the realities of the 2026 to 2032 cycle. This publication is designed to deliver foresight rather than static description, equipping executives with the context needed to anticipate regulatory pressure, technological disruption, and competitive realignment across industrial energy ecosystems.
For Chief Operating Officers, Sustainability Directors, Plant Managers, and Strategy Leaders, the value of this analysis lies in its translation of complex market signals into actionable intelligence. Energy costs, carbon compliance obligations, and operational uptime pressures now intersect in ways that demand precise forecasting and disciplined execution. Our research framework addresses these intersecting priorities by examining historical trajectories, forward-looking growth drivers, structural segmentation patterns, and the strategic positioning of incumbent and emerging players. The objective is to equip organizations with the clarity required to make high-stakes decisions with confidence, whether they are evaluating software deployments, hardware modernization programs, or integrated service engagements.
Market Scale, Trajectory, and the Architecture of Industrial Energy Transformation
Between 2020 and 2025, the global IEMS market expanded from approximately 25.0 billion USD to 35.2 billion USD, reflecting a sustained convergence of automation maturity, digital connectivity, and energy cost volatility. This foundational period established the operational baseline for what is now a market poised for acceleration. Our forecast period, spanning 2026 through 2032, projects continued expansion driven by the increasing integration of energy management into core industrial workflows, the push toward decarbonization, and the growing need for real-time performance visibility across geographically distributed operations. By the close of the forecast window, market revenue is projected to reach 61.85 billion USD, representing a compound annual growth rate of 8.27 percent.
These headline figures are more than a statistical summary. They reflect a market in which value creation is shifting from standalone monitoring hardware toward software-driven optimization platforms, integrated service architectures, and ecosystem-enabled control strategies. The growth dynamic is not uniform across all value pools. Instead, it is shaped by the way industrial operators are reconfiguring their capital priorities and operational philosophies. Companies that previously treated energy management as an isolated compliance function are now embedding it into production scheduling, asset maintenance, and supply chain planning. This behavioral shift is broadening the addressable market and elevating the strategic importance of integrated IEMS capabilities.
Our analysis also tracks concentration as a structural signal. The market exhibits a meaningful degree of consolidation among leading participants, with the top three firms accounting for approximately 38.0 percent of aggregate revenue and the top five firms representing roughly 62.0 percent of total market value. This concentration pattern suggests that scale, cross-industry installation experience, and the ability to deliver end-to-end solutions are increasingly important differentiators. At the same time, it leaves room for specialized and innovative entrants to capture differentiated positions through software-first offerings, advanced analytics, and sustainability-focused service models.
Segmentation Signals Without the Noise: Type, Application, and Regional Framing
Effective strategy formulation requires more than aggregate market sizing. It demands an understanding of how value is distributed across technology categories, end-use environments, and geographic operating realities. Our report examines these dimensions in detail while maintaining a strategic focus on what each segment implies for decision makers. Rather than offering a static breakdown, the analysis interprets segmentation as a map of where demand is maturing, where it is accelerating, and where investment logic differs by use case.
In terms of technology form factors, the market is shaped by the interplay of software, hardware, and service components. Hardware remains a significant foundation for industrial energy visibility and control, but the direction of value migration increasingly favors software platforms and service-led implementations that enable continuous optimization rather than one-time deployments. For procurement leaders, this matters because the economic case for IEMS adoption is increasingly tied to lifecycle performance, integration readiness, and the ability to scale analytics across multiple sites. For vendors and partners, it signals the importance of bundling capabilities in ways that align with how industrial customers evaluate risk, payback, and operational continuity.
Application context further differentiates demand dynamics. Industrial energy management requirements vary substantially across sectors because production intensity, process complexity, regulatory exposure, and energy profile all shape the value proposition of an IEMS deployment. Manufacturing operations typically require granular real-time monitoring and production-linked optimization logic. Energy-intensive process industries place greater emphasis on reliability, integration with legacy control environments, and compliance-driven performance tracking. Our research explores how these differing operational realities create distinct buying criteria and informs which solution architectures are most likely to succeed in each setting. Decision makers benefit from this framing because it allows them to map their own operational priorities against market-wide adoption patterns instead of treating the IEMS category as a monolith.
Regional differences add another layer of strategic nuance. Market development is not moving at the same pace everywhere. Some regions are advancing rapidly because of strong industrial automation adoption, supportive policy frameworks, and mature engineering ecosystems, while other regions are shaped by emerging incentive structures, infrastructure modernization needs, and evolving compliance expectations. Our report addresses these geographic variations as strategic context rather than as a rigid geographic scoreboard. The purpose is to help organizations anticipate where deployment conditions are most favorable, where competitive intensity is highest, and where partnership or localization strategies may be required to gain traction.
Competitive Landscape: Incumbents, Specialists, and the Emerging Intensity of Differentiation
The IEMS market is characterized by a diverse competitive field spanning global automation and power management leaders, industrial software specialists, and technology companies bringing networking, analytics, and connectivity capabilities into the energy management domain. This breadth is one of the market's defining features. It means that industrial operators can choose from established platforms with deep process integration heritage, entreprise-grade energy management suites, and increasingly agile entrants focused on software-only optimization, AI-driven control logic, and multi-site energy intelligence.
Global players such as ABB Ltd, Siemens AG, Schneider Electric SE, Emerson Electric Company, General Electric Company, Yokogawa Electric Corporation, Mitsubishi Electric Corporation, Honeywell International Inc., Azbil Corporation, Rockwell Automation, and Eaton Corporation PLC bring broad industrial portfolios and extensive installed bases to the market. Their strength lies in the ability to connect energy management with automation, process control, electrification, and facility operations in a coordinated way. For many industrial customers, this integration is not a convenience but a requirement, especially in environments where energy performance must be managed alongside throughput, safety, and asset reliability.
At the same time, the market includes specialists and newer entrants with sharply defined value propositions. Companies such as EnerNOC, Cisco Systems, Inc., IEM, explitia, Tibo Energy, Prescient Technologies, and MRI Software illustrate the growing influence of application-specific software, IIoT-enabled monitoring, demand-side management capabilities, and analytics-first approaches. These players often compete by reducing deployment friction, accelerating time to insight, or targeting particular operational pain points such as cost control, grid interaction, or multi-facility portfolio visibility.
This competitive mix creates a more dynamic environment for buyers and vendors alike. Industrial organizations are no longer limited to a single procurement model or technology philosophy. They can pursue integrated automation-led platforms, software-centric energy intelligence layers, or hybrid solutions that combine monitoring hardware, analytics, and managed services. The strategic implication is that selection criteria increasingly depend on integration ambition, internal capability, and long-term operating model rather than on product features alone. Vendor consolidation, partnership ecosystems, and solution extensibility are therefore becoming essential considerations in any IEMS investment decision.
Worldwide Power Energy Management System (EMS) Market
Recent Corporate Moves That Reshape Investment Signals
Market intelligence is not abstract when it is anchored in recent corporate behavior. Several developments during 2025 and early 2026 provide useful indicators of where capabilities, priorities, and competitive momentum are heading. Emerson Electric Company's move into a new global headquarters in Clayton, Missouri, in February 2026 is not only an organizational milestone but also a signal of renewed emphasis on industrial automation and IEMS-related capabilities within a major player's operating footprint. Such infrastructure investments often coincide with expanded R&D focus, stronger cross-functional collaboration, and improved delivery capacity for the industrial automation and energy management solutions that underpin market demand.
In May 2025, Tibo Energy completed a funding round of EUR 6 million to expand its AI-based energy management system, with a focus on industrial grid congestion solutions and multi-site optimization. This development is strategically significant because it underscores investor confidence in software-driven, AI-enhanced energy optimization for industrial environments. It also reflects a growing recognition that energy management is increasingly connected to broader grid constraints, site-level load flexibility, and the ability to coordinate optimization across multiple facilities. For competitive analysis, moves like this suggest that advanced analytics and intelligent control are becoming central battlegrounds, especially for organizations seeking differentiation through operational efficiency and cost reduction.
In November 2025, Azbil Corporation relocated its headquarters to the Marunouchi Park Building in Tokyo, reinforcing its commitment to industrial automation and energy management offerings. Relocations of this kind often accompany strategic realignment, talent concentration, and upgraded collaboration environments. While such events do not directly determine market share, they provide context for how established players are reinvesting in their long-term positioning within the IEMS value chain. Documenting these shifts helps buyers and investors assess whether momentum is consolidating around incumbents or whether specialized innovators are gaining the space needed to scale.
Regulatory and Standards Pressure as a Core Demand Driver
A defining feature of the IEMS market is the extent to which policy and standards frameworks shape adoption timing, deployment scope, and solution requirements. Regulatory momentum is not a background condition in this market; it is one of the most direct drivers of commercial activity.
In the European Union, the Energy Efficiency Directive has increased expectations for industrial facilities to implement energy management systems and maintain regular reporting on consumption and efficiency improvements. This creates both a compliance obligation and a strategic incentive to adopt systems that can substantiate measurable performance gains. In the United States, the Energy Policy Act supports energy management practices in industrial settings as part of broader efforts to reduce consumption and advance sustainability goals. Parallel to these national and regional mandates, ISO 50001 remains widely adopted as a structured framework for improving energy performance across industrial operations. Its influence is important because it encourages repeatable measurement, management review, and continuous improvement, all of which reinforce the need for capable IEMS platforms and services.
Industrial Energy Management System (IEMS) Market
Climate policy commitments add another layer of pressure and opportunity. Paris Agreement implementation efforts continue to influence carbon pricing mechanisms, incentive programs, and reporting expectations that affect industrial energy use. Meanwhile, regional code updates, such as the 2025 California Energy Code revisions, illustrate how subnational policy can accelerate demand for mandatory efficiency measures and energy monitoring in industrial contexts. Taken together, these regulatory and standards dynamics mean that IEMS adoption is increasingly tied to risk management, audit readiness, and the ability to demonstrate credible energy performance improvement over time.
What the Report Delivers: Operational Content for Decision Making
A high-quality market study must move beyond descriptive commentary and provide materials that can be used directly in commercial planning, technology evaluation, and competitive assessment. This report is structured to support those practical needs. It combines market sizing, segmentation interpretation, competitive profiling, and regulatory context into a single analytical framework so that readers can see how demand signals, vendor behavior, and policy developments interact.
The report includes detailed profiles of key companies active in the IEMS market, with attention to their specific offering orientation, geographic presence, and strategic relevance. These profiles help readers understand not only who the major participants are, but also what kinds of problems they are positioned to solve. For buyers, this supports more disciplined vendor shortlisting and stronger evaluation criteria. For investors and partners, it provides a clearer picture of where differentiation is emerging and which capability gaps may represent opportunity.
In addition to company profiles, the report examines recent developments that indicate shifting momentum across the competitive field. By connecting corporate moves to broader market logic, the analysis helps readers interpret events such as funding rounds, headquarters transitions, and capability expansions as part of a larger strategic narrative rather than as isolated news items. This approach is especially valuable in a market where competitive positioning can change quickly as software, analytics, and integration models evolve.
How to Use This Intelligence in 2026 Planning Cycles
For executives planning capital expenditure, digital transformation initiatives, or sustainability roadmaps, the most valuable use of this research is as a decision-support instrument rather than a passive reference document. The report is designed to help teams answer several practical questions: Where is demand growth most structurally supported? Which solution archetypes fit different operational and compliance needs? What types of vendors are likely to compete on integration depth versus agility and specialized functionality? How do regulatory expectations influence procurement timelines and evaluation criteria?
The strategic value of the research increases when it is used to stress-test assumptions. For example, organizations evaluating IEMS investments can use the segmentation and competitive analysis to determine whether their preferred path aligns with market-wide adoption patterns or whether they are intentionally pursuing a differentiated niche. Procurement teams can use the company profiles and recent development intelligence to anticipate vendor trajectories and refine negotiation positions. Sustainability and operations leaders can use the regulatory context to align energy management projects with compliance obligations and reporting requirements, strengthening the business case for deployment.
In markets characterized by both consolidation and innovation, clarity about the competitive landscape is a genuine advantage. The fact that the market includes both large-scale integrated players and more specialized innovators means that the best choice is rarely obvious. The report helps decision makers navigate that ambiguity by presenting the landscape as a set of strategic trade-offs rather than a simple vendor ranking. It provides the context needed to decide whether the priority is breadth of integration, speed of deployment, analytics sophistication, service continuity, or a specific combination of these attributes.
Conclusion: A Market Entering a More Discriminating Phase
The Industrial Energy Management System market is entering a phase in which growth is increasingly tied to measurable operational value, integration capability, and alignment with regulatory and sustainability expectations. The projected rise from 35.2 billion USD in 2025 to 61.85 billion USD by 2032, at a compound annual growth rate of 8.27 percent, reflects more than incremental adoption. It reflects a structural shift in how industrial organizations think about energy: as a controllable, monitorable, and optimizable part of operational performance rather than as a fixed overhead cost.
This shift creates both opportunity and complexity. Organizations that approach IEMS investment with strategic discipline will be better positioned to select solutions that scale, integrate, and deliver continuing returns. Those that treat energy management as a purely tactical purchase risk missing the broader value that modern platforms, services, and analytics can provide. PW Consulting's report is intended to reduce that risk by equipping leaders with a thorough, decision-oriented view of the market's size, shape, competitive dynamics, and directional forces.
The full research publication contains the complete segmentation analysis, competitive assessment, regional context, and forward-looking interpretation needed to support 2026 strategy execution and planning through the end of the decade. For organizations seeking to make informed IEMS decisions with confidence, the report offers a structured foundation for action. Detailed data, complete segmentation breakdowns, and the full competitive matrix are available through the source report, where readers can access the comprehensive intelligence required to turn market insight into operational strategy.
For detailed analysis of this topic, please visit the official page: Industrial Energy Management System (IEMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ignition Coil Market to Reach $15.91B by 2032, Expanding at 4.4% CAGR
By pmarketresearch, 2026-09-15
Ignition Coil Market Strategic Outlook 2026: Navigating Growth, Supply Chain Pressures, and Competitive Evolution
Executive Summary
The global ignition coil market stands at a pivotal juncture as aftermarket demand, OEM electrification pathways, and tightening emission mandates reshape component specifications. PW Consulting's latest research confirms a robust trajectory with a base-year valuation of USD 11.77 billion in 2025 and a projected climb to USD 15.91 billion by 2032. This growth is anchored by a steady compound annual growth rate of 4.4% across the 2026 to 2032 forecast window, reflecting sustained automotive production, vehicle parc replacement cycles, and regulatory-driven performance upgrades. For strategic planners, procurement leaders, and category managers, these figures are more than macroeconomic indicators—they are decision anchors that must be paired with granular segmentation, regional allocation, and competitive intelligence to unlock actionable foresight. This article previews the structural insights embedded in our full report while demonstrating why deeper data is essential for 2026 planning cycles.
Market Trajectory and Strategic Implications
The market's historical arc from 2020 through 2025 reveals a resilient expansion despite intermittent supply disruptions and macroeconomic volatility. Starting at USD 9.49 billion in 2020, the sector progressed through incremental but meaningful gains, crossing the USD 10 billion threshold by 2022 and sustaining momentum into 2025. The transition from 2024 to 2025 alone underscores how steady vehicle assembly rates, combined with aftermarket replenishment cycles, continue to support revenue expansion. Looking forward, the forecast period through 2032 signals a market that will not merely grow but evolve in composition. Demand patterns will increasingly favor coil architectures optimized for combustion stability, emission compliance, and integration with advanced engine management systems. This means that volume growth will be accompanied by specification upgrades, testing requirements, and material sourcing constraints that demand proactive supply chain redesign.
Strategic decision-makers must recognize that headline valuations obscure the operational realities of regional demand intensity, application-specific replacement cycles, and type-driven performance premiums. A market expanding toward USD 15.91 billion over the forecast horizon will not reward generic sourcing strategies or static inventory assumptions. Instead, it will favor organizations that can align production planning with coil architecture trends, anticipate copper-dependent cost pressures, and position themselves within the shifting competitive hierarchy. Our full report dissects these layers with precision, enabling readers to move from aggregate awareness to targeted action.
Structural Dynamics Shaping the 2026 Landscape
Several converging forces are redefining how ignition coils are specified, manufactured, and deployed across vehicle platforms. Among the most consequential is the regulatory environment. Recent emission standards now require ignition systems to reduce emissions by up to 30%, directly elevating the importance of precise spark timing, stable combustion, and high-voltage delivery consistency. This regulatory pressure does not merely influence engineering priorities; it redraws the competitive baseline, favoring suppliers capable of delivering coils that meet stringent performance thresholds without compromising durability.
Simultaneously, material and trade dynamics are introducing new cost and risk variables. Copper has been designated as a critical mineral, with high-purity copper windings essential to ignition coil manufacturing triggering supply chain constraints. Adjusted Section 232 tariffs on imported copper articles have further impacted component costs, particularly for assemblies relying on copper wire and iron cores. These factors are not isolated price fluctuations; they represent structural pressures that influence sourcing geography, inventory buffers, and supplier diversification strategies. In parallel, updated standards such as ISO 6518-1:2025 are formalizing testing and performance expectations for single-ended and other road-vehicle ignition coil types, reinforcing the need for certified design validation and consistent quality assurance across production lines.
Fan Coils Market
Together, these dynamics create a market in which technical compliance, material resilience, and certification readiness are as critical as unit cost. Organizations that treat regulation and raw-material volatility as peripheral concerns will face margin erosion and qualification delays. Those that integrate these variables into their roadmap will secure more predictable supply, stronger OEM and aftermarket positioning, and greater readiness for next-generation specification shifts.
Competitive Landscape: Pioneers and Differentiators
The ignition coil market is defined by a concentrated yet diversified competitive field. The top three players account for 48% of market share, while the top five collectively command 55%, signaling meaningful consolidation around established technical capabilities, global distribution networks, and long-standing OEM relationships. Yet concentration does not imply uniformity. Each leading participant brings a distinct value proposition that shapes how the market segments, prices, and innovates.
Denso Corporation continues to anchor its offering in high-precision ignition coils designed for global vehicle manufacturers, with advanced designs aimed at improved combustion efficiency and emission compliance. Robert Bosch GmbH differentiates through high-performance coils integrated into broader vehicle electrical systems, supporting precise spark timing and fuel efficiency across passenger cars and commercial vehicles. Niterra North America, Inc., under the NGK brand, emphasizes aftermarket ignition coils that meet or exceed original equipment specifications, backed by extensive vehicle-in-operation coverage and rigorous testing for heat, vibration, and electrical stress. BorgWarner Inc. brings specialized focus to diesel cold-start ignition coils engineered for reliable starting and reduced emissions in both heavy-duty and light-duty applications.
Beyond these global anchors, regional and specialized players add depth and responsiveness to the competitive ecosystem. Diamond Electric Mfg. Corp. supplies automotive ignition coils and electronic control devices to global OEM customers including Ford, Dodge, and Subaru, leveraging manufacturing operations across Japan and the United States. Hitachi Ltd. positions automotive ignition coils within powertrain systems, emphasizing durability and integration with advanced engine management. Standard Motor Products, Inc. offers aftermarket and OEM ignition coils with full line coverage, engineered for performance and emissions control in independent aftermarket applications. Nissens Automotive manufactures aftermarket ignition coils in ISO and IATF 16949-certified facilities, delivering reliable solutions tailored to today's vehicle parc with enhanced performance. Walker Products, Inc. provides ThunderSpark ignition coils engineered for precise high-voltage pulses that meet OEM performance standards. Taiwan Ignition System Co., Ltd. supplies high-quality aftermarket coils, including pencil and block types, meeting vehicle amperage and voltage requirements under ISO 9001 and IATF 16949 certification. Wells Vehicle Electronics delivers aftermarket coils with full coverage for major vehicle makes, supporting emission compliance and engine performance. SMP Corporation aligns OEM and aftermarket ignition coils with emission standards, supporting global independent aftermarket sourcing and engineering.
Recent activity illustrates how these players are translating technical strengths into market momentum. In December 2025, Nissens Automotive partnered with Standard Motor Products to launch its ignition coil line, adding system-critical components for engine performance and emissions control to the aftermarket portfolio. In May 2026, Nissens hosted a global press event in Białystok, Poland, combining factory visits, technical sessions on design, testing, and manufacturing, and hands-on racing activities to showcase a new ignition coil range to European media. These developments highlight a broader pattern: competition is intensifying not only through volume and coverage but through demonstrable engineering credibility, certification transparency, and strategic channel partnerships. For procurement and strategy teams, this means supplier evaluation must extend beyond price and availability to encompass testing rigor, compliance alignment, and future-proof architecture roadmaps.
What the Full Report Delivers for 2026 Decision-Making
The complete PW Consulting research is designed to convert market awareness into executable strategy. Rather than stopping at aggregate trends, the report provides a structured operational framework that helps teams plan, source, and position with confidence across the 2026 to 2032 horizon. The analysis is built around actionable lenses that matter in day-to-day decisions:
- How market revenue is distributed across regions and what that implies for sourcing geography, logistics planning, and regional pricing strategy
- How ignition coil types compare in demand intensity and specification trajectory, including coil-on-plug architectures, distributor-based configurations, distributor-less systems, and other emerging formats
- Where passenger car and commercial vehicle applications diverge in replacement cycles, performance requirements, and margin profiles
- Which competitive capabilities are becoming table stakes for OEM qualification and aftermarket credibility, from emissions-aligned design to certified manufacturing and testing protocols
- How raw-material criticalness, tariff exposure, and regulatory updates should be integrated into supplier selection, inventory buffers, and cost forecasting models
Each of these areas is supported by detailed segmentation, comparative benchmarks, and forward-looking scenario framing. The objective is not to provide a static snapshot but to equip decision-makers with a data-rich map of where value is concentrated, where risk is emerging, and where strategic investments can create durable advantage. Because the market's trajectory is influenced by overlapping technical, regulatory, and supply-chain variables, the full report connects the dots across segmentation, company strategy, and macro-environment shifts—creating a single reference point for cross-functional planning.
Ignition Coil Market
Why Deeper Intelligence Matters Now
A CAGR of 4.4% and a market moving toward USD 15.91 billion by 2032 tell an encouraging story, but aggregate data cannot answer the questions that shape competitive outcomes in 2026. Which regions will absorb the bulk of incremental demand? Which coil types will capture specification upgrades driven by emission compliance? How should organizations balance copper exposure, tariff adjustments, and localization pressure without compromising responsiveness? Where do the strongest competitive differentiators lie within a field that is both concentrated and highly specialized? The answers to these questions determine sourcing resilience, pricing power, and market-access timing.
The preview above illustrates the structural logic of the market and the competitive forces at play. To move from indication to implementation, organizations need the underlying segmentation values, regional allocations, type-level demand splits, vehicle-type comparisons, and company-specific positioning that our full report details. These insights are deliberately developed to support precise decisions rather than broad assumptions. For teams preparing annual operating plans, supplier negotiations, product-portfolio updates, or capacity strategies, the complete intelligence offers the resolution required to act with confidence.
Conclusion
The ignition coil market is expanding with disciplined momentum, but its real significance lies in the structural shifts beneath the headline growth. Emission-driven performance requirements, copper criticalness, tariff adjustments, and formal testing standards are reshaping how coils are engineered, qualified, and sourced. At the same time, competitive intensity is rising through technical differentiation, certification transparency, and strategic channel partnerships. PW Consulting's full market research translates these forces into a coherent, decision-ready framework for the 2026 planning cycle and beyond. To access the complete segmentation, competitive analysis, and forward-looking scenario detail that support high-stakes strategic choices, we invite you to explore the full report and secure the intelligence your organization needs to act decisively.
For detailed analysis of this topic, please visit the official page: Ignition Coil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microbial Air Samplers Market Reaches $222.97M by 2032 at 5% CAGR
By pmarketresearch, 2026-09-15
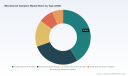
Strategic Air Quality Intelligence: Navigating the Microbial Air Samplers Market in 2026 and Beyond
In an era where environmental sterility directly correlates with product safety, regulatory compliance, and operational continuity, the microbial air samplers market has evolved from a niche monitoring tool into a critical pillar of quality assurance infrastructure. For executives, compliance leaders, and strategic planners operating across pharmaceuticals, food and beverage, healthcare, and advanced research environments, understanding the trajectory of this market is no longer optional—it is a strategic imperative.
This article introduces PW Consulting’s flagship market research on the Microbial Air Samplers Market, a comprehensive analytical report designed to equip decision-makers with actionable intelligence for the 2026 planning cycle and the decade ahead. Rather than presenting a superficial overview, this study dissects the structural dynamics, competitive pressures, and technological inflection points that will shape procurement strategies, capacity investments, and risk mitigation frameworks in the coming years.
Market Trajectory and the 2026 Inflection Point
The microbial air samplers market has demonstrated steady, compounding growth over the past half-decade, with historical revenue climbing from approximately 127.36 million USD in 2020 to an estimated 158.5 million USD in 2025. Forecasts indicate a continuation of this upward trajectory, positioning the market at roughly 163.75 million USD in 2026 before expanding toward 222.97 million USD by 2032. This progression translates to a compound annual growth rate of 5.0 percent across the 2026 to 2032 forecast window, a pace that reflects sustained demand for reliable environmental monitoring rather than speculative market hype.
For corporate strategists, a 5.0 percent CAGR in a highly regulated, technically specialized equipment segment carries distinct implications. It signals predictable demand expansion, but also intensifying competition for market share, evolving compliance expectations, and the need for procurement frameworks that balance capital efficiency with technological obsolescence risk. The 2026 planning year sits precisely at the intersection of post-pandemic operational normalization and the tightening of sterile manufacturing standards, making this the ideal moment to recalibrate equipment portfolios and vendor relationships.
Report Scope and Operational Deliverables
PW Consulting’s Microbial Air Samplers Market research is structured around operational utility. The report moves beyond macro-level projections to deliver granular, decision-ready insights across multiple analytical dimensions. Key components include:
- A thorough segmentation analysis covering equipment form factors and operational typologies, enabling buyers and manufacturers to map capacity requirements against specific monitoring use cases.
- Cross-industry application mapping that identifies where monitoring demand is most concentrated, how procurement cycles vary by sector, and which operational pain points are driving equipment adoption.
- Regional demand profiling that highlights where regulatory maturity, manufacturing density, and infrastructure investment are shaping localized market conditions.
- Supply-side competitive analysis that evaluates manufacturer positioning, product differentiation strategies, and channel dynamics across established and emerging players.
- Regulatory and technical compliance mapping that connects equipment specifications to prevailing environmental monitoring standards, decontamination protocols, and data integrity mandates.
- Historical performance benchmarks and forward-looking scenario modeling to support budget forecasting, capacity planning, and risk assessment.
Each section is designed to translate market data into procurement logic. Whether the objective is to evaluate replacement cycles for existing monitoring fleets, assess entry opportunities in underrepresented geographies, or benchmark vendor capabilities against evolving cleanroom requirements, the report provides the structural context needed to move from assumption to evidence-based planning.
Active Air Sampler Market
Competitive Landscape: Who Shapes the Market and How
The microbial air samplers sector is characterized by a moderately concentrated competitive environment, with the top three players collectively commanding roughly 25.8 percent of market revenue and the top five extending that footprint to approximately 31.2 percent. This concentration level indicates that while scale advantages and brand recognition matter, the market remains sufficiently fragmented to reward manufacturers that excel in niche engineering, compliance alignment, and service ecosystem integration.
Several companies have established recognizable positions through specialized product architectures and targeted industry focus. Climet Instruments Company, based in Redlands, California, has built its reputation around high-quality cleanroom environmental monitoring equipment, with offerings such as the CI-97 Intelligent Microbial Air Sampler and the CI-x70 series reflecting a focus on precision and operational reliability. Particle Measuring Systems, headquartered in Niwot, Colorado, provides contamination monitoring and control solutions that include remote and active microbial air samplers like the MiniCapt® Pro and MiniCapt® Mobile, which are frequently deployed in pharmaceutical and semiconductor cleanroom environments where continuous oversight and data traceability are essential.
Sartorius AG, operating from Göttingen, Germany, supplies microbial air monitoring solutions with particular emphasis on the MD8 Airscan® and portable AirPort MD8 Air Samplers, targeting continuous, intervention-free environmental monitoring in Grade A pharmaceutical settings. MBV AG, based in Stäfa, Switzerland, has developed and manufactured the MAS-100 Sirius®, MAS-100 NT®, and related MAS-100 portable microbial air samplers, marketed globally across pharmaceutical, food, and medical device applications. bioMérieux S.A., from Marcy-l'Étoile, France, contributes the AIR IDEAL® 3P active air sampler for viable organism detection in cleanrooms, isolators, and aseptic manufacturing contexts. Merck KGaA, headquartered in Darmstadt, Germany, functions as a global distributor and provider of MAS-100 microbial air monitoring systems manufactured by MBV, extending reach across pharmaceutical, biopharmaceutical, food, and medical device industries.
Additional contributors shape the competitive texture of the market. Lighthouse Worldwide Solutions, located in Newport Beach, California, supplies ActiveCount and other viable air monitoring systems for pharmaceutical and hospital cleanrooms. aquaria srl, based in Lacchiarella, Italy, manufactures high-flow rate and isokinetic microbial air samplers, including the MICROFLOW series for environmental and workplace monitoring. EMTEK LLC, in Longmont, Colorado, produces the P100 portable microbial air samplers for the detection of bacteria and mold in cleanroom and critical environments. Together, these players illustrate a market where differentiation is driven not only by volume, but by engineering specificity, regulatory alignment, and the ability to serve diverse monitoring requirements across sectors.
Recents Developments and Innovation Signals
Competitive positioning in this market is increasingly defined by product evolution and the pace of innovation. In January 2025, MBV AG introduced the MAS-100 Sirius® as the new benchmark for smart microbial air sampling, emphasizing features such as a magnetic perforated lid, smart functions, maximum process safety, minimal secondary contamination risk, and 100 percent data integrity. This launch reflects a broader industry shift toward instruments that reduce operator-dependent variability and strengthen traceability. By December 2025, MBV AG released its annual review and updated product catalog, highlighting ongoing innovation within the MAS-100 series for pharmaceutical cleanrooms and related industries.
These developments matter because they signal how vendors are responding to the operational realities of modern sterile environments. Smart functionality, contamination control during sampling, and data integrity are no longer optional enhancements; they are becoming baseline expectations for organizations operating under heightened regulatory scrutiny and internal quality governance. For procurement teams, tracking this innovation cadence is essential when evaluating whether existing equipment is approaching functional obsolescence or whether emerging alternatives offer meaningful improvements in workflow efficiency and compliance assurance.
Market Dynamics: Regulation, Sterilization, and Operational Realities
The structural dynamics of the microbial air samplers market are heavily influenced by regulatory and technical requirements that govern how environmental monitoring is conducted in critical settings. Instruments must align with EU-GMP Annex 1, ISO 14698, EN 17141, FDA Aseptic Guidance, and USP <1116> for environmental monitoring in Grade A and B cleanrooms. Compliance with these frameworks shapes not only product design, but also procurement criteria, validation workflows, and ongoing audit readiness.
Sterilization constraints further define equipment performance expectations. Sampling heads and flow paths are increasingly specified to be fully VHP-compatible and constructed from electropolished stainless steel to enable complete decontamination between uses. This requirement directly affects instrument durability, cleaning cycle compatibility, and the operational burden associated with changeover and cross-contamination prevention. In parallel, the use of gamma-sterilized gelatin membrane filters with isokinetic samplers has become relevant for applications demanding extended shelf life and HEPA-like retention rates, with performance benchmarked at 99.995 percent for Bacillus subtilis spores. Such specifications are critical for organizations that must balance monitoring sensitivity with supply chain predictability and material cost considerations.
Data integrity has also emerged as a decisive dynamic in the market. Remote samplers designed for continuous monitoring can support compliance with 21 CFR Part 11 data integrity requirements for pharmaceutical production, making connectivity, audit trails, and electronic recordkeeping central considerations in equipment selection. Beyond manufacturing, the broader operational context includes hospital and surgical suite applications, where routine viable air monitoring supports efforts to reduce healthcare-associated infections in alignment with USP <1116> and ISO 14698 standards. These cross-sector use cases illustrate that microbial air sampling is no longer confined to a single operational archetype; it is a flexible capability that must adapt to varying risk profiles, compliance regimes, and monitoring frequencies.
Strategic Implications for 2026 Decision-Making
For organizations planning their 2026 capital allocation and environmental monitoring strategies, the market research offers several practical implications. First, the steady growth trajectory suggests that demand for microbial air samplers will remain resilient, but the composition of demand will continue to shift as regulatory emphasis evolves and monitoring technologies mature. This means procurement strategies should account for not only unit volume, but also the functional requirements that are becoming more discriminating across cleanroom classes, production workflows, and sector-specific compliance obligations.
Second, the competitive landscape indicates that vendor selection should extend beyond headline specifications. Differences in sterilization compatibility, data integrity support, smart functionality, and service integration can materially affect total cost of ownership and operational risk. In a market where the top five firms collectively hold just over 31 percent of revenue, buyers have genuine alternatives, but they must evaluate those alternatives against real-world deployment conditions rather than marketing claims alone.
Third, the regulatory environment continues to raise the floor for acceptable performance. Instruments that cannot meet expectations for decontamination, documentation, and monitoring continuity will face increasing pressure as audit scrutiny intensifies and internal quality systems tighten. For manufacturers, this reinforces the importance of engineering for compliance durability; for buyers, it underscores the value of selecting equipment that aligns with both current mandates and anticipated regulatory drift.
Finally, regional demand patterns and application mix variations create opportunities for targeted market participation. Organizations with the ability to match equipment capabilities to localized regulatory maturity, manufacturing density, and sector-specific monitoring needs are better positioned to capture value than those relying on one-size-fits-all assumptions. The research provides the contextual framework to identify where demand is forming, how it is likely to evolve, and what type of equipment positioning will resonate in each context.
Why This Research Matters for Your Next Move
Market intelligence is most valuable when it reduces uncertainty without oversimplifying complexity. PW Consulting’s Microbial Air Samplers Market report is built around that principle. It combines historical grounding, forecast visibility, competitive mapping, and regulatory context into a single structured reference that can inform budgeting, vendor evaluation, product development, and market entry decisions. Rather than presenting isolated statistics, the study links market size, growth dynamics, segmentation behavior, and competitive responses into a coherent narrative that helps leadership teams anticipate change instead of merely reacting to it.
For executives who need to align environmental monitoring strategy with broader quality, compliance, and operational goals, this research offers a disciplined foundation for discussion. It clarifies where the market stands, how competitive forces are organizing, and which technical and regulatory drivers will shape purchasing behavior through 2032. More importantly, it creates a shared analytical baseline that enables cross-functional teams to make coordinated decisions rather than fragmented assumptions.
To access the full segmentation detail, regional demand profiles, application-level breakdowns, and complete competitive assessments, we invite you to view the complete report on the PW Consulting source page. The comprehensive analysis provides the depth required to convert high-level market awareness into precise strategic action, ensuring that your 2026 planning is grounded in evidence, not extrapolation.
Microbial Air Samplers Market
For detailed analysis of this topic, please visit the official page: Microbial Air Samplers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Streetwear With a Recognizable Identity
The Travis Scott Merch Shop has developed a visual identity that is difficult to mistake for ordinary streetwear. Its combination of bold artwork, oversized shapes, athletic references, and Cactus Jack branding gives each collection a distinctive character. Fans are not simply buying clothing; they are adding pieces that represent a recognizable approach to contemporary fashion.
The current official Cactus Jack x Nike lineup demonstrates how broad that approach has become. It includes heavyweight hoodies, tees, sweatpants, crewnecks, quarter zips, rugby shirts, windbreakers, tennis shorts, and hats.
Hoodies Remain at the Center
A Travis Scott hoodie is arguably one of the most recognizable ways to embrace the aesthetic. Oversized proportions give the garment a strong streetwear shape, while artwork and branding make it visually distinctive. travis scott merch
Hoodies also offer endless styling possibilities. Wear one with loose jeans for a relaxed outfit or pair it with baggy cargos for a more aggressive streetwear look. Add a jacket over the top when you want to create a layered silhouette.
The Cactus Jack Hoodie Is a Classic
The Cactus Jack hoodie continues to appeal because it combines recognizable branding with everyday practicality. Hoodies naturally fit into casual wardrobes, so a strong design can be worn repeatedly without feeling out of place.
Try pairing one with neutral pants so the hoodie remains the main focus. Black cargos, washed denim, or charcoal trousers can all create a strong foundation. Finish the outfit with sneakers that complement the overall proportions.
Heavyweight Tees Are More Than Basics
A good graphic tee can become the foundation of an entire outfit. Heavyweight construction gives tees more structure, while detailed artwork adds visual interest. They can also be worn throughout the year because they work equally well alone or underneath layers.
The current Court Logo Tee uses heavyweight cotton and combines front applique embroidery with puff-printed artwork on the back. These details demonstrate how simple silhouettes can become more distinctive through texture and artwork.
Sweatpants Have Become Streetwear Staples
Sweatpants are no longer reserved for relaxing at home. In modern streetwear, they can form the base of complete outfits when paired with the right tops and sneakers. Baggy silhouettes especially complement oversized hoodies and crewnecks.
The Cactus Court Sweatpants use heavyweight cotton and a baggy fit, with embroidered Cactus Jack x Nike artwork and contrast piping. Pair them with a matching top for a coordinated appearance or contrast them with a graphic tee.
Crewnecks Bring Texture
Crewnecks provide an alternative to hoodies while maintaining a relaxed streetwear shape. They are also useful for layering because there is no hood competing with a jacket or coat.
The Reverse Swoosh Crewneck features heavyweight cotton, faded spray treatment, puff-printed Cactus Jack x Nike artwork, and screen-print detailing. The official shop notes that the freehand spray process can make individual pieces vary naturally.
That variation adds personality and makes the garment feel less uniform.
Sporty Influences Are Growing
One of the most interesting directions in current Travis Scott fashion is the use of athletic-inspired silhouettes. Quarter zips, rugby shirts, tennis shorts, and windbreakers bring sportswear into the streetwear conversation.
This creates more styling possibilities than traditional hoodies and tees alone. A quarter zip can create a sporty layered look, while tennis shorts can bring a lighter summer feel. These pieces help the wardrobe feel more versatile.
Windbreakers Create Lightweight Layers
A windbreaker is ideal when you want outerwear without the weight of a traditional jacket. It can be worn over graphic tees, hoodies, or crewnecks depending on the weather.
The Cactus Court Zip Windbreaker features lightweight polyester, a baggy fit, embroidered logos, and printed Cactus Jack x Nike graphic details. Its relaxed shape makes it particularly easy to pair with wide-leg pants or sweatpants.
Rugby Shirts Make Outfits More Interesting
The 713 Rugby Longsleeve offers another way to build a distinctive streetwear outfit. Its heavyweight cotton construction and extensive graphic detailing give it a stronger presence than a standard long-sleeve tee.
Style it with relaxed denim and sneakers for a casual look. For additional layering, place an oversized jacket over the top. This combination works especially well when you want something different from the traditional hoodie formula.
Utopia Merch Adds Artistic Energy
Utopia merch remains an important part of the Travis Scott fashion conversation because it connects clothing with a strong creative era. Graphic-heavy pieces can become instant focal points in a wardrobe.
Instead of combining several loud graphics, choose one Utopia-inspired item and build around it. Neutral pants and understated sneakers create enough contrast to let the artwork stand out.
Building a Signature Wardrobe
A strong Travis Scott-inspired wardrobe does not need dozens of pieces. Start with a reliable hoodie, two or three graphic tees, relaxed pants, a crewneck, and versatile sneakers. From there, add outerwear and accessories according to your personal style.
The goal is to create combinations rather than collect random pieces. A hoodie should work with several pairs of pants. A graphic tee should be useful both alone and as a base layer. This makes the wardrobe more practical.
Final Thoughts
The Travis Scott Merch Shop continues to define a particular side of modern streetwear through oversized fits, expressive artwork, heavyweight fabrics, and athletic influences. The Travis Scott hoodie , Cactus Jack hoodie , graphic tees, sweatpants, crewnecks, rugby shirts, and windbreakers all offer different ways to build that aesthetic.
What makes these pieces stand out is their ability to feel both recognizable and wearable. You can embrace the full streetwear look or simply introduce one statement piece into an otherwise simple wardrobe. Either way, the result can feel confident, creative, and distinctly Travis Scott.
PW Consulting: DNS Security Software Market to Hit $310M by 2032 at 8.9% CAGR
By pmarketresearch, 2026-09-15
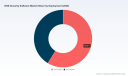
Navigating the DNS Security Revolution: Strategic Intelligence for the 2026 Enterprise Landscape
The digital perimeter has dissolved. In an era where hybrid workforces, cloud-native architectures, and interconnected critical infrastructure define operational reality, the Domain Name System (DNS) has evolved from a simple directory service into a primary battlefield for cyber adversaries. As organizations confront increasingly sophisticated threats that exploit DNS for data exfiltration, command-and-control communication, and distributed denial-of-service campaigns, the imperative for robust DNS security software has never been more acute. This strategic briefing introduces our latest comprehensive market research on the DNS Security Software sector, a publication engineered specifically to equip executive leadership, security architects, and investment strategists with the foresight required to navigate 2026 and beyond.
Our analytical framework draws upon a multi-year trajectory of observable market expansion. Between 2020 and 2025, the global DNS security software market demonstrated consistent upward momentum, reflecting the accelerated digital transformation initiatives and the escalating frequency of DNS-layer attacks across all sectors. By the close of 2025, the market had reached a mature inflection point, with total revenues positioning the industry for a structured, high-growth forecast period spanning 2026 through 2032. Market modeling indicates a compound annual growth rate of approximately 8.9 percent across this horizon, driven by the convergence of regulatory mandates, cloud migration imperatives, and the integration of artificial intelligence into threat detection workflows. This trajectory is not merely a statistical projection; it represents a structural realignment in how enterprises deploy, fund, and operationalize domain-layer security controls.
For decision-makers evaluating technology portfolios in 2026, this research functions as a strategic compass. It dissects the forces shaping procurement priorities, identifies the architectural paradigms gaining traction, and contextualizes the competitive maneuvers that will define market leadership in the coming years. The following sections outline the scope of the publication and the operational intelligence it delivers to stakeholders seeking to align security investments with organizational resilience objectives.
The Strategic Imperative: Why DNS Security Demands Executive Attention in 2026
DNS remains the foundational protocol that enables network communication, yet it has historically been treated as a utility rather than a security control. That paradigm is rapidly eroding. Adversaries now weaponize DNS to bypass traditional perimeter defenses, leveraging encrypted tunnels, fast-flux techniques, and domain generation algorithms to maintain persistent access while evading signature-based detection. The growing reliance on cloud-hosted workloads and distributed endpoints further amplifies the attack surface, making DNS-layer visibility and policy enforcement a non-negotiable component of modern security architectures.
Simultaneously, the regulatory environment is tightening around DNS infrastructure. Procurement guidelines now increasingly require encrypted DNS protocols for federal and critical infrastructure engagements, signaling a shift from voluntary adoption to compliance-driven deployment. In parallel, cybersecurity agencies and international policy frameworks are emphasizing the need for AI-enabled DNS analytics to counter adaptive threat behaviors. Organizations operating across North America, Europe, and Asia Pacific are responding by retooling their security stacks, prioritizing solutions that can provide real-time threat intelligence, automated remediation, and unified visibility across hybrid environments. These shifts create both urgency and opportunity for enterprises willing to invest in forward-looking DNS security capabilities.
Market Architecture and Momentum: A High-Level View of the 2026–2032 Outlook
Our research models the DNS security software market as a dynamic ecosystem shaped by deployment preferences, organizational scale, and industry-specific risk profiles. Over the forecast period, cloud-based delivery models are positioned to dominate adoption curves, reflecting the broader industry migration toward scalable, subscription-driven security services. At the same time, on-premises deployments continue to hold strategic relevance for organizations with stringent data sovereignty requirements or legacy infrastructure dependencies. The interplay between these deployment pathways will influence vendor positioning, service design, and integration strategies throughout the forecast window.
Adoption patterns also diverge across organization size and vertical exposure. Large enterprises are expected to drive a substantial portion of total spending, reflecting their complex infrastructure footprints, compliance obligations, and higher tolerance for integrated security platforms. Small and medium-sized enterprises, meanwhile, are accelerating their investment cycles as managed service providers and simplified cloud offerings lower the barrier to entry. In terms of vertical exposure, sectors that handle sensitive data or operate mission-critical network environments—such as financial services, healthcare, and government—are likely to sustain elevated investment levels, reinforced by sector-specific threat landscapes and regulatory expectations. The full report unpacks these structural drivers in greater detail, offering qualitative and quantitative analysis that maps adoption trajectories to operational outcomes.
Inside the Report: Actionable Intelligence for Technology, Procurement, and Investment Decisions
This market research publication is designed to move beyond high-level market sizing and deliver practical decision support. The report is structured to provide clear visibility into the forces shaping vendor selection, architecture planning, and long-term budget allocation. Key components include:
DNS Security Software Market
- Market Sizing and Forecast Modeling – A multi-year revenue trajectory analysis covering historical performance and projected growth through 2032, contextualized by macroeconomic indicators, threat trends, and adoption drivers.
- Deployment and Operational Patterns – An assessment of cloud-based versus on-premises adoption dynamics, including the operational implications of hybrid DNS architectures, integration requirements, and total cost of ownership considerations.
- Organizational and Vertical Demand Profiles – An examination of how spending behavior differs across enterprise scale and industry context, helping readers benchmark internal priorities against broader market demand signals.
- Competitive Positioning and Product Differentiation – A detailed review of leading vendors, their strategic capabilities, and the evolving product features that are reshaping buyer expectations in the DNS security category.
- Regulatory and Policy Impact Analysis – A synthesis of recent mandates and guidelines influencing DNS procurement, encryption requirements, and AI-enabled security expectations, with implications for compliance-driven buying cycles.
- Deployment Readiness and Implementation Considerations – Practical guidance on evaluating solution fit, integration complexity, visibility requirements, and remediation workflows for real-world enterprise environments.
By aligning these analytical dimensions, the report enables technology leaders to assess capability gaps, procurement teams to structure evaluation criteria, and investors to understand where durable competitive advantages are likely to emerge.
Competitive Dynamics: The Vendors Reshaping DNS Security Strategy
The market landscape is defined by a concentrated group of established vendors, each pursuing distinct strategic angles within the DNS security category. Market concentration metrics suggest a competitive arena where the top tier collectively commands a meaningful share of overall revenue, while the remaining addressable space continues to invite differentiation through innovation, partnerships, and domain-specific solutions.
Cisco Systems anchors its offering in cloud-delivered DNS-layer security integrated with threat intelligence capabilities, positioning its platform as a proactive defense mechanism that blocks malicious activity before a connection is established. Infoblox emphasizes protective DNS and threat defense designed to safeguard core DNS infrastructure from hijacking attempts, cache poisoning, and denial-of-service disruptions. Cloudflare has expanded its footprint through DNS firewall functionality and resolver services that incorporate built-in DDoS mitigation, DNSSEC support, and malware blocking for both enterprise and consumer environments. Akamai Technologies continues to leverage its edge network strength with DDoS-resilient DNS delivery and posture management capabilities for hybrid cloud security. F5 Networks, Verisign, and Neustar contribute additional depth to the competitive field, offering advanced DNS security, load balancing, authoritative DNS services, and threat intelligence features tailored to enterprise and critical infrastructure use cases.
Competitive differentiation is increasingly shaped by agility, visibility, and ecosystem alignment. A recent product development from Akamai illustrates this trajectory: the introduction of DNS Posture Management, an agentless solution designed to deliver unified multicloud visibility over DNS assets with real-time monitoring and remediation capabilities. Alongside such product movements, partnership activity is also reshaping go-to-market dynamics. In a notable collaboration, IGIT partnered with NS1 and Cisco to accelerate agile DNS security application deployments focused on the EMEA region. These developments highlight how vendors are expanding beyond baseline DNS protection to deliver broader operational resilience, cross-cloud oversight, and regionally targeted implementation strategies.
Regulatory Currents and Industry Shifts Redefining the DNS Security Agenda
Beyond competitive activity, the DNS security market is being reshaped by policy evolution and operational standards that influence how organizations validate and procure security capabilities. Recent regulatory and guidance developments are pushing enterprises toward more resilient, encrypted, and intelligence-driven DNS practices. The U.S. Executive Order requiring support for encrypted DNS protocols as a procurement condition for federal agency DNS resolvers has established a compliance precedent that reverberates beyond the public sector, encouraging vendors and enterprise buyers to prioritize encrypted transport and stronger integrity controls.
Domain Name System Tools Market
At the same time, cybersecurity guidance bodies are increasingly emphasizing AI-enabled DNS solutions as a response to attackers targeting critical infrastructure through DNS-based vectors. This shift reinforces the expectation that next-generation DNS security will combine protocol-level safeguards with behavioral analytics and automated response mechanisms. In parallel, national cybersecurity strategies in markets such as Japan are driving broader adoption of AI-enabled threat detection within DNS protection solutions, signaling a global trend toward smarter, more adaptive defense architectures. These policy directions are not abstract mandates; they actively shape procurement criteria, vendor evaluations, and long-term technology roadmaps.
What 2026 Decision-Makers Should Prioritize
For organizations planning security investments in 2026, the market signals point toward a few strategic priorities. First, DNS security should no longer be treated as an ancillary network function; it must be integrated into the broader security architecture as a control point for threat prevention, visibility, and compliance assurance. Second, enterprises should evaluate solutions based on their ability to operate across hybrid environments, provide encrypted DNS support, and integrate with existing orchestration, logging, and response workflows. Third, buyers should scrutinize vendor roadmaps for evidence of AI-enabled analytics, multicloud DNS posture visibility, and partnerships that accelerate deployment in targeted regions or verticals.
Procurement teams will also benefit from understanding how market demand varies across organization size and industry exposure, enabling them to calibrate solution scope, service levels, and total cost expectations. For investors and analysts, the concentration dynamics and recent product and partnership movements offer useful indicators of where consolidation, differentiation, and channel expansion are most likely to occur.
Conclusion: Toward a More Resilient DNS Security Posture
The DNS Security Software market is entering a phase defined by higher adoption expectations, stronger regulatory alignment, and accelerating technical differentiation. Our latest market research provides the structured intelligence required to interpret these changes and translate them into actionable enterprise strategy. By examining the market’s growth trajectory, deployment patterns, competitive movements, and policy-driven demand shifts, the report equips leaders with the perspective needed to make informed decisions in 2026 and throughout the forecast period.
To access the full analysis, including detailed market sizing, forecast breakdowns, competitive assessments, and implementation insights, readers are encouraged to explore the complete report on the PW Consulting research portal. The full publication expands on every dimension discussed here and provides the deeper intelligence necessary for precise strategic planning.
For detailed analysis of this topic, please visit the official page: DNS Security Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Varicella Attenuated Live Vaccine Market to Hit $274.9M by 2032 at 5.65% CAGR
By pmarketresearch, 2026-09-15
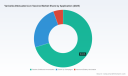
Strategic Intelligence for the Varicella Attenuated Live Vaccine Market 2026-2032
The global landscape for varicella attenuated live vaccines is entering a decisive phase of expansion and strategic realignment. As immunization programs mature across diverse healthcare systems and regulatory frameworks evolve to address safety nuances, manufacturers, policymakers, and investors require a precise, forward-looking view of demand trajectories, competitive positioning, and operational constraints. PW Consulting's latest Varicella Attenuated Live Vaccine Market study delivers exactly that: a comprehensive, data-grounded intelligence asset designed to inform enterprise strategy through 2032. This overview previews the analytical architecture of the report, demonstrating why it is an essential reference for decision-makers navigating the 2026 market environment.
Market Trajectory and the Strategic Imperative for 2026
The varicella attenuated live vaccine sector has demonstrated sustained momentum over the past half-decade. Historical revenue data from 2020 through 2025 illustrates a consistent upward curve, with the global market expanding from approximately 145.3 million USD in 2020 to 188.5 million USD in 2025. This growth reflects the compounding effects of routine childhood immunization scale-up, targeted catch-up initiatives, and gradual adoption of adult and elderly vaccination protocols. Building on this foundation, the market is projected to reach 197.66 million USD in 2026, with a compound annual growth rate of 5.65 percent throughout the 2026-2032 forecast period, ultimately approaching 274.9 million USD by 2032.
Numbers alone, however, do not capture the strategic inflection points that define the current landscape. The forecast horizon coincides with a period of regulatory recalibration, supply chain stress testing, and geographic expansion by key manufacturers. Enterprise leaders must understand not only where the market is heading but how the interplay of dosing regimens, application channels, and regional healthcare infrastructure will shape market share, pricing power, and operational resilience. The full report decomposes these dynamics into actionable frameworks, while this preview highlights the structural insights that will shape 2026 planning cycles.
Worldwide Live Attenuated Varicella Vaccine Market
What the Report Delivers: Operational Depth and Decision-Ready Frameworks
PW Consulting's analysis is structured to move beyond descriptive market sizing and into the realm of executable strategy. The study integrates historical performance analysis, multi-dimensional segmentation, competitive benchmarking, and regulatory mapping to produce a cohesive intelligence package. Decision-makers will find granular assessments of how product type, administration route, and target population interact with regional reimbursement environments, public health procurement models, and supply continuity risks.
The report's operational architecture includes the following core components:
Varicella Attenuated Live Vaccine Market
- A comprehensive historical and forecast revenue analysis spanning 2020 through 2032, anchored in base-year 2025 data and calibrated across multiple demand scenarios.
- A detailed segmentation analysis that maps market distribution across product types, application channels, and geographic regions, with an emphasis on how demand elasticity varies by immunization policy and healthcare procurement structure.
- A competitive landscape evaluation that profiles leading manufacturers, examines product positioning, and assesses the strategic implications of recent regulatory authorizations and supply developments.
- A regulatory and reimbursement dynamics module that tracks evolving immunization schedules, pricing list mechanisms, and programmatic restrictions that directly affect commercial access and demand forecasting.
- A market concentration assessment that quantifies competitive intensity and identifies structural pressures on pricing, innovation velocity, and partnership strategy.
Each section is designed to translate market intelligence into concrete strategic options. Whether the objective is to evaluate market entry feasibility, optimize geographic distribution strategy, or anticipate supply constraints that could disrupt procurement planning, the report supplies the analytical scaffolding required for informed judgment.
Competitive Landscape and the Race for Geographic and Regulatory Advantage
The varicella attenuated live vaccine market is shaped by a concentrated group of manufacturers whose commercial footprints span North America, Europe, Asia Pacific, and emerging markets in Latin America and Southeast Asia. The report provides in-depth profiles of these core players, examining their product portfolios, strain lineages, administration routes, and recent authorization milestones to reveal the strategic contours of present-day competition.
Merck & Co., Inc. continues to anchor its position in the United States and multiple international markets through VARIVAX, a monovalent attenuated live vaccine based on the Oka/Merck strain. The product's subcutaneous administration profile and ongoing supply programs position it as a reference point for both public health procurement and private-sector demand. GlaxoSmithKline plc maintains a parallel presence through VARILRIX, an Oka-strain monovalent vaccine whose marketing authorization was extended in Canada in March 2026, broadening availability across a key North American market. VARILRIX is also actively distributed in Australia, the United Kingdom, and several additional territories, underscoring GSK's focus on established immunization programs and government-backed procurement channels.
In Asia and Latin America, a new wave of authorizations is reshaping competitive dynamics. GC Biopharma Corp., headquartered in Yongin, South Korea, has advanced BARYCELA, a second-generation attenuated live vaccine based on the MAV/06 strain. The product secured marketing authorization in Guatemala in June 2025, representing the first Latin American clearance for this strain lineage, and shortly thereafter obtained authorization in Vietnam in June 2025, supporting expansion throughout Southeast Asia. These milestones, alongside ongoing distribution in South Korea, signal a deliberate strategy to penetrate markets where local and regional immunization priorities are intensifying. SK Bioscience Co., Ltd. complements this regional architecture through SKY Varicella, an Oka/SK strain vaccine with ongoing distribution in South Korea, Turkey, and other markets, reinforcing the growing footprint of Korean manufacturers in the global varicella vaccine ecosystem.
Sinovac Biotech Ltd. has also expanded its commercial reach through PROVARIX / VarV, a Vero cell-derived attenuated live vaccine that holds WHO prequalification and has achieved significant regulatory milestones. The product received marketing authorization in Argentina in June 2025, and China's NMPA approved its use for adolescents and adults in June 2024. With real-world safety studies proceeding through 2026, Sinovac is positioning PROVARIX to serve both established immunization channels and broader age-group indications, illustrating how regulatory approvals and epidemiological evidence combine to open new demand pathways.
The report's competitive analysis goes beyond corporate profiles to examine how these developments alter market concentration, distribution leverage, and strategic collaboration opportunities. With the top three competitors accounting for 48.2 percent of market revenue and the top five capturing 72.8 percent, the landscape is moderately concentrated, creating both barriers to entry and opportunities for targeted differentiation. Understanding which manufacturers are extending geographic coverage, which are navigating supply constraints, and which are adapting to evolving dosing guidance is essential for any organization evaluating partnership, competition, or market entry strategies.
Industry Dynamics: Regulation, Reimbursement, and Supply Chain Volatility
Market growth does not occur in a vacuum. The varicella attenuated live vaccine sector is being reshaped by regulatory adjustments, reimbursement mechanisms, and supply-side disruptions that directly influence demand forecasting and commercial execution. The report integrates these dynamics into its core analytical framework so that decision-makers can stress-test strategies against realistic programmatic and operational scenarios.
On the regulatory front, the CDC updated child immunization schedules in October 2025 to recommend standalone varicella vaccination for toddlers through age three, a shift driven by febrile seizure risk considerations associated with MMRV combination vaccines. This guidance reorients demand toward monovalent formulations and alters the age-group targeting that manufacturers and procurement agencies must factor into supply planning. Simultaneously, product monographs in Canada and the United States have been updated to clarify dosing and administration instructions for intramuscular and subcutaneous routes, reflecting the importance of administration flexibility in both public health and clinical settings.
Reimbursement and supply conditions add further complexity. VARILRIX has experienced manufacturing-related shortages in Australia from September 2025 through June 2026, restricting availability to National Immunization Program and government channels. Such constraints highlight the vulnerability of demand fulfillment when supply continuity falters, and they underscore the strategic value of diversified manufacturing and proactive procurement planning. At the same time, the CDC Vaccine Price List, reviewed on June 1, 2026, provides current contract and private-sector pricing for public health immunization programs, offering a critical reference point for commercial pricing strategy and budget forecasting.
These dynamics are not isolated events; they are structural factors that interact with regional immunization policies, procurement volumes, and manufacturer capacity. The full report analyzes how these variables shape regional demand patterns and identifies the operational implications for companies managing supply, pricing, and market access across multiple jurisdictions.
Why This Study Matters for 2026 Decision-Making
For executives, strategy teams, and investment analysts, the varicella attenuated live vaccine market represents both a growth opportunity and a complexity challenge. The convergence of regulatory updates, geographic expansion by emerging manufacturers, supply interruptions in key markets, and evolving dosing guidance demands a level of insight that general market summaries cannot provide. PW Consulting's study is built to meet that demand by delivering a decision-ready intelligence package that connects market sizing with the operational and competitive realities that determine commercial outcomes.
The strategic value of the report lies in its ability to translate macro-level growth trends into actionable context. Decision-makers gain a structured understanding of how demand is distributed across application channels, how product-type preferences vary by immunization policy, and how regional healthcare infrastructure shapes revenue potential. Equally important, the study illuminates the competitive and regulatory forces that will influence pricing, market access, and supply resilience throughout the 2026-2032 period.
This preview has outlined the analytical architecture and the strategic logic behind the market assessment. The full study provides the detailed segmentation breakdowns, regional and application-level demand scenarios, and granular competitive benchmarking necessary to convert insight into action. For organizations preparing 2026 strategy cycles, the complete report offers the precision, depth, and operational framing required to navigate a market defined by both steady expansion and rapid structural change.
For detailed analysis of this topic, please visit the official page: Varicella Attenuated Live Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Grinding Wheels Market Hits $6.67B in 2025, Projects 4.1% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for 2026: Navigating the Global Grinding Wheels Market
The global manufacturing landscape is undergoing a profound transformation, driven by the dual imperatives of precision engineering and operational efficiency. At the heart of material removal operations lies the grinding wheel, a critical consumable that bridges the gap between raw material and finished component. As we move through 2026, enterprise decision-makers face a complex matrix of evolving demand drivers, regulatory shifts, and competitive technological differentiators. PW Consulting has released a comprehensive market intelligence study designed to cut through the noise and provide actionable strategic clarity. This article provides a high-level preview of the analytical depth contained within the full report, demonstrating why this intelligence is essential for capital allocation, product portfolio planning, and market positioning in the coming years.
Market Trajectory and the 2026 Baseline
Understanding where the market has been is the first step toward predicting where it is going. The historical performance of the grinding wheels sector from 2020 through 2025 reveals a resilient upward trend, even as global supply chains faced intermittent disruptions. The analysis establishes a robust baseline for 2025, setting the stage for the forecast period extending through 2032. The trajectory indicates a steady expansion of the total addressable market, underpinned by sustained industrial activity across key verticals. The compound annual growth rate projected for the forecast horizon signals a moderate but reliable growth environment, characteristic of a mature industrial sector that is still expanding through technological substitution and infrastructure development.
Grinding Media Market
Strategic planners must recognize that while the top-line growth appears stable, the underlying dynamics are shifting. Volume growth is no longer the sole driver; value growth is increasingly tied to high-performance segments. The 2026 figures serve as a critical pivot point. Stakeholders evaluating market entry, expansion, or consolidation strategies need to understand the magnitude of the current opportunity relative to historical baselines. Our full analysis provides the granular time-series data necessary to build financial models that account for both baseline demand and cyclical variations. However, the specific valuation of these market segments and the exact growth contributions of different industrial clusters are detailed exclusively in the complete dataset, ensuring that our clients have the advantage of precise data when negotiating partnerships or securing financing.
Segmentation Dynamics: Type, Application, and Geography
The market is not a monolith. The strategic value of this report lies in its deconstruction of the overall market into actionable segments. The breakdown by product type reveals the continuing dominance of traditional bond technologies alongside the encroachment of advanced materials. Vitrified bond wheels remain a cornerstone for heavy-duty industrial applications, offering durability and precision. Resinoid bond wheels present a different value proposition, often linked to faster cutting speeds and specific metalworking requirements. The remaining category captures the diverse array of specialized products, including superabrasives that are gaining traction in high-value manufacturing sectors. Understanding the relative weight of these categories is vital for manufacturers deciding where to focus R&D resources and production capacity.
Similarly, the application landscape is diverse. The transport industry continues to be a significant consumer, driven by the need for precision components in automotive and aerospace manufacturing. The steel industry remains a foundational pillar, utilizing grinding wheels for surface finishing and dimensioning. However, the breadth of other applications should not be underestimated, as general industrial maintenance and specialized toolmaking contribute substantially to the aggregate demand. Regional consumption patterns also tell a story of globalized production networks. While mature markets in North America and Europe maintain strong consumption levels, the Asia Pacific region represents a significant volume center, reflecting the concentration of manufacturing capacity. Latin America and the Middle East and Africa offer emerging opportunities that require nuanced market entry strategies.
To protect the integrity of our client's strategic planning, we do not disclose the specific percentage splits or absolute dollar values for each region, type, or application in this summary. These figures are critical competitive intelligence. Revealing the exact proportional size of the Vitrified Bond segment versus Resinoid Bond, or the precise revenue contribution of the Transport Industry in a specific region, would dilute the proprietary value of the study. Instead, we invite stakeholders to leverage the full report to access the exact segmentation data required to benchmark their internal market share and identify white space opportunities with confidence.
Competitive Landscape and Strategic Positioning
The grinding wheels market is characterized by a mix of global conglomerates and specialized niche players. The competitive intensity is moderate, with a concentration ratio that suggests room for both challengers and consolidators. Our analysis profiles the key entities shaping the industry landscape. Saint-Gobain Abrasives, leveraging the Norton brand heritage, maintains a strong foothold with offerings that span vitrified, resin-bonded, and CBN wheels tailored for demanding metalworking and aerospace applications. While the Norton Abrasives entity operates distinctly in certain contexts, its synergy with Saint-G Gobain underscores the scale of technology available to large players. 3M Abrasives continues to innovate with precision-shaped grain technologies, such as the Cubitron II series, offering performance advantages in depressed-center and cut-off wheels that appeal to high-efficiency manufacturing lines.
Grinding Wheels Market
In Europe, Tyrolit Group specializes in metal and precision grinding, competing directly in the high-quality vitrified and superabrasive segments crucial for automotive and toolmaking. Klingspor complements this landscape with a broad portfolio of abrasive discs and bonded wheels, while Camel Grinding Wheels serves the North American market with a focus on resin-bonded and vitrified solutions. On the global stage, Carborundum Universal Limited represents a significant force in the Indian subcontinent and beyond, highlighting the importance of regional manufacturing hubs. These companies represent the current guard, but the landscape is fluid.
Recent industry events provide a window into the immediate strategic moves of these players. During GrindingHub 2026 in May, several key developments signaled the direction of technology. Hyperion MT showcased diamond and CBN abrasives applicable to grinding wheels, emphasizing the shift toward superabrasive solutions for harder materials. KREBS & RIEDEL presented double disc grinding wheels with 1500 mm diameter for face and fine grinding, indicating investment in large-scale precision capabilities. EMAG showcased grinding machines compatible with electroplated and dressable CBN grinding wheels, reinforcing the integration of machine tooling with abrasive technology. Furthermore, in March 2026, Xingtai Shuangjian Pitch and Grinding Wheel Co., Ltd. presented their resin-bonded grinding wheels at the China International Hardware Fair, illustrating the continued output of cost-competitive solutions from Asian manufacturers. These events are not merely exhibitions; they are signals of capacity expansion, technological pivots, and regional focus. The full report analyzes how these developments impact market share and pricing power, but we reserve the detailed competitor benchmarking and vulnerability analysis for our subscribers.
Market Dynamics, Regulations, and Operational Risks
Strategic decision-making in 2026 cannot occur in a vacuum. The operating environment is shaped by regulatory frameworks and raw material realities that directly impact cost structures and compliance requirements. One critical dynamic is the composition of abrasive grains. Aluminum Oxide abrasive grains account for a significant share of the abrasive grains market in 2026. This dominance has implications for supply chain stability and cost sensitivity, as fluctuations in raw material availability can ripple through to finished wheel pricing. Manufacturers must assess their exposure to specific grain types and consider long-term procurement strategies.
Regulatory compliance is another major pillar of market dynamics. The industry is seeing clearer standardization regarding safety and performance. The revised 2025 standard GB2025.3-2025/IE 20255-2-3-2025 clarifies arbor hole dimensions and anti-overspeed requirements for grinding wheels and accessories. This type of regulatory clarity drives consolidation around compliant products and can alter the competitive landscape for manufacturers who fail to adapt quickly. Additionally, EN ISO 16089:2025 classifies grinding machines into three risk levels (A/B/C) requiring appropriate safety measures, including burst guard strength calculations. This classification affects the machine-tool interface and indirectly influences the specification of grinding wheels used in these environments. Furthermore, marking requirements under BS EN 12413 and BS ISO 525 mandate that grinding wheels display maximum operating speed, shelf life or expiry date, dimensions, restrictions on use, traceable manufacturing numbers, mounting instructions, and ISO type number. These requirements increase the administrative and quality assurance burden but also create barriers to entry for unorganized competitors.
Understanding the interplay between these regulatory shifts and market behavior is essential. For instance, stricter safety standards may accelerate the adoption of higher-quality, certified wheels over unbranded alternatives in certain regions. Our report integrates these dynamics into the forecast model, assessing the potential for regulatory changes to act as demand catalysts or constraints. The detailed impact assessment of each regulation on specific market sub-segments is a key component of the full study, providing the risk analysis necessary for legal and operational planning.
Strategic Imperatives for Enterprise Decision-Makers
For Senior Vice Presidents of Strategy, Heads of Market Intelligence, and Corporate Development executives, the value of this market research extends beyond simple market sizing. It is about building a resilient strategy in a market that rewards precision and compliance. The data suggests that while the overall market grows at a steady pace, the opportunity for outperformance lies in segmentation accuracy and regional focus. Companies that align their product portfolios with the high-growth applications and adhere strictly to the evolving regulatory standards will be better positioned to protect margins. Conversely, those relying on legacy products without accounting for raw material shifts or regulatory updates face increased risk.
The competitive analysis provided in the full report allows enterprises to benchmark their positioning against the key players. Knowing the profile of competitors like Saint-Gobain, 3M, Tyrolit, and others helps in identifying potential partnership opportunities or acquisition targets. The recent developments section offers a real-time pulse on the industry, helping strategy teams anticipate competitor moves before they fully materialize in market share data. For organizations looking to enter new geographies, the regional analysis provides the context needed to evaluate infrastructure, demand density, and competitive saturation without revealing the specific revenue figures that would compromise strategic surprise.
Conclusion: Accessing the Full Intelligence
The Grinding Wheels Market is at a juncture where historical data, forward-looking forecasts, and current industry dynamics must be synthesized to make informed decisions. The 2026 baseline offers a solid foundation for planning through 2032, with a growth trajectory that supports continued investment. However, the devil is in the details. The specific segmentation sizes, the exact regional growth rates, the granular competitor vulnerabilities, and the quantified impact of regulatory changes are the elements that transform general market knowledge into a winning strategy.
This article has outlined the scope and strategic depth of the PW Consulting Grinding Wheels Market study. We have highlighted the key themes: the steady market expansion, the critical segmentation by type and application, the complex competitive field, and the regulatory environment. Yet, to truly empower your organization with the precision required for 2026 decision-making, you need the complete dataset. The full report contains the actionable intelligence, the detailed tables, and the proprietary analysis that our clients rely on to outperform the market average. We invite you to access the source page to obtain the comprehensive intelligence necessary to navigate the grinding wheels market with confidence and strategic advantage.
For detailed analysis of this topic, please visit the official page: Grinding Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PAPR Market Hits $3.08B in 2025, Projected to Reach $5.38B by 2032 at 8.3% CAGR
By pmarketresearch, 2026-09-15
Strategic Horizons in Respiratory Protection: Why the 2026 Powered Air Purifying Respirator Market Demands Executive Attention
The global landscape for Powered Air Purifying Respirators is undergoing a structural transformation that extends far beyond incremental product updates. For corporate strategists, procurement leaders, and industrial safety directors, the current market cycle presents a rare convergence of regulatory recalibration, technological maturation, and cross-sector demand acceleration. Our latest market research publication is designed not merely as a statistical compendium, but as a decision architecture tool that maps how these converging forces will redistribute capital, reshape competitive positioning, and redefine procurement thresholds through 2032.
This introductory analysis outlines the strategic rationale behind the study, previews the operational intelligence embedded within its framework, and demonstrates why enterprises that treat respirator procurement as a tactical expense rather than a strategic capability will face measurable competitive disadvantage in the coming planning cycle.
The Trajectory Beneath the Headlines: Sizing the Opportunity Without Losing Sight of Nuance
Between 2020 and 2025, the global PAPR market expanded from approximately 2.07 billion USD to 3.08 billion USD, reflecting a compound trajectory that underscores sustained institutional adoption rather than cyclical procurement spikes. Looking forward, our modeling projects the market to reach 3.39 billion USD in 2026 and continue its ascent toward 5.38 billion USD by 2032. The forecast period is anchored by a calculated compound annual growth rate of 8.3 percent, a figure that signals durable expansion powered by structural rather than temporary demand drivers.
Numbers of this magnitude carry strategic weight only when contextualized against operational reality. The upward curve is not uniform across use cases, nor is it distributed evenly across operating environments. Instead, it reflects a market where high-filtration respiratory protection has transitioned from compliance-driven acquisition to capability-driven investment. Healthcare infrastructures continue to absorb units for pathogenic exposure mitigation. Heavy industrial operators are standardizing powered systems to reduce worker fatigue and extend safe exposure windows in particulate-heavy environments. Manufacturers of welding, fabrication, and chemical handling equipment are embedding PAPR compatibility into broader safety ecosystem designs.
The strategic insight for decision-makers lies in recognizing that this growth curve is supported by overlapping adoption triggers. Procurement budgets that previously treated respirator specifications as static safety requirements are now evaluating airflow optimization, filter lifecycle economics, battery architecture, and integration compatibility with existing personal protective equipment portfolios. The result is a market where total cost of ownership calculations increasingly outweigh unit price comparisons, and where early movers in specification standardization are capturing downstream procurement leverage.
Regulatory Realignment and the Shifting Compliance Landscape
No strategic assessment of the PAPR sector would be complete without accounting for the regulatory currents actively reshaping procurement pathways. In mid-2026, the U.S. Food and Drug Administration issued draft guidance proposing an enforcement discretion compliance policy for NIOSH-approved PAPRs and related non-surgical respirators intended for healthcare and public health applications. The practical implication is a potential reduction in premarket requirements for specific deployment contexts, which could accelerate procurement cycles for hospital systems and public health response networks while simultaneously altering the risk calculus for manufacturers positioning products across clinical and industrial boundaries.
Simultaneously, a proposed OSHA amendment from mid-2025 targets respiratory protection standard medical evaluation requirements. The proposal removes clearance mandates specifically for users of filtering facepiece respirators and loose-fitting powered air-purifying respirators, citing insufficient evidence that mandatory medical clearance materially reduces impairment risk in these configurations. If finalized, this regulatory adjustment would meaningfully alter onboarding workflows, expand the addressable operator pool in industrial settings, and shift compliance management from individual medical gating toward system-level safety oversight.
These regulatory movements do not operate in isolation. They intersect with documented quality control considerations, including references in recent guidance to device recall events involving assembly integrity concerns in specific PAPR configurations. For procurement and risk management teams, the lesson is clear: specification selection now requires a broader lens that incorporates regulatory trajectory, manufacturing quality assurance, and lifecycle maintainability rather than relying solely on baseline certification status.
The Competitive Architecture: Who Is Shaping the Next Cycle
The PAPR market remains moderately concentrated, with the top three players commanding a combined share that reflects the influence of established safety equipment ecosystems, distribution breadth, and cross-industry brand trust. The top five manufacturers collectively account for approximately 65 percent of market revenue, a structure that rewards scale, supply chain resilience, and the ability to align product roadmaps with sector-specific compliance and operational requirements.
Several incumbent and specialized manufacturers are actively repositioning their portfolios to capture emerging demand vectors. Dräger continues to anchor its respiratory protection strategy on industrial and decontamination applications, with its helmet and facepiece system architecture tailored for environments where sustained filtered airflow and user isolation are operational priorities. MSA Safety has expanded its North American footprint through an exclusive distribution partnership that introduces specialized welding and industrial PAPR configurations, integrating external technology into a broader safety equipment ecosystem. Bullard recently advanced its industrial protective equipment line with a third-generation platform emphasizing refined battery architecture, higher filter efficiency targets, and streamlined maintenance workflows. AirBoss Defense Group has focused on compact, lightweight configurations with integrated battery systems and NIOSH-approved particulate protection pathways, targeting applications where mobility and minimal system encumbrance influence adoption. 3M maintains a strong presence in heavy industrial and hazardous location applications through its powered air purification portfolio, leveraging cross-category engineering infrastructure to support high-demand environments.
The strategic signal for enterprise buyers is not simply which manufacturers are active, but how product differentiation is evolving. Competition is increasingly defined by battery density and charge-cycle economics, filter replacement logistics, ergonomic integration with existing hard hats and protective garments, and the ability to support standardized training and maintenance protocols across large workforces. Specifying organizations that align procurement criteria with these differentiation axes will capture operational efficiency gains that extend well beyond initial acquisition cost.
Segmentation Dynamics: Where Demand Is Actually Concentrated
Market growth is rarely uniform, and the PAPR sector reflects a landscape where application-specific deployment logic dictates volume concentration. Healthcare environments represent a substantial demand pillar, driven by exposure mitigation protocols, infection control infrastructure, and the ongoing institutionalization of respiratory protection programs that treat powered systems as long-term operational assets rather than episodic procurement items. Manufacturing follows closely, where particulate exposure, welding fume management, and prolonged shift endurance requirements sustain steady replacement and expansion cycles.
Oil and gas operations, construction environments, and a broader category of specialized applications contribute additional volume streams, each governed by distinct specification priorities. High-exposure industrial sites tend to prioritize durability, filter capacity, and compatibility with hazard-specific protective layering. Construction and intermittent-use environments often weigh portability, battery runtime, and setup simplicity more heavily. The strategic implication is that a single procurement strategy cannot efficiently serve multiple verticals. Specification frameworks must be calibrated to deployment frequency, maintenance resourcing, and the operational cost of downtime or user non-compliance.
From a product architecture perspective, half-mask configurations continue to dominate volume discussions due to their adaptability across industrial and general-purpose applications. Full-face systems maintain relevance in deployments where eye protection integration and sealed exposure control are non-negotiable. Hood-based configurations occupy specialized niches where unrestricted peripheral vision, reduced facial contact, and shared-use sanitation workflows influence adoption. The relative weight of each configuration type reflects not only technical suitability but also training overhead, storage logistics, and the institutional familiarity of end users.
Total Cost of Ownership: The Hidden Variable in Procurement Strategy
Enterprise buyers increasingly recognize that unit pricing captures only a fraction of the economic reality surrounding PAPR deployment. Battery chemistry costs remain a primary material expense in system manufacturing, with lithium-ion and nickel-metal hydride architectures influencing both acquisition cost and operational replacement cycles. Labor associated with fit testing, maintenance scheduling, filter replacement, and decontamination workflows drives a significant portion of capital and operational expenditure in hospital and industrial environments alike.
For healthcare systems, respiratory protection programs continue to classify PAPR consumables under existing procedural frameworks without dedicated reimbursement code revisions. This means procurement decisions must be evaluated against internal cost recovery models, labor efficiency targets, and compliance assurance thresholds rather than external reimbursement incentives. In industrial contexts, the economic calculus extends to worker throughput, exposure-related downtime avoidance, and the administrative burden of maintaining documentation for regulatory audits.
The strategic advantage belongs to organizations that integrate these cost layers into a unified evaluation model. Procurement teams that isolate hardware price from maintenance labor, training cadence, battery lifecycle replacement, and filter availability risk underestimating long-term program cost. Conversely, organizations that standardize specifications, consolidate maintenance workflows, and align training programs with actual deployment frequency can convert respiratory protection from a compliance line item into a managed operational capability.
Worldwide Medical Powered Air Purifying Respirators Market
What the Full Study Delivers: Operational Intelligence for 2026 Decision Cycles
Our comprehensive market research publication is structured to translate macro trajectory into executable planning inputs. The study maps historical adoption patterns from 2020 through 2025, establishes forward-looking projections through 2032, and embeds those projections within a segmentation framework that allows readers to isolate the demand drivers most relevant to their operational context without exposure to irrelevant market noise.
The report details procurement specification trends, product architecture comparisons, and competitive positioning dynamics across incumbent and emerging participants. It evaluates how regulatory proposals, enforcement guidance, and compliance workflow adjustments are likely to influence procurement timelines, training requirements, and documentation burdens. It also examines material cost structures, maintenance labor implications, and the economic logic that distinguishes short-term price optimization from long-term program efficiency.
For strategic planning teams, the study provides a structured basis for scenario planning. Readers can assess how shifts in regulatory posture, changes in battery and filter supply economics, and evolving competitive offerings may alter procurement thresholds and specification priorities over multiple budget cycles. The analysis is designed to support capital planning, vendor evaluation, training program design, and risk management architecture without requiring readers to reconstruct those connections from raw data tables.
Strategic Imperatives for Executives Evaluating Respiratory Protection Portfolios
The 2026 market environment rewards organizations that treat powered air purifying respirator procurement as a strategic interface between worker safety, operational continuity, and compliance management. Several imperatives emerge for decision-makers preparing budget cycles and specification roadmaps.
-
Align specification criteria with deployment reality rather than baseline certification alone. Operational endurance, maintenance accessibility, and user acceptance often determine whether a system delivers its intended safety value over time.
Powered Air Purifying Respirator (PAPR) Market -
Model total program cost across hardware, consumables, battery replacement, fit testing, and training labor. Procurement decisions optimized solely on unit price frequently shift expense into less visible operational budgets.
-
Anticipate regulatory trajectory in procurement planning. Proposed changes to medical clearance requirements and enforcement discretion guidance may expand usable operator pools and compress procurement cycles, but they also shift compliance management responsibilities.
-
Standardize where feasible, customize where necessary. Multi-site organizations benefit from baseline specification consistency, but vertical-specific hazards and workflow differences often require targeted configuration adjustments.
-
Evaluate vendor ecosystems for lifecycle support rather than initial product availability. Filter supply continuity, maintenance documentation, battery replacement pathways, and training resources determine long-term program stability.
Why This Research Matters Now
The convergence of regulatory adjustment, product generation upgrades, competitive portfolio realignment, and sustained cross-sector demand places the PAPR market at an inflection point where procurement decisions carry multi-year consequences. Organizations that invest in structured intelligence before finalizing specification frameworks and budget allocations will be positioned to manage compliance risk, control lifecycle cost, and maintain operational continuity as market conditions evolve.
Our full study provides the depth, segmentation resolution, competitive mapping, and forward-looking scenario analysis required to convert market trajectory into actionable strategy. The macro growth path, regulatory shifts, and competitive dynamics outlined here establish the context. The complete research deliverable provides the specification-level intelligence, procurement strategy frameworks, and segmentation insights necessary to support confident 2026 decision-making and multi-year planning through 2032.
For executives, safety directors, and procurement strategists seeking to move beyond headline figures and understand where demand is concentrating, how regulatory changes will reshape deployment logic, and which competitive and cost-structure variables will define program efficiency, the complete market research briefing offers the operational clarity required to act with precision rather than approximation.
For detailed analysis of this topic, please visit the official page: Powered Air Purifying Respirator (PAPR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com