

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: IEMS Market Hits $35.2B in 2025, Projected 8.27% CAGR to Reach $61.85B by 2032

Strategic Intelligence for Industrial Energy Management: Navigating the $61.85 Billion Horizon by 2032
The global industrial landscape is undergoing a fundamental transformation where energy efficiency and operational resilience are no longer peripheral concerns but central pillars of competitive strategy. As we move through the mid-2020s, Industrial Energy Management System (IEMS) solutions have evolved from optional optimization tools into critical infrastructure for manufacturing, heavy industry, and process sectors. PW Consulting has released a comprehensive market research report that provides enterprise decision makers with the analytical rigor required to align capital allocation, technology procurement, and sustainability roadmaps with the realities of the 2026 to 2032 cycle. This publication is designed to deliver foresight rather than static description, equipping executives with the context needed to anticipate regulatory pressure, technological disruption, and competitive realignment across industrial energy ecosystems.
For Chief Operating Officers, Sustainability Directors, Plant Managers, and Strategy Leaders, the value of this analysis lies in its translation of complex market signals into actionable intelligence. Energy costs, carbon compliance obligations, and operational uptime pressures now intersect in ways that demand precise forecasting and disciplined execution. Our research framework addresses these intersecting priorities by examining historical trajectories, forward-looking growth drivers, structural segmentation patterns, and the strategic positioning of incumbent and emerging players. The objective is to equip organizations with the clarity required to make high-stakes decisions with confidence, whether they are evaluating software deployments, hardware modernization programs, or integrated service engagements.
Market Scale, Trajectory, and the Architecture of Industrial Energy Transformation
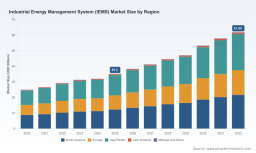
Between 2020 and 2025, the global IEMS market expanded from approximately 25.0 billion USD to 35.2 billion USD, reflecting a sustained convergence of automation maturity, digital connectivity, and energy cost volatility. This foundational period established the operational baseline for what is now a market poised for acceleration. Our forecast period, spanning 2026 through 2032, projects continued expansion driven by the increasing integration of energy management into core industrial workflows, the push toward decarbonization, and the growing need for real-time performance visibility across geographically distributed operations. By the close of the forecast window, market revenue is projected to reach 61.85 billion USD, representing a compound annual growth rate of 8.27 percent.
These headline figures are more than a statistical summary. They reflect a market in which value creation is shifting from standalone monitoring hardware toward software-driven optimization platforms, integrated service architectures, and ecosystem-enabled control strategies. The growth dynamic is not uniform across all value pools. Instead, it is shaped by the way industrial operators are reconfiguring their capital priorities and operational philosophies. Companies that previously treated energy management as an isolated compliance function are now embedding it into production scheduling, asset maintenance, and supply chain planning. This behavioral shift is broadening the addressable market and elevating the strategic importance of integrated IEMS capabilities.
Our analysis also tracks concentration as a structural signal. The market exhibits a meaningful degree of consolidation among leading participants, with the top three firms accounting for approximately 38.0 percent of aggregate revenue and the top five firms representing roughly 62.0 percent of total market value. This concentration pattern suggests that scale, cross-industry installation experience, and the ability to deliver end-to-end solutions are increasingly important differentiators. At the same time, it leaves room for specialized and innovative entrants to capture differentiated positions through software-first offerings, advanced analytics, and sustainability-focused service models.
Segmentation Signals Without the Noise: Type, Application, and Regional Framing
Effective strategy formulation requires more than aggregate market sizing. It demands an understanding of how value is distributed across technology categories, end-use environments, and geographic operating realities. Our report examines these dimensions in detail while maintaining a strategic focus on what each segment implies for decision makers. Rather than offering a static breakdown, the analysis interprets segmentation as a map of where demand is maturing, where it is accelerating, and where investment logic differs by use case.
In terms of technology form factors, the market is shaped by the interplay of software, hardware, and service components. Hardware remains a significant foundation for industrial energy visibility and control, but the direction of value migration increasingly favors software platforms and service-led implementations that enable continuous optimization rather than one-time deployments. For procurement leaders, this matters because the economic case for IEMS adoption is increasingly tied to lifecycle performance, integration readiness, and the ability to scale analytics across multiple sites. For vendors and partners, it signals the importance of bundling capabilities in ways that align with how industrial customers evaluate risk, payback, and operational continuity.
Application context further differentiates demand dynamics. Industrial energy management requirements vary substantially across sectors because production intensity, process complexity, regulatory exposure, and energy profile all shape the value proposition of an IEMS deployment. Manufacturing operations typically require granular real-time monitoring and production-linked optimization logic. Energy-intensive process industries place greater emphasis on reliability, integration with legacy control environments, and compliance-driven performance tracking. Our research explores how these differing operational realities create distinct buying criteria and informs which solution architectures are most likely to succeed in each setting. Decision makers benefit from this framing because it allows them to map their own operational priorities against market-wide adoption patterns instead of treating the IEMS category as a monolith.
Regional differences add another layer of strategic nuance. Market development is not moving at the same pace everywhere. Some regions are advancing rapidly because of strong industrial automation adoption, supportive policy frameworks, and mature engineering ecosystems, while other regions are shaped by emerging incentive structures, infrastructure modernization needs, and evolving compliance expectations. Our report addresses these geographic variations as strategic context rather than as a rigid geographic scoreboard. The purpose is to help organizations anticipate where deployment conditions are most favorable, where competitive intensity is highest, and where partnership or localization strategies may be required to gain traction.
Competitive Landscape: Incumbents, Specialists, and the Emerging Intensity of Differentiation
The IEMS market is characterized by a diverse competitive field spanning global automation and power management leaders, industrial software specialists, and technology companies bringing networking, analytics, and connectivity capabilities into the energy management domain. This breadth is one of the market's defining features. It means that industrial operators can choose from established platforms with deep process integration heritage, entreprise-grade energy management suites, and increasingly agile entrants focused on software-only optimization, AI-driven control logic, and multi-site energy intelligence.
Global players such as ABB Ltd, Siemens AG, Schneider Electric SE, Emerson Electric Company, General Electric Company, Yokogawa Electric Corporation, Mitsubishi Electric Corporation, Honeywell International Inc., Azbil Corporation, Rockwell Automation, and Eaton Corporation PLC bring broad industrial portfolios and extensive installed bases to the market. Their strength lies in the ability to connect energy management with automation, process control, electrification, and facility operations in a coordinated way. For many industrial customers, this integration is not a convenience but a requirement, especially in environments where energy performance must be managed alongside throughput, safety, and asset reliability.
At the same time, the market includes specialists and newer entrants with sharply defined value propositions. Companies such as EnerNOC, Cisco Systems, Inc., IEM, explitia, Tibo Energy, Prescient Technologies, and MRI Software illustrate the growing influence of application-specific software, IIoT-enabled monitoring, demand-side management capabilities, and analytics-first approaches. These players often compete by reducing deployment friction, accelerating time to insight, or targeting particular operational pain points such as cost control, grid interaction, or multi-facility portfolio visibility.
This competitive mix creates a more dynamic environment for buyers and vendors alike. Industrial organizations are no longer limited to a single procurement model or technology philosophy. They can pursue integrated automation-led platforms, software-centric energy intelligence layers, or hybrid solutions that combine monitoring hardware, analytics, and managed services. The strategic implication is that selection criteria increasingly depend on integration ambition, internal capability, and long-term operating model rather than on product features alone. Vendor consolidation, partnership ecosystems, and solution extensibility are therefore becoming essential considerations in any IEMS investment decision.
Worldwide Power Energy Management System (EMS) Market
Recent Corporate Moves That Reshape Investment Signals
Market intelligence is not abstract when it is anchored in recent corporate behavior. Several developments during 2025 and early 2026 provide useful indicators of where capabilities, priorities, and competitive momentum are heading. Emerson Electric Company's move into a new global headquarters in Clayton, Missouri, in February 2026 is not only an organizational milestone but also a signal of renewed emphasis on industrial automation and IEMS-related capabilities within a major player's operating footprint. Such infrastructure investments often coincide with expanded R&D focus, stronger cross-functional collaboration, and improved delivery capacity for the industrial automation and energy management solutions that underpin market demand.
In May 2025, Tibo Energy completed a funding round of EUR 6 million to expand its AI-based energy management system, with a focus on industrial grid congestion solutions and multi-site optimization. This development is strategically significant because it underscores investor confidence in software-driven, AI-enhanced energy optimization for industrial environments. It also reflects a growing recognition that energy management is increasingly connected to broader grid constraints, site-level load flexibility, and the ability to coordinate optimization across multiple facilities. For competitive analysis, moves like this suggest that advanced analytics and intelligent control are becoming central battlegrounds, especially for organizations seeking differentiation through operational efficiency and cost reduction.
In November 2025, Azbil Corporation relocated its headquarters to the Marunouchi Park Building in Tokyo, reinforcing its commitment to industrial automation and energy management offerings. Relocations of this kind often accompany strategic realignment, talent concentration, and upgraded collaboration environments. While such events do not directly determine market share, they provide context for how established players are reinvesting in their long-term positioning within the IEMS value chain. Documenting these shifts helps buyers and investors assess whether momentum is consolidating around incumbents or whether specialized innovators are gaining the space needed to scale.
Regulatory and Standards Pressure as a Core Demand Driver
A defining feature of the IEMS market is the extent to which policy and standards frameworks shape adoption timing, deployment scope, and solution requirements. Regulatory momentum is not a background condition in this market; it is one of the most direct drivers of commercial activity.
In the European Union, the Energy Efficiency Directive has increased expectations for industrial facilities to implement energy management systems and maintain regular reporting on consumption and efficiency improvements. This creates both a compliance obligation and a strategic incentive to adopt systems that can substantiate measurable performance gains. In the United States, the Energy Policy Act supports energy management practices in industrial settings as part of broader efforts to reduce consumption and advance sustainability goals. Parallel to these national and regional mandates, ISO 50001 remains widely adopted as a structured framework for improving energy performance across industrial operations. Its influence is important because it encourages repeatable measurement, management review, and continuous improvement, all of which reinforce the need for capable IEMS platforms and services.
Industrial Energy Management System (IEMS) Market
Climate policy commitments add another layer of pressure and opportunity. Paris Agreement implementation efforts continue to influence carbon pricing mechanisms, incentive programs, and reporting expectations that affect industrial energy use. Meanwhile, regional code updates, such as the 2025 California Energy Code revisions, illustrate how subnational policy can accelerate demand for mandatory efficiency measures and energy monitoring in industrial contexts. Taken together, these regulatory and standards dynamics mean that IEMS adoption is increasingly tied to risk management, audit readiness, and the ability to demonstrate credible energy performance improvement over time.
What the Report Delivers: Operational Content for Decision Making
A high-quality market study must move beyond descriptive commentary and provide materials that can be used directly in commercial planning, technology evaluation, and competitive assessment. This report is structured to support those practical needs. It combines market sizing, segmentation interpretation, competitive profiling, and regulatory context into a single analytical framework so that readers can see how demand signals, vendor behavior, and policy developments interact.
The report includes detailed profiles of key companies active in the IEMS market, with attention to their specific offering orientation, geographic presence, and strategic relevance. These profiles help readers understand not only who the major participants are, but also what kinds of problems they are positioned to solve. For buyers, this supports more disciplined vendor shortlisting and stronger evaluation criteria. For investors and partners, it provides a clearer picture of where differentiation is emerging and which capability gaps may represent opportunity.
In addition to company profiles, the report examines recent developments that indicate shifting momentum across the competitive field. By connecting corporate moves to broader market logic, the analysis helps readers interpret events such as funding rounds, headquarters transitions, and capability expansions as part of a larger strategic narrative rather than as isolated news items. This approach is especially valuable in a market where competitive positioning can change quickly as software, analytics, and integration models evolve.
How to Use This Intelligence in 2026 Planning Cycles
For executives planning capital expenditure, digital transformation initiatives, or sustainability roadmaps, the most valuable use of this research is as a decision-support instrument rather than a passive reference document. The report is designed to help teams answer several practical questions: Where is demand growth most structurally supported? Which solution archetypes fit different operational and compliance needs? What types of vendors are likely to compete on integration depth versus agility and specialized functionality? How do regulatory expectations influence procurement timelines and evaluation criteria?
The strategic value of the research increases when it is used to stress-test assumptions. For example, organizations evaluating IEMS investments can use the segmentation and competitive analysis to determine whether their preferred path aligns with market-wide adoption patterns or whether they are intentionally pursuing a differentiated niche. Procurement teams can use the company profiles and recent development intelligence to anticipate vendor trajectories and refine negotiation positions. Sustainability and operations leaders can use the regulatory context to align energy management projects with compliance obligations and reporting requirements, strengthening the business case for deployment.
In markets characterized by both consolidation and innovation, clarity about the competitive landscape is a genuine advantage. The fact that the market includes both large-scale integrated players and more specialized innovators means that the best choice is rarely obvious. The report helps decision makers navigate that ambiguity by presenting the landscape as a set of strategic trade-offs rather than a simple vendor ranking. It provides the context needed to decide whether the priority is breadth of integration, speed of deployment, analytics sophistication, service continuity, or a specific combination of these attributes.
Conclusion: A Market Entering a More Discriminating Phase
The Industrial Energy Management System market is entering a phase in which growth is increasingly tied to measurable operational value, integration capability, and alignment with regulatory and sustainability expectations. The projected rise from 35.2 billion USD in 2025 to 61.85 billion USD by 2032, at a compound annual growth rate of 8.27 percent, reflects more than incremental adoption. It reflects a structural shift in how industrial organizations think about energy: as a controllable, monitorable, and optimizable part of operational performance rather than as a fixed overhead cost.
This shift creates both opportunity and complexity. Organizations that approach IEMS investment with strategic discipline will be better positioned to select solutions that scale, integrate, and deliver continuing returns. Those that treat energy management as a purely tactical purchase risk missing the broader value that modern platforms, services, and analytics can provide. PW Consulting's report is intended to reduce that risk by equipping leaders with a thorough, decision-oriented view of the market's size, shape, competitive dynamics, and directional forces.
The full research publication contains the complete segmentation analysis, competitive assessment, regional context, and forward-looking interpretation needed to support 2026 strategy execution and planning through the end of the decade. For organizations seeking to make informed IEMS decisions with confidence, the report offers a structured foundation for action. Detailed data, complete segmentation breakdowns, and the full competitive matrix are available through the source report, where readers can access the comprehensive intelligence required to turn market insight into operational strategy.
For detailed analysis of this topic, please visit the official page: Industrial Energy Management System (IEMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com