

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ignition Coil Market to Reach $15.91B by 2032, Expanding at 4.4% CAGR

Ignition Coil Market Strategic Outlook 2026: Navigating Growth, Supply Chain Pressures, and Competitive Evolution
Executive Summary
The global ignition coil market stands at a pivotal juncture as aftermarket demand, OEM electrification pathways, and tightening emission mandates reshape component specifications. PW Consulting's latest research confirms a robust trajectory with a base-year valuation of USD 11.77 billion in 2025 and a projected climb to USD 15.91 billion by 2032. This growth is anchored by a steady compound annual growth rate of 4.4% across the 2026 to 2032 forecast window, reflecting sustained automotive production, vehicle parc replacement cycles, and regulatory-driven performance upgrades. For strategic planners, procurement leaders, and category managers, these figures are more than macroeconomic indicators—they are decision anchors that must be paired with granular segmentation, regional allocation, and competitive intelligence to unlock actionable foresight. This article previews the structural insights embedded in our full report while demonstrating why deeper data is essential for 2026 planning cycles.
Market Trajectory and Strategic Implications
The market's historical arc from 2020 through 2025 reveals a resilient expansion despite intermittent supply disruptions and macroeconomic volatility. Starting at USD 9.49 billion in 2020, the sector progressed through incremental but meaningful gains, crossing the USD 10 billion threshold by 2022 and sustaining momentum into 2025. The transition from 2024 to 2025 alone underscores how steady vehicle assembly rates, combined with aftermarket replenishment cycles, continue to support revenue expansion. Looking forward, the forecast period through 2032 signals a market that will not merely grow but evolve in composition. Demand patterns will increasingly favor coil architectures optimized for combustion stability, emission compliance, and integration with advanced engine management systems. This means that volume growth will be accompanied by specification upgrades, testing requirements, and material sourcing constraints that demand proactive supply chain redesign.
Strategic decision-makers must recognize that headline valuations obscure the operational realities of regional demand intensity, application-specific replacement cycles, and type-driven performance premiums. A market expanding toward USD 15.91 billion over the forecast horizon will not reward generic sourcing strategies or static inventory assumptions. Instead, it will favor organizations that can align production planning with coil architecture trends, anticipate copper-dependent cost pressures, and position themselves within the shifting competitive hierarchy. Our full report dissects these layers with precision, enabling readers to move from aggregate awareness to targeted action.
Structural Dynamics Shaping the 2026 Landscape
Several converging forces are redefining how ignition coils are specified, manufactured, and deployed across vehicle platforms. Among the most consequential is the regulatory environment. Recent emission standards now require ignition systems to reduce emissions by up to 30%, directly elevating the importance of precise spark timing, stable combustion, and high-voltage delivery consistency. This regulatory pressure does not merely influence engineering priorities; it redraws the competitive baseline, favoring suppliers capable of delivering coils that meet stringent performance thresholds without compromising durability.
Simultaneously, material and trade dynamics are introducing new cost and risk variables. Copper has been designated as a critical mineral, with high-purity copper windings essential to ignition coil manufacturing triggering supply chain constraints. Adjusted Section 232 tariffs on imported copper articles have further impacted component costs, particularly for assemblies relying on copper wire and iron cores. These factors are not isolated price fluctuations; they represent structural pressures that influence sourcing geography, inventory buffers, and supplier diversification strategies. In parallel, updated standards such as ISO 6518-1:2025 are formalizing testing and performance expectations for single-ended and other road-vehicle ignition coil types, reinforcing the need for certified design validation and consistent quality assurance across production lines.
Fan Coils Market
Together, these dynamics create a market in which technical compliance, material resilience, and certification readiness are as critical as unit cost. Organizations that treat regulation and raw-material volatility as peripheral concerns will face margin erosion and qualification delays. Those that integrate these variables into their roadmap will secure more predictable supply, stronger OEM and aftermarket positioning, and greater readiness for next-generation specification shifts.
Competitive Landscape: Pioneers and Differentiators
The ignition coil market is defined by a concentrated yet diversified competitive field. The top three players account for 48% of market share, while the top five collectively command 55%, signaling meaningful consolidation around established technical capabilities, global distribution networks, and long-standing OEM relationships. Yet concentration does not imply uniformity. Each leading participant brings a distinct value proposition that shapes how the market segments, prices, and innovates.
Denso Corporation continues to anchor its offering in high-precision ignition coils designed for global vehicle manufacturers, with advanced designs aimed at improved combustion efficiency and emission compliance. Robert Bosch GmbH differentiates through high-performance coils integrated into broader vehicle electrical systems, supporting precise spark timing and fuel efficiency across passenger cars and commercial vehicles. Niterra North America, Inc., under the NGK brand, emphasizes aftermarket ignition coils that meet or exceed original equipment specifications, backed by extensive vehicle-in-operation coverage and rigorous testing for heat, vibration, and electrical stress. BorgWarner Inc. brings specialized focus to diesel cold-start ignition coils engineered for reliable starting and reduced emissions in both heavy-duty and light-duty applications.
Beyond these global anchors, regional and specialized players add depth and responsiveness to the competitive ecosystem. Diamond Electric Mfg. Corp. supplies automotive ignition coils and electronic control devices to global OEM customers including Ford, Dodge, and Subaru, leveraging manufacturing operations across Japan and the United States. Hitachi Ltd. positions automotive ignition coils within powertrain systems, emphasizing durability and integration with advanced engine management. Standard Motor Products, Inc. offers aftermarket and OEM ignition coils with full line coverage, engineered for performance and emissions control in independent aftermarket applications. Nissens Automotive manufactures aftermarket ignition coils in ISO and IATF 16949-certified facilities, delivering reliable solutions tailored to today's vehicle parc with enhanced performance. Walker Products, Inc. provides ThunderSpark ignition coils engineered for precise high-voltage pulses that meet OEM performance standards. Taiwan Ignition System Co., Ltd. supplies high-quality aftermarket coils, including pencil and block types, meeting vehicle amperage and voltage requirements under ISO 9001 and IATF 16949 certification. Wells Vehicle Electronics delivers aftermarket coils with full coverage for major vehicle makes, supporting emission compliance and engine performance. SMP Corporation aligns OEM and aftermarket ignition coils with emission standards, supporting global independent aftermarket sourcing and engineering.
Recent activity illustrates how these players are translating technical strengths into market momentum. In December 2025, Nissens Automotive partnered with Standard Motor Products to launch its ignition coil line, adding system-critical components for engine performance and emissions control to the aftermarket portfolio. In May 2026, Nissens hosted a global press event in Białystok, Poland, combining factory visits, technical sessions on design, testing, and manufacturing, and hands-on racing activities to showcase a new ignition coil range to European media. These developments highlight a broader pattern: competition is intensifying not only through volume and coverage but through demonstrable engineering credibility, certification transparency, and strategic channel partnerships. For procurement and strategy teams, this means supplier evaluation must extend beyond price and availability to encompass testing rigor, compliance alignment, and future-proof architecture roadmaps.
What the Full Report Delivers for 2026 Decision-Making
The complete PW Consulting research is designed to convert market awareness into executable strategy. Rather than stopping at aggregate trends, the report provides a structured operational framework that helps teams plan, source, and position with confidence across the 2026 to 2032 horizon. The analysis is built around actionable lenses that matter in day-to-day decisions:
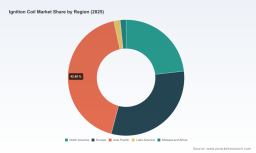
- How market revenue is distributed across regions and what that implies for sourcing geography, logistics planning, and regional pricing strategy
- How ignition coil types compare in demand intensity and specification trajectory, including coil-on-plug architectures, distributor-based configurations, distributor-less systems, and other emerging formats
- Where passenger car and commercial vehicle applications diverge in replacement cycles, performance requirements, and margin profiles
- Which competitive capabilities are becoming table stakes for OEM qualification and aftermarket credibility, from emissions-aligned design to certified manufacturing and testing protocols
- How raw-material criticalness, tariff exposure, and regulatory updates should be integrated into supplier selection, inventory buffers, and cost forecasting models
Each of these areas is supported by detailed segmentation, comparative benchmarks, and forward-looking scenario framing. The objective is not to provide a static snapshot but to equip decision-makers with a data-rich map of where value is concentrated, where risk is emerging, and where strategic investments can create durable advantage. Because the market's trajectory is influenced by overlapping technical, regulatory, and supply-chain variables, the full report connects the dots across segmentation, company strategy, and macro-environment shifts—creating a single reference point for cross-functional planning.
Ignition Coil Market
Why Deeper Intelligence Matters Now
A CAGR of 4.4% and a market moving toward USD 15.91 billion by 2032 tell an encouraging story, but aggregate data cannot answer the questions that shape competitive outcomes in 2026. Which regions will absorb the bulk of incremental demand? Which coil types will capture specification upgrades driven by emission compliance? How should organizations balance copper exposure, tariff adjustments, and localization pressure without compromising responsiveness? Where do the strongest competitive differentiators lie within a field that is both concentrated and highly specialized? The answers to these questions determine sourcing resilience, pricing power, and market-access timing.
The preview above illustrates the structural logic of the market and the competitive forces at play. To move from indication to implementation, organizations need the underlying segmentation values, regional allocations, type-level demand splits, vehicle-type comparisons, and company-specific positioning that our full report details. These insights are deliberately developed to support precise decisions rather than broad assumptions. For teams preparing annual operating plans, supplier negotiations, product-portfolio updates, or capacity strategies, the complete intelligence offers the resolution required to act with confidence.
Conclusion
The ignition coil market is expanding with disciplined momentum, but its real significance lies in the structural shifts beneath the headline growth. Emission-driven performance requirements, copper criticalness, tariff adjustments, and formal testing standards are reshaping how coils are engineered, qualified, and sourced. At the same time, competitive intensity is rising through technical differentiation, certification transparency, and strategic channel partnerships. PW Consulting's full market research translates these forces into a coherent, decision-ready framework for the 2026 planning cycle and beyond. To access the complete segmentation, competitive analysis, and forward-looking scenario detail that support high-stakes strategic choices, we invite you to explore the full report and secure the intelligence your organization needs to act decisively.
For detailed analysis of this topic, please visit the official page: Ignition Coil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com