

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PAPR Market Hits $3.08B in 2025, Projected to Reach $5.38B by 2032 at 8.3% CAGR

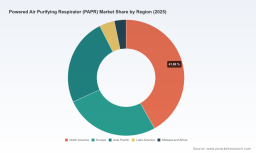
Strategic Horizons in Respiratory Protection: Why the 2026 Powered Air Purifying Respirator Market Demands Executive Attention
The global landscape for Powered Air Purifying Respirators is undergoing a structural transformation that extends far beyond incremental product updates. For corporate strategists, procurement leaders, and industrial safety directors, the current market cycle presents a rare convergence of regulatory recalibration, technological maturation, and cross-sector demand acceleration. Our latest market research publication is designed not merely as a statistical compendium, but as a decision architecture tool that maps how these converging forces will redistribute capital, reshape competitive positioning, and redefine procurement thresholds through 2032.
This introductory analysis outlines the strategic rationale behind the study, previews the operational intelligence embedded within its framework, and demonstrates why enterprises that treat respirator procurement as a tactical expense rather than a strategic capability will face measurable competitive disadvantage in the coming planning cycle.
The Trajectory Beneath the Headlines: Sizing the Opportunity Without Losing Sight of Nuance
Between 2020 and 2025, the global PAPR market expanded from approximately 2.07 billion USD to 3.08 billion USD, reflecting a compound trajectory that underscores sustained institutional adoption rather than cyclical procurement spikes. Looking forward, our modeling projects the market to reach 3.39 billion USD in 2026 and continue its ascent toward 5.38 billion USD by 2032. The forecast period is anchored by a calculated compound annual growth rate of 8.3 percent, a figure that signals durable expansion powered by structural rather than temporary demand drivers.
Numbers of this magnitude carry strategic weight only when contextualized against operational reality. The upward curve is not uniform across use cases, nor is it distributed evenly across operating environments. Instead, it reflects a market where high-filtration respiratory protection has transitioned from compliance-driven acquisition to capability-driven investment. Healthcare infrastructures continue to absorb units for pathogenic exposure mitigation. Heavy industrial operators are standardizing powered systems to reduce worker fatigue and extend safe exposure windows in particulate-heavy environments. Manufacturers of welding, fabrication, and chemical handling equipment are embedding PAPR compatibility into broader safety ecosystem designs.
The strategic insight for decision-makers lies in recognizing that this growth curve is supported by overlapping adoption triggers. Procurement budgets that previously treated respirator specifications as static safety requirements are now evaluating airflow optimization, filter lifecycle economics, battery architecture, and integration compatibility with existing personal protective equipment portfolios. The result is a market where total cost of ownership calculations increasingly outweigh unit price comparisons, and where early movers in specification standardization are capturing downstream procurement leverage.
Regulatory Realignment and the Shifting Compliance Landscape
No strategic assessment of the PAPR sector would be complete without accounting for the regulatory currents actively reshaping procurement pathways. In mid-2026, the U.S. Food and Drug Administration issued draft guidance proposing an enforcement discretion compliance policy for NIOSH-approved PAPRs and related non-surgical respirators intended for healthcare and public health applications. The practical implication is a potential reduction in premarket requirements for specific deployment contexts, which could accelerate procurement cycles for hospital systems and public health response networks while simultaneously altering the risk calculus for manufacturers positioning products across clinical and industrial boundaries.
Simultaneously, a proposed OSHA amendment from mid-2025 targets respiratory protection standard medical evaluation requirements. The proposal removes clearance mandates specifically for users of filtering facepiece respirators and loose-fitting powered air-purifying respirators, citing insufficient evidence that mandatory medical clearance materially reduces impairment risk in these configurations. If finalized, this regulatory adjustment would meaningfully alter onboarding workflows, expand the addressable operator pool in industrial settings, and shift compliance management from individual medical gating toward system-level safety oversight.
These regulatory movements do not operate in isolation. They intersect with documented quality control considerations, including references in recent guidance to device recall events involving assembly integrity concerns in specific PAPR configurations. For procurement and risk management teams, the lesson is clear: specification selection now requires a broader lens that incorporates regulatory trajectory, manufacturing quality assurance, and lifecycle maintainability rather than relying solely on baseline certification status.
The Competitive Architecture: Who Is Shaping the Next Cycle
The PAPR market remains moderately concentrated, with the top three players commanding a combined share that reflects the influence of established safety equipment ecosystems, distribution breadth, and cross-industry brand trust. The top five manufacturers collectively account for approximately 65 percent of market revenue, a structure that rewards scale, supply chain resilience, and the ability to align product roadmaps with sector-specific compliance and operational requirements.
Several incumbent and specialized manufacturers are actively repositioning their portfolios to capture emerging demand vectors. Dräger continues to anchor its respiratory protection strategy on industrial and decontamination applications, with its helmet and facepiece system architecture tailored for environments where sustained filtered airflow and user isolation are operational priorities. MSA Safety has expanded its North American footprint through an exclusive distribution partnership that introduces specialized welding and industrial PAPR configurations, integrating external technology into a broader safety equipment ecosystem. Bullard recently advanced its industrial protective equipment line with a third-generation platform emphasizing refined battery architecture, higher filter efficiency targets, and streamlined maintenance workflows. AirBoss Defense Group has focused on compact, lightweight configurations with integrated battery systems and NIOSH-approved particulate protection pathways, targeting applications where mobility and minimal system encumbrance influence adoption. 3M maintains a strong presence in heavy industrial and hazardous location applications through its powered air purification portfolio, leveraging cross-category engineering infrastructure to support high-demand environments.
The strategic signal for enterprise buyers is not simply which manufacturers are active, but how product differentiation is evolving. Competition is increasingly defined by battery density and charge-cycle economics, filter replacement logistics, ergonomic integration with existing hard hats and protective garments, and the ability to support standardized training and maintenance protocols across large workforces. Specifying organizations that align procurement criteria with these differentiation axes will capture operational efficiency gains that extend well beyond initial acquisition cost.
Segmentation Dynamics: Where Demand Is Actually Concentrated
Market growth is rarely uniform, and the PAPR sector reflects a landscape where application-specific deployment logic dictates volume concentration. Healthcare environments represent a substantial demand pillar, driven by exposure mitigation protocols, infection control infrastructure, and the ongoing institutionalization of respiratory protection programs that treat powered systems as long-term operational assets rather than episodic procurement items. Manufacturing follows closely, where particulate exposure, welding fume management, and prolonged shift endurance requirements sustain steady replacement and expansion cycles.
Oil and gas operations, construction environments, and a broader category of specialized applications contribute additional volume streams, each governed by distinct specification priorities. High-exposure industrial sites tend to prioritize durability, filter capacity, and compatibility with hazard-specific protective layering. Construction and intermittent-use environments often weigh portability, battery runtime, and setup simplicity more heavily. The strategic implication is that a single procurement strategy cannot efficiently serve multiple verticals. Specification frameworks must be calibrated to deployment frequency, maintenance resourcing, and the operational cost of downtime or user non-compliance.
From a product architecture perspective, half-mask configurations continue to dominate volume discussions due to their adaptability across industrial and general-purpose applications. Full-face systems maintain relevance in deployments where eye protection integration and sealed exposure control are non-negotiable. Hood-based configurations occupy specialized niches where unrestricted peripheral vision, reduced facial contact, and shared-use sanitation workflows influence adoption. The relative weight of each configuration type reflects not only technical suitability but also training overhead, storage logistics, and the institutional familiarity of end users.
Total Cost of Ownership: The Hidden Variable in Procurement Strategy
Enterprise buyers increasingly recognize that unit pricing captures only a fraction of the economic reality surrounding PAPR deployment. Battery chemistry costs remain a primary material expense in system manufacturing, with lithium-ion and nickel-metal hydride architectures influencing both acquisition cost and operational replacement cycles. Labor associated with fit testing, maintenance scheduling, filter replacement, and decontamination workflows drives a significant portion of capital and operational expenditure in hospital and industrial environments alike.
For healthcare systems, respiratory protection programs continue to classify PAPR consumables under existing procedural frameworks without dedicated reimbursement code revisions. This means procurement decisions must be evaluated against internal cost recovery models, labor efficiency targets, and compliance assurance thresholds rather than external reimbursement incentives. In industrial contexts, the economic calculus extends to worker throughput, exposure-related downtime avoidance, and the administrative burden of maintaining documentation for regulatory audits.
The strategic advantage belongs to organizations that integrate these cost layers into a unified evaluation model. Procurement teams that isolate hardware price from maintenance labor, training cadence, battery lifecycle replacement, and filter availability risk underestimating long-term program cost. Conversely, organizations that standardize specifications, consolidate maintenance workflows, and align training programs with actual deployment frequency can convert respiratory protection from a compliance line item into a managed operational capability.
Worldwide Medical Powered Air Purifying Respirators Market
What the Full Study Delivers: Operational Intelligence for 2026 Decision Cycles
Our comprehensive market research publication is structured to translate macro trajectory into executable planning inputs. The study maps historical adoption patterns from 2020 through 2025, establishes forward-looking projections through 2032, and embeds those projections within a segmentation framework that allows readers to isolate the demand drivers most relevant to their operational context without exposure to irrelevant market noise.
The report details procurement specification trends, product architecture comparisons, and competitive positioning dynamics across incumbent and emerging participants. It evaluates how regulatory proposals, enforcement guidance, and compliance workflow adjustments are likely to influence procurement timelines, training requirements, and documentation burdens. It also examines material cost structures, maintenance labor implications, and the economic logic that distinguishes short-term price optimization from long-term program efficiency.
For strategic planning teams, the study provides a structured basis for scenario planning. Readers can assess how shifts in regulatory posture, changes in battery and filter supply economics, and evolving competitive offerings may alter procurement thresholds and specification priorities over multiple budget cycles. The analysis is designed to support capital planning, vendor evaluation, training program design, and risk management architecture without requiring readers to reconstruct those connections from raw data tables.
Strategic Imperatives for Executives Evaluating Respiratory Protection Portfolios
The 2026 market environment rewards organizations that treat powered air purifying respirator procurement as a strategic interface between worker safety, operational continuity, and compliance management. Several imperatives emerge for decision-makers preparing budget cycles and specification roadmaps.
-
Align specification criteria with deployment reality rather than baseline certification alone. Operational endurance, maintenance accessibility, and user acceptance often determine whether a system delivers its intended safety value over time.
Powered Air Purifying Respirator (PAPR) Market -
Model total program cost across hardware, consumables, battery replacement, fit testing, and training labor. Procurement decisions optimized solely on unit price frequently shift expense into less visible operational budgets.
-
Anticipate regulatory trajectory in procurement planning. Proposed changes to medical clearance requirements and enforcement discretion guidance may expand usable operator pools and compress procurement cycles, but they also shift compliance management responsibilities.
-
Standardize where feasible, customize where necessary. Multi-site organizations benefit from baseline specification consistency, but vertical-specific hazards and workflow differences often require targeted configuration adjustments.
-
Evaluate vendor ecosystems for lifecycle support rather than initial product availability. Filter supply continuity, maintenance documentation, battery replacement pathways, and training resources determine long-term program stability.
Why This Research Matters Now
The convergence of regulatory adjustment, product generation upgrades, competitive portfolio realignment, and sustained cross-sector demand places the PAPR market at an inflection point where procurement decisions carry multi-year consequences. Organizations that invest in structured intelligence before finalizing specification frameworks and budget allocations will be positioned to manage compliance risk, control lifecycle cost, and maintain operational continuity as market conditions evolve.
Our full study provides the depth, segmentation resolution, competitive mapping, and forward-looking scenario analysis required to convert market trajectory into actionable strategy. The macro growth path, regulatory shifts, and competitive dynamics outlined here establish the context. The complete research deliverable provides the specification-level intelligence, procurement strategy frameworks, and segmentation insights necessary to support confident 2026 decision-making and multi-year planning through 2032.
For executives, safety directors, and procurement strategists seeking to move beyond headline figures and understand where demand is concentrating, how regulatory changes will reshape deployment logic, and which competitive and cost-structure variables will define program efficiency, the complete market research briefing offers the operational clarity required to act with precision rather than approximation.
For detailed analysis of this topic, please visit the official page: Powered Air Purifying Respirator (PAPR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com