
Blogs
Navigating the Next Wave: Strategic Intelligence for the Global Electric Ambulance Stretchers Market
The emergency medical services landscape is undergoing a profound transformation, driven by an aging global population, increasing emergency call volumes, and an uncompromising focus on paramedic safety and patient outcomes. In this high-stakes environment, the equipment used for patient transport is no longer mere hardware; it is a critical determinant of operational efficiency, staff retention, and clinical safety. PW Consulting's latest comprehensive study on the Worldwide Electric Ambulance Stretchers Market offers a decisive roadmap for stakeholders preparing for the 2026 fiscal year and beyond.
As agencies face tightening budgets and escalating compliance standards, understanding the trajectory of this specialized equipment segment is essential. This research brief outlines the strategic value embedded within our full market intelligence report, designed to empower procurement officers, investors, and C-suite executives with the foresight needed to navigate a complex and evolving competitive arena.
Market Trajectory: The Growth Imperative
The macroeconomic indicators for electric ambulance stretchers signal a robust and sustained expansion phase. Our analysis tracks historical performance from 2020 through the base year of 2025, projecting a clear upward trajectory that extends through the forecast period ending in 2032. The market has demonstrated resilience and consistent value appreciation, moving from a valuation of approximately 385.12 million USD in 2020 to an estimated 560.0 million USD in 2025.
Worldwide Electric Ambulance Stretchers Market
Looking toward the immediate future, the momentum가속 (accelerates) as we enter the 2026-2032 forecast window. The market is poised to reach significant new highs, driven by the replacement of legacy manual equipment with powered solutions that reduce physical strain on emergency responders. The compound annual growth rate (CAGR) stands at a compelling 8.31 percent, indicating that demand is not merely recovering but structurally expanding. For decision-makers, this growth rate suggests that investment in electric transport infrastructure is not a discretionary expense but a strategic necessity to maintain operational parity.
Emergency Stretcher Market
Competitive Landscape: Concentration and Innovation
The market structure is characterized by moderate to high concentration, with established players leveraging technological integration and fleet-scale contracts to secure market share. Our report details the positioning of key industry participants, including global giants like Stryker Corporation and Fenro-Washington, Inc., alongside specialized manufacturers such as Kartsana S.L. and several prominent Chinese medical equipment firms including Jiangyin Everise Medical Equipment Co., Ltd. and Jiangsu Rixin Medical Equipment Co., Ltd. (Red Leaf).
Understanding the rivalry requires more than recognizing brand names; it demands insight into how these companies are differentiating their offerings. Leading manufacturers are increasingly focusing on connected technologies, lithium-ion battery efficiency, and compliance with rigorous crash standards such as SAE J3027 and BS EN 1789. For instance, recent industry movements highlight the intensity of this competition. Major contracts are being awarded based on comprehensive RFP testing and facility visits, as seen in significant fleet agreements involving hundreds of powered units. Furthermore, the inclusion of specific electric powered ambulance gurneys in federal market surveys, such as the DHS SAVER program, underscores the importance of meeting standardized performance metrics across multiple jurisdictions.
The barrier to entry remains significant due to the technical requirements of load capacities ranging from 300 to 700+ lbs, battery reliability, and the need for manual backup systems in critical failure scenarios. However, the presence of multiple manufacturers across different regions indicates a healthy supply chain capable of meeting varied regional procurement needs, from North American GSA Schedule contracts to European compliance frameworks.
Regulatory and Operational Dynamics
Operational compliance is a pivotal factor shaping procurement strategies in the electric ambulance stretcher sector. Regulatory frameworks vary by region but converge on safety and electrical reliability. Powered wheeled stretchers occupy a specific niche within medical device regulations; notably, they are often exempt from 510(k) premarket notification requirements under FDA regulations for Class II devices in the United States. This regulatory distinction impacts time-to-market strategies for manufacturers and influences the vetting process for procurement agencies.
Beyond regulatory exemptions, adherence to physical and electrical safety standards is non-negotiable. Equipment must meet standards including IEC 60601-1 for medical electrical equipment, alongside flammability and durability requirements. For agency directors, navigating these specifications is critical to risk management. Procurement under GSA Schedule contracts in the U.S. adds another layer of complexity, requiring vendors to maintain specific contractual standings. Our report dissects these regulatory layers, providing clarity on how compliance influences total cost of ownership and supply chain reliability.
Segmentation: Strategic Focus Areas
While the overall market growth is impressive, the real strategic value lies in understanding where demand is originating and what technological configurations are gaining traction. The market is segmented by product type and end-user application, each offering distinct opportunities for stakeholders.
- Product Technology: The landscape is divided between hydraulic-electric hybrids and fully electric systems. Hydraulic-electric stretchers continue to hold significant market presence, leveraging established reliability and high load capacities. However, fully electric stretchers are gaining ground as battery technology improves, offering reduced operator injury and enhanced maneuverability. The choice between these systems often depends on the specific operational environment, ranging from urban paramedic services to military and defense applications where durability and specific load requirements are paramount.
- End-User Verticals: Demand is distributed across emergency medical service centers, hospitals and clinics, and military and defense sectors. Emergency Medical Service Centers remain a primary driver, given the direct impact of powered stretchers on paramedic health and efficiency during scene responses. Hospitals and clinics utilize these units for internal transport and inter-facility transfers, where ergonomic considerations are increasingly prioritized to reduce staff injury claims. The military and defense segment represents a specialized niche requiring ruggedized solutions that meet unique logistical and safety standards.
- Regional Variations: Market value is distributed across key global regions, with North America historically representing a substantial portion of revenue generation, followed by Europe and the Asia Pacific region. Latin America and the Middle East and Africa present emerging opportunities driven by infrastructure development and modernization of emergency response fleets. Understanding the nuanced demand drivers in each region—such as reimbursement structures, public vs. private procurement models, and local manufacturing capabilities—is essential for market entry or expansion strategies.
Report Scope: Actionable Intelligence for 2026
PW Consulting's Worldwide Electric Ambulance Stretchers Market research is designed to be more than a static snapshot; it is a dynamic tool for strategic planning. The full report provides a granular breakdown of the data required to make informed decisions in 2026.
Key components of the full study include:
- Historical and Forecast Data: Detailed revenue analysis from 2020 to 2032, allowing users to model growth scenarios and budget accordingly.
- Competitive Profiling: In-depth company profiles covering product specifications, recent developments, and strategic moves, enabling benchmarking against key rivals.
- Segment Analysis: A comprehensive look at product types, end-user applications, and regional distributions without the constraints of summarized data, offering the granularity needed for specific market entry or product development plans.
- Supply Chain and Sales Channels: Analysis of distribution networks and procurement pathways, including insights into government contracting vehicles like GSA schedules.
- Regulatory Landscape: A thorough examination of safety standards and compliance requirements affecting product design and procurement.
By accessing the full report, stakeholders can unlock the specific percentage splits and exact monetary values for each segment and region. This level of detail is crucial for validating investment theses, optimizing inventory levels, and tailoring marketing strategies to the highest-value segments.
Conclusion: The Cost of Inaction
In the electric ambulance stretchers market, the cost of inaction is rising. As paramedic health concerns grow and operational efficiency becomes a key metric for funding, agencies that rely on outdated transport equipment risk higher injury rates, slower response times, and increased liability. For manufacturers and investors, the 8.31 percent CAGR signals a market ripe with opportunity, but success requires precise navigation of the competitive and regulatory environment.
The data presented in this overview provides a foundation, but the complete strategic picture requires deeper analysis. The specific revenue contributions of each region, the precise market share of competing product types, and the detailed sales channel dynamics are reserved for the comprehensive report. We invite industry leaders to leverage this intelligence to secure their position in the evolving emergency medical equipment landscape. To access the full dataset, competitive matrices, and forward-looking forecasts necessary for your 2026 planning, please refer to the complete PW Consulting Worldwide Electric Ambulance Stretchers Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Electric Ambulance Stretchers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Aircraft Windows Market to Reach $1,162.16M by 2032, 4.25% CAGR
By pmarketresearch, 2026-09-16
Strategic Transparency: Navigating the Worldwide Aircraft Windows Market Outlook 2026-2032
The global aerospace industry is currently navigating a complex landscape defined by post-pandemic recovery, supply chain recalibration, and an aggressive push toward fuel efficiency. Within this ecosystem, the aircraft windows market serves as a critical barometer for broader manufacturing health, regulatory compliance, and technological innovation. As we enter 2026, stakeholders across the value chain—from original equipment manufacturers (OEMs) to maintenance, repair, and overhaul (MRO) providers—require precise intelligence to capitalize on emerging opportunities. PW Consulting is proud to introduce our comprehensive Worldwide Aircraft Windows Market research, a definitive guide designed to inform high-stakes corporate strategy over the next decade.
This report is not merely a collection of statistics; it is a strategic roadmap. It synthesizes historical performance from 2020 through 2025 with a robust forecast extending to 2032. By analyzing the trajectory from a market valuation of approximately 702.5 million USD in 2020 to a projected 1.16 billion USD by 2032, we uncover the underlying forces driving growth. The compound annual growth rate (CAGR) of 4.25 percent signals a steady, resilient expansion, yet the nuances behind this aggregate figure hold the key to competitive advantage. Our analysis delves into the segmentation splits, material innovations, and regional dynamics that general industry reports often overlook, providing the granularity necessary for actionable decision-making.
Market Trajectory and Macro Drivers
Understanding the historical context is essential for validating future projections. The market demonstrated consistent resilience between 2020 and 2025, recovering from initial disruptions to reach an estimated 868.42 million USD in the base year. This recovery sets the stage for the forecast period beginning in 2026, where valuations are expected to climb from 908.11 million USD to over 1.1 billion USD by 2032. Such growth is not organic fluke; it is anchored in tangible macroeconomic and industry-specific drivers.
Several macro trends are converging to sustain this demand. Strong global passenger demand continues to fuel air travel recovery, necessitating both new aircraft production and significant retrofit programs for aging fleets. Industry forecasts indicate over 2,000 annual narrowbody deliveries projected from 2027 onwards. Each new airframe requires a full suite of transparencies, while retired fleets undergoing modernization require updated window assemblies to meet contemporary safety and comfort standards. Furthermore, the Airbus 2025 Global Market Forecast projects a passenger traffic CAGR of 3.6 percent to 2044. This long-term traffic growth ensures that demand for new passenger aircraft and their associated transparencies will remain robust, creating a sustained pipeline for window manufacturers and suppliers.
Aircraft Flooring Market
Additionally, regulatory frameworks are tightening. Pressure from authorities such as the FAA and EASA is driving more frequent windshield replacement cycles to ensure safety and compliance in commercial aircraft. These regulatory mandates act as a floor for aftermarket demand, ensuring that even during fluctuations in new aircraft orders, the MRO segment remains active. Our report quantifies how these regulatory cycles interact with material lifespans to create predictable revenue streams for service providers.
Worldwide Aircraft Windows Market
Material Innovations and Segment Dynamics
The aircraft windows market is segmented by product type, material, and platform, each presenting unique value propositions and challenges. Our research dissects these segments to reveal where margin potential lies. By product type, the market is divided between cabin windows and cockpit windows. While cabin windows represent a significant portion of the volume due to the number of units per aircraft, cockpit windows demand higher precision and optical fidelity, often commanding different pricing structures and supply chain requirements.
Material selection is perhaps the most critical technical decision facing engineers and procurement teams. The industry is currently weighing the trade-offs between acrylic, glass, and polycarbonate. Traditional stretched acrylic remains common for cabin windows due to its proven performance and cost-effectiveness. However, polycarbonate is gaining traction, offering up to 40 percent less weight than glass alternatives. In an industry obsessed with fuel efficiency and carbon reduction, this weight savings is a compelling value driver. Conversely, glass laminates held a significant share in commercial aircraft windows and windshields in 2025 due to superior optical fidelity and scratch resistance.
Our analysis highlights that while glass maintains dominance in specific high-performance applications, the polycarbonate segment shows a stronger growth trajectory. This shift is not uniform across all platforms. Commercial aviation continues to be the largest platform segment, driven by the sheer volume of passenger aircraft. However, military aviation and business and general aviation segments offer specialized opportunities. Military transparency systems require ruggedization and specific coating technologies for survivability, while business aviation focuses on luxury, noise reduction, and bespoke customization. Understanding the interplay between material costs, weight savings, and platform requirements is essential for suppliers positioning themselves in 2026 and beyond.
Competitive Landscape and Strategic Positioning
The market structure is moderately concentrated, with the top three companies holding a significant share of the revenue pool. This concentration suggests that while barriers to entry exist, there is still room for specialized players in niche segments such as general aviation or aftermarket repairs. Our report provides detailed profiles of key companies shaping the competitive environment, analyzing their strategic moves, product portfolios, and geographic footprints.
Major players such as PPG Aerospace and GKN Aerospace dominate large portions of the original-equipment and aftermarket transparency markets. PPG Aerospace is recognized for its advanced coatings, including SOLARON BLUE PROTECTION UV+ blocking technology, which enhances passenger comfort and reduces cabin heat load. GKN Aerospace stands as a world-leading provider of military transparency systems and holds a strong second position in the commercial aircraft transparency market, with over 2 million CrystalVue II coated windows in service. Their focus on aerospace-grade acrylic and advanced coatings underscores the industry trend toward multifunctional window assemblies.
Saint-Gobain Aerospace continues to supply aircraft windows and windshields trusted by airlines worldwide. A notable recent development includes their partnership with Lilium to supply and support windows and windshields for the Lilium Jet, signaling a strategic pivot toward emerging electric vertical takeoff and landing (eVTOL) and advanced air mobility platforms. This move highlights how traditional aerospace suppliers are diversifying into next-generation aviation sectors.
In the aftermarket and general aviation space, specialized manufacturers play a crucial role. Lee Aerospace specializes in FAA-approved aircraft windows and windshields for business and general aviation aircraft, including brands like Bombardier, Cessna, and Gulfstream. They offer CoolView upgrades and robust aftermarket support, catering to owners seeking performance enhancements. Similarly, L.P. Aero Plastics Inc. stands as a leading FAA-PMA manufacturer of aircraft windshields and windows for the general aviation market with over 60 years of history. Perkins Aircraft Windows manufactures, repairs, and installs business aircraft windshields and cabin windows for a wide range of models, including Citation, Challenger, Embraer, and Falcon.
Other key entities include The NORDAM Group, which provides repair, overhaul, and manufacturing services as part of its global aerospace MRO solutions, and Gentex Corporation, focusing on advanced optical and protective systems. Smaller but significant players like Cee Bailey's Aircraft Plastics and Llamas Plastics, Inc. produce light aircraft windows and transparencies meeting high optical requirements. The presence of these specialized firms indicates a healthy ecosystem where large monopolies coexist with agile specialists capable of serving niche requirements.
Strategic Implications for 2026 Decision Makers
For executives and strategists, the data presented in this report translates into several critical imperatives. First, supply chain resilience is paramount. The concentration of key players in specific regions suggests that geopolitical shifts or localized disruptions could impact availability. Diversifying supplier bases or investing in regional manufacturing capabilities may be necessary to mitigate risk. Second, material innovation offers a pathway to differentiation. Companies that can effectively integrate lightweight polycarbonate solutions without compromising optical quality or safety certifications will capture premium market segments.
Third, the aftermarket presents a stable revenue anchor. With regulatory pressure driving replacement cycles and fleets aging, the MRO segment for windows and windshields is poised for growth independent of new aircraft delivery rates. Service providers who invest in certification and capacity for these replacement cycles will secure long-term contracts. Finally, the emergence of new platform types, such as the Lilium Jet partnership exemplifies, suggests that agility in adapting window technologies to novel airframe designs will be a key differentiator.
Our report goes beyond surface-level observations to provide the operational details needed to execute these strategies. It includes comprehensive scope definitions, research methodologies, and an in-depth analysis of market dynamics that influence pricing, adoption rates, and regional performance. We examine the regulatory landscape, raw material cost structures, and the specific technological advancements that are reshaping the value chain. By integrating quantitative data with qualitative industry context, we provide a holistic view that supports investment appraisal, product development roadmaps, and market entry strategies.
Conclusion
The Worldwide Aircraft Windows Market is at an inflection point. The convergence of rising passenger traffic, regulatory mandates, and material science advancements creates a fertile environment for growth. However, navigating this landscape requires more than general market awareness; it demands precise, data-backed insight. PW Consulting's latest research empowers organizations to look past the aggregate numbers and understand the specific drivers that will define success in 2026 and beyond.
To access the full depth of this analysis, including detailed segmentation data, competitive benchmarking, and region-specific forecasts, we invite you to explore the complete report. The strategic advantages hidden within the data are available to those ready to invest in comprehensive intelligence. Equip your organization with the knowledge needed to steer through the complexities of the aerospace supply chain and capitalize on the transparency revolution.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Windows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pod Hotel Market to Reach $398.1M by 2032 Growing at 7.15% CAGR
By pmarketresearch, 2026-09-16
The Pod Hotel Revolution: A Strategic Blueprint for 2026 and Beyond
The hospitality sector is undergoing a structural transformation driven by the need for space efficiency, cost optimization, and changing traveler preferences. At the forefront of this shift is the pod hotel segment, a niche that has evolved from a novelty into a viable asset class with distinct operational advantages. As enterprises evaluate expansion strategies and asset allocation for 2026 and beyond, understanding the trajectory of this market is no longer optional; it is a strategic imperative.
PW Consulting’s newly released Pod Hotel Market Research Report offers a comprehensive, data-driven examination of this dynamic industry. This document serves as a strategic overview, outlining the market’s growth trajectory, competitive intensity, and operational drivers. It is designed to equip executives, investors, and development teams with the contextual intelligence required to make informed decisions. While this article highlights the strategic framework and key market signals, the full report contains the granular segmentation, quantitative forecasts, and detailed company benchmarking necessary for precise planning.
Market Trajectory: A Decade of Structured Growth
The pod hotel market has demonstrated consistent expansion over the past five years, establishing itself as a resilient component of the broader accommodation sector. Historical data from 2020 through 2025 reveals a steady upward curve, driven by urbanization, the demand for budget-conscious yet technology-enabled accommodations, and the post-pandemic recalibration of travel behaviors. The market has matured beyond early-stage experimentation, achieving a stabilized revenue momentum that signals sustainable growth potential.
Looking ahead, the forecast period from 2026 to 2032 projects a continued expansion with a compound annual growth rate (CAGR) of 7.15%. This growth is underpinned by several converging factors: the increasing prevalence of modular construction technologies, the strategic adoption of pod concepts by both independent operators and established hospitality brands, and the growing preference for compact, efficient urban lodging among specific traveler segments. The revenue trajectory points toward a significant scale-up by the end of the forecast window, reflecting both organic market penetration and the entry of new capital into the space.
Importantly, the market structure remains relatively fragmented. With a CR3 of 15.5% and a CR5 of 22.0%, no single entity or small coalition dominates the landscape. This fragmentation presents a dual strategic reality: it offers flexibility for new entrants and M&A opportunities, but it also necessitates a clear differentiation strategy to capture share in a competitive environment. The data underscores that growth will not be uniform; it will be shaped by regional adoption curves, operational execution, and the ability to integrate technology that enhances the guest experience while controlling costs.
Pod Hotel Market
Core Research Components: Actionable Intelligence for Decision-Makers
The PW Consulting report is structured to bridge the gap between high-level market observation and operational decision-making. It moves beyond descriptive analysis to provide a toolkit for strategic planning. The following sections represent the core pillars of the research, each designed to address specific enterprise needs.
Segmentation Analysis and Demand Drivers
Understanding who occupies these spaces and how they are booked is critical to pricing, location selection, and service design. The report dissects demand across key user typologies, revealing how business travel, leisure, and other usage patterns interact with pod hotel offerings. It examines the booking channel dynamics, analyzing the balance between Online Travel Agencies (OTAs) and direct/walk-in reservations. This channel mix analysis is essential for operators navigating commission structures, brand visibility, and customer relationship management. The research further explores regional variations, identifying where demand is most concentrated and how local market characteristics influence occupancy and average revenue per available pod.
Operational Economics and Construction Dynamics
One of the most compelling value propositions of the pod hotel model is its capital efficiency. The research delves into the economic mechanics of pod deployment, highlighting how modular construction shifts labor to factory settings, reducing on-site dependency and material waste. Standardized pods can be customized and deployed rapidly, often within a three-month timeframe, significantly accelerating the path to revenue generation. The report contextualizes the per-pod construction costs relative to traditional hotel rooms, demonstrating how the lower capital intensity enables faster payback periods, typically ranging from two to four years. This unit economics analysis is vital for developers and lenders assessing project viability and return profiles.
Regulatory and Compliance Landscape
Scaling a pod hotel concept requires navigating a complex web of local building codes and safety standards. The report compiles a detailed overview of the regulatory environment, focusing on fire safety, ventilation requirements, and privacy standards for shared facilities. These compliance factors vary significantly by jurisdiction and can impact design choices, deployment timelines, and operational costs. By mapping these requirements, the research helps stakeholders anticipate barriers to entry and structure their projects to meet local mandates without compromising the core efficiency of the pod model.
Competitive Landscape and Strategic Positioning
The market features a diverse array of players, from minimalist capsule operators focused on sleep optimization to upscale cabin-style accommodations and modular IoT-enabled systems. The report profiles key enterprises, analyzing their value propositions, geographic footprints, and recent strategic moves. Companies like nine hours Inc. are advancing the integration of health and sleep monitoring technologies, signaling a shift toward wellness-oriented hospitality. Others, such as First Cabin and YOTEL, are expanding their reach by positioning pod-style rooms as a premium or transitional experience between traditional budget and business hotels. Meanwhile, agile operators like Bobobox are rapidly expanding their networks, leveraging modular designs to penetrate urban and nature locations alike.
The competitive analysis also tracks recent developments that signal market momentum. New property openings, such as the latest nine hours location in Shinjuku featuring a collaboration for sleep and health monitoring, illustrate the focus on differentiating through technology and wellness partnerships. Network expansions by regional players and new construction starts in European markets highlight the global spread of interest. The research evaluates these moves to identify patterns in capital deployment, target demographics, and brand positioning, helping readers benchmark their own strategies against industry leaders.
Strategic Implications for 2026 Enterprise Decisions
As organizations formulate their strategies for 2026, the pod hotel market presents several actionable pathways. The data and analysis within the report support decision-making across multiple dimensions:
- Market Entry and Site Selection: The regional demand patterns and regulatory insights enable targeted site selection, reducing the risk of misaligned investments. Enterprises can identify high-potential zones where the combination of traveler profile, land costs, and regulatory feasibility aligns with the pod model.
- Capital Allocation and Phasing: The unit economics and construction timelines provide a framework for phased deployment. Investors and developers can structure capital calls to match the rapid build-out cycles of modular pods, optimizing cash flow and mitigating exposure to construction delays.
- Technology Integration and Differentiation: The emphasis on IoT features, sleep analytics, and compact efficiency highlights opportunities to embed technology that enhances guest experience and operational control. Companies can leverage these insights to design service offerings that justify premium positioning or drive higher occupancy through unique value propositions.
- Partnership and M&A Opportunities: Given the fragmented market structure, there are clear avenues for consolidation, franchising, or joint ventures. The competitive profiling and recent development tracking help identify potential partners or acquisition targets that complement an existing portfolio or accelerate market entry.
- Risk Mitigation and Compliance: A proactive understanding of building codes, safety standards, and operational constraints allows enterprises to design compliant facilities from the outset, avoiding costly retrofits and delays. The report’s regulatory overview serves as a reference point for engaging with local authorities and engineering partners.
Conclusion: Navigating the Next Phase of Pod Hospitality
The pod hotel market is at an inflection point where early adoption is giving way to scaled, disciplined growth. The convergence of lower construction costs, modular deployment speed, and evolving traveler expectations creates a favorable environment for strategic investment. However, success in this space requires more than a conceptual appeal; it demands rigorous market analysis, precise financial modeling, and a clear understanding of competitive dynamics.
PW Consulting’s Pod Hotel Market Research Report delivers the depth and granularity required to navigate this landscape. It provides the historical context, forward-looking forecasts, and competitive intelligence that enterprise leaders need to validate hypotheses, refine strategies, and execute with confidence. For those seeking to capitalize on the opportunities within this segment, the full report offers the detailed segmentation data, region-specific insights, and comprehensive company benchmarks that form the bedrock of informed decision-making.
Worldwide Hotel Market
We invite stakeholders to explore the complete research to access the full spectrum of data and analysis. The strategic clarity gained from this intelligence will be instrumental in shaping successful outcomes in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pod Hotel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Column Bioimpedance Analyzer Market to Reach $907.86M by 2032, CAGR 9.02%
By pmarketresearch, 2026-09-16
Strategic Horizons in the Worldwide Column Bioimpedance Analyzer Market: A 2026 Decision-Maker's Preview
Executive Overview: Why This Intelligence Matters Now
The global healthcare technology landscape is undergoing a profound transformation, driven by an aging population, the rising prevalence of chronic diseases, and an escalating emphasis on preventative wellness. Within this volatile environment, the Worldwide Column Bioimpedance Analyzer Market stands out as a critical nexus of medical diagnostics and consumer health technology. As we move deeper into 2026, understanding the trajectory of this sector is not merely an academic exercise but a fundamental requirement for strategic planning.
PW Consulting is proud to introduce our latest comprehensive market research study, designed specifically to equip stakeholders with the actionable intelligence needed to navigate the forecast period of 2026 through 2032. This report serves as a strategic compass, offering a granular view of market dynamics, competitive forces, and technological shifts that will define the next decade of body composition analysis. By leveraging historical data from 2020 to 2025 and projecting forward, we provide a robust framework for risk assessment and opportunity identification.
For investors, manufacturers, and healthcare providers, the stakes have never been higher. The convergence of regulatory scrutiny, reimbursement policy evolution, and rapid innovation in multi-frequency segmentation technology requires a decision-making framework grounded in hard data. This article outlines the strategic value of our forthcoming analysis, highlighting the macro-environmental factors and competitive intricacies that will shape market leadership in the coming years.
Market Trajectory and Financial Forecast
The financial narrative of the column bioimpedance analyzer sector is characterized by consistent upward momentum, reflecting the broadening adoption of body composition monitoring across clinical and wellness settings. Our analysis traces the market's evolution from a base year of 2020, capturing the recovery and expansion phases post-pandemic, through to the current baseline in 2025.
The data indicates a substantial expansion in total market revenue, measured in USD millions, over the historical period. This growth has been fueled by increased procurement of medical-grade devices in hospitals and the surge in consumer interest regarding precise body metrics. Looking ahead, the forecast period from 2026 to 2032 suggests a continuation of this positive trajectory. The Compound Annual Growth Rate (CAGR) during this forecast window is projected to sustain robust expansion, signaling strong market confidence and sustained demand drivers.
Key financial milestones outlined in our full report include the valuation progression from 2026 through 2032. Stakeholders reviewing the complete dataset will observe how revenue streams are expected to compound, influenced by both volume growth in emerging markets and value growth in developed regions through premium product placements. The transition from single-frequency to multi-frequency technologies is a significant driver of this value increase, as higher precision commands higher price points and broader clinical adoption. Understanding these financial levers is essential for capacity planning, R&D budgeting, and merger and acquisition strategy.
Segmentation Dynamics: Technology, Application, and Geography
The market is not a monolith; it is a complex tapestry woven from distinct technological preferences, end-user requirements, and regional economic conditions. Our research dissects these layers to reveal where value is being created and captured.
Technology Type: The Multi-Frequency Shift
A critical divide exists within the product landscape between single-frequency and multi-frequency bioimpedance analyzers. The industry is witnessing a decisive migration toward multi-frequency segmental analysis. This technology provides superior accuracy in distinguishing between fat mass, body water, and muscle tissue, making it indispensable for clinical diagnostics and high-end wellness tracking. While single-frequency units retain presence in cost-sensitive segments, the revenue contribution and growth rate of multi-frequency column-type analyzers are outpacing their counterparts. The full report details the revenue attribution of these technology types, offering insights into where R&D investment will yield the highest returns.
End-User Landscape
The demand source for these analyzers is diverse. Hospitals and clinics remain primary purchasers, driven by the need for diagnostic tools that integrate seamlessly into patient care workflows for conditions ranging from renal failure to oncology-related lymphedema. However, the fitness and wellness sector represents a formidable and rapidly growing pillar of demand. As consumers become more data-literate regarding their health, professional wellness centers are upgrading their equipment to provide research-grade insights to clients. Additionally, academic and research institutes continue to utilize these devices for longitudinal studies, while home healthcare is an emerging frontier as portable and connected devices gain traction. Our analysis breaks down the revenue contributions across these end-user groups without oversimplifying the nuances of procurement cycles in each sector.
Regional Perspectives
Geographic deployment of column bioimpedance analyzers varies significantly based on healthcare infrastructure, reimbursement policies, and competitive density. North America maintains a dominant position, supported by a robust medical device ecosystem and favorable reimbursement coding for specific bioimpedance applications. Europe follows as a mature market with strong regulatory frameworks driving device quality. Asia Pacific presents a high-growth opportunity, fueled by expanding healthcare access and a large population base increasingly focused on preventative health. Latin America and the Middle East and Africa constitute emerging avenues where market penetration is still in developmental stages but holds long-term potential. The comprehensive report provides a detailed view of these regional dynamics, helping organizations tailor their go-to-market strategies to local realities.
Competitive Landscape and Strategic Positioning
The market concentration indicates a moderately consolidated environment where key players hold significant sway. With the top three companies commanding a substantial share of the market and the top five consolidating further, barriers to entry remain high for new competitors lacking established distribution networks or proprietary technology. Our report provides a deep dive into the profiles and strategic moves of major industry participants.
Key Market Participants
Several global entities define the current competitive frontier. InBody Co., Ltd. , headquartered in Seoul, South Korea, continues to be a powerhouse in the segment, offering multiple column and standing-type analyzers with multi-frequency segmental analysis capabilities. Their model range supports precise fat mass and body water assessment, catering to both clinical and research needs. Meanwhile, Tanita Corporation of Tokyo, Japan, provides robust column-type multi-frequency segmental body composition analyzers, including models with column kits designed for clinical and professional assessment of fat, muscle, bone, and water.
Ion Chromatography Column Market
In the medical device space, seca GmbH & Co. KG from Hamburg, Germany, develops medical body composition analyzers with advanced BIA technology, often validated against gold-standard models like MRI and 4C for fat mass and skeletal muscle analysis. Charder Electronic Co., Ltd. , based in Taichung, Taiwan, manufactures column-mounted analyzers using bioelectrical impedance for medical and professional tracking, including visceral fat metrics. Marsden Weighing Machine Group in the United Kingdom offers column-type analyzers with class III grading and BMI calculations for clinical use. Finally, manufacturers in China, such as Zhongshan Jinli Electronic Weighing Equipment Co., Ltd. , produce column-type analyzers for routine and customizable human body composition analysis, often targeting cost-effective segments.
Recent Developments and Regulatory Headwinds
The competitive field is dynamic, with regulatory milestones acting as significant moats. For instance, in January 2026, ImpediMed Limited received FDA 510(k) clearance for MySOZO Software version 6.0.1.2. This update enhances the bioimpedance spectroscopy platform for L-Dex assessment in lymphedema, a development that underscores the importance of regulatory compliance and software integration in maintaining market leadership. Although this specific clearance relates to spectroscopy, it signals the broader industry trend where advanced bioimpedance technologies are being scrutinized and validated for specific clinical indications.
Furthermore, the regulatory environment remains a critical factor. Bioimpedance analyzers intended for clinical use must comply with FDA Class II clearance (510(k)) in the United States and CE marking as Class IIa medical devices in the European Union. Medical-grade bioimpedance spectroscopy devices also require compliance with ISO 13485 quality management standards. These requirements ensure accuracy and patient safety but also create compliance costs that favor established players. Additionally, reimbursement dynamics, such as CPT code 93702 covering bioimpedance spectroscopy for extracellular fluid analysis in lymphedema assessment, influence the purchasing power of healthcare providers. Understanding these regulatory and reimbursement layers is vital for market entry and product positioning.
Strategic Implications for Stakeholders in 2026
As organizations formulate their strategies for the remainder of 2026 and beyond, several key implications emerge from our market intelligence.
- Technology Investment: Companies should prioritize R&D in multi-frequency segmental analysis. The shift towards higher precision is not just a technological upgrade but a value driver that justifies premium pricing and expands clinical utility.
- Regulatory Compliance: With tightening regulations around medical device classification and quality management standards, maintaining rigorous compliance is no longer optional. It is a competitive advantage that builds trust with healthcare providers and payers.
- Market Diversification: While hospitals remain a core customer base, there is significant untapped potential in fitness, wellness, and home healthcare. Strategies that address the specific needs of these sectors—such as usability, connectivity, and cost-efficiency—can unlock new revenue streams.
- Regional Targeting: Growth rates vary by region. Developed markets may offer stability and higher unit prices, while emerging markets offer volume growth. A balanced portfolio approach allows companies to mitigate regional economic risks.
- Competitive Monitoring: The market concentration suggests that competitive moves by top players can shift market dynamics quickly. Continuous monitoring of competitor product launches, partnerships, and regulatory filings is essential for staying ahead.
Conclusion: Accessing the Full Intelligence
The Worldwide Column Bioimpedance Analyzer Market is at an inflection point, driven by technological advancement, regulatory evolution, and shifting healthcare priorities. For decision-makers, generalizing market trends is insufficient. Success requires a granular understanding of revenue splits, regional nuances, end-user preferences, and competitive strategies.
This article serves as a preview of the depth and breadth of insight available in PW Consulting's full Worldwide Column Bioimpedance Analyzer Market research report. We have highlighted the macro trajectory and the critical factors at play, but the detailed data—the specific revenue contributions by segment, the precise growth rates by region, and the in-depth competitive benchmarking—is essential for crafting a winning strategy.
Worldwide Column Bioimpedance Analyzer Market
To access the complete analysis, including the full dataset covering 2020 to 2032, detailed company profiles, and actionable strategic recommendations, we invite you to explore the full report on the PW Consulting website. Equip your organization with the intelligence needed to navigate the future of body composition analysis with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Column Bioimpedance Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Off-Highway Wheels Market Hits $8.4B in 2025, 5.6% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Horizons: Navigating the Worldwide Off-highway Wheels Market Through 2032
A Comprehensive Intelligence Briefing for Executive Decision-Makers
The global off-highway wheels market stands at a critical inflection point. As heavy equipment manufacturers, fleet operators, and component suppliers plan their strategic moves for the remainder of the decade, understanding the trajectory of this essential industrial component market is no longer optional—it is a prerequisite for competitive advantage. This analysis draws upon the latest comprehensive research to illuminate the market's structural dynamics, growth vectors, and competitive intensity, providing the foundational intelligence necessary for informed capital allocation and product strategy development.
Based on rigorous historical analysis spanning 2020 through 2025 and extending forward through 2032, the worldwide off-highway wheels market is projected to follow a disciplined growth trajectory. The market generated revenues of approximately 8.4 billion USD in 2025, building on a base of roughly 8.0 billion USD the previous year. Looking ahead, the forecast period from 2026 to 2032 anticipates a compound annual growth rate of 5.6 percent, culminating in a market valuation that exceeds 12.3 billion USD by the close of the forecast window. These figures represent more than abstract statistics; they encode the underlying momentum of global infrastructure investment, agricultural mechanization, and mining activity that drives demand for rugged, reliable wheel assemblies capable of operating in the most demanding terrains and heaviest load conditions.
For enterprises operating in or adjacent to this space, the takeaway is clear. The market is expanding at a pace that rewards those who can align product development cycles, supply chain readiness, and regional go-to-market strategies with the emerging growth pockets. Yet the headline numbers only scratch the surface. The real value lies in dissecting how different material preferences, end-user verticals, and geographic demand centers interact with macroeconomic forces, raw material price volatility, and an evolving regulatory landscape that increasingly mandates compliance with stringent safety and performance standards.
Deconstructing the Demand Architecture: Material Choices, End-User Verticals, and Regional Weightings
Any serious strategic assessment of the off-highway wheels market must begin with a granular understanding of the segmentation architecture that shapes revenue pools and competitive positioning. The market is fundamentally divided along three axes: material composition, end-user application, and regional consumption patterns. Each axis reveals distinct customer requirements, pricing sensitivities, and supply chain considerations that dictate where incumbents can defend share and where new entrants or expanding players can capture ground.
Material Dynamics: The Enduring Primacy of Steel and the Gradual Rise of Alternatives
Steel remains the defining material choice for the majority of off-highway wheels produced globally. Its allure is rooted in a combination of affordability, structural strength, and proven capacity to withstand the extreme torsional and compressive loads encountered in agriculture, construction, and mining environments. Steel wheels, particularly those configured in multi-piece designs such as three-piece and five-piece assemblies, offer maintenance flexibility, ease of tire mounting and replacement, and a durability profile that fleet operators have trusted for decades. The global steel ecosystem supporting this demand is vast. World steel demand is projected at approximately 1,749 million tonnes in 2025, with a modest rebound of 1.3 percent anticipated in 2026, signaling that the raw material backbone underpinning off-highway wheel manufacturing will remain stable albeit with periodic price fluctuations that require active procurement management.
That said, the material narrative is not monolithic. Aluminum wheels represent a complementary segment, gaining traction in applications where weight reduction translates directly into operational efficiency, fuel economy, or payload optimization. While steel commands the overwhelming majority of market revenue, aluminum's share underscores a strategic divergence: customers in certain segments are willing to pay a premium for lighter components that reduce machine strain, improve maneuverability, and align with broader sustainability and electrification agendas. The interplay between these two materials will continue to shape product portfolios, supplier capabilities, and regional manufacturing footprints throughout the forecast period.
End-User Verticals: Where the Revenue Flows
The end-user segmentation reveals a market anchored by heavy-duty sectors that cannot compromise on wheel reliability. Agriculture constitutes a massive revenue center, driven by the continuous expansion of mechanized farming, precision agriculture adoption, and the replacement cycle of aging equipment across diverse geographic markets. Construction and mining represent the second major pillar, with demand fueled by large-scale earthmoving projects, resource extraction activities, and infrastructure build-out programs that require wheels capable of surviving abrasive surfaces, rocky terrain, and continuous high-load operation.
Industrial and forestry applications, while smaller in relative terms, represent a specialized niche where wheel specifications must accommodate unique operational parameters such as steep gradients, dense vegetation, and specialized vehicle configurations. Understanding the distinct purchasing behaviors, replacement cycles, and specification requirements within each vertical is essential for any supplier seeking to optimize its sales coverage, aftermarket support, and inventory positioning.
Regional Footprints: Mapping Demand Concentration
Geographically, the market exhibits pronounced regional disparities that reflect the distribution of heavy equipment manufacturing, agricultural intensity, mining activity, and infrastructure investment. Asia Pacific commands the largest share of market revenue, reflecting both the scale of industrial and agricultural activity across the region and the growing localization of equipment manufacturing and component supply chains. North America and Europe constitute significant secondary markets, each with mature equipment bases, stringent compliance requirements, and a strong presence of major original equipment manufacturers and aftermarket distributors.
Latin America and the Middle East and Africa, while smaller in absolute revenue terms, represent emerging demand zones where resource extraction, land development, and agricultural modernization are generating incremental growth. For companies evaluating market entry, expansion, or localized production strategies, the regional breakdown provides a roadmap for prioritizing sales territory investments, establishing distribution partnerships, and tailoring product specifications to regional operating conditions and regulatory frameworks.
Watching the Competitive Battlefield: Intensity, Consolidation, and Strategic Posturing
The off-highway wheels market is characterized by a competitive landscape that blends established global manufacturers with specialized regional players, each leveraging distinct advantages in manufacturing scale, engineering heritage, product breadth, andcustomer intimacy. Market concentration metrics indicate that the top three players collectively account for approximately 42.5 percent of total market revenue, while the top five expand that share to roughly 58.8 percent. This level of concentration signals a market where scale, brand reputation, and long-standing OEM relationships confer meaningful defensive moats, yet it also leaves substantial room for specialized suppliers and regional specialists to compete on customization, service responsiveness, and niche application expertise.
Profiles of Leading Competitors and Their Strategic Anchors
Titan International, Inc., headquartered in West Chicago, Illinois, operates as a leading global manufacturer of off-highway wheels, tires, assemblies, and undercarriage products serving agricultural, construction, earthmoving, and consumer markets. Its dual focus on OEM supply and aftermarket distribution, combined with a durability-centric product philosophy, positions it as a comprehensive solutions provider for heavy-duty off-highway applications.
Moveero Limited, based in the United Kingdom and tracing its lineage back to 1908, has built a world-leading reputation in off-highway steel wheels, with particular expertise in innovative three- and five-piece wheel designs for earthmoving, agriculture, and construction equipment. The company supplies major global OEMs with high-performance solutions including flotation wheels engineered to maximize ground contact and reduce soil compaction. Recent developments underscore Moveero's continued investment in product leadership: in March 2026, the company launched Profi-Max, a next-generation high-performance flotation wheel for off-highway applications, and in January 2026 it showcased its industry-leading wheel solutions including a new hubs range at the Farm Progress show. Earlier in June 2025, Moveero was featured in a Manufacturing Marvels broadcast on Fox Business Network, highlighting the sophistication of its off-highway wheel manufacturing operations.
Maxion Wheels, located in Novi, Michigan, stands as the world's largest manufacturer of steel wheels, producing components for passenger cars, light trucks, and commercial and off-highway vehicles, including heavy-duty industrial applications in mining, agriculture, and construction. Its sheer scale provides advantages in procurement, production efficiency, and global distribution reach, making it a formidable benchmark against which competitors must differentiate through speed, customization, or specialized engineering.
Accuride Corporation, operating from the United States, remains a major producer of wheels and rims for commercial and off-highway vehicles, with a focus on durable steel wheels engineered for heavy-duty applications in construction, mining, and agriculture. The company's product durability and application-specific engineering reinforce its position within the industrial supply chain.
Off Highway Vehicle Engine Market
Trelleborg AB, headquartered in Sweden, brings a distinct materials science perspective to the market, providing off-highway wheels and integrated wheel-tire systems for agricultural, construction, and industrial equipment. Its emphasis on advanced materials and performance in demanding terrains reflects a strategy that blends wheel engineering with broader system-level optimization, appealing to customers seeking holistic solutions rather than component-level procurement.
Topy Industries Ltd., based in Japan, manufactures steel wheels for off-highway and commercial applications, serving agriculture, construction, and mining sectors with high-strength products that draw on Japanese precision engineering traditions. RIMEX Supply Ltd., from Canada, specializes in off-highway wheels for mining, construction, and earthmoving equipment, with a reputation for custom and heavy-duty wheel solutions designed to perform in extreme operating conditions. OTR Wheel Engineering, in the United States, concentrates on off-highway and OTR wheels for mining, construction, and industrial applications, emphasizing durability and specialized designs tailored to the harshest service environments.
Additional competitors further enrich the competitive mosaic. Carrier Wheels Pvt. Ltd., in India, manufactures steel wheels including heavy-duty industrial wheels for mining, agriculture, and construction environments, capitalizing on the growing localization of component supply in South Asia. Titan Steel Wheels, operating from the United Kingdom, designs, manufactures, and exports off-highway wheels in three- and five-piece configurations for earthmoving and demanding projects worldwide. Sun Tyre and Wheel Systems produces off-highway wheels for agricultural, construction, and mining equipment, while Jantsa Jant Sanayi, based in Turkey, manufactures wheels for off-highway and heavy-duty applications, benefiting from its positioning between European and Middle Eastern demand centers. Steel Strips Wheels Limited, in India, supplies steel wheels for off-highway and commercial vehicle segments, STARCO provides wheels and wheel systems for off-highway machinery including agriculture and construction, and Pronar Wheels, in Poland, manufactures wheels for agricultural and off-highway equipment, collectively illustrating the breadth of regional manufacturing capabilities that support global supply chains.
Innovation Signals: Product Launches, Trade Presence, and Financial Momentum
The competitive landscape is further animated by visible innovation and commercial activity that signals where players are directing their investment. Beyond Moveero's Profi-Max launch and Farm Progress exhibition, Evolution Wheel showcased its EWRS-series airless off-highway tires and wheels lineup at ConExpo 2026, highlighting the industry's exploration of airless technologies that promise reduced maintenance, puncture resistance, and operational continuity in remote or hazardous environments. Titan International, meanwhile, announced plans in February 2026 to report Q4 2025 financial results, reinforcing its continued role as a leading producer navigating the interplay of market demand, raw material costs, and global supply chain dynamics. These developments collectively suggest an industry that is not merely sustaining legacy products but actively pursuing next-generation designs, new material applications, and enhanced system integration to capture emerging value pools.
Navigating the Forces Reshaping Market Dynamics
The trajectory of the off-highway wheels market is not determined by demand alone. A constellation of structural forces is reshaping how products are specified, manufactured, priced, and supported throughout their lifecycle. Smart strategists will treat these forces not as external noise but as core variables in their planning models.
Worldwide Off-highway Wheels Market
Raw Material Realities: Steel Pricing, Availability, and Procurement Strategy
Steel's dominance in off-highway wheel manufacturing ties market participants directly to the broader steel economy. With global steel demand projected at approximately 1,749 million tonnes in 2025 and a modest 1.3 percent rebound expected in 2026, the raw material base appears stable, yet price volatility remains a persistent risk. In the United States, structural steel prices stood at $2,477.25 per ton in October 2025, a level that directly influences manufacturing cost structures, margin planning, and the ability to offer competitive pricing in both OEM and aftermarket channels. Companies that succeed will be those that build robust procurement hedging strategies, maintain flexible supplier relationships, and integrate cost modeling into product planning well ahead of price cycles turning.
Regulatory and Standards Compliance: A Non-Negotiable Baseline
Compliance with recognized standards forms a foundational requirement for market participation. Off-highway wheels and related equipment must adhere to SAE standards such as J237, J236, and J319b governing braking systems on self-propelled rubber-tired machinery, alongside broader occupational safety regulations including OSHA 1926.602. For manufacturers and suppliers, maintaining rigorous compliance is not merely a defensive obligation; it is a competitive credential that reassures OEMs, end-users, and fleet managers that components will perform safely under regulated operating conditions. As regulatory scrutiny intensifies across jurisdictions, those with well-documented quality systems and traceable testing protocols will find it easier to secure contracts and expand into regulated markets.
Macro Trends: Lightweighting, Sensor Integration, and Electrification-Compatible Design
Beyond traditional durability and load-bearing requirements, an emerging set of macro trends is reshaping customer expectations. There is an increasing focus on lightweight materials, sensor integration, and electrification-compatible designs in off-highway wheels, driven by the pursuit of improved efficiency, reduced operational emissions, and alignment with sustainability goals in heavy equipment. Electrification introduces new considerations around torque delivery, thermal management, and wheel geometry optimization, while sensor integration enables predictive maintenance, load monitoring, and real-time performance analytics that can reduce downtime and extend service life. Suppliers that begin embedding these capabilities into their product roadmaps now will be better positioned to capture premium specifications and long-term service agreements as equipment fleets evolve.
Inside the Research: What the Complete Analysis Delivers
The accompanying Worldwide Off-highway Wheels Market research publication is designed to move beyond high-level market sizing and provide the operational intelligence that strategy teams, product managers, and commercial leaders require to execute with confidence. The analysis covers the historical period from 2020 through 2025 and offers a detailed forecast extending to 2032, using a base year of 2025 and expressing all revenue figures in USD millions. Throughout the document, readers will find a thorough examination of market segmentation by region, material, and end-user, with granular data that exposes relative share, growth rates, and structural shifts without relying on surface-level aggregates.
The competitive landscape section profiles the key companies shaping the market, combining corporate overviews, product and application coverage, recent developments such as product launches, exhibition participation, media features, and financial announcements, and an assessment of strategic positioning that reveals where each player is vulnerable and where it holds advantage. The report also integrates an analysis of raw material dynamics, regulatory frameworks, and macro trends, connecting these external forces to specific implications for pricing, sourcing, product development, and market entry timing.
For executives evaluating investment in capacity, toolings, new product lines, or geographic expansion, the research provides the evidentiary base to test assumptions, size opportunities, and calibrate risk. For procurement and supply chain leaders, it illuminates cost drivers, material trends, and supplier concentration patterns that inform negotiation strategy and inventory planning. For sales and marketing teams, the segmentation detail supports territory prioritization, specification targeting, and messaging alignment with the distinct needs of agriculture, construction and mining, and industrial and forestry customers.
Conclusion: Turning Intelligence into Action
The worldwide off-highway wheels market is entering a phase where disciplined growth intersects with rapid technological and regulatory evolution. The projected expansion from approximately 8.4 billion USD in 2025 toward over 12.3 billion USD by 2032, at a compound annual growth rate of 5.6 percent, offers a compelling growth narrative, but sustainable success will belong to organizations that pair that top-line optimism with granular insight into material choices, end-user requirements, regional demand centers, competitive maneuvering, and the structural forces that will redefine value creation over the next several years. The complete research publication delivers the depth required to convert market awareness into executable strategy, equipping decision-makers with the clarity to invest confidently, differentiate intelligently, and outperform in a market where durability, compliance, and innovation are increasingly inseparable.
For detailed analysis of this topic, please visit the official page: Worldwide Off-highway Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide IT Market Hits $5.7B in 2025, Projected to Reach $9.93B by 2032 at 8.25% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Wave: Navigating the Worldwide Information Technology Market in 2026
The global information technology landscape is undergoing a structural transformation that demands more than incremental budgeting or reactive procurement. As organizations move deeper into an AI-augmented, hyperconnected operating environment, the capacity to distinguish durable growth from temporary hype has become a critical strategic competency. PW Consulting’s latest Worldwide Information Technology Market research study provides that distinguishing lens, synthesizing historical performance, forward-looking projections, and competitive intelligence into a single decision-ready framework. For leaders planning capital allocation, capability building, and market positioning throughout 2026 and beyond, this research offers the operational clarity required to act with precision rather than speculation.
The study opens with a clear macroeconomic baseline: the worldwide IT market has expanded from an estimated 3.92 trillion USD in 2020 to approximately 5.70 trillion USD in 2025, reflecting sustained enterprise digitization, cloud migration, and the emergence of generative AI as a core operational driver. Looking ahead, the forecast period through 2032 projects continued expansion at a measured compound annual growth rate of 8.25 percent, with the market trajectory climbing toward nearly 10 trillion USD by the final projection year. These figures are not abstract indicators; they frame the scale of investment, capability development, and competitive positioning that enterprise leaders must now plan for. The revenue is tracked in USD millions, providing consistent comparability across time horizons, and the growth profile suggests that IT spending will remain a central pillar of corporate strategy rather than a discretionary cost center.
Before executives attempt to translate these top-line trajectories into portfolio decisions, it is essential to understand where momentum is concentrated and how it is flowing through the ecosystem. The research deliberately segments the market across type, application, and geographic dimensions, allowing decision-makers to see how capital and demand are distributed across the value chain without overwhelming them with raw spreadsheets. Rather than treating the IT market as a monolith, the analysis reveals the underlying balance between IT services, software, devices, communications services, and data center systems, each carrying distinct margin profiles, adoption cycles, and competitive dynamics. The same logic applies to end-use verticals, where enterprise deployments, consumer adoption, government and public sector programs, and small and medium business digitization present different buying behaviors, procurement cycles, and resilience factors.
This segmentation foundation matters because 2026 is shaping up as a year of divergence. Recent industry signals indicate that spending on servers, storage, and network equipment is accelerating sharply as service providers expand data center infrastructure to accommodate AI workloads and cloud-native architectures. At the same time, semiconductor revenue is projected to climb to levels not seen in decades, with memory markets experiencing particularly pronounced expansion. These shifts are not isolated technical trends; they represent structural changes in how IT capacity is built, where value is captured, and which vendors are positioned to influence enterprise buying behavior. In parallel, trade exhibitions and analyst forecasts have emphasized robotics enabled by physical AI, digital health innovation, and advanced mobility as reinforcing themes within the broader IT ecosystem, while strategic trends for the year increasingly center on domain-specific language models and AI-powered connectivity across business functions.
Equally important, macro and regulatory conditions are reshaping the operating environment. Tariff policies and geopolitical tensions continue to introduce supply chain uncertainty for IT hardware and semiconductor components, prompting organizations to invest in resilient sourcing strategies and cloud-based visibility tools. AI-driven investment across telecom, fiber, and data centers is also accelerating infrastructure development, making the TMT sector’s physical and digital layers more interdependent than ever. In that context, the strategic question for senior leaders is no longer whether IT will remain a growth engine, but how to allocate resources in a market where innovation cycles, regulatory exposure, and supply-side volatility intersect.
What the Research Delivers: Operational Content for 2026 Decision-Making
PW Consulting’s Worldwide Information Technology Market study is designed to move directly from market structure to actionable planning. The report assembles a comprehensive historical record spanning 2020 through the base year of 2025, then extends forward across a multi-year forecast period through 2032. This dual lens allows organizations to test strategic assumptions against both proven performance patterns and expected transitions in demand. Historical data illuminates how the market absorbed shocks, scaled cloud and services growth, and rebalanced around shifting enterprise priorities. The forecast component, meanwhile, translates those patterns into forward indicators that support budget planning, capacity modeling, and investment prioritization.
Segmentation Analysis That Supports Portfolio Strategy
One of the most valuable components of the research is its segmentation architecture. By disaggregating the market into type, application, and regional dimensions, the study enables leaders to examine how growth is distributed across the IT ecosystem rather than relying on a single aggregate figure. This approach supports more precise questions: Where is incremental spending likely to appear? Which segments are expanding on the back of structural infrastructure demand, and which are being reshaped by software-led transformation or services migration? How does demand differ between large enterprise buyers and smaller commercial entities? Because the report maintains a consistent unit framework in USD millions throughout, readers can compare relative scale without losing sight of absolute investment levels.
The analysis is intentionally built to support segmentation-informed strategy. For technology vendors, this means clearer insight into which product and service categories are most relevant to near-term growth narratives. For enterprise buyers, it means better visibility into where cost, speed, and capability trade-offs are likely to emerge. For investors and advisors, it means a more defensible basis for assessing which parts of the market are consolidating around durable demand and which are subject to faster disruption or substitution.
Competitive Intelligence Grounded in Company Profiles
A market of this size is shaped not only by end-user demand but also by the strategies of a concentrated set of leading firms. The report integrates detailed profiles of core participants across the IT ecosystem, capturing their headquarters, primary capabilities, and strategic positioning. These include organizations spanning cloud platforms, productivity suites, AI tooling, operating systems, semiconductor and data center infrastructure, enterprise databases, business applications, hybrid cloud, IT services, digital transformation consulting, and application development. Each profile is structured to help readers understand not just what a company offers today, but how it is positioned relative to the demand shifts that the forecast anticipates.
Worldwide Information Technology Market
The competitive picture is especially relevant given the market’s concentration profile. The top three firms account for roughly 14.82 percent of overall market share, while the top five firms account for approximately 21.35 percent. That level of concentration does not imply a static landscape; rather, it signals where competitive pressure, ecosystem influence, and partnership leverage are likely to concentrate in 2026. Companies outside the top tier still play essential roles in implementation, services delivery, and regional execution, but large platform players continue to shape pricing expectations, integration norms, and enterprise adoption patterns across cloud, software, and AI-enabled services.
To complement these corporate profiles, the study integrates recent developments that illustrate how market participants are reacting to structural change. Industry output from late 2025 and early 2026 highlights a strong spending environment, with worldwide IT investment projected to grow significantly in 2025 and maintain positive momentum into 2026, driven by AI infrastructure, cloud services, and device refresh cycles. Simultaneously, semiconductor revenue forecasts point to one of the strongest growth intervals in recent history, reinforcing the importance of hardware and data center capacity in the broader IT economy. Analyst commentary and industry events further underscore domain-specific AI, robotics, digital health, and advanced mobility as themes that are becoming embedded in mainstream IT planning rather than remaining peripheral innovation stories.
Why This Research Matters for 2026 Strategy
For executives and strategy teams, the value of this research lies in its ability to connect market scale with operational decision-making. The data does more than confirm that IT continues to grow; it defines the magnitude of that growth, the timeframe over which it is expected to unfold, and the degree of concentration within the competitive field. That combination helps organizations answer a set of core strategic questions: How much capacity should we plan for? Which demand pools should we prioritize? Where do we face the greatest exposure to supply chain or tariff-related disruption? How should we position ourselves relative to dominant platforms and service providers?
The practical applications are broad. A CIO planning a multi-year technology roadmap can use the macro trajectory and segmentation structure to validate investment phasing and align procurement with anticipated demand shifts. A product leader can use the type-based segmentation to identify where service, software, or infrastructure demand is likely to be strongest, and adjust roadmap focus accordingly. A corporate development team can use the competitive profiles and concentration data to assess partnership, acquisition, and ecosystem entry opportunities with a realistic sense of market power distribution. A risk and operations leader can use the latest industry dynamics to anticipate supplier-side volatility and adjust sourcing, inventory, or cloud dependency strategies.
Because the report is built around both history and forecast, it also supports scenario planning. Decision-makers can examine how sensitive their plans are to different adoption speeds, how exposure to specific segments may shift over time, and where the difference between headline growth and segment-level realities is most pronounced. That capacity is especially important in a market where AI infrastructure, data center expansion, and advanced connectivity are reshaping spending priorities faster than traditional budgeting cycles can accommodate.
How the Study Turns Market Complexity into Executive Clarity
PW Consulting’s approach emphasizes clarity without oversimplification. The study preserves the granularity needed for serious planning while organizing the information so that leadership teams can move quickly from market context to internal implications. Historical revenue trends demonstrate how the market has scaled over the last several years; the forward forecast establishes a structured view of expected momentum through the end of the decade and into the early 2030s; segmentation data allows readers to separate broad growth from segment-specific dynamics; and competitive profiles translate market structure into strategic awareness.
This is not a static market description. It is a working base for strategic action in 2026, when IT spending behavior is being reshaped by AI-led infrastructure demand, cloud expansion, hardware refresh cycles, and a more uncertain geopolitical and supply chain environment. Leaders who rely on aggregate narratives alone risk misjudging where growth is concentrated, where costs will move, and where competitive advantage can be built. The research is designed to reduce that risk by providing a structured, evidence-based view of the market as it is today and as it is expected to evolve.
IT Services Market
The full depth of this analysis is available in the complete Worldwide Information Technology Market report, where the underlying segment detail, regional context, company intelligence, and forecast logic are presented in full. For organizations that need to move from high-level awareness to committed investment decisions, the complete study offers the granular intelligence necessary to align strategy with market reality and to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Information Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Battery Software Market Hits $1,127.29M in 2025, Projected 18.24% CAGR to $3,642.24M by 2032
By pmarketresearch, 2026-09-16
Navigating the Battery Manufacturing Software Boom: Strategic Imperatives for 2026 and Beyond
The global battery manufacturing software market is undergoing a transformation that mirrors the electrification of the automotive industry itself. No longer a back-office utility, manufacturing software has become the central nervous system of gigafactory operations, influencing everything from cell yield rates to regulatory compliance. According to our latest research, the worldwide market for battery manufacturing software is projected to expand from an estimated 1,127.29 million USD in 2025 to 3,642.24 million USD by 2032. This trajectory represents a compound annual growth rate of 18.24 percent over the forecast period.
Such figures are not merely indicators of market expansion. They signal a structural shift in how battery producers approach scalability, quality assurance, and operational intelligence. As capital intensity rises and regulatory scrutiny tightens, software platforms that once supported discrete manufacturing processes are being reimagined as integrated digital threads. For executives planning their 2026 investment roadmaps, understanding the architecture, competitive dynamics, and external pressures shaping this market is no longer optional. It is a prerequisite for sustainable growth.
Our comprehensive Worldwide Battery Manufacturing Software Market report is designed to provide the analytical rigor and actionable granularity required to navigate this inflection point. What follows is a strategic overview of the forces driving this market, the competitive landscape defining it, and the practical dimensions our study unpacks for industry leaders.
Market Trajectory and the Case for Strategic Investment
The historical trajectory of the battery manufacturing software market reflects the broader acceleration of electrification. Between 2020 and 2025, the market expanded consistently each year, growing from 510.45 million USD to the aforementioned 1,127.29 million USD. This doubling of market value over a five-year period underscores how quickly software has moved from a supplementary expenditure to a core operational necessity.
Looking ahead, the forecast period from 2026 through 2032 indicates that this momentum will not decelerate. The market is expected to surpass 1,367.57 million USD in 2026 and continue climbing steadily to 1,606.81 million USD in 2027, 1,875.33 million USD in 2028, 2,182.17 million USD in 2029, and 2,669.49 million USD in 2030. By the close of the forecast window in 2032, revenue is projected to reach 3,642.24 million USD. An 18.24 percent CAGR across this horizon suggests that software adoption will remain tightly coupled with production capacity expansion, technological maturation, and the evolving demands of downstream customers.
Importantly, these projections are not homogeneous across all solution types or end-user segments. The composition of market value reflects distinct adoption curves for manufacturing execution systems, simulation and design platforms, quality management tools, asset performance management suites, and data analytics and AI offerings. Similarly, the demand profile varies meaningfully across application domains such as electric vehicle batteries, consumer electronics, energy storage systems, and industrial and medical batteries. Our report dissects these structural nuances in detail, enabling decision-makers to align software procurement with their specific operational priorities rather than relying on aggregate market narratives.
External Pressures Redefining Software Requirements
Market growth is being accelerated by a confluence of regulatory, economic, and technical forces that are simultaneously raising the stakes for manufacturing software vendors and end-users. One of the most consequential developments is the emergence of the EU battery passport framework. By 2027, mandatory requirements for carbon footprint declaration and quality component disclosure will apply to large segments of the battery industry. This regulatory shift is not simply a compliance exercise. It is driving a fundamental need for enhanced traceability, data sovereignty, and interoperable data architectures within manufacturing software environments.
Parallel to regulatory evolution, cost structures in battery production are creating new incentives for digitalization. In a baseline 40 GWh per annum lithium-ion battery cell production plant, labor accounts for approximately 6.9 percent of total costs. Research indicates that digitalization solutions encompassing predictive quality, automated traceability, and workflow optimization can reduce required staffing and overall production costs by up to 0.8 percent per use case. While these percentages may appear incremental in isolation, their cumulative impact across multiple production lines and operational domains can materially improve margins in an industry where cost-per-kWh remains a central competitive battleground.
Energy efficiency represents another critical lever. Energy tracking and optimization use cases in battery manufacturing digitalization hold the potential for a 9.5 percent reduction in energy consumption. The electrode production stage, in particular, stands to benefit most from integrated scrap reduction and energy efficiency initiatives. As energy prices remain volatile and sustainability commitments tighten, software platforms capable of delivering granular energy visibility and actionable optimization insights are gaining strategic prominence.
Cybersecurity is equally reshaping vendor selection criteria. Standards such as ISO 21434 and IEC 62443 are increasingly referenced in battery-related systems procurement. Recommendations for end-to-end encryption, including AES-256 and TLS 1.3, alongside secure update mechanisms in connected manufacturing environments, are becoming baseline expectations rather than premium differentiators. In this context, software platforms must demonstrate not only operational functionality but also resilient security architectures that align with evolving compliance mandates.
Geopolitical dynamics add further complexity. US domestic battery manufacturing output grew 359 percent in inflation-adjusted terms from 2020 to 2024, supported by policy actions encouraging onshoring of supply chain elements. This surge amplifies the importance of software integration for traceability, quality assurance, and regulatory reporting, particularly for manufacturers seeking to align with domestic content requirements and localized production incentives.
Competitive Landscape: Differentiated Platforms and Strategic Positioning
The competitive landscape in battery manufacturing software is characterized by a mix of established industrial automation players, specialized software vendors, and emerging analytics-focused firms. Market concentration data indicates that the top three players account for 34.2 percent of the market, while the top five represent 48.15 percent. This distribution reflects a market that is substantial enough to attract broad participation yet fragmented enough to allow differentiated value propositions to thrive.
GE Vernova continues to leverage its Proficy Smart Factory MES software to support diverse battery production processes within a single manufacturing platform. Its offering emphasizes end-to-end production visibility, quality control, traceability, and scalability for gigafactories while aiming to reduce operational technology costs and maintenance burdens. Siemens, meanwhile, integrates battery manufacturing execution systems, quality management systems, and process planning tools into its broader digital thread and smart manufacturing portfolio. Its approach is oriented toward standardization and optimization across battery production workflows.
Rockwell Automation delivers end-to-end MES solutions tailored specifically for EV lithium-ion battery producers. Its focus on integrated automation and manufacturing execution positions it as a relevant partner for organizations prioritizing tightly coupled control and execution architectures. Honeywell has made notable moves in this space, including its June 2024 launch of the Battery Manufacturing Excellence Platform, an AI-powered solution designed to optimize gigafactory operations, improve battery cell yields, reduce material waste, and compress production ramp-up cycles. Public disclosures around this launch highlighted a potential 60 percent reduction in startup material scrap, underscoring the growing emphasis on AI-driven process optimization.
Voltaiq offers an enterprise battery intelligence software platform that extends data analytics and insights from research and development through to giga-scale production. Its value proposition centers on helping manufacturers detect and correct battery issues using existing data streams, thereby improving quality, safety, and efficiency. Energsoft serves a different segment by providing subscription-based predictive battery analytics software aimed at medium-sized companies. Its model focuses on automating data export, storage, and analysis to boost manufacturing yield and streamline workflows in battery production environments.
camLine, operating under the Elisa IndustrIQ umbrella, supplies MES, manufacturing operations management, and AI-powered solutions with a specific emphasis on efficiency, quality control, and end-to-end traceability for battery manufacturing processes. ABB contributes through its Manufacturing Operations Management software, which integrates secure data services, predictive analytics, and collaboration capabilities to deliver end-to-end visibility, including dedicated support for smart production in battery manufacturing. Panasonic Connect expanded the competitive field with its October 2024 launch of Syncora, an end-to-end manufacturing execution system designed to accelerate the digital transformation of EV battery manufacturing. Finally, PDF Solutions provides Exensio Battery, a modular solution set that addresses critical challenges in battery manufacturing through advanced analytics applicable to both semiconductor and battery processes.
Together, these players illustrate the breadth of approaches available to manufacturers. The strategic question is not simply which vendor offers the most features, but which platform architecture best aligns with a company's production scale, data maturity, regional compliance requirements, and integration constraints. Our report evaluates these competitive dynamics with a structured lens, allowing readers to assess fit beyond marketing narratives.
What the Report Covers: Operational Intelligence for Decision-Makers
The Worldwide Battery Manufacturing Software Market study is structured to serve as both a strategic compass and a practical reference for procurement, operations, and technology leadership. Rather than relying on surface-level aggregations, the report provides a detailed exploration of market architecture, adoption patterns, and the operational contexts in which software solutions deliver measurable value.
The analysis begins with a rigorous framing of market size and growth trajectories, contextualized across historical performance and forward-looking projections. It then examines segmentation structures that matter for enterprise planning, including solution type categories and end-user applications. By isolating the distinct demand drivers behind manufacturing execution systems, simulation and design software, quality management systems, asset performance management, and data analytics and AI platforms, the report helps readers understand where investment is concentrating and why.
Worldwide Battery Manufacturing Software Market
A substantial portion of the study is dedicated to competitive profiling. Each of the key companies is assessed for its product strategy, integration approach, target customer profile, and recent market moves. This includes not only incumbents with broad industrial automation portfolios but also specialized vendors whose solutions address niche but increasingly important requirements such as predictive analytics, battery intelligence, and modular process optimization. Recent product launches and strategic announcements are contextualized within broader market trends, enabling readers to distinguish between incremental updates and genuinely transformative offerings.
The report also integrates an assessment of external market dynamics, including regulatory developments, cost structure considerations, energy optimization potential, cybersecurity expectations, and regional manufacturing policy shifts. These factors are examined not as isolated observations but as interconnected forces that shape software selection criteria, implementation timelines, and total cost of ownership. By mapping these dynamics to practical procurement and deployment considerations, the study equips leaders to anticipate compliance requirements, align software capabilities with operational KPIs, and build internal business cases that withstand executive and board-level scrutiny.
Importantly, the report avoids treating the market as a monolith. Where relevant, it highlights the structural differences that emerge across regions, solution types, and end-user applications without overemphasizing any single segment in isolation. This balanced approach ensures that readers can extract insights applicable to a range of strategic scenarios, whether they are scaling gigafactory operations, optimizing existing production lines, or evaluating entry into new battery market segments.
Strategic Recommendations for 2026 Planning
As organizations move into 2026, several strategic priorities should guide battery manufacturing software decisions. First, traceability and data sovereignty must be treated as foundational requirements rather than afterthoughts. With regulatory frameworks such as the EU battery passport approaching, manufacturers should evaluate whether their software platforms can support the granularity, auditability, and data governance necessary for compliance. Solutions that lack robust traceability frameworks may require costly retrofits or integration work later.
Second, AI-enabled optimization should be assessed against measurable operational outcomes. The market is seeing a growing number of platforms that promise yield improvement, scrap reduction, and faster ramp-up cycles. However, the value of these capabilities depends on data quality, integration depth, and change management. Procurement teams should seek evidence of performance in comparable production environments and establish clear baseline metrics before committing to large-scale deployments.
Third, cybersecurity and secure data exchange must be embedded into vendor evaluation criteria from the outset. As manufacturing environments become more connected, the attack surface expands. Software platforms that support recognized security standards and provide secure update mechanisms, encryption, and access controls will reduce long-term risk and simplify compliance reporting.
Fourth, total cost of ownership should be evaluated across labor, energy, and material efficiency dimensions. The potential for digitalization to reduce staffing requirements, lower energy consumption, and minimize scrap represents a multi-dimensional value proposition. Organizations that model these benefits holistically are better positioned to justify investments and prioritize use cases with the highest return potential.
Finally, alignment with regional manufacturing incentives and supply chain strategies is essential. In markets where domestic production is being actively supported through policy mechanisms, software platforms that facilitate traceability, compliance reporting, and integration with localized production workflows can provide strategic advantages beyond their operational functionality.
Accessing the Full Intelligence
The battery manufacturing software market is expanding at a pace that rewards organizations capable of making informed, timely decisions. The aggregate growth trajectory is compelling, but the real strategic value lies in understanding the segmentation dynamics, competitive differentiators, regulatory pressures, and operational use cases that will determine success in specific deployment contexts.
Our Worldwide Battery Manufacturing Software Market report provides the depth, structure, and analytical discipline required to navigate this complexity. It is intended for leaders who need more than headline figures. It offers a comprehensive view of how the market is evolving, who is shaping it, and what practical considerations should inform software strategy in 2026 and beyond.
Battery Design And Manufacturing Software Market
For detailed segmentation breakdowns, competitive assessments, regional analyses, and the full set of market projections, we invite you to explore the complete report. The full intelligence is available through our official research portal, where you can access the complete dataset, methodology documentation, and supporting exhibit materials designed to support executive planning, procurement strategy, and investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Battery Manufacturing Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Global 2-Cyano-phenothiazine Market to Hit $63.74M by 2032, 5.06% CAGR From $45.12M in 2025
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Global 2-Cyano-phenothiazine Market Landscape
In the rapidly evolving landscape of pharmaceutical intermediates, the 2-Cyano-phenothiazine market stands as a critical nexus for supply chain stability, regulatory compliance, and manufacturing excellence. As we approach 2026, enterprises involved in the synthesis of antipsychotics, specialty chemicals, and advanced pharmaceutical ingredients must rely on data-driven foresight rather than reactive strategies. PW Consulting is proud to unveil our comprehensive Worldwide 2-Cyano-phenothiazine Market Research, a definitive guide designed to empower stakeholders with the actionable intelligence required to thrive in a volatile global chemistry market.
Worldwide 2-Cyano-phenothiazine Market
This market study is not merely a collection of figures; it is a strategic roadmap. By analyzing historical trajectories from 2020 through the base year of 2025 and projecting forward to 2032, we provide a longitudinal view of market health and momentum. For decision-makers, the value lies in understanding the cadence of growth and the underlying forces shaping demand and supply. This article serves as a preview of the depth and rigor contained within the full report, highlighting why this intelligence is indispensable for your 2026 planning cycle.
Market Trajectory and Growth Dynamics
The financial narrative of the 2-Cyano-phenothiazine market over the past five years tells a story of steady expansion and resilience. Our research tracks the revenue trajectory from 2020, when the market was valued at approximately 35.88 million USD, through to a projected valuation of 63.74 million USD by the end of the forecast period in 2032. This progression underscores a compound annual growth rate (CAGR) of roughly 5.06 percent during the forecast window.
For procurement officers and strategic planners, these figures represent more than just growth; they indicate a maturing market with increasing demand density. The upward trend observed from 2020 to 2025 demonstrates consistent annual increments, suggesting robust underlying demand from downstream pharmaceutical applications. Understanding this momentum is crucial for capacity planning and investment timing. Our full report dissects these trends to help you anticipate inflection points, ensuring that your supply agreements and production schedules align with market realities rather than lagging behind them.
Segmentation Insights: Purity, Application, and Regional Nuances
A monolithic view of the market obscures the strategic opportunities hidden within specific segments. Our analysis reveals distinct preferences and volume drivers across purity specifications, application types, and geographic regions. For instance, the market shows a pronounced preference for high-purity grades, specifically those above 99 percent purity, which command a significant share of the total volume compared to the 98 to 99 percent range. This preference signals to manufacturers that quality consistency is a primary driver for customer retention and premium pricing strategies.
In terms of end-use, the synthesis of Periciazine remains a dominant application driver, followed by its use as a Propericiazine intermediate. These pharmaceutical-specific uses highlight the compound's critical role in the production of antipsychotic medications and related therapeutics. Beyond these primary uses, there is a steady niche for other pharmaceutical research applications, indicating that the compound's utility extends into broader R&D pipelines.
Geographically, the market dynamics are heavily influenced by manufacturing hubs in Asia Pacific, which accounts for the largest share of volume, followed by established markets in Europe and North America. Latin America and the Middle East and Africa represent emerging or niche demand centers. However, accessing the precise revenue breakdowns, regional growth rates, and application-specific market sizes for these segments requires a detailed examination of the full dataset. Our report provides these granular insights, allowing you to identify high-potential markets without the noise of aggregated data.
Competitive Landscape: Key Players and Strategic Positioning
The concentration of market power is a defining feature of the 2-Cyano-phenothiazine industry. With a CR3 (concentration ratio of the top three companies) of approximately 62.45 percent and a CR5 of 78.12 percent, the market is moderately consolidated. This structure implies that a handful of key manufacturers wield significant influence over pricing, availability, and supply chain reliability.
Our research profiles several pivotal entities shaping this landscape. Sanjeevan Pharmachem Pvt. Ltd., based in Aurangabad, India, stands out as a manufacturer and exporter adhering to GMP-equivalent facilities and ICH Guidelines, offering 99.0 percent purity with a capacity of approximately 5 MT per annum. Similarly, Anjali Labs, also located in Aurangabad, positions itself as a pioneer producer with KSM approval for both Indian and overseas companies, enforcing a minimum order quantity of 100 kg for export-worthy 25 kg drums.
In the Indian sector, Finocure Laboratories contributes to the supply chain with a focus on Triflupromazine intermediates, maintaining capabilities that meet global standards and authorizing KSM use for international clients. The Chinese manufacturing base is also robust, featuring players such as Jinan Haihang Chemical Co., Ltd., Ningbo Inno Pharmchem, Capot Chemical Co., Ltd. in Hangzhou, and Mikem (Shandong) Biopharmaceutical Science and Technology Co., Ltd. These Chinese suppliers cater to the fine chemicals and organic intermediates segments, with Capot Chemical emphasizing strict moisture control limits of 0.5 percent or less for their product offerings.
Understanding the specific capabilities, capacity constraints, and quality certifications of these competitors is vital for benchmarking your own operations or selecting reliable partners. The full report goes beyond profiles to analyze supply chain vulnerabilities, capacity utilization trends, and the strategic implications of sourcing from these specific regions.
3-Cyano Pyridine Market
Industry Dynamics: Regulatory, Raw Material, and Safety Considerations
The operational environment for 2-Cyano-phenothiazine is shaped by a complex interplay of raw material dependencies and regulatory frameworks. At the upstream level, Phenothiazine (CAS 92-84-2) serves as the core feedstock for the synthesis of 2-cyano-phenothiazine derivatives. Fluctuations in the availability or pricing of this upstream material can have cascading effects on the downstream 2-Cyano-phenothiazine market. Our report integrates supply chain analysis to help you model these risks and secure alternative sourcing strategies where necessary.
Regulatory compliance is another pillar of market stability. 2-Cyano-phenothiazine is classified under transport regulations as environmentally hazardous, requiring adherence to ADR/RID, IMDG, and IATA standards for shipping and handling. This classification necessitates specific packaging precautions and compliance protocols that can impact logistics costs and lead times. Furthermore, the substance is intended strictly for research and pharmaceutical intermediate use, prohibiting direct medicinal or consumer applications. This restriction limits the addressable market to qualified industrial and research entities, reinforcing the need for precise market sizing and targeted marketing strategies.
These dynamics create a barrier to entry that favors established players with the infrastructure to manage compliance and safety efficiently. For new entrants or companies looking to expand their footprint, understanding these regulatory hurdles is as important as understanding the financial metrics. The detailed report includes sections dedicated to navigating these regulatory landscapes, offering FAQs and guidance based on the latest safety data sheets and industry recommendations.
Strategic Value for 2026 Decision-Making
Why does this market research matter for your 2026 strategy? The answer lies in the ability to move from reactive scrambling to proactive positioning. As the market moves from a 2025 base value of 45.12 million USD toward the 2032 horizon, the opportunities for value creation will concentrate in specific segments and regions. Companies that rely on generic market intelligence risk misallocating resources, overpaying for intermediates, or missing out on high-growth application areas.
Our report enables you to:
- Optimize Sourcing Strategies: Leverage detailed supplier profiles and capacity data to negotiate better terms and ensure supply continuity, particularly when dealing with concentrated markets where supplier leverage can be high.
- Target High-Value Segments: Identify which purity grades and application areas offer the best margin potential, avoiding low-value segments that drain resources.
- Mitigate Regulatory Risk: Incorporate compliance requirements into your operational planning to avoid costly delays or non-compliance penalties associated with hazardous material transport and handling.
- Benchmark Performance: Compare your production efficiency, purity standards, and pricing structures against key competitors to identify areas for improvement.
- Forecast with Confidence: Use the historical and forecast data to build robust financial models that account for cyclical trends and long-term growth trajectories.
The preview provided here only scratches the surface of the actionable intelligence available. The full Worldwide 2-Cyano-phenothiazine Market Research contains a wealth of additional data, including precise segmentation breakdowns, detailed competitive analysis matrices, and in-depth regional assessments that are essential for granular strategic planning. We have deliberately withheld these specific figures to preserve the proprietary value of the complete study, which is designed to provide your organization with a competitive edge.
To access the comprehensive data, detailed tables, and strategic recommendations that will drive your 2026 success, we invite you to request the full report. Equip your team with the insights needed to navigate the complexities of the global chemical intermediate market and secure your position in the evolving pharmaceutical supply chain.
PW Consulting – Delivering Clarity in Complexity.
For detailed analysis of this topic, please visit the official page: Worldwide 2-Cyano-phenothiazine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cast Iron Manhole Covers Market to Hit $6,143M by 2032, 4.3% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Underground Infrastructure Sector: Inside the Worldwide Cast Iron Manhole Covers Market Study
Urban resilience begins beneath the surface. While often overlooked, the cast iron manhole cover serves as a critical interface between municipal operations, utility networks, and the daily reality of traffic, drainage, and public safety. For executives tracking infrastructure exposure, materials pricing, and regional project pipelines, understanding the trajectory of this market is no longer a niche exercise. It is a strategic input for capital allocation, supply chain positioning, and competitive forecasting.
Our latest Worldwide Cast Iron Manhole Covers Market research is designed to equip decision-makers with the analytical framework needed to navigate a segment undergoing steady structural expansion, shifting procurement standards, and intensifying competition across foundries and engineering-casting manufacturers. This article previews the strategic architecture of the report, outlines the macro forces that will shape 2026 planning, and clarifies how a detailed segmentation view can sharpen market-entry, sourcing, and pricing decisions.
A Market Defined by Durable Demand and Measured Expansion
Cast iron manhole covers remain a cornerstone of underground access solutions because of their compressive strength, load-bearing reliability, and compatibility with heavy-traffic environments. That functional durability translates into a market that grows through infrastructure renewal, utility upgrades, and the recurring need for compliant fittings in municipal and commercial settings. The global market for cast iron manhole covers has demonstrated a consistent expansion profile, with revenue crossing several billion-dollar thresholds over the past half-decade and continuing to advance through the forecast horizon.
The trajectory framed in the study is anchored in historical data from 2020 through 2025 and extended across a forecast window to 2032. This structure allows readers to compare post-pandemic recovery momentum, observe the inflection points where procurement cycles accelerated, and evaluate how the market compounds over time. The overall growth rate indicated by the analysis points to a compound annual growth rate of 4.3 percent across the forecast period, reflecting the combined influence of sustained municipal spending, utility modernization, and ongoing replacement demand in mature and developing regions alike.
It is worth emphasizing that the market’s resilience is not driven by sudden spikes but by the steady cadence of infrastructure necessity. That makes the sector particularly valuable for planning purposes: the growth is measurable, the product requirement is tied to standards, and the regional distribution reflects where construction activity, maintenance budgets, and export-oriented manufacturing capabilities intersect. For a company evaluating exposure to infrastructure-linked product lines, this is a segment where informed positioning can compound advantage over multiple project cycles.
Why 2026 Is a Decision-Point Year
The beginning of the forecast period is especially relevant because it sits at the convergence of several operational forces. Input costs are fluctuating, capacity utilization in upstream metal sectors is shifting, and regulatory expectations continue to sharpen around load classes, material specifications, and certification requirements. In this environment, companies that rely on generalized assumptions about demand or pricing can misjudge margins, lead times, and competitive positioning.
The research is therefore built to support three classes of strategic action. First, it helps leadership evaluate where demand is structurally concentrated by application type and geographic market, without reducing the analysis to superficial regional rankings. Second, it enables procurement and supply chain teams to connect market-level revenue movement with underlying cost dynamics, such as scrap input trends and foundry capacity behavior. Third, it provides executives with a competitive map that goes beyond brand presence and instead examines manufacturing focus, export footprint, product range breadth, and recent strategic moves that may signal capacity expansion or product-mix evolution.
This is not a static sizing exercise. The report connects top-line market evolution with the operational realities that determine who can serve which projects efficiently, which load and compliance specifications are gaining procurement emphasis, and how manufacturers are differentiating through product design and regional distribution capability.
What the Study Covers: Practical Intelligence, Not Just Aggregate Sizing
A market study earns its value when it can be operationalized. To that end, the worldwide cast iron manhole covers analysis is structured around the details that executives, project developers, and supply chain leaders actually use during planning. The report examines revenue performance across the historical base and forecast timeline, then breaks the market into actionable dimensions so readers can locate their own exposure within the broader landscape.
The segmentation architecture includes regional and national-level demand contexts, product-type distinctions, and application categories that matter for procurement strategy. These dimensions are essential because a manhole cover deployed in a municipal roadway is not interchangeable with a utility access point or an industrial facility fitting, even if the underlying material category is similar. Likewise, regional dynamics differ in terms of project sourcing models, standard preference, export orientation, and the competitive intensity of local foundries versus international manufacturers.
The study also investigates the competitive field in depth. Rather than listing companies as isolated profiles, the analysis situates manufacturers within the market’s structure by examining their production orientation, geographic reach, product design emphasis, and recent activities that may affect their ability to win contracts or expand share. This includes attention to firms with strong municipal-project pedigrees, exporters serving multiple continents, Gulf-region producers with municipality-linked demand, and specialized manufacturers offering custom casting configurations. The result is a competitive view that helps readers understand not only who participates, but how they may be positioned to capture demand differently.
Beyond segmentation and company profiling, the report incorporates market-concentration metrics that reveal the degree of fragmentation and consolidation. These indicators are useful for assessing bargaining dynamics, entry barriers, and the likelihood that pricing power will remain distributed or begin to concentrate among a smaller group of high-volume producers. The inclusion of these metrics helps clarify whether a market is defined more by broad participation or by the strategic influence of a handful of scaled players.
Recent Moves That Signal Where the Market Is Heading
Recent corporate activity adds a practical dimension to the forecast. Product development efforts, trade-show participation, and targeted launches can reveal where manufacturers see the greatest opportunities and what kinds of performance demands they expect to dominate procurement conversations. Recent developments captured in the study include product offering updates from manufacturers emphasizing customized round cast iron manhole cover solutions, continued trade-show engagement by exporters showcasing cast iron solutions across international audiences, and specialized product introductions aimed at climate-resilient performance with innovative clamping and hinge systems designed for extreme weather conditions.
These moves matter because they reflect how manufacturers are adapting to procurement priorities that increasingly combine durability, standard compliance, and application-specific resilience. For buyers and investors, such developments can signal which suppliers are investing in design differentiation versus competing primarily on volume and price. For analysts, they provide leading indicators of where future revenue may be won—especially in applications exposed to heavy loads, repeated service cycles, and environmental stress.
Structural Dynamics: Materials, Standards, and Competitive Realities
No forecast for cast iron manhole covers can be separated from the inputs and standards that govern production and procurement. The study integrates current industry context around raw material economics and regulatory expectations so that strategic conclusions remain grounded in operational reality.
On the input side, scrap pricing and foundry-level capacity utilization are recurring variables that influence cost structures and margin stability. Recent data points on cast iron scrap price movement and steel mill capacity utilization highlight the ongoing volatility that manufacturers must manage. These fluctuations do not change the long-term demand story, but they do affect short-to-medium-term pricing, tendering behavior, and the relative competitiveness of regional producers with different sourcing configurations. For a company planning procurement or export strategy, these dynamics are not background noise; they are a direct factor in cost forecasting and sourcing negotiation.
On the regulatory side, compliance standards and certification requirements shape product design, market access, and the credibility of suppliers in public-sector and infrastructure projects. International standards defining load classes and performance requirements for gully tops and manhole tops remain relevant across vehicular and pedestrian environments. At the same time, national certification regimes continue to reinforce quality expectations for cast iron covers and frames in key infrastructure markets. The study discusses how these requirements influence product differentiation and procurement preference, especially in settings where safety, durability, and compliance documentation are procurement prerequisites rather than optional enhancements.
The broader materials context also affirms the continued relevance of cast iron. The segment retains a significant material share in the wider manhole cover category because of its suitability for high-load applications and its compatibility with established installation and maintenance practices. That structural advantage is one reason the market can sustain expansion even as alternative materials and composite solutions evolve in adjacent niches.
Worldwide Cast Iron Manhole Covers Market
What Leaders Should Do With This Intelligence
The purpose of this research is to convert a complex, infrastructure-linked market into clear strategic options. The following priorities emerge naturally from the structure of the study:
- Map demand exposure by application and region to determine where your product mix, certifications, and distribution capabilities are best aligned with near-term procurement cycles.
- Track input-cost volatility and upstream capacity conditions as part of pricing strategy, especially when negotiating long-cycle municipal or utility contracts.
- Use the competitive analysis to distinguish between volume-driven suppliers, export-oriented manufacturers, and firms investing in design or resilience-oriented product features.
- Assess whether market concentration trends will affect entry feasibility, bidding dynamics, or the need for partnership and localization strategies.
- Evaluate regulatory and standards alignment as a precondition for market access in regions where compliance documentation and load-class performance are procurement gatekeepers.
These actions are most effective when supported by the full segmentation view and company-level detail provided in the complete study. The preview above establishes the strategic rationale; the full research delivers the numbers, comparisons, and trend interpretation needed to act on it.
Manhole Covers Market
Why the Complete Report Is Worth the Deep Dive
Executive summaries can indicate direction, but they cannot replace the analytical resolution required for sourcing strategy, regional prioritization, or competitive benchmarking. The full market study provides detailed segmentation data, supplier profiling, concentration metrics, and forward-looking interpretation that together support more decisive planning. It allows teams to move from general awareness of market expansion to specific conclusions about where opportunity is concentrated and which operational factors will determine execution success.
For organizations comparing market-entry options, evaluating supply agreements, or tracking infrastructure-exposed product lines, the study is built to reduce uncertainty and improve forecast credibility. Readers gain a structured view of how the cast iron manhole covers market has evolved, how it is likely to progress through the end of the decade, and which competitive and operational variables will matter most in the next planning cycle.
How to Access the Full Strategic Analysis
The complete Worldwide Cast Iron Manhole Covers Market study is available through the PW Consulting research portal. It provides the detailed segmentation, company-level competitive assessment, historical and forecast revenue trajectory, and the market-concentration context needed to translate infrastructure demand into practical business strategy. For teams preparing for 2026 decisions, the full report offers the depth required to move beyond high-level assumptions and into actionable intelligence.
This market remains defined by durable demand, standards-driven procurement, and competitive positioning shaped by manufacturing capability, export reach, and ongoing product innovation. With the right analytical foundation, those characteristics become manageable variables rather than unknowns. The study is designed to provide precisely that foundation.
For detailed analysis of this topic, please visit the official page: Worldwide Cast Iron Manhole Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vertical Screen Short Drama Market to Hit $2.45B in 2025, 24.5% CAGR
By pmarketresearch, 2026-09-16
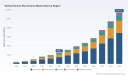
Navigating the Vertical Screen Short Drama Boom: Strategic Intelligence for 2026 Decision-Making
The New Screen Paradigm
The entertainment landscape has fundamentally shifted toward the vertical frame, transforming how audiences consume narrative content and how capital flows through the global media sector. Vertical screen short dramas, characterized by their mobile-first orientation, concise episode lengths, and binge-friendly pacing, have evolved from a niche format into a dominant revenue engine. This structural shift is not merely aesthetic; it represents a complete reconfiguration of production workflows, distribution channels, and monetization mechanics. For enterprises operating at the intersection of media, technology, and consumer engagement, understanding the trajectory of this vertical ecosystem is no longer optional. It is a strategic imperative for portfolio allocation, partnership architecture, and market entry sequencing in 2026 and beyond.
The vertical short drama market has demonstrated remarkable growth velocity over the past half-decade. Historical revenue figures climbed from approximately $450.12 million in 2020 to $2.4505 billion in 2025, reflecting an accelerating adoption curve that has fundamentally outpaced broader streaming segment benchmarks. The forecast period spanning 2026 through 2032 projects a compound annual growth rate of 24.5 percent, with projected market size expected to approach $3.12097 billion in 2026 and continue expanding toward a trajectory that crosses nine figures by the early 2030s. This macro momentum underscores a sector transitioning from early experimentation to mature commercial scaling. However, aggregate figures alone cannot guide precise capital deployment, content pipeline design, or platform positioning. The granular mechanics of regional demand elasticity, revenue model adoption curves, and application channel concentration require dedicated intelligence to navigate effectively.
Market Architecture and Growth Trajectory
The mathematics of vertical short drama expansion reveal a compounding growth structure rather than a linear trend. Revenue progression from 2020 through 2025 established a robust baseline, with each consecutive year delivering incremental acceleration that signals deepening mainstream integration. The passage from 2025 to 2026 represents a critical inflection point, where platform maturity, improved monetization pipelines, and expanded international distribution converge to support projected market expansion to $3.12097 billion. Looking further ahead, sequential growth through 2032 projects a landscape where total market valuation approaches $11.36161 billion, driven by sustained audience acquisition, content volume scaling, and the migration of traditional narrative IP toward vertical-native formats.
This trajectory is underpinned by several structural advantages unique to the vertical format. Production cycles operate on dramatically compressed timelines compared to conventional scripted television or feature film pipelines. Typical development phases span roughly one month, with principal photography frequently completed within a single week. This efficiency enables high-volume content output, rapid iteration based on audience feedback, and lower barriers to entry for production teams. The economic model inherently supports rapid job creation across writing, directing, acting, editing, and platform operations, while simultaneously allowing studios and independent producers to test narrative concepts with minimal sunk cost. For corporate strategists evaluating content investment or ecosystem partnerships, this production agility translates directly into portfolio flexibility and faster time-to-market for branded or licensed properties.
Segmentation Dynamics and Monetization Architecture
The commercial architecture of vertical short dramas is defined by a multi-channel monetization ecosystem that balances direct consumer spending, advertising inventory, and institutional licensing. Revenue generation is distributed across subscription and pay-per-episode models, ad-supported streaming frameworks, and licensing or B2B content partnerships. Each stream carries distinct margin profiles, audience expectations, and operational requirements. Subscription and episodic payment structures reward high-retention content and consistent release scheduling, while ad-supported models demand precise audience targeting and inventory optimization. Licensing and B2B arrangements open pathways for IP extension, brand integration, and cross-platform distribution, particularly as traditional studios seek low-risk testing environments for new concepts.
Consumption occurs predominantly through mobile applications and dedicated platforms, which capture the largest share of audience engagement and transactional activity. Social media integration represents a secondary but strategically vital channel, enabling viral distribution, algorithmic discovery, and cross-platform audience migration. Web and other distribution routes, while smaller in relative volume, serve as complementary touchpoints for international niche audiences, web-based community engagement, and experimental format trials. The interplay among these application channels dictates platform strategy, user acquisition cost structures, and retention engineering. Understanding how revenue and audience flows distribute across these channels is essential for optimizing content placement, partnership negotiations, and regional rollout sequencing.
Geographic consumption patterns reflect a highly asymmetric distribution architecture. The Asia Pacific region currently anchors the largest share of market activity, driven by mature domestic platform ecosystems, high mobile penetration, and deeply entrenched user habits around short-form narrative content. North America operates as a rapidly scaling secondary engine, characterized by accelerating platform competition, growing advertiser interest, and expanding domestic production capacity. European, Latin American, and Middle Eastern and African markets continue to develop at varying paces, each shaped by localized content preferences, platform availability, and payment infrastructure maturity. For global enterprises, these regional asymmetries create distinct market entry windows, localization requirements, and partnership imperatives. Strategic success depends on recognizing which geographies offer immediate monetization traction versus which represent long-term audience accumulation plays.
Competitive Landscape and Strategic Positioning
The competitive ecosystem of vertical short dramas is concentrated but increasingly contested, with a core group of platform operators commanding a significant portion of total revenue while a broad base of regional and niche players competes for audience share. The top three companies collectively capture approximately 35.5 percent of market revenue, while the top five expand that concentration to roughly 48.2 percent. This concentration profile indicates a market that has established clear leading platforms yet retains sufficient fragmentation to allow new entrants, localized content strategies, and disruptive monetization experiments to gain traction. For investors and corporate planners, this balance between concentration and contestability creates targeted acquisition opportunities, partnership leverage points, and niche positioning pathways.
DramaBox, operating through StoryMatrix and Dianzhong Technology with headquarters spanning Singapore and Beijing, has emerged as a leading global vertical short drama platform with a mobile-first orientation. Its international footprint and strong in-app purchase and subscription revenue streams position it as a central node in global microdrama distribution. ReelShort, developed by Crazy Maple Studio and based in Sunnyvale, California, specializes in fast-paced, highly addictive microdramas with a substantial United States and global user base. Its growth strategy emphasizes domestic production expansion, signaling a deliberate pivot toward localized content pipelines and scaled original programming. NetShort operates as a prominent international distribution platform, capturing meaningful revenue share alongside established leaders and reinforcing the multi-platform nature of global short drama consumption. GoodShort continues to demonstrate rapid growth in both download volume and revenue generation, underscoring the intensity of competition within the microdrama segment and the potential for emerging platforms to disrupt established rankings through aggressive user acquisition and content volume.
Beyond dedicated vertical platforms, major traditional media and technology players are embedding vertical content into broader ecosystem strategies. Holywater, headquartered in Ukraine and operating My Drama and My Passion, has secured equity investment from Fox Entertainment, laying the groundwork for localized microdrama production focused on Western markets. iQiyi, Youku under Alibaba, and Tencent through WeChat Video Accounts represent major Chinese ecosystem players investing in professionally produced vertical drama series, brand integration frameworks, and youth-oriented narrative strategies. Kuaishou operates dedicated vertical short drama applications and content within its larger short-video ecosystem, reflecting the integration of duanju formats into established domestic platforms. These hybrid strategies illustrate a broader industry movement in which vertical formats are no longer siloed niche products but rather integral components of larger content, distribution, and engagement architectures.
Recent Developments and Sector Catalysts
Recent corporate activity signals accelerating institutional commitment to vertical narrative formats. Fox Entertainment entered a multiyear agreement with Dhar Mann Studios to produce forty scripted vertical-video shows for Holywater's My Drama platform, contributing to a broader commitment to over two hundred vertical titles. This deal follows Fox Entertainment's equity stake acquisition in Holywater in 2025, alongside a production commitment exceeding two hundred vertical video titles over a two-year horizon for the My Drama platform. These moves illustrate a strategic bet by legacy entertainment entities on vertical formats as both testing environments for new IP and scalable distribution channels. Disney similarly selected DramaBox for its accelerator program, signaling support for microdrama platform expansion and innovation, while broader Hollywood studios continue to explore vertical layouts for concept validation and IP extension. Major streaming applications, including Disney+, have begun rolling out vertical video features, reflecting an industry-wide recognition of format convergence and audience behavior evolution.
On the production side, ReelShort has outlined plans to produce four hundred shows during 2026 with a focus on domestic United States filming, highlighting the scale-up trajectory of leading platforms as they transition from acquisition-led growth to original content volume expansion. The broader market context reinforces this momentum, with industry reporting indicating that by mid-2025 over two hundred vertical drama platforms existed globally, and leading operators captured more than half of total market revenue through mobile in-app purchases. China's duanju market alone generated over 50 billion yuan in gross consumer spending by the end of 2024, with continued growth extending into 2025 and 2026 as platform ecosystems matured and monetization mechanisms deepened. These developments collectively validate the vertical short drama sector as a structurally expanding market rather than a transient trend.
Strategic Implications for 2026 Enterprise Decision-Making
For enterprises formulating 2026 strategy, the vertical short drama market presents a set of interconnected decision points spanning content investment, platform partnership, geographic prioritization, and monetization design. The compressed production cycle and low cost structure enable rapid concept testing, allowing brands and studios to evaluate audience response with minimal upfront exposure. This capability supports agile IP development, format experimentation, and data-driven iteration, which are especially valuable in a media environment where attention is fragmented and release velocity matters. Organizations that integrate vertical formats into broader content portfolios can use them as low-risk entry points for new narrative properties, audience acquisition drivers, and cross-promotion vehicles for larger-scale productions.
Partnership architecture requires careful calibration. The concentration profile of the market suggests that collaboration with leading platforms can deliver immediate reach and monetization access, while engagement with emerging or regionally focused platforms may offer differentiated audience access, lower competition, and strategic positioning for future market phases. Licensing and B2B pathways provide opportunities for brand integration, format extension, and content syndication, particularly as Western studios and technology groups increase their investment footprint. Simultaneously, advertising-supported models demand a deep understanding of audience demographics, engagement patterns, and inventory pricing dynamics to ensure margin sustainability.
Geographic strategy must reflect the asymmetric demand and platform maturity across regions. Enterprises targeting high-volume monetization should prioritize markets with established mobile payment infrastructure, mature platform ecosystems, and proven audience willingness to spend on episodic short-form content. Organizations focused on long-term audience accumulation, brand presence, or localized content development should evaluate secondary and emerging regions where platform competition is still structuring itself and early positioning can yield disproportionate advantages as ecosystems mature. In all cases, localization of content styles, release cadence, pricing models, and platform features remains essential to capturing organic growth rather than relying solely on import-driven distribution.
Vertical Screen Short Drama Market
What the Full Research Delivers
This overview establishes the macro trajectory, competitive architecture, and strategic stakes of the vertical screen short drama market, but enterprise-grade decision-making requires a deeper analytical layer. The full PW Consulting market research expands far beyond high-level growth figures to provide actionable intelligence across revenue model breakdowns, regional demand drivers, application channel performance, competitive positioning metrics, and scenario-based forecasting. The report maps monetization pathways across subscription, advertising, and licensing streams with operational detail, examines how platform concentration and fragmentation influence partnership leverage, and traces the interplay between production economics, content volume scaling, and audience retention. It integrates recent corporate developments, regulatory and ecosystem dynamics, and consumer habit shifts into a cohesive strategic framework designed to support market entry planning, investment prioritization, and platform partnership design.
Worldwide Mini Program Short Drama Market
To translate these structural insights into precise, executable strategy for 2026 and the forecast horizon through 2032, decision-makers need the complete dataset, segmentation depth, and modeled scenarios contained in the full report. Access the complete Vertical Screen Short Drama Market research on the PW Consulting source page to obtain the full intelligence portfolio, including detailed market sizing, revenue model analysis, competitive benchmarking, and regional application insights designed to support high-stakes corporate strategy, investment allocation, and content ecosystem planning.
For detailed analysis of this topic, please visit the official page: Vertical Screen Short Drama Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com