

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Aircraft Windows Market to Reach $1,162.16M by 2032, 4.25% CAGR

Strategic Transparency: Navigating the Worldwide Aircraft Windows Market Outlook 2026-2032
The global aerospace industry is currently navigating a complex landscape defined by post-pandemic recovery, supply chain recalibration, and an aggressive push toward fuel efficiency. Within this ecosystem, the aircraft windows market serves as a critical barometer for broader manufacturing health, regulatory compliance, and technological innovation. As we enter 2026, stakeholders across the value chain—from original equipment manufacturers (OEMs) to maintenance, repair, and overhaul (MRO) providers—require precise intelligence to capitalize on emerging opportunities. PW Consulting is proud to introduce our comprehensive Worldwide Aircraft Windows Market research, a definitive guide designed to inform high-stakes corporate strategy over the next decade.
This report is not merely a collection of statistics; it is a strategic roadmap. It synthesizes historical performance from 2020 through 2025 with a robust forecast extending to 2032. By analyzing the trajectory from a market valuation of approximately 702.5 million USD in 2020 to a projected 1.16 billion USD by 2032, we uncover the underlying forces driving growth. The compound annual growth rate (CAGR) of 4.25 percent signals a steady, resilient expansion, yet the nuances behind this aggregate figure hold the key to competitive advantage. Our analysis delves into the segmentation splits, material innovations, and regional dynamics that general industry reports often overlook, providing the granularity necessary for actionable decision-making.
Market Trajectory and Macro Drivers
Understanding the historical context is essential for validating future projections. The market demonstrated consistent resilience between 2020 and 2025, recovering from initial disruptions to reach an estimated 868.42 million USD in the base year. This recovery sets the stage for the forecast period beginning in 2026, where valuations are expected to climb from 908.11 million USD to over 1.1 billion USD by 2032. Such growth is not organic fluke; it is anchored in tangible macroeconomic and industry-specific drivers.
Several macro trends are converging to sustain this demand. Strong global passenger demand continues to fuel air travel recovery, necessitating both new aircraft production and significant retrofit programs for aging fleets. Industry forecasts indicate over 2,000 annual narrowbody deliveries projected from 2027 onwards. Each new airframe requires a full suite of transparencies, while retired fleets undergoing modernization require updated window assemblies to meet contemporary safety and comfort standards. Furthermore, the Airbus 2025 Global Market Forecast projects a passenger traffic CAGR of 3.6 percent to 2044. This long-term traffic growth ensures that demand for new passenger aircraft and their associated transparencies will remain robust, creating a sustained pipeline for window manufacturers and suppliers.
Aircraft Flooring Market
Additionally, regulatory frameworks are tightening. Pressure from authorities such as the FAA and EASA is driving more frequent windshield replacement cycles to ensure safety and compliance in commercial aircraft. These regulatory mandates act as a floor for aftermarket demand, ensuring that even during fluctuations in new aircraft orders, the MRO segment remains active. Our report quantifies how these regulatory cycles interact with material lifespans to create predictable revenue streams for service providers.
Worldwide Aircraft Windows Market
Material Innovations and Segment Dynamics
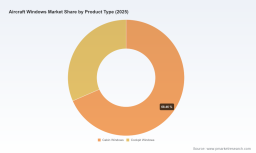
The aircraft windows market is segmented by product type, material, and platform, each presenting unique value propositions and challenges. Our research dissects these segments to reveal where margin potential lies. By product type, the market is divided between cabin windows and cockpit windows. While cabin windows represent a significant portion of the volume due to the number of units per aircraft, cockpit windows demand higher precision and optical fidelity, often commanding different pricing structures and supply chain requirements.
Material selection is perhaps the most critical technical decision facing engineers and procurement teams. The industry is currently weighing the trade-offs between acrylic, glass, and polycarbonate. Traditional stretched acrylic remains common for cabin windows due to its proven performance and cost-effectiveness. However, polycarbonate is gaining traction, offering up to 40 percent less weight than glass alternatives. In an industry obsessed with fuel efficiency and carbon reduction, this weight savings is a compelling value driver. Conversely, glass laminates held a significant share in commercial aircraft windows and windshields in 2025 due to superior optical fidelity and scratch resistance.
Our analysis highlights that while glass maintains dominance in specific high-performance applications, the polycarbonate segment shows a stronger growth trajectory. This shift is not uniform across all platforms. Commercial aviation continues to be the largest platform segment, driven by the sheer volume of passenger aircraft. However, military aviation and business and general aviation segments offer specialized opportunities. Military transparency systems require ruggedization and specific coating technologies for survivability, while business aviation focuses on luxury, noise reduction, and bespoke customization. Understanding the interplay between material costs, weight savings, and platform requirements is essential for suppliers positioning themselves in 2026 and beyond.
Competitive Landscape and Strategic Positioning
The market structure is moderately concentrated, with the top three companies holding a significant share of the revenue pool. This concentration suggests that while barriers to entry exist, there is still room for specialized players in niche segments such as general aviation or aftermarket repairs. Our report provides detailed profiles of key companies shaping the competitive environment, analyzing their strategic moves, product portfolios, and geographic footprints.
Major players such as PPG Aerospace and GKN Aerospace dominate large portions of the original-equipment and aftermarket transparency markets. PPG Aerospace is recognized for its advanced coatings, including SOLARON BLUE PROTECTION UV+ blocking technology, which enhances passenger comfort and reduces cabin heat load. GKN Aerospace stands as a world-leading provider of military transparency systems and holds a strong second position in the commercial aircraft transparency market, with over 2 million CrystalVue II coated windows in service. Their focus on aerospace-grade acrylic and advanced coatings underscores the industry trend toward multifunctional window assemblies.
Saint-Gobain Aerospace continues to supply aircraft windows and windshields trusted by airlines worldwide. A notable recent development includes their partnership with Lilium to supply and support windows and windshields for the Lilium Jet, signaling a strategic pivot toward emerging electric vertical takeoff and landing (eVTOL) and advanced air mobility platforms. This move highlights how traditional aerospace suppliers are diversifying into next-generation aviation sectors.
In the aftermarket and general aviation space, specialized manufacturers play a crucial role. Lee Aerospace specializes in FAA-approved aircraft windows and windshields for business and general aviation aircraft, including brands like Bombardier, Cessna, and Gulfstream. They offer CoolView upgrades and robust aftermarket support, catering to owners seeking performance enhancements. Similarly, L.P. Aero Plastics Inc. stands as a leading FAA-PMA manufacturer of aircraft windshields and windows for the general aviation market with over 60 years of history. Perkins Aircraft Windows manufactures, repairs, and installs business aircraft windshields and cabin windows for a wide range of models, including Citation, Challenger, Embraer, and Falcon.
Other key entities include The NORDAM Group, which provides repair, overhaul, and manufacturing services as part of its global aerospace MRO solutions, and Gentex Corporation, focusing on advanced optical and protective systems. Smaller but significant players like Cee Bailey's Aircraft Plastics and Llamas Plastics, Inc. produce light aircraft windows and transparencies meeting high optical requirements. The presence of these specialized firms indicates a healthy ecosystem where large monopolies coexist with agile specialists capable of serving niche requirements.
Strategic Implications for 2026 Decision Makers
For executives and strategists, the data presented in this report translates into several critical imperatives. First, supply chain resilience is paramount. The concentration of key players in specific regions suggests that geopolitical shifts or localized disruptions could impact availability. Diversifying supplier bases or investing in regional manufacturing capabilities may be necessary to mitigate risk. Second, material innovation offers a pathway to differentiation. Companies that can effectively integrate lightweight polycarbonate solutions without compromising optical quality or safety certifications will capture premium market segments.
Third, the aftermarket presents a stable revenue anchor. With regulatory pressure driving replacement cycles and fleets aging, the MRO segment for windows and windshields is poised for growth independent of new aircraft delivery rates. Service providers who invest in certification and capacity for these replacement cycles will secure long-term contracts. Finally, the emergence of new platform types, such as the Lilium Jet partnership exemplifies, suggests that agility in adapting window technologies to novel airframe designs will be a key differentiator.
Our report goes beyond surface-level observations to provide the operational details needed to execute these strategies. It includes comprehensive scope definitions, research methodologies, and an in-depth analysis of market dynamics that influence pricing, adoption rates, and regional performance. We examine the regulatory landscape, raw material cost structures, and the specific technological advancements that are reshaping the value chain. By integrating quantitative data with qualitative industry context, we provide a holistic view that supports investment appraisal, product development roadmaps, and market entry strategies.
Conclusion
The Worldwide Aircraft Windows Market is at an inflection point. The convergence of rising passenger traffic, regulatory mandates, and material science advancements creates a fertile environment for growth. However, navigating this landscape requires more than general market awareness; it demands precise, data-backed insight. PW Consulting's latest research empowers organizations to look past the aggregate numbers and understand the specific drivers that will define success in 2026 and beyond.
To access the full depth of this analysis, including detailed segmentation data, competitive benchmarking, and region-specific forecasts, we invite you to explore the complete report. The strategic advantages hidden within the data are available to those ready to invest in comprehensive intelligence. Equip your organization with the knowledge needed to steer through the complexities of the aerospace supply chain and capitalize on the transparency revolution.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Windows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com