

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vertical Screen Short Drama Market to Hit $2.45B in 2025, 24.5% CAGR

Navigating the Vertical Screen Short Drama Boom: Strategic Intelligence for 2026 Decision-Making
The New Screen Paradigm
The entertainment landscape has fundamentally shifted toward the vertical frame, transforming how audiences consume narrative content and how capital flows through the global media sector. Vertical screen short dramas, characterized by their mobile-first orientation, concise episode lengths, and binge-friendly pacing, have evolved from a niche format into a dominant revenue engine. This structural shift is not merely aesthetic; it represents a complete reconfiguration of production workflows, distribution channels, and monetization mechanics. For enterprises operating at the intersection of media, technology, and consumer engagement, understanding the trajectory of this vertical ecosystem is no longer optional. It is a strategic imperative for portfolio allocation, partnership architecture, and market entry sequencing in 2026 and beyond.
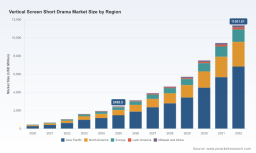
The vertical short drama market has demonstrated remarkable growth velocity over the past half-decade. Historical revenue figures climbed from approximately $450.12 million in 2020 to $2.4505 billion in 2025, reflecting an accelerating adoption curve that has fundamentally outpaced broader streaming segment benchmarks. The forecast period spanning 2026 through 2032 projects a compound annual growth rate of 24.5 percent, with projected market size expected to approach $3.12097 billion in 2026 and continue expanding toward a trajectory that crosses nine figures by the early 2030s. This macro momentum underscores a sector transitioning from early experimentation to mature commercial scaling. However, aggregate figures alone cannot guide precise capital deployment, content pipeline design, or platform positioning. The granular mechanics of regional demand elasticity, revenue model adoption curves, and application channel concentration require dedicated intelligence to navigate effectively.
Market Architecture and Growth Trajectory
The mathematics of vertical short drama expansion reveal a compounding growth structure rather than a linear trend. Revenue progression from 2020 through 2025 established a robust baseline, with each consecutive year delivering incremental acceleration that signals deepening mainstream integration. The passage from 2025 to 2026 represents a critical inflection point, where platform maturity, improved monetization pipelines, and expanded international distribution converge to support projected market expansion to $3.12097 billion. Looking further ahead, sequential growth through 2032 projects a landscape where total market valuation approaches $11.36161 billion, driven by sustained audience acquisition, content volume scaling, and the migration of traditional narrative IP toward vertical-native formats.
This trajectory is underpinned by several structural advantages unique to the vertical format. Production cycles operate on dramatically compressed timelines compared to conventional scripted television or feature film pipelines. Typical development phases span roughly one month, with principal photography frequently completed within a single week. This efficiency enables high-volume content output, rapid iteration based on audience feedback, and lower barriers to entry for production teams. The economic model inherently supports rapid job creation across writing, directing, acting, editing, and platform operations, while simultaneously allowing studios and independent producers to test narrative concepts with minimal sunk cost. For corporate strategists evaluating content investment or ecosystem partnerships, this production agility translates directly into portfolio flexibility and faster time-to-market for branded or licensed properties.
Segmentation Dynamics and Monetization Architecture
The commercial architecture of vertical short dramas is defined by a multi-channel monetization ecosystem that balances direct consumer spending, advertising inventory, and institutional licensing. Revenue generation is distributed across subscription and pay-per-episode models, ad-supported streaming frameworks, and licensing or B2B content partnerships. Each stream carries distinct margin profiles, audience expectations, and operational requirements. Subscription and episodic payment structures reward high-retention content and consistent release scheduling, while ad-supported models demand precise audience targeting and inventory optimization. Licensing and B2B arrangements open pathways for IP extension, brand integration, and cross-platform distribution, particularly as traditional studios seek low-risk testing environments for new concepts.
Consumption occurs predominantly through mobile applications and dedicated platforms, which capture the largest share of audience engagement and transactional activity. Social media integration represents a secondary but strategically vital channel, enabling viral distribution, algorithmic discovery, and cross-platform audience migration. Web and other distribution routes, while smaller in relative volume, serve as complementary touchpoints for international niche audiences, web-based community engagement, and experimental format trials. The interplay among these application channels dictates platform strategy, user acquisition cost structures, and retention engineering. Understanding how revenue and audience flows distribute across these channels is essential for optimizing content placement, partnership negotiations, and regional rollout sequencing.
Geographic consumption patterns reflect a highly asymmetric distribution architecture. The Asia Pacific region currently anchors the largest share of market activity, driven by mature domestic platform ecosystems, high mobile penetration, and deeply entrenched user habits around short-form narrative content. North America operates as a rapidly scaling secondary engine, characterized by accelerating platform competition, growing advertiser interest, and expanding domestic production capacity. European, Latin American, and Middle Eastern and African markets continue to develop at varying paces, each shaped by localized content preferences, platform availability, and payment infrastructure maturity. For global enterprises, these regional asymmetries create distinct market entry windows, localization requirements, and partnership imperatives. Strategic success depends on recognizing which geographies offer immediate monetization traction versus which represent long-term audience accumulation plays.
Competitive Landscape and Strategic Positioning
The competitive ecosystem of vertical short dramas is concentrated but increasingly contested, with a core group of platform operators commanding a significant portion of total revenue while a broad base of regional and niche players competes for audience share. The top three companies collectively capture approximately 35.5 percent of market revenue, while the top five expand that concentration to roughly 48.2 percent. This concentration profile indicates a market that has established clear leading platforms yet retains sufficient fragmentation to allow new entrants, localized content strategies, and disruptive monetization experiments to gain traction. For investors and corporate planners, this balance between concentration and contestability creates targeted acquisition opportunities, partnership leverage points, and niche positioning pathways.
DramaBox, operating through StoryMatrix and Dianzhong Technology with headquarters spanning Singapore and Beijing, has emerged as a leading global vertical short drama platform with a mobile-first orientation. Its international footprint and strong in-app purchase and subscription revenue streams position it as a central node in global microdrama distribution. ReelShort, developed by Crazy Maple Studio and based in Sunnyvale, California, specializes in fast-paced, highly addictive microdramas with a substantial United States and global user base. Its growth strategy emphasizes domestic production expansion, signaling a deliberate pivot toward localized content pipelines and scaled original programming. NetShort operates as a prominent international distribution platform, capturing meaningful revenue share alongside established leaders and reinforcing the multi-platform nature of global short drama consumption. GoodShort continues to demonstrate rapid growth in both download volume and revenue generation, underscoring the intensity of competition within the microdrama segment and the potential for emerging platforms to disrupt established rankings through aggressive user acquisition and content volume.
Beyond dedicated vertical platforms, major traditional media and technology players are embedding vertical content into broader ecosystem strategies. Holywater, headquartered in Ukraine and operating My Drama and My Passion, has secured equity investment from Fox Entertainment, laying the groundwork for localized microdrama production focused on Western markets. iQiyi, Youku under Alibaba, and Tencent through WeChat Video Accounts represent major Chinese ecosystem players investing in professionally produced vertical drama series, brand integration frameworks, and youth-oriented narrative strategies. Kuaishou operates dedicated vertical short drama applications and content within its larger short-video ecosystem, reflecting the integration of duanju formats into established domestic platforms. These hybrid strategies illustrate a broader industry movement in which vertical formats are no longer siloed niche products but rather integral components of larger content, distribution, and engagement architectures.
Recent Developments and Sector Catalysts
Recent corporate activity signals accelerating institutional commitment to vertical narrative formats. Fox Entertainment entered a multiyear agreement with Dhar Mann Studios to produce forty scripted vertical-video shows for Holywater's My Drama platform, contributing to a broader commitment to over two hundred vertical titles. This deal follows Fox Entertainment's equity stake acquisition in Holywater in 2025, alongside a production commitment exceeding two hundred vertical video titles over a two-year horizon for the My Drama platform. These moves illustrate a strategic bet by legacy entertainment entities on vertical formats as both testing environments for new IP and scalable distribution channels. Disney similarly selected DramaBox for its accelerator program, signaling support for microdrama platform expansion and innovation, while broader Hollywood studios continue to explore vertical layouts for concept validation and IP extension. Major streaming applications, including Disney+, have begun rolling out vertical video features, reflecting an industry-wide recognition of format convergence and audience behavior evolution.
On the production side, ReelShort has outlined plans to produce four hundred shows during 2026 with a focus on domestic United States filming, highlighting the scale-up trajectory of leading platforms as they transition from acquisition-led growth to original content volume expansion. The broader market context reinforces this momentum, with industry reporting indicating that by mid-2025 over two hundred vertical drama platforms existed globally, and leading operators captured more than half of total market revenue through mobile in-app purchases. China's duanju market alone generated over 50 billion yuan in gross consumer spending by the end of 2024, with continued growth extending into 2025 and 2026 as platform ecosystems matured and monetization mechanisms deepened. These developments collectively validate the vertical short drama sector as a structurally expanding market rather than a transient trend.
Strategic Implications for 2026 Enterprise Decision-Making
For enterprises formulating 2026 strategy, the vertical short drama market presents a set of interconnected decision points spanning content investment, platform partnership, geographic prioritization, and monetization design. The compressed production cycle and low cost structure enable rapid concept testing, allowing brands and studios to evaluate audience response with minimal upfront exposure. This capability supports agile IP development, format experimentation, and data-driven iteration, which are especially valuable in a media environment where attention is fragmented and release velocity matters. Organizations that integrate vertical formats into broader content portfolios can use them as low-risk entry points for new narrative properties, audience acquisition drivers, and cross-promotion vehicles for larger-scale productions.
Partnership architecture requires careful calibration. The concentration profile of the market suggests that collaboration with leading platforms can deliver immediate reach and monetization access, while engagement with emerging or regionally focused platforms may offer differentiated audience access, lower competition, and strategic positioning for future market phases. Licensing and B2B pathways provide opportunities for brand integration, format extension, and content syndication, particularly as Western studios and technology groups increase their investment footprint. Simultaneously, advertising-supported models demand a deep understanding of audience demographics, engagement patterns, and inventory pricing dynamics to ensure margin sustainability.
Geographic strategy must reflect the asymmetric demand and platform maturity across regions. Enterprises targeting high-volume monetization should prioritize markets with established mobile payment infrastructure, mature platform ecosystems, and proven audience willingness to spend on episodic short-form content. Organizations focused on long-term audience accumulation, brand presence, or localized content development should evaluate secondary and emerging regions where platform competition is still structuring itself and early positioning can yield disproportionate advantages as ecosystems mature. In all cases, localization of content styles, release cadence, pricing models, and platform features remains essential to capturing organic growth rather than relying solely on import-driven distribution.
Vertical Screen Short Drama Market
What the Full Research Delivers
This overview establishes the macro trajectory, competitive architecture, and strategic stakes of the vertical screen short drama market, but enterprise-grade decision-making requires a deeper analytical layer. The full PW Consulting market research expands far beyond high-level growth figures to provide actionable intelligence across revenue model breakdowns, regional demand drivers, application channel performance, competitive positioning metrics, and scenario-based forecasting. The report maps monetization pathways across subscription, advertising, and licensing streams with operational detail, examines how platform concentration and fragmentation influence partnership leverage, and traces the interplay between production economics, content volume scaling, and audience retention. It integrates recent corporate developments, regulatory and ecosystem dynamics, and consumer habit shifts into a cohesive strategic framework designed to support market entry planning, investment prioritization, and platform partnership design.
Worldwide Mini Program Short Drama Market
To translate these structural insights into precise, executable strategy for 2026 and the forecast horizon through 2032, decision-makers need the complete dataset, segmentation depth, and modeled scenarios contained in the full report. Access the complete Vertical Screen Short Drama Market research on the PW Consulting source page to obtain the full intelligence portfolio, including detailed market sizing, revenue model analysis, competitive benchmarking, and regional application insights designed to support high-stakes corporate strategy, investment allocation, and content ecosystem planning.
For detailed analysis of this topic, please visit the official page: Vertical Screen Short Drama Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com