

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Report: Desktop Cloud Terminal Market Forecast to Grow at a 4.98% CAGR Through 2032
By pmarketresearch, 2026-07-06
Desktop Cloud Terminal Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
As enterprises across industries accelerate desktop virtualization and cloud-first workplace strategies, the desktop cloud terminal market emerges as a strategic fulcrum for cost optimization, security posture, and operational resilience. PW Consulting’s newest market research — built on a historical lens (2020–2025) and a forward-looking forecast (2026–2032) — presents the directional intelligence executives need to make defensible decisions in 2026. The market was valued at approximately USD 1,690.8 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of c. 4.98% through our forecast horizon, underscoring steady expansion driven by hybrid work models, DaaS adoption, and regulatory-led security investments.
Desktop Cloud Terminal Market
Why this brief matters to 2026 decision-makers
-
Timing: Many large enterprises and public-sector institutions plan refresh cycles and cloud migration milestones in 2026. Decisions taken this year will lock in platform choices, supplier commitments, and security architectures for multiple years.
Desktop Cloud Terminal Market -
Cost-structure optimization: With rising data center energy costs (notably a reported ~15% uplift in 2025 driven by AI workloads), total cost of ownership (TCO) calculus for hosted virtual desktop environments has shifted materially. The report models these dynamics and provides scenario-based TCO comparisons for cloud terminals versus legacy PCs and thin-client on-prem deployments.
Desktop Cloud Terminal Market -
Risk and compliance: New regulatory touchpoints — from the EU Data Governance Act to updated zero-trust expectations in the US federal sphere — are reshaping procurement criteria. Our analysis translates these rules into practical vendor and architecture requirements for 2026 procurement.
Top strategic themes highlighted
-
Modernizing the endpoint without recreating the desktop: Organizations balancing user experience and security will increasingly prioritize cloud terminals that support multi-protocol VDI, multi-monitor workflows, and local peripheral handling while minimizing on-device data sprawl.
-
Security converges with identity and network posture: The move to zero-trust frameworks elevates endpoint attestation, firmware integrity, and secure boot as procurement non-negotiables. The report identifies practical control sets and validation steps for enterprise buyers.
-
Supply chain and geopolitical resilience: Export controls and trade measures are compressing some hardware supply options. Our advisory highlights sourcing strategies and vendor diversification approaches to reduce disruptions for 2026 deployments.
-
Sustainability and operational cost pressure: Increased energy consumption at data centers affects the marginal cost of hosted desktops. Buyers now need to factor both energy intensity of workloads and device lifecycle emissions into buy-versus-build analyses.
-
Architectural pluralism — cloud, edge, and ARM-capable endpoints: The ecosystem is moving toward heterogeneous deployments where ARM-based cloud terminals, x86 thin clients, and zero clients coexist. We map decision criteria for mixing architectures without adding operational complexity.
Competitive landscape — what to watch in 2026
The market remains moderately concentrated; the top three players command a material share of revenue, and the top five intensify competitive dynamics through differentiated software and channel strategies. This concentration creates both stability and barriers for new entrants, while opening white-space for niche vendors specializing in security, vertical workflows, or managed DaaS integration.
-
Dell Technologies (Round Rock, Texas) continues to invest in its Wyse thin client portfolio with explicit support for mainstream cloud desktop platforms. Recent product activity signals a push to optimize multi-monitor and Cloud PC interoperability — a response to enterprises standardizing on services like Windows 365.
-
HP Inc. (Palo Alto) leverages certification and compatibility as a commercial differentiator. Certifications for major VDI stacks ease procurement friction in regulated environments and support broader Azure Virtual Desktop and Citrix adoption patterns.
-
Lenovo (Beijing / Morrisville) is refreshing thin-client offerings around modern CPUs to better host virtual desktop clients locally and support richer user experiences, targeting both enterprise and edge computing scenarios.
-
IGEL Technology (Reading, UK) is notable for its software-first endpoint approach, with recent OS releases embedding new cloud desktop protocols and zero-trust features — a blueprint for vendors that aim to monetize software and services over hardware.
-
10ZiG, Huawei, Acer and other specialists continue to hold strategic positions: 10ZiG with protocol specialization for PCoIP/Blast, Huawei with integrated offerings for domestic enterprise clouds, and Acer focused on cost-effective thin-client SKUs for managed service providers.
Recent vendor developments — from product launches to OS and certification updates — signify incremental innovation rather than disruptive shifts. For procurement teams, the practical implication is to prioritize interoperability and long-term software support commitments over isolated hardware features.
What PW Consulting’s report delivers — practical, executable intelligence
-
Actionable decision frameworks: Playbooks for operator models (in-house VDI, DaaS, hybrid managed services), migration paths, and procurement checklists that align with regulatory and security requirements.
-
Vendor evaluation toolkit: Scorecards and weighted criteria that translate product, software lifecycle, channel strength, and security posture into defensible vendor shortlists.
-
Financial models: Scenario-based TCO tools that account for device economics, data-center energy impacts, staffing, and projected licensing costs under multiple workload mixes.
-
Security and compliance blueprints: Mapped controls for zero-trust maturity stages, evidence artifacts for audits, and recommended validation tests for firmware and endpoint attestation.
-
Operational runbooks: Patch, image, and lifecycle management workflows designed to minimize user disruption during endpoint refreshes and to simplify scaled rollouts across regions.
-
Scenario planning appendices: Three strategic scenarios (Consolidation, Diversification, and Edge-first) with decision triggers and supplier playbooks that guide C-suite timing and capital allocation.
Guidance for procurement and IT leaders in 2026
-
Shift evaluation from device-centric to experience-centric metrics: Assess solutions by end-user experience (latency, peripheral support, multimedia fidelity) and the vendor’s commitment to lifecycle software updates.
-
Embed regulatory mapping into technical RFPs: Ensure RFPs require vendor attestations for data sovereignty, export-compliance evidence, and an audited supply chain transparency statement.
-
Prioritize interoperable, software-first approaches: Vendors offering robust OS/firmware update channels and cloud-agnostic clients reduce lock-in and lower long-term migration costs.
-
Build energy-aware TCO into procurement governance: Require energy-performance metrics and real-world hosting cost scenarios when assessing managed DaaS offers.
-
Adopt phased migration with clear rollback triggers: Pilot narrow cohorts, validate security baselines, then scale; maintain a rollback play to mitigate user-impact risk during larger rollouts.
Regulatory and macro risks to factor in
-
Cross-border data rules: New governance frameworks introduce constraints on how virtual desktop images and user data traverse jurisdictions.
-
Export control exposure: Restrictions on certain compute hardware can complicate procurement strategies for global programs — dual-sourcing and regional vendor partnerships are practical mitigants.
-
Rising infrastructure costs: Energy and data-center economics now materially affect marginal cost per hosted desktop; buyers must stress-test vendor pricing under higher-cost scenarios.
-
Zero-trust enforcement: As federal and sector-specific guidelines evolve, compliance will increasingly be a procurement gating item rather than a post-deployment initiative.
Why PW Consulting’s brief is your strategic shortcut
We have combined market modeling, vendor diagnostics, regulatory impact analysis, and operational playbooks into a single, practitioner-oriented deliverable. The report’s high-level market figures (including the 2025 market valuation and the forecast CAGR to 2032) provide clear directional context, while the core report contains the granular segmentation, regional breakdowns, and vendor-by-vendor revenue analysis needed for procurement committees and CIO offices.
In keeping with our “preview” approach, this article emphasizes strategic conclusions and executable guidance without reproducing the full set of segmentation tables and sensitive vendor metrics. Procurement teams, CIOs, and strategy leaders seeking the detailed appendices — regional market splits, end-user vertical sizing, and vendor revenue schedules — will find them in the full report and companion data workbook.
Next steps
-
For an executive briefing: Request a tailored 60-minute workshop where PW Consulting will map the report’s scenarios to your estate and present a prioritized migration roadmap for 2026.
-
For procurement teams: Access the full dataset and vendor scorecards to generate an RFP aligned to your security and TCO requirements.
-
For investors and partners: Contact our industry research desk for a deep dive on competitive positioning, M&A risk factors, and white-space opportunities in managed services and protocol specialization.
PW Consulting’s Desktop Cloud Terminal Market report is designed to convert market intelligence into practical action for 2026 planning cycles. We provide the strategic context you need now — and the detailed instruments you’ll use to execute next.
For detailed analysis of this topic, please visit the official page: Desktop Cloud Terminal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Special Electronic Chemicals for Photoresist Market Set to Expand at 5.51% CAGR Through 2032
By pmarketresearch, 2026-07-06
Special Electronic Chemicals for Photoresist Market: Strategic Imperatives for 2026 — PW Consulting Special Report Preview
Executive snapshot
PW Consulting’s Special Report on Special Electronic Chemicals for Photoresist provides a focused, strategy-first briefing for senior executives preparing capital, sourcing and product roadmaps in 2026. The research synthesizes historical performance (2020–2025), a detailed seven-year forecast horizon (2026–2032), and practitioner-grade playbooks that link chemistry, fab economics and regulatory risk into executable options. The headline market trajectory — underpinned by a mid-single-digit compound annual growth rate (CAGR) — confirms steady expansion but masks important inflection points that will determine winners in the next planning cycle.
Special Electronic Chemicals For Photoresist Market
Market trajectory and headline economics
The market for specialty electronic chemicals used in photoresist and photolithography processes has shown resilient growth through the early 2020s and continues to expand into the decade. Our model, built on supplier capacity data, demand-side adoption curves for advanced nodes and displays, and raw-material flows, estimates the global market size increased materially between 2020 and 2025 and is projected to accelerate through 2032. The compounded annual growth rate across the forecast window is 5.51%, and the absolute expansion should be evaluated not as uniform growth but as a sequence of demand pulses driven by fabs ramping EUV and next-generation patterning programs, display investment cycles, and the ongoing modernization of legacy fabs.
Special Electronic Chemicals For Photoresist Market
Why 2026 is an inflection year
- Capacity timing: Several leading producers have announced capacity investments and greenfield plans whose first-volume effects begin to materialize in 2026–2027. This changes supply dynamics in ways that will affect contract leverage for buyers and margin trajectories for suppliers.
- Technology adoption: Customer transitions to EUV-compatible chemistries and novel resist architectures create differentiated demand pockets. Suppliers that combine material innovation with scalable manufacturing will capture premium growth.
- Regulatory pressure: Emerging restrictions and reporting requirements tied to PFAS and related chemistries introduce compliance costs and sourcing constraints that must be baked into 2026 procurement strategies.
Key growth engines and demand vectors
Three structural drivers underpin the mid-single-digit CAGR and the shape of the horizon curve. First, the ongoing production increases for advanced logic and foundry capacity elevate demand for high-purity resins, photoacid generators and specialty solvents engineered to meet sub-10 nm impurity thresholds. Second, display technologies and high-resolution patterning for advanced packaging create differentiated demand for solvent and additive chemistries. Third, PCB and legacy-node manufacturing remain meaningful baseloads that absorb differentiated film and dry-film resist formulations.
Special Electronic Chemicals For Photoresist Market
Supply chain and raw-material dynamics — what matters for procurement
Volume and quality of upstream inputs are decisive. Industry aggregates show multi-million‑liter scale consumption of high-purity solvents and multi‑hundred‑thousand‑kilogram scale polymer resin usage annually, with polymers representing a material share of the raw-material volume base. For advanced nodes, solvent impurity thresholds routinely fall below 1 ppm, making supplier qualification and analytics capability strategic necessities rather than tactical concerns. Buyers must therefore pivot from price-only RFQs to capability- and compliance-based sourcing: traceable supply chains, validated ultra-high-purity lots, and contingency plans for solvent and monomer supply interruptions.
Regulatory and sustainability headwinds
Regulatory developments are no longer peripheral. Ongoing assessments under TSCA and state-level PFAS frameworks are introducing potential substance-level restrictions and reporting obligations that will cascade through purchasing, storage, waste management and product design. Some photoacid generators and fluorinated additives are explicitly in regulatory focus; suppliers and users should assume a phased timeline of disclosure, restriction and substitution pressure through 2032. Companies that proactively invest in non-fluorinated alternatives and maintain robust compliance analytics will avoid expensive redesigns and permit delays.
Competitive landscape — who sets the tone
The market structure remains consolidated at the top: a small group of global leaders controls a majority of advanced photoresist capacity, while a broader field of specialized and regional suppliers serves niches and legacy segments. Market concentration metrics indicate that the top three firms capture a clear plurality of advanced-product supply, and the top five account for an even larger share — underscoring the strategic premium of partnerships with tier‑one suppliers.
- Tokyo Ohka Kogyo (TOK): A technology frontrunner for advanced photoresists across EUV and ArF families. Recent capital allocations and land acquisitions signal a multi-year capacity build aligned to its tok Vision 2030. For firms negotiating long-term supply, TOK’s capacity trajectory is a leading indicator of availability for EUV-grade resists.
- JSR Corporation: Deep expertise in next-generation resist chemistries, including metal-oxide and other EUV-compatible formulations. The joint‑venture path into Taiwan manufacturing indicates a strategy of proximity to high-growth foundry clusters and faster qualification cycles with Asian customers.
- Shin-Etsu Chemical, FUJIFILM, DuPont and Merck (EMD): These large, diversified suppliers combine chemistry IP with global production footprints. DuPont’s recent expansions in Japan illustrate the industry’s approach to geographically distributed capacity to mitigate supply risk for critical lithography inputs.
- Regional innovators and niche specialists: Firms from Korea, Taiwan and Europe continue to supply specialized resists, spin-on hardmasks and R&D-intense materials, providing alternatives for customers prioritizing flexibility or unique chemistries.
Recent strategic moves — signal analysis
- Capacity expansions and new plant sites demonstrate that the supply base expects continued demand for advanced chemistries. Those commitments will loosen near-term tightness for certain products but also intensify competition for higher-margin, differentiated formulations.
- Localized manufacturing partnerships and JVs signal a shift toward proximity sourcing. For global OEMs and foundries, this reduces qualification time and logistical complexity, but it raises the bar for suppliers seeking to maintain a single global standard across facilities.
- Manufacturers are also incorporating sustainability and regulatory resilience into site planning and product design — a trend we expect to accelerate as PFAS-related regulatory action unfolds.
Report deliverables — what’s inside (practical, not theoretical)
PW Consulting’s special report translates the above into actionable instruments for 2026 decision cycles. Core deliverables include:
- Forward-looking global demand model (2026–2032) with scenario outputs tied to foundry ramps, display cycles and legacy-node attrition.
- Supplier scorecards benchmarking capacity, technology fit (EUV/ArF/KrF), quality systems, geographic exposure and regulatory posture.
- Supply-risk heatmaps and procurement playbooks: dual‑sourcing templates, qualification timelines, and inventory optimization for high‑purity solvents and polymer resins.
- M&A and partnership opportunity matrix highlighting adjacencies in specialty solvents, PAGs and additives where consolidation or JV structures unlock scale or IP synergies.
- Regulatory impact framework that maps PFAS/TSCA trajectories to product portfolios and compliance cost estimates, with substitution pathways for affected chemistries.
- Operational checklists for fab integration teams covering lot traceability, impurity analytics and change-control protocols essential to qualifying new supplier lots for sub‑10 nm processes.
How to use this intelligence in 2026 — tactical recommendations
- Rebase procurement KPIs: move from price and lead time to a multi-dimensional scorecard that includes impurity analytics capability, regulatory readiness and localization options.
- Prioritize early engagement with tier‑one suppliers who are expanding capacity or establishing local sites in fabrication clusters; qualification lead times materially affect time-to-production.
- Invest in analytics: in-house or partner labs capable of sub-ppm impurity detection reduce qualification friction and provide leverage in commercial negotiations.
- Stress-test your portfolio against PFAS regulatory scenarios with staged substitution plans and alternative-formulation pilots to avoid late-stage disruptions.
- Consider strategic inventory buffers for solvent classes and select polymer resins while ramp plans for supplier capacity take effect — but balance this against working-capital impacts using PW’s optimization templates.
Why this “preview” matters — and what we deliberately withhold
This release is structured as a strategic preview: it surfaces the most consequential insights and executable options that will shape boardroom decisions in 2026 while preserving the granular segmentation tables, supplier-level volume forecasts and proprietary pricing curves that are contained in the full report. Those core sub‑segment datasets are the high-value outputs intended for subscribers and clients who require transaction‑grade intelligence for tendering, M&A diligence or capital allocation.
Next steps and how to engage
Executives seeking to convert the market trajectory into defensible 2026 plans should request a consultative briefing with PW Consulting’s photoresist chemicals practice. Our briefings pair the full dataset with scenario simulations tailored to your supply base, CAPEX calendar and regulatory exposure, enabling a concrete, time-bound action plan for procurement, engineering and corporate development teams.
For detailed analysis of this topic, please visit the official page: Special Electronic Chemicals For Photoresist Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Inline Viscometers Market Set to Grow at a 6.85% CAGR Through 2032, Fueled by Asia‑Pacific Demand
By pmarketresearch, 2026-07-06
Inline Viscometers Market: Strategic Briefing for 2026 Decision‑Makers
Executive summary
As PW Consulting’s senior industry analyst, I present a concise strategic briefing distilled from our new Inline Viscometers Market report. The market for inline viscometers has moved from niche process instrumentation toward a core enabling technology across multiple process industries. After a steady recovery through 2020–2025, the market is forecast to expand at a compound annual growth rate (CAGR) of 6.85% through our 2026–2032 projection horizon, moving from an estimated USD 248.5 million in 2025 to roughly USD 395.7 million by 2032. This trajectory, together with a moderate market concentration profile among leading suppliers, creates a window of opportunity for manufacturers, system integrators, and end‑users to recalibrate product, channel and M&A strategies in 2026.
Inline Viscometers Market
Why 2026 is an inflection point
-
Operationalization of real‑time process control: More production lines are shifting from lab‑based QC to real‑time, inline analytics to reduce cycle time and waste. Inline viscometers are central to that shift because they provide continuous rheological context that correlates directly with quality and yield.
Inline Viscometers Market -
Technology maturation and product differentiation: Resonant sensor techniques, integration with Coriolis and density meters, and robust vibrational/rotational sensor families now make inline measurement more repeatable and maintainable in harsh process environments.
Inline Viscometers Market -
Commercial momentum: The market’s growth profile—backed by the 2020–2025 historical trend and the 2026–2032 forecast—signals that buyers will increasingly allocate CAPEX and OPEX budgets to inline control rather than episodic lab testing.
Snapshot of the report’s practical value
The PW Consulting Inline Viscometers report is designed as a decision‑ready toolkit for executives planning 2026 initiatives. It blends quantitative forecasting with actionable playbooks tailored for three types of stakeholders: vendors seeking share expansion, industrial end‑users integrating inline analytics, and investors evaluating consolidation or growth investments. Key practical modules include:
-
Demand forecasting and scenario modeling — flexible models that translate market CAGR and baseline market size into addressable market estimates under alternative adoption curves.
-
Product and technology playbook — comparative analysis of sensor modalities (vibrational, rotational, torsional oscillation and others), integration patterns with flow/density measurement systems, and recommended roadmaps for R&D prioritization.
-
Commercial benchmarking — pricing sensitivity, typical procurement cycles, and channel strategies for OEMs, distributors and system integrators.
-
Implementation playbooks for end users — specifications templates, risk checklists, and maintenance/ calibration regimes to minimize downtime and realize ROI faster.
-
M&A and partnership heat maps — acquisition targets, strategic partnership archetypes, and integration pitfalls informed by concentration metrics and vendor capabilities.
Market dynamics and what the numbers mean for strategy
The market’s numerical story is simple but strategic: after a compound recovery from the early‑2020s, industry demand accelerates in tandem with broader automation and digitalization investments. A forecast CAGR of 6.85% through 2032 represents not only volume growth but also value capture from higher‑functioning product tiers and integrated solutions. For management teams, three implications stand out:
-
Move from components to solutions: Suppliers that can sell viscometry as part of a closed‑loop control system (hardware + software + lifecycle services) will disproportionately capture revenue and margin as buyers prefer single‑vendor accountability for process KPIs.
-
Invest in robustness and maintainability: Field reliability and low maintenance drive adoption in continuous processes (e.g., chemical and food production). Investments in sensor immunity to fouling and simplified in‑line cleaning will shorten sales cycles.
-
Targeted vertical plays: Although demand spans multiple applications, the fastest near‑term ROI often comes from deployments with tight viscosity–quality correlations where continuous control eliminates rework or scrap.
Competitive landscape — who to watch
The sector exhibits moderate concentration: the top three suppliers control a meaningful share, and the top five further increase market aggregation. This structure creates both defensive pressures for incumbents and strategic entry points for challengers.
-
AMETEK Brookfield (USA) — A legacy instrumentation player known for inline viscosity sensors tailored to food, chemical and pharmaceutical continuous monitoring. Their broad product family and established service network make them a go‑to for risk‑averse buyers. ( https://www.brookfieldengineering.com)
-
Anton Paar GmbH (Austria) — A premium provider with strong engineering credentials in inline process sensors. Their emphasis on accuracy and process integration positions them well where measurement precision directly impacts product specs. ( https://www.anton-paar.com)
-
Rheonics AG (Switzerland) — A technology‑driven supplier specializing in resonant sensor technology that combines viscosity and density sensing. Their solutions are particularly compelling where multisensor fusion improves process control. ( https://rheonics.com)
-
Emerson Electric Co. (USA) — Known for systems integration and for bundling viscometry with Coriolis flow measurements, Emerson is a strategic partner for large process plants seeking end‑to‑end automation. ( https://www.emerson.com)
-
KROHNE Messtechnik GmbH (Germany) — Offers robust inline viscometers for chemical and petrochemical environments, with deep experience in industrial installations and field service. ( https://www.krohne.com)
For buyers and investors, the competitive map suggests two viable strategies: (1) pursue partnerships with integrated systems suppliers to shorten procurement cycles, or (2) differentiate through specialized sensing modalities and post‑sale services in targeted verticals.
Regulatory and standards context
Standards provide the backbone for acceptance of inline measurement. Notably, ISO 3219:2021 remains the active standard that specifies rotational viscometer methods. Alignment with recognized standards reduces procurement friction and often shortens validation timelines in regulated industries (e.g., pharmaceuticals and food & beverage). For vendors, early compliance and transparent certification are defensible features in competitive bids.
Practical recommendations for 2026 planning
-
Vendors : Prioritize modular, serviceable designs and package measurement into outcome‑based offerings (e.g., reduced scrap, increased throughput). Use the projected CAGR to model recurring revenue from service contracts and remote diagnostics.
-
End users : Initiate pilot projects in lines with the clearest viscosity–quality linkage. Define KPIs tied to yield and downtime and require vendors to provide data demonstrating those improvements.
-
Investors : Look for targets that combine robust sensor IP with SaaS‑capable analytics; these firms are likely to command premium exit multiples as buyers seek both hardware and recurring software revenues.
-
System integrators : Build capabilities to integrate viscometers with DCS/PLC environments and provide lifecycle maintenance packages—this positions integrators as indispensible partners for digitalization roadmaps.
Risk considerations and mitigation
Key risks include sensor fouling in high‑viscosity or particulate environments, integration complexity across heterogeneous control systems, and potential commoditization pressure as more suppliers enter. Mitigations include investing in adaptive cleaning protocols, emphasizing interoperable communication stacks (OPC UA, Modbus, etc.), and protecting higher‑margin segments through value‑added services and certification.
How to use the full report
This article is a strategic “trailer” that surfaces the report’s central narratives and prescriptive themes. The full PW Consulting Inline Viscometers Market report contains the operational detail that will convert strategy into execution: customizable financial models, procurement‑grade specifications, a vendor short‑list with comparative matrices, and step‑by‑step deployment playbooks. These elements are intentionally granular to support 2026 investment approvals, CAPEX planning, and supplier selection processes.
Closing — why engage now
The 2026 planning cycle is the decisive moment to capture the projected market upside. The combination of technology readiness, accelerating adoption and a predictable growth trajectory creates a limited window for market entrants and incumbents to secure advantageous positions. PW Consulting’s report does more than predict growth; it prescribes the operational moves—product design choices, go‑to‑market plays, and integration tactics—that will determine who captures the lion’s share of the value created over the next business cycle.
For executives ready to translate the market trajectory into concrete actions in 2026, PW Consulting offers tailored briefings and implementation support derived from the full report. Contact our advisory team to schedule a confidential strategy session and obtain the complete report package.
For detailed analysis of this topic, please visit the official page: Inline Viscometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bipolar Laparoscopic Forceps Market Reaches USD 825.5 Million in 2025, Signaling Robust Growth
By pmarketresearch, 2026-07-06
Bipolar Laparoscopic Forceps Market — Strategic Preview for 2026 Decision-Making
Executive Summary
PW Consulting’s latest market research on the Bipolar Laparoscopic Forceps market provides a focused, decision-oriented briefing for executives planning moves in 2026. The global market has expanded steadily through the first half of the decade, and our analysis quantifies a clear growth trajectory underpinned by clinical adoption, device innovation, and material/regulatory shifts. While this release intentionally withholds detailed subsegment figures to preserve the full-service value of the report, it demonstrates the strategic lines of sight leaders need to prioritize in the coming 12–18 months.
Bipolar Laparoscopic Forceps Market
Market Snapshot (macro)
Using 2025 as the base year, PW Consulting measures the global Bipolar Laparoscopic Forceps market in USD Million and models performance across a 2026–2032 forecast period. The market recorded robust growth from the start of the decade and reached a significant milestone in the base year. Our forecast translates into a compound annual growth rate (CAGR) of 6.15% for the period ahead, reflecting steady demand from hospitals and ambulatory surgery centers, continued preference for minimally invasive procedures, and product refresh cycles driven by clinical and environmental priorities.
Bipolar Laparoscopic Forceps Market
Key headline figures (presented at the aggregate level) underscore predictable expansion and the size of the opportunity for equipment manufacturers, distributors, and private equity participants looking to enter or scale within the segment. For access to the complete time-series tables and downloadable datasets, consult the full report on the PW Consulting site.
Bipolar Laparoscopic Forceps Market
What the Report Contains — Practical, Actionable Deliverables
- Proprietary market model calibrated to manufacturer sell‑through, hospital procurement cycles, and device replacement rates — designed for scenario analysis across 2026 budget cycles.
- End‑user intelligence: synthesis of hospital procurement criteria, preference drivers (durability, ergonomics, compatibility with energy platforms), and sterilization/cycle cost considerations.
- Regulatory and reimbursement compendium: device classification roadmap, key compliance checkpoints for product updates, and practical guidance on coding environments relevant to laparoscopic bipolar coagulation.
- Commercial playbooks: go‑to‑market options for OEMs, value propositions for distributors, bundle/consumable approaches for energy-platform vendors, and tender management templates for supply agreements.
- Supply chain and manufacturing risk matrix: vulnerability scoring for contract manufacturing locations, single‑sourcing exposure, and recommendations for nearshoring and dual‑sourcing strategies.
- Environmental and materials guidance: assessment of PVC‑free disposable solutions, life‑cycle tradeoffs of disposable vs. reusable instruments, and hospital sustainability procurement levers.
- Scenario planning tools: three pathway scenarios (base, accelerated adoption, and constrained procurement) with operating assumptions to stress test investment decisions.
Market Dynamics — Drivers, Frictions, and Inflection Points
- Clinical adoption and procedure mix: Continued migration to minimally invasive approaches sustains baseline demand, while pockets of procedure-specific innovation (instrument multifunctionality, integrated irrigation) create incremental replacement cycles.
- Regulatory and reprocessing burden: Reusable laparoscopic bipolar forceps require rigorous cleaning, inspection, and validated sterilization (gravity displacement, ethylene oxide, hydrogen peroxide plasma systems such as Sterrad, or broad‑spectrum washer‑sterilizers like Steris) in accordance with manufacturer IFUs. These operational requirements drive hospital TCO calculations and influence preference for disposable alternatives in select settings.
- Materials and sustainability trends: The emergence of PVC‑free disposable forceps — introduced in recent regional rollouts — is reshaping supplier differentiation, especially where environmental purchasing policies are enforced.
- Technology convergence: Compatibility with electrosurgical platforms and energy generators is a competitive lever. Devices optimized for precise coagulation, non‑stick performance, and integrated irrigation are winning clinical preference in high‑volume theatres.
- Market structure: The market shows moderate concentration among leading global OEMs, leaving clear space for specialized entrants and regional champions, particularly those offering localized service, lower capital intensity, or compelling environmental credentials.
Competitive Landscape — Profiles and Strategic Posture
Our report includes a detailed competitive assessment of incumbent and emerging providers. Below is an executive synthesis of the core players covered:
- B. Braun / Aesculap (Melsungen, Germany): Broad portfolio of reusable and single‑use bipolar forceps with recent product introductions emphasizing irrigation and non‑stick coatings. Strengths: deep clinical relationships, service networks, and integrated product ecosystems.
- Medtronic (Dublin, Ireland): Focus on compatibility of bipolar instruments with energy platforms; leverages platform breadth to drive procurement bundling. Strengths: global sales channels and strong presence in hospital purchasing frameworks.
- Karl Storz (Tuttlingen, Germany): Notable for rotating bipolar designs and narrow‑profile offerings for gynecology and general surgery. Strengths: high‑precision engineering and brand recognition among specialty surgeons.
- Boer Medical (Hangzhou, China) and Zhejiang Geyi Medical Instrument (China): Cost‑competitive disposable and reusable lines with increasingly sophisticated manufacturing capabilities. Strengths: scale and cost agility for price‑sensitive markets.
- Advin Health Care (Ahmedabad, India): Regional supplier with emphasis on reusable instruments and cable‑integrated Maryland variants. Strengths: localized manufacturing and distribution, rapid response to tender requirements.
- Purple Surgical (United Kingdom): Differentiates with multifunctional bipolar cutting forceps that integrate dissection, coagulation, and transection. Strengths: niche product innovation and surgeon‑driven design.
Notable recent product moves included the launch of an irrigating disposable bipolar forceps with higher irrigation output and non‑stick features by Aesculap (Oct 2025) and the regional introduction of PVC‑free disposable options by Duomed (July 2024). These developments crystallize two near‑term battlegrounds: performance enhancement (irrigation, non‑stick) and sustainability/material compliance (PVC‑free disposables).
Implications for 2026 Strategy
We translate the above dynamics into six strategic imperatives for market participants planning activity in 2026:
- Prioritize platform compatibility and clinical evidence: Devices that demonstrate superior clinical outcomes (reduced OR time, lower instrument exchange rates) and seamless integration with electrosurgical platforms will command price premiums and preferred formulary positions.
- Optimize the reusable vs. disposable calculus: Hospitals will increasingly quantify sterilization costs, turnaround times, and environmental KPIs. Vendors should arm purchasers with transparent TCO and carbon‑footprint models and offer hybrid supply models (consumables + service).
- Differentiate on materials and sustainability: PVC‑free materials and reduced adhesive chemistries are becoming procurement filters in advanced markets; product roadmaps should include compliance milestones for these materials.
- Invest in service and training: Given the procedural sensitivity of bipolar instruments, structured surgeon and OR‑team training programs — combined with data capture on OR performance — are powerful retention tools for OEMs and distributors.
- Mitigate supply chain concentration risk: With moderate market concentration, agile players that offer guaranteed supply continuity through diversified manufacturing footprints will win tenders during periods of supply stress.
- Scan for M&A and partnership opportunities: Small innovators with differentiated materials, irrigation technologies, or digital OR integrations are attractive targets for incumbents seeking rapid capability acquisition.
How Buyers and Investors Should Use the Report
- Procurement teams: Use the report’s vendor scorecards and TCO calculators to streamline tender specifications and to negotiate bundled energy‑platform contracts.
- Product and R&D leaders: Leverage the clinical preference mapping and sterilization constraint matrix to prioritize design targets and materials choices for 2026 development cycles.
- Private equity and corporate development: Apply the concentration analysis and scenario models to size investment theses, identify consolidation targets, and stress‑test exit multiples under alternate adoption scenarios.
Regulatory and Reimbursement Checklist (Practical)
- Device classification alignment: Laparoscopic manual instruments, including bipolar forceps, are regulated as Class II devices under common regulatory frameworks — ensure documentation aligns with relevant product codes and guidance.
- Sterilization validation: Reusable devices must have validated reprocessing instructions; suppliers should provide validated IFUs for all recommended sterilization modalities.
- Reimbursement awareness: Procedural coding regimes commonly used for laparoscopic sterilization/coagulation should be factored into hospital economic models and budget impact analyses.
Conclusion and Next Steps
For decision-makers preparing capital, product, or M&A moves in 2026, the Bipolar Laparoscopic Forceps market presents a mix of steady organic growth and pockets of disruptive opportunity driven by materials innovation and platform integration. PW Consulting’s full report supplies the granular datasets, regional and application splits, and downloadable models required to finalize commercial plans. This preview has surfaced the strategic levers — sterilization economics, material choices, platform compatibility, and service‑led retention — that are likely to determine winners over the next planning cycle.
Accessing the Full Report
PW Consulting offers the complete research package, including the full time‑series market model, segment‑level forecasts, pricing curves, and supplier scorecards. Because the most commercially sensitive subsegment data are gated to preserve client value, please contact PW Consulting for access to the full dataset and bespoke advisory options tailored to your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Bipolar Laparoscopic Forceps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Modular Steering Column Market to Hit USD 3,969.5 Million by 2032
By pmarketresearch, 2026-07-06
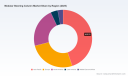
Modular Steering Column Market: Strategic Imperatives for 2026 Decision‑Making
As OEMs and tier suppliers prepare their 2026 roadmaps, the modular steering column market is transitioning from a component-centric supply space into a systems and software battleground. PW Consulting’s forthcoming Modular Steering Column Market report synthesizes seven years of historical performance with a forward-looking 2026–2032 forecast to help executives make confident, time‑sensitive choices. Our analysis combines quantitative market sizing and growth assumptions with a pragmatic, transaction‑ready playbook for procurement, product development, and M&A teams.
Modular Steering Column Market
Market snapshot: scale, trajectory, and structural cues
After steady expansion in the early 2020s, the global modular steering column market reached roughly USD 2.65 billion in our 2025 base year. Under the assumptions and demand drivers set out in this report, the market is projected to sustain a mid‑single digit compound annual growth rate (CAGR) through 2032, reaching an industry magnitude approaching USD 4.0 billion by the end of the forecast window. This trajectory is driven by a confluence of factors: accelerating vehicle electrification, rising safety and functional integration requirements, and continuing OEM preference for modular platforms that compress time‑to‑market.
Modular Steering Column Market
Two structural characteristics are central to strategic planning: first, market concentration is meaningful but not insurmountable — the top three and top five suppliers collectively account for a material share of industry revenues, signaling both defensive moats and pockets of opportunity for challengers. Second, value is migrating from mechanical fit‑and‑form to software, systems integration and safety validation — an evolution that alters supplier economics and the rationale for vertical integration.
Modular Steering Column Market
What this report delivers — practical intelligence for 2026 decisions
- Validated market sizing and forecast model (2020–2032), with scenario variants calibrated to electrification and regulation sensitivity.
- Competitive scorecards for incumbent and emerging suppliers, emphasizing product modularity, software capability, manufacturing footprint, and validation throughput.
- Regulatory and standards map (including safety and functional safety requirements) tied to compliance cost estimates and testing timelines.
- Supplier selection framework and total cost of ownership (TCO) tool that models unit cost, warranty exposure, and integration engineering effort.
- Technology roadmaps for tilt/telescopic actuation, electric adjustable columns, and electronic control modules, with milestone gating for 2026–2029 product programs.
- M&A and partnership heatmaps identifying targets by capability gaps, integration risk, and valuation multipliers.
- Raw material and commodity risk assessment focusing on lightweight alloy exposure and mitigation strategies for supply volatility.
Key strategic implications for OEMs and suppliers
- Design to modularity, procure for systems integration: OEMs should shift procurement briefs from part specifications toward validated systems interfaces. Doing so reduces integration cycles and clarifies warranty allocation between mechanical and electronic domains.
- Prioritize functional safety early: Electronic steering column control modules fall within ISO 26262 scope — early architectural choices materially affect validation cost and calendar risk. Programs that defer functional safety scoping to late development stages face outsized timeline and rework exposure.
- Balance weight reduction with manufacturability: Magnesium and aluminum alloys remain attractive for weight savings but introduce supply and processing complexity. Suppliers with proven lightweighting processes and in‑house validation deliver a lower ramp risk for high‑volume programs.
- Plan for electrified adjustment functions: Electric adjustable columns are no longer niche; they are a critical differentiator for premium packaging and advanced driver assistance integration. Suppliers offering scalable electric actuation modules accelerate OEM feature rollouts.
- Manage concentration risk through supplier diversification and nearshoring: Given the moderate level of market concentration, intelligent diversification — combined with selective nearshoring — reduces program break risk without sacrificing unit economics.
Competitive landscape — positioning and dynamics
The market features a mix of global systems houses, regional specialists, and component specialists. Strategic positioning varies from full systems integrators to focused module providers; each archetype brings different advantages for OEMs and investors.
- Nexteer Automotive (Auburn Hills, MI, USA): Offers a wide portfolio across steering columns and intermediate shafts, with modular, scalable EPS solutions. Recent product premieres emphasize high‑output column‑assist systems that enable powertrain‑agnostic integration and lower calibration burden for OEMs.
- thyssenkrupp AG (Essen, Germany): Focuses on adaptive crash behavior and modular columns tailored to upper‑segmented vehicles, combining mechanical engineering depth with regionally diversified production.
- Kongsberg Automotive (Kongsberg, Norway): Strengths lie in tailored tilt/telescope modules for off‑highway and commercial segments, backed by full in‑house development and validation capabilities.
- Merit Automotive (Spain, global): Excels at integrating security and convenience features into column modules, enabling large variant counts while simplifying vehicle wiring and assembly.
- NSK Ltd. (Tokyo, Japan): Notable for electric tilt/telescope architectures and polymer‑based impact absorption technologies conducive to lightweight, upper‑pivot implementations.
- Robert Bosch GmbH (Gerlingen, Germany): Targets trucks and buses with maintenance‑free concepts using magnesium and plastics to cut weight and assembly complexity.
- ZF Friedrichshafen AG (Friedrichshafen, Germany): Via TRW integration, provides column control modules emphasizing safety and electronic integration for mixed passenger and commercial portfolios.
- JTEKT Corporation (Osaka, Japan): Leverages broad steering system portfolios to embed modular columns within EPS and HPS strategies across vehicle segments.
- Hyundai Mobis (Seoul, South Korea): Positions modular columns within broader chassis and safety suites for global OEM sourcing.
- Mando Corporation (Seoul, South Korea): Concentrates on electronic locking and lightweight actuation systems with an eye toward reducing assembly weight and cost.
Collectively, the competitive set demonstrates that value capture increasingly flows to suppliers that can combine mechanical modularity with electronic control, validated safety functions, and scalable manufacturing footprints. The concentration metrics we model confirm that the market is consolidated enough to favor incumbents on large programs, but open enough for well‑executed entrants with distinct software or lightweighting propositions.
Regulatory and materials environment — practical risks and responses
- Safety standards: Federal and international crash safety rules demand energy‑absorbing steering column behavior and controlled displacement under impact. These constraints influence mechanical architecture and validation scope early in program definition.
- Functional safety: ISO 26262 obligations for electronic column modules require defined ASIL targets, traceability, and high‑assurance toolchains. Failure to align architecture and supplier responsibilities creates certification delays.
- Materials and supply: Lightweight alloys (magnesium and aluminum) remain a primary lever for mass savings but expose programs to commodity cycles and processing complexity. Substitution strategies and alloy sourcing agreements are now routine elements of supplier negotiations.
Transaction playbook — how to use the report in 90 days
Executives can convert our analysis into actionable plans in three steps:
- Week 1–3: Decision triage. Use our supplier scorecards and TCO sensitivity tables to classify existing suppliers into retain/grow/replace buckets. Identify single‑sourced columns with high safety or software content for immediate risk mitigation.
- Week 4–8: Partnership and procurement design. Deploy our RFP templates and integration SLAs to negotiate fixed SLAs for software, firmware updates, and validation deliverables. Include commodity pass‑through terms for magnesium/aluminum exposure.
- Week 9–12: Capability builds and M&A scans. Apply our M&A heatmap to prioritize 1–3 bolt‑on targets or tech partnerships that close capability gaps in electric actuation, electronic locking, or systems validation.
Why this matters for 2026 planning
2026 marks a pivot year for many vehicle programs that began concept or alpha phases in 2023–2024. Decisions taken now — about whether to standardize on manual adjustable vs. electric adjustable columns, how to apportion functional safety responsibility, and where to locate validated manufacturing — will determine cost and feature parity through the next vehicle cycle. Our forecast and playbook are structured to inform those tradeoffs without requiring organizations to reinvent validation processes or rebaseline program economics.
Accessing the full intelligence
This release is a strategic preview intended to demonstrate the depth of our methodologies and the immediate applicability of findings. Detailed regional and application splits, supplier revenue models, proprietary scenario outputs, and the full set of validation checklists are intentionally excluded from this summary to preserve the integrity of the underlying research product.
To obtain the complete Modular Steering Column Market report — including the granular segment tables, supplier financial proxies, and executable procurement templates — please contact PW Consulting or visit our report portal. For program teams seeking immediate support, our consultants are available for short, focused engagements to run the TCO model against your specific BOM assumptions and to workshop supplier selection with your engineering and procurement leaders.
Prepared by PW Consulting’s Advanced Mobility Practice — our team combines industry‑grade forecasting, hands‑on supplier diligence, and program implementation experience to turn market insight into executable advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Modular Steering Column Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Recycled Rare Earths to Surge at 12.7% CAGR from USD 550.6M in 2025 to USD 1.27B by 2032 — NdFeB Magnets Lead with USD 384.9M
By pmarketresearch, 2026-07-06
Recycled Rare Earth Market 2026: Strategic Imperatives for Corporate Decision‑Makers
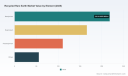
As global supply chains and technology roadmaps pivot toward sustainability and resilience, recycled rare earths have moved from niche sustainability projects to core strategic assets for manufacturers, refiners, and governments. PW Consulting’s latest market study—anchored on 2025 as the base year with a historical review from 2020–2025 and forecasts through 2032—frames recycled rare earths as a rapidly scaling market that will materially influence sourcing, investment, and policy choices in 2026. The market reached roughly USD 550 million in 2025 and, with a compound annual growth rate (CAGR) of 12.7% in our base-case projection, is expected to exceed USD 1.2 billion by 2032. This trajectory creates both opportunity and urgency for corporate strategy teams.
Recycled Rare Earth Market
Why 2026 Is a Pivotal Year
Several convergent forces elevate recycled rare earths to board-level consideration in 2026. First, regulatory and trade dynamics have accelerated supply‑chain realignment: export controls and policy shifts are prompting governments and OEMs to secure non-primary sources of neodymium, dysprosium and related elements. Second, a growing evidence base shows recycled magnet feedstock can offer substantial cost advantages versus primary mining routes—an important commercial lever as manufacturers face margin pressure and decarbonization targets. Third, a wave of capacity expansions and vertically integrated initiatives—from hydrometallurgical hubs to short‑loop magnet-to-magnet processors—is reshaping the competitive map.
Recycled Rare Earth Market
What PW Consulting’s Report Delivers
Our study is designed as an operational playbook for 2026 decisions. Highlights include:
Recycled Rare Earth Market
- Market sizing and scenario forecasts (2026–2032) under alternative policy and demand paths, showing a robust mid‑case growth trajectory at a 12.7% CAGR and downside/upside sensitivities tied to regulatory access and feedstock availability.
- Commercial readiness assessment of recovery and refining technologies—hydrometallurgical routes, hydrogen processing for magnet reconditioning, and short‑loop magnet-to-magnet techniques—mapped to CAPEX intensity, time‑to‑commercial, and impurity tolerance profiles.
- Supply‑chain risk matrices that combine geopolitical exposure, feedstock quality variability, and logistics constraints to produce prioritized mitigation options for OEMs and converters.
- Unit‑economics templates and a price‑scenario engine that translate TREO cost inputs into plant-level margin outcomes—enabling finance teams to stress-test investments and off‑take arrangements.
- A practical M&A and partnership playbook with diligence checklists, technology validation criteria, and contractual safeguards tailored to recycled REE operations.
- Regulatory and incentives tracker that assesses policy levers across major markets and their implications for project economics and procurement strategies.
To preserve competitive value for subscribers, the report omits public disclosure of the granular geographic or application splits and proprietary company-level recovery curves; those are included in the full report and data annex.
Competitive Landscape: Who’s Moving First—and How
The industry is maturing from dispersed pilots into a concentrated set of industrial actors and vertically integrated projects. Current market concentration reflects a moderate level of aggregation—top three firms control a meaningful share of capacity and brand influence, while a broader set of specialized recyclers and technology providers account for expanding processing capability.
- Cyclic Materials (Toronto): Operating North America’s first facility commercializing Mixed Rare Earth Oxide (MREO) from end‑of‑life magnets, Cyclic’s Mag‑Cycle and REEPure hydrometallurgical suite position the company as a hub‑centric processor. Its announced campus expansion in the U.S. signals a scale-up strategy focused on integrated spoke‑and‑hub networks designed to secure feedstock and downstream partnerships.
- MP Materials Corp. (Mountain Pass): As an integrated rare earth producer, MP is pivoting to commercial-scale magnet recycling with closed‑loop ambitions. High-profile offtake commitments and sustainability partnerships underline a model combining primary and recycled feedstocks to serve domestic magnet casters.
- American Resources Corporation (Electrified Materials) : Expansion of pre‑processing at domestic facilities exemplifies the move toward near‑source sorting, demagnetization and pre‑concentration—capabilities that materially affect logistics and yield for downstream refiners.
- HyProMag / Mkango Resources and University of Birmingham partnerships : Short‑loop hydrogen processing and magnet‑to‑magnet recycling offer rapid turnaround for remanufactured magnetic products, reducing reliance on deep chemical refining for certain magnet grades.
- Established recyclers and technology specialists such as Umicore, Geomega, Hitachi Metals, Accurec, REEcycle and Carester: These players bring diverse approaches—ranging from industrial-scale metal recovery to specialized separation and remanufacture—creating an ecosystem where strategic partnerships are as important as outright M&A.
Recent 2025–2026 developments—capacity announcements, hub launches, and commercial offtake commitments—underline a market transitioning to industrial scale. These moves are not merely incremental; they indicate strategic positioning to capture feedstock economics and to lock in OEM relationships as supply chains reconfigure.
Policy, Cost and Supply: Practical Implications for Strategy
Three dynamics will dominate corporate boardroom conversations in 2026:
- Policy-driven re‑routing of supply chains. Export controls and trade measures implemented in recent years are heightening the value of domestically controlled or allied recycling capacity. Companies should model scenarios for restricted access to primary material and quantify the role recycled streams play in hedging supply interruptions.
- Cost arbitrage between recycled and primary TREO. Recycled magnet routes can present materially lower TREO production costs under many feedstock quality assumptions. Our report includes a modular cost model that allows procurement teams to test procurement strategies and to quantify how incremental recycled content improves gross margins across product lines.
- Siting, logistics and feedstock aggregation. The economics of recycling scale with consistent feedstock throughput and pre‑processing quality. Expect a premium on assets and partnerships that can secure municipal and industrial end‑of‑life streams, and on logistics nodes that reduce contamination and handling losses.
Actionable Recommendations for 2026 Decision Timelines
For C‑suite and corporate strategy teams, PW Consulting recommends a prioritized set of actions for 2026:
- Run a rapid supply‑security assessment: quantify how much recycled content is required to meet 2026–2028 product roadmaps under stress‑test scenarios (export controls, tariffs, demand spikes).
- Develop near‑term offtake and feedstock aggregation pilots: lock bilateral supply agreements with electronics recyclers and motors remanufacturers, with staged options to scale into longer‑term off‑takers.
- Consider minority equity or strategic JV stakes in regional processors to secure preferential access and technology transfer—especially where short‑loop magnet refurbishment reduces processing complexity.
- Align procurement and product design: embed design‑for‑disassembly standards that increase recovery yields and lower recycling costs, and update procurement contracts to reward recycled content.
- Update capital allocation frameworks to include recycling projects: assign higher strategic value to lower‑CO2, lower‑risk feedstock projects even when payback profiles differ from primary mining investments.
- Engage proactively with regulators: shape incentive schemes and tariffs and influence standards for recycled REE content and testing protocols.
What the Full Report Contains (Subscriber‑Only)
PW Consulting’s full report expands on the themes above with exclusive content that includes: plant‑level cost build‑ups; proprietary recovery yield curves by technology; company‑specific capability matrices; commercial case studies of closed‑loop supply agreements; and an interactive scenario dashboard that lets users model price and policy shocks. We intentionally withhold proprietary regional and application splits, and detailed company revenue breakdowns from this summary to preserve the actionable value for subscribing organizations.
Final Considerations
2026 will be the year when recycled rare earths stop being a sustainability talking point and become a strategic supply‑chain instrument. Firms that move early to secure feedstock, validate processing partners, and embed recycled content into product roadmaps will reap downstream benefits—price resilience, lower Scope 3 exposure, and access to premium procurement pools. Conversely, organizations that defer may face higher sourcing costs and constrained flexibility as policy and market forces accelerate.
PW Consulting stands ready to support boards, strategy teams, and investment committees with tailored workshops, scenario modeling, and due‑diligence support packages built on the dataset and frameworks in our Recycled Rare Earth Market report. For access to the full analysis, datasets, and interactive tools, please consult PW Consulting’s market research portal or contact our industry team directly.
For detailed analysis of this topic, please visit the official page: Recycled Rare Earth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electrode Boiler Steam Humidifier Market Poised to Hit USD 325.25 Million by 2032, Backed by 5.85% CAGR (2026–2032)
By pmarketresearch, 2026-07-06
Electrode Boiler Steam Humidifier Market: Essential Strategic Intelligence for 2026 Decision‑Making
PW Consulting today releases an executive overview of our forthcoming market research on the Electrode Boiler Steam Humidifier Market — an operationally focused, strategy‑grade briefing built to guide boardrooms, procurement teams, and engineering leaders as they set priorities for 2026. The global market for electrode boiler steam humidifiers is emerging from a period of steady expansion: our base‑year analysis (2025) identifies a market size of USD 218.45 Million, and our forecast through 2032 points to continued growth, reaching USD 325.25 Million by 2032 at a compound annual growth rate (CAGR) of 5.85% across the 2026–2032 projection horizon.
Electrode Boiler Steam Humidifier Market
Why 2026 Is a Pivotal Year for Buyers and OEMs
Three converging forces make next year especially consequential. First, building decarbonization and electrification commitments are shifting demand toward electric humidification solutions that align with low‑carbon targets. Electrode boiler systems — which produce hygienic steam from potable water with minimal treatment — are squarely in that policy and procurement sweet spot.
Electrode Boiler Steam Humidifier Market
Second, product innovation is accelerating. Leading suppliers are refreshing controls, enhancing user experience, and adding field‑friendly features for rooftop and outdoor installation. These incremental innovations materially affect total cost of ownership (TCO), ease of integration, and lifecycle maintenance costs — variables that procurement teams must model explicitly in 2026 buying cycles.
Electrode Boiler Steam Humidifier Market
Third, supply‑side cost dynamics and material availability are beginning to factor into sourcing strategy. Stainless steel remains the primary material for cylinders and enclosures; market price movements and regional production trends are a non‑trivial driver of OEM margin pressure and lead times. Procurement and engineering teams that integrate supply‑chain scenarios into technical specifications will have a competitive edge.
What Our Report Delivers: Practical, Executable Intelligence
- Actionable market sizing and validated growth drivers: clear line‑of‑sight from historical performance (2020–2025) into the forecast period (2026–2032), including scenario modelling for energy policy and infrastructure investment shocks.
- Decision frameworks for specification and procurement: an OEM‑agnostic checklist for performance, hygiene, controls, and maintainability that supports RFx drafting and source evaluation without requiring costly engineering trials.
- TCO and payback templates: plug‑and‑play models to compare electrode boiler humidifiers against competing technologies, calibrated for energy mix, water costs, maintenance schedules, and replacement intervals.
- Vendor due‑diligence tools: scorecards and failure‑mode checklists to prioritize suppliers based on reliability, aftermarket support, ease of integration, and documented field performance.
- Integration playbooks for facilities and data centers: step‑by‑step guidance on controls integration, remote diagnostics, and commissioning best practices to reduce downtime risk during retrofit projects.
- Regulatory and hygiene compliance guidance: distilled requirements and conformity checkpoints for commercial and healthcare environments where hygienic steam production is mandatory.
Competitive Landscape: Who Matters and Why
The supplier set combines longstanding HVAC incumbents and specialized humidification OEMs. Our analysis emphasizes capabilities that matter to buyers in 2026: hygienic steam certification, control sophistication, outdoor/rated enclosures, and service network depth.
- Condair Group AG (Switzerland) — Condair’s EL series is positioned around hygienic steam production and extended cylinder life through advanced conductivity management. Recent product documentation and a 2026 commercial catalog roll‑out underline their focus on precision controls, energy analysis tools, and IP55‑rated outdoor models suitable for rooftop mounting. For buyers seeking modularity and field serviceability, Condair’s packaging is a strong contender.
- DriSteem (United States) — Historically strong in commercial and industrial segments, DriSteem refreshed its XT Series in 2025 to improve reliability and user experience. Their portfolio emphasizes ruggedness and simplified maintenance, making them well suited to high‑duty cycles in institutional applications.
- CAREL (Italy) — CAREL’s immersed electrode lines, including humiSteam and compactSteam, emphasize precision control and potable‑water operation. Their product architecture is attractive to projects where tight humidity control and compact footprints are essential.
- steamOvap technologies inc. (Montréal) — Canadian engineering focus yields feature sets targeting easy maintenance and compatibility with a range of water qualities. Their IER offerings are optimized for HVAC integrations in commercial and light industrial installations.
- Thermolec (Canada) — Thermolec’s AcuSteam series addresses the commercial‑grade segment with a focus on robust electric element designs for straightforward steam dispersion.
- Armstrong International (United States) — With industrial pedigree, Armstrong provides electrodes for conditioned steam applications and emphasizes system integration within larger steam networks.
- Honeywell (Resideo) (United States) — Honeywell’s HM750 targets whole‑home and light commercial humidification, featuring compact design, smart controls, and self‑diagnostics, appealing to channel partners and OEM integrators.
Overall, the market remains service‑competitive: a set of established players owns meaningful share, yet differentiation is primarily driven by controls, field reliability, and aftermarket support rather than by dramatic technology differentials.
Recent Developments and Their Strategic Implications
- Product platform refreshes (e.g., DriSteem’s 2025 redesign) reduce lifecycle maintenance costs and change the competitive calculus for retrofit projects by shortening commissioning windows.
- Condair’s 2026 catalog and documented MES2 submittal updates signal a trend toward richer control features and energy‑analysis integration — a trend that will pressure legacy installed bases to upgrade or add remote monitoring to remain competitive on service contracts.
- Raw material cost and availability remain core supplier risk variables. Engineering teams that standardize interfaces and tolerate supplier substitution will mitigate single‑vendor exposure and expedite procurement cycles.
Supply‑Chain and Cost Dynamics: Practical Considerations
Stainless steel remains central to cylinder and enclosure manufacturing; industry price and production trends should therefore be factored into both supplier negotiations and capital budgeting. Regional variations — driven by tariffs, logistics, and capacity expansion in Asia — will continue to influence lead times and OEM margin structures. For 2026 sourcing plans, PW Consulting recommends instituting dual‑track procurement strategies: a near‑term sourcing pool for fast‑track projects and a strategic panel for longer‑horizon specifications that require performance warranties and extended service agreements.
How to Use This Report in 90 Days
- Week 1–2: Use the vendor scorecards and the RFx checklist to reduce a longlist to a shortlist of 3–4 suppliers that meet hygiene, controls, and service criteria.
- Week 3–4: Run the TCO templates against the shortlisted proposals, adjusting energy price and water consumption assumptions to your facility profile.
- Month 2: Pilot one candidate in a controlled environment (e.g., a single AHU or data‑hall corridor) using the commissioning playbook and remote diagnostics templates.
- Month 3: Finalize procurement terms with integrated spare parts and SLA commitments; align installation schedules to minimize HVAC downtime during seasonal transition windows.
Methodology and Why Our Findings Are Reliable
PW Consulting’s report combines quantitative market sizing (historical 2020–2025; base year 2025) with supplier primary interviews, vendor catalog and submittal validation, and technical field reviews. Forecasts are stress‑tested across policy, energy price, and raw‑material scenarios. Importantly for procurement teams, our models are delivered with sensitivity tables and an editable TCO workbook so decision makers can adapt assumptions to their local energy mixes and maintenance economics.
What We Intentionally Omit Here — And Why
This release is designed as a strategic “trailer.” To preserve the value of the full research product and to guide stakeholders into an evidence‑rich procurement path, we do not publish detailed regional or application split tables or the granular segmentation revenue figures in this announcement. The full report includes that segmentation — regionally and by application and capacity — together with the supplier market‑share analysis, product‑level performance matrices, and downloadable procurement templates. If your 2026 plan requires the granular breakouts or the vendor evaluation workbook, the full report will deliver them.
Next Steps
For procurement directors, facility managers, and OEM strategy teams preparing for 2026 procurements, PW Consulting’s Electrode Boiler Steam Humidifier Market Report is designed to accelerate decision cycles and de‑risk specifications. To obtain the full report, supporting data files, and the editable TCO workbook, visit PW Consulting’s market reports portal or contact our industry desk to schedule a briefing and walk‑through with one of our senior analysts.
In an electrifying era for building services, decisions made in 2026 about humidification technology and supplier strategy will echo through operating budgets and decarbonization plans for years. This report equips leaders with the frameworks and data they need to make those decisions confidently — and to act quickly when opportunity windows open.
For detailed analysis of this topic, please visit the official page: Electrode Boiler Steam Humidifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metaverse in Manufacturing Market Set to Surge at 28.5% CAGR Through 2032
By pmarketresearch, 2026-07-06
Metaverse in Manufacturing Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive summary
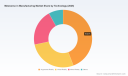
PW Consulting’s new Metaverse in Manufacturing Market report (base year 2025, forecast period 2026–2032) quantifies a fast-maturing industry that is shifting from experimentation to production-scale deployment. Our top‑line modelling places the global market at approximately USD 12,500 Million in 2025 and growing at a compound annual growth rate (CAGR) of 28.5% through 2032, reaching an estimated USD 72,315.58 Million by 2032. This trajectory reflects accelerating adoption of digital twins, immersive training, collaborative engineering environments, and GPU‑driven simulation across discrete and process manufacturing.
Metaverse In Manufacturing Market
This release follows a “trailer” principle: we surface the strategic conclusions and practical implications that matter to 2026 decision-makers while intentionally withholding the granular segment-by-segment tables and select proprietary indices available in the full report. Use the insights below to validate executive priorities and to shape investment conversations — and visit the full report page to access the detailed tables, regional and application splits, vendor scorecards and financial models that informed our guidance.
Metaverse In Manufacturing Market
What the full report delivers (practical capabilities)
- Robust market sizing and forecasting methodology (historical 2020–2025, base 2025, forecast 2026–2032), including sensitivity scenarios tied to compute availability and standards adoption.
- Actionable use‑case playbooks: step‑by‑step templates for Digital Twin Simulation, Virtual Training & Operations, Collaborative Product Development, and Remote Maintenance — each with KPI frameworks and cost/benefit mapping.
- Vendor assessment framework and procurement checklist: independent scoring across technical interoperability, cloud/edge readiness, ecosystem partnerships, and enterprise supportability.
- Implementation roadmaps for pilots to scale (0→1→N), with milestone templates, organizational change guidance, and vendor contracting considerations tailored to CAPEX vs OPEX models.
- Financial impact models and executive dashboards: multi-year ROI templates that link metaverse initiatives to productivity, lead-time reduction, quality improvement, and maintenance cost avoidance.
- Case studies and validated reference deployments from industry leaders and early-adopter manufacturers, with concrete lessons for transfer to mid‑market firms.
Macro dynamics shaping 2026 decisions
Three structural forces are converging to make 2026 a pivotal year for industrial metaverse investments:
Metaverse In Manufacturing Market
- Hardware and simulation capability: real‑time physics and photorealistic rendering — enabled by high‑performance GPUs and platforms such as NVIDIA Omniverse — have removed a key technical barrier to realistic digital twins at factory scale. This compute layer shifts projects from proof‑of‑concepts to mission‑critical workflows.
- Standards and regulatory clarity: convergence around standards (including workstreams under ISO and IEC, and IEEE initiatives) is improving interoperability and procurement confidence for IT/OT leaders. Compliance with emerging guidance for multimedia and twin definitions materially de‑risks integrations.
- Ecosystem consolidation: a mix of large industrial software providers, real‑time 3D engine vendors, and systems integrators is forming multi‑party stacks. Strategic partnerships — rather than single‑vendor dominance — are the dominant route to scale in 2026.
Taken together, these dynamics justify accelerated pilot funding for manufacturing firms that want to secure first‑mover advantages in productivity and sustainability metrics. The market’s high CAGR both signals upside for strategic investors and underscores the need for disciplined vendor and standards governance to avoid rework and stranded assets.
Competitive landscape — who matters in 2026
The industrial metaverse value chain is populated by a small set of platform leaders and a broad field of specialist integrators. Market concentration metrics indicate a moderately concentrated environment, with a handful of major players accounting for a meaningful share of market revenues while a vigorous long tail pursues niche solutions.
- Siemens AG (Munich, Germany) — Strengths: deep PLM and shop‑floor integration via Xcelerator, coupled with a deliberate pathway to Omniverse‑enabled Digital Twin Composer. Strategic posture in 2026: industrial‑grade, enterprise‑scale deployments tied to factory planning and adaptive manufacturing. Implication: Siemens is the partner of choice where tight PLM‑to‑production integration matters most.
- NVIDIA Corporation (Santa Clara, USA) — Strengths: Omniverse as the computational substrate for photoreal, multi‑user digital twins and real‑time physics. Recent 2026 partnership activity demonstrates NVIDIA’s role as an enabler rather than a direct systems integrator. Implication: manufacturers should treat NVIDIA as a foundational infrastructure partner and build vendor neutrality into procurement specs.
- Dassault Systèmes (France) — Strengths: 3DEXPERIENCE’s virtual twin and immersive collaboration capabilities for complex engineering lifecycles. Implication: strong fit where design‑centric digital continuity is required across global engineering teams.
- PTC Inc. (USA) — Strengths: Vuforia and digital thread assets for AR/MR and field operations. Implication: highly relevant for companies prioritizing frontline worker augmentation and rapid serviceability improvements.
- Microsoft Corporation (USA) — Strengths: Mesh and HoloLens for collaborative mixed reality experiences, with deep cloud and enterprise platform integrations. Implication: attractive where integration with enterprise identity, security, and Azure cloud services is a procurement priority.
- Unity Technologies (USA) — Strengths: Unity Industry for real‑time 3D and simulation fidelity optimized for manufacturing scenarios. Implication: preferred when bespoke interactive experiences and simulation extensibility are required.
- ABB Ltd (Switzerland) — Strengths: robotics and automation expertise blended with digital twin capabilities for operations and predictive maintenance. Implication: a natural ally for robotics‑centric factories seeking closed‑loop digital/physical workflows.
Recent industry moves reinforce ecosystem dynamics: NVIDIA’s March 2026 partnership wave with Siemens, Dassault and PTC accelerates platform integration; Siemens’ announced Digital Twin Composer readies enterprise marketplaces for mid‑2026 shipments; and industry forums such as ARENA2036 are translating laboratory learning into reproducible factory transfers. These developments mean that by the second half of 2026, procurement windows for platform and compute commitments will become firmer.
Practical strategic guidance for 2026 decision-makers
Based on cross‑industry interviews, financial modelling and technical assessments in our report, PW Consulting recommends the following priorities for 2026:
- Prioritize value-driven pilots — Select 2–3 use cases from operations, training, or product engineering that promise measurable outcomes within 9–15 months. Use pilots to validate data flows, latency constraints, and interoperability with PLM/ERP systems.
- Design for interoperability — Specify standards compliance and open data contracts up front. Require vendors to demonstrate alignment with emerging ISO/IEC/IEEE metaverse standards in RFPs to reduce lock‑in risk.
- Secure compute capacity strategically — GPUs and edge‑to‑cloud orchestration are gating factors. Structure procurement to allow phased capacity expansion and explore shared compute consortium models if capital is constrained.
- Adopt a platform + integrator model — Separate platform licensing (simulation/engine/infrastructure) from systems integration and domain consulting. This reduces vendor coupling and preserves flexibility for future innovation.
- Embed governance and cyber risk controls — Treat metaverse environments as extensions of OT estates. Define identity, asset ownership, and incident response playbooks before scaling to production.
- Invest in workforce transition — Combine technical upskilling for systems engineers with change programs for production supervisors and frontline maintenance teams to accelerate adoption and capture benefits.
Implementation playbook — from pilot to scale
Our stepwise blueprint for 2026 starts with “minimum viable digital twin” pilots and progresses to enterprise rollouts. Key checkpoints:
- Define business KPIs and acceptance tests (throughput, mean time to repair, training transfer metrics).
- Map data sources and latency budgets; pilot with a single production line or asset family.
- Choose a reference platform (engine + physics layer + interoperability stack) and negotiate clear IP and data rights.
- Execute a 3‑phase scaling plan: stabilize → standardize → industrialize; each phase links to budget gates and architecture reviews.
- Measure and communicate benefits centrally to maintain executive sponsorship and to fund scale‑up investments.
Why 2026 is a decision inflection point
The combination of rapid market growth, maturing platform partnerships, and clearer standards makes 2026 a year when strategic commitments will produce wide separations in operational performance. The market’s projected trajectory — a near‑quadrupling from 2025 to the 2032 horizon in our central scenario — favors organizations that align technology choices with business outcomes and that secure platform interoperability early.
Next steps — where to find the full analysis
This preview highlights the strategic framing and operational playbooks contained in PW Consulting’s full Metaverse in Manufacturing Market report. If you are preparing capital and strategic plans for 2026, the full report provides the withheld granular analytics: regional and application splits, vendor scorecards, CR‑based concentration analyses, and the financial models required for board‑level approvals.
Contact PW Consulting or visit our report page to download the complete dataset and to schedule a bespoke briefing with our lead analysts. For executive teams, we offer tailored workshops that map the report’s findings directly onto your factory footprints, supplier relationships, and transformation roadmaps.
— PW Consulting, Advanced Industries Practice & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Metaverse In Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com