

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Special Electronic Chemicals for Photoresist Market Set to Expand at 5.51% CAGR Through 2032

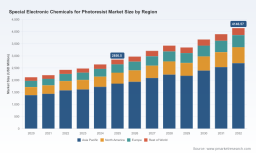
Special Electronic Chemicals for Photoresist Market: Strategic Imperatives for 2026 — PW Consulting Special Report Preview
Executive snapshot
PW Consulting’s Special Report on Special Electronic Chemicals for Photoresist provides a focused, strategy-first briefing for senior executives preparing capital, sourcing and product roadmaps in 2026. The research synthesizes historical performance (2020–2025), a detailed seven-year forecast horizon (2026–2032), and practitioner-grade playbooks that link chemistry, fab economics and regulatory risk into executable options. The headline market trajectory — underpinned by a mid-single-digit compound annual growth rate (CAGR) — confirms steady expansion but masks important inflection points that will determine winners in the next planning cycle.
Special Electronic Chemicals For Photoresist Market
Market trajectory and headline economics
The market for specialty electronic chemicals used in photoresist and photolithography processes has shown resilient growth through the early 2020s and continues to expand into the decade. Our model, built on supplier capacity data, demand-side adoption curves for advanced nodes and displays, and raw-material flows, estimates the global market size increased materially between 2020 and 2025 and is projected to accelerate through 2032. The compounded annual growth rate across the forecast window is 5.51%, and the absolute expansion should be evaluated not as uniform growth but as a sequence of demand pulses driven by fabs ramping EUV and next-generation patterning programs, display investment cycles, and the ongoing modernization of legacy fabs.
Special Electronic Chemicals For Photoresist Market
Why 2026 is an inflection year
- Capacity timing: Several leading producers have announced capacity investments and greenfield plans whose first-volume effects begin to materialize in 2026–2027. This changes supply dynamics in ways that will affect contract leverage for buyers and margin trajectories for suppliers.
- Technology adoption: Customer transitions to EUV-compatible chemistries and novel resist architectures create differentiated demand pockets. Suppliers that combine material innovation with scalable manufacturing will capture premium growth.
- Regulatory pressure: Emerging restrictions and reporting requirements tied to PFAS and related chemistries introduce compliance costs and sourcing constraints that must be baked into 2026 procurement strategies.
Key growth engines and demand vectors
Three structural drivers underpin the mid-single-digit CAGR and the shape of the horizon curve. First, the ongoing production increases for advanced logic and foundry capacity elevate demand for high-purity resins, photoacid generators and specialty solvents engineered to meet sub-10 nm impurity thresholds. Second, display technologies and high-resolution patterning for advanced packaging create differentiated demand for solvent and additive chemistries. Third, PCB and legacy-node manufacturing remain meaningful baseloads that absorb differentiated film and dry-film resist formulations.
Special Electronic Chemicals For Photoresist Market
Supply chain and raw-material dynamics — what matters for procurement
Volume and quality of upstream inputs are decisive. Industry aggregates show multi-million‑liter scale consumption of high-purity solvents and multi‑hundred‑thousand‑kilogram scale polymer resin usage annually, with polymers representing a material share of the raw-material volume base. For advanced nodes, solvent impurity thresholds routinely fall below 1 ppm, making supplier qualification and analytics capability strategic necessities rather than tactical concerns. Buyers must therefore pivot from price-only RFQs to capability- and compliance-based sourcing: traceable supply chains, validated ultra-high-purity lots, and contingency plans for solvent and monomer supply interruptions.
Regulatory and sustainability headwinds
Regulatory developments are no longer peripheral. Ongoing assessments under TSCA and state-level PFAS frameworks are introducing potential substance-level restrictions and reporting obligations that will cascade through purchasing, storage, waste management and product design. Some photoacid generators and fluorinated additives are explicitly in regulatory focus; suppliers and users should assume a phased timeline of disclosure, restriction and substitution pressure through 2032. Companies that proactively invest in non-fluorinated alternatives and maintain robust compliance analytics will avoid expensive redesigns and permit delays.
Competitive landscape — who sets the tone
The market structure remains consolidated at the top: a small group of global leaders controls a majority of advanced photoresist capacity, while a broader field of specialized and regional suppliers serves niches and legacy segments. Market concentration metrics indicate that the top three firms capture a clear plurality of advanced-product supply, and the top five account for an even larger share — underscoring the strategic premium of partnerships with tier‑one suppliers.
- Tokyo Ohka Kogyo (TOK): A technology frontrunner for advanced photoresists across EUV and ArF families. Recent capital allocations and land acquisitions signal a multi-year capacity build aligned to its tok Vision 2030. For firms negotiating long-term supply, TOK’s capacity trajectory is a leading indicator of availability for EUV-grade resists.
- JSR Corporation: Deep expertise in next-generation resist chemistries, including metal-oxide and other EUV-compatible formulations. The joint‑venture path into Taiwan manufacturing indicates a strategy of proximity to high-growth foundry clusters and faster qualification cycles with Asian customers.
- Shin-Etsu Chemical, FUJIFILM, DuPont and Merck (EMD): These large, diversified suppliers combine chemistry IP with global production footprints. DuPont’s recent expansions in Japan illustrate the industry’s approach to geographically distributed capacity to mitigate supply risk for critical lithography inputs.
- Regional innovators and niche specialists: Firms from Korea, Taiwan and Europe continue to supply specialized resists, spin-on hardmasks and R&D-intense materials, providing alternatives for customers prioritizing flexibility or unique chemistries.
Recent strategic moves — signal analysis
- Capacity expansions and new plant sites demonstrate that the supply base expects continued demand for advanced chemistries. Those commitments will loosen near-term tightness for certain products but also intensify competition for higher-margin, differentiated formulations.
- Localized manufacturing partnerships and JVs signal a shift toward proximity sourcing. For global OEMs and foundries, this reduces qualification time and logistical complexity, but it raises the bar for suppliers seeking to maintain a single global standard across facilities.
- Manufacturers are also incorporating sustainability and regulatory resilience into site planning and product design — a trend we expect to accelerate as PFAS-related regulatory action unfolds.
Report deliverables — what’s inside (practical, not theoretical)
PW Consulting’s special report translates the above into actionable instruments for 2026 decision cycles. Core deliverables include:
- Forward-looking global demand model (2026–2032) with scenario outputs tied to foundry ramps, display cycles and legacy-node attrition.
- Supplier scorecards benchmarking capacity, technology fit (EUV/ArF/KrF), quality systems, geographic exposure and regulatory posture.
- Supply-risk heatmaps and procurement playbooks: dual‑sourcing templates, qualification timelines, and inventory optimization for high‑purity solvents and polymer resins.
- M&A and partnership opportunity matrix highlighting adjacencies in specialty solvents, PAGs and additives where consolidation or JV structures unlock scale or IP synergies.
- Regulatory impact framework that maps PFAS/TSCA trajectories to product portfolios and compliance cost estimates, with substitution pathways for affected chemistries.
- Operational checklists for fab integration teams covering lot traceability, impurity analytics and change-control protocols essential to qualifying new supplier lots for sub‑10 nm processes.
How to use this intelligence in 2026 — tactical recommendations
- Rebase procurement KPIs: move from price and lead time to a multi-dimensional scorecard that includes impurity analytics capability, regulatory readiness and localization options.
- Prioritize early engagement with tier‑one suppliers who are expanding capacity or establishing local sites in fabrication clusters; qualification lead times materially affect time-to-production.
- Invest in analytics: in-house or partner labs capable of sub-ppm impurity detection reduce qualification friction and provide leverage in commercial negotiations.
- Stress-test your portfolio against PFAS regulatory scenarios with staged substitution plans and alternative-formulation pilots to avoid late-stage disruptions.
- Consider strategic inventory buffers for solvent classes and select polymer resins while ramp plans for supplier capacity take effect — but balance this against working-capital impacts using PW’s optimization templates.
Why this “preview” matters — and what we deliberately withhold
This release is structured as a strategic preview: it surfaces the most consequential insights and executable options that will shape boardroom decisions in 2026 while preserving the granular segmentation tables, supplier-level volume forecasts and proprietary pricing curves that are contained in the full report. Those core sub‑segment datasets are the high-value outputs intended for subscribers and clients who require transaction‑grade intelligence for tendering, M&A diligence or capital allocation.
Next steps and how to engage
Executives seeking to convert the market trajectory into defensible 2026 plans should request a consultative briefing with PW Consulting’s photoresist chemicals practice. Our briefings pair the full dataset with scenario simulations tailored to your supply base, CAPEX calendar and regulatory exposure, enabling a concrete, time-bound action plan for procurement, engineering and corporate development teams.
For detailed analysis of this topic, please visit the official page: Special Electronic Chemicals For Photoresist Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com