

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Desktop Cloud Terminal Market Forecast to Grow at a 4.98% CAGR Through 2032

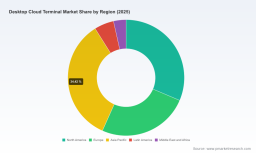
Desktop Cloud Terminal Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
As enterprises across industries accelerate desktop virtualization and cloud-first workplace strategies, the desktop cloud terminal market emerges as a strategic fulcrum for cost optimization, security posture, and operational resilience. PW Consulting’s newest market research — built on a historical lens (2020–2025) and a forward-looking forecast (2026–2032) — presents the directional intelligence executives need to make defensible decisions in 2026. The market was valued at approximately USD 1,690.8 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of c. 4.98% through our forecast horizon, underscoring steady expansion driven by hybrid work models, DaaS adoption, and regulatory-led security investments.
Desktop Cloud Terminal Market
Why this brief matters to 2026 decision-makers
-
Timing: Many large enterprises and public-sector institutions plan refresh cycles and cloud migration milestones in 2026. Decisions taken this year will lock in platform choices, supplier commitments, and security architectures for multiple years.
Desktop Cloud Terminal Market -
Cost-structure optimization: With rising data center energy costs (notably a reported ~15% uplift in 2025 driven by AI workloads), total cost of ownership (TCO) calculus for hosted virtual desktop environments has shifted materially. The report models these dynamics and provides scenario-based TCO comparisons for cloud terminals versus legacy PCs and thin-client on-prem deployments.
Desktop Cloud Terminal Market -
Risk and compliance: New regulatory touchpoints — from the EU Data Governance Act to updated zero-trust expectations in the US federal sphere — are reshaping procurement criteria. Our analysis translates these rules into practical vendor and architecture requirements for 2026 procurement.
Top strategic themes highlighted
-
Modernizing the endpoint without recreating the desktop: Organizations balancing user experience and security will increasingly prioritize cloud terminals that support multi-protocol VDI, multi-monitor workflows, and local peripheral handling while minimizing on-device data sprawl.
-
Security converges with identity and network posture: The move to zero-trust frameworks elevates endpoint attestation, firmware integrity, and secure boot as procurement non-negotiables. The report identifies practical control sets and validation steps for enterprise buyers.
-
Supply chain and geopolitical resilience: Export controls and trade measures are compressing some hardware supply options. Our advisory highlights sourcing strategies and vendor diversification approaches to reduce disruptions for 2026 deployments.
-
Sustainability and operational cost pressure: Increased energy consumption at data centers affects the marginal cost of hosted desktops. Buyers now need to factor both energy intensity of workloads and device lifecycle emissions into buy-versus-build analyses.
-
Architectural pluralism — cloud, edge, and ARM-capable endpoints: The ecosystem is moving toward heterogeneous deployments where ARM-based cloud terminals, x86 thin clients, and zero clients coexist. We map decision criteria for mixing architectures without adding operational complexity.
Competitive landscape — what to watch in 2026
The market remains moderately concentrated; the top three players command a material share of revenue, and the top five intensify competitive dynamics through differentiated software and channel strategies. This concentration creates both stability and barriers for new entrants, while opening white-space for niche vendors specializing in security, vertical workflows, or managed DaaS integration.
-
Dell Technologies (Round Rock, Texas) continues to invest in its Wyse thin client portfolio with explicit support for mainstream cloud desktop platforms. Recent product activity signals a push to optimize multi-monitor and Cloud PC interoperability — a response to enterprises standardizing on services like Windows 365.
-
HP Inc. (Palo Alto) leverages certification and compatibility as a commercial differentiator. Certifications for major VDI stacks ease procurement friction in regulated environments and support broader Azure Virtual Desktop and Citrix adoption patterns.
-
Lenovo (Beijing / Morrisville) is refreshing thin-client offerings around modern CPUs to better host virtual desktop clients locally and support richer user experiences, targeting both enterprise and edge computing scenarios.
-
IGEL Technology (Reading, UK) is notable for its software-first endpoint approach, with recent OS releases embedding new cloud desktop protocols and zero-trust features — a blueprint for vendors that aim to monetize software and services over hardware.
-
10ZiG, Huawei, Acer and other specialists continue to hold strategic positions: 10ZiG with protocol specialization for PCoIP/Blast, Huawei with integrated offerings for domestic enterprise clouds, and Acer focused on cost-effective thin-client SKUs for managed service providers.
Recent vendor developments — from product launches to OS and certification updates — signify incremental innovation rather than disruptive shifts. For procurement teams, the practical implication is to prioritize interoperability and long-term software support commitments over isolated hardware features.
What PW Consulting’s report delivers — practical, executable intelligence
-
Actionable decision frameworks: Playbooks for operator models (in-house VDI, DaaS, hybrid managed services), migration paths, and procurement checklists that align with regulatory and security requirements.
-
Vendor evaluation toolkit: Scorecards and weighted criteria that translate product, software lifecycle, channel strength, and security posture into defensible vendor shortlists.
-
Financial models: Scenario-based TCO tools that account for device economics, data-center energy impacts, staffing, and projected licensing costs under multiple workload mixes.
-
Security and compliance blueprints: Mapped controls for zero-trust maturity stages, evidence artifacts for audits, and recommended validation tests for firmware and endpoint attestation.
-
Operational runbooks: Patch, image, and lifecycle management workflows designed to minimize user disruption during endpoint refreshes and to simplify scaled rollouts across regions.
-
Scenario planning appendices: Three strategic scenarios (Consolidation, Diversification, and Edge-first) with decision triggers and supplier playbooks that guide C-suite timing and capital allocation.
Guidance for procurement and IT leaders in 2026
-
Shift evaluation from device-centric to experience-centric metrics: Assess solutions by end-user experience (latency, peripheral support, multimedia fidelity) and the vendor’s commitment to lifecycle software updates.
-
Embed regulatory mapping into technical RFPs: Ensure RFPs require vendor attestations for data sovereignty, export-compliance evidence, and an audited supply chain transparency statement.
-
Prioritize interoperable, software-first approaches: Vendors offering robust OS/firmware update channels and cloud-agnostic clients reduce lock-in and lower long-term migration costs.
-
Build energy-aware TCO into procurement governance: Require energy-performance metrics and real-world hosting cost scenarios when assessing managed DaaS offers.
-
Adopt phased migration with clear rollback triggers: Pilot narrow cohorts, validate security baselines, then scale; maintain a rollback play to mitigate user-impact risk during larger rollouts.
Regulatory and macro risks to factor in
-
Cross-border data rules: New governance frameworks introduce constraints on how virtual desktop images and user data traverse jurisdictions.
-
Export control exposure: Restrictions on certain compute hardware can complicate procurement strategies for global programs — dual-sourcing and regional vendor partnerships are practical mitigants.
-
Rising infrastructure costs: Energy and data-center economics now materially affect marginal cost per hosted desktop; buyers must stress-test vendor pricing under higher-cost scenarios.
-
Zero-trust enforcement: As federal and sector-specific guidelines evolve, compliance will increasingly be a procurement gating item rather than a post-deployment initiative.
Why PW Consulting’s brief is your strategic shortcut
We have combined market modeling, vendor diagnostics, regulatory impact analysis, and operational playbooks into a single, practitioner-oriented deliverable. The report’s high-level market figures (including the 2025 market valuation and the forecast CAGR to 2032) provide clear directional context, while the core report contains the granular segmentation, regional breakdowns, and vendor-by-vendor revenue analysis needed for procurement committees and CIO offices.
In keeping with our “preview” approach, this article emphasizes strategic conclusions and executable guidance without reproducing the full set of segmentation tables and sensitive vendor metrics. Procurement teams, CIOs, and strategy leaders seeking the detailed appendices — regional market splits, end-user vertical sizing, and vendor revenue schedules — will find them in the full report and companion data workbook.
Next steps
-
For an executive briefing: Request a tailored 60-minute workshop where PW Consulting will map the report’s scenarios to your estate and present a prioritized migration roadmap for 2026.
-
For procurement teams: Access the full dataset and vendor scorecards to generate an RFP aligned to your security and TCO requirements.
-
For investors and partners: Contact our industry research desk for a deep dive on competitive positioning, M&A risk factors, and white-space opportunities in managed services and protocol specialization.
PW Consulting’s Desktop Cloud Terminal Market report is designed to convert market intelligence into practical action for 2026 planning cycles. We provide the strategic context you need now — and the detailed instruments you’ll use to execute next.
For detailed analysis of this topic, please visit the official page: Desktop Cloud Terminal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com