

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Modular Steering Column Market to Hit USD 3,969.5 Million by 2032

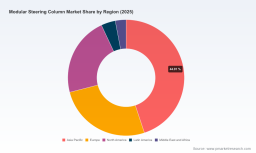
Modular Steering Column Market: Strategic Imperatives for 2026 Decision‑Making
As OEMs and tier suppliers prepare their 2026 roadmaps, the modular steering column market is transitioning from a component-centric supply space into a systems and software battleground. PW Consulting’s forthcoming Modular Steering Column Market report synthesizes seven years of historical performance with a forward-looking 2026–2032 forecast to help executives make confident, time‑sensitive choices. Our analysis combines quantitative market sizing and growth assumptions with a pragmatic, transaction‑ready playbook for procurement, product development, and M&A teams.
Modular Steering Column Market
Market snapshot: scale, trajectory, and structural cues
After steady expansion in the early 2020s, the global modular steering column market reached roughly USD 2.65 billion in our 2025 base year. Under the assumptions and demand drivers set out in this report, the market is projected to sustain a mid‑single digit compound annual growth rate (CAGR) through 2032, reaching an industry magnitude approaching USD 4.0 billion by the end of the forecast window. This trajectory is driven by a confluence of factors: accelerating vehicle electrification, rising safety and functional integration requirements, and continuing OEM preference for modular platforms that compress time‑to‑market.
Modular Steering Column Market
Two structural characteristics are central to strategic planning: first, market concentration is meaningful but not insurmountable — the top three and top five suppliers collectively account for a material share of industry revenues, signaling both defensive moats and pockets of opportunity for challengers. Second, value is migrating from mechanical fit‑and‑form to software, systems integration and safety validation — an evolution that alters supplier economics and the rationale for vertical integration.
Modular Steering Column Market
What this report delivers — practical intelligence for 2026 decisions
- Validated market sizing and forecast model (2020–2032), with scenario variants calibrated to electrification and regulation sensitivity.
- Competitive scorecards for incumbent and emerging suppliers, emphasizing product modularity, software capability, manufacturing footprint, and validation throughput.
- Regulatory and standards map (including safety and functional safety requirements) tied to compliance cost estimates and testing timelines.
- Supplier selection framework and total cost of ownership (TCO) tool that models unit cost, warranty exposure, and integration engineering effort.
- Technology roadmaps for tilt/telescopic actuation, electric adjustable columns, and electronic control modules, with milestone gating for 2026–2029 product programs.
- M&A and partnership heatmaps identifying targets by capability gaps, integration risk, and valuation multipliers.
- Raw material and commodity risk assessment focusing on lightweight alloy exposure and mitigation strategies for supply volatility.
Key strategic implications for OEMs and suppliers
- Design to modularity, procure for systems integration: OEMs should shift procurement briefs from part specifications toward validated systems interfaces. Doing so reduces integration cycles and clarifies warranty allocation between mechanical and electronic domains.
- Prioritize functional safety early: Electronic steering column control modules fall within ISO 26262 scope — early architectural choices materially affect validation cost and calendar risk. Programs that defer functional safety scoping to late development stages face outsized timeline and rework exposure.
- Balance weight reduction with manufacturability: Magnesium and aluminum alloys remain attractive for weight savings but introduce supply and processing complexity. Suppliers with proven lightweighting processes and in‑house validation deliver a lower ramp risk for high‑volume programs.
- Plan for electrified adjustment functions: Electric adjustable columns are no longer niche; they are a critical differentiator for premium packaging and advanced driver assistance integration. Suppliers offering scalable electric actuation modules accelerate OEM feature rollouts.
- Manage concentration risk through supplier diversification and nearshoring: Given the moderate level of market concentration, intelligent diversification — combined with selective nearshoring — reduces program break risk without sacrificing unit economics.
Competitive landscape — positioning and dynamics
The market features a mix of global systems houses, regional specialists, and component specialists. Strategic positioning varies from full systems integrators to focused module providers; each archetype brings different advantages for OEMs and investors.
- Nexteer Automotive (Auburn Hills, MI, USA): Offers a wide portfolio across steering columns and intermediate shafts, with modular, scalable EPS solutions. Recent product premieres emphasize high‑output column‑assist systems that enable powertrain‑agnostic integration and lower calibration burden for OEMs.
- thyssenkrupp AG (Essen, Germany): Focuses on adaptive crash behavior and modular columns tailored to upper‑segmented vehicles, combining mechanical engineering depth with regionally diversified production.
- Kongsberg Automotive (Kongsberg, Norway): Strengths lie in tailored tilt/telescope modules for off‑highway and commercial segments, backed by full in‑house development and validation capabilities.
- Merit Automotive (Spain, global): Excels at integrating security and convenience features into column modules, enabling large variant counts while simplifying vehicle wiring and assembly.
- NSK Ltd. (Tokyo, Japan): Notable for electric tilt/telescope architectures and polymer‑based impact absorption technologies conducive to lightweight, upper‑pivot implementations.
- Robert Bosch GmbH (Gerlingen, Germany): Targets trucks and buses with maintenance‑free concepts using magnesium and plastics to cut weight and assembly complexity.
- ZF Friedrichshafen AG (Friedrichshafen, Germany): Via TRW integration, provides column control modules emphasizing safety and electronic integration for mixed passenger and commercial portfolios.
- JTEKT Corporation (Osaka, Japan): Leverages broad steering system portfolios to embed modular columns within EPS and HPS strategies across vehicle segments.
- Hyundai Mobis (Seoul, South Korea): Positions modular columns within broader chassis and safety suites for global OEM sourcing.
- Mando Corporation (Seoul, South Korea): Concentrates on electronic locking and lightweight actuation systems with an eye toward reducing assembly weight and cost.
Collectively, the competitive set demonstrates that value capture increasingly flows to suppliers that can combine mechanical modularity with electronic control, validated safety functions, and scalable manufacturing footprints. The concentration metrics we model confirm that the market is consolidated enough to favor incumbents on large programs, but open enough for well‑executed entrants with distinct software or lightweighting propositions.
Regulatory and materials environment — practical risks and responses
- Safety standards: Federal and international crash safety rules demand energy‑absorbing steering column behavior and controlled displacement under impact. These constraints influence mechanical architecture and validation scope early in program definition.
- Functional safety: ISO 26262 obligations for electronic column modules require defined ASIL targets, traceability, and high‑assurance toolchains. Failure to align architecture and supplier responsibilities creates certification delays.
- Materials and supply: Lightweight alloys (magnesium and aluminum) remain a primary lever for mass savings but expose programs to commodity cycles and processing complexity. Substitution strategies and alloy sourcing agreements are now routine elements of supplier negotiations.
Transaction playbook — how to use the report in 90 days
Executives can convert our analysis into actionable plans in three steps:
- Week 1–3: Decision triage. Use our supplier scorecards and TCO sensitivity tables to classify existing suppliers into retain/grow/replace buckets. Identify single‑sourced columns with high safety or software content for immediate risk mitigation.
- Week 4–8: Partnership and procurement design. Deploy our RFP templates and integration SLAs to negotiate fixed SLAs for software, firmware updates, and validation deliverables. Include commodity pass‑through terms for magnesium/aluminum exposure.
- Week 9–12: Capability builds and M&A scans. Apply our M&A heatmap to prioritize 1–3 bolt‑on targets or tech partnerships that close capability gaps in electric actuation, electronic locking, or systems validation.
Why this matters for 2026 planning
2026 marks a pivot year for many vehicle programs that began concept or alpha phases in 2023–2024. Decisions taken now — about whether to standardize on manual adjustable vs. electric adjustable columns, how to apportion functional safety responsibility, and where to locate validated manufacturing — will determine cost and feature parity through the next vehicle cycle. Our forecast and playbook are structured to inform those tradeoffs without requiring organizations to reinvent validation processes or rebaseline program economics.
Accessing the full intelligence
This release is a strategic preview intended to demonstrate the depth of our methodologies and the immediate applicability of findings. Detailed regional and application splits, supplier revenue models, proprietary scenario outputs, and the full set of validation checklists are intentionally excluded from this summary to preserve the integrity of the underlying research product.
To obtain the complete Modular Steering Column Market report — including the granular segment tables, supplier financial proxies, and executable procurement templates — please contact PW Consulting or visit our report portal. For program teams seeking immediate support, our consultants are available for short, focused engagements to run the TCO model against your specific BOM assumptions and to workshop supplier selection with your engineering and procurement leaders.
Prepared by PW Consulting’s Advanced Mobility Practice — our team combines industry‑grade forecasting, hands‑on supplier diligence, and program implementation experience to turn market insight into executable advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Modular Steering Column Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com