

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Operating Tables Market—3.5% CAGR to USD 196.8M by 2032
By pmarketresearch, 2026-07-09
Operating Tables Market — Strategic Briefing for 2026 Decision-Makers
As hospitals and integrated health systems prioritize operating room modernization, the operating tables market has moved from a commoditized equipment purchase to a strategic asset that shapes clinical capability, workflow efficiency, and capital allocation. PW Consulting’s Operating Tables Market study (base year 2025, historical window 2020–2025, forecast 2026–2032) synthesizes market performance, regulatory inflection points, supplier dynamics, and practical tools you can use to make confident procurement, integration, and financing decisions in 2026.
Operating Tables Market
Top-line market trajectory (what the numbers are signaling)
The market expanded from approximately USD 130.0 Million in 2020 to USD 155.0 Million in 2025, reflecting steady, healthcare-driven demand for upgraded surgical infrastructure. Our forecast assumes a 3.5% compound annual growth rate across the 2026–2032 horizon, with a projected market size approaching USD 197.0 Million by 2032 under the base scenario. These macro trends reflect a convergence of capital refresh cycles, hybrid OR investments, and selective replacement of legacy tables for robotics- and imaging-compatible platforms.
Operating Tables Market
Market concentration metrics show moderate supplier concentration (CR3 ~38%, CR5 ~52%), which signals that a handful of global vendors exert meaningful influence on pricing, standards, and aftermarket depth — but there remains sufficient competitive space for regional specialists, value players, and niche innovators to capture share via focused clinical differentiation or service models.
Operating Tables Market
What the PW Consulting report delivers — practical, executable content
- Actionable 7‑year forecasts (2026–2032) with scenario runs calibrated to capital availability, reimbursement adjustments, and regulatory change.
- Procurement playbook: RFP templates, vendor scorecards, total cost of ownership (TCO) models, and CapEx prioritization matrices for hospital networks.
- Technical and clinical decision frameworks: modularity vs. specialization, imaging/radiolucency requirements, robotics compatibility, and OR footprint planning.
- Regulatory and reimbursement impact analysis: compliance gap checklists, documentation templates, and billing scenario modeling reflecting 2026 code updates and quality management expectations.
- Competitive intelligence: vendor positioning maps, strengths/weaknesses, likely moves, and supplier risk heatmaps (service coverage, spare-parts lead times, and aftermarket margins).
- Operational tools: clinical training needs assessment, service contract negotiation playbook, and timelines for phased rollouts to minimize surgical downtime.
- Executive summary and board-ready briefing decks tailored for CFOs, CMOs, and clinical engineering leaders.
Note: the report contains granular segmentation by region, product type, and clinical application to support site-level decisions. To preserve strategic value in this briefing we intentionally omit the granular splits here — full segment-level tables and model-level pricing are available in the full report.
Key market dynamics that will shape decisions in 2026
- Regulatory tightening: The implementation of an updated Quality Management System regulation (effective 2 Feb 2026) raises the bar for documentation and process validation for powered tables. Buyers must require evidence of compliant design control and validation artifacts as part of procurement.
- Reimbursement adjustments: HCPCS code updates (effective 1 Jan 2026) change the economics of certain OR billings. Institutions should refresh their procedure-level reimbursement models and align capital requests to net revenue impacts.
- Hybrid OR and imaging integration: Carbon-fiber tabletops and radiolucent designs are no longer niche: they are integral for hybrid suites. Raw-material availability and supplier capability to deliver carbon-fiber components are a source of risk and differentiation.
- Labor and skills: Advanced motorized and robotic-compatible tables increase the need for clinician and biomed training. Expect incremental O&M and training budgets post-purchase, and ensure vendor-led competency programs are contractually defined.
- CapEx prioritization: Hospitals increasingly bundle operating table upgrades into broader OR modernization capital programs. Procurement teams must balance one-off table acquisitions against integrated systems that deliver ROI via throughput gains or procedure mix shifts.
Competitive landscape — strategic implications for procurement
The current vendor field blends multinational incumbents with specialized OEMs. Procurement teams should evaluate not just headline specifications but the total delivery ecosystem: service reach, integration interfaces, future-proofing (modularity, upgradeability), and aftermarket economics.
- STERIS plc (Ireland) — Strengths: broad portfolio of general and radiolucent fluoroscopic tables, orthopedic extensions, and all-electric operation. Strategic implication: strong for hospitals prioritizing imaging workflows and comprehensive service packages; expect premium pricing for integrated X‑ray-ready platforms.
- Hill-Rom Holdings, Inc. (United States) — Strengths: TruSystem series with ISO-center motion and mobile models designed for precision positioning and robotic interplay. Strategic implication: a front-runner for sites planning robotic integrations and centers of excellence focused on minimally invasive surgery.
- Getinge AB (Sweden) — Strengths: Maquet Magnus platform emphasizing modularity and carbon-fiber tabletops for hybrid ORs. Strategic implication: compelling where hybrid imaging and interdisciplinary workflows are a strategic priority; trade-offs often involve higher integration engineering effort.
- SCHMITZ medical GmbH (Germany) — Strengths: electrically driven, robust universal tables with emphasis on precision tilt and German engineering. Strategic implication: attractive to hospitals valuing durability, ergonomics, and deterministic performance for high-utilization theatres.
- Mindray DS USA, Inc. (United States) — Strengths: ergonomic, versatile models positioned for general and bariatric procedures with competitive pricing. Strategic implication: value-oriented choice for cost-conscious systems seeking modern features without the high premium of flagship platforms.
- Mizuho OSI (United States) — Strengths: specialized systems for orthopedic and spine indications with modularity for complex positioning. Strategic implication: best-in-class for specialty surgical centers and academic hospitals with a high volume of spine/orthopedics.
Given the CR3/CR5 concentration dynamics, expect continued consolidation pressure in adjacent segments (imaging, OR integration software, and robotics). Buyers should build vendor scorecards that weight not only product specs but also pension on geographic service coverage, spare-parts exposure, and regulatory readiness.
Practical recommendations for 2026 procurement and executive leaders
- Align capital requests with an OR modernization roadmap that accounts for hybrid imaging and robotics; structure approvals to enable modular upgrades rather than full replacement where possible.
- Embed regulatory compliance requirements into vendor contracts (design history files, process validation evidence, and post-market surveillance obligations) to meet the 2026 Quality Management expectations.
- Update reimbursement models post-HCPCS changes and stress-test budgets under alternative utilization scenarios to estimate payback horizons accurately.
- Negotiate service-level agreements with explicit KPIs for uptime, response times, and parts lead-time guarantees; include training packages and credentialing support for clinical staff.
- Mitigate supply risk for carbon-fiber and other specialty components by requiring dual-sourcing options or confirmed lead-time commitments in purchase orders.
- Use pilot programs to validate integration with imaging and robotic systems before large-scale rollouts; capture real-world data on procedure time savings and positioning accuracy to support broader adoption.
- Standardize interfaces and consumables across site networks where possible to lower inventory and maintenance complexity and to improve negotiating leverage.
How PW Consulting supports your 2026 roadmap
PW Consulting offers a suite of services designed to convert the study’s insights into executable programs: tailored procurement workshops, vendor RFI/RFP management, TCO and CapEx optimization, regulatory readiness audits, and clinical-technical integration planning. For clients executing multi-site rollouts, we provide project governance templates, staging schedules to minimize OR disruption, and post-implementation performance baselines to measure success.
This briefing has showcased the strategic contours of the operating tables market while reserving granular segmentation data, model-level pricing, and the full vendor scorecards for the complete report. If your 2026 decisions require validated segment splits, model comparators, or a supplier-selection deep dive, the full PW Consulting Operating Tables Market report provides those assets along with downloadable tools and executive-ready decks.
Accessing the full report will equip your procurement, clinical engineering, and executive teams with the detailed numeric intelligence and practical templates needed to act decisively in 2026. Contact PW Consulting to request the full dossier, scorecards, and the operational toolset that accompanies this strategic analysis.
For detailed analysis of this topic, please visit the official page: Operating Tables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Gripper Market to Reach $830.62M by 2032 at 5.5% CAGR
By pmarketresearch, 2026-07-09
Electric Gripper Market — 2026 Strategic Briefing
As factories and distribution centers accelerate the shift from pneumatic and manual handling to intelligent end-of-arm tooling, the electric gripper market has evolved from a niche automation component into a strategic lever for productivity and resiliency. PW Consulting’s latest market research—anchored on a 2025 base year, historical coverage from 2020–2025 and a forward-looking forecast for 2026–2032—provides the decision-grade analysis executives need to align R&D, procurement, and M&A priorities for the coming three to five years. The market expanded materially through 2020–2025 (from under USD 450 Million to over USD 570 Million) and, at a steady 5.5% CAGR, is projected to move meaningfully toward the high hundreds of millions by 2032. For 2026 planning, this trajectory is as much an opportunity signal as it is a timing imperative.
Electric Gripper Market
Why this study matters for 2026 decisions
-
Timing of capital commitments: A predictable mid-single-digit CAGR creates a window for measured scale investments—firms that invest in adaptable electric gripper platforms now can capture share as cobot and smart-automation adoption accelerates.
Electric Gripper Market -
Portfolio prioritization: The market’s steady growth but concentrated supplier base (top-three firms hold a meaningful plurality of sales, top-five further extend concentration) means competitive advantage will come from product differentiation, system integration, and aftermarket services rather than pure price competition alone.
Electric Gripper Market -
Procurement and supply-chain strategy: Raw-material volatility and modularization trends make supplier consolidation, long-term supplier agreements, and dual-sourcing mandatory elements of any 2026 sourcing playbook.
Market trajectory — what the headline numbers imply
PW Consulting’s topline series tracks how the market rose through 2020–2025 and projects steady expansion across the 2026–2032 forecast window. The combination of rising cobot penetration, energy-efficiency regulations favoring electric systems, and persistent labor shortages is creating a predictable base of demand. That predictability enables scenario-based capital planning: conservative scenarios assume continued retrofit cycles in established factories; aggressive scenarios model faster greenfield automation in logistics and light manufacturing.
Key demand drivers and cost dynamics
-
Automation intensity and cobot adoption: Collaborative robot arms are now a standard channel for electric grippers. This has shifted buyer priorities from raw gripping force toward intelligence (force sensing, adaptive grasping), safety, and simple integration.
-
Regulatory push and safety: Standards for collaborative workplaces require force-limiting and collision detection—features that increase product complexity but also raise switching costs for buyers that prioritize compliance and worker safety.
-
Cost composition: Material and component choices matter. For industrial-grade units, raw-material costs for structural steels and high-performance polymers vary considerably across complexity tiers, and high-force or long-stroke designs materially increase bill of materials (BOM) and final price. Energy-efficiency mandates further tilt TCO in favor of electric grippers versus pneumatic alternatives.
-
Labor-market pressure: High-mix, low-volume manufacturing environments face the steepest pain from labor shortages, accelerating adoption of flexible electric grippers that can be reprogrammed for frequent changeovers.
What PW Consulting’s report delivers (practical outputs)
Beyond narrative analysis, the report is designed as an operational toolkit for teams executing 2026 strategies. Deliverables include:
-
Market-sizing and forecast model (2020–2032) with scenario toggles, sensitivity to unit prices, and adoption curves.
-
Competitive scorecards for leading suppliers, including product architecture mappings, channel footprints, and integration capability assessments.
-
Buyer segmentation framework and decision maps for procurement teams (TCO calculators, payback models, and rebound analysis to compare electric vs. pneumatic solutions).
-
Go-to-market playbooks for OEMs and system integrators, including partner selection criteria and pricing strategies for value-based selling.
-
M&A and partnership screening framework identifying strategic fit, technology gaps, and likely integration risks.
-
Operational checklists (supply-chain risk mitigations, compliance readiness, and after-sales service models) and downloadable templates for immediate use.
Competitive landscape — who matters and why
The vendor ecosystem combines global automation OEMs, cobot-focused innovators, and regionally competitive low-cost manufacturers. Market concentration is meaningful—leading firms hold a large share of the market’s value—so incumbents set standards for interoperability and safety while challengers compete on integration speed, affordability, and niche specialization.
-
Global OEMs (examples: SMC Corporation, SCHUNK, Festo): These players compete on breadth of portfolio, integration with factory automation systems, and long-standing distributor networks. For 2026, their competitive edge will rest on modular, easily programmable gripper families that simplify system-level integration and reduce total installation time.
-
Cobot-native suppliers (examples: OnRobot, Robotiq, HIWIN): These firms focus on rapid deployment, plug-and-play compatibility with major collaborative robot arms, and developer-friendly APIs. Product launches in 2025 (notably several high-payload and miniature force-sensing grippers) demonstrate a continued race to broaden the use-case envelope.
-
Regional and cost leaders (examples: China-based DH-Robotics, HITBOT, TallMan): These vendors compete on price and rapid iteration; they are most relevant in price-sensitive segments and for large-scale rollouts where basic functionality is sufficient.
Notable 2025 product activity reinforces competitive dynamics: announcements of new high-payload and miniature force-sensing products from multiple vendors indicate both product diversification and commoditization at different tiers. Strategic moves by niche and established suppliers alike suggest 2026 will be a year of increased platform competition and partnership consolidation.
Strategic implications for executives (2026 playbook)
-
Prioritize modularity: Invest in or procure gripper platforms that support software-upgradable features (force sensing, expanded I/O) to protect against obsolescence and speed deployment cycles.
-
Negotiate TCO-based contracts: Move away from unit-price procurement to performance- and uptime-linked contracts that reflect energy savings, reduced labor costs, and maintenance efficiencies.
-
Lock in supply resilience: Establish multi-tier sourcing for key mechanical components and negotiate long-term supply agreements for critical polymers and actuators to buffer raw-material cost volatility.
-
Accelerate integration capability: For OEMs and integrators, develop certified integration stacks for dominant cobot arms and provide turn-key kits that shorten installation time—this is where premium pricing is defensible.
-
Scan for M&A and partnerships: Seek bolt-on acquisitions that add force-sensing, vision-guided gripping, or advanced control IP; for system integrators, partner with regionally strong low-cost manufacturers to hedge price-sensitive opportunities.
Risk matrix — what to watch in 2026
-
Regulatory shifts increasing compliance costs (safety or energy mandates).
-
Rapid commoditization of basic electric grippers leading to margin compression in lower tiers.
-
Supply-chain disruptions for specialty materials that impact lead times for high-complexity units.
-
Integration inertia at customer sites—lack of skilled integrators can slow adoption despite strong product value.
Immediate next steps for executive teams
-
For procurement: Run the report’s TCO calculator against current contracts and target a 12–18 month renegotiation window where energy and uptime metrics form compensation levers.
-
For product leaders: Map your roadmap against the report’s capability tiers and prioritize force-sensing and software-defined features for the next product release.
-
For corporate development: Use the M&A screening matrix to shortlist targets that fill control-layer or sensing gaps (target list available in the full report).
-
For operations: Begin pilot deployments in high-mix lines where payback is shortest; capture real-world ROI data to build the internal case for scale-up during 2026.
PW Consulting’s Electric Gripper Market study is structured to be immediately actionable: it pairs a transparent, model-driven market forecast (2020–2032) with practical tools, supplier scorecards, and integration playbooks. To preserve the strategic value of granular segmentation and company-level scorecards, detailed breakouts—regional and application split tables, unit-price ladders, and company share matrices—are provided in the full deliverable available on our site. For teams preparing 2026 budgets and strategic roadmaps, the report is both a compass and a set of ready-to-use instruments for execution.
For detailed analysis of this topic, please visit the official page: Electric Gripper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Screen Protective Film Market to Reach USD 71.52B by 2032 (8.3% CAGR)
By pmarketresearch, 2026-07-09
Screen Protective Film Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As organizations plan product roadmaps, capital allocation, and go-to-market strategies for 2026, the screen protective film market presents a compelling blend of steady expansion, moderate concentration, and technology-driven differentiation. Our sector analysis at PW Consulting frames this growth in numbers you can act on: the market has expanded meaningfully over the past half decade (base year 2025) and, under our principal scenario, will continue to scale at a compound annual growth rate (CAGR) of roughly 8.3% through the 2026–2032 forecast horizon. By integrating historical performance, supplier dynamics, materials innovation, and end-market shifts, this briefing translates the headline growth trajectory into strategic imperatives for procurement, R&D, M&A, and commercial teams.
Screen Protective Film Market
Why this matters in 2026
-
Visibility into a market that is re-scaling: The category’s trajectory from the early-2020s to the 2025 base year signals both persistent consumer demand and expanding industrial use-cases — a combination that alters competitive returns and risk profiles for new entrants and incumbents alike.
Screen Protective Film Market -
Timing is strategic: With projected double-digit upticks in adjacent device penetration and rising standards for durability and optical performance, 2026 is a critical planning year for firms seeking to secure raw-material supply, lock in partnerships with tier-1 OEMs, or accelerate specialty protective-film launches.
Screen Protective Film Market -
Risk-reward calibration: A mid-single-digit-to-high-single-digit CAGR creates windows for volume-driven efficiency and premiumization; the right moves in 2026 can shift a player from a volume-dependent margin profile to one supported by specialized formulations and services.
Market dynamics — what’s driving growth
-
Device proliferation and display complexity: Continued adoption of high-resolution, flexible, and chemically strengthened glass surfaces pushes demand for films that preserve optical clarity while offering scratch, impact, and anti-glare properties. The result: product differentiation is increasingly technical rather than purely price-based.
-
Commercial and industrial uptake: Beyond consumer handsets and tablets, growth is being underwritten by industrial displays, point-of-sale terminals, and transport-grade interfaces. These applications raise requirements for environmental resistance and longevity, favoring suppliers with validated performance and warranty frameworks.
-
Materials and process innovation: Advances in polymer chemistry and thin-glass laminates have created tiered offerings — from low-cost polymer films to high-performance glass-based protectors — enabling tailored value propositions for different segments of the market.
-
Sustainability and circularity pressures: Increasing scrutiny around polymer waste and recycling is nudging OEMs and suppliers toward recyclable substrates, lower-VOC adhesives, and take-back programs — all of which become decision factors in supplier selection and product design.
Competitive structure and concentration
The category is moderately concentrated: the top three companies account for the majority share of the market’s revenue base, and the top five capture an even larger portion, creating a competitive landscape where scale matters for distribution and OEM partnerships. This concentration provides advantages for incumbents (economies of scale, channel reach, and co-development agreements) but leaves room for focused challengers that can win on niche performance, speed to market, or service bundles.
Profiles of select players (strategic takeaways)
-
3M Company (St. Paul, MN) — With a long heritage in specialty films and protective coatings, 3M leverages deep materials science capability and global industrial channels. Their portfolio is positioned around high-margin, certified solutions for industrial displays and packaging applications. Strategic consideration: 3M is a natural partner for OEMs seeking validated performance and compliance, but cost-conscious buyers may need to negotiate on service terms and scale commitments.
-
Belkin International, Inc. (Los Angeles, CA) — Belkin combines consumer-channel strength with product customization capabilities (notably privacy filters and impact-resistant films). Their go-to-market is anchored in retail, aftermarket distribution, and brand collaborations. Strategic consideration: Belkin’s value lies in consumer reach and private-label partnerships; incumbents looking to defend retail shelf space should prioritize brand-differentiated co-marketing and IP-protected formulations.
-
ZAGG Inc. (Salt Lake City, UT) — ZAGG specializes in glass and film protectors geared toward scratch and impact resistance, with clear traction in both consumer and light-commercial applications. They are often a bellwether for premium, install-ready products. Strategic consideration: ZAGG represents a case study in converging product design with after-sales services (installation, warranty), underlining the importance of bundled offerings in winning repeat revenues.
Supply chain and margin pressures
-
Raw-material volatility: Pricing and availability of specialty polymers, adhesives, and ultra-thin glass layers drive margin variability. Firms with secured long-term contracts or backward integration show superior margin resilience.
-
Manufacturing scale vs. agility: Investing in high-throughput coating and laminating lines spreads fixed costs, but agility to run short-batch specialty films is increasingly valuable for premium segments. Strategic plant footprint decisions in 2026 should balance automation investments with proximity to key OEM partners.
-
Logistics and inventory: Given thin margins on some commodity films, inventory optimization and just-in-time delivery are critical. Conversely, premium products command higher margins that justify buffer stock for service-level differentiation.
Technology and product trends to watch
-
Multi-functional coatings — anti-fingerprint, anti-microbial, and privacy layers — are becoming table stakes for higher ASP (average selling price) brackets.
-
Thin glass laminates and hybrid film-glass solutions are gaining traction where scratch resistance must be balanced with optical purity.
-
Integration with services — installation, certification, warranty — is a lever for margin expansion and customer lock-in.
Strategic implications for 2026 decision-making
-
Portfolio strategy: Decide whether to pursue a breadth (covering commodity and premium films) or depth (specializing in a high-margin niche). Each route has capital and channel implications — breadth demands scale and distribution, depth demands R&D and intellectual property protection.
-
Partnerships and M&A: Given the market’s moderate concentration, bolt-on acquisitions that add formulation capabilities, regional logistics, or OEM relationships can rapidly alter competitive positioning. In 2026, acquirers should prioritize targets with validated performance data and customer contracts that de-risk integration.
-
Pricing and commercial models: Transitioning from pure product sales to service-enabled offers (installation, extended warranty, sustainability certification) can justify higher price points and stabilize demand.
-
Supply-security planning: For procurement teams, 2026 is the year to move from spot buying to multi-year agreements for critical inputs, or to evaluate partial backward integration where margin benefits exceed capital costs.
-
Regulatory and sustainability positioning: Firms that proactively redesign products and packaging to meet future recycling mandates will enjoy first-mover advantage in tendered OEM contracts and public-sector procurement.
What the full PW Consulting report delivers (practical, transaction-ready content)
Our comprehensive study — grounded in a 2025 base-year audit and a 2026–2032 forecast — provides the tools executive teams need to convert insight into action. The full deliverable contains:
-
Robust market sizing and validated growth scenarios that reconcile historical performance (2020–2025) with multiple demand trajectories for 2026–2032.
-
Segment analysis across region, material type, and application with sensitivity testing and downside/upside case modeling (note: segmented breakdowns and proprietary financial runs are available in the full report).
-
Supplier benchmarking, including cost stacks, capacity maps, and margin pools to guide negotiation and investment decisions.
-
Technology roadmaps and an innovation matrix that prioritize R&D investments by expected commercial impact and time-to-market.
-
M&A playbooks, valuation ranges, and integration checklists tailored to strategic acquirers and private-equity investors.
-
Go-to-market templates for OEM and aftermarket channels, including pricing ladders, channel economics, and sample contract terms.
-
Commercial intelligence dossiers on major competitors, distributors, and raw-material suppliers to support diligence and counterparty assessments.
How to use this analysis
-
CEOs and corporate strategy teams: Use our forecast scenarios to stress-test capital allocation plans and M&A targets against market growth and concentration metrics.
-
Product and R&D leads: Apply the technology matrix to prioritize formulation and coating projects that unlock premium ASPs within a 12–36 month horizon.
-
Procurement and operations: Leverage the supplier benchmarking and capacity maps to redesign sourcing strategies, optimize inventory, and reduce exposure to raw-material swings.
-
Investors and PE firms: Use our valuation frameworks and playbooks as a basis for diligence, focusing on targets that add proprietary materials, regional reach, or OEM contracts.
Final word — the 2026 inflection
In aggregate, the screen protective film market offers a stable growth runway supported by device proliferation, industrial adoption, and materials innovation. The 8.3% projected CAGR through the 2026–2032 window reflects durable end-market demand, but the path to superior returns in 2026 hinges on strategic choices around specialization, supply-security, and service integration. PW Consulting’s full report packages the granular segmentation, financial models, and playbooks that decision-makers need to move from intent to impact — while this briefing delivers the strategic north star to guide those choices.
Next steps
For access to the complete dataset, segmented forecasts, and transaction-ready annexes (including the granular region/type/application splits and proprietary valuation models that are intentionally omitted here to preserve the report’s commercial value), please consult the full PW Consulting Screen Protective Film Market report. That material contains the specific figures and tables your teams will require to finalize 2026 budgets and execute on growth strategies.
For detailed analysis of this topic, please visit the official page: Screen Protective Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cobalt Market 2026: Strategic Intelligence for Boardroom Decisions
As PW Consulting’s lead industry analyst, I present an executive preview of our Cobalt Market research — a targeted, decision-focused briefing structured to help executives calibrate strategy in 2026. Built on a base year of 2025 and a historical lens covering 2020–2025, the full study projects the market across 2026–2032. Our headline finding: the global cobalt market is on a sustained growth trajectory with a compound annual growth rate of 6.69%, expanding materially from an assessed USD 16.96 billion in 2025 toward a projected market north of USD 26 billion by 2032. This preview outlines the strategic implications, competitive dynamics, and the precise operational modules included in the full report — while intentionally withholding granular segment tables and regional splits to preserve the analytic value available only in the report itself.
Cobalt Market
Why this research matters for 2026 decision cycles
-
Timing capital allocation: The medium-term growth path (2026–2032) is clear and durable, driven by electric mobility, industrial metallurgy, and high-performance applications. Boards and CFOs evaluating capex, offtake agreements, or refinery investments in 2026 need an evidence-based view of demand momentum and realistic upside scenarios. Our forecast provides that trajectory and quantifies growth sensitivity to key demand levers.
Cobalt Market -
Supply-chain resilience and sourcing strategy: Geopolitical concentration of upstream supply and concentrated refining capacity are constraining factors that can amplify price volatility and availability risk. Strategic procurement teams must weigh long-term supply contracts, backward integration, and inventory policy against heightened policy risk and trade frictions.
Cobalt Market -
M&A and partnership prioritization: With midstream and downstream pockets of value, 2026 is a year for opportunistic consolidation and strategic partnerships — particularly where firms can secure feedstock, battery-grade refinement, or end-market integration. The full study identifies the most accretive deal archetypes and valuation benchmarks.
-
Regulatory and ESG readiness: Increasing regulatory intervention, import tariffs, and scrutiny of cobalt sourcing and processing require a proactive compliance and traceability posture. Our analysis maps regulatory vectors and provides an operational readiness checklist for 2026 implementation.
Market dynamics: what the numbers reveal (and what we do not disclose here)
From a macro perspective, the cobalt market has expanded significantly during the 2020–2025 vintage years. Our base-year assessment (2025) and the forecast window (2026–2032) demonstrate a steady compound growth rate of approximately 6.69% — enough to justify multi-year investments but not so steep as to rule out meaningful substitution or efficiency gains in adjacent technologies. By 2032 the market is projected to exceed USD 26 billion, confirming a multi-billion-dollar incremental pool of demand for participants along the value chain.
What we are not publishing in this teaser are the full segment-level revenue schedules, regional and application-level percentage splits, and granular cost curves — the core analytic assets in our paid model. These withheld datasets are central to contract negotiation strategies, plant-sizing, and region-specific entry/exit decisions; they are accessible in the full briefing.
Supply-side structure and concentration
Two structural features stand out and carry immediate implications for 2026 strategy:
-
Concentration among producers and refiners: Market concentration is non-trivial — our study estimates that the top three companies control a near-majority share of the market, and the top five account for roughly 60% of global supply. For buyers, this implies counterparty concentration risk and potential price-setting dynamics that favor large incumbent suppliers.
-
Geopolitical supply risk: Recent industry reporting and public data indicate that a substantial share of mine production and refining feedstock comes from a very limited set of source countries and integrated refiners. This centralization elevates the impact of export restrictions, tariffs, and policy shifts on global availability and pricing.
These structural realities inform several high-priority actions: diversification of supplier networks, strategic inventory buffers, increased due diligence of midstream partners, and accelerated investment in processing capability outside highly concentrated basins.
Competitive landscape: profiles and strategic posture
Our research evaluates the strategic positions of major global actors. A selection of these profiles and inferred strategic implications follows.
-
Glencore (Baar, Switzerland) — A major integrated miner and trader active across nickel-copper assets and byproduct cobalt. Its diversified footprint and trading capabilities make it a pivotal swing supplier. Notably, Glencore reported full-year 2025 cobalt production of 36.1 kt, a decline versus 2024 as the company prioritized copper processing amid regional export constraints. For counterparties, Glencore’s flexibility makes it a key partner for spot and strategic purchases, but its allocation decisions can create transient supply tightness.
-
CMOC Group (Beijing, China) — A leading miner with integrated cathode and hydroxide production geared toward battery-grade markets. CMOC’s vertical integration into battery-materials production positions it as a strategic supplier for OEMs and battery manufacturers seeking secure, quality-assured feedstock.
-
Zhejiang Huayou Cobalt (Tongxiang, China) — A large refiner and precursor supplier with operations in multiple jurisdictions. Its strength lies in downstream refinement capability and established offtake relationships with battery makers; for companies requiring consistent chemical-grade material, Huayou is a go-to partner.
-
Vale S.A. (Rio de Janeiro, Brazil) — Produces cobalt as a byproduct of nickel and copper mining, offering geographic diversification to buyers. Vale’s assets provide optionality for offtake and incremental supply security outside the most concentrated mining basins.
-
BHP Group (Melbourne, Australia) — Supplies cobalt principally as a nickel byproduct and benefits from stable regulatory environments in core jurisdictions. BHP can be a strategic supplier for long-duration contracts tied to nickel-cobalt chemistry demands.
-
Rio Tinto (London, UK) — With byproduct flows from large copper operations, Rio Tinto’s role is complementary but strategically significant for customers seeking North American or diversified sourcing.
These profiles are supplemented in the full report by supplier scorecards that quantify operational scale, counterparty risk, ESG performance, and integration potential — information that underpins supplier selection and M&A screening.
Regulatory and trade environment: the 2026 playbook
Policy and trade measures have altered the operational landscape: public data show tariff adjustments and an active regulatory emphasis on traceability and import origin. Notably, recent government disclosures highlight tariff rate increases affecting ores and concentrates from certain origins and record-high mine and refinery production dynamics concentrated in a few jurisdictions. China remains the largest consumer of refined cobalt products, primarily driven by the lithium-ion battery sector, and a meaningful portion of refinery feedstock has been derived from partially refined imports from key producing countries. For corporate strategists, this means:
-
Increased compliance risk and the need to validate supply chains end-to-end.
-
Potential for sudden cost impacts due to tariff regimes or export controls that require dynamic scenario planning.
-
An incentive to localize or regionalize refining and recycling capabilities where feasible.
What’s in the full PW Consulting Cobalt Market report (operational overview)
The full deliverable is designed as a practical playbook for 2026 action, not an academic exercise. Core modules include:
-
Top-line market forecast (2026–2032) with scenario variants tied to EV adoption curves, battery chemistry transitions, and recycling uptake.
-
Supply-demand balancing by year with sensitivity runs for key shocks (export restrictions, rapid substitution, macro downturns).
-
Comprehensive supplier scorecards and a ranked watchlist for strategic partnerships or acquisition targets.
-
Price-modeling engine that decomposes landed cost by origin, processing tier, and tariff/regulatory overlay for contract negotiation support.
-
Risk matrix covering geopolitical, regulatory, ESG, technical, and reputational vectors, with mitigation playbooks.
-
Operational toolkits: negotiation templates, RFP frameworks for long-term offtake, and refinery project financial model baselines.
-
Scenario-based recommendations for OEMs, battery manufacturers, traders, and upstream miners on optimal strategies through 2032.
Immediate tactical recommendations for 2026
-
Lock in a portion of three-year supply via staggered offtake agreements to smooth price exposure while preserving spot optionality.
-
Invest in third-party supplier audits and blockchain-enabled traceability pilots to de-risk sourcing and satisfy downstream clients’ ESG demands.
-
Accelerate feasibility work on regional refining or recycling to reduce dependence on single-source refining hubs.
-
Define clear substitution thresholds and R&D milestones for cathode chemistry adjustments to keep procurement flexible.
Next steps
For executives preparing 2026 budgets, procurement strategies, or M&A pipelines, this preview should be treated as a directional roadmap. The full PW Consulting Cobalt Market report contains the actionable data feeds, segmented forecasts, supplier scorecards, and contractual templates necessary to execute the recommendations outlined here. To convert insight into advantage, access to the complete dataset and models is required — the detailed segmentation and scenario outputs are intentionally reserved to preserve their strategic value for subscribers and clients.
Contact PW Consulting to obtain the full report, interactive models, and an implementation workshop tailored to your organization’s role in the cobalt value chain.
For detailed analysis of this topic, please visit the official page: Cobalt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lightweight Jackets Market to Hit USD 191.81M by 2032 at 6.1% CAGR
By pmarketresearch, 2026-07-09
Lightweight Jackets Market — Strategic Preview for 2026 Decision-Making
As companies prepare strategy for 2026 and beyond, the lightweight jackets market represents a clear, measurable growth corridor—one shaped by consumer mobility, materials innovation, and tightening regulation on chemical finishes. PW Consulting’s new market research provides the scenario modeling, competitive mapping, and regulatory risk analysis that senior leaders need to convert market momentum into defensible growth. Below is a concentrated preview of the report’s most actionable insights designed to demonstrate depth and direction while preserving the proprietary segment-level intelligence that makes the full study indispensable.
Lightweight Jackets Market
Market trajectory at a glance
-
Base year and scope: the study uses 2025 as the base year, covers historical performance from 2020–2025, and delivers forward-looking forecasts for 2026–2032. Financials are reported in USD, with revenue figures given in millions.
Lightweight Jackets Market -
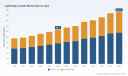
Historical growth: the global lightweight jackets market expanded steadily through the first half of the decade, rising from USD 94.22 Million in 2020 to USD 126.7 Million in 2025—reflecting sustained consumer demand for packable, travel-ready outerwear and a shift toward multifunctional garments.
Lightweight Jackets Market -
Forecast and momentum: our baseline model projects the market to reach USD 191.81 Million by 2032, representing a compound annual growth rate of approximately 6.1% across the forecast window. This trajectory is driven by product innovation (lighter weight, improved insulation ratios), greater adoption in mainstream apparel assortments, and channel diversification.
-
Market structure: concentration metrics indicate a moderately fragmented landscape—top-three firms account for roughly one-third of market revenues, while the top-five account for approximately 42%—a dynamic that favors both premium brand defense and scale-driven consolidation opportunities.
What’s inside the full PW Consulting study (practical contents)
-
Robust demand model: a transparent bottom-up model reconciling shipment, retail sell-through, and ASP trends across 2020–2032. The model is parameterized so clients can run custom scenarios (price shocks, raw-material stress, regulatory compliance costs).
-
Profitability map: SKU-level margin benchmarks and a cost-stack diagnostic (materials, fill power, membrane tech, trimming, and logistics) for margin recovery playbooks.
-
Channel and route-to-market playbook: actionable guidance for e‑commerce expansion, wholesale assortment rationalization, and wholesale-to-direct migration, including KPIs to monitor during rollout.
-
Technology and materials radar: assessment of insulation technologies, waterproof-breathable membranes, fluorine-free durable water repellents (DWRs), and lifecycle repair/reuse models—prioritized by commercial readiness and cost-to-adopt.
-
Regulatory impact model: quantified cost and time-to-market implications for emerging PFAS restrictions in major U.S. states and analogous regulatory movements globally.
-
Competitive profiles and strategic moves: in-depth company dossiers, capability maps, and expansion playbooks for leading brands, plus deal-screening guidance for M&A or JV candidates.
-
Go-to-market case studies: three executable pilots (premium performance, mass-market basics, and direct-to-consumer light outerwear) with supply-chain design, inventory cadence, and marketing and pricing templates.
Strategic implications for 2026 corporate planning
-
Product portfolio: invest in a tiered product architecture. Maintain a high-margin technical line to defend brand equity while expanding value-oriented, high-turnover SKUs for broader retail penetration. Use the elasticity ranges in our model to set launch price points and promotional cadence.
-
Materials and sourcing: prioritize early qualification of PFAS-free DWRs and alternative membranes. Our scenario analysis shows manufacturers that front-load certification and supplier audits in 2026–2027 avoid costly rework and inventory write-down risk as state-level restrictions tighten.
-
Supply chain resilience: dual-sourcing of critical inputs (high-fill down, advanced synthetics, and membrane laminates) reduces single-point-of-failure exposure. For companies reliant on Asia-centric supply chains, building buffer capacity on key components will materially shorten recovery timelines during logistics disruption.
-
Channel strategy: accelerate direct-to-consumer capabilities where margin recovery is highest, but treat wholesale partners as strategic volume engines; optimize SKU depth between channels rather than duplicating assortments.
-
P&L management: implement a product-cost transparency program to reclaim margin through trimming complexity, negotiating long-term agreements on fill-down and membrane purchases, and targeting inventory turns improvement.
-
M&A and partnerships: look for bolt-on acquisitions that provide differentiated materials IP, scale in cold‑weather essentials, or digital fulfillment expertise. The current concentration profile implies opportunities to buy scale at reasonable multiples without bidding wars among incumbents.
Competitive landscape — what leaders are doing
-
Patagonia (Ventura, CA) — plays to sustainability credentials and product longevity. Its repair and lifetime-value positioning defends premium pricing and attracts environmentally motivated consumers. Strategically, Patagonia’s model signals the commercial upside of investing in product durability and traceable supply chains.
-
The North Face (San Francisco, CA) — leverages R&D in warmth-to-weight and packability to target hybrid urban-outdoor consumers. Recent product launches in late 2025 emphasize improved warmth-to-weight ratios and water-resistant shells—moves that increase relevancy across lifestyle occasions.
-
Uniqlo (Tokyo) — advances the mass-market segment through scale, high-fill down technologies, and aggressive global rollouts. Its line extensions in early 2025 demonstrate how cost-efficient engineering and supply-chain scale can compress premium attributes into accessible price points.
-
Outdoor Research (Seattle, WA) — focuses on ultralight waterproof performance using advanced membranes and minimalistic construction. Catalog updates in mid-2025 highlight the commercial niche for consumers who pay up for lightweight technical protection.
-
Implication: incumbents are bifurcating around two winning plays—premium technical differentiation versus mass-market optimization. Mid-market players face the strategic choice to tilt toward one axis or adopt a hybrid model with clear channel-specific assortments.
Regulatory dynamics that will shape 2026 strategy
-
PFAS restrictions and disclosures: multiple U.S. states have enacted prohibitions or disclosure regimes for intentionally added PFAS in textiles. Notably, California’s AB 1817 came into effect in January 2025 and requires disclosures for certain outdoor apparel; its provisions include a staged lowering of total organic fluorine thresholds. New York enacted a prohibition effective January 2025, and Connecticut implemented disclosure requirements in January 2026.
-
Operational impacts: compliance will require lab testing, supply-chain traceability, and labeling adjustments. Firms that are proactive in reformulating DWR chemistry, certifying suppliers, and redesigning care/marketing copy will avoid disruption and gain first-mover advantage in sustainability-conscious channels.
-
Risk mitigation roadmap: our report provides a compliance playbook—testing cadence, supplier contractual clauses, and contingency timelines—that quantifies the cost and time penalties across alternative regulatory scenarios.
Where the value pools are (and what we intentionally do not publish here)
High-level: the greatest value over the next three-to-six years is concentrated in (a) premium ultra-light technical jackets with differentiated materials, (b) mass-market light-down essentials that prioritize cost and fit, and (c) adjacent services (repair, refurbishment, and resale) that extend customer lifetime value. PW Consulting’s full report contains the granular split by type, application, and region that corporate leaders use to size opportunities, allocate capex, and plan launches. In keeping with our “trailer” principle, those segment-level numbers and the underlying models are available in the complete study and through our advisory engagements.
How PW Consulting helps executives translate insight into action
-
Decision-ready deliverables: a downloadable model (Excel) permitting executives to test pricing, sourcing, and regulatory scenarios; a 25-slide executive playbook that distills strategic options by company archetype; and a 12-month rapid-implementation roadmap for prioritized initiatives.
-
Workshops and pilots: facilitated strategy workshops to align product, sourcing, and channel teams; pilot program design to test mass-market launches or premium technical rollouts with measurable KPIs.
-
Ongoing advisory: bespoke diligence for M&A targets, supplier qualification support, and regulatory pre-clearance services to shorten time-to-market for reformulated chemistries.
Next steps for 2026 planning
Leaders preparing budgets and strategic plans for 2026 should prioritize three actions this quarter: (1) perform a materials and supplier audit with a PFAS risk scorecard, (2) stress-test assortments against the 6.1% CAGR baseline and alternate scenarios in our model, and (3) define a pilot to validate margin recovery levers (pricing, cost-to-serve, and inventory turns). PW Consulting’s full report and scenario model provide the evidence base and the executable templates needed to run these initiatives with speed and confidence.
For boards and executive teams, the choice is simple: use 2026 to lock in supply-chain resilience and regulatory compliance while selectively investing in product differentiation and channel capabilities—because the market is growing, but the true winners will be the organizations that convert growth into sustainable margin expansion and defensible market positions. Access the full study or contact PW Consulting to commission a tailored variant that maps these findings directly to your portfolio.
For detailed analysis of this topic, please visit the official page: Lightweight Jackets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pinch Valve Market to Hit USD 847M by 2032 on 4.2% CAGR
By pmarketresearch, 2026-07-09
Pinch Valve Market 2026: Strategic Preview for Executive Decision-Makers
Executive summary
As we approach 2026, pinch valves occupy a quietly strategic position in industrial and process-control portfolios. Our latest market study—anchored to a 2025 base year and projecting through 2032—shows the market following a steady growth trajectory (CAGR 4.2% across the forecast horizon). The market has moved from an early-growth posture in the first half of this decade into a phase characterized by selective product innovation, distribution consolidation, and application-driven adoption that rewards lifecycle optimization and system integration.
Pinch Valve Market
This preview outlines the strategic value of the full PW Consulting report for executives preparing 2026 plans. It highlights directional market sizing, competitive dynamics, technology and channel trends, and the practical tools included in the publication that enable fast, decision-ready actions—while intentionally omitting core segmented datapoints that are reserved for subscribers.
Pinch Valve Market
Why 2026 is a decisive planning year
-
CapEx cycles: Capital allocation in water/wastewater, mining, and food & beverage is moving from catch-up replacement toward targeted modernization programs. Buyers in 2026 will favor suppliers who can demonstrate lower total cost of ownership rather than lowest first-cost.
Pinch Valve Market -
Supply-chain resilience: Material choices and tube-sleeve sourcing have emerged as differentiators. Designs that permit the use of lower-cost tube materials in appropriate applications are expanding addressable markets without compromising reliability.
-
Regulatory and hygiene demands: Sterile and single-use trends in pharmaceuticals and life sciences compress design cycles and increase the premium on compatibility with regulated environments.
Market trajectory—what the macro data tells you
PW Consulting’s topline market sizing shows clear, measurable momentum. From our historical baseline, the market has expanded meaningfully through 2025 and continues to advance through the forecast period to 2032 under a steady compound annual growth rate (CAGR) of 4.2%. This growth path reflects combined demand from replacement cycles, capacity additions in targeted end markets, and incremental uptake driven by product innovation in sleeve life and actuator efficiency.
For executives, this profile creates a predictable planning envelope: investment cases that hinge on multi-year paybacks can be built with confidence, while shorter-cycle go-to-market initiatives can exploit pockets of higher-than-average demand. The market is large enough to support new entrants and adjacent incumbents, yet fragmented enough that focused tactical moves—distribution agreements, tube-material partnerships, or niche product launches—can meaningfully shift competitive position.
Key dynamics and technology trends shaping 2026 decisions
-
Longevity of consumables: Sleeve technology innovations and manufacturing methods that extend sleeve life materially change maintenance intervals and whole-life costs. Innovations that extend sleeve life or reduce stress on the tube sleeve will command premium valuation in industrial applications.
-
Design-for-single-use and compact automation: Motorized, compact pinch valve designs tailored for single-use systems reduce plant footprint and ease integration into automated lines—critical for pharmaceutical single-use processing and lab automation.
-
Cost-down tube compatibility: New valve designs that permit the controlled use of cost-effective tube materials (e.g., certain PVC compounds) without sacrificing process integrity open large pricing-sensitive segments, especially in filling and dispensing.
-
Diagnostics and integration: The addition of state-feedback, LED diagnostics, and cleaner actuation options increases appeal to labs and automated production facilities where uptime and traceability are non-negotiable.
-
Channel plays and regional distribution: Strategic distribution partnerships that bundle certification (ASME/ANSI, DIN, ISO) and local service capabilities accelerate municipal and utilities adoption where compliance and serviceability are primary buying criteria.
Competitive landscape—strategic profiles and implications
The market is consolidated at the top but remains broadly fragmented, providing opportunity for regionally strong, technology-focused, and service-led players. The report analyzes leading vendors and their strategic postures; below is a high-level synthesis of core players and what they represent for potential partners or acquirers.
-
Onyx Valve Company (Cinnaminson, NJ, USA) — A U.S.-based manufacturer focused on pneumatic and heavy-duty pinch valves with a vertically integrated, in-house machining and assembly model. Onyx’s strength lies in industrial-grade robustness and a manufacturing footprint that supports rapid customization for heavy industrial flow-control needs. Strategic implication: attractive partner for end-users requiring fast customization and domestic sourcing assurances.
-
Lexair, Inc. (Lexington, KY, USA) — Known for Tube-O-Matic® pneumatic pinch valves, Lexair targets abrasive, corrosive, and fibrous media control. In-house manufacturing produces consistent quality for fluid power and industrial applications. Strategic implication: compelling fit for distributors and OEMs seeking proven solutions for abrasive-service lines.
-
RF Valves, Inc. (Hanover, MD, USA) — Differentiates on sleeve longevity and ruggedness with patented tube-folding technologies. Their product set spans high-pressure conditions and a wide dimensional range, making them a go-to for applications demanding extended sleeve life. Strategic implication: potential acquisition target for firms aiming to own key sleeve-life IP.
-
Valmet Oyj (Espoo, Finland) — Through Flowrox™ products, Valmet brings a heavy-duty, process-centric portfolio targeting slurry, powder and granule handling across mining, wastewater, and power generation. The company’s global reach and cross-industry experience make it a strong contender for large projects requiring integrated supply and lifecycle services.
-
AKO Armaturen & Separationstechnik GmbH (Trebur-Astheim, Germany) — Specializes in hygienic and sterile pinch valves, offering online commerce and a wide DN range. AKO’s emphasis on hygiene, Ex-rated products, and rapid web-based ordering meets the needs of food, pharma, and process industries prioritizing compliance and speed.
Recent market moves—motorized pinch valves for single-use systems, power-optimized designs for cost-sensitive filling processes, precision lab-focused valves with integrated diagnostics, and strengthened regional distribution partnerships—highlight how vendors are carving out differentiated plays. Each of these moves translates into tactical opportunities for buyers and bidders: product licensing, co-development, and exclusive distribution are practical levers to accelerate market entry or defend share.
What the full report contains (practical, execution-ready content)
The PW Consulting market study is designed for immediate operational use by strategists, BD teams, product managers, and procurement. Key deliverables include:
-
Methodology and transparent market-sizing model (base year 2025; historical 2020–2025; forecast 2026–2032) with downloadable inputs and sensitivity toggles.
-
Segment-level frameworks (by type, by application, by region) and buyer-persona heat maps—note: granular segment-specific financial tables are available in the subscriber edition.
-
Supply-chain mapping, bill-of-material cost drivers, and sleeve-material sourcing playbooks.
-
Competitive benchmarking with strategic positioning matrices, SWOTs, and M&A candidate shortlists.
-
Commercial playbooks: pricing strategies, distributor scoring, tender-response templates, and channel incentive models geared to 2026 procurement cycles.
-
Risk and scenario analysis covering raw-material shocks, regulatory tightening in hygienic sectors, and rapid substitution risk from alternative flow-control technologies.
-
Implementation roadmaps: 90/180/365 day execution plans for product launches, partner rollouts, and retrofit campaigns targeting mid-sized utilities and process OEMs.
Actionable strategic implications for 2026
-
Prioritize whole-life economics: Reframe selling propositions to procurement teams around sleeve longevity, mean-time-between-maintenance (MTBM), and field-service limits—not just per-unit price.
-
Targeted product bets: Invest selectively in motorized compact designs and state-feedback diagnostics for single-use and lab markets, while preserving a robust industrial portfolio for heavy-duty slurry and abrasive services.
-
Channel acceleration: Secure distribution agreements in geographies where local certifications and on-the-ground service convert tenders—partner with regional players that can offer ASME/ANSI/DIN/ISO compliance and rapid spare-part fulfillment.
-
M&A and IP strategy: Consider tuck-in acquisitions that bring sleeve-life innovations or tube-material compatibility into your product set to quickly differentiate on lifecycle cost.
-
Operational readiness: Align production footprints to support customization and rapid lead times—vertical integration can be a competitive advantage in industrial and high-spec applications.
How to access the full intelligence
This preview is designed to demonstrate the depth and directionality of our analysis while reserving the detailed segment-level models and transactional intelligence for the full report. Subscribers receive the complete dataset, downloadable market model, supplier scorecards, and implementation templates needed to start executing in 2026.
For direct inquiries and bespoke briefings—competitive benchmarking tailored to your portfolio, acquisition target screens, or a 90-day go-to-market plan—PW Consulting’s Pinch Valve Market team is available for executive workshops. The full report includes named company analyses, recent development timelines, and an appendix with sourced primary interviews and supplier contacts to accelerate your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Pinch Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ostomy Products Market Poised for 5.1% CAGR Through 2032
By pmarketresearch, 2026-07-09
Ostomy Products Market 2026: Strategic Imperatives for Leadership — A PW Consulting Preview
As healthcare systems, reimbursement frameworks, and patient expectations evolve, the ostomy products market is entering a phase where incremental innovation and operational excellence no longer suffice. PW Consulting’s full Ostomy Products Market study (base year 2025; forecast period 2026–2032) synthesizes five years of historical performance (2020–2025) with forward-looking scenario analysis to equip executives with the insights they need to make decisive moves in 2026. In short: the market is stable and growing, but the distribution of value and the levers of competitive advantage are changing fast.
Ostomy Products Market
Why this study matters to corporate decision-makers in 2026
The global ostomy products market reached approximately USD 3.02 billion in 2025 and, under our central scenario, is projected to approach USD 4.3 billion by 2032 — reflecting a compound annual growth rate (CAGR) of 5.1% over the forecast period. These headline numbers hide important strategic realities. Growth is being driven by a blend of demographic tailwinds, incremental product innovation (particularly around skin barriers, adhesives and user-centric pouch systems), and channel shifts toward digital distribution. At the same time, regulatory and reimbursement vectors are introducing new sources of volatility that can quickly magnify or erode margin pools.
Ostomy Products Market
For executive teams planning 2026 strategy cycles, three imperatives emerge: (1) anticipate and model regulatory/reimbursement scenarios explicitly, (2) reshape go-to-market models to capture both clinical and consumer value, and (3) invest selectively in product and supply-chain resilience where the payoff aligns with projected margin expansion. The full report provides the economic levers, scenario matrices and profit-impact models you’ll need to operationalize these priorities — this preview outlines the strategic logic and practical next steps.
Ostomy Products Market
Market dynamics that will define 2026 decision-making
- Reimbursement and procurement shifts: Medicare Part B’s coverage framework remains a foundational demand driver for eligible patients. However, proposed regulatory shifts — notably the CMS consideration to reclassify ostomy and urological supplies for inclusion in DMEPOS competitive bidding programs — represent a material risk to pricing and distribution economics. Our scenarios quantify the revenue and margin exposure across bidding and non-bidding outcomes so leaders can prioritize advocacy, contracting and pricing playbooks.
- Regulatory and certification requirements: ISO 13485 and FDA 510(k) pathways remain non-negotiable for market access in key geographies. Firms that compress regulatory timelines through modular design, standardized clinical evidence packages and early regulator engagement will unlock faster product rollouts and reduce time-to-revenue risk in 2026.
- Raw material and manufacturing constraints: The quality and source of medical-grade hydrocolloids, silicone adhesives and barrier films are critical to both clinical performance and product differentiation. Our supplier risk heatmaps and cost-sensitivity models show where vertical integration or qualified dual-sourcing yields disproportionate value.
- Patient-centric product innovation: Advances such as ceramide-containing skin barriers and system-level pouch ergonomics are shifting purchasing decisions from purely functional to experience-based. Clinical outcomes and comfort now factor directly into volume growth and retention, especially in self-payer and consumer-direct channels.
- Channel and digital adoption: Catalogs, digital storefronts and subscription models are reducing friction in replenishment while increasing visibility on real-world adherence. Early movers are using digital channels to bundle education, telehealth support and product replenishment — improving lifetime value and reducing clinical complications.
Competitive map — where consolidation and differentiation collide
The market exhibits meaningful concentration among a handful of incumbent manufacturers and specialist suppliers. Our concentration metrics indicate that the top three firms control a substantial majority of market share, and the top five dominate an even larger portion. This structure shapes both competitive behavior (pricing discipline, innovation investment) and strategic options for mid-tier players seeking to carve defensible niches.
- Major system players: Established global manufacturers — offering integrated pouching systems, wafers and differentiated skin-care technologies — continue to invest in platform innovation and clinical evidence generation. Their strengths are scale, brand recognition and long-term relationships with providers and payers.
- Specialists and regional champions: A cohort of companies focuses on specific clinical segments, accessory portfolios or regional distribution excellence. These firms often compete on service levels, custom-fit solutions and responsiveness to clinician feedback, creating attractive acquisition targets for larger players seeking complementary capabilities.
- New entrants and private-label threats: Channel evolution and supplier consolidation raise the possibility of private-label offerings from large distributors. The risk is most acute in commoditized accessory categories where differentiation is thin and price sensitivity is high.
Key names warranting executive attention in 2026 include a mix of global incumbents and regional specialists. These companies represent the spectrum of strategic approaches in the market — from high-touch system innovation to distribution-led scale. Understanding their product strategies, recent launches, and partner networks will be essential for formulating competitive responses.
Recent developments that change the calculus for 2026
- Policy pressure on procurement: In mid‑2025 CMS proposed reclassification of ostomy supplies in a way that could expose the category to competitive bidding — a structural event that could compress prices and reroute flows to low-cost distributors if enacted. Industry advocacy groups are actively responding, and we quantify the economic impact under alternative policy outcomes.
- Advocacy and patient voice: Patient groups are sharpening their messaging around clinical nuance and the need for individualized coverage — an important counterbalance to procurement-driven cost-squeezing. Expect advocacy to be a decisive factor in shaping final policy language.
- Commercial activity and product messaging: Several manufacturers and distributors refreshed their commercial collateral and product portfolios in late 2025 and early 2026, emphasizing skin-health technologies (including ceramide barriers), improved pouch ergonomics and expanded digital catalogs. These moves signal a shift from product-only competition to integrated patient experience propositions.
What the full PW Consulting report delivers — practical tools for 2026
Our report is intentionally operational. Beyond market sizing and growth projections, it contains tools that executives can apply directly to budgeting, M&A screening, product roadmaps and regulatory planning:
- Segment-level demand models (by product type and clinical application) with sensitivity levers for pricing, reimbursement and adoption curves.
- Scenario analyses for CMS rule outcomes, including detailed P&L impact estimates across channel and customer segments.
- Supplier risk and cost-mitigation playbooks focused on adhesives, hydrocolloid wafers and critical barrier films.
- Competitive benchmarking with capability heatmaps for R&D, regulatory throughput, distribution reach and digital engagement.
- Commercial playbooks that translate clinical evidence into payer value propositions and clinician adoption tactics.
- M&A target shortlists and integration checklists aligned to different strategic arcs (scale, capability, channel).
Note: This preview is calibrated to show the depth and applicability of our analysis while deliberately withholding granular segment-level figures and regional breakdowns that drive transactional decisions. The full dataset and financial models — including disaggregated revenue by product type and application, regional market splits and competitor share tables — are available in the complete report and Excel deliverables.
Practical strategic recommendations for 2026
- Run regulatory scenario war games: Treat the proposed CMS competitive-bidding pathway as a high-probability disruptor. Create adaptive commercial playbooks: one for a status-quo reimbursement environment and one for a bidding-dominated landscape.
- Prioritize adhesive and barrier supply resilience: Map single-source exposure and develop dual-sourcing or qualifying plans for key hydrocolloid and silicone suppliers. Consider inventory strategies that balance working capital and continuity of supply for high-value SKUs.
- Double down on clinical differentiation: Invest in outcomes studies and quality-of-life data that support premium positioning for system-level products, especially where skin integrity and complication avoidance can be quantitatively tied to reduced downstream costs.
- Re-engineer go-to-market economics: Pilot subscription or bundled-service models in select geographies to capture higher lifetime value and predictable demand while testing digital engagement levers.
- Prepare M&A and partnership playbooks: Identify targets that fill capability gaps (e.g., digital patient support, specialized accessories, regional distribution) and design fast-integration playbooks to extract synergies within 12–18 months.
Final note — how to use this preview
Think of this briefing as a strategic trailer: it distills the forces that will shape the ostomy products market in 2026 and highlights the actions that separate winners from laggards. The full PW Consulting market study supplies the granular inputs — segment revenues, regional splits, competitor share tables and downloadable financial models — that are required to convert these strategic priorities into concrete budgets, contracts and product roadmaps.
For companies planning board-level strategy sessions or preparing investor materials for 2026, the full report is designed as a working toolset rather than a static document. Contact PW Consulting to obtain the complete dataset, scenario models and a tailored executive briefing that aligns findings to your organization’s objectives and risk tolerance.
For detailed analysis of this topic, please visit the official page: Ostomy Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Depth of Anesthesia Monitor Market — USD 378.8M in 2025, 4.4% CAGR to 2032
By pmarketresearch, 2026-07-09
Depth of Anesthesia Monitor Market — Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
As health systems intensify focus on perioperative safety, processed‑EEG depth‑of‑anesthesia monitoring has moved from niche adjunct to operational consideration for hospitals, anesthesia groups, and device OEMs. Our market model — anchored to a 2025 base year and spanning 2026–2032 forecast scenarios — shows steady expansion driven by adoption in perioperative suites, tighter integration with anesthesia delivery platforms, and supportive regulatory and reimbursement environments. The total market grew from approximately USD 303.9 Million in 2020 to USD 378.8 Million in 2025 and is projected to approach USD 516.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of 4.4% across the forecast horizon.
Depth of Anesthesia Monitor Market
Why this report matters for 2026 strategic decisions
- Investment prioritization: The market’s predictable growth and concentration dynamics enable CFOs and corporate development teams to size opportunity corridors for organic R&D versus M&A.
- Procurement and clinical pathways: Hospital CEOs and CMOs can use the evidence and reimbursement mapping in the report to design adoption pilots that show near‑term ROI and support scaled rollouts across surgical service lines.
- Product and platform roadmaps: Device OEMs and software integrators can prioritize telemetry, interoperability, and disposable strategies to capture recurring revenue streams.
- Regulatory and reimbursement timing: With recent clearances and ongoing 510(k) activity, the report’s regulatory roadmap helps legal and market access teams sequence filings and payer engagement to maximize launch impact.
Market trajectory — what the numbers mean (high level)
The market exhibits steady, mid‑single‑digit growth: after increasing from roughly USD 303.9M in 2020 to USD 378.8M in 2025, demand is expected to continue expanding through 2032, reaching an estimated USD 516.0M under our baseline scenario. This reflects a combination of volume growth in monitored procedures, higher attach rates in new anesthesia platforms, and incremental selling into retrofit and health‑system upgrade cycles. The macro picture is one of maturation rather than explosion — predictable expansion that rewards disciplined go‑to‑market execution and clinical evidence generation.
Depth of Anesthesia Monitor Market
Competitive structure and implications
The market is moderately concentrated: the top three vendors account for the majority of revenue, while the top five strengthen that concentration further. For incumbents and challengers, this creates two strategic imperatives: defend core perioperative relationships through integrated platform offers and pursue differentiated value propositions (pediatric clearance, software analytics, consumable ecosystems) to pick off share in specialty niches.
Depth of Anesthesia Monitor Market
- Medtronic — With its BIS™ Monitoring System and recent interface refreshes, Medtronic is leaning into clinical familiarity and an established index to support dosing optimization. Regulatory milestones and platform usability upgrades are supporting continued commercialization activity.
- GE HealthCare — GE’s entropy‑based offerings, integrated into its Carescape/Carestation anesthesia platforms, position it to monetize system conversions and workstation upgrades. Pending U.S. clearances for next‑generation platforms create a launch window through 2026 for aggressive platform adoption plays.
- Masimo — Masimo’s SedLine and Patient State Index (PSI) emphasize processed‑EEG analytics and pediatric indications, highlighting a route to clinical differentiation that can underpin hospital procurement decisions where pediatric or neuro‑monitoring use cases are material.
- Mindray — As a platform OEM with strong anesthesia system sales, Mindray’s integration of EEG monitoring into anesthesia workstations offers a low‑friction path to higher attach rates in price‑sensitive markets and system upgrade cycles.
- Nihon Kohden — With next‑generation indices and BIS‑compatible systems, Nihon Kohden is positioned to serve hospital perioperative suites that prioritize compatibility and enterprise monitoring standards.
Recent vendor activity underscores the strategic themes above: regulatory clearances, platform launches, and tactical hospital installations all point to vendors pursuing both platform integration and point‑solution differentiation. For example, several vendors have announced product upgrades and platform launches through 2024–2025, while targeted installation contracts demonstrate demand for validated use cases in major academic centers.
Market dynamics and technology drivers
- Clinical drivers: Growing emphasis on reducing postoperative delirium and optimizing anesthetic dosing pushes clinicians to consider processed‑EEG monitoring as part of multimodal strategies. Large annual surgical volumes in key markets sustain a strong underlying procedure base.
- Platform integration: The most scalable commercial plays are those that embed depth‑of‑anesthesia indices into anesthesia workstations and perioperative monitoring portfolios, enabling bundled hardware plus disposable revenue models.
- Regulation and reimbursement: Favorable reimbursement policies in several jurisdictions and recent 510(k) clearances for upgraded monitors accelerate hospital adoption; understanding regional payer dynamics remains essential to launch sequencing.
- Service and consumables: Consumables and service contracts are a reliable, recurring revenue lever — strategies that lock in ongoing consumable spend will materially improve lifetime value of installed base.
What the report contains — practical, transaction‑grade deliverables
This report is intentionally operational. It provides the tools leaders need to convert insight into decisions without exposing every cell in our model in this preview:
- Detailed market model (historical 2020–2025; forecast 2026–2032) with scenario and sensitivity modules that let you stress test volume, pricing, and attach‑rate assumptions.
- Regulatory and reimbursement roadmap across primary markets, including filing timelines, typical review risks, and payer engagement tactics.
- Competitive profiles and capability matrices for incumbent and challenger vendors, with go‑to‑market playbooks and acquisition targets ranked by strategic fit.
- Commercial playbooks tailored for OEMs, device distributors, and hospital procurement teams — covering bundling, pricing, demo protocols, and clinical trial design to accelerate adoption.
- Clinical value case templates and hospital ROI calculators you can populate with local data to make the internal funding case for pilots and rollouts.
- M&A and partnership heatmaps that prioritize targets by technology gaps, geographic strength, and consumables potential, supported by synergy and valuation heuristics.
How to use this intelligence in 2026 — practical paths forward
- For OEMs: Prioritize integration with leading anesthesia platforms, invest in clinical studies that demonstrate cost of care improvements (e.g., reduced anesthetic usage, shorter PACU stays), and accelerate software analytics that create lock‑in across installed bases.
- For private equity and corporate development: Focus on targets that expand consumable annuities, fill technology gaps (e.g., pediatric validation, advanced indices), or accelerate footholds in fast‑growing, price‑sensitive regions.
- For hospitals and IDNs: Use staged procurement pilots to validate clinical protocols and capture site‑specific ROI; negotiate platform‑level pricing that secures favorable consumable rates and service uptime SLAs.
- For payers and policymakers: Leverage clinical evidence templates to calibrate coverage policies that reward demonstrated reductions in postoperative complications and total cost of care.
Competitive watchpoints through 2026
Watch for three inflection activities that will re‑shape the competitive map:
- Platform launches and clearances: New workstation introductions and 510(k) clearances can materially increase attach rates; vendors with timely regulatory approvals can win early enterprise procurement cycles.
- Clinical evidence wins: High‑quality randomized and registry data demonstrating outcome or cost improvements will be decisive in persuading conservative hospital buyers.
- Consumables and data services: Companies that convert monitoring into a recurring revenue stream through disposables, analytics subscriptions, or cloud services will expand enterprise value disproportionately vs. pure‑hardware sellers.
Closing — the strategic edge of this briefing
This report is built to be actionable in 2026: it combines a defensible market model (anchored to the 2025 base year), competitive diligence on the incumbents and challengers shaping supply, and hands‑on commercial playbooks to convert market growth into tangible revenue and margin improvements. The market’s steady CAGR and concentration structure favor focused execution: the right combination of clinical evidence, platform integration, and consumable economics wins.
To access segment‑level forecasts, regional and application splits, detailed company financial proxies, and the downloadable model that underpins our conclusions, consult the full Depth of Anesthesia Monitor Market report on the PW Consulting portal or contact our industry team to schedule a tailored briefing. The preview above demonstrates the strategic depth we bring — the full research delivers the granular cells and scenario engines your 2026 decisions require.
For detailed analysis of this topic, please visit the official page: Depth of Anesthesia Monitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com