

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ostomy Products Market Poised for 5.1% CAGR Through 2032

Ostomy Products Market 2026: Strategic Imperatives for Leadership — A PW Consulting Preview
As healthcare systems, reimbursement frameworks, and patient expectations evolve, the ostomy products market is entering a phase where incremental innovation and operational excellence no longer suffice. PW Consulting’s full Ostomy Products Market study (base year 2025; forecast period 2026–2032) synthesizes five years of historical performance (2020–2025) with forward-looking scenario analysis to equip executives with the insights they need to make decisive moves in 2026. In short: the market is stable and growing, but the distribution of value and the levers of competitive advantage are changing fast.
Ostomy Products Market
Why this study matters to corporate decision-makers in 2026
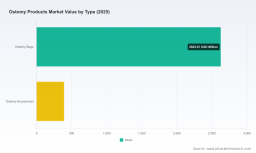
The global ostomy products market reached approximately USD 3.02 billion in 2025 and, under our central scenario, is projected to approach USD 4.3 billion by 2032 — reflecting a compound annual growth rate (CAGR) of 5.1% over the forecast period. These headline numbers hide important strategic realities. Growth is being driven by a blend of demographic tailwinds, incremental product innovation (particularly around skin barriers, adhesives and user-centric pouch systems), and channel shifts toward digital distribution. At the same time, regulatory and reimbursement vectors are introducing new sources of volatility that can quickly magnify or erode margin pools.
Ostomy Products Market
For executive teams planning 2026 strategy cycles, three imperatives emerge: (1) anticipate and model regulatory/reimbursement scenarios explicitly, (2) reshape go-to-market models to capture both clinical and consumer value, and (3) invest selectively in product and supply-chain resilience where the payoff aligns with projected margin expansion. The full report provides the economic levers, scenario matrices and profit-impact models you’ll need to operationalize these priorities — this preview outlines the strategic logic and practical next steps.
Ostomy Products Market
Market dynamics that will define 2026 decision-making
- Reimbursement and procurement shifts: Medicare Part B’s coverage framework remains a foundational demand driver for eligible patients. However, proposed regulatory shifts — notably the CMS consideration to reclassify ostomy and urological supplies for inclusion in DMEPOS competitive bidding programs — represent a material risk to pricing and distribution economics. Our scenarios quantify the revenue and margin exposure across bidding and non-bidding outcomes so leaders can prioritize advocacy, contracting and pricing playbooks.
- Regulatory and certification requirements: ISO 13485 and FDA 510(k) pathways remain non-negotiable for market access in key geographies. Firms that compress regulatory timelines through modular design, standardized clinical evidence packages and early regulator engagement will unlock faster product rollouts and reduce time-to-revenue risk in 2026.
- Raw material and manufacturing constraints: The quality and source of medical-grade hydrocolloids, silicone adhesives and barrier films are critical to both clinical performance and product differentiation. Our supplier risk heatmaps and cost-sensitivity models show where vertical integration or qualified dual-sourcing yields disproportionate value.
- Patient-centric product innovation: Advances such as ceramide-containing skin barriers and system-level pouch ergonomics are shifting purchasing decisions from purely functional to experience-based. Clinical outcomes and comfort now factor directly into volume growth and retention, especially in self-payer and consumer-direct channels.
- Channel and digital adoption: Catalogs, digital storefronts and subscription models are reducing friction in replenishment while increasing visibility on real-world adherence. Early movers are using digital channels to bundle education, telehealth support and product replenishment — improving lifetime value and reducing clinical complications.
Competitive map — where consolidation and differentiation collide
The market exhibits meaningful concentration among a handful of incumbent manufacturers and specialist suppliers. Our concentration metrics indicate that the top three firms control a substantial majority of market share, and the top five dominate an even larger portion. This structure shapes both competitive behavior (pricing discipline, innovation investment) and strategic options for mid-tier players seeking to carve defensible niches.
- Major system players: Established global manufacturers — offering integrated pouching systems, wafers and differentiated skin-care technologies — continue to invest in platform innovation and clinical evidence generation. Their strengths are scale, brand recognition and long-term relationships with providers and payers.
- Specialists and regional champions: A cohort of companies focuses on specific clinical segments, accessory portfolios or regional distribution excellence. These firms often compete on service levels, custom-fit solutions and responsiveness to clinician feedback, creating attractive acquisition targets for larger players seeking complementary capabilities.
- New entrants and private-label threats: Channel evolution and supplier consolidation raise the possibility of private-label offerings from large distributors. The risk is most acute in commoditized accessory categories where differentiation is thin and price sensitivity is high.
Key names warranting executive attention in 2026 include a mix of global incumbents and regional specialists. These companies represent the spectrum of strategic approaches in the market — from high-touch system innovation to distribution-led scale. Understanding their product strategies, recent launches, and partner networks will be essential for formulating competitive responses.
Recent developments that change the calculus for 2026
- Policy pressure on procurement: In mid‑2025 CMS proposed reclassification of ostomy supplies in a way that could expose the category to competitive bidding — a structural event that could compress prices and reroute flows to low-cost distributors if enacted. Industry advocacy groups are actively responding, and we quantify the economic impact under alternative policy outcomes.
- Advocacy and patient voice: Patient groups are sharpening their messaging around clinical nuance and the need for individualized coverage — an important counterbalance to procurement-driven cost-squeezing. Expect advocacy to be a decisive factor in shaping final policy language.
- Commercial activity and product messaging: Several manufacturers and distributors refreshed their commercial collateral and product portfolios in late 2025 and early 2026, emphasizing skin-health technologies (including ceramide barriers), improved pouch ergonomics and expanded digital catalogs. These moves signal a shift from product-only competition to integrated patient experience propositions.
What the full PW Consulting report delivers — practical tools for 2026
Our report is intentionally operational. Beyond market sizing and growth projections, it contains tools that executives can apply directly to budgeting, M&A screening, product roadmaps and regulatory planning:
- Segment-level demand models (by product type and clinical application) with sensitivity levers for pricing, reimbursement and adoption curves.
- Scenario analyses for CMS rule outcomes, including detailed P&L impact estimates across channel and customer segments.
- Supplier risk and cost-mitigation playbooks focused on adhesives, hydrocolloid wafers and critical barrier films.
- Competitive benchmarking with capability heatmaps for R&D, regulatory throughput, distribution reach and digital engagement.
- Commercial playbooks that translate clinical evidence into payer value propositions and clinician adoption tactics.
- M&A target shortlists and integration checklists aligned to different strategic arcs (scale, capability, channel).
Note: This preview is calibrated to show the depth and applicability of our analysis while deliberately withholding granular segment-level figures and regional breakdowns that drive transactional decisions. The full dataset and financial models — including disaggregated revenue by product type and application, regional market splits and competitor share tables — are available in the complete report and Excel deliverables.
Practical strategic recommendations for 2026
- Run regulatory scenario war games: Treat the proposed CMS competitive-bidding pathway as a high-probability disruptor. Create adaptive commercial playbooks: one for a status-quo reimbursement environment and one for a bidding-dominated landscape.
- Prioritize adhesive and barrier supply resilience: Map single-source exposure and develop dual-sourcing or qualifying plans for key hydrocolloid and silicone suppliers. Consider inventory strategies that balance working capital and continuity of supply for high-value SKUs.
- Double down on clinical differentiation: Invest in outcomes studies and quality-of-life data that support premium positioning for system-level products, especially where skin integrity and complication avoidance can be quantitatively tied to reduced downstream costs.
- Re-engineer go-to-market economics: Pilot subscription or bundled-service models in select geographies to capture higher lifetime value and predictable demand while testing digital engagement levers.
- Prepare M&A and partnership playbooks: Identify targets that fill capability gaps (e.g., digital patient support, specialized accessories, regional distribution) and design fast-integration playbooks to extract synergies within 12–18 months.
Final note — how to use this preview
Think of this briefing as a strategic trailer: it distills the forces that will shape the ostomy products market in 2026 and highlights the actions that separate winners from laggards. The full PW Consulting market study supplies the granular inputs — segment revenues, regional splits, competitor share tables and downloadable financial models — that are required to convert these strategic priorities into concrete budgets, contracts and product roadmaps.
For companies planning board-level strategy sessions or preparing investor materials for 2026, the full report is designed as a working toolset rather than a static document. Contact PW Consulting to obtain the complete dataset, scenario models and a tailored executive briefing that aligns findings to your organization’s objectives and risk tolerance.
For detailed analysis of this topic, please visit the official page: Ostomy Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com