

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electric Gripper Market to Reach $830.62M by 2032 at 5.5% CAGR

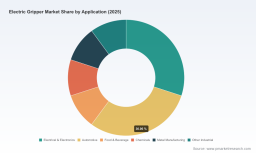
Electric Gripper Market — 2026 Strategic Briefing
As factories and distribution centers accelerate the shift from pneumatic and manual handling to intelligent end-of-arm tooling, the electric gripper market has evolved from a niche automation component into a strategic lever for productivity and resiliency. PW Consulting’s latest market research—anchored on a 2025 base year, historical coverage from 2020–2025 and a forward-looking forecast for 2026–2032—provides the decision-grade analysis executives need to align R&D, procurement, and M&A priorities for the coming three to five years. The market expanded materially through 2020–2025 (from under USD 450 Million to over USD 570 Million) and, at a steady 5.5% CAGR, is projected to move meaningfully toward the high hundreds of millions by 2032. For 2026 planning, this trajectory is as much an opportunity signal as it is a timing imperative.
Electric Gripper Market
Why this study matters for 2026 decisions
-
Timing of capital commitments: A predictable mid-single-digit CAGR creates a window for measured scale investments—firms that invest in adaptable electric gripper platforms now can capture share as cobot and smart-automation adoption accelerates.
Electric Gripper Market -
Portfolio prioritization: The market’s steady growth but concentrated supplier base (top-three firms hold a meaningful plurality of sales, top-five further extend concentration) means competitive advantage will come from product differentiation, system integration, and aftermarket services rather than pure price competition alone.
Electric Gripper Market -
Procurement and supply-chain strategy: Raw-material volatility and modularization trends make supplier consolidation, long-term supplier agreements, and dual-sourcing mandatory elements of any 2026 sourcing playbook.
Market trajectory — what the headline numbers imply
PW Consulting’s topline series tracks how the market rose through 2020–2025 and projects steady expansion across the 2026–2032 forecast window. The combination of rising cobot penetration, energy-efficiency regulations favoring electric systems, and persistent labor shortages is creating a predictable base of demand. That predictability enables scenario-based capital planning: conservative scenarios assume continued retrofit cycles in established factories; aggressive scenarios model faster greenfield automation in logistics and light manufacturing.
Key demand drivers and cost dynamics
-
Automation intensity and cobot adoption: Collaborative robot arms are now a standard channel for electric grippers. This has shifted buyer priorities from raw gripping force toward intelligence (force sensing, adaptive grasping), safety, and simple integration.
-
Regulatory push and safety: Standards for collaborative workplaces require force-limiting and collision detection—features that increase product complexity but also raise switching costs for buyers that prioritize compliance and worker safety.
-
Cost composition: Material and component choices matter. For industrial-grade units, raw-material costs for structural steels and high-performance polymers vary considerably across complexity tiers, and high-force or long-stroke designs materially increase bill of materials (BOM) and final price. Energy-efficiency mandates further tilt TCO in favor of electric grippers versus pneumatic alternatives.
-
Labor-market pressure: High-mix, low-volume manufacturing environments face the steepest pain from labor shortages, accelerating adoption of flexible electric grippers that can be reprogrammed for frequent changeovers.
What PW Consulting’s report delivers (practical outputs)
Beyond narrative analysis, the report is designed as an operational toolkit for teams executing 2026 strategies. Deliverables include:
-
Market-sizing and forecast model (2020–2032) with scenario toggles, sensitivity to unit prices, and adoption curves.
-
Competitive scorecards for leading suppliers, including product architecture mappings, channel footprints, and integration capability assessments.
-
Buyer segmentation framework and decision maps for procurement teams (TCO calculators, payback models, and rebound analysis to compare electric vs. pneumatic solutions).
-
Go-to-market playbooks for OEMs and system integrators, including partner selection criteria and pricing strategies for value-based selling.
-
M&A and partnership screening framework identifying strategic fit, technology gaps, and likely integration risks.
-
Operational checklists (supply-chain risk mitigations, compliance readiness, and after-sales service models) and downloadable templates for immediate use.
Competitive landscape — who matters and why
The vendor ecosystem combines global automation OEMs, cobot-focused innovators, and regionally competitive low-cost manufacturers. Market concentration is meaningful—leading firms hold a large share of the market’s value—so incumbents set standards for interoperability and safety while challengers compete on integration speed, affordability, and niche specialization.
-
Global OEMs (examples: SMC Corporation, SCHUNK, Festo): These players compete on breadth of portfolio, integration with factory automation systems, and long-standing distributor networks. For 2026, their competitive edge will rest on modular, easily programmable gripper families that simplify system-level integration and reduce total installation time.
-
Cobot-native suppliers (examples: OnRobot, Robotiq, HIWIN): These firms focus on rapid deployment, plug-and-play compatibility with major collaborative robot arms, and developer-friendly APIs. Product launches in 2025 (notably several high-payload and miniature force-sensing grippers) demonstrate a continued race to broaden the use-case envelope.
-
Regional and cost leaders (examples: China-based DH-Robotics, HITBOT, TallMan): These vendors compete on price and rapid iteration; they are most relevant in price-sensitive segments and for large-scale rollouts where basic functionality is sufficient.
Notable 2025 product activity reinforces competitive dynamics: announcements of new high-payload and miniature force-sensing products from multiple vendors indicate both product diversification and commoditization at different tiers. Strategic moves by niche and established suppliers alike suggest 2026 will be a year of increased platform competition and partnership consolidation.
Strategic implications for executives (2026 playbook)
-
Prioritize modularity: Invest in or procure gripper platforms that support software-upgradable features (force sensing, expanded I/O) to protect against obsolescence and speed deployment cycles.
-
Negotiate TCO-based contracts: Move away from unit-price procurement to performance- and uptime-linked contracts that reflect energy savings, reduced labor costs, and maintenance efficiencies.
-
Lock in supply resilience: Establish multi-tier sourcing for key mechanical components and negotiate long-term supply agreements for critical polymers and actuators to buffer raw-material cost volatility.
-
Accelerate integration capability: For OEMs and integrators, develop certified integration stacks for dominant cobot arms and provide turn-key kits that shorten installation time—this is where premium pricing is defensible.
-
Scan for M&A and partnerships: Seek bolt-on acquisitions that add force-sensing, vision-guided gripping, or advanced control IP; for system integrators, partner with regionally strong low-cost manufacturers to hedge price-sensitive opportunities.
Risk matrix — what to watch in 2026
-
Regulatory shifts increasing compliance costs (safety or energy mandates).
-
Rapid commoditization of basic electric grippers leading to margin compression in lower tiers.
-
Supply-chain disruptions for specialty materials that impact lead times for high-complexity units.
-
Integration inertia at customer sites—lack of skilled integrators can slow adoption despite strong product value.
Immediate next steps for executive teams
-
For procurement: Run the report’s TCO calculator against current contracts and target a 12–18 month renegotiation window where energy and uptime metrics form compensation levers.
-
For product leaders: Map your roadmap against the report’s capability tiers and prioritize force-sensing and software-defined features for the next product release.
-
For corporate development: Use the M&A screening matrix to shortlist targets that fill control-layer or sensing gaps (target list available in the full report).
-
For operations: Begin pilot deployments in high-mix lines where payback is shortest; capture real-world ROI data to build the internal case for scale-up during 2026.
PW Consulting’s Electric Gripper Market study is structured to be immediately actionable: it pairs a transparent, model-driven market forecast (2020–2032) with practical tools, supplier scorecards, and integration playbooks. To preserve the strategic value of granular segmentation and company-level scorecards, detailed breakouts—regional and application split tables, unit-price ladders, and company share matrices—are provided in the full deliverable available on our site. For teams preparing 2026 budgets and strategic roadmaps, the report is both a compass and a set of ready-to-use instruments for execution.
For detailed analysis of this topic, please visit the official page: Electric Gripper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com