

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Security Control Room Market to Reach USD 10.26B in 2025; 6.2% CAGR to 2032
By pmarketresearch, 2026-07-13
Security Control Room Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As enterprises and critical infrastructure operators plan capital and operational programs for 2026, the Security Control Room market presents a familiar paradox: steady, predictable expansion on the surface, and accelerating technical and organizational complexity beneath. PW Consulting’s forthcoming in-depth market study — grounded in a 2025 base year and projecting through 2032 — synthesizes historical performance (2020–2025), forward-looking scenarios (2026–2032), and practical tools for decision-makers who must balance resilience, cost, and operational excellence.
Security Control Room Market
Market trajectory at a glance
The market’s multi-year trend shows steady growth from the start of the decade and into the mid-2020s, with a compound annual growth rate of approximately 6.2% through the forecast horizon. In nominal terms the industry reaches just over USD 10 billion in the 2025 base year and is projected to continue expanding toward mid-decade targets and beyond, driven by continuous demand for higher-fidelity situational awareness, integrated OT/IT security tooling, and enterprise-grade monitoring centers.
Security Control Room Market
Two implications are immediate for 2026 planning cycles. First, the market is large enough to sustain multiple competing models — from fully integrated vendor suites to specialist component suppliers and systems integrators — which makes vendor selection a strategic decision rather than a commoditized procurement exercise. Second, while growth is predictable, it is not frictionless: rising expectations around real-time analytics, redundancy, and regulatory compliance introduce cost and complexity that must be modeled explicitly in capital budgeting and vendor contracts.
Security Control Room Market
Why PW Consulting’s study matters to executives in 2026
- Actionable TCO and investment scenarios: We translate market growth and segment dynamics into multi-year total cost of ownership (TCO) models that help justify or challenge capital approval requests for control room modernizations.
- Procurement and vendor-play playbooks: The study provides structured approaches to tender design, supplier shortlisting, and staged implementation — critical when procurement must balance uptime guarantees, cybersecurity SLAs, and lifecycle refresh cycles.
- Risk-to-reward frameworks: Executives receive scenario-based risk matrices that map investment choices to resilience outcomes (e.g., hybrid on-premises vs. managed SOC arrangements), enabling faster but more informed governance decisions.
Core market dynamics shaping decisions in 2026
Four interdependent forces will govern near-term outcomes:
- Technology consolidation with point-solution specialization: Hardware, software and services continue to evolve along different time horizons. Control-room hardware investments (video walls, sensor arrays, resilient networking and displays) remain capital-intensive, while software capabilities (analytics, automation, digital twins) enable operational leverage. Services — from 24/7 SOC staffing to system integration — complete the value chain but require continuous talent investment.
- Operational resilience and energy/infra costs: Continuous operations impose non-trivial energy and facilities demands. Redundancy in power, network and cooling is non-negotiable for mission-critical operations and should be treated as part of the system design rather than an add-on.
- Regulatory and data control preferences: For many government, defense and critical infrastructure customers, on-premises deployments remain the preferred baseline due to latency, data sovereignty and auditability concerns. Hybrid architectures are emerging as an optimization, but they require explicit controls and validated trust boundaries.
- Market concentration and partner ecosystems: The market exhibits a moderate degree of concentration among leading platform and services providers, which has implications for negotiation leverage, interoperability risks, and M&A dynamics. Buyers should balance the benefits of deep vendor ecosystems against the risks of supplier lock-in.
Competitive landscape — what to watch in 2026
Our competitive analysis profiles leading suppliers that influence both technology roadmaps and procurement behaviors. Each vendor brings a distinct strategic posture customers should evaluate against their own risk and capability requirements:
- Honeywell: Positioned as a provider of industrial-grade security operations and control-room technologies, Honeywell pairs OT-focused SOC capabilities with command-center products that integrate fire, audio evacuation and industrial monitoring. Recent platform-level innovation — including a digital twin capability introduced mid-2025 — highlights a push toward safer change-management and simulated testing before live rollouts.
- Johnson Controls: Emphasizes a global SOC services model with standardized incident protocols, risk-based prioritization and regulatory-compliance support. Their approach is attractive to organizations seeking outsourced operations with enterprise SLAs and multi-jurisdictional staffing coverage.
- Schneider Electric: Focuses on staffed SOC operations and incident triage for continuous monitoring. Their strength lies in operational continuity and energy-aware building integration for control room environments.
- IHSE: Specializes in critical-environment KVM-over-fiber solutions that address latency, display fidelity and secure signal delivery — often an essential component in control rooms where visual continuity is paramount.
- Siemens: Brings integrated IT/OT SOC solutions and strategic partnerships to the table, enabling proactive threat management in industrial settings. Collaborations with global consultancies expand their delivery footprint for complex industrial customers.
Tactical takeaways: suppliers are differentiating along three axes — OT/IT security integration, managed operations and specialist hardware for mission-critical visualization. For buyers, the practical question is which axis best aligns with the organization’s risk profile, staffing model, and regulatory obligations.
Practical content in the PW Consulting study — what’s inside
This research is designed for decision-makers and program owners who must move from strategy to execution. The report packages include:
- Scenario-driven demand models and forecast sensitivities that map investment outcomes to market and technology shifts.
- Vendor scorecards and capability matrices tailored for procurement, compliance and operations teams.
- Implementation playbooks — covering procurement SOWs, integration sequencing, test plans, and runbook templates for incident response and business continuity.
- Detailed TCO templates and procurement negotiation checklists to uncover lifecycle costs beyond initial equipment purchase.
- Regulatory and standards alignment guidance to streamline audits and cross-border deployments.
Importantly, the report focuses on operational applicability: downloadable Excel models, vendor evaluation rubrics and phased deployment timelines are included so teams can go from read-to-action in weeks rather than months.
How to convert insight into decisive action for 2026
We recommend a three-track approach for executives planning control room investments in 2026:
- Clarify mission profiles and risk tolerance: Establish whether the control room’s priority is operational continuity, regulatory compliance, rapid threat response, or a blend. This determines whether to emphasize on-premises redundancy, managed SOC services, or investment in digital-twin validation capabilities.
- Adopt modular modernization with gated investments: Prioritize projects that deliver measurable uplift (e.g., faster detection-to-response times) and stage larger capital commitments behind proof-of-concept and interoperability tests. Treat display/hardware refresh, network resilience, and analytics integration as separable workstreams with defined success metrics.
- Negotiate for openness and escape clauses: Given moderate market concentration, procurement should insist on interoperability, data portability and clear exit provisions. Include performance-based SLAs and periodic capability re-assessments tied to vendor roadmaps.
Risks and unknowns to monitor
Key uncertainties that should shape governance in 2026 include the speed of cloud adoption for SOC functions (which will vary by jurisdiction and sector), the availability of specialized integration talent, and energy/regulatory cost dynamics that materially affect operating expenditures. PW Consulting’s sensitivity scenarios explore these inflection points and provide contingency paths for both conservative and aggressive adopters.
Why this preview — and what it does not reveal
This article highlights strategic conclusions and actionable frameworks from PW Consulting’s Security Control Room Market study but intentionally omits granular segmentation tables and vendor-level revenue splits that many organizations use to refine procurement and M&A strategies. Those detailed matrices — including regional heatmaps, application breakdowns and vendor financials — are available in the full report and accompanying data package for subscribers and purchasers.
Next steps for leaders
If you are responsible for capital planning, security operations, or critical infrastructure resilience in 2026, consider the following immediate steps:
- Commission a short diagnostic using PW Consulting’s readiness checklist to validate current control-room capabilities against near-term risk scenarios.
- Run a focused pilot that pairs a digital-twin validation of change control with a managed SOC overlay; measure time-to-detect and mean-time-to-recovery as primary KPIs.
- Engage procurement and legal early to codify interoperability and data-portability clauses in vendor contracts.
For readers who need the full segmentation, vendor scorecards, and downloadable models referenced here, PW Consulting’s complete Security Control Room Market study provides the necessary depth to convert this preview into a project-ready plan. Visit our research page to access the full report, Excel workbooks, and an executive briefing tailored to your sector.
For detailed analysis of this topic, please visit the official page: Security Control Room Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water Delivery Market to hit USD 216.6M by 2032 (5.2% CAGR)
By pmarketresearch, 2026-07-13
Water Delivery Service Market: Strategic Outlook for 2026 — A PW Consulting Preview
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise yet forward-looking preview of our flagship Water Delivery Service Market study — a practical, decision-grade research product designed to inform boardrooms, private equity teams, and corporate strategy functions as they prepare plans and capital allocations for 2026. This preview highlights the study’s strategic value, the primary market dynamics we observed, and the competitive and regulatory inflection points that will shape winners and losers over the next planning cycle.
Water Delivery Service Market
Why this study matters for 2026 decisions
In an industry characterized by operational intensity, low technological differentiation, and increasing environmental scrutiny, timing and precision in strategy execution are everything. Our market model — calibrated to a 2025 base year — shows the global Water Delivery Service market at approximately USD 151.8 Million (base year 2025), following a recovery and acceleration path from the 2020–2025 period. Under our central scenario the market expands at a compound annual growth rate (CAGR) of 5.2% over the 2026–2032 forecast window, reaching roughly USD 216.6 Million by 2032. These headline metrics are not merely descriptive: they define the envelope for addressable demand, capital deployment cadence, and scale economics that will validate or invalidate strategic initiatives in the immediate term.
Water Delivery Service Market
For executives evaluating near-term moves — whether it’s fleet electrification, automated warehousing, pricing reengineering, or M&A — the 2026 planning horizon is pivotal. In many cases the projects greenlit this year will determine incremental margins through 2030 and beyond. The study equips decision-makers with the scenario analyses, unit economics, and risk-adjusted investment cases they need to prioritize with confidence.
Water Delivery Service Market
Key market dynamics shaping 2026 strategy
- Operational automation and labor economics: Warehouse robotics and automated guided vehicles (AGVs) are already demonstrating measurable labor cost reductions and delivery efficiency gains. Our synthesis of industry data indicates automation deployments can reduce direct labor spend by double-digit percentages while improving last-mile productivity. For companies with dense urban routes, the calculus of retrofitting depots and redesigning workflows becomes compelling in 2026.
- Sustainability as a commercial lever: Growing regulatory scrutiny and activist pressure are forcing providers to invest in sustainable packaging, circular refill models, and lower-emission delivery fleets. These investments are increasingly linked to customer retention and enterprise contracts; in several bids we analyzed, sustainability credentials were a clear tie-breaker.
- Cost sensitivity and value capture: High service costs — driven by logistics complexity and the premium nature of certain water products — continue to deter price-sensitive household segments. Providers will need to balance premium offerings with lower-cost, high-frequency delivery options to broaden penetration without compressing margins.
- Regulatory accelerants: New water-safety standards in key markets are raising infrastructure compliance requirements. These impose both cost and opportunity: while retrofit and certification costs rise, certified providers gain competitive advantage in procurement for institutional customers.
Taken together, these dynamics create a bifurcated landscape in 2026: operators that aggressively adopt automation and demonstrate credible sustainability will expand share and margin; those that maintain legacy models risk margin erosion or forced consolidation.
Report contents — practical deliverables for immediate action
Our full report is structured to convert insight into action. Major deliverables include:
- Proprietary market model (2020–2032): granular, transparent assumptions and downloadable scenario outputs that let teams stress-test revenue and capex plans under alternative demand, price, and cost trajectories.
- Unit-economics playbook: route-level profitability calculators, sensitivity analyses on fuel/energy and labor, and benchmark KPIs for CAC (customer acquisition cost), churn, lifetime value, and fleet utilization.
- Investment decision support: NPV/IRR templates, break-even analyses for automation and electrification investments, and prioritization frameworks for capex deployment across hubs and routes.
- Go-to-market and pricing frameworks: segmentation-based offer design (household vs. commercial), bundling strategies, and playbooks for converting retail members into recurring delivery subscribers.
- Regulatory and sustainability roadmap: stepwise compliance checklists, TCO implications of circular packaging and refill stations, and supplier partner evaluation criteria.
- Competitor intelligence matrix: capability maps, likely strategic moves, and M&A heatmaps focused on acquirers, targets, and disruptors.
Each module is grounded in primary-sourced interviews, operational benchmarking, and a transparent assumptions log so clients can adapt the model to their internal data while preserving comparability to the PW Consulting baseline.
Competitive landscape — what the majors are signaling for 2026
The market remains fragmented — our concentration analysis shows a low top-three and top-five share footprint, underscoring the room for both regional specialists and national consolidators. That fragmentation creates attractive pockets for disciplined scale plays and capability-driven roll-ups.
- Primo Brands Corporation (Winston-Salem, NC): A leading North American operator, Primo’s recent roll-out of urban eco-friendly refill stations signals a pivot toward circular models and retail-adjacent touchpoints. For competitors, Primo’s move underscores the commercial potential of blending delivery with decentralized refill networks to reduce single-use packaging exposure.
- Culligan International Company (Rosemont, IL): Culligan’s integrated offering — pairing dispenser services with water treatment and softening — highlights a durable cross-sell strategy that improves retention and ARPU in commercial accounts. Expect similar service bundling to be a defensive priority for regional players aiming to protect midsize enterprise contracts.
- Absopure Water Company (Plymouth, MI): As a strong regional provider with a focus on natural spring and purified products, Absopure exemplifies the value of localized sourcing and brand trust in the household segment. Their model remains instructive for operators seeking to deepen regional loyalty while optimizing delivery density.
- Danone Waters of America Inc.: Danone’s selective market play through partnerships and direct channels demonstrates how global CPG players can leverage brand strength and supply-chain scale without deploying full-fledged delivery networks in every locale. Partnership-driven expansion is a near-term strategic lever for companies looking to enter new geographies with constrained capex.
- Costco Wholesale Corporation: Costco’s member-centric delivery offers exemplify an alternative route-to-market: leveraging an embedded membership base to distribute water delivery and dispenser units, thereby compressing CAC and accessing high-retention households and small offices.
Recent developments — from Primo’s eco-station roll-out to Nestlé’s partnership for AI routing in Europe, and regulatory tightening in Australia — illustrate three interlocking themes: operational optimization, platform and partnership plays, and compliance-driven capex. These are the vectors that will separate compounding gains from stagnation in 2026.
How to use the study in your 2026 planning cycle
- Prioritize automation where density supports payback: Use our route-level calculators to identify depots and corridors where robotics, AGVs, and smart routing deliver real break-even within typical investment horizons.
- Convert sustainability into revenue protection: Model the TCO of refill networks and recycled packaging to quantify retention and bid-winning advantages in institutional RFPs.
- Test partnership-led expansion: For entrants or firms with capital constraints, the report’s partnership frameworks provide a staged path to geographic expansion without owning every leg of the logistics chain.
- Design for segmentation-driven pricing: Our pricing playbooks enable you to design offers that preserve margins on premium water types while opening lower-cost, high-frequency channels for price-sensitive households.
- Build an M&A heatmap: With fragmentation and modest incumbent concentration, consolidation remains a viable route to scale. The report’s target criteria and accretion models help identify high-value tuck-ins and defensive buys.
What this preview does — and does not — offer
This executive preview is intentionally curated to demonstrate the analytical depth and practical orientation of the full PW Consulting study. It surfaces overarching market size, growth trajectory, and the strategic implications that matter for 2026 decisions. In keeping with our “trailer” approach, we intentionally withhold detailed segment-level splits, route-level unit economics, and the full set of proprietary forecasts that are available in the complete report and interactive model. These deliverables contain the granular inputs and downloadable templates that teams will use to finalize budgets, capex proposals, and M&A decks.
Next steps — for strategy teams and investors
For companies and investors moving from strategic hypothesis to commitment in 2026, we recommend three immediate actions:
- Acquire the full PW Consulting Water Delivery Service Market package (model + playbooks) to run bespoke scenario stress tests tied to your route and customer data;
- Run a fast-track pilot in one high-density corridor combining automated warehousing, AI routing, and a circular packaging trial to validate unit-economics improvements;
- Map potential partnerships and tuck-in targets using our M&A heatmaps to accelerate scale while preserving capital flexibility.
To access the full dataset, interactive model, and downloadable playbooks that underpin these conclusions, please visit our report landing page. PW Consulting’s analysts stand ready to run custom workshops and model calibrations tailored to your operating footprint and capex constraints.
Prepared by: PW Consulting — Senior Strategic Advisor & Chief Industry Analyst.
For detailed analysis of this topic, please visit the official page: Water Delivery Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Magnetic Beads Market to Grow at 11.8% CAGR Through 2032 — PW Consulting
By pmarketresearch, 2026-07-13
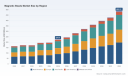
Magnetic Beads Market — Strategic Outlook for 2026 Decisions
Executive snapshot
The magnetic beads market is entering a phase of accelerated commercialisation and structural transition. From a 2025 base-year valuation of approximately USD 224.6 Million, the market is projected to grow at a compound annual growth rate (CAGR) of roughly 11.8% over the 2026–2032 forecast horizon, reaching an expected market size in the high hundreds of millions of USD by 2032. Historical momentum (2020–2025) indicates an established recovery and reorientation following pandemic-related disruptions; forward growth will be shaped as much by application-driven demand (life‑science workflows, diagnostic and separation platforms) as by cross‑industry dynamics (electronics component supply chains and raw‑material inflation).
Magnetic Beads Market
Why this report matters to 2026 planning
For executives preparing 2026 budgets, sourcing strategies and R&D roadmaps, the magnetic beads market represents a compact but highly strategic arena. It sits at the intersection of two important value chains: bioprocessing and diagnostics on one side, and electronic component manufacture on the other. That intersection produces distinctive opportunities (new detection workflows, automated sample prep, hybrid device architectures) and distinctive risks (raw-material price shocks; supplier concentration). Our study frames these forces in business-relevant terms so leaders can prioritise capital allocation, supplier engagement and product development through 2026 and beyond.
Magnetic Beads Market
Market trajectory: what the headline numbers tell you
-
Mid‑decade momentum: The market recorded consistent expansion from 2020 to 2025, moving from a modest base into stronger commercial adoption and investment. The 2025 base of ~USD 224.6 Million provides a reliable pivot for near‑term planning.
Magnetic Beads Market -
Fast forward to 2032: Under the central forecast, the market approximately doubles from the 2025 base to approach USD 485.5 Million by 2032—an outcome driven by both volume adoption in established workflows and higher‑value product introductions tied to automation, single‑cell and molecular assays.
-
Concentration and competitive implications: Market concentration is moderate; the largest three players control a meaningful share of industry revenues while the top five consolidate the market further (CR3 ≈ 38.2%, CR5 ≈ 62.4%). This balance creates opportunities for mid‑tier challengers to capture niche or value‑added positions while reminding purchasers that supplier disruption could propagate quickly through the supply chain.
Key demand drivers and structural headwinds
-
Application diversification: Demand is being pulled by both established separation workflows and emergent analytical uses (e.g., exosome analysis, rapid IVD assay development). Adoption of beads in automated NGS and immunoassay workflows is a particular high‑growth vector.
-
Automation and throughput: Shorter product cycles and increasing throughput requirements in electronics and life sciences alike place a premium on bead uniformity, surface chemistry precision and compatibility with robotic handling.
-
Raw‑material volatility: Input cost swings—illustrated by sharp movements in materials that feed into ferrite and multilayer chip production—are already affecting pricing strategies across the supplier base. Such volatility translates directly into procurement risk for both electronics‑ and bio‑oriented buyers.
-
Regulatory and sourcing shifts: Announcements of list‑price increases from major component manufacturers and the prospect of further region‑specific pricing adjustments force global sourcing teams to revisit supplier networks and hedging approaches in 2026.
Competitive landscape — structure and strategic postures
The competitive map for “magnetic beads” in 2026 is multi‑layered. Our analysis distinguishes two overlapping supplier archetypes:
-
Life‑science specialists: Companies focused on polymer‑ or iron‑oxide‑based particles with bespoke surface chemistries, automation compatibility and application‑centric validation. Recent product launches targeting automated NGS and affinity‑ligand capabilities are emblematic of this cohort’s strategy: expand technical differentiation and embed sales into instrument OEM workflows.
-
Component and ferrite suppliers: Established electromechanical component manufacturers (including several Asia‑based multilayer and ferrite specialists, and long‑standing Japanese and North American players) whose product families and manufacturing ecosystems overlap materially with bead and bead‑like products in the electronics domain. For these players, cost pressures from raw materials and shifts in downstream demand (for EVs, high‑density electronics) drive both price actions and portfolio prioritisation.
Between these groups sits an active middle: regional Chinese and Taiwanese manufacturers that leverage high‑volume production and competitive pricing to serve broad OEM and distribution channels. Strategic movement in 2024–2026 shows consolidation of higher‑value product lines among life‑science specialists and cost rationalisations among component manufacturers—creating both partnership opportunities and competitive tensions for buyers and investors.
Recent developments that will shape 2026 decisions
-
Pricing moves by component manufacturers: Late‑2025 and early‑2026 price notices from prominent component manufacturers signalled upward pressure across inductors and bead families. For procurement leaders this means revisiting cost baselines and considering contract re‑negotiations or alternative sourcing strategies in 2026.
-
Targeted product launches: In early 2026, automation‑friendly particle platforms and affinity‑ligand innovations were announced that materially improve integration into high‑throughput single‑cell and epigenomic workflows. These launches accelerate adoption cycles in labs that prioritise automation and closed‑system processing.
-
Supply‑chain rhythm: Faster dev‑to‑market expectations in electronics are shortening acceptable lead times across the board. Buyers should expect suppliers to push for longer‑term commitments in exchange for capacity guarantees or priority allocation.
What our full report delivers (practical use cases)
PW Consulting’s full study is designed as an operational toolkit for strategic decision‑makers. Highlights include:
-
Transparent market sizing and scenario forecasts (base year 2025; historical 2020–2025; outlook 2026–2032) that support budgeting and revenue target setting.
-
Actionable segmentation analysis (type, application, region) with use‑case driven demand assumptions — presented so procurement, R&D and commercial teams can map investments to expected return horizons.
-
Supplier benchmarking and capability matrices enabling rapid short‑listing and negotiation playbooks.
-
Price‑impact models and procurement mitigation strategies that quantify the P&L sensitivity to raw‑material and list‑price shifts.
-
M&A and partnership opportunity scans with heuristic valuation levers for vertical integration or technology licence plays.
We intentionally present segmentation and granular supplier share tables behind the paywall to ensure that subscribers receive the detailed numeric splits needed to operationalise these recommendations. The executive narrative here is sufficient to inform strategy, while the full datasets enable tactical execution.
Strategic recommendations for 2026
-
Prioritise dual sourcing for critical inputs. Given input price volatility and concentration among top suppliers, organisations should identify alternative qualified vendors and create flexible allocation mechanisms that can be invoked if list‑price adjustments or capacity constraints emerge.
-
Accelerate integration with automations teams. New particle chemistries and automation‑friendly formats will differentiate winners in diagnostics and high‑throughput genomics; cross‑functional pilots with OEMs should be fast‑tracked in 2026.
-
hedge pricing exposure selectively. Use a mix of fixed‑price contracts for critical volumes and indexed agreements where appropriate to balance protection and flexibility.
-
Monitor and model regulatory shifts and regional pricing announcements. Japanese and other regional list‑price changes have global sourcing implications—scenario plans should be updated quarterly.
-
Consider targeted partnerships or minority investments. For firms seeking rapid capability upgrades (e.g., affinity ligands, single‑cell compatible beads), partnership can be a faster route than in‑house development.
How to use this insight now
For 2026 planning cycles, use our headline findings to: (1) set conservative revenue and procurement baselines that incorporate potential list‑price increases; (2) prioritise product projects that link directly to automation and high‑value analytical use cases; and (3) activate supplier contingency plans for any upward pricing shocks. If you require immediate tactical outputs, ask our team for the supplier benchmarking module and the procurement mitigation spreadsheet that model the P&L impact of the most likely raw‑material shock scenarios.
Concluding perspective
The magnetic beads space is compact but strategically dense: modest headline revenues today, sizable upside in the decade ahead, and a market architecture that rewards technical differentiation and supply‑chain foresight. For 2026, leaders who blend short‑term procurement resilience with medium‑term product differentiation will capture outsized value. PW Consulting’s full report provides the granular splits, supplier scores and scenario models that translate this strategic lens into executable actions—visit the publication page to access the complete datasets and operational playbooks.
For detailed analysis of this topic, please visit the official page: Magnetic Beads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LDS Resin Market to reach USD 1,155.46M by 2032, up from USD 488.89M (11.3% CAGR)
By pmarketresearch, 2026-07-13
Laser Direct Structuring (LDS) Grade Resin Market — Strategic Briefing for 2026 Decision-Making
As companies plan capital allocation, product roadmaps, and commercial strategies in 2026, Laser Direct Structuring (LDS) grade resins are rapidly moving from a niche enabler into a strategic materials category. The LDS resin market has shown robust expansion through the mid-2020s and is entering a phase where material selection, supplier alignment, and process integration will materially affect time-to-market, cost, and differentiation for electronics, automotive, and industrial customers.
Laser Direct Structuring (LDS) Grade Resin Market
Market Trajectory — What the headline numbers mean for strategy
Between 2020 and 2025 the global LDS-grade resin market moved from roughly USD 265 million to nearly USD 489 million (base year 2025), reflecting accelerating adoption across antenna, connector, and mixed electronics use cases. Looking ahead, our forecast for the 2026–2032 period anticipates sustained expansion at a compound annual growth rate (CAGR) of 11.3%, taking the market into the order of USD 1.15 billion by 2032. This profile signals a market that is large enough to attract continued upstream investment yet still in a consolidating phase where supplier selection and technical partnerships matter.
Laser Direct Structuring (LDS) Grade Resin Market
For executive teams, the implications are straightforward: decisions made in 2026 about qualification, tooling, and supplier contracts will compound as the market scales. Early positioning with the right resin platforms and process partners will yield asymmetric returns as LDS moves from prototyping into higher-volume applications.
Laser Direct Structuring (LDS) Grade Resin Market
Why 2026 is a strategic inflection point
- From prototyping to volume: Many OEMs have successfully validated LDS-enabled designs; the next step is industrializing those designs at scale. That shift exposes thermoforming, molding, and plating tolerances that are often underestimated early in development.
- Platform bets matter: Choosing base polymer families and compatible compounders now determines mechanical/thermal limits, plating performance, and recyclability profiles for the product lifecycle.
- Supplier capture and lock-in: With market concentration moderately high among the top players, early commercial agreements and co-development programs create meaningful switching costs and supply security.
- Regulatory and sustainability expectations: Brand owners face growing pressure to demonstrate responsible material sourcing and lower lifecycle impacts. Bio-based and recyclable LDS options are moving from R&D into commercial availability.
Competitive landscape — how incumbent and emerging suppliers are evolving
The supplier base includes global petrochemical majors, regional compounders, and specialty polymer houses. Market concentration metrics indicate that the top three players control a meaningful share of the market, while the top five broaden that footprint—an environment that supports both strategic collaboration and selective vertical integration.
- SABIC (Riyadh) — Expanding its LDS-dedicated LNP™ and ELCRIN™ portfolios, SABIC’s recent catalog refreshes emphasize grades tailored to 5G and automotive needs, highlighting processing latitude and chemical resistance for harsh environments.
- RTP Company (Winona, MN) — Focused on custom-engineered thermoplastic compounds, RTP is extending PC/ABS and reinforced families for platable resin applications, addressing OEMs seeking tailored performance and rapid qualification.
- DSM (Heerlen) — Moving bio-based chemistries toward LDS readiness, DSM’s ForTii® Eco LDS grades underline the market’s evolving sustainability vector, particularly for consumer electronics and security casings.
- Kingfa (Guangzhou) — Regional scale with targeted LDS PC/ABS compounds positions Kingfa to serve high-volume manufacture where proximity and cost matter.
- Other notable players: LG Chem, Lucky Enpla, Celanese, Ensinger, Teijin, Zeon, Lanxess, and Evonik are each advancing portfolio or process fitments that address specific temperature, dimensional stability, or plating compatibility requirements.
Across these incumbents, 2024–2025 activity focused on portfolio expansions and spec-aligned launches. Examples include new LDS variants optimized for LPKF process specifications, bio-based LDS grades with improved ductility, and reinforced PC/ABS compounds designed for platable surface finishes. These moves lower barriers to application adoption while raising the technical bar for marginal suppliers.
What we cover in the full study — actionable intelligence you can operationalize
Our market study is built to support commercial, technical, and M&A decisions. The full report provides:
- Top-down and bottom-up market sizing with historical validation and a detailed 2026–2032 forecast model.
- Demand-driver analysis across antennas, connectors and adjacent electronics applications, including adoption levers and constraint mapping.
- Supplier benchmarking and a vendor scorecard that combines technical fit, capacity, geographic reach, and innovation velocity.
- Process compatibility matrix linking polymer classes and compound families to laser parameters, plating outcomes, and in-line quality checkpoints.
- Scenario-based supply chain stress tests and an investment model for molding/capacity expansions under different adoption curves.
- Regulatory and sustainability risk assessments paired with transition roadmaps to bio-based and recyclable LDS material systems.
- M&A and partnership playbooks: target screens, valuation sensitivities, and integration risk frameworks specific to resin and compound manufacturers.
To preserve competitive advantage for clients, the report selectively withholds certain granular segmentation tables and supplier-specific revenue disclosures behind client access. This is intentional: the summary enables strategic planning, while the full data set provides the executable inputs buyers and investors need to act with conviction.
Practical recommendations for executives in 2026
- Short-term (0–12 months): Begin dual-track qualification—select at least two resin platforms (one incumbent supplier, one alternative) to mitigate supply risk and validate process window variability at production-representative conditions.
- Mid-term (12–24 months): Lock in co-development or long-term supply agreements that include yield targets, pricing collars, and joint troubleshooting cadences. Use these to secure preferential access to new LDS grades as they reach commercialization.
- Long-term (24–60 months): Evaluate backward integration or strategic equity in specialty compounders only when a clear volume ramp justifies capital intensity. Prioritize flexible contracts and modular tooling to avoid over-exposure to a single polymer family.
- Sustainability action: Integrate lifecycle criteria into resin selection, and demand transparency from compounders about feedstock origin and end-of-life options—this is increasingly a procurement differentiator with major OEMs.
Risks to monitor
- Technology risk: Laser process parameter evolution can change material performance expectations faster than OEM qualification cycles.
- Supply risk: Concentration among top suppliers creates exposure to capacity constraints and lead-time expansion during volume ramps.
- Regulatory risk: Evolving chemical regulations and end-of-life mandates may force reformulation or relining of qualified parts.
- Commercial risk: Poorly structured supplier agreements can lock buyers into suboptimal cost or quality profiles as new grades improve performance.
Why PW Consulting — and next steps
Our study blends polymer science translation with commercial strategy: we map laser-material interactions to supply chain realities and provide pragmatic roadmaps for supplier engagement, qualification programs, and investment timing. The market’s projected CAGR of 11.3% across the 2026–2032 forecast window makes this a material strategic decision for Electronics and Automotive executives alike.
If your team is preparing procurement, product, or investment decisions in 2026, use the high-level insights in this briefing to orient internal stakeholders. For the full dataset, interactive models, and vendor scorecards (including the withheld granular segmentation and supplier revenue analytics), access PW Consulting’s complete LDS Grade Resin Market report—those assets convert strategic intent into executable plans.
For detailed analysis of this topic, please visit the official page: Laser Direct Structuring (LDS) Grade Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Imaging Colorimeters Market to Hit USD 797.44M by 2032 at 6.95% CAGR
By pmarketresearch, 2026-07-13
Imaging Colorimeters Market: Strategic Insights for 2026 Decision-Makers
Executive summary
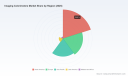
Between 2020 and 2025 the global imaging colorimeters market expanded steadily, rising from USD 358.01 Million in 2020 to USD 496.38 Million in our 2025 base year. Our forecast projects continued expansion through the 2026–2032 horizon, reaching an estimated USD 797.44 Million by 2032 at a compound annual growth rate (CAGR) of 6.95%. Despite this healthy topline trajectory, the market remains relatively unconsolidated — the leading three and five suppliers together account for a modest share of industry revenue, reflecting a landscape where technological specialization, channel diversity and application-specific requirements drive customer choice.
Imaging Colorimeters Market
Why this report matters for decisions made in 2026
- Capital allocation: manufacturers and OEMs evaluating next-wave production investments need an empirically grounded demand forecast and scenario analysis to justify automation and quality-test stations.
- Product strategy: vendors prioritizing spectral-integration, higher spatial resolution, or portable devices require validated roadmaps for R&D spend and go-to-market sequencing.
- Supply chain and procurement: sensor supply (CCD/CMOS) economics and vendor diversification are material to cost and lead-time risk; component-level dynamics must be quantified when negotiating multi-year agreements.
- Regulatory and certification readiness: compliance with laboratory and color-management standards influences certification timelines and market access across display, lighting and medical segments.
- M&A and partnership screening: corporates and PE firms seeking bolt-ons or white-label opportunities must distinguish which niche capabilities actually translate into defensible margins and defensible customer contracts.
What the PW Consulting report delivers (practical scope)
This research is structured to support rapid, actionable decision-making in 2026. Key operational deliverables include:
Imaging Colorimeters Market
- Integrated market model (2020–2032): base-year calibration, alternate scenarios (conservative, baseline, upside) and sensitivity to display-cycle and automotive demand drivers.
- Demand-driver decomposition: quantitative mapping of end-market pull (display manufacturing, surface inspection, automotive, laboratory/R&D) and technology shifts that alter testing modalities.
- Supplier intelligence and scorecards: capability matrices, product roadmaps, compliance posture, channel reach and manufacturing footprints for incumbent and emerging vendors.
- Component cost and procurement playbook: bill-of-materials impact analysis and supplier risk heatmaps — including CCD/CMOS sensor cost ranges and the leverage points for negotiation.
- Factory integration guide: recommended architectures for inline/at-line test stations, software integration patterns for 24/7 automated operation, and validation templates for high-volume lines.
- Regulatory and lab-compliance checklist: practical steps to secure ISO 17025 accreditation and align display testing with relevant IEC standards for medical and safety-critical devices.
- Commercial strategies: price positioning, warranty and service models, and channel strategies for OEM, system integrator and lab segments.
- M&A and technology scouting dossiers: prioritized target lists, valuation benchmarks and integration risks for bolt-on opportunities in optics, software and sensor subsystems.
- Data pack and dashboards: downloadable datasets, model files and interactive visualizations for internal scenario workshops.
Competitive landscape — what to watch in 2026
The market is shaped by specialist vendors that combine optical hardware, imaging sensors and software intelligence into distinct value propositions. Key strategic positions and near-term moves we profile in the report include:
Imaging Colorimeters Market
- Radiant Vision Systems (Redmond, WA) — strong in high-volume manufacturing integration, automated visual inspection and production test stations. Their engineering focus is on inline-ready systems that reduce per-unit test time; their December 2025 launch of a combined imaging colorimeter and spectrometer underscores the trend toward integrated spectral diagnostics in display testing.
- Instrument Systems GmbH (Munich, Germany) — positioned around precision 2D measurement for accurate display and surface inspection applications. Instrument Systems' strength is metrology-grade instrumentation that appeals to customers where measurement traceability is paramount.
- TechnoTeam Bildverarbeitung GmbH (Ilmenau, Germany) — notable for its laboratory software and modular imaging systems; it serves customers requiring bespoke analysis workflows and laboratory-to-production handover.
- RayClouds Photoelectric Technology (Dongguan, China) — active in AR/VR display analyzers and optical measurement systems; their product strategy targets integration with new-form-factor displays and local OEM channels.
- Westboro Photonics (Westboro, MA) — emphasizes high-resolution imaging colorimeters and holds ISO/IEC 17025 accreditation, an important credential for customers who require accredited calibration and test services.
- UPRtek (Taiwan) — focused on portable, high-precision instruments for lab and field use; their July 2025 portable imaging colorimeter launch highlights the growing sub-segment for mobile spectral measurement and clinical/field diagnostics.
- Konica Minolta Sensing (Japan) — offers production-oriented solutions and benefits from global service networks and established brand trust in metrology.
Collectively, vendor moves reflect two converging trends: deeper integration between imaging and spectrometry (driven by complex display stacks and HDR/mini-LED/OLED calibration needs), and diversification of form factors from portable to fully automated inline stations.
Regulatory and operational context that will shape 2026 outcomes
- ISO 17025 accreditation is increasingly a prerequisite for labs offering imaging colorimeter services for display and lighting — buyers are factoring accreditation into vendor selection and contracting timelines.
- IEC color-management standards (e.g., IEC 61966-2-1 relevance in medical device calibration) place additional validation burdens on suppliers who serve medical and safety-critical segments.
- Some clinical uses (e.g., colorimeter-based dermatology assessments) are referenced in trial protocols but lack specific reimbursement coding; this adds uncertainty for vendors seeking to enter clinical workflows.
- Component economics matter: CCD/CMOS image sensors used in these instruments typically range in purchase cost depending on resolution and sensor class; sensor selection materially affects BOM cost and margin dynamics.
- High-volume production customers require dedicated, automated test stations and robust software integration for continuous operation — a supplier’s systems-integration capability is as important as optical performance.
Strategic recommendations for stakeholders acting in 2026
- Manufacturers and OEMs: Lock in multi-supplier sensor agreements and model scenarios that stress-test lead times. Prioritize investments in inline test automation where return-on-capital aligns with projected volume growth within the next 18 months.
- Vendors and product managers: Accelerate development of hybrid imaging+spectrometer modules and software analytics that reduce operator intervention. Product roadmaps should target interoperability and certification as differentiators.
- Procurement and supply-chain leaders: Build a layered sourcing strategy (primary, secondary, contingency) for high-cost sensors and optical subsystems. Negotiate phased supplier commitments with volume rebates tied to production ramps.
- Service providers and labs: Invest in ISO 17025 accreditation and standardized validation protocols to capture accredited test services demand — this converts into higher ASPs and stickier customer relationships.
- Investors and corporate development teams: Use the report’s target-screening framework to prioritize acquisitions that add unique optical IP, software analytics, or regional OEM channels rather than generic hardware scale.
The PW Consulting value proposition and next steps
This research functions as a decision-grade primer for executives who must make capital, product, procurement and M&A decisions in 2026. It pairs an empirical market model with tactical playbooks and supplier dossiers so that C-suite and business-unit leaders can act with conviction.
To preserve the strategic advantage of subscribers, we present detailed segmentation, full company scorecards, and the interactive model exclusively within the full report and data pack. Accessing the complete files will enable you to run bespoke scenarios (by geography, application and product type), extract supplier-level financial projections and obtain customized go-to-market roadmaps tailored to your organization’s objectives.
For access to the full Imaging Colorimeters Market report, raw datasets and consulting engagement options, contact PW Consulting’s Industry Analysis team.
For detailed analysis of this topic, please visit the official page: Imaging Colorimeters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Backhoe Loader Market to Hit USD 10.85 Billion in 2025, 4.28% CAGR
By pmarketresearch, 2026-07-13
Backhoe Loader Market 2026: Strategic Outlook and Actionable Intelligence
As PW Consulting’s senior industry analyst, I present this strategic overview to frame the immediate and medium-term decision-making landscape for executives engaging with the global backhoe loader market in 2026. This briefing synthesizes the high-level market trajectory, competitive dynamics, and actionable levers that matter to manufacturers, OEM suppliers, fleet operators, and investors — while preserving the proprietary granularity of our full study to encourage direct engagement with the source report.
Backhoe Loader Market
Market Trajectory: A Steady Expansion with Structural Shifts
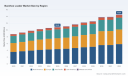
The backhoe loader market has demonstrated resilient expansion through the early 2020s and continues on a steady growth path into the next decade. Our report centers on a base year of 2025 and traces performance across 2020–2025, with a detailed forecast through 2032. After incremental gains through the post-pandemic recovery, the market in 2025 stands materially above the early-2020 level and, at a compounded annual growth rate (CAGR) of 4.28% across the forecast horizon, is projected to continue growing into 2032.
Backhoe Loader Market
This steady growth masks important structural changes: demand drivers are shifting from pure volume expansion to value-led replacement cycles, product differentiation (notably electrification and operator ergonomics), and region-specific infrastructure investment patterns. For 2026 decision-makers, the implication is clear — growth will no longer be won by scale alone; winning requires targeted portfolio investments, supply-chain resilience, and go-to-market agility.
Backhoe Loader Market
Why 2026 Is a Strategic Inflection Point
- Capital allocation decisions hinge on near-term clarity: With predictable CAGR and a visible forward revenue runway, companies must decide whether to prioritize incremental product updates, new powertrain investments, or channel expansion. The capital mix chosen in 2026 will determine competitive positioning for the 2026–2032 cycle.
- Electrification transitions from R&D to commercial rollout: Leading OEMs are now launching electric backhoe models that deliver on-site zero-emissions while matching diesel performance. Early adopters will gain access to differentiated value propositions for urban and regulated environments.
- Input-cost volatility is intensifying procurement risk: Raw material cost pressure — exemplified by recent increases in scrap steel prices — and a shrinking pool of skilled technicians raise both manufacturing and operating cost baselines for 2026 planning.
Key Strategic Imperatives for Executives
- Prioritize modular electrification: Design architectures that allow hybrid/electric variants to share common platforms with conventional models. This reduces development cost per derivative and accelerates time-to-market for emission-sensitive projects.
- Hedge raw-material exposure: Incorporate dynamic procurement strategies — longer-term alloy contracts, alternative material evaluation, and local sourcing trade-offs — to soften short-cycle steel-price shocks and protect margin.
- Invest in aftersales and digital services: With replacement cycles elongating in some regions and fleet uptime becoming a differentiator, revenue from telematics, predictive maintenance, and training will outpace hardware-only margins.
- Re-skill and decentralize expertise: Given the diminishing pool of skilled labor across construction markets, companies must combine human-capital investment with automation and remote service capabilities to secure operating reliability.
Segmentation and Concentration — What the Macro Signals Mean
Our study maps demand across geographic, type, and application dimensions — and uncovers a market that is meaningfully concentrated. The top three players capture a substantial share of global sales, and the top five consolidate that leadership to an even greater extent. These concentration metrics indicate high barriers to scale for late entrants, but they also create opportunities for niche players that can deliver differentiated value in cost, product features, or service models.
While the full report provides the granular splits by region, machine type, and end-application, we intentionally withhold the finer percentages here to preserve the research economics and to encourage engagement with the complete dataset. The high-level takeaway: decisions should be informed by both global flows and local market idiosyncrasies — one-size-fits-all strategies will underperform.
Competitive Landscape: Who to Watch and Why
The market is anchored by a group of global OEMs that combine brand equity, dealer networks, and broad product portfolios. Several dynamics are important when evaluating competitive threats and partnership opportunities in 2026:
- Incumbent global leaders: Established manufacturers continue to defend share through broad line-ups, deep aftermarket channels, and integrated financing offerings. Their scale gives them cost and distribution advantages, but incumbency also creates potential inertia around rapid technology shifts.
- Electrification pioneers: A notable OEM recently unveiled a commercially viable electric backhoe loader that claims zero on-site emissions while delivering performance parity with diesel models. This milestone accelerates competitive pressure on diesel-centric portfolios and creates urgent demand signals for fleet electrification pilots.
- Regional champions and OEM diversity: Several manufacturers originating from established equipment hubs have optimized product mixes for local operating conditions — from compact urban units to heavier, utility-grade machines. These players can outcompete global brands on localized cost and service metrics.
- New-technology integrators: A subset of firms is leveraging telematics, operator assistance, and remote maintenance to create sticky service ecosystems. Their value is increasingly measured in lifetime customer economics rather than unit-level sales.
Our full competitor profiles include headquarter locations, product highlights, and strategic moves — providing procurement teams and corporate strategists with the intelligence needed to map partnership, M&A, and benchmarking targets.
Operational and Supply-Chain Signals to Monitor in 2026
- Materials and input costs: Recent data points show upward movement in scrap steel pricing, underscoring the need for proactive materials strategy in 2026 procurement plans.
- Labor availability and skill shift: The construction sector faces a persistent contraction in skilled labor supply. Firms should accelerate investments in operator training, remote diagnostics, and semi-autonomous assistance to preserve throughput.
- Regulatory and project-level emissions compliance: Zero on-site emissions technologies are moving from pilot stage to procurement requirement in urban projects and clean-energy driven infrastructure schemes. Compliance will increasingly shape RFP outcomes.
What the Report Delivers: Practical, Actionable Tools
PW Consulting’s Backhoe Loader Market Report is designed as an implementation instrument for executives, not just as an academic exercise. Key deliverables include:
- Validated market-sizing and a 2026–2032 forecast built from bottom-up demand drivers and top-down macro checks.
- Segment-level demand models (by geography, type, and application) that can be reweighted for custom scenario planning.
- Financial impact simulations that translate material-price and labor-cost scenarios into margin and pricing stress-tests.
- Competitive profiles and capability matrices that map product portfolios, distribution structures, and electrification readiness.
- Go-to-market playbooks for fleet electrification pilots, dealer transformation, and service-monetization strategies.
- A prioritized roadmap of strategic options — from targeted M&A and JV blueprints to low-cost product strategies for price-sensitive segments.
Each deliverable is accompanied by actionable templates and executive summaries designed for board briefings and investment committee use. The full report also contains appendices with primary-interview excerpts and supplier-cost benchmarks that are not published in this preview.
Recommended First-Move Actions for 2026
- Initiate a two-track product strategy: Develop short-cycle improvements for current diesel platforms while accelerating a modular electric variant for regulated and urban deployments.
- Launch procurement stress tests: Run scenarios that model steel-price spikes and labor-availability reductions to stress financial plans and set contingent sourcing actions.
- Pilot electrification with key customers: Secure limited-scale pilots targeting urban utility and infrastructure projects where zero on-site emissions are prioritized; capture operational telemetry to refine aftermarket services.
- Reconfigure dealer economics: Align incentives to reward uptime, digital-service adoption, and operator training — shifting revenue focus from pure unit sales to lifetime customer value.
- Explore targeted partnerships: Identify local OEMs and technology integrators for co-development or distribution partnerships that accelerate market entry without requiring full-scale greenfield investments.
Closing: Translating Insight into Competitive Advantage
By 2026, the backhoe loader market offers a predictable growth envelope combined with disruptive vectors that merit careful strategic calibration. Our analysis quantifies the growth trajectory and illuminates the levers that will determine who captures durable value: platform modularity, supply-chain resilience, service monetization, and rapid adoption of low-emission technologies.
This article is a strategic preview. For the detailed datasets, regional and application splits, financial scenario models, and complete competitor dossiers that underpin these insights, access to the full PW Consulting Backhoe Loader Market Report is required. The full report converts the directional intelligence presented here into executable plans, prioritized initiatives, and board-ready decision briefs tailored for 2026 execution.
For detailed analysis of this topic, please visit the official page: Backhoe Loader Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cable Blowing Machine Market to Expand at 5.5% CAGR Through 2032
By pmarketresearch, 2026-07-13
Cable Blowing Machine Market — Strategic Outlook for 2026
Executive summary
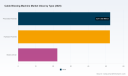
As fibre-first network rollouts continue to shape telecom and infrastructure agendas globally, the cable blowing machine (CBM) market has emerged as a strategic bellwether for operators, OEMs and investors. Our PW Consulting base-year synthesis (2025) and forward projection (2026–2032) show a resilient market trajectory: after rising from USD 95.0 Million in 2020 to USD 127.0 Million in 2025, the sector is projected to grow at a compound annual growth rate (CAGR) of 5.5% over the forecast window, reaching roughly USD 185.5 Million by 2032. These topline dynamics mask important tactical inflections — product modularity, deployment productivity, and supply-chain security — that will determine winners in 2026 and beyond.
Cable Blowing Machine Market
Why this research matters to 2026 decision-makers
-
Timing investments: 2026 is a pivot year for capital allocation across carriers and infrastructure providers. With steady market expansion indicated by our projections, executives must decide whether to accelerate procurement, co-invest in rental fleets, or prioritize in-house deployment capability upgrades.
Cable Blowing Machine Market -
Product roadmaps: OEMs need to align new-generation blowing units (mini/micro capability, energy-efficient drives, and integrated sensors) with buyer preferences that increasingly prize throughput, repeatability and low life-cycle cost.
Cable Blowing Machine Market -
M&A and partnerships: Fragmentation and technology-led differentiation create windows for bolt-on acquisitions, strategic alliances with system integrators, and selective R&D partnerships.
-
Supplier resilience: Raw-material volatility and trade policy shifts mean procurement teams must re-evaluate dual-sourcing, nearshoring and inventory strategies to avoid deployment delays in 2026.
Market trajectory and what the numbers signal
Our historical series (2020–2025) demonstrates a recovery and acceleration post-2021: the market expanded from USD 95.0 Million in 2020 to USD 127.0 Million in 2025. The forward path embeds a moderate, sustained growth profile — 5.5% CAGR — resulting in an estimated market size of approximately USD 185.5 Million by 2032. This pattern reflects a blend of ongoing fibre-push programs, incremental uptake of automated and electric-drive units, and replacement demand for aging fleets.
Two implications are immediate. First, the absolute growth is meaningful for suppliers and investors: predictable, multi-year expansion supports capacity investments and product investments that have multi-year payback horizons. Second, the rate is not hypergrowth; efficiency and differentiation — not simply scale — will determine relative vendor performance. Our concentration metrics underline this: the market remains fragmented (CR3 ~24.6%, CR5 ~26.2%), indicating low top-player dominance and persistent space for regional and specialist players to capture niches.
Key dynamics shaping 2026 strategy
-
Deployment economics and the rise of micro/mini-fibre tools: Operators are optimizing for speed and repeatability. Machines that reduce crew time per metre and lower rework rates are commanding premium consideration in procurement decisions.
-
Technology convergence: Ballasts, drive systems and integrated measurement/sensor suites are moving from novelty to standard specification. Buyers increasingly evaluate total cost of ownership (TCO), which factors energy consumption, maintenance intervals and integration with fleet-management software.
-
Raw-material and supply-chain disruption: Fluctuating input prices and periodic supply shocks continue to pressure component lead times and margins. Procurement playbooks that were resilient before 2022 require revision for 2026 realities.
-
Trade and regulatory headwinds: Recent tariffs and localisation incentives in key markets have altered vendor sourcing strategies. Producers with diversified manufacturing footprints or flexible BOMs are better positioned to manage tariff-induced cost pass-throughs.
-
Rental vs ownership economics: Infrastructure players are recalibrating the rental vs buy decision as deployment horizons shorten and equipment utilization optimization improves.
Competitive landscape — who to watch and why
The CBM ecosystem is a mix of long-established engineering houses, niche innovators and regionally dominant suppliers. Our competitive review profiles leading and strategic players, focusing on product positioning, go-to-market vectors and capability gaps relevant to 2026 decisions.
-
Fremco A/S (Denmark) — Known for precision engineering and a product suite tailored to high-reliability deployments. Fremco’s reputation for durable, maintenance-friendly equipment makes them an attractive partner for operators with long-term asset strategies.
-
Plumettaz SA (Switzerland) — Brings a strong tradition in mechanical innovation and ergonomic design; appeals where operator safety, modularity and calibration fidelity are procurement priorities.
-
General Machine Products Co. (GMP) (United States) — US-based engineering focus with strong aftermarket capabilities; an option for buyers prioritising local support and rapid spares availability.
-
Condux International (United States) — Leverages a broad portfolio across conduit and cable technologies. Their integrated solutions approach suits customers seeking single-vendor accountability for complex projects.
-
LANCIER CABLE GmbH (Germany) — European engineering with strong customisation options; tends to compete on specialised product configurations for industrial deployments.
-
Allame Makina, Asian Contec, Skyfibertech, Kösmak Machine (Turkey/India/Turkey/Turkey) — Regional manufacturers offering competitive price-performance for emerging-market deployments and rental fleets, often with shorter lead times and local service advantages.
-
Jetting (Germany), FiberNet (Italy), FCST (China), Stanlay (UK) — Each brings particular strengths: trade-show product launches and specialised mini/micro machines, rapid product refreshes, or strong regional OEM partnerships. Recent trade-show activity and catalog updates in 2026 highlight a market still investing in product refresh and demand-generation efforts.
Recent vendor activity — what it reveals
-
Trade-show presences (e.g., fibre-centric events in 2026) underscore vendor intent to capture mini/micro cable segments and to demonstrate new gearboxes and sensor integrations.
-
Catalog updates for micro cable machines and refreshed model lines indicate product-cycle momentum: buyers should expect rolling introductions rather than a single generational leap.
What our full report contains — practical deliverables for 2026 action
PW Consulting’s full CBM market study is designed as an operational toolset, not just a prognosis. Highlights include:
-
Market-sizing methodology and transparent assumptions, with time-series from 2020 through a detailed 2026 baseline and scenario forecasts to 2032.
-
Demand modelling for deployment and replacement drivers, calibrated to operator roll-out schedules and productivity thresholds.
-
Supplier matrix and capability heatmaps: comparative scores on product features, service footprint, price bands and innovation roadmaps.
-
Procurement playbook: procurement timelines, specification templates, and TCO calculators tailored to rental vs purchase decisions.
-
Risk and resilience assessment: supplier concentration analysis, supply-chain choke-point mapping, and recommended mitigation strategies (dual sourcing, local assembly, inventory buffers).
-
Deal and M&A playbook: valuation heuristics for tuck-ins, checklist for technical due diligence, and scenarios where vertical integration enhances margin capture.
-
Implementation checklists and pilot frameworks for field trials — how to structure proof-of-performance tests and set go/no-go KPIs.
Strategic choices and recommended next steps for 2026
-
Operators: Move from capex-only procurement to blended fleet strategies. Pilot newer, sensor-enabled units on high-value routes to validate TCO improvements before large-scale rollouts.
-
OEMs: Prioritise modularity and after-sales platforms. Investing in remote diagnostics and consumables-lock-in can transform low-margin equipment into recurring revenue streams.
-
Investors: Target smaller regional champions with strong service networks as acquisition candidates — integration into a rental and services platform can unlock value.
-
Procurement teams: Reassess supplier qualification criteria to include lead-time flexibility, alternative BOM options and tariff exposure.
How to use this “trailer” and where to find the full intelligence
This piece is intentionally constructed as a strategic trailer: it outlines macro growth, market architecture and near-term tactical choices while withholding granular segmentation outputs and full vendor share data that are often the decisive inputs for procurement, bid and M&A models. PW Consulting’s comprehensive report contains the detailed regional, type and application splits, priced scenarios, vendor scorecards and appendices you will need to execute on the strategies outlined above.
For teams preparing board materials, RFPs or investment memoranda in 2026, the full dataset ensures defensible, audit-ready assumptions; the executive-level guidance here will help you prioritise which deep dives to commission first (e.g., rental economics, tariff modelling, or pilot specifications).
Closing — from insight to impact
The cable blowing machine market in 2026 is neither a high-growth staple nor a mature commodity market; it sits between, offering predictable expansion but rewarding precise strategy. Executives who translate the macro signal — steady CAGR growth from a USD 127.0 Million 2025 baseline toward an approximately USD 185.5 Million 2032 opportunity — into concrete procurement, product and partnership decisions will turn sector growth into durable competitive advantage.
To move from strategic intent to operational execution, access the full PW Consulting CBM study for the granular segmentation, vendor benchmarking and implementation templates essential to succeeding in 2026.
For detailed analysis of this topic, please visit the official page: Cable Blowing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Off-The-Road Tyre Market to Reach USD 346.03M by 2032 at 6.45% CAGR
By pmarketresearch, 2026-07-13
Off-The-Road (OTR) Tyre Market: Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise but substantive preview of our full Off-The-Road (OTR) Tyre Market study — a practical intelligence product designed to inform capital allocation, commercial positioning, and operational moves in 2026. This preview surfaces the macro trends, competitive trajectories, regulatory and technology inflection points, and the types of pragmatic analyses you will find in the full report. Per the “trailer” principle, we reveal methodological rigor, high-level outcomes, and strategic implications while deliberately withholding detailed segment-level tables and model outputs to encourage access to the full dataset and scenario models on our source page.
Off-The-Road Tyre Market
Market Context — High-Level Numbers and Growth Trajectory
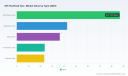
The OTR tyre market has demonstrated steady expansion since 2020 and is poised for continued growth through the forecast horizon. Using 2025 as the base year, our historical reconstruction (2020–2025) and forward projections (2026–2032) show a clear upward trend driven by infrastructure investment, mining cyclical recovery, and technology-led product enhancements. Key macro datapoints embedded in our modelling include a compound annual growth rate (CAGR) of approximately 6.45% for the forecast window. In monetary terms (USD, Million), the overall market expanded from an estimated market size in 2020 through a larger base in 2025 and is forecast to reach materially higher levels by 2032. These headline figures anchor all scenario work in the report and provide the quantitative foundation for the strategic recommendations that follow.
Off-The-Road Tyre Market
Why this research matters for 2026 corporate decisions
- Capital allocation: Prioritize greenfield expansions, brownfield capacity conversion, and buy-versus-build choices using a demand-driven, location-sensitive model calibrated to 2026 legislative and tariff scenarios.
- Commercial strategy: Translate macro growth into actionable go-to-market plans — channel optimization, OEM partnerships, and aftermarket service rollouts — supported by elasticity and price-sensitivity analysis.
- Supply chain resilience: Stress-test manufacturing footprints against tariff uncertainty, raw-material price swings, and logistics bottlenecks to define near-term hedges and two- to five-year resilience investments.
- Product roadmaps: Align R&D and SKU rationalization with expected equipment mix and performance requirements — leveraging insights on AI-assisted design, giant-tyre technologies, and serviceability trends.
- M&A and JV screening: Use our target universe and valuation heuristics to prioritize inorganic plays that accelerate access to capacity, technologies, or regional distribution networks.
Market dynamics and structural drivers
The market’s expansion through 2025 reflected a combination of cyclical and structural forces: recovery in heavy industries, renewed infrastructure programs, and a gradual premiumization of fleets seeking higher-durability solutions. Looking into 2026, several near-term dynamics will shape strategic choices:
Off-The-Road Tyre Market
- Policy and trade noise: Tariff uncertainty and countervailing duty reviews have elevated the cost of cross-border procurement for some manufacturers and distributors. These developments directly affect pricing strategies and manufacturing footprints when quick responsiveness to demand is required.
- Infrastructure as a demand engine: Legislative outlooks emphasizing infrastructure spending are a clear upside catalyst; firms that calibrate product portfolios and distribution for large-scale civil programs will capture disproportionate share gains.
- Right to Repair and service economics: Emerging “Right to Repair” provisions will influence aftersales, refurbishment, and service business models — presenting monetizable opportunities in remanufacturing and digital diagnostics.
- Technology adoption: AI-powered design platforms and new material/process innovations are improving tyre life, load capacities, and predictive maintenance capabilities — changing the value proposition away from pure price competition toward total cost of ownership (TCO) outcomes.
- Market structure: Competitive concentration metrics indicate a moderate level of market power among incumbents, which shapes pricing dynamics and competitive responses in supply-constrained scenarios.
What the full report delivers — practical, decision-ready content
The complete PW Consulting OTR Tyre Market study is structured to move clients from strategic question to operational decision in 90 to 365 days. Key deliverables include:
- Robust market-sizing and forecasting model (historical 2020–2025, forecast 2026–2032) with scenario toggles for price, capex, and policy variables.
- Segment demand models by application, tyre type, and vehicle class, each linked to fleet activity and replacement cycles (note: subsegment tables are available only in the full report).
- Supply-side mapping: global plant capacities, lead times, and a risk heatmap for geopolitically sensitive routes and inputs.
- Competitive diagnostic: comprehensive one-page profiles and strategic positioning matrices for the leading manufacturers and fast-moving challengers.
- Commercial playbooks for aftermarket, OEM, distribution, and project-based sales — including pricing levers and channel economics.
- Manufacturing optimization tools: footprint scenarios, utilization sensitivities, and an M&A screener tailored to OTR strategies.
- Regulation and sustainability tracker: Right to Repair, emissions and material circularity implications, and compliance pathways for 2026–2032.
- Rapid scenario templates: tariff shock, infrastructure surge, and technology disruption, each with quantified P&L and balance-sheet impact estimates.
Competitive landscape — strategic takeaways
The competitive field blends global incumbents, regional champions, and specialized niche producers. Our benchmarking assesses strategy across four dimensions: product breadth, scale & capacity, distribution & service footprint, and technology/innovation capability.
- Global incumbents (e.g., Bridgestone, Michelin, Goodyear, Continental) maintain advantage through scale, broad product lines for mining/construction/agriculture, and deep OEM relationships. Their strategic moves will focus on premiumization, digital services, and selective capacity expansion to protect margins.
- Specialist manufacturers (e.g., Titan International, Trelleborg, certain European and US players) compete on application-specific expertise and aftermarket service models, often commanding higher lifecycle economics in targeted niches.
- Emerging and scale-up manufacturers from Asia (including multiple established Chinese and Indian firms) are expanding radial OTR capabilities and pursuing export-led growth, supported by local capacity investments and competitive price points. These firms are also increasingly investing in technology upgrades to reduce the performance delta.
- Strategic implications: incumbents should protect premium segments and accelerate digital aftersales; mid-tier players may find the most value in targeted specialization or partnering; new entrants—especially those expanding plant capacity—need credible access to distribution and service networks to convert volume into sustainable revenue.
Recent developments that matter in 2026
- New product introductions: A 2026 radial OTR product launch targeting North America underscores ongoing segmentation of performance tiers and the criticality of tailored SKU strategies.
- Capacity moves: Announced greenfield plants for giant tyres in India and Mexico by a major manufacturer signal a shift in geographic supply capacity and faster local-serviceability — a factor for customers seeking reduced lead times.
- Technology launches: The introduction of specialized efficiency technologies for giant tyres indicates continued innovation centered on lifecycle cost reduction rather than unit price.
- Policy updates: Tariff reviews and Right to Repair initiatives are reshaping procurement decisions and service economics; proactive commercial and supply-chain strategies will reduce downside risk.
How to use this research in 90 days and over the next 12 months
- 90-day priorities: Run immediate scenario tests for pricing and tariffs, prioritize inventory hedges for exposed SKUs, and initiate OEM negotiations to lock favorable terms for upcoming infrastructure programs.
- 6–12 month priorities: Complete footprint optimization using the report’s plant-utilization and logistics models; pursue targeted partnerships for service coverage; and accelerate AI-enabled product development pilots informed by our performance benchmarks.
- Capital planning: Use the forecast model to stress-test payback timelines for capacity investments and to refine acquisition filters for bolt-on M&A targets that provide route-to-market or technology lift.
Closing—Why PW Consulting’s OTR report is a practical asset for 2026
Decisions in 2026 will be made in an environment of measured growth, localized capacity shifts, and increasing regulatory and technological complexity. Our OTR Tyre Market study packages forward-looking scenarios, commercial playbooks, and supply-side diagnostics into a cohesive decision-support tool. The executive-ready takeaways and the deep, model-driven appendices are designed to convert market signals into high-confidence actions — from price-setting and plant siting to R&D prioritization and M&A screening.
If your organization is planning capital allocation, go-to-market shifts, or supply-chain reengineering in 2026, the full report provides the granular segment tables, demand-driver elasticities, and downloadable scenario models required to operationalize these strategies. Access to the full dataset and model repository is available through our source portal.
For detailed analysis of this topic, please visit the official page: Off-The-Road Tyre Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com