

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Security Control Room Market to Reach USD 10.26B in 2025; 6.2% CAGR to 2032

Security Control Room Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As enterprises and critical infrastructure operators plan capital and operational programs for 2026, the Security Control Room market presents a familiar paradox: steady, predictable expansion on the surface, and accelerating technical and organizational complexity beneath. PW Consulting’s forthcoming in-depth market study — grounded in a 2025 base year and projecting through 2032 — synthesizes historical performance (2020–2025), forward-looking scenarios (2026–2032), and practical tools for decision-makers who must balance resilience, cost, and operational excellence.
Security Control Room Market
Market trajectory at a glance
The market’s multi-year trend shows steady growth from the start of the decade and into the mid-2020s, with a compound annual growth rate of approximately 6.2% through the forecast horizon. In nominal terms the industry reaches just over USD 10 billion in the 2025 base year and is projected to continue expanding toward mid-decade targets and beyond, driven by continuous demand for higher-fidelity situational awareness, integrated OT/IT security tooling, and enterprise-grade monitoring centers.
Security Control Room Market
Two implications are immediate for 2026 planning cycles. First, the market is large enough to sustain multiple competing models — from fully integrated vendor suites to specialist component suppliers and systems integrators — which makes vendor selection a strategic decision rather than a commoditized procurement exercise. Second, while growth is predictable, it is not frictionless: rising expectations around real-time analytics, redundancy, and regulatory compliance introduce cost and complexity that must be modeled explicitly in capital budgeting and vendor contracts.
Security Control Room Market
Why PW Consulting’s study matters to executives in 2026
- Actionable TCO and investment scenarios: We translate market growth and segment dynamics into multi-year total cost of ownership (TCO) models that help justify or challenge capital approval requests for control room modernizations.
- Procurement and vendor-play playbooks: The study provides structured approaches to tender design, supplier shortlisting, and staged implementation — critical when procurement must balance uptime guarantees, cybersecurity SLAs, and lifecycle refresh cycles.
- Risk-to-reward frameworks: Executives receive scenario-based risk matrices that map investment choices to resilience outcomes (e.g., hybrid on-premises vs. managed SOC arrangements), enabling faster but more informed governance decisions.
Core market dynamics shaping decisions in 2026
Four interdependent forces will govern near-term outcomes:
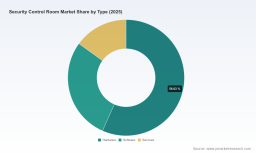
- Technology consolidation with point-solution specialization: Hardware, software and services continue to evolve along different time horizons. Control-room hardware investments (video walls, sensor arrays, resilient networking and displays) remain capital-intensive, while software capabilities (analytics, automation, digital twins) enable operational leverage. Services — from 24/7 SOC staffing to system integration — complete the value chain but require continuous talent investment.
- Operational resilience and energy/infra costs: Continuous operations impose non-trivial energy and facilities demands. Redundancy in power, network and cooling is non-negotiable for mission-critical operations and should be treated as part of the system design rather than an add-on.
- Regulatory and data control preferences: For many government, defense and critical infrastructure customers, on-premises deployments remain the preferred baseline due to latency, data sovereignty and auditability concerns. Hybrid architectures are emerging as an optimization, but they require explicit controls and validated trust boundaries.
- Market concentration and partner ecosystems: The market exhibits a moderate degree of concentration among leading platform and services providers, which has implications for negotiation leverage, interoperability risks, and M&A dynamics. Buyers should balance the benefits of deep vendor ecosystems against the risks of supplier lock-in.
Competitive landscape — what to watch in 2026
Our competitive analysis profiles leading suppliers that influence both technology roadmaps and procurement behaviors. Each vendor brings a distinct strategic posture customers should evaluate against their own risk and capability requirements:
- Honeywell: Positioned as a provider of industrial-grade security operations and control-room technologies, Honeywell pairs OT-focused SOC capabilities with command-center products that integrate fire, audio evacuation and industrial monitoring. Recent platform-level innovation — including a digital twin capability introduced mid-2025 — highlights a push toward safer change-management and simulated testing before live rollouts.
- Johnson Controls: Emphasizes a global SOC services model with standardized incident protocols, risk-based prioritization and regulatory-compliance support. Their approach is attractive to organizations seeking outsourced operations with enterprise SLAs and multi-jurisdictional staffing coverage.
- Schneider Electric: Focuses on staffed SOC operations and incident triage for continuous monitoring. Their strength lies in operational continuity and energy-aware building integration for control room environments.
- IHSE: Specializes in critical-environment KVM-over-fiber solutions that address latency, display fidelity and secure signal delivery — often an essential component in control rooms where visual continuity is paramount.
- Siemens: Brings integrated IT/OT SOC solutions and strategic partnerships to the table, enabling proactive threat management in industrial settings. Collaborations with global consultancies expand their delivery footprint for complex industrial customers.
Tactical takeaways: suppliers are differentiating along three axes — OT/IT security integration, managed operations and specialist hardware for mission-critical visualization. For buyers, the practical question is which axis best aligns with the organization’s risk profile, staffing model, and regulatory obligations.
Practical content in the PW Consulting study — what’s inside
This research is designed for decision-makers and program owners who must move from strategy to execution. The report packages include:
- Scenario-driven demand models and forecast sensitivities that map investment outcomes to market and technology shifts.
- Vendor scorecards and capability matrices tailored for procurement, compliance and operations teams.
- Implementation playbooks — covering procurement SOWs, integration sequencing, test plans, and runbook templates for incident response and business continuity.
- Detailed TCO templates and procurement negotiation checklists to uncover lifecycle costs beyond initial equipment purchase.
- Regulatory and standards alignment guidance to streamline audits and cross-border deployments.
Importantly, the report focuses on operational applicability: downloadable Excel models, vendor evaluation rubrics and phased deployment timelines are included so teams can go from read-to-action in weeks rather than months.
How to convert insight into decisive action for 2026
We recommend a three-track approach for executives planning control room investments in 2026:
- Clarify mission profiles and risk tolerance: Establish whether the control room’s priority is operational continuity, regulatory compliance, rapid threat response, or a blend. This determines whether to emphasize on-premises redundancy, managed SOC services, or investment in digital-twin validation capabilities.
- Adopt modular modernization with gated investments: Prioritize projects that deliver measurable uplift (e.g., faster detection-to-response times) and stage larger capital commitments behind proof-of-concept and interoperability tests. Treat display/hardware refresh, network resilience, and analytics integration as separable workstreams with defined success metrics.
- Negotiate for openness and escape clauses: Given moderate market concentration, procurement should insist on interoperability, data portability and clear exit provisions. Include performance-based SLAs and periodic capability re-assessments tied to vendor roadmaps.
Risks and unknowns to monitor
Key uncertainties that should shape governance in 2026 include the speed of cloud adoption for SOC functions (which will vary by jurisdiction and sector), the availability of specialized integration talent, and energy/regulatory cost dynamics that materially affect operating expenditures. PW Consulting’s sensitivity scenarios explore these inflection points and provide contingency paths for both conservative and aggressive adopters.
Why this preview — and what it does not reveal
This article highlights strategic conclusions and actionable frameworks from PW Consulting’s Security Control Room Market study but intentionally omits granular segmentation tables and vendor-level revenue splits that many organizations use to refine procurement and M&A strategies. Those detailed matrices — including regional heatmaps, application breakdowns and vendor financials — are available in the full report and accompanying data package for subscribers and purchasers.
Next steps for leaders
If you are responsible for capital planning, security operations, or critical infrastructure resilience in 2026, consider the following immediate steps:
- Commission a short diagnostic using PW Consulting’s readiness checklist to validate current control-room capabilities against near-term risk scenarios.
- Run a focused pilot that pairs a digital-twin validation of change control with a managed SOC overlay; measure time-to-detect and mean-time-to-recovery as primary KPIs.
- Engage procurement and legal early to codify interoperability and data-portability clauses in vendor contracts.
For readers who need the full segmentation, vendor scorecards, and downloadable models referenced here, PW Consulting’s complete Security Control Room Market study provides the necessary depth to convert this preview into a project-ready plan. Visit our research page to access the full report, Excel workbooks, and an executive briefing tailored to your sector.
For detailed analysis of this topic, please visit the official page: Security Control Room Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com