

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Magnetic Beads Market to Grow at 11.8% CAGR Through 2032 — PW Consulting

Magnetic Beads Market — Strategic Outlook for 2026 Decisions
Executive snapshot
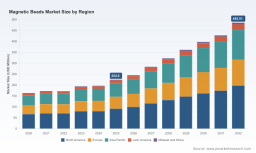
The magnetic beads market is entering a phase of accelerated commercialisation and structural transition. From a 2025 base-year valuation of approximately USD 224.6 Million, the market is projected to grow at a compound annual growth rate (CAGR) of roughly 11.8% over the 2026–2032 forecast horizon, reaching an expected market size in the high hundreds of millions of USD by 2032. Historical momentum (2020–2025) indicates an established recovery and reorientation following pandemic-related disruptions; forward growth will be shaped as much by application-driven demand (life‑science workflows, diagnostic and separation platforms) as by cross‑industry dynamics (electronics component supply chains and raw‑material inflation).
Magnetic Beads Market
Why this report matters to 2026 planning
For executives preparing 2026 budgets, sourcing strategies and R&D roadmaps, the magnetic beads market represents a compact but highly strategic arena. It sits at the intersection of two important value chains: bioprocessing and diagnostics on one side, and electronic component manufacture on the other. That intersection produces distinctive opportunities (new detection workflows, automated sample prep, hybrid device architectures) and distinctive risks (raw-material price shocks; supplier concentration). Our study frames these forces in business-relevant terms so leaders can prioritise capital allocation, supplier engagement and product development through 2026 and beyond.
Magnetic Beads Market
Market trajectory: what the headline numbers tell you
-
Mid‑decade momentum: The market recorded consistent expansion from 2020 to 2025, moving from a modest base into stronger commercial adoption and investment. The 2025 base of ~USD 224.6 Million provides a reliable pivot for near‑term planning.
Magnetic Beads Market -
Fast forward to 2032: Under the central forecast, the market approximately doubles from the 2025 base to approach USD 485.5 Million by 2032—an outcome driven by both volume adoption in established workflows and higher‑value product introductions tied to automation, single‑cell and molecular assays.
-
Concentration and competitive implications: Market concentration is moderate; the largest three players control a meaningful share of industry revenues while the top five consolidate the market further (CR3 ≈ 38.2%, CR5 ≈ 62.4%). This balance creates opportunities for mid‑tier challengers to capture niche or value‑added positions while reminding purchasers that supplier disruption could propagate quickly through the supply chain.
Key demand drivers and structural headwinds
-
Application diversification: Demand is being pulled by both established separation workflows and emergent analytical uses (e.g., exosome analysis, rapid IVD assay development). Adoption of beads in automated NGS and immunoassay workflows is a particular high‑growth vector.
-
Automation and throughput: Shorter product cycles and increasing throughput requirements in electronics and life sciences alike place a premium on bead uniformity, surface chemistry precision and compatibility with robotic handling.
-
Raw‑material volatility: Input cost swings—illustrated by sharp movements in materials that feed into ferrite and multilayer chip production—are already affecting pricing strategies across the supplier base. Such volatility translates directly into procurement risk for both electronics‑ and bio‑oriented buyers.
-
Regulatory and sourcing shifts: Announcements of list‑price increases from major component manufacturers and the prospect of further region‑specific pricing adjustments force global sourcing teams to revisit supplier networks and hedging approaches in 2026.
Competitive landscape — structure and strategic postures
The competitive map for “magnetic beads” in 2026 is multi‑layered. Our analysis distinguishes two overlapping supplier archetypes:
-
Life‑science specialists: Companies focused on polymer‑ or iron‑oxide‑based particles with bespoke surface chemistries, automation compatibility and application‑centric validation. Recent product launches targeting automated NGS and affinity‑ligand capabilities are emblematic of this cohort’s strategy: expand technical differentiation and embed sales into instrument OEM workflows.
-
Component and ferrite suppliers: Established electromechanical component manufacturers (including several Asia‑based multilayer and ferrite specialists, and long‑standing Japanese and North American players) whose product families and manufacturing ecosystems overlap materially with bead and bead‑like products in the electronics domain. For these players, cost pressures from raw materials and shifts in downstream demand (for EVs, high‑density electronics) drive both price actions and portfolio prioritisation.
Between these groups sits an active middle: regional Chinese and Taiwanese manufacturers that leverage high‑volume production and competitive pricing to serve broad OEM and distribution channels. Strategic movement in 2024–2026 shows consolidation of higher‑value product lines among life‑science specialists and cost rationalisations among component manufacturers—creating both partnership opportunities and competitive tensions for buyers and investors.
Recent developments that will shape 2026 decisions
-
Pricing moves by component manufacturers: Late‑2025 and early‑2026 price notices from prominent component manufacturers signalled upward pressure across inductors and bead families. For procurement leaders this means revisiting cost baselines and considering contract re‑negotiations or alternative sourcing strategies in 2026.
-
Targeted product launches: In early 2026, automation‑friendly particle platforms and affinity‑ligand innovations were announced that materially improve integration into high‑throughput single‑cell and epigenomic workflows. These launches accelerate adoption cycles in labs that prioritise automation and closed‑system processing.
-
Supply‑chain rhythm: Faster dev‑to‑market expectations in electronics are shortening acceptable lead times across the board. Buyers should expect suppliers to push for longer‑term commitments in exchange for capacity guarantees or priority allocation.
What our full report delivers (practical use cases)
PW Consulting’s full study is designed as an operational toolkit for strategic decision‑makers. Highlights include:
-
Transparent market sizing and scenario forecasts (base year 2025; historical 2020–2025; outlook 2026–2032) that support budgeting and revenue target setting.
-
Actionable segmentation analysis (type, application, region) with use‑case driven demand assumptions — presented so procurement, R&D and commercial teams can map investments to expected return horizons.
-
Supplier benchmarking and capability matrices enabling rapid short‑listing and negotiation playbooks.
-
Price‑impact models and procurement mitigation strategies that quantify the P&L sensitivity to raw‑material and list‑price shifts.
-
M&A and partnership opportunity scans with heuristic valuation levers for vertical integration or technology licence plays.
We intentionally present segmentation and granular supplier share tables behind the paywall to ensure that subscribers receive the detailed numeric splits needed to operationalise these recommendations. The executive narrative here is sufficient to inform strategy, while the full datasets enable tactical execution.
Strategic recommendations for 2026
-
Prioritise dual sourcing for critical inputs. Given input price volatility and concentration among top suppliers, organisations should identify alternative qualified vendors and create flexible allocation mechanisms that can be invoked if list‑price adjustments or capacity constraints emerge.
-
Accelerate integration with automations teams. New particle chemistries and automation‑friendly formats will differentiate winners in diagnostics and high‑throughput genomics; cross‑functional pilots with OEMs should be fast‑tracked in 2026.
-
hedge pricing exposure selectively. Use a mix of fixed‑price contracts for critical volumes and indexed agreements where appropriate to balance protection and flexibility.
-
Monitor and model regulatory shifts and regional pricing announcements. Japanese and other regional list‑price changes have global sourcing implications—scenario plans should be updated quarterly.
-
Consider targeted partnerships or minority investments. For firms seeking rapid capability upgrades (e.g., affinity ligands, single‑cell compatible beads), partnership can be a faster route than in‑house development.
How to use this insight now
For 2026 planning cycles, use our headline findings to: (1) set conservative revenue and procurement baselines that incorporate potential list‑price increases; (2) prioritise product projects that link directly to automation and high‑value analytical use cases; and (3) activate supplier contingency plans for any upward pricing shocks. If you require immediate tactical outputs, ask our team for the supplier benchmarking module and the procurement mitigation spreadsheet that model the P&L impact of the most likely raw‑material shock scenarios.
Concluding perspective
The magnetic beads space is compact but strategically dense: modest headline revenues today, sizable upside in the decade ahead, and a market architecture that rewards technical differentiation and supply‑chain foresight. For 2026, leaders who blend short‑term procurement resilience with medium‑term product differentiation will capture outsized value. PW Consulting’s full report provides the granular splits, supplier scores and scenario models that translate this strategic lens into executable actions—visit the publication page to access the complete datasets and operational playbooks.
For detailed analysis of this topic, please visit the official page: Magnetic Beads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com