

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Water Delivery Market to hit USD 216.6M by 2032 (5.2% CAGR)

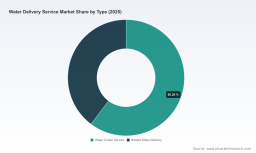
Water Delivery Service Market: Strategic Outlook for 2026 — A PW Consulting Preview
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise yet forward-looking preview of our flagship Water Delivery Service Market study — a practical, decision-grade research product designed to inform boardrooms, private equity teams, and corporate strategy functions as they prepare plans and capital allocations for 2026. This preview highlights the study’s strategic value, the primary market dynamics we observed, and the competitive and regulatory inflection points that will shape winners and losers over the next planning cycle.
Water Delivery Service Market
Why this study matters for 2026 decisions
In an industry characterized by operational intensity, low technological differentiation, and increasing environmental scrutiny, timing and precision in strategy execution are everything. Our market model — calibrated to a 2025 base year — shows the global Water Delivery Service market at approximately USD 151.8 Million (base year 2025), following a recovery and acceleration path from the 2020–2025 period. Under our central scenario the market expands at a compound annual growth rate (CAGR) of 5.2% over the 2026–2032 forecast window, reaching roughly USD 216.6 Million by 2032. These headline metrics are not merely descriptive: they define the envelope for addressable demand, capital deployment cadence, and scale economics that will validate or invalidate strategic initiatives in the immediate term.
Water Delivery Service Market
For executives evaluating near-term moves — whether it’s fleet electrification, automated warehousing, pricing reengineering, or M&A — the 2026 planning horizon is pivotal. In many cases the projects greenlit this year will determine incremental margins through 2030 and beyond. The study equips decision-makers with the scenario analyses, unit economics, and risk-adjusted investment cases they need to prioritize with confidence.
Water Delivery Service Market
Key market dynamics shaping 2026 strategy
- Operational automation and labor economics: Warehouse robotics and automated guided vehicles (AGVs) are already demonstrating measurable labor cost reductions and delivery efficiency gains. Our synthesis of industry data indicates automation deployments can reduce direct labor spend by double-digit percentages while improving last-mile productivity. For companies with dense urban routes, the calculus of retrofitting depots and redesigning workflows becomes compelling in 2026.
- Sustainability as a commercial lever: Growing regulatory scrutiny and activist pressure are forcing providers to invest in sustainable packaging, circular refill models, and lower-emission delivery fleets. These investments are increasingly linked to customer retention and enterprise contracts; in several bids we analyzed, sustainability credentials were a clear tie-breaker.
- Cost sensitivity and value capture: High service costs — driven by logistics complexity and the premium nature of certain water products — continue to deter price-sensitive household segments. Providers will need to balance premium offerings with lower-cost, high-frequency delivery options to broaden penetration without compressing margins.
- Regulatory accelerants: New water-safety standards in key markets are raising infrastructure compliance requirements. These impose both cost and opportunity: while retrofit and certification costs rise, certified providers gain competitive advantage in procurement for institutional customers.
Taken together, these dynamics create a bifurcated landscape in 2026: operators that aggressively adopt automation and demonstrate credible sustainability will expand share and margin; those that maintain legacy models risk margin erosion or forced consolidation.
Report contents — practical deliverables for immediate action
Our full report is structured to convert insight into action. Major deliverables include:
- Proprietary market model (2020–2032): granular, transparent assumptions and downloadable scenario outputs that let teams stress-test revenue and capex plans under alternative demand, price, and cost trajectories.
- Unit-economics playbook: route-level profitability calculators, sensitivity analyses on fuel/energy and labor, and benchmark KPIs for CAC (customer acquisition cost), churn, lifetime value, and fleet utilization.
- Investment decision support: NPV/IRR templates, break-even analyses for automation and electrification investments, and prioritization frameworks for capex deployment across hubs and routes.
- Go-to-market and pricing frameworks: segmentation-based offer design (household vs. commercial), bundling strategies, and playbooks for converting retail members into recurring delivery subscribers.
- Regulatory and sustainability roadmap: stepwise compliance checklists, TCO implications of circular packaging and refill stations, and supplier partner evaluation criteria.
- Competitor intelligence matrix: capability maps, likely strategic moves, and M&A heatmaps focused on acquirers, targets, and disruptors.
Each module is grounded in primary-sourced interviews, operational benchmarking, and a transparent assumptions log so clients can adapt the model to their internal data while preserving comparability to the PW Consulting baseline.
Competitive landscape — what the majors are signaling for 2026
The market remains fragmented — our concentration analysis shows a low top-three and top-five share footprint, underscoring the room for both regional specialists and national consolidators. That fragmentation creates attractive pockets for disciplined scale plays and capability-driven roll-ups.
- Primo Brands Corporation (Winston-Salem, NC): A leading North American operator, Primo’s recent roll-out of urban eco-friendly refill stations signals a pivot toward circular models and retail-adjacent touchpoints. For competitors, Primo’s move underscores the commercial potential of blending delivery with decentralized refill networks to reduce single-use packaging exposure.
- Culligan International Company (Rosemont, IL): Culligan’s integrated offering — pairing dispenser services with water treatment and softening — highlights a durable cross-sell strategy that improves retention and ARPU in commercial accounts. Expect similar service bundling to be a defensive priority for regional players aiming to protect midsize enterprise contracts.
- Absopure Water Company (Plymouth, MI): As a strong regional provider with a focus on natural spring and purified products, Absopure exemplifies the value of localized sourcing and brand trust in the household segment. Their model remains instructive for operators seeking to deepen regional loyalty while optimizing delivery density.
- Danone Waters of America Inc.: Danone’s selective market play through partnerships and direct channels demonstrates how global CPG players can leverage brand strength and supply-chain scale without deploying full-fledged delivery networks in every locale. Partnership-driven expansion is a near-term strategic lever for companies looking to enter new geographies with constrained capex.
- Costco Wholesale Corporation: Costco’s member-centric delivery offers exemplify an alternative route-to-market: leveraging an embedded membership base to distribute water delivery and dispenser units, thereby compressing CAC and accessing high-retention households and small offices.
Recent developments — from Primo’s eco-station roll-out to Nestlé’s partnership for AI routing in Europe, and regulatory tightening in Australia — illustrate three interlocking themes: operational optimization, platform and partnership plays, and compliance-driven capex. These are the vectors that will separate compounding gains from stagnation in 2026.
How to use the study in your 2026 planning cycle
- Prioritize automation where density supports payback: Use our route-level calculators to identify depots and corridors where robotics, AGVs, and smart routing deliver real break-even within typical investment horizons.
- Convert sustainability into revenue protection: Model the TCO of refill networks and recycled packaging to quantify retention and bid-winning advantages in institutional RFPs.
- Test partnership-led expansion: For entrants or firms with capital constraints, the report’s partnership frameworks provide a staged path to geographic expansion without owning every leg of the logistics chain.
- Design for segmentation-driven pricing: Our pricing playbooks enable you to design offers that preserve margins on premium water types while opening lower-cost, high-frequency channels for price-sensitive households.
- Build an M&A heatmap: With fragmentation and modest incumbent concentration, consolidation remains a viable route to scale. The report’s target criteria and accretion models help identify high-value tuck-ins and defensive buys.
What this preview does — and does not — offer
This executive preview is intentionally curated to demonstrate the analytical depth and practical orientation of the full PW Consulting study. It surfaces overarching market size, growth trajectory, and the strategic implications that matter for 2026 decisions. In keeping with our “trailer” approach, we intentionally withhold detailed segment-level splits, route-level unit economics, and the full set of proprietary forecasts that are available in the complete report and interactive model. These deliverables contain the granular inputs and downloadable templates that teams will use to finalize budgets, capex proposals, and M&A decks.
Next steps — for strategy teams and investors
For companies and investors moving from strategic hypothesis to commitment in 2026, we recommend three immediate actions:
- Acquire the full PW Consulting Water Delivery Service Market package (model + playbooks) to run bespoke scenario stress tests tied to your route and customer data;
- Run a fast-track pilot in one high-density corridor combining automated warehousing, AI routing, and a circular packaging trial to validate unit-economics improvements;
- Map potential partnerships and tuck-in targets using our M&A heatmaps to accelerate scale while preserving capital flexibility.
To access the full dataset, interactive model, and downloadable playbooks that underpin these conclusions, please visit our report landing page. PW Consulting’s analysts stand ready to run custom workshops and model calibrations tailored to your operating footprint and capex constraints.
Prepared by: PW Consulting — Senior Strategic Advisor & Chief Industry Analyst.
For detailed analysis of this topic, please visit the official page: Water Delivery Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com