

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Ethylhexylglycerin Market to Hit USD 344.79M by 2032 at 6.98% CAGR (2026-2032)
By pmarketresearch, 2026-07-13
Ethylhexylglycerin Market 2026: Strategic Imperatives for Commercial Leaders
Executive snapshot
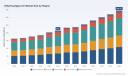
As businesses plan for 2026, the ethylhexylglycerin market presents a compelling mix of steady growth, structural fragmentation, and emerging risk vectors that together shape near-term strategic choices. Our latest PW Consulting study — anchored on a 2025 base year, with a historical window from 2020–2025 and a forecasting horizon to 2032 — projects the market to grow at a compound annual growth rate (CAGR) of 6.98% through the forecast period. The market trajectory that underpins this forecast shows a recovery and acceleration from roughly USD 163.2 Million in 2020 to USD 215.0 Million in 2025, and further to an anticipated USD 344.8 Million by 2032.
Ethylhexylglycerin Market
Why this report matters to 2026 decision-makers
2026 will be a year in which executive teams must translate validated market momentum into defensible, capital-efficient actions. The combination of predictable volumetric growth and concentrated supplier dynamics — our CR3 is approximately 25.8% and CR5 near 29.4% — means that neither a purely defensive nor an aggressively expansionary posture will uniformly succeed. Instead, companies that take a calibrated approach — aligning commercial investments, supply-chain resilience, and regulatory preparedness — will maximize return on scarce deployment capital.
Ethylhexylglycerin Market
Key market dynamics shaping strategy
-
Demand fundamentals: Growth is being driven primarily by continued uptake in personal care and cosmetics formulations where ethylhexylglycerin functions as a multifunctional additive. Our demand model integrates historical consumption patterns with formulation trend analysis and projects a steady acceleration through the latter half of the forecast window.
Ethylhexylglycerin Market -
Upstream volatility: The principal upstream feedstock, 2-ethylhexanol, experienced significant price volatility linked to crude oil movements and refinery operating rates during Q3 2025. This creates margin pressure for producers and opportunistic pricing for buyers — a dynamic that favors firms with raw-material hedging capabilities or diversified feedstock access.
-
Regulatory & safety considerations: Occupational cases of allergic contact dermatitis associated with ethylhexylglycerin in alcohol-based hand disinfectants were documented in 2025. While incidence rates remain low relative to exposure, the event underscores the need for continuous safety monitoring, conservative labeling strategies, and proactive engagement with regulatory authorities to avoid sudden market access constraints.
-
Competitive structure: The market remains moderately fragmented with established specialty chemical suppliers coexisting alongside regional producers. This structure creates opportunities for differentiation through technical service, formulation partnerships, and supply security rather than purely on price.
What our report contains — practical, action-focused deliverables
The PW Consulting Ethylhexylglycerin Market study is built to be directly operational for commercial, supply-chain, and corporate development teams. Highlights include:
-
Validated market sizing and three-tier forecasting (conservative, baseline, upside) from 2026–2032, with transparent assumptions and sensitivity levers so teams can re-run scenarios under bespoke inputs.
-
Demand-driver mapping linking end-use formulation trends to volumetric consumption and pricing elasticity; the model supports “what-if” stress tests for raw-material shocks and substitution events.
-
Supply-side assessment, including capacity maps, utilization ranges, and logistics constraints; we identify chokepoints and levers for short-cycle ramp-up.
-
Regulatory risk matrix detailing documented safety incidents, potential exposures across formulations, and mitigation pathways (labeling, alternative formulations, stewardship programs).
-
Commercial playbook: tailored go-to-market options by buyer archetype (global CPGs, regional formulators, ingredient distributors), recommended commercial KPIs, channel economics, and sample negotiation playbooks for supply contracts under volatile feedstock pricing.
-
M&A and partnership scanner: a strategic screening tool that highlights target attributes (capability clusters, regional footholds, customer exposure) to inform inorganic growth or strategic alliances.
-
Scenario-driven pricing toolkit: models that translate feedstock price moves and utilization changes into margin impact across the value chain, enabling pricing cadence and rebate strategies aligned with corporate margin targets.
Competitive landscape — how to interpret the players
The report includes carefully curated company profiles of core market participants and regional specialists. Coverage extends beyond static descriptions to analyze capabilities that matter for near-term competition:
-
Schülke & Mayr GmbH (Norderstedt, Germany) — profile emphasizes their proprietary formulations and safety positioning relevant to hygiene and personal-care segments, and how those capabilities affect competitive dynamics in markets sensitive to antimicrobial claims. ( https://www.schuelke.com)
-
SACHEM, Inc. (Port St. Lucie, Florida, USA) — treated as a U.S.-based specialty chemical supplier with specific offerings tailored to formulators; our profile examines supply model resilience and technical support value. ( https://www.sacheminc.com)
-
Shinsung Materials Co., Ltd. (South Korea) — positioned in our analysis as a regional manufacturer whose cost and logistics footprint create strategic options for Asia-based customers; the profile assesses implications for regional sourcing strategies. ( http://ssmoled.com/eng/)
-
THOR Personal Care (United Kingdom) — featured for its formulation-focused product portfolio and customer engagement model with European personal-care brands; the profile highlights collaboration levers and technical-service differentiation. ( https://www.thor.com)
-
Belchem Industries (India) Pvt. Ltd. (India) — assessed in the report as a cost-competitive supplier with potential scale advantages for emerging-market demand; the profile discusses implications for price benchmarking and regional sourcing strategies. ( https://belchem.com)
Each company profile in the report includes strategic assessment points: supply-security posture, technical service capability, channel approach, and possible partnership/exit scenarios — actionable inputs for negotiation and competitive benchmarking.
Strategic recommendations for 2026
For executives preparing budgets and capital plans for 2026, we recommend a pragmatic, multi-pronged approach that balances growth capture with risk mitigation:
-
Supply resilience first: secure multi-source supply agreements with tiered pricing triggers tied to feedstock indices. If you are a buyer, prioritize suppliers offering hedging or pass-through transparency; if you are a supplier, offer contract structures that provide predictable volumes and margin protection.
-
Operational readiness for formulation shifts: invest in small-batch formulation labs and technical-service teams to accelerate co-development with strategic customers — this is where margin differential will increasingly be extracted.
-
Regulatory and safety playbook: implement enhanced adverse-event monitoring and conservative labeling strategies for alcohol-based disinfectant formulations. Proactively engage regulators and industry associations to shape guidance and avoid reactive restrictions.
-
Commercial segmentation: adopt value-based pricing for customers that prize technical support and supply security; use spot/premium pricing in volatile periods while protecting baseline sales with contracted volumes.
-
M&A and collaboration: use the market’s moderate fragmentation to explore tuck-in acquisitions for capability fill-ins (technical service, regional logistics), or structured partnerships to secure routes to high-growth end-markets without large upfront investments.
-
Data-driven decision processes: adopt the report’s scenario models in monthly planning cycles to stress-test budgets against feedstock swings and demand shocks; make capital spend contingent on predefined lead indicators rather than point forecasts.
How to use the study as an operational tool
Beyond being a reference, this study is a working document. Subscribers receive the forecasting models and sensitivity spreadsheets with clear documentation so internal teams can plug in proprietary contract terms and immediately see P&L and cash-flow impacts. We also provide a short-list of prioritized initiatives with estimated ROI and timelines — enabling 90–180 day action plans that align procurement, R&D, and commercial functions.
Closing: the strategic premium in disciplined information
The ethylhexylglycerin market offers both predictable growth and episodic disruption. The right information architecture — validated market sizing, supply-side vulnerability mapping, and scenario-driven margin models — converts market growth into shareholder value. Our PW Consulting study gives leaders the tools to operationalize those inputs in 2026, but the most valuable content (detailed segment analytics, the full list of supplier capabilities, and transaction-ready due-diligence appendices) is curated behind our source portal.
To move from insight to execution, access the full dataset and interactive models on our site — they contain the granular intelligence required to finalize contracts, prioritize capital, and design product strategies for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Ethylhexylglycerin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive headrest market to hit USD 272.3M by 2032 (5.7% CAGR)
By pmarketresearch, 2026-07-13
Automotive Headrest Market 2026: Strategic Imperatives for Decision-Makers
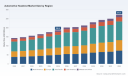
As OEMs and Tier‑1 suppliers plan product roadmaps and capital allocations for 2026, the automotive headrest market is no longer a peripheral sourcing decision — it has become a strategic focal point at the intersection of safety regulation, occupant comfort, and vehicle architecture transformation. PW Consulting’s latest Automotive Headrest Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market sizing, competitive dynamics, regulatory trajectories, and technology pathways to inform those decisions. Our analysis shows the market expanding from USD 186.4 Million in 2025 to an anticipated USD 272.3 Million by 2032, growing at a compound annual growth rate (CAGR) of 5.7% for the 2026–2032 forecast window — a trajectory that underlines both opportunity and the urgency to adapt.
Automotive Headrest Market
Why headrests matter in 2026 strategic planning
- Regulatory momentum is real and near‑term. Recent advances in whiplash prevention testing and an active rulemaking process on seating systems are pushing head restraint performance from a compliance checkbox to a design driver. The Insurance Institute for Highway Safety (IIHS) launched a new whiplash prevention evaluation in January 2026 and updated its protocol in late 2025, while national regulators have signaled further dynamic performance requirements that can materially affect seat architecture and supplier selection.
- Functional complexity is rising. Headrests are evolving from passive cushions to smart, dynamic elements: active movement to mitigate whiplash, thermal comfort integration, sensor embedding for occupant monitoring, and interfaces for ADAS and automated driving states. These capabilities change cost structures, manufacturing processes, and supplier qualifications.
- Value reallocation along the seat bill of materials. As vehicles electrify and interior user experience gains prominence, spend on smart and premium seating content is reallocating — creating pockets of higher margin for suppliers who can combine safety compliance with comfort and sustainability credentials.
Market trajectory and what it implies for investment choices
Between 2020 and 2025 the market demonstrated steady expansion, reflecting recovery from pandemic disruptions and accelerating content upgrades. With the 2026–2032 CAGR projected at 5.7%, the sector presents predictable growth but not runaway expansion; returns will therefore favor disciplined investments that either (a) reduce time‑to‑compliance with new dynamic test protocols, (b) unlock premium content (thermal, active safety, comfort sensors), or (c) materially lower cost or complexity through manufacturing innovation. In short, scale alone is not sufficient — strategic capabilities and speed to market will determine winners.
Automotive Headrest Market
Competitive structure: concentrated capabilities, fragmented supply chain
Our concentration analysis shows a market with moderate concentration: the top three players account for roughly 26.8% of the market and the top five about 32.1%. This structure indicates sizable market share for established seat system integrators alongside a broad base of specialized suppliers and regional manufacturers. That mix creates options for OEMs — from end‑to‑end seating system contracts to modular, best‑of‑breed headrest components — but it also increases complexity in supplier management, especially where safety certification and software integration are required.
Automotive Headrest Market
- Large seat system integrators (e.g., Adient, FORVIA, Toyota Boshoku, Lear). These firms offer integrated seat assemblies including advanced headrest mechanisms and are positioned to win OEM contracts where systems integration, warranty accountability, and content bundling matter.
- Specialists and component innovators (e.g., Windsor Machine Group, Innotec Group, Honasco, Polydesign, Tachi‑S). These players bring focused IP — tube forming, metal stays, precision guides, wrapped headrest covers — and are critical partners for differentiation at the component level.
- Hybrid models. Some companies combine design, proprietary mechanisms, and aftermarket channels to capture cross‑segment value, and these hybrid strategies will become more relevant as headrest functions increasingly cross into electronics and software domains.
Company plays and strategic postures
- Adient (Ireland) : Strength lies in system integration and adjustable/dynamic mechanisms — suited to OEM programs that prioritize turnkey seating solutions and regulatory compliance across markets.
- Lear Corporation (United States) : Competitive edge is in thermal comfort and smart integration — attractive for OEMs targeting premium cabin experiences and seamless sensor integration for occupant monitoring.
- Toyota Boshoku (Japan) : Deep OEM relationships and parts manufacturing capability enable strong platform‑level alignment, particularly where vehicle manufacturers seek co‑development and long lead‑time harmonization.
- Windsor Machine Group (Canada) : Differentiation through custom design and power headrest solutions — a fit for bespoke vehicle segments and aftermarket conversions.
- Polydesign Systems & Innotec Group (United States) : Focus on coverings and patented metal forming technologies respectively — critical for suppliers and OEMs seeking weight optimization and durability.
- Tachi‑S & Honasco (Japan, Germany) : Expertise in seat assemblies and precision headrest components positions these firms for premium and luxury segments where finish, fit, and component reliability are non‑negotiable.
Each player’s strategic choices — from vertical integration to technology licensing and localized manufacturing — will determine access to the fastest‑growing pockets in the forecast horizon. The full report provides comparative scorecards and supplier maps that are essential for supplier selection and procurement negotiation strategies.
Regulatory and technology catalysts
- Dynamic performance requirements. Regulatory signals (including NHTSA advance notices and updated IIHS protocols) emphasize forward movement and geometry/strength performance to reduce whiplash. Suppliers must demonstrate validated dynamic behavior under realistic crash conditions, not only static strength metrics.
- Sensorization and electronics. Embedded sensors for occupant detection, posture, and health monitoring are shifting headrests into the domain of software and functional safety, requiring suppliers to adopt ISO 26262 practices and software development capabilities.
- Lightweighting and materials innovation. Materials that balance energy absorption, recyclability, and tactile quality will determine cost and emissions outcomes for seat bills of materials — an important factor for OEM sustainability targets.
What the PW Consulting report provides (practical, decision‑ready content)
Our full study is organized to support executive and operational decision‑makers with actionable outputs:
- Market sizing and a rigorous forecast framework (historical 2020–2025; base year 2025; outlook 2026–2032) with scenario sensitivity to regulatory and technology adoption rates.
- Competitive landscape: profiles, capability matrices, and partnership/transaction case studies for the leading suppliers.
- Regulatory impact analysis: mapping of IIHS, NHTSA, Euro NCAP and regional test protocols to design requirements and cost implications.
- Technology deep dives: active head restraint mechanics, sensor integration pathways, thermal systems, and manufacturing innovations such as tube‑forming and modular subassemblies.
- Supply chain and cost models: material, process, and labor inputs with strategic levers for cost reduction without compromising safety performance.
- Commercial playbooks: go‑to‑market approaches for Tier‑1s and specialists, OEM procurement strategies, and M&A/partnership opportunities ranked by strategic fit and value creation potential.
- Risk register and mitigation plans: regulatory, supplier concentration, and tech obsolescence risks with recommended contingency actions.
To preserve competitive value and comply with “preview” disclosure best practices, the report deliberately withholds granular regional and application split figures in this summary. Readers seeking the detailed segmentation, unit economics, and supplier share tables are directed to the full report where we provide downloadable datasets and model access.
How to use these insights in 2026 planning cycles
- Short‑term (next 12 months): Prioritize compliance assessments and prototype validation for dynamic whiplash tests. Lock down suppliers with validated dynamic performance or establish engineering partnerships to accelerate validation.
- Medium‑term (12–36 months): Invest in modular headrest platforms that allow incremental feature addition (active movement, sensors, thermal units) to capture premium content without full redesigns of seat platforms.
- Long‑term (36+ months): Build software and systems competence (functional safety, data integration) or partner with electronics specialists — headrests will increasingly participate in vehicle state management, occupant interaction, and wellbeing ecosystems.
Closing: strategic choices for 2026
The headrest market’s predictable growth (USD 186.4 Million in 2025 to a projected USD 272.3 Million by 2032 at a 5.7% CAGR) belies the strategic inflection points embedded in regulatory shifts, technology convergence, and changing value pools in the seat bill of materials. For decision‑makers preparing 2026 investments, the question is not whether to engage, but how: choose partners who can validate dynamic safety performance, prioritize modular architectures that protect future feature upgrades, and embed software and material strategies into your headrest roadmap.
PW Consulting’s full Automotive Headrest Market study provides the detailed segmentation, supplier benchmarking, and economic models required to operationalize these choices. For executives seeking to convert the forecast into a winning strategy — supplier selection, product roadmap, or M&A target list — our report is designed as the playbook for 2026 action.
Contact PW Consulting to license the full report and access the underlying data models, scenario simulators, and supplier scorecards that senior decision‑makers rely on to turn market forecasts into competitive advantage.
For detailed analysis of this topic, please visit the official page: Automotive Headrest Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LABSA Market to Reach USD 7,964M by 2032 at 5.36% CAGR
By pmarketresearch, 2026-07-13
LABSA Market 2026: Strategic Intelligence for Executive Decisions
As companies plan capital allocation, procurement hedges, and M&A strategies for 2026, Linear Alkylbenzene Sulfonic Acid (LABSA) is re-emerging as a strategic commodity with both cyclical and structural opportunities. PW Consulting’s new market study—anchored on 2025 as the base year—combines a rigorous historical reconstruction (2020–2025) with a seven-year forecast (2026–2032). At the aggregate level the market has expanded meaningfully over the past half decade and, under our base-case trajectory, continues to grow at a mid-single-digit compound annual growth rate (CAGR) through 2032. This briefing highlights the actionable intelligence within the report and why it should influence board-level choices in 2026.
Linear Alkylbenzene Sulfonic Acid (LABSA) Market
Market snapshot: what the numbers mean for strategy
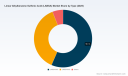
By 2025 the global LABSA market had more than recovered from pandemic-era disruptions and structural dislocations, reaching a multi-billion USD scale. Our modelling shows steady expansion into the forecast window, driven by persistent demand from detergents and adjacent surfactant applications, supportive regulatory preference for biodegradable chemistries, and incremental penetration of premium, sustainability-differentiated grades. Growth at a ~5.4% CAGR through 2032 implies a meaningful increase in absolute market size—large enough to justify greenfield projects in the right markets while also sustaining attractive returns on retrofits and capacity upgrades.
Linear Alkylbenzene Sulfonic Acid (LABSA) Market
Key dynamics shaping 2026 decisions
- Demand drivers: regulatory and end-use resilience.
Biodegradability standards in major markets continue to favour LABSA over some alternative surfactants, underpinning baseline consumption in household detergents and institutional cleaning. Long-term secular drivers—urbanization, rising hygiene standards in emerging markets, and growth in industrial cleaning—support a predictable demand floor even as near-term cycles oscillate.
Linear Alkylbenzene Sulfonic Acid (LABSA) Market - Feedstock and supply-chain risk.
Raw-material sourcing (notably n-paraffin and other Middle East-derived feedstocks) remains the dominant supply-side vulnerability. Recent disruptions to petrochemical flows and export bottlenecks have periodically tightened availability in Asia, prompting short-term price spikes and plant idling among smaller producers. For 2026, supply-risk management must be elevated from a procurement task to a strategic capability—covering dual-sourcing, strategic inventory, and long-term offtake contracts.
- Price volatility and operating leverage.
Pricing episodes in regional markets have shown how sensitive small and mid-tier manufacturers are to feedstock shocks. Companies with integrated LAB-to-LABSA platforms or strong purchasing clout have demonstrated superior resilience. Expect episodic margin compression for non-integrated players during supply squeezes unless they hedge or pass through costs effectively.
- Sustainability as a commercial inflection.
Producers investing in verified low-carbon or negative-carbon feedstocks and plant certifications are already capturing strategic advantages: differentiated access to sustainability-focused buyers, preferential contracting in Western markets, and improved long-term pricing power. Certification milestones, notably lifecycle and EDP declarations, are fast becoming prerequisites for large global buyers.
- Market structure and concentration.
The LABSA market exhibits a moderate concentration profile. A handful of global players hold sizeable positions, while the remainder is made up of regional specialists and independent producers. This structure produces localized pockets of competitiveness and recurring arbitrage opportunities for agile traders and regional consolidators.
Competitive landscape – what incumbents are doing
The competitive map blends global specialty chemical majors with regional integrated producers and nimble local suppliers. Large multinational surfactant companies maintain scale and technology advantages, using integrated LAB-LABSA assets and global offtake relationships to protect margins. Several Asia- and Middle East-based producers combine feedstock access with cost-position advantages for regional demand.
- Global specialty players are emphasizing sustainability-certified grades and premium product lines to preserve margins in developed markets.
- Regional integrated producers focus on reliability and cost competitiveness for domestic detergent manufacturers, while selectively exporting to neighbouring markets.
- Smaller independent plants compete on lead time, custom grades, and price—but face higher vulnerability to feedstock shocks without integration or strategic partners.
Notable market developments in the recent 12–18 months have sharpened competitive positioning: leading LAB/LABSA producers have announced verified low-carbon product offerings and certification milestones; at the same time, regional supply squeezes and logistics constraints have forced temporary consolidation among small manufacturers in certain markets. These shifts are re-pricing risk and re-defining the playbook for both sellers and buyers.
Strategic implications for 2026 planning
- Procurement and supply assurance become value creation levers.
Boards should treat raw-material sourcing strategy for LABSA as a primary business risk. Near-term tactics (multi-year purchase agreements, physical hedges, safety stocks) need to be paired with mid-term structural moves (vertical integration, strategic alliances with LAB producers, and regional proximate sourcing hubs).
- Capex decisions must be calibrated to demand certainty and feedstock visibility.
Given the market’s mid-single-digit CAGR, selective expansions—especially bolt-on capacity in high-growth corridors—can deliver attractive returns. However, greenfield green-chemical builds should be underpinned by long-term offtake or feedstock contracts and stress-tested across adverse supply scenarios.
- M&A and consolidation are tactical answers to fragmentation.
Acquisitions of regional producers offer rapid access to local customers, existing plant permits, and feedstock arrangements. Private equity and strategic acquirers should prioritise targets with strong local customer relationships and proven feedstock resilience.
- Product portfolio and premiumisation.
Investment in certified low-carbon LABSA grades, product quality upgrades, and differentiated formulations will unlock new buyer segments. Premiumisation is a viable route for value capture, particularly in export-oriented manufacturers.
- Operational resiliency and scenario planning.
Scenario modelling for force majeure events, port congestion, and rapid feedstock inflation should be standard in 2026 planning cycles. Operational playbooks—fast shutdown procedures, alternate logistics routes, and cross-border backup supply—will materially reduce downside.
What PW Consulting’s full report delivers (practical content)
Our study is built for decision-makers who need both strategic context and executable tools. The report provides:
- Market sizing and forward-looking demand scenarios through 2032, with transparent methodology and sensitivity testing.
- Supply-side mapping and a supplier risk matrix that grades integration, feedstock exposure, certification status, and force majeure vulnerability.
- Commercial playbooks for procurement, including contract term templates, hedging options, and inventory optimization models.
- Investment appraisals for greenfield and brownfield projects, with IRR ranges under multiple feedstock/price scenarios.
- M&A screening filters and target profiles, enabling rapid identification of acquisition candidates that de-risk supply or accelerate market access.
- Regulatory and sustainability matrix detailing certification pathways, compliance timelines, and premium capture strategies.
- Executive dashboard assets: scenario heatmaps, pricing-stress simulations, and a supplier scorecard ready for board review.
To respect competitive sensitivity and to follow the “trailer” principle, the public-facing brief highlights trends and tools—but the full dataset, regional breakouts, granular application mixes, and company-level financials are available only in the complete report and accompanying Excel models.
Actionable next steps for executives in 2026
- Run a rapid supplier resilience audit focused on feedstock concentration and alternative sourcing pathways.
- Stress-test any planned capital spend against a “supply-shock” scenario and a “sustainability-premium” uptake scenario.
- Prioritise partnerships or acquisitions that deliver feedstock security or certified low-carbon grades.
- Embed LABSA-specific KPIs in procurement and R&D agendas, linking incentive plans to supply stability and premium revenue targets.
- Engage with our scenario models to calibrate contract duration and pricing pass-through clauses for 2026 purchasing cycles.
Final perspective
LABSA’s outlook for the 2026 planning window is characterized by a stable structural demand backdrop, rising importance of sustainability credentials, and elevated supply-chain risk driven by feedstock geopolitics. These forces create asymmetric opportunities: companies that secure feedstock access, adopt certified low-carbon grades, and maintain commercial flexibility will capture disproportionate value. PW Consulting’s report equips executives with the analytical rigor and the practical instruments needed to convert market uncertainty into competitive advantage.
For the complete dataset, regional segmentation, supplier scorecards and model-ready outputs to support board-level decisions in 2026, access the full report and tools on our website.
For detailed analysis of this topic, please visit the official page: Linear Alkylbenzene Sulfonic Acid (LABSA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: XRF Analysers Market to grow at a 7.2% CAGR (2026-2032)
By pmarketresearch, 2026-07-13
XRF Analysers Market — 2026 Strategic Outlook and Executive Trailer
Executive trailer: why this briefing matters for 2026 decisions
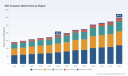
As organizations re-tool measurement capabilities across mining, environmental testing, healthcare, and regulated commodities, the XRF analysers market is evolving from a niche instrumentation category into a platform for compliance, process efficiency, and field-deployable analytics. Our PW Consulting market research — base year 2025, forecast window 2026–2032 — shows a sustained expansion driven by regulation, product miniaturization, and digital service models. Between 2020 and 2025 the market grew from roughly USD 141.5 Million to USD 186.5 Million, and our scenario-led forecast projects growth to approximately USD 300.2 Million by 2032 at a compound annual growth rate (CAGR) of 7.2% (2026–2032). These macro trajectories matter now: 2026 is the year many capital plans and product roadmaps will be either accelerated or deferred based on the signals in this report.
XRF Analysers Market
Why senior leaders should read this report
- Align CapEx and R&D budgets with a market growing at a mid-single-digit CAGR and shifting toward portable, connected analyzers.
- Prioritize procurement and regulatory readiness in response to near-term contract opportunities and emerging certification standards.
- Position product differentiation beyond hardware — e.g., analytics, detection limits, user ergonomics, and lifecycle services — to capture higher-margin recurring revenue.
- Identify M&A, JV and distribution plays in a market with moderate incumbent concentration (CR3 ~28.5%; CR5 ~36.2%).
What’s inside the report — the practical toolkit
The research is designed as a decision support package rather than a purely academic market map. Key deliverables include:
XRF Analysers Market
- Top‑line market sizing and a conservative/central/aggressive forecast model (base year 2025; forecast 2026–2032) with downloadable scenario inputs to stress-test CapEx decisions.
- Buyer needs matrices and procurement scorecards aligned to regulated use‑cases (e.g., medical device and food/commodity heavy metal screening), enabling rapid bid/no‑bid decisions for RFPs and public tenders.
- Supplier benchmarking and playbooks: technology attributes (EDXRF vs WDXRF vs micro‑XRF), form factor tradeoffs (benchtop vs handheld vs portable), and software connectivity KPIs for SaaS enablement.
- Regulatory intelligence and procurement signals — compiled RFIs/RFPs and certification trends — that identify timing and technical thresholds likely to drive 12–24 month purchase cycles.
- Commercial models and margin sensitivity analyses for instrumentation, consumables, and service/subscription bundles.
- Case studies and go‑to‑market templates for partnerships, channel expansion, and aftermarket service scaling.
Market dynamics shaping near-term strategy
Three dynamics are redefining supplier economics and buyer requirements in 2026:
XRF Analysers Market
- Regulatory acceleration: Public agencies and laboratories are actively procuring benchtop and portable XRF capacity for rapid, non‑destructive heavy metal screening. Recent government requests for information underscore the need for instruments that meet stringent detection thresholds and small‑sample workflows — a procurement signal with immediate implications for suppliers that can demonstrate low detection limits, reproducible sample handling, and documented quality systems.
- Form factor and feature differentiation: Innovation continues along two axes: extreme miniaturization (handheld/portable instruments with improved ergonomics and wireless connectivity) and high‑precision benchtop/micro‑XRF systems for regulated lab work. Vendors that offer an integrated product+software experience (cloud analytics, centralized device management, and secure audit trails) will capture a larger share of buyer wallet over one-time hardware sales.
- Standards and operator competency: Adoption of operator certification frameworks and ISO‑based standards is increasing. Buyers are beginning to demand certified operator programs and traceable measurement workflows, raising the bar on vendor documentation, training services, and software logging.
Recent industry signals you cannot ignore
- Federal procurement activity in 2026 signaled by an FDA sources‑sought for benchtop XRF instruments — an illustrative near‑term revenue opportunity for suppliers that can meet laboratory throughput and traceability requirements.
- Product refreshes from major vendors: launches of next‑generation handheld lines and ergonomic models at industry trade shows reflect ongoing investment in user experience, connectivity, and alloy identification features.
- Regulatory history and device safety events underscore compliance risk: past recalls and subsequent software remediation highlight the importance of robust lifecycle engineering and post‑market surveillance capabilities.
- Standards adoption by national certification bodies reinforces the need for vendor participation in operator certification and third‑party method validation.
Competitive landscape — strategic implications
Competition mixes global instrumentation leaders with specialized optics and software houses. The profile of incumbent and challenger behaviour points to varied routes for value capture:
- Malvern Panalytical (United Kingdom): Strong bench and portable portfolio with emphasis on regulated commodities and pharmaceutical powders. Strategic advantage: broad benchtop product family and deep applications support — an attractive partner for labs requiring validated workflows.
- Evident (United States): Focused on handheld analyzers with rapid screening capability. Strategic advantage: ergonomics and field usability — well positioned to win fast‑moving field procurement and contractor use cases.
- Horiba Instruments (Japan): EDXRF and micro‑XRF systems with credentials in pharmaceutical and clinical impurity screening. Strategic advantage: niche regulatory applications and micro‑analysis capabilities.
- Bruker Corporation (United States): Handheld TITAN series and ongoing product refreshes. Strategic advantage: recognized brand and extensive channel network — an effective contender in industrial and alloy ID markets.
- Thermo Fisher Scientific (United States): Portfolio spanning handheld Niton devices and integrated solutions for regulated industries. Strategic advantage: extensive service infrastructure and established lab procurement relationships.
- SPECTRO Analytical Instruments (Germany): Focus on high‑precision EDXRF spectrometers for regulated settings. Strategic advantage: precision instrumentation for customers needing lab‑grade repeatability.
- Rigaku Corporation (Japan): XRF analyzers tuned to coating, thin film, and medical device quality control. Strategic advantage: specialized solutions for process control and quality assurance.
Market concentration metrics indicate a moderate level of incumbent strength: the top three players account for under one‑third of market value, and the top five for just over one‑third. That competitive dispersion creates opportunities for niche specialists, regional challengers, and technology differentiators to scale via targeted partnerships, certification wins, or government contracts.
Actionable 90‑day playbook for corporate leaders
- Audit procurement pipelines for 2026–2027 to align tender responses with documented regulatory requirements (traceability, detection thresholds, operator certification).
- Prioritize product investments that improve connectivity, cloud analytics, and user workflows — these yield higher long‑term service revenues than incremental hardware upgrades alone.
- Build evidence of compliance readiness: invest in validation studies, third‑party method papers, and training modules that meet national certification expectations.
- Explore selective partnerships with specialty optics vendors or software providers to accelerate feature delivery without full internal development.
- Model M&A opportunities not as broad consolidation but as capability acquisitions (e.g., a micro‑XRF specialist, a SaaS analytics provider, or a regional service network) that close specific gaps identified in buyer scorecards.
Scenario framing and risk exposures
Our central forecast assumes a 7.2% CAGR through 2032, reflecting steady demand under current regulatory and economic conditions. Upside scenarios hinge on accelerated adoption by government labs and expanded use in clinical/food safety testing; downside risks include substitution by competing technologies, prolonged supply‑chain disruptions, and slower public procurement cycles. Use the report’s scenario model to quantify these paths and set internal decision thresholds for investment or market entry.
Closing — the strategic value of the full report
This introductory briefing demonstrates the kind of strategic clarity our full XRF Analysers Market report delivers: macro sizing, actionable buyer requirements, supplier scorecards, regulatory timelines, and an executable go‑to‑market playbook. To preserve competitive intelligence integrity, we intentionally withheld granular regional and application splits from this trailer — those detailed segmentations, unit‑level pricing benchmarks, and supplier financial models are contained within the full report and the downloadable forecast model. If your 2026 capital allocation, product roadmap, or M&A agenda depends on credible, scenario‑tested XRF market intelligence, the complete PW Consulting study is designed to be your operational handbook.
Contact PW Consulting to obtain access to the full dataset, supplier scorecards, and the interactive forecast model to support your 2026 strategic decisions.
For detailed analysis of this topic, please visit the official page: XRF Analysers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LED Grow Lights to Reach USD 5,596M by 2032 at 16.7% CAGR
By pmarketresearch, 2026-07-13
LED Grow Lights Market: Strategic Briefing for 2026 Decision-Makers
As capital allocators, product leaders, and commercial growers prepare strategic plans for 2026, understanding where the LED grow lights market is headed is no longer optional — it is foundational to commercial viability. PW Consulting’s newest industry study, grounded in a 2020–2025 historical analysis and a 2026–2032 forecast horizon, synthesizes market trajectories, standards shifts, and competitive dynamics into a practical, decision-ready framework. This briefing outlines the strategic value of that research for near-term corporate action while intentionally withholding granular segment tables to encourage direct access to the full report.
LED Grow Lights Market
Market trajectory at a glance
The global LED grow lights market is in a sustained expansion phase. Underpinning this growth is a robust compound annual growth rate (CAGR) of 16.7% across the forecast period, which translates to an expansion from a mid‑single‑billion base year to a multi‑billion market by the end of the decade. That scale-up signals not only rising demand from conventional greenhouse and indoor horticulture, but also accelerated adoption in high-density vertical and controlled-environment agriculture applications.
LED Grow Lights Market
What this means for 2026: organizations should assume accelerated product adoption curves, compressing time-to-value on innovations in spectral design, controls, and integrated systems. Investment windows for product launches, channel expansion, and M&A activity will be tight — and those who move with clarity will secure favorable positions in an industry that is maturing quickly but remains fragmented.
LED Grow Lights Market
Why this study matters to 2026 corporate strategy
- Market sizing with operational relevance: Our model reconciles historical shipment, pricing, and installed‑base dynamics to produce a revenue-led view (USD, base year 2025). That allows CFOs and commercial leads to stress-test capex and revenue plans under realistic adoption scenarios.
- Standards-driven product risk assessment: We integrate recent regulatory and standards updates — including the DesignLights Consortium’s horticultural technical updates — to quantify the compliance and relisting risk for product portfolios and to forecast retrofit demand.
- Competitive concentration insights: The market exhibits meaningful concentration at the top, with the leading three firms capturing close to half of market revenue and the top five approaching two‑thirds. This structure creates both competitive pressure and acquisition opportunity for mid-tier players.
- Actionable ROI guidance: Growers and systems integrators receive practical payback scenarios that map light efficacy, labor savings, and yield improvements into cash-flow impacts — the kind of numbers procurement teams need when negotiating long-term supply agreements.
Drivers, friction points and inflection signals
Three categories of forces will determine winners and losers across 2026 plans: technological performance, regulatory/standards evolution, and commercial economics.
- Performance improvements are now table stakes. Advances in efficacy (µmol/J), spectral tunability, and thermal management continue to lift the baseline for commercial solutions. The DesignLights Consortium’s Horticultural Technical Requirements V4.0 (effective April 18, 2025) significantly raises the bar for listed fixtures; product teams that cannot meet the new thresholds will face cooling demand in professional channels.
- Standards growth creates channel momentum and risk. The DesignLights Consortium’s QPL expanded rapidly in recent years: by early 2025, the program encompassed well over a thousand products and many dozens of manufacturers. That critical mass drives buyer confidence but also concentrates purchasing toward QPL-listed suppliers — a distributional shift that has immediate implications for OEM certification, lab testing pipelines, and product roadmaps.
- Commercial economics are shifting at the margins. Labor, incentives, and on-farm capital flows continue to reshape total cost of ownership (TCO) calculations. We track jurisdiction-level incentive changes and adoption patterns — for example, incentive downgrades in some residential markets and high LED canopy penetration in certain commercial sectors — and quantify how these changes alter payback thresholds for both suppliers and end-users.
Practical contents of the PW Consulting report
The full study is designed as a playbook for executives and includes:
- Integrated market model (historical and forecast revenue in USD, base year 2025) with sensitivity scenarios and a downloadable workbook enabling fast scenario toggles.
- Standards and compliance tracker that maps products to the DesignLights Consortium QPL lifecycle and V4.0 transition impacts.
- Go-to-market diagnostic for five commercial channels (commercial greenhouse, vertical farms, cannabis/controlled crops, R&D/growth chambers, and residential), including channel economics, procurement cycles, and buyer personas.
- Product strategy toolkit: feature-pricing matrices, modularization playbooks, and recommended R&D prioritization sequences for spectral platforms and integrated control systems.
- Supplier and M&A playbook: screening criteria, financial yardsticks, and a short list methodology for identifying bolt-on and transformational targets given current market concentration metrics.
- Operational annexes: installation labor models, fixture lifespan sensitivity, and capex/opex calculators optimized for grower-level decision-making.
Competitive landscape — who to watch
The industry is anchored by a mix of specialized horticultural brands and larger lighting incumbents. Our competitive analysis emphasizes strategic positioning rather than raw product lists:
- Valoya (Finland) — Patent-protected full‑spectrum platforms aimed at commercial cultivation, tissue culture, and growth chambers. Valoya’s differentiation is technical: targeted spectrums coupled with application-level guidance to extract premium per-fixture value.
- Signify (Fluence) (Netherlands) — An award-winning portfolio with strong footprints in cannabis, greenhouse, and vertical farming. Fluence combines global distribution scale with R&D investments that focus on both efficacy and integrated controls.
- Philips GreenPower (Netherlands) — Horticulture-focused toplighting and supplemental systems that leverage Philips’ scale and channel access. Their strength lies in system-level partnerships with greenhouse integrators and legacy lighting relationships.
- Illumitex (United States) — Focused on cannabis, vertical farming, and commercial horticulture with emphasis on scalability and reliability in North American markets.
- LumiGrow (United States) — Full‑spectrum solutions positioned for commercial and premium residential adoption; their go-to-market centers on data-backed controls and retrofit services.
- GE Current (Daintree) (United States) — Emphasis on manufacturing and supply-chain localization within the U.S., attractive to buyers focused on domestic sourcing and compliance.
- P.L. Light Systems (United States) — Noted for fixtures that align with horticultural standards and commercial grower requirements, often competing on spec-compliance and field support.
From a strategic standpoint, the top-tier firms have converted technical leadership and distribution depth into defensible positioning. Yet the CR3 and CR5 concentration figures indicate meaningful runway for consolidation and for specialist vendors that can package differentiated value (software-enabled control, research partnerships, or certified efficacy claims).
Strategic implications and near‑term plays for 2026
- Prioritize compliance-first product upgrades: Firms should audit product roadmaps against DLC V4.0 and QPL relisting timelines today. Non-compliant SKUs will face channel exclusion risks in professional tenders.
- Shift from fixture-only to systems economics: Buyers increasingly prize predictable yields and operational savings. Suppliers that bundle lights with controls, warranty frameworks, and outcome guarantees will command premium pricing and stronger renewal rates.
- Build a fast-follower product cadence: Given the steep CAGR, first-to-market advantages are ephemeral. A two-tiered launch strategy — flagship performance SKUs plus a configurable mid-market platform — balances margin capture and share expansion.
- Use the consolidation window: With the market leader concentration leaving gaps across certain channels and geographies, 2026 is an opportunistic year for acquisitive growth — particularly for assets that add software, testing labs, or regional manufacturing capacity.
- Operationalize grower economics: Sales teams must present farm-level ROI narratives, not just lumens/efficacy claims. Our report provides ready-to-use TCO slides and payback calculators for commercial negotiations.
How to use this analysis
Leaders preparing 2026 plans should use this briefing as a decision accelerator. The full PW Consulting report contains the detailed segmentation, product-level revenue forecasts, and scenario workbooks organizations need to build investment cases, structure partnerships, and prioritize product investments. We intentionally withhold detailed segment tables here to preserve the full value proposition of the comprehensive dataset and interactive model available in the report package.
For executives seeking immediate tactical support, our advisory services can map the report’s insights into three deliverables in twelve weeks: a tailored market-entry or expansion roadmap, a prioritized product development plan aligned to DLC V4.0, and an M&A shortlist with financial filters and integration playbooks.
Next steps
To convert these insights into a defensible 2026 strategy, request the report and model access. Companies that align R&D, channel strategy, and compliance programs during the 2025–2026 transition will capture disproportionately more of the upside created by a market growing at a 16.7% CAGR. PW Consulting stands ready to brief your leadership team and translate the analysis into executable plans that preserve margin, reduce technical and certification risk, and accelerate time to commercial traction.
For detailed analysis of this topic, please visit the official page: LED Grow Lights Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mosquito Killer Market Poised for 6.2% CAGR Through 2032
By pmarketresearch, 2026-07-13
Mosquito Killer Market 2026: Strategic Preview for Decision-Makers
PW Consulting’s latest Mosquito Killer Market study—anchored on a 2025 base year with historical coverage from 2020–2025 and forecasts through 2032—arrives at a clear strategic conclusion: this is a growth market defined by technology-driven product differentiation, regulatory friction, and fragmented competition. The market expanded from roughly USD 150 million in 2020 to about USD 215 million in 2025 and is projected to grow at a steady compound annual growth rate (CAGR) of 6.2% to reach approximately USD 345 million by 2032. For executives preparing 2026 playbooks, the study is designed to convert that macro momentum into actionable choices—where to invest, what to build, and how to defend.
Mosquito Killer Market
Why this study matters for 2026 decisions
-
Clarity on growth trajectories: With a robust historical base and a clear 2026–2032 forecast horizon, the report translates headline CAGR into scenario-based demands on product lines, production capacity, and channel investments.
Mosquito Killer Market -
Risk-adjusted regulatory mapping: EPA and related agency requirements materially affect time-to-market and product claims. Our analysis quantifies how regulatory timelines (from months to multi-year field trials) influence portfolio sequencing and partnership choices.
Mosquito Killer Market -
Competitive granularity without giving away playbooks: We profile the strategic posture of leading manufacturers and new entrants—highlighting capabilities, go-to-market approaches, and technological differentiators—so leaders can model responses without revealing proprietary market splits in this preview.
-
Investment-grade commercial intelligence: The study provides investor-facing assessments—capex needs, likely margins by device architecture, and acquisition targets—calibrated to a market that remains largely fragmented (top-3 concentration around 28.5% and top-5 near 32.0%).
Market dynamics: What’s driving growth in plain terms
-
Technology push and product diversification: The market is moving beyond basic UV zappers. Innovations—app-controlled smart traps, integration of fans and glue boards, photocatalytic approaches, solar-powered lamps, and lure chemistries designed to disrupt breeding behavior—are driving consumer and commercial upgrades.
-
Channel expansion and distribution partnerships: Traditional retail still matters, but growth is accelerating through specialized distribution alliances and online direct-to-consumer models. Distribution plays (including expanded agreements with pest-control wholesalers) shorten commercial adoption cycles for higher-priced, feature-rich devices.
-
Regulatory friction as a market shaper: EPA and allied agency requirements for devices that claim pesticidal effects create both entry barriers and strategic windows. Registration timelines and the need for field efficacy data mean first-mover advantage on verified claims is attainable but expensive and time-consuming.
-
Price and performance bifurcation: The market is stratifying into low-cost commodity zappers and higher-margin, feature-rich systems positioned for yard-level, urban, and municipal users. The mid-market is the battleground for volume and brand loyalty.
-
Geography matters—operationally: Climatic and vector-borne disease patterns influence demand seasonality and product mix. Supply-chain flexibility to shift inventory and localize firmware/features for region-specific pests is a competitive differentiator.
Competitive landscape—who’s doing what
The competitive field is populated by legacy electronics firms, pest-control specialists, and nimble startups. Below are high-level strategic positions of representative players identified in the study; these observations are designed to help senior teams benchmark and prioritize partnerships or M&A targets.
-
Legacy consumer-electronics and outdoor brands (e.g., Flowtron, Aspectek, Armatron, KAZ-Stinger): These players leverage established manufacturing and retail distribution. Their strength is scale in low- to mid-price segments and reliable supply chains; their challenge is modernizing products for smart and sustainable buyer preferences.
-
Smart-device and premium innovators (e.g., Mosqitter, Katchy, Dynatrap): Focused on app control, sensor integration, and multi-modal trapping (light + fan + glue), these firms target consumers willing to pay for efficacy and convenience. Mosqitter’s recent launch of a large-area, app-driven Grand model is a case in point—indicating a push into enterprise and large property markets.
-
Entomology-driven and surveillance specialists (e.g., Biogents, Veseris/In2Care): These companies differentiate via science-backed attractants, monitoring tools, and integrated population-control systems. Their products appeal to public-health agencies and commercial pest-management services that require validated efficacy.
-
OEMs and low-cost suppliers (e.g., a number of Chinese and US-based manufacturers): These firms dominate price-sensitive channels and power private-label assortments. Their edge is cost; their risk is being squeezed as buyers demand feature parity with premium devices.
-
Adjacent-category entrants (e.g., Thermacell Repellents, Ryobi): Companies with strong consumer brands and alternative technologies are expanding offerings (repellent cartridges, cordless zappers), accelerating category adoption among users seeking integrated outdoor comfort solutions.
Regulatory and commercialization playbook
-
Plan for elongated approval cycles: If your product will carry pesticidal claims, EPA registration pathways and field-trial requirements often extend lead times. The guidance landscape shows reviews from months to years and field datasets that can stretch total product qualification to multiple years—hence staged launches and parallel claims (e.g., “captures” vs “kills”) are tactical levers.
-
Leverage validated science for premium pricing: Devices that can demonstrate entomological efficacy—especially against disease vectors such as Aedes species—command trust and premium position in municipal and commercial tenders.
-
Channel partnerships reduce commercialization friction: Distribution agreements with pest-control wholesalers and retail channels can offset the slow adoption curve for expensive units while enabling field trials required by regulators.
-
Localization is not optional: From lure formulation to energy and connectivity considerations, successful global deployments require product variants and firmware that reflect local expectations and regulatory constraints.
Strategic scenarios and investment priorities for 2026
-
Core stabilization + product upgrade: For established suppliers, prioritize modular upgrades (smart controls, battery/solar options) to protect margins while keeping SKU complexity manageable.
-
Scale-through-distribution for mid-sized players: If you cannot or do not want to underwrite long regulatory timelines, secure distribution partnerships and co-branded assortments that emphasize fast-selling, claim-light products while developing a validated premium line.
-
Science-first market entry for specialized firms: Invest in entomological partnerships and field studies that create defensible differentiation and open doors to municipal contracts and public-health procurement.
-
M&A and bolt-on acquisitions: Given the market’s fragmentation, acquisitive strategies that add science IP, distribution reach, or smart-software capabilities are likely to deliver synergies faster than greenfield R&D alone.
What the full PW Consulting report contains (practical deliverables)
-
Detailed market-sizing and methodology notes that reconcile historical sales with forecast scenarios through 2032, including sensitivity analyses for price, seasonality, and regulation.
-
Competitive profiles with strategic capabilities maps, product roadmaps, and channel footprints for more than a dozen manufacturers and suppliers.
-
Regulatory playbook and timelines: an actionable map of EPA/FDA expectations, evidence requirements, and suggested field-trial protocols to accelerate approvals.
-
Go-to-market playbooks for three buyer segments (low-cost retail, premium consumer, and institutional/municipal), including margin models, SKU rationalization templates, and channel commission frameworks.
-
Investment and M&A screening tools: value-creation checklists, integration red flags, and a short-list of target capabilities that yield the fastest ROI in the 2026–2028 window.
-
New-product radar and innovation tracker that monitors product launches, patents, and partnerships—updated to include recent launches and distribution moves observed through late 2025.
Key near-term signals to monitor in 2026
-
Regulatory milestones and any EPA guidance changes that could simplify or tighten product claims; even incremental guidance shifts materially affect go-to-market timing.
-
Distribution consolidation or new national agreements—these accelerate adoption of premium devices.
-
Proof-of-concept results from large-area smart traps and science-backed attractant systems; positive field performance will reshape tender dynamics for municipal programs.
-
Supply-chain stressors (components, solar modules, fans) and the cost of compliance testing; these drive decisions on near-shoring versus cost-lead manufacturing.
PW Consulting’s Mosquito Killer Market study offers a concise, implementable path from the broad macro trend—USD 150M in 2020 to USD 215M in 2025 and a projected USD 345M by 2032 at a 6.2% CAGR—through to product, regulatory, and channel choices that define winners in 2026. This preview intentionally highlights strategic direction while withholding detailed segment breakdowns; that granularity is reserved for the full report and interactive dashboards hosted on our source page. For teams preparing budgets, R&D roadmaps, or M&A screens in 2026, the full study is the operational roadmap you need to convert market growth into sustained advantage.
For detailed analysis of this topic, please visit the official page: Mosquito Killer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Heptane Market 2026: Strategic Intelligence for Decision‑Makers — A PW Consulting Preview
As companies set strategy for 2026, the heptane market is transitioning from a commodity solvent into a differentiated industrial input shaped by purity, recovery technology, and regulatory boundaries. PW Consulting’s forthcoming Heptane Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes commercial, regulatory, and technological signals to translate a modest macro expansion (3.1% CAGR over the forecast period) into concrete choices for suppliers, buyers, investors, and policy teams. Below is a strategic preview that highlights where value will be created and where critical blind spots remain — the full dataset and segment-level breakouts are reserved for the complete report.
Heptane Market
Headline Market Trajectory
The global heptane market recorded steady expansion through the recent five-year horizon, rising from roughly USD 163 million in 2020 to about USD 215 million in 2025 (revenue unit: Million USD). Our base-case forecast projects continued growth into the next decade, with the market moving toward an estimated USD 345 million by 2032 under a 3.1% CAGR for 2026–2032. This trajectory reflects a blend of incremental demand in specialty applications and supply-side adjustments rather than rapid structural shifts — a dynamic that rewards precise commercial positioning more than scale alone.
Heptane Market
Why 2026 Is a Strategic Inflection Point
- Regulatory acceleration: Environmental restrictions on volatile organic compounds (VOCs) are now a primary restraint in the heptane market. These rules are driving formulation changes in coatings and consumer applications and increasing demand for higher-purity grades in regulated industries.
- Purity and recovery premium: Advances in separation and reclamation (notably membrane-based systems) are creating a two-tier market — commoditised solvent supply on one side and premium, ultra-pure, or reclaimed streams on the other.
- Fragmented supply: Market concentration remains low (CR3 ~24.6%; CR5 ~26.2%), indicating many regional and specialty players. That fragmentation increases tactical opportunities for aggregation, selective upstream investment, and commercial playbooks oriented around service and compliance rather than volume alone.
Supply-Side Dynamics and What They Mean for Procurement
Recent capacity moves and technology deployments are reshaping sourcing risk profiles. Major incumbents have targeted purification and downstream partnerships: for example, advanced purification capacity came online in the US in 2025, and a sizeable Middle Eastern expansion completed its ramp for Asia-Pacific supply. At the same time, feedstock pricing softened in mid‑2025 — U.S. bench prices reached about USD 2,322 per metric tonne in Q2 2025 as domestic availability outpaced near-term demand. These twin trends — increased purified capacity and downward price pressure — create short-term buyer leverage, but also raise the bar for suppliers that compete on quality, service, and regulatory coverage (e.g., registration and compliance for export markets).
Heptane Market
Demand Evolution — Not All Consumption Is Equal
Heptane demand is being reallocated rather than simply expanding. Traditional uses such as fuel-related streams and laboratory solvents remain material, but growth pockets are driven by:
- High-purity solvent needs in pharmaceutical and specialty chemical synthesis.
- Low-VOC coating formulations that rely on specific solvent profiles.
- Agrochemical and extraction segments where regulatory and purity requirements differ by market.
Importantly, technology that reduces gross solvent consumption — demonstrated by recent commercial-scale solvent recovery systems achieving recovery efficiencies near industry-leading benchmarks — shifts procurement decisions from “how much” to “how clean and how recoverable.” For buyers, capital investment in in‑plant recovery systems can materially lower exposure to feedstock price volatility and supply disruptions.
Competitive Landscape — Patterns and Strategic Implications
The competitive map combines global majors, regional refiners, and specialty distributors. Representative strategic moves observed through 2025 include:
- Scale plus quality: Major energy‑chemical players have invested in high‑purity purification capacity to capture margin in pharmaceutical and coating segments.
- Partnerships to shape demand: Joint ventures between chemical suppliers and formulators are forming to accelerate low‑VOC coating portfolios, effectively co‑creating demand for specific solvent grades.
- Regional specialization: Several Asia‑based producers are targeting export and compliance requirements (including European registration regimes), while European and North American specialty houses compete on technical service and high‑purity offerings.
For incumbents and new entrants alike, three playbooks dominate: invest in purification and reclamation technology; develop co‑innovation ties with formulators to lock in product specifications; and secure regulatory readiness (REACH/HS code alignment and export documentation) to access high-value markets.
Technology & Sustainability — Where Competitive Advantage Emerges
Two technological trajectories are particularly consequential. First, membrane and advanced separation systems now operate at commercial scale, enabling purity levels that unlock pharmaceutical and advanced coatings applications. Second, solvent reclamation technologies are shifting lifecycle economics: demonstrated installations report double‑digit reductions in fresh solvent consumption, creating demand-side resilience and an environmental narrative that resonates with procurement and investor ESG frameworks.
Regulation and Trade — Practical Compliance Risks
Regulatory developments are imposing both risk and opportunity. A notable trade classification update in 2025 (revision of customs coding for heptane in a major exporter) underscores the operational friction companies face in cross-border logistics and compliance. For organizations trading in global supply chains, harmonizing tariff codes and ensuring registration/REACH status across target markets is no longer an administrative footnote — it is a commercial imperative.
Strategic Recommendations for 2026 Decision-Makers
- Producers: Prioritize investments that differentiate on purity and circularity (purification lines, membrane separation, on‑site reclamation services). Structure offtake contracts should embed quality premiums and flexibility clauses for reclaimed streams.
- Buyers (pharma, coatings, formulators): Redesign sourcing playbooks to value recovery and supplier compliance capabilities. Pilot on-site recovery where capex payback aligns with procurement savings; secure multi-supplier agreements with technical performance SLAs rather than price-only contracts.
- Investors: Seek asymmetric return opportunities in specialty purification technologies, solvent-recovery service providers, and regional consolidators that can scale compliance capabilities rapidly.
- Policy and compliance teams: Track harmonization of customs classifications and VOC regulation timelines. Early engagement with suppliers on registration and documentation can prevent costly supply interruptions during regulatory rollouts.
What the Full PW Consulting Heptane Report Contains
The complete study is designed as an operational toolkit for 2026 decisions. Deliverables include:
- A calibrated market model (historical 2020–2025; forecast 2026–2032) with scenario analysis and sensitivity testing around price, regulatory tightening, and recovery adoption.
- Supplier benchmarking and a verified supplier matrix that captures capacity, purity capabilities, compliance status, and recent investments.
- Commercial playbooks for buyers and sellers, including contract templates, SLA constructs for reclaimed solvent, and a procurement scorecard aligned to purity and sustainability metrics.
- Capex build vs. buy analyses for onsite recovery technologies and ROI timetables under multiple price and utilization assumptions.
- A regulatory tracker and trade code implications matrix to mitigate cross-border compliance risk.
- Expert interviews and primary-source validation of recent capacity moves and joint ventures.
Note: To preserve strategic value for subscribers, the report preview intentionally limits disclosure of granular regional and application splits and proprietary segment tables. Access to the full segmentation, supplier-level volumes, and price pathway spreadsheets is available through the PW Consulting report portal.
Final Thought — From Commodity to Managed Input
Heptane’s near-term market growth is steady rather than explosive, but the composition of demand and the cost-of-ownership economics are changing quickly. A 3.1% CAGR and a projected market approaching USD 345 million by 2032 mask a critical truth for 2026 strategy: commercial outcomes will be determined less by raw volume and more by who manages purity, recovery, and regulatory alignment best. Organizations that act now to lock in technical partnerships, invest selectively in recovery infrastructure, and redesign contracts to reward compliance and circularity will capture the disproportionate upside in the next planning cycle.
For decision-makers preparing budgets, M&A screens, or procurement strategies for 2026, PW Consulting’s Heptane Market report provides the quantitative backbone and pragmatic playbooks required to convert market signals into defensible action. Visit the PW Consulting Heptane Market page to access the full report, dataset, and proprietary supplier matrices.
For detailed analysis of this topic, please visit the official page: Heptane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Carbon Brake Disc Market Set to Grow at 6.1% CAGR Through 2032
By pmarketresearch, 2026-07-13
Aircraft Carbon Brake Disc Market: Strategic Briefing for 2026 Corporate Decision-Making
Executive Snapshot
The aircraft carbon brake disc market is entering a phase of measured but sustained expansion. Our analysis at PW Consulting places the global market at approximately USD 1.11 Billion in the 2025 base year, with an expected compound annual growth rate (CAGR) of roughly 6.1% through our 2026–2032 forecast window. By 2032, the market is projected to approach the high single‑digit billions range, driven by fleet renewal, rising aircraft utilization following normalization of air travel, replacement cycles in both commercial and military segments, and ongoing material and production innovations.
Aircraft Carbon Brake Disc Market
Why This Report Matters for 2026 Decisions
Leading aerospace suppliers, OEM procurement teams, private equity investors, and Tier‑2 component manufacturers will confront a clustered market structure, accelerating capital investments, and evolving technical requirements in 2026. Decisions made in 2026 — about capacity, strategic partnerships, product development roadmaps, and procurement contracting — will determine competitive positioning for the rest of the decade. This report provides the analytical foundation to make those choices with confidence, combining historical elasticity (2020–2025) and scenario‑based forecasts (2026–2032) with actionable supplier intelligence and risk matrices.
Aircraft Carbon Brake Disc Market
Market Dynamics: What’s Driving Growth
-
Fleet turnover and replacement: Global airline and military operators are refreshing landing‑gear and braking subsystems as part of broader fleet modernization programs. Replacement cycles for carbon brake discs remain a core demand driver, supported by rising flight hours and heavier mission profiles on certain aircraft types.
Aircraft Carbon Brake Disc Market -
Materials and performance innovation: High‑strength carbon and carbon‑ceramic composite formulations, multi‑layer functional architectures, and proprietary processing routes are improving thermal and mechanical durability. These material advances are lengthening service intervals for some platforms and enabling weight reductions — both financially and operationally significant for lessors and operators.
-
Capacity investments and automation: Major suppliers are committing to large, automated facilities to increase throughput, improve quality consistency, and reduce energy intensity. These investments are also framed as emissions and sustainability initiatives that resonate with OEMs and national regulators.
-
Military procurement tailwinds: Continued defense spend and sustainment contracts provide a stable, often higher‑margin, revenue stream. Multiple suppliers hold certifications and delivery agreements for military platforms, underpinning a dual commercial/military demand profile that smooths cyclical exposure.
Competitive Landscape: Profiles & Strategic Signals
The market is moderately concentrated. The top three suppliers control a significant portion of the global installed base, and the top five account for the majority of revenue and certified platform coverage. This configuration creates both barriers and opportunities: incumbents benefit from scale, certification portfolios, and long OEM relationships, while focused challengers can win share through flexible supply, competitive pricing, and niche technical advantages.
-
Safran — A market pioneer and de facto leader, Safran operates multi‑continental manufacturing footprints and is scaling to meet future demand with a new 30,000 m² automated facility planned at Plaine de l’Ain Industrial Park, slated for operations by 2030. The plant is positioned to support a material production uplift over the coming decade and is explicitly linked to efficiency and emissions reductions. Safran’s installed program list — spanning major Airbus and Boeing platforms — and its broad airline and military customer base make it the strategic fulcrum for many supply chains.
-
Meggitt Aircraft Braking Systems — A well‑established player with NuCarb carbon brakes and recent military delivery awards, Meggitt underscores how supply contracts spanning civil and defense segments can stabilize volumes and provide a platform for growth. Its active long‑term supply engagements with OEM programs are a signal for procurement teams considering supplier risk sharing.
-
Honeywell and Collins Aerospace — Both firms supply integrated braking and landing systems and bring systems‑level integration expertise, aftermarket service networks, and installed base scale. Their proprietary technologies and aftersales footprints (including large installed aircraft counts) are strategic differentiators when customers evaluate lifecycle costs and reliability.
-
China‑based manufacturers and materials specialists — A cohort of Chinese producers has secured airworthiness certifications for prominent commercial platforms and is aggressively expanding supply to domestic and export markets. Their emergence is shaping global competitive dynamics and creating alternate sourcing pathways for OEMs and MRO networks.
-
Materials and component specialists — European and global material suppliers and component houses play a pivotal role as upstream enablers. Proprietary materials (including carbon‑carbon and specialized composite variants) influence product differentiation and aftermarket service life.
Strategic Themes for 2026 Planning
-
Build vs. buy decisions: Organizations must evaluate the total cost of ownership, certification timeline, and volume economics. For high‑volume OEMs or nationalized suppliers, internalizing production with targeted automation may make strategic sense; for others, long‑term supply partnerships reduce certification burden and capital outlay.
-
Capacity and geographic exposure: The next wave of capacity additions by established suppliers will shift lead times and pricing power. Procurement teams should stress‑test supplier roadmaps, prioritize suppliers with redundant geographically distributed capacity, and factor in political and trade considerations when qualifying second sources.
-
Certification and technical moat: Certification portfolios for commercial and military platforms remain a high barrier to entry. Investment in testing, materials R&D, and close collaboration with airworthiness authorities accelerates access to OEM programs and creates long‑term revenue stickiness.
-
Aftermarket and MRO strategies: With an aging installed base in some fleets and intensified fleet activity, aftermarket service and parts availability present revenue upside. Suppliers with robust MRO partnerships can capture both replacement parts and life‑cycle upgrades.
-
Sustainability and operational efficiency: Automation projects are increasingly framed around energy use, waste reduction, and emissions. Suppliers articulating verifiable sustainability metrics can influence OEM procurement decisions tied to ESG commitments.
What the PW Consulting Report Delivers (Practical Elements)
-
A concise executive dashboard with historical market sizing (2020–2025), and a transparent forecast model through 2032 built on scenario analysis and sensitivity testing.
-
A supplier‑level competitive map with capabilities, planned capacity investments, program certifications, and strategic risk profiles — including the closest comparable programs and aftermarket exposure for each named supplier.
-
A materials and technology primer that explains performance trade‑offs (durability, thermal capacity, weight) and identifies which material pathways are most likely to influence procurement specifications.
-
Procurement playbooks and negotiation levers tailored to OEMs, Tier‑1s, and MROs — including contract structures, service level expectations, and suggested KPIs for supplier governance.
-
Risk matrices for supply chain disruption, certification lead times, and geopolitical exposure, with recommended mitigation strategies and contingency sourcing options.
Practical Implications: Actionable Steps for 2026
-
For OEM procurement leaders: Initiate multi‑year framework agreements with tiered pricing tied to verified production capacity expansions, and require transparency on automation and sustainability milestones from existing prime suppliers.
-
For component manufacturers and potential entrants: Prioritize certification paths that map to the largest OEM programs and invest in retrofit solutions that reduce entry barriers into aftermarket channels.
-
For investors and corporate development teams: Use the report’s scenario outputs to assess M&A timing and target profiles — particularly suppliers with niche material IP, in‑place military certifications, or cost‑advantaged regional capacity.
-
For MRO networks: Reassess stocking policies and repair capabilities in light of projected service life improvements from newer materials; a small increase in repair throughput can yield outsized aftermarket returns.
Limitations & Where to Find the Full Intelligence
This briefing highlights the core themes and strategic levers. For readers requiring detailed segmentation tables, regional and application splits, company revenue/market‑share estimates, and the full quantitative model underlying the 6.1% CAGR and 2026–2032 outlook, the full PW Consulting report includes comprehensive datasets, supplier scorecards, and downloadable models. The full report also provides validated citations, contractual timelines for key supplier agreements, and the raw inputs used in scenario simulations.
Concluding Perspective
The aircraft carbon brake disc market in 2026 sits at a tactical inflection: stable structural demand intersecting with supplier capacity shifts, material innovation, and a concentrated competitive set. Organizations that align procurement, engineering, and capital planning around the trajectories described here — while leveraging the deeper, transaction‑level intelligence in the full report — will be best placed to capture value, reduce supply risk, and influence product roadmaps during the next growth cycle.
For detailed analysis of this topic, please visit the official page: Aircraft Carbon Brake Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com