

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LED Grow Lights to Reach USD 5,596M by 2032 at 16.7% CAGR

LED Grow Lights Market: Strategic Briefing for 2026 Decision-Makers
As capital allocators, product leaders, and commercial growers prepare strategic plans for 2026, understanding where the LED grow lights market is headed is no longer optional — it is foundational to commercial viability. PW Consulting’s newest industry study, grounded in a 2020–2025 historical analysis and a 2026–2032 forecast horizon, synthesizes market trajectories, standards shifts, and competitive dynamics into a practical, decision-ready framework. This briefing outlines the strategic value of that research for near-term corporate action while intentionally withholding granular segment tables to encourage direct access to the full report.
LED Grow Lights Market
Market trajectory at a glance
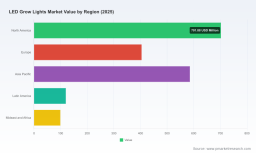
The global LED grow lights market is in a sustained expansion phase. Underpinning this growth is a robust compound annual growth rate (CAGR) of 16.7% across the forecast period, which translates to an expansion from a mid‑single‑billion base year to a multi‑billion market by the end of the decade. That scale-up signals not only rising demand from conventional greenhouse and indoor horticulture, but also accelerated adoption in high-density vertical and controlled-environment agriculture applications.
LED Grow Lights Market
What this means for 2026: organizations should assume accelerated product adoption curves, compressing time-to-value on innovations in spectral design, controls, and integrated systems. Investment windows for product launches, channel expansion, and M&A activity will be tight — and those who move with clarity will secure favorable positions in an industry that is maturing quickly but remains fragmented.
LED Grow Lights Market
Why this study matters to 2026 corporate strategy
- Market sizing with operational relevance: Our model reconciles historical shipment, pricing, and installed‑base dynamics to produce a revenue-led view (USD, base year 2025). That allows CFOs and commercial leads to stress-test capex and revenue plans under realistic adoption scenarios.
- Standards-driven product risk assessment: We integrate recent regulatory and standards updates — including the DesignLights Consortium’s horticultural technical updates — to quantify the compliance and relisting risk for product portfolios and to forecast retrofit demand.
- Competitive concentration insights: The market exhibits meaningful concentration at the top, with the leading three firms capturing close to half of market revenue and the top five approaching two‑thirds. This structure creates both competitive pressure and acquisition opportunity for mid-tier players.
- Actionable ROI guidance: Growers and systems integrators receive practical payback scenarios that map light efficacy, labor savings, and yield improvements into cash-flow impacts — the kind of numbers procurement teams need when negotiating long-term supply agreements.
Drivers, friction points and inflection signals
Three categories of forces will determine winners and losers across 2026 plans: technological performance, regulatory/standards evolution, and commercial economics.
- Performance improvements are now table stakes. Advances in efficacy (µmol/J), spectral tunability, and thermal management continue to lift the baseline for commercial solutions. The DesignLights Consortium’s Horticultural Technical Requirements V4.0 (effective April 18, 2025) significantly raises the bar for listed fixtures; product teams that cannot meet the new thresholds will face cooling demand in professional channels.
- Standards growth creates channel momentum and risk. The DesignLights Consortium’s QPL expanded rapidly in recent years: by early 2025, the program encompassed well over a thousand products and many dozens of manufacturers. That critical mass drives buyer confidence but also concentrates purchasing toward QPL-listed suppliers — a distributional shift that has immediate implications for OEM certification, lab testing pipelines, and product roadmaps.
- Commercial economics are shifting at the margins. Labor, incentives, and on-farm capital flows continue to reshape total cost of ownership (TCO) calculations. We track jurisdiction-level incentive changes and adoption patterns — for example, incentive downgrades in some residential markets and high LED canopy penetration in certain commercial sectors — and quantify how these changes alter payback thresholds for both suppliers and end-users.
Practical contents of the PW Consulting report
The full study is designed as a playbook for executives and includes:
- Integrated market model (historical and forecast revenue in USD, base year 2025) with sensitivity scenarios and a downloadable workbook enabling fast scenario toggles.
- Standards and compliance tracker that maps products to the DesignLights Consortium QPL lifecycle and V4.0 transition impacts.
- Go-to-market diagnostic for five commercial channels (commercial greenhouse, vertical farms, cannabis/controlled crops, R&D/growth chambers, and residential), including channel economics, procurement cycles, and buyer personas.
- Product strategy toolkit: feature-pricing matrices, modularization playbooks, and recommended R&D prioritization sequences for spectral platforms and integrated control systems.
- Supplier and M&A playbook: screening criteria, financial yardsticks, and a short list methodology for identifying bolt-on and transformational targets given current market concentration metrics.
- Operational annexes: installation labor models, fixture lifespan sensitivity, and capex/opex calculators optimized for grower-level decision-making.
Competitive landscape — who to watch
The industry is anchored by a mix of specialized horticultural brands and larger lighting incumbents. Our competitive analysis emphasizes strategic positioning rather than raw product lists:
- Valoya (Finland) — Patent-protected full‑spectrum platforms aimed at commercial cultivation, tissue culture, and growth chambers. Valoya’s differentiation is technical: targeted spectrums coupled with application-level guidance to extract premium per-fixture value.
- Signify (Fluence) (Netherlands) — An award-winning portfolio with strong footprints in cannabis, greenhouse, and vertical farming. Fluence combines global distribution scale with R&D investments that focus on both efficacy and integrated controls.
- Philips GreenPower (Netherlands) — Horticulture-focused toplighting and supplemental systems that leverage Philips’ scale and channel access. Their strength lies in system-level partnerships with greenhouse integrators and legacy lighting relationships.
- Illumitex (United States) — Focused on cannabis, vertical farming, and commercial horticulture with emphasis on scalability and reliability in North American markets.
- LumiGrow (United States) — Full‑spectrum solutions positioned for commercial and premium residential adoption; their go-to-market centers on data-backed controls and retrofit services.
- GE Current (Daintree) (United States) — Emphasis on manufacturing and supply-chain localization within the U.S., attractive to buyers focused on domestic sourcing and compliance.
- P.L. Light Systems (United States) — Noted for fixtures that align with horticultural standards and commercial grower requirements, often competing on spec-compliance and field support.
From a strategic standpoint, the top-tier firms have converted technical leadership and distribution depth into defensible positioning. Yet the CR3 and CR5 concentration figures indicate meaningful runway for consolidation and for specialist vendors that can package differentiated value (software-enabled control, research partnerships, or certified efficacy claims).
Strategic implications and near‑term plays for 2026
- Prioritize compliance-first product upgrades: Firms should audit product roadmaps against DLC V4.0 and QPL relisting timelines today. Non-compliant SKUs will face channel exclusion risks in professional tenders.
- Shift from fixture-only to systems economics: Buyers increasingly prize predictable yields and operational savings. Suppliers that bundle lights with controls, warranty frameworks, and outcome guarantees will command premium pricing and stronger renewal rates.
- Build a fast-follower product cadence: Given the steep CAGR, first-to-market advantages are ephemeral. A two-tiered launch strategy — flagship performance SKUs plus a configurable mid-market platform — balances margin capture and share expansion.
- Use the consolidation window: With the market leader concentration leaving gaps across certain channels and geographies, 2026 is an opportunistic year for acquisitive growth — particularly for assets that add software, testing labs, or regional manufacturing capacity.
- Operationalize grower economics: Sales teams must present farm-level ROI narratives, not just lumens/efficacy claims. Our report provides ready-to-use TCO slides and payback calculators for commercial negotiations.
How to use this analysis
Leaders preparing 2026 plans should use this briefing as a decision accelerator. The full PW Consulting report contains the detailed segmentation, product-level revenue forecasts, and scenario workbooks organizations need to build investment cases, structure partnerships, and prioritize product investments. We intentionally withhold detailed segment tables here to preserve the full value proposition of the comprehensive dataset and interactive model available in the report package.
For executives seeking immediate tactical support, our advisory services can map the report’s insights into three deliverables in twelve weeks: a tailored market-entry or expansion roadmap, a prioritized product development plan aligned to DLC V4.0, and an M&A shortlist with financial filters and integration playbooks.
Next steps
To convert these insights into a defensible 2026 strategy, request the report and model access. Companies that align R&D, channel strategy, and compliance programs during the 2025–2026 transition will capture disproportionately more of the upside created by a market growing at a 16.7% CAGR. PW Consulting stands ready to brief your leadership team and translate the analysis into executable plans that preserve margin, reduce technical and certification risk, and accelerate time to commercial traction.
For detailed analysis of this topic, please visit the official page: LED Grow Lights Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com