

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive headrest market to hit USD 272.3M by 2032 (5.7% CAGR)

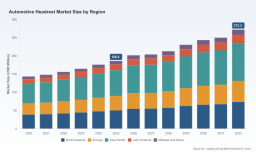
Automotive Headrest Market 2026: Strategic Imperatives for Decision-Makers
As OEMs and Tier‑1 suppliers plan product roadmaps and capital allocations for 2026, the automotive headrest market is no longer a peripheral sourcing decision — it has become a strategic focal point at the intersection of safety regulation, occupant comfort, and vehicle architecture transformation. PW Consulting’s latest Automotive Headrest Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market sizing, competitive dynamics, regulatory trajectories, and technology pathways to inform those decisions. Our analysis shows the market expanding from USD 186.4 Million in 2025 to an anticipated USD 272.3 Million by 2032, growing at a compound annual growth rate (CAGR) of 5.7% for the 2026–2032 forecast window — a trajectory that underlines both opportunity and the urgency to adapt.
Automotive Headrest Market
Why headrests matter in 2026 strategic planning
- Regulatory momentum is real and near‑term. Recent advances in whiplash prevention testing and an active rulemaking process on seating systems are pushing head restraint performance from a compliance checkbox to a design driver. The Insurance Institute for Highway Safety (IIHS) launched a new whiplash prevention evaluation in January 2026 and updated its protocol in late 2025, while national regulators have signaled further dynamic performance requirements that can materially affect seat architecture and supplier selection.
- Functional complexity is rising. Headrests are evolving from passive cushions to smart, dynamic elements: active movement to mitigate whiplash, thermal comfort integration, sensor embedding for occupant monitoring, and interfaces for ADAS and automated driving states. These capabilities change cost structures, manufacturing processes, and supplier qualifications.
- Value reallocation along the seat bill of materials. As vehicles electrify and interior user experience gains prominence, spend on smart and premium seating content is reallocating — creating pockets of higher margin for suppliers who can combine safety compliance with comfort and sustainability credentials.
Market trajectory and what it implies for investment choices
Between 2020 and 2025 the market demonstrated steady expansion, reflecting recovery from pandemic disruptions and accelerating content upgrades. With the 2026–2032 CAGR projected at 5.7%, the sector presents predictable growth but not runaway expansion; returns will therefore favor disciplined investments that either (a) reduce time‑to‑compliance with new dynamic test protocols, (b) unlock premium content (thermal, active safety, comfort sensors), or (c) materially lower cost or complexity through manufacturing innovation. In short, scale alone is not sufficient — strategic capabilities and speed to market will determine winners.
Automotive Headrest Market
Competitive structure: concentrated capabilities, fragmented supply chain
Our concentration analysis shows a market with moderate concentration: the top three players account for roughly 26.8% of the market and the top five about 32.1%. This structure indicates sizable market share for established seat system integrators alongside a broad base of specialized suppliers and regional manufacturers. That mix creates options for OEMs — from end‑to‑end seating system contracts to modular, best‑of‑breed headrest components — but it also increases complexity in supplier management, especially where safety certification and software integration are required.
Automotive Headrest Market
- Large seat system integrators (e.g., Adient, FORVIA, Toyota Boshoku, Lear). These firms offer integrated seat assemblies including advanced headrest mechanisms and are positioned to win OEM contracts where systems integration, warranty accountability, and content bundling matter.
- Specialists and component innovators (e.g., Windsor Machine Group, Innotec Group, Honasco, Polydesign, Tachi‑S). These players bring focused IP — tube forming, metal stays, precision guides, wrapped headrest covers — and are critical partners for differentiation at the component level.
- Hybrid models. Some companies combine design, proprietary mechanisms, and aftermarket channels to capture cross‑segment value, and these hybrid strategies will become more relevant as headrest functions increasingly cross into electronics and software domains.
Company plays and strategic postures
- Adient (Ireland) : Strength lies in system integration and adjustable/dynamic mechanisms — suited to OEM programs that prioritize turnkey seating solutions and regulatory compliance across markets.
- Lear Corporation (United States) : Competitive edge is in thermal comfort and smart integration — attractive for OEMs targeting premium cabin experiences and seamless sensor integration for occupant monitoring.
- Toyota Boshoku (Japan) : Deep OEM relationships and parts manufacturing capability enable strong platform‑level alignment, particularly where vehicle manufacturers seek co‑development and long lead‑time harmonization.
- Windsor Machine Group (Canada) : Differentiation through custom design and power headrest solutions — a fit for bespoke vehicle segments and aftermarket conversions.
- Polydesign Systems & Innotec Group (United States) : Focus on coverings and patented metal forming technologies respectively — critical for suppliers and OEMs seeking weight optimization and durability.
- Tachi‑S & Honasco (Japan, Germany) : Expertise in seat assemblies and precision headrest components positions these firms for premium and luxury segments where finish, fit, and component reliability are non‑negotiable.
Each player’s strategic choices — from vertical integration to technology licensing and localized manufacturing — will determine access to the fastest‑growing pockets in the forecast horizon. The full report provides comparative scorecards and supplier maps that are essential for supplier selection and procurement negotiation strategies.
Regulatory and technology catalysts
- Dynamic performance requirements. Regulatory signals (including NHTSA advance notices and updated IIHS protocols) emphasize forward movement and geometry/strength performance to reduce whiplash. Suppliers must demonstrate validated dynamic behavior under realistic crash conditions, not only static strength metrics.
- Sensorization and electronics. Embedded sensors for occupant detection, posture, and health monitoring are shifting headrests into the domain of software and functional safety, requiring suppliers to adopt ISO 26262 practices and software development capabilities.
- Lightweighting and materials innovation. Materials that balance energy absorption, recyclability, and tactile quality will determine cost and emissions outcomes for seat bills of materials — an important factor for OEM sustainability targets.
What the PW Consulting report provides (practical, decision‑ready content)
Our full study is organized to support executive and operational decision‑makers with actionable outputs:
- Market sizing and a rigorous forecast framework (historical 2020–2025; base year 2025; outlook 2026–2032) with scenario sensitivity to regulatory and technology adoption rates.
- Competitive landscape: profiles, capability matrices, and partnership/transaction case studies for the leading suppliers.
- Regulatory impact analysis: mapping of IIHS, NHTSA, Euro NCAP and regional test protocols to design requirements and cost implications.
- Technology deep dives: active head restraint mechanics, sensor integration pathways, thermal systems, and manufacturing innovations such as tube‑forming and modular subassemblies.
- Supply chain and cost models: material, process, and labor inputs with strategic levers for cost reduction without compromising safety performance.
- Commercial playbooks: go‑to‑market approaches for Tier‑1s and specialists, OEM procurement strategies, and M&A/partnership opportunities ranked by strategic fit and value creation potential.
- Risk register and mitigation plans: regulatory, supplier concentration, and tech obsolescence risks with recommended contingency actions.
To preserve competitive value and comply with “preview” disclosure best practices, the report deliberately withholds granular regional and application split figures in this summary. Readers seeking the detailed segmentation, unit economics, and supplier share tables are directed to the full report where we provide downloadable datasets and model access.
How to use these insights in 2026 planning cycles
- Short‑term (next 12 months): Prioritize compliance assessments and prototype validation for dynamic whiplash tests. Lock down suppliers with validated dynamic performance or establish engineering partnerships to accelerate validation.
- Medium‑term (12–36 months): Invest in modular headrest platforms that allow incremental feature addition (active movement, sensors, thermal units) to capture premium content without full redesigns of seat platforms.
- Long‑term (36+ months): Build software and systems competence (functional safety, data integration) or partner with electronics specialists — headrests will increasingly participate in vehicle state management, occupant interaction, and wellbeing ecosystems.
Closing: strategic choices for 2026
The headrest market’s predictable growth (USD 186.4 Million in 2025 to a projected USD 272.3 Million by 2032 at a 5.7% CAGR) belies the strategic inflection points embedded in regulatory shifts, technology convergence, and changing value pools in the seat bill of materials. For decision‑makers preparing 2026 investments, the question is not whether to engage, but how: choose partners who can validate dynamic safety performance, prioritize modular architectures that protect future feature upgrades, and embed software and material strategies into your headrest roadmap.
PW Consulting’s full Automotive Headrest Market study provides the detailed segmentation, supplier benchmarking, and economic models required to operationalize these choices. For executives seeking to convert the forecast into a winning strategy — supplier selection, product roadmap, or M&A target list — our report is designed as the playbook for 2026 action.
Contact PW Consulting to license the full report and access the underlying data models, scenario simulators, and supplier scorecards that senior decision‑makers rely on to turn market forecasts into competitive advantage.
For detailed analysis of this topic, please visit the official page: Automotive Headrest Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com